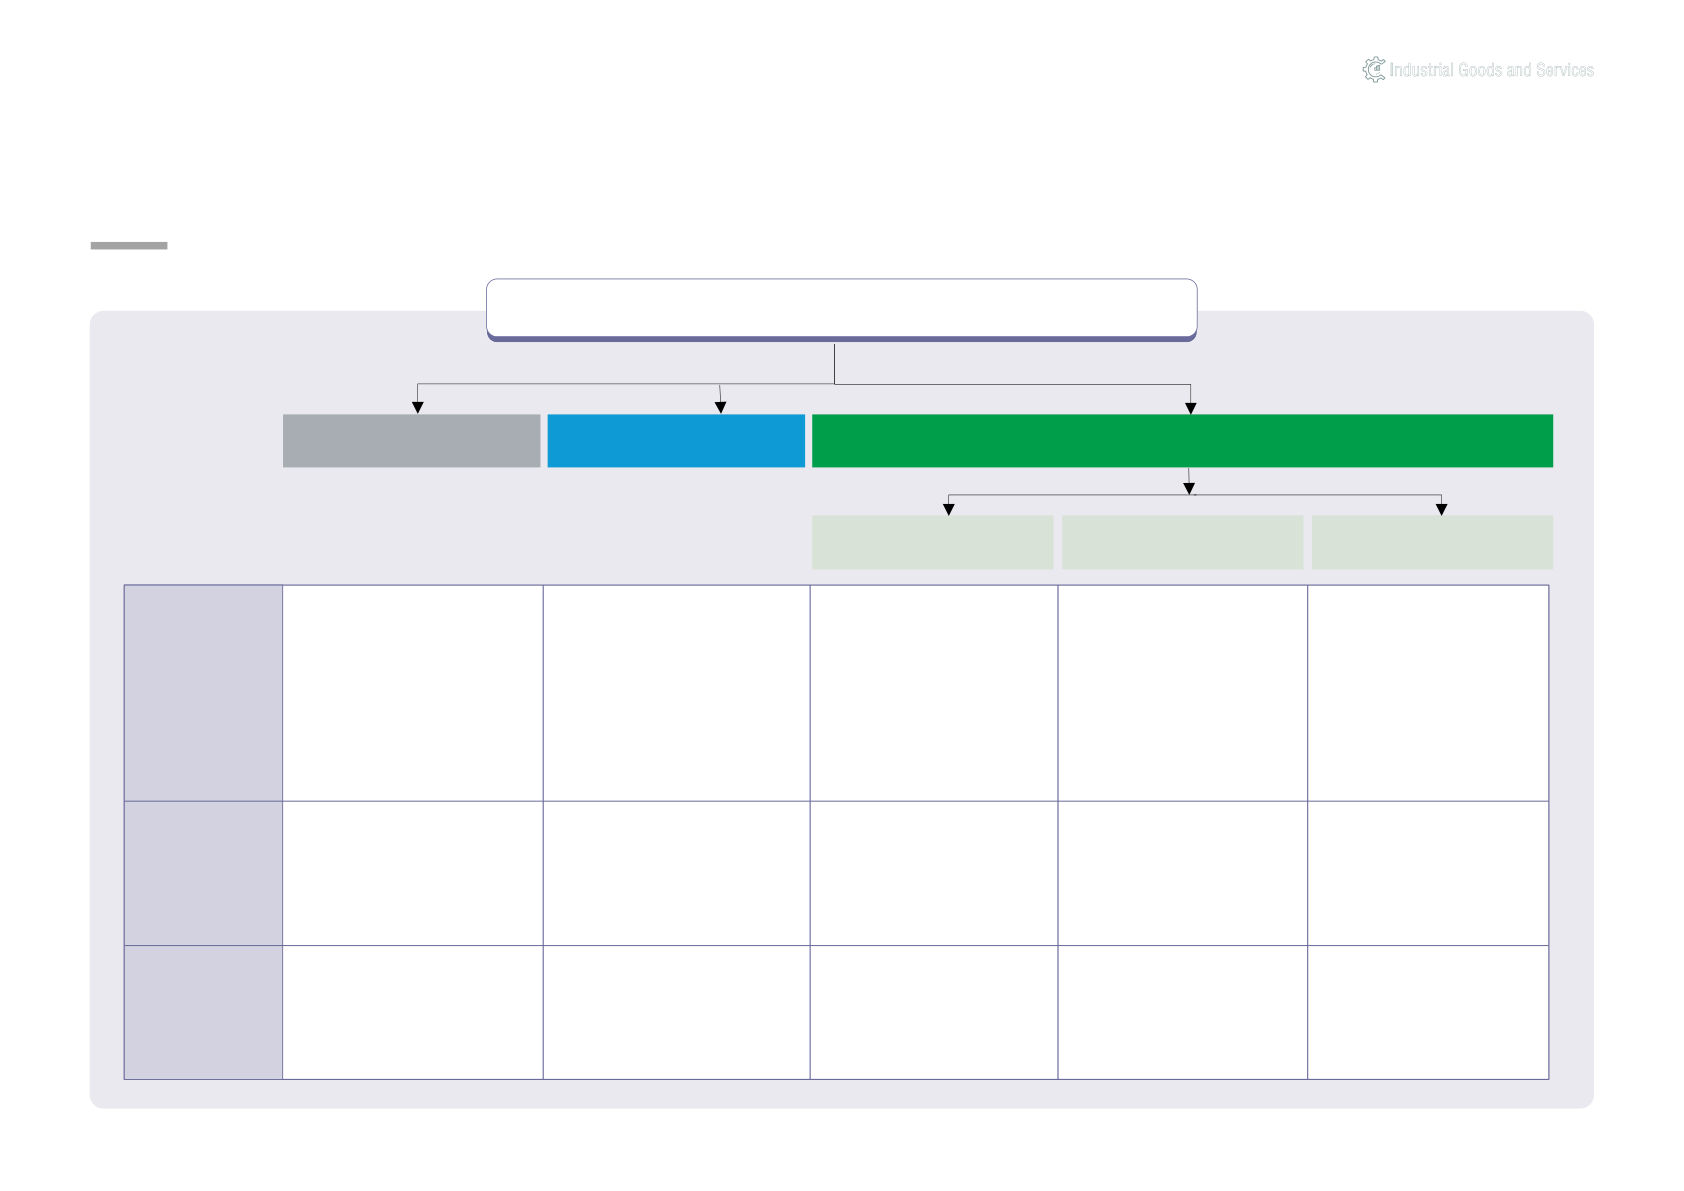
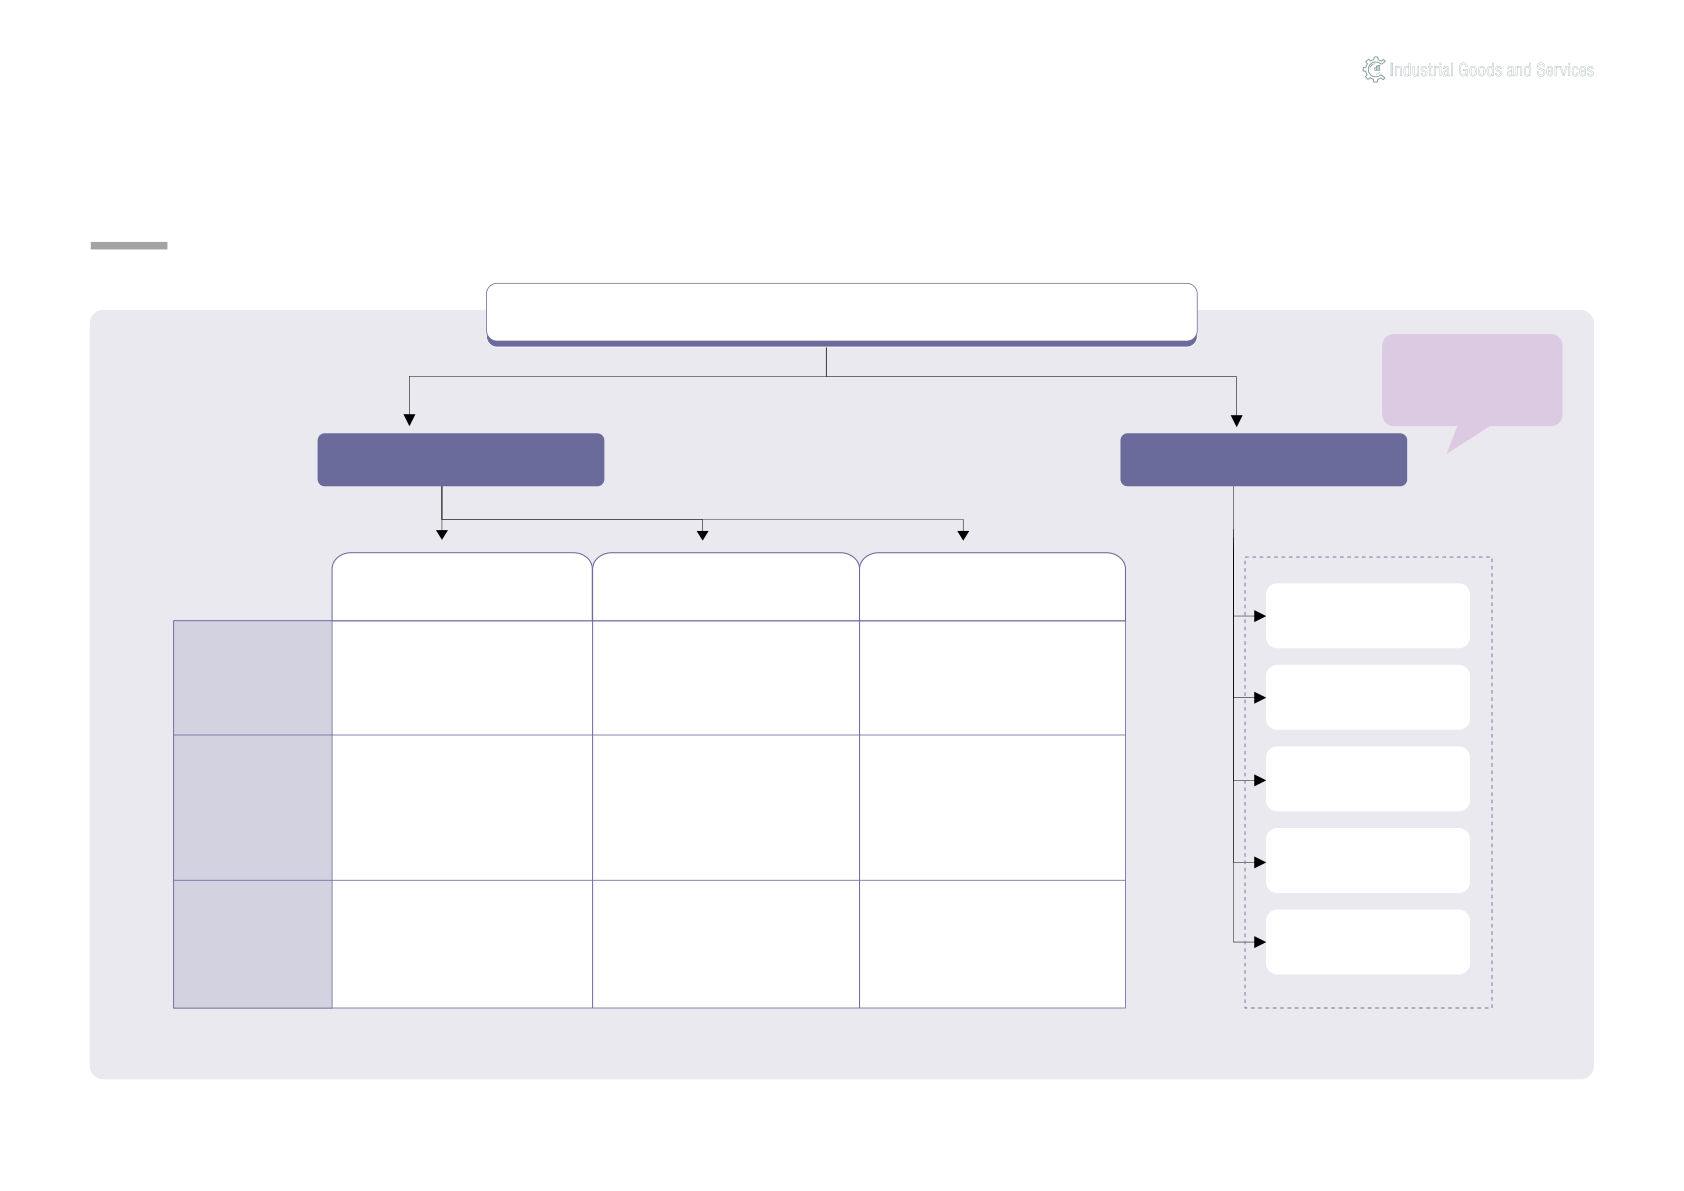
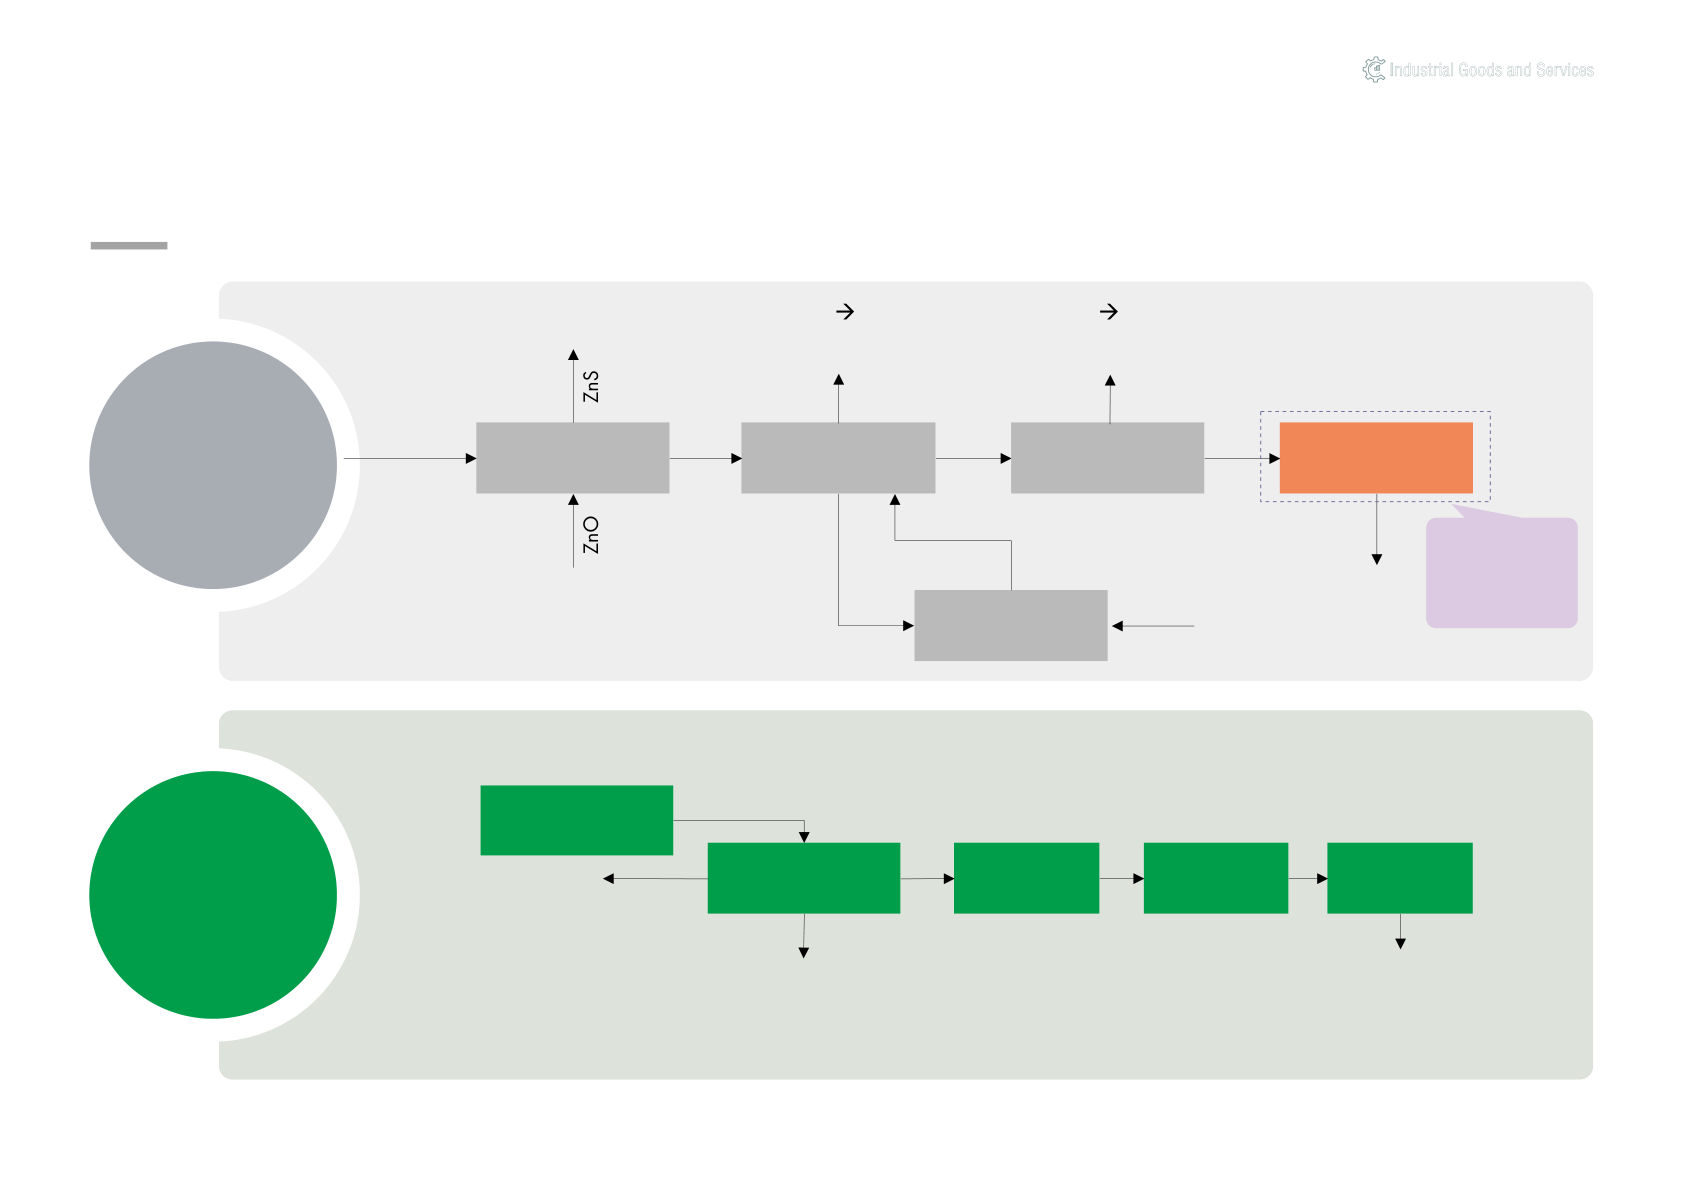
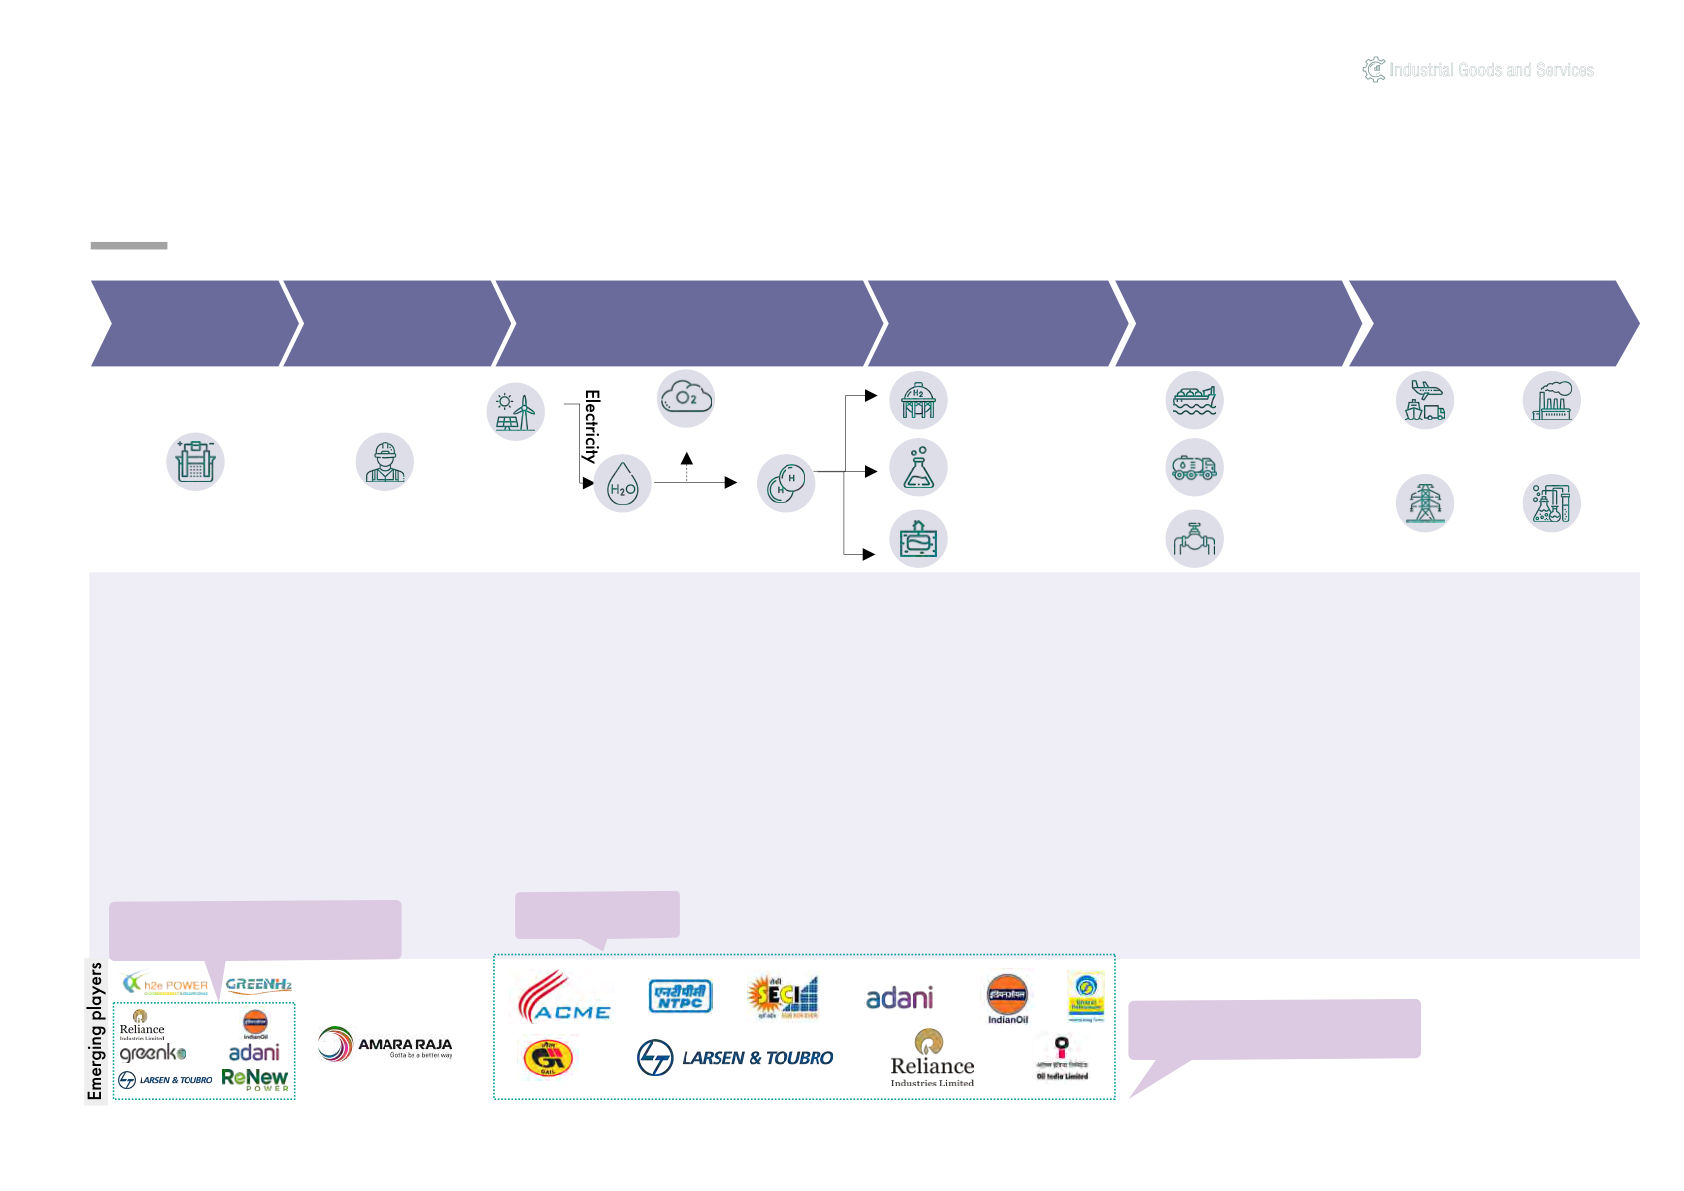
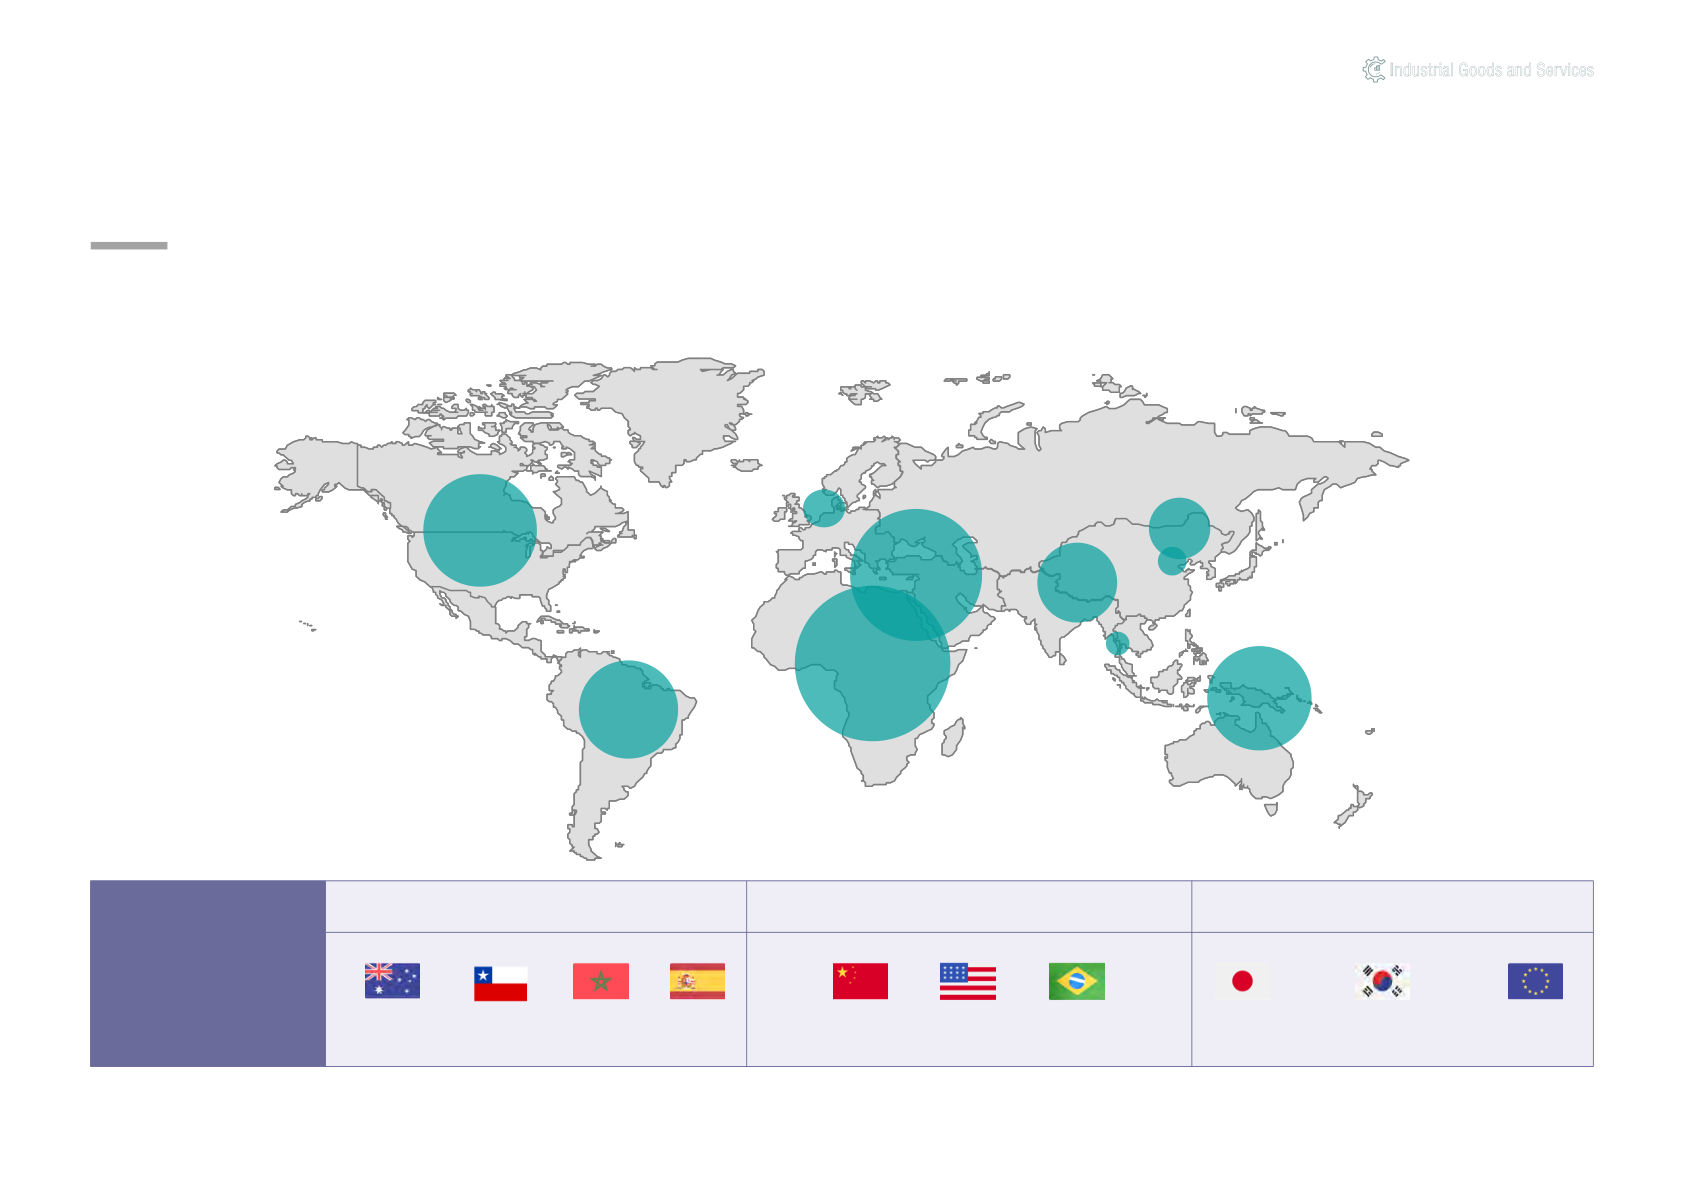
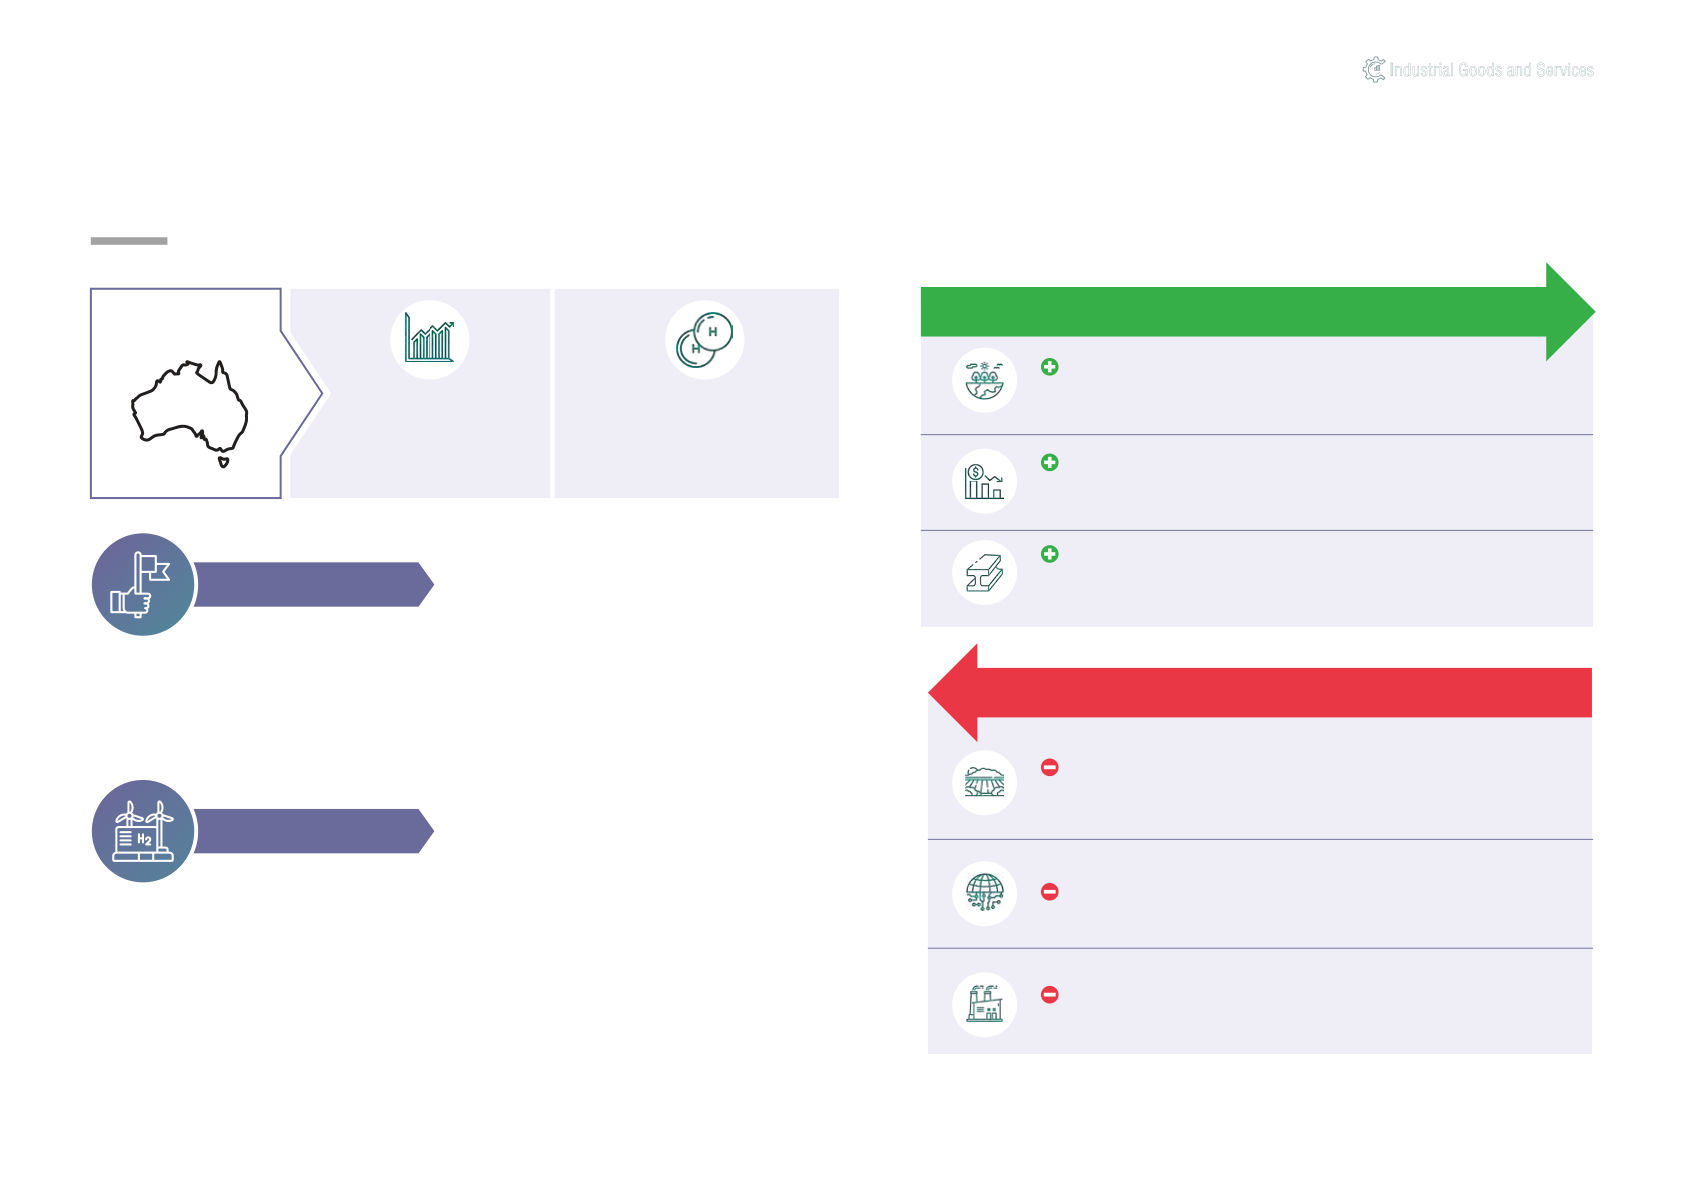
Industrial Goods and Se r vices GREEN HYDROGEN Report June 2023 Confidential and proprietary © Lattice Technologies Pvt. Ltd. Green hydrogen, produced through renewable resources such as solar and wind holds significant promise in meeting the world’s future energy demands. Foreword The global green hydrogen market is predicted to develop as people become more aware of the benefits of using hydrogen as an energy carrier. Furthermore, the industry is being driven by an increase in environmental concerns, emphasizing the need for clean energy generation to reduce emissions. In this report, we have intended to provide insights into the green hydrogen sector of India. The economics of green hydrogen are challenging today because of the high underlying costs and availability of renewable energy sources varying widely. In India, players such as RIL, NTPC, GAIL, BPCL and L&T are leading the green hydrogen revolution by getting involved in storage of hydrogen and manufacturing electrolyzers which are required for producing hydrogen. Green hydrogen has emerging potential demand in sectors such as crude oil refining, transportation, power, ammonia, methanol and steel manufacturing in India. This report aims to provide various industry stakeholders including business leaders an overall perspective on the market. The situation is evolving rapidly, and some of the expected scenarios might have slight variations. The report reflects our perspectives as of January 2023. We, at 1Lattice, look forward to continuing the discussion with our friends across sectors and exchanging notes. Abhishek Maiti Director Executive summary Grey, blue and green are the hydrogen colour codes or nicknames used RIL, NTPC, GAIL, BPCL and L&T are leading the green revolution in in the energy industry to differentiate between types of hydrogen. Rather India. Players such as RIL and L&T are planning to manufacture than using fossil fuels, green hydrogen is made by using a process electrolyzers in India and also develop capabilities for hydrogen called electrolysis to split water into hydrogen and oxygen. The water storage in partnership with various Indian or foreign organizations. electrolysis method for deriving green hydrogen is divided into three Green hydrogen is becoming a key component in bringing energy different types: Alkaline Water (ALK), Polymer Electrolyte Membrane transition and ensuring a sustainable future. Green hydrogen is majorly (PEM) and Solid Oxide Electrolyzer (SOE). used in two sectors: Chemical industry and steel industry. Green While there are several commercial electrolysis systems for producing hydrogen is used for manufacturing ammonia and fertilizers. It is also hydrogen, polymer electrolyte membrane (PEM) technology has used in the petrochemical industry to produce petroleum products and emerged as the most efficient method because of its versatility of crude oil refining. producing higher quality of hydrogen with greater efficiency. The major Furthermore, it has been started to be used widely in the steel industry, a capital cost components of PEM electrolyzer includes catalyst coated sector which is under considerable pressure because of its polluting membrane, porous transport layer, frame, membrane electrode effect. With the increased use of green hydrogen gas, there is an assembly and overall assembly. Catalyst coated membrane has the opportunity to change some of the industry's processes to make them highest cost share of ~50% amongst all the other major components. less aggressive to the environment. Amongst the major cost components of capital cost for balance of plant (BOP) of PEM electrolyzer system, power supply and water circulation Hon’ble Prime Minister launched the National Hydrogen Mission on make ~60% of the overall cost. India’s 75th Independence Day (i.e. 15th August, 2021). The Mission aims to aid the government in meeting its climate targets and making For energy-starved India, which is aiming for carbon neutrality by 2070, India a green hydrogen hub. This will help in meeting the target of the path to energy security goes through a mix of oil, coal, blended production of 5 million tonnes of green hydrogen by 2030 and the fuels, natural gas, renewables and electricity. However, the game related development of renewable energy capacity. Government of changer will be green hydrogen, as other ways of generating energy India has introduced several policy initiatives such as waiver of ISTS are not 100% carbon neutral. The declining cost of renewable electricity charges, RPO incentives, unconsumed renewable power banking etc. to and electrolysis technology indicates that green hydrogen is the next provide clean fuel to the common people of the country. best investment in the world of clean energy and Indian players such as Overview of green hydrogen Green hydrogen in India Global green hydrogen scenario Industrial Goods and Se r vices Overview of green hydrogen Green is the most common type of hydrogen used currently and is obtained through 3 main types of processes Hydrogen as a fuel Grey Blue (CCUS) Green Alkaline water Polymer Electrolyte Solid Oxide (ALK) Membrane (PEM) Electrolyzer (SOE) • Natural gas or coal used as • Basic process is similar to • Electrolysis of water to split • Electrolysis of water to split • The process uses solid Process feedstock to react with grey hydrogen water molecules into H₂ water molecules into H₂ ceramic material as the steam at high temp. to and O₂ and O₂ electrolyte to split the • Uses carbon capture produce gas (H₂ and CO) water molecule by methodology to limit the CO₂ • Use of alkaline water to • Use of Sulfonic acid transferring oxygen ions • Gas reacted with additional emissions from the process perform electrolysis of polymer to perform through a conductive water to produce pure H₂ water electrolysis of water • Various dried oil wells and membrane and CO₂ sinks are envisaged to store carbon captured Benefits • Oldest and easiest process • Traps up to 90% of the GHG • Currently the cheapest • Higher quality of H₂ • SOE needs upto 30% to obtain H₂ emissions through carbon method for green hydrogen obtained less electricity than PEM capturecarbon captured and ALK • Long operational life • Process can run intermittently • The heat coming out of stack can be reused • Significant CO₂ emissions • Costlier than grey hydrogen • Expensive technology • Expensive than ALK • Costlier than alkaline Disadvantages technology water • Utilization by other sectors • Equipment can get does not remove the carbon damaged if process is not • Lower production rate • Lower efficiency (55%) as in principle run continuously than ALK technology compared to the other methods Source(s): Secondary research, 1Lattice analysis © 1Lattice | 05 Industrial Goods and Se r vices Overview of green hydrogen Compressed gas method is the most used hydrogen storage technique; Material-based techniques can significantly alter hydrogen storage landscape Hydrogen storage Material-based hydrogen storage techniques are currently under R&D process Physical-based Material-based Cold or Liquid H 2 Compressed gas cryo-compressed Adsorbent • Pressure applied upon • Requires liquefaction • Gaseous hydrogen is cooled Features O hydrogen gas to reduce at -253 C and then compressed by its volume and stored in applying pressure to reduce Liquid organic special tanks its volume • Cheapest and • Higher energy density than • Lower tank space required Benefits most-widely used form gaseous hydrogen as compared to liquid H₂ Interstitial hydride or uses of hydrogen storage • Application in industry having high purity requirement, such as chip industry Complex hydride • Large tanks required • Additional cost due to cooling • Additional cost due to Risks as compared to other requirement cooling requirement Chemical hydrogen forms of storage due to • Special insulated tanks lower energy density required for storage Compression, storage, and transportation of Hydrogen is expensive and hence not yet commercially viable. However, many pilot projects are on the anvil for hydrogen as an energy storage Source(s): Secondary research, 1Lattice analysis © 1Lattice | 06 Industrial Goods and Se r vices Overview of green hydrogen Green hydrogen requires an electrolyzer and renewable electricity source for production CH + H O CO + 3H CO + H O CO + H 4 2 2 2 2 2 Capture H Capture H 2 2 Natural gas Syngas Steam methane Grey and Cleaning Water gas shift Carbon capture reforming blue hydrogen Additional step in hydrogen production process (blue CO 2 hydrogen) Heat recovery Water RE source H gas 2 Deoxidizer Dryer O exhaust Electrolyzer Green 2 separator hydrogen For compression and Water purifier liquid storage Source(s): Secondary research, 1Lattice analysis © 1Lattice | 07 Industrial Goods and Se r vices Overview of green hydrogen There is huge potential for hydrogen in energy and transportation sectors over the next couple of decades especially with green hydrogen technology Existing use case Potential or future use case Industrial usage Grid Transport Ammonia manufacturing Crude oil refining • Manufacture ammonia • Process crude oil into • Used in industrial application such as • Hydrogen blended • Replace petrol or Uses through Haber process refined fuels, such as into natural gas to be diesel with hydrogen ▪ Metal alloying which is ultimately used petrol and diesel, and used by electricity for running ▪ Flat glass production (used as to produce urea for removing plants to produce automobiles protective gas and for cleaning) contaminants, such as electricity ▪ Electricity plants for generator sulphur, from the fuels cooling and corrosion prevention • Urea is the cheapest fertilizer • Reduce product • Cheaper and effective than • Decarbonization • Retail cost gap Benefits available, as other fertilizers boiling range by other alternatives opportunities for between petrol or is require temperature and converting the power players lower than other fuels humidity-controlled feed to lower environment boiling products Risks • N/A • N/A • N/A • Unproven customer • Refueling acceptability infrastructure not • Regulatory restrictions available • Safety testing required • Switching cost for car for end-use appliances owners Current usage level Low High Source(s): Secondary research, 1Lattice analysis © 1Lattice | 08 Industrial Goods and Se r vices Overview of green hydrogen Globally, green hydrogen market can focus on having about 4 types of operating models Contractual payments Regulated returns Obligatory consumption End-user subsidy • Oil and gas companies • Oil and gas companies • Private producers • Oil and gas companies Asset owner • GENCOs and IPPs • GENCOs and IPPs • GENCOs and IPPs • Other private producers • Other private producers • Other private producers • Self-consumption • Self-consumption • Oil and gas companies • Industrial customers Customers • Oil and gas companies • Oil and gas companies • Industrial customers • Industrial customers • Industrial customers • Hydrogen producer receives subsidy • Hydrogen producers earn a • End-users obligated to replace • End-user gets subsidy for additional Key features to cover incremental cost of regulated return on cost a certain % of their fuel costs incurred due to switching to low-carbon hydrogen over alternative consumption with low-carbon low-carbon hydrogen fuels alternatives • Capex model • Capex model • Opex model • Opex model Business or • Opex model • Opex model Revenue models • Long-term contracts which are • Returns on capital costs can be • Assured minimum demand in • Creates potential to increase demand Benefits unaffected by short-term policy gained irrespective of demand the market in the industries changes by the government • Requires high monetary support • Inadequate demand may lead • Increased competition without • Subsidy can be altered or removed Risks from government to cover to reduced government support increase in obligations or demand by policymakers over time incremental costs and shift to alternatives can lower prices and margins • Obligations can be adjusted or reduced by policymakers over time Source(s): Frontier Economics, Secondary research, 1Lattice analysis © 1Lattice | 09 Industrial Goods and Se r vices Overview of green hydrogen Green hydrogen production cost is expected to reach US$ 1.5/ kg by 2030 and become lower than blue hydrogen before 2050 Demand for pure hydrogen has increased Cost of green hydrogen is expected to become at ~2% CAGR over 2000-18 lower than blue hydrogen between 2030-2050 Global demand for pure hydrogen Hydrogen cost by production type (Million tonnes) (US$ per kg) 1.9 CAGR 2000-18 1.5 1.9% 74 72 1.3 1.3 1.3 62 4.2 2.9% 3.8 54 1.1 53 3.1 0.9 0.9 0.9 2.7 38.2 2.5 36 31 3.3% 21.4 25.3 31.9 31.5 28.6 0.5% 28.3 26.1 2000 2005 2010 2015 2018 2020 2030E 2050E Grey Hydrogen Blue Hydrogen Green Hydrogen Others Crude oil refining Ammonia manufacturing Note(s): EUR 1 = US$ 1.22; E= Estimated Source(s): IEA, 1Lattice analysis © 1Lattice | 10 Industrial Goods and Se r vices Overview of green hydrogen Cost breakdown for a 1MW green hydrogen PEM electrolyzer [1/2] 2% 15% 3% Catalyst Stack 50% coated PEM electrolyzer membrane cost breakdown 30% 13% Stack 42% Catalysed coated membrane 45% 25% Porous transport layer Frame Stack Membrane electrode assembly Balance Assembly 21% components of plant incl. CCM Balance Manufacturing PFSA membrane of plant 4% Iridium 12% 55% Platinum 30% Power supply Balance Water circulation 24% of plant Hydrogen processing Colling Others 30% Note(s): PEM – Polymer electrolyte membrane © 1Lattice | 11 Source(s): Secondary research, 1Lattice analysis Industrial Goods and Se r vices Overview of green hydrogen Cost breakdown for a 1MW green hydrogen PEM electrolyzer [2/2] Breakdown of capital cost of stack components Breakdown of capital cost of Balance of plant of PEM electrolyzer system (BOP) of PEM electrolyzersystem Major Share of Dominant Unit Cost Major Share of Unit Cost components major costs (In US$ K) components major (In US$ K) components components Platinum, iridium, US$ 337-339 50% Per MW 30% Per MW US$ 247-249 Catalyst coated Power supply (Nafion) membrane membrane Titanium powder, Porous 30% Per MW US$ 202-204 Water 30% Per MW US$ 247-249 gold (coating transport circulation material) layer 24% Per MW US$ 197.5-198.5 Hydrogen 3% Materials (95%) Per MW US$ 20-22 Frame processing 15% Materials (90%) Per MW US$ 101-102 12% Per MW US$ 98-99 Membrane Cooling electrode assembly 2% Labour (90%) Per MW US$ 13.2-13.7 4% Per MW US$ 32.5-33.5 Assembly Others The operating cost of the electrolyzer and photovoltaic system is US$ 17 kW/year and US$ Components that can be outsourced 9.82 kW/ year respectively. Water charges are US$ 1.44 per 100 kg of H2 produced Note(s): PEM – Polymer electrolyte membrane © 1Lattice | 12 Source(s): IRENA; Department of Energy, USA; 1Lattice analysis Overview of green hydrogen Green hydrogen in India Global green hydrogen scenario Industrial Goods and Se r vices Green hydrogen in India Players such as RIL, NTPC, GAIL, BPCL, and L&T are leading the green hydrogen revolution in India Manufacturing Green hydrogen Energy generation & Transmission & Storage Utilization electrolyzers EPC & developer hydrogen production distribution Tanker ships Storage tanks Oxygen released Transport Industrial Renewable Chemical storage Trucks energy Electrolysis Electrolyzers Developers Green Underground hydrogen Pipelines Power Chemicals storage • Electrolyzers - Key • Basic functions • Green hydrogen produced through • Storage tanks: Simplest & • Tanker ships: • Industrial: Used in industrial device used for include: electrolysis by splitting water into economical way to store in processes such as iron, steel ▪ Used for larger volume, achieving hydrogen hydrogen & oxygen atoms only the form of compressed and plants & refineries ▪ Consulting, sales long-distance transport production cryo-compressed hydrogen & design of • Electrolysis performed through electricity • Transportation: Used as fuel in ▪ Expensive due to added • India will initially project produced from renewable sources such • Chemical storage: Storage light-duty vehicles, buses, trucks, conversion costs import electrolyzers, as wind, solar, water in the form of compounds trains, and potentially shipping ▪ Procuring (liquefaction or while Indian state-run such as liquified organic and aircraft equipment at best chemical conversion) refiners plan to form hydrogen carriers (LOHCs) available prices • Power: Can be used in gas • Trucks: Used for smaller joint ventures with and hydrides turbines to increase power ▪ After sales volumes, both in gaseous foreign companies • Underground storage in system flexibility & for storing services like & liquid form, for local manufacturing the salt caverns & salt domes: renewable energy maintenance & distribution & longer equipment Large volume, low-cost, monitoring journeys • Chemicals : Used as a feedstock natural storage options to produce ammonia (used in Involved in both • Pipelines*: Cheapest way Prospective players planning to manufacture production & storage fertilizer industry), methane, and to move hydrogen over electrolyzersin India soon in partnership with methanol various Indian or foreign organizations longer distances OIL has a current green hydrogen production capacity of ~4 tonnes/ year with an aim to increase production capacity to ~11 Note(s): *Hydrogen produced through clean pathways can be injected into natural gas pipelines, and the resulting blends can be used to generate heat & power with lower emissions than using natural gas alone © 1Lattice | 14 Source(s): NITI Aayog, Press releases, Company website, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India Various MNCs & PSUs such as RIL, Adani, NTPC, Indian Oil, GAIL are [1/2] ramping up & taking steps towards the green hydrogen mission in India Players Plant location Plans & steps taken towards green hydrogen Investments • Plans to build 2.5 GW electrolyzer manufacturing capacity for producing 400K tonnes of hydrogen , • Invested INR 60,000 Cr. in partnership with Stiesdal (~US$ 7.5B) in green energy • Jamnagar, integrated complex called • Targets to bring down cost of green-hydrogen to <US$ 1/kg by the end of CY30 Gujarat Dhirubhai Ambani Green • Partnered with Stiesdal & other leading electrolyzer technology players globally to set up a Energy Giga Complex giga-scale electrolyzer manufacturing facility at Jamnagar • Awarded project of ‘Standalone Fuel-Cell based Micro-grid with hydrogen production using • Plans to invest INR 10,00,000 electrolyzer’ Cr. (~US$ 125B) between • Simhadri, 2019 and 2024 to become a • Looking to leverage hydrogen for transportation by mixing fuel with natural gas for City Gas Andhra 130GW power producer by Distribution (CGD) network Pradesh 2032 • Plans to produce green hydrogen using an advanced 240 KW electrolyzer by taking input power from the nearby Floating Solar project • Economies of scale to be achieved by gradually reducing the cost of hydrogen from US$ 2.8-3/kg • Plans to supply power through its windmill in Rajasthan to produce green hydrogen through • Invested ~INR 100 Cr. (~US$ electrolysis which will then be used in processing crude oil 13M) for setting up green • Mathura, hydrogen fuel infrastructure in • Also plans to build a stand-alone green hydrogen manufacturing unit in Kochi that will draw energy Uttar Pradesh Kerala from the solar power facility of Kochi International Airport • Targets to convert at least 10% of its hydrogen consumption at refineries to green hydrogen soon • Tied up with Renew power & L&T to jointly develop & supply green hydrogen at an industrial scale • Plans to develop and operate green hydrogen projects in India in partnership with ReNew Power • Plans to spend INR 1,000-5,000 Cr. (~US$ • Signed a pact with Norway-based company HydrogenPro to set up an electrolyzer manufacturing • Hazira, 125-630M) on its green unit in India Gujarat initiatives, spread over • Plans to install few more hydrogen plants in other manufacturing units several years Source(s): Press releases, 1Lattice analysis, 1US$= INR 79.8 © 1Lattice | 15 Industrial Goods and Se r vices Green hydrogen in India Various MNCs & PSUs such as RIL, Adani, NTPC, Indian Oil, GAIL are [2/2] ramping up & taking steps towards the green hydrogen mission in India Players Plant location Plans & steps taken towards green hydrogen Investments • Plan to build I ndia’s largest green hydrogen-making plant as it looks to supplement its natural gas • Plans to invest ~ INR 26,000 business with carbon-free fuel Cr (~US$ 3B) in its renewable • Vijaipur, portfolio by 2030, contingent • Plans to build a 10 MW electrolyzer capable of generating 4.5 tonnes of green hydrogen daily Madhya upon certain technical aspects Pradesh on green hydrogen • Signed a non-binding pact with Ballard Power Systems to evaluate a joint venture for investment in the • Plans to invest ~ US$ 50 billion commercial production of green hydrogen fuel cells for various mobility & industrial applications over next 10 years on green N/A hydrogen projects • Adani New Industries Ltd. & TotalEnergies to jointly build world’s biggest green hydrogen ecosystem as they seek to cut their reliance on fossil fuels & transition to zero net carbon emissions • Initial phase plan to develop a green hydrogen production capacity of 1 MTPA by 2030 • Building India’s first 99.999% pure green hydrogen plant with an installed capacity for producing 10 kg of hydrogen per day • Jorhat, • 100 KW electrolyser used with installed Anion Exchange Membrane (AEM) technology Assam • Initiated a detailed study with IIT Guwahati on blending green hydrogen with natural gas for commercial application of blended fuel • Collaborated with Bhabha Atomic Research Center on alkaline electrolyzer tech for green hydrogen production • Bina, Madhya • Aims to scale up the production of electrolyzer for commercial use, especially in refineries Pradesh • Plans to put up a 20 MW electrolyzer at its refinery in Bina, Madhya Pradesh to produce green hydrogen Source(s): Press releases, 1Lattice analysis, 1US$= INR 79.8 © 1Lattice | 16 Industrial Goods and Se r vices Green hydrogen in India Cheaper renewable electricity costs & faster charging time of hydrogen-based vehicles compared to EVs are driving the growth for green hydrogen in India Growth drivers Green hydrogen production Company Current capacity Planned capacity Year Reducing renewable electricity cost: name (Tonnes) (Tonnes) • Renewable electricity cost has got significantly cheaper in India over the years, from US$ 359 per MWh¹ in 2009 to US$ 40 per MWh1 in 2019, • According to International Renewable Energy Agency’s report, reducing the cost of renewable-based electricity by half can halve the levelized cost of 4 11 Undisclosed green hydrogen if other cost components such as capital cost, annual load factor of electrolyzer remain unchanged - 1,570 2023 RPO² Mandate: • According to RPO mandate, all electricity distribution licensees should purchase or produce a minimum specified quantity of their requirements from renewable energy sources • With increased pressure on steel & refining industries to reduce their carbon - 20,000 2025 footprint, green hydrogen’s importance and scale of production & usage are bound to increase - 70,000 2030 Faster charging compared to EVs: • Increasing consumer preference toward environment-friendly vehicle options • EVs take over 90 minutes to recharge whereas FCEVs3 take 5-15 minutes • Demand for hydrogen is projected to increase by 3-10 times by 2050 as most countries, including India, are focusing on hydrogen-based vehicles - 10,00,000 2030 Note(s): 1MWh: MegaWatt hour, 2Renewable Purchase Obligation, 3Fuel Cell Electric Vehicles (FCEVs) are run by hydrogen © 1Lattice | 17 Source(s): Company websites, Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India Green hydrogen has emerging potential demand in sectors such as crude oil refining, transport, power, ammonia, methanol & steel manufacturing in India Industries Demand drivers Industries Demand drivers • Considerable increase in demand of petroleum products if • Potential to reduce carbon emissions in blast furnaces by Crude oil Steel efficiency measures & low or zero carbon alternatives are not 20%. However, 100% green hydrogen-based steelmaking refining manufacturing adopted would be commercially viable only by 2040 • Potential to decarbonize steel manufacturing which currently • Stringent policies on limiting sulphur content from petroleum accounts for 35% of GHG* emissions from India’s products - the more stringent the standards, the higher the manufacturing sector requirement of hydrogen in desulphurization • Replacing majority of natural gas-based hydrogen feedstock • Increasing growth rate in vehicle population & travel Ammonia Transport with renewable-based electrolysis process to form green demand. Two technology options exist to electrify HDVs: manufacturing ammonia battery electric vehicles (BEVs) and fuel cell electric vehicles (FCEVs) • Expected rise in demand for nitrogenous fertilizers at ~3% CAGR over the next decade where ammonia is used in the • Green hydrogen’s role as a fuel for transport can extend manufacturing of nitrogen-based (urea) & other complex beyond road transport to shipping & aviation which use fertilisers heavy fuel oil and jet fuel respectively • India currently produces only 13% of its methanol • Hydrogen advocates proposed the concept of Methanol Power consumption with a policy goal to increase its production for power-H2-power** as another form to provide storage and manufacturing its application in transport, military, industrial & residential flexibility to the grid, opening an end-use sector for sector hydrogen • Existing global methanol supply chain that can be leveraged • Potential fuel source for peaking power generation through to store, transport, & distribute methanol as a hydrogen carrier existing gas turbines, and for power generation and backup applications for distributed assets like cell phone towers and replacement of diesel gensets Note(s): *Greenhouse gases, **Storing excess hydrogen, either physically or chemically, & discharging it at time of need either through gas turbines or fuel cells © 1Lattice | 18 Source(s): NITI Aayog, Policy papers, CEEW, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India High cost of production, transportation & storage are the key barriers to green hydrogen production & growth in India Barriers to growth Intensity Rationale • Higher cost of production of green hydrogen a s compared to grey and blue hydrogen High production • Expensive electrolyzers make it uneconomical to produce green hydrogen at large scale cost • Insufficient strong monetary support from government and financial institutions to set up green hydrogen plants • High cost of storage due to large tank space requirement (compressed gas) and high cost of cooling High transportation (liquid H₂) & storage cost • Difficult to transport high volumes of hydrogen while considering all safety aspects Inadequate • Few electrolyzer or hydrogen generator manufacturers in India; electrolyzer or hydrogen generator is a key device in performing electrolysis for green hydrogen production infrastructure & • Significant investments required in electrolyzers & renewable electricity by government need for investments • No clarity on the industrial categorization of green hydrogen under the Central Board Directions for the categorization of industries into red, orange, green, & white categories resulting in complete chaos while Uncertainty on seeking approvals* policy framework • No clarity on taxability on the production of green hydrogen so far • Limited availability of sufficient water streams due to multiple application areas Limited availability • Consumption of ~9 liters of demineralized water as an input to electrolyzer for producing 1 kg of of fresh water hydrogen Low High Notes(s): *Hydrogen has been categorized as a hazardous substance & industries producing hydrogen as a secondary product have been kept under ‘Red’ category © 1Lattice | 19 Source(s): NITI Aayog, Press releases, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India Key steps taken by Government of India towards the National Hydrogen Mission Access to Unconsumed Waiver of ISTS² Procurement of Direct connectivity renewable energy renewable power charges renewable energy to the grid for manufacturing ISTS charges for green Distribution licensees can Direct connectivity to the Unconsumed renewable Procurement of renewable hydrogen manufacturers procure and supply grid given to the green power can be banked up power by green hydrogen waived off for projects renewable energy at hydrogen and renewable to 30 days with the th manufacturers from power commissioned before 30 concessional prices³ to the energy manufacturers to distribution company & exchange or by setting up June 2025 manufacturers of green avoid procedural delays withdrawn when required renewable energy capacity hydrogen 01 02 03 04 05 RPO¹ incentives Online portal for Connectivity Green hydrogen Permission for ease of doing at both ends storage storage Granted incentive of RPO Connectivity granted on Storage bunkers near ports Providing permission for business benefits to the priority basis to ISTS for exporting & use of green renewal energy storage up manufacturers of green Development of a single between generation end hydrogen to 30 days for renewable hydrogen and distribution online portal for and manufacturing end for energy that is used for land for the bunkers licensees for the consolidating all the production of green making green hydrogen provided at a price by the consumption of renewable activities including statutory hydrogen respective port authority power clearances in a time bound manner will be set up by MNRE 06 07 08 09 10 Note(s): 1Renewable Purchase Obligation, 2ISTS: Inter-state Transmission System, 3includes cost of procurement, wheeling charges, & a small margin as determined by the State Commission © 1Lattice | 20 Source(s): NITI Aayog, Ministry of Power, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India India’s favorable geographical conditions & cheaper availability of renewable energy are key supporting pillars for the growth of green hydrogen in India • Significant edge in green hydrogen production because of the country’s tropical nature & availability of abundant natural resources Favourable • India is estimated to generate >1,000 GW of solar energy on just 0.5% of landmass & seawater from the vast coastline that can be geographical used for electrolysis process conditions • Cost of electricity from solar energy dropped by ~90% from US$ 359/MWh in 2009 to US$ 40/MWh in 2019 Cheap availability • Electricity cost from onshore wind dropped by ~70% from US$ 135/MWh in 2009 to US$ 41/MWh in 2019 of renewable • Minimum renewable LCOE* because of cheap availability of renewable energy in India energy • Increased hydrogen use can substantially reduce greenhouse gas emissions in hard-to-abate sectors, particularly steel and cement production, heavy-duty transportation, shipping & aviation Staving off • Green hydrogen sector will not only play a key role in decarbonizing transportation & energy but has the potential to create millions of climate change high-quality, green jobs • National targets of achieving 500 GW of renewable energy capacity t o meet India’s 50% energy requirements by 2030 to further Goal to achieve complement production cost & volumes of green energy national targets • Requirement of more diversified approach by the Government of India’s objective to cut its emission intensity by 33-35% of 2005 levels by 2030 Wide application • Grey hydrogen used in industries such as crude oil refining, ammonia production, steel manufacturing, heavy-duty vehicles & power across multiple sector can be replaced with green hydrogen sectors • With technological improvements, green hydrogen will become more affordable and accessible sooner than expected Note(s): *Levelized cost of hydrogen © 1Lattice | 21 Source(s): NITI Aayog, Press releases, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India High cost of production & shortage of skilled force are key barriers to electrolyzer manufacturing in India Domestic demand for electrolyzer is expected to Barriers to Recommendations grow at a CAGR of 12.6% between FY30 to FY50 production • Identify & invest in research, development, & commercialization Electrolyzer demand in India High input of low-cost electrolyzer technologies that require minimum rare (FY30E-50E) earth metals costs • Secure critical mineral supply either through indigenous development or global collaborations for supply chain of nickel, platinum, iridium & other key raw materials used in electrolyzers CAGR • Implement a focused & commercial results-oriented R&D FY30E-50E Improper fund program with well-defined targets for funds allocated utilization • Reward or incentivize development of commercial technology 9.5% to catalyze the development of commercial green hydrogen 31 technologies across the value chain • Arrange proper training and organize skill development Shortage of 23 programs to ensure labor has the required skill set to skilled manufacture electrolyzers work-force 216 12.6% • Provide incentives to existing manufacturers to increase Shortage of domestic production incentives to 112 • Provide incentives to emerging manufacturers with existing manufacturers 5 capabilities to initiate manufacturing within the country 20 • Build large-scale centralized facilities to minimize green Small sale of FY30(E) FY40(E) FY50(E) hydrogen cost production • Adopt large-scale (10-20 MW) projects to bring down the rd Volume (GW) Value (US$ B) cost of producing hydrogen by 1/3 as compared to small-scale (1 MW) projects Note(s): *BoP: Balance of Plant includes systems such as gas turbine, steam turbine, waste heat boiler, etc., **PMP: Phased Manufacturing Programme © 1Lattice | 22 Source(s): Company websites, Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Green hydrogen in India Export opportunities exist for India amidst the challenges of insufficient funds for hydrogen research & inexperienced hydrocarbon exporter Global demand for clean hydrogen is expected to Tailwinds and Opportunities grow at a CAGR of 17% from FY25(E) to FY30(E) • Indulging in export of green hydrogen-based products (green ammonia) to avoid costs associated with green hydrogen production Global demand for clean hydrogen – by value (US$ B, FY22-30E) • Pre-empting the green steel market through export-oriented pilot Indian demand for hydrogen could grow projects and manufacturing scheme more than fourfold by 2050, representing almost 10% of global demand 5.95 • Willingness to pay premium prices & the increasing pursuit of importing hydrogen through ocean shipping by traditional energy transporters such as Japan & South Korea Headwinds and Challenges 17% • Inadeqaute experience as a hydrocarbon exporter in comparison to 2.67 Middle Eastern countries & Australia 1.94 1.65 • Insufficient funds for hydrogen research with only INR 25 crore (US$ 3M) allocated to MNRE1 for R&D • Shortage of developed pipelines for transportation of green hydrogen • Reservation of pipelines for high volume flows due to their high capital FY22 FY23(E) FY25(E) FY30(E) cost & long lifetime Note(s): 1Ministry of New and Renewable Energy © 1Lattice | 23 Source(s): NiITI Aayog, Secondary research Industrial Goods and Se r vices Green hydrogen in India Establishing clear targets for electrolyzer manufacturing & cost reduction by the government are recommended to foster green hydrogen production in India Detailed roadmap Shortage of allied Initiating Setting up targets Initiating green focused on all aspects public infrastructural mandates & for electrolyzer hydrogen standards of green hydrogen facilities incentives manufacturing • To elaborate on the • Setting up & running • To identify those end-use • To identify a timeline • To c onstruct new government’s vision for costs of hydropower sectors r eady for scaled and scale of standards for green green hydrogen in plants requires transport consumption and those manufacturing support hydrogen keeping in multiple sectors with of heavy equipments like ripe for small-scale & for electrolyzer mind the widespread timelines & investment turbines & motors large-scale pilot accounting not only for use of hydrogen across aspirations given the development Indian demand but also sectors • Dams being in remote long-term cost for burgeoning global locations deprive • To propose clear • To initiate a digital advantage demand effective road mandates around (AI/ML equipped) • This will improve connectivity & other hydrogen blending in • To encourage labeling and tracing investors’ confidence & public facilities which existing and potential manufacturing of mechanism certification converge the entire disincentivize private future consumption necessary value chain of origin for value chain and the players sectors to encourage components such as ascertaining green various government early market pipes, cylinder storage, credentials of all supply agencies towards a development compressors, etc. routes of hydrogen singular vision Note(s): *Variable Renewable Energy Source(s): NITI Aayog, 1Lattice Analysis © 1Lattice | 24 Industrial Goods and Se r vices Green hydrogen in India Promoting exports of green hydrogen & encouraging state-level actions by the government is recommended to foster green hydrogen production in India Promoting exports of Facilitation of Encourage Encourage capacity Construct an green hydrogen investments state-level actions building & skill inter-ministerial embedded products & policy making Development governance structure • To form government- • To develop a functioning • To encourage all states • To necessitate • To create an to-government carbon market to to launch their own appropriate and rapid interdisciplinary project partnerships with target accelerate state-level green skills development management unit with geographies such as decarbonization of hydrogen policies to across the ecosystem globally trained experts Japan, Korea, Germany, hard-to-abate sectors, complement including government, dedicating full-time etc. for integration of thereby making green national-level policies industry, and academia resources for effective hydrogen into existing hydrogen projects more based on their unique implementation of the • To design, develop & energy financially viable in the needs & strengths mission deploy a scalable skill process • To explore near-term • For example, some states program including • To institute an inter- incentives around green • To access low-cost could focus on low-cost business models, ministerial mechanism to ammonia & green steel climate finance through green hydrogen policies, and geopolitics coordinate across the production through either multilateral production while others various line ministries’ & public incentives to institutions or by could focus on demand departmental efforts bridge the initial viability capitalizing on bilateral clusters, etc. required to achieve the gap agreements with target of the mission developed nations Source(s): NITI Aayog, 1Lattice Analysis © 1Lattice | 25 Overview of green hydrogen Green hydrogen in India Global green hydrogen scenario Industrial Goods and Se r vices Global green hydrogen scenario Various countries across the globe are coming up with different strategies to promote a green hydrogen economy 126 projects 19 projects 46 projects 8 projects 5 projects 24 projects ~US$ 10.2T ~US$ 70B ~US$ 2.5T 114 countries ~20 countries ~30 countries ~250 cities Expected global Government support for Estimated annual Setting targets for Announced sales ban Announced national Targets for 100% investment until 2050 hydrogen transition sales by 2050 cutting emissions ICE vehicle by 2050 hydrogen mission renewable energy Source(s): Hydrogen Council Report, 1Lattice analysis © 1Lattice | 26 Industrial Goods and Se r vices Global green hydrogen scenario Various MNCs such as Siemens Energy, Masdar, ADNOC, Fertiglobe & Engie are taking steps towards a global green hydrogen mission Players Plant location Plans & steps taken towards green hydrogen Investments • Siemens Energy, in collaboration with Dubai Electricity and Water Authority (DEWA) and Expo 2020 • Investment of ~US$ 13.6B with has plans to establish a solar-powered green hydrogen plant a planned production capacity • Dubai, UAE of 5,000 MW by 2030 • PEM electrolysis technology to be adopted • Berlin, • Air Liquide & Siemens Energy announce a joint venture dedicated to production of renewable Germany hydrogen electrolyzersin Europe • Masdar has collaborated with Engie and Fertiglobe to co-develop green hydrogen • Investment of ~US$ 5B for a production plants in UAE with plans to install 200 MW capacity plants by CY25 capacity of at least 2 GW by • Abu Dhabi, 2030 • Fertiglobe will be the sole long-term user of the hydrogen, which will be used to produce UAE green ammonia • The Abu Dhabi National Oil Company (ADNOC), Mubadala, and TAQA have come together for • Investment of ~US$ 1.9B developing green hydrogen • Abu Dhabi, • The green hydrogen will be produced from natural gas and will be exported to emerging international UAE markets • The partnership aims to create a global clean energy entity that would consolidate renewable energy and green hydrogen • ACWA Power, in collaboration with Air Products, proposes to manufacture green hydrogen in Saudi • Investment of ~US$ 5B to • Dhofar, Arabia's future city Neom, a US$ 5B project that will be the world's largest develop green hydrogen-based Oman ammonia production Source(s): Press releases, 1Lattice analysis, 1US$= INR 79.8 © 1Lattice | 27 Industrial Goods and Se r vices Global green hydrogen scenario Various MNCs such as Cummins, Yara & InterContinental Energy is taking steps towards the green hydrogen mission in China, Norway & Australia respectively Players Plant location Plans & steps taken towards green hydrogen Investments • Cummins Inc. & China Petrochemical Corporation announced a 50:50 joint venture • Investment of ~US$ 47M for manufacturing capacity of 500 • The plant will initially have a manufacturing capacity of 5 00 MW of electrolyzers per year upon • Foshan, MW completion in 2023 China • Plans to expand the capacity to 1 GW by 2027 • Yara and Linde Engineering agreed to build a 24 MW green hydrogen plant in Norway • Value undisclosed • Aim to reduce 41K tonnes of CO₂ emissions annually • Porsgrunn, • PEM electrolysis technology to be adopted Norway • FFG¹ & Toshiba ESS² signed an MoU to explore technical & commercial opportunities in the • Value undisclosed fast-growing green hydrogen sector N/A • The companies will also explore potential collaboration for future sales of solid oxide electrolysis cells • Air Products will build a facility to produce 10 metric tons per day of green liquid hydrogen which will • Value undisclosed • Casa Grande, be functional from 2023 United States • B uilding Saudi Arabia’s flagship 2 GW green hydrogen plant at Noem, which intends to produce • Noem, 650 tonnes of green hydrogen per day from 2026 Saudi Arabia • Announced plans to build a green liquid hydrogen production facility in southwestern USA, which will produce zero-carbon for California and other areas Note(s): ¹Fusion Fuel Green, ²Toshiba Energy Systems & Solutions © 1Lattice | 28 Source(s): Press releases, 1Lattice analysis, 1US$= INR 79.8 Industrial Goods and Se r vices Global green hydrogen scenario Countries like Australia, Chile, Morocco & Spain have high technical potential to produce large volumes of low-cost green hydrogen by 2050 Technical potential for producing green hydrogen under USD 1.5/kg by 2050, in EJ 88 Europe Northeast Asia 21 1,314 2 Middle East & 2,203 684 Rest of Asia North Africa North America 64 2,715 Southeast Asia 1,272 1,114 Sub-Saharan Africa Oceania South America Countries with export potential Countries with sufficient domestic production Countries with reliance on imports Major future importer or exporter of green hydrogen Japan Republic of Korea Europe Australia Chile Morocco Spain China USA Brazil Note(s): 1 EJ (exajoule) = 277,777,777,777.78 Kwh Source(s): IRENA, 1Lattice analysis © 1Lattice | 29 Industrial Goods and Se r vices Global green hydrogen scenario Australia has abundance of natural resources to produce & export green hydrogen; Limited availability of land to set up electrolyzer capacity poses a hindrance Tailwinds and Opportunities Australia Geographical advantage with abundance of natural resources to produce clean hydrogen & scale green Focused hydrogen Hydrogen demand hydrogen economy (FY22) source Expected decline in cost of setting up an electrolysis plant 650 KTPA* Low-carbon - Blue / Green because of cheaper availability of electrolyzers & increasing scale of production & upcoming refined technologies Aim to u se green hydrogen to turn iron ore into green steel. If successful it would enable one of Australia’s biggest Key initiatives export-earning commodities to continue in the net zero era • Investment of US$ 1.4B by the Australian government to build hydrogen industry • Australian Renewable Energy Agency to award US$ 70M funding for two Headwinds and Challenges or more electrolyzerprojects • Green hydrogen project of 9 GW scale planned or under development Limited land (only 3% of total area) suitable for green hydrogen production after considering water, ports, pipelines & electricity infrastructure Key projects • A ustrom Hydrogen to build solar farm and battery facility with 3,600 MW Scope of improvement in technology required to produce capacity with potential hydrogen production of 200K tonnes per year green hydrogen at low cost • Hydrogen Park Gladstone Hub to install electrolyzer plant with a capacity of ~3 GW and produce up to 5K tonnes of ammonia Absence of large-scale manufacturing capacity & freshwater • The Desert Bloom Hydrogen project aims to use solar power to split water to to perform electrolysis make green hydrogen Note(s): *Kilo tonnes per annum © 1Lattice | 30 Source(s): Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario Chile has ample availability of solar & wind energy to manufacture green hydrogen at low cost; shortage of comprehensive government regulations pose a challenge Tailwinds and Opportunities Chile Region with greatest possibility of producing green hydrogen at low cost due to ample availability of solar & Focused hydrogen Hydrogen demand wind energy (FY22) source Favourable energy policy leading to mobilized renewable 58.5 KTPA* Clean - Green industry resulting in low cost of renewable-sourced electricity Incentive for investments in renewable projects because of supportive government policies Key initiatives Exemption on transmission tolling & VAT charges on critical imported equipment & other services required for construction • Aims towards a carbon-neutral country by 2050 through a series of of renewable energy projects projects promoted by Enel Green Power, Linde, Engie, Air Liquide, GNL Quintero, and CAP, attracting investments of US$1B • Launched green hydrogen strategy in 2020 with an aim to reach 5 GW of electrolyzer capacity by 2025 and 25 GW by 2030 Headwinds and Challenges • Aims to produce the world’s cheapest hydrogen by 2030 and become one of the world’s top 3 hydrogen fuel exporters by 2040 Unavailability of fresh water in the southern parts of the country required to perform electrolysis Key projects S hortage of comprehensive & complete regulations • Project HyEx - Green hydrogen production led by the French Engie , seeks to regarding the green hydrogen industry generate an industrial pilot-scale plant in the Antofagasta region • H2V CAP - seeks to implement a green hydrogen plant in Biobío region in order to produce 1,550 tonnes of green hydrogen per year and reduce Insuffiicient coordination between supply-demand sides & more than 1,61,000 tonnes of CO₂ emission per year various technological & financial risks associated with investments in green hydrogen Note(s): *Kilo tonnes per annum © 1Lattice | 31 Source(s): Press releases, Secondary research, European Electrolyser Summit report, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario China’s rich renewable energy base enables it to produce green hydrogen at low cost; however, is behind developed countries in related R&D & technological advancements Tailwinds and Opportunities China Huge potential for green hydrogen production with the world's largest renewable power capacity Focused hydrogen Current hydrogen source demand Low cost of production from photovoltaic electrolysis in Clean - Green 20 MTPA* sunlight-rich Xinjiang region Rising hydrogen-related R&D expenditure with government schemes for funding hydrogen technology Key initiatives Strong state-led support at each stage of the value chain, • Stepping up efforts for transition to cleaner fuels under its net-zero emissions from research to technology, production, and applications goal by 2060 • Prioritizing hydrogen as an emerging industry under the 14th five-year plan with the following aims: ▪ To secure energy supply Headwinds and Challenges ▪ To speed up decarbonization efforts ▪ To adopt more efficient energy use practices through 2025 Lags countries such as Europe, United States & Japan in R&D & advanced technological capabilities Key projects Shortage of a systematic & comprehensive hydrogen strategy to promote its domestic production • China's state-owned oil giant Sinopec has recently announced country's first 1 0K tonne photovoltaic green hydrogen demonstration project Coal-based hydrogen costs roughly half of renewable-based • State-owned utility Beijing Jingneng to spend US$ 3B on a 5 GW hybrid hydrogen. This cost disadvantage hampers green hydrogen solar, wind, hydrogen, and storage facility in northern China development due to insufficient stringent government policies • State Power Investment Corp (SPIC) kicked off a flagship demonstration to mix green hydrogen with natural gas at Chaoyang district, Beijing Note(s): *Million tonnes per annum © 1Lattice | 32 Source(s): Press releases, Secondary research, CSIS analysis, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario Europe is head starting with strong electrolyzer manufacturing capabilities; reluctance from investors to invest in unproven technology acts as a barrier Tailwinds and Opportunities Europe Support from EU programs & funds for hydro technologies used for manufacturing green hydrogen Focused hydrogen Hydrogen demand (FY22) source Offshore winds Low-carbon - Blue / Green 9-11 MTPA* head start in developing equipment manufacturing capacities (producing & selling electrolyzers) Key initiatives Spike in natural gas prices in 2021, making green • Target of 4 0 GW electrolyzer capacity by 2030 & an annual production hydrogen relatively affordable of ~10 MT hydrogen • As part of Fit for 55 policy, EC¹ proposed a RE² Directive modification to mandate 50% renewable hydrogen consumption in industry by 2030 • Under ReFuel Aviation Initiative, EC proposed a rising quota for synthetic Headwinds and Challenges aviation fuels (from a 0.7% share in 2030 to 28% in 2050) Reluctance from investors to provide funding for a relatively unproven technology for green hydrogen & perceived Key projects shortage of financial returns • Hydeal Ambition project producing 3.6 MT green hydrogen in 2030 with 95 Absence of cheap & effective Carbon capture utilization & GW solar & 67 GW electrolyzer capacity, in an integrated system spanning storage (CCUS or CCS) technologies from Spain to France & Germany • Development of 600 MW electrolyzer by Orsted & EDF under Westkuste Availability of fewer natural resources required to produce 100 project in Germany green hydrogen • NortH2: Europe’s largest electrolyzer project with 10 GW capacity powered by offshore wind proposed by Shell-led conglomerate in The Netherlands Note(s): *Million tonnes per annum, ¹European Commission, ²Renewable Energy © 1Lattice | 33 Source(s): Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario USA plans to establish multiple clean hydrogen hubs to boost production of green hydrogen; insufficient incentives limits the development of clean hydrogen industry Tailwinds and Opportunities USA Businesses' inclination to transform their operations hit net zero targets , with hydrogen emerging as a frontrunning Focused hydrogen Hydrogen demand solution to cut emissions (FY22) source Low-carbon - Blue / Green 10 MTPA* Presence of active & dedicated pipeline infrastructure to distribute hydrogen. Developments of several new hydrogen pipelines Key initiatives with access to hydrogen fuelling stations. Significant growth expected in the coming years for hydrogen fuel • Clean hydrogen manufacturing & recycling program to support the hydrogen supply chain by FY26 and investing US$ 500M • Establishment of ~4 regional clean hydrogen hubs by FY26 with investments of ~US$ 8B • Signed the Infrastructure Investment & Jobs Act into law in November 2021 to accelerate the development of clean hydrogen technology with Headwinds and Challenges investments of US$ 9.5B Limited pool Key projects • CF Industries is building a green ammonia project at Donalsonville Nitrogen Complex to produce ~20K tonnes of green ammonia per year Insufficient regulations & proper incentives limit the development of clean hydrogen industry. Green criteria for • Hydrogen EarthShot sets an ambitious "111 goal": to reduce the cost of clean hydrogen projects consistent with global standards should hydrogen to US$ 1 per kilogram in 1 decade be defined by the government • US start-up Green Hydrogen International (GHI) announced a 60 GW renewable H2 project in Texas powered by wind & solar energy Note(s): *Million tonnes per annum, ¹Fuel Cell Electric Vehicles © 1Lattice | 34 Source(s): UREL, Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario UAE can capitalize on its solar conditions & existing industrial capacity; Limited access to freshwater poses a challenge to green hydrogen production Tailwinds and Opportunities UAE Access to excellent solar conditions to capitalize on & optimize costs for producing green hydrogen using solar Focused hydrogen Hydrogen demand energy (FY22) source Low-carbon - Blue / Green Availability of vast land, existing industrial capacity, proximity to ports, & openness to international partnerships Export opportunity for GCC countries¹ for ~200 MT green Key initiatives hydrogen production worth US$ 300B by 2050 • UAE's hydrogen roadmap aims to establish the country as a leader in blue & green hydrogen export & capture 25% of the global low-carbon hydrogen market by 2030 • Plans to shift the production of grey hydrogen to green & blue hydrogen in Headwinds and Challenges a plant that currently produces 300 KTPA of hydrogen Shortage of freshwater access for industrial usage is a Key projects problem for UAE due to its exposure to limited water bodies • Helios Green Fuel Project announced, a US$ 5B green hydrogen & green Expected increase in green hydrogen’s cost of production ammonia plant powered entirely by solar and wind energy. Plant expected to due to setting up of filtering plants to desalinate salty ocean start operation in 2025 in Neom water to make it suitable for performing electrolysis • Country’s first green hydrogen project having a capacity of 1.2 MW in Dubai commissioned last year No formal pledge by the government to phase out coal • Korea Electric Power Corporation, Samsung C&T Corporation, Korea Western usage is an indication that coal can be used for industrial Power, & Petrolyn Chemie to build green hydrogen & green ammonia usage at will production plant in UAE worth US$ 1B Note(s): 1Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, & UAE © 1Lattice | 35 Source(s): IHS Markit clean energy report, Press releases, Secondary research, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario Egypt has huge potential for green hydrogen production with the world’s largest renewable power capacity; shortage of freshwater supply poses a big challenge Tailwinds and Opportunities Egypt Declining costs of renewable electricity and electrolyzers enable Egypt use renewable energy to power the Focused hydrogen Current hydrogen electrolyzers and produce green hydrogen source demand >1.4 MTPA* Clean - Green Unique renewables profile with strong solar and wind loads and proximity to markets with a hydrogen deficit make it an ideal location to produce & export green hydrogen Rise in oil & natural gas prices due to recent Key initiatives Russian-Ukrainian war leading to many energy-dependent countries like Egypt venturing into green hydrogen • Announced a new 100 MW project for producing green ammonia in December 2021 • Egypt government plans to release a US$ 40M hydrogen plan • Government to announce various green hydrogen projects at the COP27 UN Headwinds and Challenges Climate Change Conference , to be held in Sharm El Sheikh in November 2022 Shortage of freshwater supply due to Nile water issue with Ethiopia Key projects • In order to decrease the water demand-supply gap, Egypt plans to develop several desalination plants to • ReNew Power signed MOU with Egyptian government agencies and a produce clean water from seawater, which could sovereign fund to set up green hydrogen manufacturing plant with 20 KTPA increase the cost of producing green hydrogen capacity at the Suez Canal Economic Zone Shortage of suitable infrastructure; need for separate • Fertiglobe signed an agreement with Scatec, & the Sovereign Fund of Egypt infrastructure to promote large-scale hydrogen production (“TSFE”) to develop a 50-100 MW electrolysis plant at EBIC in Egypt to produce green hydrogen as a feedstock for ~90 KTPA of green ammonia Absence of local regulations & suitable policies to encourage • Abu Qir Fertilizers and Chemicals Industries studying a project to produce green investors to invest in green hydrogen sector hydrogen & green ammonia in cooperation with French oil and gas giant Note(s): *Miliion tonnes per annum © 1Lattice | 36 Source(s): Press releases, Secondary research, European Electrolyser Summit report, 1Lattice analysis Industrial Goods and Se r vices Global green hydrogen scenario Developing clear roadmaps, providing incentives & mobilizing investments are key actions recommended to promote truly carbon-free global hydrogen production Create incentives Provide innovation support Mobilize investments • Measures to facilitate adoption of low-carbon • Continuous innovation to reduce costs & increase hydrogen to replace unabated fossil-based the competitiveness of hydrogen technologies • Policy framework to stimulate demand & alternatives prompt investment in low-carbon • Larger R&D budgets and support to ensure that ▪ To close the price gap between cost of production plants, infrastructure, & key hydrogen technologies reach the using low-carbon hydrogen & unabated manufacturing capacity commercialization phase as soon as possible fossil-based hydrogen • Providing tailor-made support to selected • Wider adoption , combined with other policy shovel-ready flagship projects to kick-start instruments such as auctions, & quotas can help scaling up of low-carbon hydrogen de-risk investments Develop strategies & roadmap Establish regulation regime • National hydrogen strategies & • An international agreement on a roadmaps with concrete targets for methodology to calculate the carbon deploying low-carbon production footprint of hydrogen production ▪ To build stakeholder confidence ▪ To ensure truly carbon-free in low-carbon hydrogen market hydrogen production Recommended actions ▪ To create momentum and ▪ To develop global hydrogen trigger more investments to market to promote low-carbon scale up & accelerate and green hydrogen deployment Source(s): IEA, 1Lattice analysis © 1Lattice | 37 We are here for you Let us know how we can meet your business requirement? Abhishek Maiti Connect now Director Vaishnav Kumar Rai 1Lattice Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 Gurugram Bengaluru New Delhi Mumbai www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. Our team Abhishek Maiti Abhilasha Jaju Vaibhav Tamrakar Praneet Singhal Industrial Good & Services, Financial Services Financial Investors Technology & Internet Technology & Internet 6.5+ yrs. of experience 9+ yrs. of experience 13+ yrs. of experience 16+ yrs. of experience BITS Pilani, IIM Lucknow IIT Bombay NMIMS IIT Delhi, IIM Indore Roma Dixit Arindam Gupta Ashish Dhir Parul Garg Financial Investor Group, Healthcare & Lifesciences Consumer & Retail Consumer Consumer & Retail 25+ yrs. of experience 25 yrs. of experience 5+ yrs. of experience 14+ yrs. of experience Faculty of Management Masters of Business Administration from NIT Kurukshetra, ICFAI Business School Studies, New Delhi Lancaster University Management School, University of Delhi UK Harsh Salgaonkar Kiran Achanta Tarak Pandey Aastha Singh Technology & Internet Financial Services Financial Investor Group, Financial Services Consumer & Retail 5+ yrs. of experience 6+ yrs. of experience 6+ yrs. of experience 1.5+ yrs. of experience Mumbai University VIT University, IMT Ghaziabad SRM University, Chennai LSR, Delhi 1Lattice We enable better decision making. Technology-backed business support that helps you ENABLE BETTER 500+ 30% annual engagements faster to outcomes DECISIONS Deep on-ground insights that you can act on 8 600+ practices years domain expertise 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy One-ness of data and people networks to harness the collective power of data, network, and technology 100+ 2.5M towns & cities panel members Multi-faceted teams offering a stack of consulting, advisory, and research services 15+ 40:60 languages covered she/he ratio The team at appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, Tower A, 4th Floor, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District DLF Centre Court, Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 DLF Phase 5, Sector 42, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram - 122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Lattice Technologies Pvt. Ltd., Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025