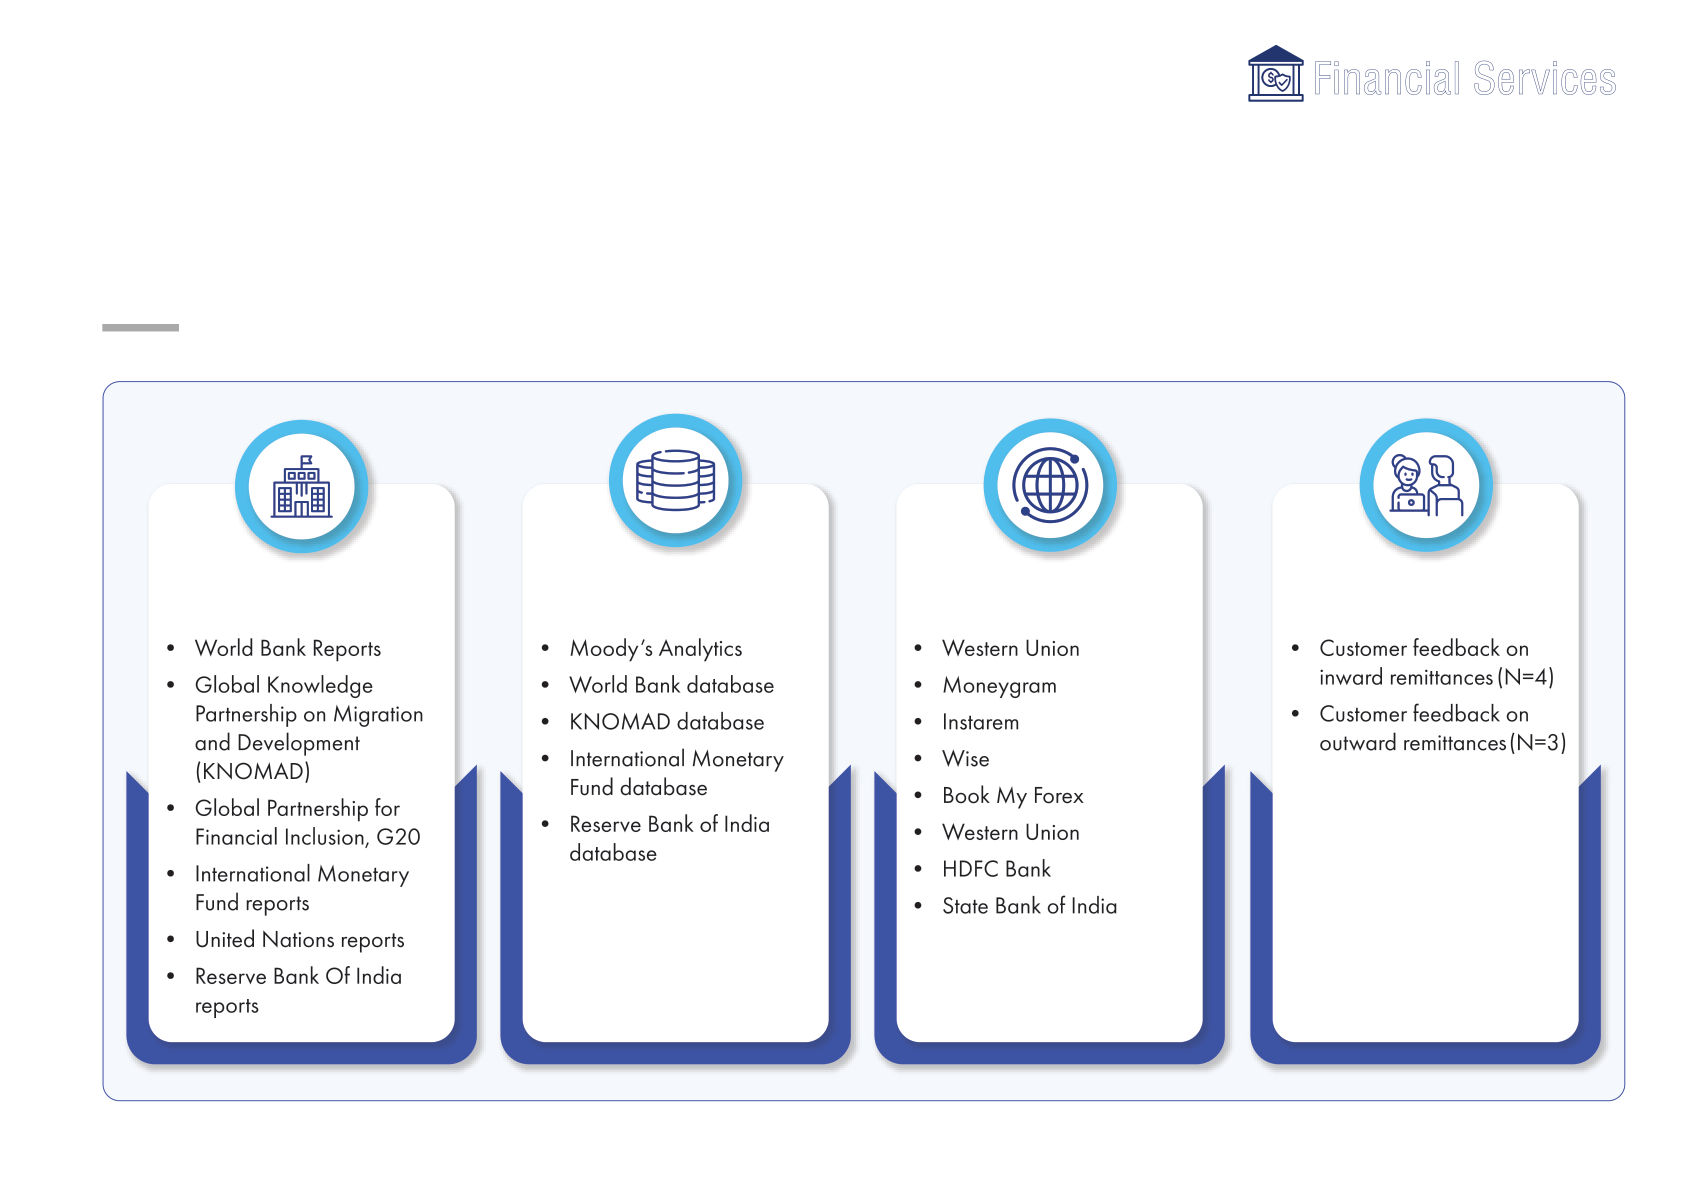
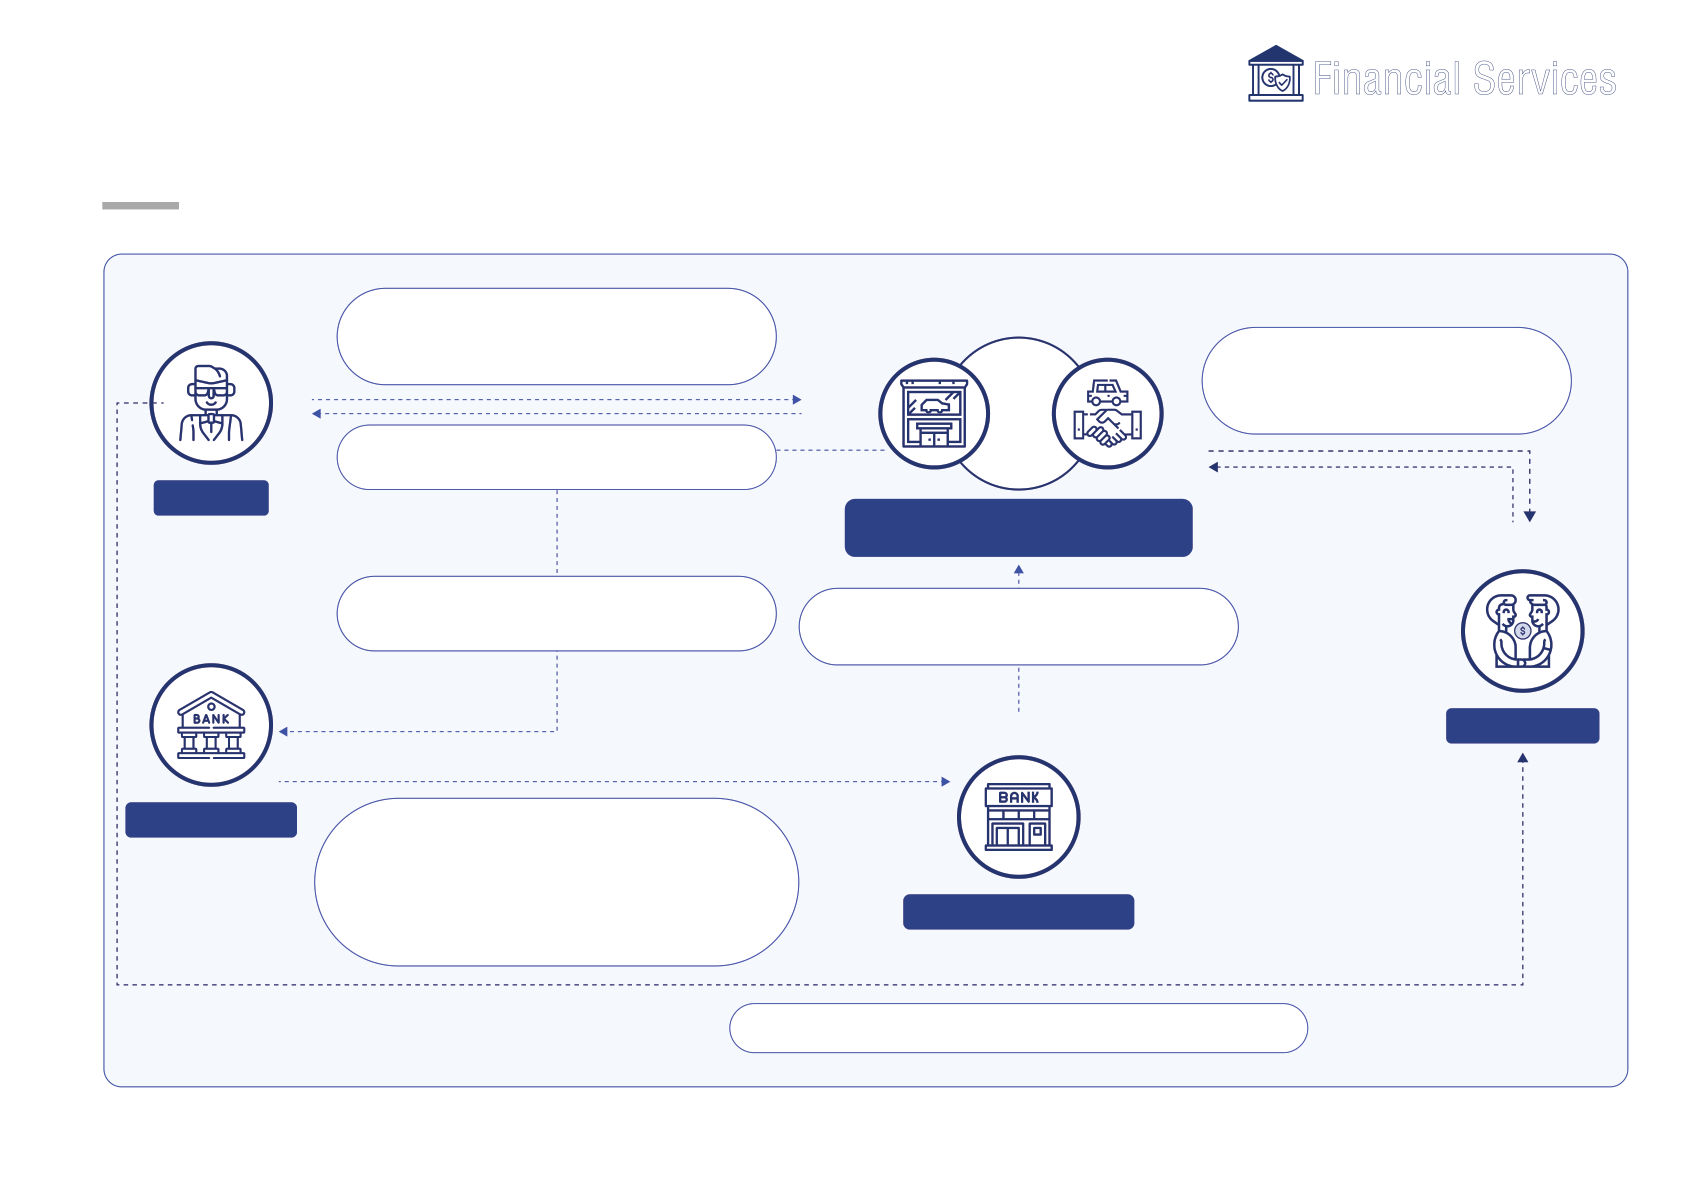
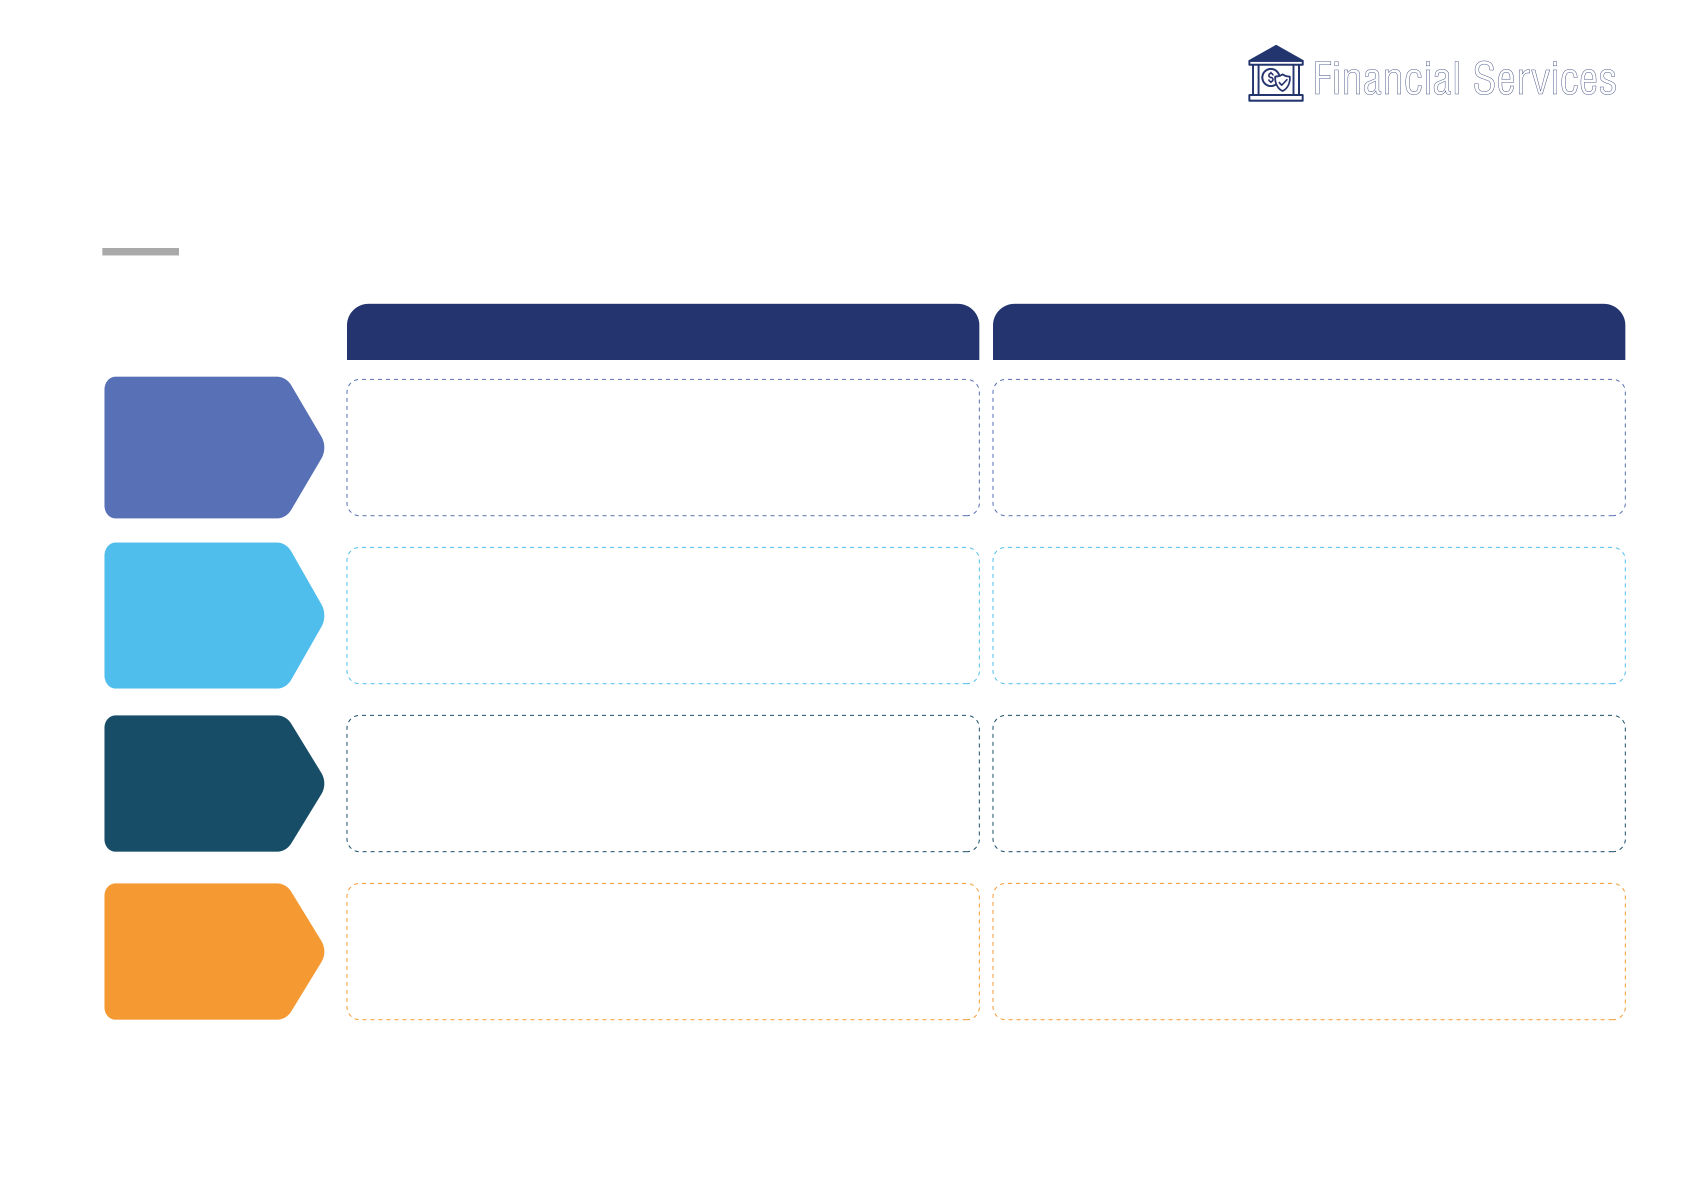
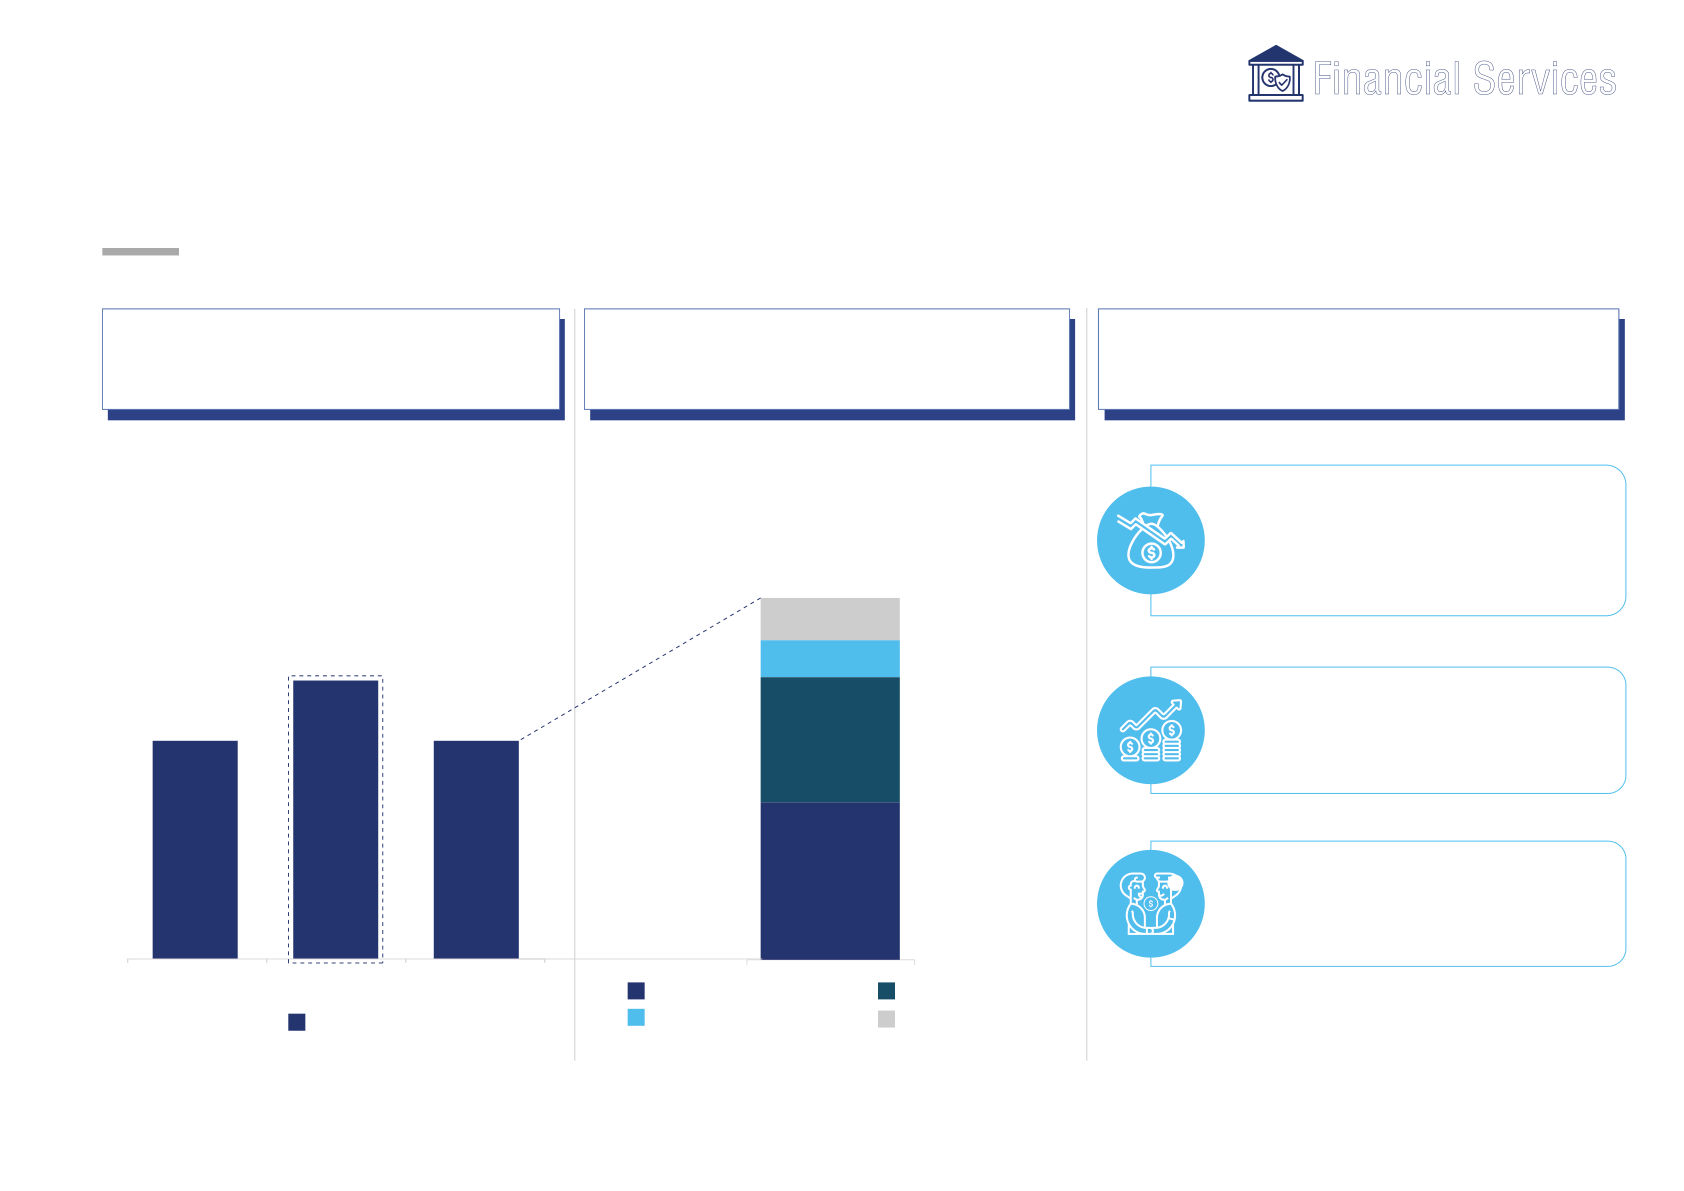
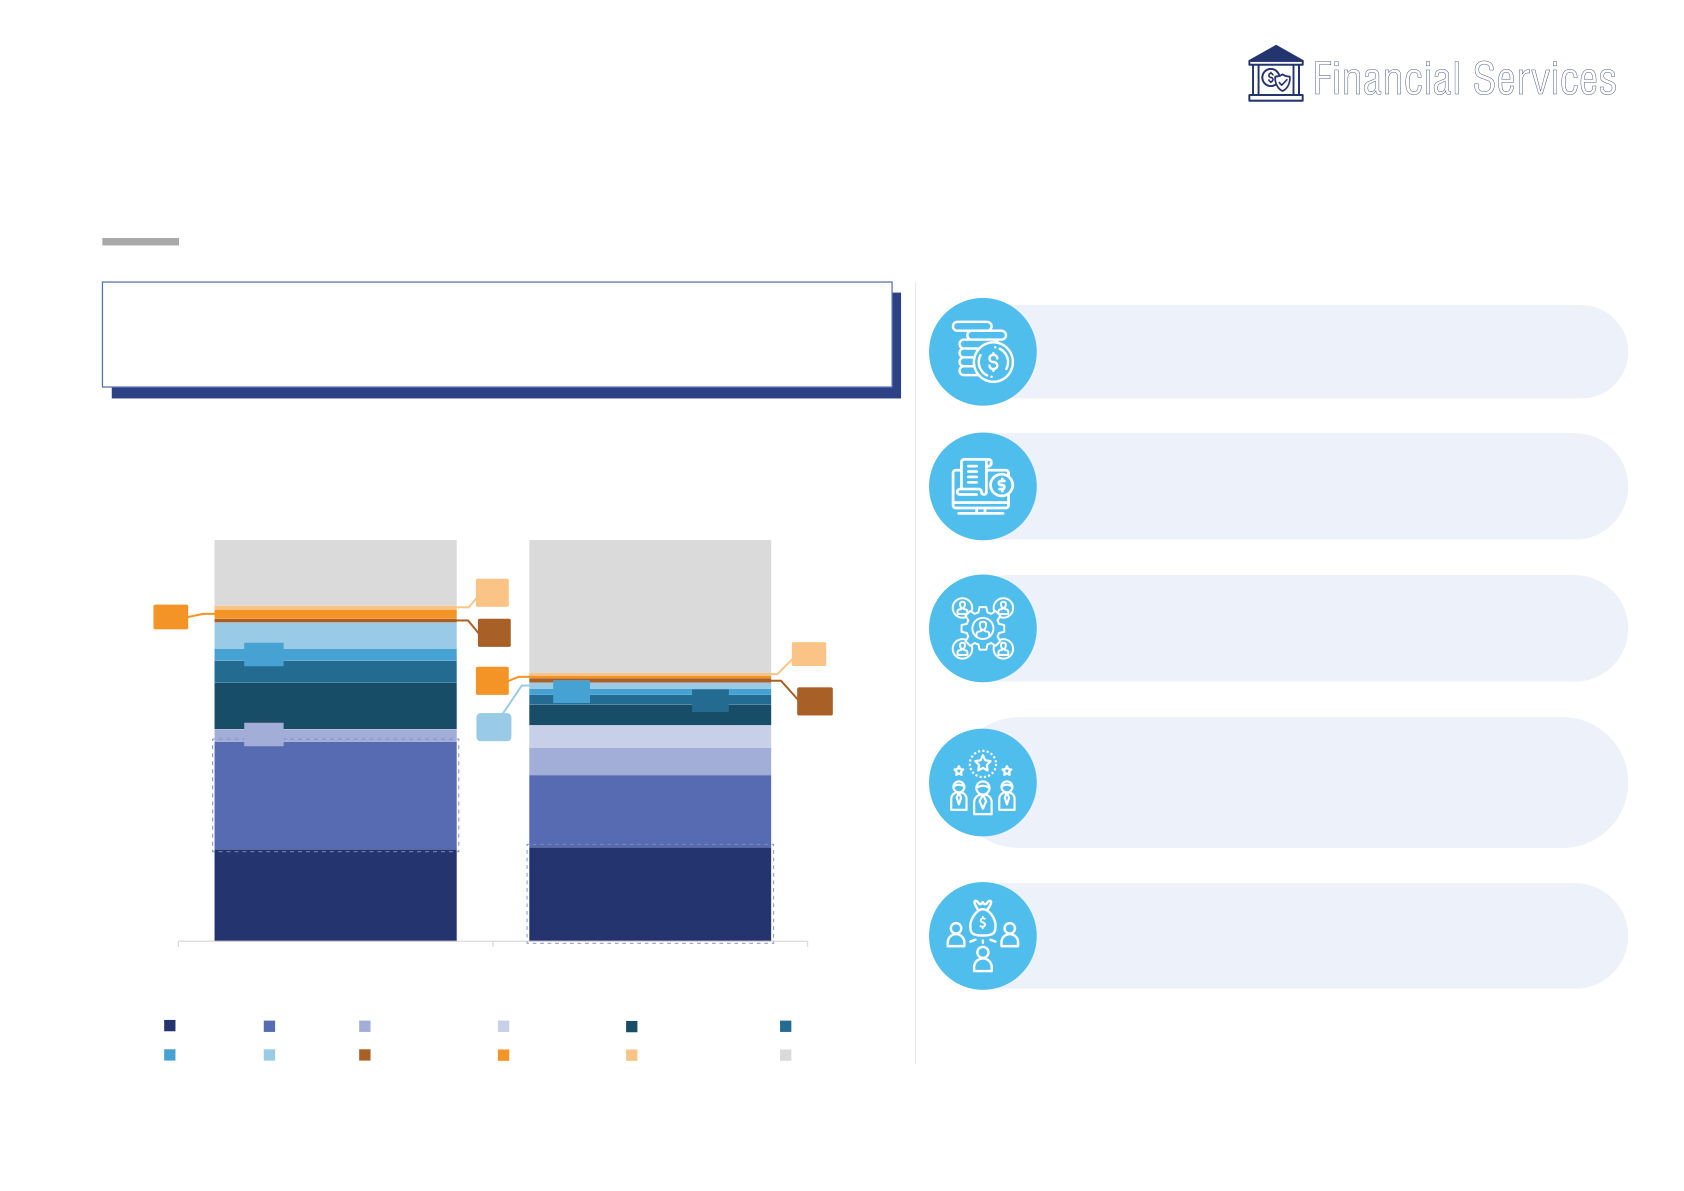
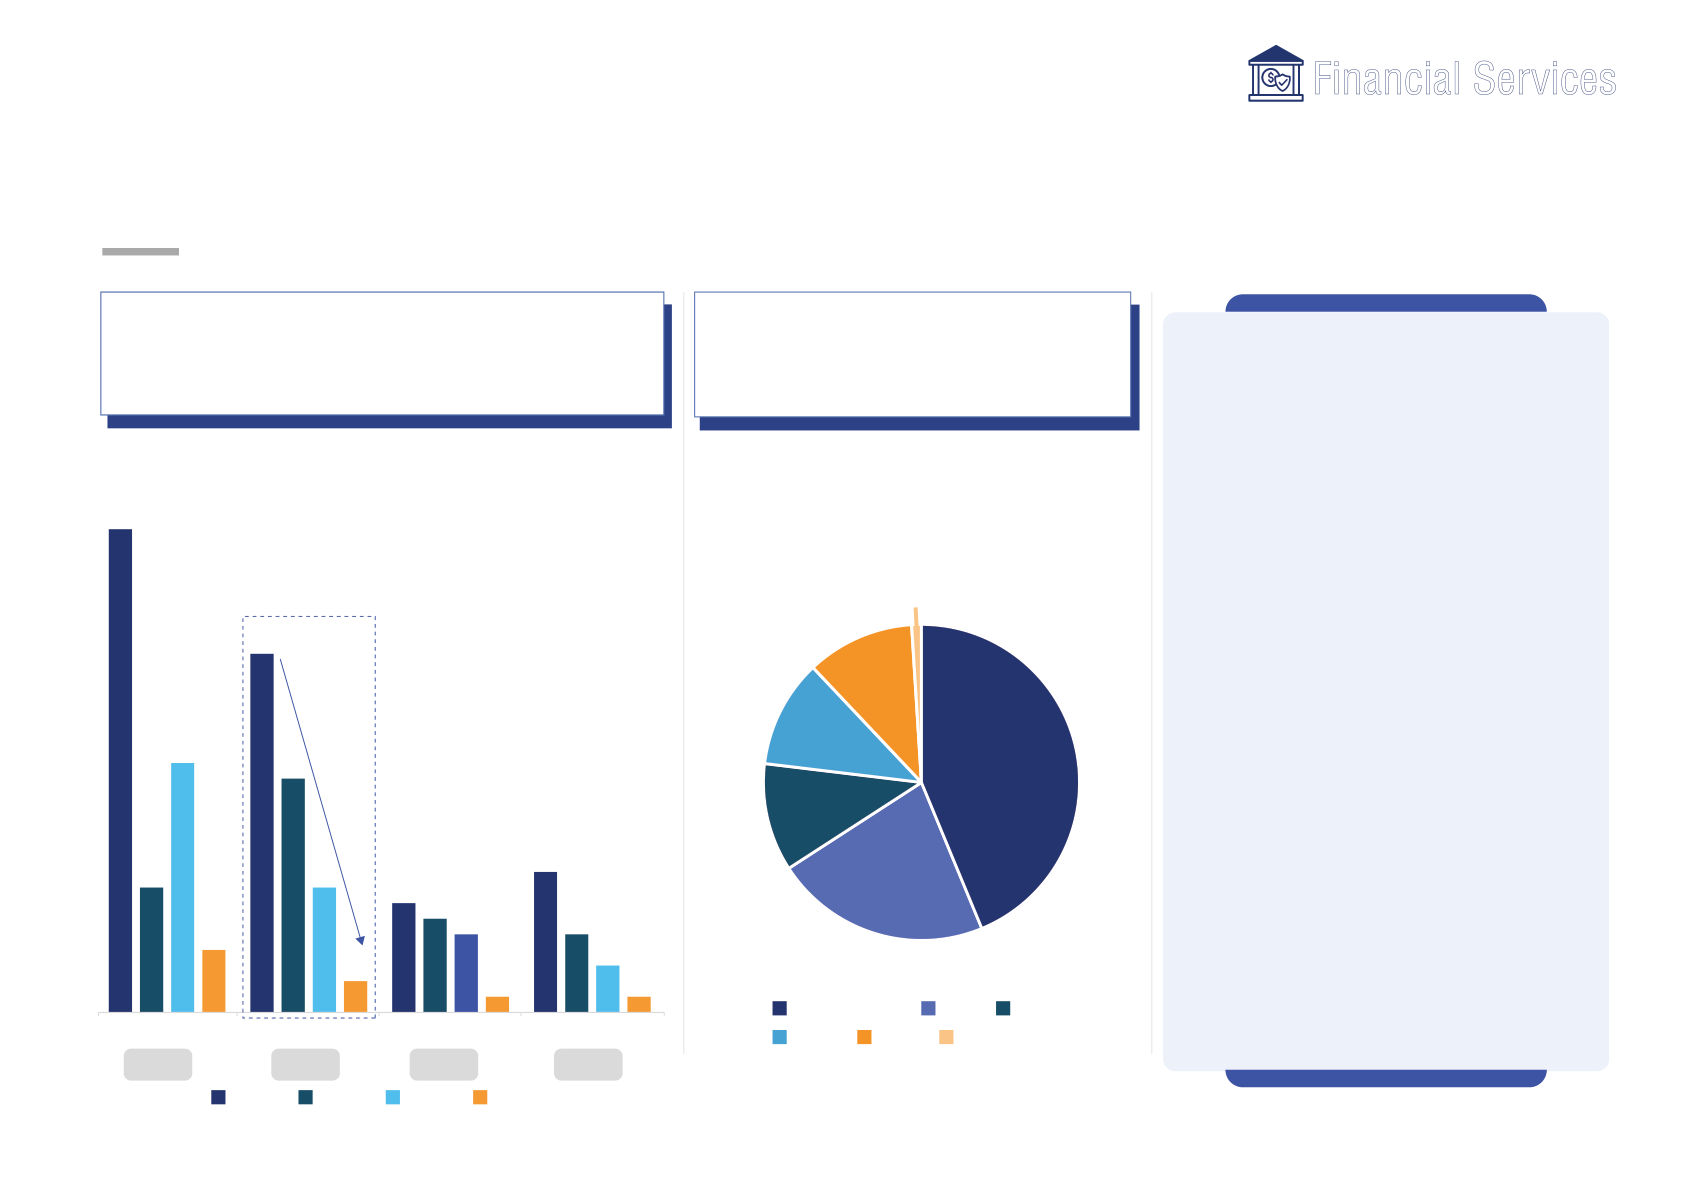
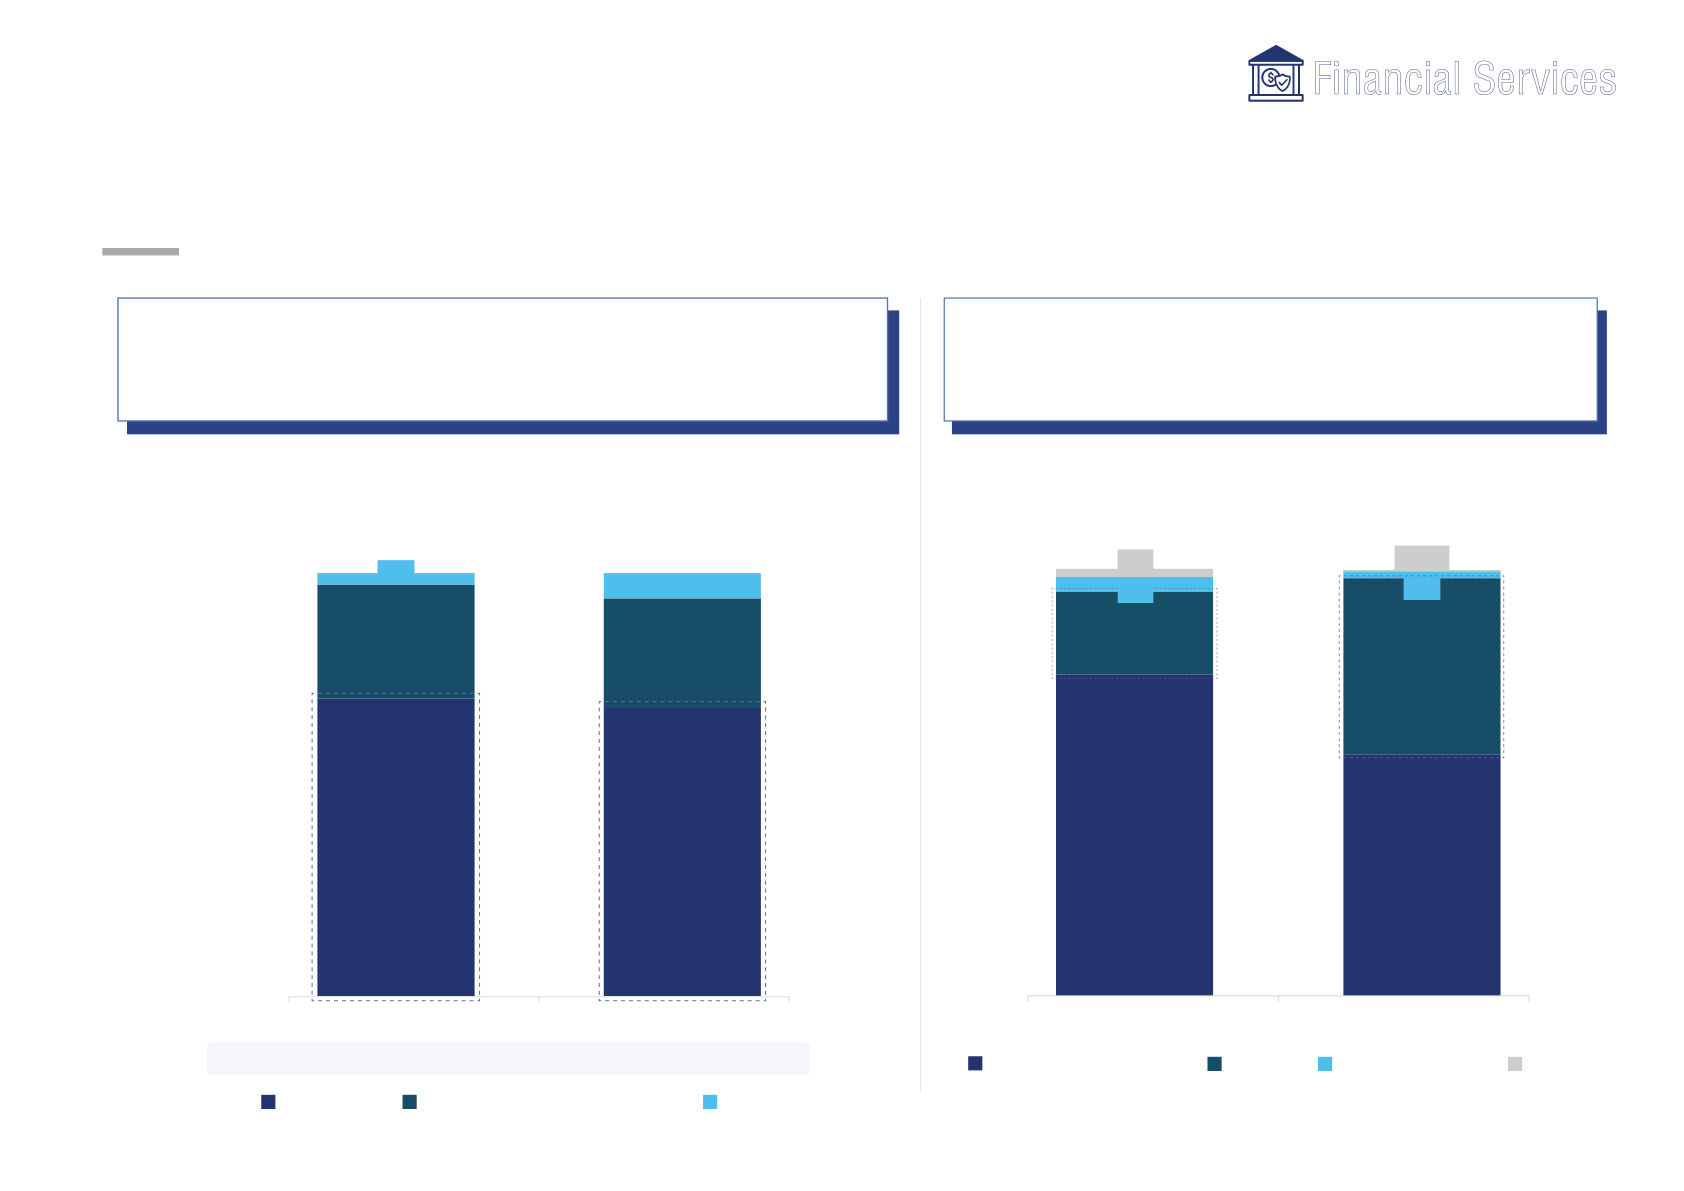
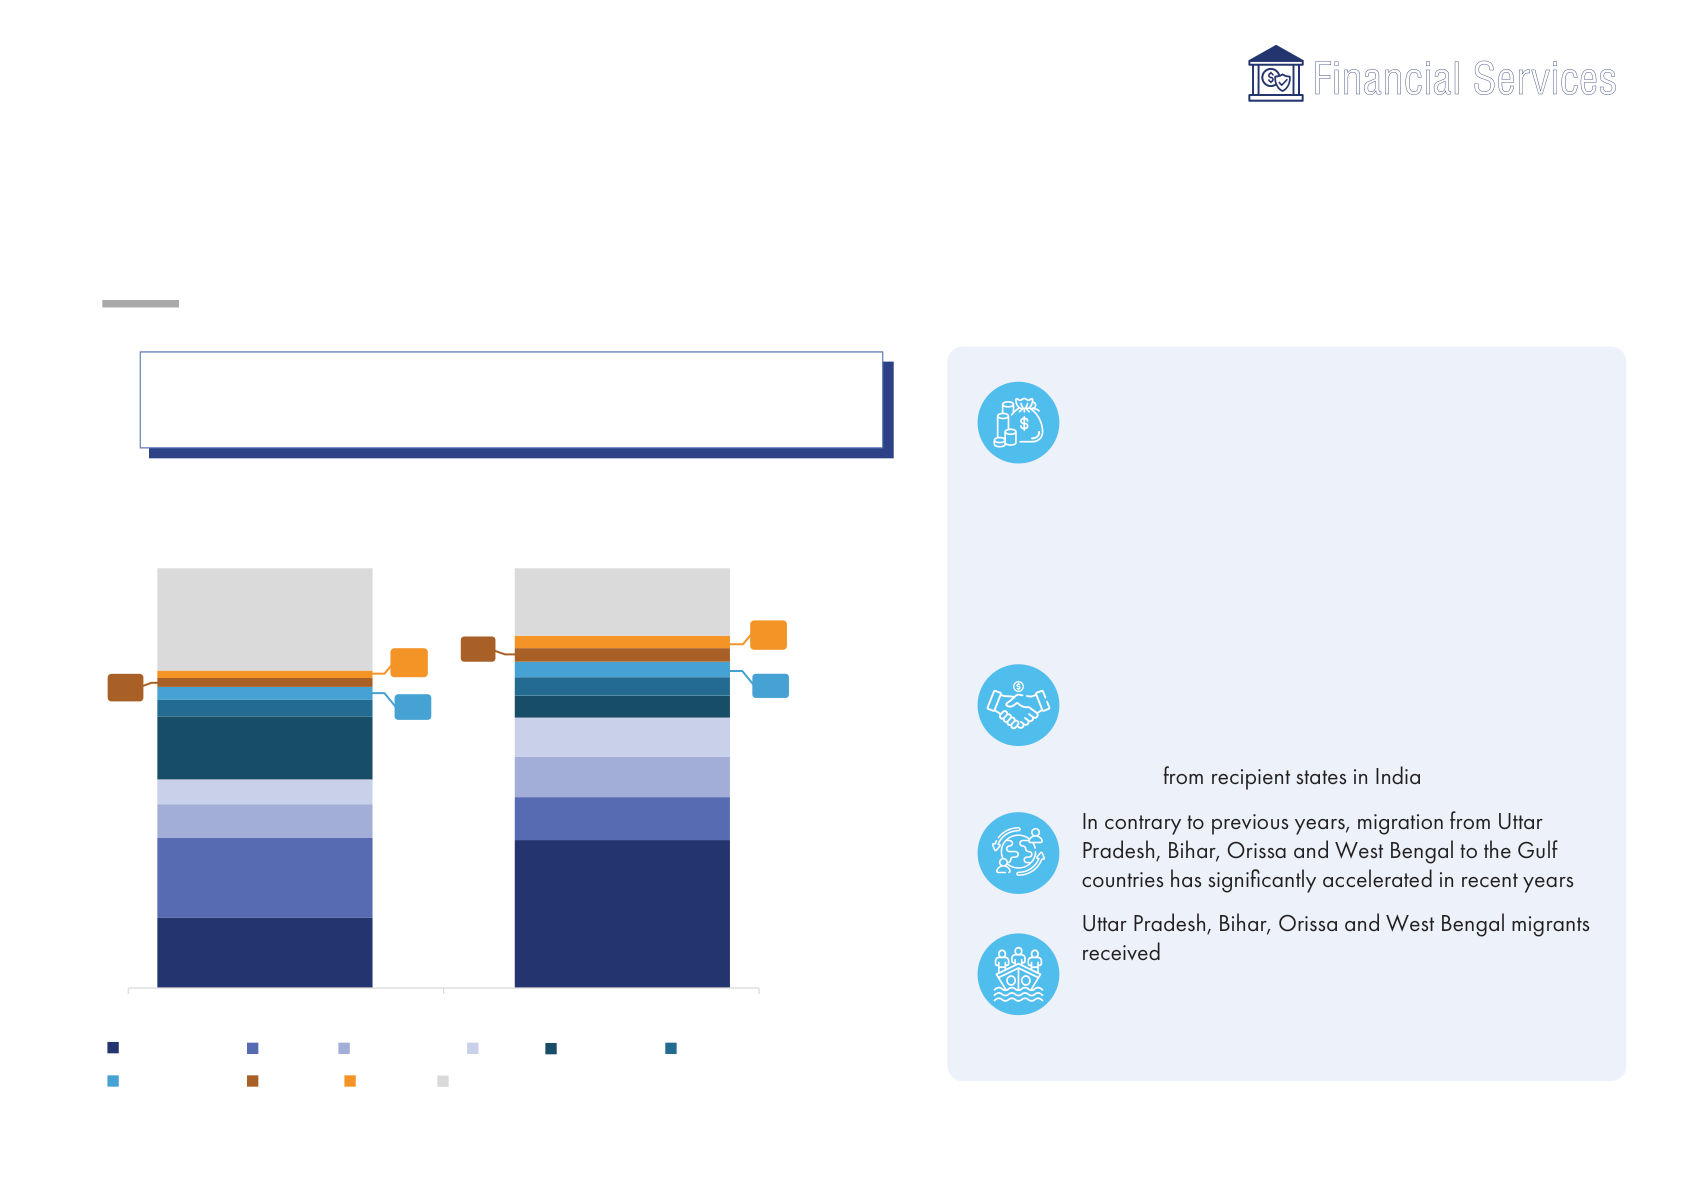
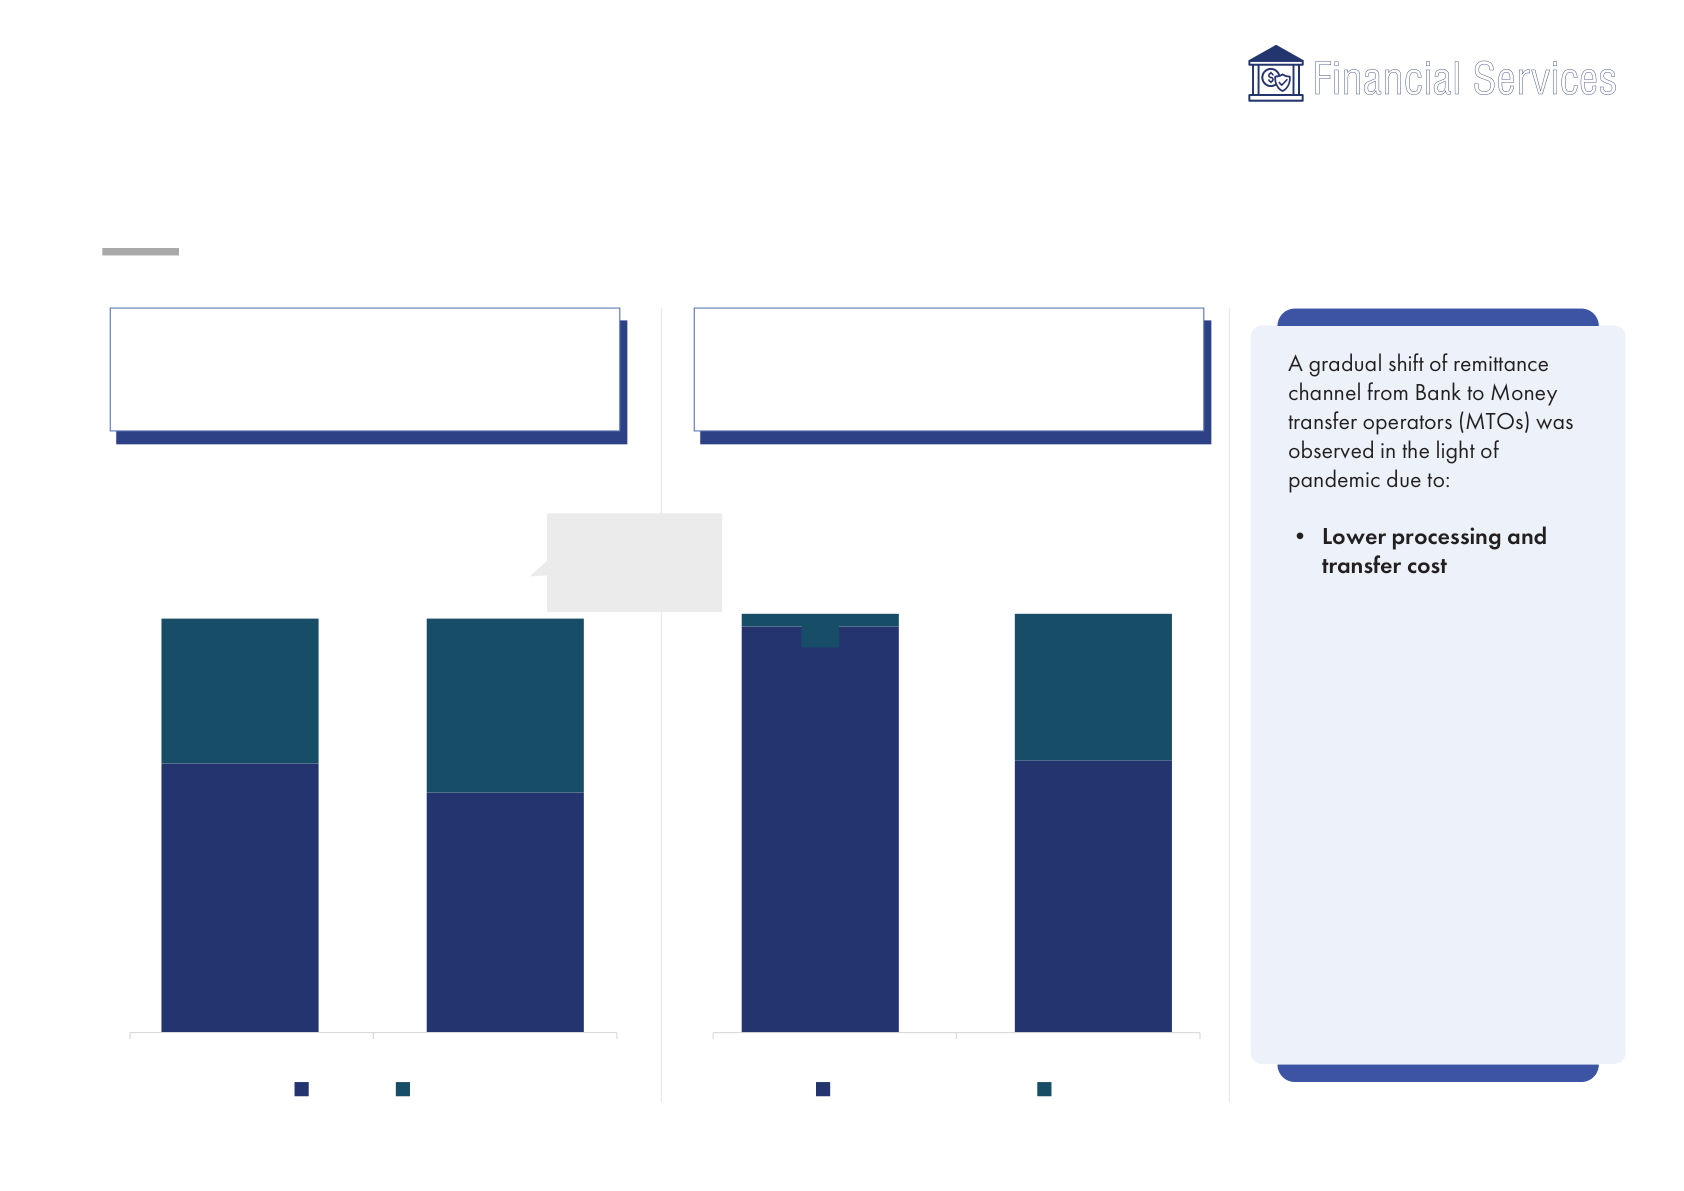
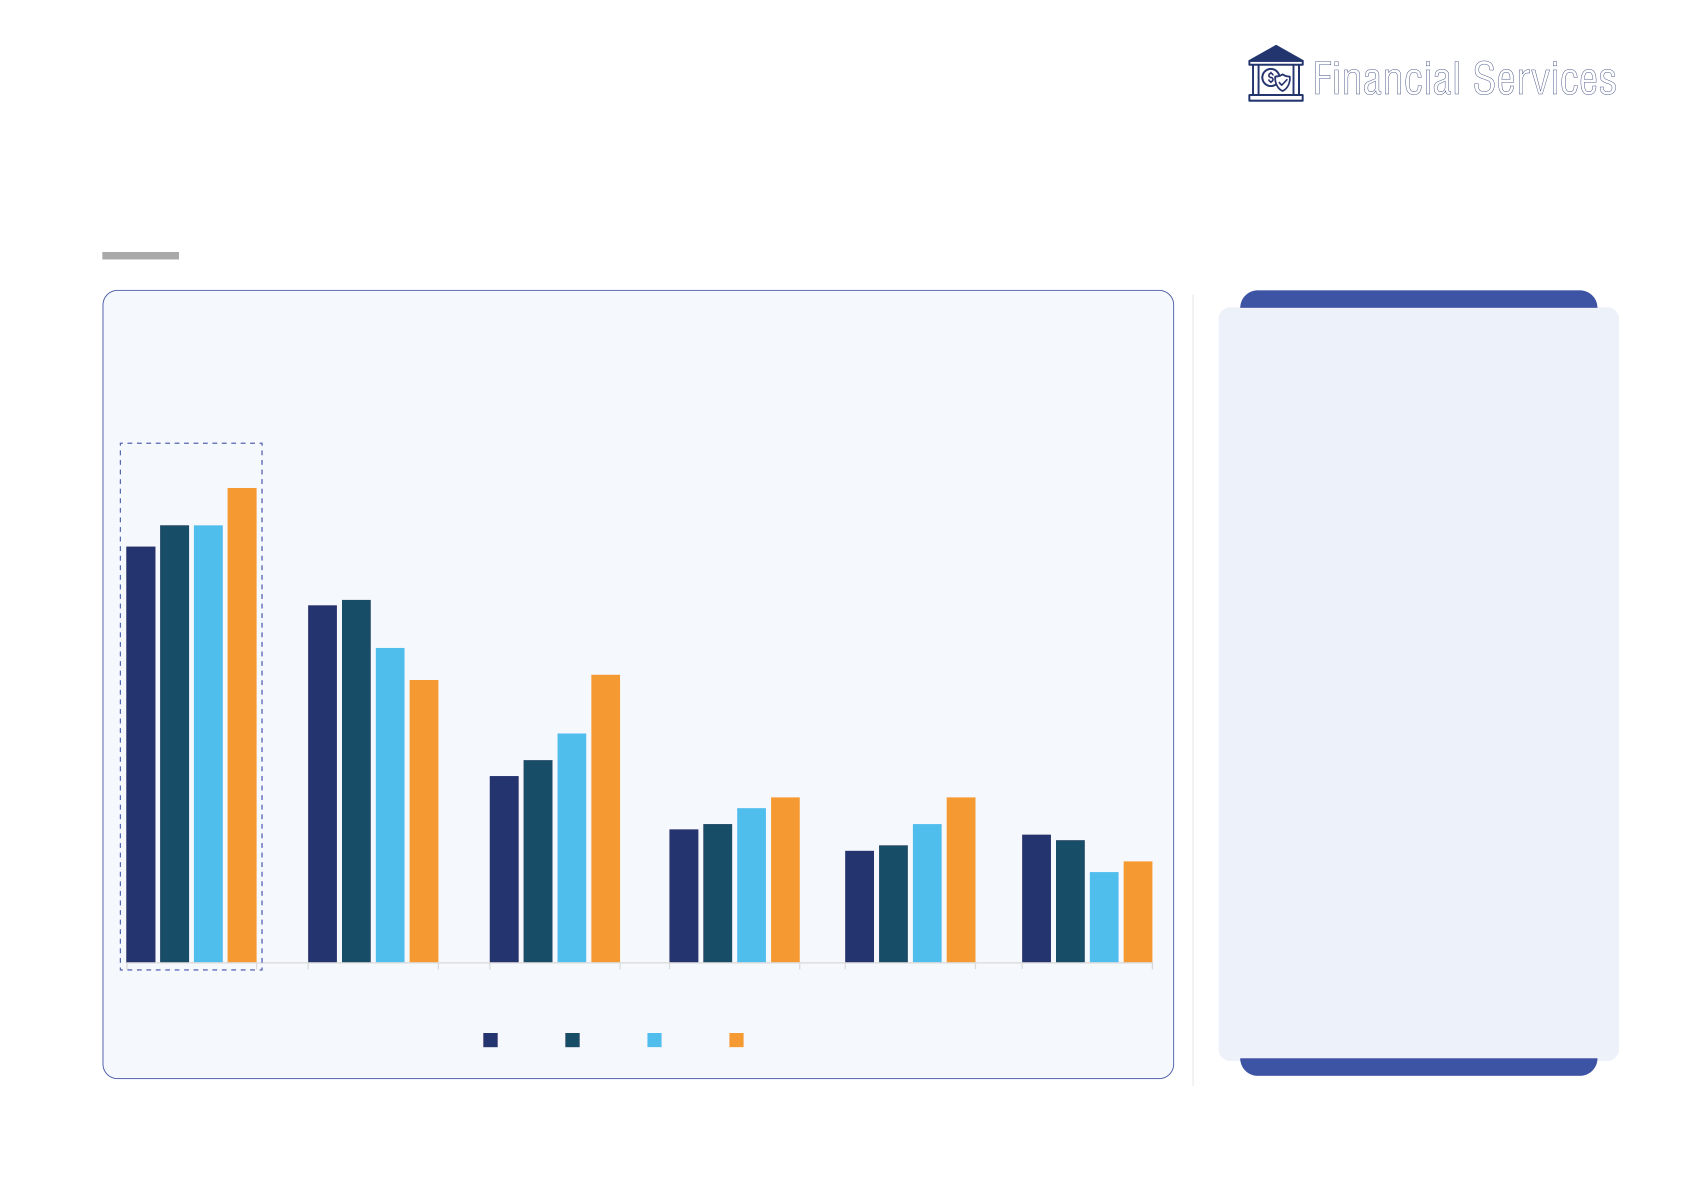
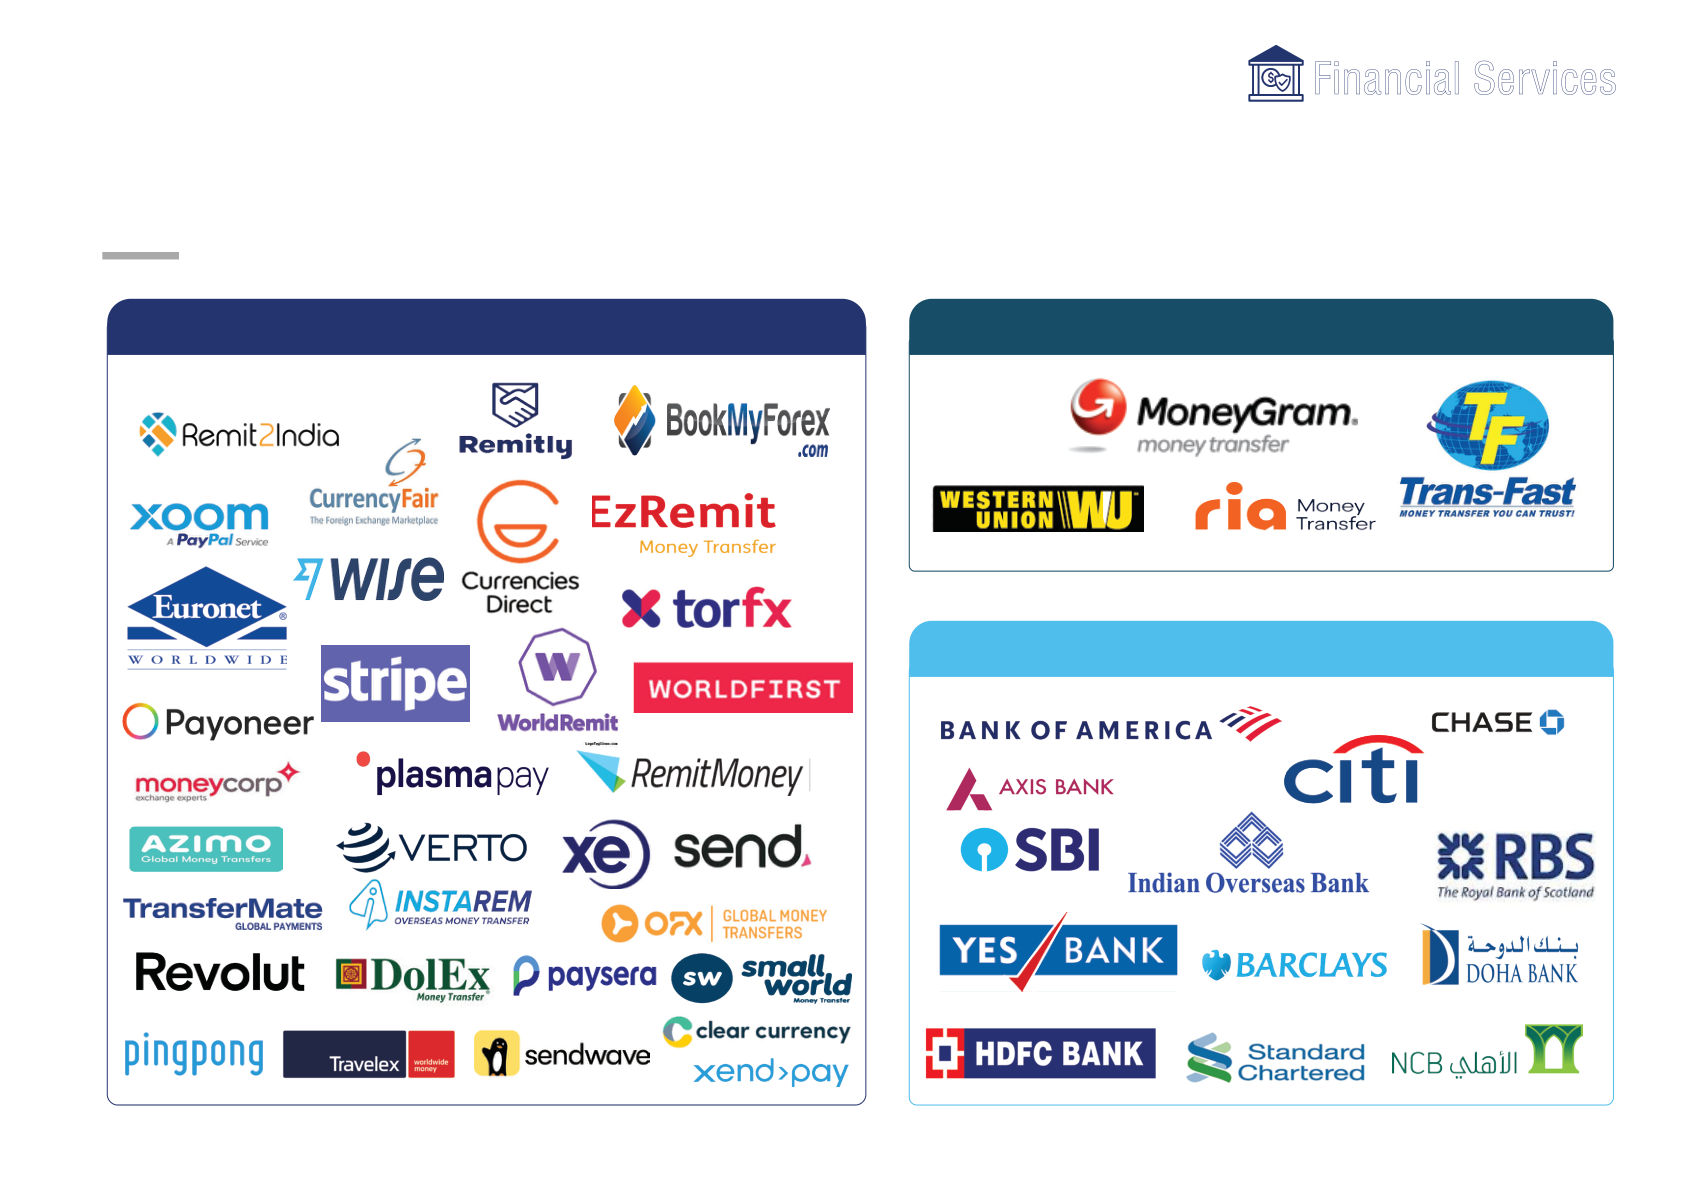
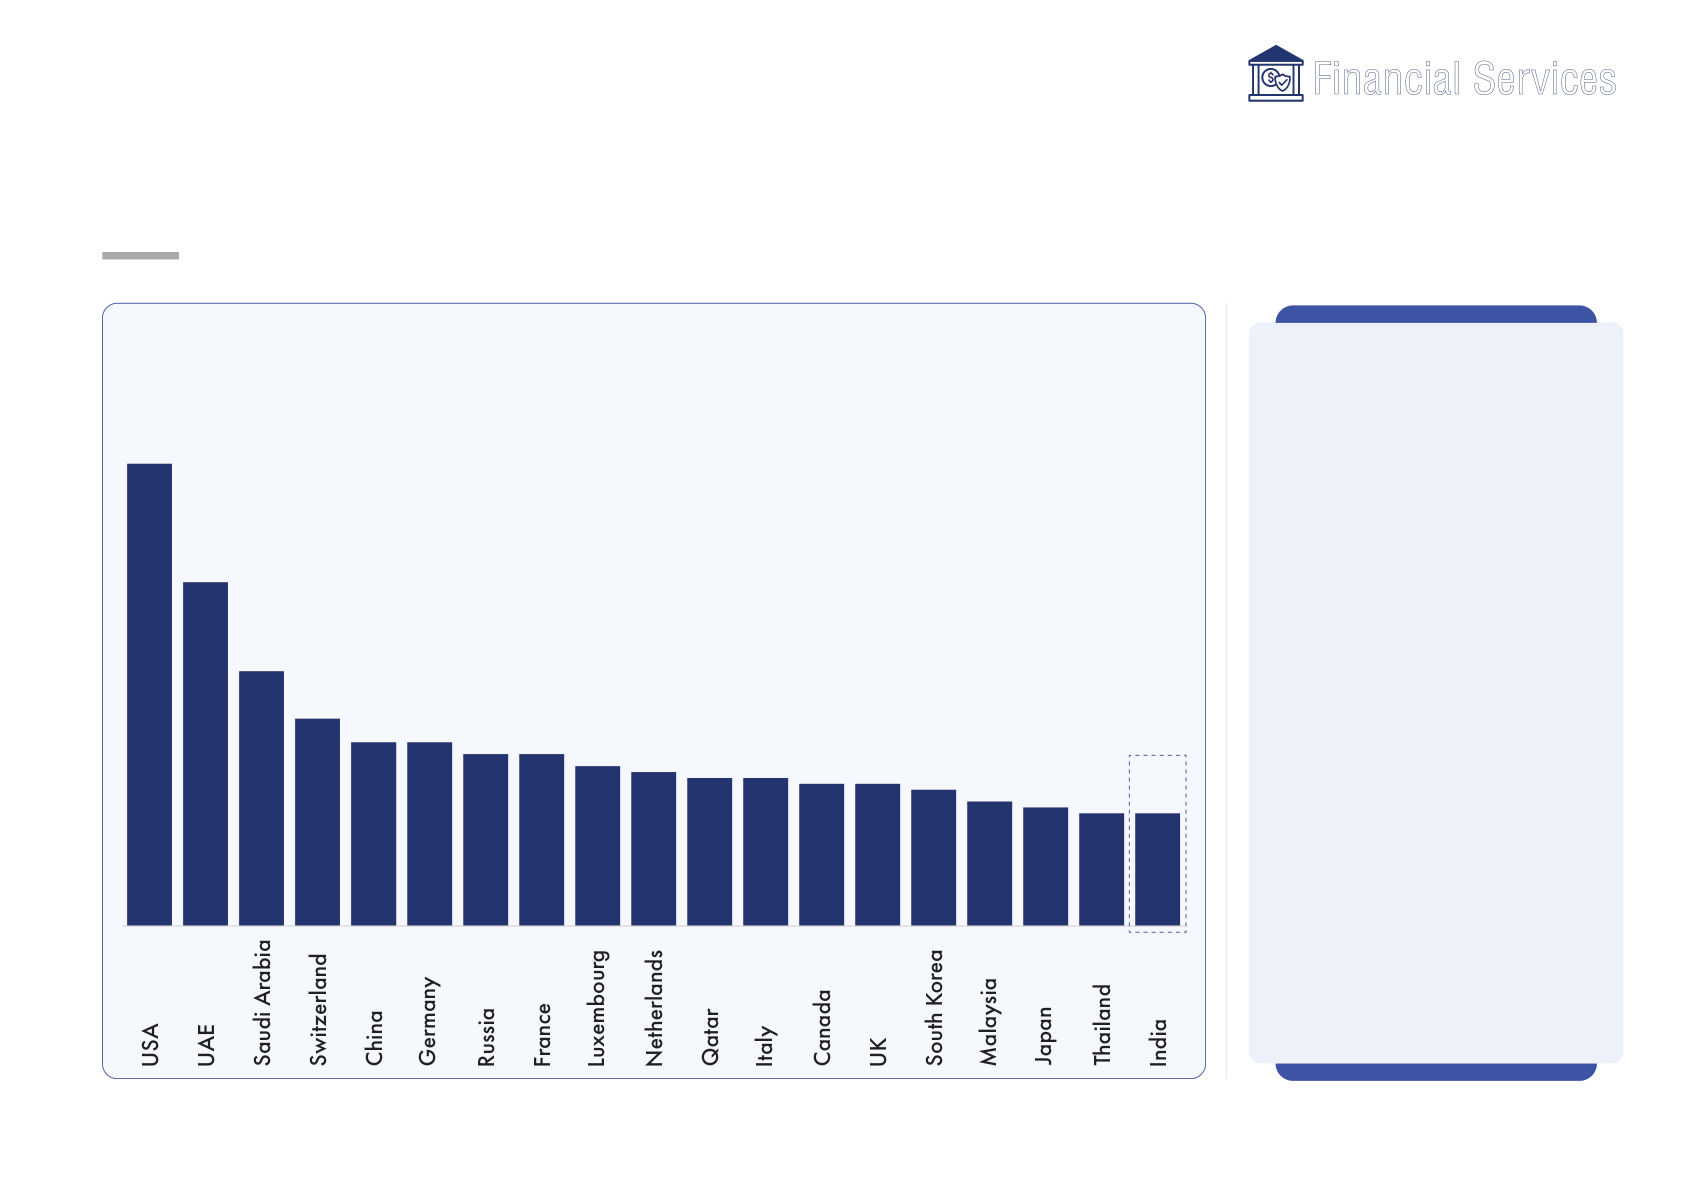
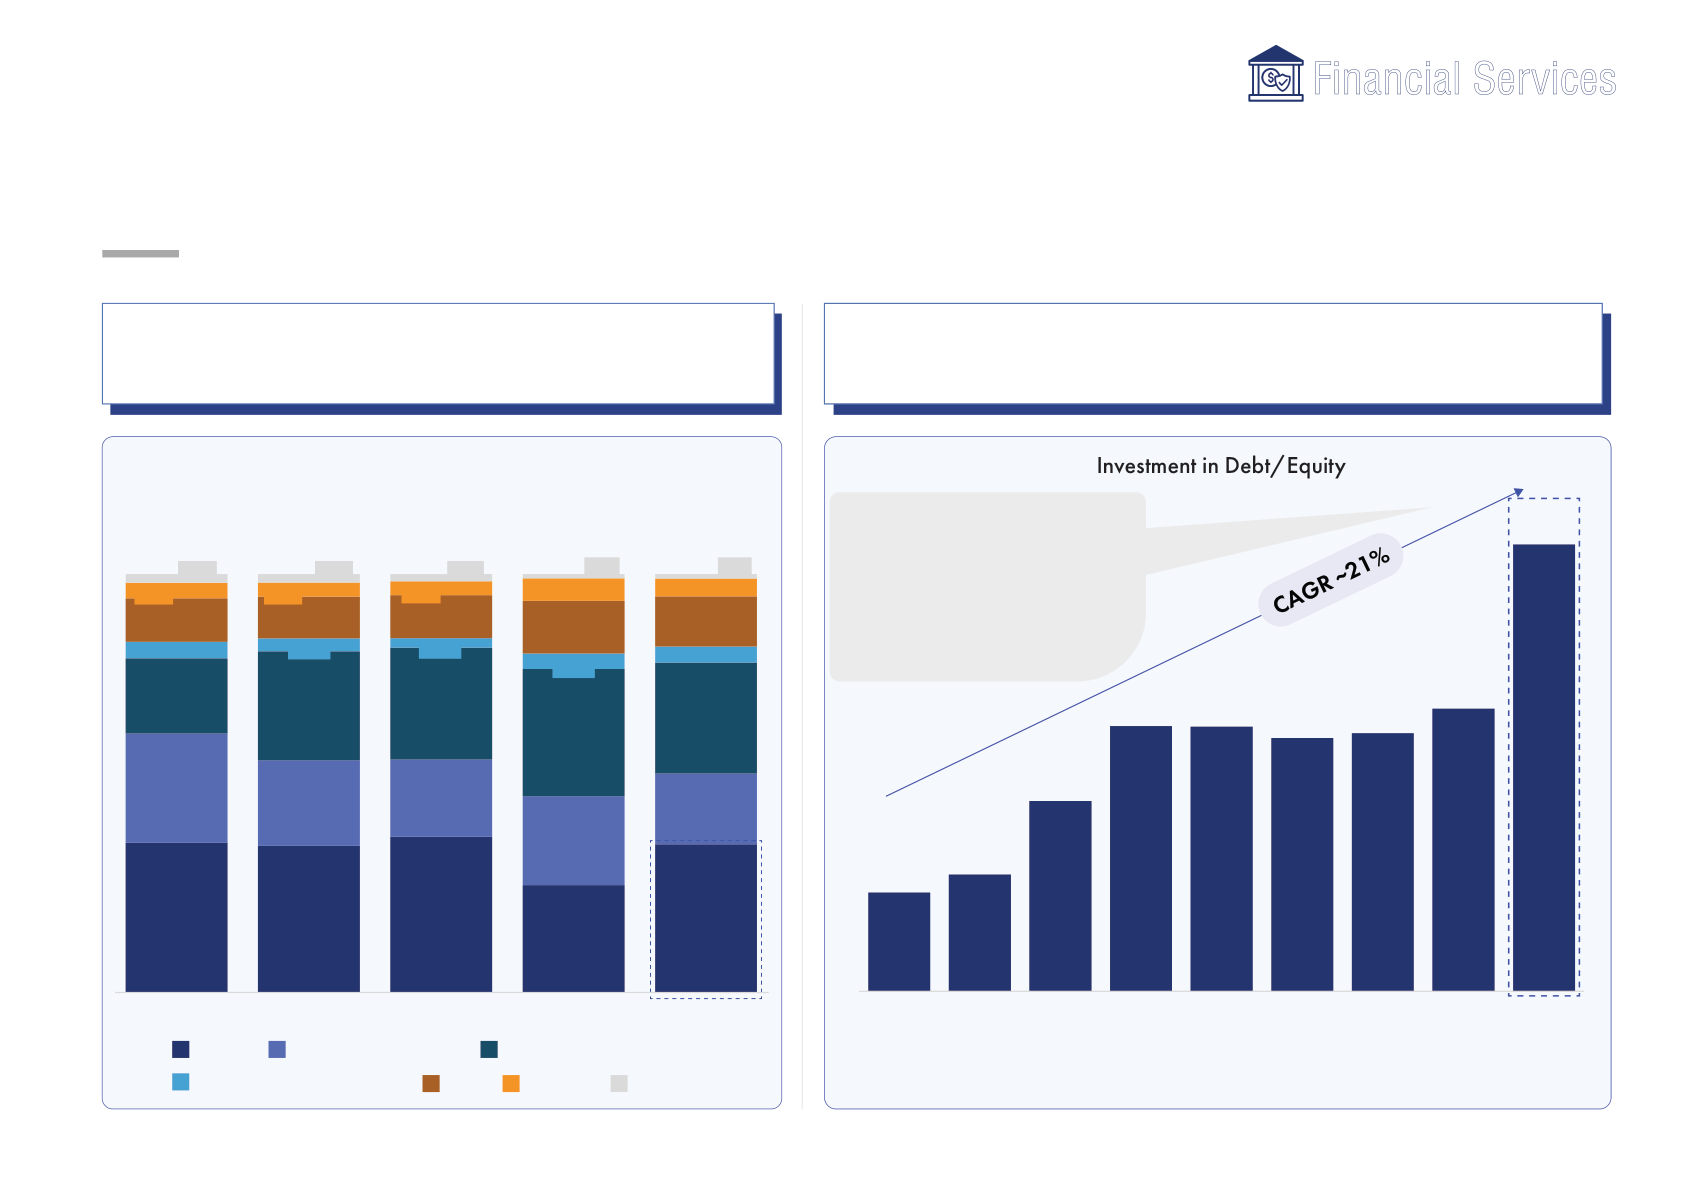
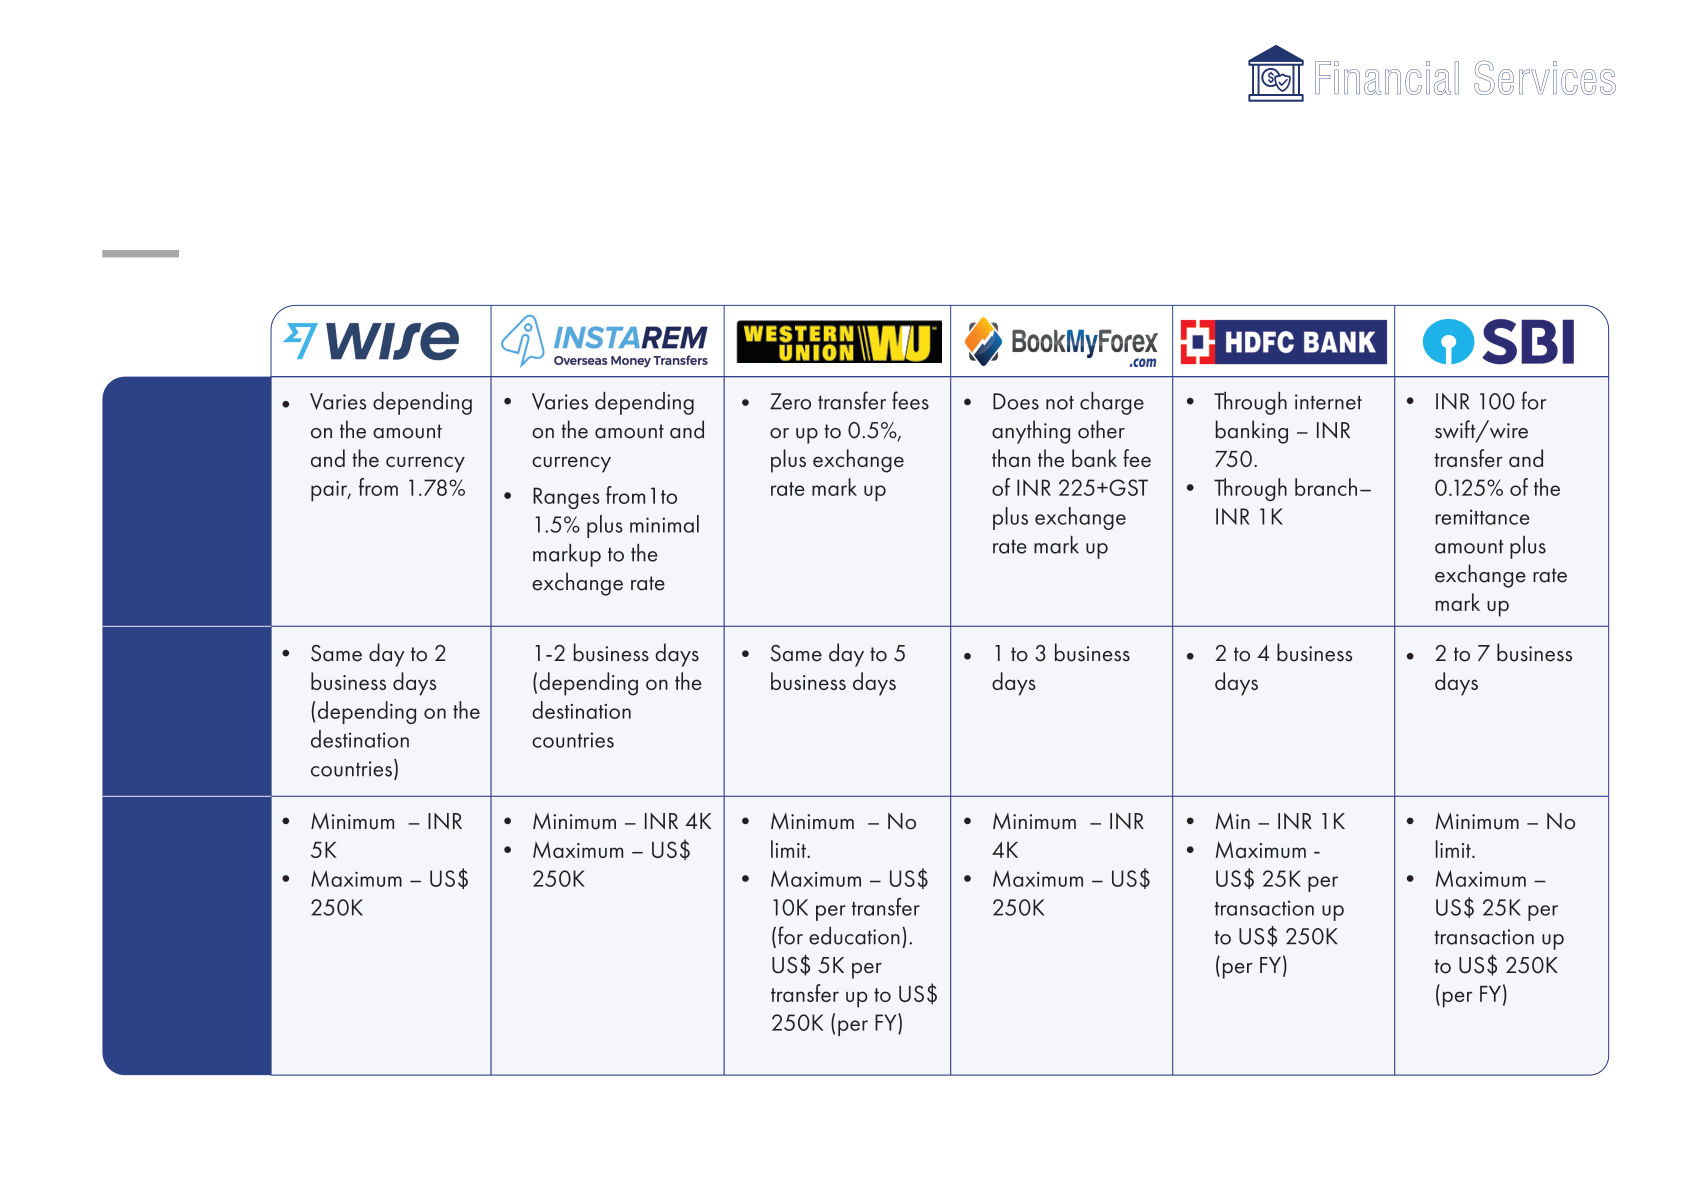
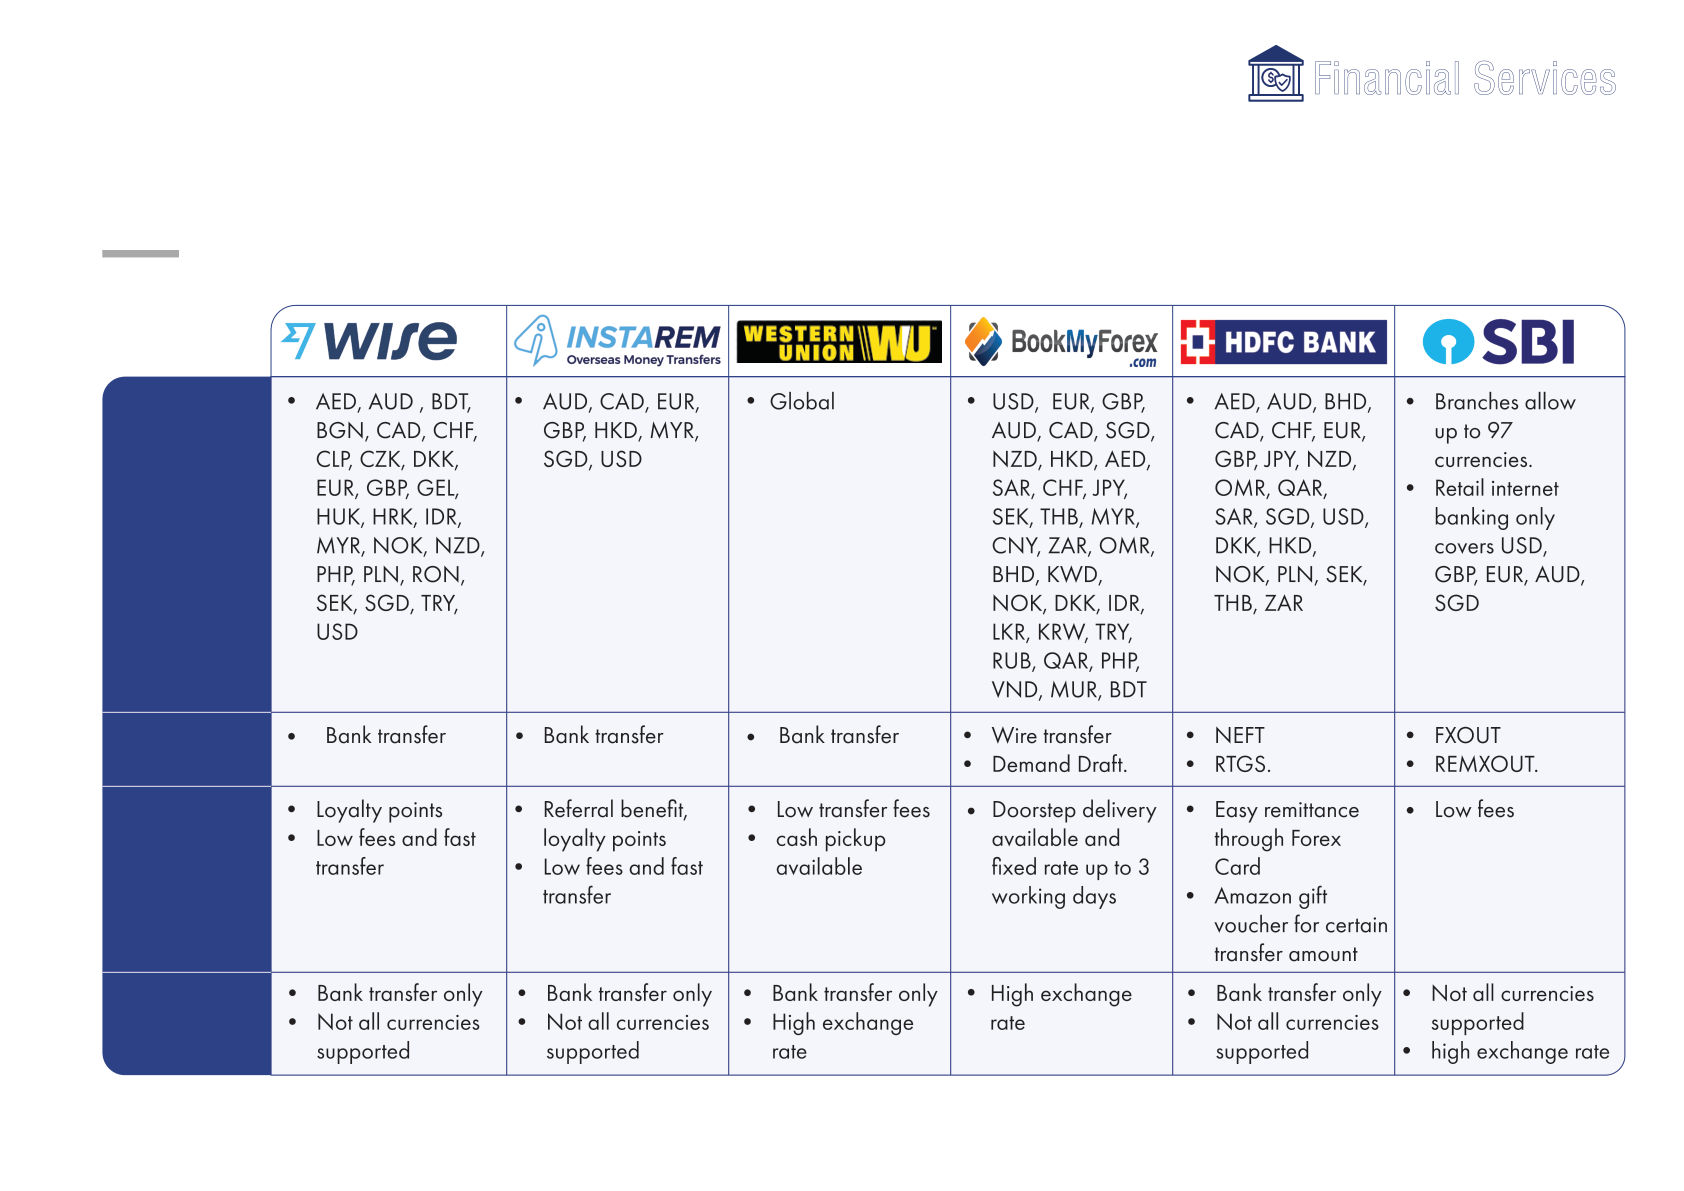
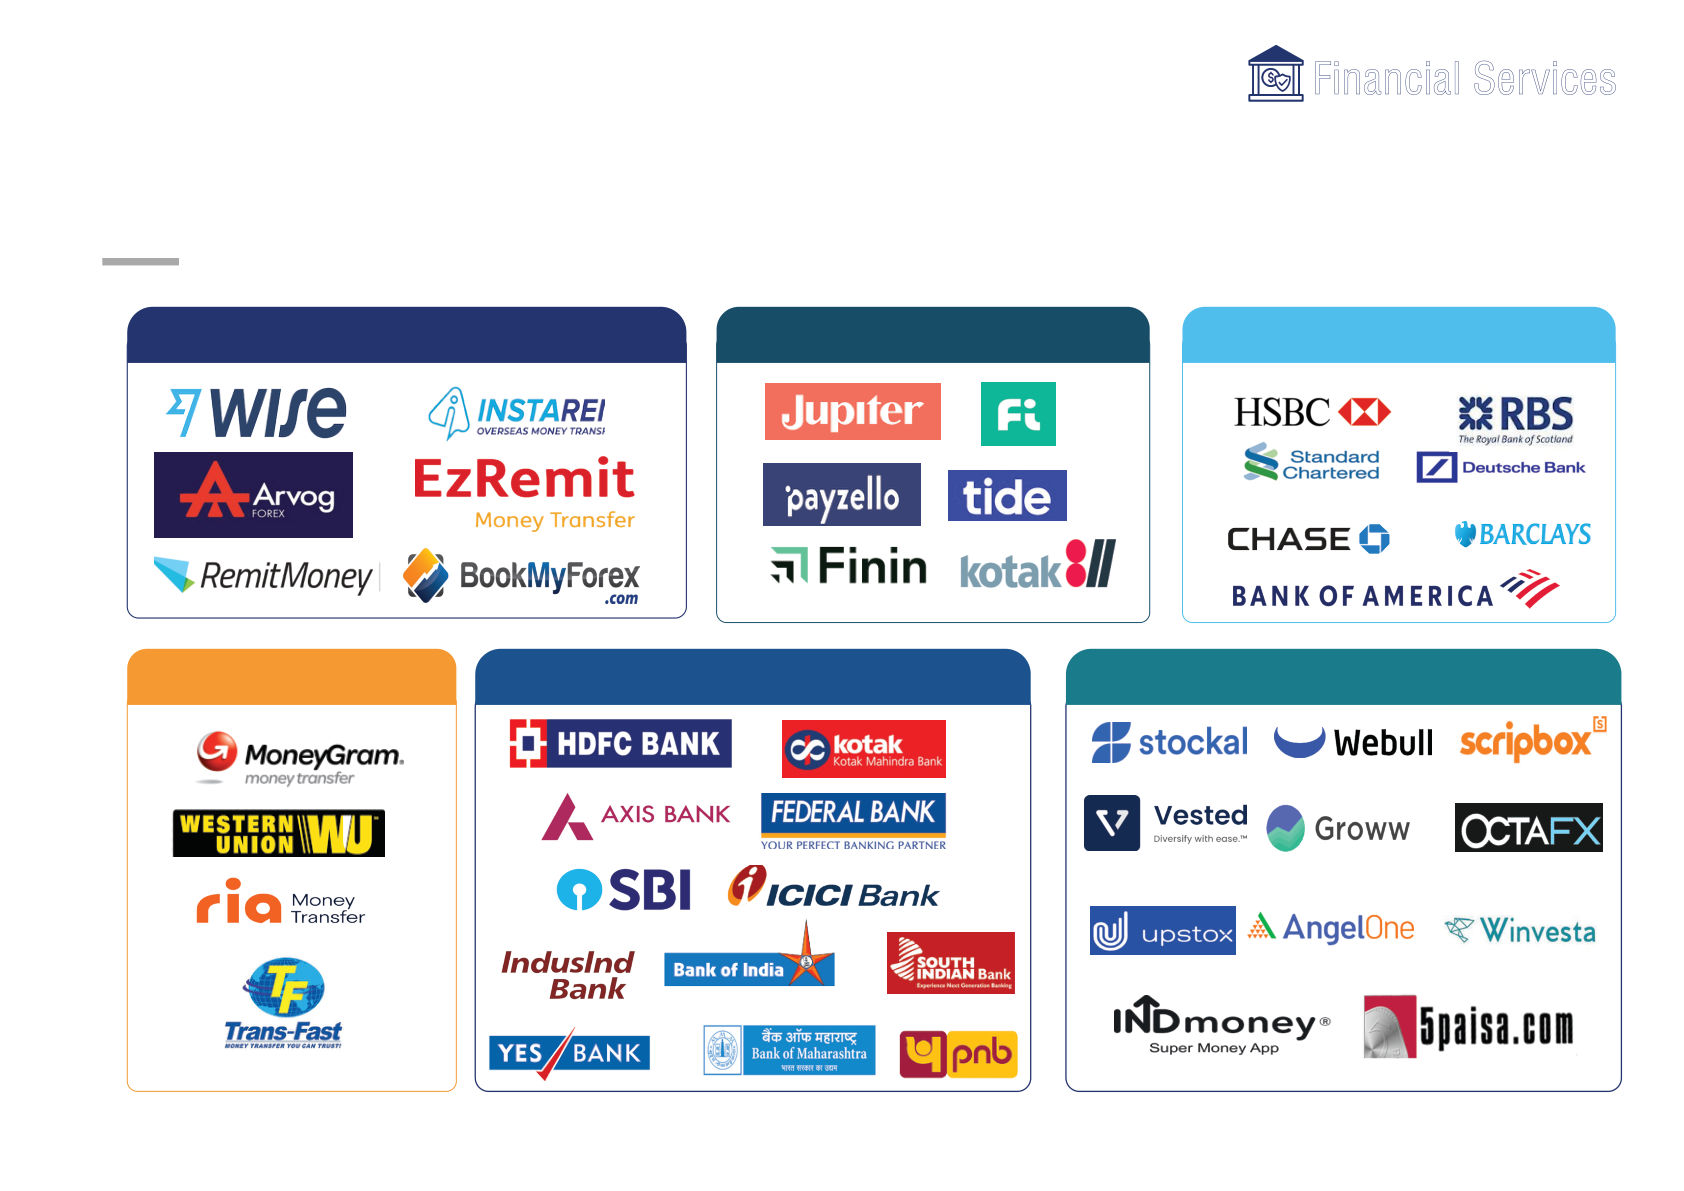
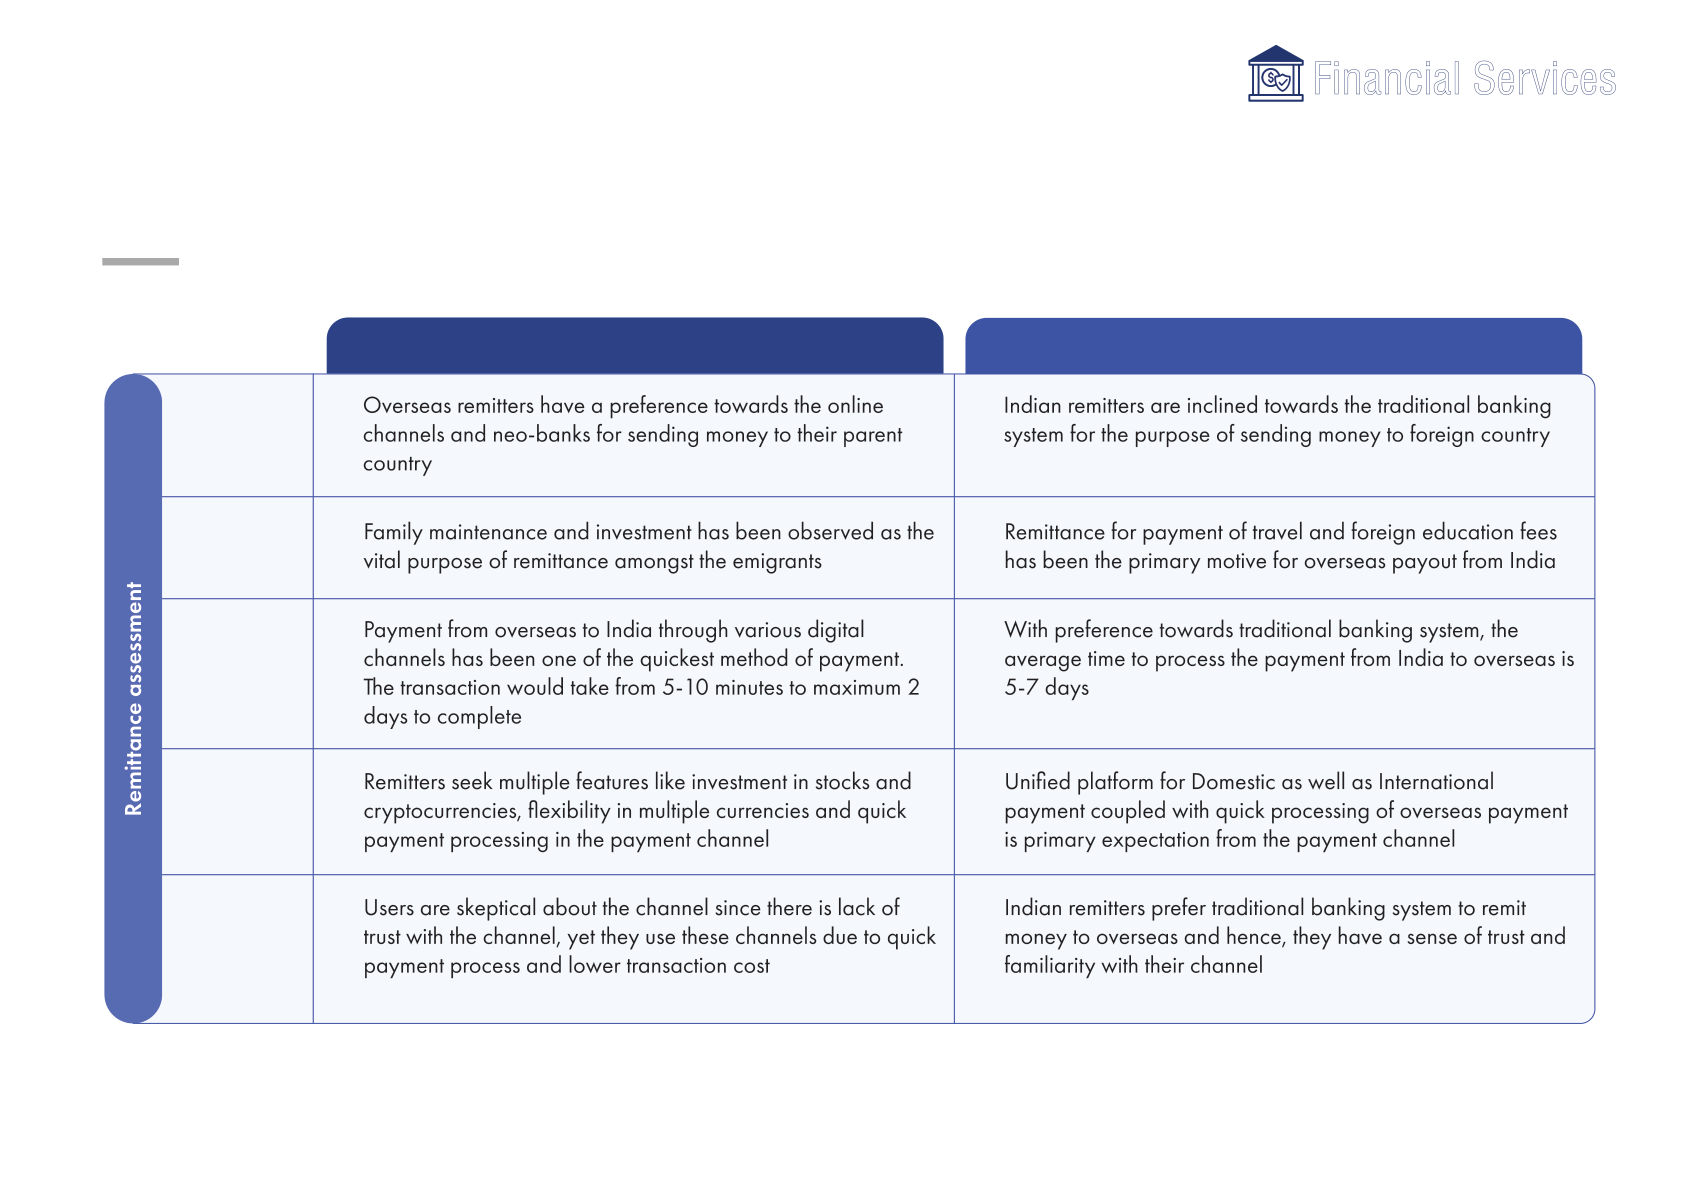
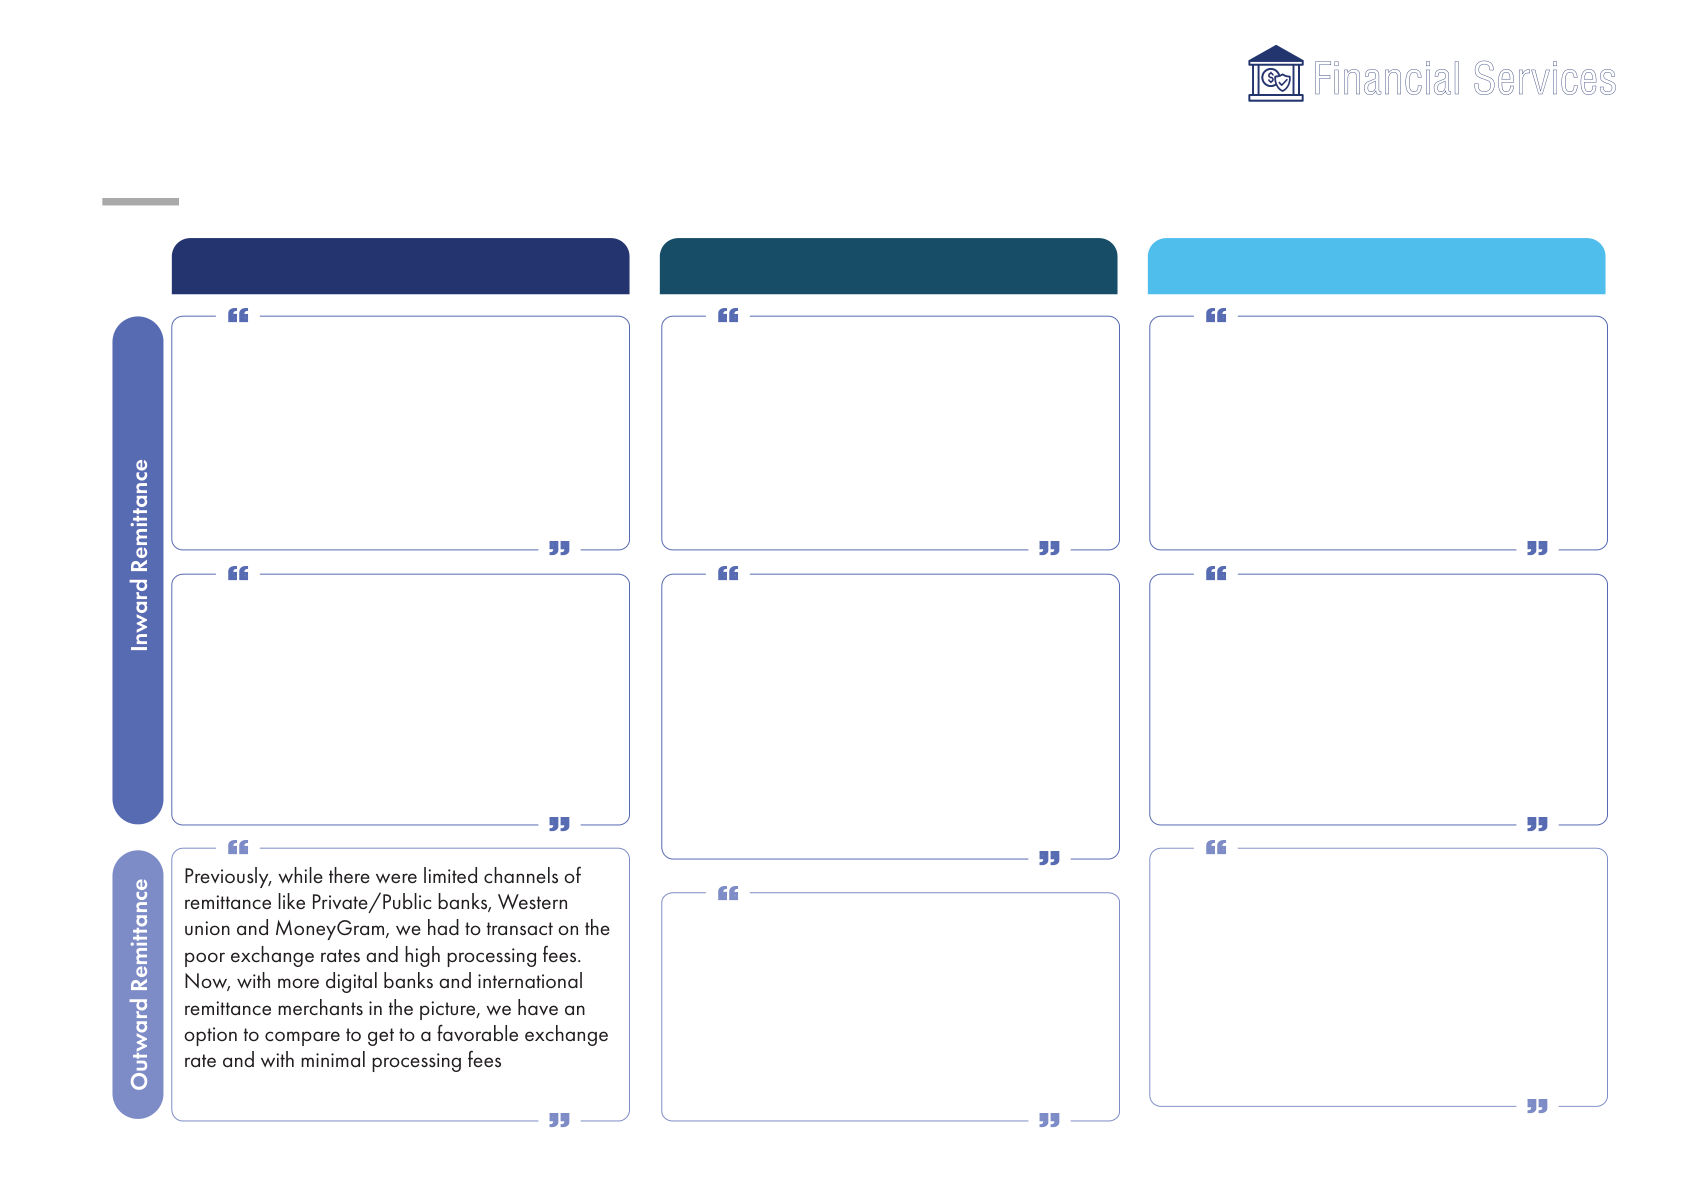
Financial Services RESILIENCE IN REMITTANCES Report December 2022 Confidential and proprietary © 1Lattice Pvt. Ltd. Remittance landscape in India Foreword • India was expected to be one of the worst sent overseas while India ranked 20th on affected countries (projected decline of the list with ~US$ 19B sent in FY22. Travel, 23%) by the pandemic as the host education & family maintenance are key countries were vulnerable to the twin drivers for outward remittances in FY22. A effect of economic slowdown and slump significant rise in outward remittances in oil prices. Yet, defying the projections, towards investments in debt/equity is India remained among the top recipient observed with ~21% CAGR from countries, with a rise of 8% in total inward FY14-FY22. The increase in investment in remittances from the previous financial foreign stocks is attributed to rise in varied year, accumulating US$ ~89B in inward foreign equity/ debt investment platforms. remittances in FY21. The share of The marketing strategy of spreading remittances from the GCC (Gulf financial literacy towards foreign Cooperation Council) region in India's investment has helped with their growing inward remittances has declined from popularity amongst Indians. This report more than ~50% in FY17 to ~30% in aims to provide various industry FY21. Economic slowdown, sluggish oil stakeholders, including business leaders, prices, stricter labour laws, an overall perspective on the personal nationalization policies, and higher work remittances market. The report reflects our permit renewal fees and taxes were perspectives as of November 2022. The observed as the primary reasons for the situation is evolving rapidly, and some decline in the share of remittances from expected scenarios may unfold GCC regions. differently. We look forward to hearing from you and exchanging notes on this • In context of outward remittances, US exciting industry. topped the list in FY22 with ~US$ 78B Abhilasha Jaju Director Financial Services Glossary Acronyms/Abbreviations Description Authorized Dealer AD Full Fledged Money Changer FFMC Gulf Cooperation Council GCC Global Knowledge Partnership in Migration and Development KNOMAD Liberalised Remittance Scheme LRS Money Transfer Operator MTO Money Transfer Service Scheme MTSS Payment and Settlement Systems Act PSS Act Remittance Community Task Force RCTF Rupee Drawing Arrangement RDA Remittance Service Provider RSP SWIFT The Society for Worldwide Interbank Financial Telecommunications © 1Lattice | 03 Financial Services Sources of input: Conducted thorough analysis using various reports, datasets and captured detailed customer feedback through in-depth interviews Institutional resources Service providers In-depth interviews Data platforms © 1Lattice | 04 EXECUTIVE SUMMARY Financial Services [1/2] Executive summary Remittances can be classified into two categories: Inward (received from a foreign country) and Outward (Sent to a foreign country). The global remittances market is segmented based on remittance channel, application, and region. India’s inward remittances receipts in FY21 were ~US$ 89B while Outward remittances in FY22 were ~US$ 19B Inward Remittances • India remained the top recipient country, contributing to 12% of total global remittance received essentially for family maintenance and as deposits in banks, investment in immovable property, equity and debt etc • The share of remittances from the GCC (Gulf Cooperation Council) region in India's inward remittances has declined from more than ~50% in FY17 to ~30% in FY21 Remittances landscape • Economic slowdown, sluggish oil prices, stricter labour laws, nationalization policies and higher work permit in India renewal fees and taxes were observed as the primary reasons for the decline in the share of remittance from the GCC region Outward Remittances • US topped the list in FY22 with ~US$ 78B sent overseas while India ranked 20th on the list of Outward remittances with ~US$ 19B sent in FY22. • A significant rise in outward remittances towards investments in debt/equity is observed with ~21% CAGR from FY14-FY22. The increase in investment in foreign stocks is attributed to the rise in various f oreign equity/debt investment platforms . The marketing strategy of spreading greater awareness for foreign investments has helped with their growing popularity amongst Indians Sources: Secondary research, in-depth interviews, 1Lattice analysis © 1Lattice | 06 Financial Services [2/2] Executive summary • The commitment and resourcefulness of emigrants to support their families back home ensured that the flow of remittances remained stable during the pandemic • There was an unprecedented switch to authorized and digital channels for remittances as consumer behaviour and Resilience in business models were affected due to pandemic Remittances • International bodies & national governments facilitated continuous flow of remittances by initiating efforts towards digitalizing KYC, improving cyber security, enabling partnership between remittance service providers & bank etc • Indian emigrants had an added advantage of the depreciating value of INR against USD and hence, there was a significant growth in the inward remittances in FY21 • With the advent of digital remittance service providers, the industry dynamics have changed. New-age digital remittance service providers entering the market have increased the levels of competition, making fees and exchange rates offers as major differentiating factors to position themselves • Building the business models on pure digital platforms also provides them with optimizing fixed costs and modern, cleaner technological operational platforms resulting into quicker turnaround times for consumers Future Outlook • The outward remittances for the purpose of Investment in equity and debts has grown significantly at CAGR of ~21% from FY14 to Remittances to FY22 and is expected to grow further in upcoming years • Digital remittance service providers can develop a wider network of agents and correspondent banks in order to scale across different geographies and corridors • With higher competition on the transfer fees, RSPs can differentiate themselves by inducing powerful technology to reconcile the transfers, managing working capital risks and observing customer trends to offer them value added services Sources: Secondary research, in-depth interviews, 1Lattice analysis © 1Lattice | 07 PROCESS OF REMITTANCES Financial Services Remittance journey followed from host country to recipient country Host Country Recipient Country 1 . Sender submits application to send Host Country remittance along with receiver’s 7 . AD pays the remittance to the information beneficiary upon presenting the draft/pay code 2 . Authorized dealer (AD) draws draft/ pay code Sender Authorised Dealers (AD) / Money Transfer Operators MTOs Recipient Country 3 . AD initiates transaction as per the 6 . Correspondent bank transfers funds application Host Country to AD in beneficiary country Beneficiary Recipient Country Sender’s Bank 4 . Sender’s bank issues remittance instructions through SWIFT, web-enabled instructions, telegraphic transfer to the correspondent bank in Correspondent Bank the beneficiary country 5 . Sender shares the draft/pay code with the beneficiary © 1Lattice | 09 Source(s): RBI Bulletin, 2018, IMF, 1Lattice Analysis PROCESS OF REMITTANCES INWARD REMITTANCES Financial Services RBI has issued RDA and MTSS arrangements to govern the inward remittances in India and align the remittance structure between banks and overseas principals Rupee Drawing Arrangement (RDA) Money Transfer Service Scheme (MTSS) Rupee Drawing Arrangement (RDA) is a procedure to receive Money Transfer Service Scheme (MTSS) is a way to receive inward trans-border remittances from foreign countries. Under this method, personal remittances in India from overseas jurisdiction. It only allows Premises banks partner with the non-resident exchange houses to open towards family maintenance & remittances for foreign tourists and manage their account in India in India RBI does not permit cross-border outward remittances from India Indian agents need authorization from the RBI to function under the under RDA. The inward remittances into India are received in a MTSS framework. Moreover, the Overseas Principal also needs to Process private account and requires relevant permissions from RBI. obtain permission from RBI under the provisions of the Payment & Settlement Systems Act (PSS Act), 2007 RBI has restricted cash disbursement of remittances under RDA. The Any amount >INR 50K shall be credited directly to the beneficiary's Permission to remittances must be credited to the bank account of the beneficiary bank account or paid through account payee cheque/ DD etc. or disburse cash There is no restriction on the remittance amount as well as on A cap limit of US$ 2.5K is laid on individual remittances under Upper cap limit the number of remittances. However, an upper limit of INR 15L is the scheme. Furthermore, thirty remittances can be received by an on remittance laid on trade related transactions individual under the scheme during a calendar year. © 1Lattice | 11 Sources: RBI, Ministry of finance, 1Lattice Analysis Financial Services India remained the top recipient country, contributing 12% to the total global remittance received essentially for family maintenance and as deposits in banks Remittances contributed 3.7% to the Family Maintenance (44%) was the India remained the top recipient country GDP in FY20 due to inert economy primary source of remittances in FY21 with 12% of total global remittances India’s inward remittances as a Purpose of inward remittances India was expected to be one of the worst percentage of GDP (%, FY21) affected (projected decline of 23% ) (World (%) Bank, 2020) as the host countries were vulnerable to the twin effect of economic 89 slowdown and slump in oil prices 12% 10% Defying the World Bank projections, India received 12% of global remittances and 35% remained the top recipient country with US$ ~89B in inward remittances 3.7 2.9 2.9 Family maintenance has been observed as 44% the primary factor contributing to the inward remittance in India followed by investments in immovable property, equity and debentures FY19 FY20 FY21 Family maintenance Deposits in banks Investment (immovable Others % of GDP property/equity/debt etc.) Source(s): Global Knowledge Partnership in Migration and Development(KNOMAD), World Bank, RBI Remittance Survey, 1Lattice Analysis © 1Lattice | 12 Financial Services Inward remittances in India has been predominantly received from the USA and the UAE while there is an exponential increase in remittance from the South Asian countries UAE (~27%) had the highest share of inward remittances in USA surpassed UAE as the top source country , accounting FY17 while USA (~23%) contributed the highest in FY21 23% of total remittances in FY21 Inward Remittances from different countries (to India) Singapore eased norms of doing business leading to (%, US$ B) increase in companies registering their offices in Singapore, hence, attracting foreign migration stock 69 89 16% 1% Indians with employment pass (EP) in Singapore have 33% 2% doubled from 13% to 26% between FY05 and FY21 1% 7% 3% 1% 6% 1% 2% 2% 1% 12% 5% 2% 3% 6% Developed countries like USA, UK, Canada etc. also 7% offered visa pathways for business professionals such as 27% start-up visa, investment visa, entrepreneur visa, golden visa, 18% and self-employed visa 23% 23% The share of remittances from the GCC (Gulf Cooperation Council) region in India's inward remittances has declined FY17 FY21 from more than 50% in FY17 to about 30% in FY21 USA UAE UK Singapore Saudi Arabia Kuwait Oman Qatar Hong Kong Malaysia Canada Others Note: Others in FY 2016-17 and FY 2020-21 comprises of Australia, Germany, Italy, Philippines etc. © 1Lattice | 13 Source(s): Global Knowledge Partnership in Migration and Development(KNOMAD), World Bank, RBI Remittance Survey, 1Lattice Analysis Financial Services Fall in the remittances from the Gulf Cooperation Council(GCC) region is impacted due to a sharp contraction in the number of emigration clearances from the GCC The UAE witnessed the steepest decline in Saudi Arabia(44%) had the Migration from India to the Gulf the emigrant stock since 2015 followed maximum share of emigrant Cooperation Council (GCCs) slowed in by Oman stock amongst the GCC countries the last five years due to - • Economic slowdown India’s emigration in GCC region % distribution of emigrants (0.9 lakh) in GCC • Sluggish oil prices (# Lakhs) (%, CY20) 3.1 • Stricter labour laws, • Introduction of nationalization policies • Higher work permit renewal fees and 1% taxes 2.3 • These factors coupled with 11% pandemic-induced travel restrictions and changes in the region’s labour 11% 1.6 market reduced the employment 1.5 opportunities and dented the scope 44% for absorption of blue-collar workers 11% 0.9 • According to MEA, the emigrant stock 0.8 0.8 22% 0.7 in GCC countries has dropped 0.6 0.5 0.5 significantly to 0.9 Lakh in CY20 with 0.4 0.3 the highest share of Saudi Arabia 0.2 (44%) followed by UAE (22%) 0.1 0.1 Saudi Arabia UAE Kuwait Saudi Arabia UAE Kuwait Oman Oman Qatar Bahrain CAGR -34% -39% -32% -36% 2015 2017 2019 2020 Note: MEA releases the emigration stock data for Calendar year, Sources: Emigration clearance data, MEA, Govt. of India, 1Lattice analysis © 1Lattice | 14 Financial Services Since the advent of the pandemic, lumpsum receipts of >US$ 500 has decreased compared to pre-pandemic while SWIFT transactions have increased significantly The lumpsum receipts of US$ 500 has marginally dipped in Remittances through SWIFT (~41%) has FY21 yet the overall remittances has increased significantly significantly increased in FY21 compared to FY17 Share of lumpsum receipts of remittance Mode-wise Remittance transfer (%, US$ B) (%, US$ B) 69 89 69 89 0.3% 2% 3% 6% 2% 3% 20% 27% 26% 41% 70% 75% 68% 57% FY17 FY21 FY17 FY21 Average (US$) 496.5 506.8 RDA/Vostro Account SWIFT Direct Transfers Others >= US $500 Between US $200 and US $500 <= US $200 © 1Lattice | 15 Source(s): RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice Analysis Financial Services Kerala, Tamil Nadu and Karnataka witness a decline in remittances while Uttar Pradesh, Orissa and West Bengal have emerged as prime origin for emigrants in GCC The proportion of remittances received in Kerala, Tamil Maharashtra (~35%) has the highest share of remittance Nadu and Karnataka has reduced significantly in FY21, receipts in FY21 while Kerala’s share has significantly dipped accumulating to 25% State-wise share of Remittances receipts • Maharashtra emerged as highest remittances (%, US$ B) recipient in FY21 with 35% of total inward 69 89 remittances received in India • Kerala, Tamil Nadu and Karnataka, earlier, had 16% strong dominance in low skilled migrants in GCC 25% 3% 3% 2% According to MEA, the composition shift of recipient 4% 4% 2% states is due to adoption of higher education in Indian 5% 3% 4% youth, change in host country dynamics, changing 9% occupational patterns from low skilled to high skilled 15% workers 10% 6% 10% 8% 19% 35% 17% >50% of the emigration clearances for the GCC region FY17 FY21 • Despite the high share in emigration clearance, their Maharashtra Kerala Tamil Nadu Delhi Karnataka Andhra Pradesh share in total remittances is relatively low Uttar Pradesh Gujarat Punjab Others Note: West Bengal, Jharkhand, Rajasthan, Bihar, Haryana etc are consist of others in FY 2016-17 and FY 2020-21 © 1Lattice | 16 Source(s): RBI Remittance Survey 1Lattice Analysis Financial Services A rapid growth has been observed in direct bank transfer through MTOs due to development in digital infrastructure & cost-effective transactions offered by MTOs A decline in the share of remittances A steer shift in direct bank transfer is through banking channel was observed observed in transfer through MTOs in during pandemic the light of pandemic Share of inward remittances channels Mode of Transfer through MTOs (%, US$ B) (%, US$ B) In FY21, only 0.2% of inward remittances are received in 69 89 24 38 fintech wallets. • Favorable exchange 3% rates provided by MTOs 35% 35% 42% While most of the transactions in FY17 were cash oriented, a steer shift to direct bank transfer was observed in MTO transactions due to prevalence 97% of digital mode of payment. 65% 65% 58% FY17 FY17 FY21 FY21 Bank MTO Direct Transfer to Bank Cash © 1Lattice | 17 Source(s): RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice Analysis Financial Services Significant growth has been observed in remittances in the initial quarters of FY21 across nations; while FY20 observed resilience despite economic slump Recipients of highest inbound remittances • India witnessed an overall decline (US$ B) in remittances between Q2:FY20 to Q4:FY20, with a rebound in FY21 89 • The major contributing factor for 8383 the rebound was the 78 unprecedented switch to 68 67 regulated and digital channels for remittances as the pandemic 59 forced consumer behaviour and 54 53 business model changes 43 • A similar trajectory was observed 38 for remittances in Mexico, Egypt 35 31 31 29 and Pakistan as well 26 26 25 24 23 22 21 19 • Meanwhile, due to prevalence of 17 COVID-19, China witnessed a continuous decline in the remittance receipts despite the increased outflow of emigrant stock China Mexico Egypt Pakistan Nigeria India FY18 FY19 FY20 FY21 © 1Lattice | 18 Source(s): RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice Analysis Financial Services Remittances industry has seen the rise of many international players with dedicated routes to India and SEA countries Digital Money Transfer Operators Traditional Money Transfer Operators Traditional Banks (Transfers and Forex Cards) © 1Lattice | 19 Source(s): Secondary research, 1Lattice analysis PROCESS OF REMITTANCES OUTWARD REMITTANCES Financial Services Under the Liberalized Remittance Scheme, resident individuals are allowed to remit up to US$ 250K per financial year • Under the Liberalized Remittance Scheme, • For remittances pertaining to permissible any resident individuals, are allowed to remit capital account transactions, if the applicant up to US$ 250K per financial year for any seeks to make the remittance and is a new permissible current or capital account customer of the bank, Authorized Dealers transactions should carry out due diligence on the opening, operation and maintenance of the account Outward Remittances • AD will be directed by the category of transaction as stated by the remitter in LRS • An individual will have to assign a (Form A2) and will certify that the remittances is branch of an authorized dealer in accordance with the instructions issued by through which all the capital account the RBI remittances will be made. • However, the remitter is entirely responsible to • The applicants should have ensure due compliance of FEMA regulations maintained the bank account with the bank for a minimum period of one year prior to the remittance. © 1Lattice | 21 Source: RBI, FEMA’1999 Financial Services USA (~US$ 78B) sent highest remittance in FY22 while India stands 20th on the list, being marginally behind Japan and Thailand Outward Remittances in 2022 USA topped the outward (US$, B) remittances list in FY22 with ~78 Bn US$ sent overseas. 78 India ranked 20th on the list of outward remittances with ~19 Bn US$ sent in FY22. 58 The major contributing factors towards outward remittances are: 43 • Travel • Maintenance for family 35 and relatives 31 31 29 29 • Education 27 26 25 25 24 24 23 • Investment in 21 20 19 19 Debt/Equity • Deposits • Gift • Purchase of Immovable property Source(s): RBI data, 1Lattice analysis © 1Lattice | 22 Financial Services Travel, education & family maintenance are key drivers for outward remittances in FY22; Investment in debt/equity has escalated significantly in FY22 Overseas travel and leisure (35%) has the highest Significant rise in outward remittances towards Investments share in the outward remittance from India in debt/equity is observed with ~21% CAGR from FY14-FY22 Outward Remittances (%, US$ B) (US$ M) • Increase in investment in foreign stocks 746 is due to foreign equity/debt 11 14 18 12 19 investment platforms like INDmoney, 1% 1% 2% 2% 2% Groww, Upstox etc. 4% 5% 4% 3% 3% • The marketing strategy of spreading 10% greater awareness for foreign 10% 12% 10% 13% investments has helped with their 3% 4% 2% 4% growing popularity 4% 472 18% 442 443 27% 26% 431 423 26% 30% 318 26% 18% 20% 17% 21% 195 165 37% 35% 35% 35% 26% FY19 FY18 FY20 FY21 FY22 FY14 FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 Travel Family Maintenance Education Investment in Equity/Debt Gift Deposit Others © 1Lattice | 23 Source(s): RBI data, 1Lattice analysis Financial Services Digital channels have streamlined the remittances process to reduce the turnaround time (Instant to 2 days) along with competitive exchange rates Transfer fees Transfer speed Transfer Amount permitted per financial year © 1Lattice | 24 Sources: Websites of Banks and RSPs, 1Lattice Analysis Financial Services Rewards on referral, loyalty points, low fees and quick transfers are some of the attractive features offered by the digital remittance service providers Supporte currencies pair Payment options Pros Cons © 1Lattice | 25 Sources: Websites of Banks and RSPs, 1Lattice analysis Financial Services Remittance industry has seen emergence of several players in the overseas investment domain as well as money transfer domain Digital Money Transfer Operators Neo Banks (Forex Cards) Foreign Banks (Bank transfers) Traditional Money Traditional Banks Overseas investment platforms Transfer Operators (Transfers and Forex Cards) © 1Lattice | 26 Sources: Websites of Banks and RSPs, 1Lattice analysis RESILIENCE IN REMITTANCES Financial Services Development of digital payment channels, policy & regulatory responses from International bodies paved way towards resilience in remittances Commitment of the migrant Digital Channels Foreign Currency Exchange Policy & Regulations • The commitment and • There was an unprecedented • Indian emigrants had an • International bodies & national resourcefulness of emigrants switch to authorized and added advantage of the governments facilitated to support their families back digital channels for depreciating value of INR continuous flow of remittances home ensured that the flow of remittances as consumer against USD and hence, there by initiating efforts towards remittances remained stable behaviour and business models was a significant growth in the digitalizing KYC, improving were affected due to pandemic inward remittances in FY21 cyber security, enabling RSP & • With disruption in traditional bank partnerships etc. sources of income, migrants • Under pandemic conditions, • The depreciating value of INR took alternate jobs and digital channels of remittances accelerated the inward • Industrial stakeholders took reduced consumption to fund became apparent and gained remittance as the migrants diverse measures to create a their crucial remittances to popular attraction due to their were determined to send more enabling environment in family convenience, cost and security higher share of their incomes to order to keep remittances their family flowing & to promote the digital • This saved many pandemic • Countries with well-developed channels affected households in payment system infrastructures • The value of INR vis-à-vis USD low-middle income countries, and policies saw a relatively increased from INR 72.17 in • As an immediate step, many including rural, women-led and easy shift from cash to digital Feb’2020 to INR 76.31 in governments declared refugee households from payments. Globally, consumer Dec’2021 remittance services as essential falling into poverty preference for contactless service and used their authority payments rose and so did to congregate industry demand for digital-only stakeholders to boost to existing payment methods remittance goals © 1Lattice | 28 Source(s): KNOMAD, World Bank. RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice analysis Financial Services Rapid adoption of digital channels coupled with action from industry stakeholders helped in building long term resilience for remittances Quick adoption of digital channels Industry stakeholder actions Regulatory Responses Mobile money-enabled remittances The pandemic forced a change in The United Nations launched dedicated provided immediate access to inflow of operation process of many RSPs. Those campaigns to dictate remittances, namely, money when and where traditional with OTC or in person business models “building resilience in times of crisis” and over-the-counter cash remittances are not (i.e. cash-based) had to adapt to digital “recovery and resilience through digital accessible models and financial inclusion” Various security norms were introduced Existing digital remittance service users Many RSPs announced awareness and by the International Institutions in order to and those equipped with a transaction marketing campaigns to promote the use reduce the impact of cyber attacks on the account reinforced their preference for of digital channels, including step-by-step digital RSPs operations to secure the trust online sending methods guides on social media of remitters The Remittance Community Task Force Digital channels became a natural choice (RCTF) was launched by IFAD in March Other RSPs offered incentives, including for users already accustomed with that 2020, for global solidarity. The Task free healthcare insurance for remittance method while appealing incentives, social Force developed the Blueprint raise recipients, sign-up rewards and free networks and intrinsic convenience awareness for the impact of pandemic on airtime for receiving digital remittances. convinced non-digital users to overcome people directly affected by slump in the Some even offered cash prizes their reluctance to change flow of remittances © 1Lattice | 29 Source(s): KNOMAD, World Bank, RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice analysis Financial Services Rapid adoption of digital channels coupled with action from industry stakeholders helped in building long term resilience for remittances Outward Remittances Inward remittances have accelerated due to gradual (%, US$ B) structural change in Indian migrants’ key destinations • The migrant stock has s hifted from blue collar/ 100 low-skilled (informal employment in the GCC countries) to a dominant share of white collar/ high-skilled jobs in developed nations such as USA, UK, Singapore, Japan, Australia and New Zealand The economic conditions in the GCC are also 60 favorable from India’s perspective (since July’22) 51 • GCC’s financial policies kept inflation low in 2022 • Higher oil prices increased demand for labour , 38 enabling Indian migrants to increase remittances 32 29 Indian migrants also seem to have leveraged the 21 21 depreciation of the INR vs USD • The depreciated value of INR has influenced Indian migrants to remit a higher share of their income to families in India India Mexico China Phillippines Egypt Pakistan Bangaldesh Nigeria Though remittance receipts have grown significantly, it is likely to be impacted by higher inflation in the USA coupled with economic slowdown © 1Lattice | 30 Source(s): KNOMAD, World Bank, RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice analysis Financial Services Traditional TSPs can optimize the fixed costs, streamline their operations, analyze consumer trends and scale significantly by adopting digital application platform Future outlook for traditional and digital remittance service providers New-age digital remittance With higher competition on the service providers entering the transfer fees, RSPs can differentiate market have increased the levels themselves by inducing powerful of competition, making fees and technology to reconcile the exchange rates offers as transfers, managing working major differentiating factors capital risks and observing to position themselves customer trends to offer them value added services Traditional RSPs can build their Digital remittance service providers business models on digital can further scale their business by platforms as it would provide them having a deep bench of agents with optimizing fixed costs along and correspondent banks in with modern technological order to increase their array of platforms to offer the consumers countries and corridors with quicker turnaround times © 1Lattice | 31 Source(s): KNOMAD, World Bank, RBI Remittance Survey, 2016-17 & 2020-21, 1Lattice analysis CUSTOMER FEEDBACK Financial Services Unified platform for Domestic as well as International payment and quicker processing of payment are key expectations from the payment channel Inward Remittances Outward Remittances Preferred remittance channel Intent of remittance Average time to process payment Expectations from the channel Perception towards safety of the channel © 1Lattice | 32 Source(s):,in-depth interviews (N=7), 1Lattice analysis Financial Services Voice of Customers Processing and transaction cost Process Expectations from the channel Processing cost of sending the remittance plays a Sending out money to family has become a cake Some of the new-age digital remittance service major role in the amount of remittance sent in walk with digitalization of the remittance process providers provide the facility to manage funds lumpsum. Since the advent of many digital players and emergence of plethora of RSPs. I have been along with unified platform for investment in stocks in this space, there are ample offers provided to able to send money to my family in India with one and crypto. I expect increase in number of such increase the lumpsum amount of remittance. I used single click after smooth onboarding platforms as they provide a handful of consumer to send money through dedicated banks only, experiences - Indian emigrant in USA -Indian emigrant in United Kingdom -Indian emigrant in Poland Earlier I used to send out € 700-800 every month Local remittance service providers provide I often face the situations wherein if any remittance to my family in India but now I see a lot of offers favorable exchange rates and cheaper transaction service provider has lower processing/transaction on many digital remittance portals wherein they fees, but the process requires a lot of manual fees then they do not have flexibility to convert provide high discounts on the transaction fees and checks and consumes a lot of time to reach the money in different currencies. Platform must come even provide better exchange rates if the amount if beneficiary account in India. If similar support up with facility to convert more and more higher than € 1500. Hence, I have been sending service couples with favorable exchange rates are currencies € 1500 every 2 months provided on the online channels, then it would ease the entire experience - Indian emigrant in Poland - Indian emigrant in Kuwait - Indian emigrant in Kuwait A single unified platform for domestic as well as international payments must be provided by the Sending money to any foreign country becomes a public/private sector banks along with cheaper tedious process as it requires an individual to fill transaction charges to provide a wholesome LRS form with details of transaction along with encounter of the platform transaction IDs of previous. We hope this process gets automated in future - Indian whose kin lives in Kyrgyzstan - Indian whose kin lives in USA - Indian whose kin lives in Australia © 1Lattice | 33 Source(s):,in-depth interviews (N=7), 1Lattice analysis We’re here for you Let us know how can we meet your business requirement? Abhilasha Jaju Connect now Director Vaishnav Kumar Rai 1Lattice Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 Gurugram Bengaluru hello@1lattice.com New Delhi Mumbai www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. Our team Abhishek Maiti Abhilasha Jaju Vaibhav Tamrakar Praneet Singhal Industrial Good & Services, Financial Services Fintech, Ed Tech & Food Tech Technology & Internet Technology & Internet 6.5+ yrs. of experience 9+ yrs. of experience 13+ yrs. of experience 16+ yrs. of experience BITS Pilani, IIM Lucknow IIT Bombay NMIMS IIT Delhi, IIM Indore Roma Dixit Arindam Gupta Ashish Dhir Anil Razdan Financial Investor Group, Healthcare & Lifesciences Consumer & Retail Consumer & Retail Consumer & Retail 25+ yrs. of experience 25 yrs. of experience 10+ yrs. of experience 14+ yrs. of experience Faculty of Management Masters of Business Administration from MBA from University of ICFAI Business School Studies, New Delhi Lancaster University Management School, Mumbai, Mumbai UK Parul Garg Vamsi Krishna Kiran Achanta Consumer Technology & Internet Technology & Internet 5+ yrs. of experience 14+ yrs. of experience 5+ yrs. of experience NIT Kurukshetra, ICFAI Business School VIT University, IMT Ghaziabad University of Delhi Tarak Pandey Aastha Singh Financial Services Financial Investor Group, Consumer & Retail 6+ yrs. of experience 1.5+ yrs. of experience SRM University, Chennai LSR, Delhi 1Lattice We enable better decision making. Technology-backed business support that helps you ENABLE BETTER 500+ 30% annual engagements faster to outcomes DECISIONS Deep on-ground insights that you can act on 8 600+ practices years domain expertise 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy One-ness of data and people networks to harness the collective power of data, network, and technology 100+ 2.5M towns & cities panel members Multi-faceted teams offering a stack of consulting, advisory, and research services 15+ 40:60 languages covered she/he ratio The team at appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, Tower A, 4th Floor, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District DLF Centre Court, Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 DLF Phase 5, Sector 42, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram-122002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025