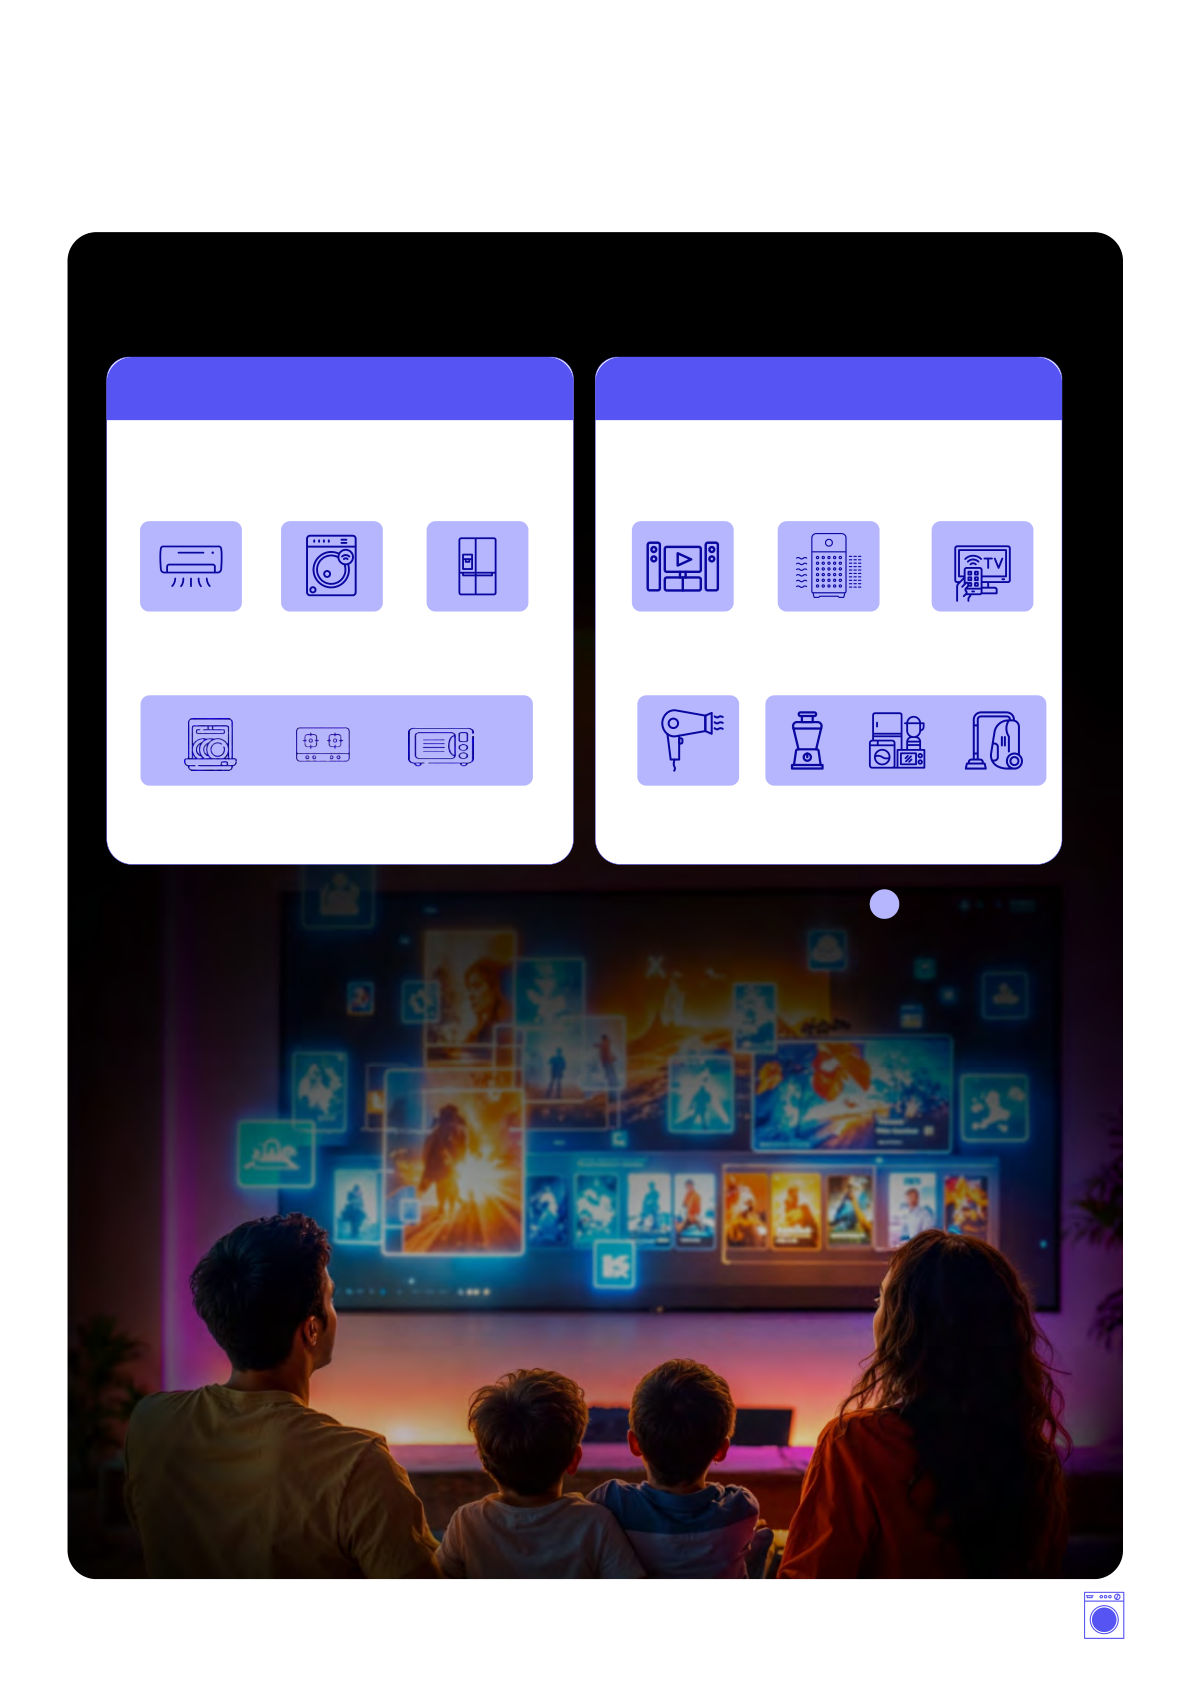
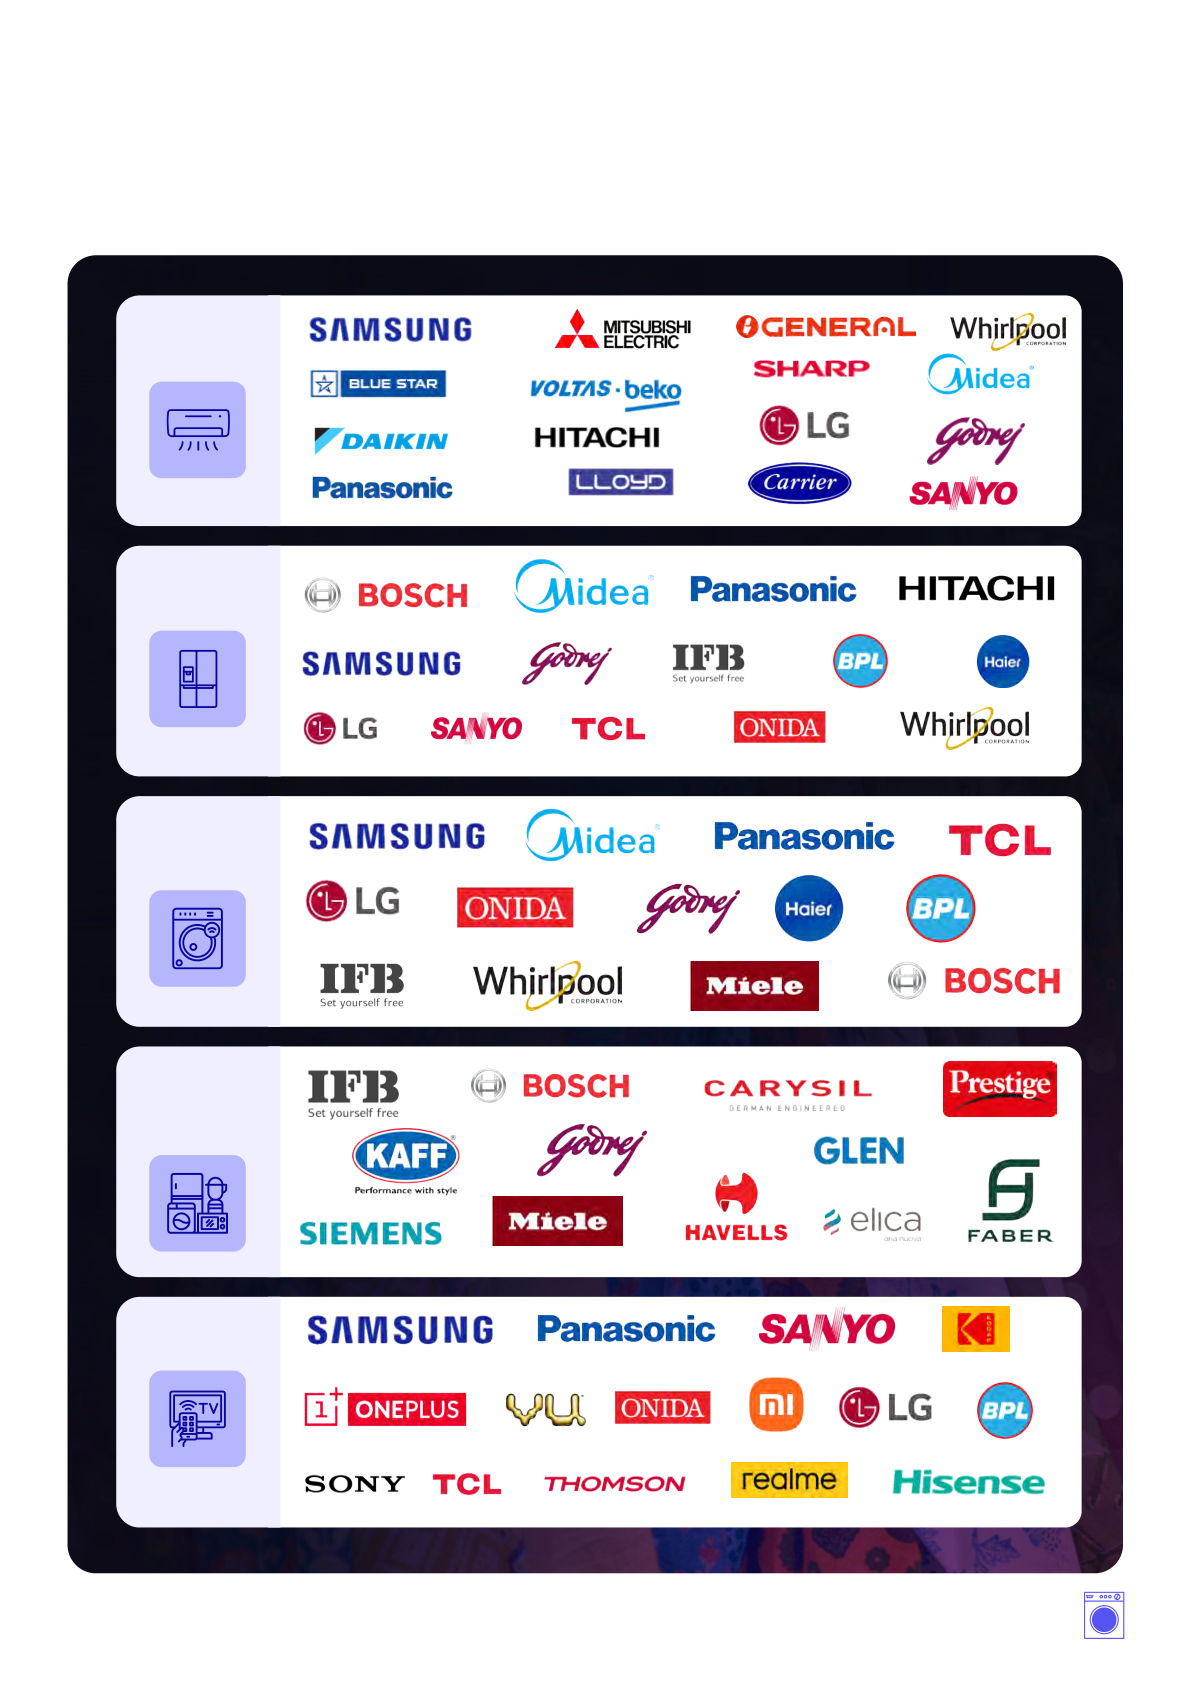
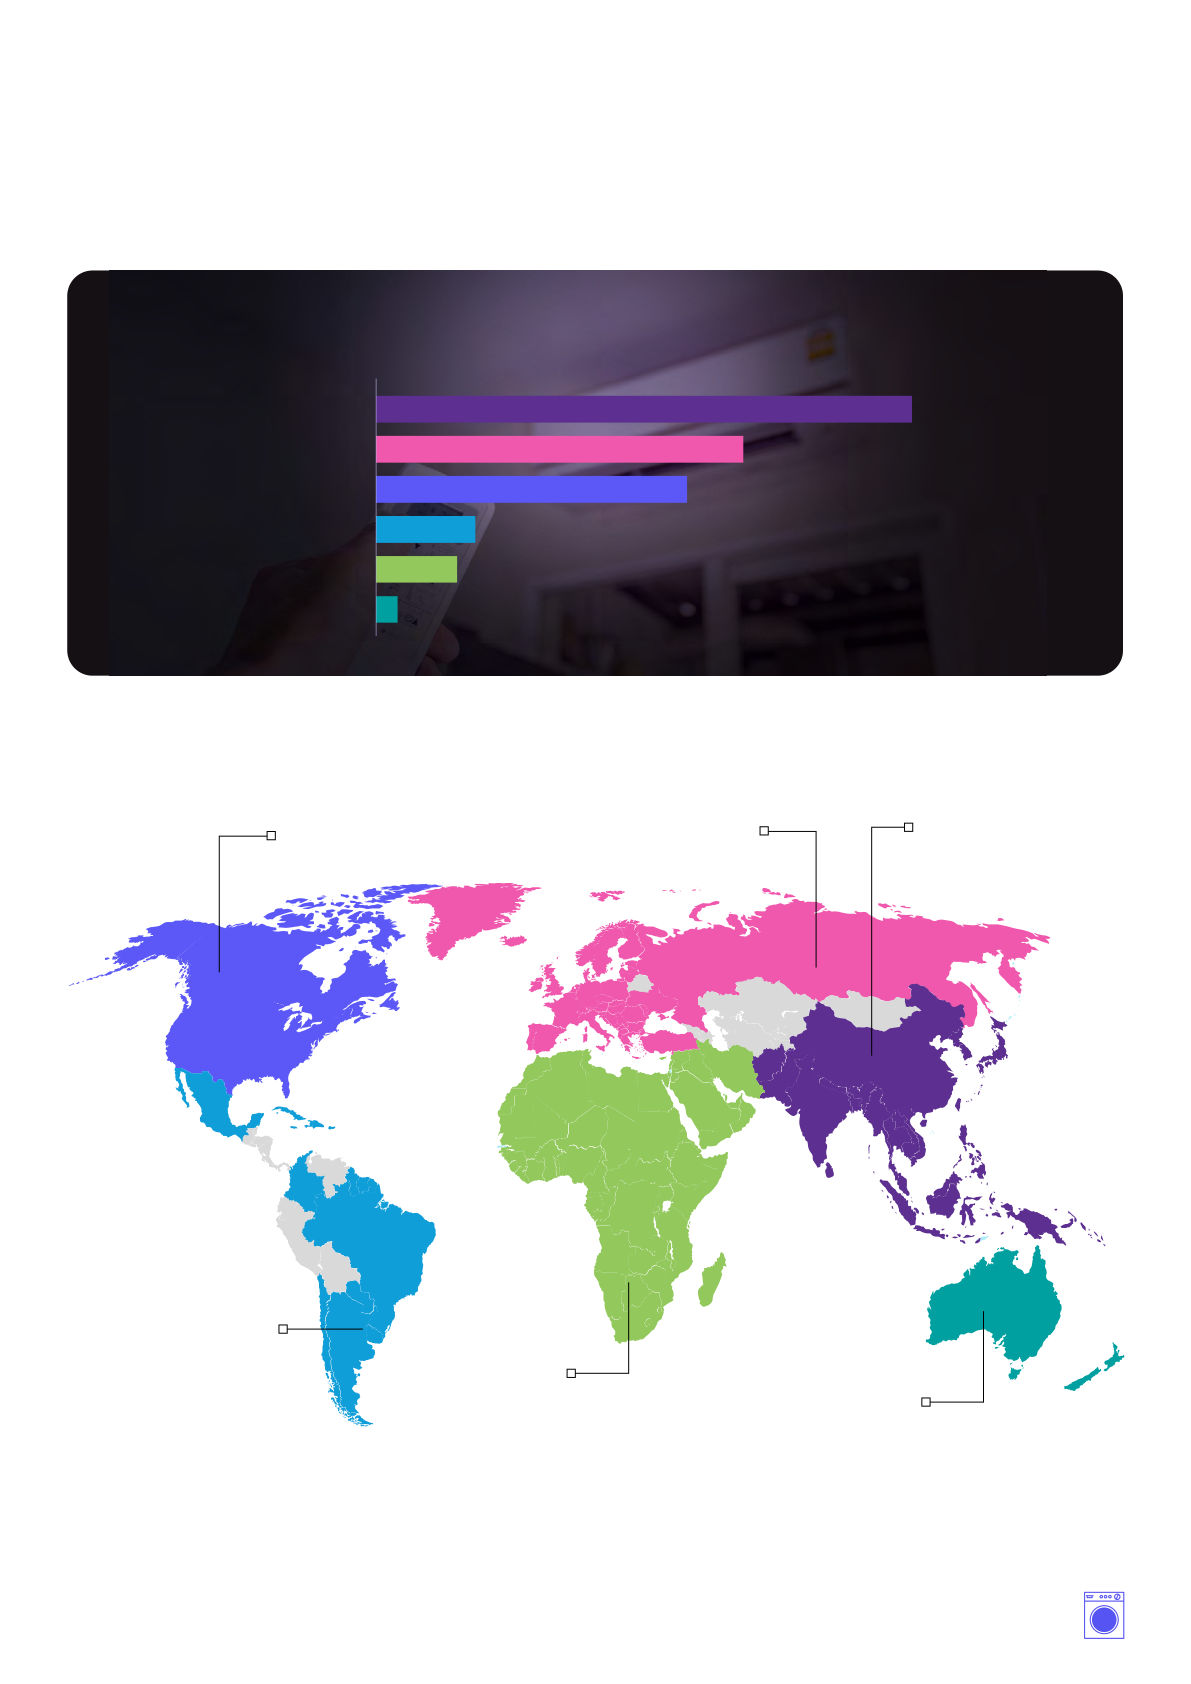
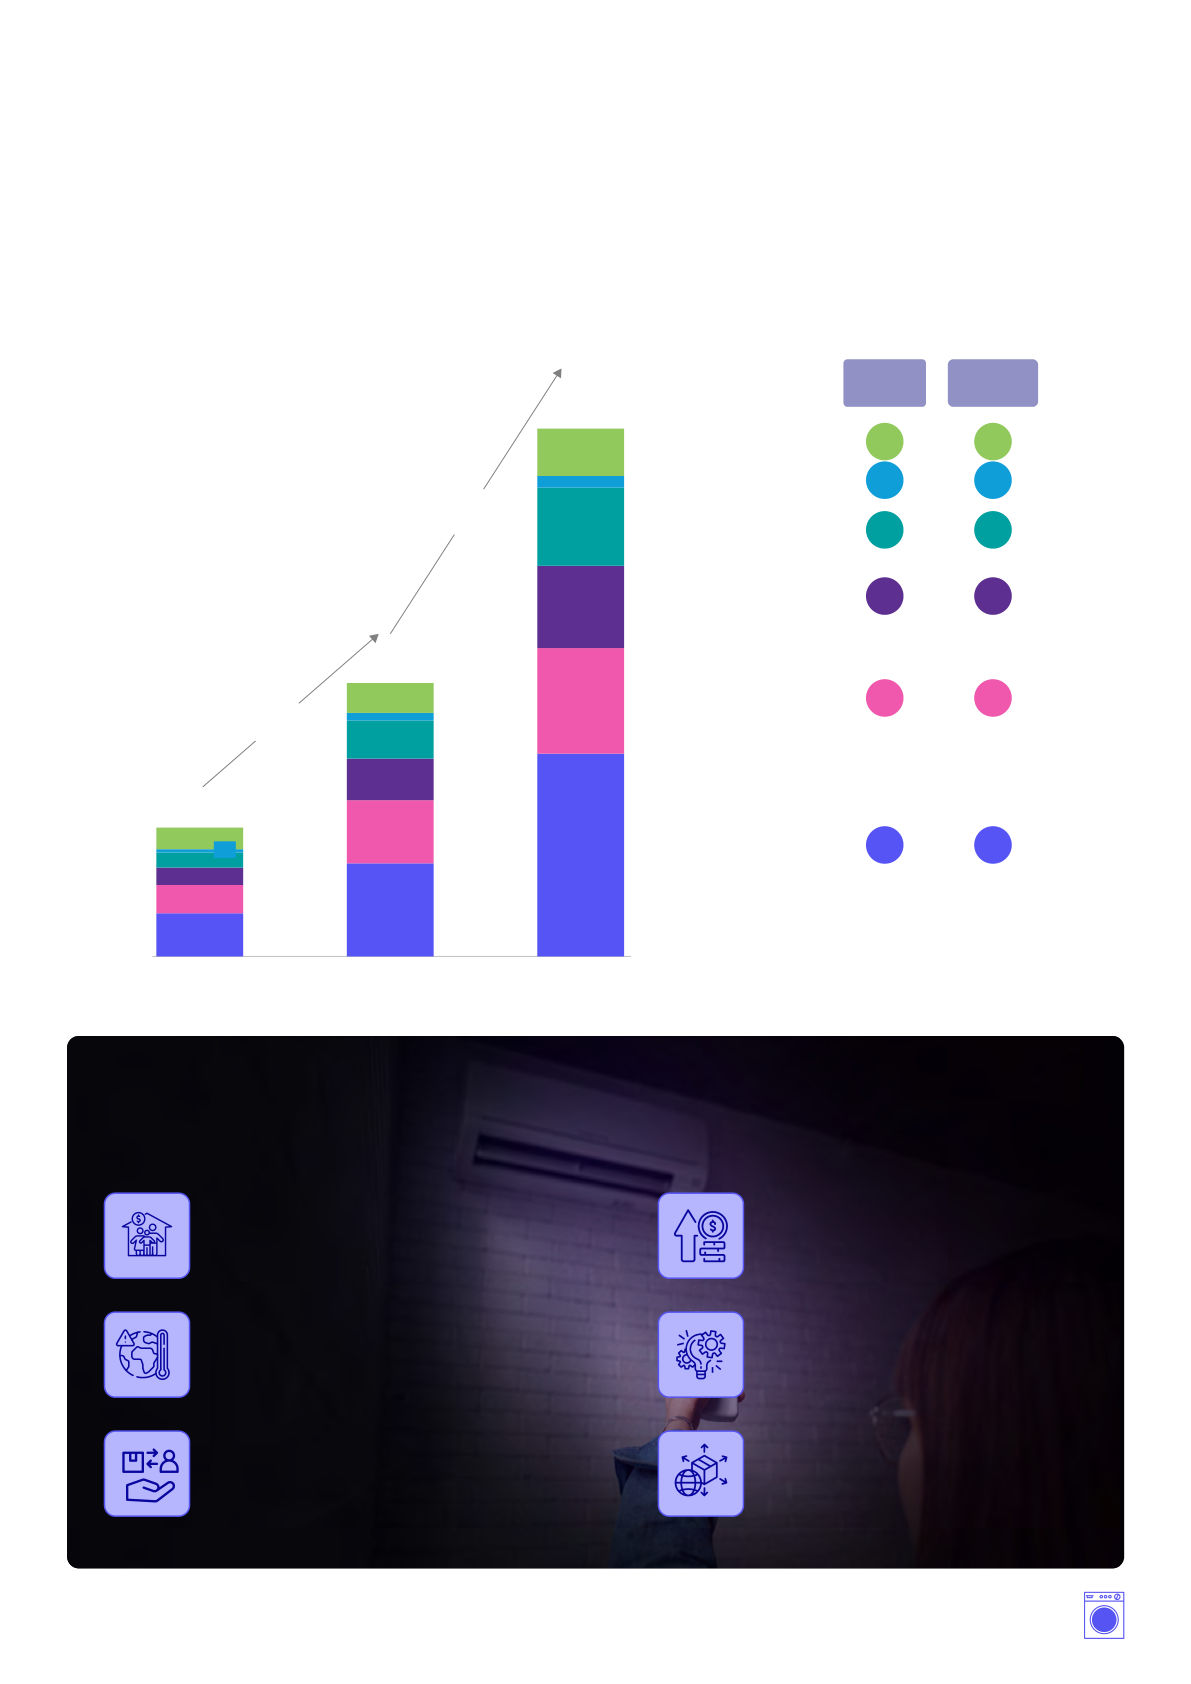
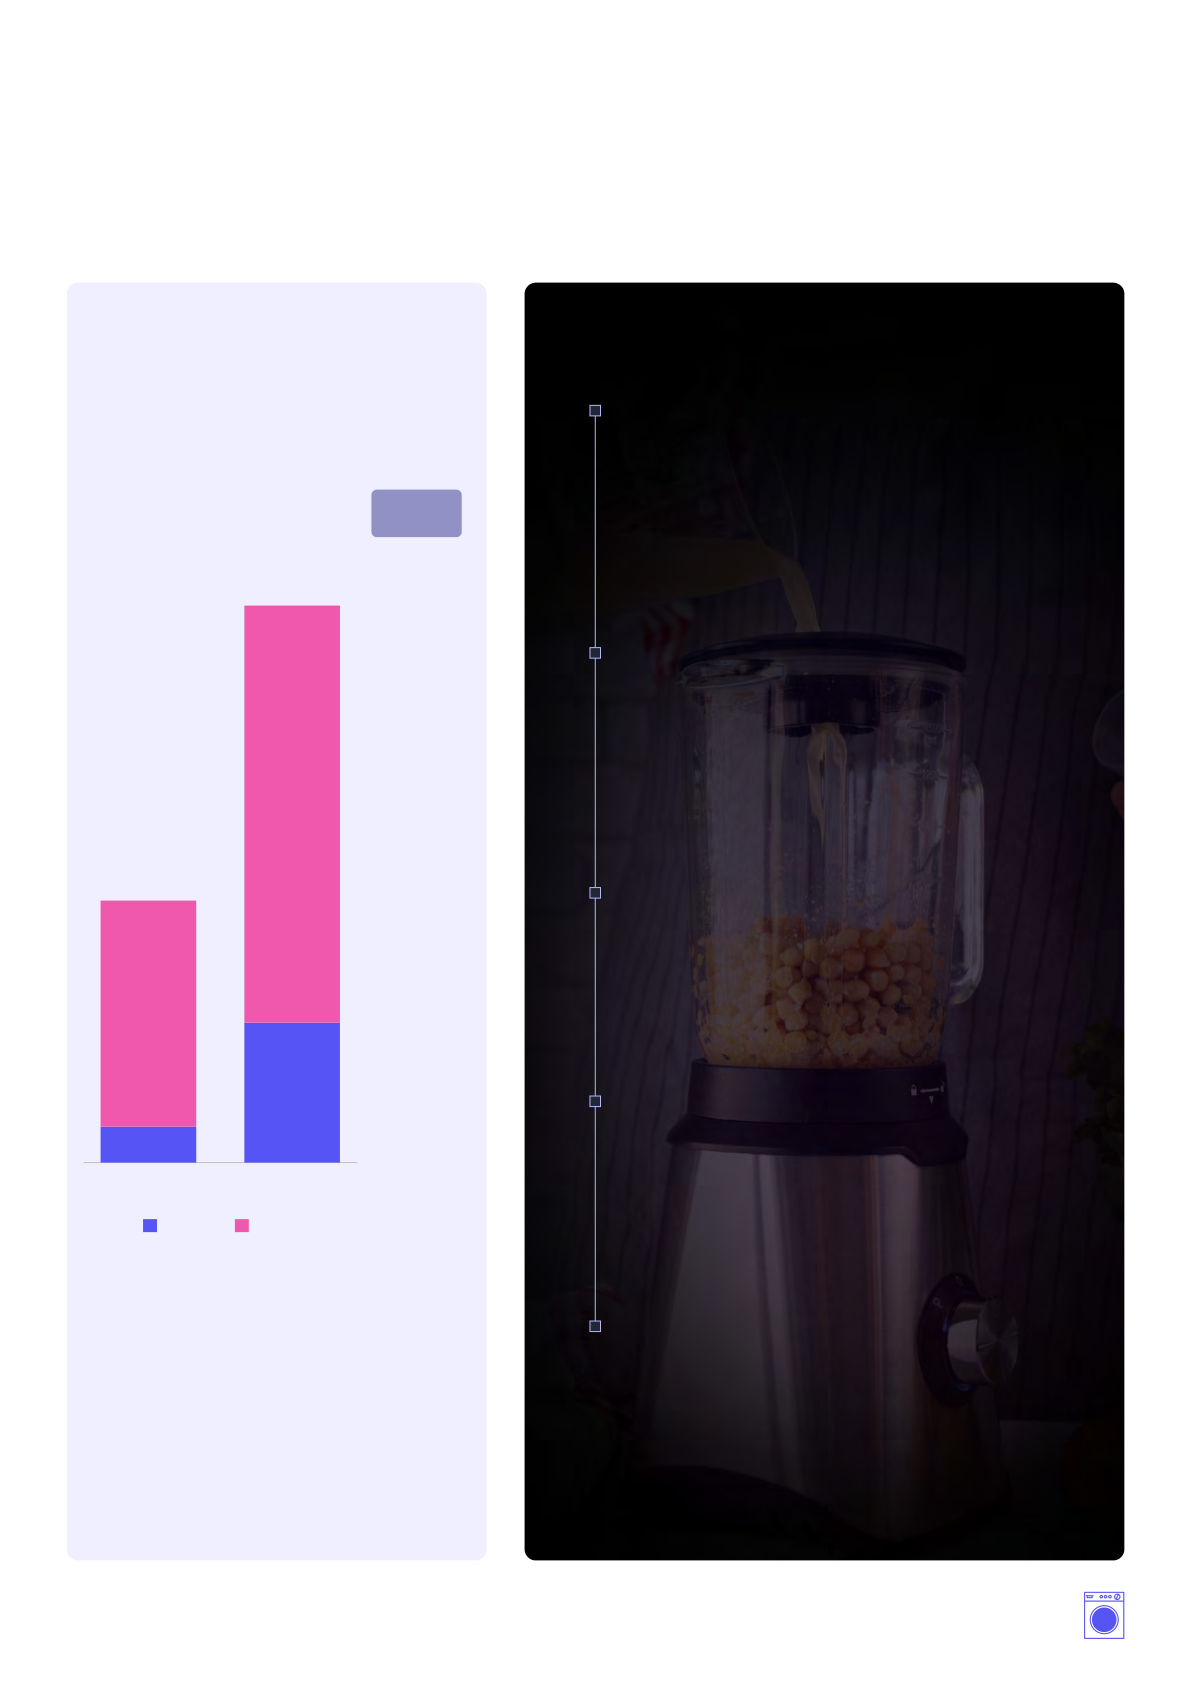
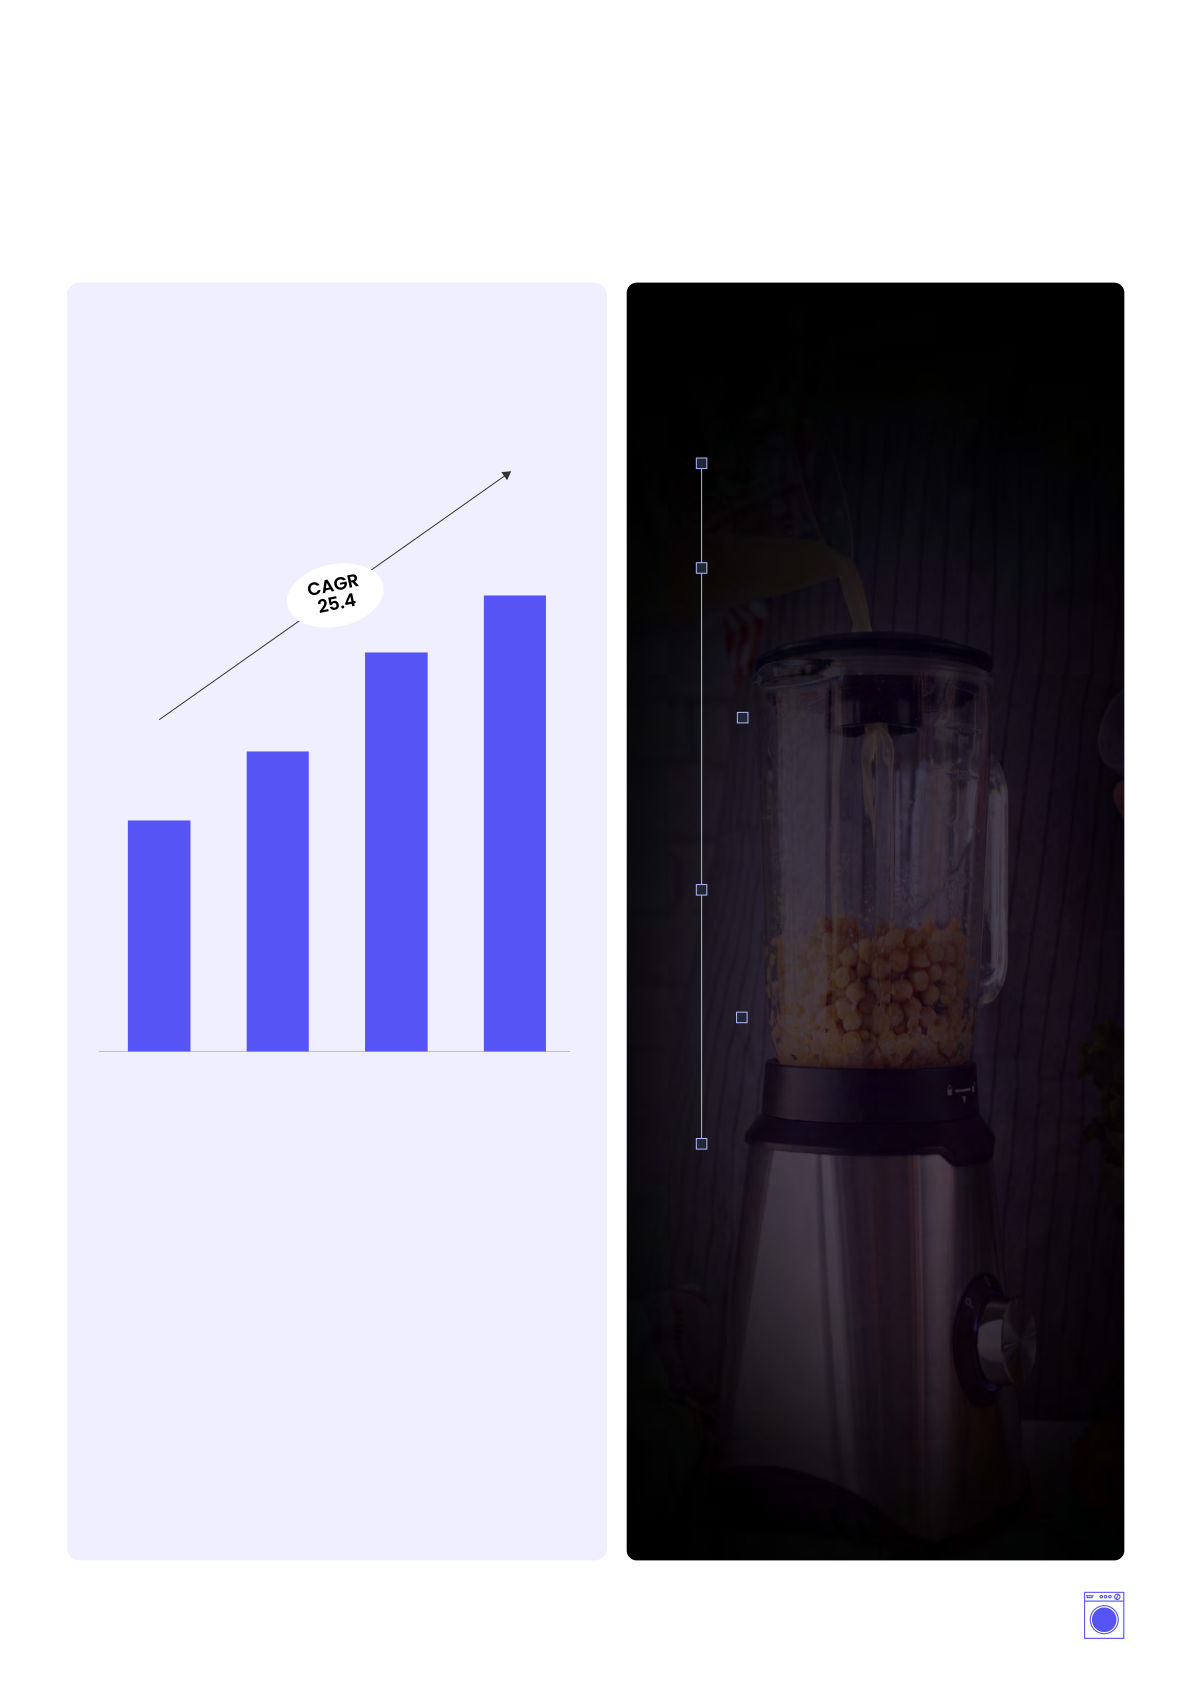
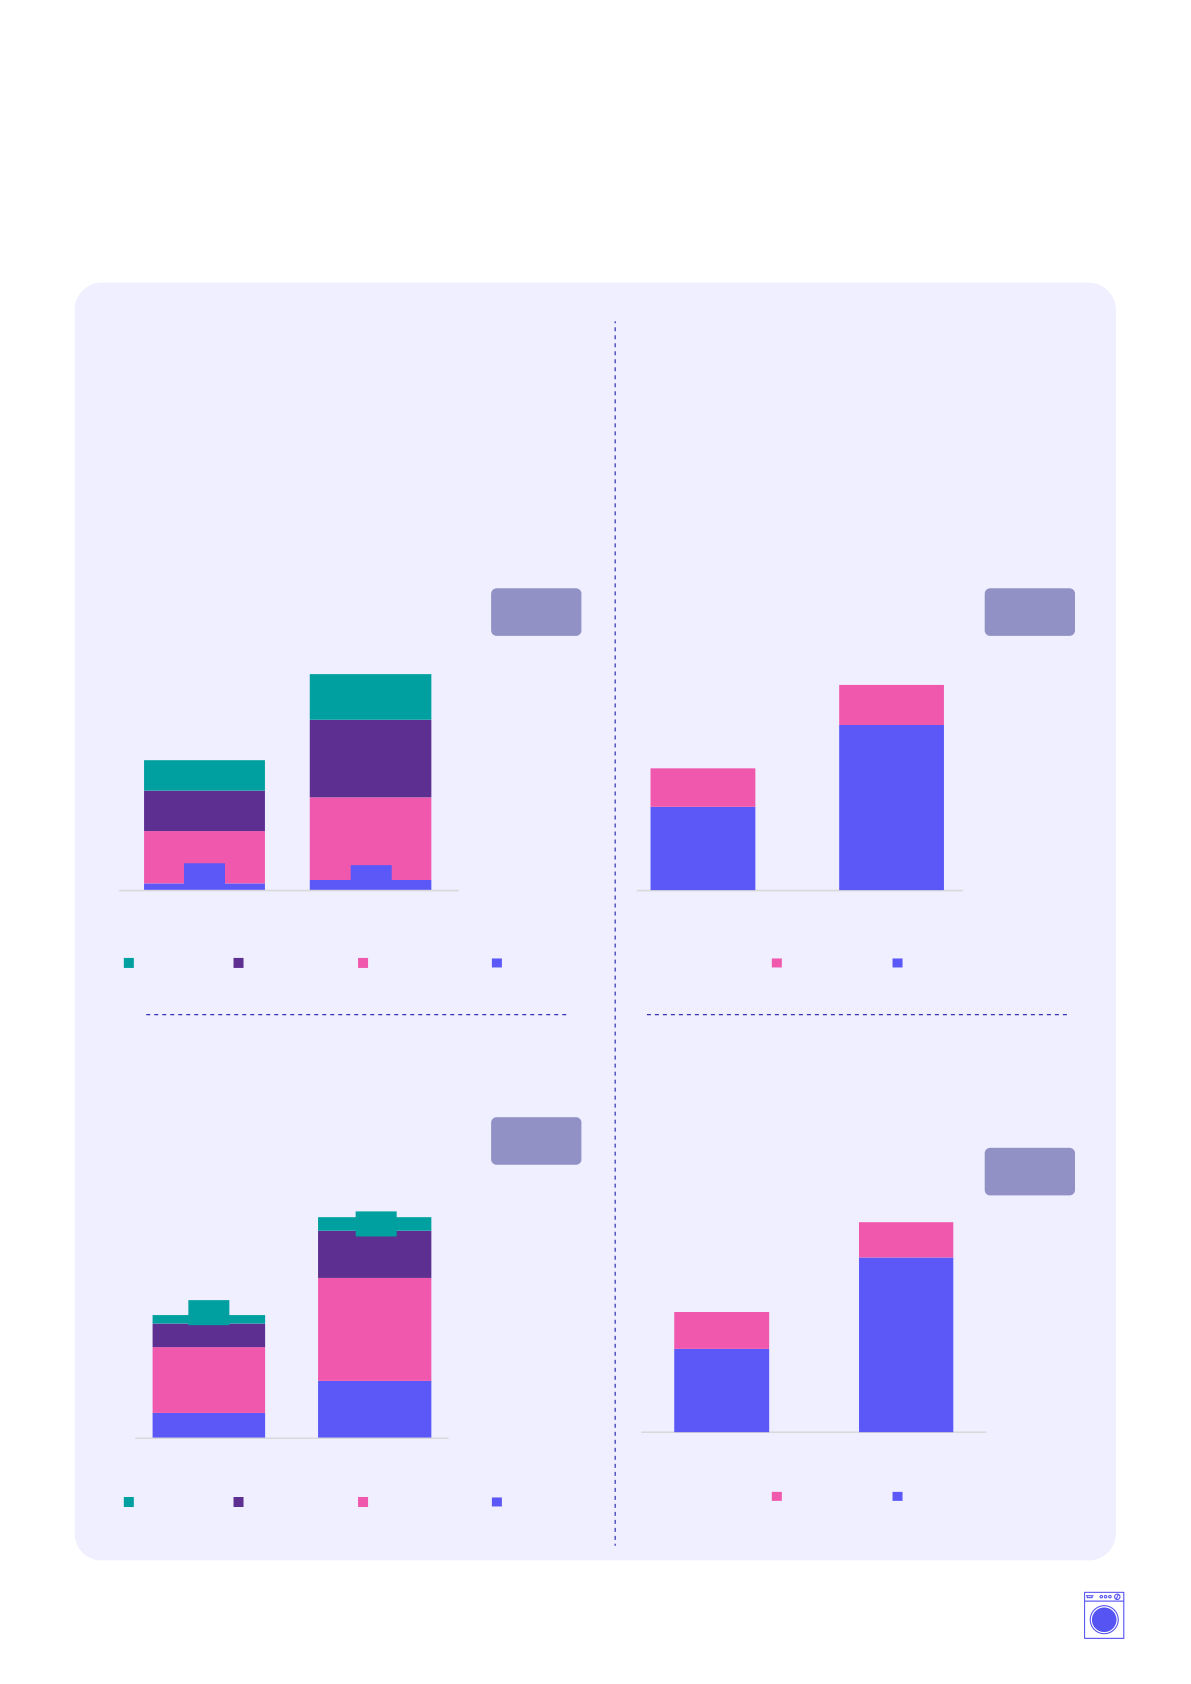
Confidential and proprietary © 1Lattice Foreword India’s consumer durables sector is experiencing transformative disruption, fueled by rising demand for intelligent and energy-efficient solutions. While incumbents continue to anchor the market, the industry is steadily modernizing, integrating advanced technologies while building on established strengths. Growth is increasingly being driven by a dual engine: first-time adoption across underpenetrated categories, and premiumisation as consumers upgrade to larger, smarter, and more efficient products. Categories such as televisions, air conditioners, and refrigerators are at the forefront of this shift, supported by urbanisation, climate-driven demand, and rising digital awareness. Deepening access to consumer finance has further amplified this momentum, with loan originations and portfolio Ashish Dhir outstanding growing steadily over recent years, reflecting both broader market participation and a Senior Director gradual shift toward higher-value purchases. The rise Consumer and Retail of no-cost EMI and e-commerce has democratised access to durables, bringing first-time buyers across income segments into the market and structurally expanding the addressable base. Despite headwinds such as price volatility, regulatory shifts, and intensifying competition from global brands, India continues to represent a high-growth market. Accelerated digital adoption, the rapid rise of e-commerce, and the growing influence of younger consumers are positioning the industry for sustained long-term expansion. This report examines how India’s consumer durables sector is responding to emerging trends, addressing key challenges, and capitalizing on new growth opportunities. As the industry strengthens its global presence, its long-term success will hinge on the ability to drive innovation while sustaining growth. At 1Lattice, we are excited to collaborate with visionaries across industries, fostering meaningful conversations and driving impactful actions to shape a sparkling future together. Product in Spotlight: 1Insights This report has been curated using 1Insights, 1Lattice’s proprietary market intelligence platform designed to deliver structured, data-backed analysis across sectors. Built on a strong foundation of industry research, company disclosures, consumer surveys, and in-house analytics, this edition presents a comprehensive view of India’s Consumer Durables market and its evolving growth trajectory. This report provides a forward-looking view of India’s Consumer Durables industry, covering market size, growth trajectory, and FY30 projections. It analyzes key growth drivers such as premiumization, rising first-time adoption, increasing demand across Tier 2 and Tier 3 markets, and the shift toward smart and energy-efficient appliances. The study examines how evolving consumer behaviour and digital acceleration are reshaping purchase journeys, while mapping the competitive landscape across key categories and decoding the rapid rise of e-commerce in the consumer durables market. Executive summary India’s consumer durables market is set to grow to INR 539K Cr. by FY30, driven by 14% CAGR FY25-30 INR 539K Cr US$ 714B Projected Indian Global consumer consumer durables durables market market by FY30 ~14% ~17% CAGR from Fastest category FY25-30 growth – TV (FY25-30) ~10% Growth ~25% Tier 3 cities Online market share of demand in Q4 total consumer durable in FY25 ~25% ~31% Consumer durable loans Online durables market AUM CAGR (FY22-25) CAGR (FY20-25) © 1Lattice 04 Source(s): Industry reports, Secondary research, 1Lattice analysis 01 Market Overview Market Overview Consumer durables market summary Market Size Challenges • Global consumer durables market projected at • Heavy import dependence on compressors, ~US$ 714B in CY25; Asia Pacific leads at US$ 270B, semiconductors, PCBs, and lighting drivers; followed by Europe (US$ 185B), North America (US$ rupee depreciation inflates input costs; stricter 157B), Latin America (US$ 50B), MEA (US$ 41B), and e-waste, energy efficiency, and recycling Australasia (US$ 10B) compliance norms adding to operational and capital costs • India’s consumer durables market is projected to nearly double from ~INR 280K Cr in FY25 to ~INR • Consumer durable portfolios largely built on 539K Cr by FY30P, growing at ` CAGR global product platforms with design and engineering controlled outside India, limiting • Televisions are the fastest-growing category of the rapid localization to Indian usage patterns, cost consumer durable market at ~17% CAGR (FY25–30P); constraints, and regulatory requirements Washing Machines at 16%, ACs at 15%, Refrigerators at 11%, and Major Kitchen Appliances at 10% • Frequent voltage fluctuations discouraging purchases of ACs, refrigerators, and washing • By FY30P, televisions are expected to lead with ~38% machines; uneven access to piped water market share, followed by refrigerators (~20%), room remains a structural barrier to appliance ACs (~16%) and washing machines (~15%), while adoption in rural and semi-urban markets brown goods (~9%) and major kitchen appliances (~2%) account for a smaller share of the market Growth Trends Drivers • Smart, energy-efficient, and premium appliances • Low household penetration in large appliance — especially TVs, ACs, and refrigerators — driving categories drives first-time adoption; value growth fueled by rising incomes, urban demand, growth outpacing unit growth as consumers and government incentives upgrade to larger, premium, and energy-efficient formats • Online consumer durables market grew at 25% CAGR (FY20–25); online share reached ~25% of • Tier 3 cities outpaced metros in Q4 2024 — 10% total market by FY25 (INR 70K Cr of INR 280K Cr); demand growth vs. 7% (Tier 1) and 6% (Tier 2) — online segment growing at 31% CAGR vs. offline highlighting rural and semi-urban market at 13% acceleration • Innovation is focused on localization and lifecycle • Climate and lifestyle shifts structurally value, with products tailored to Indian usage increasing demand for cooling, refrigeration, patterns, durability, energy efficiency, and ease and health-oriented appliances; of service technology-driven innovation shortening © 1Lattice 06 Source(s): 1Lattice analysis 08 Consumer Durables: Market Segmentation Consumer Durables are categorized into two primary segments: White goods and Brown goods Consumers Durables-Key sub-categories White goods Brown goods Water and Air Home Home audio Refrigerators Air treatment Televisions conditioners laundry and video devices Personal care Small Major kitchen appliances appliances appliances Key focus area © 1Lattice 07 Source(s): Industry reports, Secondary research, 1Lattice analysis 08 Consumer Durables: Market landscape India’s white goods and television market is fiercely contested, with global giants competing across all categories while several brands remain concentrated in specific segments Air conditioners Refrigerators Home laundry Major kitchen appliances Television © 1Lattice Note(s): The above list is indicative and not exhaustive 08 Source(s): Industry reports, Secondary research, 1Lattice analysis 08 Consumer Durables: Market landscape India’s brown goods market is defined by category-specific brand clusters, with limited cross-category presence and growing competition from digital ecosystem Small appliances Water and air treatment products Home audio Personal care appliances Streaming devices and media players © 1Lattice Note(s): The above list is indicative and not exhaustive 09 08 Source(s): Industry reports, Secondary research, 1Lattice analysis Global Consumer durables market The global consumer durables market reached ~US$ 714B in CY25, with Asia Pacific leading as the largest regional market at ~US$ 270B Global Consumer Durables Market Size (US$ B , CY25) Asia Pacific 270 Europe 185 North America 157 Latin America 50 MEA* 41 Australasia 10 US$ 185B US$ 270B US$ 157B US$ 50B US$ 41B US$ 10B © 1Lattice Note(s): *Middle East and Africa 10 Source(s): Industry Reports, 1Lattice analysis 08 Indian Consumer durables market India’s consumer durables market is expected to grow at ~14% CAGR between FY25-30, with televisions emerging as the fastest-growing category at ~17% CAGR Indian Consumer Durables Market Size (INR ‘000 Cr) CAGR CAGR FY20-25 FY25-30P 539 7% 9% 48 Brown Goods Major Kitchen appliances 16% 10% 12 CAGR 14% 80 Washing Machine 20% 16% Room Air conditioner 20% 15% 85 280 Refrigerator 18% 11% 31 108 CAGR 8 16% 39 43 131 65 22 207 Television 16% 17% 4 15 17 29 95 44 FY20 FY25 FY30P Key growth drivers and favorable trends for the Indian consumer durables industry Low household penetration in several large Value growth outpacing unit growth appliance categories continues to drive as consumers upgrade to larger, first-time adoption across income segments , premium and energy-efficient providing a long runway for volume growth appliance formats Climate and lifestyle shifts structurally Technology-driven innovation increasing demand for cooling, refrigeration, shortening replacement cycles and health-oriented household appliances across TVs, air conditioners, and washing machines categories Improving affordability through consumer Expansion of omnichannel financing and wider price segmentation distribution and service networks across product portfolios, expanding the unlocking demand beyond top-tier addressable market metro markets © 1Lattice 11 Source(s): Industry Reports, 1Lattice analysis Channel split: Indian Consumer Durables Market Indian online consumer durable market is growing at ~31% CAGR, led by hyper local logistics, supported by easy financing, hyper local logistics Indian Consumer Durables Market: Tailwinds Channel split (INR ‘000 Cr) Enabling faster delivery & installation for large appliances CAGR FY20-25 Rapid expansion of city-level warehouses, dark stores, and installation-led fulfillment is reducing delivery timelines and failed installations for 280 16% large appliances Driving purchases through embedded financing at checkout Seamless, instant credit integrated into checkout is shifting decisions from affordability- led to desirability-led, especially in premium 13% 210 categories 131 Reducing reliance on physical stores for decision-making Reviews, ratings, comparison tools, and influencer validation are increasing confidence in online purchases of consumer 113 durables 31% 70 Building trust in online channels for high-value 18 purchases FY20 FY25 Standardized installation, service guarantees, Online Offline and warranties are shifting consumer trust from local retailers to e-commerce platforms Expanding assortment beyond physical retail constraints Online platforms can economically list thousands of SKUs, enabling deeper assortment, exclusive variants, and extended model life cycles that physical retail cannot support profitably © 1Lattice 12 Source(s): Industry Reports, 1Lattice analysis 08 Financing Trends: Consumer Durable Loans Rising consumer aspirations and easier credit access are fueling India’s consumer durable market, as reflected in loan AUM nearly doubling from INR 37.4K Cr to INR 73.7K Cr between FY22 and FY25 Consumer durable loans AUM Consumer durable (in INR K Cr, FY22-25) loans market trends Growing urbanization, evolving lifestyles, and easy access to consumer finance are driving the growth of consumer durable loans Demand for financing consumer 73.7 durables primarily comes from the low- to middle-income segment, with young professionals, 64.4 millennials and Gen Z being the most substantial demand drivers No-cost EMI has become a 48.5 popular financing option Growth of e-commerce platforms with the convenience of online 37.4 shopping has increased the accessibility of consumer durables Market share for entry-level TVs, appliances, and mobile phones has declined over the past three years, indicating the consumer shift toward premiumization Market share of premium segment (>INR 30K) accounted for one in every five FY22 FY23 FY24 FY25 smartphones shipped in India in CY24 (~20%) Consumer durable loans have among the highest share of new-to-credit borrowers across consumption loan categories, indicating that first-time buyers are increasingly entering the consumer durable market, pointing to a structurally expanding addressable base © 1Lattice 13 Source(s): Industry Reports, 1Lattice analysis 08 Financing Trends: Ticket Size & Lender Mix Consumer durable loan originations grew at ~19% value CAGR and ~20% volume CAGR between FY22-25, driven by deeper credit penetration and a gradual shift toward higher-value purchases Originations have shifted toward mid- and NBFCs have steadily gained market higher-ticket loans, with the INR 25–50K share over banks by both value and segment gaining share by both value and volume, driven by extensive volume between FY22 and FY25, indicating point-of-sale financing networks, shorter early signs of premiumization replacement cycles, and deeper penetration in underpenetrated markets Consumer durable loans originations Consumer durable loans originations value-by Ticket size value- by lender type (in INR K Cr, % ) (in INR K Cr, % ) CAGR CAGR FY22-25 FY22-25 160 19% 19% 160 0.3% 22% 17% 19% 96 36% 96 23% 23% 32% 32% 81% 26% 16% 38% 41% 68% 18% 5% 5% FY22 FY25 FY22 FY25 >INR 50K INR 25-50K INR 10-25K <INR 10K Pvt Banks NBFCs Consumer durable loans originations Consumer durable loans originations volume-by Ticket size volume- by lender type (in L, % ) (in L, % ) CAGR FY22-25 CAGR FY22-25 778 20% 778 20% 15% 6% -2% 16% 24% 21% 449 449 7% 30% 47% 16% 28% 19% 84% 52% 70% 26% 33% 19% FY22 FY25 FY22 FY25 Pvt Banks NBFCs >INR 50K INR 25-50K INR 10-25K <INR 10K © 1Lattice 14 Source(s): Industry Reports, 1Lattice analysis 08 Indian Economic Policy for white goods Indian Economic Policy for white goods Flagship schemes under Viksit Bharat Viksit PM Awas Yojana - Urban Bharat Deliver durable, eco-friendly housing for EWS, LIG, and MIG segments using resilient, sustainable 2047 construction technologies Startup India Transform India into a global Encourages innovation in appliance design, manufacturing powerhouse for energy efficiency, IoT integration, and consumer durables, especially component manufacturing appliances and electronics , positioning the country as a key player in global supply chains Ujala Yojana Prioritize energy efficiency and Accelerates adoption of energy-efficient sustainability , while boosting appliances, reinforcing sustainability and lower household energy costs domestic value addition in white goods manufacturing to reduce import dependence Digital Payment Infrastructure Accelerate local manufacturing Advancing economic digitization with 40% of through PLI schemes , a thriving transactions conducted through digital platforms. startup ecosystem , and deeper Also, facilitates financing, EMI-led purchases, and component localization omni-channel retail adoption Fuel demand growth via rapid Saubhagya electrification , housing Yojana expansion , and increasing digital adoption across households Ensuring universal household electrification by providing free power connections to rural homes and enabling appliance penetration across Empower MSMEs with improved underserved regions financing access and integration into supply chains, strengthening the backbone of appliance Pradhan Mantri manufacturing MUDRA Yojana Providing affordable credit to non-corporate, Advance the vision of Atmanirbhar non-farm small and micro enterprises for Bharat , enhancing export income-generating activities beyond agriculture competitiveness and building a resilient, future-ready manufacturing sector © 1Lattice 15 Source(s): Industry reports, Secondary research, 1Lattice analysis 08 Headwinds Key headwinds constraining growth in India’s consumer durables market include rising input costs, import dependence, regulatory escalation, limited domestic R&D, and uneven infrastructure readiness Rising input costs in a Limited Domestic 01 04 price-sensitive market Product R&D • Rising commodity and component • A significant portion of consumer costs, especially metals, durable portfolios in India are built semiconductors, and memory, are on global product platforms with elevating bills of materials and design and engineering squeezing OEM profitability controlled outside the country • Elevated input costs have forced price • This limits rapid localization to increases across appliances and Indian usage patterns, cost electronics, dampening affordability constraints, and regulatory and price elasticity. Smaller brands and requirements mass SKUs are most impacted as OEMs struggle to absorb costs without sacrificing volumes Import dependence Electrification/ 02 05 and currency exposure piped water • India’s consumer durables industry • Significant progress has been remains heavily dependent on achieved in expanding rural imported components such as electrification, but a comparable compressors, semiconductors, PCBs, push is needed to ensure access and lighting drivers. Rupee depreciation to safe, piped drinking water directly inflates input costs, • Frequent voltage fluctuations can compressing margins or forcing price harm household appliances, hikes in a price-sensitive market discouraging consumers from • Despite PLI progress, local value purchasing expensive electrical addition remains limited, keeping goods such as air conditioners, currency risk structurally embedded refrigerators, and washing machines Regulatory & compliance 03 cost Escalation • Stricter e-waste, energy efficiency, and recycling compliance norms are increasing operational and capital costs for manufacturers • Higher collection targets and compliance enforcement are adding to cost structures, forcing difficult trade-offs between margin absorption and consumer price increases © 1Lattice 16 Source(s): Invest India, Ministry of Textiles, Government of India 08 02 Future trends and outlook Key Trends: Category wise Consumer preferences are increasingly experience and efficiency-led, shaping demand across consumer durables through smart functionality, performance reliability, and energy efficiency Televisions • Television demand is increasingly experience-driven , with smart functionality now baseline, as 76% of consumers prioritize Smart TV systems and OTT integration, making non-smart models increasingly marginal • Display and audio performance remain critical, with 66% focusing on screen size, 55% on resolution, and 59% on sound quality, while 58% cite design aesthetics as a differentiator • Channel behavior shows high digital comfort , with ~70% of purchases via multi-brand outlets and e-commerce Air Conditioners • Air conditioner demand is driven by cooling performance and efficiency , with 75% of consumers prioritizing fast cooling and 67% focusing on cooling capacity • Inverter-based systems are preferred, with 53% valuing efficient inverter compressors , indicating a shift away from fixed-speed models, while post-COVID expectations have increased demand for air filtration (40%) and quieter operation (51%) • Purchases remain comparison-led, with 44% via multi-brand outlets and 23% through e-commerce , and satisfaction closely tied to after-sales service (54%) Refrigerators • Refrigerator purchases reflect a long-term utility mindset , with 64% of consumers prioritizing storage capacity and 62% valuing interior flexibility • Cooling consistency outweighs speed , as 41% seek long-lasting cooling retention, while perceived value remains strong, with 55% of consumers associating refrigerators with good value for money • Buying behavior remains largely offline , with ~50% of purchases through multi-brand outlets Washing Machines • Washing machine decisions are utility-led, with 63% of consumers prioritizing the type of washing machine (e.g., top-load vs front-load, automatic vs semi-automatic) and 61% focusing on size and capacity • Wash versatility matters to 58% of consumers, while 55% emphasize low power consumption as a key value driver • Multi-brand outlets dominate purchases, while online channels account for ~40% of transactions in select segments © 1Lattice 18 Source(s): In-depth interviews (N=30), White goods consumer survey (N = 1,094), 1Lattice analysis 08 Future Innovation > Consumer durables Future innovations in consumer durables; Category wise Televisions Larger screens at mass price points: Manufacturers are aggressively scaling local sourcing and assembly to bring 55” and above screens into mid-income affordability. This is expanding demand beyond metros and accelerating replacement-driven upgrades Integrated home entertainment hubs: TVs are increasingly positioned as the primary home entertainment device, consolidating streaming, audio, gaming, and smart home controls Lower energy intensity per inch: As average screen sizes rise, innovation is focused on improving panel efficiency to limit power consumption growth Refrigerator Storage designed for Indian consumption: Interior layouts are increasingly optimized for fresh food, bulk storage, and longer preservation cycles aligned with Indian cooking habits Consistency over Peak Performance: Product development prioritizes uniform cooling and temperature stability rather than just faster chilling claims Lifecycle efficiency focus: Energy efficiency and compressor durability are becoming key purchase drivers due to rising electricity costs Washing Machine Fabric-centric wash systems: Machines are moving away from generic programs toward gentler, load-specific wash actions that extend garment life Water-efficient design evolution: Innovation is centered on reducing water consumption per cycle without compromising wash outcomes Reliability and ease of service: Design simplification and motor improvements are reducing breakdowns and service frequency Air Conditioner Comfort over cooling speed: Innovation is shifting from rapid temperature drop to stable, uniform room comfort Sustained energy performance: Newer systems focus on maintaining efficiency over years of use, not just at installation Adaptation to Indian climatic extremes: ACs are increasingly designed to operate reliably in high heat, dusty environments, and unstable power conditions common across Indian regions Source(s): Industry reports, 1Lattice analysis © 1Lattice 19 08 We are here for you Let us know how we can meet your business requirement? Ashish Dhir Senior Director, Consumer & Retail E: ashish.dhir@1lattice.com Ambuj Gupta Associate Director, Consumer & Retail E: ambuj.gupta@1lattice.com For media queries, Corporate Communications communications@1lattice.com please contact www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. 4 200+ Offices in India Annual engagements 130+ 50+ Team members Inhouse research team 1,000+ 2M+ On-ground staff B2C Panel 300K+ 100K+ B2B Panel Experts & professionals 20% 100% Cost savings Controlled output & timeline What We Do Making organizations effective through data-driven insights, Vision innovative products solutions and proven expertise to enable better decisions To provide technology led solutions that unlock that power of trustable data, actionable research, and deep network Mission of experts Technology Data + People/ Accumulated Professionals/ knowledge Service providers Research +91 987 165 4747 ashish.dhir@1lattice.com Delhi NCR | Mumbai | Bengaluru | SEA | MEA