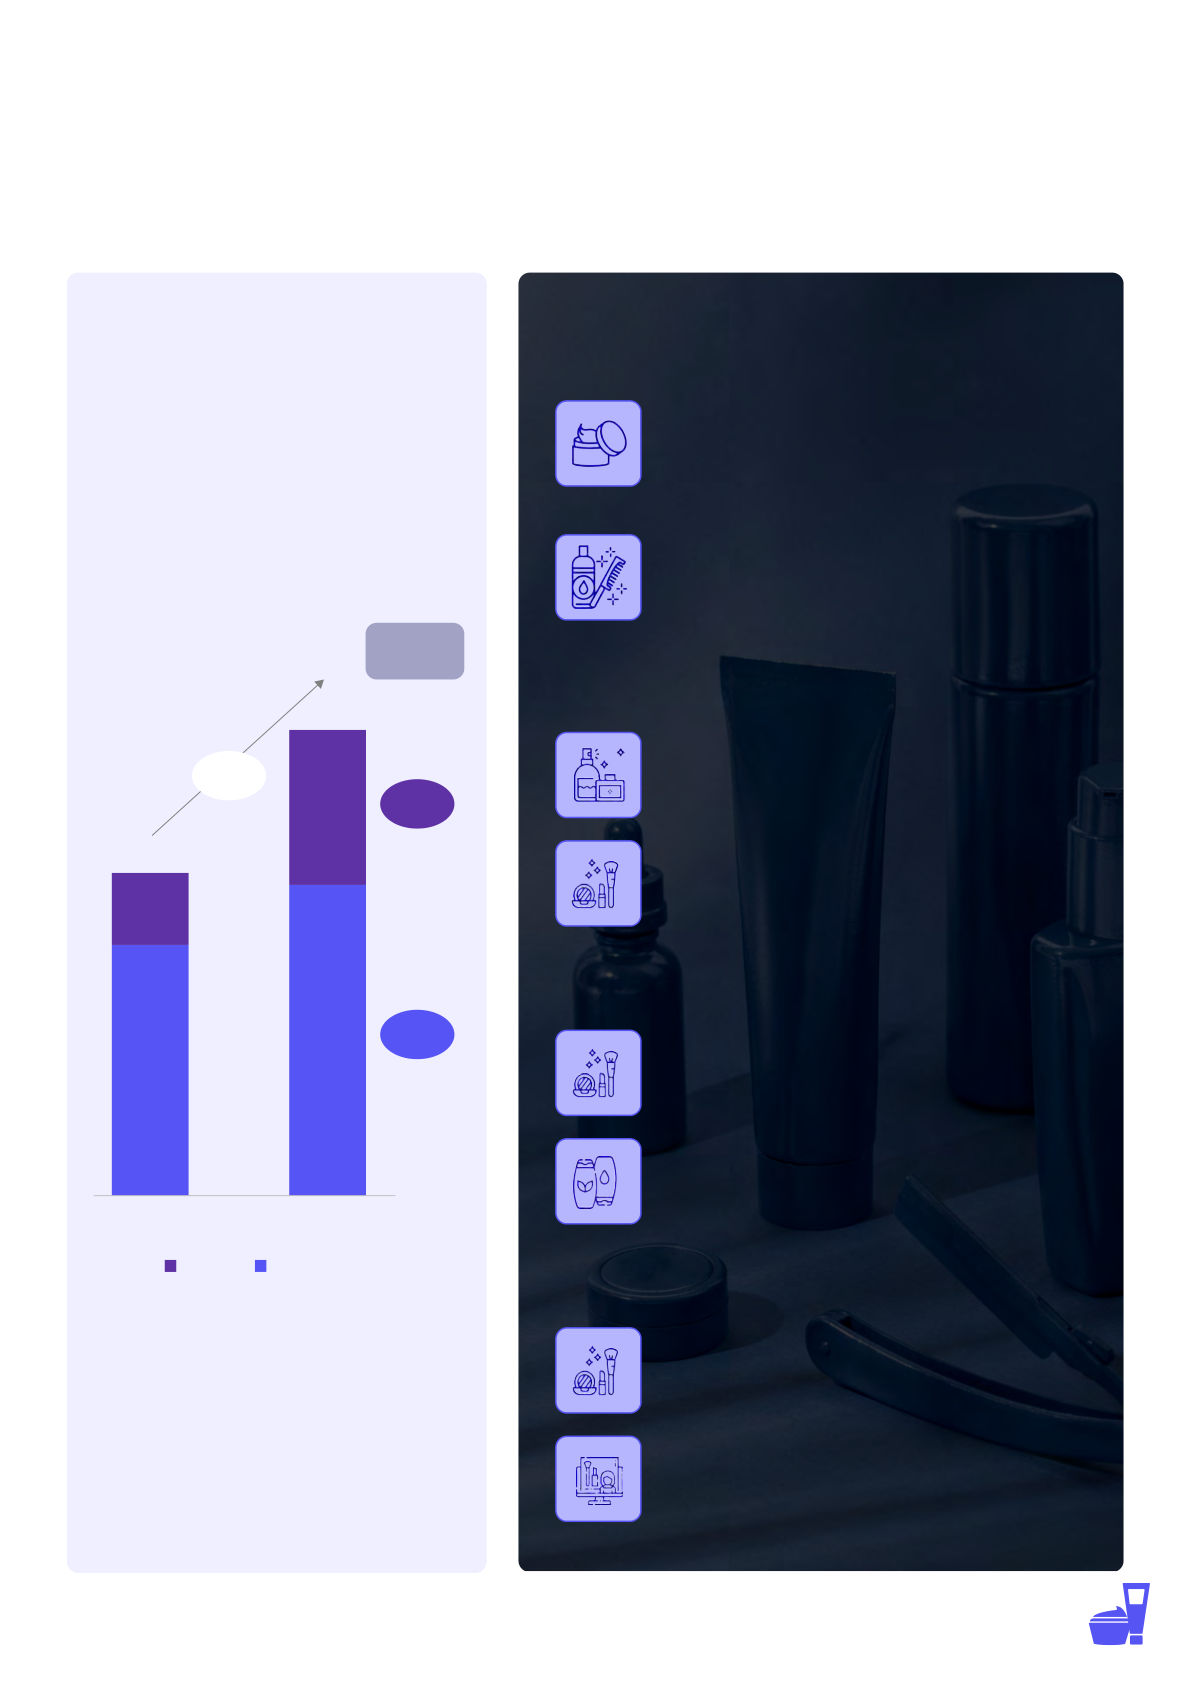
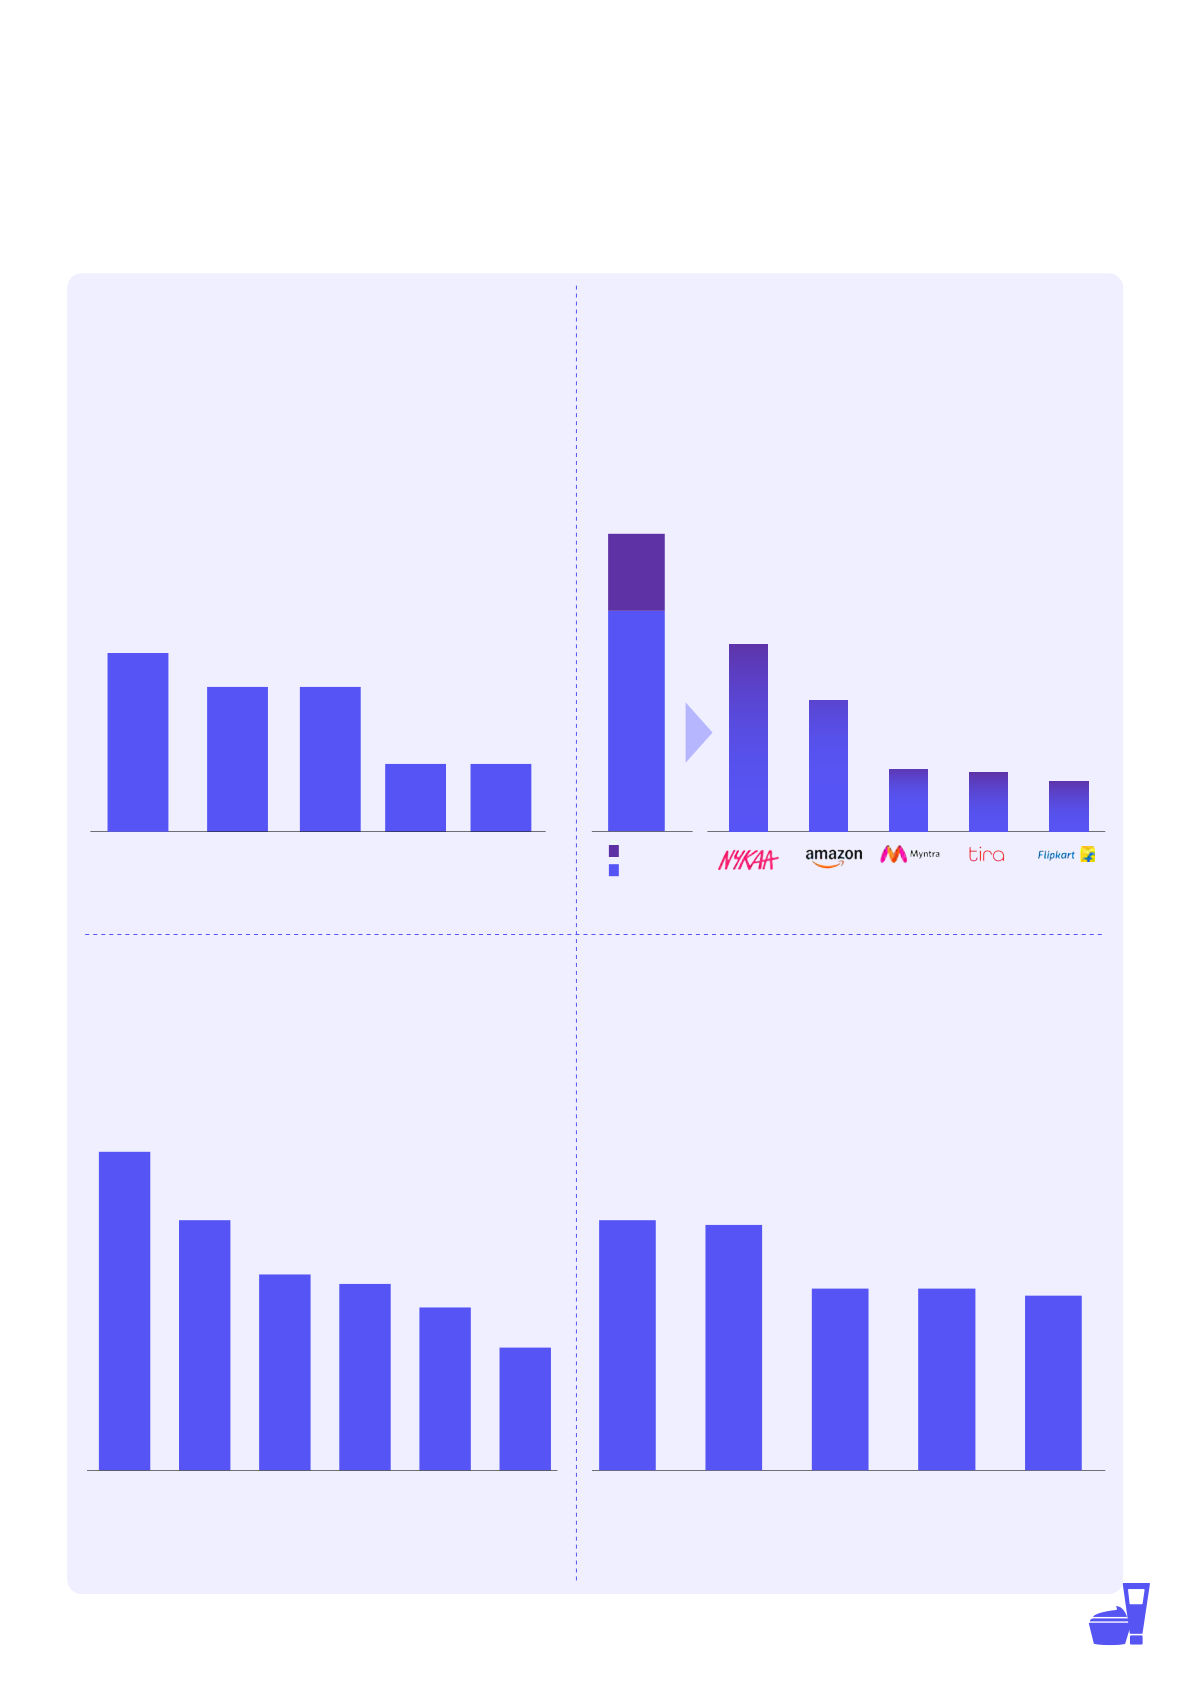
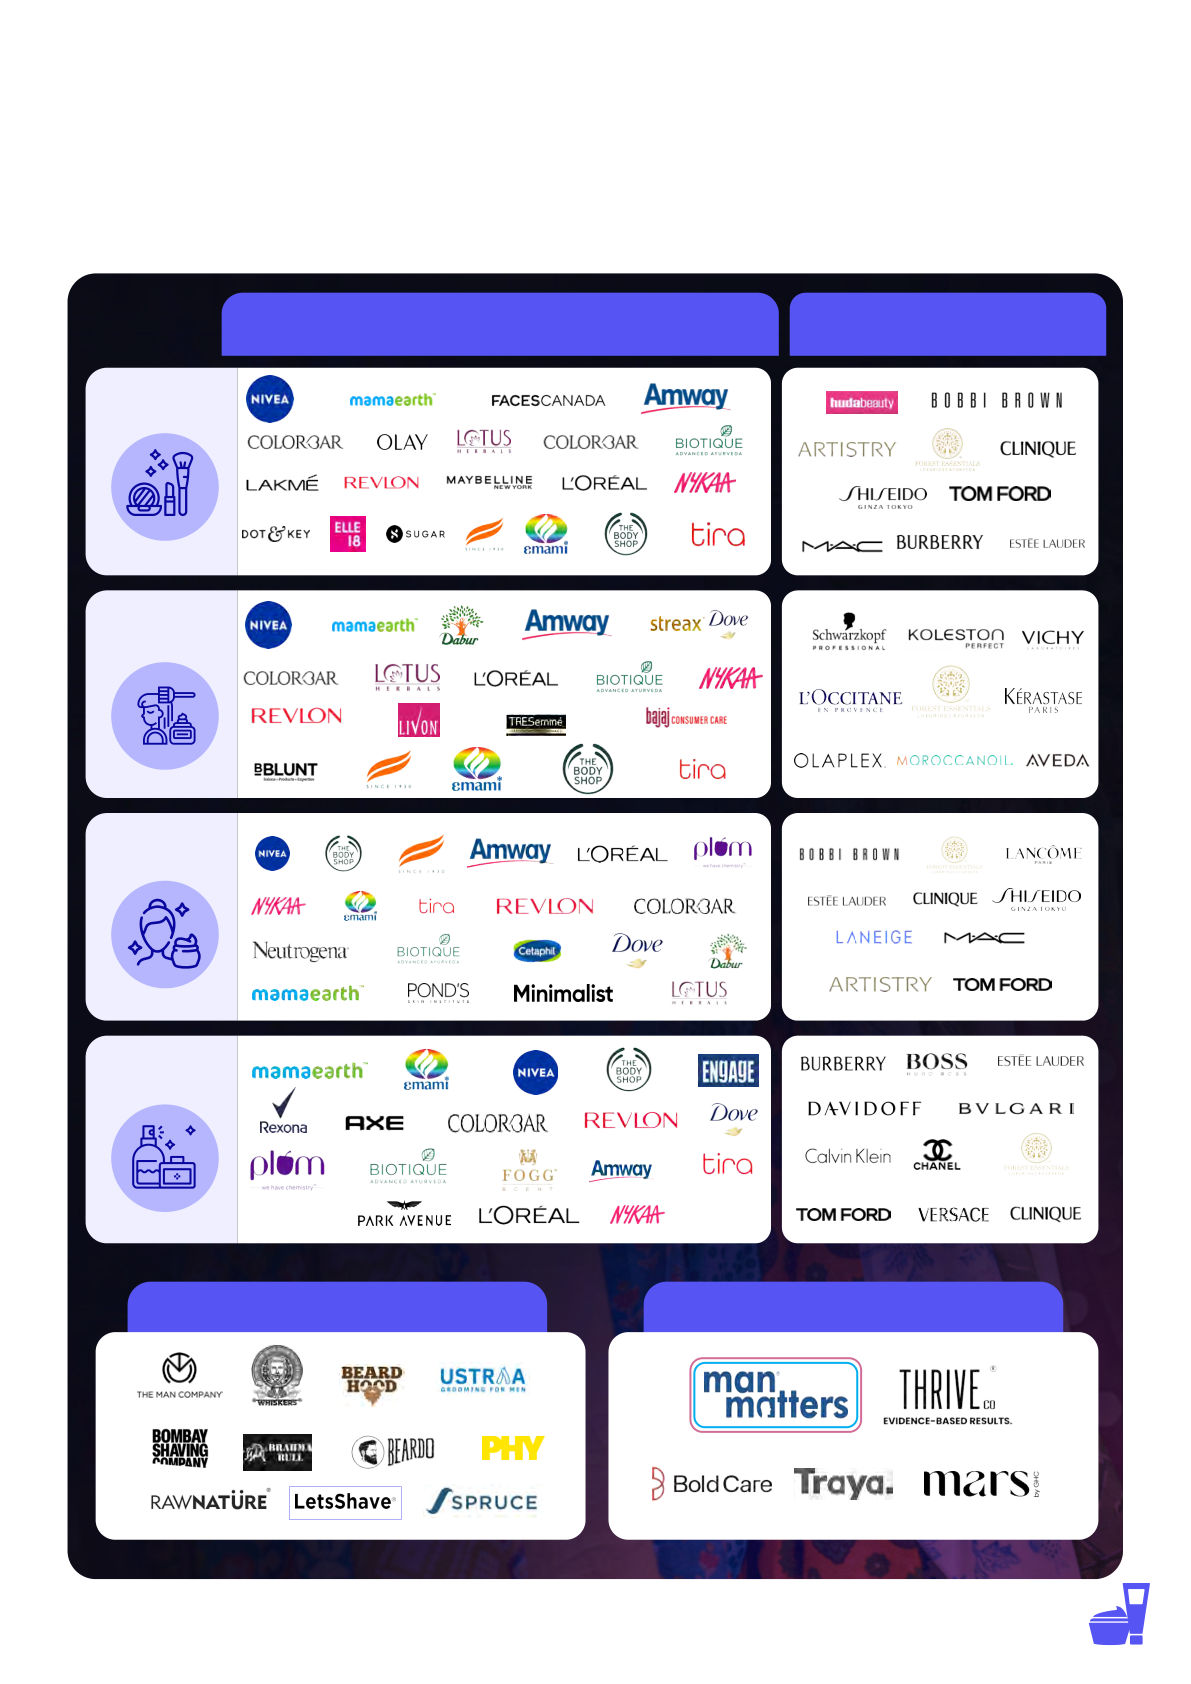
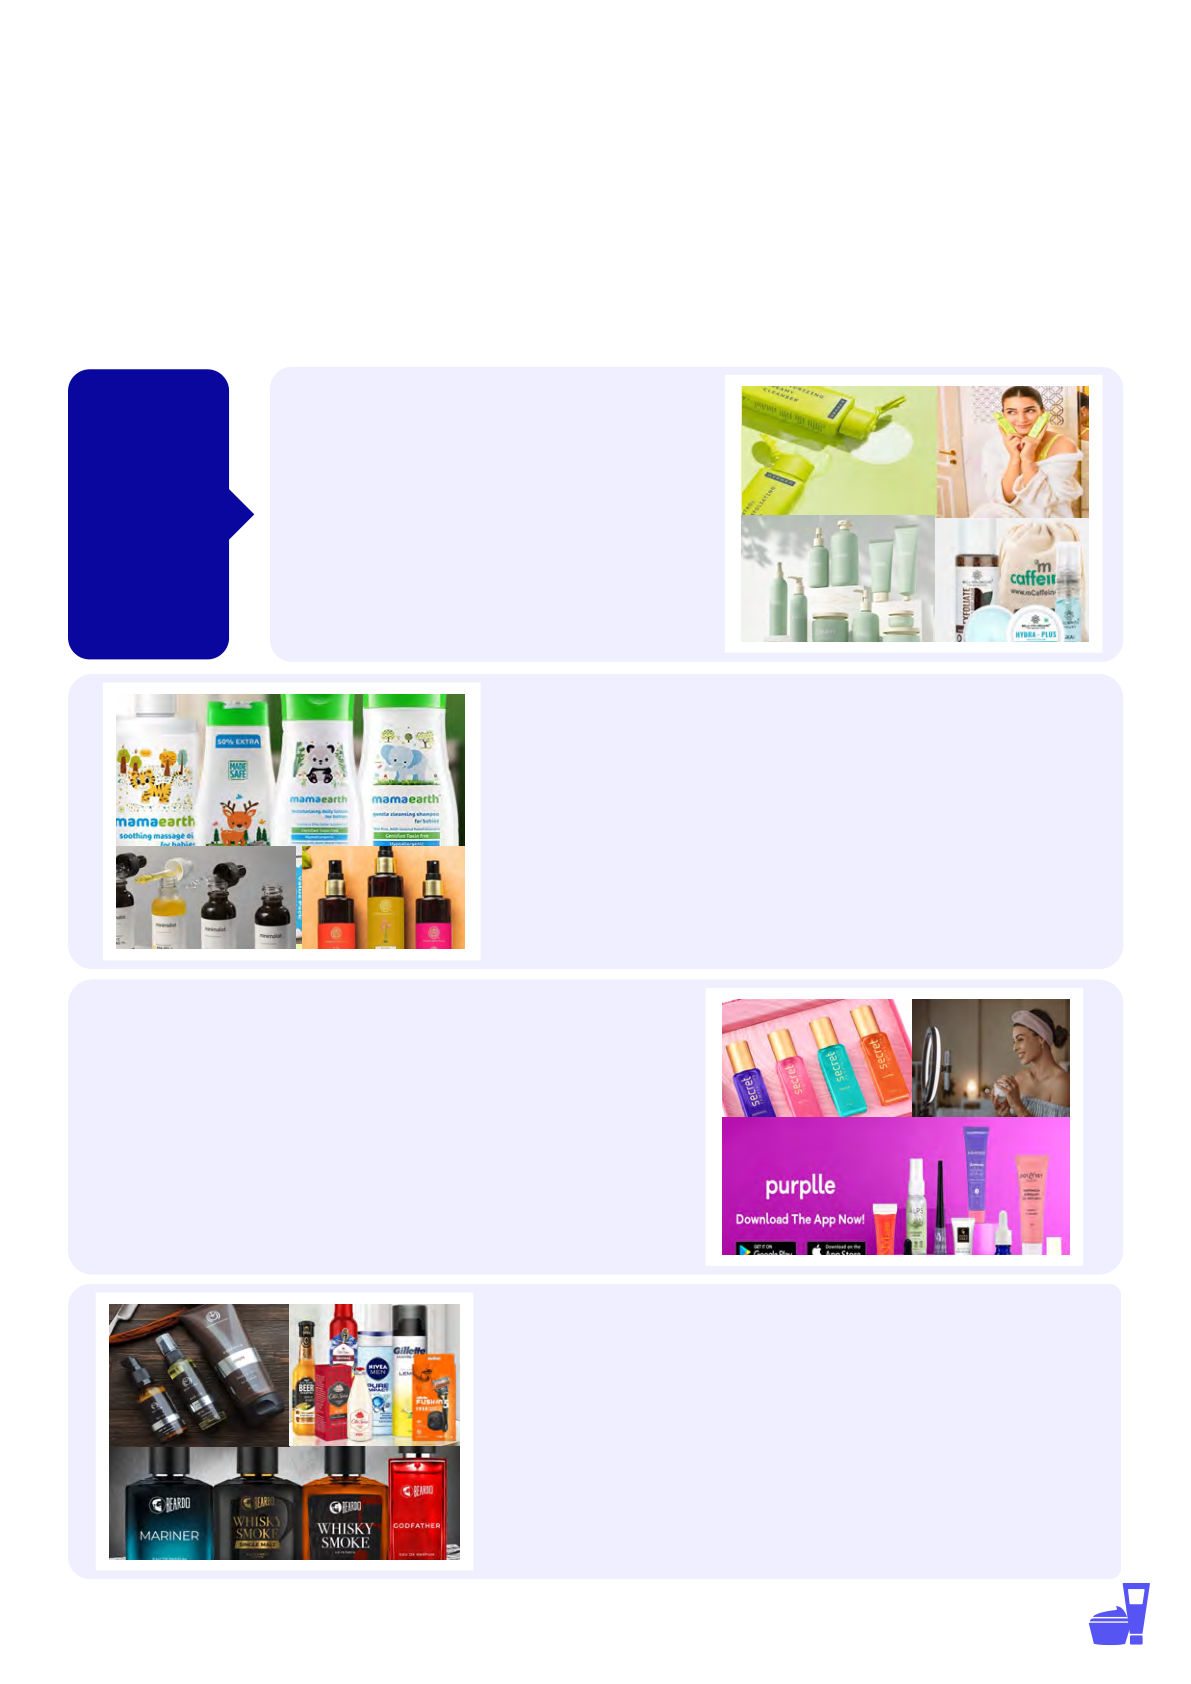
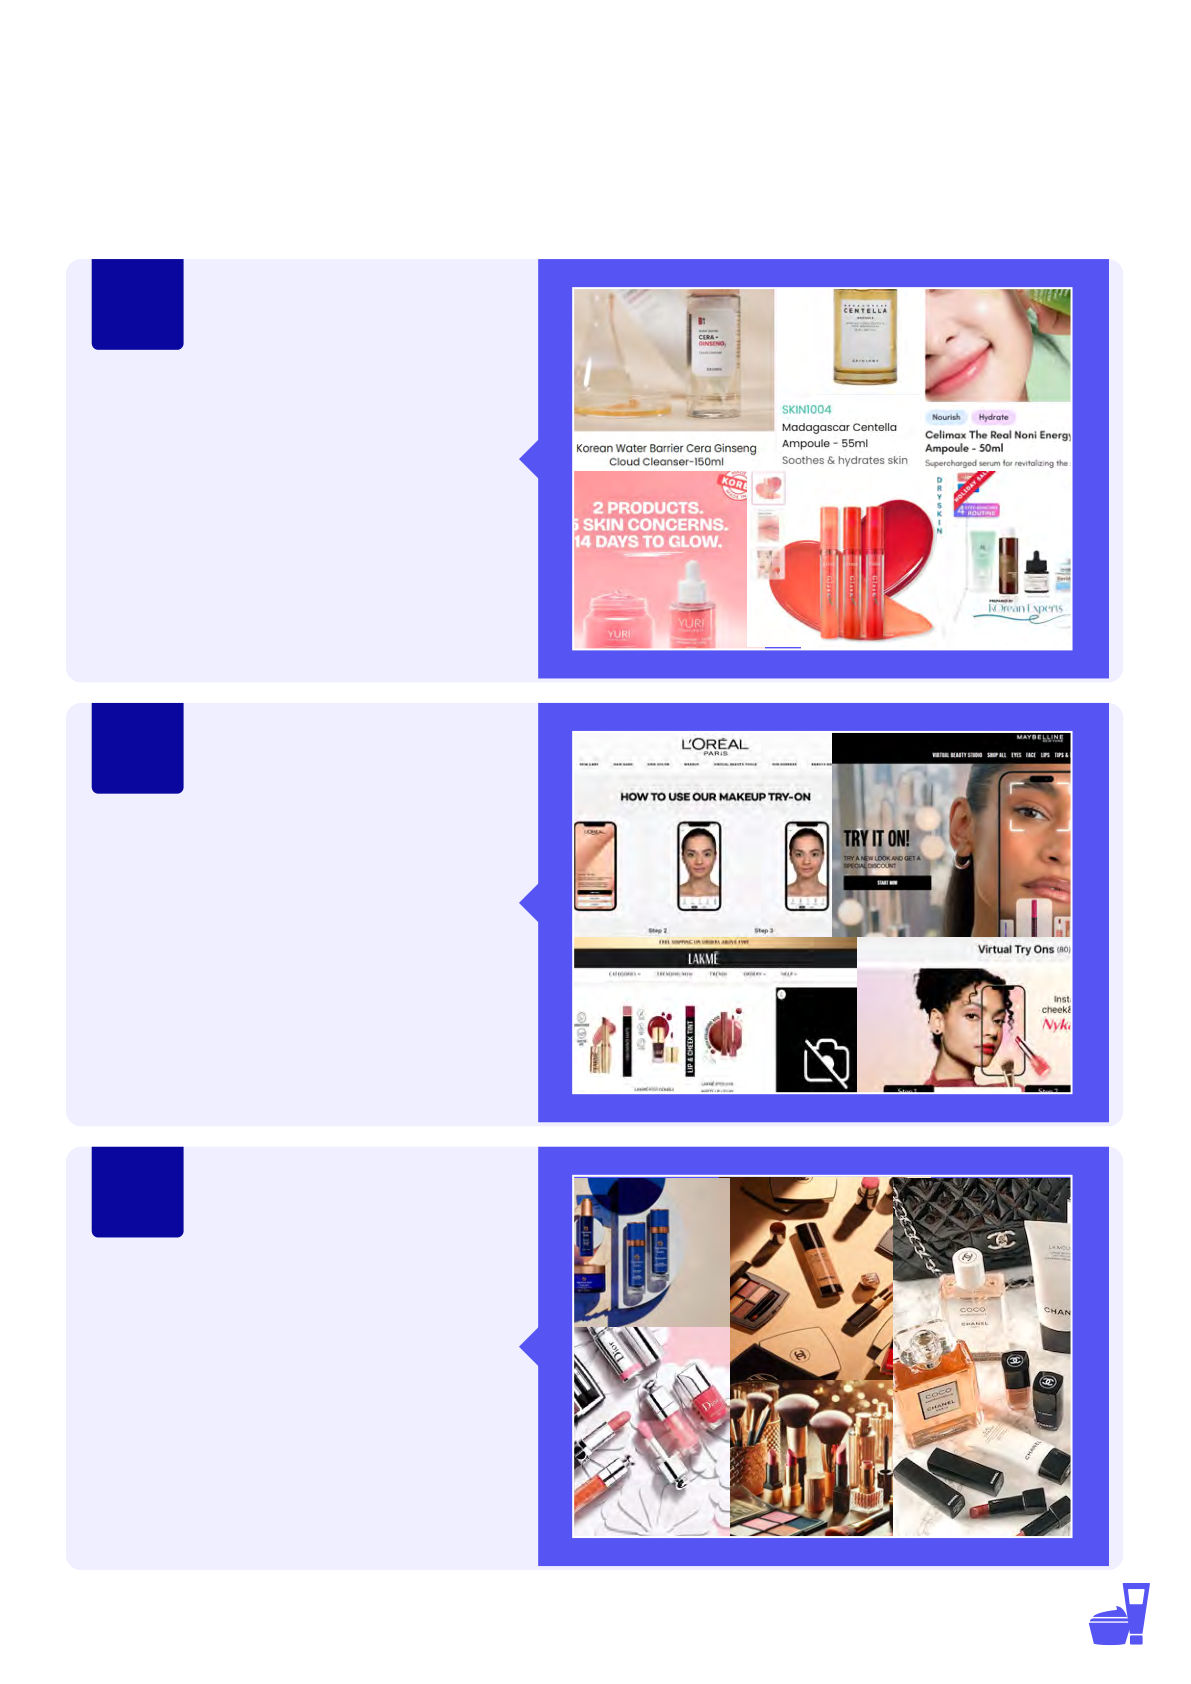
March 2026 Foreword India’s Beauty and Personal Care (BPC) market represents one of the largest and fastest-scaling consumption categories in the country. In FY25, the market is estimated at ~US$ 27B, with offline channels accounting for nearly US$ 21B in sales. While traditional retail continues to drive scale, online BPC is emerging as the fastest-growing channel and is expected to reach ~US$13B by FY30, driven by improving access, awareness, and increasing willingness to experiment. The market spans mass to premium brands across core categories, with growth increasingly driven by premiumization, rapid product variant proliferation, and ingredient-led innovation. Men’s grooming and wellness has emerged as a distinct, fast-scaling segment, supported by specialized brands such as Beardo and Bombay Shaving Company, alongside shifting self-care attitudes. Across skincare and personal care, ingredient-focused formulations and globally inspired routines, including K-beauty formats are reshaping product development and consumer engagement, with brands such as Minimalist, Dot & Key, Plum, Mamaearth, and Forest Essentials setting new benchmarks across Ashish Dhir mass-premium and premium segments. Senior Director Digital channels play a central role in brand discovery and early scale. Platforms such as Nykaa have been Consumer and Retail instrumental in shaping online BPC adoption through content-led discovery, strong curation, and private labels. In parallel, influencer- and celebrity-led brand narratives continue to accelerate trust and adoption. Reflecting these shifts, the BPC Industry Expansion Index has grown at ~8% CAGR over the past four years. Looking ahead, the industry is entering a phase of heightened disruption and consolidation. Large FMCG and beauty incumbents are actively refreshing portfolios through innovation, partnerships, and acquisitions, while digital-first brands continue to challenge traditional playbooks. The entry and scale-up of large conglomerates, notably Reliance’s expansion across beauty retail, brands, and distribution is expected to further reshape competitive dynamics with the overall market projected to reach ~US$ 39B by FY30. We, at 1Lattice, look forward to continuing the discussion with our friends across sectors and exchanging notes. Product in Spotlight: 1Insights This report has been curated using 1Insights, 1Lattice’s proprietary market intelligence platform designed to deliver structured, data-backed analysis across sectors. Built on a strong foundation of industry research, company disclosures, consumer surveys, and in-house analytics, this edition presents a comprehensive view of India’s Beauty & Personal Care market and its evolving growth trajectory. This report provides a forward-looking view of India’s Beauty & Personal Care (BPC) industry, covering market size, growth trajectory, and FY30 projections. It analyzes key growth drivers such as premiumization, digital acceleration, rising demand across Tier 2 and Tier 3 cities, and expansion beyond hygiene. The study examines how evolving consumer behaviour is reshaping purchase journeys and maps the competitive landscape, including digital-first disruptors and celebrity-led BPC brands, while decoding the rapid rise of beauty e-commerce in India. 03 India’s BPC market highlights As of FY25, India’s BPC market growth is driven by scale and premiumization, with ~US$ 21B in offline sales and ~US$ 6B in online sales US$ 21B 45% India’s offline BPC Gen Z share of market (FY25) overall BPC spend US$ 6B 14% India’s online BPC BPC premium segment market (FY25) annual growth (FY25) US$ 26B India’s offline BPC market (FY30) US$ 13B India’s online BPC market (FY30) Note(s): BPC – Beauty and Personal Care Source(s): Industry reports, company annual reports, articles, 1Lattice analysis © 1Lattice 04 Indian BPC market The Indian BPC market is led by offline channels at ~US$ 27B in FY25, while online is expected to reach ~US$ 13B by FY30, driven by rising affluence, awareness, and access Factors driving growth in beauty & personal care market Indian BPC Market size Premiumization tailwinds (US$B) Lifestyle spends growing ~1.5x faster than essentials, accelerating premium and aspirational beauty adoption Expanding tier 2/3 demand Large untapped demand pools (Tier 2 and 3 cities) with improving awareness and access are driving incremental volume growth CAGR (FY25-30) Growing localization 39 Local formulation and production improve affordability, enable faster innovation, and CAGR 8% leverage trust in Indian and heritage brands 17% 13 27 Major multinational players such as L’Oréal India locally manufacture ~95% of products sold 6 Shift beyond hygiene 4% 26 Beauty and personal care have moved 21 beyond basic hygiene to self-expression, wellness, and appearance-led consumption ~40% of young Indian consumers favor lifestyle-aligned products, underscoring the growing role of identity and values FY25 FY30 Online Offline Digital-led discovery Influencers, creators, and digital content have increased awareness, education, and trial , accelerating category adoption and premium upgrades India’s ~2M creators influence ~30% of consumer purchases across categories (including beauty) Note(s): BPC – Beauty and Personal Care Source(s): Industry reports, news articles, 1Lattice analysis © 1Lattice 05 Consumer reshaping BPC purchase behaviour BPC consumer journeys are anchored in digital discovery and online purchase, with brand trust, efficacy, and ingredients emerging as the core decision drivers Consumers primarily base BPC purchase ~75% of BPC customers prefer online channels decisions on brand image, product for purchase, with Nykaa emerging as the effectiveness, and ingredients leading platform (~76%) KPC during BPC purchase Online platform preferences Preferred (%, N = 200) for BPC purchases channel of purchase (%, N = 148) (%,N=200) 26% 76% 58% 47% 47% 53% 74% 22% 22% 25% 24% 20% Brand Effectiveness Ingredients Expert Price/ Offline Image advice value Online New BPC product discovery is largely driven Key considerations influencing BPC purchase by e-com platforms and digital influencers, decisions include ingredient safety, skin-type supported by reviews and word of mouth suitability, brand credibility, and product texture Channel of discovery Primary concerns during BPC purchase (%, N = 200) (%, N = 200) 65% 47% 51% 46% 40% 38% 34% 34% 33% 33% 25% Ecommerce Instagram YouTube Friends Online Beauty Ingredient Skin type Brand Texture Product Websites influencers reviews /family ads blogs safety suitability credibility effectiveness Source(s): BPC customer survey (N=200), 1Lattice analysis © 1Lattice 06 Market landscape BPC landscape spans mass to premium brands across core categories; Men’s grooming and wellness emerges as a distinct, fast-scaling category with specialized brands Mass brands Premium brands Cosmetics Hair care Skin care Perfumes Men’s Grooming Men’s Wellness Note(s): This is not an exhaustive list of brands Source(s): Company websites, 1Lattice analysis 07 Trends in beauty segment [1/2] BPC growth is being driven by new product variant proliferation, along with rising ingredient-focused solutions, K-beauty formats, digital tools, & premium upgrades Decoding current trends in beauty and personal care industry Explosion of choice across Trend every dimension • Market flooded with new-age indie brands, celebrity labels, D2C-first launches • Usage-led variants addressing specific needs and occasions #1 • Innovation in formats, actives, textures, routines, and regimen-based usage Overloaded choices in Proliferation of new formats (e.g., dry shampoos, beauty powdered face washes) and routine-led SKUs such as day/night creams and specialized care products Beauty moves beyond cosmetics to self-care • Skincare & haircare leading the shift toward natural and ingredient-led formulations • Natural claims by brands must now match visible, provable results Brands like Minimalist and Derma Co. emphasize on active-backed formulations Accessibility has redefined discovery & trial • Platforms like Nykaa, Amazon, Purplle democratise access across cities • Reviews, creators, tutorials now influence trust more than brand legacy • Minis & trial packs reduce entry barriers into premium brands Influencer/celebrity-led brand collaborations and co-created launches drive visibility and rapid scale-up New segments introducing new rituals • Male grooming moves from basic hygiene to routine-based care • Dedicated brands addressing men-specific skin, hair & beard needs Brands like Beardo introducing full grooming routines - face care, hair styling, and beard maintenance Source(s): Industry reports, articles, 1Lattice analysis © 1Lattice 08 Trends in beauty segment [2/2] BPC growth is being driven by new product variant proliferation, along with rising ingredient-focused solutions, K-beauty formats, digital tools, & premium upgrades Korean-Beauty Effect #2 • K-Beauty has shifted Indian beauty from instant cosmetic fixes to long-term skin health, popularising routines, prevention, and ingredient-led care over heavy makeup • Emphasis moves from concealing flaws to repairing and strengthening skin • Rise of hydration, barrier repair, and gentle actives • “Glass skin” translates locally into healthy, dewy, well-nourished skin The Digital Beauty Revolution #3 • Premium segment outpacing mass market with 13-15% annual growth • Tier-2 and tier-3 cities emerging as new luxury consumption hubs • Shift from functional to experiential beauty, with consumers paying for sensorials, packaging, and brand storytelling • Skin-first, ingredient-led formulations (derma, actives, clean beauty) commanding higher price points • Aspirational millennials and Gen Z driving premiumization across categories Growth of Luxury / Premium BPC #4 • Premium segment outpacing mass market with 13-15% annual growth • Tier-2 and tier-3 cities emerging as new luxury consumption hubs • Shift from functional to experiential beauty, with consumers paying for sensorials, packaging, and brand storytelling • Skin-first, ingredient-led formulations (derma, actives, clean beauty) commanding higher price points • Aspirational millennials and Gen Z driving premiumization across categories © 1Lattice 09 Source(s): Industry reports, articles, 1Lattice analysis Celebrity led BPC brands In the beauty and personal care category, celebrity equity acts as a shortcut to trust, trial, & early scale Some popular celebrity-led Beauty and Personal Care brands that are getting good traction What is the What is the brand known for brand known for • Inclusive shade range for • Barrier repair & hydration Indian skin focus • Performance-led • Wellness-inspired Katrina Kaif Deepika Padukone everyday makeup positioning Category focus Category focus • Strong Nykaa-led scale & • Premium, minimalist Makeup Skincare distribution product range What is the What is the brand known for brand known for • Affordable active-led • Clean & sustainable formulations haircare Kriti Sanon Priyanka Chopra • Youth / Gen-Z appeal • Global-first brand positioning • Mass-premium Category focus Category focus digital-first pricing • Inclusive hair type Skincare Haircare solutions What is the What is the brand known for brand known for • Clean, gentle skincare • Wellness-inspired skincare • Sensitive-skin friendly Sonakshi Sinha Lara Dutta positioning • Age-positive brand narrative Category focus • Ingredient-conscious Category focus formulations • Premium lifestyle Skincare & Skincare positioning wellness © 1Lattice Source(s): Company websites, 1Lattice analysis 10 Beauty e-commerce in India Online has evolved from an alternate channel to the fastest-growing avenue for beauty brands in India’s BPC market Rise of e-commerce in India Strategic lens • Win discovery before Online BPC in India has seen a 2x market distribution expansion post-2020 • Education converts faster India’s online beauty market is valued at US$ 6B, than discounts accounting for ~20% of total market sales • Reviews = reputation = revenue By FY30, online penetration in BPC is expected to • Launch digitally, scale reach ~33% of the total market selectively offline • Influencers are GTM Gen Z accounts for ~45% of total consumer partners, not media spend in the online BPC category • Brand equity now built on screens • E-commerce capabilities High online skew categories are core, not optional Skin care Premium & products Luxury (serums, products oils, etc.) Grooming & Makeup & beauty cosmetics devices Digital pull behind BPC purchases Discovery at Higher confidence scale via through ingredient influencers, education & social reviews & routines proof Access to Discreet shopping premium & niche for acne, brands unavailable pigmentation, offline hairfall, and dermat-backed solutions Reminders, and saved routines simplify ongoing care Source(s): Industry reports, company annual reports, articles, 1Lattice analysis © 1Lattice 11 Industry Expansion Index BPC Industry Expansion Index has grown at ~8% CAGR in the past 4 years Companies included in the Index: A total of 13 companies* have been included for index calculation Industry Expansion Index – Beauty and Personal Care Brands with >INR 1000 Cr Revenue 136 125 117 100 And others … FY22 FY23 FY24 FY25 Brands with <INR 1000 Cr Revenue Note(s): The index has been calculated by taking the revenue sum for all the mentioned companies for the respective years, considering FY22 figure as base for indexing * multiple brands are included under HUL like Pond’s, Lakme, Vaseline, Clinic Plus, Sunsilk, etc Source(s): Company annual reports, other secondary sources, 1Lattice analysis © 1Lattice 12 We are here for you Let us know how we can meet your business requirement? Ashish Dhir Senior Director, Consumer & Retail E: ashish.dhir@1lattice.com Ambuj Gupta Associate Director, Consumer & Retail E: ambuj.gupta@1lattice.com For media queries, Corporate Communications communications@1lattice.com please contact www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. 4 200+ Offices in India Annual engagements 130+ 50+ Team members Inhouse research team 1,000+ 2M+ On-ground staff B2C Panel 300K+ 100K+ B2B Panel Experts & professionals 20% 100% Cost savings Controlled output & timeline What We Do Making organizations effective through data-driven insights, Vision innovative products solutions and proven expertise to enable better decisions To provide technology led solutions that unlock that power of trustable data, actionable research, and deep network Mission of experts Technology Data + People/ Accumulated Professionals/ knowledge Service providers Research +91 987 165 4747 ashish.dhir@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore