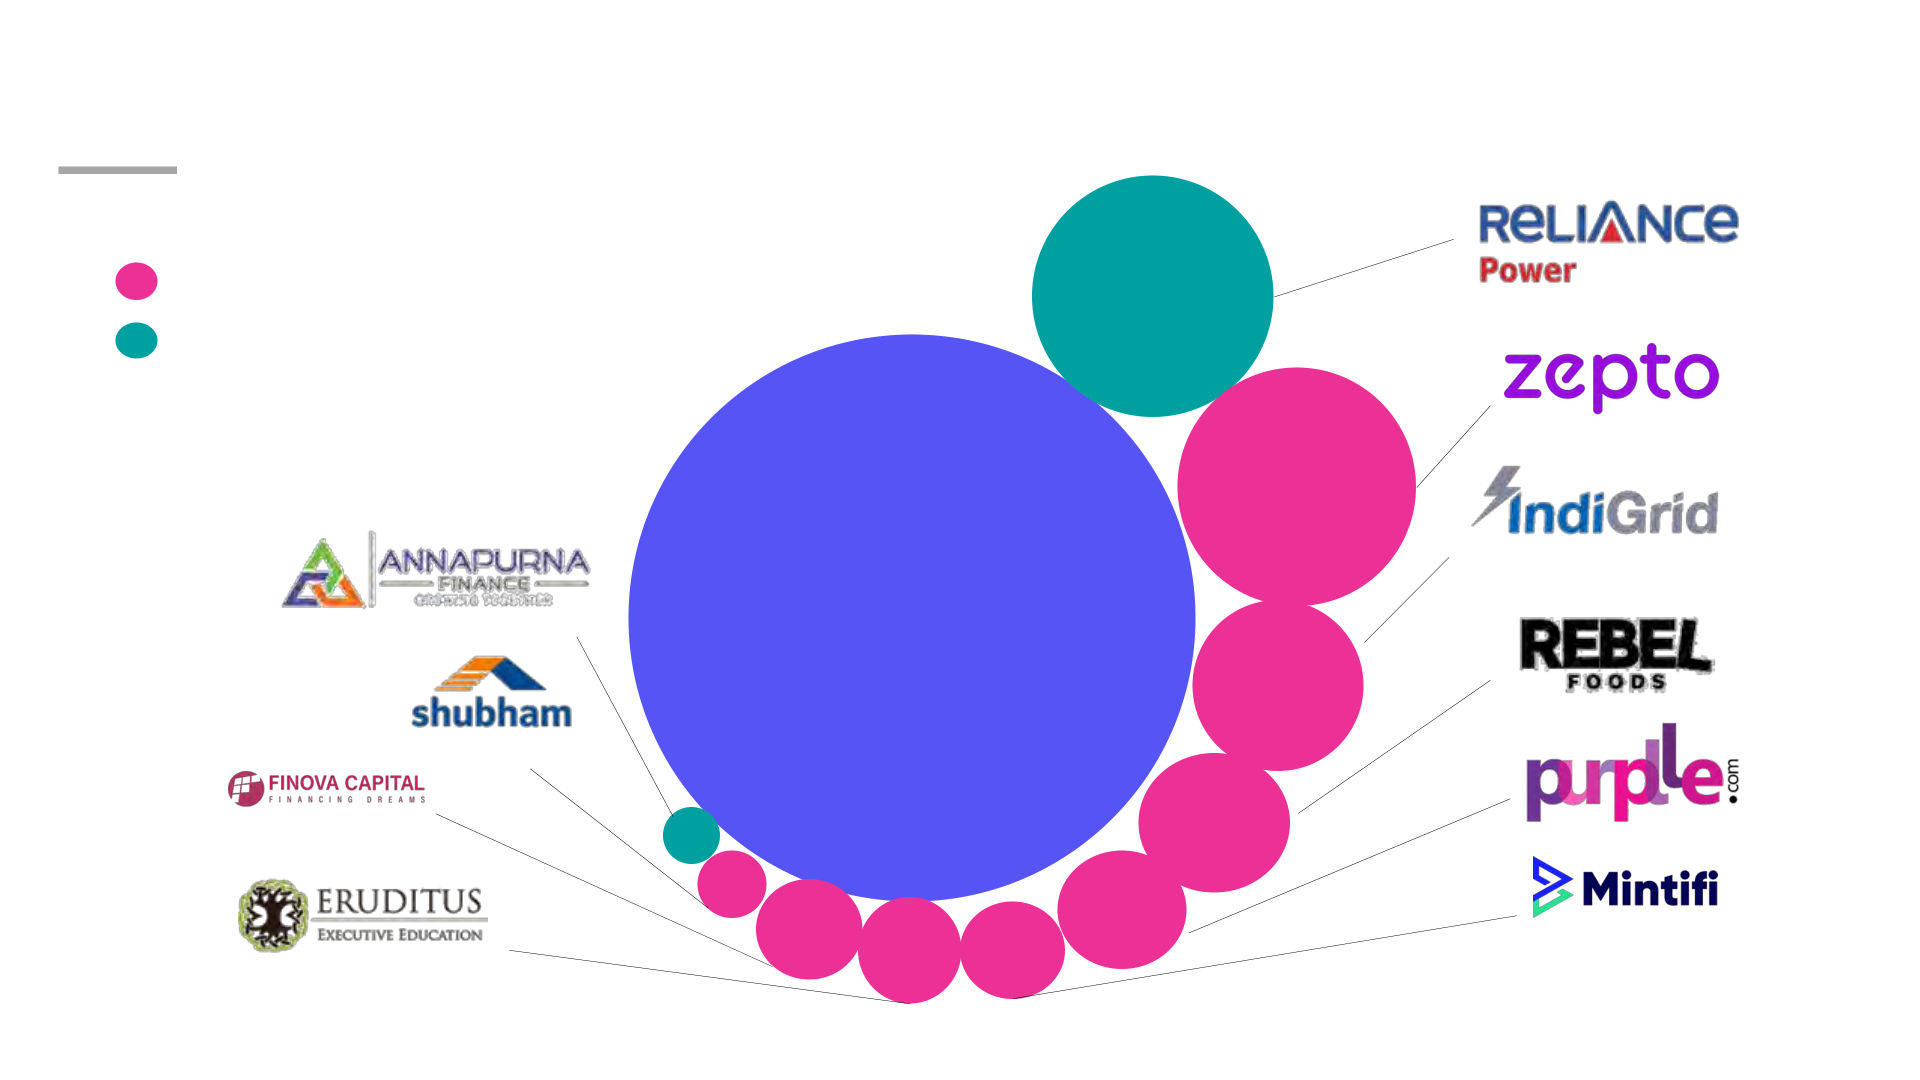
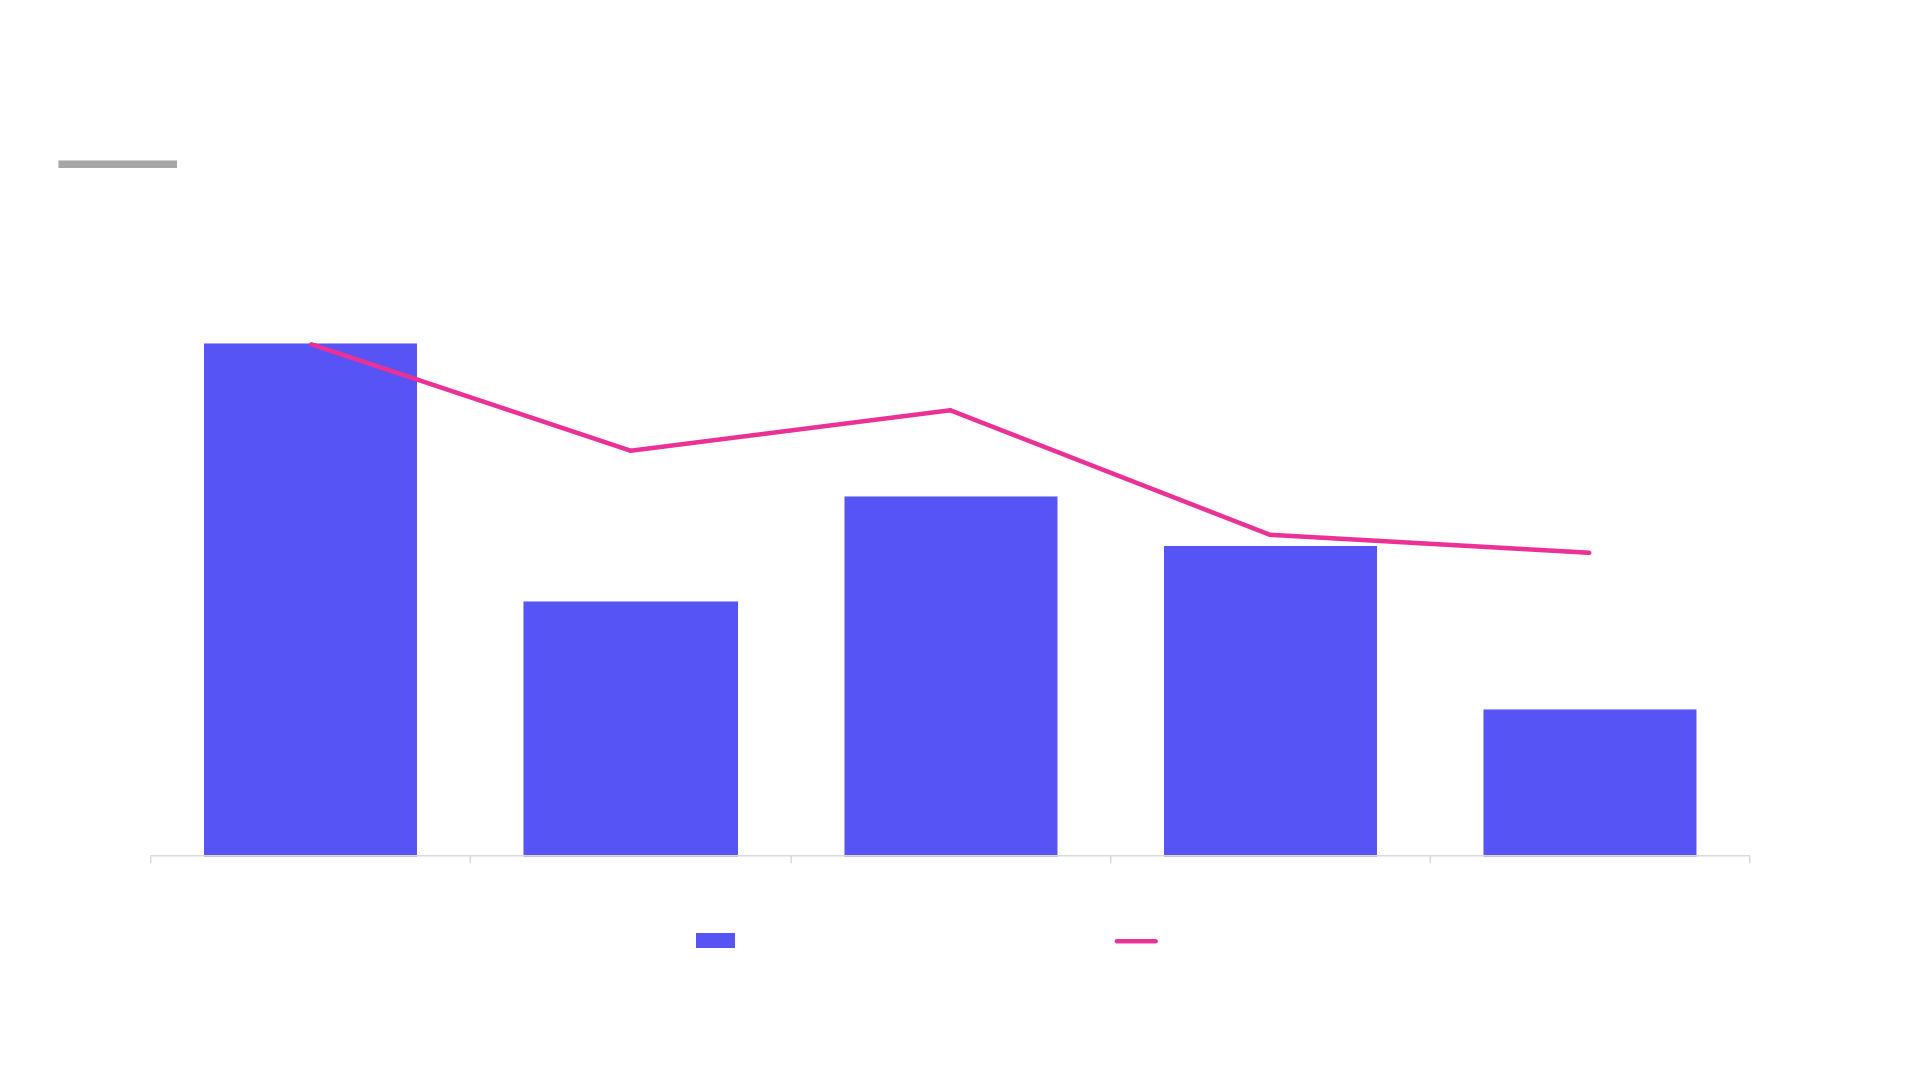
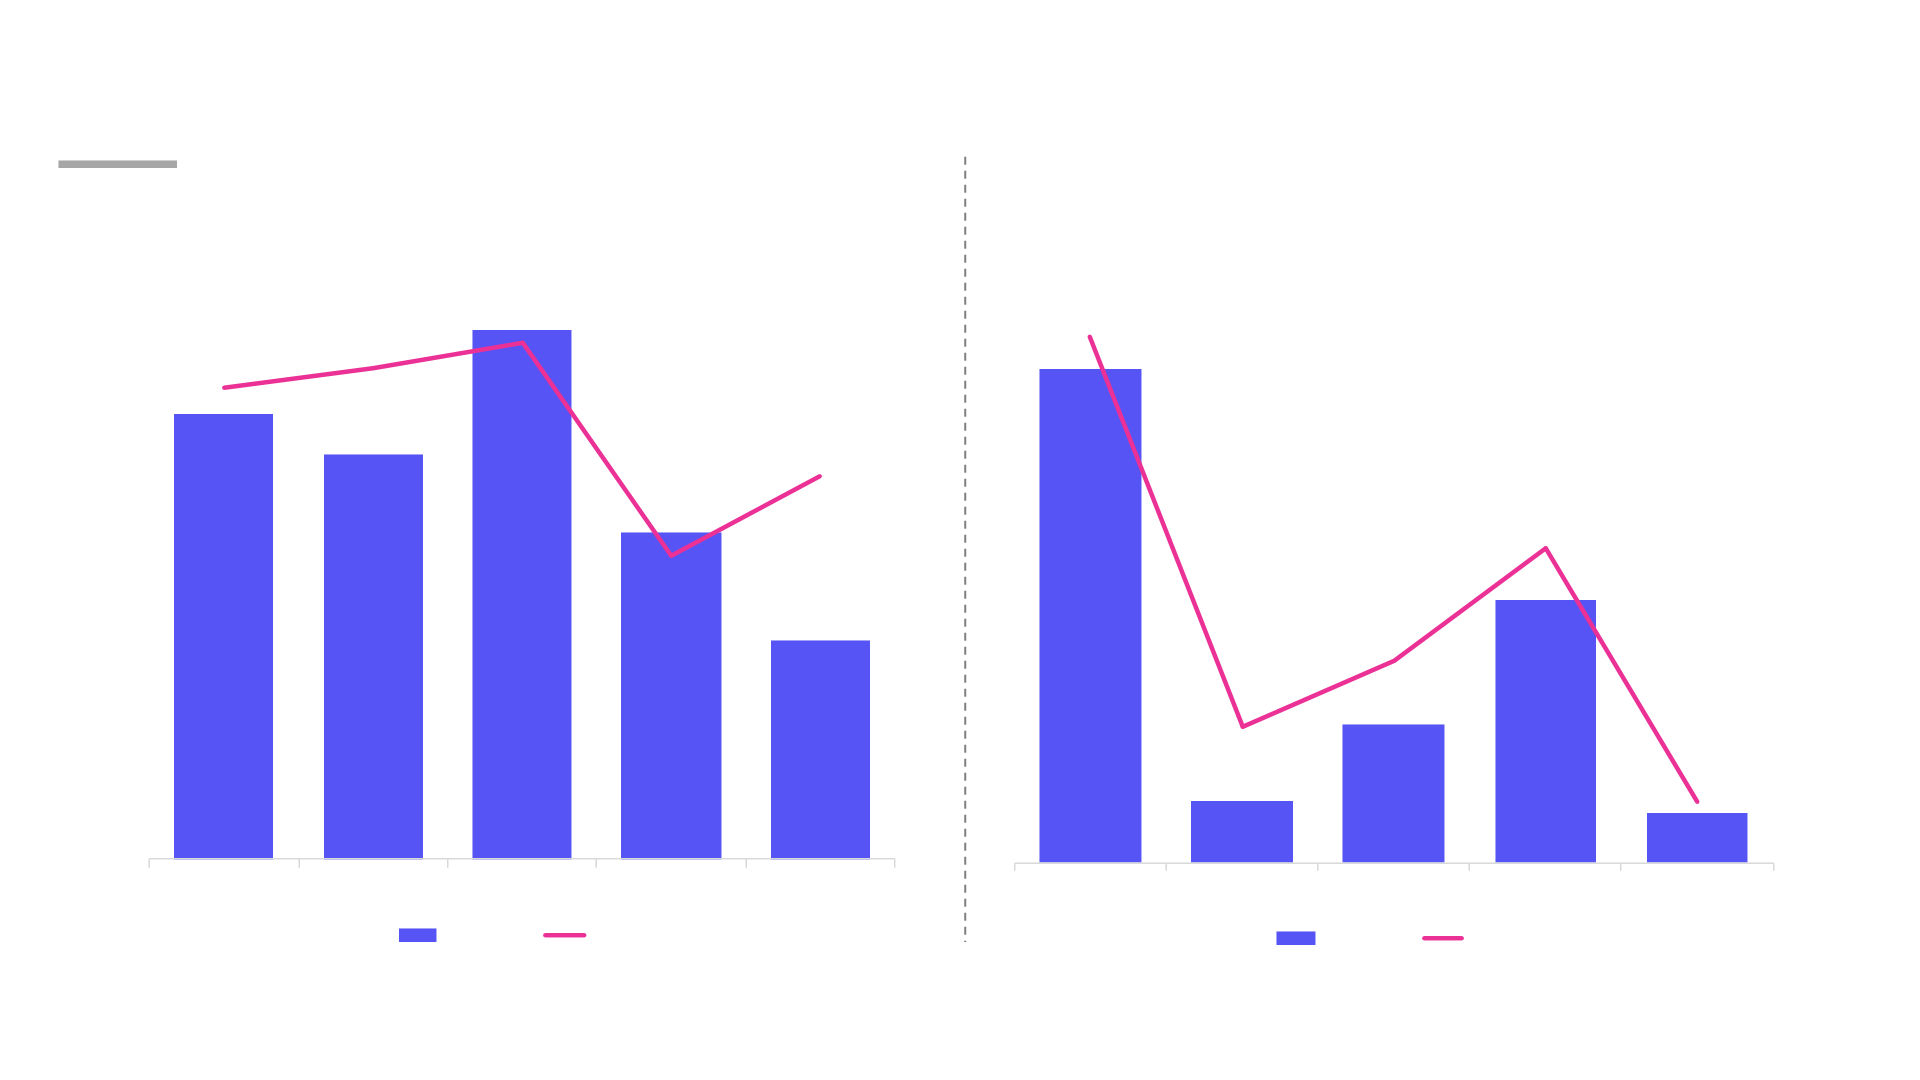
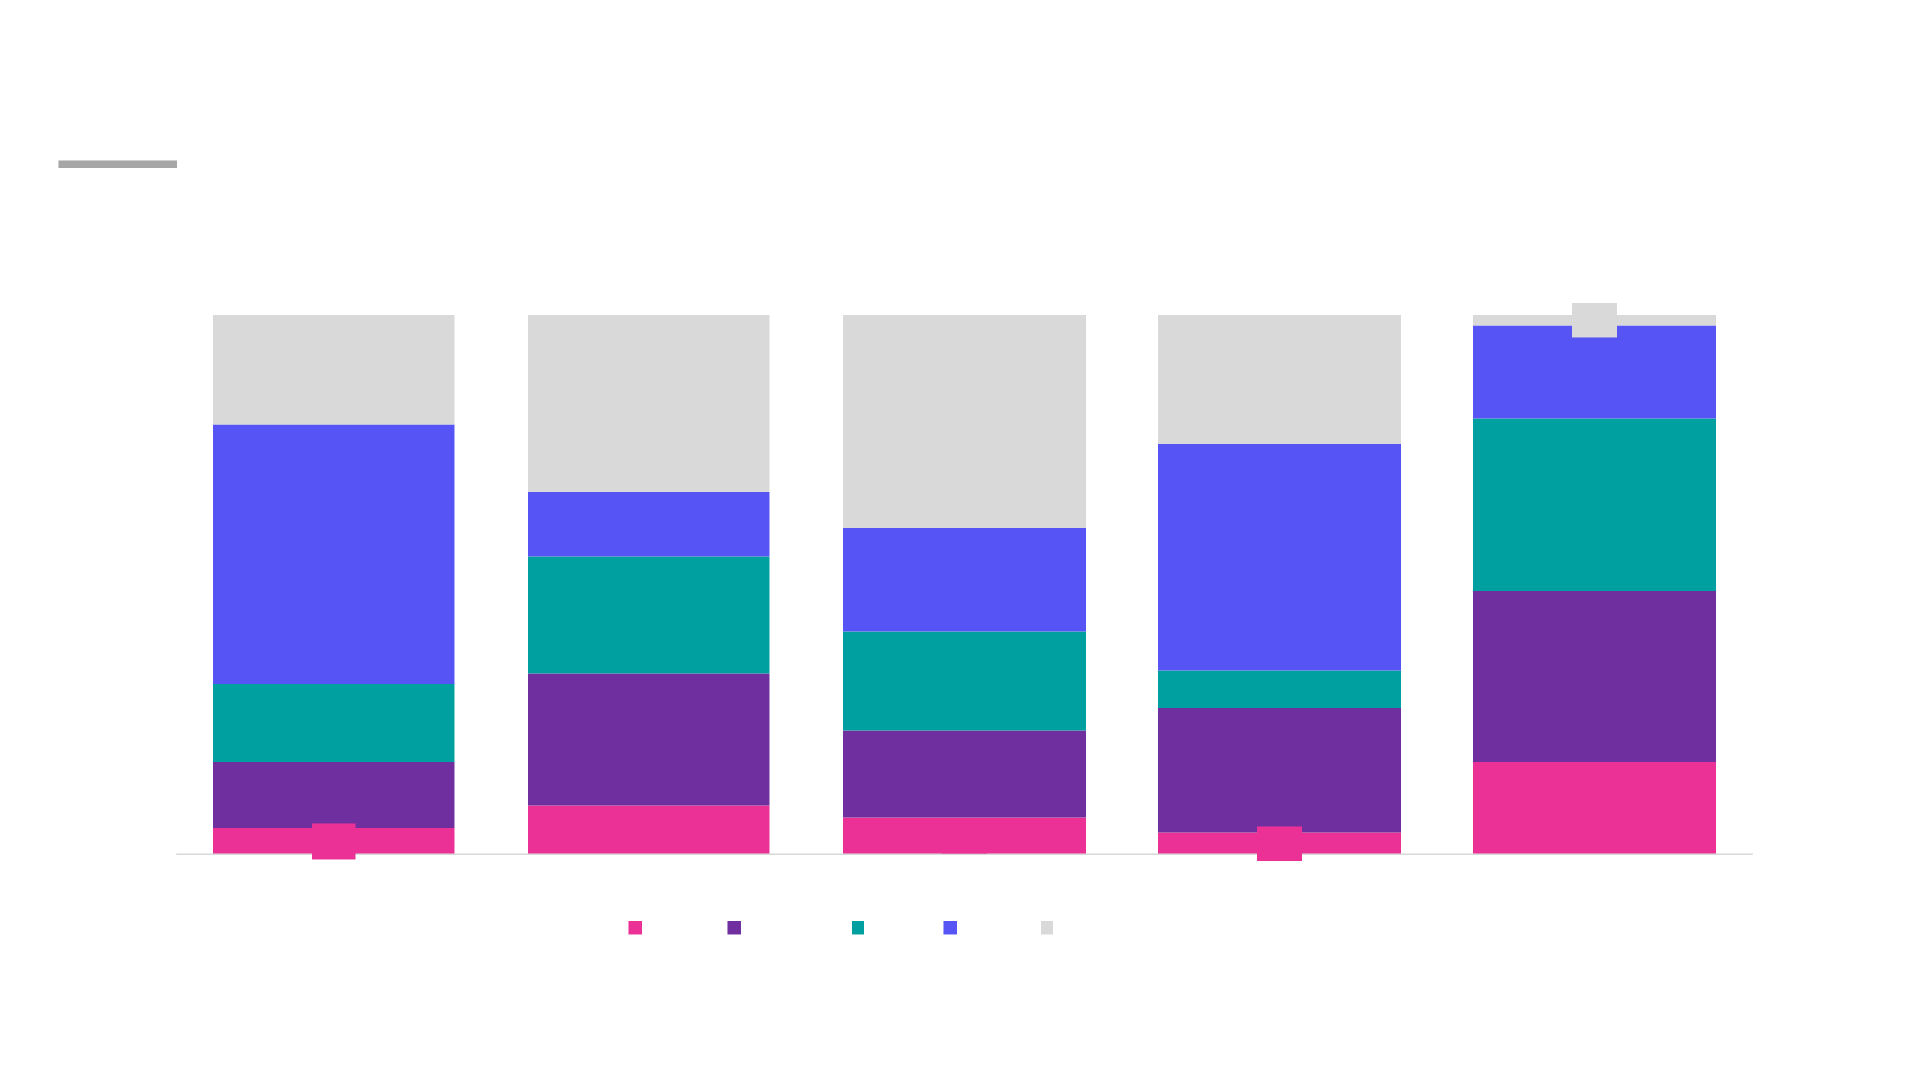
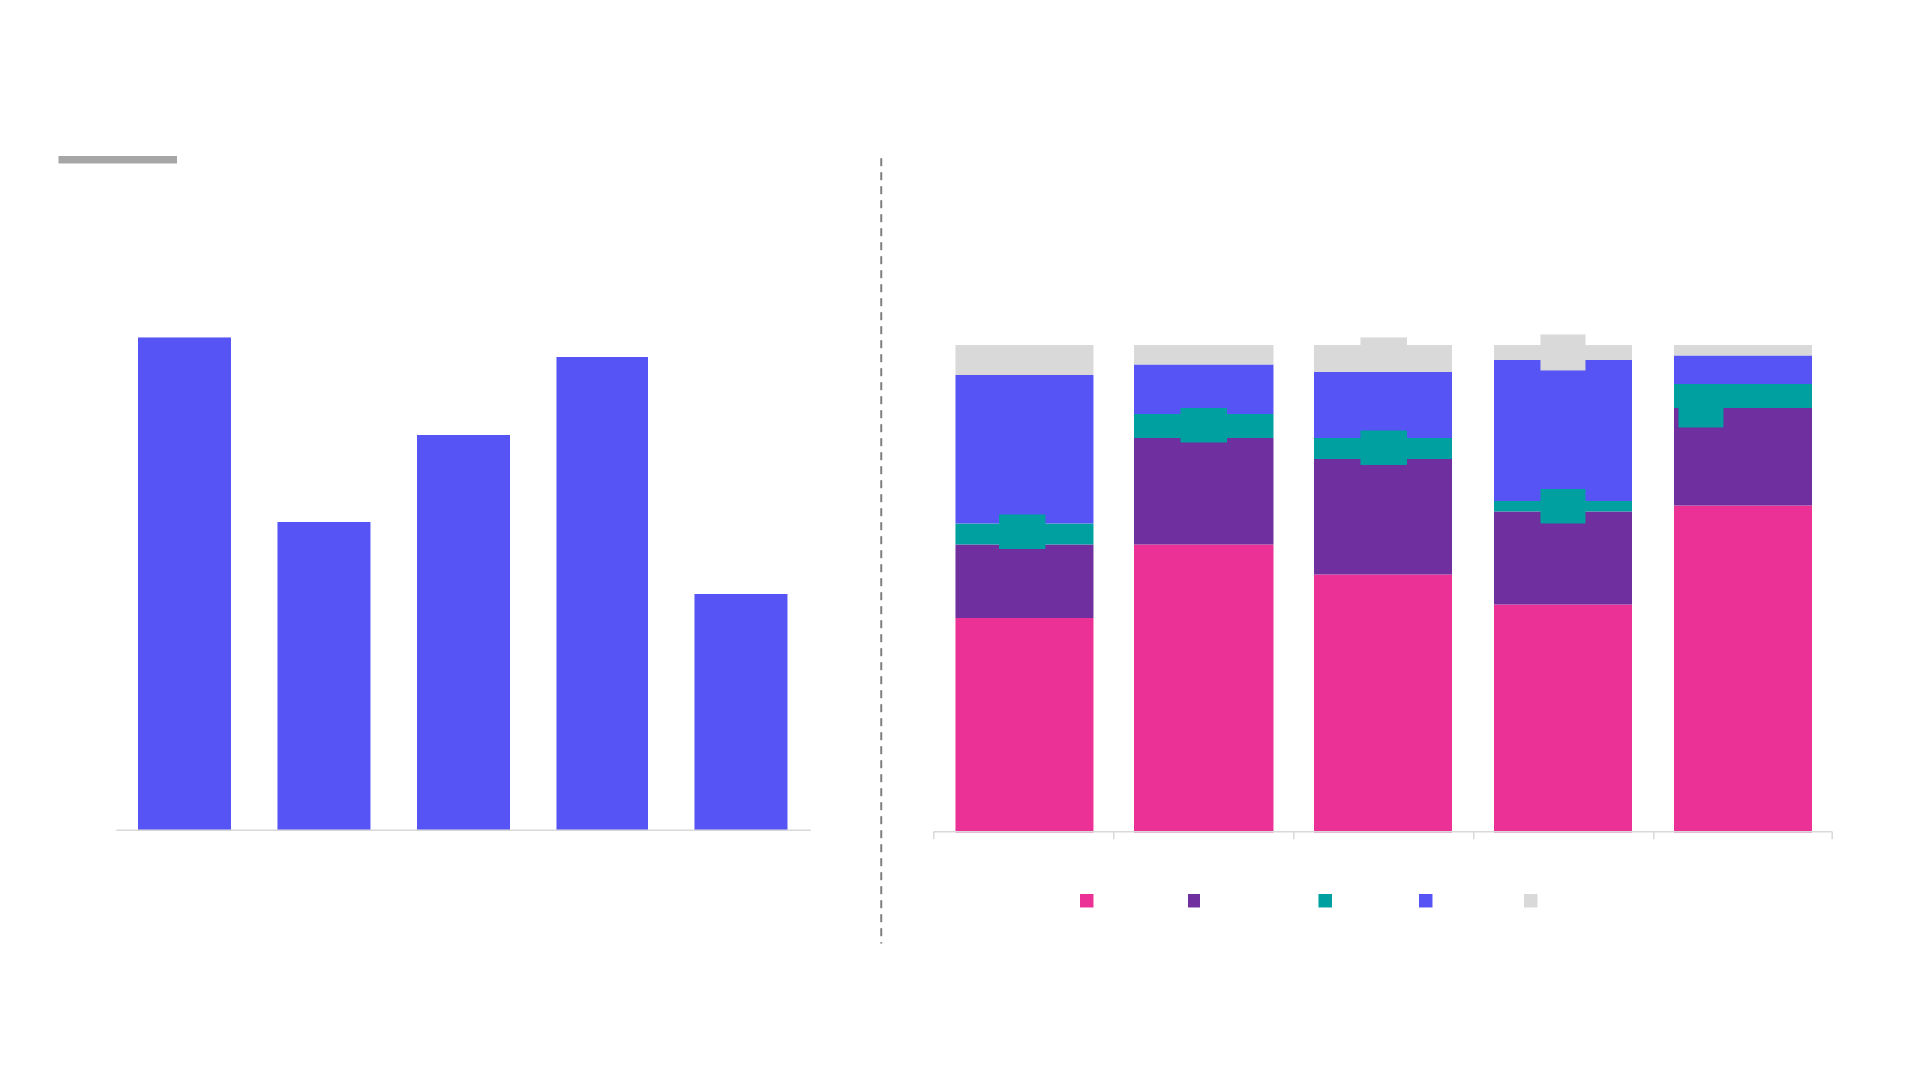
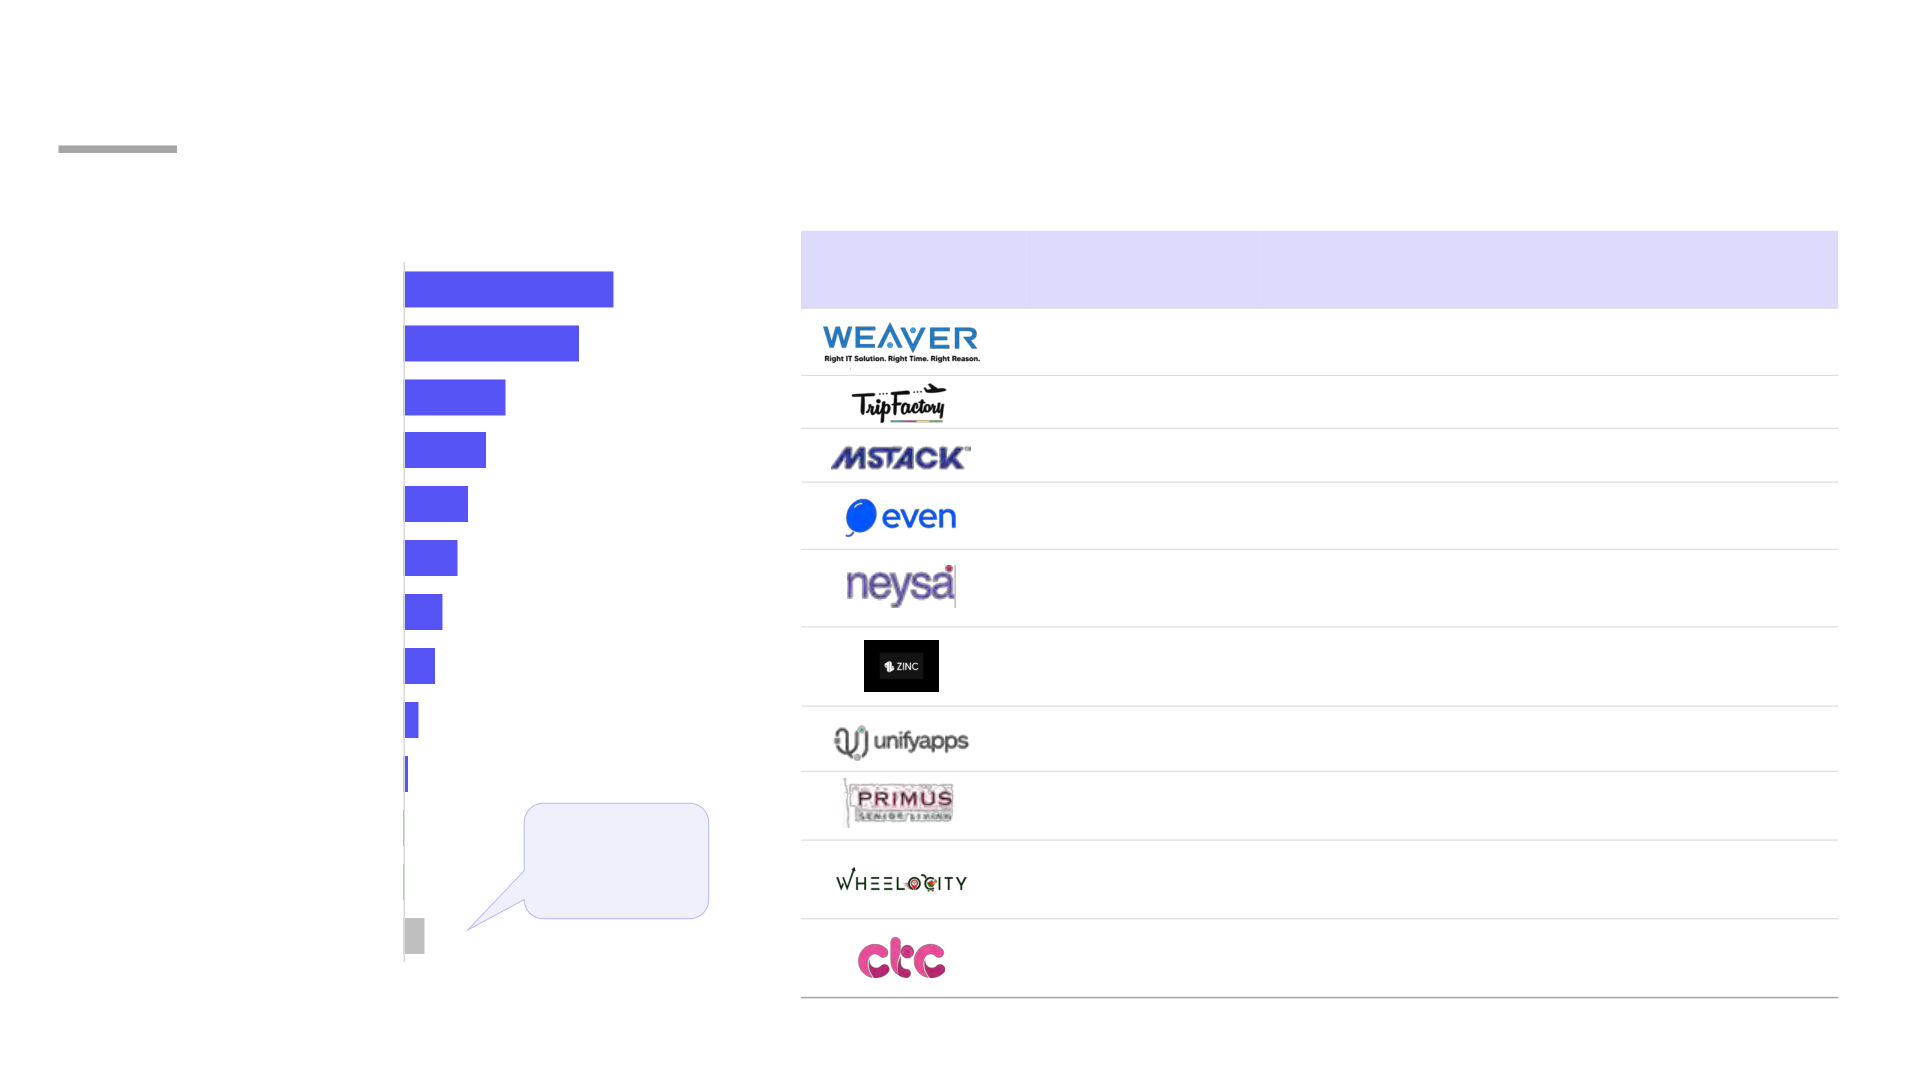
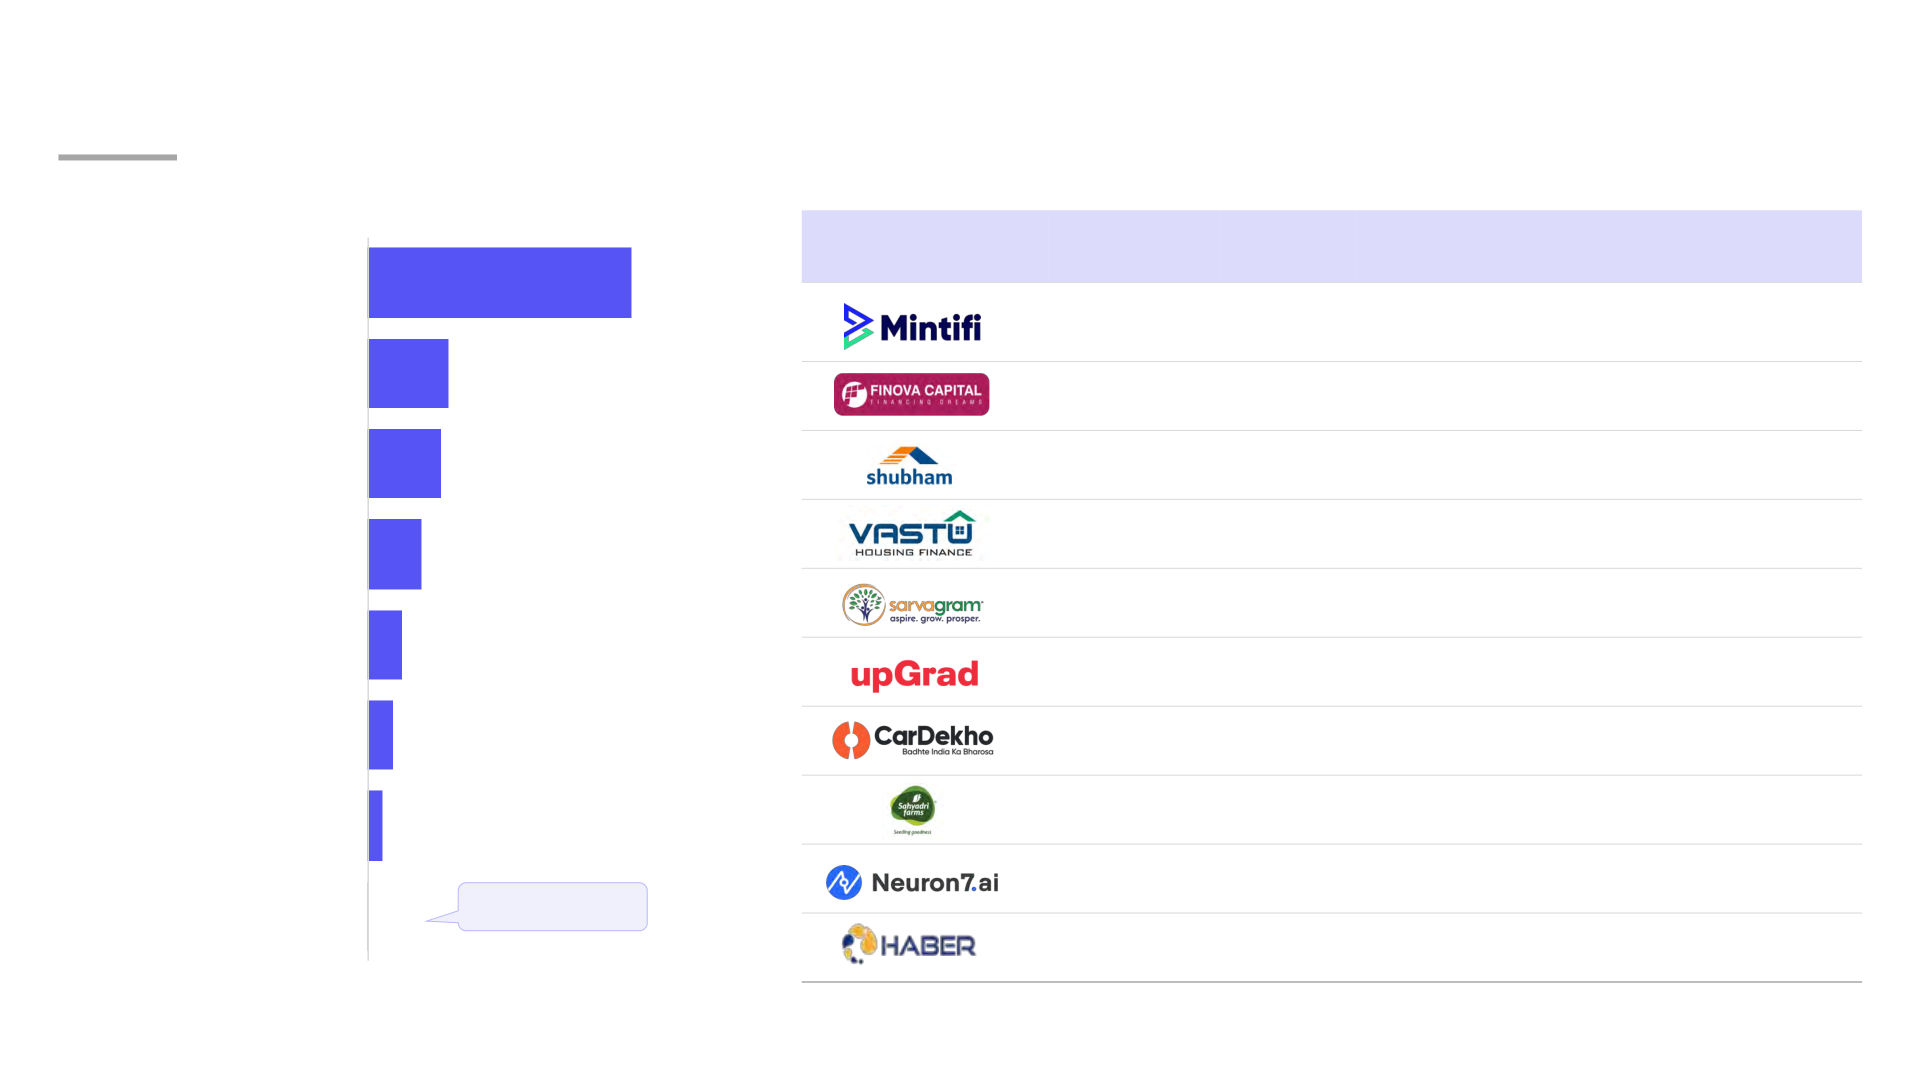
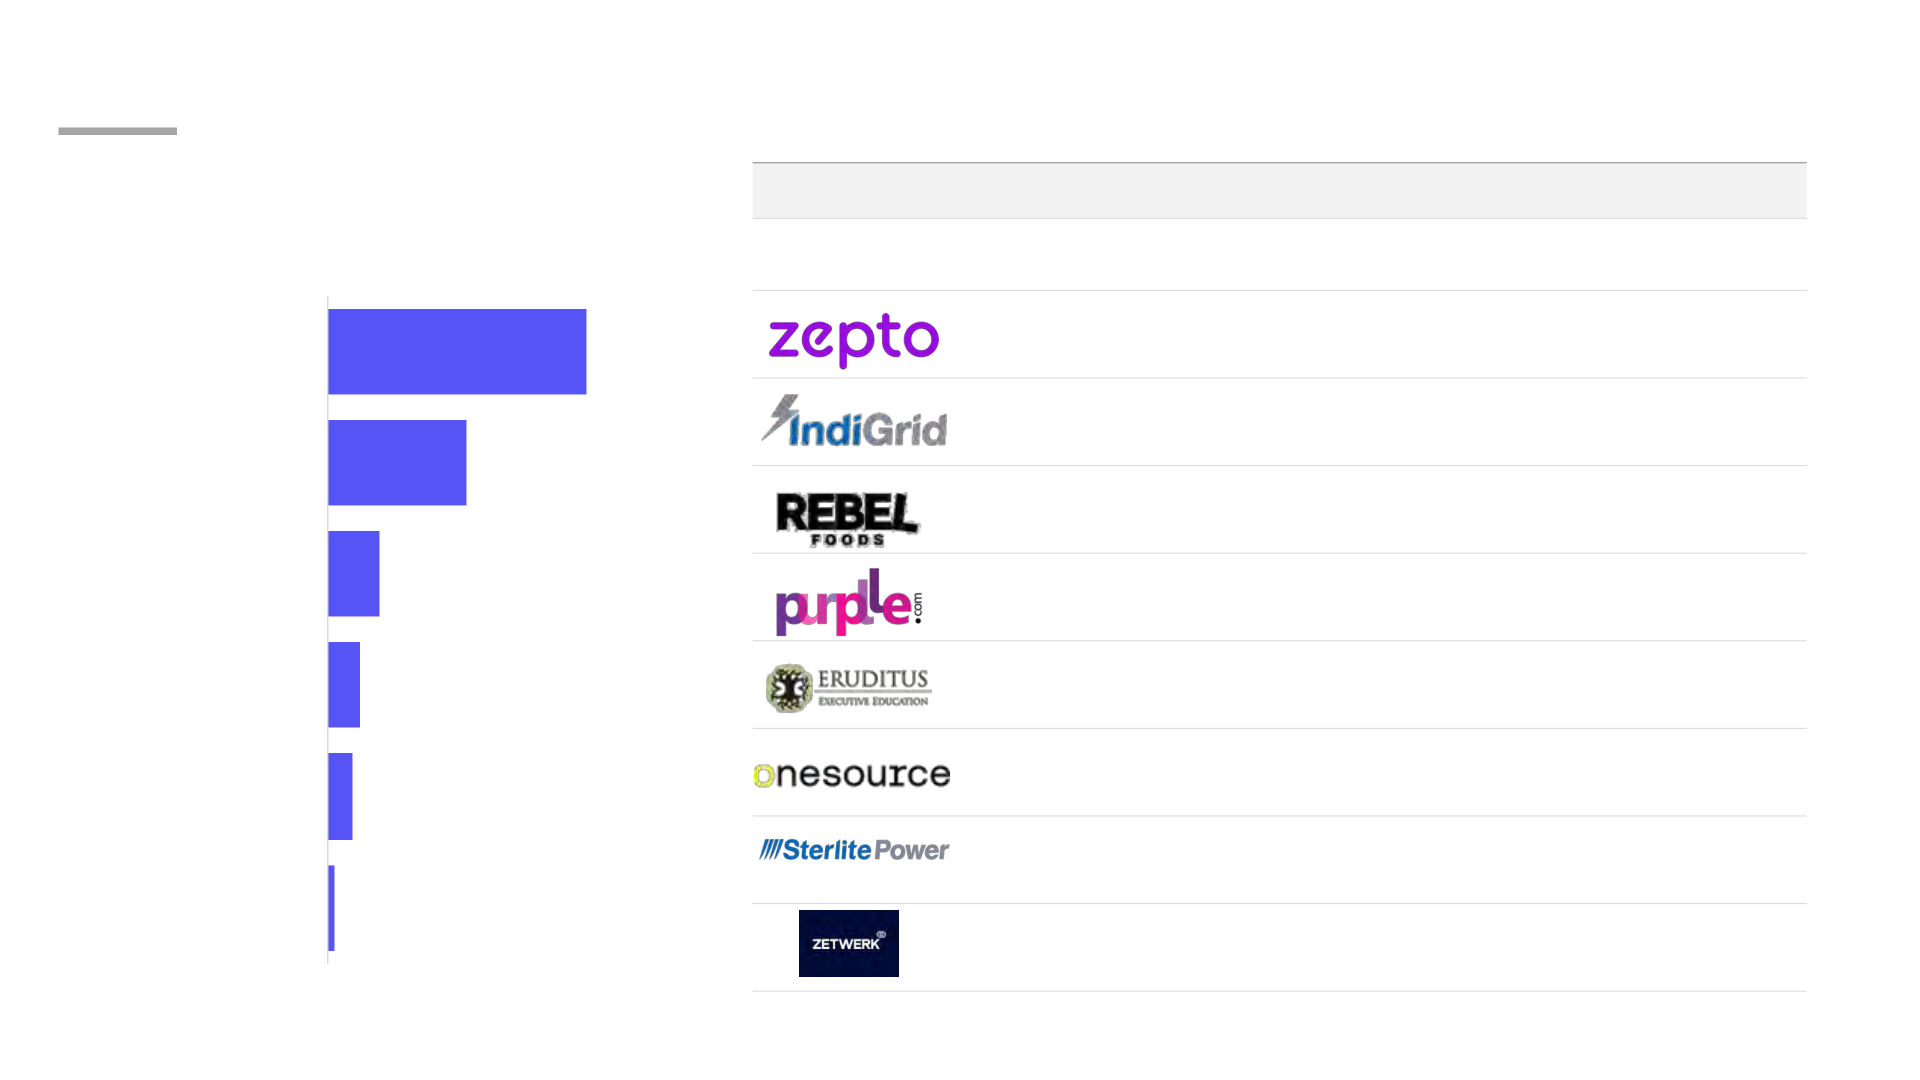
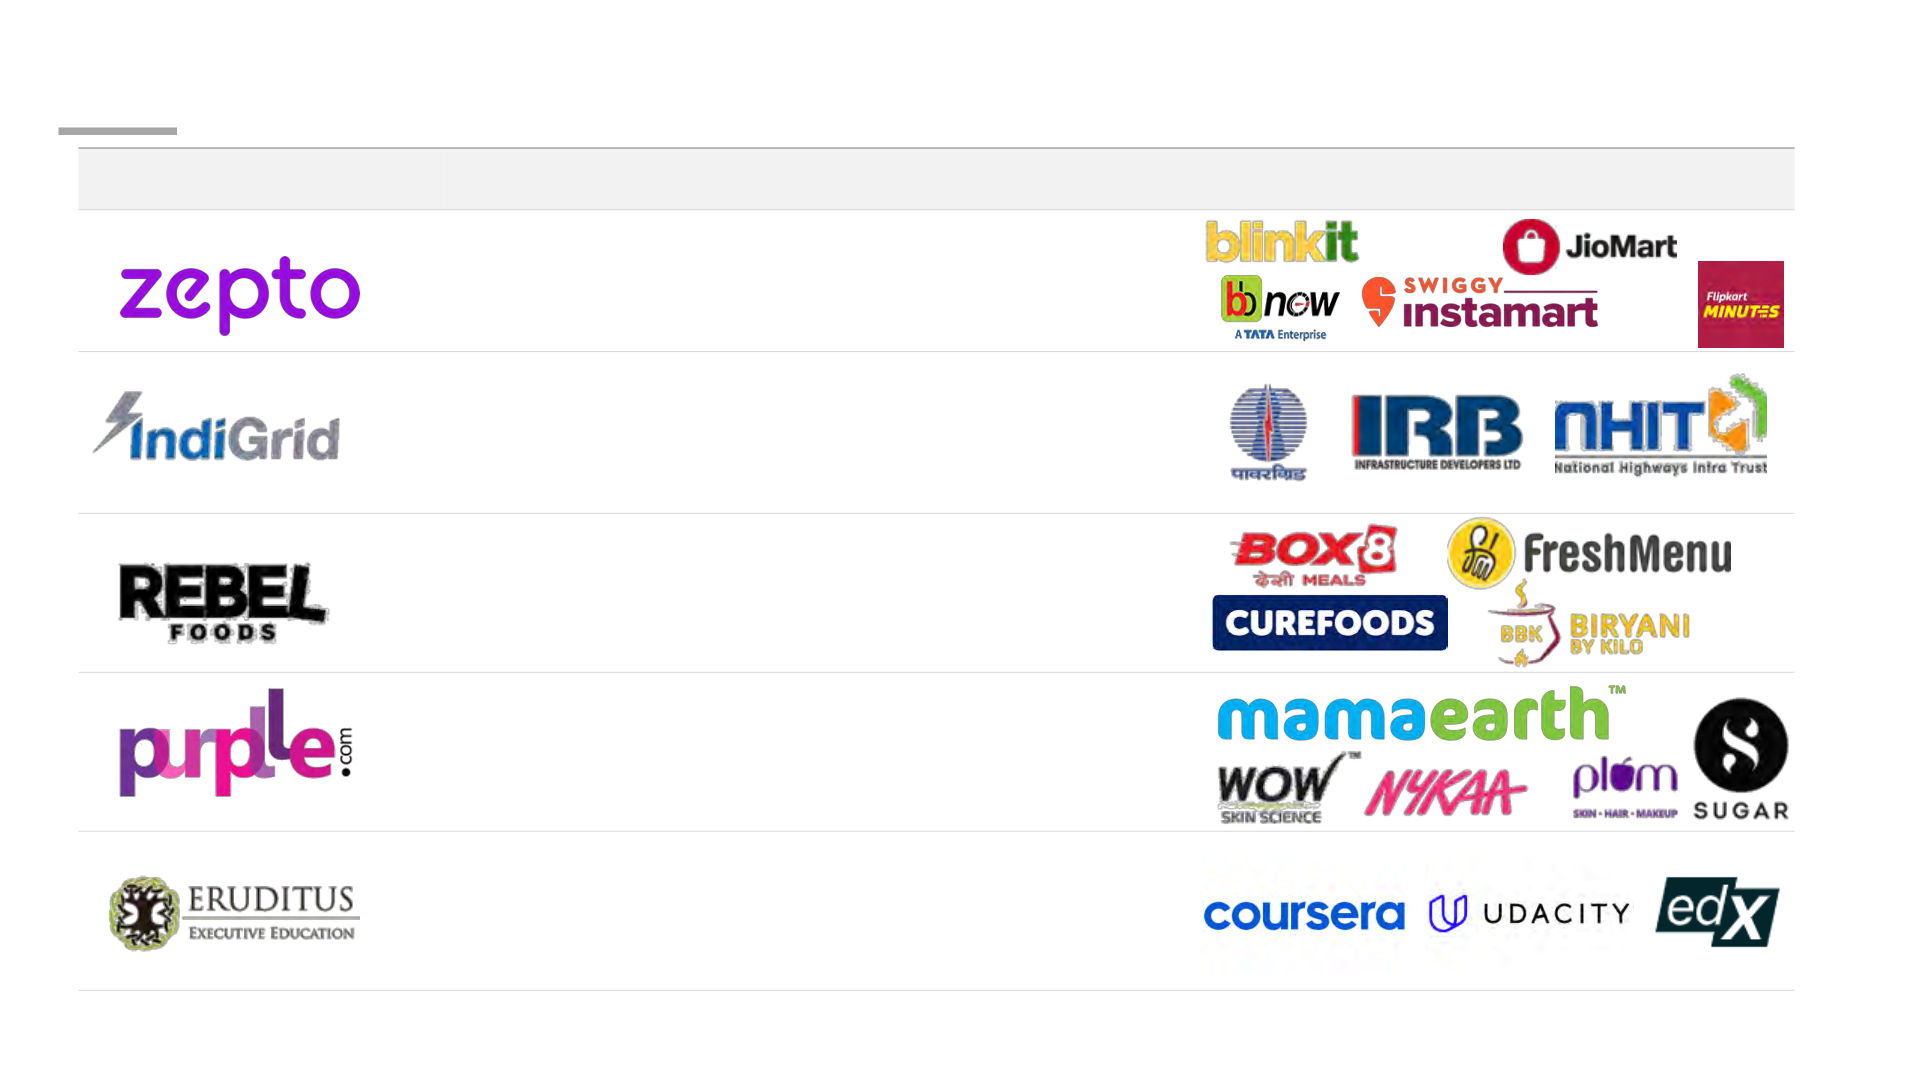
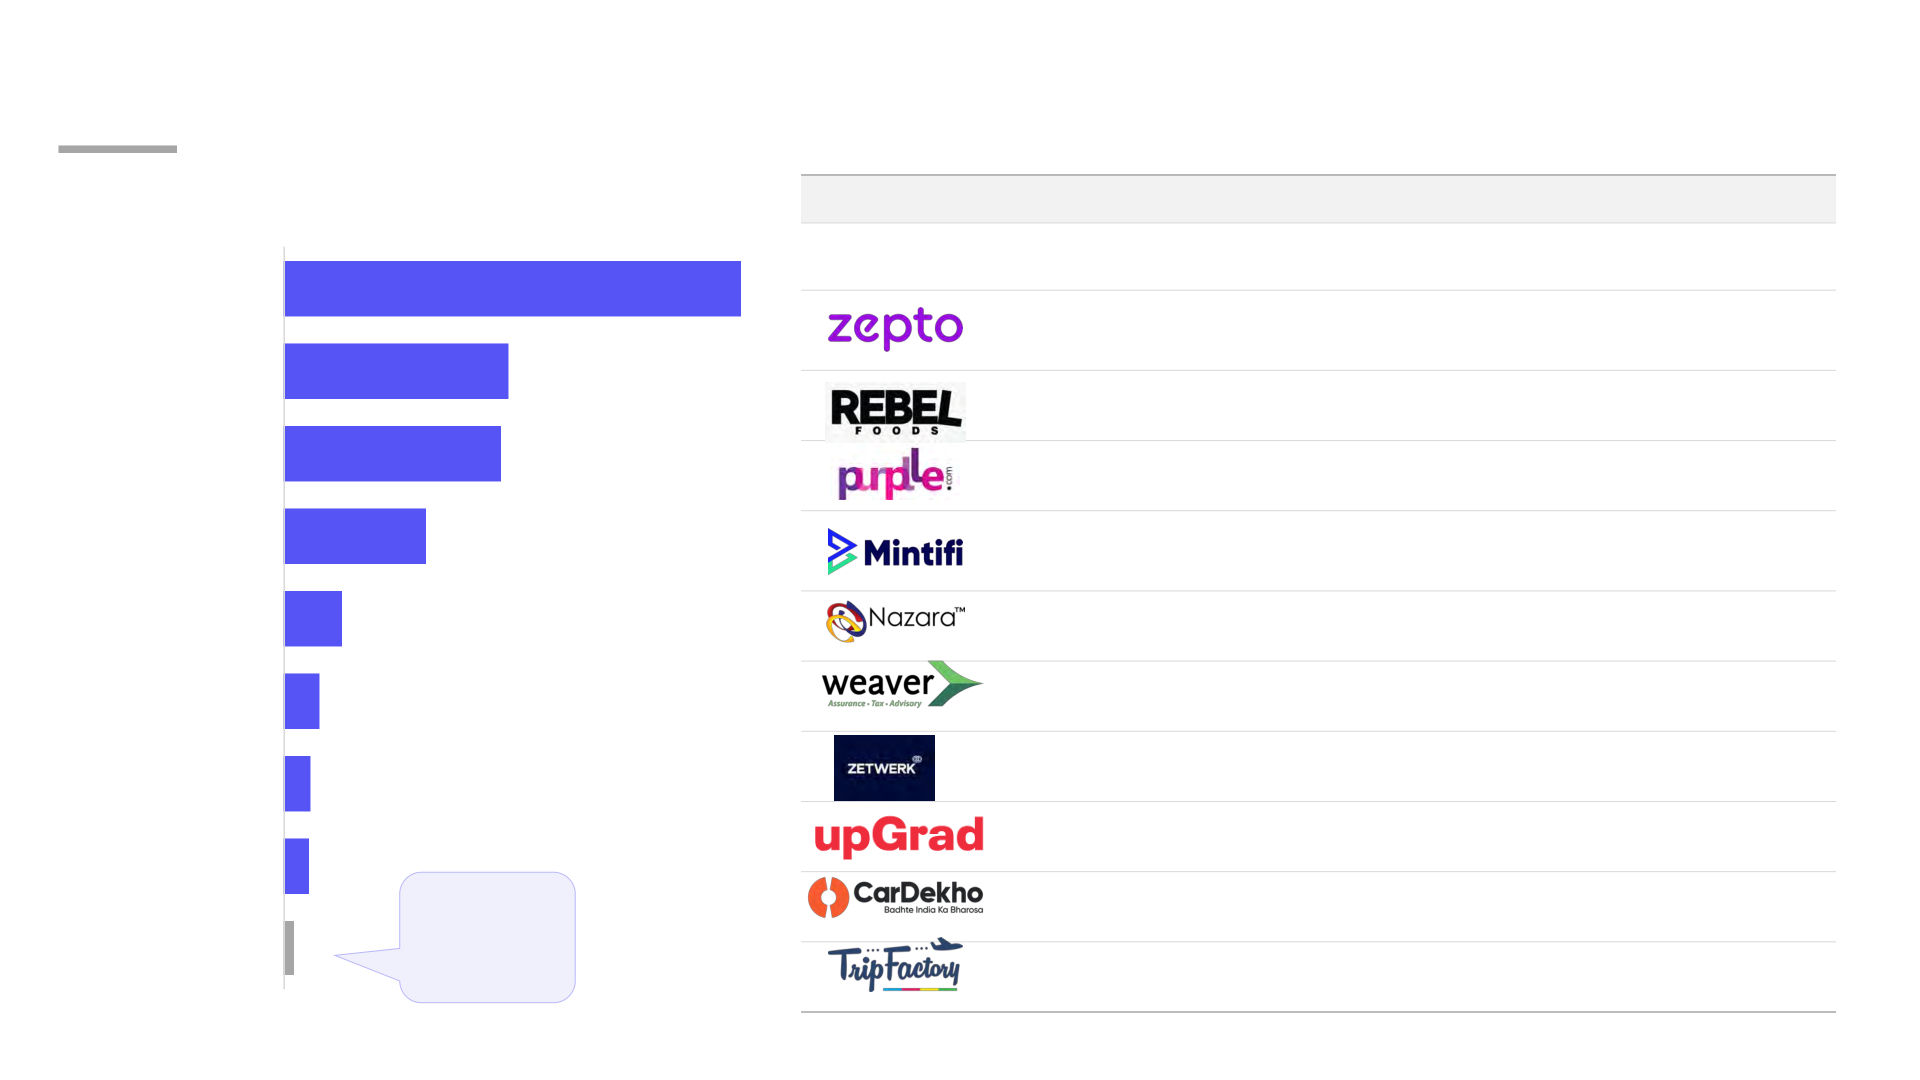
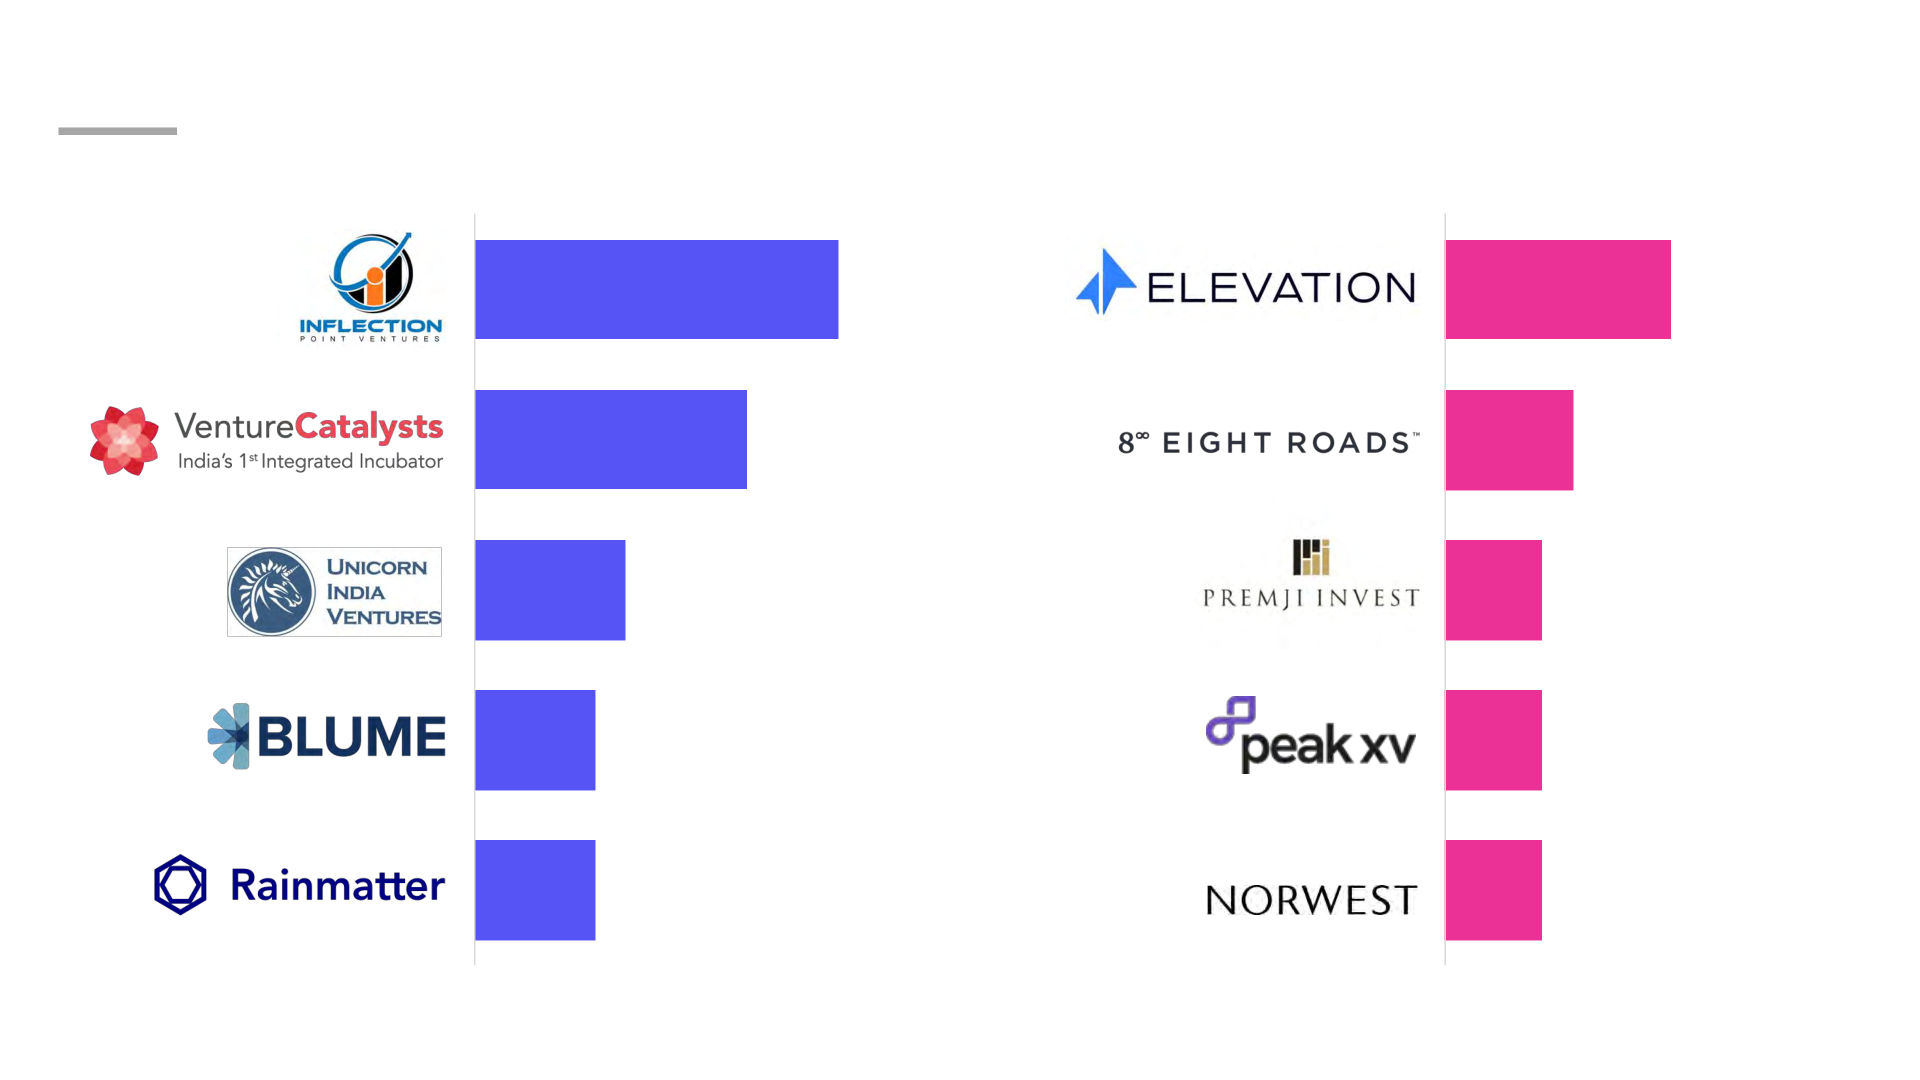
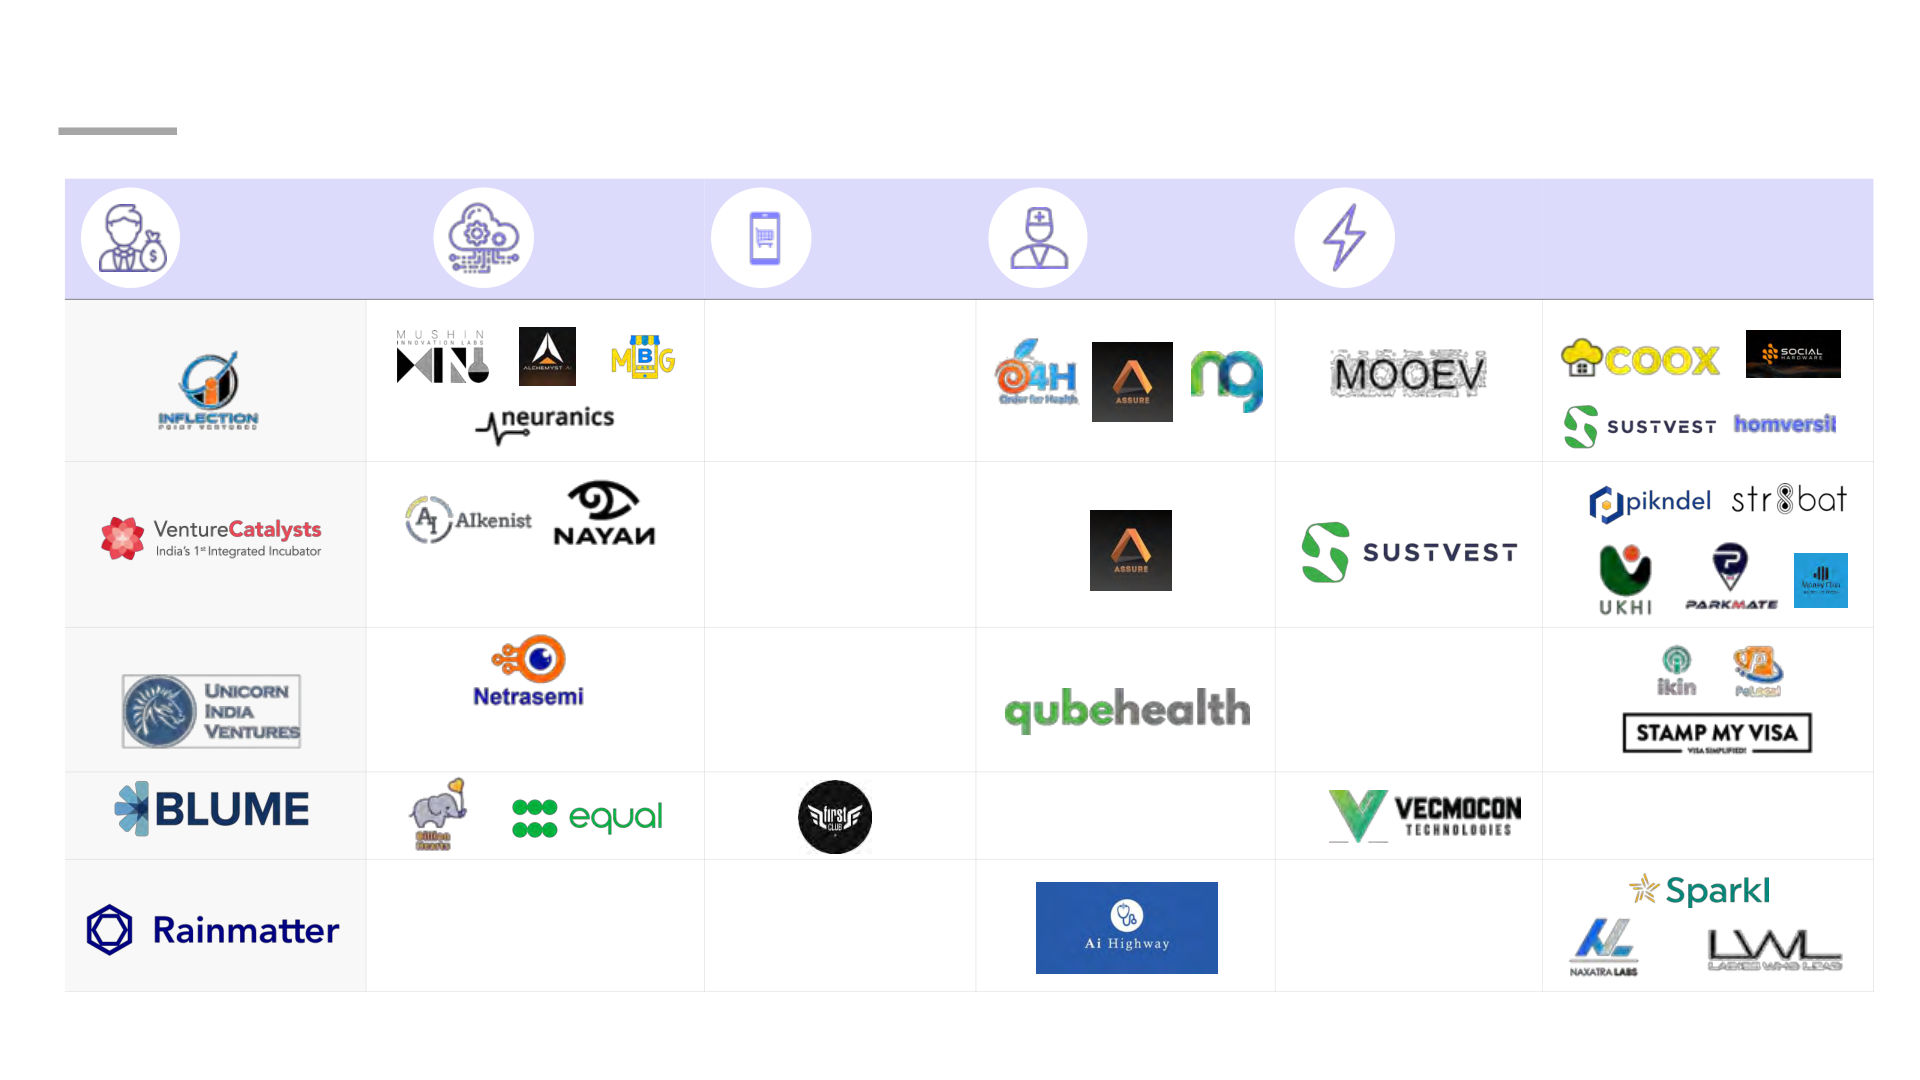
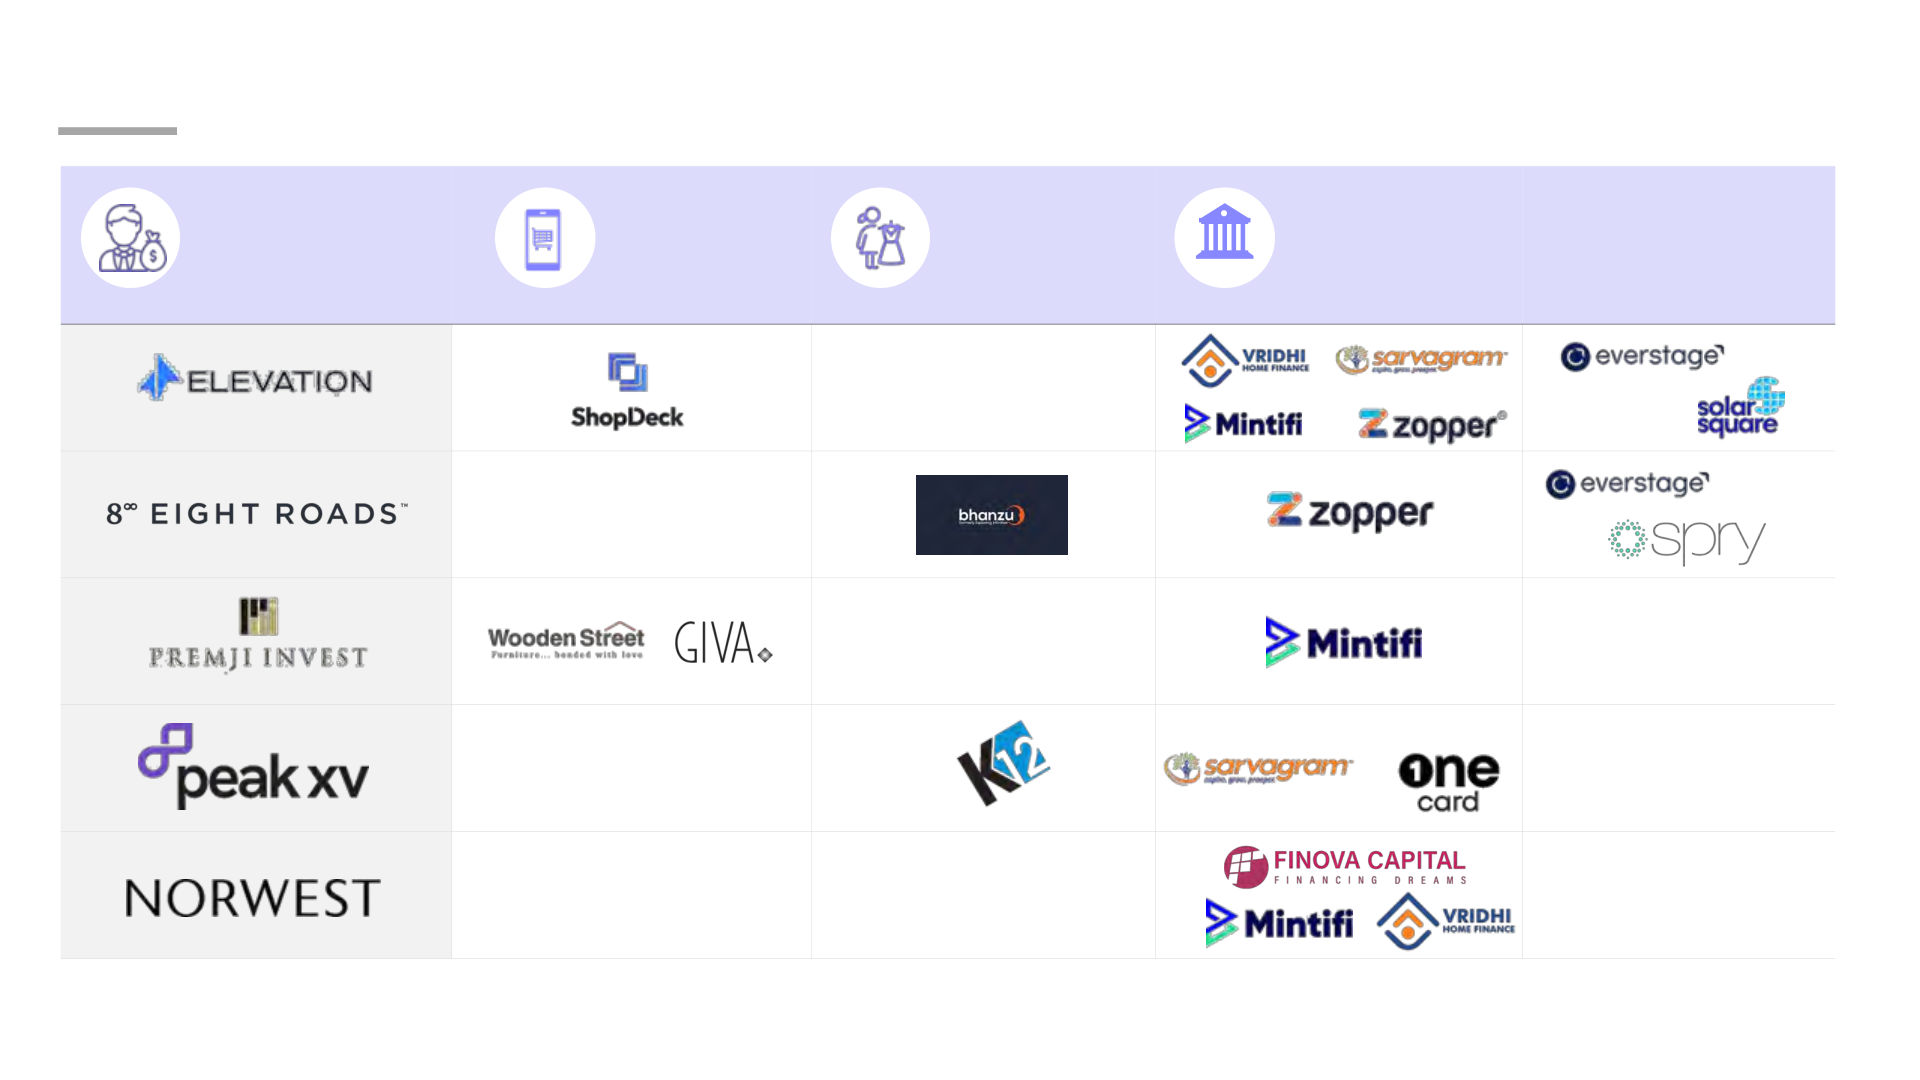
INDIA QUARTERLY INVESTMENT ANALYSIS Q4 CY 2024 FEB 2025 Foreword Projected to reach US $ 10 trillion economy by 2032 , India’s economy remains resilient, fueled by reforms that improve the business landscape . Its strategic geopolitical position enhances its appeal as an investment Devmalya Mukherjee hub . Initiatives such as 'Make in India,' 'Startup India’ & Production Linked Incentive (PLI) schemes strengthen its manufacturing capabilities . India is on track to surpass major economies like the US, China, Director Germany, South Korea, and Japan in manufacturing . However, in Q 4 CY 2024 , dealmaking activity fell by Financial Investors ~ 60 % from the previous quarter, indicating cautious investor sentiment . In equity investments, growth - stage funding has led the funding landscape, representing ~ 40 % of total funding rounds, particularly in sectors like BFSI, Consumer app & platforms, and SaaS/AI . Startups with solid fundamental metrics, mature operating metrics & sustainable growth characteristics are well - positioned for expansion, supported by a strong user base & brand identity . Despite a positive long - term outlook, Q 4 has seen a marginal ~ 5 % decline in deal volume, coupled with a ~ 60 % decrease in average deal size, signaling a cautious approach towards dealmaking and investment in quality assets . The Debt deal space also saw limited traction in Q 4 , contributing only ~ 10 % to total deal amount . However, the rapid growth of India's economy has fueled the expansion of mid - sized businesses, which are increasingly turning to Debt for tailored financial solutions, thanks to its ability to offer flexible structures In addition to a strengthening economy, supportive government policies and continuous infrastructure improvements enhance the investment climate in India . The relentless focus on technological advancement and innovation, fueled by startups, remains a key catalyst for growth . This report aims to uncover some of the key trends during Q 4 2024 . At 1 Lattice, we hold an optimistic outlook, believing that this report will provide valuable insights . We eagerly anticipate the opportunity to engage in an open dialogue with our partners across diverse industries, as we exchange notes and delve deeper into these matters while closely monitoring the evolving situation . © 1Lattice | 2 Product in Spotlight - DealPulse This report was curated using our cutting - edge product, DealPulse DealPulse provides comprehensive visibility into your industry benchmarks and best practices. From tracking macro indicators and government regulations to specific operating metrics and best practices of your peers, from monitoring pricing strategies to evaluating brand reputation through sentiment analysis and social listening, DealPulse covers all bases to help you adapt your strategies for beating the industry standards. This report offers invaluable insights into India's robust economy, driven by ongoing reforms that enhance the business environment. In this report, DealPulse empowered our expert team with comprehensive research tools to analyze the overall funding landscape, investor behavior patterns, and deal sizes. By leveraging DealPulse , we gained a detailed understanding of the factors driving investment trends and the opportunities they present. This comprehensive approach allowed us to present a thorough analysis of the current investment landscape in India, offering you the insights needed to navigate and capitalize on emerging opportunities. Equip your business with the intelligence provided by DealPulse to stay ahead in today's competitive market, consistently outperform industry standards, and achieve sustainable success. Key takeaways Funding landscape & investment dynamics • Startups raised US $ 4 . 7 B across 217 deals in Q 4 CY 24 , signaling a decline in total funding (~ 53 % by value) on a QoQ basis ; Deal volume dropped marginally from 229 deals in Q 3 CY 24 to 217 deals in Q 4 CY 24 • Early - stage investments surged, with deal volume up ~ 43 % and funding value rising 75 % QoQ, signaling strong momentum in the startup ecosystem – Similarly, late - stage investments rebounded, doubling in value QoQ, signaling renewed investor confidence – Debt deals plunged by ~ 70 % in value QoQ • Average deal size shrank ~ 50 % QoQ highlighting a cautious funding environment Sectoral focus & key deals • Ecommerce & listing platforms and energy sector led Q 4 funding with ~ US $ 1 B each, closely followed by BFSI with ~US $ 0 . 9 B funding • Reliance Power (~US $ 0 . 5 B) and Zepto (~US $ 0 . 4 B) received the highest funding in Q 4 CY 24 • While SaaS/AI dominated the early - stage funding (~US $ 0 . 2 B) , BFSI dominated the growth - stage funding (~US $ 0 . 7 B) ; E - commerce & listing platforms led the growth - stage funding (~US $ 0 . 7 B) • Zepto , Rebel Foods, and Purplle emerged as the top fundraisers among tech companies in Q 4 CY 24 • Inflection Point Venture ( 12 deals) , Venture Catalysts ( 9 deals) , Unicorn India Ventures ( 5 deals) , led early - stage investments in Q 4 CY 24 followed by Blume and Rainmatter ( 4 deals each) • Elevation ( 7 deals) and Eight Roads ( 4 deals) led growth - stage investments followed by Premji Invests, Peak XV, and Norwest (with 3 deals each) Key highlights Average ticket size Deal v olume Funding US$ 21.7M 217 US $ 4.7 B SNAPSHOT Q4 CY 2024 Top funded sector Total equity funding Most funded stage* Ecommerce & US$ 3.9B Growth listing platforms Note(s): *Most funded stage is with respect to its volume Funding market by funding round Debt (US$ 0.8B) and Series G (US$ 0.6B) were the highest contributors to overall funding raised in Q4 CY24 Funding market round wise break - up Total funding size: US$ 4.7B (US$ B, Q4 CY24) 0.4 0.4 0.5 0.8 0.5 Series F Series B PE Deb t Series C 0.6 0.5 0.3 0.2 0.1 0.4 Series G Series A Seed Series D PIPE Series E 0.03 Consists of buyout © 1Lattice | 6 Source(s): 1Lattice Deals Database Funding market by sectors Ecommerce & listing platforms and Energy (~US$ 1B each) saw the most interest from investors, followed by BFSI (~US$ 0.9B) in Q4 CY24 Funding market sector wise break - up Total funding size: US$ 4.7B (US$ B, Q4 CY24) 0.6 0.5 Consumer app SAAS/AI and platforms 1.0 1.0 0.9 Ecommerce & 0.1 FMCG Energy listing BFSI 0.03 0.3 Retail platforms 0.2 Healthcare & Manufacturing Lifesciences 0.03 0.1 Others * Travel & hospitality Note(s): *Others include telecom, transport & logistics, space tech, and drone tech © 1Lattice | 7 Source(s): 1Lattice Deals Database Funding market by sectors SaaS/AI sector saw the highest deal volume from investors (58 deals), followed by ecommerce & listing platforms (32 deals) in Q4 CY24 Funding market segment wise break - up Total deal volume: 217 (#, Q4 CY24) 26 20 32 Healthcare & Life Sciences Manufacturing Ecommerce & listing platforms 11 58 8 Others* Energy 28 15 12 5 2 Consumer app & Travel & SaaS/AI platforms BFSI FMCG Retail hospitality Note(s): *Others include telecom, transport & logistics, space tech, and drone tech © 1Lattice | 8 Source(s): 1Lattice Deals Database Top 10 highest funded companies Reliance Power has received the highest investment (US$ 500M), followed by Zepto (US$ 350M) in Q4 CY 2024 - Equity deals 500 - Debt deals 35 0 Top 10 highest funded companies of Q4 300 CY 2024 (US$ M) 210 110 118 180 135 150 180 Source(s): 1Lattice Deals Database © 1Lattice | 9 Agenda Deal landscape in Q4 CY24 Key deals and investment themes Key investors Investment amount and # deals Investments in Q4 CY24 have declined, with the total amount of investment declining to $4.7B from US$ 10B in Q3 CY24 Investment amount (US$ B) and # deals (Q4 CY23 – Q4 CY24) 366 318 290 229 217 16.5 11.6 10.0 8.2 4.7 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, PIPE, Buyout and Debt deals(Conventional, Venture, etc.) © 1Lattice | 11 Source(s): 1Lattice Deals Database Equity vs debt investments Both equity and debt deals saw a drop from previous quarter to US$ 3.9B and US$ 0.8B respectively in Q4 CY24 Equity investments (US$ B) and # deals Debt deals (US$ B) and # deals (Q4 CY23 – Q4 CY24) (Q4 CY23 – Q4 CY24) 115 275 251 261 204 67 162 9.4 7.9 43 7.9 7.2 5.8 29 4.2 3.9 13 2.2 1.0 0.8 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Amount Deals Amount Deals Note(s):Equity includes early (Pre - seed, seed, pre - series and Series A), growth stage (Series B, C, D and E), late (Series F onw ards) stage investments, others (PIPE and buyout) and Debt deals includes conventional debt and private credit © 1Lattice | 12 Source(s): 1Lattice Deals Database Stage - wise investments Early and Late - stage deals doubled in value in Q4 CY24 compared to the previous quarter while debt and buyout deals nose - dived Investment amount (US$ B) (Q4 CY23 – Q4 CY24) N = 366 290 318 229 217 0.1 3.4 0.8 2.4 2.7 4.5 1.5 1.0 7.9 4.2 2.2 1.8 1.5 2.1 0.7 2.4 2.0 2.3 1.9 2.0 0.8 0.7 0.8 0.8 0.4 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Early Growth Late Debt Others (PIPE & Buyout) Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards and PE dea ls) stage investments, others (PIPE and buyout) and Debt deals(Conventional, Venture, etc.); *Number of deals © 1Lattice | 13 Source(s): 1Lattice Deals Database Average deal size Average deal size halved from ~US$ 44M in Q3 CY24 to ~US$ 22M in Q4 CY24, while deal volume remained steady Deal volume by stage Average deal size (%, Q4 CY23 – Q4 CY24 ) (US$ M, Q4 CY23 – Q4 CY24 ) 45.3 366 290 318 229 217 43.6 3% 4% 5% 6% 6% 10% 14% 36.4 5% 5% 29% 30% 4% 20% 22% 28.3 2% 24% 4% 19% 21.7 15% 67% 59% 53% 47% 43% Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q4 CY23 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Early Growth Late Debt Others* Note(s): Stage of investment here is decided by the round of investment. Pre - seed, seed, pre - series and Series A are classified as Early, Series B, C, D and E are classified as Growth, Series F onwards are classified as Late, Debt deals includes deals with Conventional, Venture, etc. *Others include d eal s with undisclosed round, PIPE, Buyout etc. © 1Lattice | 14 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q4 CY24 Key deals and investment themes Key investors Top 10 investments in Q4 CY24 Top 10 investments in Q4 CY24 Top 10 investments in Q4 CY24 Amount Company Sector Funding stage Key Investors (US$ M) 500 Debt Energy Varde Investment Partners LP Motilal Oswal Private Wealth Management, RPSG Capital Ecommerce & listing platforms 350 Late Ventures, Motilal Oswal Asset Management, Claypond Capital Energy 300 Late BII, KLP, Norfund Ecommerce & listing platforms 210 Late Evolvence , Temasek Abu Dhabi Investment Authority, Premji Invest, Blume Ecommerce & listing platforms 180 Late Ventures, Sharrp Ventures Lok capital, Prosus Ventures, Premji Invest, Elevation Capital, BFSI 180 Growth Ontario’s Teachers pension plan, IFC, Norwest Ventures Partners TPG Capital, CPP Investments, Accel, SoftBank Group, Consumer app & platforms 150 Late Leeds Illuminate Norwest Venture Partners, Sofina , Madison India, Avataar BFSI 135 Growth Ventures Multiples Alternate Asset Management Private Limited, British BFSI 118 Growth Columbia Investment BFSI 110 Debt Undisclosed © 1Lattice | 16 Source(s): 1Lattice Deals Database Early - stage investments SaaS/AI received the highest funding of US$ 198M among early - stage investments; Weaver services received the highest funding among the early - stage startups Early - stage investments by sector Top 10 early - stage investments in Q4 CY24 (US$ M, Q4 CY24) Amount Company Sector Key investors (US$ M) SaaS/AI 198 Consumer app Consumer app & platforms 94 Lok Capital, Gaja Capital 165 and platforms Manufacturing 97 Travel & hospitality 50 Vani Kola, Mohandas Pai, Ranjan Pai Lightspeed Venture partners, Healthcare & Life Sciences 78 M anufacturing 40 Alpha wave global Ecommerce & listing platforms He althcare & life 60 3 0 Founders Fund, 8VC, Khosla Ventures sciences Travel & hospitality 51 Nexus Venture Partners, Matrix Partners S aaS /AI 30 India, NTTVC FMCG 36 Nexus Venture Partners, EDB Retail 29 S aaS /AI 26 Investments, Saison Capital, Quona Capital, Global Ventures BFSI 13 S aaS /AI 20 Elevation Capital, Iconiq Capital Transportation & logistics 4 Healthcare & General Catalyst Partners, Gruhas 20 Lifesciences Energy Others include 1 sectors such as Lightspeed Venture Partners, Anicut spacetech and SaaS/AI Telecom 15 1 dronetech Capital, Alteria Capital Others 19 Abakkus Asset Manager, Girik Capital, R etail 13 Param Capital, Sixth Sense Ventures Note(s): Early - stage investments include Pre - seed, Seed, Pre - series A and Series A © 1Lattice | 17 Source(s): 1Lattice Deals Database Top early - stage investments Top 5 early - stage startups with their competitors (in terms of funding amount) Company Description Competitors Weaver has built a nationwide presence on an unwavering commitment to its clients’ success, acting with integrity and always striving to transcend expectations Tripfactory is the fastest growing dotcom company for inbound & outbound Holiday travel Global factory for specialty chemicals and intermediates Even is a health - tech company and healthcare provider that partners directly with the top hospitals in the country Provides a range of generative AI platforms and services aimed at assisting clients in overseeing their AI projects Source(s): 1Lattice Deals Database © 1Lattice | 18 Growth - stage investments BFSI sector dominated the growth - stage investments with funding of ~US$ 740M followed by Consumer app & platforms (~US$ 230M) Growth - stage investments by sector Top 10 growth - stage investments in Q4 CY24 (US$ M, Q4 CY24) Amount Company Sector Key investors (US$ M) BFSI 740 Norwest Venture Partners, IFC, Elevation Capital, BFSI 180 Ontario’s Teacher Pension Plan, Premji Invest, Prosus Ventures, Lok Capital Consumer app & platforms 227 Norwest Venture Partners, Sofina, Madison India, BFSI 135 Avataar Ventures Multiples Alternate Asset Management Private SaaS/AI 205 BFSI 118 Limited, British Columbia Investment BFSI 100 Prosus Ventures Ecommerce & listing platforms 151 Peak XV partners, Elevar Equity, Elevation Capital, BFSI 67 Temasek, TVS Capital Manufacturing 97 Consumer app & 60 Temasek platforms Ecommerce & Healthcare & Life Sciences 72 60 Navis Capital Partners, Dragon funds listing platforms Proparco , Korys , Incofin , GEF Capital Partners, SaaS/AI 46 Responsibility Investments AG Energy 40 Smith Point Capital ,Nexus Venture SaaS/AI 44 Partners,Battery Ventures Includes the agritech , Others HoReCa , and drone 4 Manufacturing 44 Craegis , Beenext , Accel Note(s): Growth - stage investments include Series B, C, D and E; * Mintifi – Investment in 2 tranches, US$ 180M and US$ 80M © 1Lattice | 19 Source(s): 1Lattice Deals Database Top growth - stage investments Top 5 growth - stage startups with their competitors (in terms of funding amount) Company Description Competitors Online marketplace for business loans Micro - credit for low income individuals and businesses Provider of affordable housing finance solutions Housing finance company working to enable millions of Indians to fulfill their dreams of owning a bigger, better and a new home Provider of home, personal, farm and business loans Source(s): 1Lattice Deals Database © 1Lattice | 20 Late - stage investment Late - stage investments were driven by Ecommerce & listing platforms sector (~US$ 740M) Late - stage investment, by sector Top late - stage investments in Q4 CY24 (US$ M, Q4 CY24) Amount Company Sector Key Investors (US$ M) Motilal Oswal Private Wealth Management, RPSG Ecommerce & 350 Ecommerce & listing Capital Ventures, Motilal Oswal Asset listing platforms 740 Management, Claypond Capital platforms Energy 300 BII,KLP,Norfund Energy 398 Ecommerce & 210 Temasek, Evolvence listing platforms Consumer app & 150 Ecommerce & Abu Dhabi Investment Authority, Premji Invest, platforms 180 listing platforms Blume Ventures, Sharrp Ventures Healthcare & Life Consumer app & TPG Capital, CPP Investments, Accel, SoftBank 150 95 Sciences platforms Group, Leeds Illuminate SBI Life Insurance, Enam Holdings, Motilal Oswal, Heathcare & 95 Param Capital, WhiteOak Capital, HBM Healthcare Life Sciences SaaS/AI 70 Investments, Valuequest Investment Advisors Energy 85 GEF Capital Partners, Enam Holdings Manufacturing 20 SaaS/AI 70 Khosla Ventures, Greenoaks Capital, Avenir growth Note(s): Late - stage investments include Series G onwards rounds © 1Lattice | 21 Source(s): 1Lattice Deals Database Top late - stage investments Top funded late - stage startups with their competitors (in terms of funding amount) Company Description Competitors Zepto is an online grocery delivery service IndiGrid operates with the objective to empower the nation by delivering reliable power to each and every home Provider of virtual restaurant network for food businesses Purplle is an online store selling cosmetics, fragrances, skin, and hair care products Provider of executive - level programs for professionals © 1Lattice | 22 Source(s): 1Lattice Deals Database Tech investments In Q4 CY24, Ecommerce & listing platforms (US$ 915M) and SaaS/AI (US$ 451M) were the 2 most funded sector in the tech segment, followed by Consumer app & platform (US$ 434M) Tech investments by sector Top 10 tech investments in Q4 CY24 (US$ M, Q4 CY24) Amount Company Sector Key Investors (US$ M) Ecommerce & listing 915 platforms Motilal Oswal Private Wealth Management, RPSG Ecommerce & 350 Capital Ventures, Motilal Oswal Asset Management, listing platforms Claypond Capital SaaS/AI 451 Ecommerce & 210 Temasek, Evolvence listing platforms Consumer app & 434 Ecommerce & Abu Dhabi Investment Authority, Premji Invest, platforms 180 listing platforms Blume Ventures, Sharrp Ventures Norwest Venture Partners, IFC, Elevation Capital, BFSI 285 Ontario’s Teacher Pension Plan, Premji Invest, BFSI 180 Prosus Ventures, Lok Capital Consumer app & Manufacturing 118 100* Think India Opportunities Master Fund platforms Consumer app & Healthcare & Life Lok Capital,Gaja Capital 94 73 platforms Sciences SaaS/AI 70 Khosla Ventures, Greenoaks Capital, Avenir growth Energy 53 Consumer app & 60 Temasek platforms Travel & Hospitality 51 Includes telecom, Ecommerce & 60 Navis Capital Partners, Dragon Funds transportation & listing platforms logistics, Others 22 spacetech , and dronetech Travel & Hospitality 50 Vani Kola, Mohandas Pai, Ranjan Pai Notes: * represents a PIPE deal 0 © 1Lattice | 23 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q4 CY24 Key deals and investment themes Key investors Active investors Most active investors of Q4 CY24 Growth - stage investors Early - stage investors (# deals) (# deals) 12 7 9 4 5 3 4 3 4 3 Note(s): There are 11 late - stage investors with 1 investment each © 1Lattice | 25 Source(s): 1Lattice Deals Database Active early - stage investors Most active early - stage investors and their investment segments in Q4 CY24 Ecommerce Healthcare & SaaS/AI Energy Others Investors & listing Life Sciences - - - - - - - - Source(s): 1Lattice Deals Database © 1Lattice | 26 Active growth - stage investors Most active growth - stage investors and their investment segments in Q4 CY24 Ecommerce Consumer app Investors BFSI Others* & listing & platforms - - - - - - - - - Note(s): *Others include sectors such as Retail, FMCG, Healthcare & Lifesciences, Transportation & logistics, etc. © 1Lattice | 27 Source(s): 1Lattice Deals Database 4 200+ Technology - backed business Offices in India Annual engagements support that helps you ENABLE BETTER 130+ 50+ Team members Inhouse research team DECISIONS 1,000+ 2M+ On - ground staff B2C Panel Deep on - ground insights that you can act on 4 offices, deep experience across geographies – 500K+ 300K+ India, the USA, Europe, MEA, and SEA regions B2B Panel Experts & professionals One - ness of data and people networks to harness the collective power of data, network, and technology 20% 100% Multi - faceted teams offering a stack of consulting, Cost savings Controlled output & timeline advisory, and research services At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (1/2) Intelligence Input Validate Execute Measure & Insights • Market assessment, TAM, SAM • PMF test / feasibility studies • Time motion studies • SOP / process audits • GTM planning • B - plan validation • Brand health track studies • M&A landscape scan • Competitive landscape & scan • B2C Qualitative research • Segmentation and personas • Campaign evaluation • Tracking panels • Customer retention and loyalty • NPS studies • B2C Quantitative research • Customer journey mapping analyses • UI / UX testing • B2B Qualitative research • Account potential assessment • Customer retention analysis • NPS health check • B2B Quantitative research • Contract benchmarking • Sales force productivity • Customer segment GTM • Retail store audits • Retail Measurement Survey • Competitive intelligence • Benchmarking • Mystery shopping • Sentiment analysis • Channel tracks • Listed companies scan • Brand tracks • Micro market assessment • Concept Validation • Go to market Approach • MM competitive intelligence • MM planning • Impact metrics • Funding GTM strategy • Program management • Impact tracking • Founder / leadership assessment • Reputation diligence • Geo analysis • Leadership assessment • Founder integrity DD • Employee NPS • IPO program management • Industry and company data • Report key messages • IPO / QIP reports • Claims data • Claim validation • Gap analysis • Certification / Attribution • ESG standards / metrics • Stakeholder feedback • Gap analysis • ESG assessment • Risk audits and tracking © 1Lattice | 29 At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (2/2) Input Validate Execute Measure Networks • Expert interactions • Due diligence • Short - term projects • Expert access • Expert transcript library • Fitment and turnaround • Enterprise surveys time • Vendor/target search • 1Lattice panel powered by AI • Cohort matching • Short - term projects • NPS health check • Cohort based outreach • Pre search QC • Data scraping • Sales force productivity • B2B / B2C respondent search and • Detailed QC • Retail store audits DIY engagement • Retail Survey (RMS) • Capability assessment • Globally valid certification • Compliance training academy • Compliance certification • Skill matrix benchmarking • Ongoing engagement • Sales & soft skills academy • L&D feedback • Functional skills academy • Custom trainings • Coaches and mentoring network • Role transition support • Experts for mid term projects • Engineering/Technical Due • Marketing / creative hub • Compliance • Fractional CXOs Diligence • Sales hub management • Analyst hub • Analysts on demand • Leadership hiring • Reference checks • Outplacement Support • Talent access • Mid - Level hiring • Board placement • Fitment • Internships and turnaround time • Roadshows • Cohort matching • Curated events • Cohort fitment • Fundraising campaigns • RSVP Management - Channel • Business generated appointments (distributors, franchisee, M&A targets, CXOs) • Associated reports' launch © 1Lattice | 30 We are here for you Amar Choudhary Devmalya Mukherjee CEO, 1Lattice Director, Financial Investors E: amar@1lattice.com E: devmalya.mukherjee@1lattice.com For media queries, please contact Urbashree Bayan Associate Manager – Corporate Communications E: communications@1lattice.com www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in an y form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’ s o wn experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not co nstitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon diff ere nt sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for a ny unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1La ttice does not hold any liability in connection therewith. +91 881 041 9502 d evmalya.mukherjee @1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore