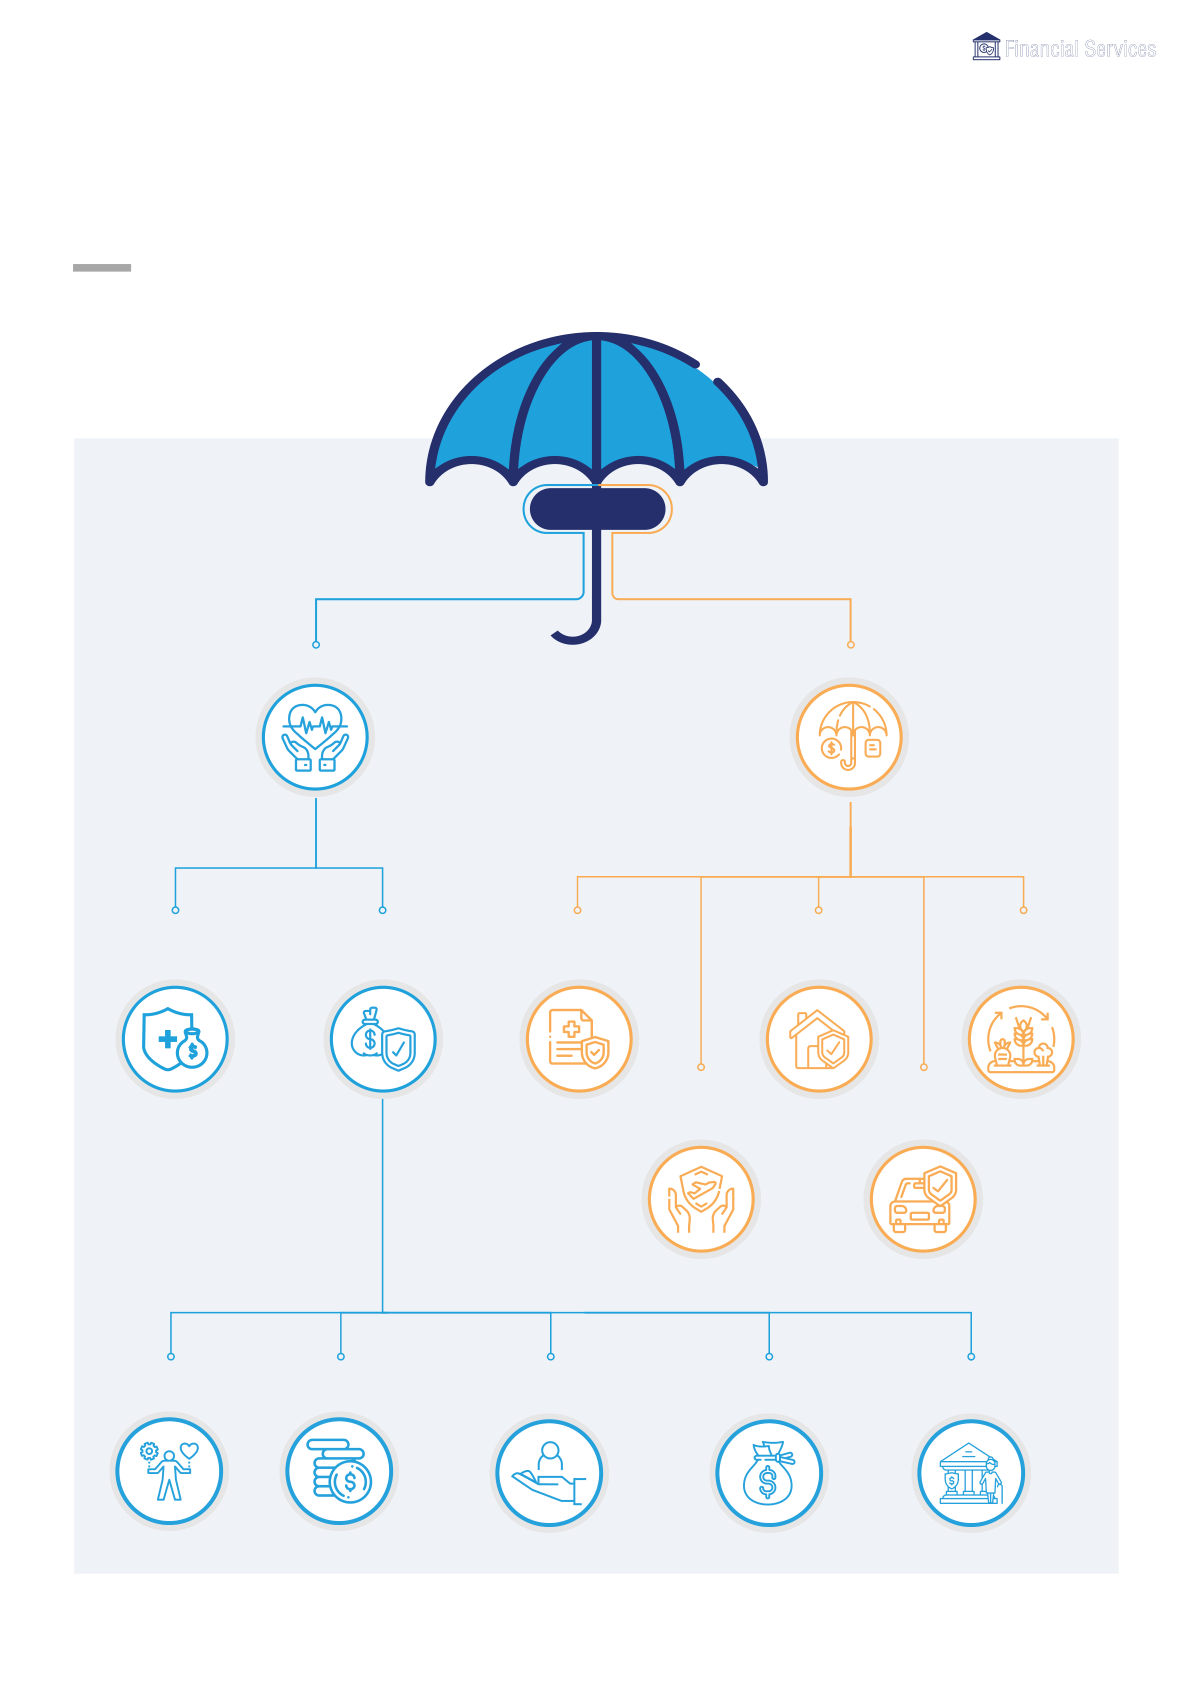
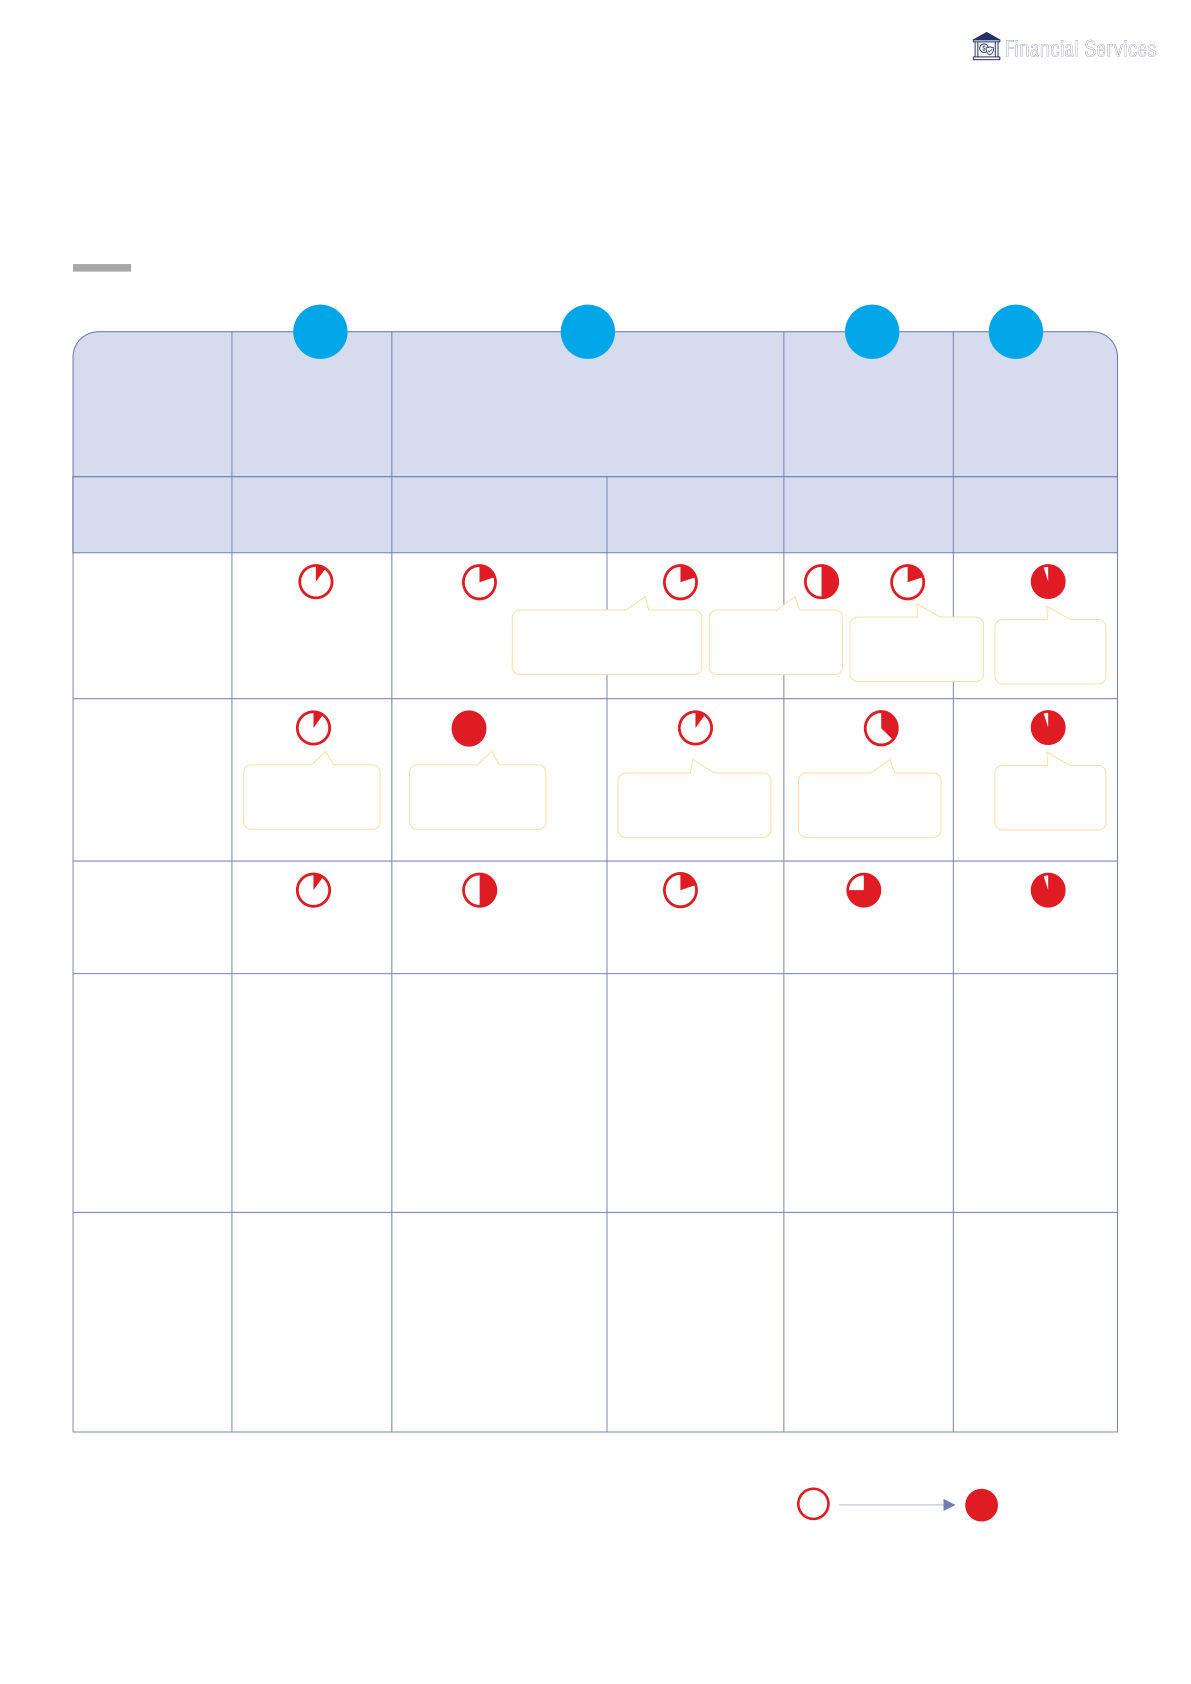
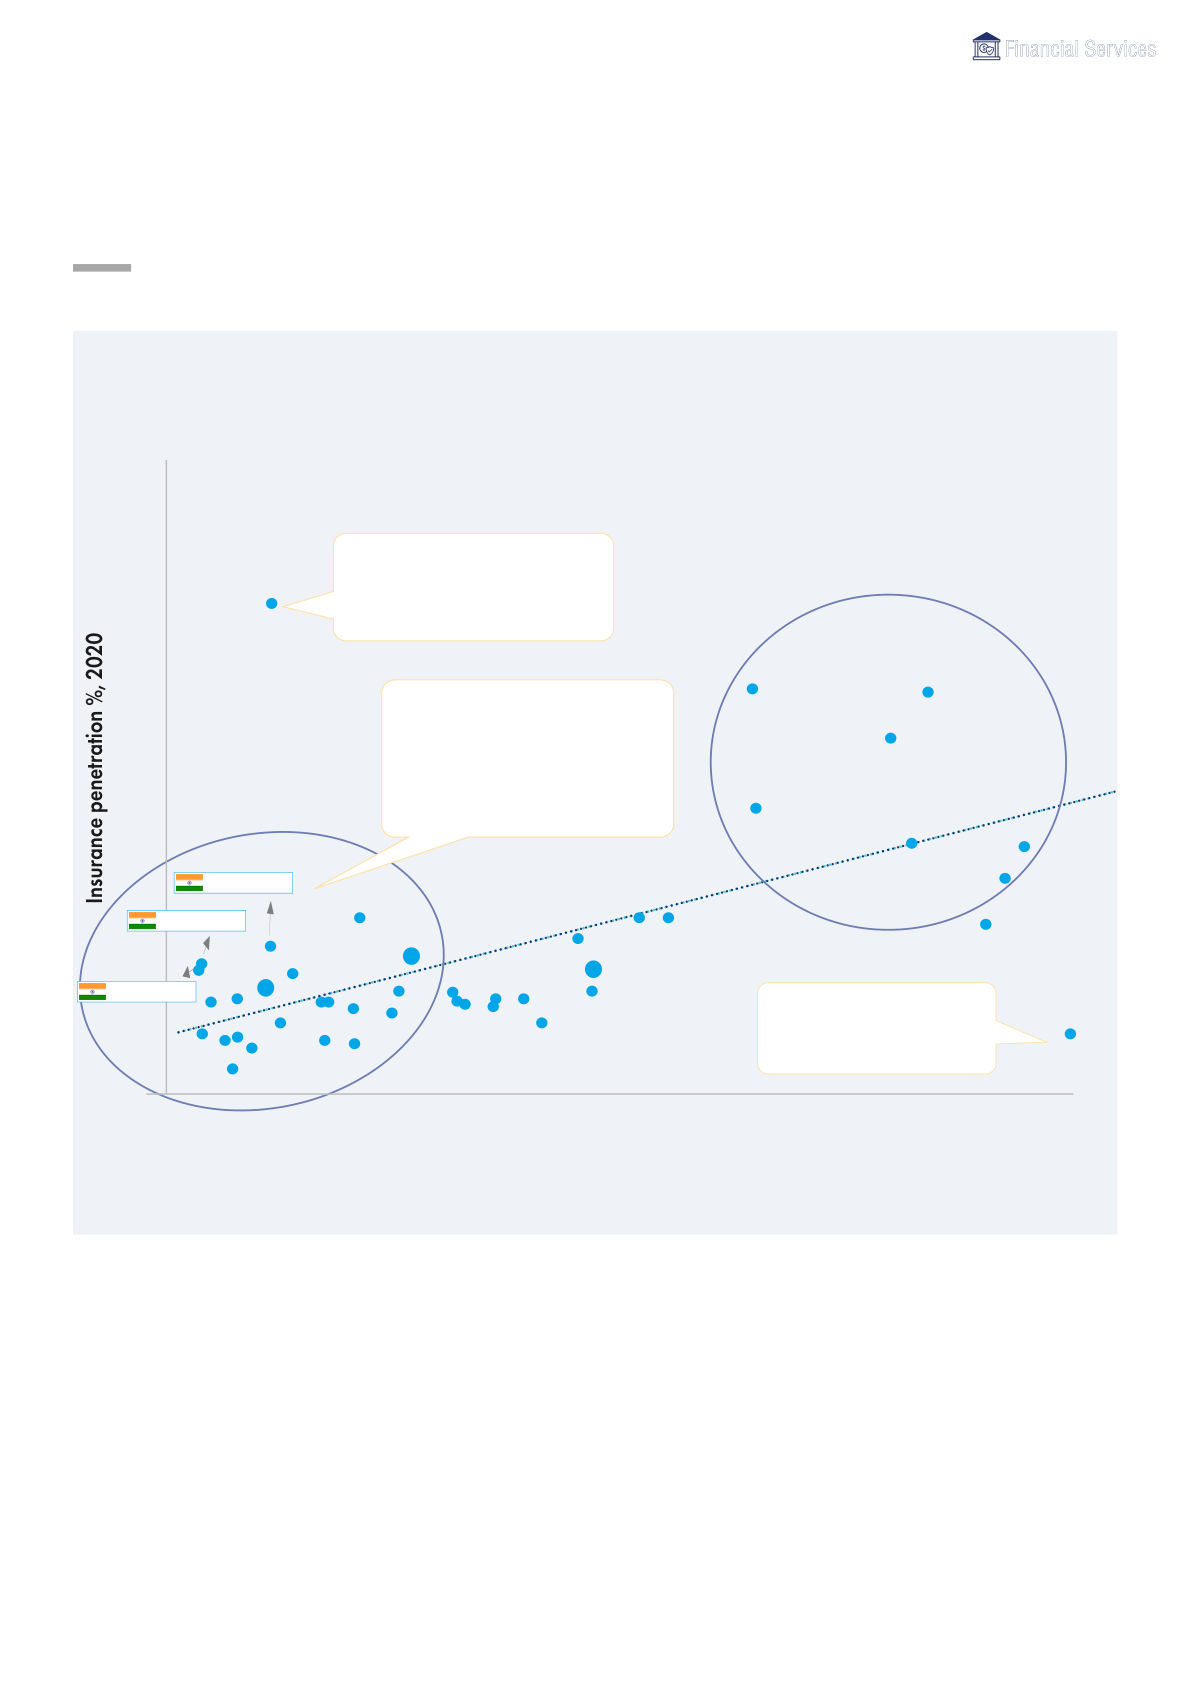
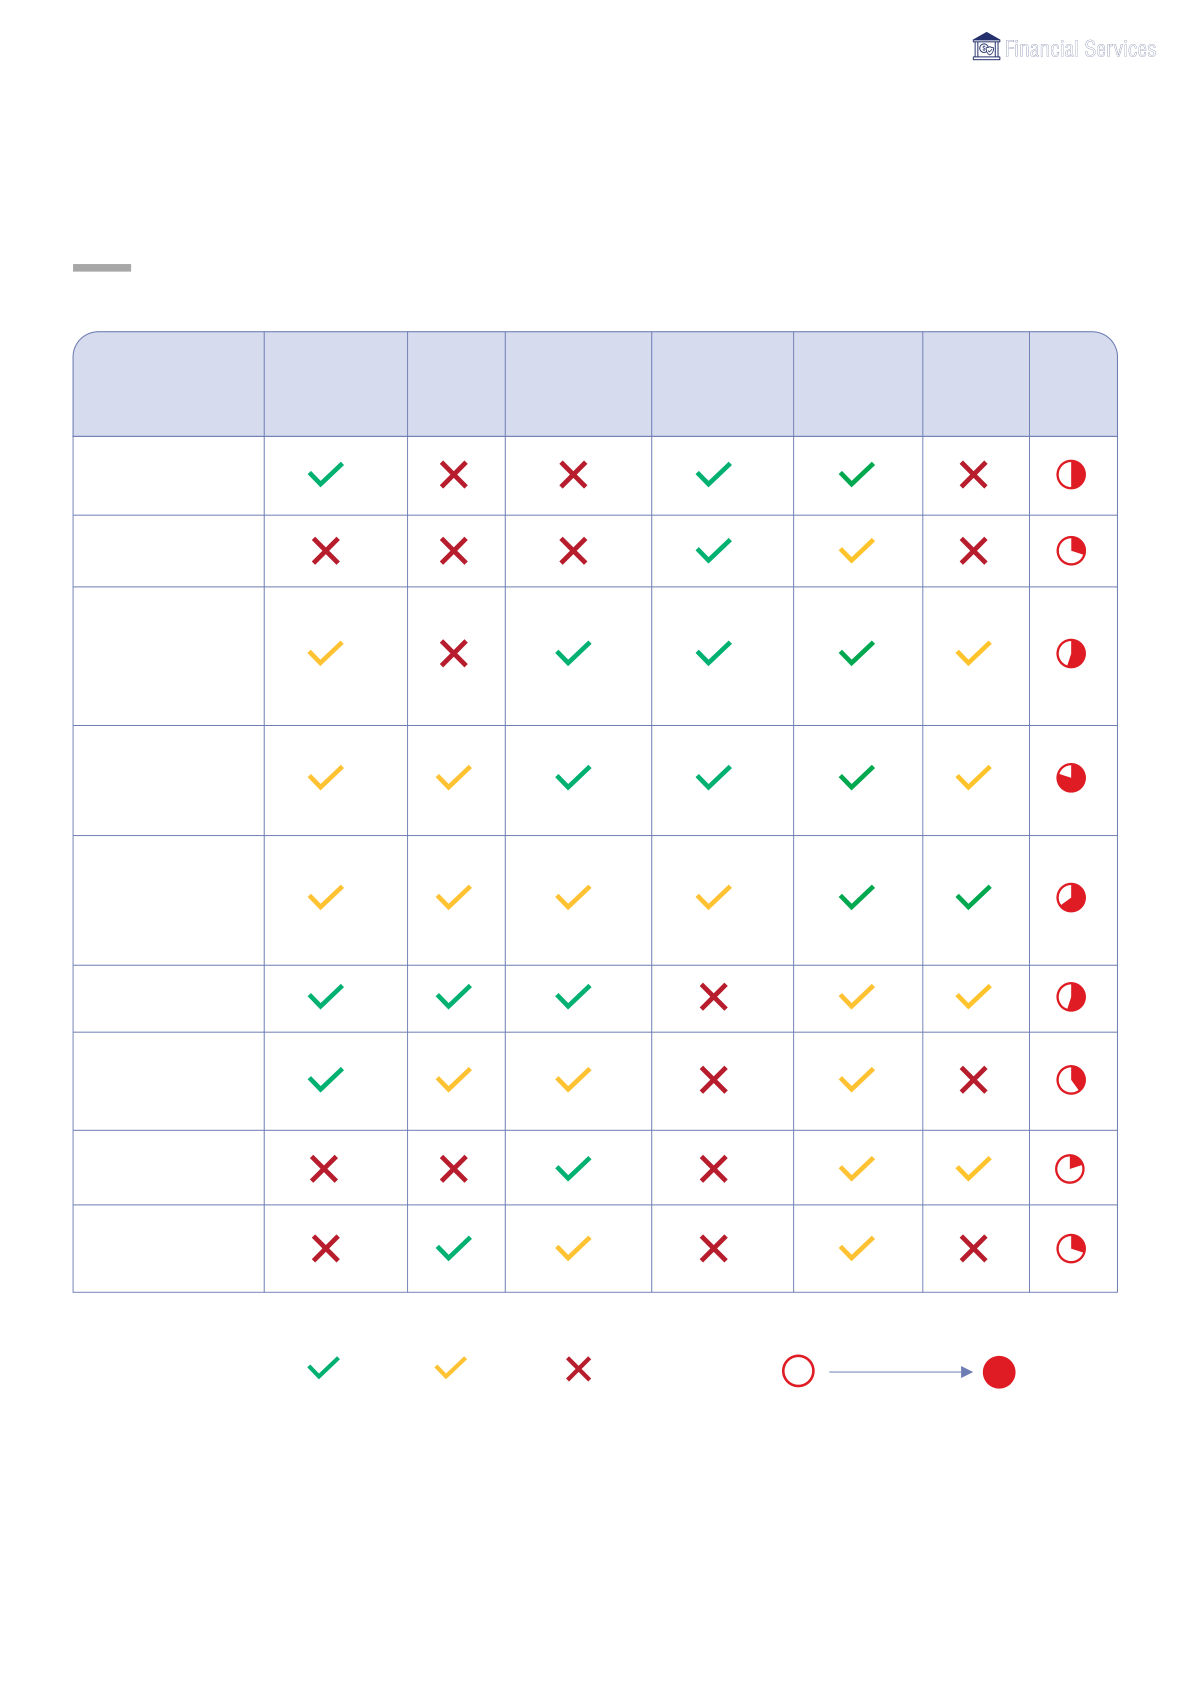
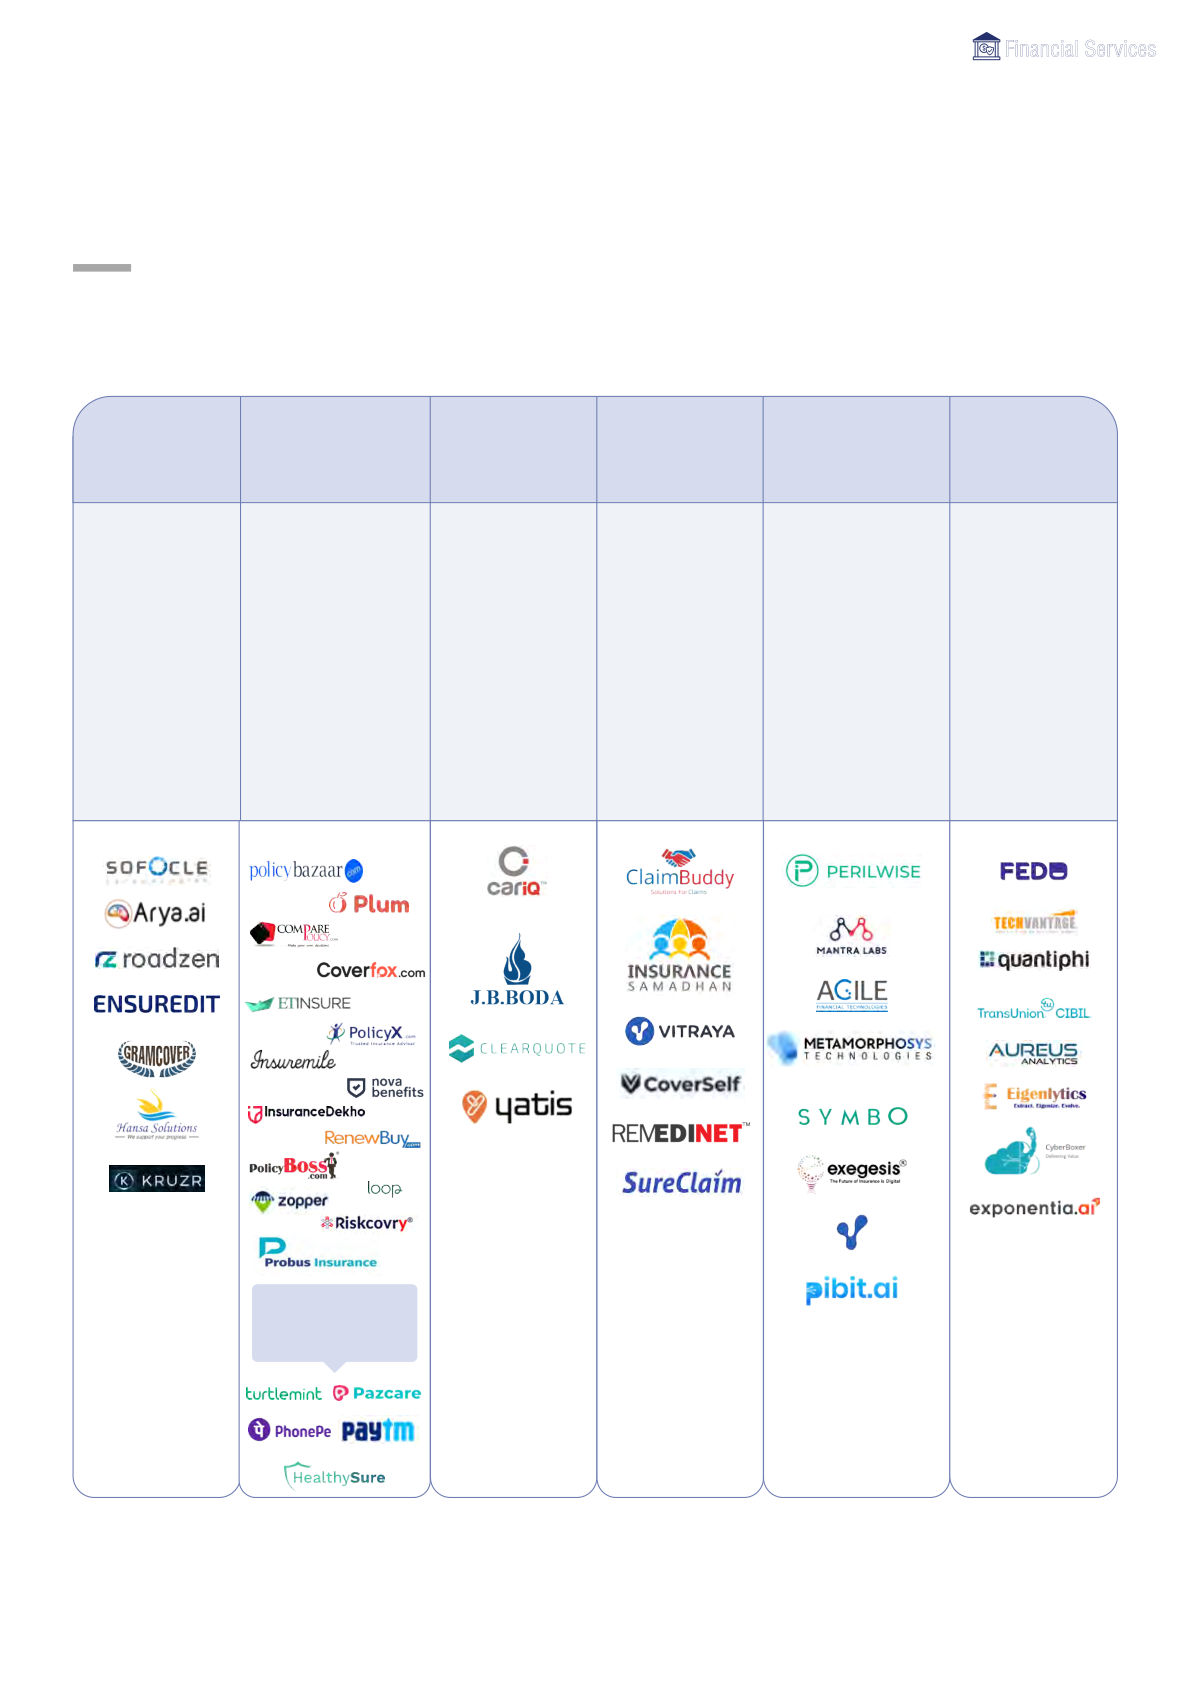
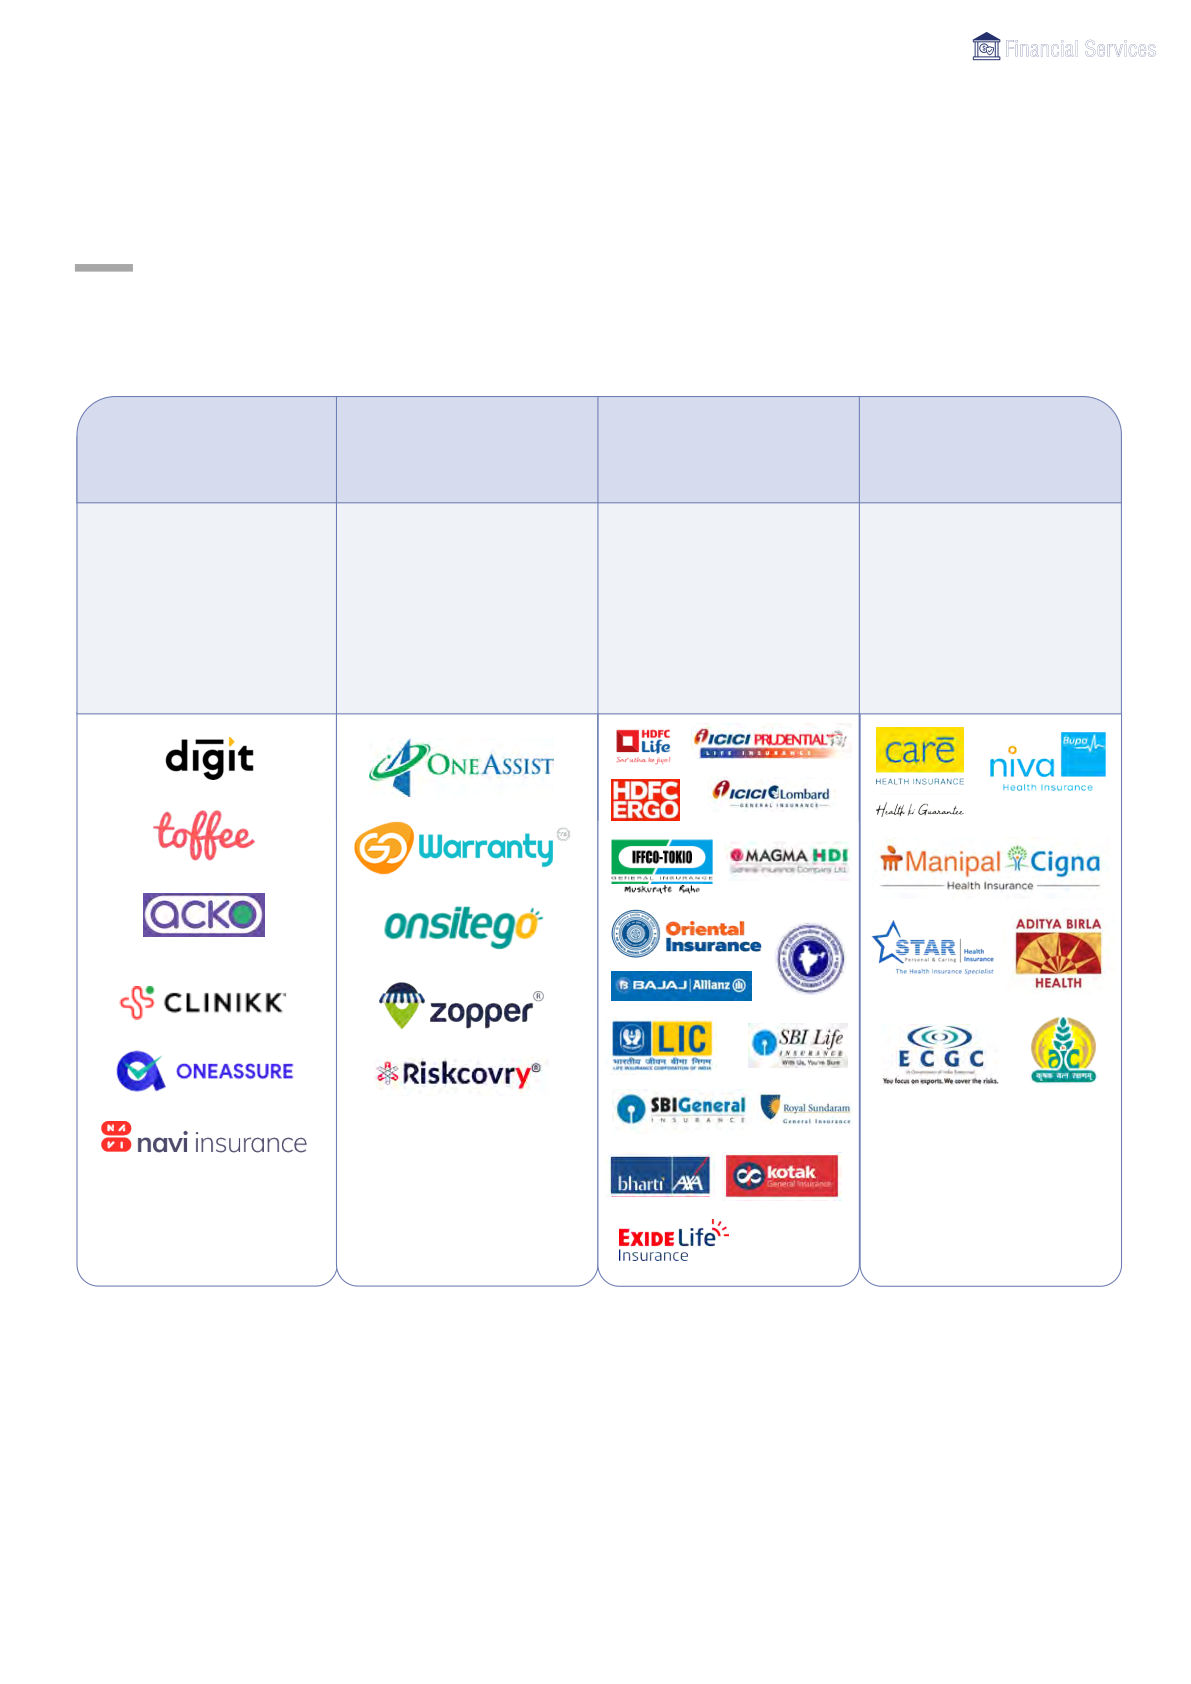
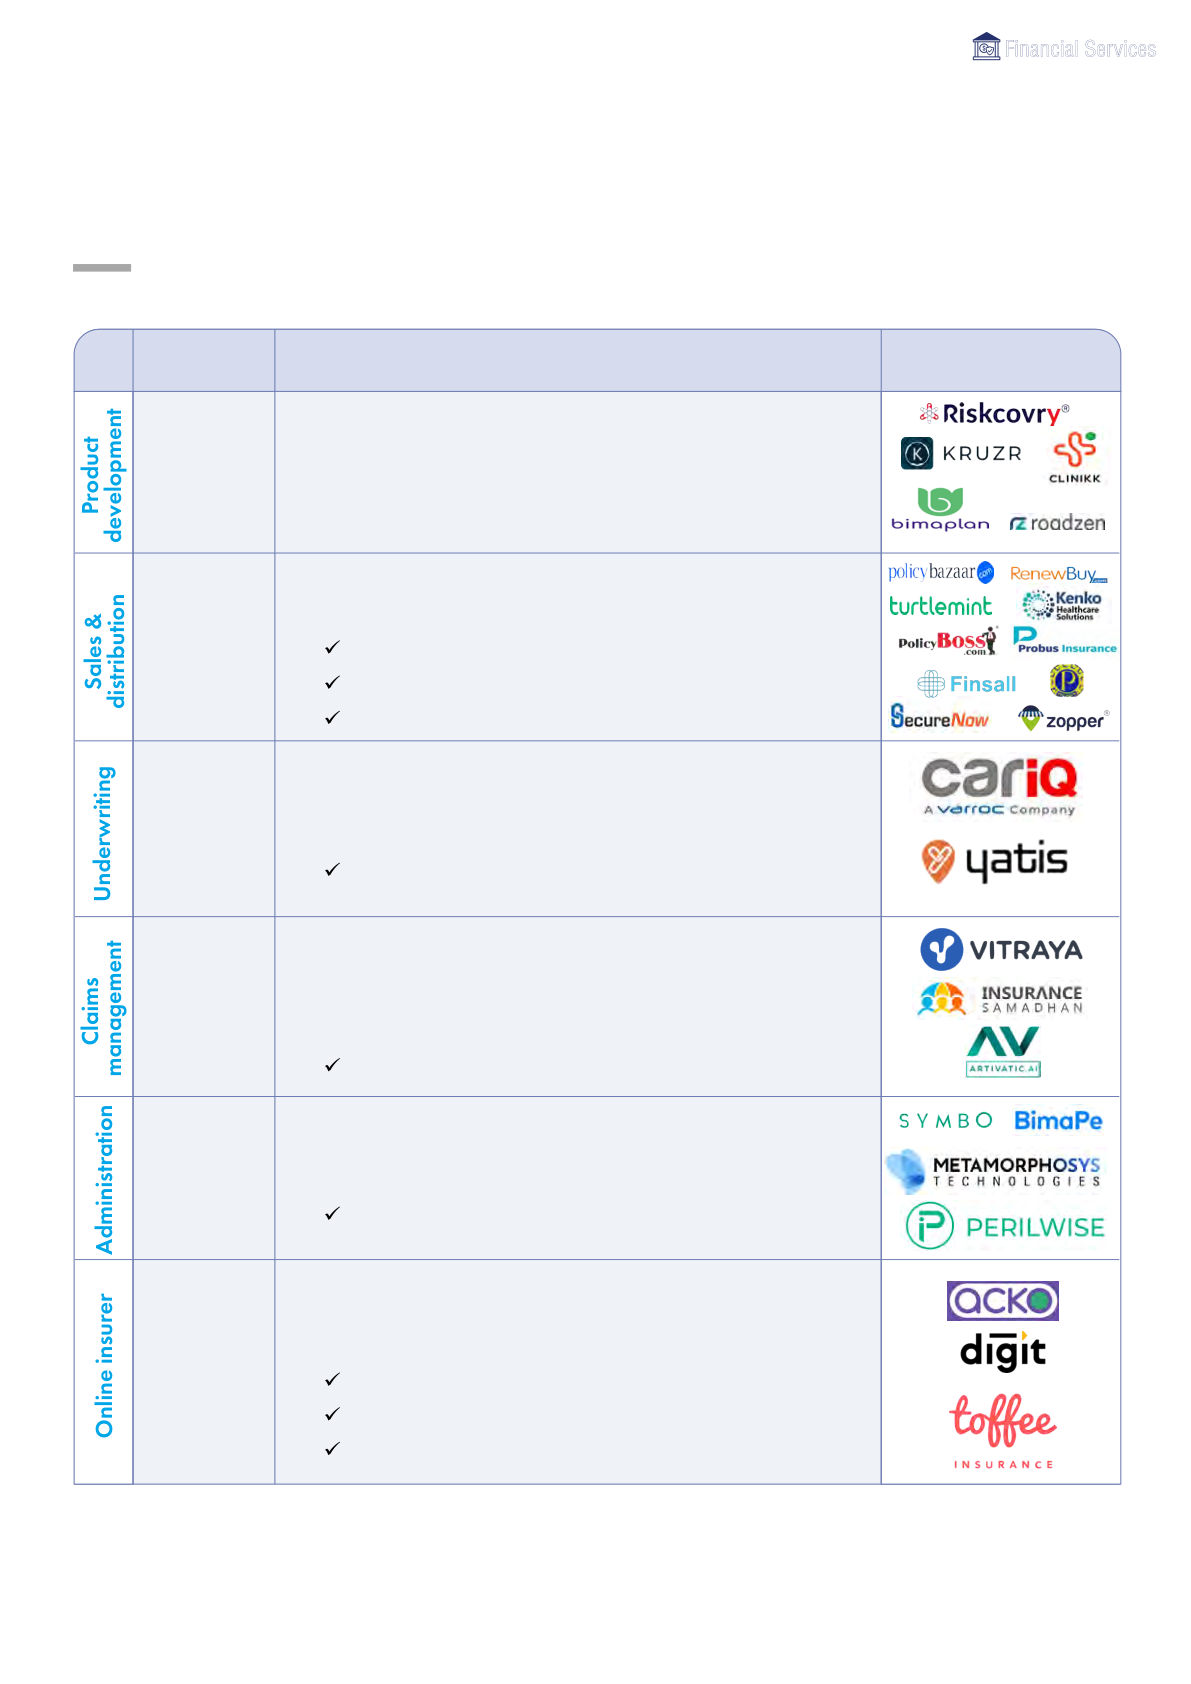
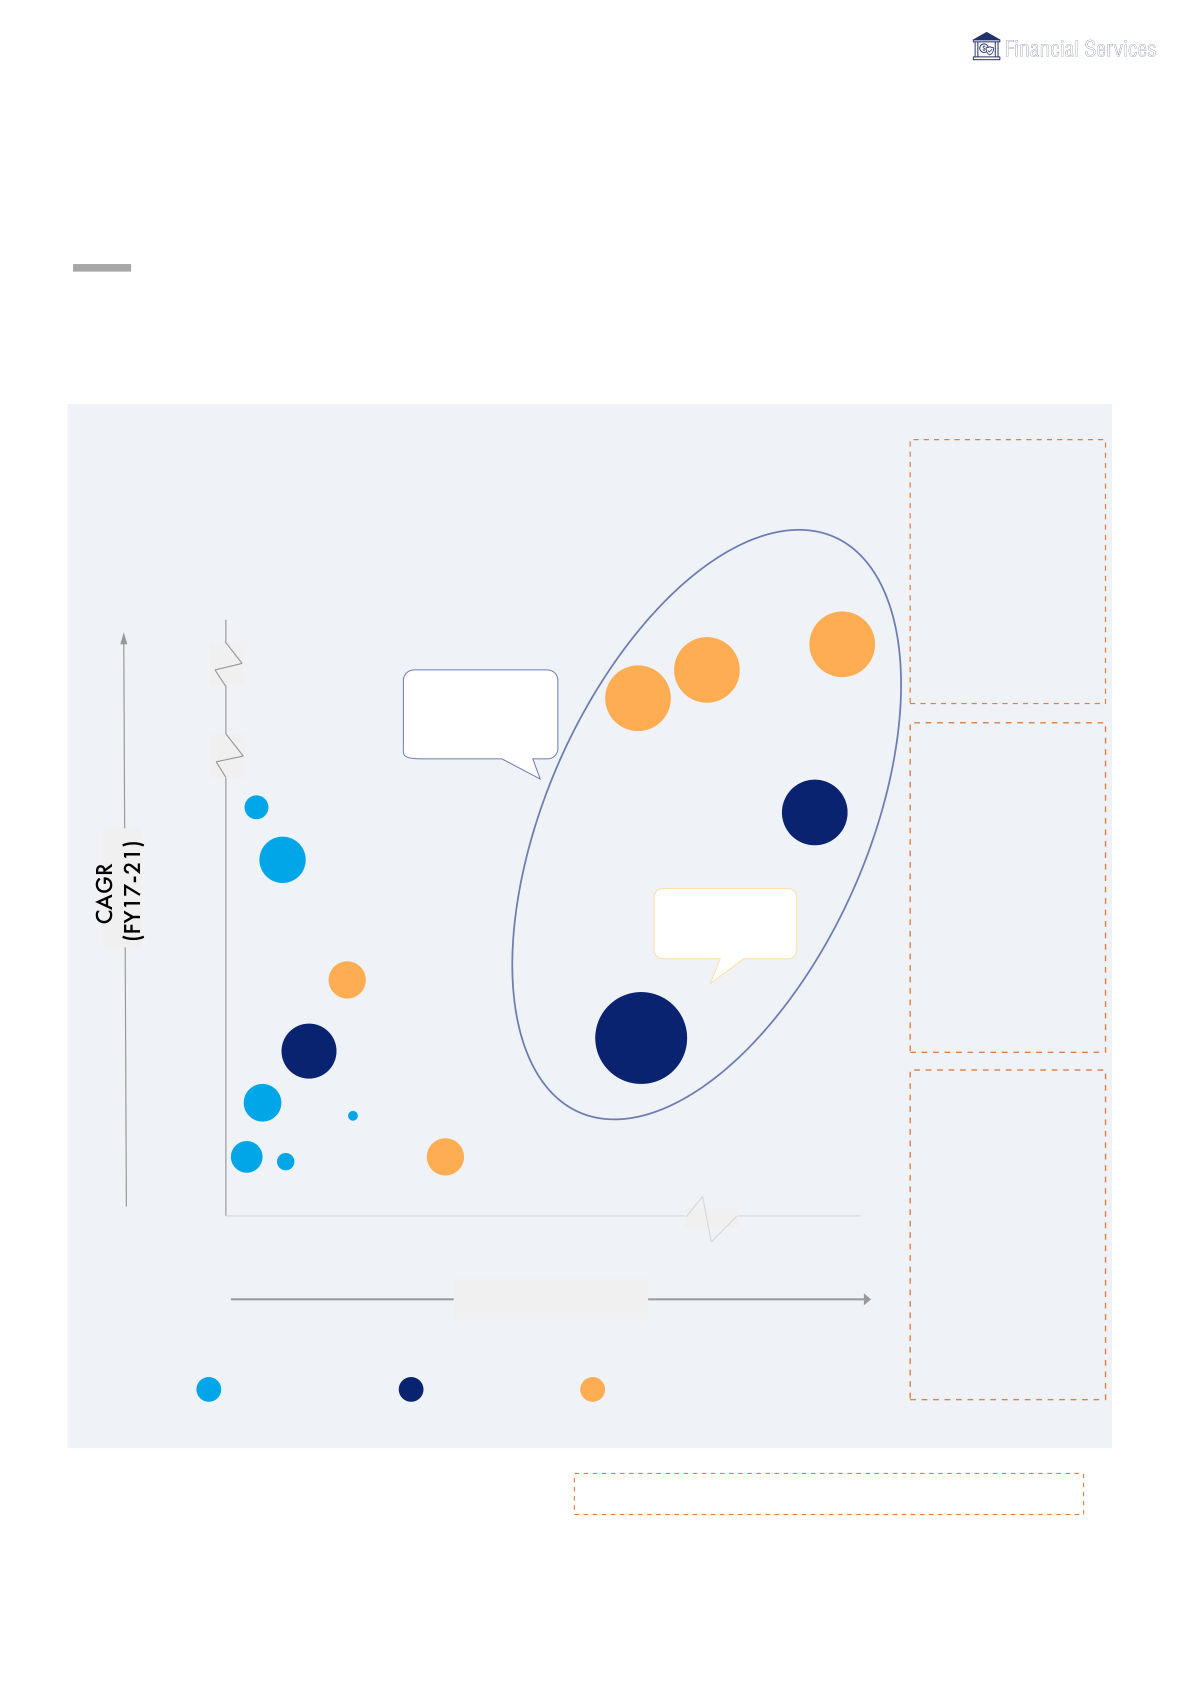
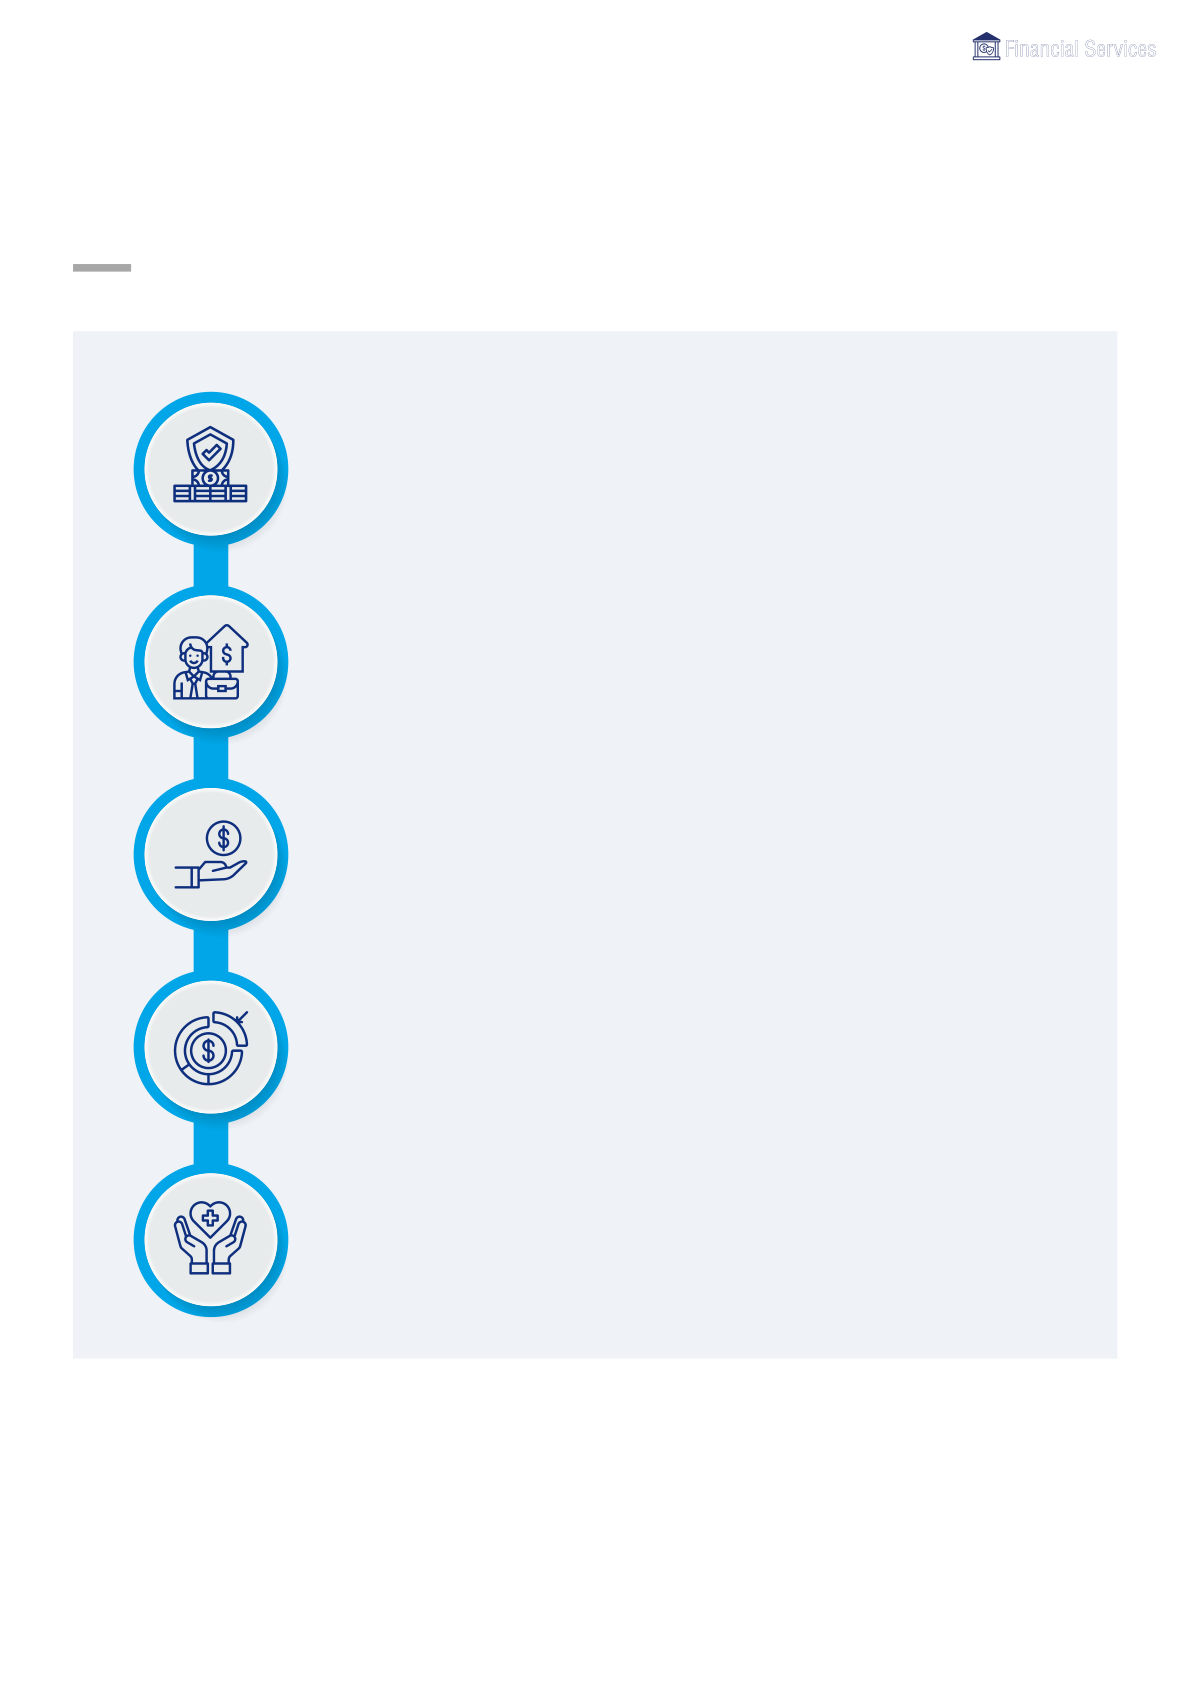
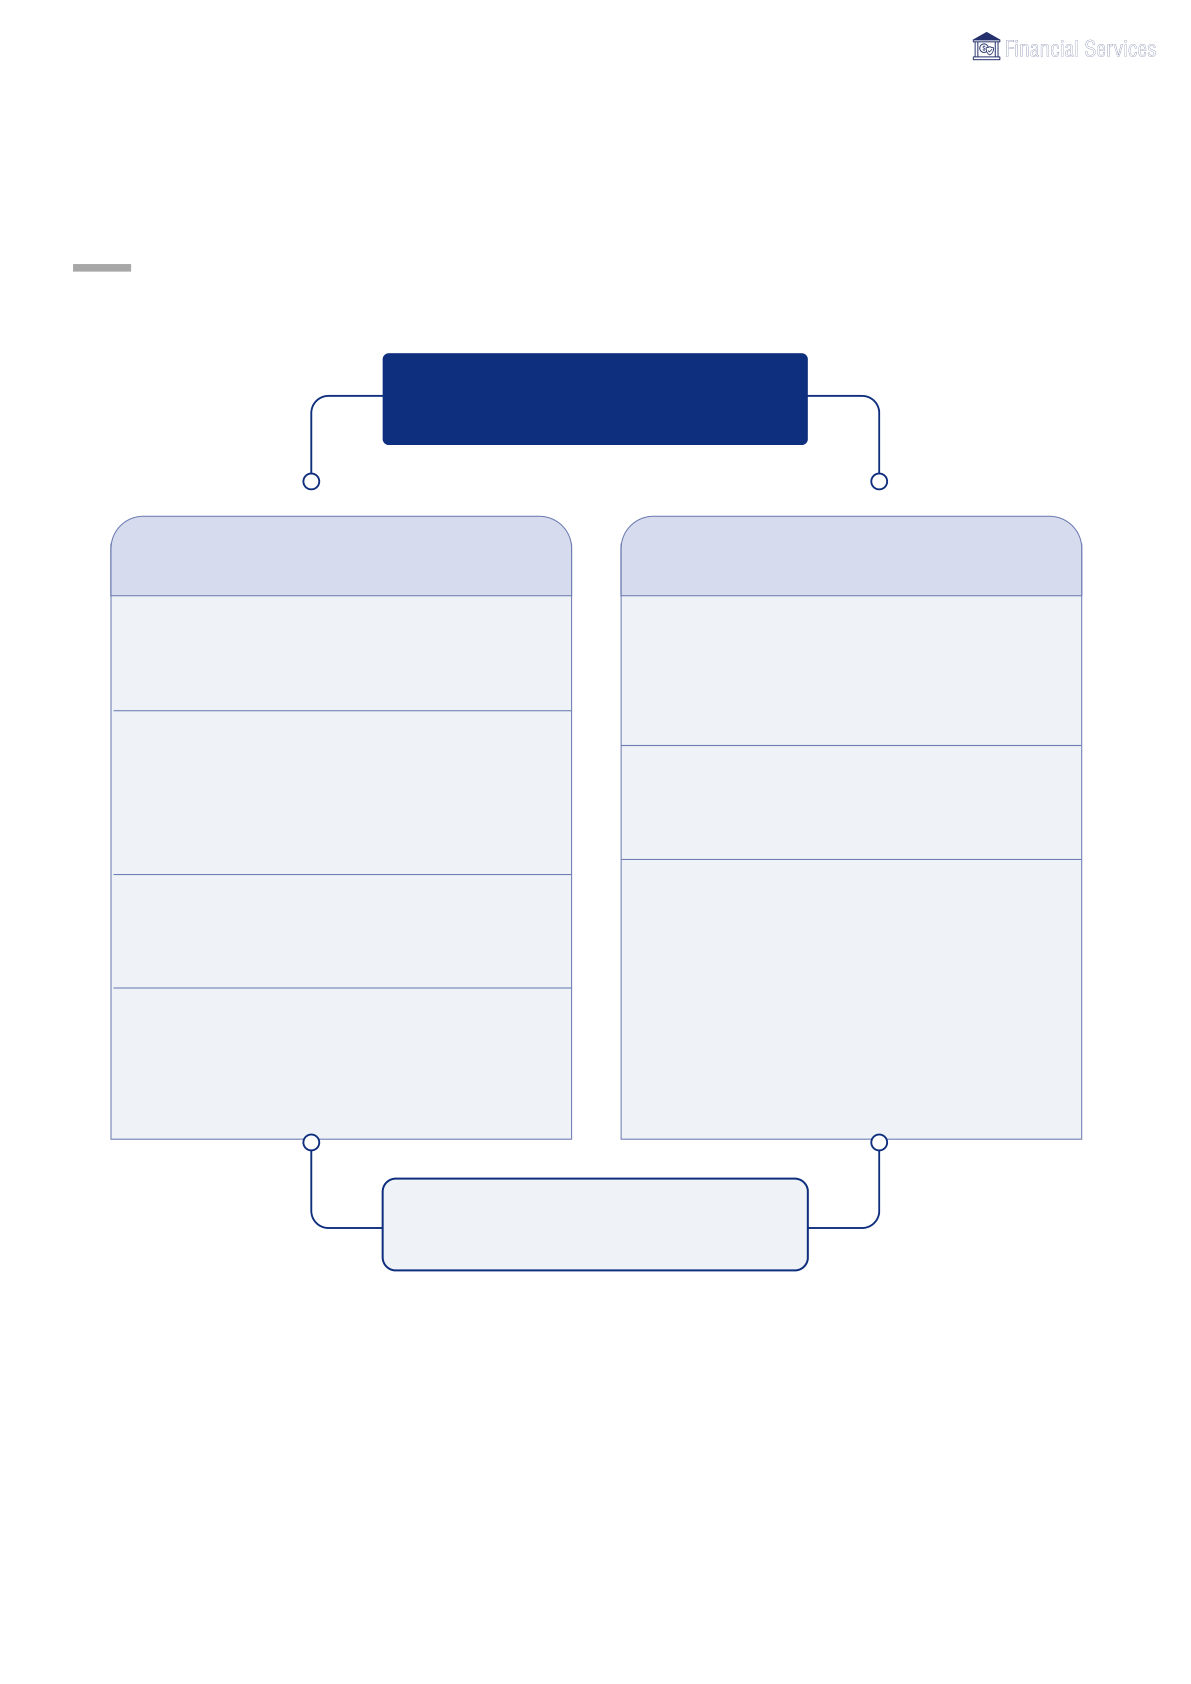
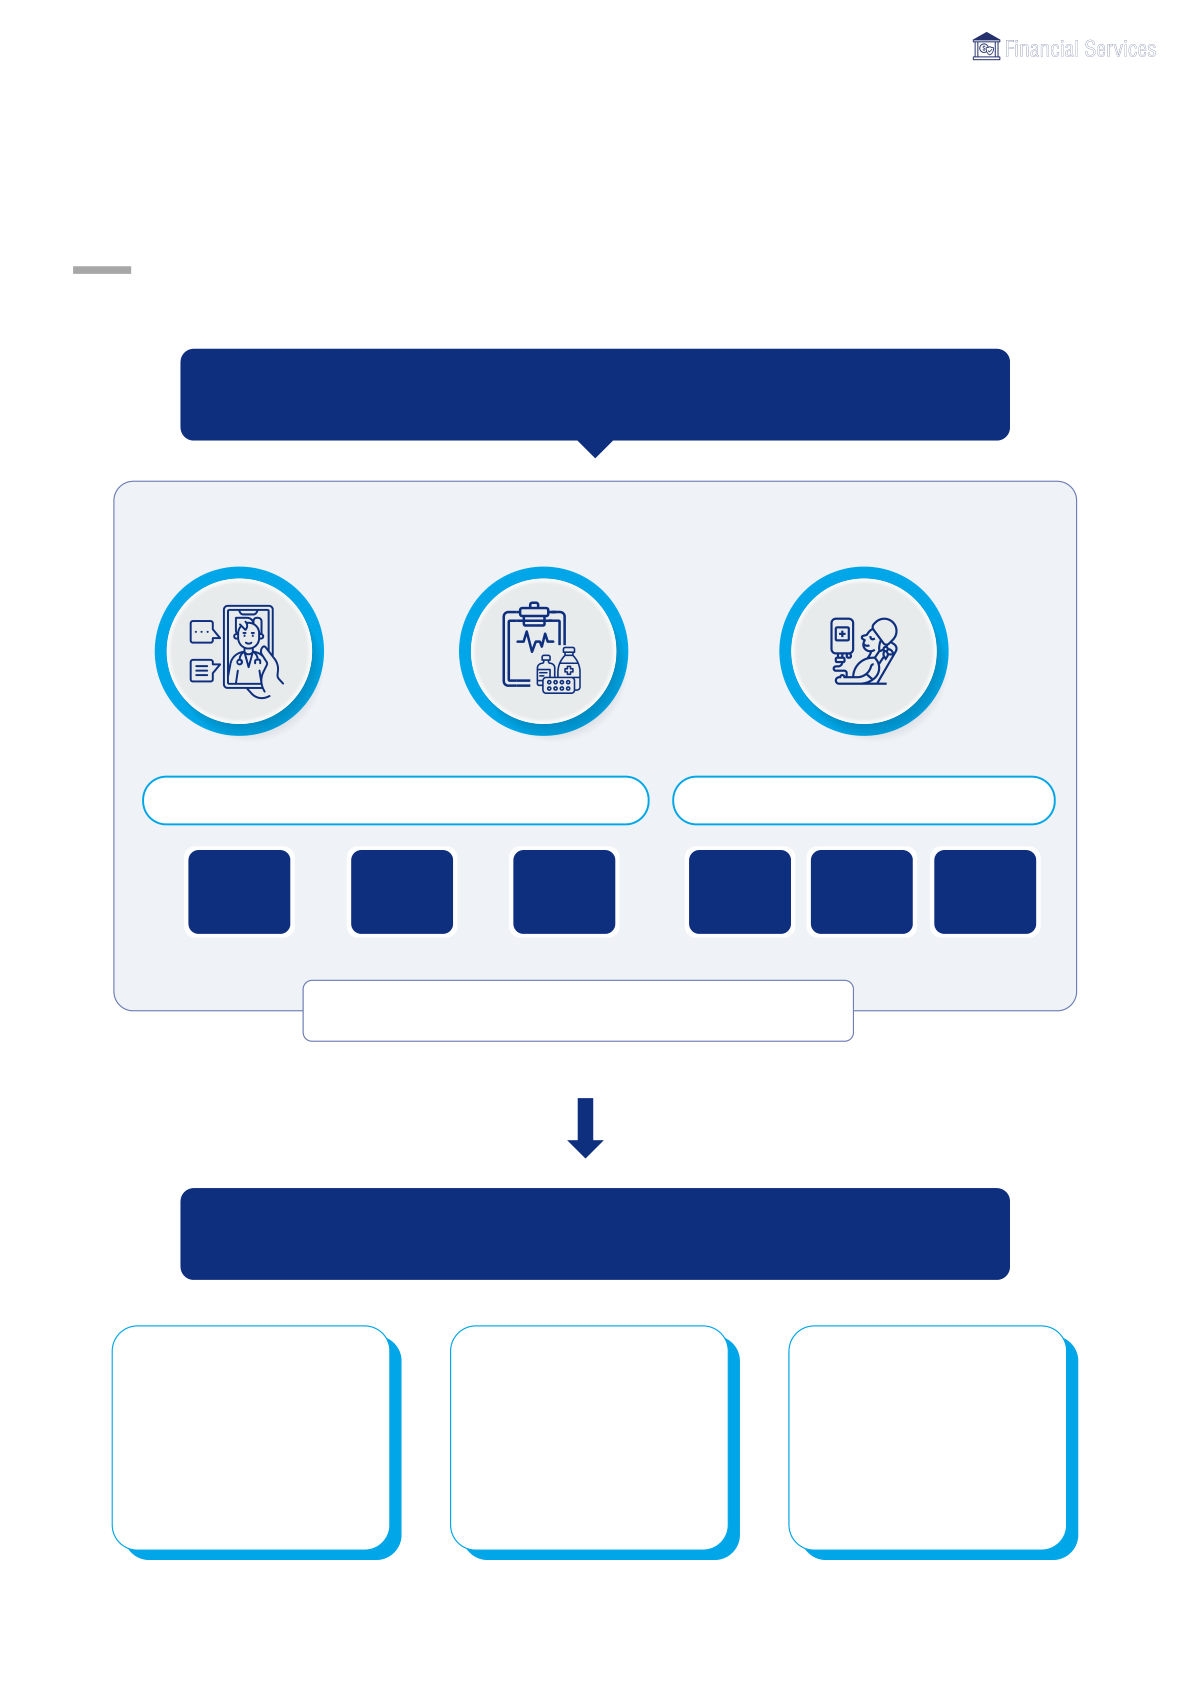
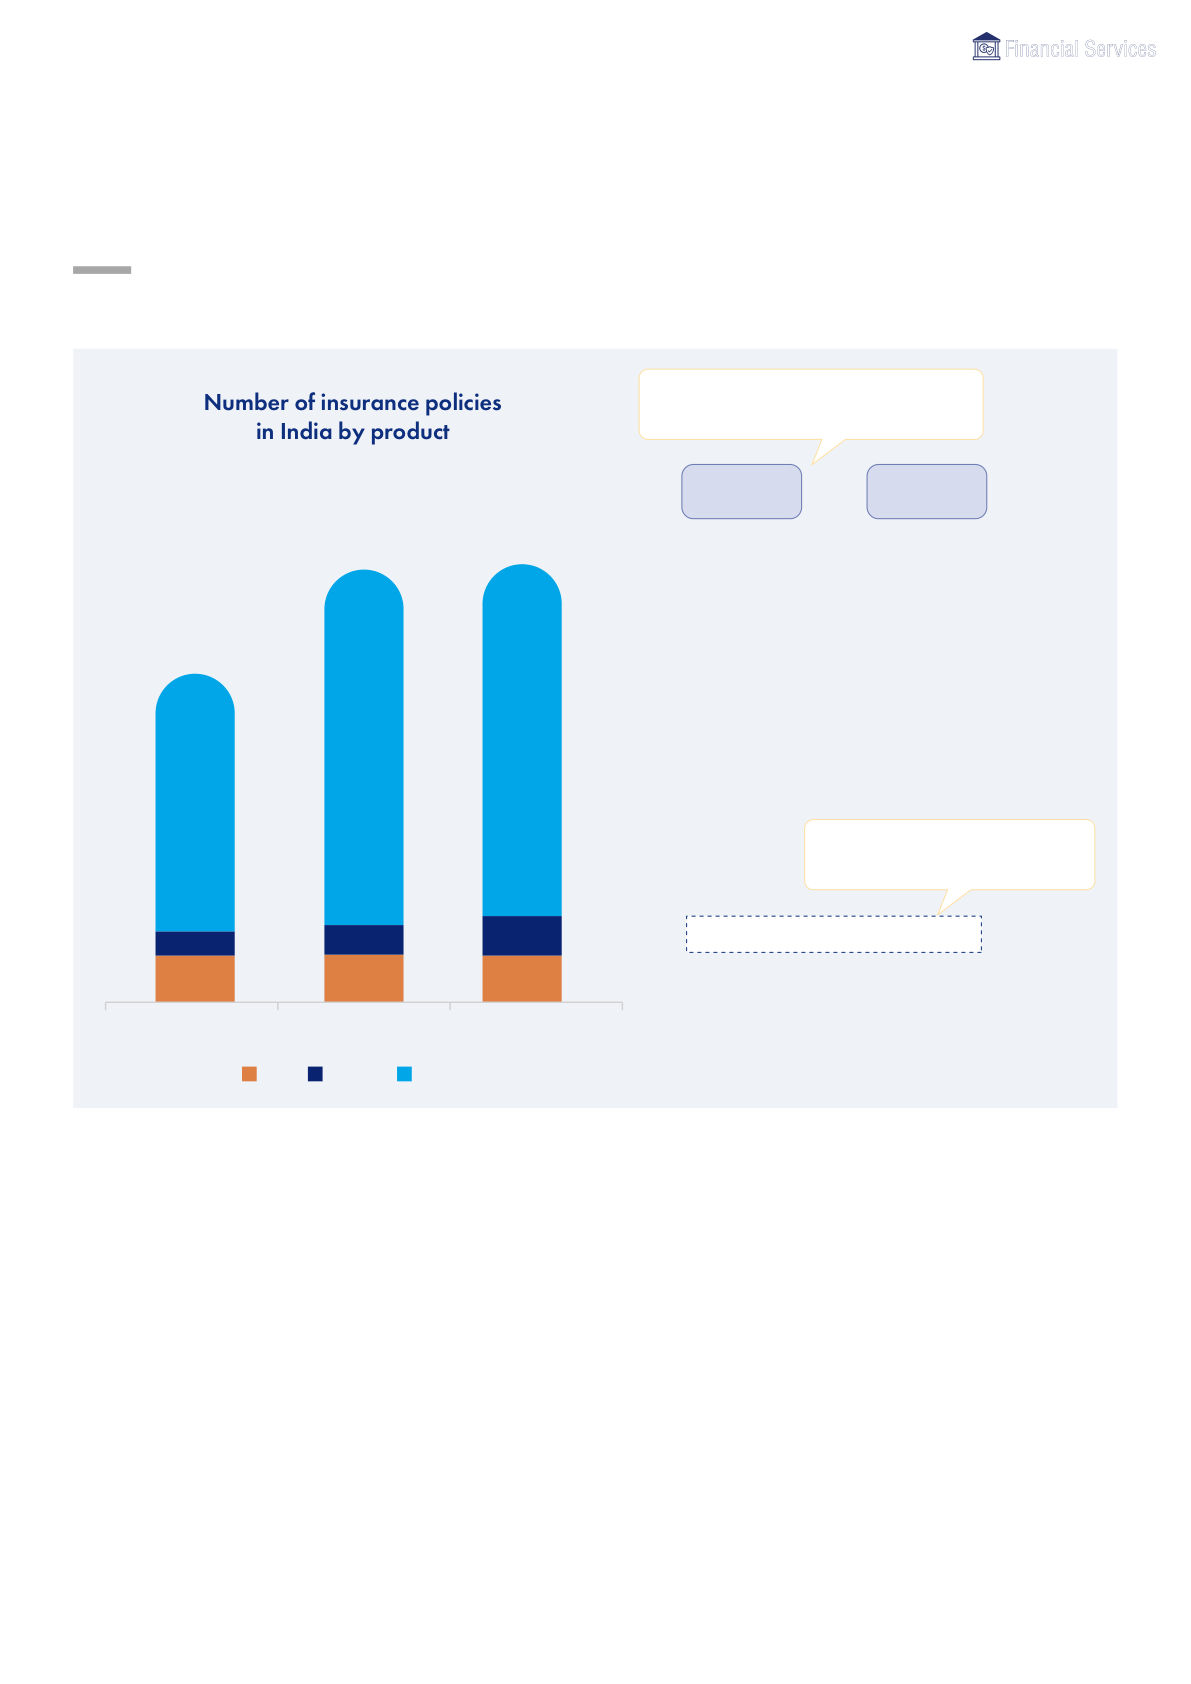
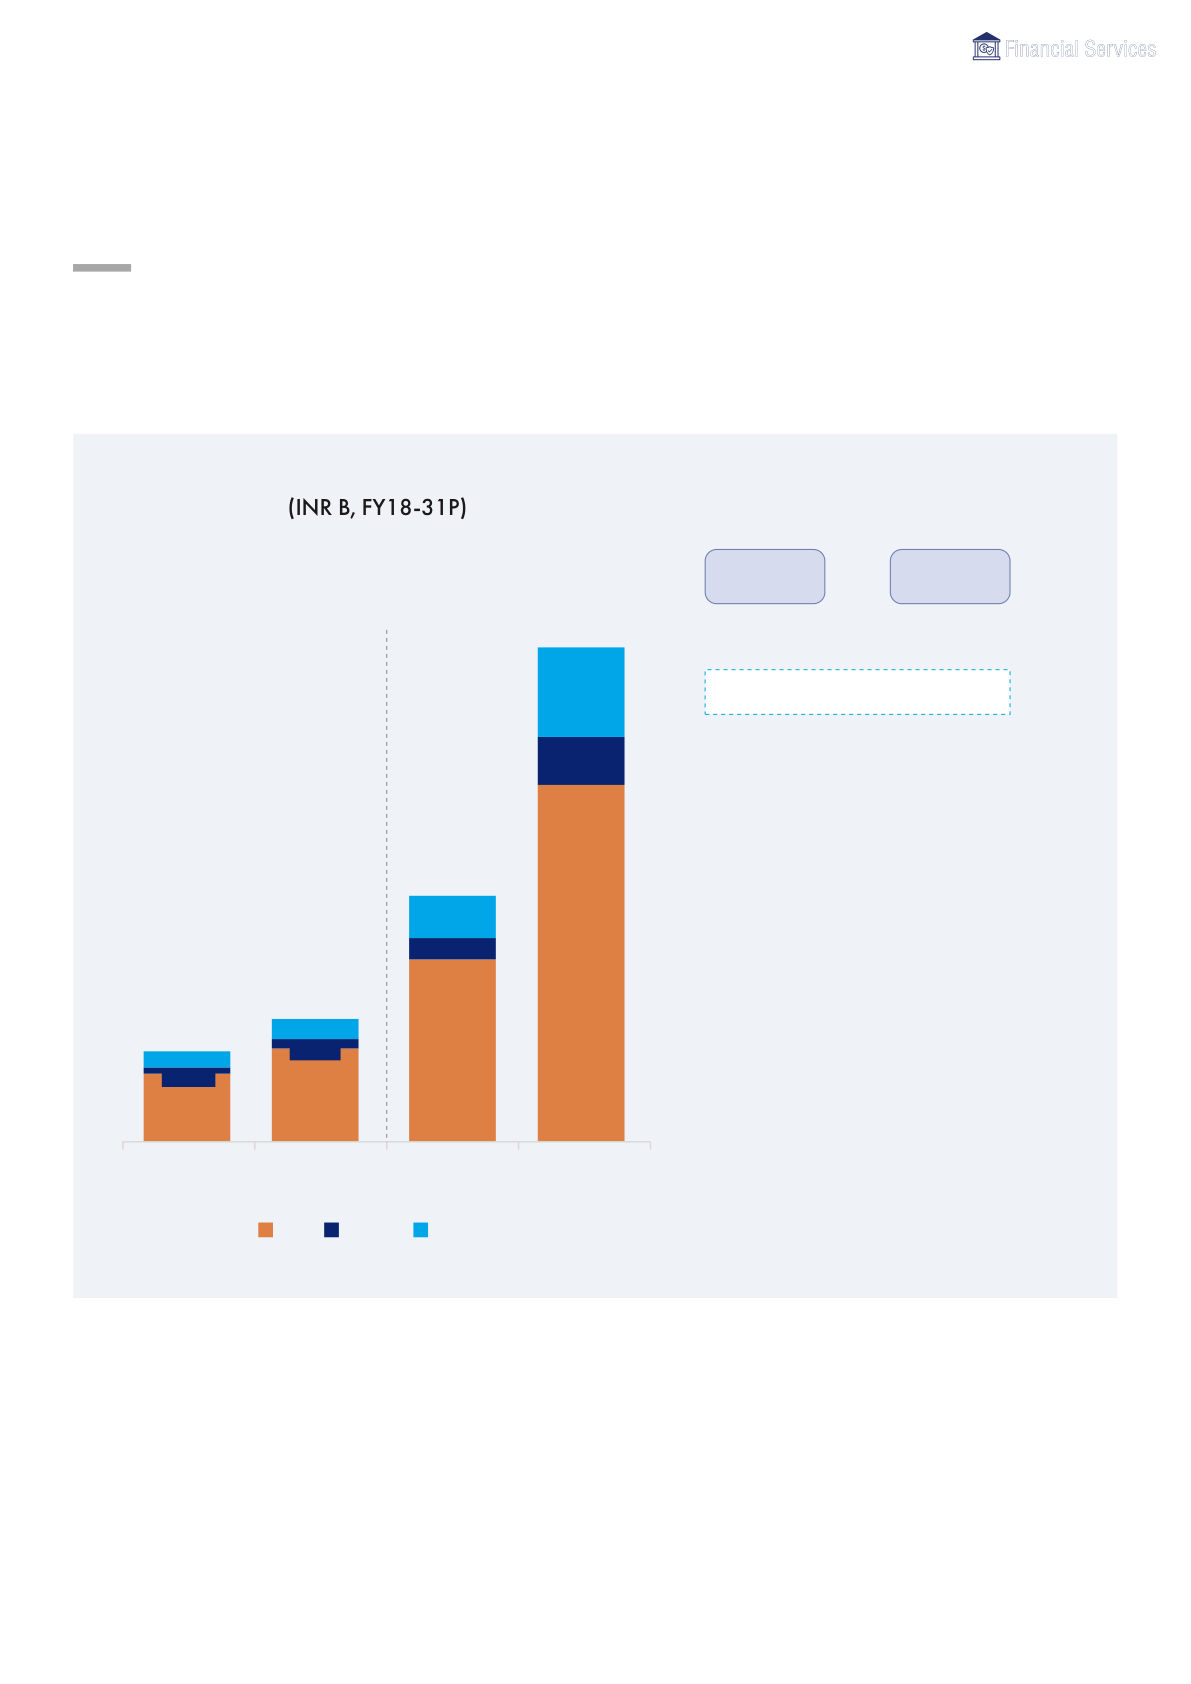
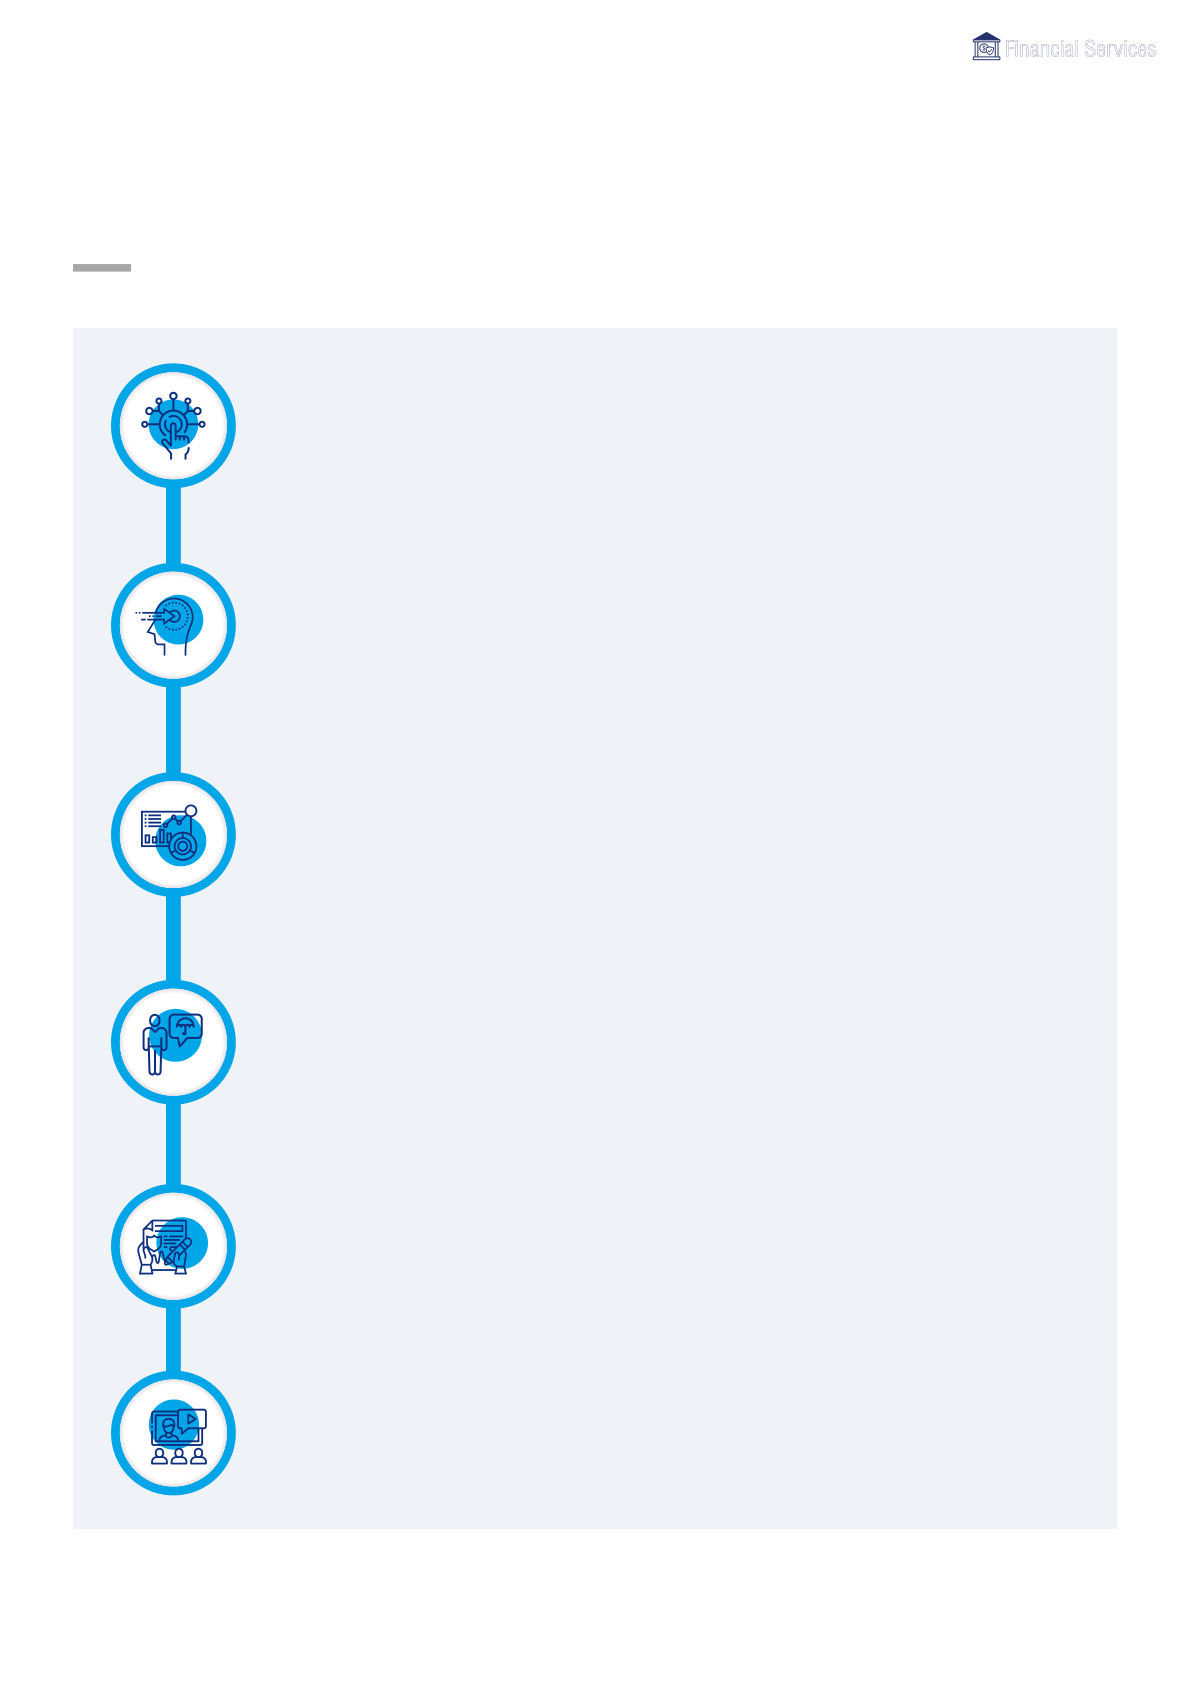
Financial Services INSURANCE AND INSURTECH LANDSCAPE November , 2022 Confidential and proprietary © PGA Labs Contents Foreword 03 Glossary 04 Executive summary 05-06 Insurance landscape 07-15 Insurance landscape 08-10 Current challenges 11-12 Scope of improvement 13 Insurance value chain 14-15 Insurtech landscape 16-21 Insurtech landscape 17-18 Funding 19 Insurtech business models 20-21 Way forward for insurance 22-28 Push by Government 23-25 Market outlook 26-27 Key action statements 28 Our team 29 Foreword Financial inclusion initiatives. Insurance value chain is also transitioning from a rigid to a modular & open structure with specialized players resulting in improved data flow, digital products & customer experience. Traditionally, Indian insurtechs have focused on sales & distribution, however new insurtechs are emerging across other parts of the value chain as well. There is growing traction in underwriting, claims tech, business analytics & administration platforms as the insurtech sector starts to mature. The challenges currently facing the insurance industry are tech, distribution, consumer perception & upskilling challenges. Indian government is already taking several initiatives to make the Insurance industry more conducive to growth and ease of doing business. Insurance companies would need to leverage technology within the organisation and customer interactions to unlock higher potential and efficiency. This report aims to provide various industry stakeholders, including business leaders, an overall perspective on the market. The report reflects our perspectives as of August 2022. The situation is evolving rapidly, and some expected scenarios may unfold differently. We look forward to hearing from you and exchanging notes on this exciting industry. Abhilasha Jaju Director Glossary Acronyms Description GDP Gross Domestic Product B2C Business-to-consumer B2B Business-to-business B2B2C Business-to-business-to-consumer CAGR Compound Annual Growth Rate ULIP Unit Linked Insurance Plan CX Customer Experience FDI Foreign Direct Investment JAM Jan Dhan – Aadhar – Mobile Trinity HIMS Hospital Information Management System LIMS Laboratory Information Management System Financial Services Executive summary Insurance landscape Insurance can broadly be categorized into life & non-life/ general insurance based on type of insurance product The penetration of insurance can be linked to wealth: higher the GDP per capita, higher the insurance penetration Challenges facing the industry • The insurance industry largely faces tech, distribution, consumer perception & upskilling challenges • Insurance industry has scope of improvement in the usage of tech, data across functionalities, and customer perception & experience Insurance value chain • The typical insurance value chain has six steps: product development, sales & distribution, underwriting, claims management, administration, business analytics • Insurance value chain is transitioning from a rigid to a modular & open structure with specialized players resulting in improved data flow, digital products & customer experience © PGA Labs | 05 Financial Services Insurtech landscape Current Insurtech landscape • Traditionally Indian insurtechs have focused on sales & distribution, however new insurtechs are emerging across other parts of the value chain. There is growing traction in underwriting, claims tech, business analytics & administration platforms as the insurtech sector starts to mature Strategic positioning • Funding raised by Indian insurtechs has grown at CAGR of 34% from 2017-21 with 2021 proving to be a watershed year • B2C business models & online-first insurers appear to be valued higher by investors due to higher operating leverage & perception of higher proximity to customers Way forward for insurance Market outlook (India) • The recently introduced National Health Stack will help bridge the gaps in health insurance by providing aggregated data from sources like doctors, medical facilities, drug registries, etc. • Total number of new insurance policies sold has increased from ~198M policies in FY18 to ~264M in FY21 at a CAGR of 10% • Total insurance market is ~INR 8T in FY21 and is projected to reach ~INR 33T by FY31 at a CAGR of 14.9% • Insurance companies would need to leverage technology within the organization and with customer interactions to unlock higher potential and efficiency © PGA Labs | 06 INSURANCE LANDSCAPE Insurance Life insurance General insurance Pure Insurance+ Health Crop Home/ Property insurance investment insurance insurance insurance Travel Vehicle insurance insurance Money back plan ULIP Wholelife Endowment plan Pension plan © PGA Labs | 08 Source(s): PGA Labs analysis Financial Services Insurance landscape The insurance market can be classified into four categories based on product-characteristics T1 T2 T3 T4 Low value, Medium risk High risk High value, low-med risk incidence on capital incidence, high risk, long incidence assets medium tenure tenure Types of Travel, Motor Home Health Life insurance Appliances Perceived materiality of Protects against calamities In urban centers In rural centers High impact on the value and and burglary which are due to high due to lower life and low probability events medical costs medical costs underlying risk well-being Need for customer Not specifically Due to a Govt. Due to high Rarely purchased for a Increasing popularity sought, but bought mandate for having risk & high self-owned house & because of rising at POS if reqd. 3rd party insurance impact almost never if rented medical expenses Probability of occurrence of underlying risk Frequency •Typically •Matches the policy •Home – •2 - 3 years •Once a short term term for 3rd party 10 years •Changed for lifetime of buying but not insurance better •Dominated bought •Four-wheeler – 3 product fit & by non-linked frequently years pricing life policies, •Two-wheeler – 5 pension years policies & ULIPs Typical •Travel – •3rd party •House – Cost •US$ 1,400- •US$ US$ two-wheeler – to rebuild the 14,000 200,000 maximum 50,000 US$ 1,428 house •Sum insured •Agent has sum assured •Mobiles – •3rd party (excludes increases significant US$ four-wheeler – land cost) with age influence on 40-220 US$ 10,714 buyers’ decision Very low Very high Impact on parameters Note(s): Non linked life insurance policies refer to insurance policies not linked to investment products © PGA Labs | 09 Source(s): Secondary research, PGA Labs analysis Financial Services Insurance landscape Insurance penetration is linked to wealth; In India it is set to increase due to financial inclusions and Govt. schemes Insurance penetration and GDP per capita (FY20) 18 High GDP per capita & high 16 In Africa, South Africa is one of the largest insurance penetration economies & has the most developed South Africa financial market, making it the largest hub 14 for Insurance and Insurtech companies on the continent. United Kingdom 12 Korea, Rep. Government schemes and financial Low GDP per inclusion initiatives will help drive adoption capita & low & penetration across all insurance segments France 10 in India. Increase in FDI in insurance from insurance 49% to 74% announced in the Union penetration Budget (Feb’21) shall further drive Italy 8 increased penetration. Germany Belgium Japan 6 India, FY30 Malaysia Slovenia India, FY20 Portugal Spain Chile Israel 4 Brazil Slovak Estonia El Salvador Panama Hungary Republic Mexico Czech Republic India, FY16 In the US, GDP per capita was Colombia Honduras US$ 63,080 in FY20, and Uruguay Finland Greece Bulgaria 2 Lithuania Costa Rica Indonesia insurance penetration was Bolivia 12.5% in FY20 Turkey Russian Federation 0 0 5000 10000 15000 20000 25000 30000 35000 40000 45000 50000 GDP per capita, current US$ (2020) © PGA Labs | 10 Sources(s): World Bank, OECD, IRDAI, Secondary research, PGA Labs analysis Financial Services Insurance landscape – Current challenges [1/2] The insurance industry largely faces tech, distribution, consumer perception and upskilling challenges Challenge Digitalization Data & Claims Perception Sales & Upskilling Overall analytics management management distribution & awareness Low penetration & density rates Lack of awareness Negative consumer experience & perception Evolving customer behavior & preferences Predominance of traditional products & distribution channels Error-Prone Manual Processes Slow rate of digitalization by incumbents Reactive management Tougher regulations Very low Very high Key Moderate Low Impact of challenge challenge challenge challenge © PGA Labs | 11 Source(s): Secondary research, PGA Labs analysis Financial Services Insurance landscape – Current challenges [2/2] The insurance industry largely faces tech, distribution, consumer perception and upskilling challenges Low penetration & density rates Error-Prone Manual Processes 01 06 Relatively few buyers & sellers in rural Lack of automation & high levels of manual areas, lead fixed costs to remain high, data entry tasks expose organizations to a further leading to lower penetration risk of error leading to high employee costs Slow rate of digitalization by incumbents Lack of awareness 02 07 Existing software and business infrastructure While COVID-19 led to awareness about health insurance, awareness of are used by traditional insurers in their value chain and can be expensive to replace, other types of insurance is growing at a snail's pace slowing down the adoption of digital technology Negative consumer experience & 03 Reactive management 08 perception Claims management and customer The industry is filled with perceptions engagement are still reactive with low focus of slow & unreliable agents who do on customer experience not have the policy takers’ best interests in mind Tougher regulations 09 Increasing competition and usage of data Evolving customer behavior & 04 drive regulators to focus on transparency and preferences consumer protection through legislations, Customers now expect instant access, policies, & compliance measures immediate responses, and demand rapid action Predominance of traditional products 05 and distribution channels Insurance products are still sold traditionally, making it tougher for advanced insurance plans to gain traction, especially in rural India. While online and point of sale channels are slowly gaining popularity, there is heavy reliance on traditional distribution channels © PGA Labs | 12 Source(s): Secondary research, PGA Labs analysis Financial Services Insurance landscape – Scope of improvement Insurance industry has scope of improvement in the usage of tech, data across functionalities, and customer perception & experience Present actions Key gaps •Introduction of tech inhouse or •Lack of tech deployment and through partnerships for integration across various parts omnichannel distribution and of the value chain leading to Digitalization for data management & inconsistencies in manual and analysis tech interventions •Usage of data primarily for •Relatively unexplored functions Data & growth in sales and customer where data can be optimally service leveraged for faster processes analytics and higher quality insights •Treated as a reactive part of the •Lack of automation & focus on value chain involving manual CX in the end-to-end Claims processing of a large set of management of claims leading management data, multiple touchpoints to slow claim resolving time & high resolving cost •Focus on selling maximum • Negative perceptions and Perception number of policies to those experiences created while management & who are aware or are part of policies are being sold, and awareness the sales funnel claims are being managed •Leveraging a mix of offline & •Offline distribution channel is Sales & online channel with a heavier becoming increasingly focus on a feet-on-street model expensive and cannot be alone distribution used to tap the rural market •Building employee soft skills •Employees lack technical through training and training creating gaps in Upskilling development digital interactions with consumers and usage of data © PGA Labs | 13 Source(s): PGA Labs analysis Financial Services Insurance landscape – Insurance value chain Insurance value chain is transitioning from a rigid to a modular and open structure resulting in improved data flow, digital products & CX Conventional insurance value chain The traditional insurance value chain is rigid with data contained within each part of the value chain Underwriting Administration Product & risk management Claims Sales & management Analytics management distribution New age insurance value chain There is a Underwriting & Product transition risk management management towards a modular ecosystem with an open Modular Sales & architecture ecosystem Administration distribution with partners This results in specialization, flow of data across the value Claims chain, products that are Analytics digital at their core, and management a better CX Note: CX stands for Customer experience © PGA Labs | 14 Source(s): Secondary research, PGA Labs analysis Financial Services Insurance landscape – Insurance value chain Indian insurance industry value chain comprises 6 elements and is addressing some of the existing challenges through Insurtech players Product Underwriting & Claims Sales & management risk management management distribution Direct sales Claims registration Product Quotation (online & offline) and validation development generation Individual Valuation Document Loss reserve agents based on risk submission creation Claims assessment Corporate agents – Risk management Underwriting and adjudication Banks and others Regulatory Subrogation & Reinsurance Brokers reporting litigation Others Fraud (Micro-insurance management agents etc.) Analytics Administration Policy Lifecycle Technological Data Management Pricing and Management network functioning and Modeling risk selection Customer Loyalty Dynamic document Automate Potential Markets management workflow Judgement identification Includes leading distribution platforms e.g. Turtlemint, Policybazaar etc © PGA Labs | 15 Source(s): PGA Labs analysis INSURTECH LANDSCAPE Financial Services Insurtech landscape [1/2] India insurtech landscape has seen an emergence of sever- al players across the value chain Insurance value chain focused companies Product Sales and Underwriting Claims Administration Analytics development distribution & risk management platforms management • Using • Strategically • Analyzing risk • Evaluating •Managing the •Conducting customer and penetrating profiles and and settling administrative analysis on market addressable premium claims, activities insurance insights to market to deliver pricing including required by related data design, products and models to payment, the insurer’s which drives develop and services bind and reinsurance in-force value-chain deploy issue policies recovery and populations decisions products and litigation services nsurance brokers © PGA Labs | 17 Source(s): Secondary research, PGA Labs analysis Financial Services Insurtech landscape [2/2] India insurtech landscape has seen an emergence of several players across the value chain Insurers & warranty providers Online first Embedded insurance & Life & General SAHI & Specialized insurers warranty providers Insurers insurers • Designing innovative • Online warranty - - policies and providers providing distributing on own warranty for specific platforms products along with other services distributed offline © PGA Labs | 18 Source(s): Secondary research, PGA Labs analysis Financial Services Insurtech landscape - Funding Funding for global and Indian insurtechs has grown rapidly, 2021 appears to be a watershed year Globally, funding to insurtechs has Funding to Indian insurtechs has grown at CAGR of 37% from FY17-20, grown at CAGR of 34% from FY17-20, 2021 proving to be a watershed year taking off in 2021 Indian Insurtech funding Global Insurtech funding US$ B US$ B 16.70 0.87 CAGR CAGR 34% 37% 0.51 0.43 8.13 0.38 6.95 0.32 5.37 0.27 4.78 4.72 2017 2018 2019 2020 2021 2022 2017 2018 2019 2020 2021 2022 • Share of late-stage funding (Series C+) globally, has increased to 70 percent in 2020 versus 40 percent in 2014. • Globally, 9 Insurtech unicorns have emerged in the past three years. Root, Wefox, Hippo, Next insurance, Lemonade, Waterdrop and Unqork are the global unicorns while Policybazaar and Digit insurance are India's entries into this exclusive club. • There are 142+ InsurTech startups operating in India as per Tracxn. Note(s): US$ 1 = INR 74 © PGA Labs | 19 Source(s): N=43 Indian insurtech companies, News reports, Tracxn, PGA Labs analysis Financial Services Insurtech landscape – Insurtech business models Most funding to Indian insurtechs has hitherto been for sales & distribu- tion players, however product development is starting to gain traction Funding Reasons for investment Emerging players US$ 31.56M • Higher traction due to dynamic market requirement CAGR: 237% • Innovative/ customized product demanded frequently (FY18-22) •These companies help insurers with proper data analysis, risk analysis and market needs US$ • Funding is majorly dominated by B2C player (Policy bazaar) 1,241.03M •Key factors driving the investment: CAGR: 75% Reduced hassle in the process, (FY16-22) Increased proximity to customers, Digitisation of business US$ 17.59M •Market at a nascent stage; huge opportunity for growth CAGR: 93% •Analytic models based on consumer behaviour and data (FY16-21) decide premiums: In Cariq, driving behaviour is decided by an app on his phone and charges the premium US$ 14.81M •Companies like Artivatic, i3 systems, & Sureclaim have CAGR: 50% received the funding (FY17-20) •Reduced TAT of claim settlement & increasing customer satisfaction: With tech based solutions based on AI, OCR tech & IOT US$ 10.40M •Symbo and Finsall resources have received major funding CAGR: 164% •Companies in this domain are trying to streamline the end to (FY16-21) end value chain of insurance: By using blockchain, API, IoT etc US$ •Major players: Digit insurance, Acko, Navi general, 1,100.65M Toffee etc. CAGR: 75% •Key factors driving investment: (FY16-21) Product customization based on individual needs, Expansion in customer base, Introducing bite-sized insurance Note(s): Funding data is taken from FY17-21 © PGA Labs | 20 Source(s) Traxcn, Press releases, PGA Labs analysis Financial Services Insurtech landscape – Insurtech business models B2C business models is valued higher by investors due to higher operating leverage and perception of higher proximity to customers Revenue, Growth rates and funding Funding • PolicyBazaar has highest funding followed by GoDigit and Acko • Turtlemint has the 1000% largest funding among B2B2C marketplaces B2C models appear GoDigit, 544 to be valued higher 500% than other insurtech Navi, 444 models Revenue Acko, 541 • B2B2C marketplace InsuranceDekho, 20 models exhibit 200% lower revenue than other business Turtlemint, 130 PolicyGenius, 288 models Policybazaar is • Established B2C 150% setting up a B2B2C (offline) business marketplaces revenue exceeds PolicyBazaar, 636 OnsiteGo, 30 the revenue of agents-based Insurify, 132 100% marketplaces Coverfox, 55 Growth rates 123seguro, 3 50% •GoDigit exhibited Renewbuy, 95 OneAssist, 53 the highest growth PolicyBoss, 10 rate followed by Navi and Acko 0% • Among B2B2C 0 20 40 60 80 200 marketplaces, InsuranceDekho Revenue (US$ M) has the highest CAGR, followed by Turtlemint B2B2C marketplace B2C marketplace Insurance companies Note: Size of the bubbles correspond to the funding (US$ M) Note(s): For Renewbuy, InsuranceDekho and GoDigit, CAGR is for FY19-20; For Navi CAGR is for FY19-21; For 123Seguro CAGR is taken © PGA Labs | 21 as 50% based on its growth per year Source(s): MCA, Company websites, Tracxn, Press release, Growjo, Zoominfo, PGA Labs analysis WAY FORWARD FOR INSURANCE Financial Services Way forward for Insurance – Push by Government Indian Government has taken several initiatives to make the Insurance industry more conducive to growth and ease of doing business Increase in FDI in insurance sector An increase in FDI in insurance from 49% to 74% announced in the Union Budget (Feb’21) shall benefit domestic insurers by increasing competition & improving product offerings Privatization of state-run general insurance company The General Insurance Business Amendment bill (Aug’21) allows the privatization of state-run insurance companies, increasing insurance penetration and efficiency across the value chain Capital infusion in the insurance sector The Finance Ministry of India plans to infuse capital of INR 3000-5000Cr in state-run general insurers to help improve the financial health of the general insurance firms Relaxation on minimum entry capital requirement The minimum capital requirement to set up an insurance firm is planning on being relaxed from INR 100Cr to INR 20Cr to widen the reach of insurers and help mini-insurers with niche product offerings Introduction of the National Health Stack The National Health Stack framework envisages centralized health data allowing health insurers to improve underwriting, fraud detection and claims processing © PGA Labs | 23 Source(s): Secondary research, PGA Labs analysis Financial Services Way forward for Insurance – Push by Government [1/2] The National Health Stack is helping to bridge the gaps in health insurance by aggregating data and optimizing insurance value chain JAM & India stack Plumbing layer Augmentation layer Extraction of data Enhances capabilities of all actors Electronic National Health Registry Protocol server Single source of health data from doctors, Defines communications protocol that medical facilities, drug registries, etc. structures requests between users and servers in a network Personal Health Records (PHR) Framework Perceptron/ Diagnostic bots Access to health data in the form of Algorithm for machine learning of input e-prescriptions & e-reports amongst data others for patients & research Matching engine Coverage and claims platform Matches user to required set of Support to health protection schemes via information, for e.g., patients to e-claims, Ayushman Bharat, etc. relevant doctors National Health Analytics Framework Includes digital health IDs, payment gateways, etc. that can be used across all health programs Digital public infrastructure Note: JAM stands for Jan Dhan – Aadhar – Mobile trinity © PGA Labs | 24 Source(s): iSpirit foundation, PGA Labs analysis Financial Services [2/2] Way forward for Insurance – Push by Government The National Health Stack is helping to bridge the gaps in health insurance by aggregating data and optimizing insurance value chain Government & private apps/platforms Tele-consultation Preventive care Treatment care Consumer apps/ portals Health provider apps/ portals Public Private Other Other sector HIMS LIMS sector apps platforms apps apps Private innovation Benefits Provides data to price Reduces Accelerates the the risk and increase touchpoints in the penetration of health coverage of health claims management insurance (especially insurance while process in low- & lowering cost of middle-income acquisition segments) Note: JAM stands for Jan Dhan – Aadhar – Mobile trinity © PGA Labs | 25 Source(s): iSpirit foundation, PGA Labs analysis Financial Services Way forward for Insurance – Market outlook Number of new insurance policies sold increased from ~198M policies in FY18 to ~264M in FY21 at 10% CAGR CAGR for FY18-20 & FY18-21 has been calculated separately to show the impact of COVID-19 on the growth/ de-growth of no. of polices (M, FY18-21) CAGR CAGR FY18-20 FY18-21 264 14.7% 10% 261 198 17.4% 11% 214 212 156 Growth in no. of policies during COVID-19 was seen in health, while de-growth was seen in the rest of the categories 10.3% 17.2% 18 24 15 29 28 28 1.1% -0.1% FY18 FY20 FY21 Life Health Others Note(s): # insurance policies doesn’t include group policies; Others include categories such as vehicle, home, crop, fire, property, travel etc. © PGA Labs | 26 Source(s): IRDAI, GIC, Secondary research, PGA Labs analysis Financial Services Way forward for Insurance – Market outlook Total insurance market is ~INR 8T in FY21 and is projected to reach ~INR 33T by FY31 at 14.9% CAGR Health grew at 7.5% during FY18-21 and it is expected to grow at 16.1% during FY21-31P Insurance market in India by product CAGR CAGR FY18-21 FY21-31P 33,303 10.7% 14.9% 6,031 7.5% 16.1% 14.9% 17.7% 3,242 16,600 2,853 1,438 24,030 11.1% 14.3% 8,274 6,095 1,350 638 12,292 1,087 420 6,287 4,588 FY18 FY21 FY26P FY31P Life Health Others • Growth in other insurance policies is driven by increasing penetration of crop, fire & property insurance in India. • In FY21, ~67% of the lives were covered under government sponsored health insurance schemes, ~23% of the lives were covered under group business and the remaining ~10% of the lives were covered under individual policies issued by general & health insurers. Note: Retail insurance market includes retail life, retail health, motor insurance and other general insurance products, © PGA Labs | 27 Others include categories such as vehicle, home, crop, fire, property, travel etc. Source(s): IRDAI, GIC, Secondary research, PGA Labs analysis Financial Services Way forward for Insurance – Key action statements Way forward: Need to leverage technology within the organization and customer interactions to unlock higher potential Digitalize the value chain Digitalization should be made a target to achieve across the value chain, with an order of priority - to reduce cost, improve efficiencies & support further ecosystem developments For e.g., core modules can be appropriately integrated to further integrate APIs (like customer engagement) Realign with customer preferences Players would need to be aligned with dynamic changes in customer behavior & preferences and manage perceptions by showcasing fiduciary responsibility For e.g., Offering quick personalized products can be prioritized over mass-product offerings to give customer more flexibility Use data & analytics across functions Data & analytics usage would need to be optimized across functions for maximum efficiency (for e.g., underwriting & claims) For e.g., underwriting can be done with more data points to design more flexible and personal products Reimagine distribution Distribution would need to be reimagined to include technology & focus on high potential markets. For e.g., hybrid distribution models with humans and technology can be adopted to focus on rural markets Design proactive & assisted claims processes The claims management process would need to be simplified for the insurer and insuree For e.g., strategic partnerships can be considered to manage scale and gain access to a further set of partners Leverage technology in upskilling Technology would need to be leveraged to create and maintain higher employee efficiency For e.g., An upskilling program can be established that develops a mix of soft, technical and digital skills © PGA Labs | 28 Source(s): Secondary research, PGA Labs analysis Our team Abhilasha Jaju Arindam Gupta Ashish Dhir Financial Services Healthcare & Lifesciences Consumer & Retail 6.5+ yrs. of experience 25+ yrs. of experience 25 yrs. of experience BITS Pilani, IIM Lucknow Faculty of Management Masters of Business Administration Studies, New Delhi from Lancaster University Management School, United Kingdom Abhishek Maiti Roma Dixit Vamsi Krishna Industrial Good & Services, Financial Investor Group, Technology & Internet Technology & Internet Consumer & Retail 14+ yrs. of experience 16+ yrs. of experience 14+ yrs. of experience ICFAI Business School IIT Delhi, IIM Indore ICFAI Business School, Hyderabad Praneet Singhal Anil Razdan Vaibhav Tamrakar Technology & Internet Consumer & Retail Fintech, Ed Tech & Food Tech 13+ yrs. of experience 10+ yrs. of experience 9+ yrs. of experience NMIMS, Mumbai MBA from University of Mumbai IIT Bombay Tarak Pandey Harsh Salgaonkar Kiran Achanta Financial Services Financial Services Technology & Internet 6+ yrs. of experience 6+ yrs. of experience 5+ yrs. of experience SRM University, Chennai Mumbai University VIT University, IMT Ghaziabad Parul Garg Prasun Dey Aastha Singh Consumer Technology & Internet Financial Investor Group, Consumer & Retail 5+ yrs. of experience 5+ yrs. of experience NIT Kurukshetra, IIT Bombay, IIM Kozhikode 1.5+ yrs. of experience University of Delhi LSR, Delhi Connect with us We will be happy to share perspectives Abhilasha Jaju Harsh Salgaonkar Director Business Development Manager PGA Labs PGA Labs For media queries, please contact Vaishnav Kumar Rai Manager - Marketing E: communications@pgalabs.in M: +91 78279 44925 www.pgalabs.in New Delhi | Gurugram | Mumbai | Bengaluru Disclaimer: This material has been prepared by PGA Labs, which is the trade name of Praxian Global Private Limited (“PGA”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the viewers on the internet but should be referenced to PGA Labs, if reused or adapted in any form or in any forum. The frameworks, approaches, tools, analysis and opinions are solely PGA’s intellectual property and are a combination of collection of best data we could find publicly, and PGA Labs team’s own experiences and observations. We make no representation or warranty, express or implied, that such information is accurate or complete, and nothing contained in here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing Recipient, its business and the markets within which it operates, nor all possible market conditions. No responsibility or liability whatsoever is accepted by any person including PGA or its Business partners and affiliates and their respective officers, employees or agents for any errors or omissions in this document. Any and all logos of companies used in the post have been published for information purposes only and PGA Labs does not hold any and all liability in connection therewith. This document is not complete without an accompanying oral discussion and presentation by PGA though PGA is not obligated to do so. PGA does not have any duty to update or supplement any information in this document. PGA shall not be responsible for any loss sustained by any person who relies on this presentation. PGA Labs We enable better decision making. 500+ 30% annual engagements faster to outcomes 50 600+ verticals years domain expertise 130+ 98%+ team members accuracy 100+ 2.5M+ towns & cities panel members 15+ 40:60 languages covered she-he ratio Deep business research and intelligence that helps in driving SMARTER DECISIONS Deep on-ground insights that you can act on 4 offices, deep experience across geographies – India, US, Europe, MEA, and SEA region Advanced technology tools and innovative data gathering approach Multifaceted teams with a unique mixture of qualitative, quantitative, and digital research experts The team at PGA Labs appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, CP-003, 004, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District GF Tower 4B, DLF Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 Corporate Park, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram -122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Praxian Global Pvt. Ltd., Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025