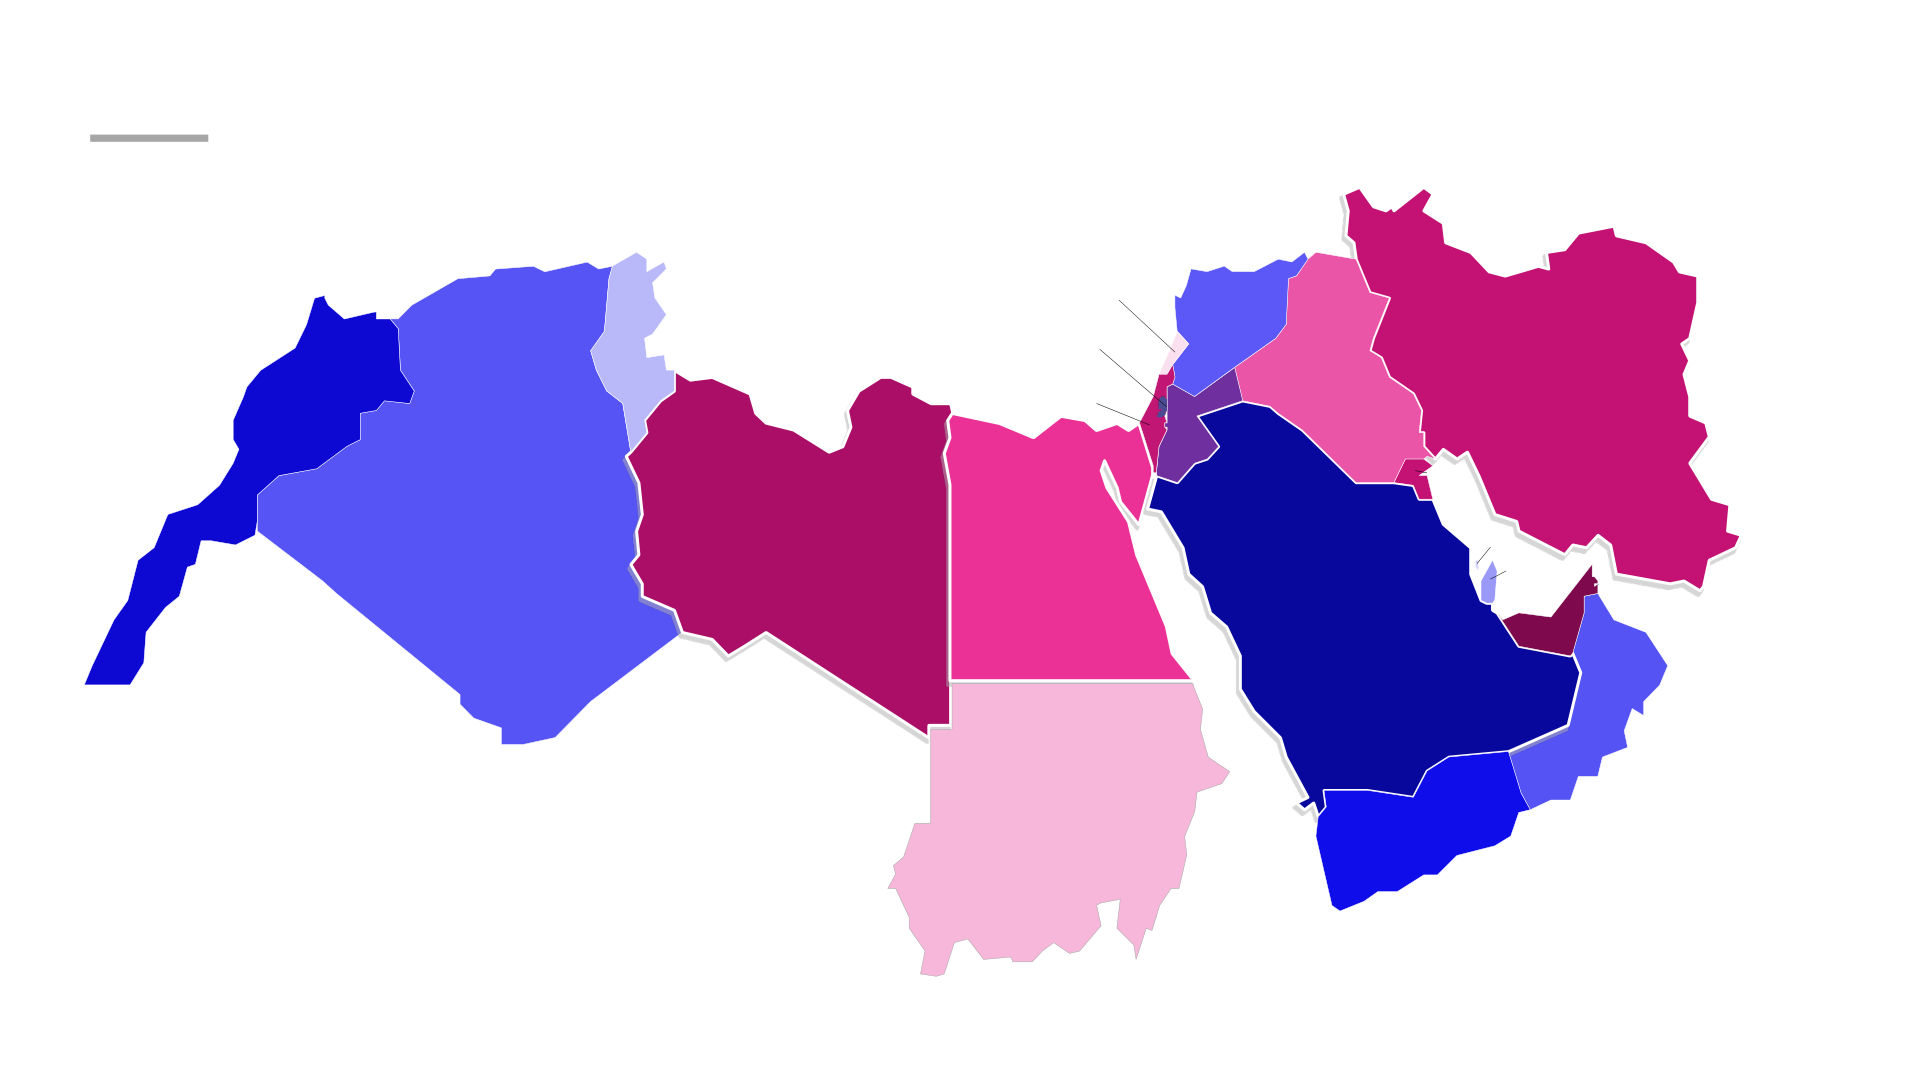
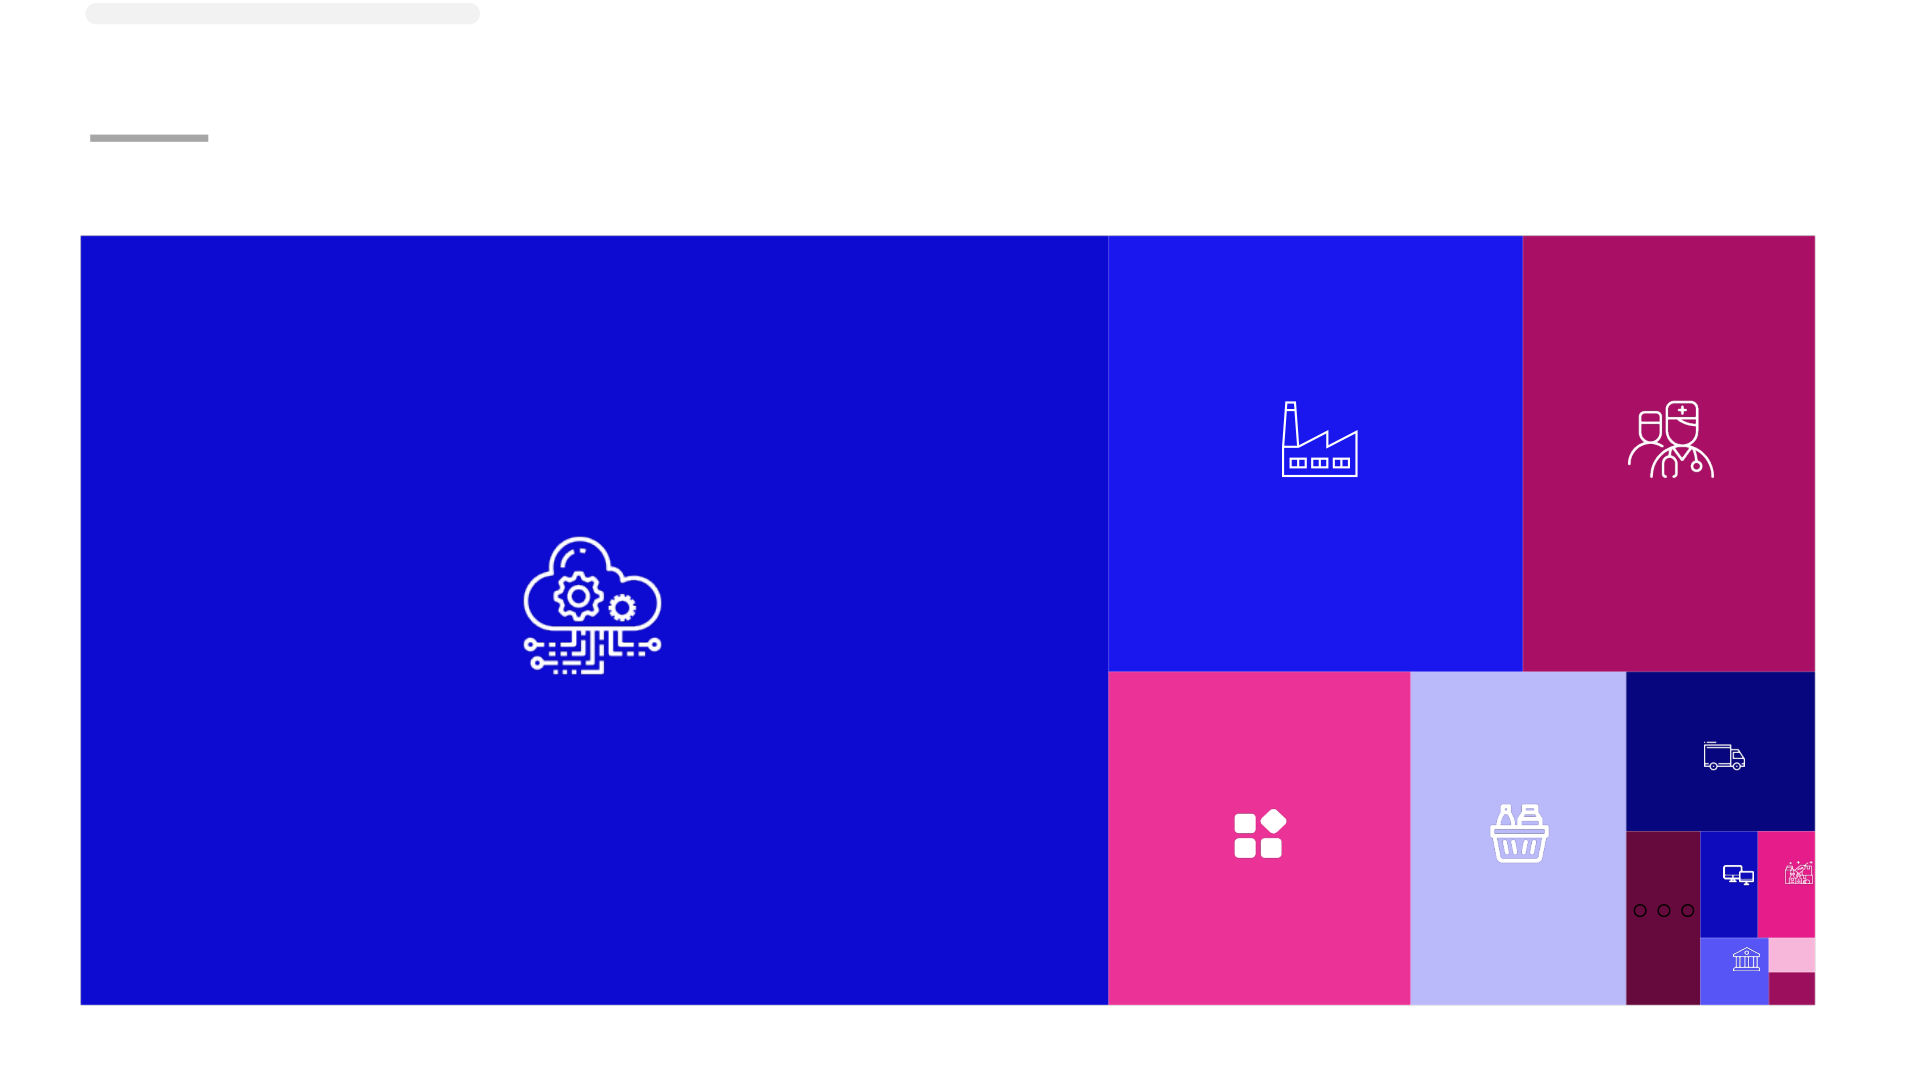
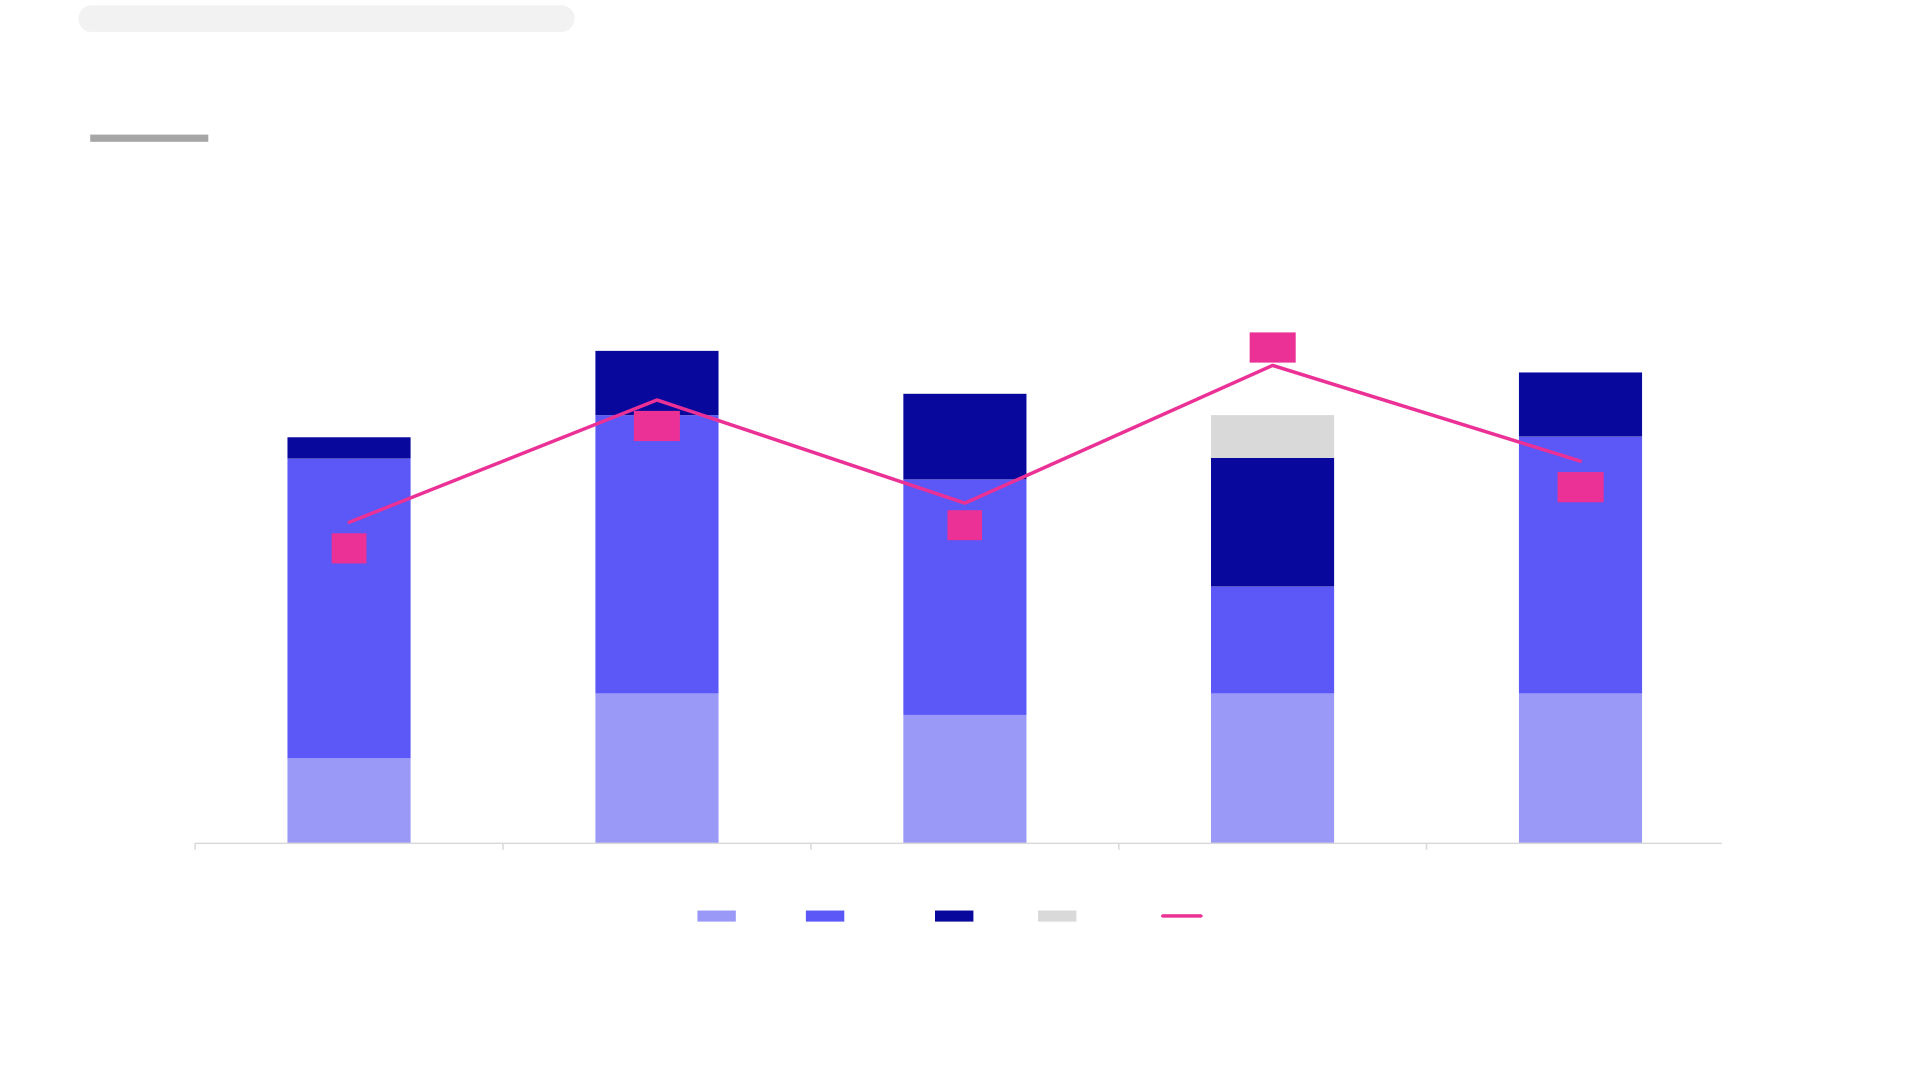
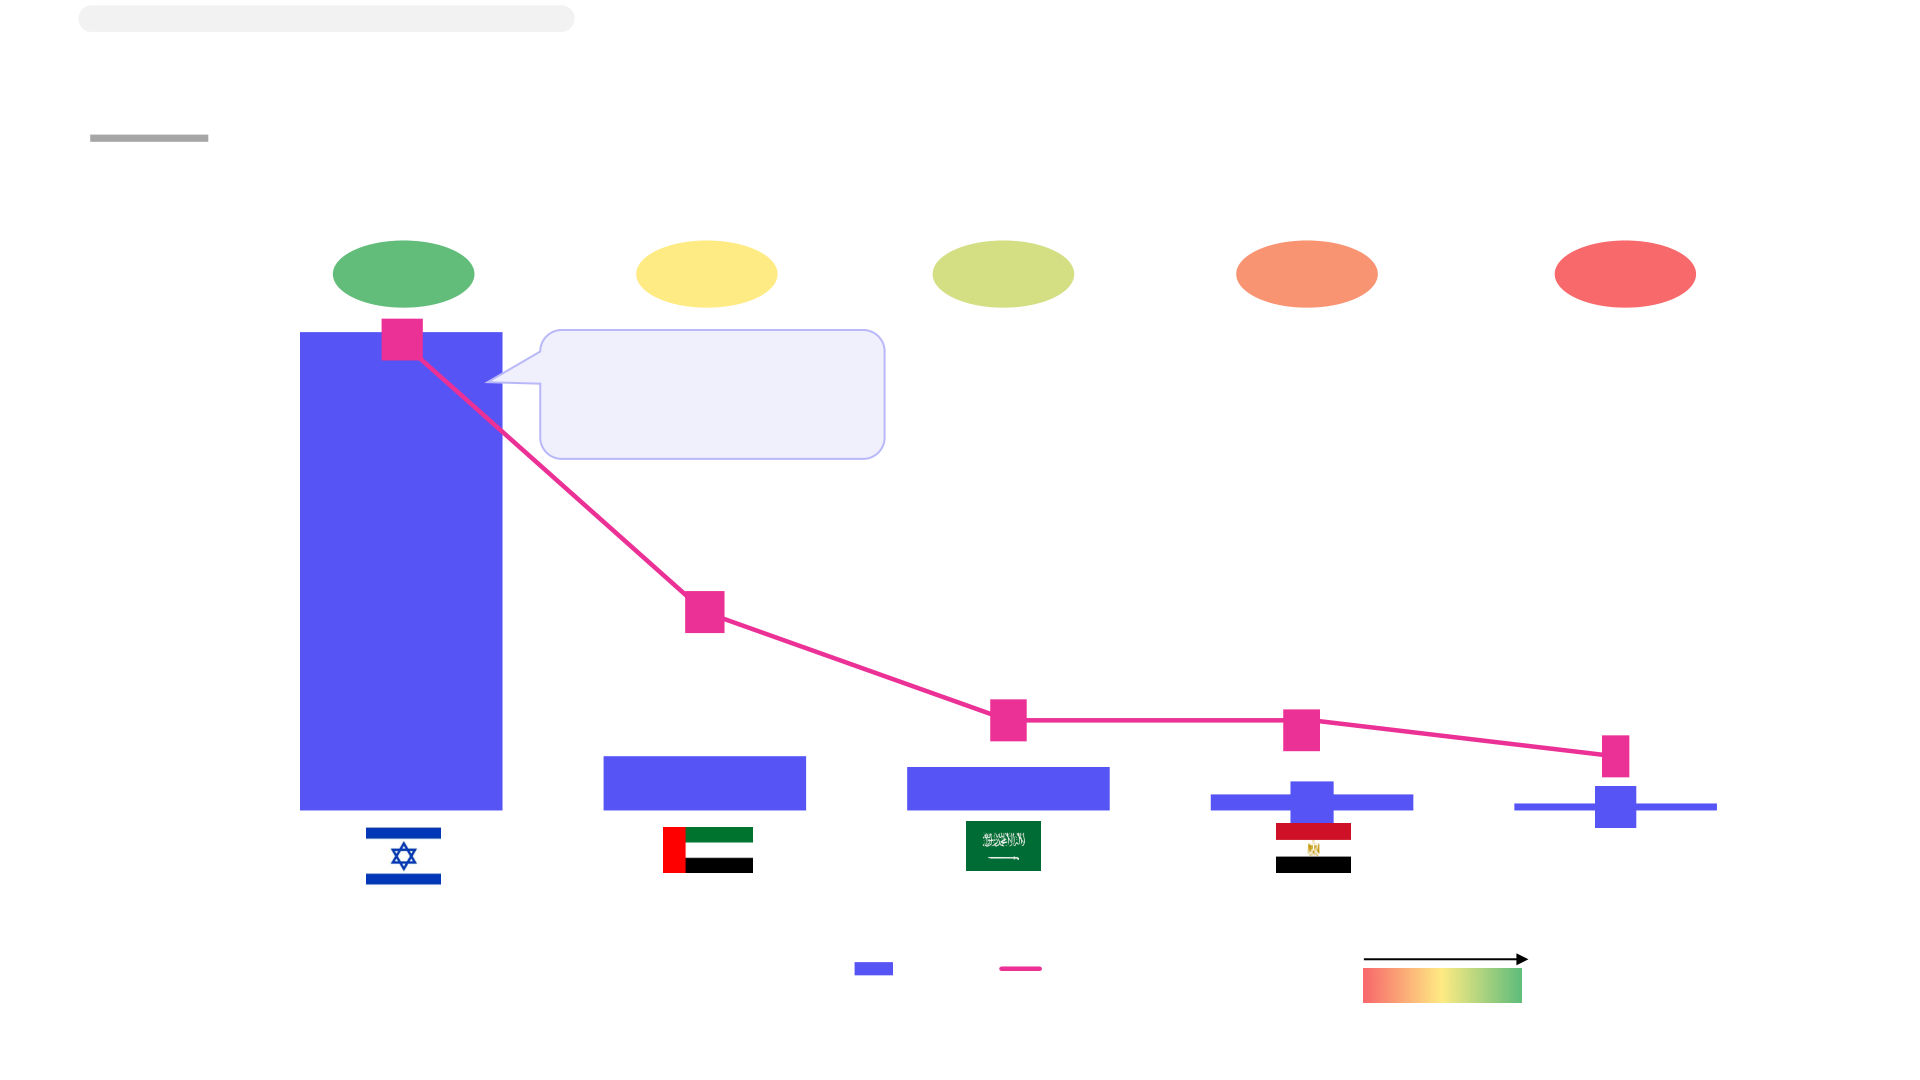
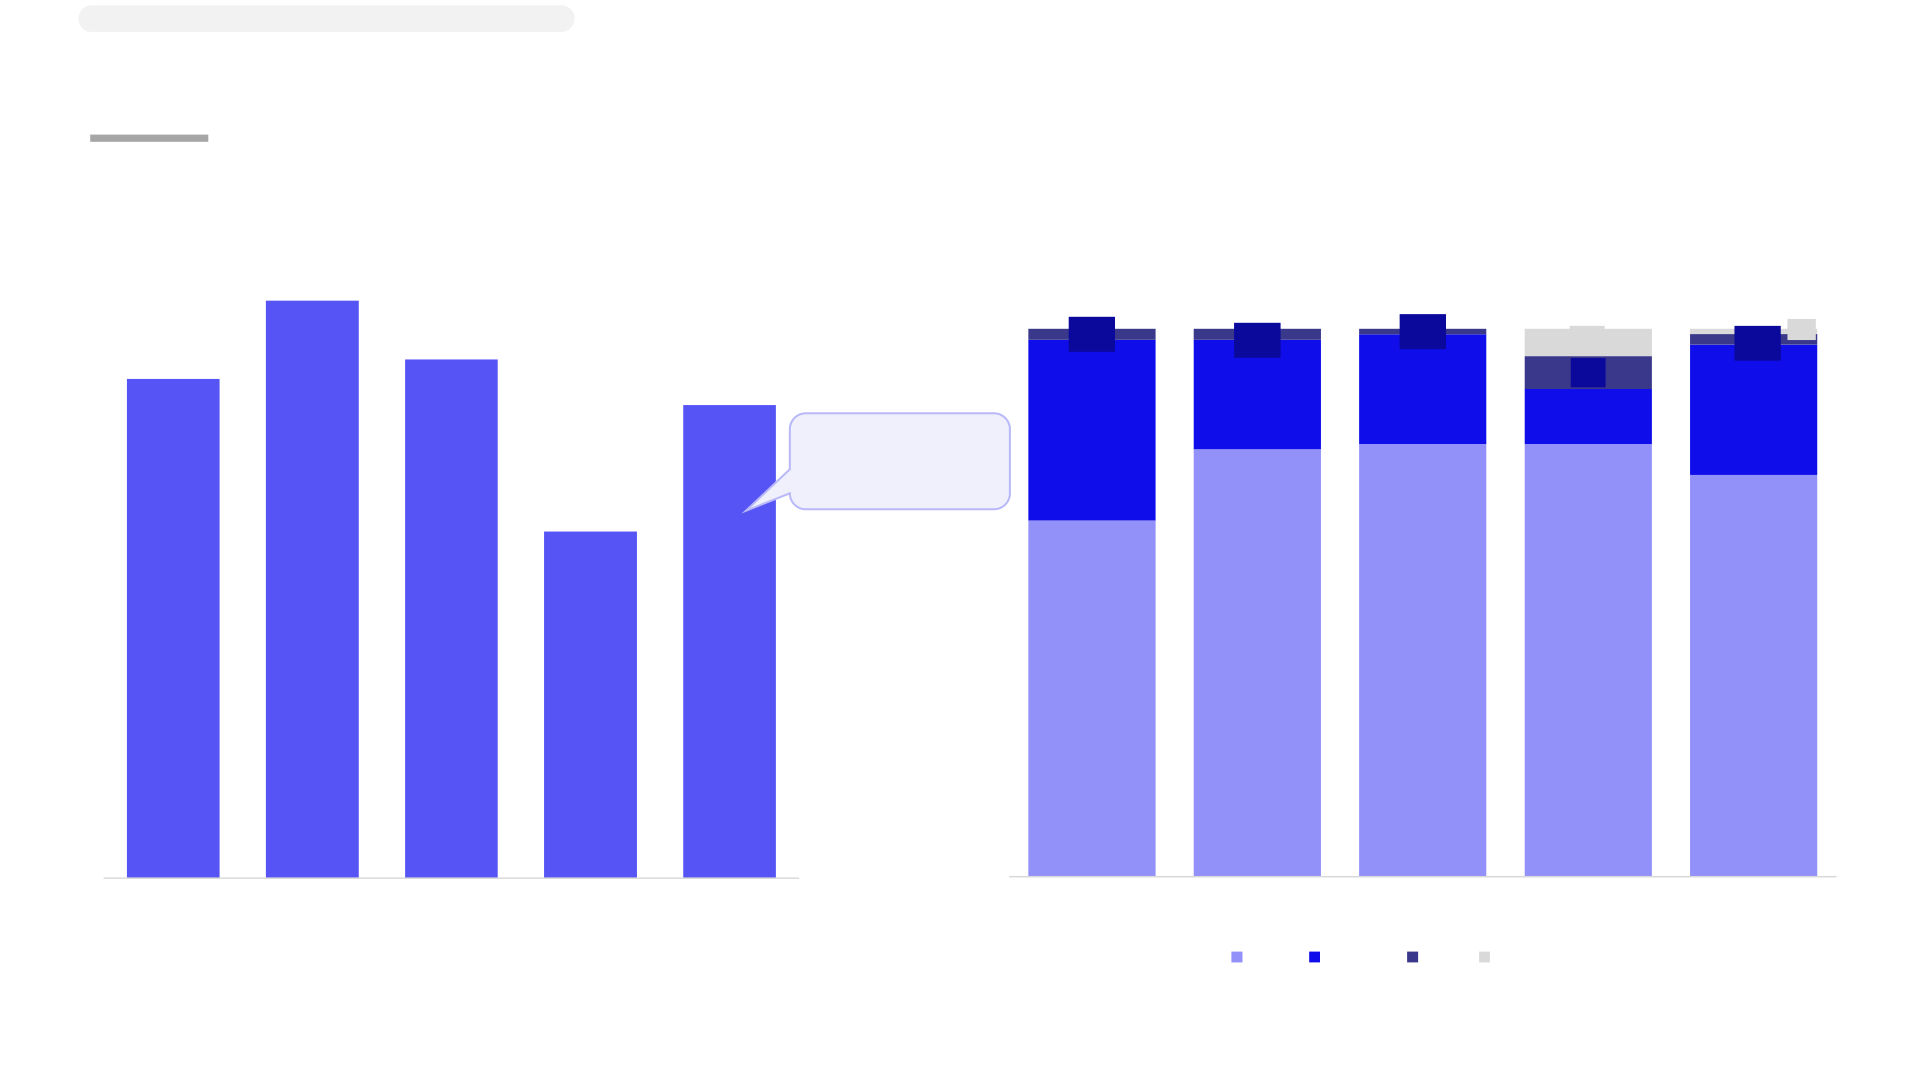
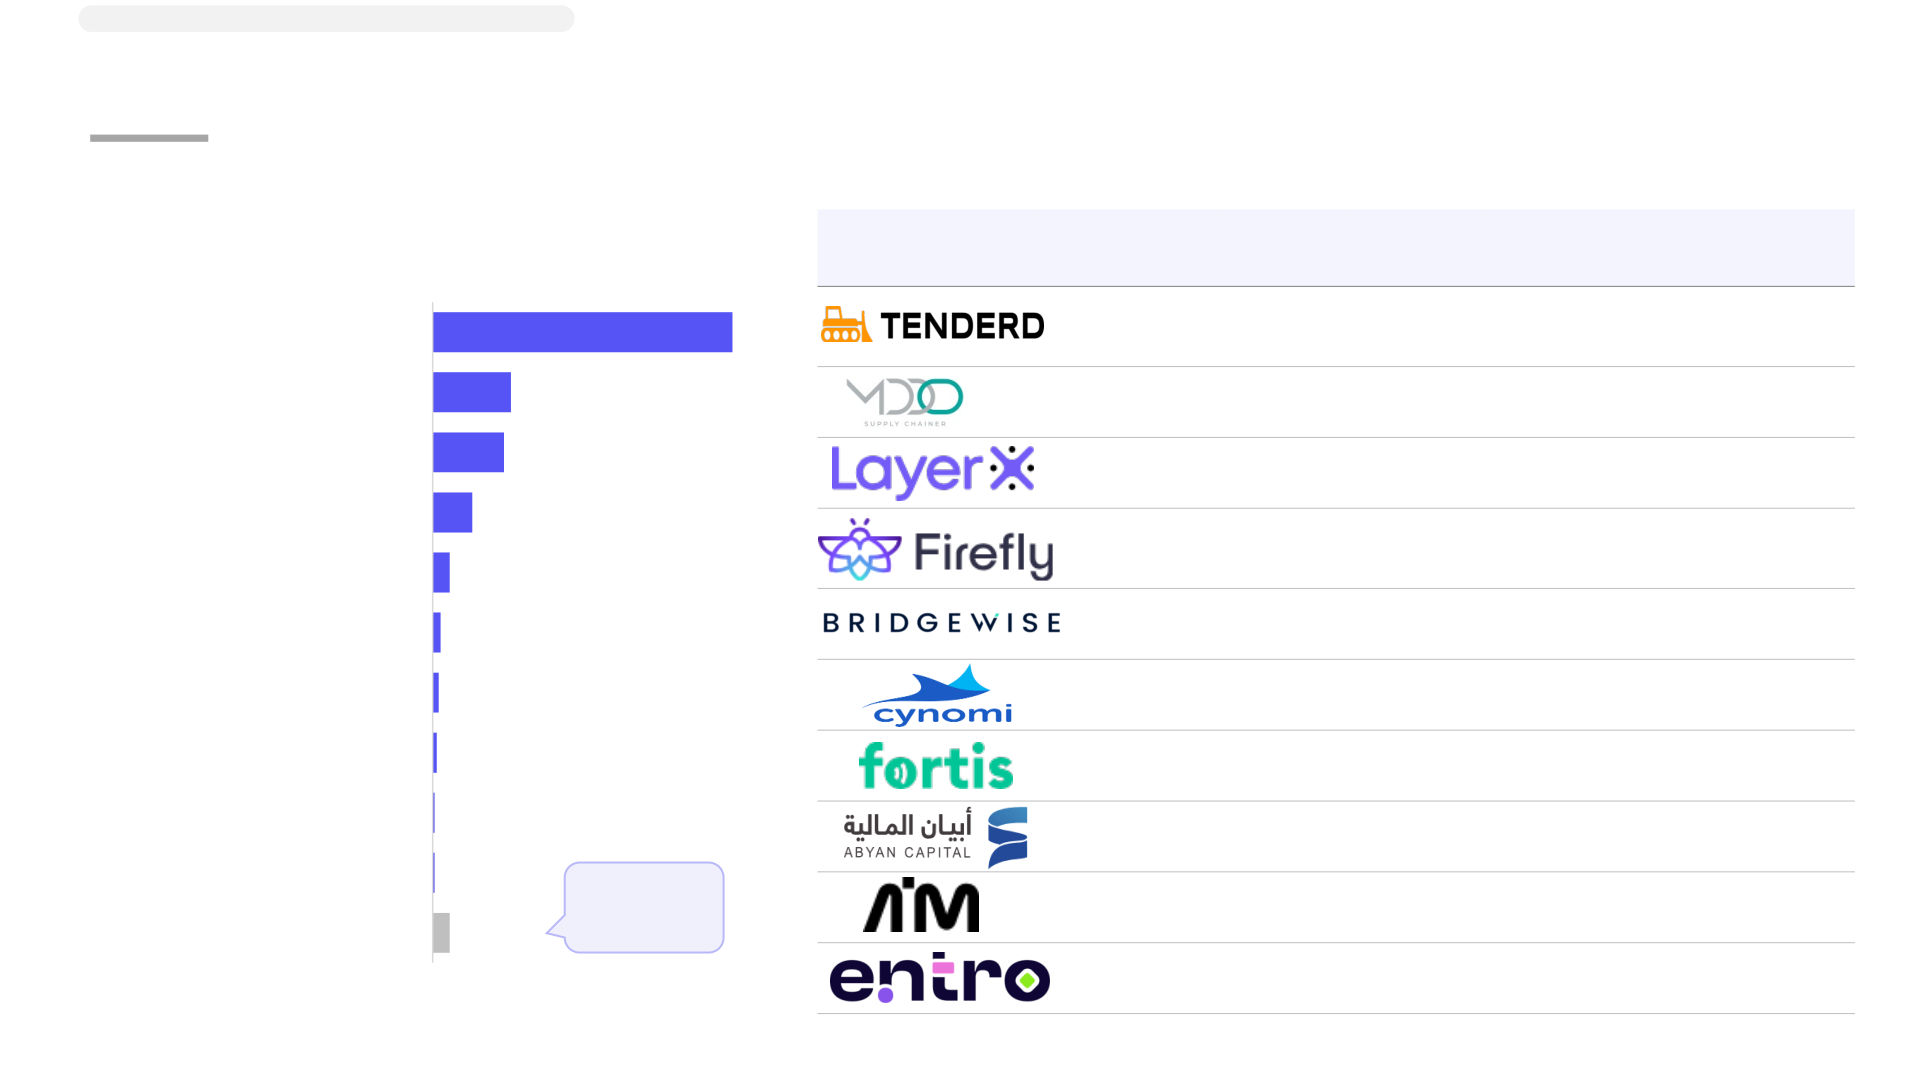
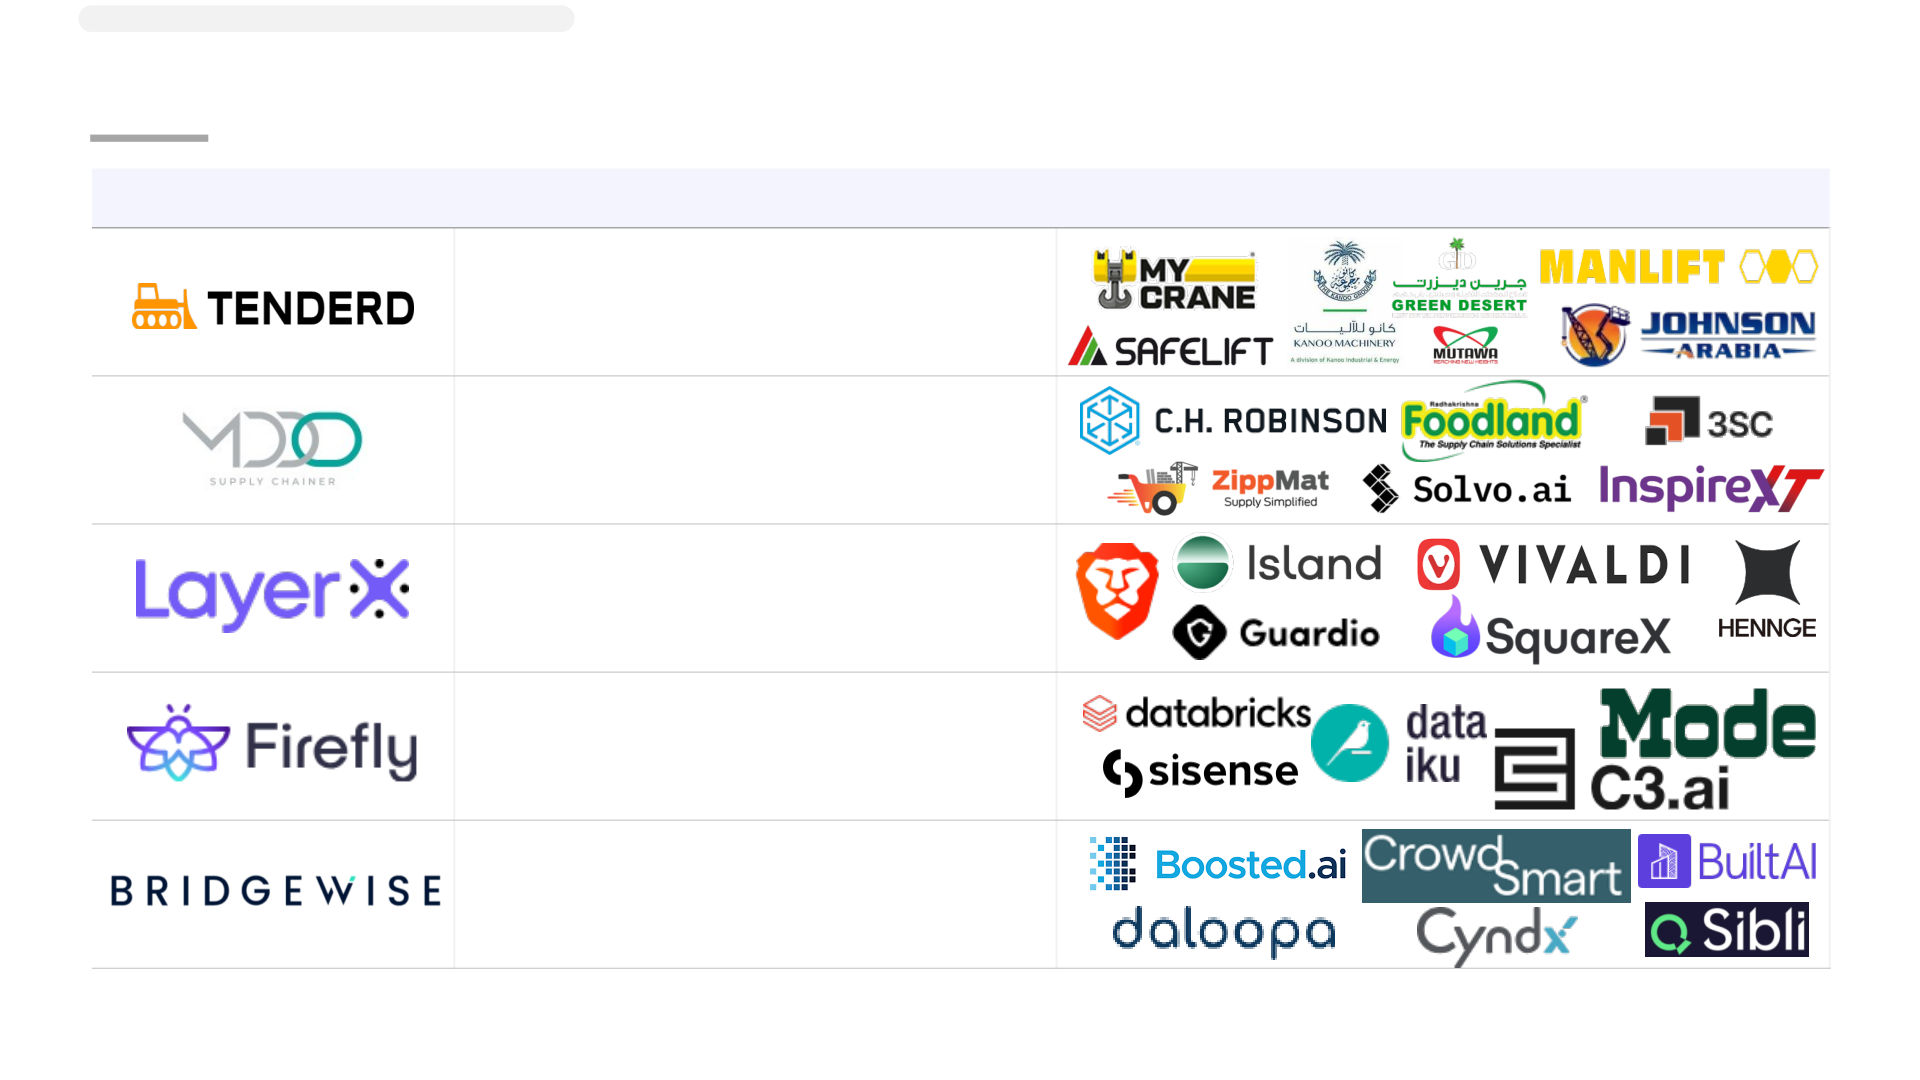
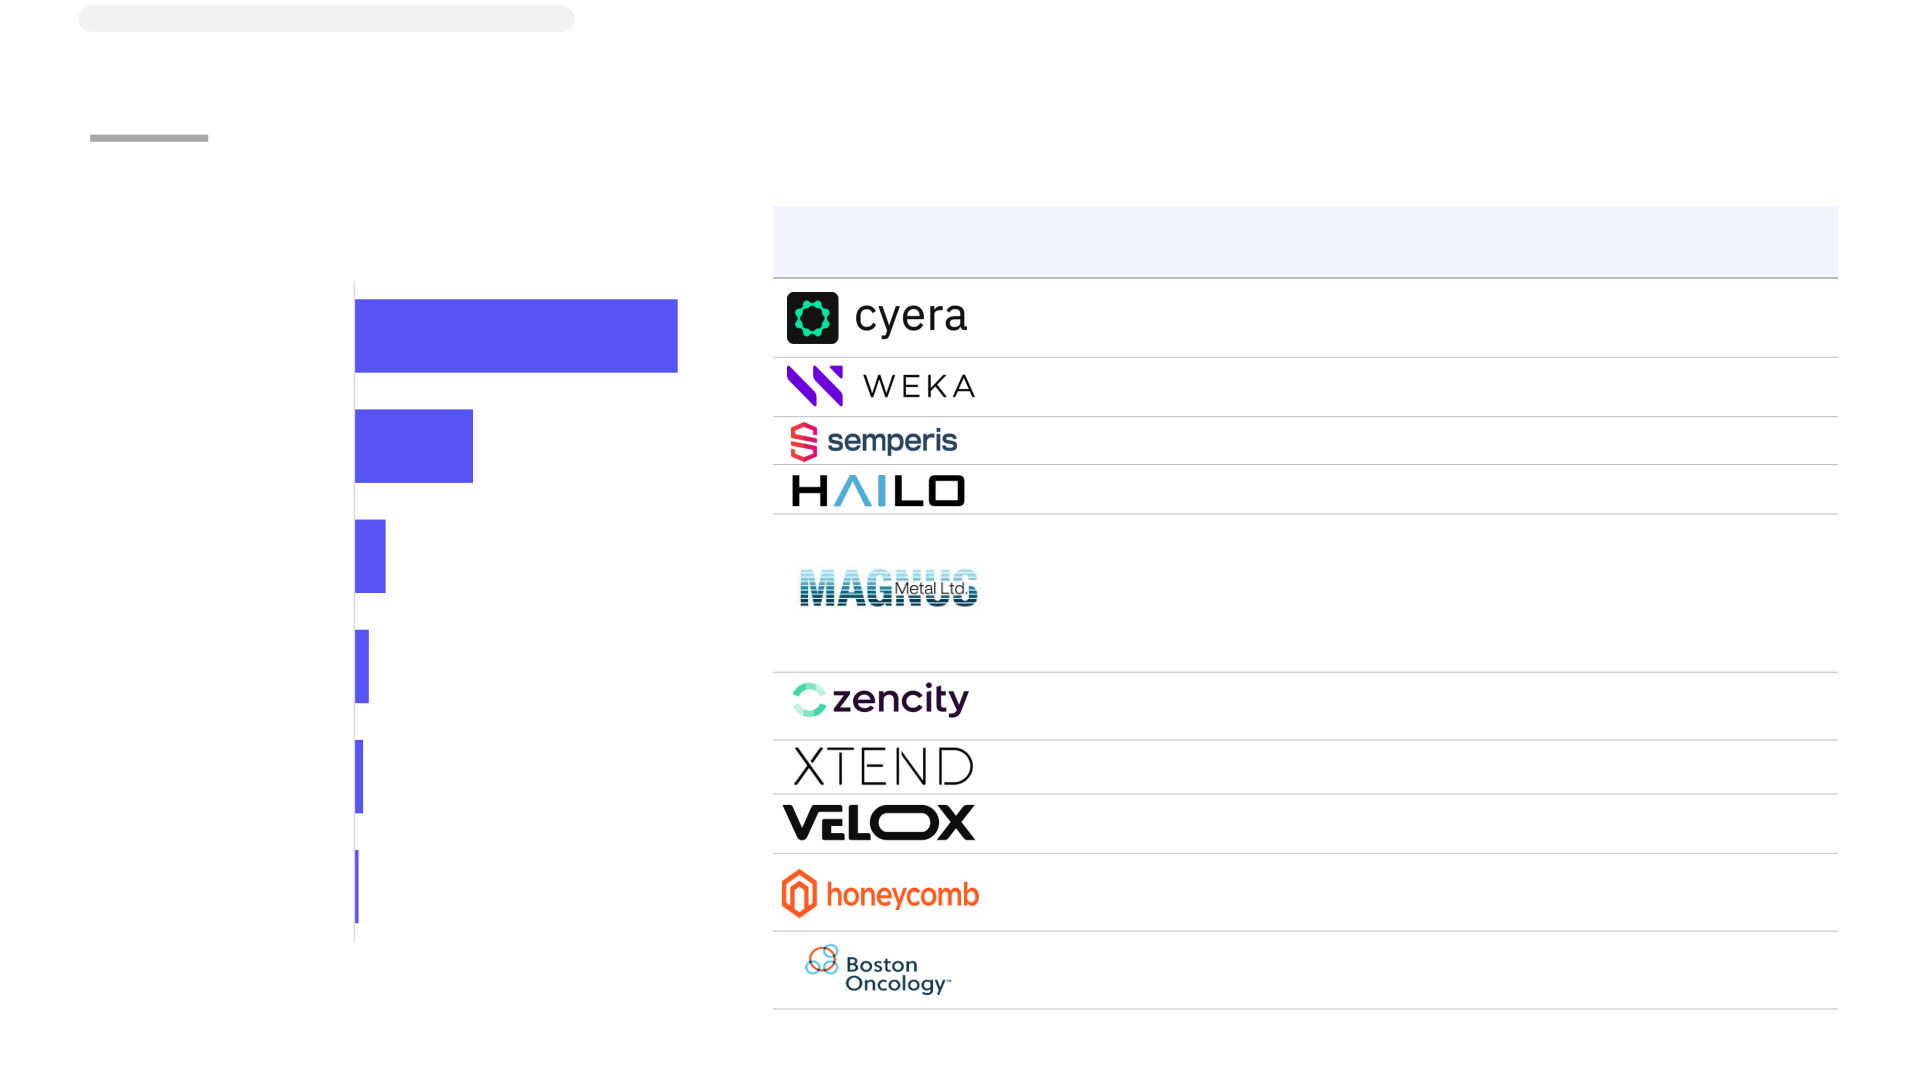
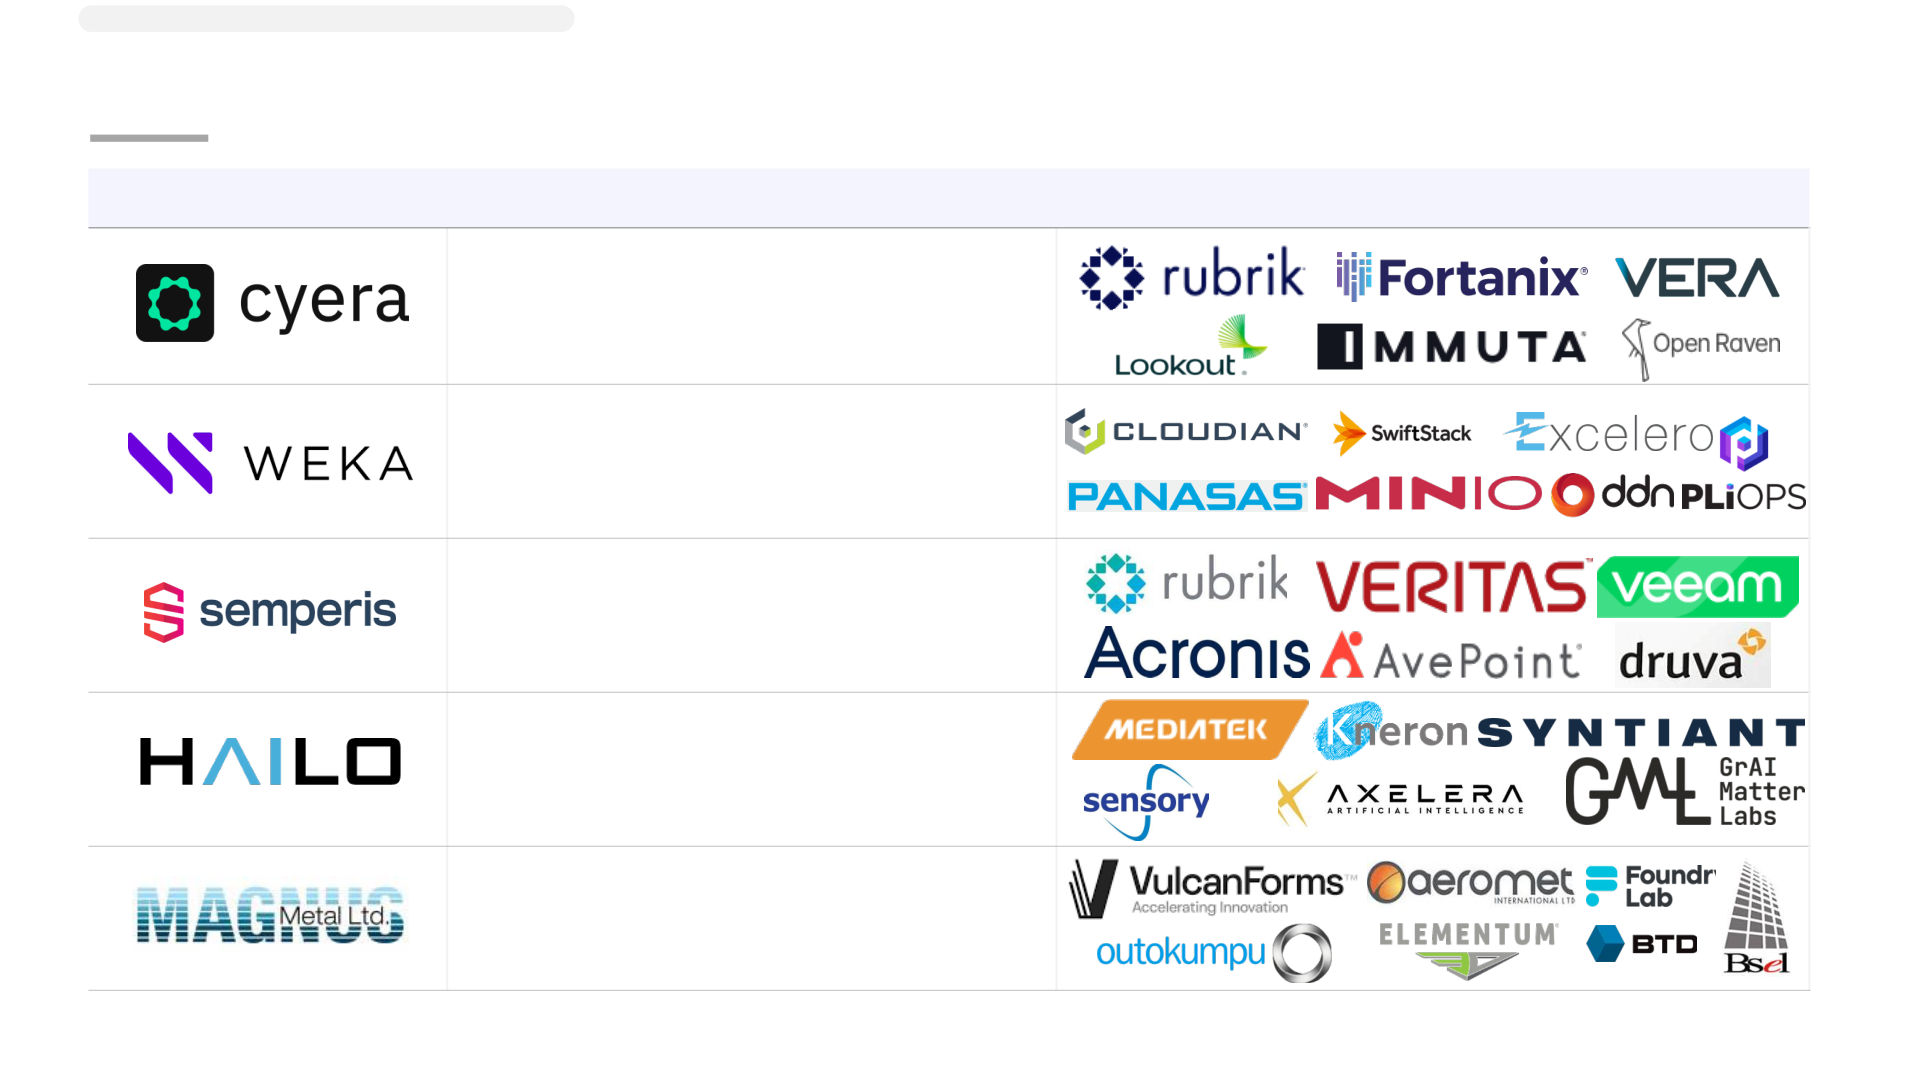
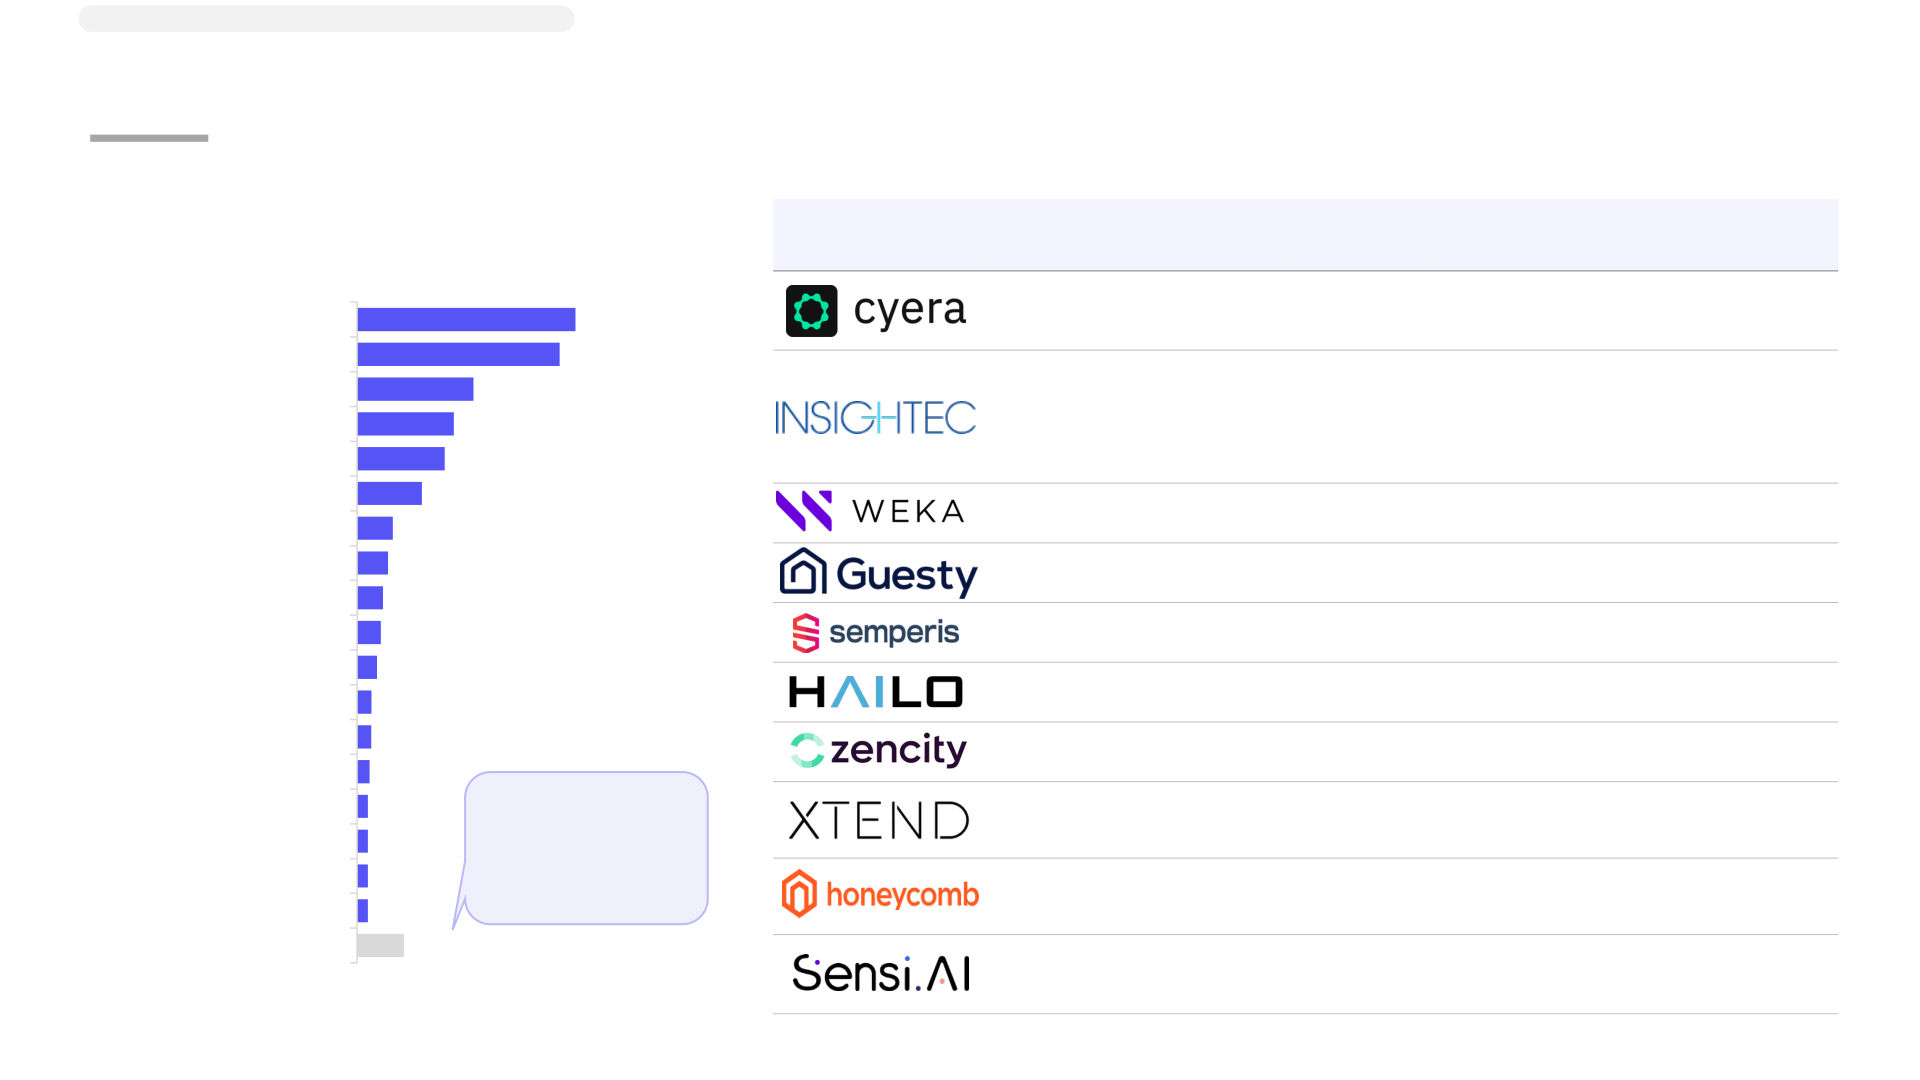
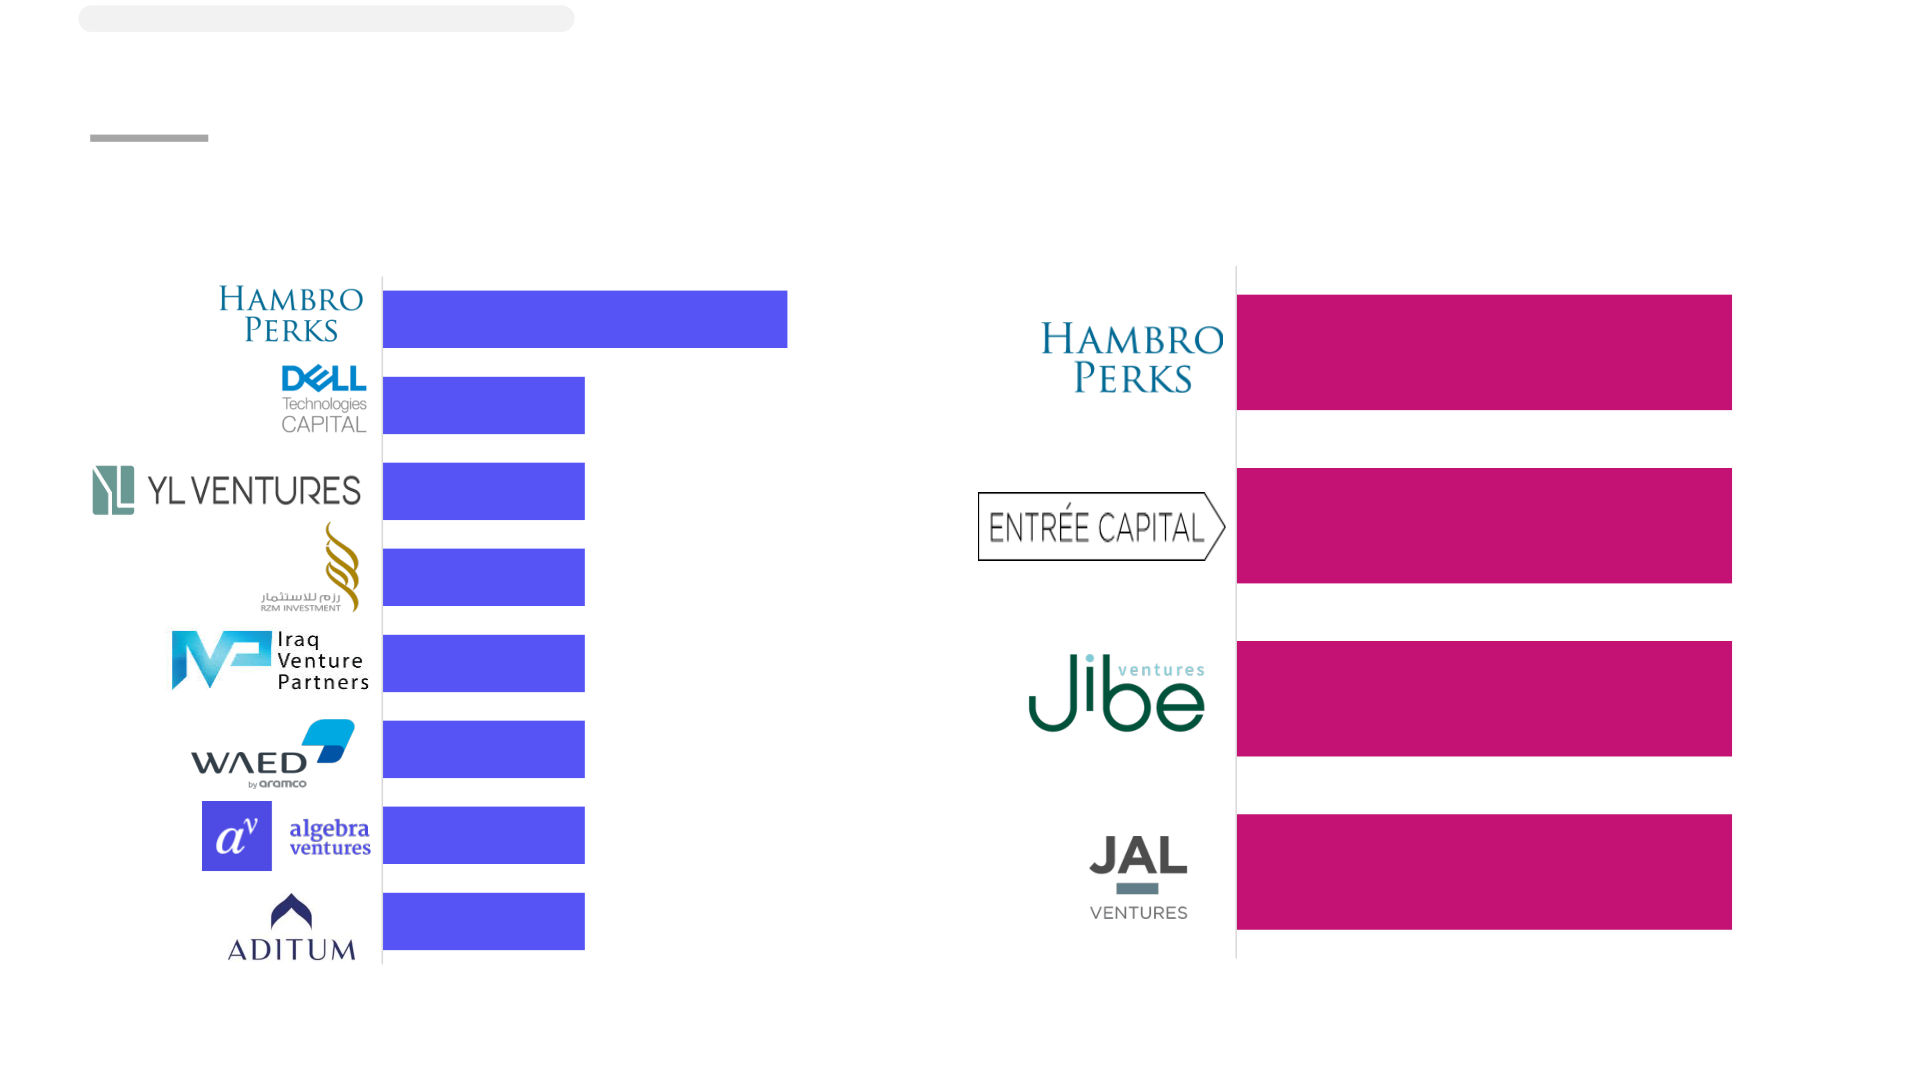
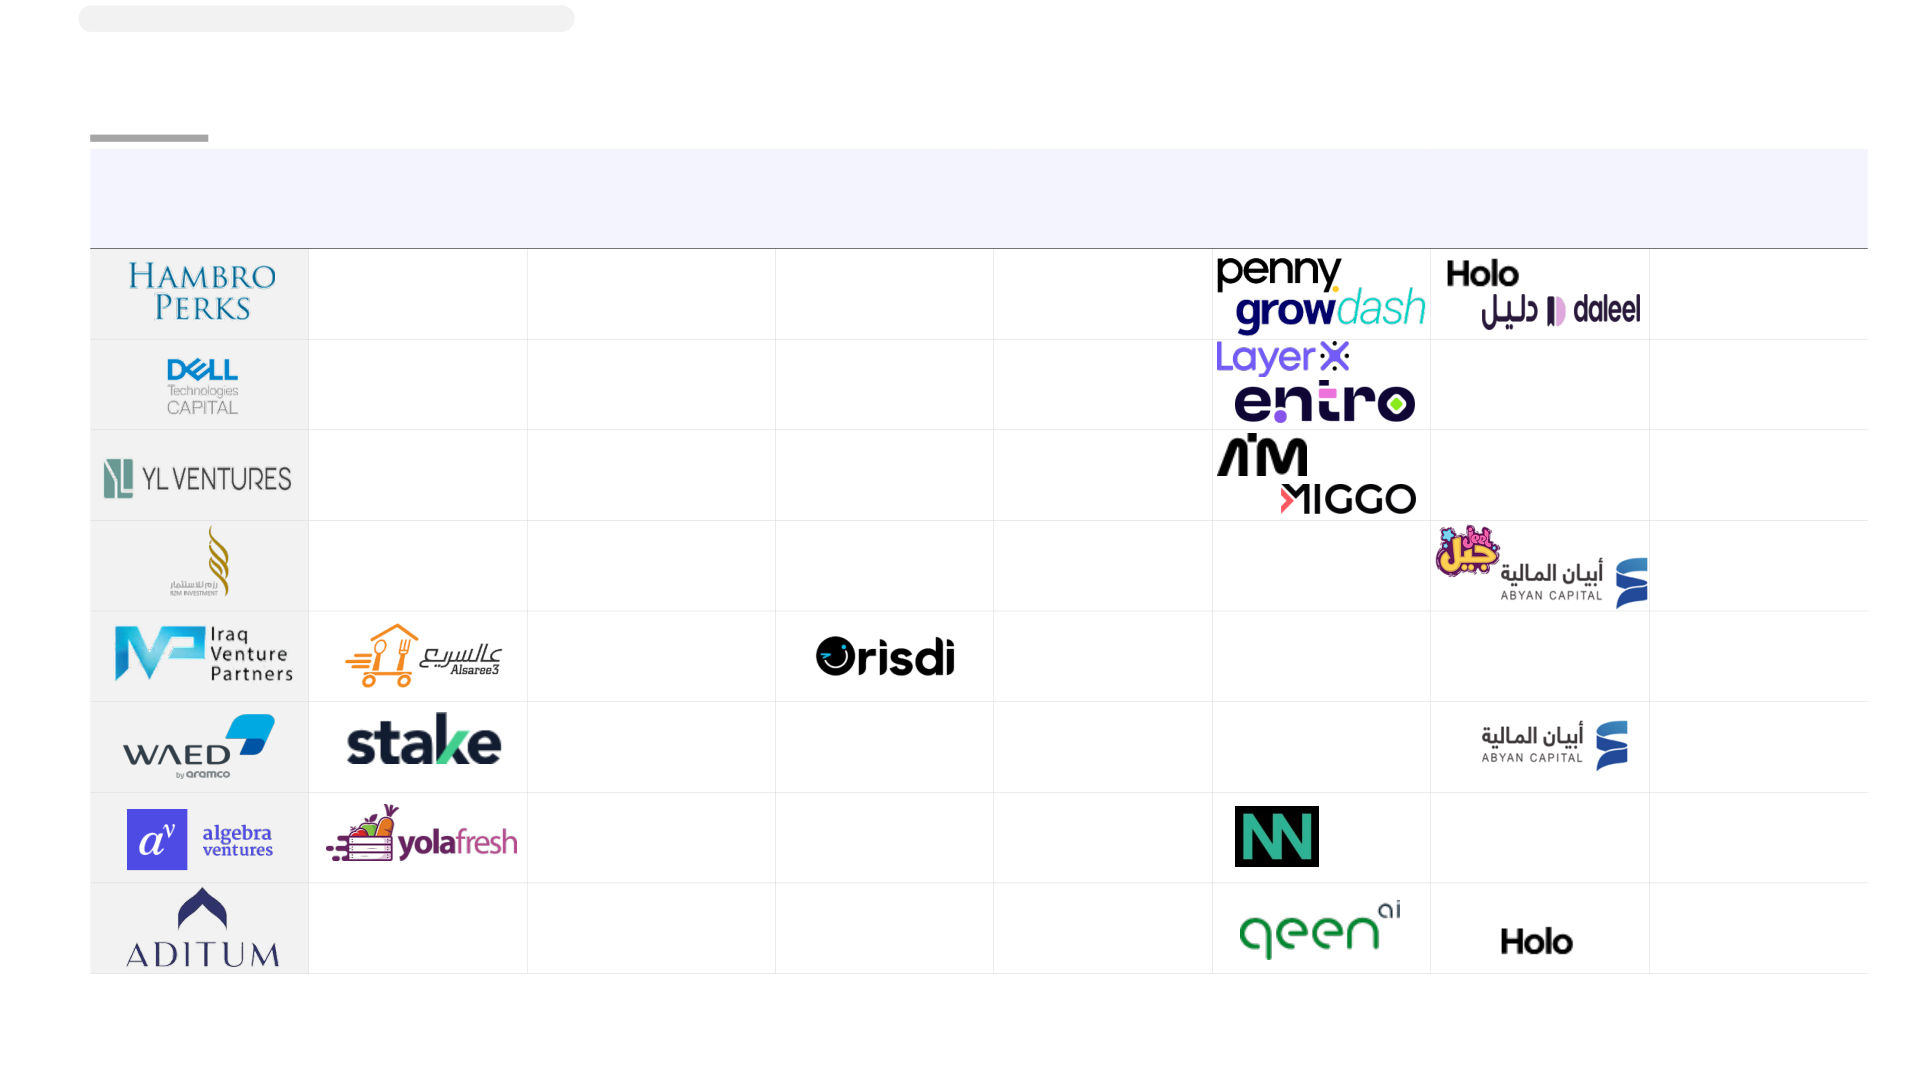
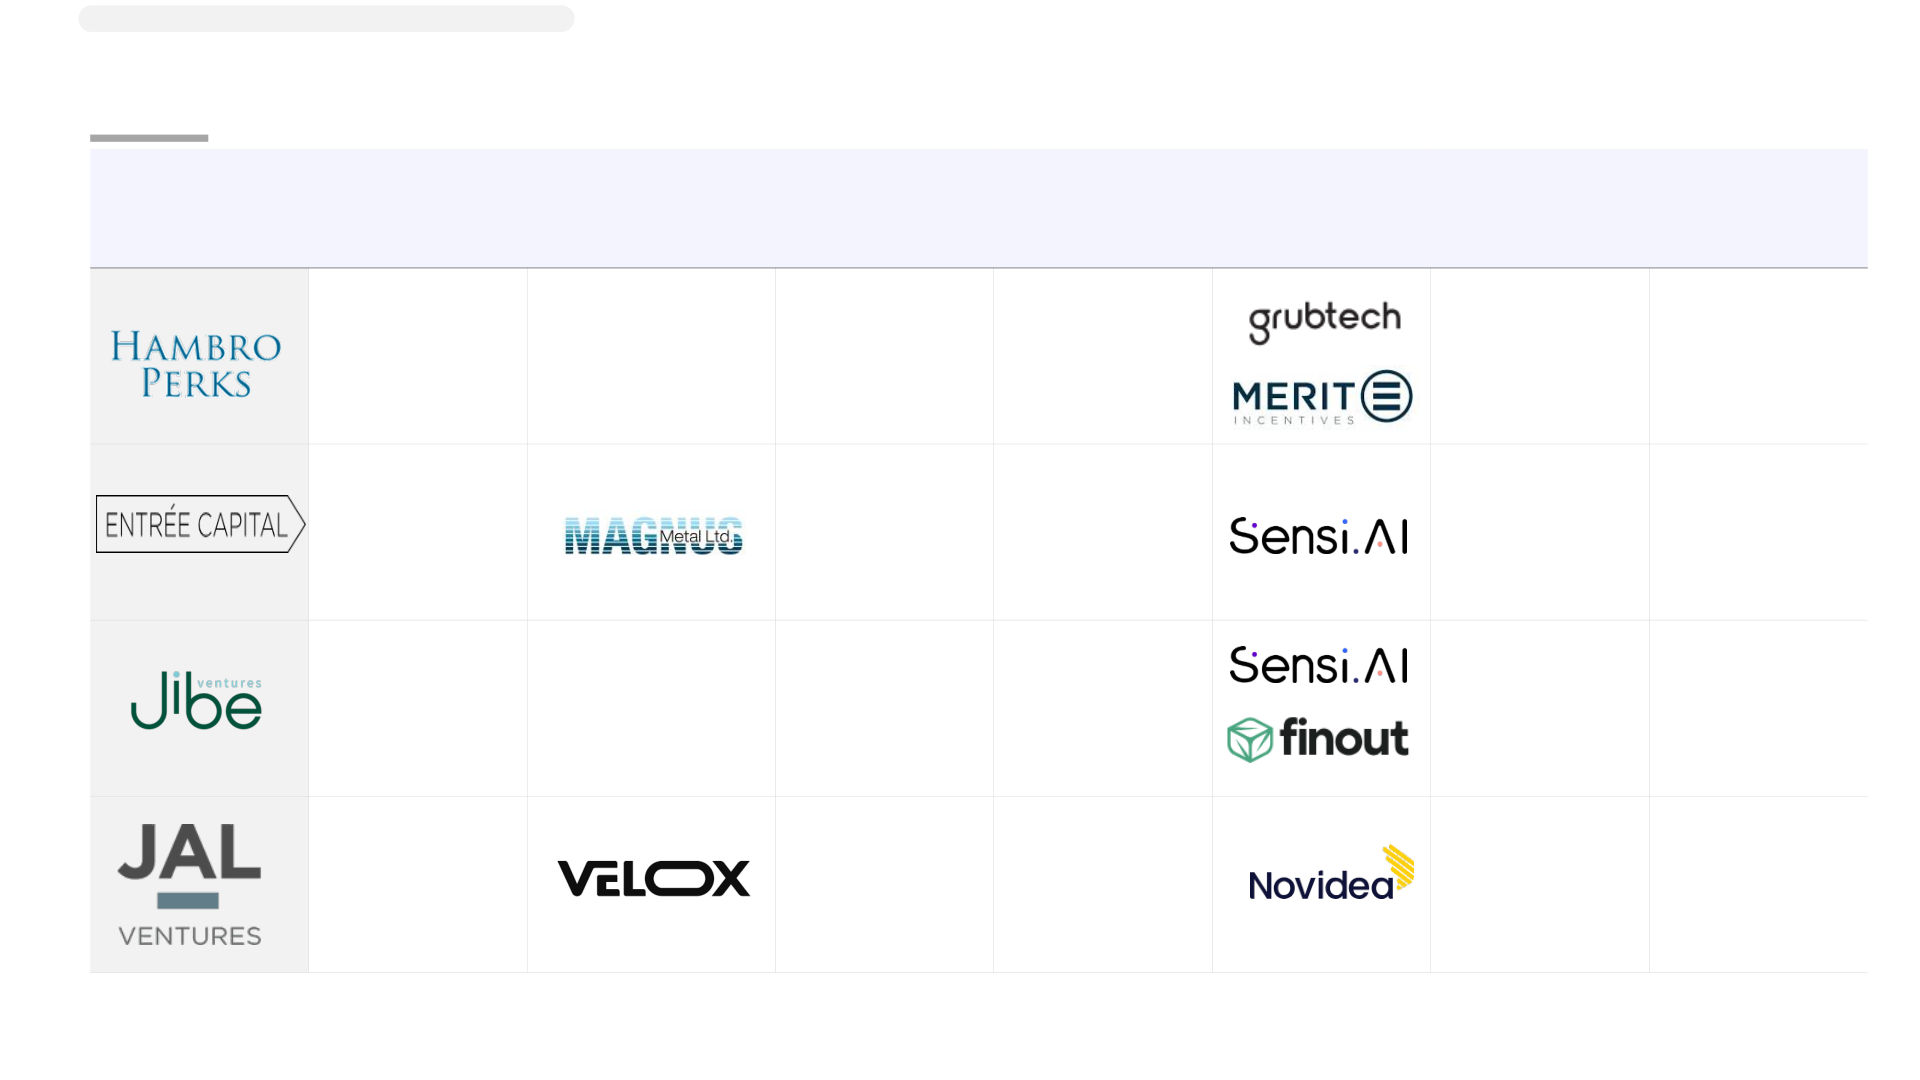
MENA Quarterly Investment Analysis Q2 CY24 July 2024 Confidential and proprietary © 1Lattice Foreword Foreword The Middle East and North Africa (MENA) region presented a fascinating contrast in Q2 CY 2024; while deal activity reduced (100 deals compared to 125 in the previous quarter), the overall deal value surged to approximately US$ 2.2B from US$ 2B in the previous quarter. Despite a decrease in the number of deals, this increase can be attributed to the increased average order value of 36% on a Q - on - Q basis. While there has been some improvement in average deal size, a closer look reveals that it remains low compared to H2 2023, indicating significant potential for growth. Investors continue to adopt a 'wait - and - see' stance until more concrete signs of war de - escalation are evident. Amar Choudhary Praneet Singhal The investment landscape and investor sentiments varied across the region. Israel, for instance, experienced a significant upswing in investment activity, capturing roughly 80% Chief Executive Officer Director , Financial of the total MENA funding compared to 55% last quarter. Investors & 1Alpha 1Lattice Tech remains the region's undisputed leader, with Software - as - a - Service (SaaS) being the 1Lattice most sought - after sector, followed by Manufacturing. This report by 1Lattice aims to illuminate the key trends shaping the investment landscape within the MENA region during Q2 2024. We believe this analysis offers valuable insights that can spark productive dialogue with partners across various industries. As the MENA investment landscape continues to evolve, we look forward to actively engaging in discussions, exchanging perspectives, and delving deeper into these developments. © 1Lattice | 2 Product in Spotlight - Pulse This report was curated using our cutting - edge product, Pulse Pulse provides comprehensive visibility into your industry benchmarks and best practices. From tracking macro indicators and government regulations to specific operating metrics and best practices of your peers, from monitoring pricing strategies to evaluating brand reputation through sentiment analysis and social listening, Pulse covers all bases to help you adapt your strategies for beating the industry standards. This report offers invaluable insights into MENA’s robust economy, driven by ongoing tech innovations that enhance the busine ss environment. In this report, Pulse empowered our expert team with comprehensive research tools to analyze the overall funding landscape, investor behavior patterns, and deal sizes. By leveraging Pulse, we gained a detailed understanding of the factors driving investment trends and the opportunities they present. This comprehensive approach allowed us to present a thorough analysis of the current investment landscape in the MENA region, offering you the insights needed to navigate and capitalize on emerging opportunities. Equip your business with the intelligence provided by Pulse to stay ahead in today's competitive market, consistently outperf orm industry standards, and achieve sustainable success. Key takeaways ● MENA companies raised ~ US$ 2.2B across 100 deals (early, growth, late, and PIPE stages) in Q2 CY24 ‒ Growth - stage deals (56% of the total funding) witnessed an increase in $ value by ~140% on a Q - on - Q basis ● Average deal size increased from US$ 15.9M to US$ 21.7M ( ~36%) in Q2 CY24 from the previous quarter; however, the number of deals decreased from 125 in Q1 CY24 to 100 (~20%) ● Israel attracted ~80% of the total funding at ~US$ 1.7B, followed by UAE (~US$ 197M), and Saudi Arabia (~US$ 158M) ● SaaS/AI was the most attractive sector for growth - stage (~US$ 789M ) and early - stage investments (~US$ 370M ) ‒ Cyera , a SaaS/AI platform, received the highest funding of ~US$ 300M among growth - stage investments ‒ Tenderd , an E - Commerce and Listing Platform, received the highest funding of ~US$ 30M among early - stage investments ● Enterprise Tech (~US$ 404M) & Cybersecurity (~US$ 375M) attracted the highest tech investments in Q2 CY24 MENA region definition Lebanon Syria Palestine Tunisia Iraq Israel Iran Morocco Jordan Kuwait Bahrain Libya Algeria Saudi Arabia Qatar Egypt UAE Oman Sudan Yemen © 1Lattice | 5 Key Highlights Funding # Deal v olume Average ticket size US $ 2.2 B 100 US$ 21. 7 M SNAPSHOT Q2 CY 2024 Top funded sector Most funded stage (by # of deals) Total tech funding SaaS / AI Early US$ 1.9B Market by segments SaaS / AI leads funding followed by Manufacturing in Q2 CY24 Funding market breakup – by segment ( US$ M, Q2 CY24) Total funding size: US$ 2,175 M 294 208 1,289 Healthcare & Life Manufacturing Sciences 49 SaaS / AI 164 117 Transportation & L ogistics 10 1 0 21 Telecom FMCG Consumer Apps E - Commerce & * Others 2.6 & P latforms Listing P latforms 7.5 2.5 BFSI Retail Note(s): *Others include Agritech , & drinking water companies © 1Lattice | 7 Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis Agenda Deal landscape in Q2 CY24 Key deals and investment themes Key investors Stage - wise investments Growth - stage deals witnessed an increase in $ value by ~140% on a Q - on - Q basis driven by growth in the manufacturing and SaaS/AI sectors Investment amount (US$ B) and # deals ( Q2 CY23 – Q2 CY24 ) 2.3 2.2 125 2.1 0.3 1.9 2.0 0.3 116 0.4 0.2 0.1 100 0.6 89 84 1.3 1.2 1.1 1.4 0.5 0.7 0.7 0.7 0.6 0.4 * * * * Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Early Growth Late Others Deals Note(s): Others include deals with PIPE round; *An approximate amount has been assumed for undisclosed deals basis previous deals of investors & the funding stage Source(s): 1Lattice deals database © 1Lattice | 9 Country - wise investments Israel drew the highest investment of ~US$ 1.7B followed by UAE (~US$ 197 M) and Saudi Arabia (~US$ 158M) Investment amount (US$ M) and # deals ( Q2 CY24 ) Avg. deal size 33 . 4 8.9 15. 8 5 .8 4.2 (US$ M) = 52 Israel witnessed a ~50% increase in value from US$ 1.1B last quarter, fueled by investor optimism on potential war de - escalation 1,737 22 10 10 6 197 158 58 25 Others* Egypt UAE Saudi Israel Arabia Amount Deals Low High Note(s): *Others include Morocco, Kuwait, Iraq, Bahrain & Jordan Source(s): 1Lattice deals database © 1Lattice | 10 Average deal size Average deal size across all funding stages increased in Q2 CY24, although it has not yet recovered to the peaks of H2 CY23; Volume of growth - stage deals increased by ~85% on a Q - on - Q basis Split of deal volume Average deal size (#, Q2 CY23 – Q2 CY24 ) (US$ M, Q2 CY23 – Q2 CY24 ) # of 26.5 84 116 89 125 100 deals = 1 1% 2% 23.8 2% 5% 2% 22.9 6% 21.7 20% 20% 25% 10% Average deal - size 33% across all stages (early to late) has increased 15.9 79% 79% 78% 77% 65% * * * * * * * * Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q2 CY24 Early Growth Late Others Note(s): *An approximate amount has been assumed for undisclosed deals basis previous deals of investors & the funding stage Source(s): 1Lattice deals database © 1Lattice | 11 Agenda Deal landscape in Q2 CY24 Key deals and investment themes Key investors Top 10 investments in Q2 CY24 Top 10 investments in the MENA region in Q2 CY24 accounted for more than 50% of the total investments received in the region Top 10 investments in Q1 CY24 Amount Funding Company Sector Country Key Investors (US$ M) stage Coatue, Spark Capital, Georgian, AT&T Ventures, Peak XV SaaS/AI 300 Growth Israel Partners, Accel, Redpoint, and Cyberstarts Fidelity Investments, Nexus Neurotech Ventures, Ally bridge group, Healthcare & Life 150 Late Israel Catalio Capital Management, Gilmartin Capital, Perceptive advisors, Sciences Fayez Sarofim & Co, and Baillie Gifford & Co SaaS/AI 140 Growth Israel Valor Equity Partners SaaS/AI 130 Late Israel KKR SaaS/AI 125 Growth Israel Hercules Capital, J P Morgan Manufacturing 120 Growth Israel Poalim Equity Entrée Capital ,Target Global, Caterpillar Ventures, Tal Ventures, Deep Insight Ventures, Awz Ventures, Lumir Ventures, Discount Manufacturing 74 Growth Israel Capital, Lip Ventures, Cresson Management, Next Gear Fund and Essentia Venture Capital Consumer app & 40 Growth Israel TLV Partners, and StepStone Group Platform SaaS/AI 40 Growth Israel Balderton Capital, Fifth Wall Manufacturing 38 Growth Israel Chartered Group Note(s): These include deals only with disclosed deal amounts © 1Lattice | 13 Source(s): 1Lattice deals database Early - stage investments SaaS/AI sector received highest funding (~US$ 370M ) among early - stage investments Top 10 early - stage investments in Q2 CY24* Early - stage investments, by sector Amount Company Sector Country Key Investors (US$ M, Q2 CY24 ) (US$ M) A P Moller Holding, Quadri Ventures, Ecommerce & UAE 30 Wa’ed Ventures, Nakhla Ventures, Saas/AI 370.0 Listing platforms SOMA Capital, and Liquid 2 Ventures Ecommerce & Listing Transportation and 96.6 MDD Saudi Arabia 26.6 Undisclosed Platforms Logistics Consumer App & Platforms 88.0 Glilot Capital Partners, and Dell SaaS / AI Israel 26 Technologies Capital Transportation and 49.1 Vertex Ventures, SoftBank Group, logistics SaaS/AI Israel 23 InMotion Ventures, and Hanaco Healthcare & Life Sciences 21.0 Ventures, RedSeed SIX Group, Group11 , and L4 Venture SaaS/AI Israel 21 Telecom 10.0 Builder Canaan, Flint Capital, s16vc, and BFSI 7.5 SaaS/AI Israel 20 Aloniq Manufacturing 5.3 SaaS/AI UAE 20 Opportunity Venture (Asia) Engg. & Construction 2.6 Consumer app & STV, RZM Investments, and Wa'ed Saudi Arabia 18.1 Platforms Ventures Retail 2.5 Others include Agriculture and AIM SaaS/AI Israel 18 Canaan partners, and YL Ventures Others Water tech 21.0 SaaS/AI Israel 18 Dell Technologies Capital © 1Lattice | 14 Note(s): * These include deals only with disclosed deal amounts Early - stage investments include Pre - seed, Seed, Pre - series and Series A; The table includes only disclosed deal amounts Source(s): 1Lattice deals database Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Online rental platform for industrial and construction equipment. Tech company specialized in supply chain management and procurement solutions. Provider of a platform offering secure browsing solutions. Brave Automatic machine learning platform for data science professionals. Online insight platform intended to provide AI - based stock analysis. Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A Source(s): 1Lattice deals database © 1Lattice | 15 Growth - stage investments SaaS / AI dominated growth - stage investments (~US$ 789M ) Top 10 growth - stage investments in Q2 CY24 Growth - stage investment, by sector Amount (US$ M, Q2 CY24 ) Company Sector Country Key Investors (US$ M) Coatue, Spark Capital, Georgian, AT&T SaaS/AI Israel 300 Ventures, Peak XV Partners, Accel, SaaS/AI 789 Redpoint, and Cyberstarts Saas /AI Israel 140 Valor Equity Partners Saas /AI Israel 125 Hercules Capital, and J P Morgan Manufacturing 289 Manufacturing Israel 120 Poalim Equity Entrée Capital ,Target Global, Caterpillar Ventures, Tal Ventures, Deep Insight Consumer app & Platform 76 Ventures, Awz Ventures, Lumir Ventures, Manufacturing Israel 74 Discount Capital, Lip Ventures, Cresson Management, Next Gear Fund and Essentia Venture Capital Healthcare & Life Sciences 35 Consumer app & Israel 40 TLV Partners, and StepStone Group Platform Ecommerce & listing SaaS/AI Israel 40 Chartered Group 21 platforms Ortissimo Capital , JAL Ventures, and Manufacturing Israel 38 Waypoint Investors Consumer app & Zeev Ventures, Arkin Holdings, FMCG 10 Israel 36 Platform Launchbay Capital, and Ibex Investors Healthcare & Saudi Arabia 35 TVM Capital Healthcare Partners Life Sciences © 1Lattice | 16 Note(s): Growth - stage investments include Series B, C, D and E; The table includes deals only with disclosed deal amounts Source(s): 1Lattice deals database Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors Offering cloud data security solutions. Cloud based platform offering parallel file system - based storage management software. Cloud based platform offering distributed directory management solutions. Israel - based chipmaker of edge artificial intelligence (AI) processors. Manufacturer of additive casting products. Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice deals database © 1Lattice | 17 Tech investments EnterpriseTech & Cybersecurity attracted highest tech investments in Q2 CY24 Top 10 tech investments in Q2 CY24 Amount Tech investments, by sector Company Sector Country Key Investors (US$ M) (US$ M, Q2 CY24 ) 0.0 200.0 Coatue, Spark Capital, Georgian,AT&T CyberSecurity Israel 300 Venttures, Peak XV Partners, Accel, EnterpriseTech 404 Redpoint, and Cyberstarts Cybersecurity 375 Fidelity Investments, Nexus Neurotech FinTech 215.3 Ventures, Ally bridge group, Catalio HealthTech Israel 150 Capital Management, Gilmartin Capital, HealthTech 179 Perceptive advisors, Fayez Sarofim & Co, Cloud services & Infrastructure 162 and Baillie Gifford & Co Electical/Electronics 120 Cloud services Israel 140 Valor Equity Partners & Infrastructure Analytics 66 Robotics 57 EnterpriseTech Israel 130 KKR Media & entertainment 47.9 Real Estate EnterpriseTech Israel 125 Hercules Capital, and J P Morgan 44 EdTech 36.6 AI Processors Israel 120 Poalim Equity Logistics services 26.6 FoodTech 26 Consumer app & Israel 40 TLV Partners, and StepStone Group Platform Fashion & lifestyle 23 Others include HR Developer Tools and Platforms 20 Services, Horizontal Retail, Robotics Israel 40 Chartered Group Water tech , Mobile & Crypto/Blockchain 20 Internet services, Advertisement & Sales 20 CRM/Chatbots, and Consumer app & Zeev Ventures, Arkin Holdings, Israel 36 Horizontal Ecommerce Agritech Platform Launchbay Capital, and Ibex Investors 20 Others 86.3 Insight Partners, Zeev Ventures, Entrée EnterpriseTech Israel 31 Capital, Flint Capital, Jibe Ventures and Secret Chord Ventures Note(s): These includes only disclosed deal amounts © 1Lattice | 18 Source(s): 1Lattice deals database Top M&As Top M&As in Q2 CY24 Top M&As in Q2 CY24 Amount Acquired Company Sector Country Date Acquirer (US$ M) BFSI Morocco 800 April, 2024 700 April, 2024 SaaS/AI Israel SaaS/AI Israel 300 May, 2024 Transportation and 31 Morocoo June, 2024 Logistics 6 Energy Israel April, 2024 Note(s): Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice deals database © 1Lattice | 19 Agenda Deal landscape in Q2 CY24 Key deals and investment themes Key investors Active investors Most active investors of Q2 CY24 Growth - stage investors Early - stage investors (# deals) (# deals) 4 2 2 2 2 2 2 2 2 2 2 2 Source(s): 1Lattice deals database © 1Lattice | 21 Active early - stage investors Most active early - stage investors and their investment segments in Q2 CY24 Ecommerce & Consumer app & Investors Manufacturing Retail BFSI SaaS/AI Others listing platforms platforms - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - Connect - - - - - Money - - - - - Note(s): Investors who have invested in more than 2 companies © 1Lattice | 22 Source(s): 1Lattice deals database Active growth - stage investors Most active growth - stage investors and their investment segments in Q2 CY24 Ecommerce & Consumer app & Investors Manufacturing Retail BFSI SaaS/AI Others listing platforms platforms - - - - - - - - - - - - - - - - - - - - - - Note(s): Investors who have invested in more than 1 company © 1Lattice | 23 Source(s): 1Lattice deals database At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (1/2) Intelligence Input Validate Execute Measure & Insights • Market assessment, TAM, SAM • PMF test / feasibility studies • Time motion studies • SOP / process audits • GTM planning • B - plan validation • Brand health track studies • M&A landscape scan • Competitive landscape & scan • B2C Qualitative research • Segmentation and personas • Campaign evaluation • Tracking panels • Customer retention and loyalty • NPS studies • B2C Quantitative research • Customer journey mapping analyses • UI / UX testing • B2B Qualitative research • Account potential assessment • Customer retention analysis • NPS health check • B2B Quantitative research • Contract benchmarking • Sales force productivity • Customer segment GTM • Retail store audits • Retail Measurement Survey • Competitive intelligence • Benchmarking • Mystery shopping • Sentiment analysis • Channel tracks • Listed companies scan • Brand tracks • Micro market assessment • Concept Validation • Go to market Approach • MM competitive intelligence • MM planning • Impact metrics • Funding GTM strategy • Program management • Impact tracking • Founder / leadership assessment • Reputation diligence • Geo analysis • Leadership assessment • Founder integrity DD • Employee NPS • IPO program management • Industry and company data • Report key messages • IPO / QIP reports • Claims data • Claim validation • Gap analysis • Certification / Attribution • ESG standards / metrics • Stakeholder feedback • Gap analysis • ESG assessment • Risk audits and tracking © 1Lattice | 24 At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (2/2) Input Validate Execute Measure Networks • Expert interactions • Due diligence • Short - term projects • Expert access • Expert transcript library • Fitment and turnaround • Enterprise surveys time • Vendor/target search • 1Lattice panel powered by AI • Cohort matching • Short - term projects • NPS health check • Cohort based outreach • Pre search QC • Data scraping • Sales force productivity • B2B / B2C respondent search and • Detailed QC • Retail store audits DIY engagement • Retail Survey (RMS) • Capability assessment • Globally valid certification • Compliance training academy • Compliance certification • Skill matrix benchmarking • Ongoing engagement • Sales & soft skills academy • L&D feedback • Functional skills academy • Custom trainings • Coaches and mentoring network • Role transition support • Experts for mid term projects • Engineering/Technical Due • Marketing / creative hub • Compliance • Fractional CXOs Diligence • Sales hub management • Analyst hub • Analysts on demand • Leadership hiring • Reference checks • Outplacement Support • Talent access • Mid - Level hiring • Board placement • Fitment • Internships and turnaround time • Roadshows • Cohort matching • Curated events • Cohort fitment • Fundraising campaigns • RSVP Management - Channel • Business generated appointments (distributors, franchisee, M&A targets, CXOs) • Associated reports' launch © 1Lattice | 25 4 200+ Technology - backed business Offices in India Annual engagements support that helps you ENABLE BETTER 130+ 50+ Team members Inhouse research team DECISIONS 1,000+ 2M+ On - ground staff B2C Panel Deep on - ground insights that you can act on 4 offices, deep experience across geographies – India, the 500K+ 300K+ USA, Europe, MEA, and SEA regions B2B Panel Experts & professionals One - ness of data and people networks to harness the collective power of data, network, and technology 20% 100% Multi - faceted teams offering a stack of consulting, advisory, Cost savings Controlled output & timeline and research services We are here for you Let us know how we can meet your business requirement? Amar Choudhary Praneet Singhal CEO, 1Lattice Director, Financial Investors and 1Alpha E: p raneet.singhal@1lattice.com E: amar@1lattice.com For media queries, please contact Vaishnav Kumar Rai Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any for m, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experie nce s and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute an y b usiness advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sour ces of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market co nd itions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any un int ended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice doe s not hold any liability in connection therewith. +91 995 810 0839 praneet.singhal@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore