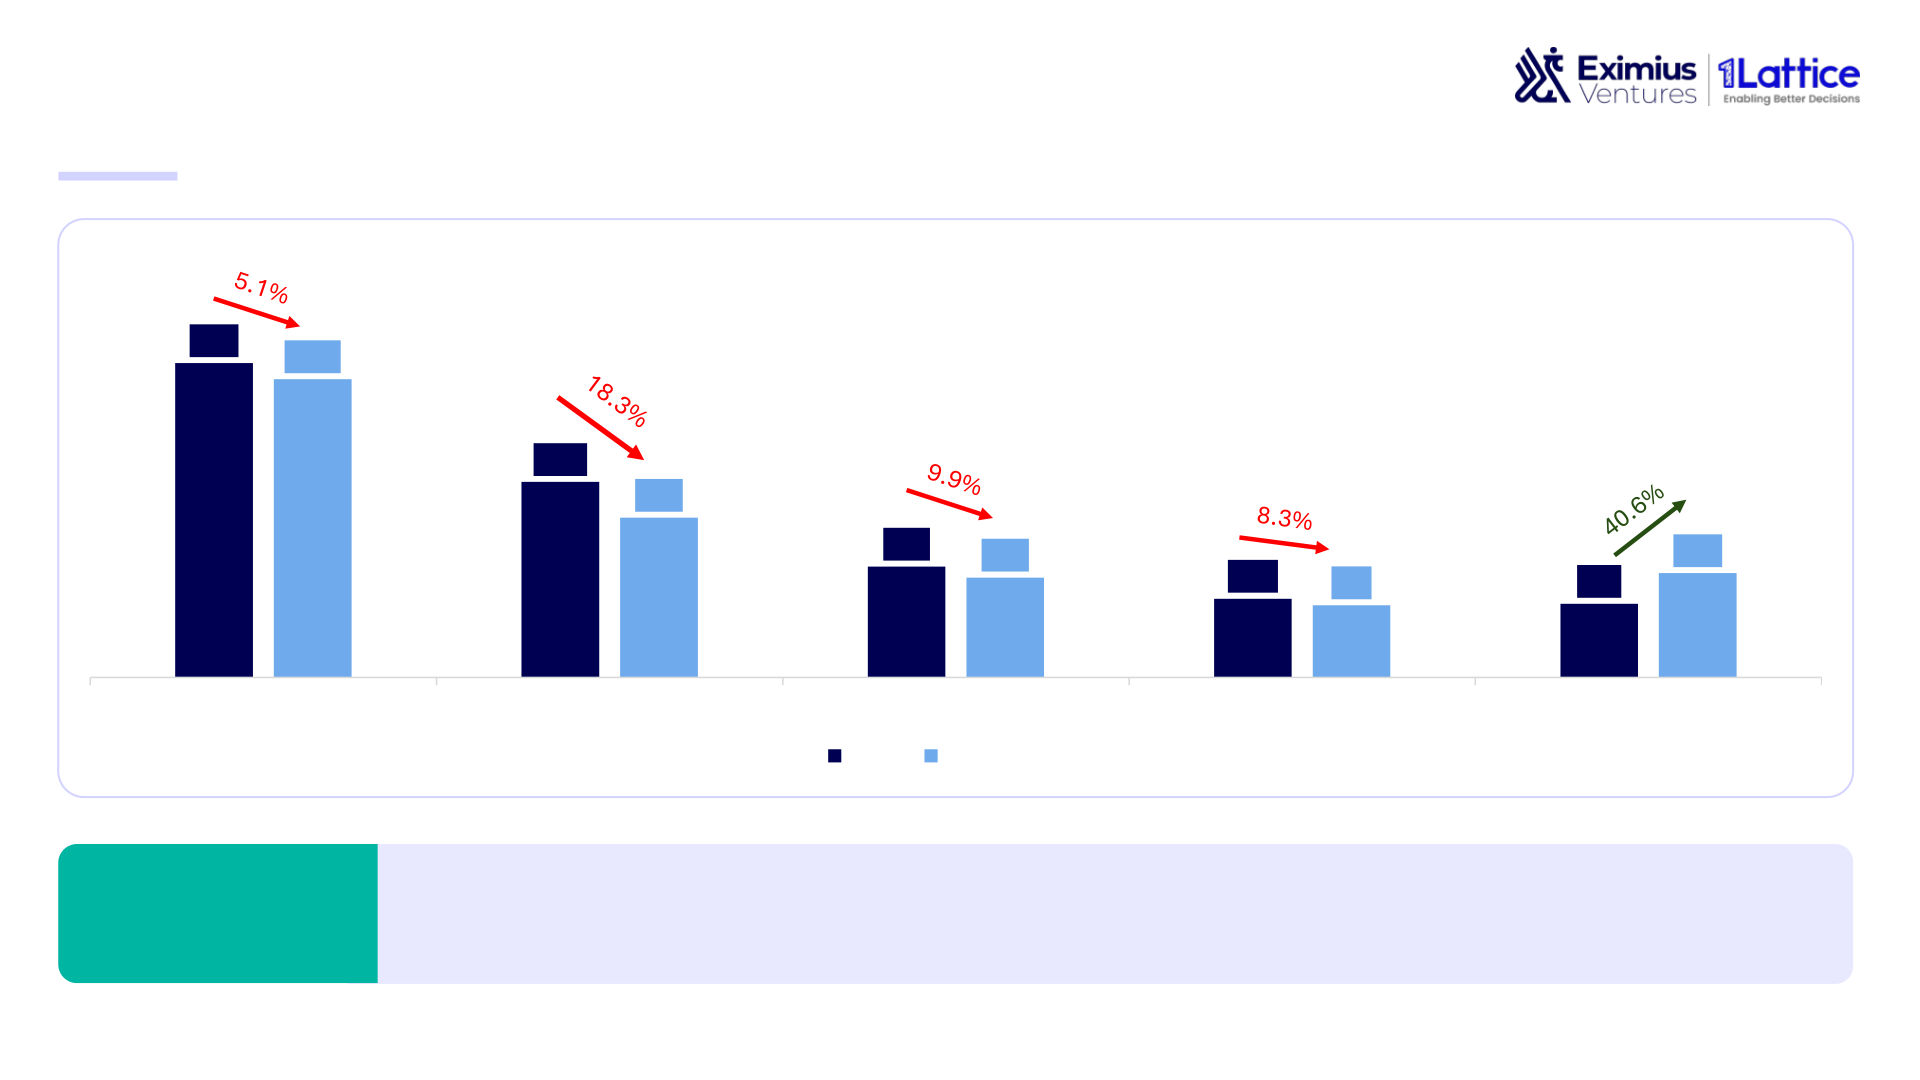
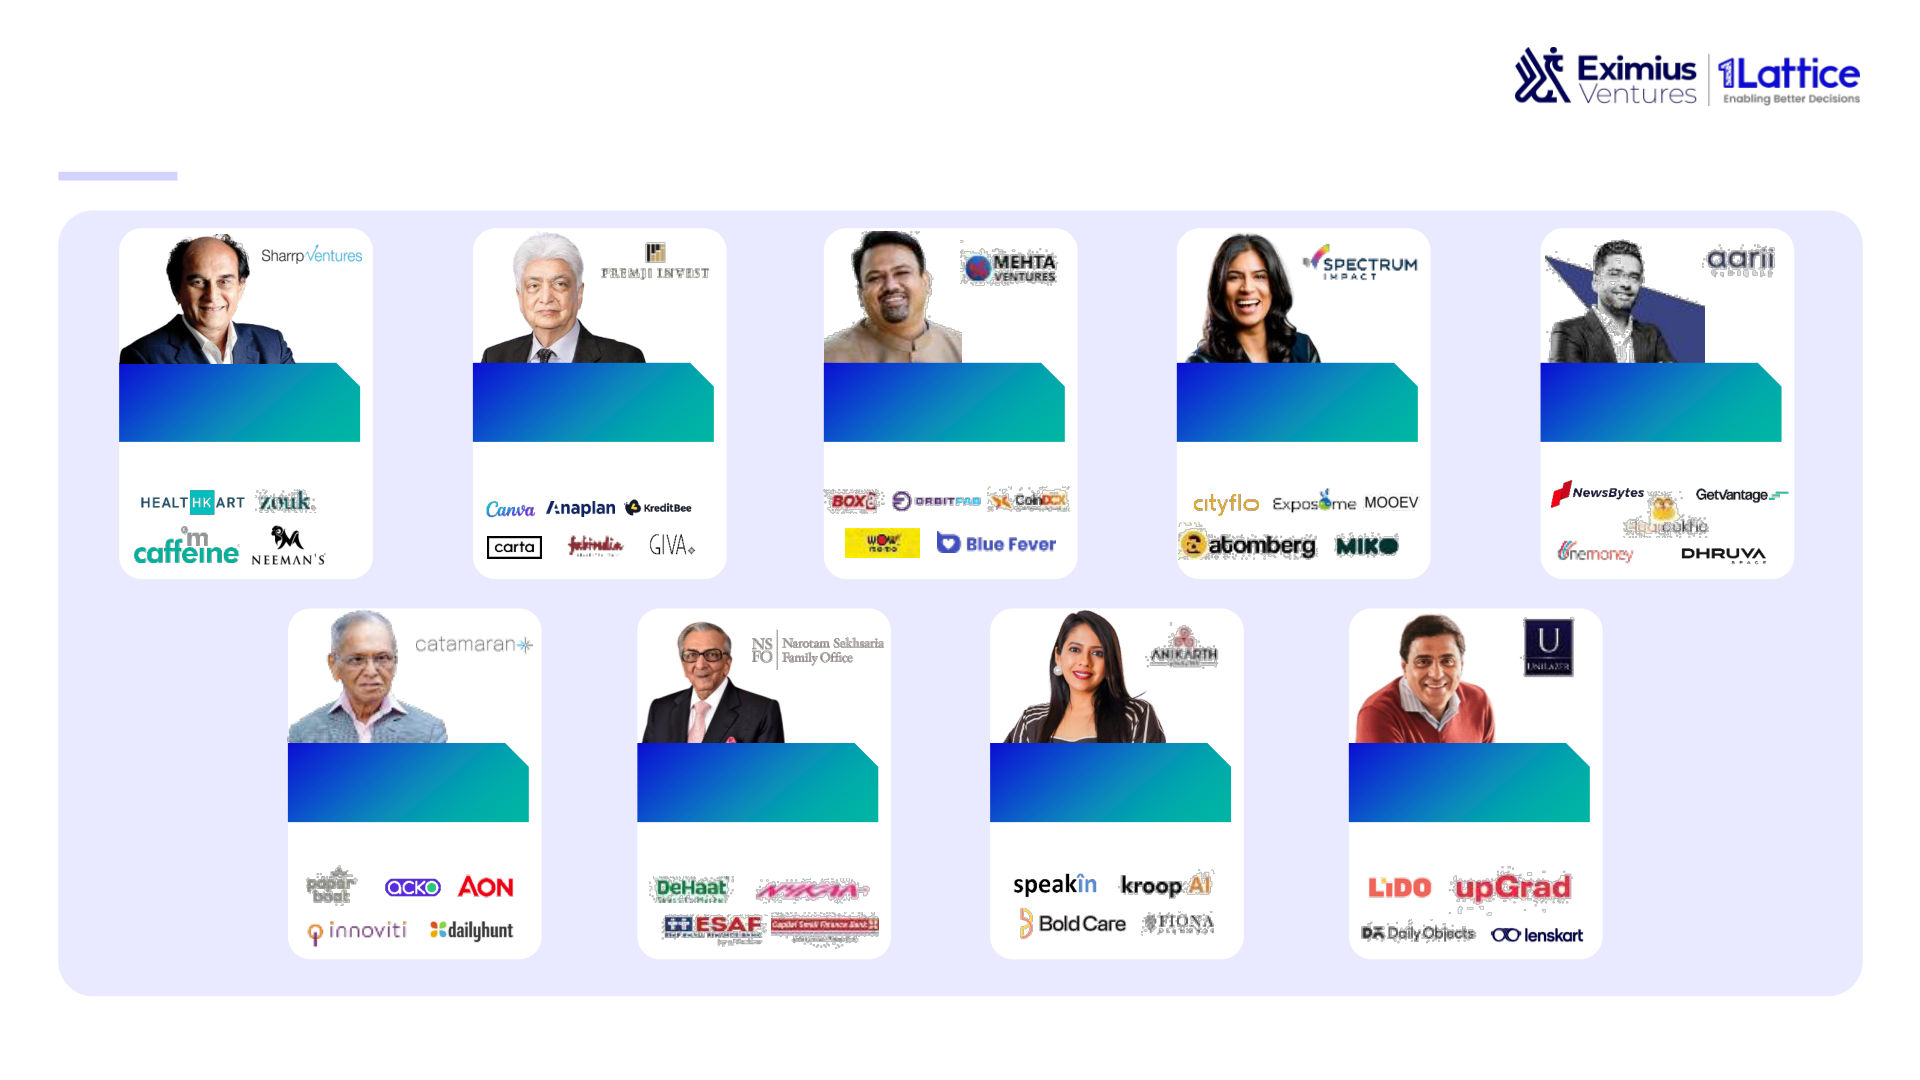
February 2026 The Indian startup ecosystem is at a defining inflection point. As the market matures, it is no longer converging, it is segmenting , demanding capital that is precise, conviction - led, Foreword and deeply aligned with stage - specific realities. This shift is most visible at the pre - seed stage . India’s rise as the world’s third - largest startup ecosystem has produced a new founder profile: increasingly experienced, often second - time entrepreneurs, building with greater ambition and speed. Over the past few years, pre - seed activity has grown steadily, with an increase in repeat / 2nd time founders , driving larger and more structured early rounds. Yet, while capital availability has expanded through angels, syndicates, family offices, and micro - VCs, ownership at this stage remains fragmented. Pre - seed today is not capital - constrained, it is execution - constrained . Syndicated angel rounds and multi - partner micro - VC participation, while valuable, often lack unified responsibility for the hard problems of 0 – 1: product - market fit, early GTM design, hiring, compliance readiness, and downstream capital preparedness. For founders building from scratch, even seasoned ones, this gap is material. A modern pre - seed strategy must therefore do more than fund ideas. It must compress time - to - traction, mitigate foundational risk, and institutionalise execution from day one . This belief has shaped Eximius Ventures since inception. Over the past four years, we have operated as a dedicated pre - seed fund, backing 32 companies across two funds , with a singular focus on high - ownership, high - conviction company building. As we deploy from Fund II, we see the next wave of value creation emerging in Enterprise AI, Fintech, and Consumertech , sectors where early structure is not optional, but decisive. Pearl Agarwal This report, developed in collaboration with 1Lattice , distills the insights, data, and patterns Founder and that have guided our approach and helped formalise India’s pre - seed playbook. We hope it Managing Partner, serves as a clear, practical resource for founders, LPs, and ecosystem partners navigating the most consequential decisions at the very start of the company - building journey Eximius Ventures India’s startup story has matured. What was once defined by rapid experimentation and Foreword abundant growth capital is now being shaped by sharper fundamentals, clearer paths to monetization, and a deeper bench of repeat founders and experienced operators. In this environment, the pre - seed round has become more than a “first cheque.” It is increasingly the moment when conviction is underwritten – on the team, the problem, and the earliest signals of distribution, product pull, and capital efficiency. Pre - seed investing sits at the intersection of asymmetry and discipline . The opportunity is undeniable: large, underpenetrated markets; accelerating digital adoption; and a growing appetite to build for India and from India for the world. At the same time, the bar has moved. Investors are asking tougher questions than earlier: Why this wedge? Why this founder? What is the learning velocity? Can the company demonstrate credible founder – market fit, a repeatable go - to - market motion, and evidence that customers will pay – sooner than later? This report is our attempt to capture the reality of that shift. It maps how pre - seed in India is evolving – who is writing the first cheques, how rounds are structured, what sectors are attracting differentiated conviction, and what “quality” looks like at the earliest stage. More importantly, it surfaces the patterns that separate noise from signal. We have built this work in collaboration with Eximius Ventures , with a simple intent: to make the pre - seed market more legible. For founders, that means clarity on what investors genuinely optimize for and how to position the opportunity without overfitting to narratives. For investors, it means a sharper lens on sourcing, diligence, and portfolio construction in a market where dispersion is widening and timelines are normalizing. For the ecosystem, it is a chance to move the conversation beyond valuation cycles to the Devmalaya underlying mechanics of building enduring companies. Mukherjee India’s next decade of venture outcomes will be determined in these early, quiet Director, Financial moments — when the product is still raw, the market is still being discovered, and the team is still being formed. Pre - seed is where the trajectory is set. This report is a guide to that Investors inflection point. Executive summary (1/2) Macro momentum: India strengthens its global position • India’s startup ecosystem remains structurally strong, with scale, policy support, and digital adoption creating a durable base for venture formation. • India remains the 3rd largest startup ecosystem globally, with 200,000+ DPIIT - recognized startups. • Global capital has become more selective, but India has still emerged as a relative winner in APAC, helped by capital reallocation and domestic demand depth. Sector leadership: Fintech & Ecommerce anchor stability • Fintech and Ecommerce remain the most resilient funding magnets; Deeptech momentum is improving, while Consumer Services have seen a sharp correction tied to monetization scrutiny. • The next investable wave is being shaped by applied AI infrastructure, embedded finance, climate/mobility, space/defence tech, healthtech rails, and commerce/logistics infrastructure. • PE - VC exits surged in 2024 – 25, with IPOs contributing over 50% of total exit value. Pre - seed & seed: India’s breakout layer • Pre - seed is the only stage growing YoY in 2024 – 25, while other stages remains comparatively volatile. • India’s pre - seed ecosystem has scaled ~3X since 2020, with cheque sizes and institutional participation deepening despite 2023 – 24 funding moderation. • Currently <20% of Indian startups reach series A by Year 4 (vs ~50% in the U.S.A.), highlighting the need for an even stronger pre - seed scaffolding. 4 Executive summary (2/2) Institutional capital: Reshaping India’s early - stage ecosystem • Rise of operator - led, high - conviction funds, driving concentrated ownership and hands - on execution at the inception stage. • Micro - VC participation ~4X since 2021, reflecting rapid capital formation and a maturing pipeline for institutional rounds. • Pre - seed is positioned as the highest alpha zone for investors who can underwrite execution quality early. Policy & regulatory tailwinds: Strengthening early - stage capital • Founder behavior on dilution is pragmatic – most prefer controlled dilution in early rounds and intend to bridge the next round in ~12 - 18 months. • “Investable” startups now signal readiness early: clean cap tables, ESOP pools (5 – 10%), FEMA & Companies Act compliance, MVP/pilot validation, analytics infrastructure, and basic financial hygiene. • Government schemes continue to play a strong catalytic role for early - stage startups (SISFS, CGSS, FFS). Early - stage capital: Asymmetry, exits & depth • Pre - seed delivers highest asymmetry, with potentially >25 – 30X MOIC in strong cycles. • Exits are strengthening, driven by IPOs, SME listings, secondaries, and strategic sales. • Family offices are scaling early - stage exposure, with >300 in India managing ~US$ 30B AUM, and growing allocation to alternatives. • Angels, forming the base of the institutional pipeline, deployed ~US$ 1.7B across ~3.4K deals (2020 – 25). 5 Agenda India as the Global Start - up Epicentre The Indian Pre - seed Opportunity What Does the Future Hold? Investors’ Rulebook to Pre - seed: Preparation, Qualifiers, Thesis, Exits and Regulatory Timelines India as the Global Start - up Epicentre The global ecosystem remains jubilant, boding well for India Key forces driving the global rise of startups Global VCs selectively backing high quality startups across stages Policy support Global VC Funding by Stage • Recent reforms focus on reducing tax & regulatory friction (US$ B) 643 (including angel tax abolition, clearer capital - gains/AIF rules, & simpler compliances), making it easier & cleaner to invest in & operate startups in India. 462 Digital adoption 408 412 • COVID accelerated digital usage by 5 years in 5 months, creating 350 entirely new venture - ready categories: telehealth, edtech, fintech, 314 304 237 remote work infra. 243 153 214 160 Cost efficiency 201 186 • The cost of launching a SaaS product dropped by >90% vs 2000s , 125 124 enabling lean founding teams and faster GTM. AWS, Stripe, and 109 101 SaaS infra democratized entrepreneurship. 30 39 37 35 40 20 2020 2021 2022 2023 2024 2025 Rise of angel & micro - VC class • Individuals with prior exits (especially in U.S.A., SEA, India) entered Angel/Pre-seed Early Growth+Late the market as operator - investors , creating a broader early - capital pipeline beyond institutions. India – 1st ~125 unicorns ~65% global Global talent & remote team architecture Highest in India startup activity • The normalization of remote work has decoupled innovation from number of ranking 3rd concentrated geography, founders tap global talent, enabling ideas from startups in globally after within U.S.A., China, anywhere to service markets everywhere accelerating startup South Asia. U.S.A. and India and U.K.. density worldwide. China. Source(s): Secondary research, 1Lattice analysis 7 India as the Global Start - up Epicentre India stands on the precipice of the global ascension Indian startup ecosystem Startup funding rd 3 Unicorns & soonicorns (#, US$ B, 2020 - 2025) Largest startup (#) 147 e cosystem in 1584 1517 126 the world 116 115 993 953 936 897 th 5 Most exports globally of digital services 200 157 117 82 56 37 st 12 42 25 10 12 11 1 Fastest growing 2020 2021 2022 2023 2024 2025 UHNI population Unicorns Soonicorns # deals Regd. Startups (in K) Funding amount 2024 2025 th 4 India’s position in household consumption US$ 47B US$ 164B+ 2,01,335 373 16.6L FDI inflows No of startups as Number of IPOs Raised by startups Jobs created as of in 2025 of Dec 2025 in 2025 2025 since 2014 Source(s): Secondary research, 1Lattice analysis 8 India as the Global Start - up Epicentre India is also the largest contributor to APAC VC activity growth APAC VC deal activity comparison (US$ B) 90 - 3% - 25% 43% 0% 0% - 47% - 31% CAGR 77 75 65.1 48.9 9.6 13.7 5.1 5.1 3.4 3.4 9.5 5 11 7.6 APAC Greater China* India Japan Aus - NZ Korea Southeast Asia 2023 2024 • Greater China witnessed a sharp decline as regulatory pressures, weak IPO markets, and property - sector stress reduced mega - deals and investor confidence. Key • India saw a strong growth as global investors reallocated capital from China, backed by rising digital adoption, fintech/AI investments, and supportive government initiatives. insights • Japan remained flat with steady flows from corporate and institutional VCs, reflecting its mature, risk - averse market focused on robotics, healthcare, and deep - tech. Note(s): Greater China* This region includes Mainland China, Taiwan, Hong Kong, Macau 9 Source(s): Secondary research, 1Lattice analysis India as the Global Start - up Epicentre Indian PE/VC exits gained momentum in 2024 - 25 with IPOs making up >50% of exits Exits activity is gaining momentum after a dip in FY 22 IPO activity has picked making up >50% of PE/VC exits in 2025 PE/VC exits PE/VC exits by type 36 (US$ B, CY2020 - 2025 ) (%, CY2020 - 2025 ) 33 1% 2% 2% 1% 29 2% 3% 16% 24% 27% 28% 24 31% 44% 22 32% 52% 38% 59% 51% 9 48% 38% 29% 29% 20% 16% 7% 2020 2021 2022 2023 2024 2025 2020 2021 2022 2023 2024 2025 Strategic sale Public/IPO Sponsored to sponsor sale Buyback 213 #Exits 232 334 360 269 212 • In 2025 , the total issue size reached its highest level, recording a significant 3x increase compared to 2023 • The Indian tech sector dominates the IPO market, contributing 48% to all listings. Key insights • Strategic sales also grew as early - stage investors employed them for accessing liquidity for long - term investments. • With the ecosystem moving towards sustainable models, the flashier models of yore face steep valuation discounts in the secondary market Source(s): In - depth interviews, secondary research, 1Lattice analysis 10 India as the Global Start - up Epicentre Decoding the Indian opportunity: The top sectors Fintech and Ecommerce have remained the most stable The top 5 sectors raised ~70% of all the funds in 2025 sectors across the last 2 years Number of deals Funding raised (US$ B) 2024 2025 2024 2025 206 2.5 2.5 203 167 162 1.8 1.8 1.8 1.7 1.5 120 87 82 75 73 65 0.7 0.7 0.7 Ecommerce Fintech Deeptech Enterprise Clean Tech Fintech Enterprise Ecommerce Consumer Healthtech Tech Tech services • As the fintech ecosystem evolved, experienced founders raised higher median cheques in spite of fewer rounds • Deeptech saw a 20% increase in the number of deals due to greater governmental support like the INR 1L Cr. RDI Fund, Key insights and investors looking to back new solutions. • Ecommerce remained stable due to keen customer interest for enhanced buying experiences and deeper curation • Consumer services saw a 61% decline in funding as investors looked for proofs of steady monetization before scale. Source(s): In - depth interviews, secondary research, 1Lattice analysis 11 India as the Global Start - up Epicentre Decoding the Indian opportunity: Tailwinds Applied & infrastructure AI • US$ 1.1B (₹ 10,300 Cr) India AI Mission and government - backed GPU Health tech cluster (10,000+ GPUs) are lowering compute barriers and enabling scalable AI infrastructure. • The Ayushman Bharat Digital Mission (ABDM) has issued • Growing demand for edge - AI chips, accelerator cards, and energy - 80+ crore ABHA IDs and linked 67 crore health records, efficient AI servers is creating a strong ecosystem for AI - native creating digital rails for care delivery hardware & infrastructure. • Whitespace exists in Revenue Cycle Management (RCM) automation, OPD digitization, and lab logistics , Fintech & embedded finance creating efficiency gains for mid - tier hospitals and clinics. • UPI processing over 700 M transactions daily , which highlights the opportunity for new SaaS platforms embedding financial features like payments, lending, and payouts. Commerce infrastructure & logistics • Supported by RBI’s regulatory clarity and digital public infrastructure • India’s logistics market stood at US$ 350B in 2025 & is (India Stack, AA framework), embedded finance offers defensible and projected to reach US$ 360B by 2030 at 7.7% CAGR , scalable models. driven by e - commerce & supply - chain digitization. • Logistics costs remain 13 – 14% of GDP , the National Space & defence tech Logistics Policy and ULI framework aim to cut costs and • India’s private space sector is gaining traction with Agnikul’s 2024 improve multimodal connectivity. launch and Pixxel’s US$ 141M (₹1,200 Cr) IN - SPACe PPP validating the commercial readiness. Consumer tech • The sector benefits from policy liberalization under IN - SPACe and increased defence R&D spending (US$ 11.7B, ₹1L Cr+ annually). • India’s consumer - tech market including consumer electronics, e - commerce, and digital devices is on a steep growth trajectory. Climate & mobility • The consumer - electronics market alone was estimated • India’s commercial power demand is rising 8 – 9% annually; grid at ~US$ 90B in 2025 and is projected to grow to reliability challenges create room for microgrid software. ~US$ 160B by 2030 , at a CAGR of ~6.56% (2026 - 2030). • Government incentives (FAME - II, PLI) & corporate net - zero mandates are accelerating demand for EV software, charging, and battery lifecycle solutions Source(s): In - depth interviews, secondary research, 1Lattice analysis 12 India as the Global Start - up Epicentre Decoding the Indian opportunity: The top stages Funding raised (US$ B) 32 14 8.1 7.4 7 6 5.7 4 3.2 2.9 2.4 1.1 0.9 0.7 0.8 2021 2022 2023 2024 2025 Seed stage Growth stage Late stage • Late - stage in India remains highly volatile with a 77% coefficient of variation over the last 5 years. • Growth - stage has also seen a ~50% decline compared to the peak of 2021 indicating heightened mortality. Key insights • With a median deal size of US$ 3M , the ecosystem is stabilizing around thesis - driven bets by investors, rather than optimistic mega deals. • With 5.8K deals in rounds under US$ 5M , investors are focussing on finding the right founders as early as possible. Source(s): In - depth interviews, Secondary research, 1Lattice analysis 13 India as the Global Start - up Epicentre The Indian pre - seed ecosystem has grown to 3X since 2020 Historical pre - seed/seed funding activity – by country (US$ B) U.S.A. SEA India 7,374 6,994 483 6,721 461 404 5,312 5,283 388 387 4,981 376 365 307 316 259 196 166 0.2 0.7 1.2 0.7 0.5 0.3 0.5 0.9 1.2 0.7 0.8 1.5 11.8 18.6 25.5 16.1 16.3 20.3 2020 2021 2022 2023 2024 2025 2020 2021 2022 2023 2024 2025 2020 2021 2022 2023 2024 2025 Key insights Key insights Key insights U.S.A.’s pre - seed/seed funding has gained India’s pre - seed/seed funding grew steadily till SEA’s pre - see/seed investing is going through a momentum post a dip since 2022 due to rising 2022, slowed in 2023 – 24 due to funding structural recalibration. Investors’ appetite for rates and valuation corrections. Investors are also challenges, and bounced back strongly in 2025 new, risky early - stage bets has reduced due to low gaining more conviction with the AI boom. with fresh investments and strong local demand. Distributed Paid - In Capital (DPI). 14 Source(s): Secondary research, 1Lattice analysis India as the Global Start - up Epicentre Decoding the Indian opportunity: Pre - seed is the most resolute stage Number of deals 431 409 268 219 152 143 137 108 99 101 Seed Series A Pre-series A Series B Pre-seed 2024 2025 • Pre - seed is the only of the top 5 deal stages to grow on a YoY basis in the 2024 - 25 period. • Series A and subsequent growth stages have seen a sharp fall caused by higher mortality and a more rigid emphasis on Key insights sustainability. • In spite of a 5% drop, seed has remained relatively stable indicating persistent investor confidence in new founders. Source(s): In - depth interviews, secondary research, 1Lattice analysis 15 Agenda India as the Global Start - up Epicentre The Indian Pre - seed Opportunity What Does the Future Hold? Investors’ Rulebook to Pre - seed: Preparation, Qualifiers, Thesis, Exits and Regulatory Timelines The Indian Pre - seed Opportunity What is pre - seed and its role? • A founder’s journey starts as soon as they [The First Cheque] spot an opportunity. Pre - seed Pre - seed marks the first juncture of a • Early discussions with potential investors • Typically, the earliest founder’s journey where, after building can strengthen thinking and confidence. investment stage with confidence on their thesis, they seek smaller capital injections. external capital to initiate building. • These conversations also reveal how the • Focuses on team market is likely to view the opportunity. formation, MVP and • Founders should deeply [Early Market Launchpad] business model validation. research the market to refine This stage funds the early team, • Involves friends, family, positioning. product trials, and go - to - market angel investors, and pre - efforts before any real revenue seed VCs. • They must map the What traction. competitive landscape. • Commences with an idea When to and belief. • They should then define is pre - raise a clear differentiation. [Institutional Support] Founders at this stage also need Seed pre - seed? seed? • The idea and its contours considerable external support for define the destination. navigating early - stage woes including • Larger capital infusions to hiring, creating GTM strategies, etc. • A roadmap is needed to set scale operations and the action plan and estimate expand. startup funding needs • Emphasis on growth, customer acquisition and [Bridge to Seed Stage] • In an early - stage company, the team is monetization. A successful pre - seed builds investor the most critical factor. • Attracts VCs, corporate confidence which is crucial for ventures, and institutional raising subsequent rounds. • Building the founding team requires investors. clear definition of founders’ roles, • Commences with traction. functions, and key early hires. Source(s): In - depth interviews, secondary research, 1Lattice analysis 17 The Indian Pre - seed Opportunity A successful pre - seed helps founders grow at their desired pace Bridging the “prototype Strategic dilution Laying the groundwork for Accelerating early Helps the company with to validation" gap the next round market entry its initial team management • Investors validate founders’ • A vote of confidence from pre - • Pre - seed funding helps • A pre - seed cheque also • Enables founders to raise ideas, and help them seed investors goes a long way founders initiate GTM plans serves as validation for smaller rounds with minimal strengthen their thesis as in convincing later entrants of prospective employees and equity dilution, retaining to test their products faster. they look to build. boosts the company’s majority ownership. a company’s merit. • Early exposure enables prospects for hiring. • They also help founders in • Pre - seed investors also work quicker feedback loops and • Establishes a strong base for drawing broader roadmaps closely with founders for future sharper interaction while • A select few funds also help attracting future and the key milestones fund - raises by sharing key founders with sourcing and institutional investors. searching for PMF. target as they scale. milestones and forming the screening new candidates. right connections. For our business, pre - seed funding was critical not for the launch, but for Pre - seed funding was critical for us it was the fuel that got our engine started. In fintech, you can’t go live without upfront capital, as scaling. While we bootstrapped with my own salary to ensure profitability compliance, regulatory approvals, and multiple external APIs all come first, investor capital allowed us to expand into new verticals like QSR carts, invest in R&D and marketing, and experiment at speed. It gave us the at a cost. It helped us survive the 4 – 5 month compliance phase, cover Industry power to play a bigger game and accelerate growth beyond what API expenses, build operations, and assemble a small team. Without it, bootstrapping alone could achieve. launching and scaling in this space would not have been possible. speak - Founder, Fintech company - Founder, Foodtech business Source(s): In - depth interviews, secondary research, 1Lattice analysis 18 The Indian Pre - seed Opportunity Survey: How do seed investors view pre - seed? Seed investors perception towards founders (%, N = 22) What risks does pre - seed mitigate? Feel that pre-seed validates the company and the founder Founder Execution Institutional 22% risk risk backing Feel that pre-seed adds institutional support which is vital Seed investors look at Since pre - seed helps Being supported by an 9% pre - seed to assess the founders in garnering initial institution gives founders 55% Feel that pre-seed lets founders founders’ hunger to traction and move towards access to bespoke prove traction execute, but also to PMF, it enables founders to networks and strategic 14% convey a compelling showcase their execution inputs, this is a good story. nous for later investors. support for their further Don't feel that a pre-seed is trajectory. distinctively valueable It definitely means that we track the company A successful pre - seed is a positive filter There are certain segments - like fintech more closely. If it was a company that we for us when looking at the broader infra - where partnerships are critical for earlier passed, we would want to revisit and market of startups, as it showcases the any startup to do well. Pre - seed helps see why that successful pre - seed round value in the vision, and the founder’s companies in leveraging their VCs’ happened. It shows that there is confidence in ability to tell a compelling story. Pre - connections to establish themselves and Industry the model to work, and they have certain seed helps us identify the right gain an advantage against the speak capital to prove out certain things. opportunities in the market. competition. - Indian Multi - stage Investor - Global VC Fund - Foreign VC Fund Source(s): In - depth interviews, secondary research, 1Lattice analysis 19 The Indian Pre - seed Opportunity The market still lacks dedicated pre - seed funds which hinders founders Gap theme Problem statement Insight In spite of ample funds, stage differentiation is yet Information & Early founders struggle to understand how to approach the to be positioned clearly. Pre - seed funds must access asymmetry right funds, and the key prerequisites. convey their theses clearly for a broad audience. Founders don’t just need cheques, but they also need hands - on While mediums for capital like accelerators exist, Lack of institutional GTM, hiring, and compliance help, but most pre - seed funds institutional funds must build comprehensive support beyond capital operate as “light touch investors.” capabilities for companies beyond capital. Founders need clarity on the milestones that specific later - stage Funds need to work closely with founders to help Fundraising ambiguity investors need. They need investors who can guide them as they them understand what other investors want and build their roadmap for future rounds. connect them whenever the founder is ready. Industry speak When I started my first startup in 2012, funding was Raising our first round was tough because Our biggest pre - seed challenge was driven by pedigree and networks, making it hard for a most VCs prefer fast - return tech models, while finding a lead investor willing to price the B.Tech dropout from Bihar to access investors or formal our NBFC model needs patient capital and a round. Even with strong interest from capital. With limited support and strict documentation longer return cycle. Realizing this mismatch, multiple investors and a highly requirements, I relied on my mother’s savings and part - we focused on family offices and individual experienced founding team, very few were time work, raising just US$ 12K (₹10L) informally. investors aligned with our long - term vision. ready to anchor the valuation. - Founder, Food and Beverages - Founder, NBFC - Co - Founder, Beauty and Personal Care Source(s): In - depth interviews, secondary research, 1Lattice analysis 20 Emerging Pre The Indian Pre - - seed Opportunity and Landscape seed Opportunity As a result, by year 4, ~50% of U.S.A. startups raise series A, compared to <20% in India U.S.A. startup graduation rate from seed to series A India startup graduation rate from seed to series A Seed round Seed round Year 1 Year 2 Year 3 Year 4 Year 1 Year 2 Year 3 Year 4 year year 2019 13.0% 29.0% 42.0% 50.0% 2019 1.4% 5.2% 11.6% 17.3% 2020 13.5% 31.0% 44.0% 49.0% 2020 1.2% 7.9% 13.9% 17.4% 2021 9.0% 20.0% 27.0% 33.0% 2021 1.1% 6.2% 9.7% 12.6% 2022 7.5% 13.0% 20.0% 2022 0.7% 3.0% 6.5% 2023 5.0% 10.0% 2023 0.5% 2.4% 2024 8.0% 2024 0.9% Time since seed fundraise Time since seed fundraise • A successful pre - seed enables a company to hire well , test multiple GTM options, and find PMF - all of which are critical factors for reducing early - stage mortality. Key insights • Specialised pre - seed investors not only tend to participate actively in future rounds, but also acquaint the founders with new investors , and inspire their conviction as well. Source(s): Secondary research, 1Lattice analysis 21 The Indian Pre - seed Opportunity Survey: How are founders benefitted by pre - seed? Top 5 factors that helped at pre - seed What benefits do founders associate with pre - seed? (%, N=14) Buying time and focus 71% Buying Operator Establishing Strategic Product Operator guidance/Mentorship 68% time and guidance and operational hiring validation & focus mentorship structure quality Operational structure 66% The leading Founders highly Capital helped Specifically for Using the raise Strategic hiring 64% benefit was the valued strategic unlock internal product, to deepen ability to reduce advice from systems, engineering, product - market Product validation/quality 57% stress and move mentors over cadence, and and early fit before deliberately the capital itself. accountability. operations expanding too toward PMF. roles. broadly. At the very beginning, we chose advisors At the pre - seed stage round our very first Giving up a measured stake early to bring in and angels who brought far more than investor felt like a best friend supporting us aligned institutional partners helped us avoid capital. They opened doors to early through early connects, mentorship, and even costlier mistakes later, especially in hiring, enterprise conversations, helped us shared spaces. As founders, we value an GTM focus, and governance setup. In Industry navigate initial GTM decisions, and truly investor who isn’t in a hurry to exit but believes hindsight, the pre - seed capital improved our understood our product and philosophy in growing with us. That kind of long - term trajectory enough that it likely protected speak making those first official funding round alignment is rare, and it’s what makes this value over time, even if we diluted earlier more focused and strategic. partnership special. than we initially wanted. - Founder, AI - tech company - Founder, BPC company - Founder, AI - SaaS platform Source(s): In - depth interviews, secondary research, 1Lattice analysis 22 The Indian Pre - seed Opportunity What do pre - seed founders look for when diluting? Equity dilution in pre - seed rounds Key considerations for founders during (%, N = 20) pre - seed equity dilution Dilution Strategic Valuation control investors trade - off A balanced mix Focus on Lower valuation of equity and partners who may be debt ensures contribute accepted to capital inflow networks, secure strong without giving mentorship, and investors and up unnecessary credibility long - term ownership. alongside market access. capital. 0-5% 5-10% 10-20% At pre - seed, dilution isn’t just about the We optimized dilution by structuring the We parted with ~15% equity in our pre - percentage of equity, it’s about balancing round at a pre - money valuation, allowing seed. The tradeoff was clear equity ownership with strategic value. Founders weigh flexibility to add capital over time. Rather means little without revenue, and fintech whether to mix equity with debt, choose investors than raising a large round upfront, we demands upfront capital to get started. Industry who bring networks and mentorship, accept strategically raised smaller tranches, While mindful of avoiding over - dilution, trade - offs on valuation for long - term growth, and preserved cash, and built momentum. we prioritized growth and chose speak protect control over IP and governance. The goal This approach minimized early dilution investors whose conviction and support is to raise just enough to prove the model, while while keeping room for future raises at mattered as much as the capital itself. preserving flexibility for future rounds. stronger valuations. - Founder, Foodtech business - Founder, BPC brand - Founder, Fintech company Source(s): In Source(s): In - - depth interviews, secondary research, 1Lattice analysis depth interviews, secondary research, 1Lattice analysis 23 The Indian Pre - seed Opportunity What time - gap do pre - seed founders want? Founders' checklist before raising the Expected time gap before raising next round (%, N = 20) next round after an early round Compliance Runway Validation completion Planning & traction • Finalize statutory filings, • Allocate funds • Build a capable core team tax obligations, and strategically to core and establish critical regulatory approval. business priorities. infrastructure. • Maintain organized • Forecast operating • Present early commercial documentation for expenses and align with results through investor due diligence. projected revenues. measurable KPIs. • Engage legal and financial • Maintain a buffer to • Run controlled advisors to avoid prevent premature experiments to showcase 0-6 Months 6-12 Months 12-18 Months 18+ Months compliance gaps. fundraising pressure. product - market signals. Raising a pre - seed within six months is The gap between our pre - seed and seed round We closed our pre - seed in September last reasonable, as this stage is now relatively was around 8 – 10 months. We planned this year, and about 12 months later we’re now in accessible. Subsequent rounds may take carefully by raising small, preserving cash, and the market for our next raise. For us, that one to two years, depending on the channeling our efforts toward validation. The means having 15 – 16 months of runway, Industry stage. Once the pre - seed is closed, pre - seed allowed us to build a strong core showing strong growth, and capitalizing on completing compliances thoroughly is team, establish the basic infrastructure, and momentum. Unlike the story - driven pre - seed, speak crucial. An initial raise also builds run targeted experiments that not only proved this round is anchored in real numbers loan credibility, making it easier for investors commercial traction but also strengthened our disbursals, revenue, and a clear path to to trust and support future rounds. readiness for the next round. scaling 10x. - Founder, BPC brand - Founder, Gaming platform - Founder, Fintech company Source(s): In Source(s): In Source(s): In - - - depth interviews, secondary research, 1Lattice analysis depth interviews, secondary research, 1Lattice analysis depth interviews, secondary research, 1Lattice analysis 24 The Indian Pre - seed Opportunity Case Study: 30 Sundays Funding summary • 30 Sundays is creating hyper - personalised travel packages, replacing offline agents with an agentic concierge by managing Pre - seed Seed Pre - series A Series A curated supply and transparent US$ 0.2M raised US$ 0.5M raised US$ 1.2M raised US$ 6M raised pricing with a luxury experience. July 2023 November 2023 July 2025 February 2026 • The company was founded in 2023 by Anuj Punjani and Kshitij Undisclosed Chaudhary, seasoned operators in marquee investor the travel and AI spaces. Fine - tune positioning Team building Outcome Post their pre - seed, 30 Sundays A successful round also boosted the 30 Sundays have enjoyed a were able to experiment heavily to company’s prestige which helped them stellar funding journey by How did hone in the exact vertical they recruit top - talent for a nascent company. raising 4 rounds so far from wanted to build in. eminent investors. During the course of their journey, they pre - seed have also doubled their revenue Validating the market Positioning for later rounds every quarter. Therefore, pre - help? seed journey helped create a 30 Sundays also iterated on their As noted earlier, larger funds view a great model with sustainable GTM strategy using the funding to successful raise as a positive signal. This economics. validate the market’s depth and the helped 30 Sundays garner interest in merit of their positioning. their future rounds. Source(s): In - depth interviews, secondary research, 1Lattice analysis 25 Agenda India as the Global Start - up Epicentre The Indian Pre - seed Opportunity What Does the Future Hold? Investors’ Rulebook to Pre - seed: Preparation, Qualifiers, Thesis, Exits and Regulatory Timelines What Does The Future Hold? Emerging pre - seed opportunity India’s pre - seed playbook is being rewritten: startups are moving beyond metros, sharper on unit economics and are increasingly led by proven repeat founders Rise of 2nd time founders – more The "Unit economics Democratization via tier funding w.r.t the whole system II & III cities first" pre - seed • Second - time founders remove early - stage uncertainty, enabling bigger cheques seen in their $1.2 Mn median seed round (144% above market). • Their stronger networks and faster validation cycles make them more fundable reflected in 45% of seed - funded founders being repeat founders. Average & median seed rounds (US$M) 144% 2.61 Median Average Entrepreneurship is no longer a ‘metro - only’ The era of "burn to learn" is over. Even at the phenomenon: pre - seed stage (where revenue is often zero), investors now demand: • As of early 2026, 50% of DPIIT - recognized startups 1.2 originate from outside Tier I hubs • High “trust - by - design": Early compliance (Bengaluru/Delhi/Mumbai). with data privacy and security. 0.49 • Localized Innovation: Expect a surge in pre - seed • Path to monetization: A clear blueprint for ventures solving vernacular education, rural reaching series A without $50Mn in burn. All founders Companies with one or more fintech, and localized manufacturing - as - a - service. second time founder Source(s): Secondary research, 1Lattice analysis 27 What Does the Future Hold? In the light of these, established funds are launching pre - seed programs Category Antler Residency Axilor Labs DeVC – Z47 Peak XV Surge Accel Atoms About An early - stage venture A seed - stage platform for Accel India’s pre - seed A residency program run A venture curation collective investing from company builders, program to support founders by Antler to help founders program by Axilor idea to early traction, backed designed to help founders in validating and scaling early build companies from Ventures tailored for IP - by a global community of launch and build enduring ideas. scratch. led and research - driven. founders and operators. startups. Provides up to US$ 3M in Provides up to US$ 2M in Invests up to US$ 500K Offering Provides curated Founders receive US$ 250K in seed funding, along with funding, structured mentorship along with hands - on mentorship , team - building pre - seed funding with a hands - on support from Accel partners and support across product, support, and seed funding commitment of another US$ including mentorship, portfolio founders, and access to GTM, hiring, and strategy tailored to help scientists 250K in next 9 - 12 months , community access, and global experts, product support, without fixed cohorts. translate their inventions. expert guidance, and access help raising the next round. and founder community. to Antler’s investor network. Focus Guiding founders through Startups at the idea or pre - Early - stage entrepreneurs Researchers are seeking to Primarily backs pre - seed PMF, GTM, hiring, growth seed stage across sectors. looking to form teams and convert deep science, and seed - stage tech strategy and long - term validate ideas. especially in health and startups, with a strong foundation building. longevity. emphasis on founder quality and execution. Cohort Source(s): Secondary research, 1Lattice analysis 28 What Does the Future Hold? The rise of domestic Indian funds Domestic capital is now the primary stabilizer of the Indian startup ecosystem, which has led to the inception of new investor categories with focused pre - seed funds and micro - VCs leading the charge. The AIF (Alternative Corporate venture Capital The micro - VC Investment Fund) boom (CVC) & accelerators revolution The “funding vacuum” left by Domestic institutional India’s largest conglomerates (Reliance, retreating global giants in 2024 - interest in startups has Tata, Mahindra) and global tech giants 25 has been filled by a new breed reached record highs. (Google/Accel via the Atoms program) of micro - VCs and solo GPs. are moving “down - funnel. SIP - to - startup pipeline Market access Speed is the moat Retail capital flowing into Mutual Domestic funds now offer “Market These funds are designed for high - Funds is being partially diverted into Access Programs” as a standard part of velocity, high - conviction “first Category I & II AIFs that target early - pre - seed deals - connecting startups cheques” (typically US$ 200K to $1M). stage tech. directly to their first 10 enterprise clients. Operator - led Regulatory support Strategic alignment Many are led by “ex - unicorn” founders The abolition of the “Angel Tax” and Programs like India Ascends 2026 who bring tactical GTM (Go - to - Market) SEBI’s streamlined accreditation for (Lightspeed) and Elevate DeepTech playbooks rather than just capital. high - net - worth individuals (HNIs) (Karnataka govt.) provide pre - seed have unlocked billions in local capital. grants and equity to align with national self - reliance goals. 02 03 01 Source(s): In Source(s): In - - depth interviews, secondary research, 1Lattice analysis depth interviews, secondary research, 1Lattice analysis 29 What Does the Future Hold? Types of pre - seed funds: angels, micro - VCs, & accelerators analyzed across metrics Accelerators & Investor archetype Angels Micro VC Family offices Friends and family incubators Usually former operators, Micro - VCs are dedicated These institutions run Private investment firms Kin and close peers of the angels invest in start - ups in a funds for early - stages that structured programs to up - that invest in start - ups founder who usually personal capacity or through combine a thesis - led skill founders and give strategically and take a participate to support About concentrated syndicates to approach with the them an ecosystem to patient and portfolio - them, without many help new founders. nimbleness of angels. learn from. They often also oriented approach. barriers to investment. invest in select companies. Angels tend to mitigate ‘error Typically thesis - led, micro They aim to boost the Family offices undertake They usually invest without of omission’ by investing in a VCs prefer to take more founders’ prospects more selective disbursal, much due - diligence and, broad coterie of companies concentrated bets and through their curricula and and offer founders patient instead, underwrite solely Philosophy across various sectors. help them closely as they take more measured bets capital through non - on the basis of their grow in subsequent stages. in some of the star standardized processes. relation with the founders. performers. Angles focus extensively on As specialised funds, they Their real value lies in the Typically undertake a Due to their non fast disbursement. They also aid extensively in GTM, community they engender. hands - off approach to specialised nature, friends aid in founder mentoring, and hiring, strategic inputs, etc. However, they lack portfolio management, but and family don’t specifically Portfolio add opening up their personal Specific aid is also provided dedicated arms for do facilitate industry contribute post fund - raise, on networks for their portfolio. in fundraising with them portfolio support and connections, and strategic except in emotional also participating. usually don’t participate in follow - on participation. support. future rounds. Example Source(s): Secondary research, 1Lattice analysis 30 What Does the Future Hold? Micro VCs and dedicated pre - seed funds take shape as domestic investors up exposure Micro VCs vs dedicated pre - seed funds: A clear distinction Category Micro VCs Dedicated pre - seed funds Fund size ₹50 crore to ₹250 – 300 crore ₹75 crore to ₹200 crore (deliberately constrained) Stage focus Pre - seed, seed, and selective early series A Exclusively pre - seed (idea → first product → early GTM) Broader portfolios with stage flexibility Highly selective, lower company count Portfolio strategy Minority ownership; dilution across rounds is expected Concentrated ownership at entry (often 8 – 15%) Ownership approach Often single - GP or lean teams; theme - or sector - driven Hands - on, operator - led, deeply involved in 0 – 1 execution Operating model Portfolio - driven returns with reliance on follow - on rounds and later - Outcomes driven by early ownership discipline, not valuation inflation Return profile stage exits Access to early capital, sector insight, founder backing Company building — PMF, GTM design, hiring, governance readiness Primary value - add Micro VCs expand the innovation funnel by validating more ideas Dedicated pre - seed funds are structured to solve the hardest inception early and providing founders their first institutional cheque, while risks and to position companies cleanly for seed and series A, benefiting maintaining optionality to follow winners into later stages. from a strong and liquid later - stage capital pipeline, which makes exits and mark - ups structurally easier if early fundamentals are right. For LPs: Pre - seed funds behave For founders: The choice is For the ecosystem: Micro VCs Why the distinction more like concentrated conviction between capital access (micro VC) widen the top of the funnel; vehicles, while micro VCs are and deep execution partnership dedicated pre - seed funds matters diversified early - stage allocators. (pre - seed fund). sharpen quality and readiness downstream. Source(s): In - depth interviews, secondary research, 1Lattice analysis 31 Agenda India as the Global Start - up Epicentre The Indian Pre - seed Opportunity What Does the Future Hold? Investors’ Rulebook to Pre - seed: Preparation, Qualifiers, Thesis, Exits and Regulatory Timelines Pre - seed Investment Overview Framework for institutional pre - seed investing Decoding the shift from gut - led early bets to structured conviction: how pre - seed investing is institutionalizing in India Why pre - seed matters? • Pre - seed is the new alpha Pre - seed frontier of venture investing, it’s Define a focused Capital planning & Measurement where conviction, not capital success starts investment thesis portfolio design infrastructure drives outcomes. with structured Define clear Structure check sizes, Track founder behavior investment themes pacing, and follow - on and execution patterns • Institutional money at pre - seed and founder strategy upfront to from day zero to build preparation! is still limited, creating a window archetypes aligned ensure disciplined, deeper judgment for where informed investors can with emerging flexible deployment in future investments. capture outsized value. market shifts. uncertain early markets. Incorporation as a Private Limited A functional MVP or prototype Basic data - room preparedness Company with a clean, fully diluted with measurable user engagement with corporate, legal, and product What makes a cap table , clear founder equity splits, or pilot validation metrics (e.g., documentation. Early adoption of IP assignment agreements , and a cohort retention, activation rate). financial hygiene (single business startup pre - structured ESOP pool (5 – 10%) Clarity on technical IP ownership account, basic MIS, GST ‘investable’ at Early compliance with FEMA and and early use of analytics compliance) and investor Companies Act norms signals infrastructure ( Mixpanel , GA, reporting cadence (monthly or pre - seed? governance maturity. Amplitude) demonstrate execution quarterly) indicates institutional depth. readiness. Source(s): Secondary research, 1Lattice analysis 33 Investors’ Contribution Investors value - add beyond capital Advisory support Strategic introductions Investors keep founders informed with Investors open doors to VCs, co - selling regular insights on market trends, partners, and industry stakeholders, competitor, and new growth opportunities. accelerating business growth. Credibility & branding Operational mentorship Association with reputed investors Experienced investors guide founders gives legitimacy, boosts brand trust, on scaling, partnerships, and and helps attract top talent. navigating tough business phases. Sectoral validation Active operational involvement Angels or domain experts bring industry - Investors also step into roles like CXOs or specific knowledge, enhancing product advisors, directly contributing to daily relevance and positioning. operations of the business. Governance & compliance rigor Ecosystem support The right investors instill strong frameworks From offering office spaces to and reporting practices, making the structured connects, investors create business resilient and future - ready. an ecosystem that nurtures growth. 34 Source(s): In - depth interviews, secondary research, 1Lattice analysis What the Ecosystem Has to Say About Pre - seed Testimonials from Investors & Founders Industry Speak Beyond capital, we support startups by offering strategic Broadly, our support works in two ways. While we Our investors have gone far beyond financial support guidance to refine their direction and decision - making. were earlier very hands - on, we realized the best by providing constant feedback on market trends, We help expand networks through introductions to founders learn fastest on their own. Today, we competitor movements, and partnership industry professionals, potential partners, and relevant focus on creating value through connections and opportunities. They have also played an active role in stakeholders. Additionally, we create business cross - portfolio synergies, while also guiding making strategic introductions to other VCs for development opportunities, either within our own group founders by highlighting blind spots and upcoming rounds and to potential co - selling partners or by leveraging wider ecosystem connections, ensuring suggesting areas they should explore to ensuring we stay aligned with market dynamics founders have both guidance and opportunities to scale. strengthen their journey. while accelerating growth. - Investor, Family office - Investor, Venture capital firm - Founder, AI - tech company Our investor initially invested US$1M, with a further I brought in Shark Tank investors who offered much As a pre - seed investor, my focus goes beyond commitment of up to US$ 2M. At 25, I had the more than capital that is market validation, capital deployment. We ensure rapid fund privilege of closing the largest funding round in the mentorship from entrepreneurs who had scaled to disbursement typically within 2 – 3 weeks and Indian co - living industry. When I asked the investor hundreds of crores, and networks that opened doors support founders in achieving product - market fit why he chose to back us, he said, “Your passion and to prime locations. Their collective guidance aligned through hands - on involvement from our venture clarity of vision were evident you knew exactly what with our vision of building a ~US$ 588M (₹5,000 Cr) partners, and actively guide the fundraising journey had to be done. All I needed to do was provide the business while driving entrepreneurship and by refining pitches and connecting the team with capital. employment in underserved regions like Bihar. relevant VCs for the next round. - Founder, Co - living company - Founder, Foodtech business - Investor, Venture capital firm 35 Source(s): In - depth interviews, 1Lattice analysis Government Startups’ Schemes and Initiatives Government’s startup funding schemes also play a major role - reassuring intent to boost entrepreneurship Government schemes SISFS CGSS FFS Startup India Seed Fund Scheme Credit Guarantee Scheme for Startups Fund of Funds for Startups Scheme Launched in 2021 – 22 with a US$ 111M ( ₹945 Cr) The scheme extends credit guarantees for Launched in June 2016 with a US$1.1B corpus for a four - year term , the SISFS provides loans granted to DPIIT - recognized startups by (₹10,000 Cr) corpus , the Fund of Funds for early - stage funding to startups for proof of Scheduled Commercial Banks, NBFCs , and Startups seeks to expand access to domestic concept, prototype development, product Venture Debt Funds under SEBI - registered capital for Indian startups and strengthen the testing, market launch, and Alternative Investment Funds. entrepreneurial ecosystem. commercialization. Administered by the National Credit Managed by SIDBI , the scheme does not The scheme has been operational since 1 April Guarantee Trustee Company Limited directly invest in startups; instead, it channels 2021 and is administered by the Experts (NCGTC) , it provides guarantees up to a funding to SEBI - registered Alternative Advisory Committee (EAC) , which reviews defined limit for eligible startups. Investment Funds (AIFs) , which subsequently and selects incubators for fund disbursement. invest in startups through equity and equity - linked instruments. US$ 62.5M US$ 82.1M US$ 2.7B approved loan investments 3,199 startups 311 startups 1,334 selected startups Source(s): Secondary research, 1Lattice analysis 36 Risk & Return Funding Matrix A lucrative risk - return index makes pre - seed particularly enticing for new investors Funding Risk Return Risk vs return across funding stages (#) stage characteristic potential 12 Strongest upside High volatility due to potential from • Pre - seed Early stage limited product early entry and validation and (pre - seed to • Seed compounding 10 dependency on pre series A) Growth stage (series A growth • Pre - series A founder execution. to series C) opportunity. 8 Attractive returns Growth Scaling risk emerges Early stage (pre - seed driven by market despite commercial stage to pre - series A) expansion and • Series A validation and (series A to business model 6 operational traction. series C) leverage. Late & Pre - IPO • Series B stage Core business is Moderate return • Series C 4 validated; risk shifts profile with Late stage to capital efficiency increased visibility (post - series D) and market into outcomes • Series D conditions. and liquidity. 2 Compressed • Pre - IPO Minimal operational returns but risk; exposure Pre - IPO higher certainty concentrated in exit 0 around exit stage timing and valuation 0 2 4 6 8 10 events and capital shifts. recycling. Risk (Higher - > More Risk) Source(s): In - depth interviews, s econdary research, 1Lattice analysis 37 Typical Exit Routes Exit are usually shaped by stronger governance, pricing discipline, and deal readiness Exit route Typical timing & size (India) Return dynamics (indicative MOIC) Key considerations Public - market exits accelerated in 2024 – 2025, High potential MOIC for early investors in favourable Requires clear visibility to profitability, governance accounting for ~45 - 55% of total exit value, market cycles; exceptional outcomes may exceed ~25 – maturity, and a credible growth narrative. Valuation supported by strong issuance and block trades. 30 × for pre - seed entries, though dispersion is wide and and liquidity risk rise sharply if market sentiment Mainboard IPO Mainboard tech listings generally become timing - sensitive. weakens. (NSE/BSE) feasible at ~US$ 120 – 300M+ market cap once companies are profitable or approaching profitability. 2024 – 2025 saw elevated listing gains (often 50 – Enables fast MOIC realisation for early investors, Low float, limited research coverage, and liquidity 90% at listing). Gains are expected to moderate especially for small cheque sizes. However, post - listing constraints. New norms improve quality but reduce SME IPO (NSE in 2026 due to tighter SEBI norms, profitability performance is mixed and gains often compress post - hype - driven momentum. Emerge / BSE SME) filters, and higher volatility. listing. Early angel secondaries typically occur below Angels often realise ~5 - 10 × ; seed / micro - VCs entering Useful for DPI improvement and risk diversification. ~US$50 – 75M valuations; institutional secondaries at US$ 10 - 40M valuations may see 5 - 10 × . Outcomes Pricing influenced by buyer Secondary become more common from ~US$ 75M to depend heavily on entry price and round momentum. quality, round dynamics, and seller signalling. sale (partial) US$1B+. Most Indian tech M&A exits cluster in the ~US$ At US$ 10 – 50M EV, seed outcomes are often ~3 – 5 × ; at Faster liquidity versus IPOs, but earn - outs, integration 10 – 500M enterprise - value range; >US$ 500M US$ 50 – 500M EV, strong assets may deliver 5 – 10 × risk, and structure complexity can dilute realised Strategic transactions remain relatively rare. Acqui - hire outcomes are typically <2 × MOIC. M&A / Trade sale Share of block - trade exits increased post - listing MOIC linked to public - market performance; enables Liquidity depends on market depth, lock - ups, Block trades / in 2024 – 2025 as funds pursued staged liquidity. programmatic DPI over time rather than reliance on a and regulatory windows; execution timing is critical. public market single liquidity event. sell - downs 38 Source(s): In - depth interviews, secondary research, 1Lattice analysis Family Offices Impact (1/2) Family offices – The new but significant capital coming at pre - seed Family offices in India are projected to see 14% AUM growth and a 5% rise in alternative investments within 3 years No. of family offices AUM of family offices Key reasons for establishing a family office (2025) (2025) Holistic wealth Customized solutions management extending GLOBALLY GLOBALLY 20,000+ US$ 6T aligned with family beyond conventional values and goals. advisory services. Structured approach for Cross - border tax and INDIA INDIA 300+ US$ 30B intergenerational wealth compliance expertise for preservation. global assets. FAMILY OFFICE TYPES AUM of leading family offices Single family office Multi family office US$ US$ US$ US$ 500M+ 15B+ 1B+ 1B+ Embedded family office Source(s): Secondary research, 1Lattice analysis Source(s): Secondary research, 1Lattice analysis 39 Family Offices Impact (2/2) Family offices powering the startup boom in India Harsh Sanjay Mehta Mariwala Azim Premji Sanjay Mehta Sanjay Mehta Sanjay Mehta Rehana Nathoo Sanjay Mehta Sanjay Mehta Ketan Kothari Founder , Sharrp Co - founder and Managing Founder, Premji Co - founder and Managing Co Co - - founder and Managing founder and Managing Founder and CEO, Co - founder and Managing Co Founder: Aarii - founder and Managing Ventures Partner, Mehta Ventures Invest Partner, Mehta Ventures Partner, Mehta Ventures Partner: Mehta Ventures Spectrum Impact Partner, Mehta Ventures Partner, Mehta Ventures Ventures Portfolio Portfolio Portfolio Portfolio Portfolio Narayan Murthy Narotam Sekhsaria Aarti Gupta Ronnie Screwvala Sanjay Mehta Sanjay Mehta Sanjay Mehta Sanjay Mehta Founder, Catamaran Co - founder and Managing Founder, Co - founder and Managing Narotam Co Partner, - founder and Managing Anikarth Founder, Co - founder and Managing Unilazer Ventures Partner, Mehta Ventures Sekhsarai Partner, Mehta Ventures Family Office Partner, Mehta Ventures Ventures Ventures Partner, Mehta Ventures Portfolio Portfolio Portfolio Portfolio Source(s): Secondary research, 1Lattice analysis 40 Angel Investment Ecosystem (1/2) Angel investors spark early growth, paving the way for institutional capital to scale Angel vs institutional investors Top tech - based sectors (by angel investments, 2020 - 2025) Stage of entry Decision process Angel investors only invest in early - Angels decide quickly, often on stage companies while institutional personal conviction. Institutions rely US$ 743M 1.13K investors come in at seed, growth, on due diligence and structured Total No. of or expansion stages. processes that ensure discipline. investment deals Consumer tech Capital size Risk appetite Angels provide smaller cheques useful Angels accept higher early - stage risks for MVPs and initial hires. Institutions but have limited capacity. Institutions bring in large - scale funding, critical for balance risk with scale, funding proven expansion and market dominance. models with growth potential. US$ 527M 401 Total No. of investment deals Fintech Pros and cons of Angel investing Capital size Limited funding & dilution risk Provide crucial early capital with lighter Often insufficient for scaling and can terms and less control than traditional cause high equity dilution. funding. US$ 471M 304 Total No. of Healthtech Guidance & connections Inconsistent expertise investment deals Offer mentorship, industry insights, and Varying investor experience may create networks that ease future growth. governance issues. 41 Source(s): In - depth interviews, secondary research, 1Lattice analysis Angel Investment Ecosystem (2/2) Indian angel investors deployed $1.7 B (2020 - 2025), with a median deal size of ~US$ 103K Key Statistics US$ 1.71B 3.36K US$ 165M US$ 103K Total Total funding Median Total 2025 (2020 - 2025) deals deal size funding DEAL DEAL DEAL DEAL DEAL COUNT COUNT COUNT COUNT COUNT 213 210 140 138 200 Top Kunal Shah Kunal Bahl Rohit Bansal Anupam Mittal angel Abhishek Goyal Sanjay Mehta Sanjay Mehta Sanjay Mehta Sanjay Mehta Sanjay Mehta Co - founder of Snapdeal; Founder of Freecharge & Founder of Shaadi.com Co - founder of Snapdeal; CRED; invests active angel, part of Titan invests via Orios Venture Co - founder and Managing Co - founder and Managing co - runs Titan Capital Co - founder and Managing Co - founder and Managing investors Co - founder and Managing Co founder of Tracxn Capital Partner, Mehta Ventures individually as an angel Partner, Mehta Ventures Partners and as an angel Partner, Mehta Ventures Partner, Mehta Ventures with Kunal Bahl (2020 – 2025) Portfolio Portfolio Portfolio Portfolio Portfolio 42 Source(s): Secondary research, 1Lattice analysis