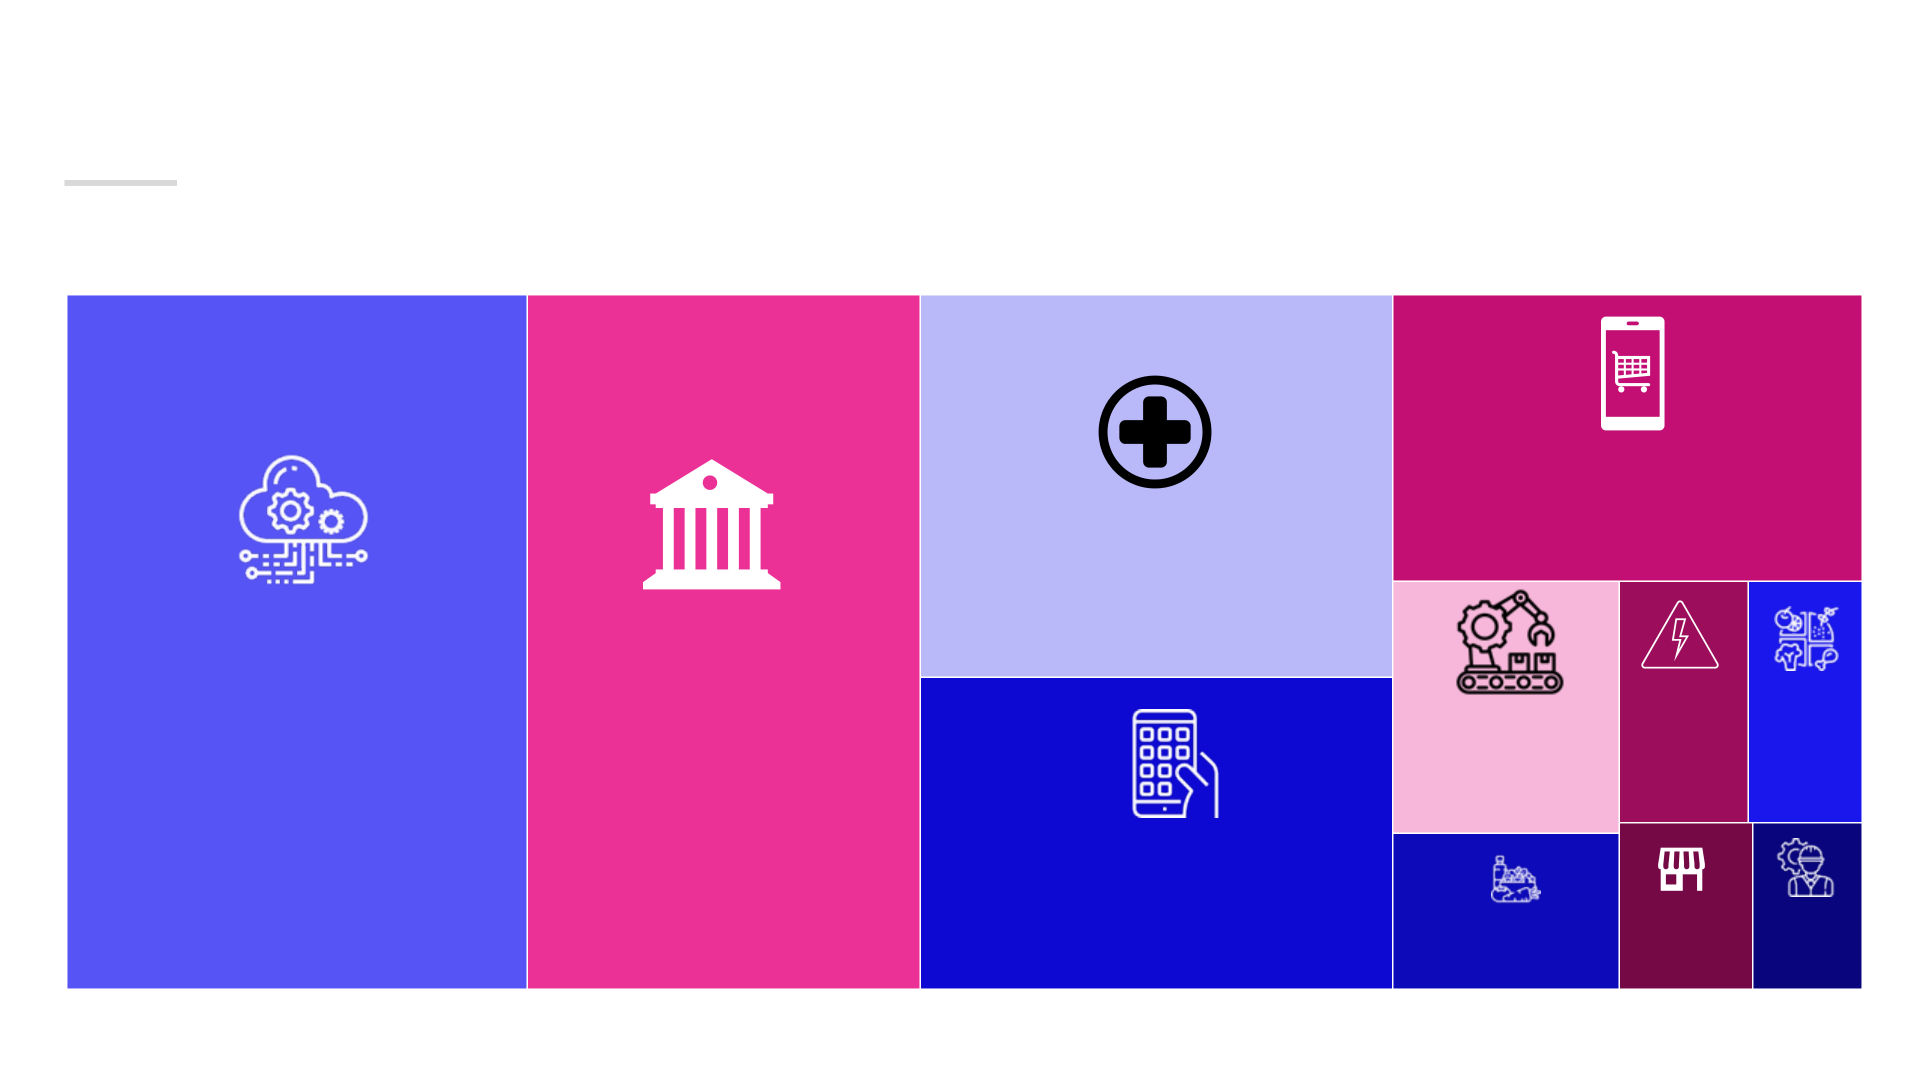
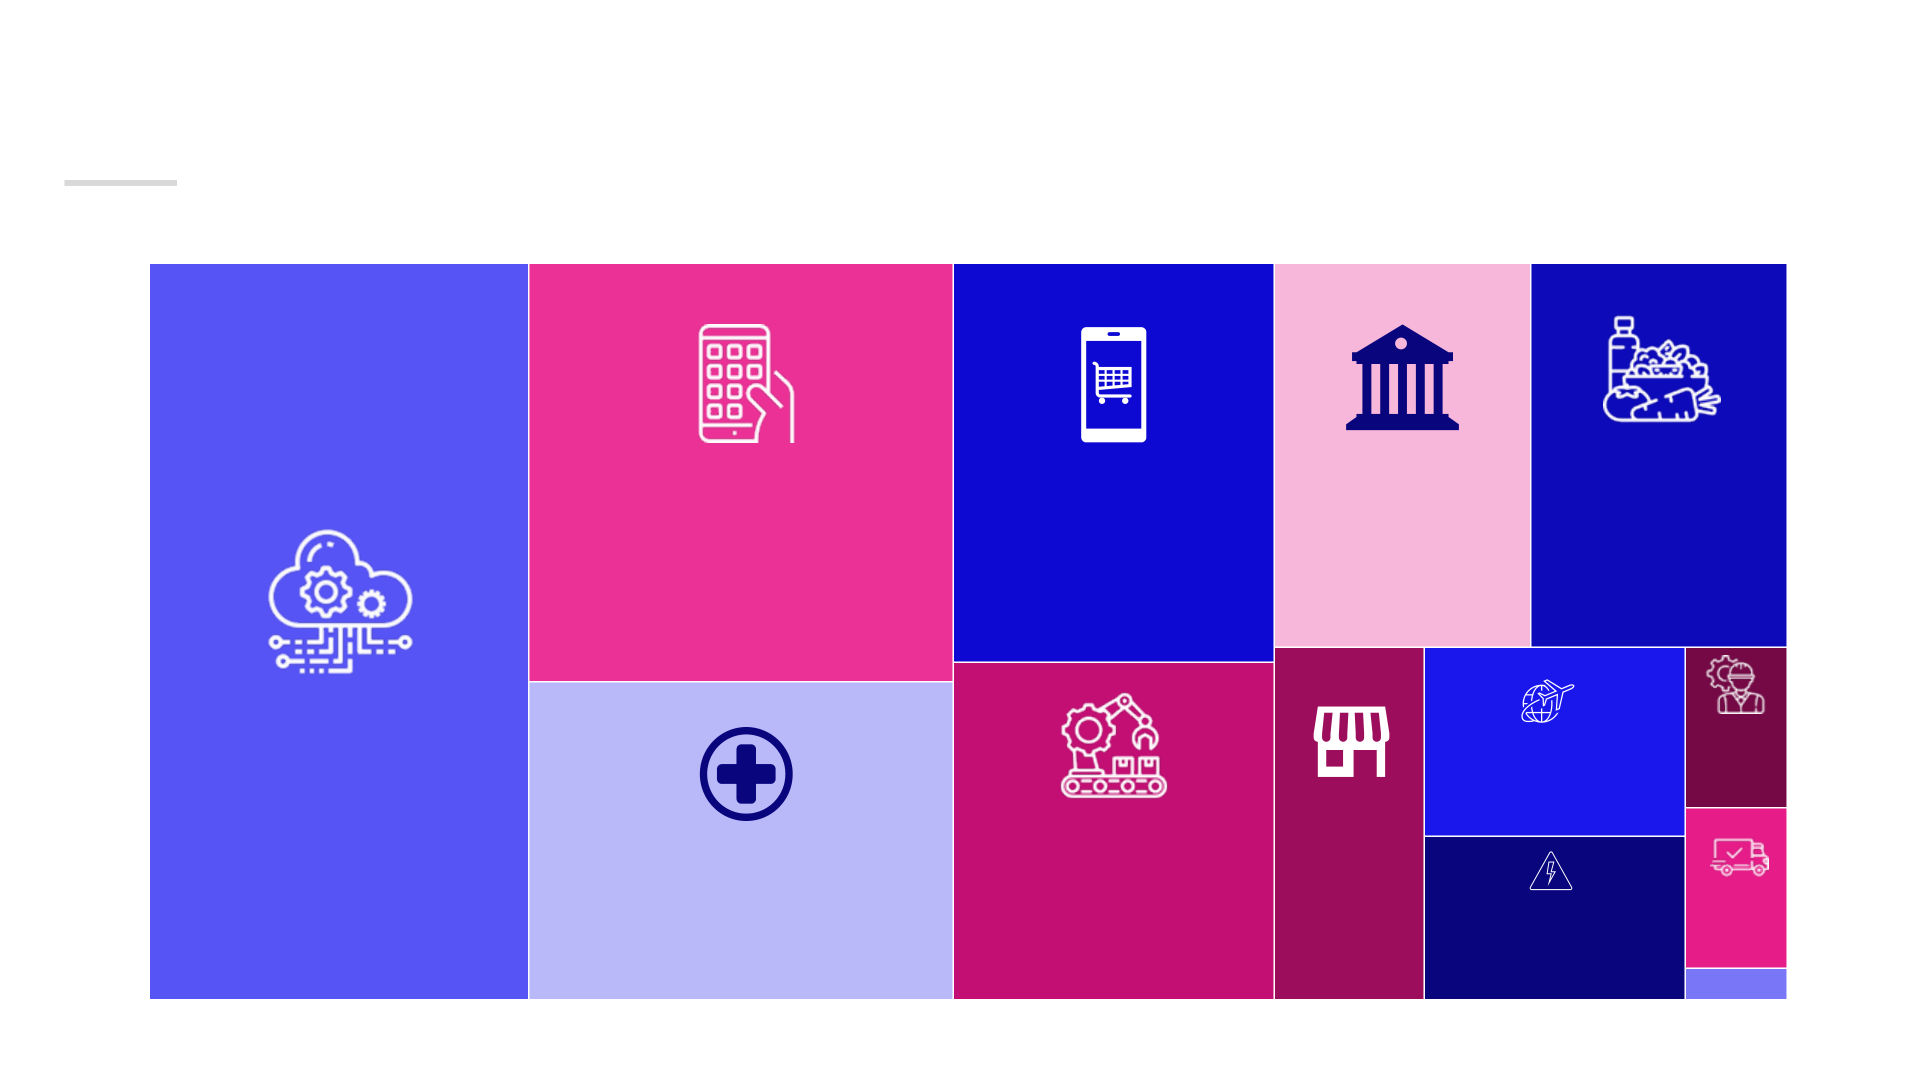
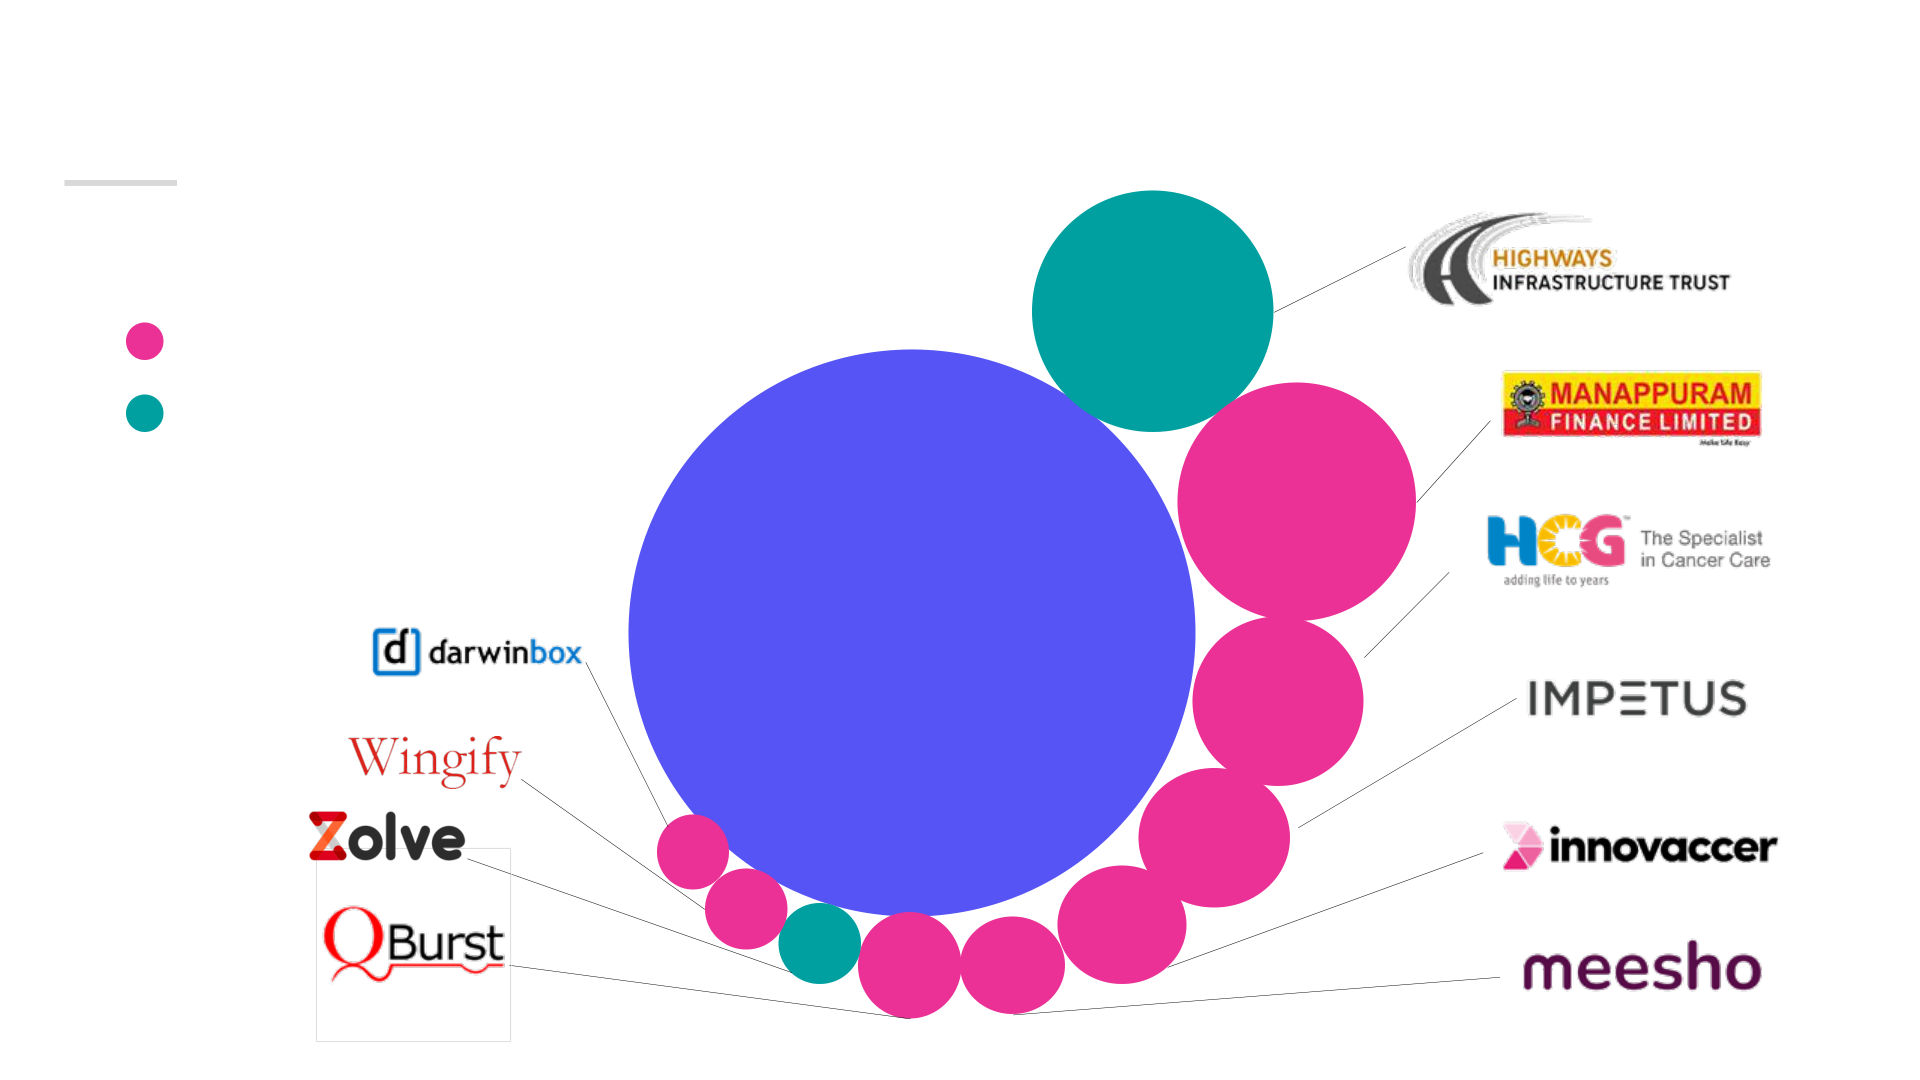
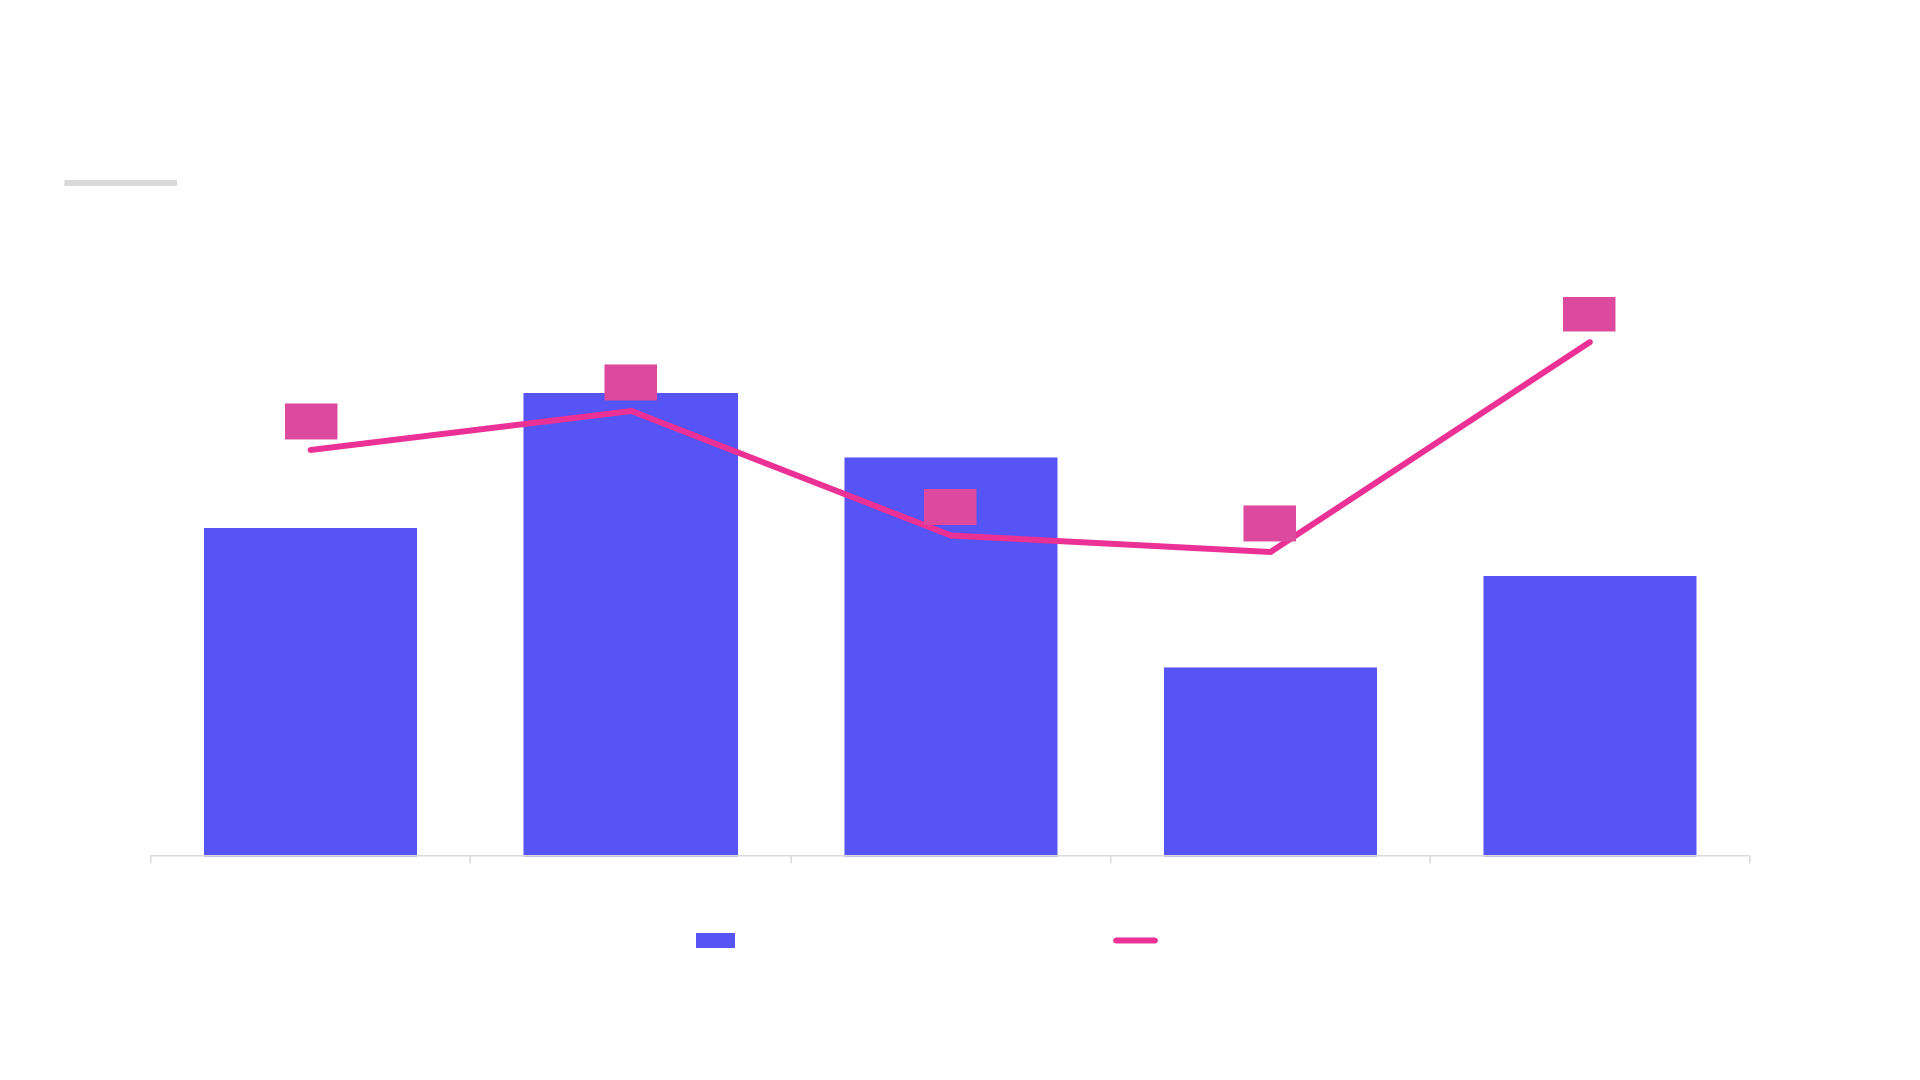
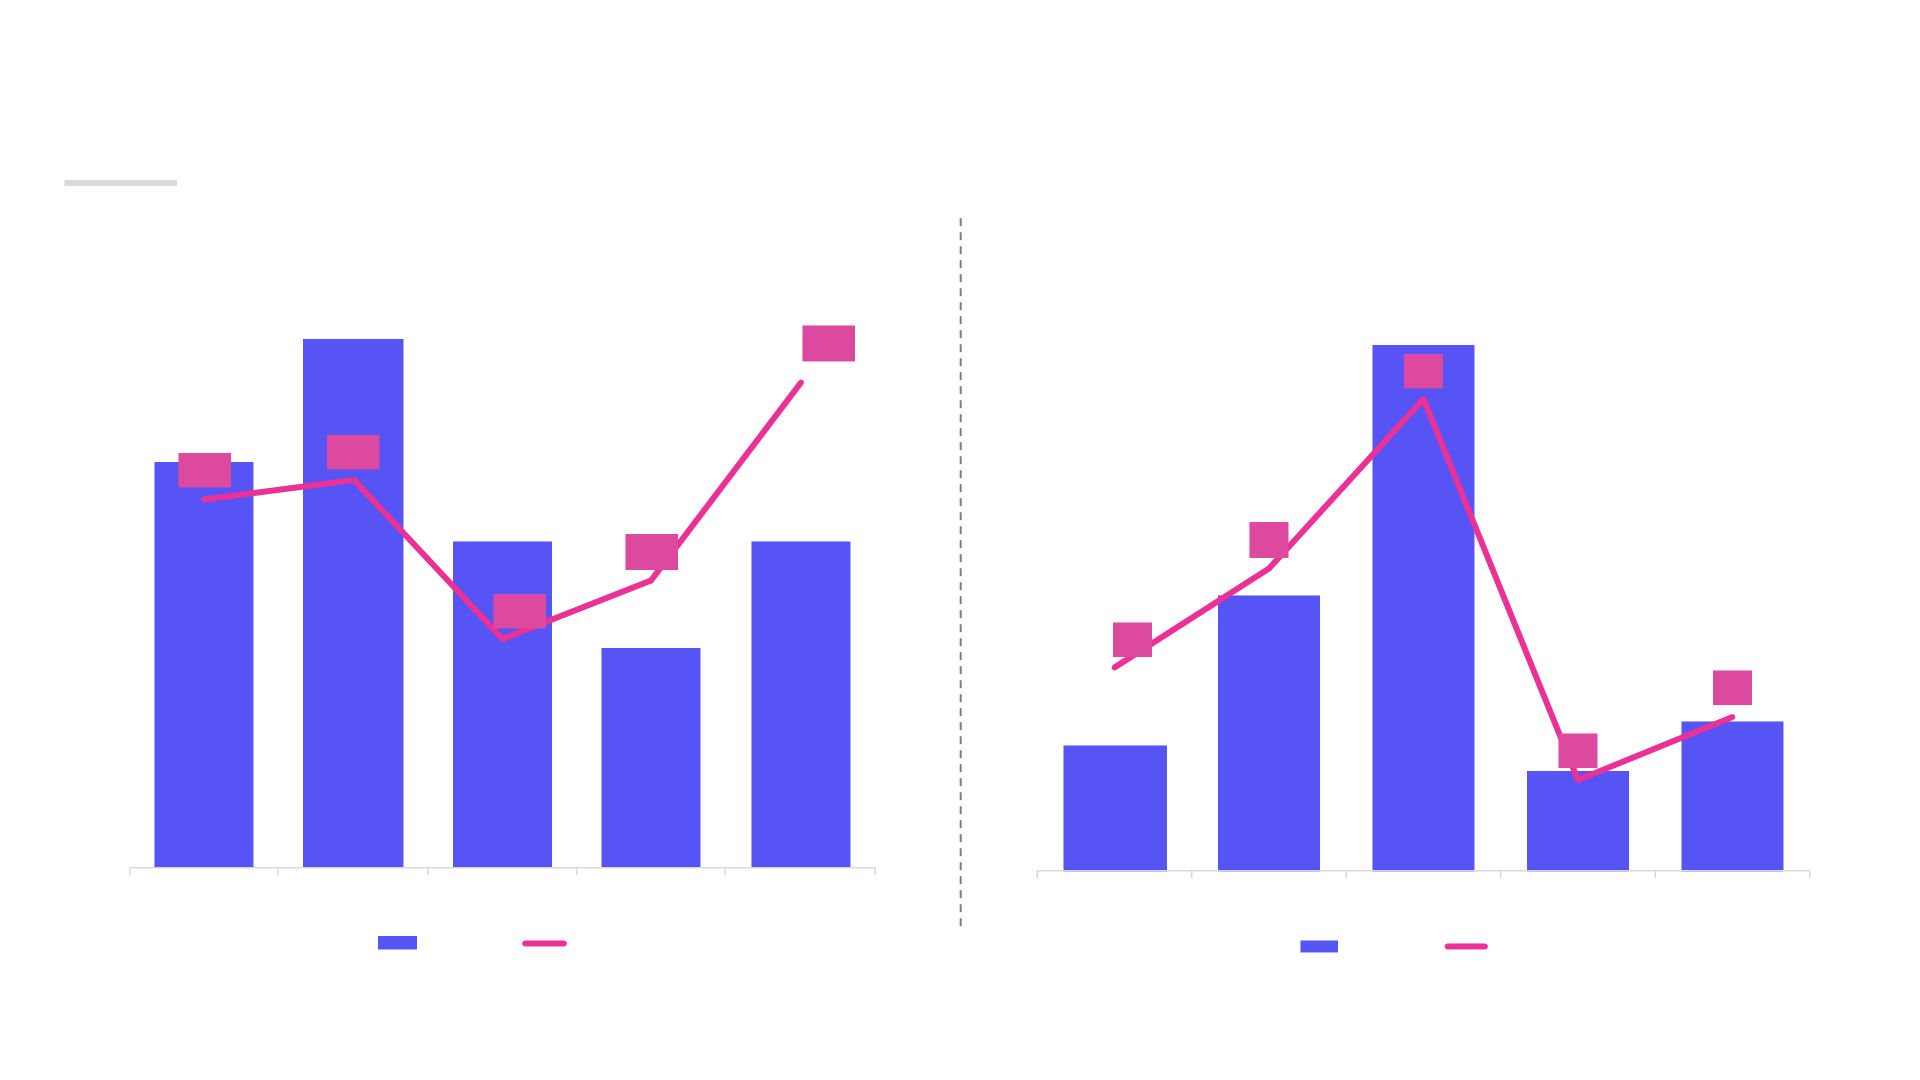
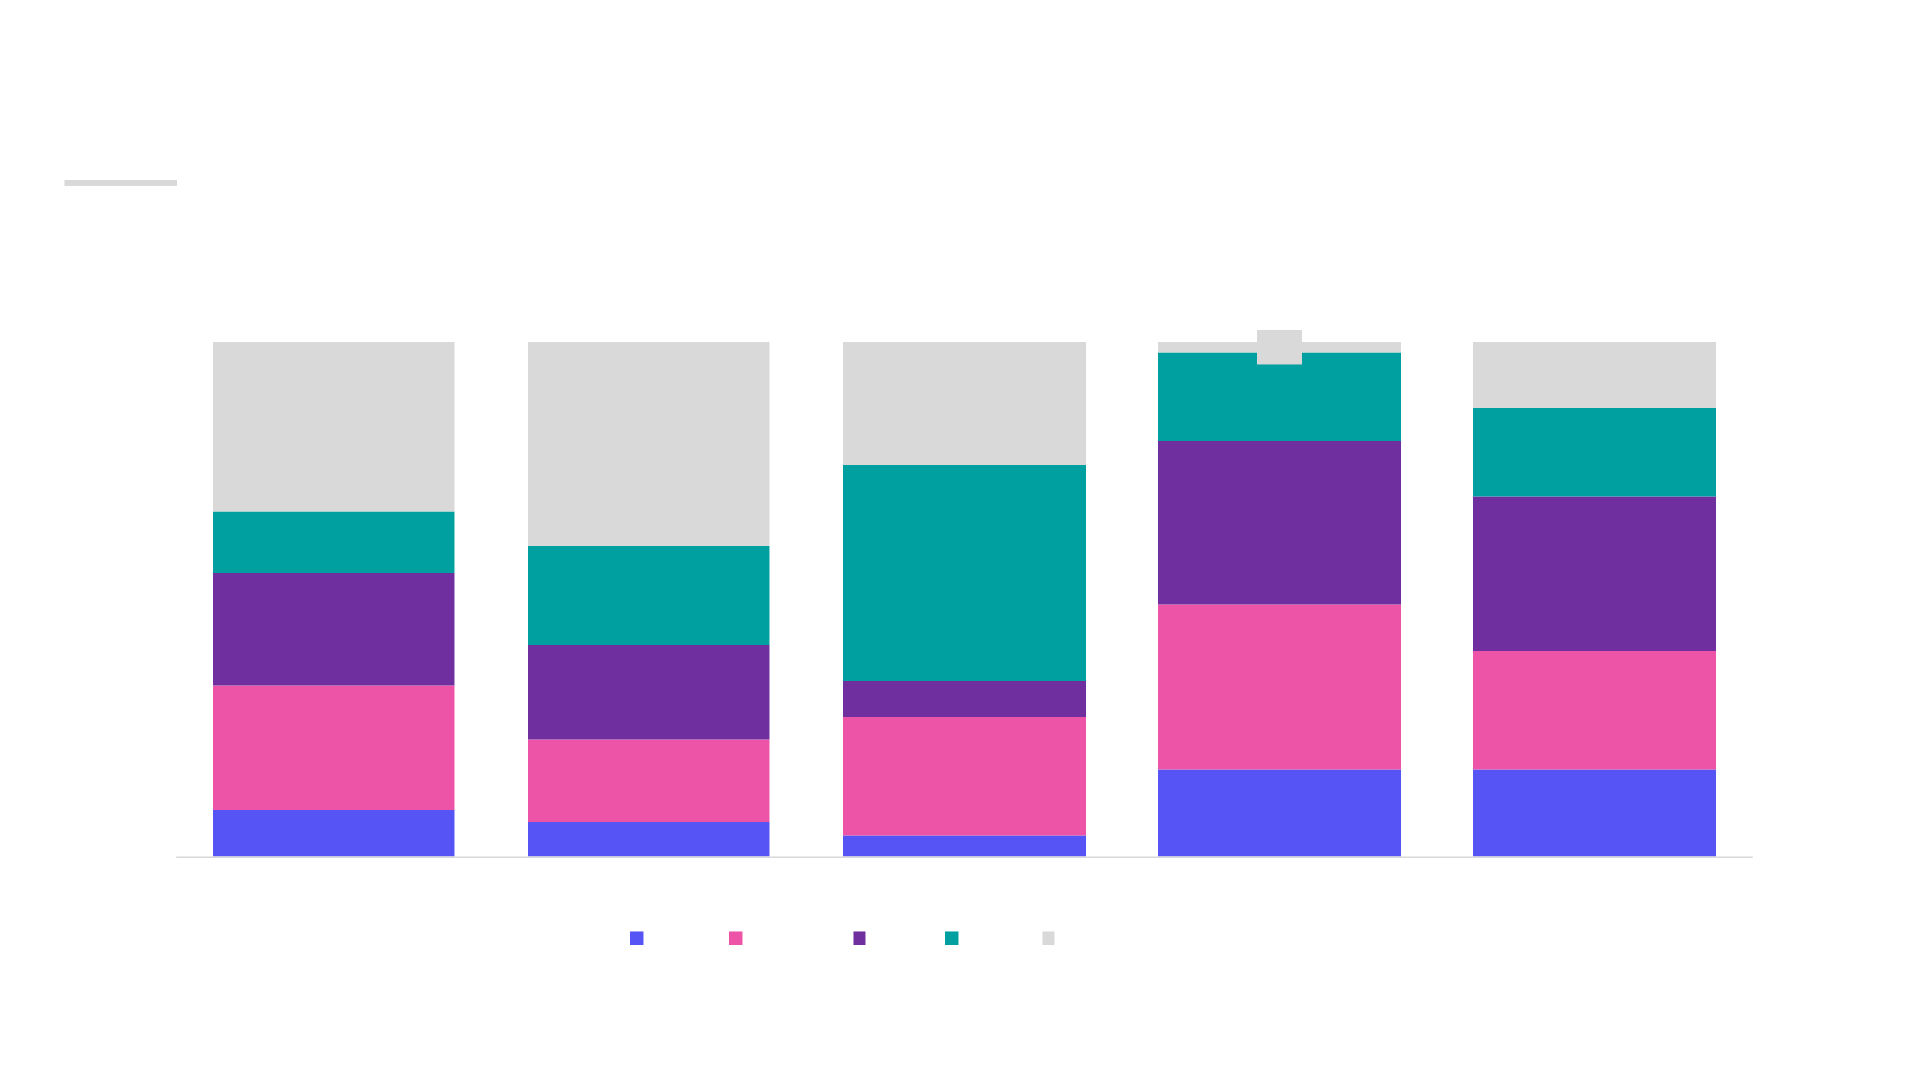
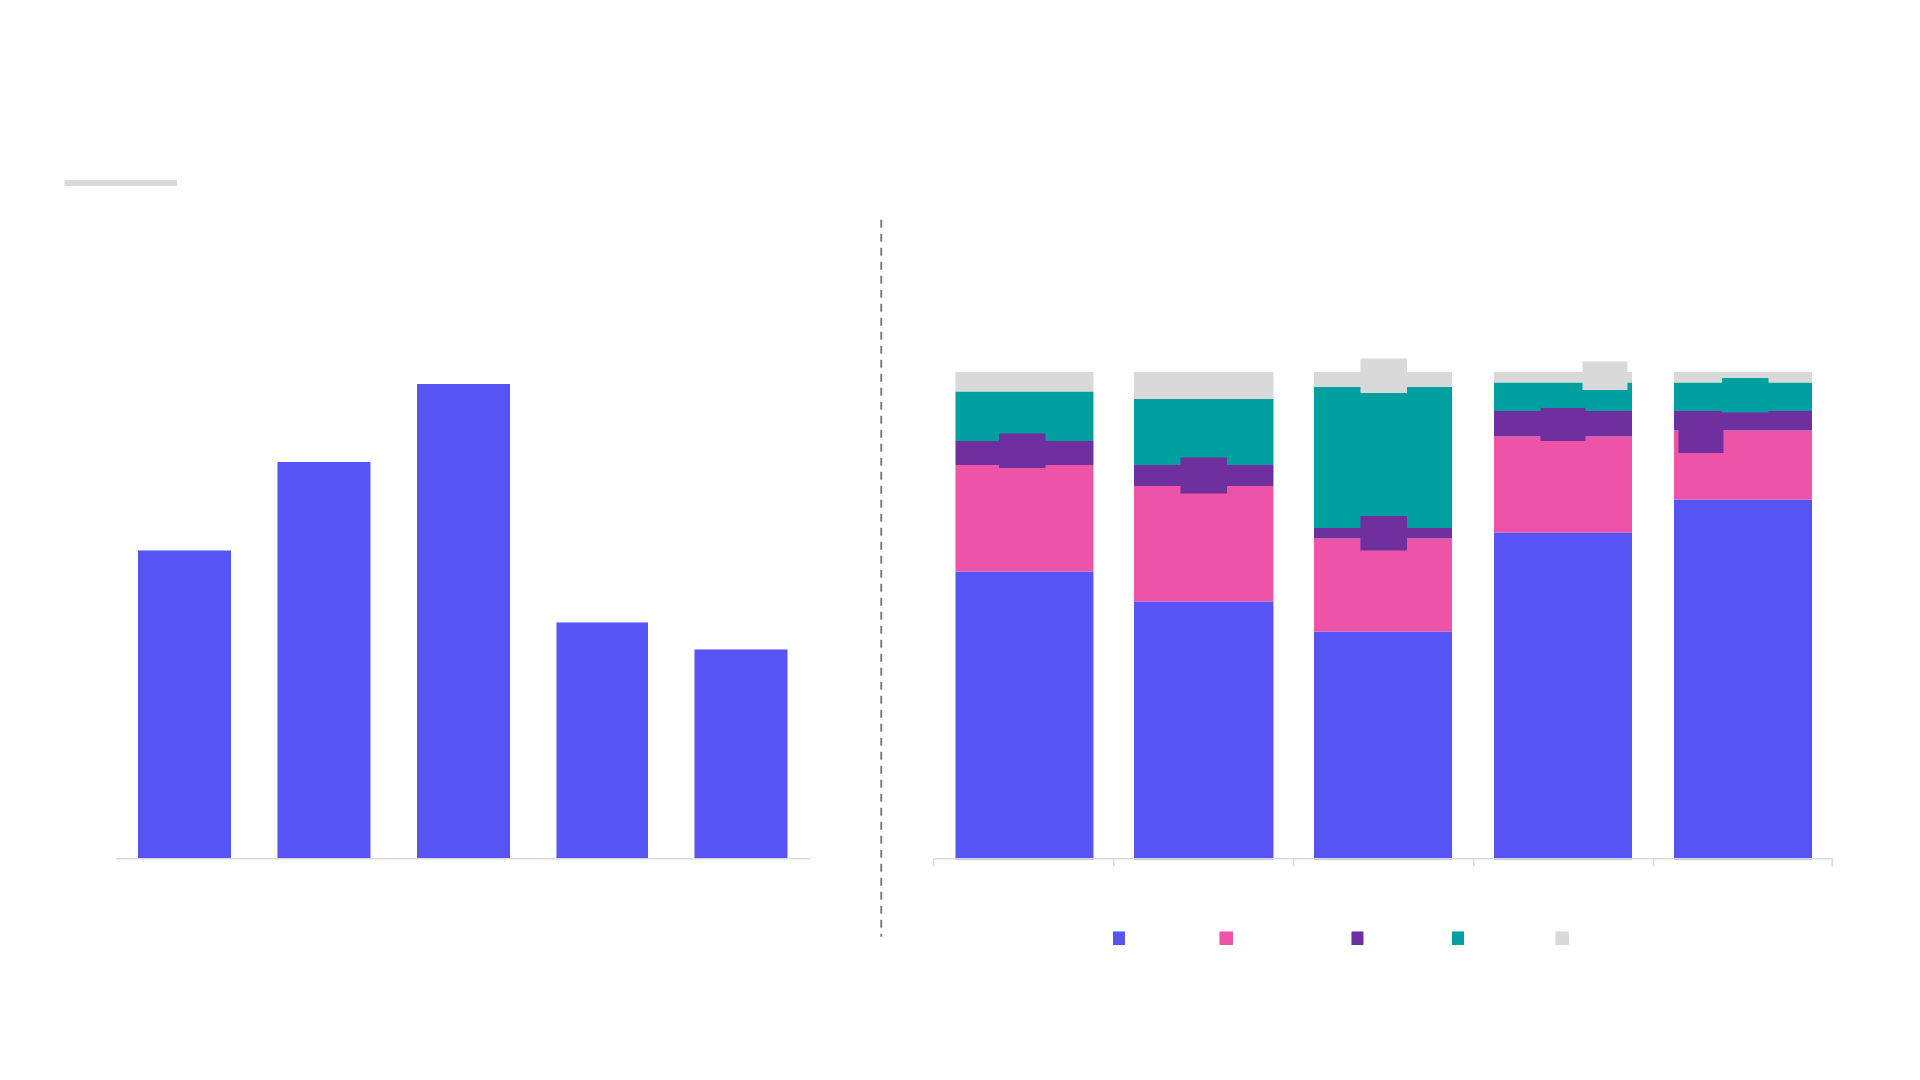
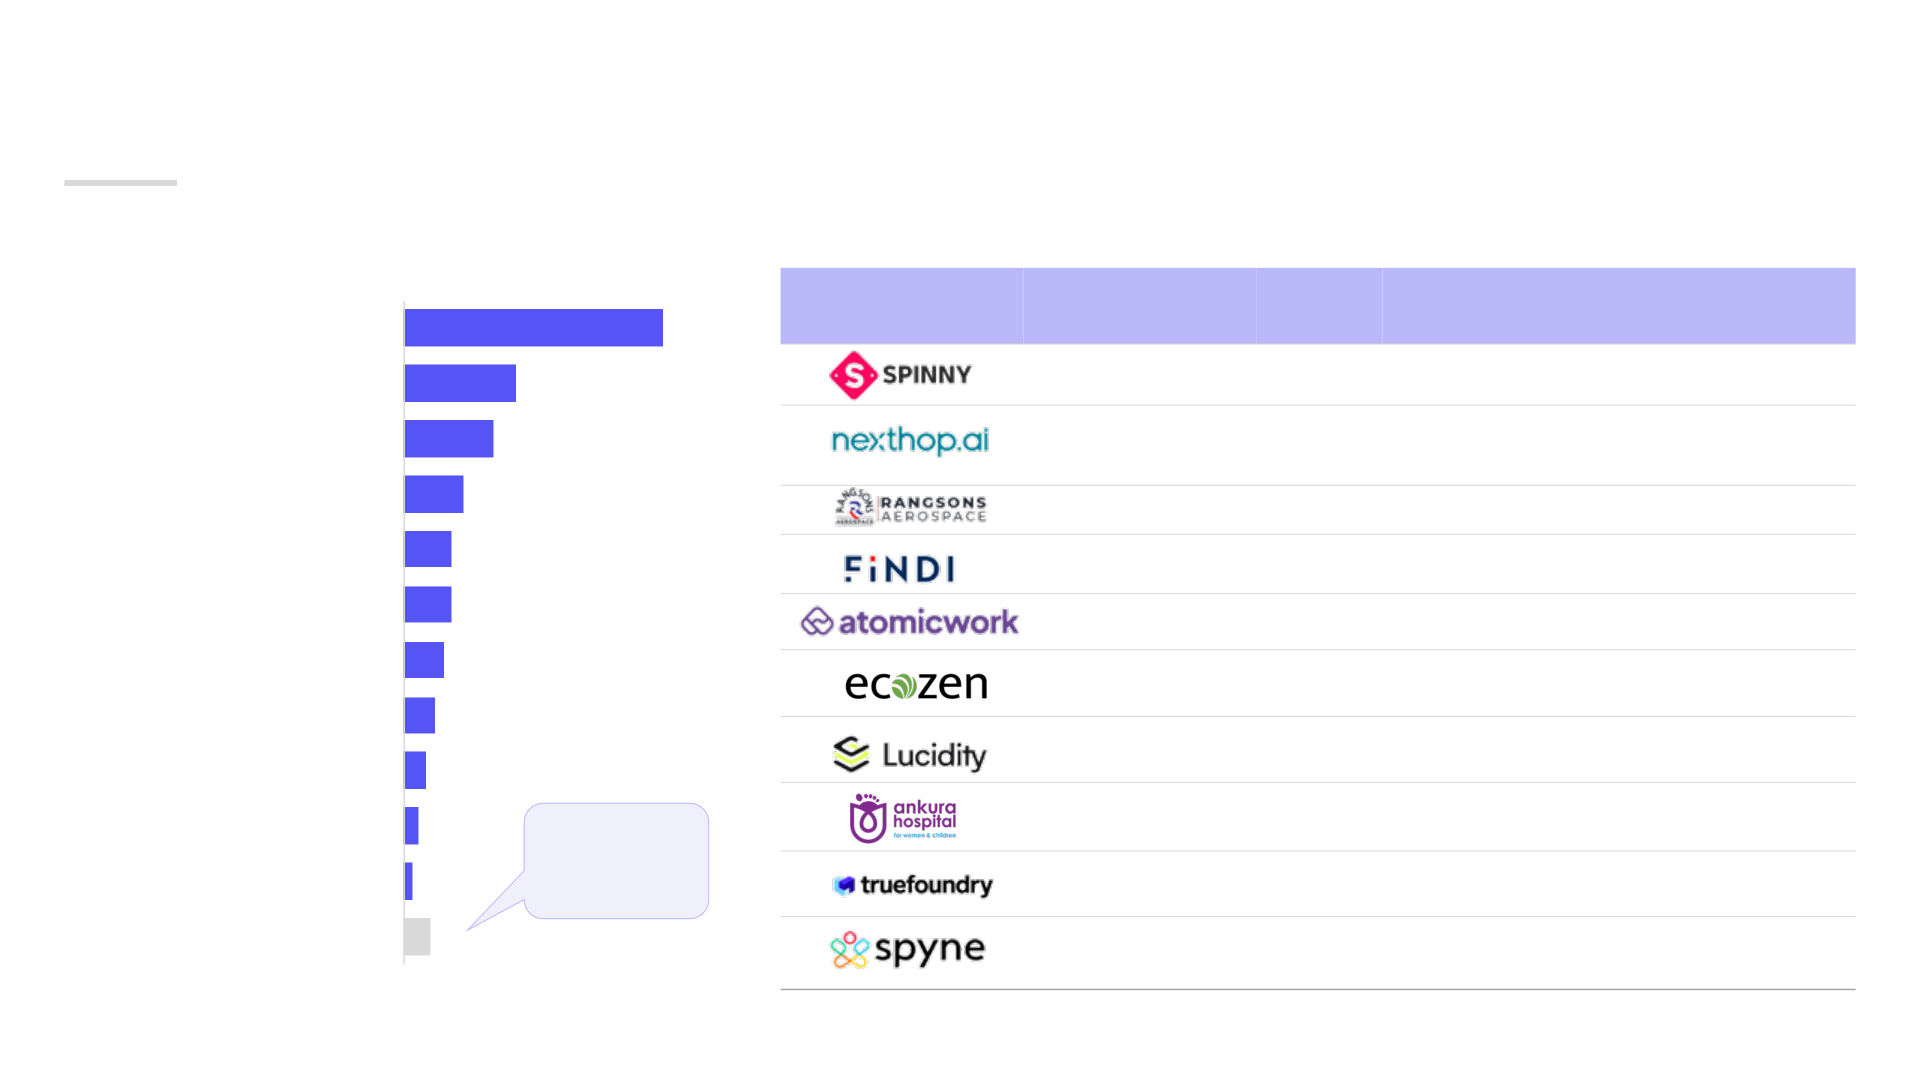
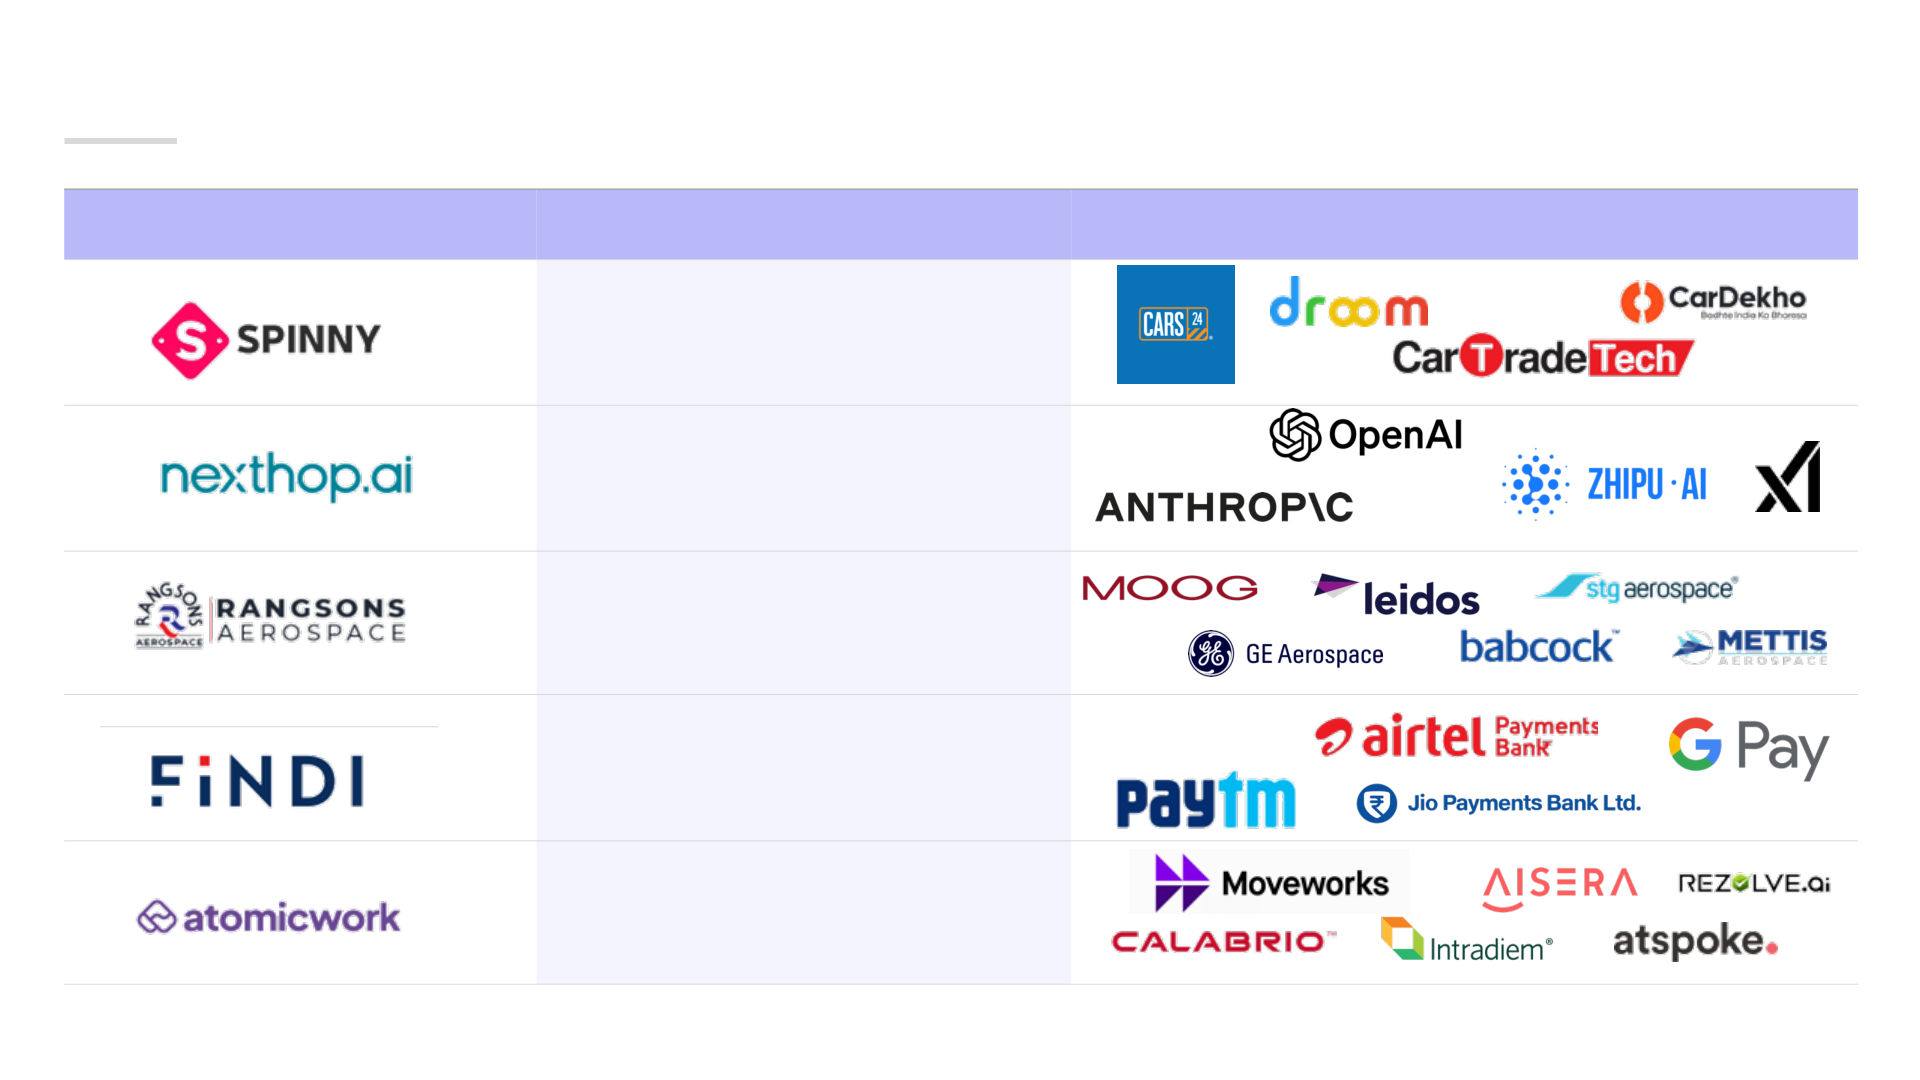
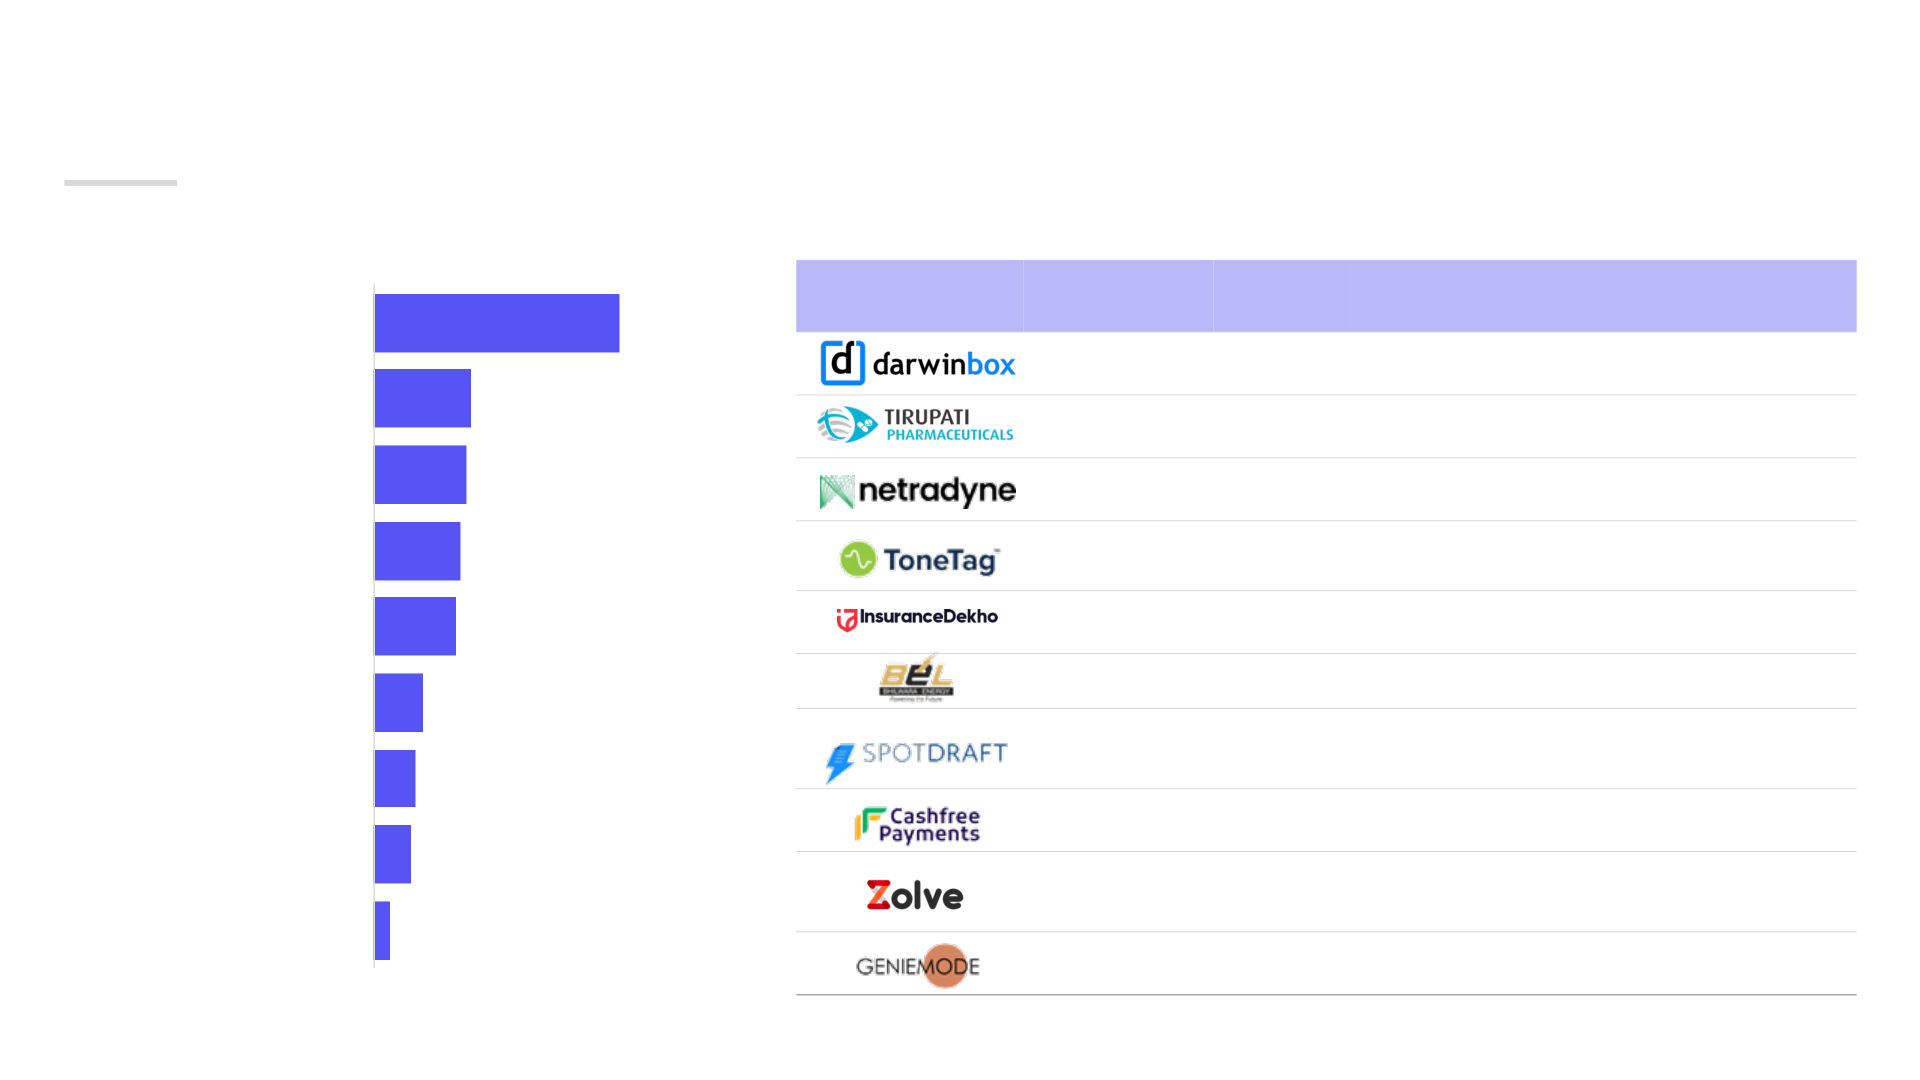
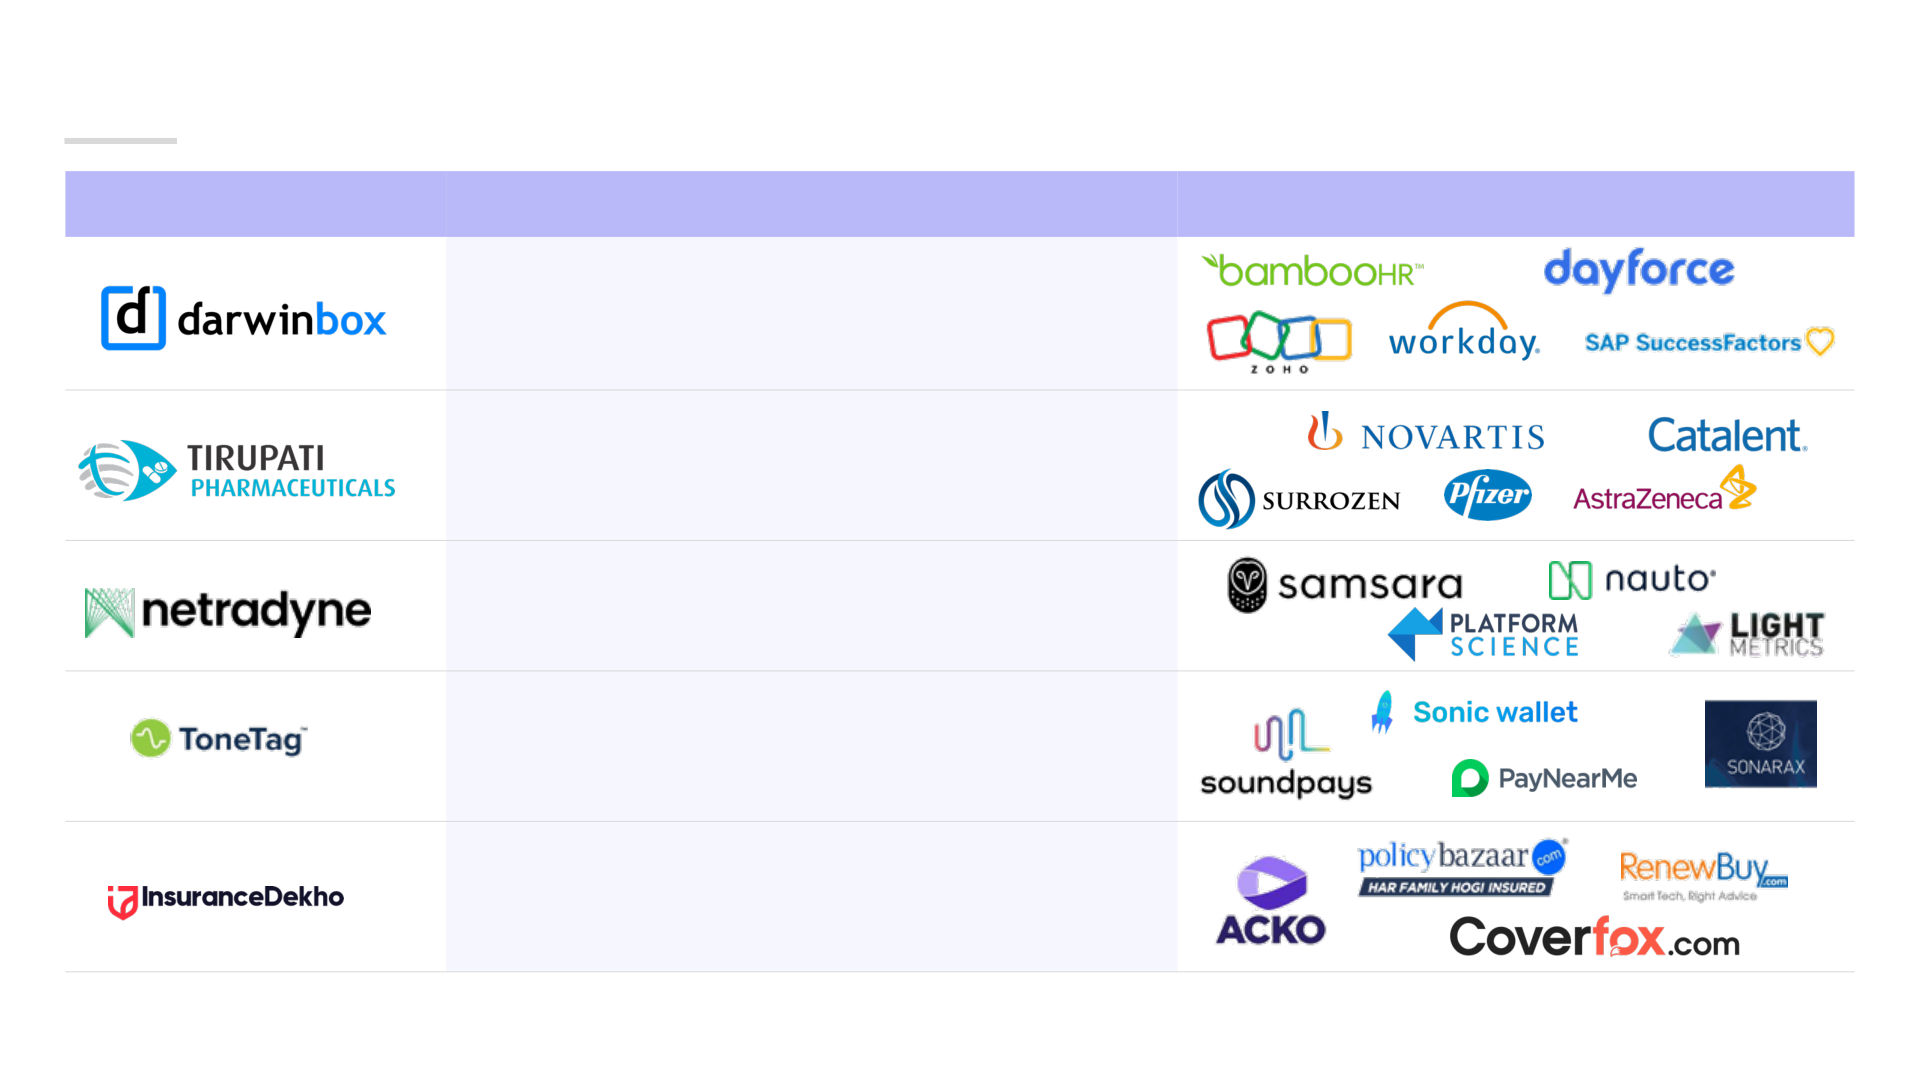
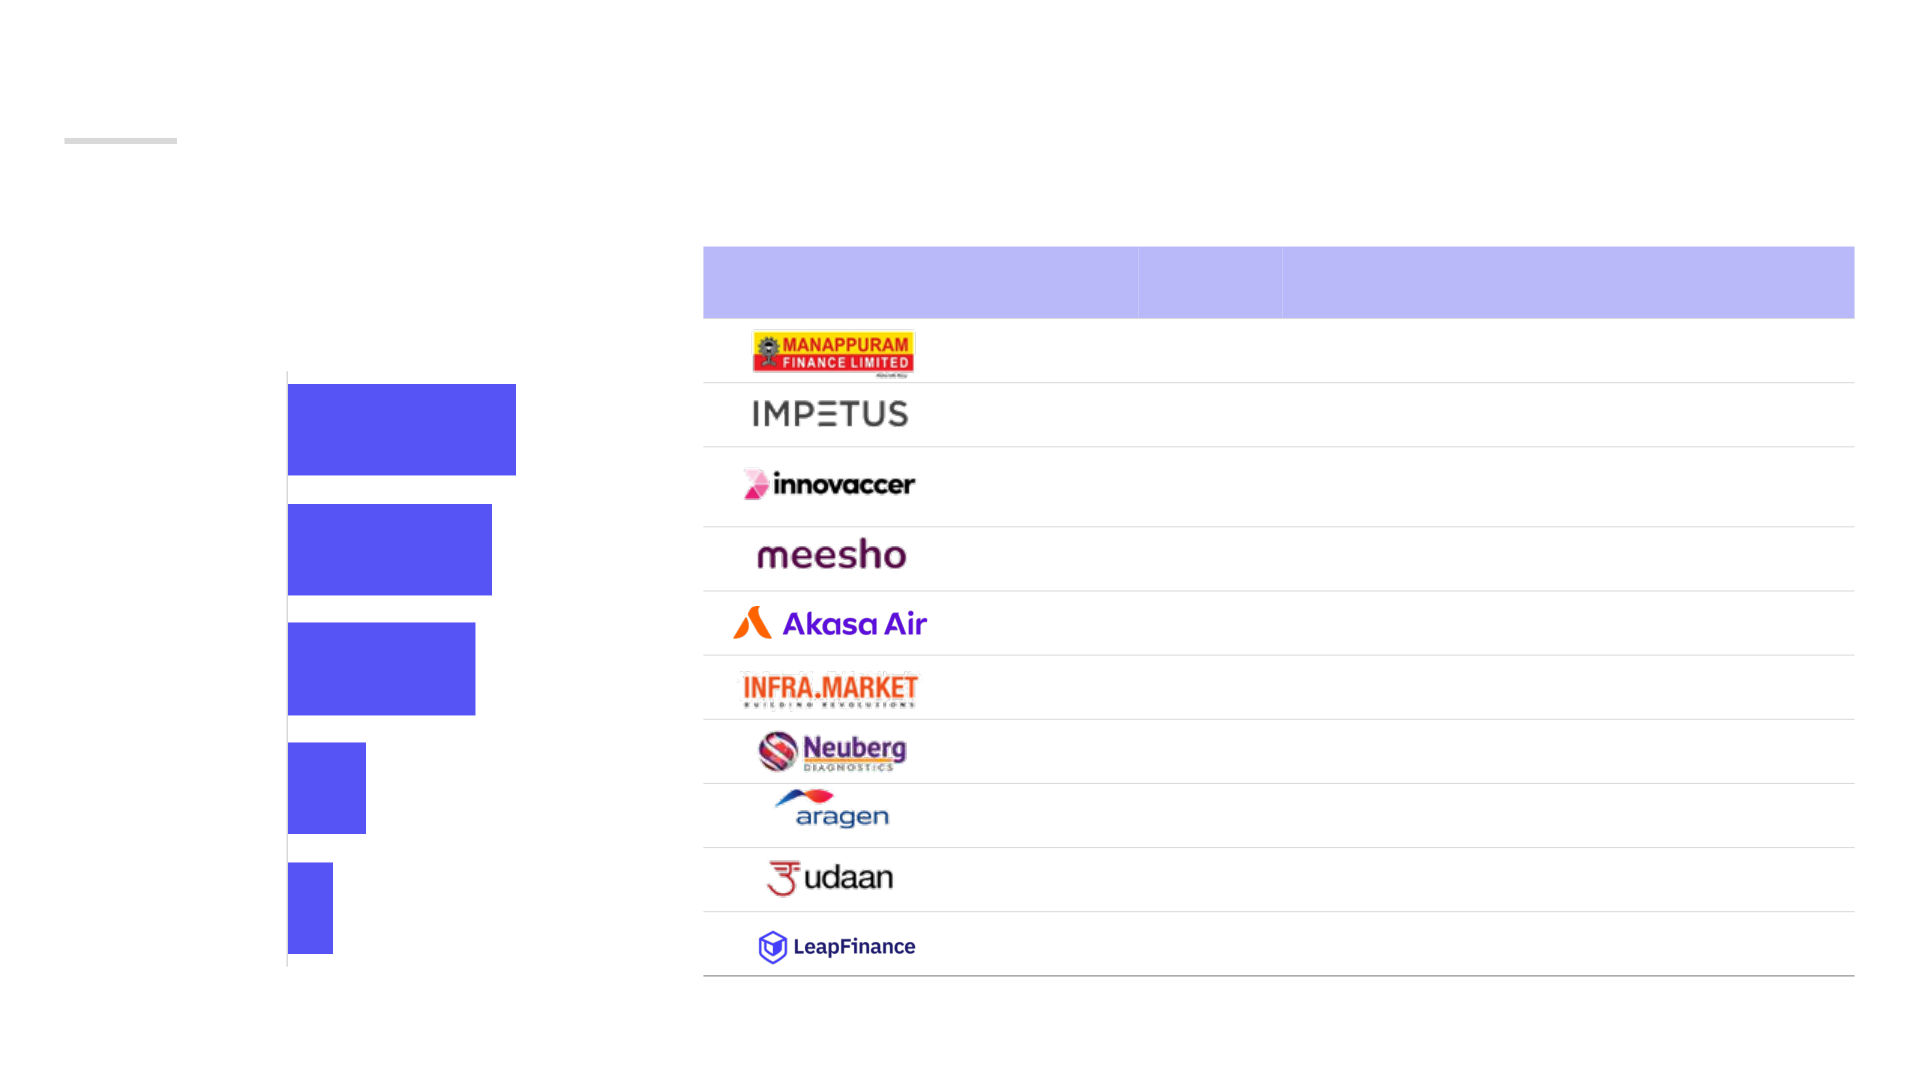
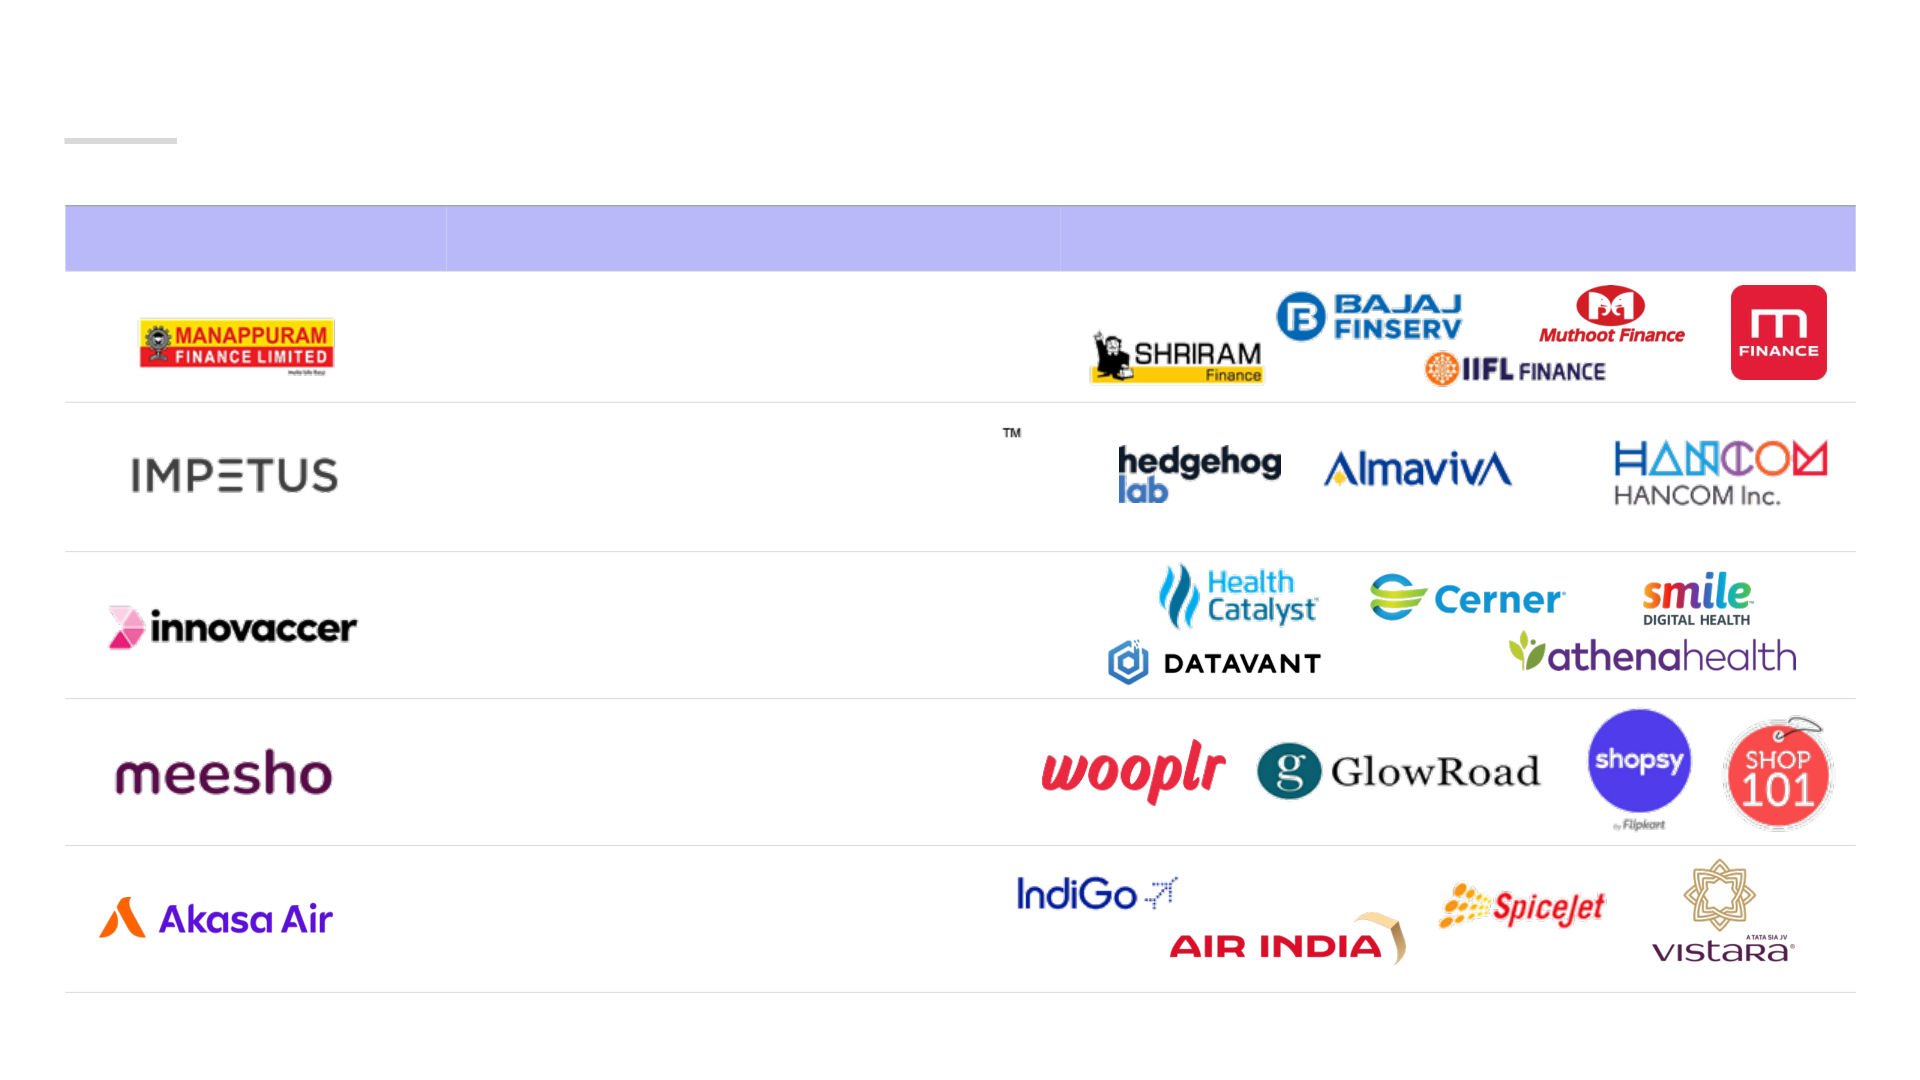
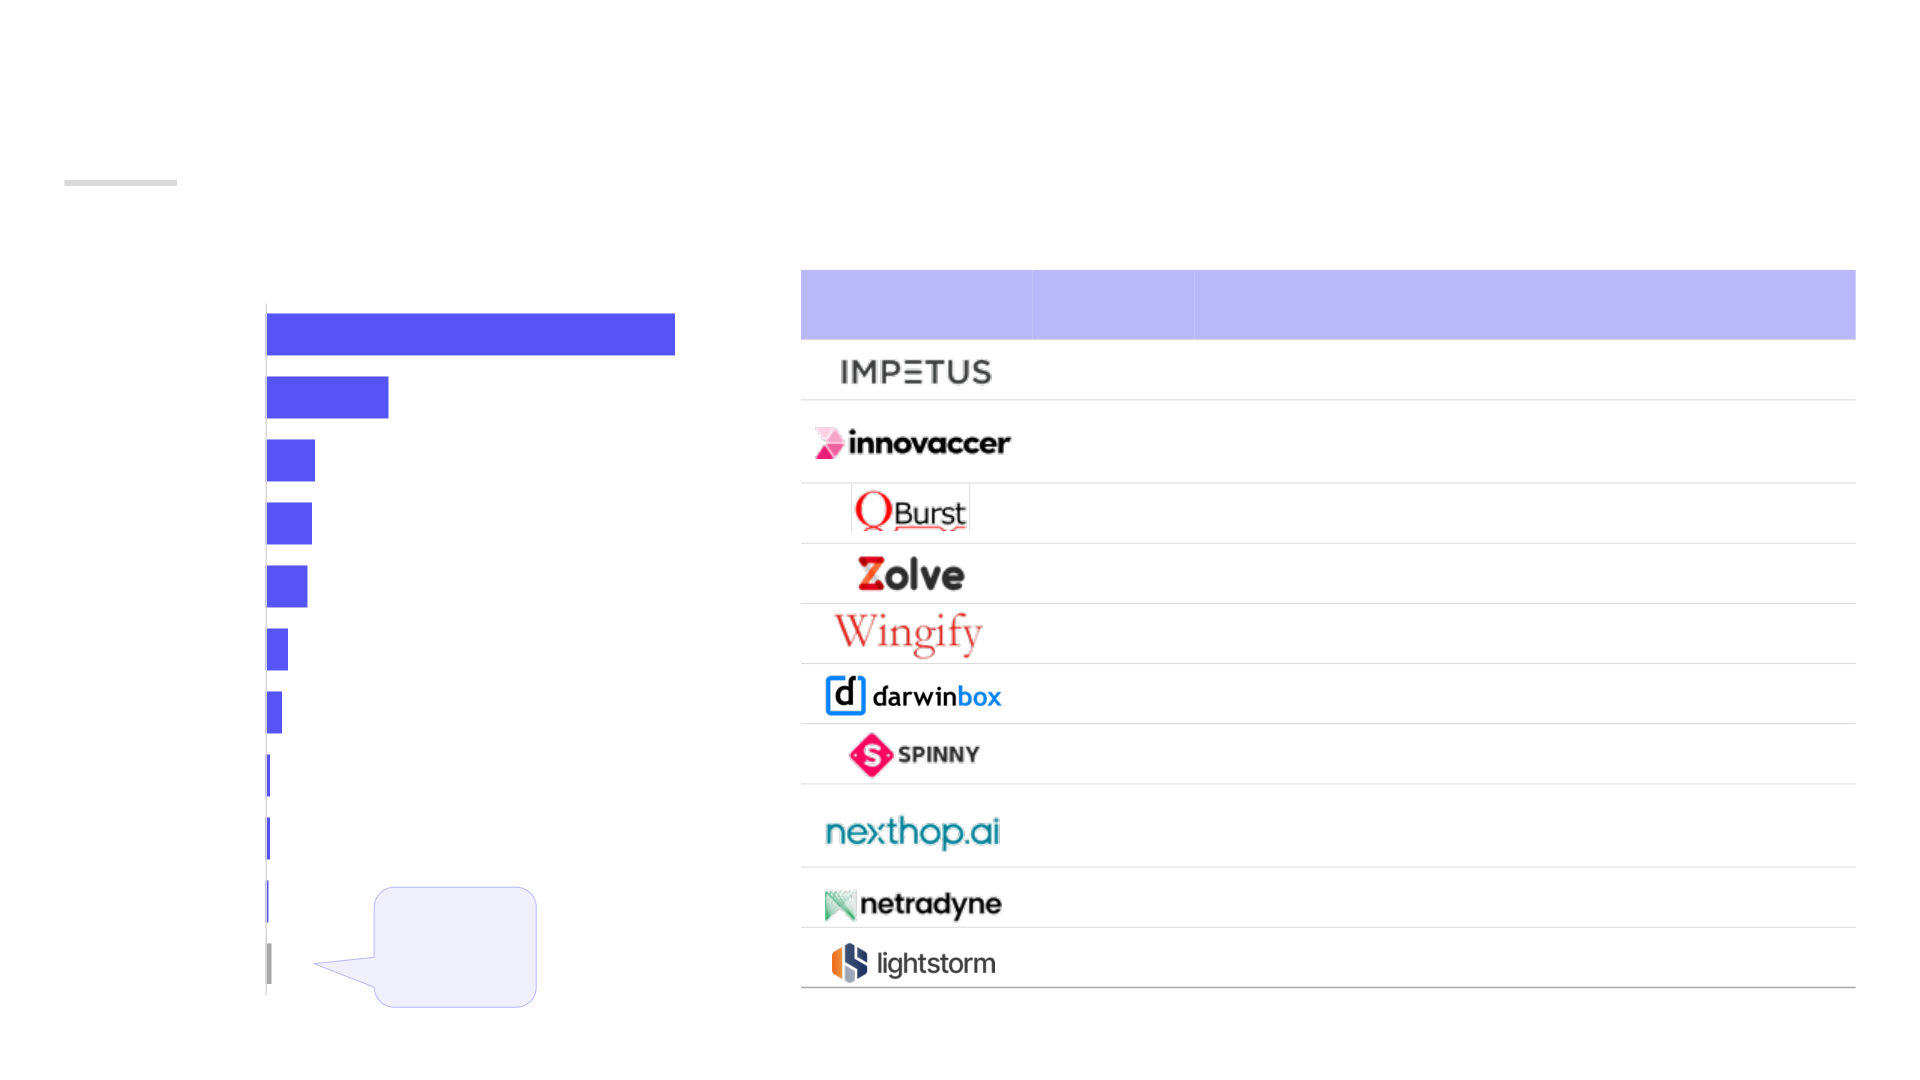
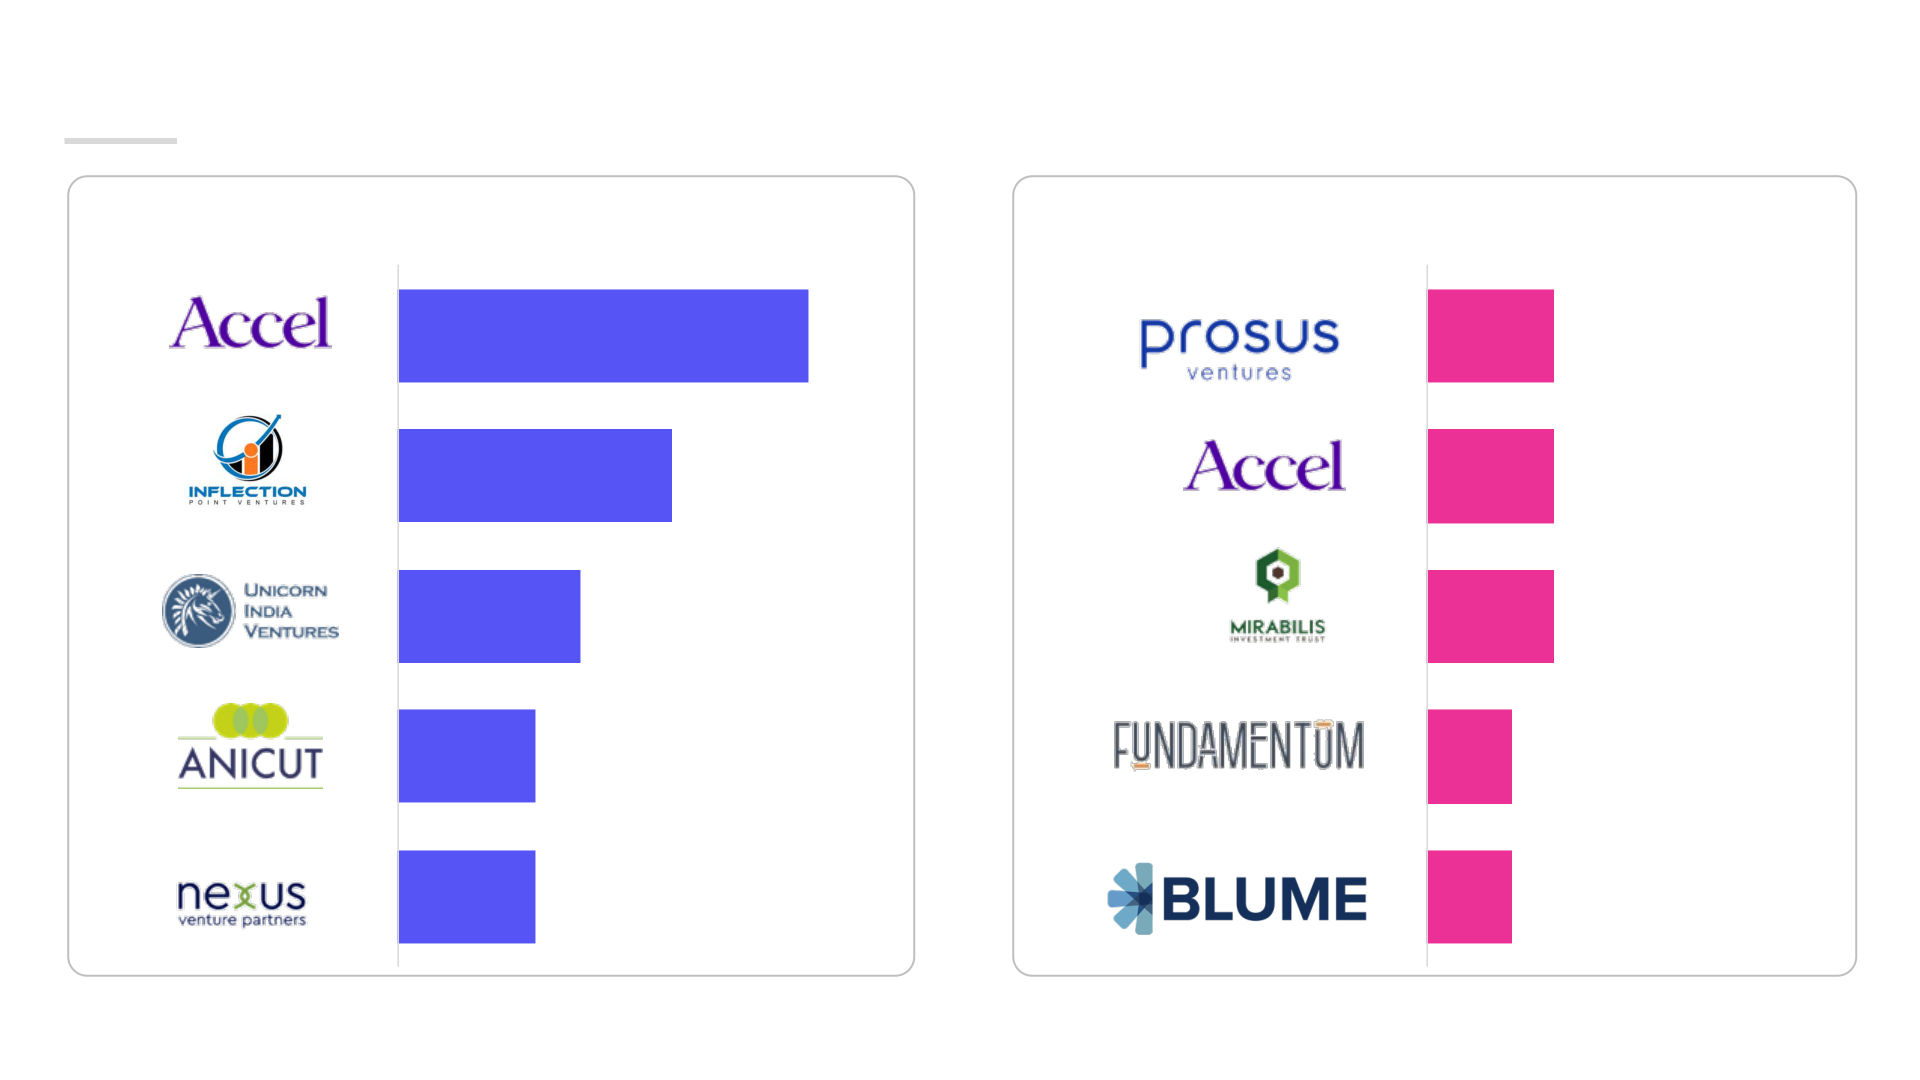
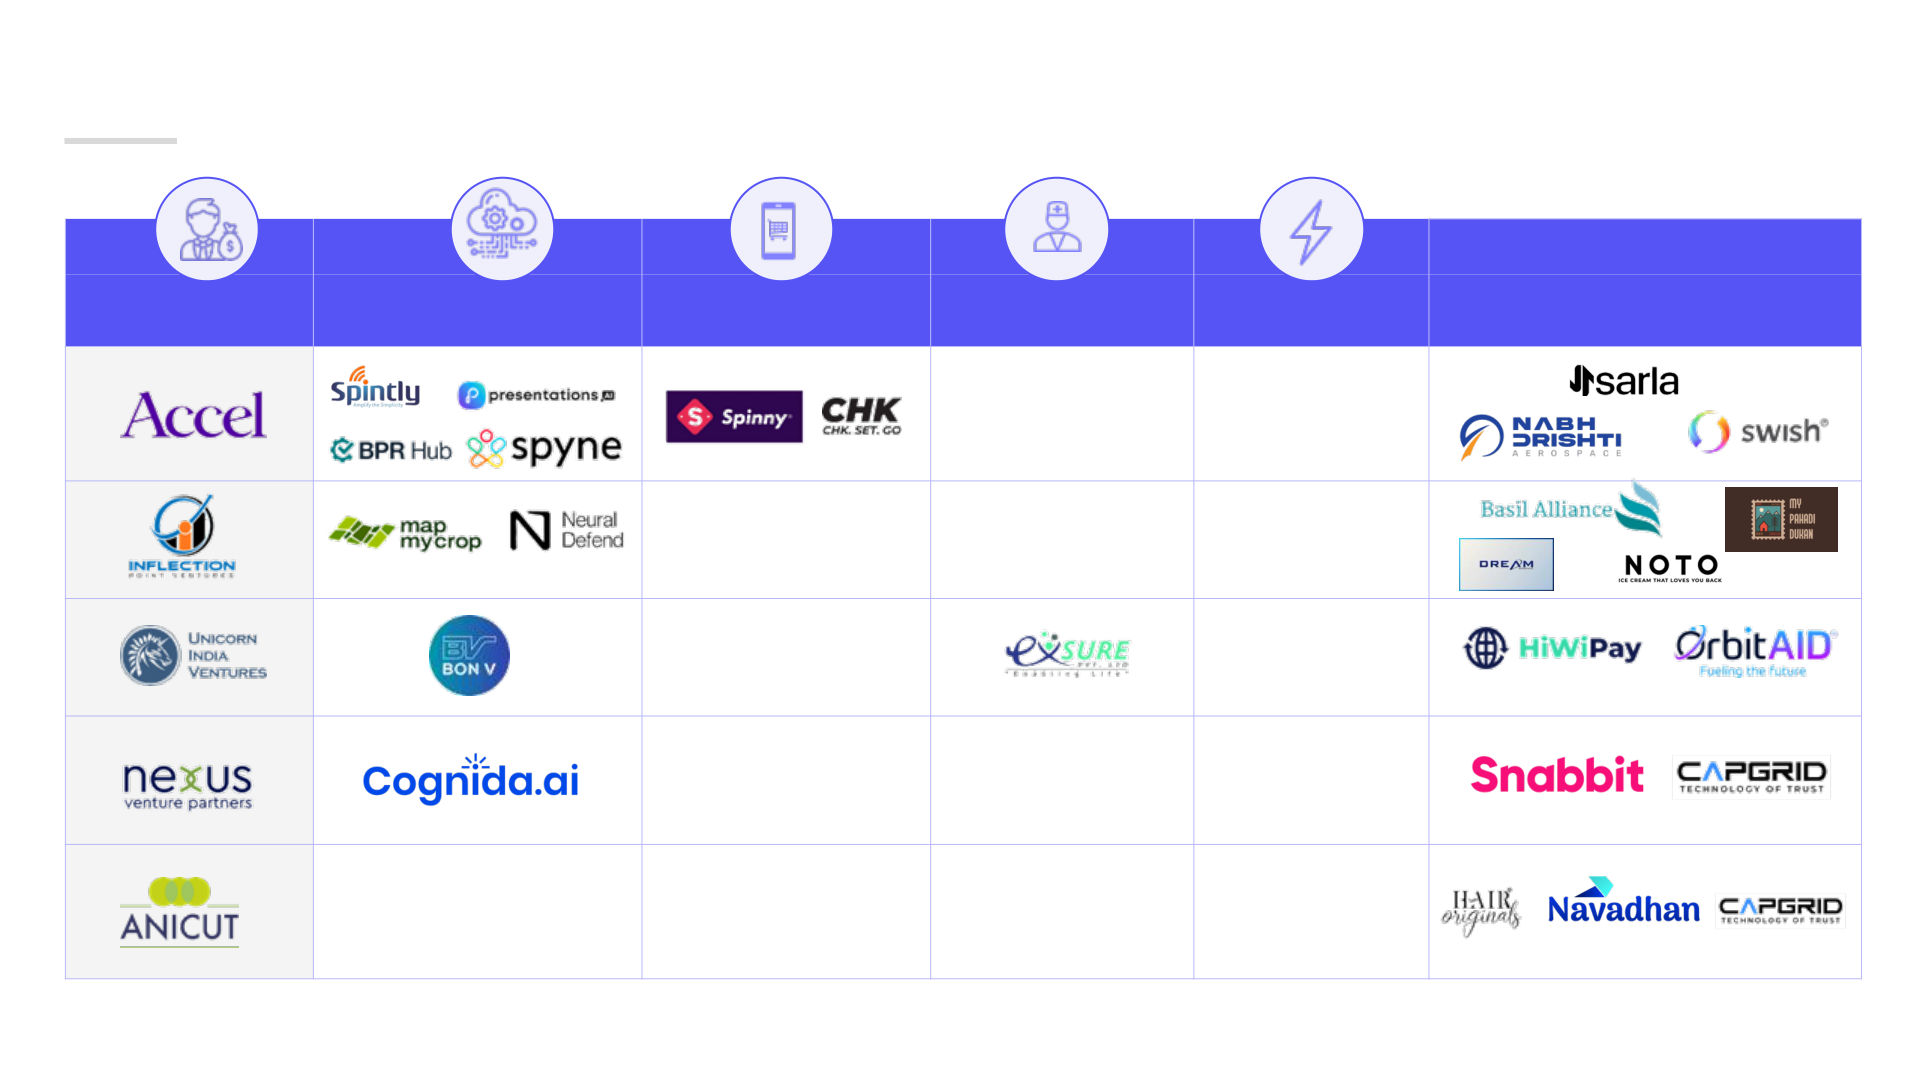
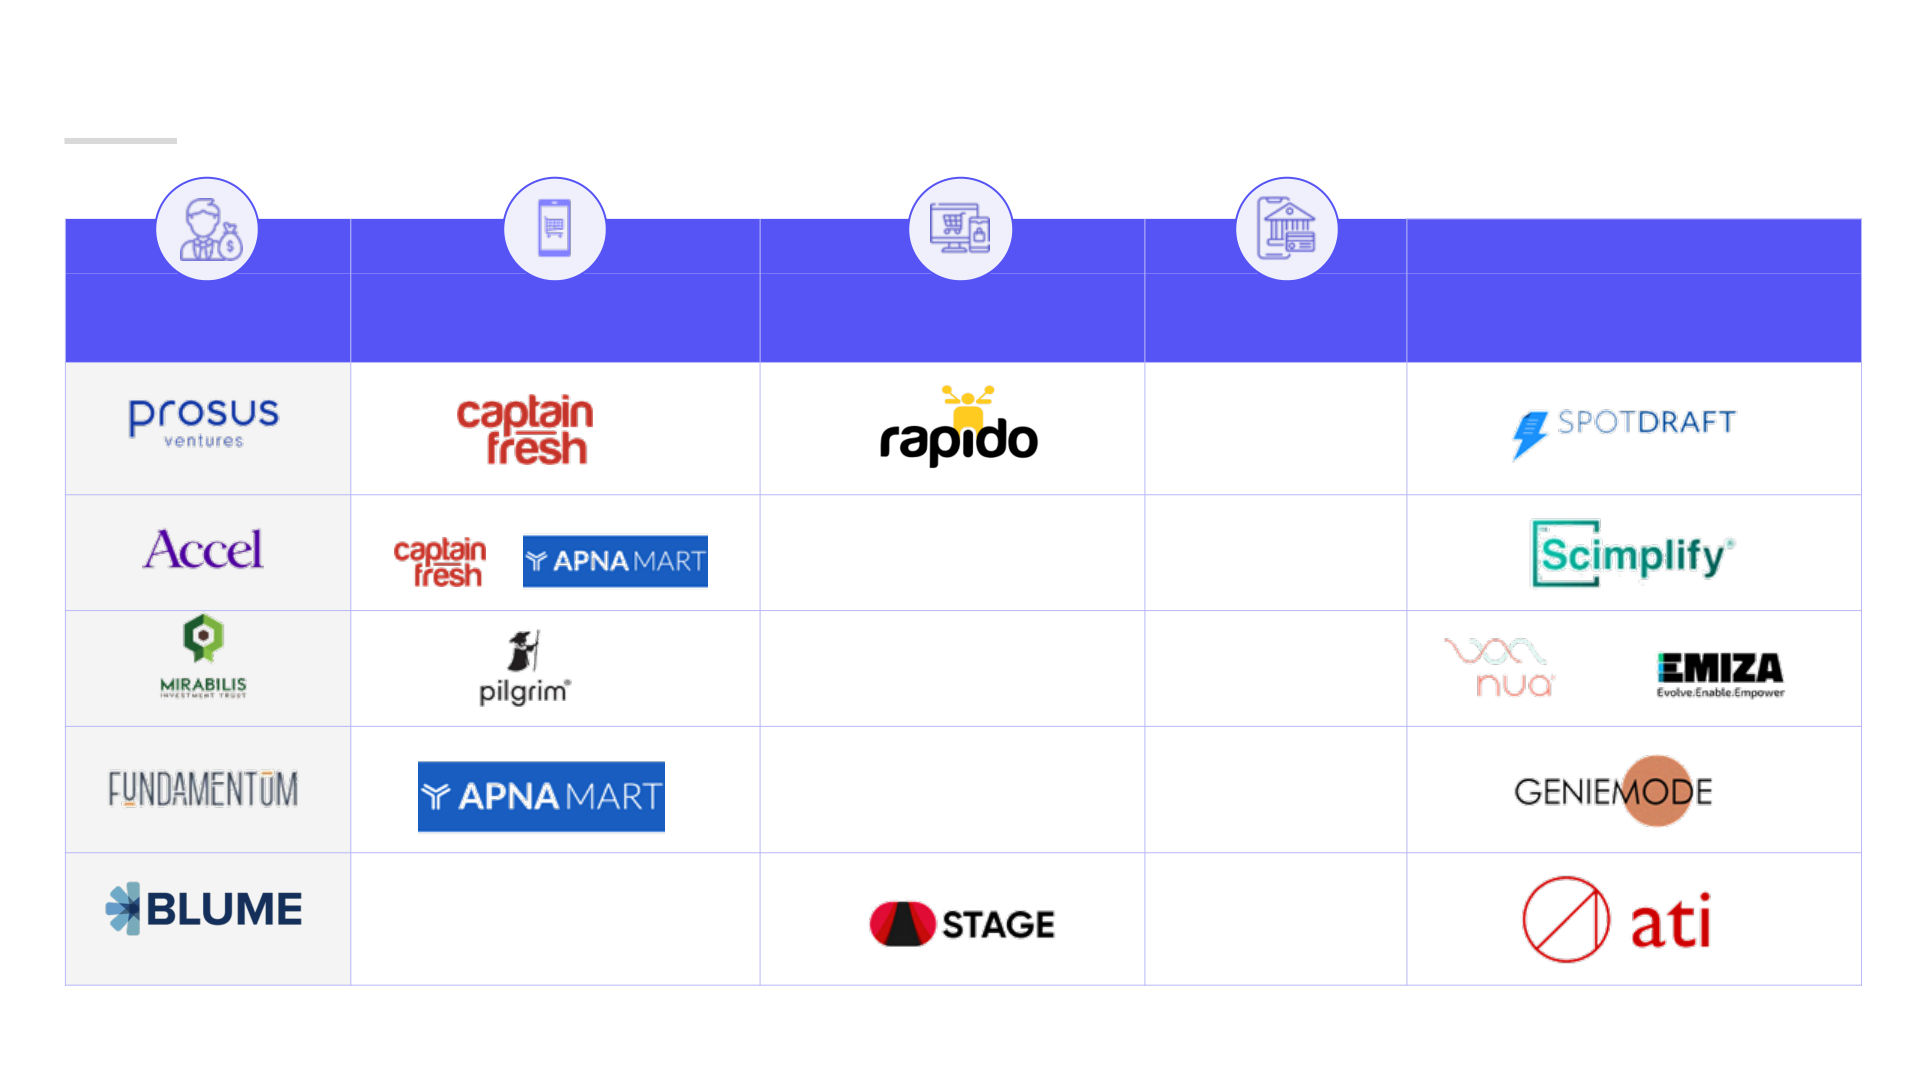
INDIA QUARTERLY INVESTMENT ANALYSIS Q1 CY 2025 May 2025 Foreword Projected to reach US $ 10 trillion economy by 2032 , India’s economy remains resilient, fueled by reforms that improve the business landscape . Its strategic geopolitical position enhances its appeal as an investment hub . Initiatives such as 'Make in India,' 'Startup India’ & Production Linked Incentive (PLI) schemes strengthen its manufacturing capabilities . India is on track to surpass major economies like the US, China, Germany, South Korea, and Japan in manufacturing . The same sentiment was reflected in Q 1 CY 2025 , when dealmaking activity improved by ~ 50 % from the previous quarter, indicating strong investor sentiment . In equity investments, late funding has led the funding rounds (by value), representing ~ 30 % of total funding rounds, particularly in sectors like SaaS/AI, BFSI, and Ecommerce & listing platforms . Startups with solid fundamental metrics, mature operating metrics & sustainable growth characteristics are well - positioned for expansion, supported by a strong user base & brand identity . Strong investor sentiment in Q 1 CY 25 was also marked by a ~ 70 % rise in deal volume compared to Q 4 Devmalya Mukherjee CY 24 . However, average deal size saw a marginal decrease from ~US $ 22 M in Q 4 CY 24 to ~US $ 19 M in Q 1 CY 25 . The Debt deal space also saw exciting growth of ~ 50 % (by value) in Q 1 CY 25 , contributing only Director, Financial Investors ~ 6 % to total deal amount . The rapid growth of India's economy has fueled the expansion of mid - sized businesses, which are increasingly turning to Debt for tailored financial solutions, thanks to its ability to offer flexible structures In addition to a strengthening economy, supportive government policies and continuous infrastructure improvements enhance the investment climate in India . The relentless focus on technological advancement and innovation, fueled by startups, remains a key catalyst for growth . This report aims to uncover some of the key trends during Q 1 2025 . At 1 Lattice, we hold an optimistic outlook, believing that this report will provide valuable insights . We eagerly anticipate the opportunity to engage in an open dialogue with our partners across diverse industries, as we exchange notes and delve deeper into these matters while closely monitoring the evolving situation . © 1Lattice | 2 Product in Spotlight - DealPulse This report was curated using our cutting - edge product, DealPulse . DealPulse offers end - to - end visibility into investment activity, empowering stakeholders with data - backed insights into sector performance, investor behavior , and funding trends. This report offers a detailed view of India’s Q1 CY25 investment landscape , shaped by robust macroeconomic fundamentals and rising investor interest across key sectors. DealPulse enabled our team to analyze evolving deal sizes, funding rounds, investor preferences, and regulatory impacts with precision. By leveraging DealPulse , we identified emerging hotbeds of investment, sectoral momentum, and strategic signals that help businesses and investors make better decisions. Stay future - ready — let DealPulse power your investment decisions. Key takeaways Funding landscape & investment dynamics • Startups raised ~ US $ 7 B across 367 deals in Q 1 CY 25 , signaling an increase in total funding (~ 49 % by value) on a QoQ basis ; Deal volume increased from 217 deals in Q 4 CY 24 to 367 deals in Q 1 CY 25 • Early - stage investments activity witnessed a ~ 9 % increase in deal volume and ~ 50 % in funding value QoQ, signaling strong momentum in the startup ecosystem – Late - stage investments grew up by ~ 40 % , reflecting renewed investor confidence – Debt deals saw an upswing, with deal value increasing by ~ 50 % in value QoQ • Average deal size marginally decreased in Q 1 CY 25 to ~US $ 19 . 2 M from ~US $ 21 . 7 in Q 4 CY 24 Sectoral focus & key deals • SaaS/AI and BFSI sector led Q 1 funding with ~ US $ 1 . 8 B & 1 . 5 B respectively, closely followed by Healthcare & Life Sciences with ~US $ 1 B funding • Highways Infrastructure Trust (~US $ 0 . 6 B) and Manappuram Finance Limited (~US $ 0 . 5 B) received the highest funding in Q 1 CY 25 • SaaS/AI dominated all the funding stages – early - stage funding (~US $ 0 . 4 B), growth - stage funding (~US $ 0 . 5 B), and late - stage funding (~US $ 0 . 6 B) • Impetus, Innovaccer, and QBurst emerged as the top fundraisers among tech companies in Q 1 CY 25 • Accel ( 9 deals) , Inflection point ventures ( 6 deals) , Unicorn India Ventures ( 4 deals) , led early - stage investments in Q 1 CY 25 followed by Anicut Capital and Nexus Venture partners ( 3 deals each) • Prosus Ventures, Accel, Mirabilis Investment Fund ( 3 deals each) led growth - stage investments followed by Fundamentum and Blume ventures (with 2 deals each) Key highlights Average ticket size Deal v olume Funding US$ 19.2M 367 US $ 7 B SNAPSHOT Q1 CY 2025 Top funded sector Total equity funding Most funded stage* SaaS/AI US$ 5.8B Late Note(s): *Most funded stage is with respect to its volume Funding market by funding round Debt (US$ 1.2B) and Series B (US$ 1.1B) were the highest contributors to overall funding raised in Q1 CY25 Total funding size: US$ 7B Funding market round wise break - up (US$ B, Q1 CY25) 1.2 0.9 0.7 0.6 Debt Buyout Series F Series A 0.4 Series C 1 .1 0.8 0.6 0. 5 Series B PE Seed Series D 0.1 0.1 Others Series G Consists of Series E, Pre seed, PIPE, Pre series A Source(s): 1Lattice Deals Database © 1Lattice | 6 Funding market by sectors SaaS/AI (~US$ 1.8B) and BFSI (~US$ 1.5B) saw the most interest from investors, followed by Healthcare (~US$ 1B) in Q1 CY25 Funding market sector wise break - up Total funding size: US$ 7B (US$ B, Q1 CY25) 0.8 Consumer apps & platforms 1.0 Healthcare & Lifesciences 1.8 1.5 SaaS/AI BFSI 0.2 0.2 0.3 Energy FMCG Manufacturing 0.8 Ecommerce & Listing 0.1 platforms 0.1 0.2 Eng. & Others IT Services Cons. Note(s): *Others include retail, telecom, transport & logistics, space tech, and drone tech © 1Lattice | 7 Source(s): 1Lattice Deals Database Funding market by sectors SaaS/AI sector saw the highest deal volume from investors (85 deals), followed by Consumer app & platform (54 deals) in Q1 CY25 Funding market segment wise break - up Total deal volume: 367 Total deal volume: 367 (#, Q1 CY25) 54 39 30 30 Consumer app Healthcare & BFSI FMCG & platform Lifesciences 5 85 15 Eng. & cons. Others SaaS/AI 16 33 41 Manufacturing E - commerce & Retail 5 13 listing platforms Transportation Energy IT Services 1 Note(s): *Others include telecom, space tech, and drone tech © 1Lattice | 8 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q1 CY25 Key deals and investment themes Key investors Top 10 highest funded companies Highways Infrastructure Trust has received the highest investment (US$ 647M), followed by Manappuram Finance Limited (US$ 508M) in Q1 CY 2025 647 - Equity deals - Debt deals 508 Top 10 highest funded companies of Q1 400 CY 2025 (US$ M) 350 140 200 275 200 200 270 Source(s): 1Lattice Deals Database © 1Lattice | 10 Investment amount and # deals Investments in Q1 CY25 have increased, with the total amount of investment going up to $7B from US$ 4.7B in Q4 CY24 Investment amount (US$ B) and # deals (Q1 CY24 – Q1 CY25) 367 318 290 229 217 11.6 10.0 8.2 7.0 4.7 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, PIPE, Buyout and Debt deals(Conventional, Venture, etc.) © 1Lattice | 11 Source(s): 1Lattice Deals Database Equity vs debt investments Both equity and debt deals saw a increase from previous quarter to US$ 5.8B and US$ 1.2B respectively in Q1 CY25 Equity investments (US$ B) and # deals Debt deals (US$ B) and # deals (Q1 CY24 – Q1 CY25) (Q1 CY24 – Q1 CY25) 345 67 275 261 43 204 9.4 4.2 162 29 7.2 22 5.8 5.8 2.2 13 3.9 1.2 1.0 0.8 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Amount Deals Amount Deals Note(s):Equity includes early (Pre - seed, seed, pre - series and Series A), growth stage (Series B, C, D and E), late (Series F onw ards) stage investments, others (PIPE and buyout) and Debt deals includes conventional debt and private credit © 1Lattice | 12 Source(s): 1Lattice Deals Database Stage - wise investments From early to Late - stage deals, there is a significant increase at every stage in the amount of investment in Q1 CY25 compared to the previous quarter Investment amount (US$ B) N = (Q1 CY24 – Q1 CY25) 290 318 318 217 368 0.1 0.9 0.8 2.4 2.7 4.5 1.2 1.5 1.0 4.2 2.1 2.2 1.8 1.5 2.1 0.7 1.6 2.0 2.3 1.9 0.8 1.2 0.7 0.8 0.4 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Early Growth Late Debt Others (PIPE & Buyout) Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards and PE dea ls) stage investments, others (PIPE and buyout) and Debt deals (Conventional, Venture, etc.); *Number of deals © 1Lattice | 13 Source(s): 1Lattice Deals Database Average deal size Average deal size decreased marginally from ~US$ 21.7M in Q4 CY24 to ~US$ 19.2M in Q1 CY25, while deal volume increased significantly Deal volume by stage Average deal size (%, Q1 CY24 – Q1 CY25 ) (US$ M, Q1 CY24 – Q1 CY25 ) 290 318 229 217 367 43.6 3% 2% 4% 5% 6% 6% 10% 5% 14% 4% 36.4 5% 29% 14% 4% 20% 22% 28.3 2% 24% 19% 21.7 19.2 74% 67% 59% 53% 47% Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Q1 CY24 Q2 CY24 Q3 CY24 Q4 CY24 Q1 CY25 Early Growth Late Debt Others* Note(s): Stage of investment here is decided by the round of investment. Pre - seed, seed, pre - series and Series A are classified as Early, Series B, C, D and E are classified as Growth, Series F onwards are classified as Late, Debt deals includes deals with Conventional, Venture, etc. *Others include deals with undisclosed rou nd, PIPE, Buyout etc. © 1Lattice | 14 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q1 CY25 Key deals and investment themes Key investors Top 10 investments in Q1 CY25 Top 10 investments in Q1 CY25 Top 10 investments in Q1 CY25 Amount Company Sector Funding stage Key Investors (US$ M) BFSI 647 Debt KKR Fund, Ontario Teachers' Pension Plan (OTPP) BFSI 508 Late Bain Capital 400 Buyout Healthcare & Life Sciences KKR SaaS/AI 350 Late Kedaara Capital B Capital Group, Banner Health, Danaher Ventures LLC, SaaS/AI 275 Late Generation Investment Management, Kaiser Permanente, M12 Tiger Global Management, Think Investments, Mars Growth Ecommerce & listing platforms 270 Late Capital, WestBridge Capital IT Services 200 Buyout Multiples PE Consumer apps & platform 200 Debt Community Investment Management SaaS/AI 200 Buyout Everstone Saa/AI 140 Growth Partners Group, KKR Source(s): 1Lattice Deals Database © 1Lattice | 16 Early - stage investments SaaS/AI received the highest funding of US$ 406M among early - stage investments; Spinny received the highest funding among the early - stage startups Early - stage investments by sector Top 10 early - stage investments in Q1 CY25 (US$ M, Q1 CY25) Amount Company Sector Key investors (US$ M) SaaS/AI 407 Ecommerce and Accel Leaders Fund, Elevation, Tiger Global, 131 Ecommerce & listing platforms 176 Listing Platform Fundamentum Kleiner Perkins, WestBridge Capital, Battery Manufacturing 142 SaaS/AI 110 Ventures, Emergent Ventures, Lightspeed Venture Partners Consumer app & platforms 95 Manufacturing 36.5 ValueQuest Investment Advisors Healthcare & Life Sciences 74 SaaS/AI 28 Piramal Alts FMCG 74 SaaS/AI 25 Khosla Ventures, Z47 BFSI 63 Energy 23 responsAbility Investments AG Energy 49 SaaS/AI 21 WestBridge Capital, Alpha Wave Global Retail 36 Healthcare & Others include 19.3 Asian Development Bank Engg. & Construction 24 Life Sciences sectors such as co - working space, Transportation & logistics space tech and 14 SaaS/AI 19 Intel Capital drone tech Others 41 Vertex Ventures, Accel, Alteria Capital, Storm SaaS/AI 16 Ventures, Note(s): Early - stage investments include Pre - seed, Seed, Pre - series A and Series A © 1Lattice | 17 Source(s): 1Lattice Deals Database Top early - stage investments Top 5 early - stage startups with their competitors (in terms of funding amount) Company Description Competitors Spinny is a new age used car end - to - end platform in India Nexthop AI is an infrastructure startup building the most efficient Al infrastructure for the world's largest cloud operators India's leading product technology company for Aerospace, Defence and Homeland security Findi provides financial empowerment and convenience to all citizens of India, while ensuring secure, accessible and efficient payments for the customers Atomicwork is the leading provider of agentic service management solution, empowering IT teams to achieve more for their business Source(s): 1Lattice Deals Database © 1Lattice | 18 Growth - stage investments SaaS/AI sector dominated the growth - stage investments with funding of ~US$ 532M followed by Consumer app & platforms(~US$ 212M) Growth - stage investments by sector Top 10 growth - stage investments in Q1 CY25 (US$ M, Q1 CY25) Amount Company Sector Key investors (US$ M) SaaS/AI 532 SaaS/AI 140 Partners Group, KKR Consumer app & platforms 212 Healthcare & 109 Kotak Alts Life Sciences Healthcare & Life Sciences 199 Point72 Private Investments, Qualcomm Ventures, SaaS/AI 90 Pavillon Capital ValueQuest Capital, S.C.A.L.E. Fund, Elevate BFSI 187 SaaS/AI 78 Innovation Partners LLC Consumer app 70 Beams Fintech Fund, MUFG, BNP Paribas Cardif Manufacturing 179 & platforms Energy 57 Singularity Ventures AMC Energy 107 Vertex Ventures Southeast Asia & India, Arkam SaaS/AI 54 Ventures, Premji Invest, Prosus Ventures, Trident Partners, Xeed VC Ecommerce & listing platforms 91 BFSI 53 KRAFTON, Apis Partners FMCG 82 Craegis , HSBC, SBI Investment, GMO Venture Consumer app 51 Partners, DG Daiwa Ventures, Accel, Lightspeed & platforms Venture Partners, Sparta Group, DST Global Retail 35 Multiple Alternate Asset Management, Info Edge Manufacturing 50 Ventures, Fundamentum, Paramark Ventures Note(s): Growth - stage investments include Series B, C, D and E © 1Lattice | 19 Source(s): 1Lattice Deals Database Top growth - stage investments Top 5 growth - stage startups with their competitors (in terms of funding amount) Company Description Competitors Cloud - based suite solutions for HR management Tirupati Medicare Limited (TML) is a pharmaceutical company that focuses on contract manufacturing of Ayurveda medicines and generic pharmaceutical formulations AI - enabled safety platform that helps fleet safety in reinforcing great driving and delivering dramatic performance improvements. ToneTag harnesses the power of sound to build a robust channel of data communication to enable extraordinary experiences across businesses InsuranceDekho is an online platform that lets you compare and buy insurance quotes from top - rated insurance companies across Motor, Health, Life, Travel and other insurance from multiple companies Source(s): 1Lattice Deals Database © 1Lattice | 20 Late - stage investment Late - stage investments were driven by SaaS/AI sector (~US$ 650M) Top 10 Late - Stage investments in Q1 CY25 Late - stage investment, by sector (US$ M, Q1 CY25) Amount Company Sector Key investors (US$ M) Bain Capital BFSI 508 SaaS/AI 350 Kedaara Capital SaaS/AI 650 B Capital Group, Banner Health, Danaher Ventures SaaS/AI 275 LLC, Generation Investment Management, Kaiser Permanente, M12 Ecommerce & Tiger Global Management, Think Investments, Mars BFSI 583 270 listing platforms Growth Capital, WestBridge Capital Ecommerce & 135 Premji Invest, 360 ONE, Claypond Capital listing platforms Ecommerce & listing 537 Tiger Global Management, Evolvence , Foundamental , Ecommerce & platforms 125 listing platforms Nikhil Kamath Healthcare & 110 Kotak Alternate Asset Managers Life Sciences Healthcare & Life 223 Sciences Healthcare & 100 Quadria India Life Sciences M&G, Lightspeed BFSI 75 Consumer app & 130 platforms Consumer app & Apis Partners, Peak XV partners, Jungle Ventures, Owl 65 Ventures platforms Note(s): Late - stage investments include Series G onwards rounds © 1Lattice | 21 Source(s): 1Lattice Deals Database Top late - stage investments Top funded late - stage startups with their competitors (in terms of funding amount) Company Description Competitors Manappuram Finance Ltd. is one of India’s largest and most trusted gold loan companies, with 4,199 branches across the length and breadth of the country Impetus Technologies enables the Intelligent Enterprise with innovative data engineering, cloud, and enterprise AI services. Recognized as an AWS Advanced Consulting Partner A leading healthcare technology company that leverages a data - driven platform to streamline care delivery and enhance patient outcomes. Online marketplace and reselling platform for multi - category consumer products Provider of passenger airline services Source(s): 1Lattice Deals Database © 1Lattice | 22 Tech investments In Q1 CY25, SaaS/AI (~US$ 1.8B) and Consumer app & platform (US$ 530M) were the 2 most funded sector in the tech segment, followed by BFSI (US$ 210M) Tech investments by sector Top 10 tech investments in Q1 CY25 (US$ M, Q1 CY25) Amount Company Sector Key Investors (US$ M) SaaS/AI 1761 SaaS/AI 350 Kedaara Capital Consumer app & 530 platforms B Capital Group, Banner Health, Danaher Ventures SaaS/AI 275 LLC, Generation Investment Management, Kaiser BFSI 210 Permanente, M12 IT Services 200 Multiples PE, Others IT Services 200 Consumer app Ecommerce and 200 Creaegis, HSBC, SBI, GMO, DG Daiwa 177 & platforms Listing Platform SaaS/AI 200 Everstone Engg. & 93 Construction SaaS/AI 140 Partners Group and KKR Manufacturing 69 Ecommerce and Accel Leaders Fund, Elevation, Tiger Global, 131 Healthcare & Life Listing Platform Fundamentum, and other 21 Sciences Kleiner Perkins, WestBridge Capital, Battery SaaS/AI 110 Ventures,Emergent Ventures & Lightspeed Venture Energy 15 Partners Point72 private Investments, Qualcomm Ventures, Transportation & SaaS/AI 90 14 Pavilion Capital logistics Includes Retail, FMCG, space Engg . & 80 NIIF Infrastructure Finance Limited Others 22 tech Construction Source(s): 1Lattice Deals Database © 1Lattice | 23 0 Agenda Deal landscape in Q1 CY25 Key deals and investment themes Key investors Active investors Most active investors of Q1 CY25 Growth - stage investors Early - stage investors (# deals) (# deals) 9 3 6 3 4 3 3 2 3 2 Note(s): There are 11 late - stage investors with 1 investment each © 1Lattice | 25 Source(s): 1Lattice Deals Database Active early - stage investors Most active early - stage investors and their investment segments in Q1 CY25 Ecommerce Healthcare & Others Investors SaaS/AI Energy & listing Life Sciences - - - - - - - - - - - - Source(s): 1Lattice Deals Database © 1Lattice | 26 Active growth - stage investors Most active growth - stage investors and their investment segments in Q1 CY25 Others Investors Ecommerce & listing Consumer app & platforms BFSI - - - - - - - Note(s): *Others include sectors such as Retail, FMCG, Healthcare & Lifesciences, Transportation & logistics, etc. © 1Lattice | 27 Source(s): 1Lattice Deals Database 4 200+ Technology - backed business Offices in India Annual engagements support that helps you ENABLE BETTER 130+ 50+ Team members Inhouse research team DECISIONS 1,000+ 2M+ On - ground staff B2C Panel Deep on - ground insights that you can act on 4 offices, deep experience across geographies – 500K+ 300K+ India, the USA, Europe, MEA, and SEA regions B2B Panel Experts & professionals One - ness of data and people networks to harness the collective power of data, network, and technology 20% 100% Multi - faceted teams offering a stack of consulting, Cost savings Controlled output & timeline advisory, and research services We are here for you Amar Choudhary Devmalya Mukherjee CEO & Co - founder 1Lattice Director, Financial Investors E: amar@1lattice.com E: devmalya.mukherjee@1lattice.com For media queries, please contact Urbashree Bayan Associate Manager – Corporate Communications E: communications@1lattice.com www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in an y form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’ s o wn experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not co nstitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon diff ere nt sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for a ny unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1La ttice does not hold any liability in connection therewith. +91 881 041 9502 d evmalya.mukherjee @1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore