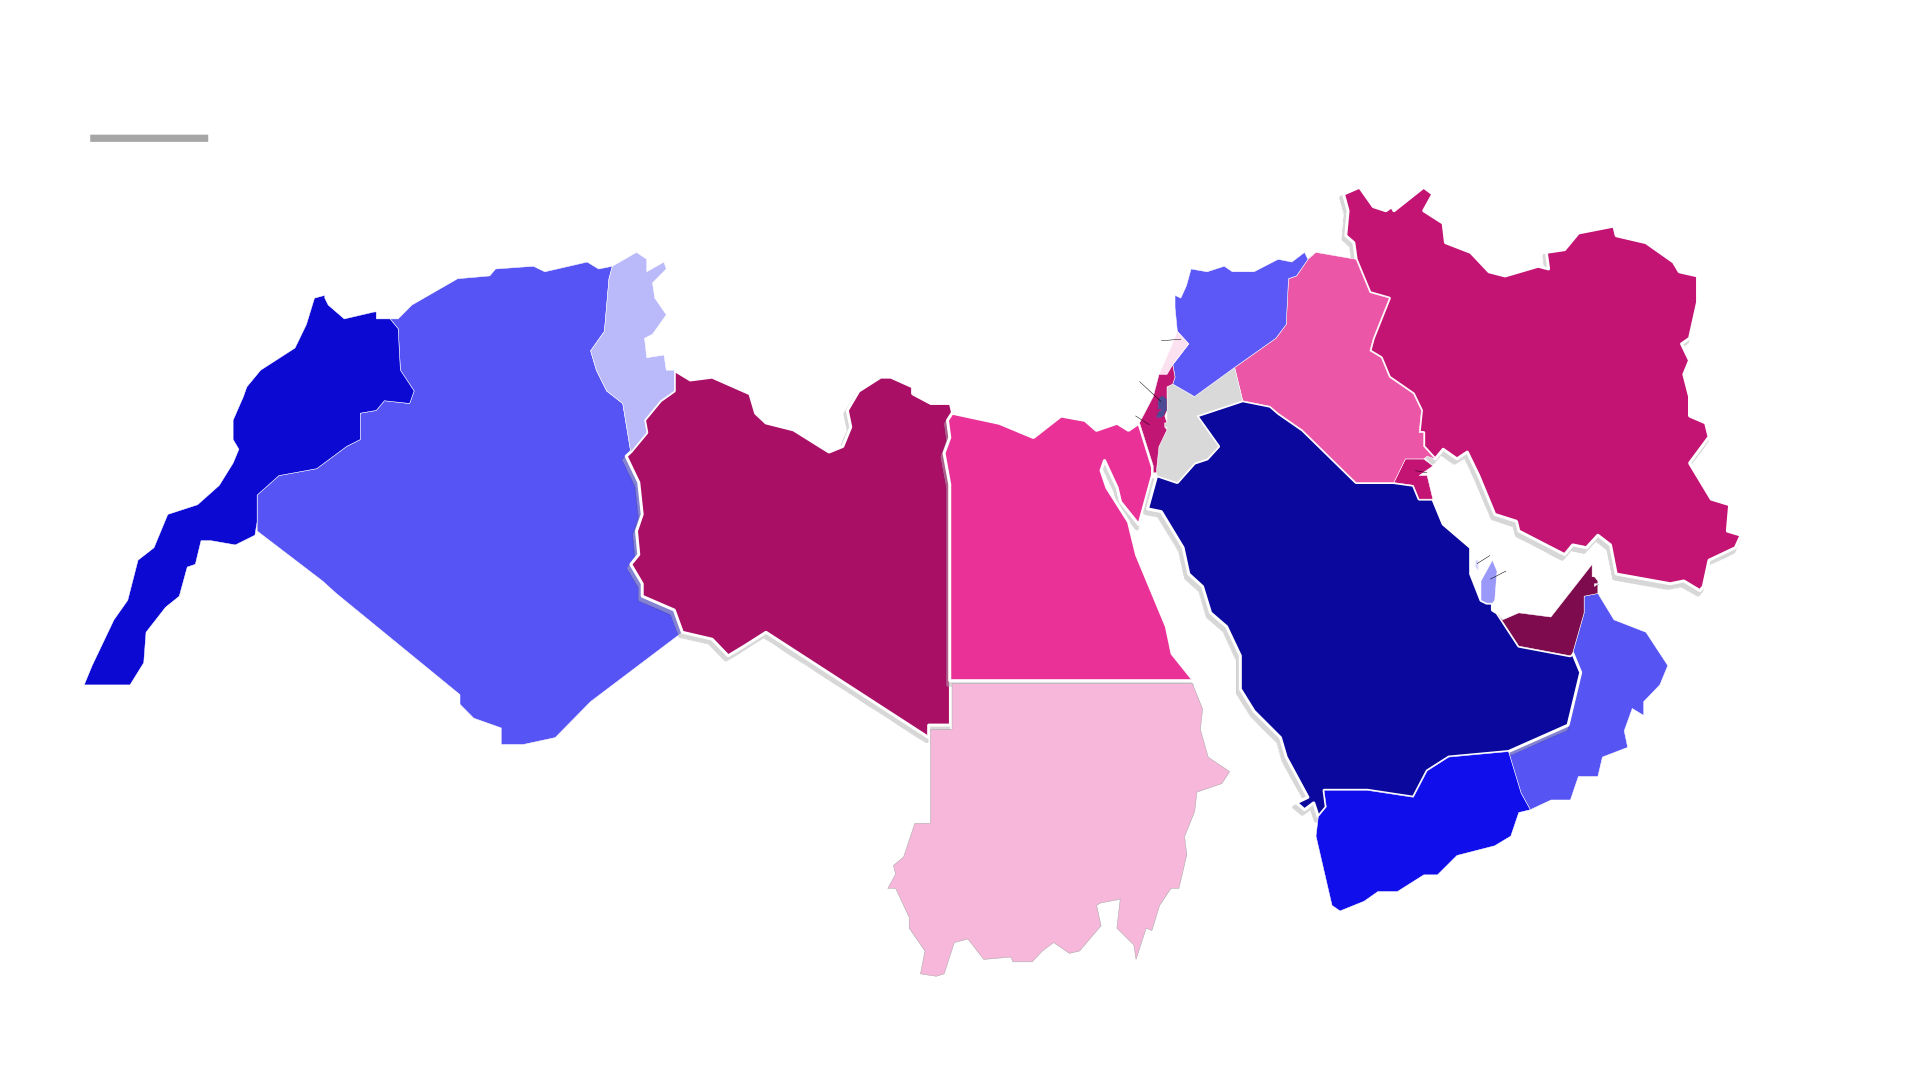
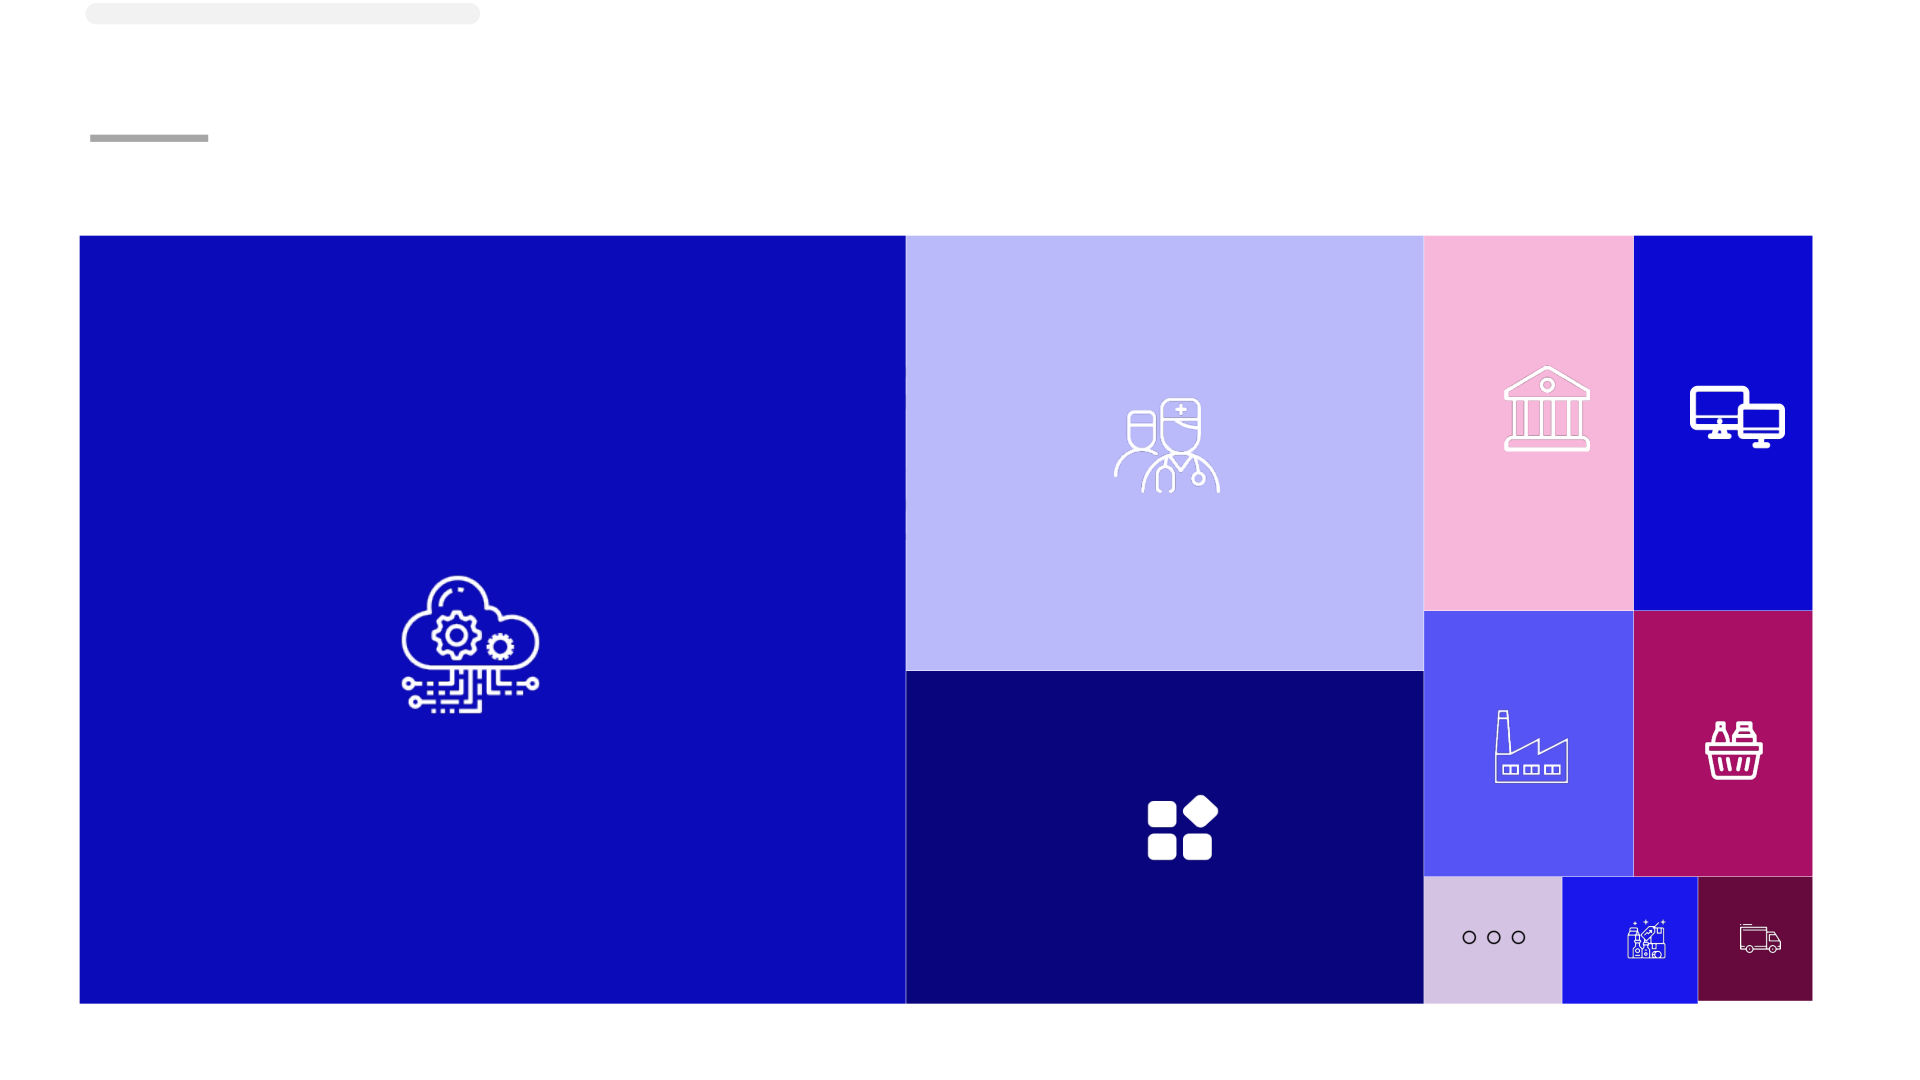
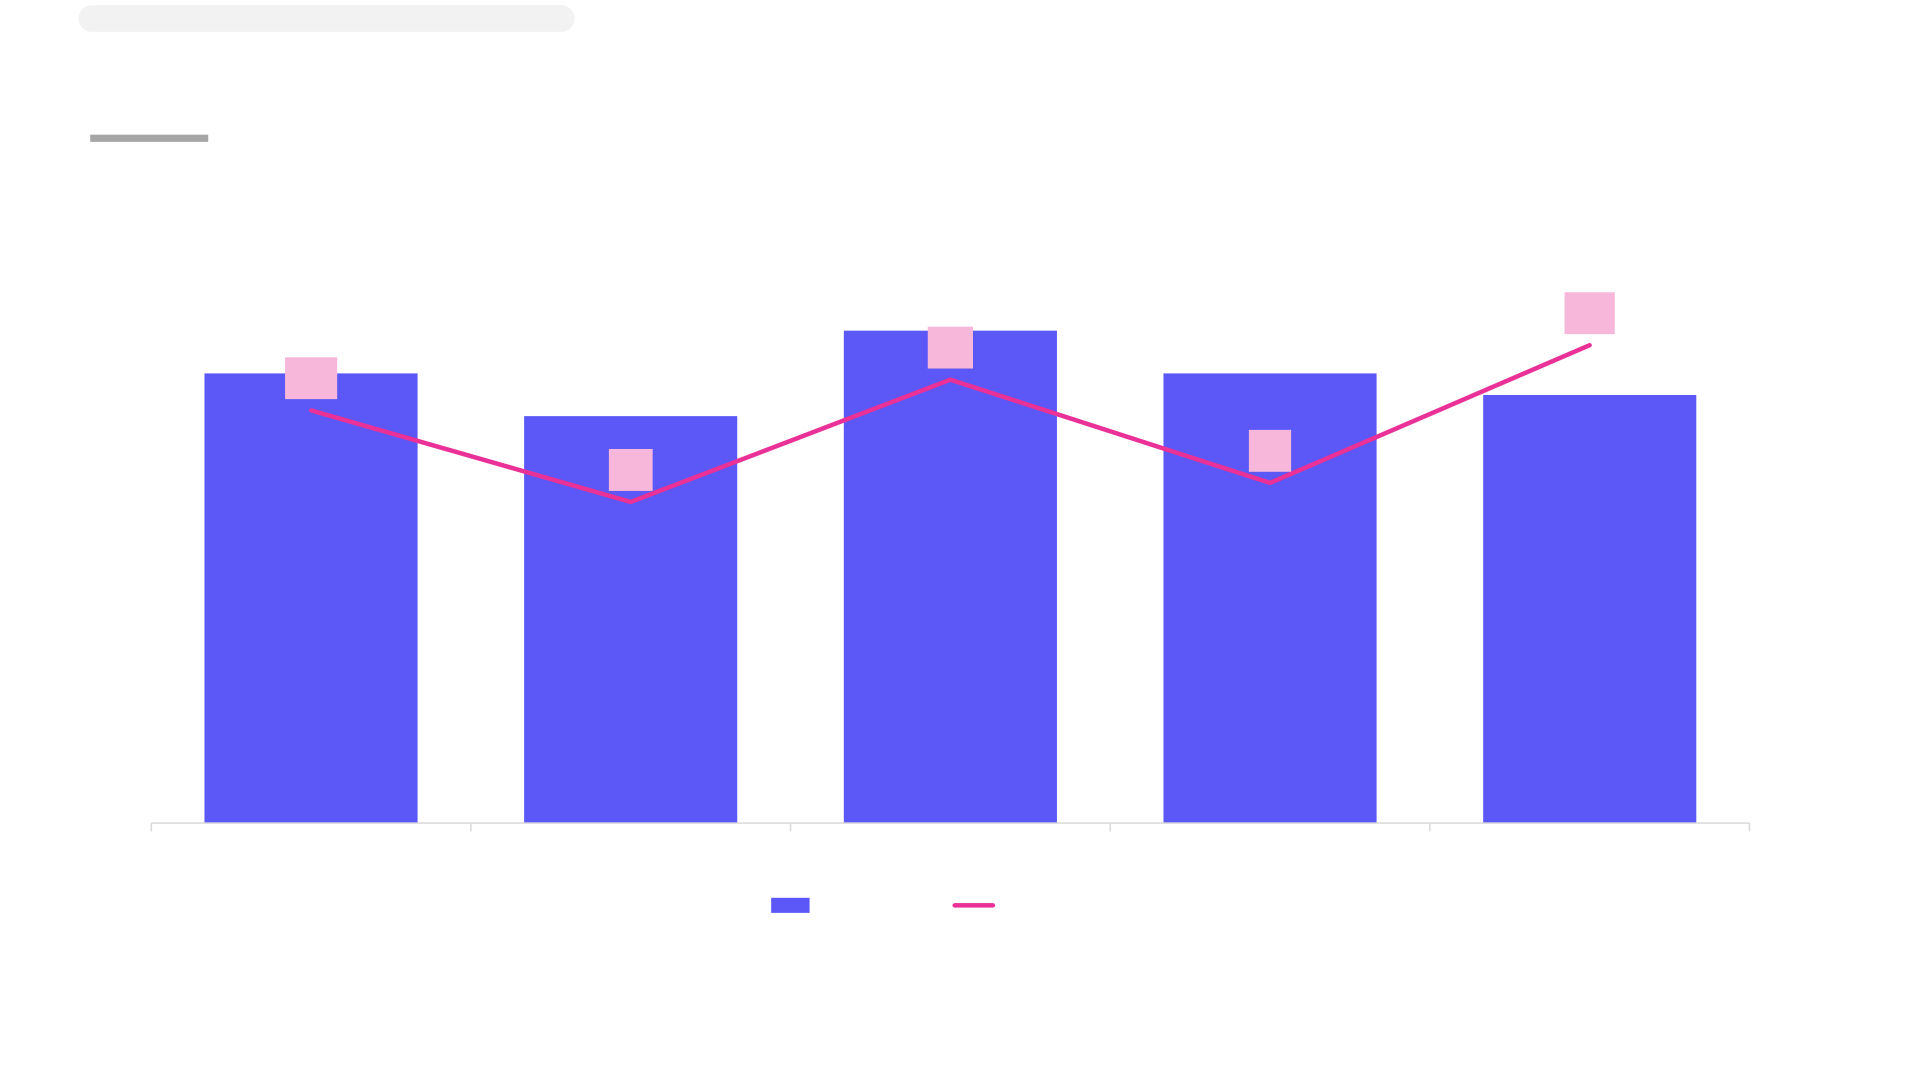
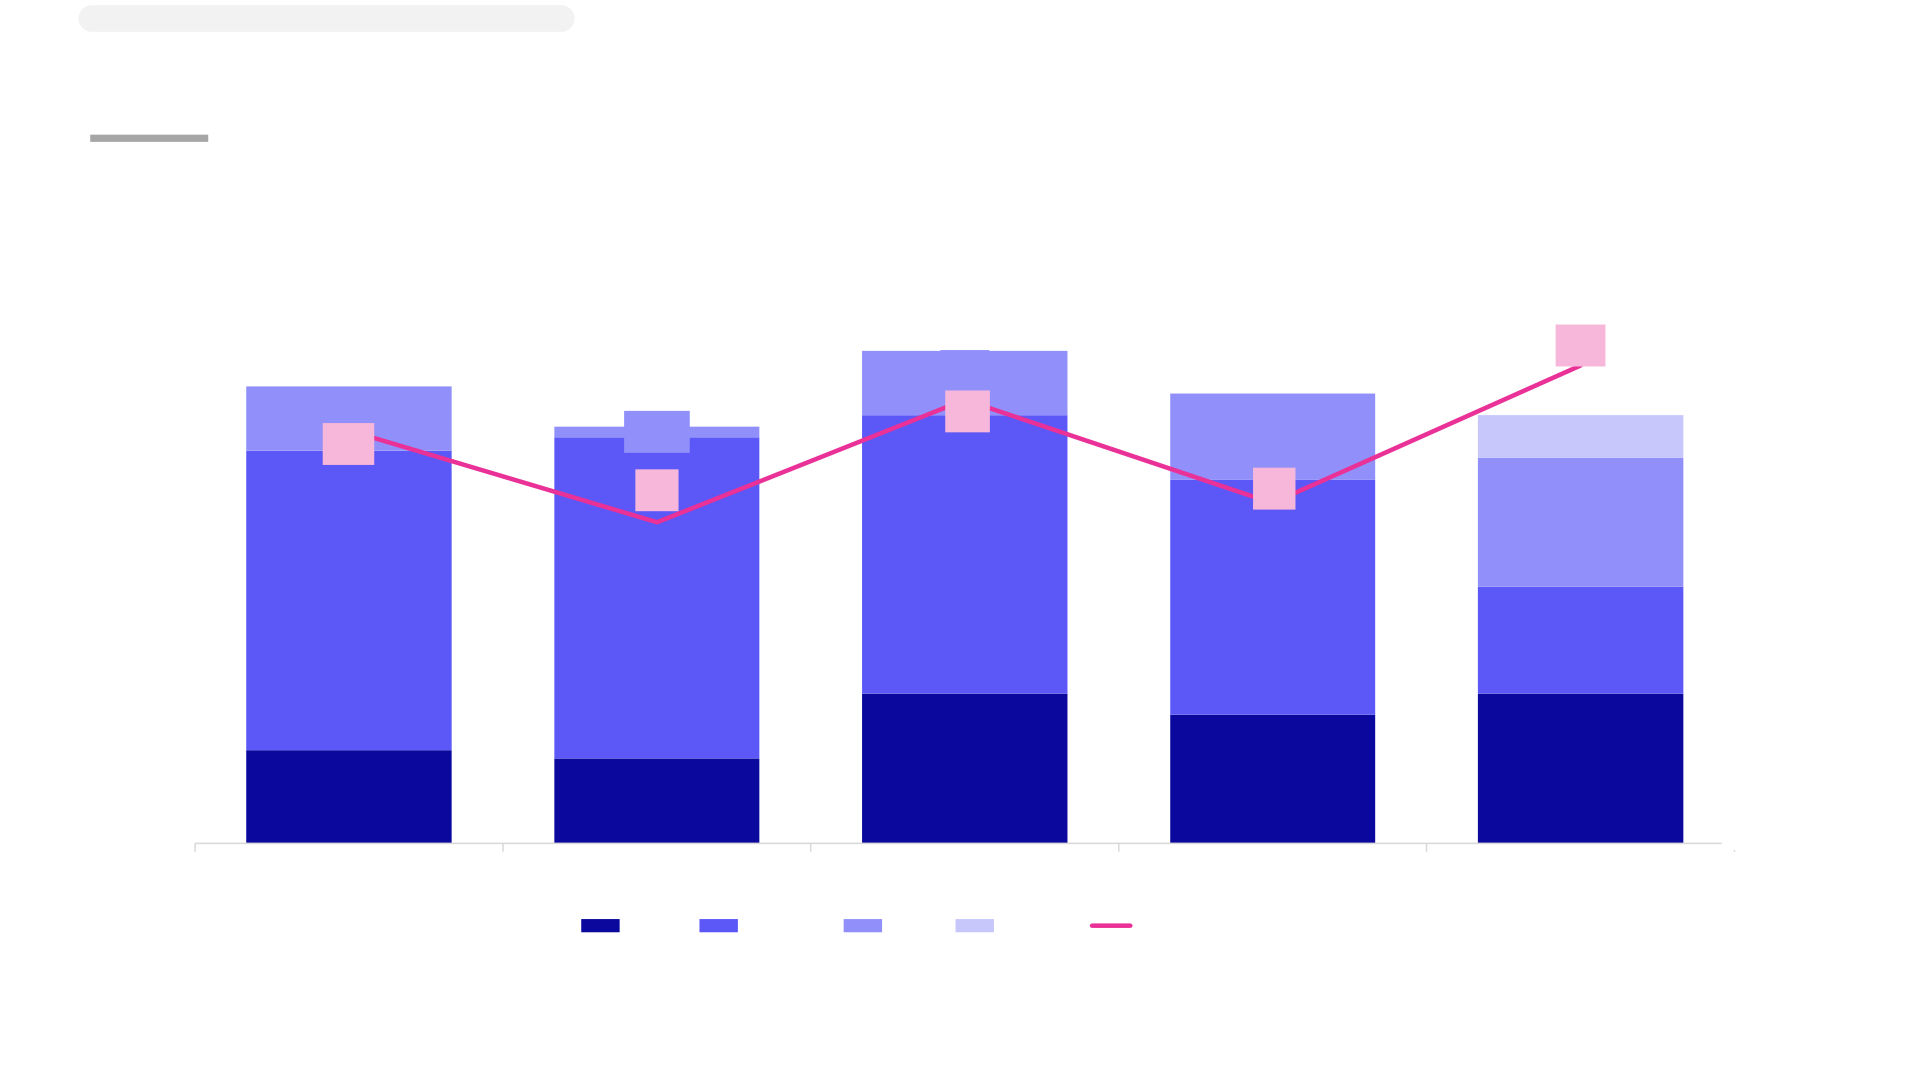
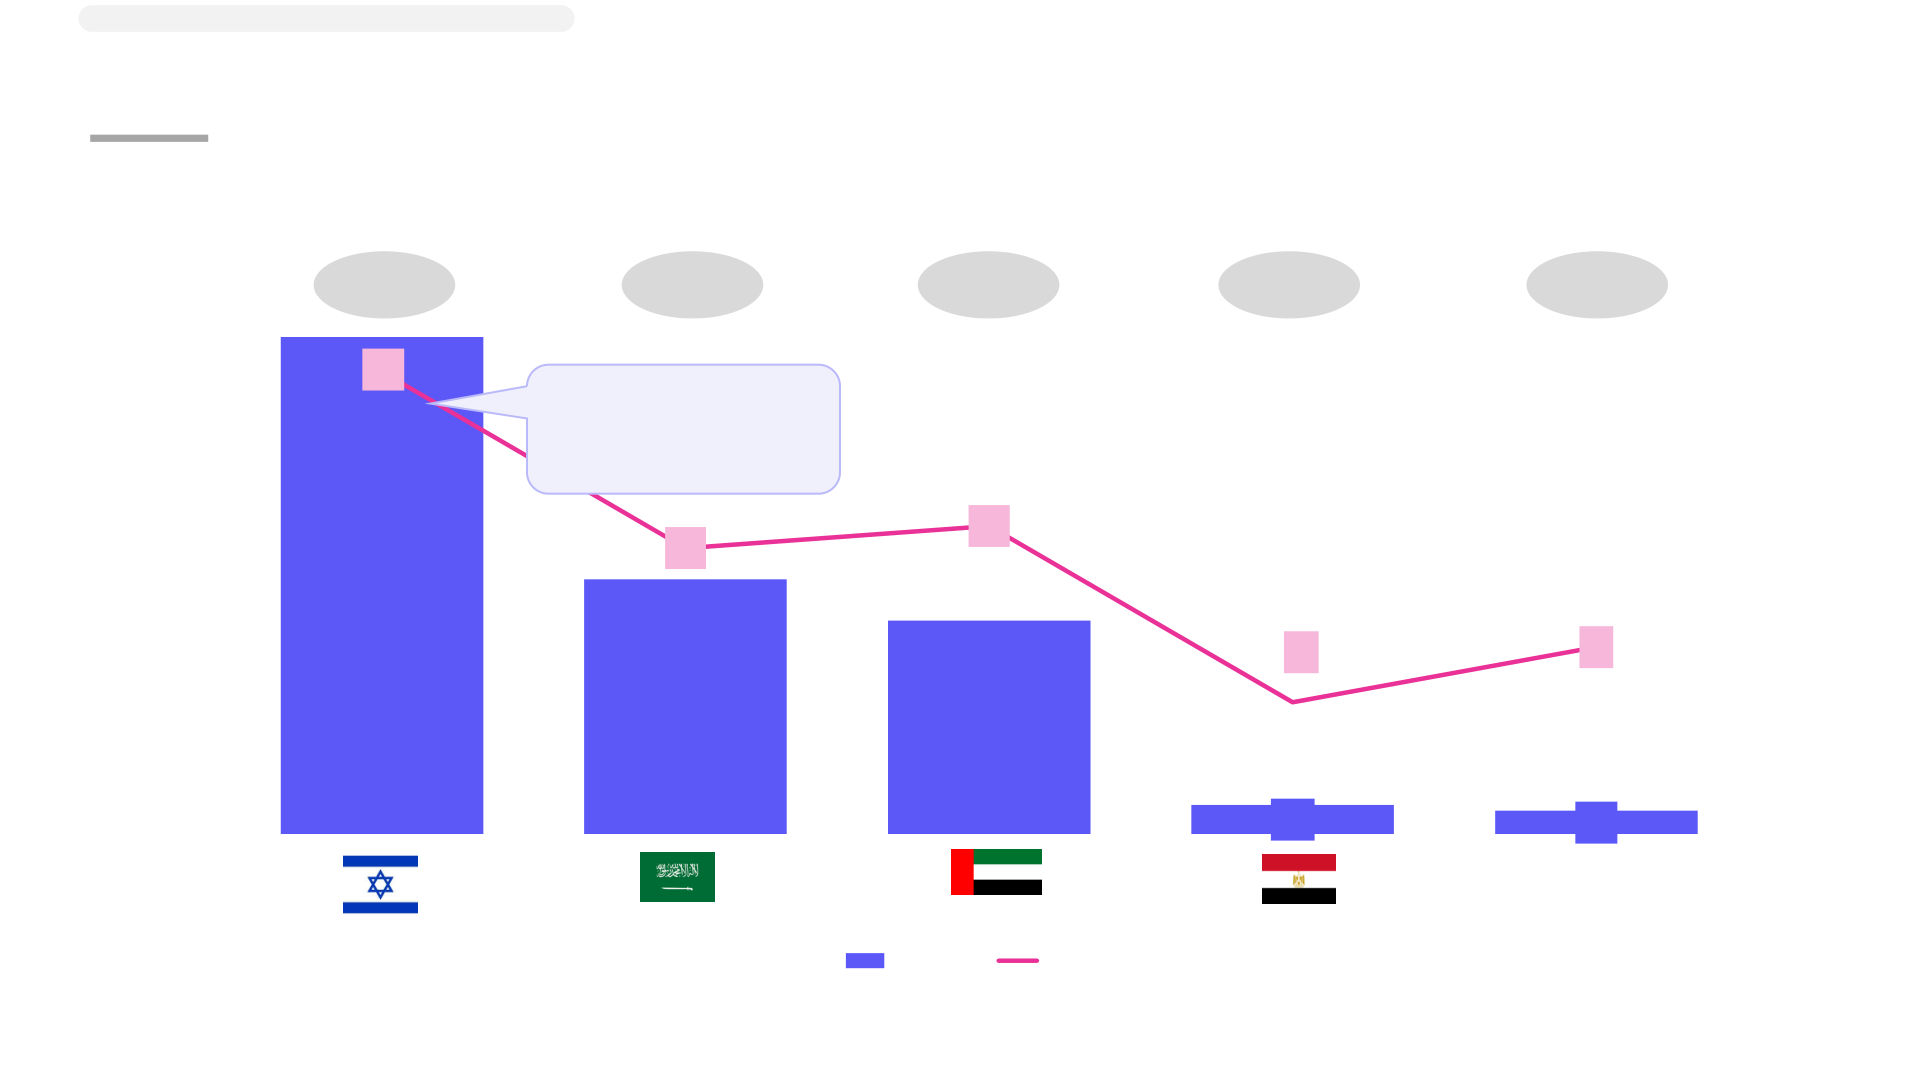
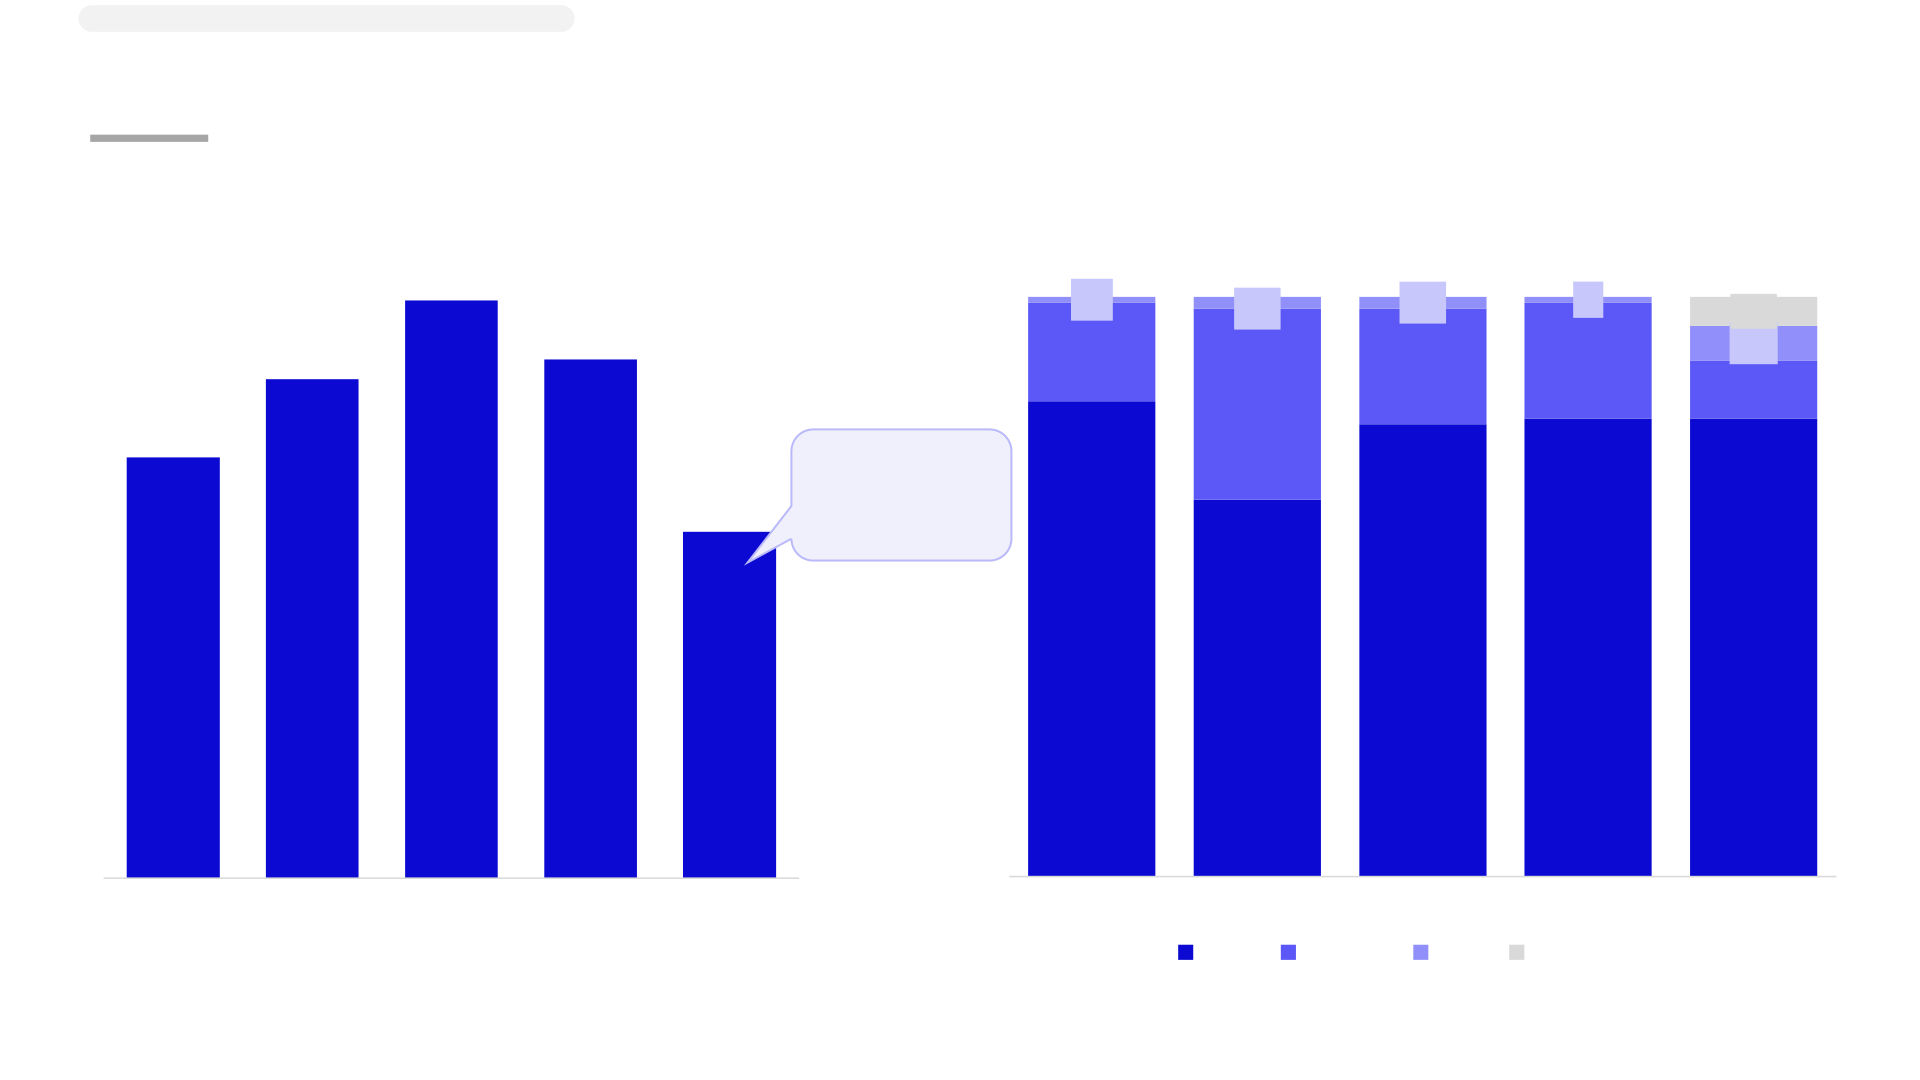
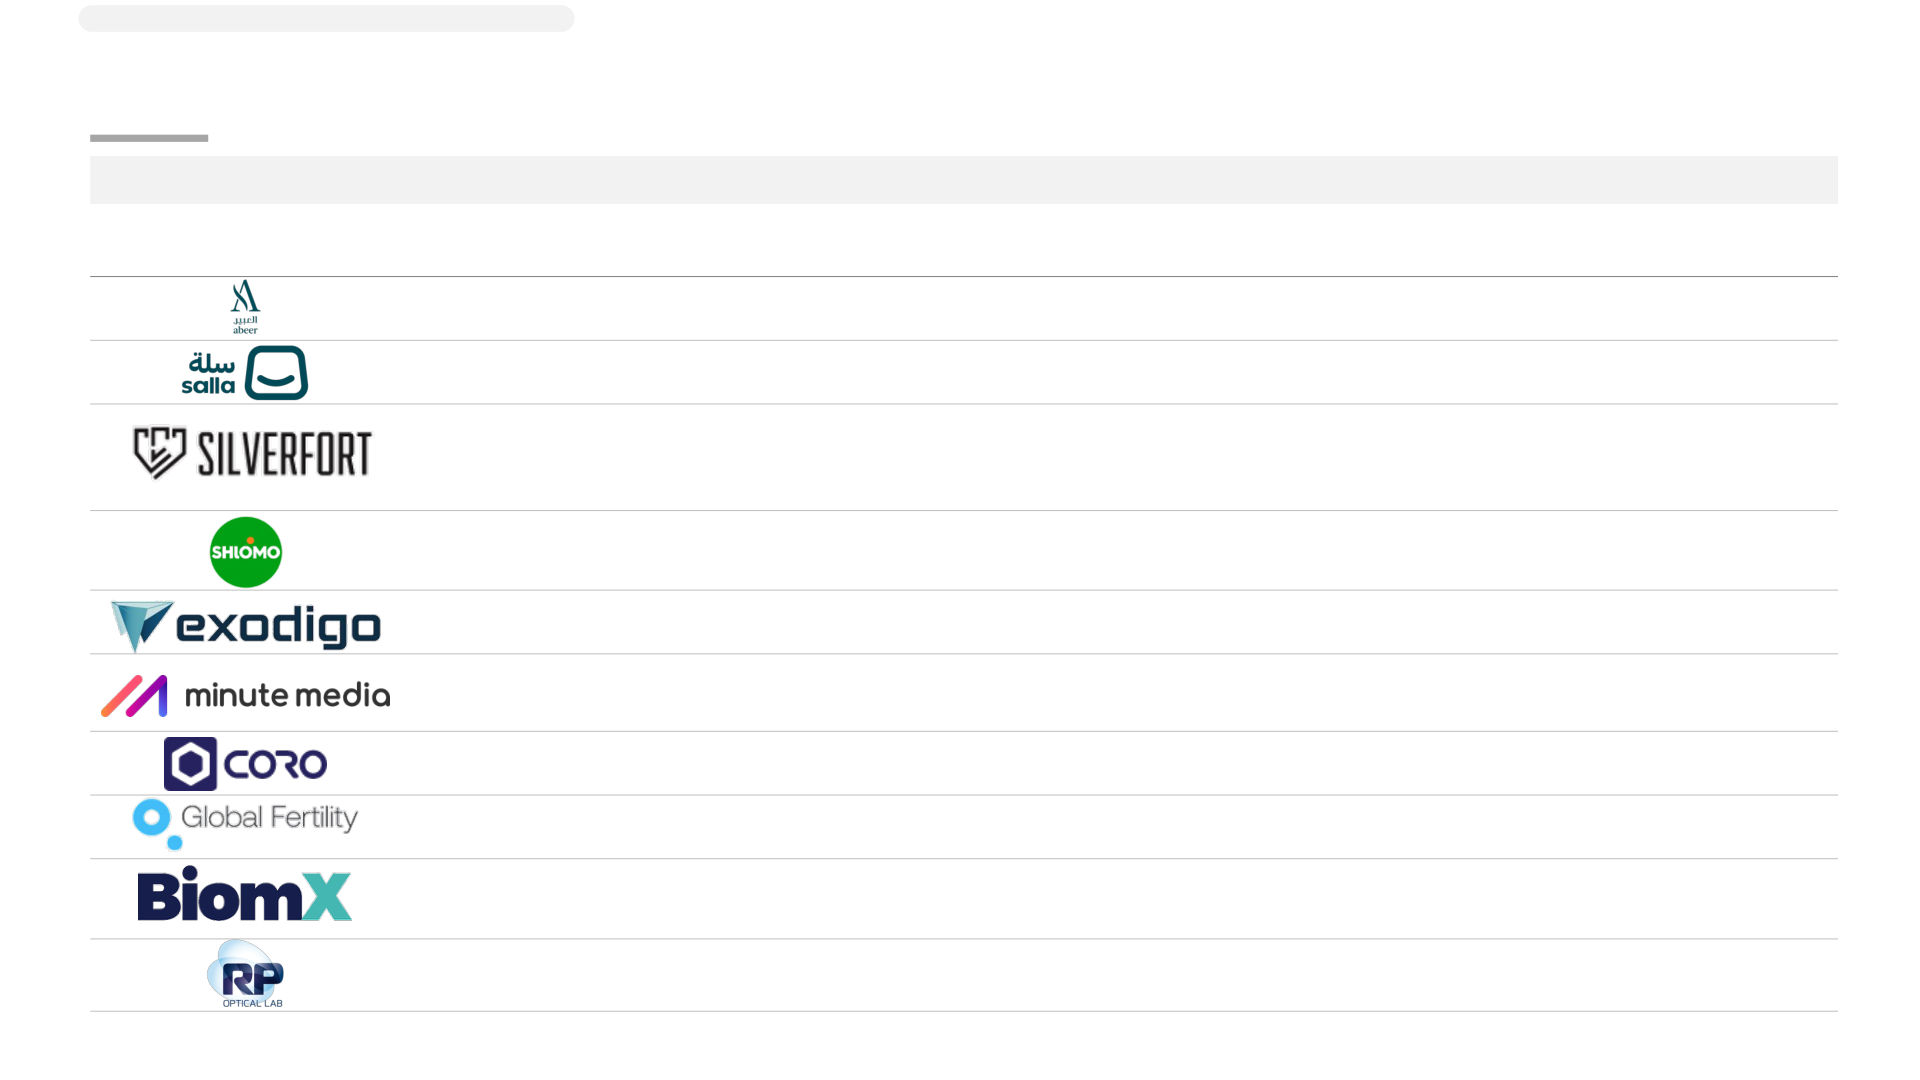
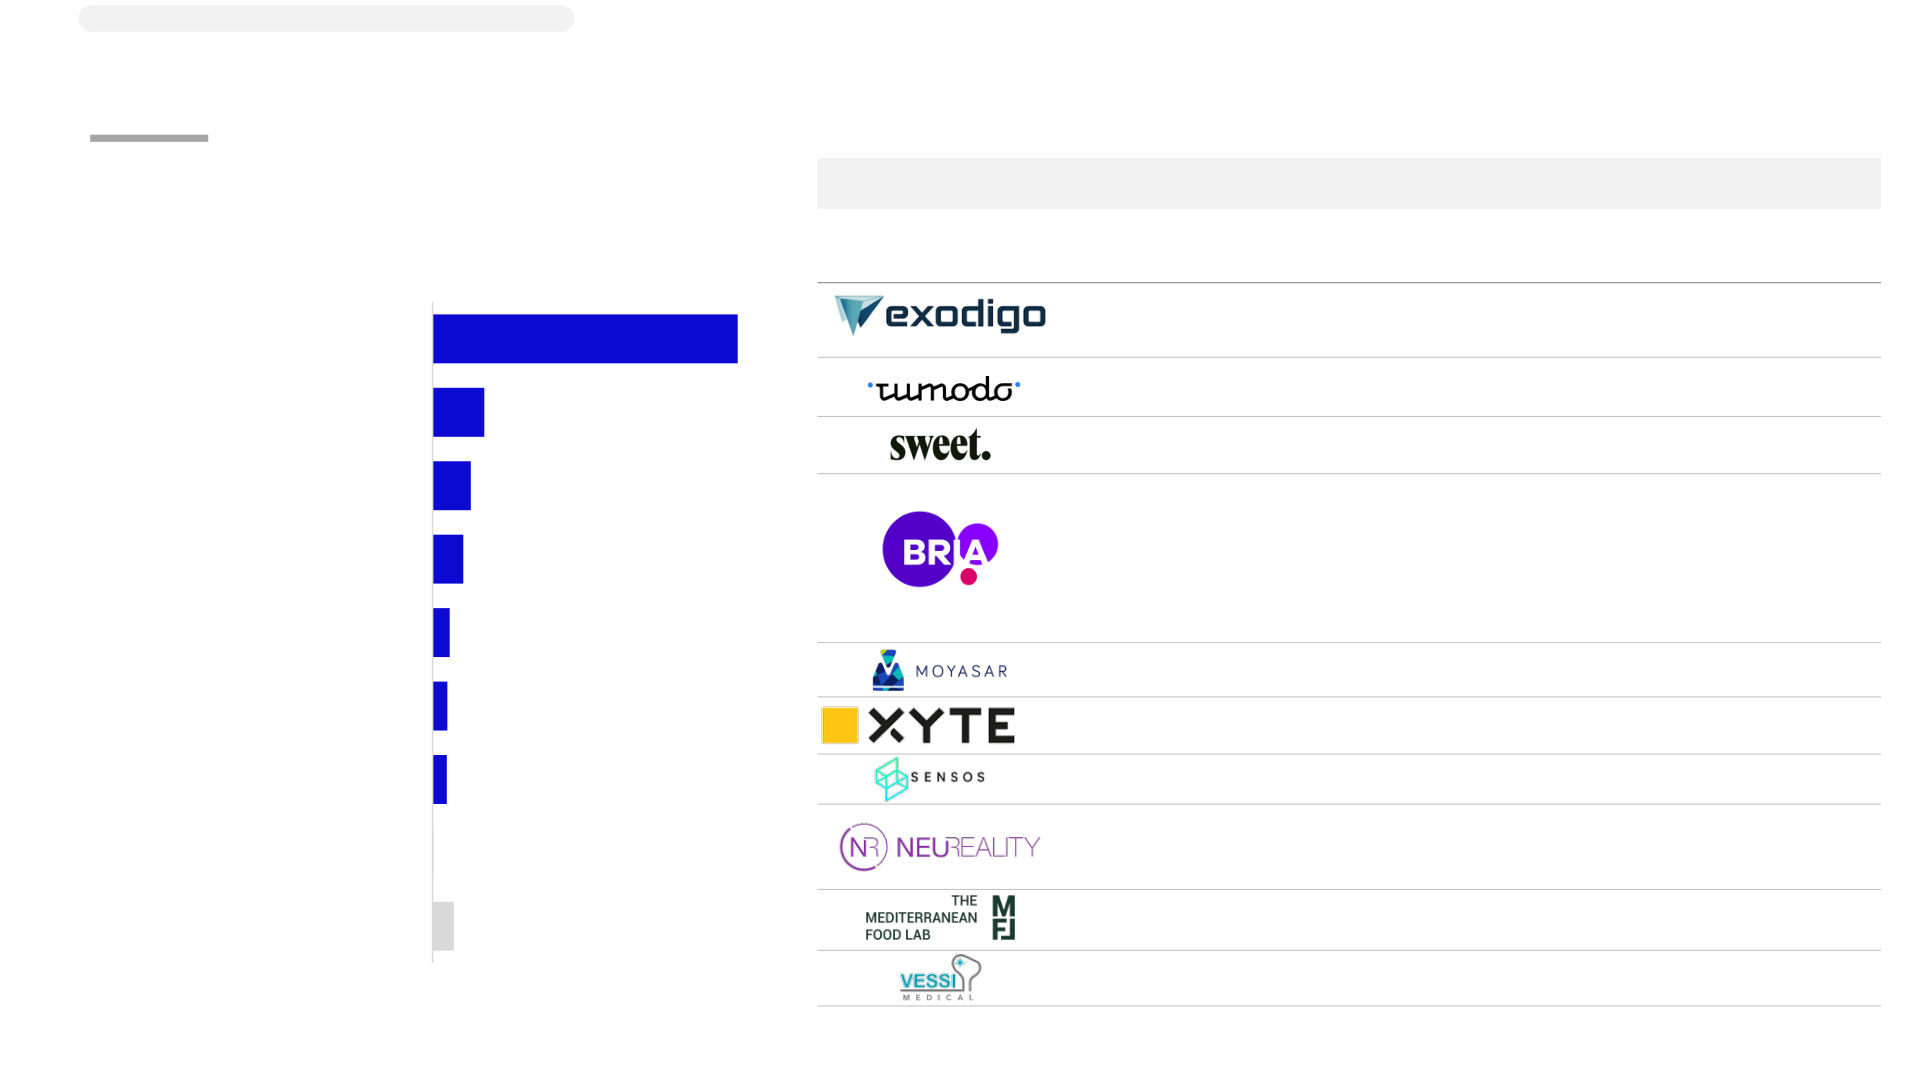
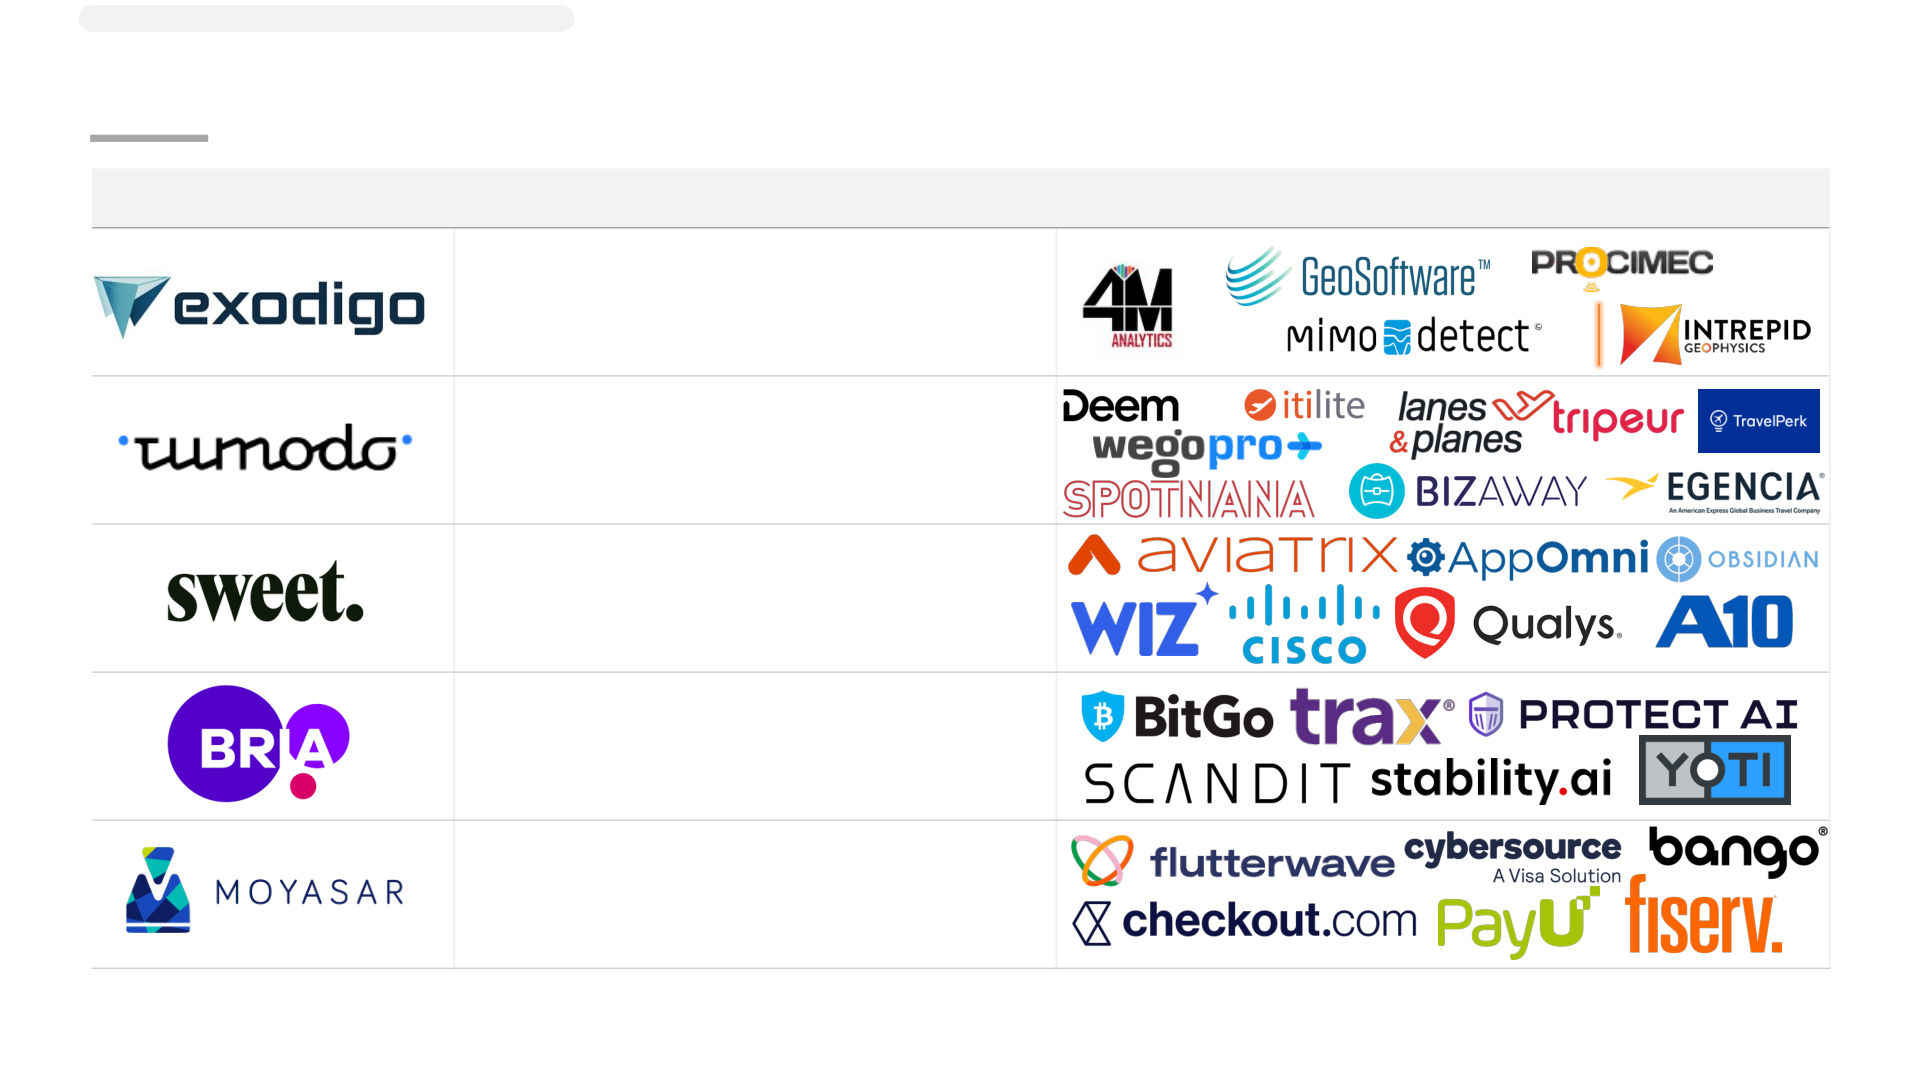
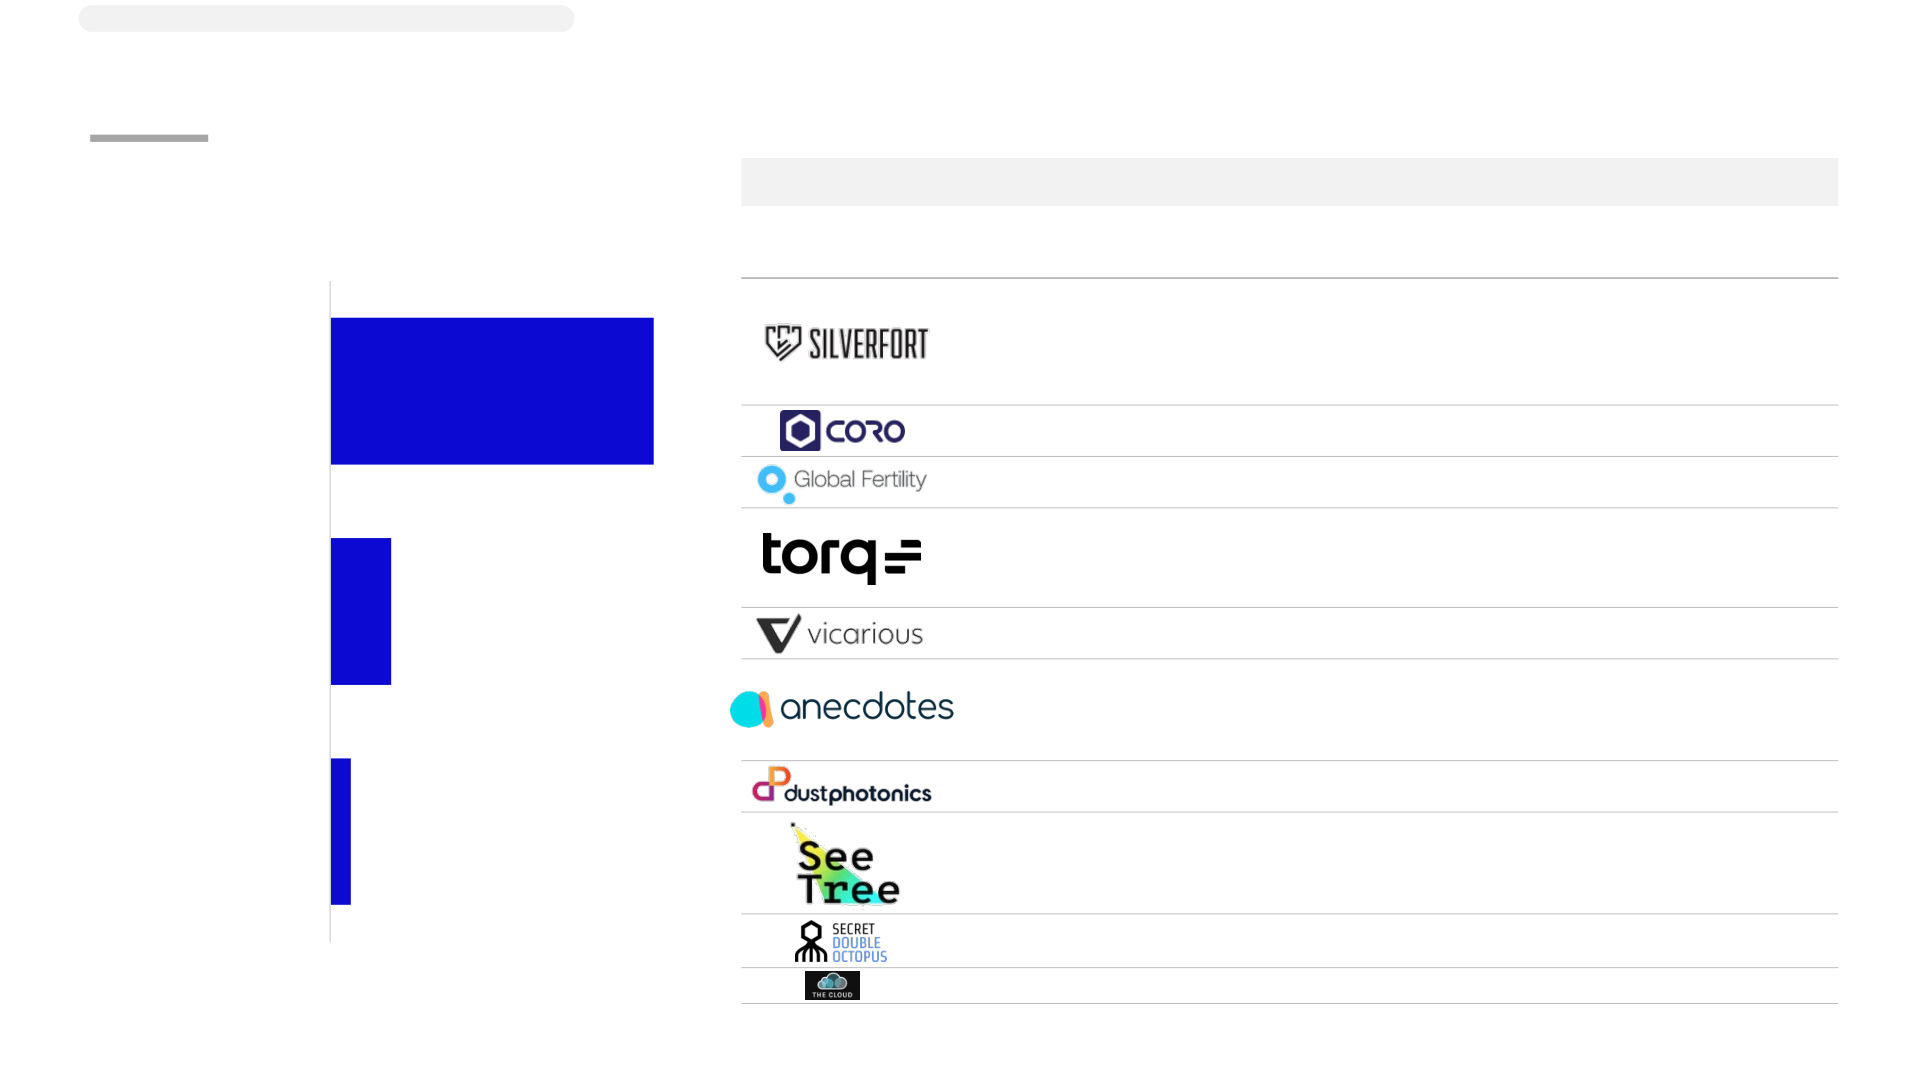
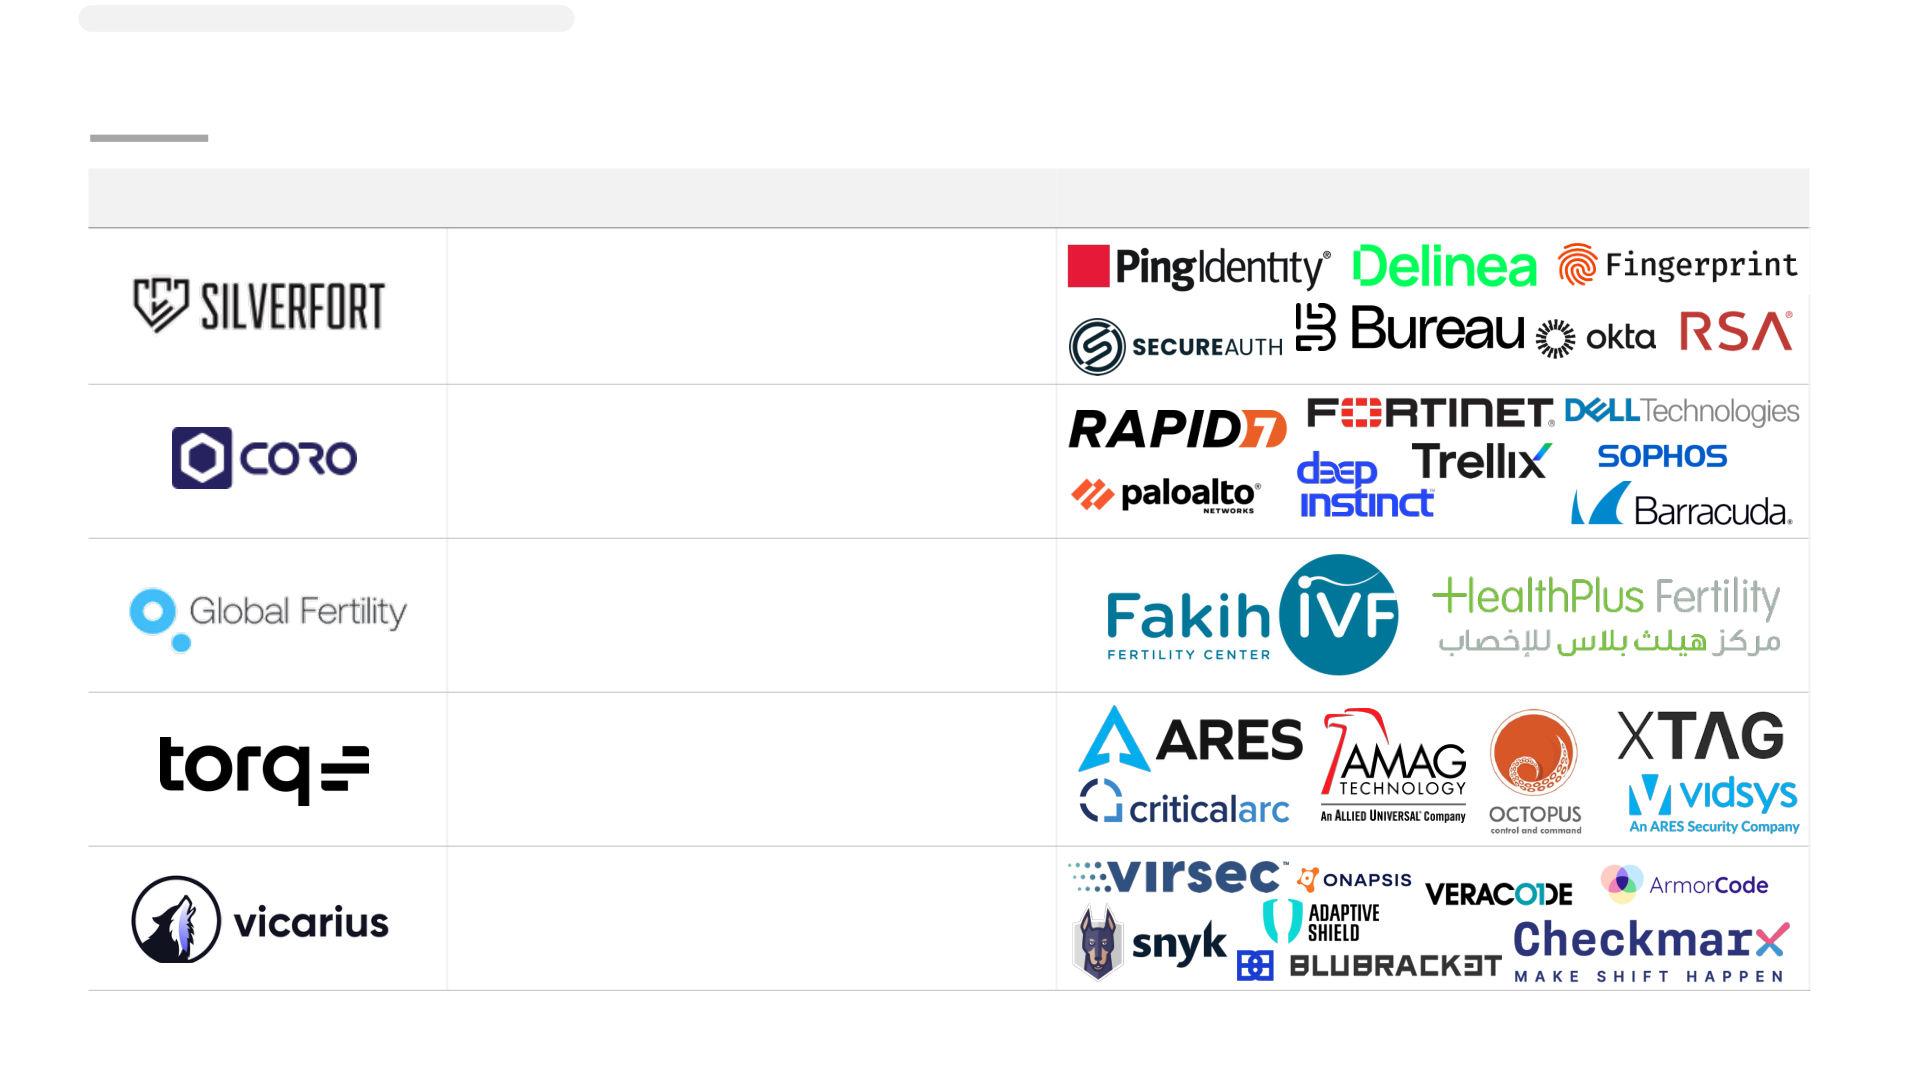
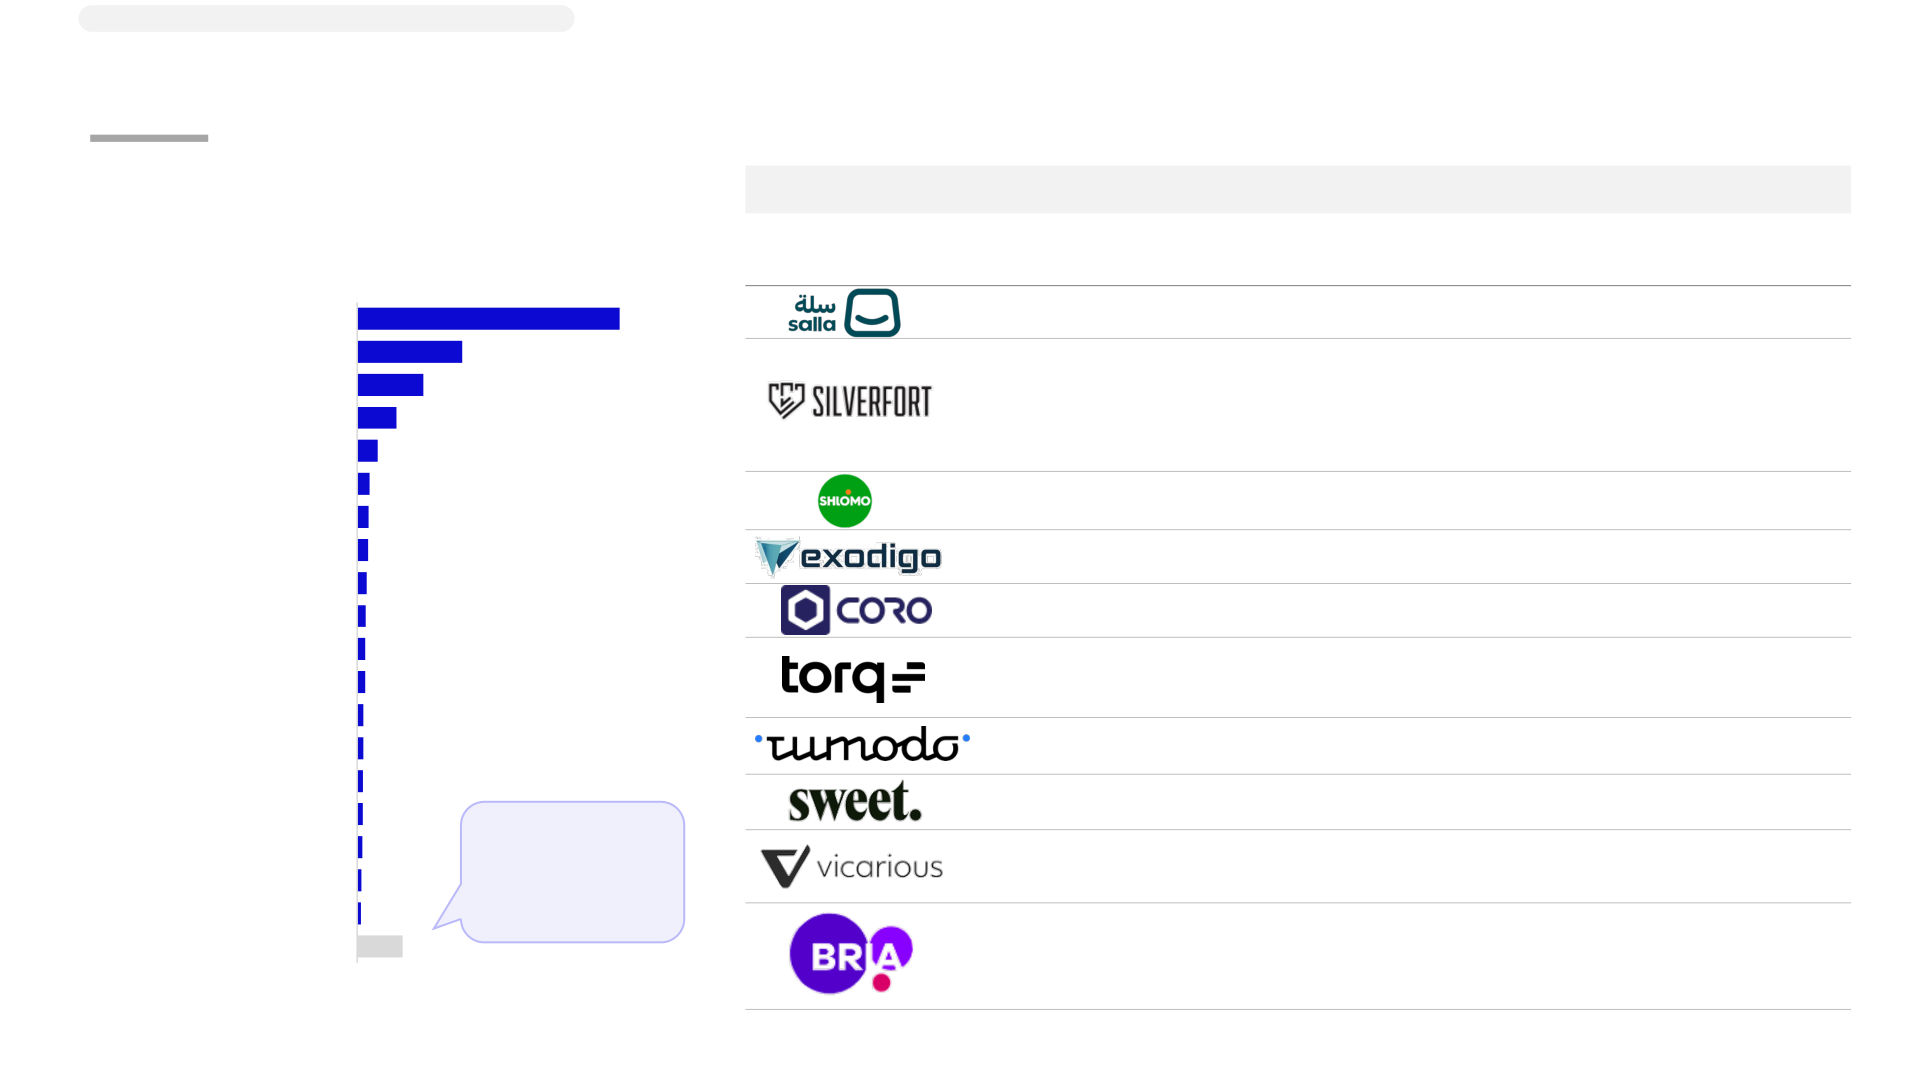
MENA quarterly investment analysis Q1 CY24 April 2024 Confidential and proprietary © 1Lattice 500+ 30% Technology - backed business annual engagements faster to outcomes support that helps you 600+ 8 ENABLE BETTER years domain practices expertise DECISIONS 130+ 98% + Deep on - ground insights that you can act on team members accuracy 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 100+ 2.5M towns & cities panel members One - ness of data and people networks to harness the collective power of data, network, and technology Multi - faceted teams offering a stack of consulting, 15+ 40:60 advisory, and research services languages covered she/ he ratio 1Lattice platform will host use cases across the decision support cycle of a client Foreword The Middle East and North Africa (MENA) presented The United Arab Emirates (UAE) presented a a fascinating dichotomy in Q1 2024. While deal contrasting story. Despite an increase in deal count activity surged (125 deals compared to 89 in the (23 to 28), the overall deal value witnessed a sharp previous quarter), the overall deal value remained decline of approximately 50% compared to the flat at approximately US$ 2 billion. This stagnation, previous quarter. despite a rise in the number of deals, can likely be Tech remains the region's undisputed leader, with attributed to the global economic slowdown Software - as - a - Service (SaaS) and healthcare & life dampening investor enthusiasm. sciences attracting the highest investment A closer look reveals a trend of reduced average allocations. deal sizes in early and growth - stage investments, This report by 1Lattice aims to illuminate the key contributing to the stalled overall deal value in trends shaping the investment landscape within the Q1 2024. MENA region during Q1 2024. We believe this However, the investment landscape and investor analysis offers valuable insights that can spark sentiments varied across the region. Israel, for productive dialogue with partners across various instance, experienced a significant upswing in industries. As the MENA investment landscape investment activity, capturing roughly 55% of the continues to evolve, we look forward to actively total funding. This optimism likely stems from engaging in discussions, exchanging perspectives, investor hopes for a de - escalation of war - related and delving deeper into these developments economic repercussions. Roma Dixit Praneet Singhal Director, Senior Director, Technology & Internet Financial Investors © 1Lattice | 4 Key takeaways ● MENA companies raised ~ US$ 2B across 125 deals (early to late stages) in Q1 CY24 ‒ Growth stage deals witnessed a slowdown in $ value by ~55% on a Q - on - Q basis ● Average deal size decreased by ~35% in Q1 CY24 on a Q - o - Q basis; however, the number of deals in Q1 CY24 increased by ~30% as compared to Q4 CY23 ● Israel drew highest investment of ~US$ 1.1B followed by Saudi Arabia (~US$ 411M) and UAE (~US$ 345M) ● SaaS/AI was the most attractive sector for early - stage investments (~US$ 377M) and growth - stage investments (~US$ 372M) due to its potential to disrupt traditional industries and help realize profits in the long run ‒ Exodigo , a Saas /AI platform, received the highest funding of ~US$ 105M among early - stage investments ‒ Silverfront , a SaaS/AI platform, received the highest funding of ~US$ 116M among growth - stage investments ● EnterpriseTech (~US$ 486M) & cybersecurity (~US$ 194M) attracted highest tech investments in Q4 CY23 MENA region definition Syria Lebanon Palestine Tunisia Iraq Israel Iran Morocco Jordan Kuwait Bahrain Libya Algeria Qatar Saudi Arabia Egypt UAE Oman Sudan Yemen © 1Lattice | 6 Key highlights Funding # Deal v olume Average ticket size US $ 2 B 125 US$ 15.9M SNAPSHOT Q1 CY 2024 Top funded sector Most funded stage (by deals) Total tech funding SaaS / AI Early US$ 1.2B Market by segments SaaS / AI leads funding followed by healthcare & life sciences in Q1 CY24 Funding market segment wise break - up ( US$ M, Q1 CY24) Total funding size: US$ 1,985 M 117 100 336 IT services BFSI 947 Healthcare & Life Sciences 83 71 257 SaaS / AI E - commerce & listing platforms Manufacturing 25 21 Consumer apps 26 & platforms Transportation FMCG & logistics * Others Note(s): *Others include Agritech companies, DaaS providers & technology consulting companies © 1Lattice | 8 Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Investment amount and # deals ~US$ 2B was raised in MENA by companies across 125 deals in Q1 CY24, experiencing stagnation Investment amount (US$ B) and # deals (Q1 CY23 – Q1 CY24) 125 116 108 89 84 2.3 2.1 2.1 2.0 1.9 * * * Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), and late (Series F onwards) stage investments, others (PIPE and unattributed); *An approximate amount has been assumed for undisclosed deals basis previous deals of investors & the funding stage Source(s): 1Lattice Deals Database © 1Lattice | 10 Stage - wise investments Growth - stage deals witnessed a slowdown in $ value by ~55% on a Q - on - Q basis Investment amount (US$ B) and # deals (Q1 CY23 – Q1 CY24) 2.3 125 2.1 0.3 2.1 1.9 2 0.3 116 0.05 0.4 0.2 108 89 84 0.6 1.3 1.5 1.1 1.4 0.5 0.7 0.7 0.6 0.4 0.4 * * * Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Early Growth Late Others Deals Note(s): Others include deals with undisclosed round, PIPE, etc.; *An approximate amount has been assumed for undisclosed deals basis previous deals of investors & the funding stage Source(s): 1Lattice Deals Database © 1Lattice | 11 Country - wise investments Israel drew highest investment of ~US$ 1.1B followed by Saudi Arabia (~US$ 411M) and UAE (~US$ 345M) Investment amount (US$ M) and # deals (Q1 CY24) Avg. deal size (US$ M) = 27.2 15.8 12.3 4.0 2.2 42 Israel witnessed a ~95% quarter - on - quarter increase fueled by investor optimism on potential war de - escalation 28 1,144 26 17 12 411 345 48 38 Others* UAE Egypt Saudi Israel Arabia Amount Deals Note(s): *Others include Oman, Tunisia, Qatar, Morocco, Kuwait, Iraq, Bahrain, and Jordan Source(s): 1Lattice Deals Database © 1Lattice | 12 Average deal size Average deal size across all funding - stages decreased in Q1 CY24; deal volume increased by approximately ~30% on Q - o - Q basis Split of deal volume Average deal size (#, Q1 CY23 – Q1 CY24) (US$ M, Q1 CY23 – Q1 CY24) # of 108 84 116 89 125 26.5 deals = 100% 1% 1% 2% 2% 5% 23.8 6% 22.9 17% 20% 20% 10% 33% 19.3 Average deal - size across all stages (early to late - 15.9 stage) has decreased 82% 79% 79% 78% 65% * * * * * * Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Early Growth Late Others Note(s): Others include deals with undisclosed round, PIPE, etc.; ; *An approximate amount has been assumed for undisclosed deals basis previous deals of investors & the funding stage Source(s): 1Lattice Deals Database © 1Lattice | 13 Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Top 10 investments in Q1 CY24 Top 10 investments in the MENA region in Q1 CY24 make ~50% of the total investments received in the region Top 10 investments in Q1 CY24 Amount Company Sector Funding stage Country Key Investors (US$ M) Healthcare & 160 Late Saudi Arabia Gulf Islamic Investments life sciences SaaS/AI 130 Pre - IPO Saudi Arabia Investcorp , 500Group, and STV Brighton Park Capital, Acrew Capital, Greenfield Partners, Citi Ventures, General Motors Ventures, SaaS/AI 116 Growth Israel Maor Investments, Vintage Investment Partners, and Singtel Innov8 Consumer app & 110 Late Israel Affinity Partners platforms Greenfield Partners, Square Peg Ventures, 10D, and SaaS/AI 105 Early Israel National Grid Partners Consumer app & 100 Late Israel BlackRock, and HSBC Innovation Bank platforms One Peak, Energy Impact Partners and Balderton Saas/AI 100 Growth Israel Capital Healthcare & 60 Growth UAE Dubai Investments life sciences AMR Action Fund, Cystic Fibrosis Foundation, Healthcare and 50 Post - IPO Israel Deerfield Management Company, OrbiMed and life sciences Nantahala Capital Manufacturing 48 Late Israel Manor Evergreen Note(s): These include deals only with disclosed deal amounts © 1Lattice | 15 Source(s): 1Lattice Deals Database Early - stage investments SaaS/AI sector received highest funding (~US$ 376.6M) among early - stage investments Top 10 early - stage investments in Q1 CY24* Early - stage investments by sector Amount Company Sector Country Key Investors (US$ M) (US$ M, Q1 CY24) Greenfield Partners, Square Peg SaaS/AI Israel 105 Ventures, 10D, and National Grid Saas/AI 376.6 Partners, SaaS/AI UAE 35 Undisclosed E-commerce & listing 63.7 platforms Evolution Equity Partners, Munich Re SaaS / AI Israel 33 Ventures and Glilot Capital Partners Consumer app & platforms Publicis Groupe, Samsung Next, IN 47.0 venture (Sumitomo Corporation, Japan), Atinum Investment (South Healthcare & Life Sciences SaaS/AI Israel 24 Korea), Z Venture Capital (LY 37.9 Corporation, Japan), Mirae Asset Venture Investment, J - Ventures, and others Transportation and logistics 21.3 SaaS/AI Saudi Arabia 21 Undisclosed FMCG 18.2 Intel Capital, Samsung Next, S Capital SaaS/AI Israel 20 VC, Mindset Ventures Magenta Venture Partners, JAL BFSI SaaS/AI Israel 20 17.6 Ventures European Innovation Council Fund, SaaS/AI Israel 20 Varana Capital, Cleveland Avenue, XT Engg. & Construction 0.5 Hi - Tech and OurCrowd Manufacturing Israel 17.00 PeakBridge Others 26.3 Healthcare & Life Israel 16.5 Agriline Products, ALIVE Sciences © 1Lattice | 16 Note(s): * These include deals only with disclosed deal amounts Early - stage investments include Pre - seed, Seed, Pre - series and Series A; The table includes only disclosed deal amounts Source(s): 1Lattice Deals Database Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Provider of AI - based subsurface mapping services SaaS - based provider of corporate travel management solutions Cloud workload and runtime security solutions Provider of an AI - based solution to create customized visual content Saudi Arabia - based, API - linked payment gateway Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A Source(s): 1Lattice Deals Database © 1Lattice | 17 Growth - stage investments SaaS / AI dominated growth - stage investments (~US$ 372M) Top 10 growth - stage investments in Q1 CY24 Growth - stage investment, by sector Amount Company Sector Country Key Investors (US$ M, Q1 CY24) (US$ M) Brighton Park Capital, Acrew Capital, Greenfield Partners, Citi Ventures, SaaS/AI Israel 116 General Motors Ventures, Maor Investments, Vintage Investment SaaS/AI Partners, and Singtel Innov8 372 One Peak, Energy Impact Partners and Saas/AI Israel 100 Balderton Capital Healthcare & UAE 60 Dubai Investments Life Sciences Bessemer Venture Partners, GGV SaaS/AI Israel 42 Capital, Insight Partners, Greenfield Partners and Evolution Equity Partners Healthcare & Life Sciences 70 Bright Pixel Capital, AllegisCyber SaaS/AI Israel 30 Capital, AlleyCorp , and Strait Capital Glilot Capital Partners, Shasta Ventures, Vertex Ventures, DTCP, Vintage SaaS/AI Israel 25 Investment Partners, and Red Dot Capital Partners Atreides Management, Exor Ventures, Manufacturing Israel 24 and Greenfield Partners EBRD, HSBC Asset Management, Manufacturing 24 OurCrowd , Hanaco Ventures, Mindset SaaS/AI Israel 18 Ventures, Orbia , Smart Agro , and Citrosuco KDDI, JVP, Benhamou Global Ventures, SaaS/AI Israel 15 and Space Center Ventures SaaS/AI UAE 12 MENA Moonshots © 1Lattice | 18 Note(s): Growth - stage investments include Series B, C, D and E; The table includes deals only with disclosed deal amounts Source(s): 1Lattice Deals Database Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors Multi - factor authentication solutions provider Threat detection and prevention solution over wifi and cellular networks Chain of fertility clinics Provider of cloud - based converged security and information management systems Proxy based isolation for malware attack prevention on the endpoints Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice Deals Database © 1Lattice | 19 Tech investments Enterprise Tech & Cybersecurity attracted highest tech investments in Q1 CY24 Top 10 tech investments in Q1 CY24 Tech investments, by sector Amount Company Sector Country Key Investors (US$ M) (US$ M, Q1 CY24) Saudi 130 EnterpriseTech Investcorp, 500Group, STV EnterpriseTech 486.2 Arabia Cybersecurity Brighton Park Capital, Acrew Capital, 194.0 Greenfield Partners, Citi Ventures, Rental services 122.5 EnterpriseTech General Motors Ventures, Maor Israel 116 Fintech 72.8 Investments, Vintage Investment Generative AI 38.0 Partners, Singtel Innov8 EdTech 23.3 Rental services Israel 110 Affinity Partners Analytics 21.5 Greenfield Partners, Square Peg Logistics services 20.0 EnterpriseTech Israel 105 Ventures, 10D, National Grid Partners, HealthTech 17.6 One Peak, Energy Impact Partners and Cybersecurity Israel 100 B2B ecommerce 16.0 Balderton Capital Agritech Bessemer Venture Partners, GGV 15.2 EnterpriseTech Capital, Insight Partners, Greenfield Israel 42 FoodTech 14.8 Partners and Evolution Equity Partners Conversational intelligence 11.0 UAE 35 Others Undisclosed Blockchain 11.0 Travel & Hospitality 10.7 Evolution Equity Partners, Munich Re Israel 33 Cybersecurity Food & Beverages Ventures and Glilot Capital Partners 10.5 Others include Fashion & lifestyle, Gaming 9.9 Bright Pixel Capital, AllegisCyber Autotech , logistics Cybersecurity Israel 30 Capital, AlleyCorp, Strait Capital CRM / Chatbots 8.2 tech, Social media, insuretech , & media Horizontal Ecommerce 7.3 Publicis Groupe, Samsung Next, IN & entertainment venture, Atinum Investment, Z Venture Others 84.2 Israel 25 Generative AI Capital, Mirae Asset Venture Investment, J - Ventures, and others Note(s): These includes only disclosed deal amounts © 1Lattice | 20 Source(s): 1Lattice Deals Database Top 10 M&As Top M&As in Q1 CY24 Top M&As in Q1 CY24 Amount Acquired Company Sector Country Date Acquirer (US$ M) Retail Saudi Arabia 67 February 07, 2024 Retail Saudi Arabia Undisclosed February 18, 2024 Others (ESG focused Undisclosed February 01, 2024 UAE engineering consultancy) Consumer app & Undisclosed February 08, 2024 Egypt platforms Undisclosed March 26, 2024 Healthcare & Life sciences UAE Consumer app & Undisclosed February 13, 2024 UAE platforms Note(s): Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice Deals Database © 1Lattice | 21 Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Active investors Most active investors of Q1 CY24 Growth - stage investors Early - stage investors (# deals) (# deals) 8 3 4 4 3 2 3 Source(s): 1Lattice Deals Database © 1Lattice | 23 Active early - stage investors Most active early - stage investors and their investment segments in Q1 CY24 Includes Engineering and Transportation & logistics Ecommerce Consumer Investors & listing Manufacturing Energy BFSI SaaS/AI app & Others platforms platforms - - - - - - - - - - - - - - - - - - - - - - Note(s): Investors who have invested in more than 2 companies © 1Lattice | 24 Source(s): 1Lattice Deals Database Active growth - stage investors Most active growth - stage investors and their investment segments in Q1 CY24 E - commerce Healthcare Consumer & listing & Life app & Investors Manufacturing FMCG SaaS/AI BFSI Telecom platforms Sciences platforms - - - - - - - - - - - - - Note(s): Investors who have invested in more than 1 company © 1Lattice | 25 Source(s): 1Lattice Deals Database +91 962 522 6697 roma.dixit@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore