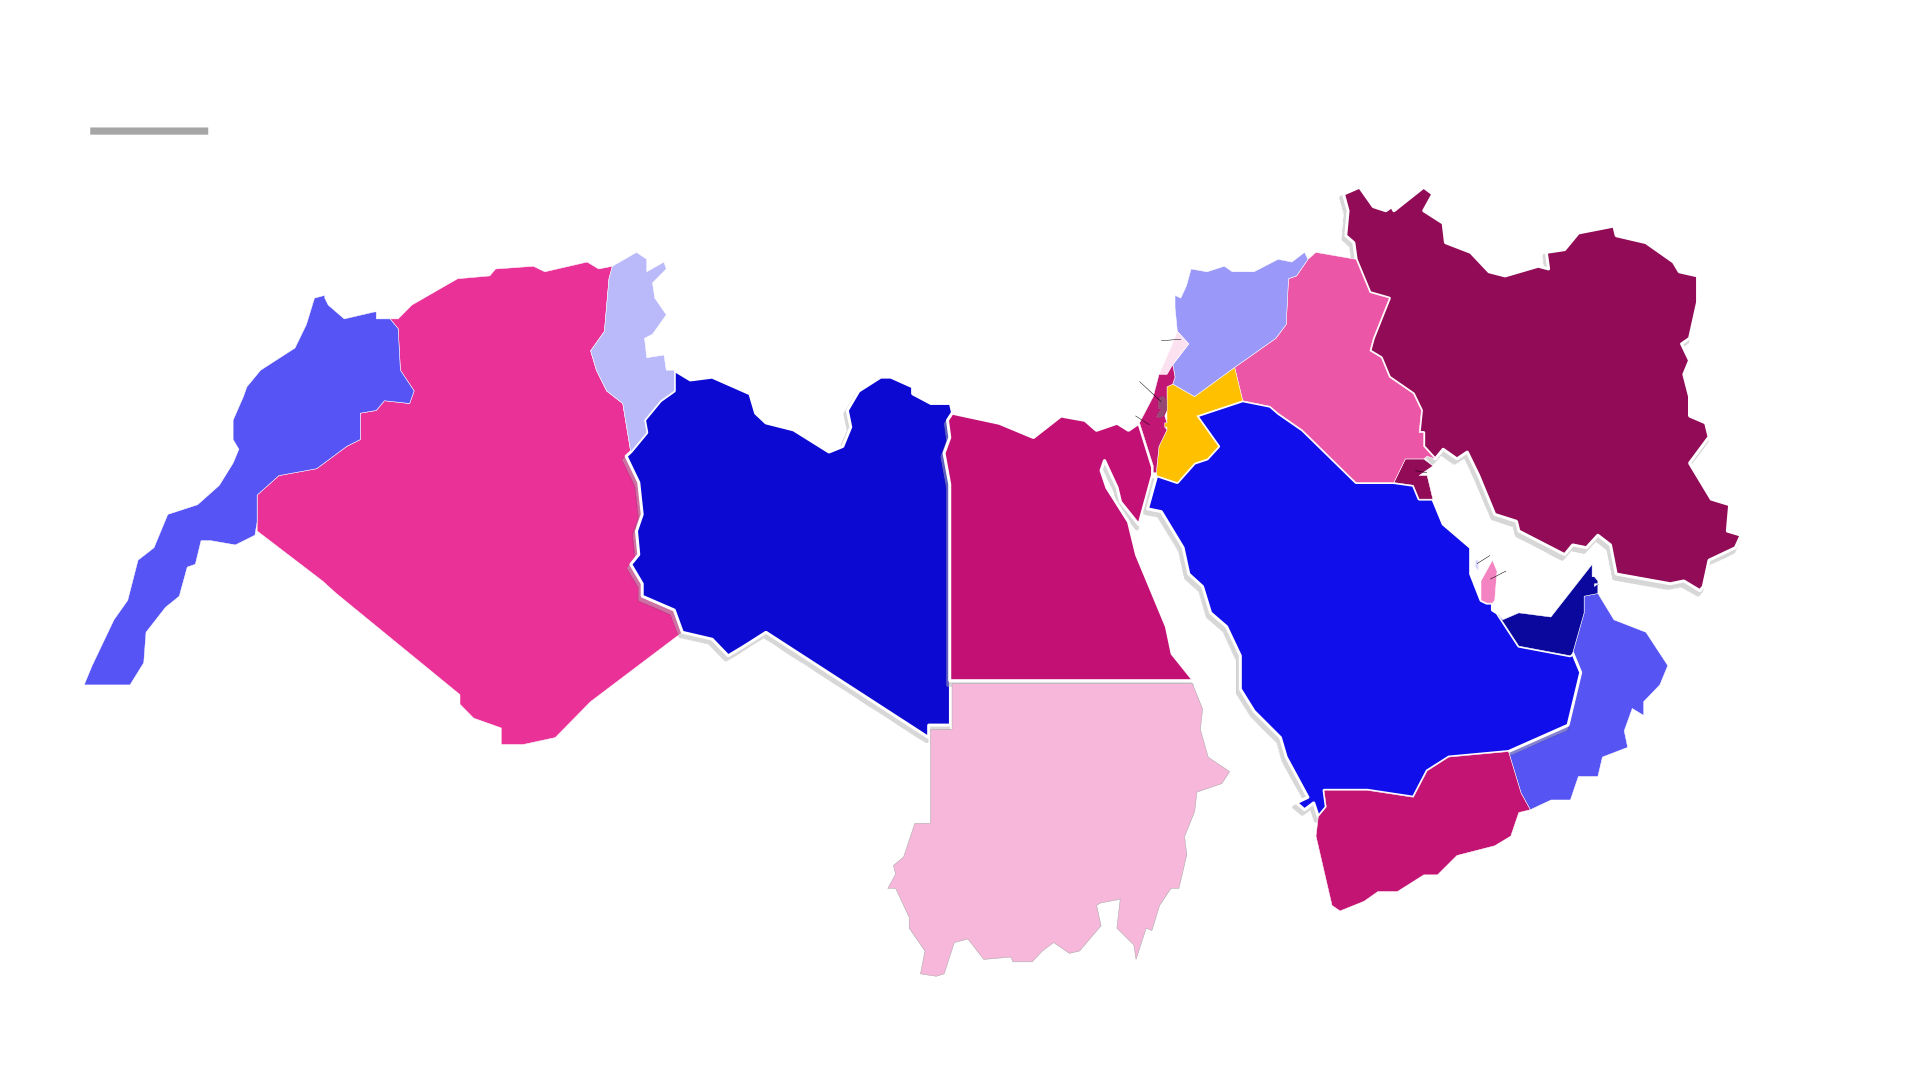
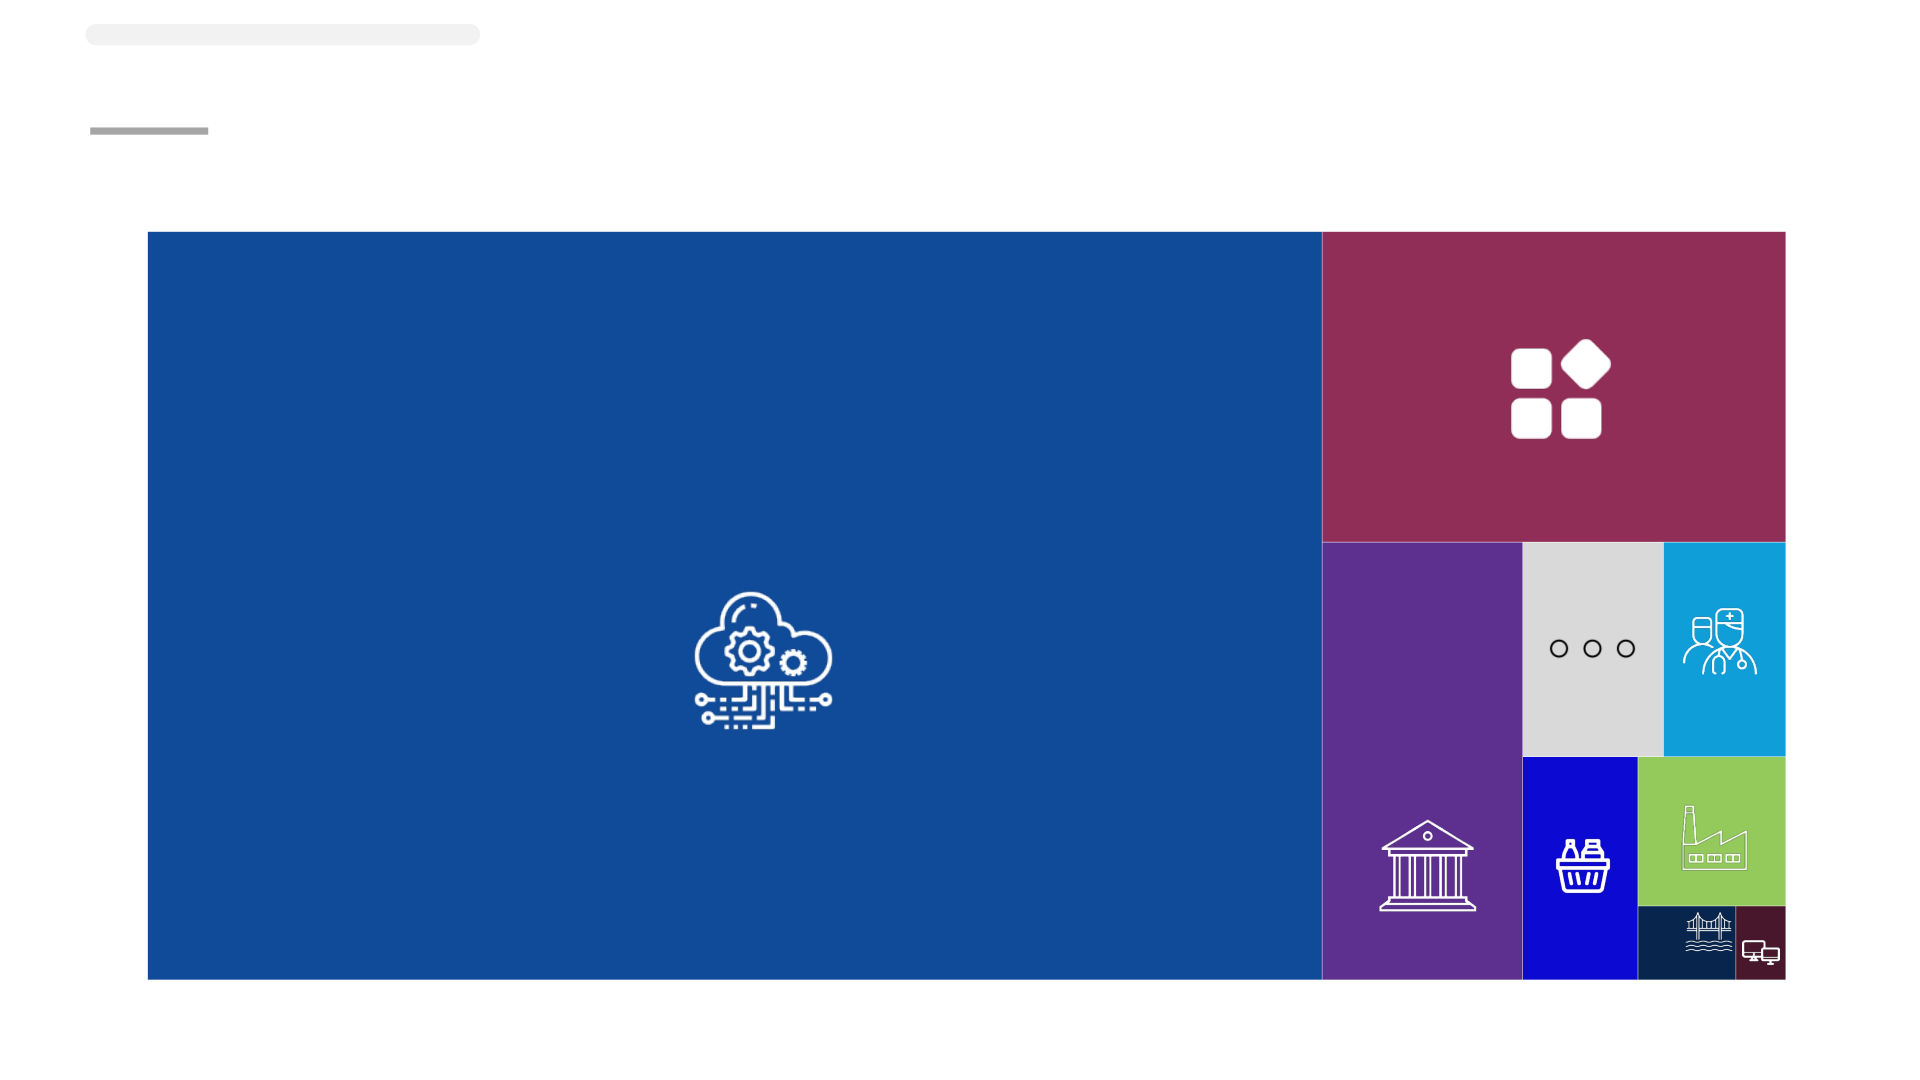
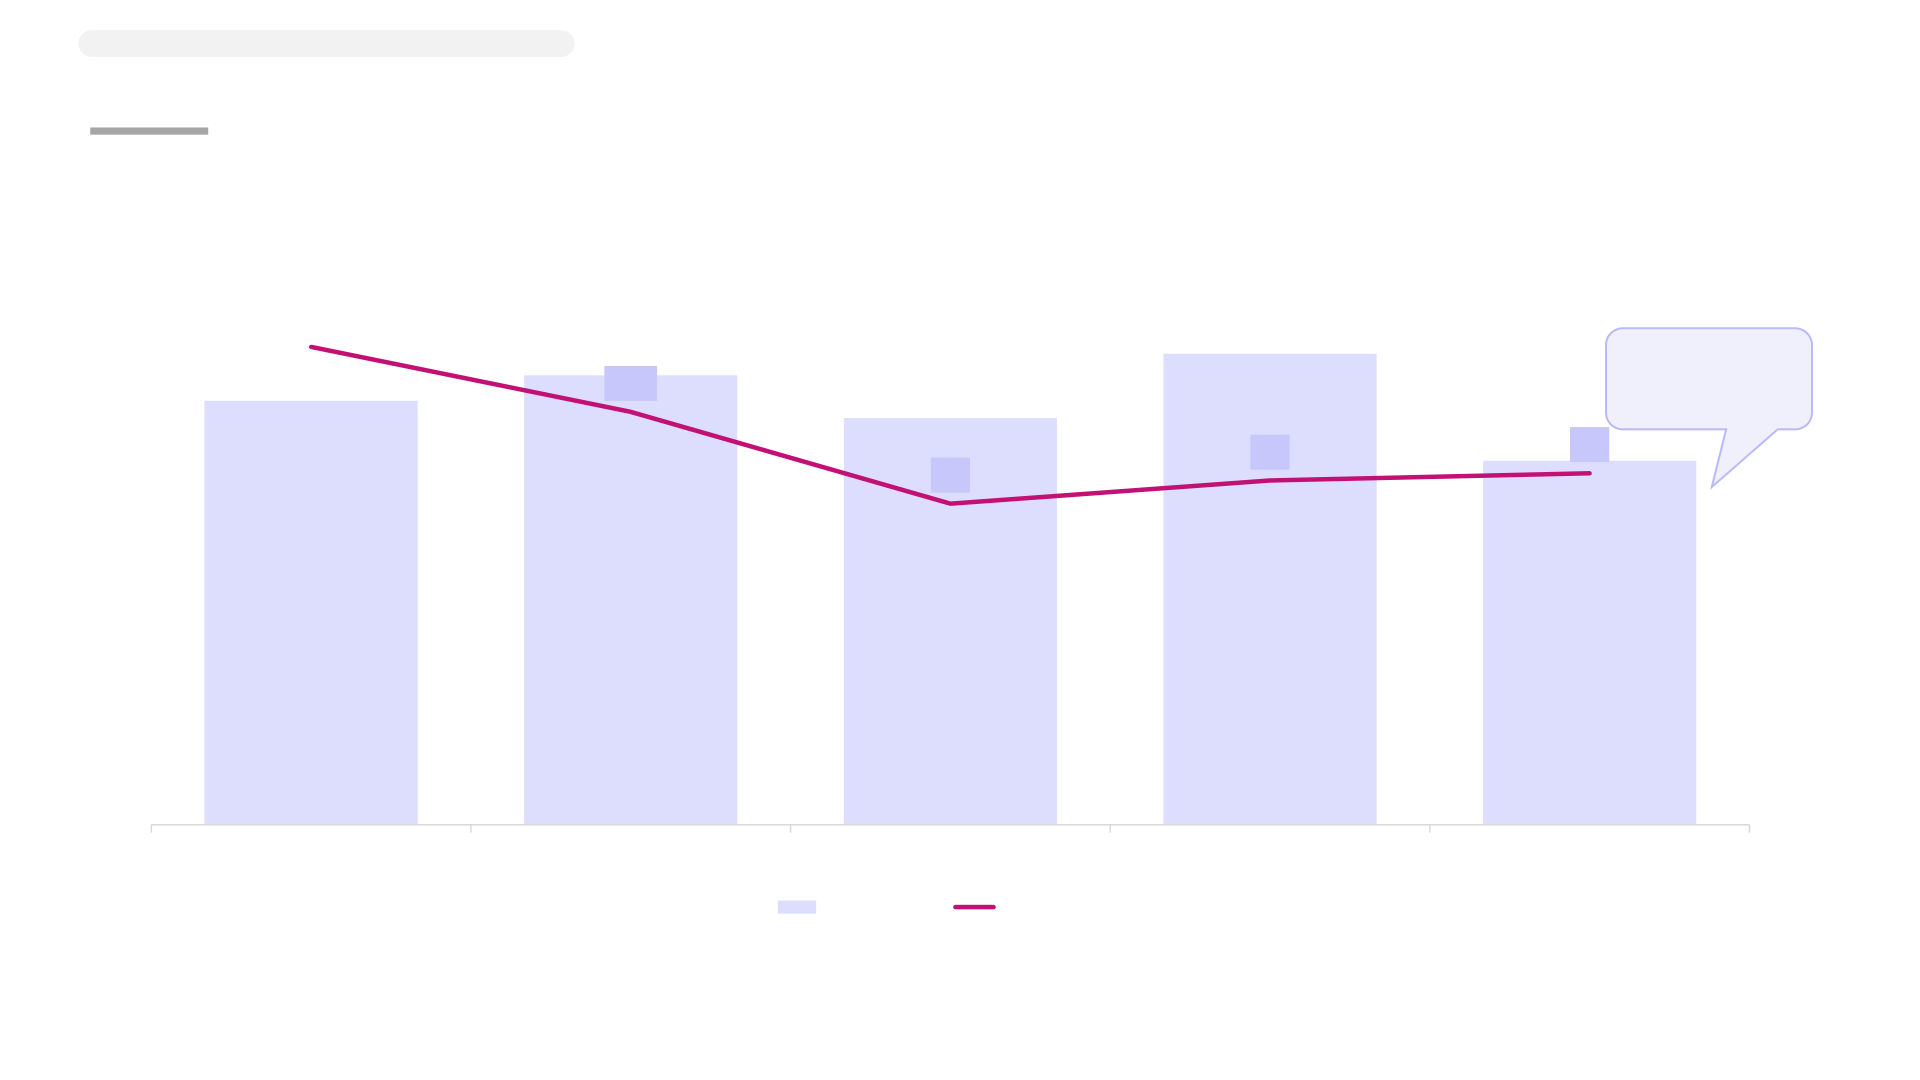
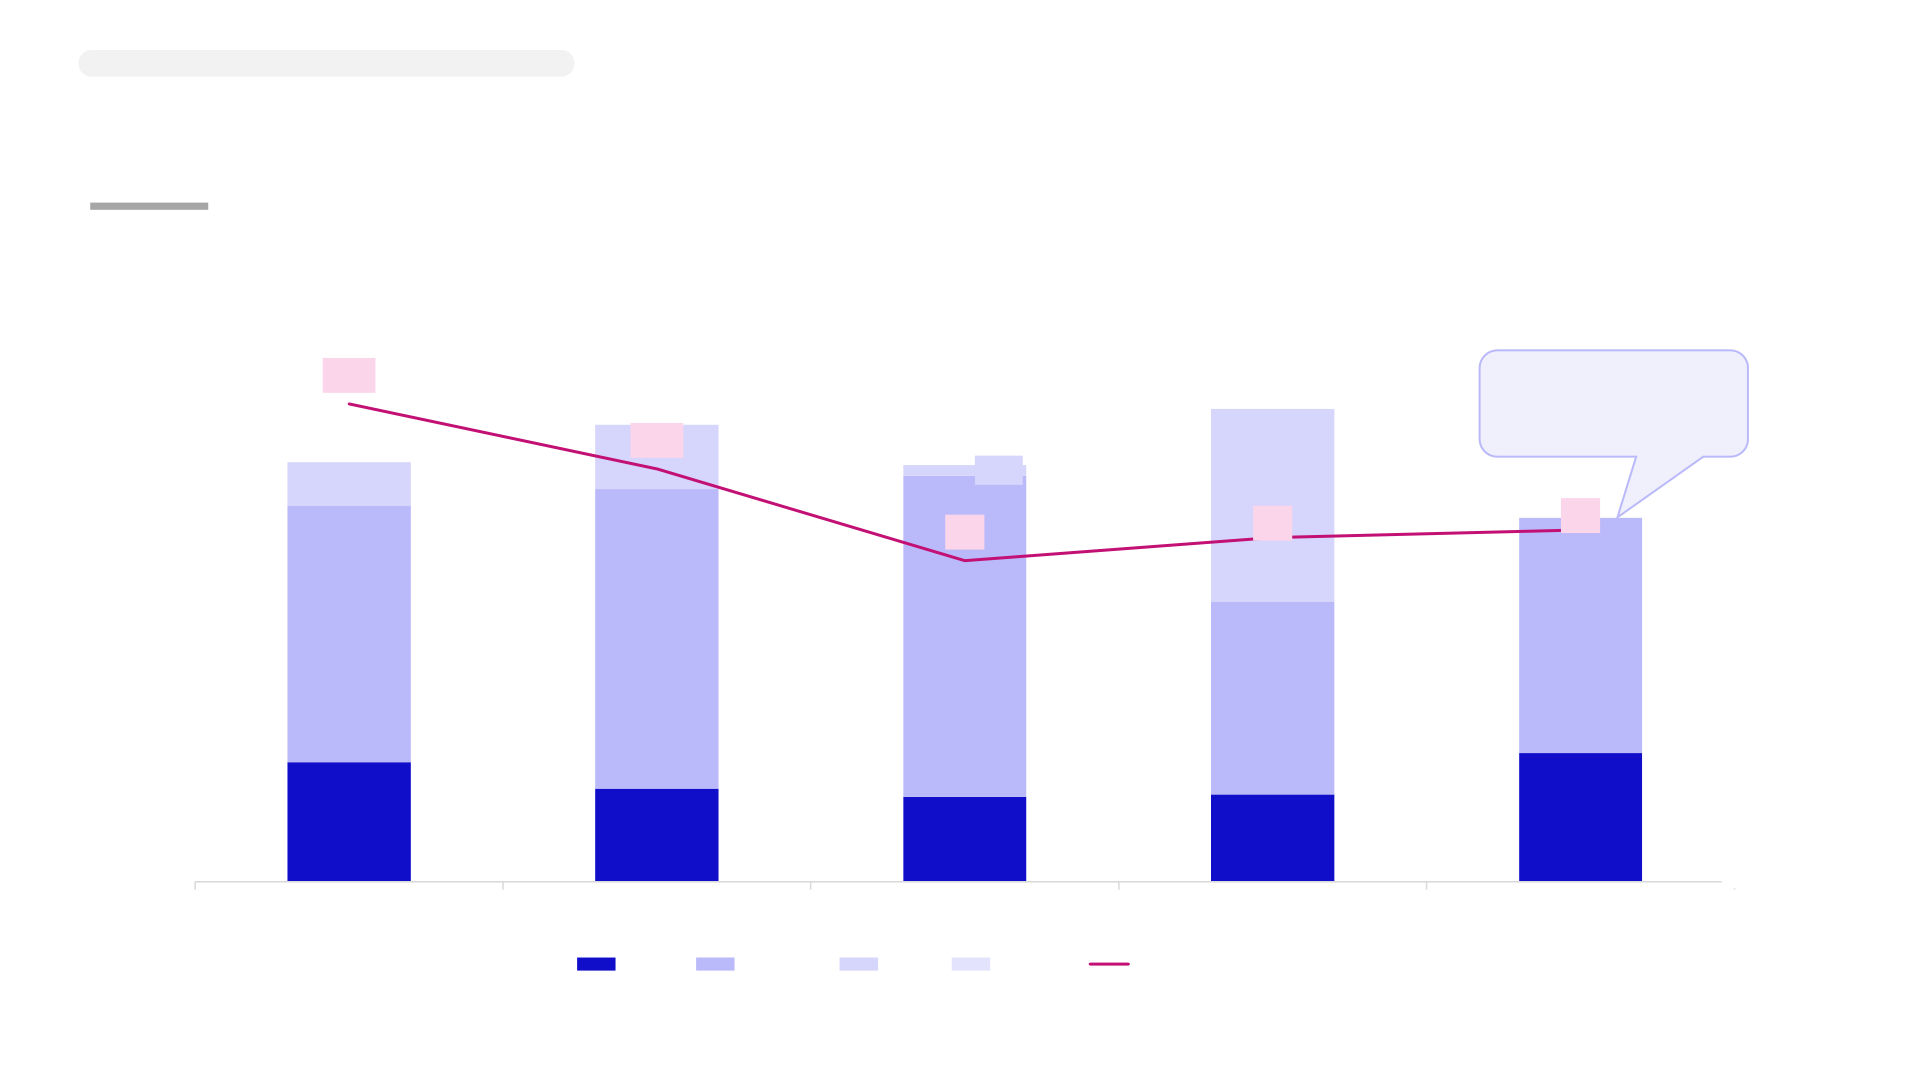
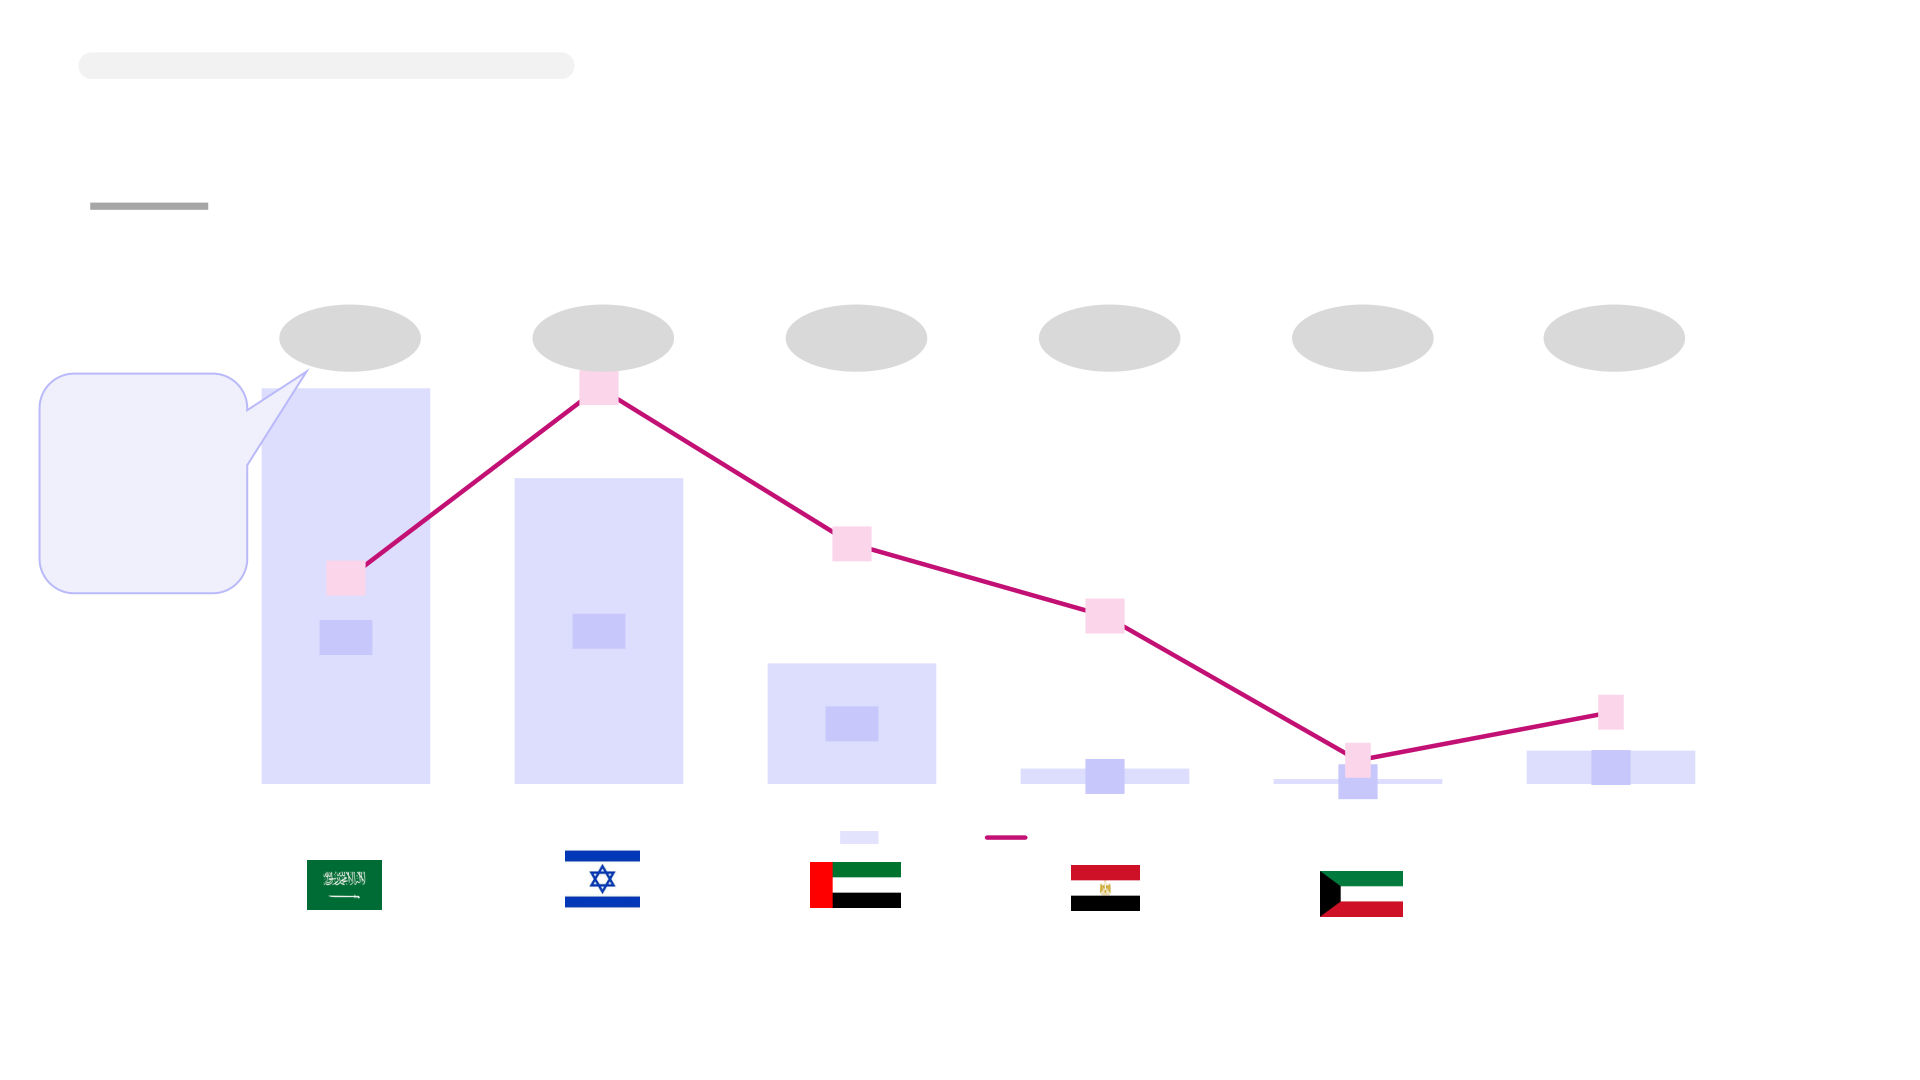
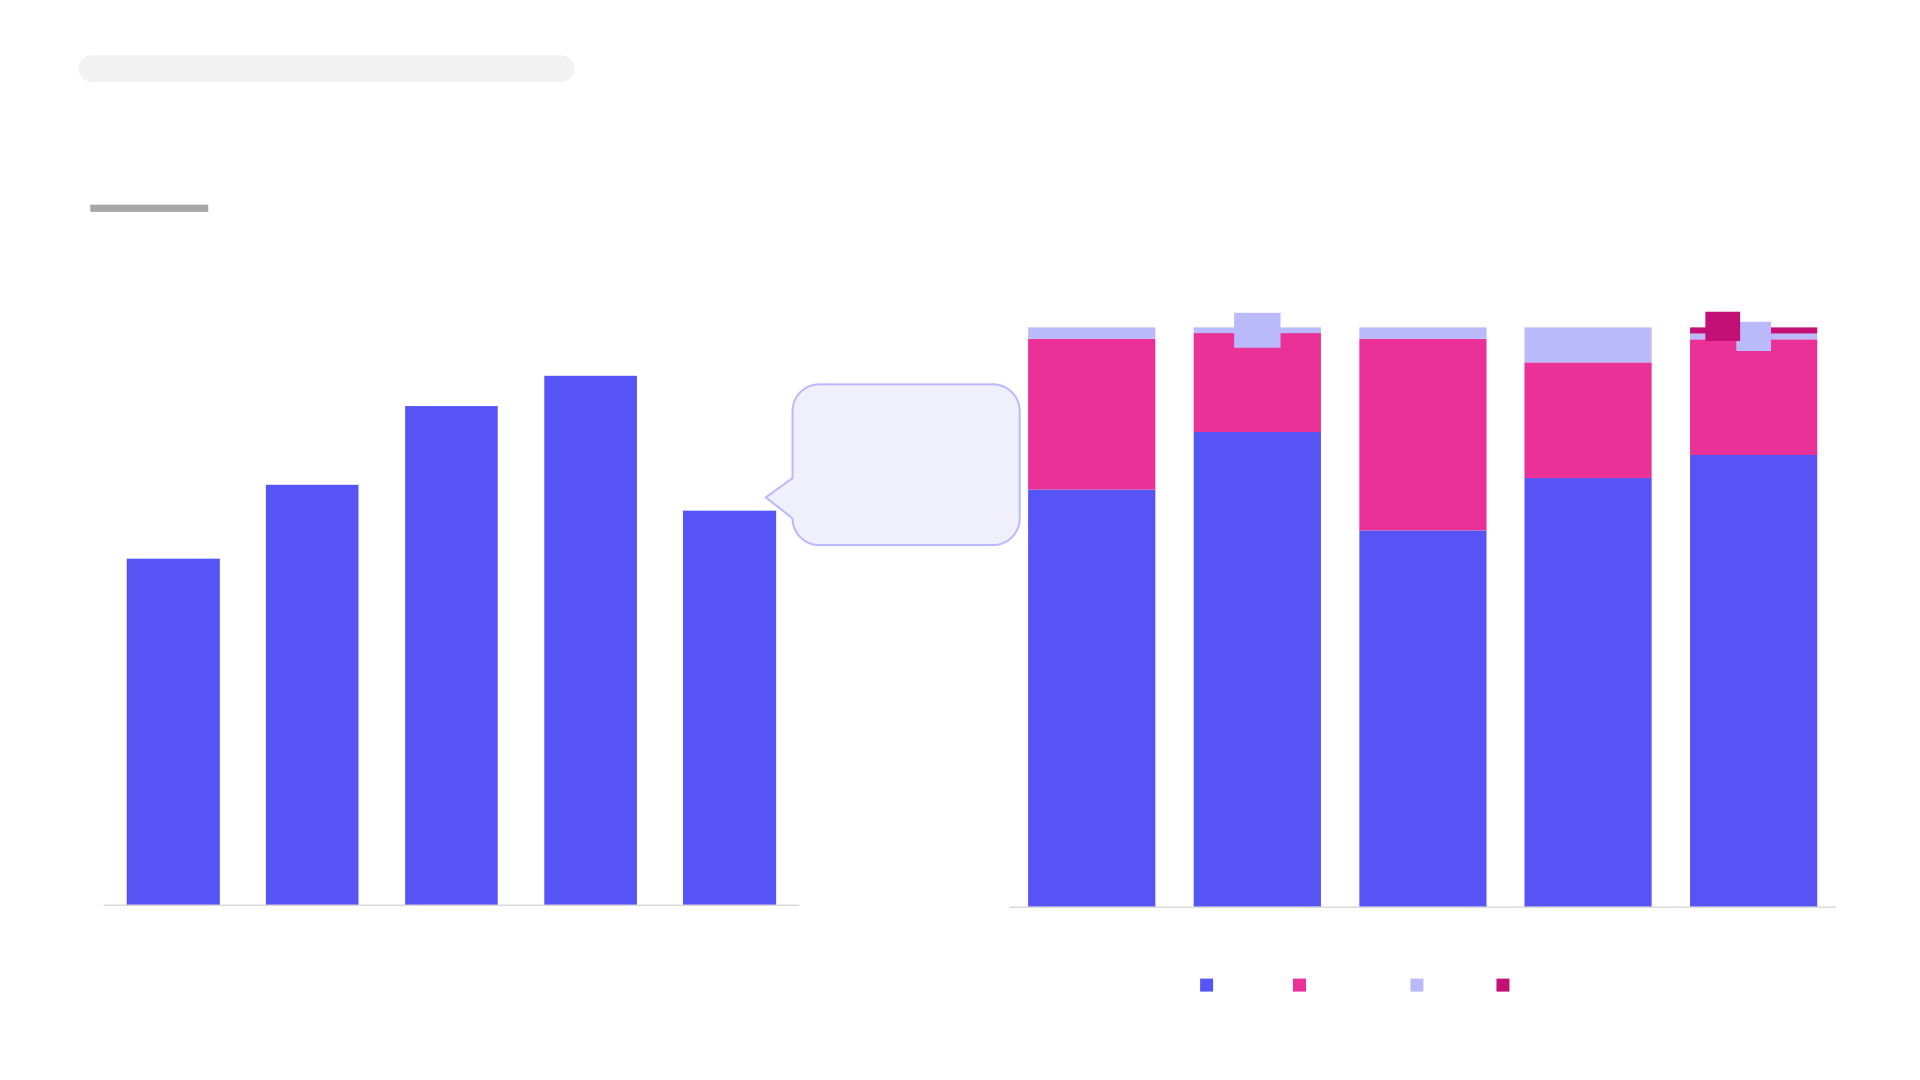
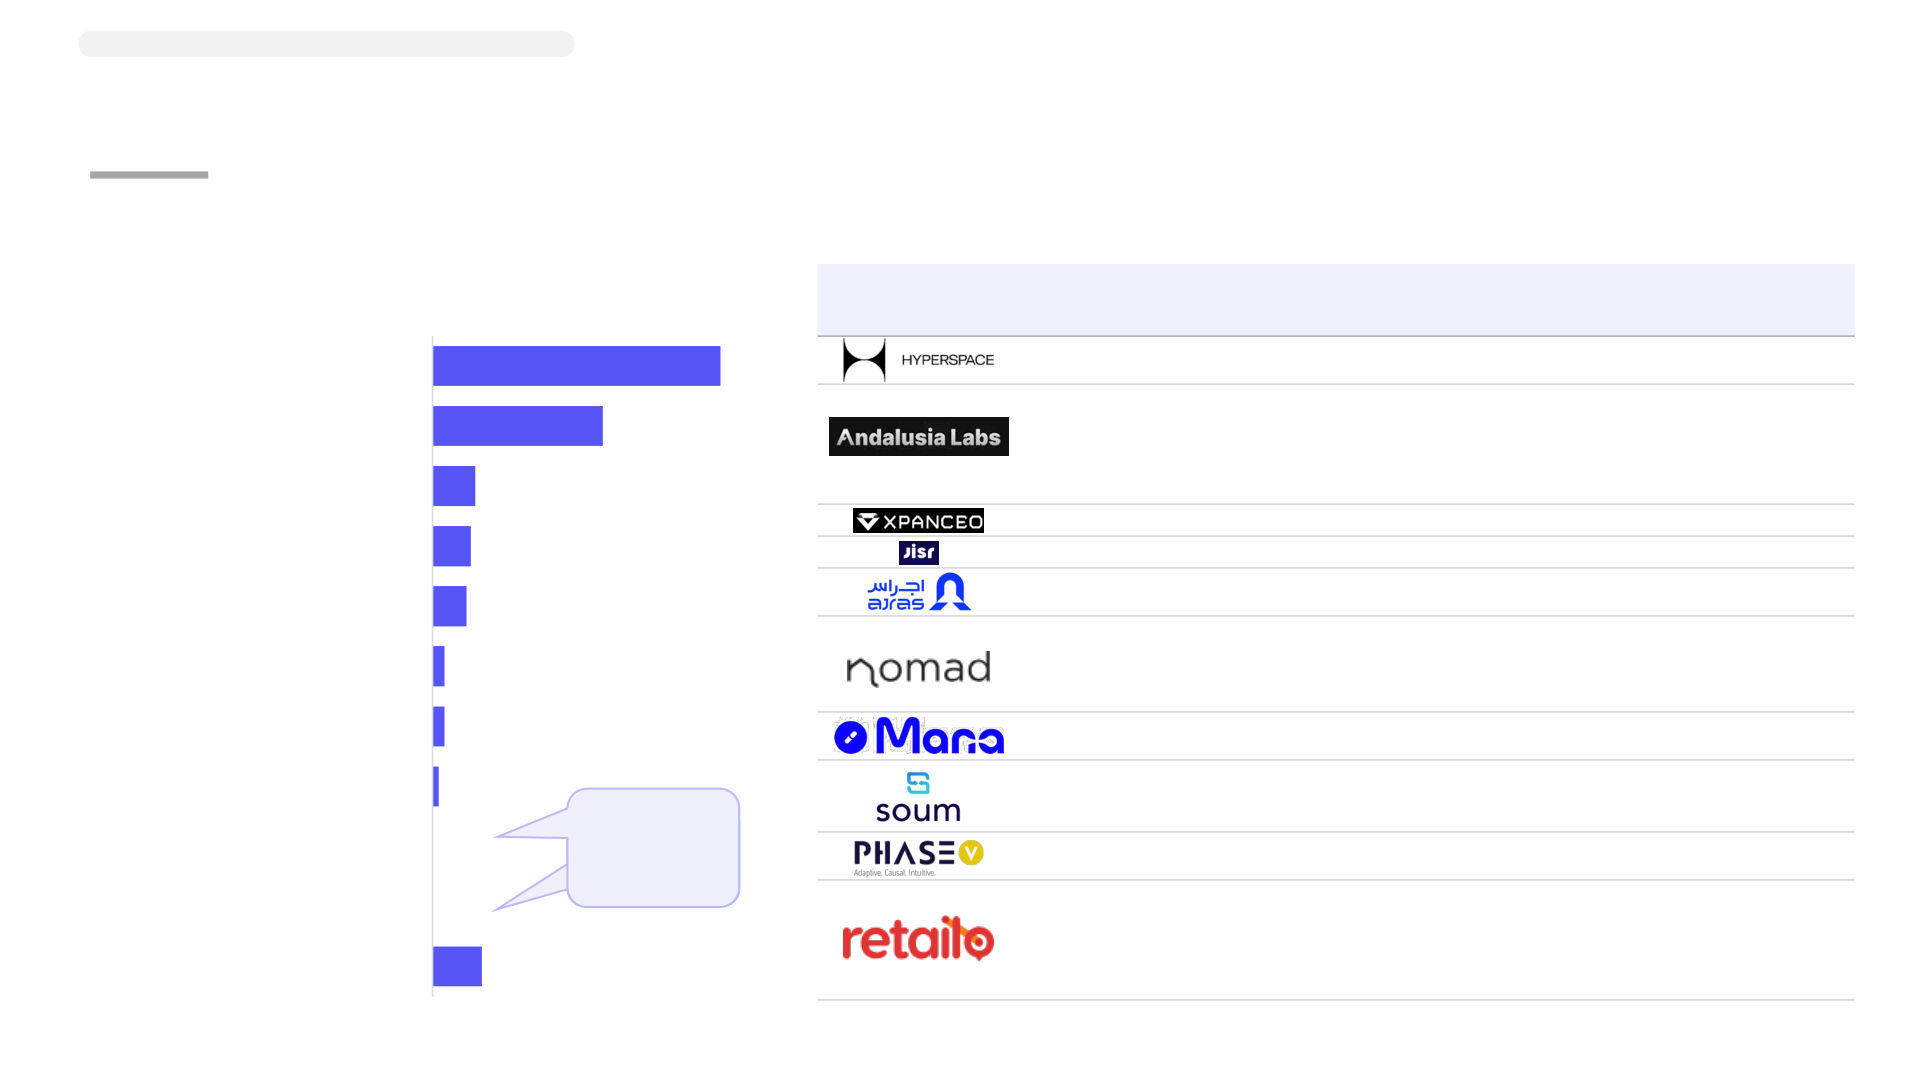
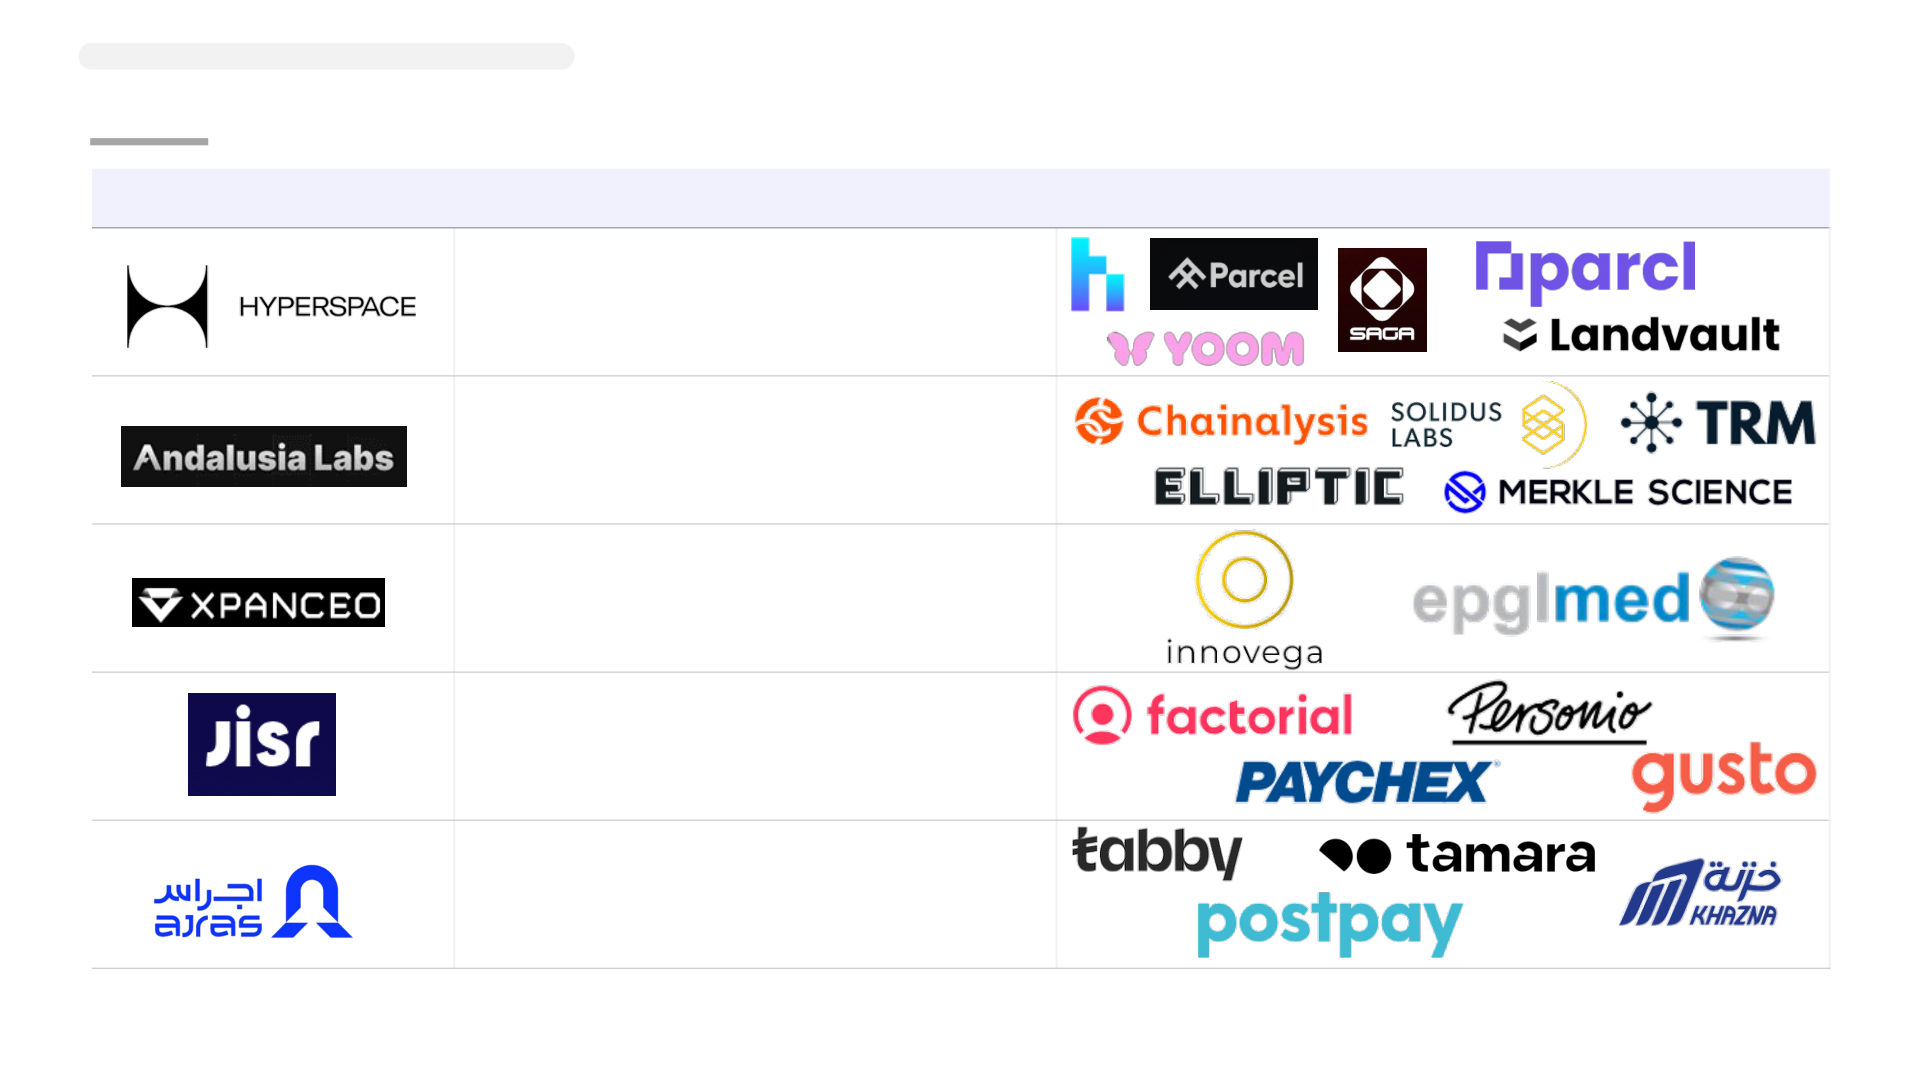
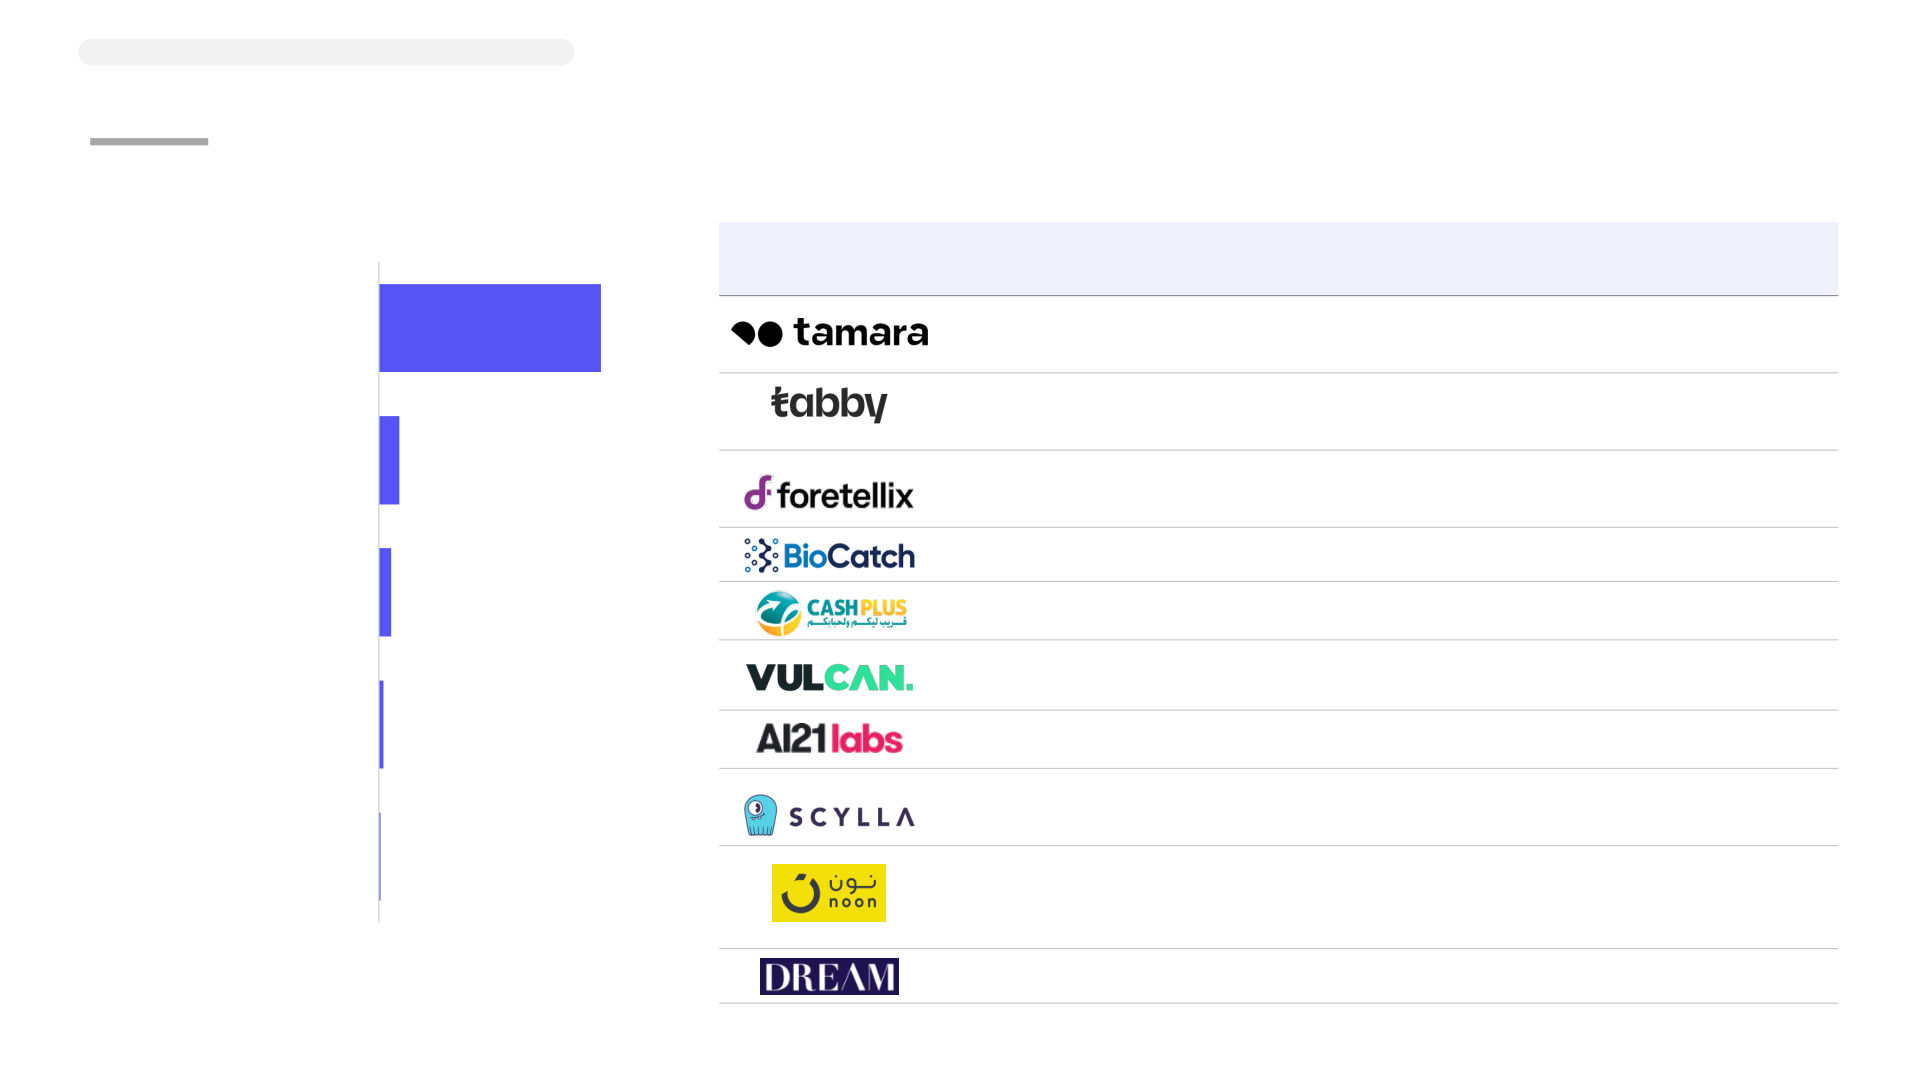
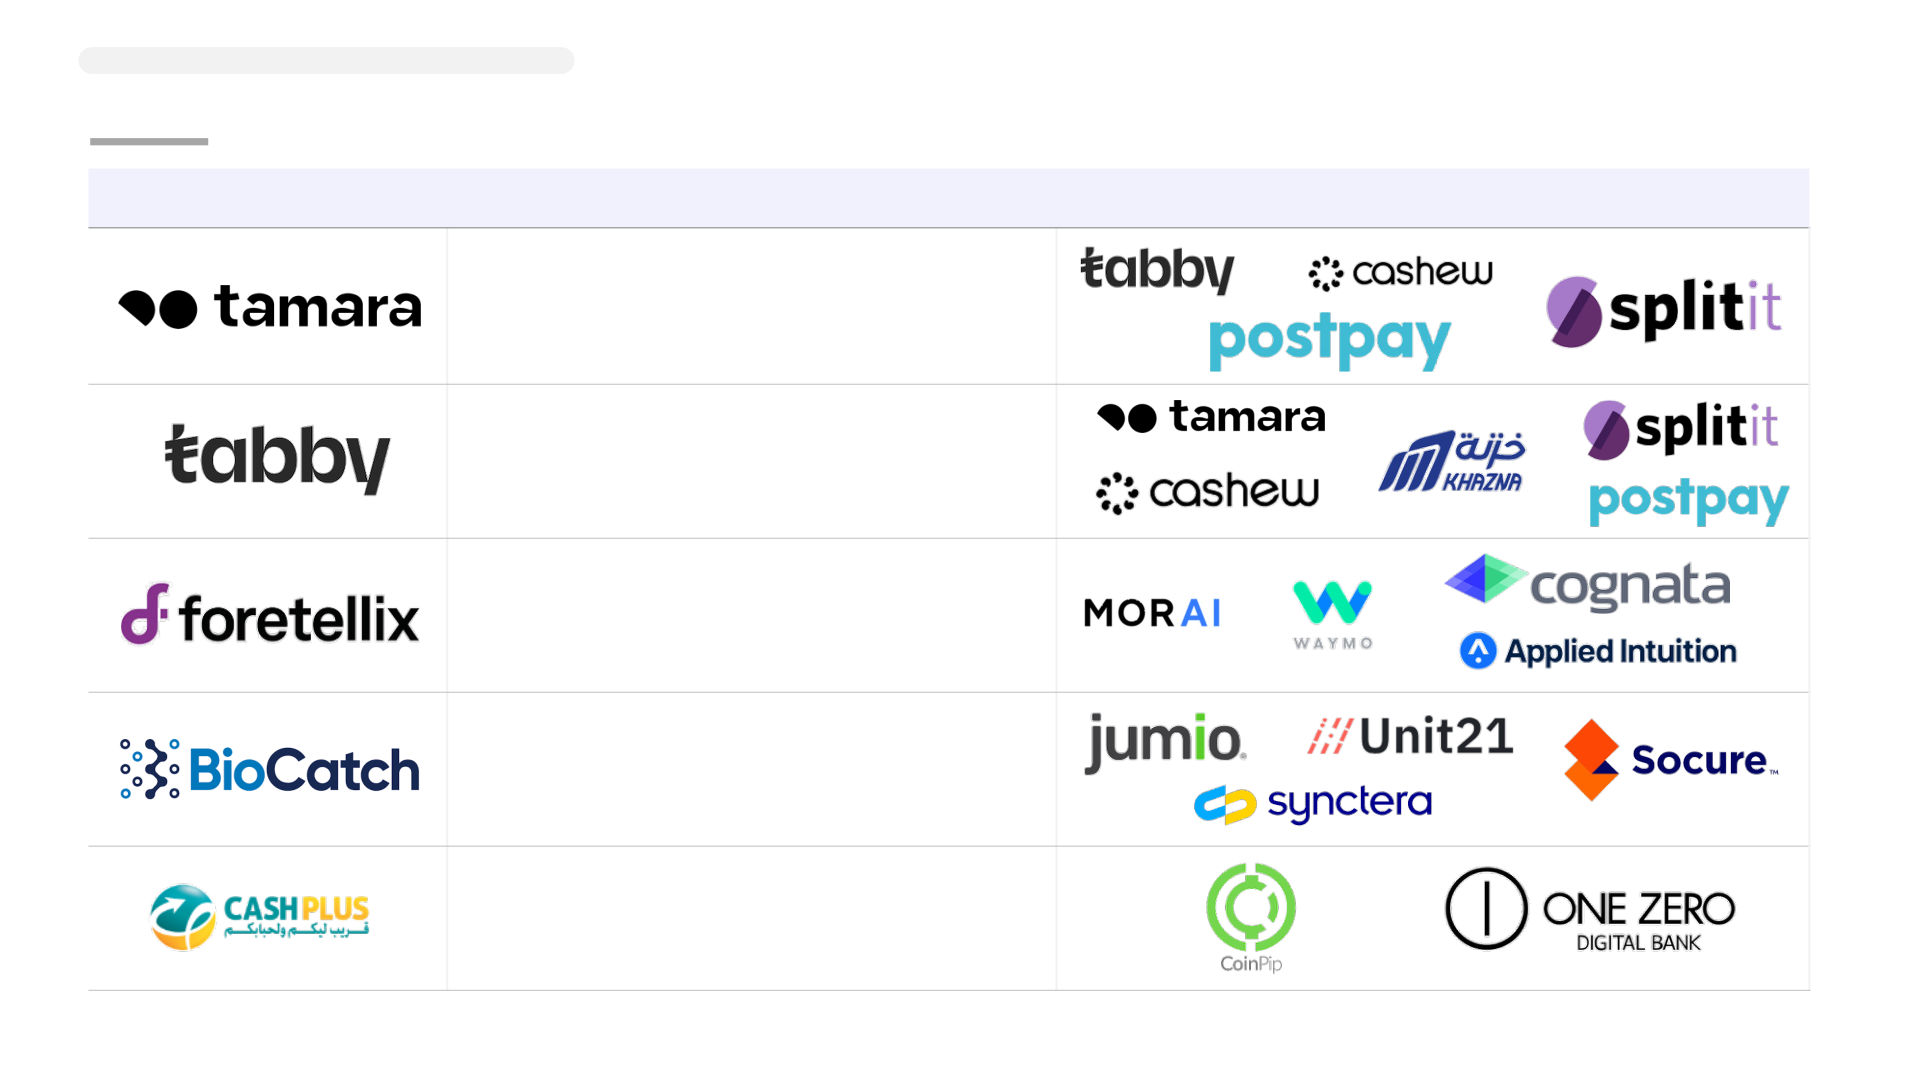
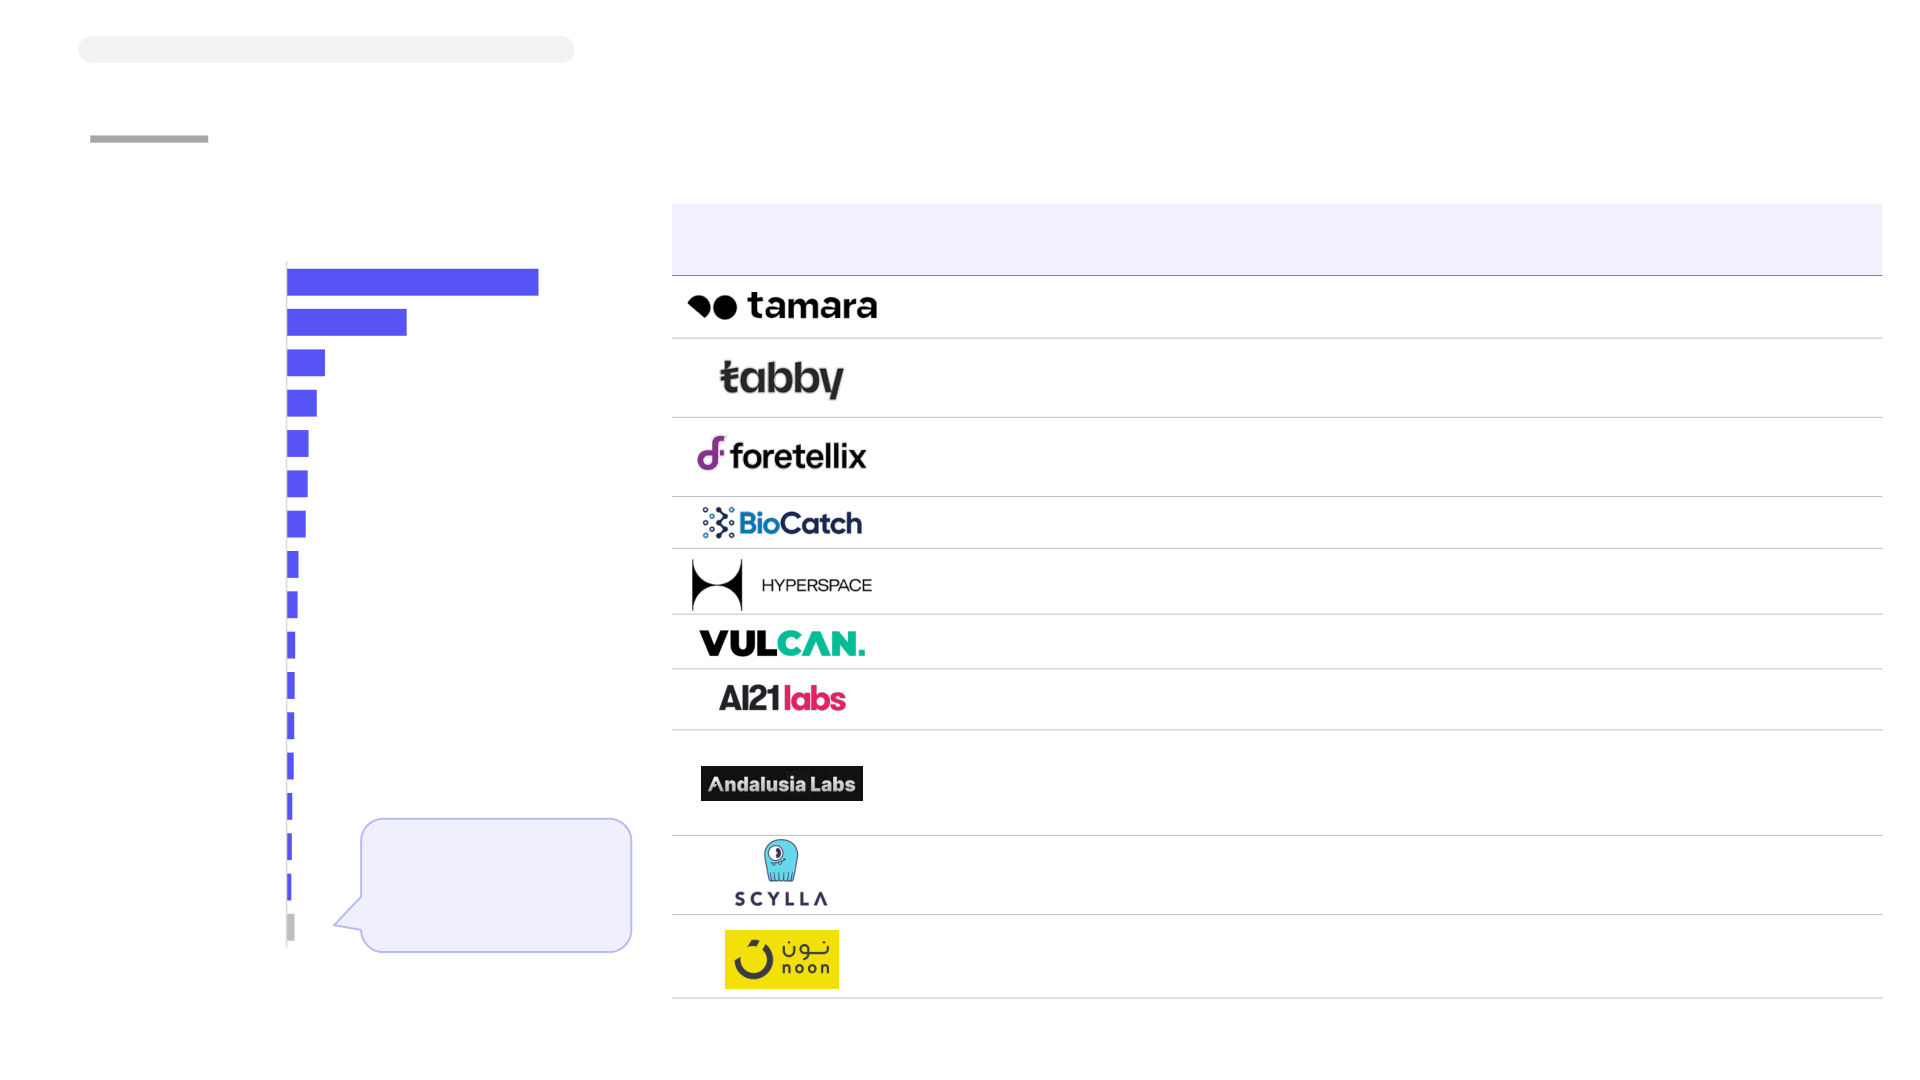
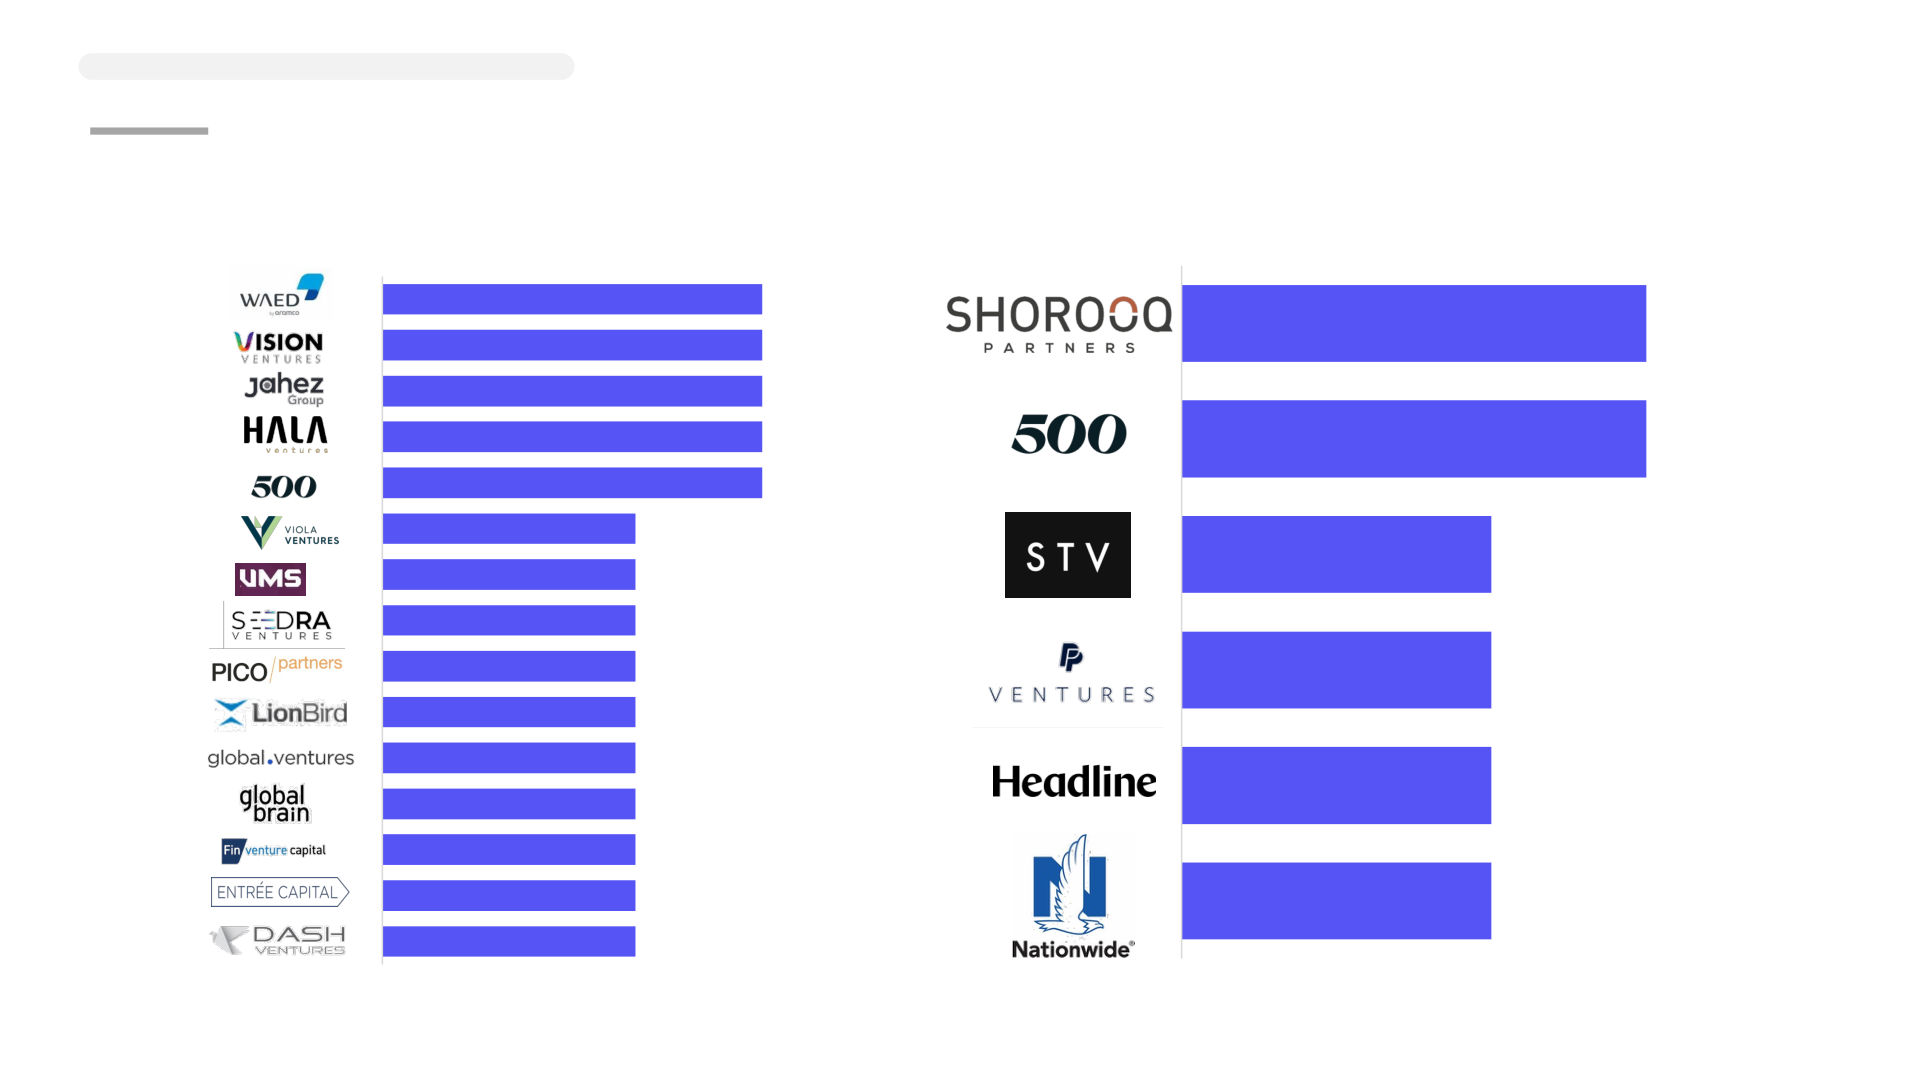
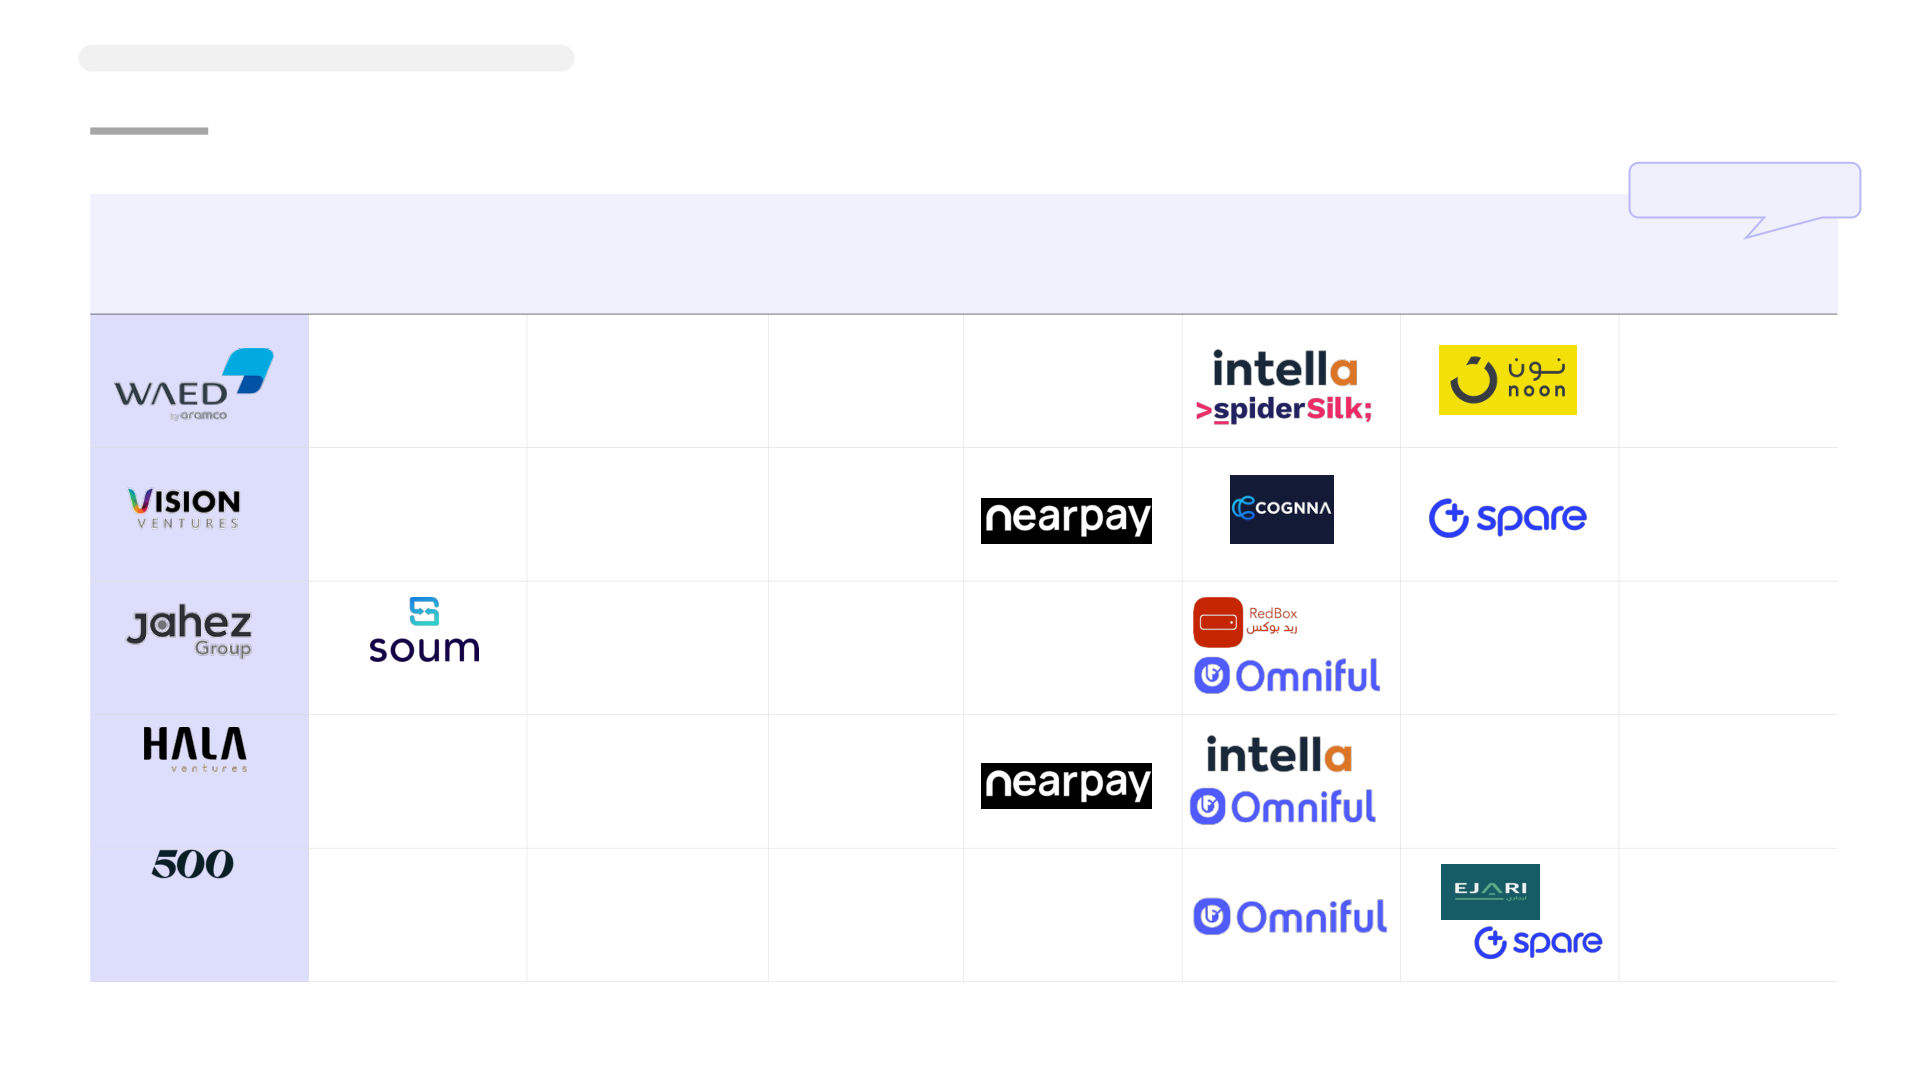
MENA quarterly investment analysis Q4 CY23 December 2023 Confidential and proprietary © 1Lattice Foreword The MENA region boasts diverse economies, rich cultural heritage, and a densely populated consumer base at the Middle East and North Africa crossroads. During the fourth quarter of 2023, Middle East and North African startups secured a total of ~US$ 1.7B across 92 deals, marking a ~23% quarter - on - quarter decrease. The region faced increased challenges in 2023, with high inflation, geopolitical tensions, and the recent outbreak of war. This led investors to prioritize smaller early - stage startups with ~65% of deals being US$ 20M and less. Despite some macro - economic challenges, the MENA region's funding ecosystem holds positive long - term prospects owing to continual digital transformation across industries and the increasing significance of the startup ecosystem. Saudi Arabia particularly, thrived in Q4 CY23, attracting around ~46% of investments. Government initiatives and programs to promote the startup ecosystem like Saudi Unicorns, National Technology Development Program, & establishment of regulatory sandboxes and fintech hubs significantly contributed. Tech remains the region's strongest sector, with SaaS and Fintech startups securing the highest funding amounts. This report seeks to uncover key trends in the funding ecosystem within the Middle East and North Africa during the fourth quarter of the calendar year 2023. At 1Lattice, we hold an optimistic outlook, confident that this report will offer invaluable insights. We eagerly look forward to engaging in open dialogues with partners across diverse industries, exchanging perspectives, and exploring these matters further while closely monitoring the evolving landscape. Roma Dixit Director, Financial Investors © 1Lattice | 2 1Lattice platform will host use cases across the decision support cycle of a client Key takeaways ● MENA companies raised US$ 1.7B across 92 deals (early to late stages) in Q4 CY23, signaling a slowdown in $ value ( - 15%) and # volume ( - 26%) as compared to Q4 CY22 ● Saudi Arabia attracted the highest funding in terms of $ value ( US$ 753M) and Israel attracted the highest funding in terms of # volume (33 deals) in Q4 CY23 ● Average deal size decreased by ~25% in Q4 to ~US$ 18.1M on quarter - over - quarter basis; however, the number of early - stage deals in Q4 CY23 compared to Q4 CY22 increased ● SaaS/AI was the most attractive sector for early - stage investments ( ~US$ 240M) and growth - stage investments (~US$ 956M) due to its potential to disrupt traditional industries and help realize profits in the long run ‒ Hyperspace, a consumer app & platform, received the highest funding of ~US$ 55M among early - stage investments ‒ Tamara, a SaaS/AI platform, received the highest funding of ~US$ 340M among growth - stage investments ● Fintech (~US$ 634M) & cybersecurity (~US$ 302M) attracted highest tech investments in Q4 CY23 MENA region definition Syria Lebanon Palestine Tunisia Iraq Israel Iran Morocco Jordan Kuwait Bahrain Libya Algeria Qatar Saudi Arabia Egypt UAE Oman Sudan Yemen © 1Lattice | 5 Key highlights Funding # Deal v olume Average ticket size US $ 1.7 B 92 US$ 18.1M SNAPSHOT Q4 CY 2023 Top funded sector Most funded stage (by deals) Total tech funding SaaS / AI Early US$ 1.5B Market by segments SaaS / AI leads funding followed by consumer apps & platforms in Q4 CY23 Funding market segment wise break - up (US$ M, Q4 CY23) Total funding size: US$ 1,667M 196 Consumer apps & platforms 1,196 35 41 Healthcare & Life Others Sciences SaaS / AI 120 30 35 Manufacturing Ecommerce 5 10 & listing BFSI Engg . & platforms IT services construction Note(s): * These include fine dining restaurants, oilfield service company, AI integrated smart contact lens, & spacetech © 1Lattice | 7 Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Investment amount and # deals ~US$ 1.7B was raised in MENA by companies across 92 deals in Q4 CY23 Investment amount (US$ B) and # deals (Q4 CY22 – Q4 CY23) 125 14 investments had undisclosed 108 amount 92 90 84 2.2 2.1 2.0 1.9 1.7 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), and late (Series F onwards) stage investments, others (PIPE and unattributed) Source(s): 1Lattice Deals Database © 1Lattice | 9 Stage - wise investments Q4 CY23 experienced a slowdown in $ value and # volume of deals of ~15% and ~26% respectively from Q4 CY22 Investment amount (US$ B) and # deals (Q4 CY22 – Q4 CY23) One late stage and 125 other investment each 2.2 2.1 have undisclosed amounts 2.0 108 1.9 0.9 0.05 0.3 0.2 1 .7 92 90 84 1.2 1.5 1.1 1.4 0.9 0.6 0.6 0.4 0.4 0.4 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Early Growth Late Others Deals Source(s): 1Lattice Deals Database © 1Lattice | 10 Country - wise investments Saudi Arabia drew highest investment of ~US$ 753M followed by Israel (~US$ 582M) and UAE (~US$ 213M) Investment amount (US$ M) and # deals (Q4 CY23) Avg. deal size (US$ M) = 44.3 17.6 11.5 2.1 5.0 10.7 800 33 Includes 2 mega deals of Tamara and Tabby worth ~US$ 540M, uplifting the 20 average deal size 17 14 582 753 6 230 2 64 30 10 Amount Deals Others* Israel UAE Saudi Arabia Egypt Kuwait Note(s): *Others include Tunisia, Lebanon, Morocco, Oman, Jordan & Palestine Source(s): 1Lattice Deals Database © 1Lattice | 11 Average deal size Average deal size decreased by ~25% in Q4 to ~US$ 18.1M on quarter - over - quarter basis Average deal size Split of deal volume (US$ M, Q4 CY22 – Q4 CY23) (#, Q4 CY22 – Q4 CY23) 125 108 84 90 92 # of deals = 1% 1% 2% 1% 2% 6% 24.3 22.9 17% While total # of deals 20% 26% in Q4 remained in line 20% 33% with Q3, deal size 19.3 reduced by ~25%, bringing down the 18.1 total investments in Q4 15.9 82% 78% 74% 72% 65% Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Early Growth Late Others Source(s): 1Lattice Deals Database © 1Lattice | 12 Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Top 10 investments in CY23 Top 10 investments in the MENA region in CY23 Top 10 investments in CY23 Amount Company Sector Funding stage Country Key Investors (US$ M) SNB Capital, 500 Group, Shorooq Partners, Pinnacle 340 Growth Saudi Arabia SaaS/AI Capital, Impulse and Checkout.com Lightspeed Venture Partners, Greenoaks Capital 300 Israel SaaS/AI Growth Partners and Index Ventures Universal Rubber Belt Manufacturing and Stars Engg. & 272 Others UAE Plastics Industries Construction ION Group, Social Leverage, SoftBank and Spark Israel SaaS/AI 250 Late Capital LightSpeed Venture Partners, Adams Street Partners, 238 Israel Softbank Vision Fund 2, Sixty Degree Capital and SaaS/AI Late Singtel Innov8 Wellington Management, Bluepool Capital, STV, Mubadala Capital, PayPal Ventures and Arbor 200 Saudi Arabia SaaS/AI Growth Ventures Development Partners International ,British International Investment (BII), South Suez and 165 Egypt Retail Growth others Ecommerce & 156 Growth Kuwait Aljazira Capital, Rainwater Partners and STV listing platforms Walden Catalyst, Pitango, SCB10X, b2venture, 155 Israel SaaS/AI Growth Samsung Next, Google and NVIDIA 150 UAE Undisclosed Manufacturing Growth © 1Lattice | 14 Source(s): 1Lattice Deals Database Top 10 investments in Q4 CY23 Top 10 investments in the MENA region in Q4 CY23 make ~60% of the total investments received in the region Top 10 investments in Q4 CY23 Amount Funding Company Sector Country Key Investors (US$ M) stage SNB Capital, 500 Group, Shorooq Partners, Pinnacle Capital, Impulse and 340 Growth Saudi Arabia SaaS/AI Checkout.com Wellington Management, Bluepool Capital, STV, Mubadala Capital, PayPal Ventures 200 SaaS/AI Growth Saudi Arabia and Arbor Ventures NVIDIA, Artofin, MoreTech, Nationwide, Volvo Group VC, Jump Capital, Next Gear SaaS/AI 85 Growth Israel Ventures and OurCrowd 70 Sapphire Ventures SaaS/AI Growth Israel 60 IFC, FMO and Mediterrania Capital Partners BFSI Growth Morocco Consumer 55 Galaxy Interactive, Apis Partners and Sega Sammy Holdings app & Early UAE platforms 55 Ten Eleven Ventures, Maor Investments, Dawn Capital and Wipro Ventures SaaS/AI Growth Israel 53 Intel Capital and Comcast Ventures SaaS/AI Growth Israel Lightspeed Venture Partners, Mubadala Capital, Pantera Capital, Framework 48 SaaS/AI Early UAE Ventures, Bain Capital Ventures, Digital Currency Group, Coinbase and Proof Group, Wa'ed Ventures, Raed Ventures, STV, Riyadh Valley Company, Endeavor, 500 Group, 43 SaaS/AI Growth Israel Qyem Development Holding and Nahlat Alarab Holding © 1Lattice | 15 Source(s): 1Lattice Deals Database Early - stage investments SaaS/AI received highest funding (~US$ 240M) among early - stage investments Top 10 early - stage investments in Q4 CY23 Early - stage investments, by sector Amount (US$ M, Q4 CY23) Company Sector Country Key Investors (US$ M) Consumer app & Galaxy Interactive, Apis Partners and UAE 55 SaaS/AI 240 platforms Sega Sammy Holdings Lightspeed Venture Partners, Mubadala Capital, Pantera Capital, Consumer app & platforms 142 Framework Ventures, Bain Capital SaaS/AI UAE 48 Ventures, Digital Currency Group, Ecommerce & listing platforms 36 Coinbase and Proof Group Opportunity Venture Others UAE 40 BFSI 32 Saudi Arabia 30 Merak Capital SaaS/AI Consumer app Saudi Arabia 28 Madarak International & platforms Healthcare & Life Sciences 28 Acrew Capital, 01 Advisors, HighSage Ventures, Abstract Ventures, Partech, Consumer app UAE 20 Manufacturing 10 Precursor Ventures, Potluck Ventures & platforms and Knollwood NFX, Andreessen Horowitz, LionBird , Healthcare & Life Engg. & Construction 10 Israel 20 Technion and Base 4 capital Sciences Jahez Group, Isometry Capital, Ecommerce & IT services 5 Saudi Arabia 18 Khwarizmi Ventures, Alrajhi Partners Deals are listing platforms and Outliers Venture Capital undisclosed Viola Ventures, LionBird , Exor Retail for retail, and 0 SaaS/AI Israel 15 Ventures transportation Yusuf Bin Kanoo Group, Technology & logistics Transportation & logistics 0 Group, Majd Digital, Aujan Group Consumer app & Saudi Arabia 15 Holdings, Shorooq Partners, platforms Abercross Holdings and Graphene Others 41 Ventures © 1Lattice | 16 0 100 200 Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A Source(s): 1Lattice Deals Database Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Online platform for building experiential attraction developer that creates, builds, operates, and funds attractions in digital world Provider of blockchain - based digital asset risk infrastructure solutions, leveraging deep experience in software systems, AI, and fintech AI - integrated smart contact lens Cloud - based platform for HRMS suite offering tools for management of employee data, document, payroll, expense, performance, etc. Provider of the online marketplace offering rental loans for businesses Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A Source(s): 1Lattice Deals Database © 1Lattice | 17 Growth - stage investments SaasS / AI dominated growth - stage investments (~US$ 956M) Top 10 growth - stage investments in Q4 CY23 Growth - stage investment, by sector (US$ M, Q4 CY23) Amount Company Sector Country Key Investors (US$ M) SNB Capital, 500 Group, Shorooq SaaS/AI 956 Partners, Pinnacle Capital, Impulse and Saas /AI Saudi Arabia 340 Checkout.com Wellington Management, Bluepool Saudi Arabia 200 SaaS/AI Capital, STV, Mubadala Capital, PayPal Ventures and Arbor Ventures BFSI NVIDIA, Artofin , MoreTech , Nationwide, 88 Israel 85 Volvo Group VC, Jump Capital, Next Gear SaaS/AI Ventures and OurCrowd SaaS/AI Israel 70 Sapphire Ventures Consumer app & platforms 54 IFC, FMO and Mediterrania Capital Morocco 60 BFSI Partners Ten Eleven Ventures, Maor Investments, Israel 55 SaaS/AI Dawn Capital and Wipro Ventures Manufaturing 20 Israel 53 Intel Capital and Comcast Ventures SaaS/AI Eight Roads Ventures, Qualcomm SaaS/AI Israel 43 Ventures, AB Private Credit Investors, TLV Partners and Magma Ventures Healthcare & Life Sciences 7 Wa'ed Ventures, Raed Ventures, STV, Consumer app Riyadh Valley Company, Endeavor, 500 Saudi Arabia 41 & platforms group, Qyem Development Holding and Nahlat Alarab Holding 1500 Israel 35 Aleph and Group 11 SaaS/AI © 1Lattice | 18 Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice Deals Database Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors Provider of an online platform for point - of - sale financing Provider of AI - based purchase financing solutions to businesses Tech - enabled system verification and simulation platform for autonomous vehicles Behavioral biometrics cybersecurity solutions Third party agent network for remittance companies. Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice Deals Database © 1Lattice | 19 Tech investments Fintech & cybersecurity attracted highest tech investments in Q4 CY23 Top 10 tech investments in Q4 CY23 Tech investments, by sector Amount Company Sector Country Key Investors (US$ M) (US$ M, Q4 CY23) FinTech 634 SNB Capital, 500 Group, Shorooq Partners, Saudi Arabia 340 Fintech CyberSecurity Pinnacle Capital, Impulse and Checkout.com 302 Wellington Management, Bluepool Capital, Logistics tech 97 Fintech Saudi Arabia 200 STV, Mubadala Capital, PayPal Ventures and EdTech 75 Arbor Ventures NVIDIA, Artofin , MoreTech , Nationwide, Volvo Media & entertainment 55 Israel 85 Group VC, Jump Capital, Next Gear Ventures, Logistics tech Generative AI and OurCrowd 53 Blockchain Israel 70 Sapphire ventures Cybersecurity 48 HR Services 30 Media & Galaxy Interactive, Apis Partners and Sega UAE 55 entertainment Sammy holdings Machine Learning 28 Ten Eleven Ventures, Maor Investments, EnterpriseTech Cybersecurity Israel 55 22 Dawn Capital and Wipro Ventures PropertyTech 21 Israel 53 Intel Capital and Comcast Ventures Generative AI Pharma & Biotech 20 Lightspeed Venture Partners, Mubadala Reselling platform 18 Capital, Pantera Capital, Framework UAE 48 Blockchain Ventures, Bain Capital Ventures, and Digital Financial services 14 Currency Group, Coinbase, Proof Group, Others include Travel & Hospitality 13 Eight Roads Ventures, Qualcomm Ventures, Advertisement & sales, B2B Israel 43 AB Private Credit Investors, TLV Partners and Cybersecurity HealthTech ecommerce, HRtech , AI, 12 Magma Ventures Spacetech , Foodtech , Others Climatetech , Insuretech 20 Wa'ed Ventures, Raed Ventures, STV, Riyadh Valley Company, Endeavor, 500 Group, Qyem Saudi Arabia 41 Edtech Development Holding, Nahlat Alarab Holding © 1Lattice | 20 Source(s): 1Lattice Deals Database Top 10 M&As Top 10 M&As in CY23 Top 10 M&As in CY23 Amount Acquired Company Sector Country Date Acquirer (US$ M) December 16, Manufacturing UAE 3 ,620 2023 September 03, Manufacturing Saudi Arabia 3 ,330 2023 November 06, Manufacturing Israel 600 2023 UAE 4 63 June 21, 2023 Others UAE 400 April 10, 2023 Consumer app & platforms September 13, Israel 300 Consumer app & platforms 2023 September 07, SaaS/AI Israel 265 2023 Saudi Arabia 1 33 October 26, 2023 Transportation and logistics September 28, Saudi Arabia 133 BFSI 2023 Israel 110 April 27, 2023 SaaS/AI Note(s): Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice Deals Database © 1Lattice | 21 Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Active investors Most active investors of Q4 CY23 Growth - stage investors Early - stage investors (# deals) (# deals) 3 3 3 3 3 3 3 2 2 2 2 2 2 2 2 2 2 2 2 2 2 Source(s): 1Lattice Deals Database © 1Lattice | 23 Active early-stage investors Most active early-stage investors and their investment segments in Q4 CY23 Includes Healthcare & Life Sciences and IT Ecommerce & Consumer app listing Investors Manufacturing Energy BFSI SaaS/AI Others & platforms platforms - - - - - - - - - - - - - - - - - - - - - - - - Note(s): Investors who have invested in more than 2 companies © 1Lattice | 24 Source(s): 1Lattice Deals Database Active growth-stage investors Most active growth-stage investors and their investment segments in Q4 CY23 Ecommerce Healthcare Consumer Investors & listing & Life Manufacturing FMCG SaaS/AI app & BFSI Telecom platforms Sciences platforms - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - Note(s): Investors who have invested in more than 1 company © 1Lattice | 25 Source(s): 1Lattice Deals Database 500+ 30% Technology - backed business annual engagements faster to outcomes support that helps you 600+ 8 ENABLE BETTER years domain practices expertise DECISIONS 130+ 98% + Deep on - ground insights that you can act on team members accuracy 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 100+ 2.5M towns & cities panel members One - ness of data and people networks to harness the collective power of data, network, and technology Multi - faceted teams offering a stack of consulting, 15+ 40:6 0 advisory, and research services languages covered she/he ratio We are here for you Let us know how we can meet your business requirement? Roma Dixit Director, Financial Investors For media queries, please contact Vaishnav Kumar Rai Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Latt ice , if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best dat a we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the sam e before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available info rma tion and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant inf ormation available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market co nd itions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affi lia tes, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice doe s not hold any liability in connection therewith. +91 987 390 5272 roma.dixit@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore