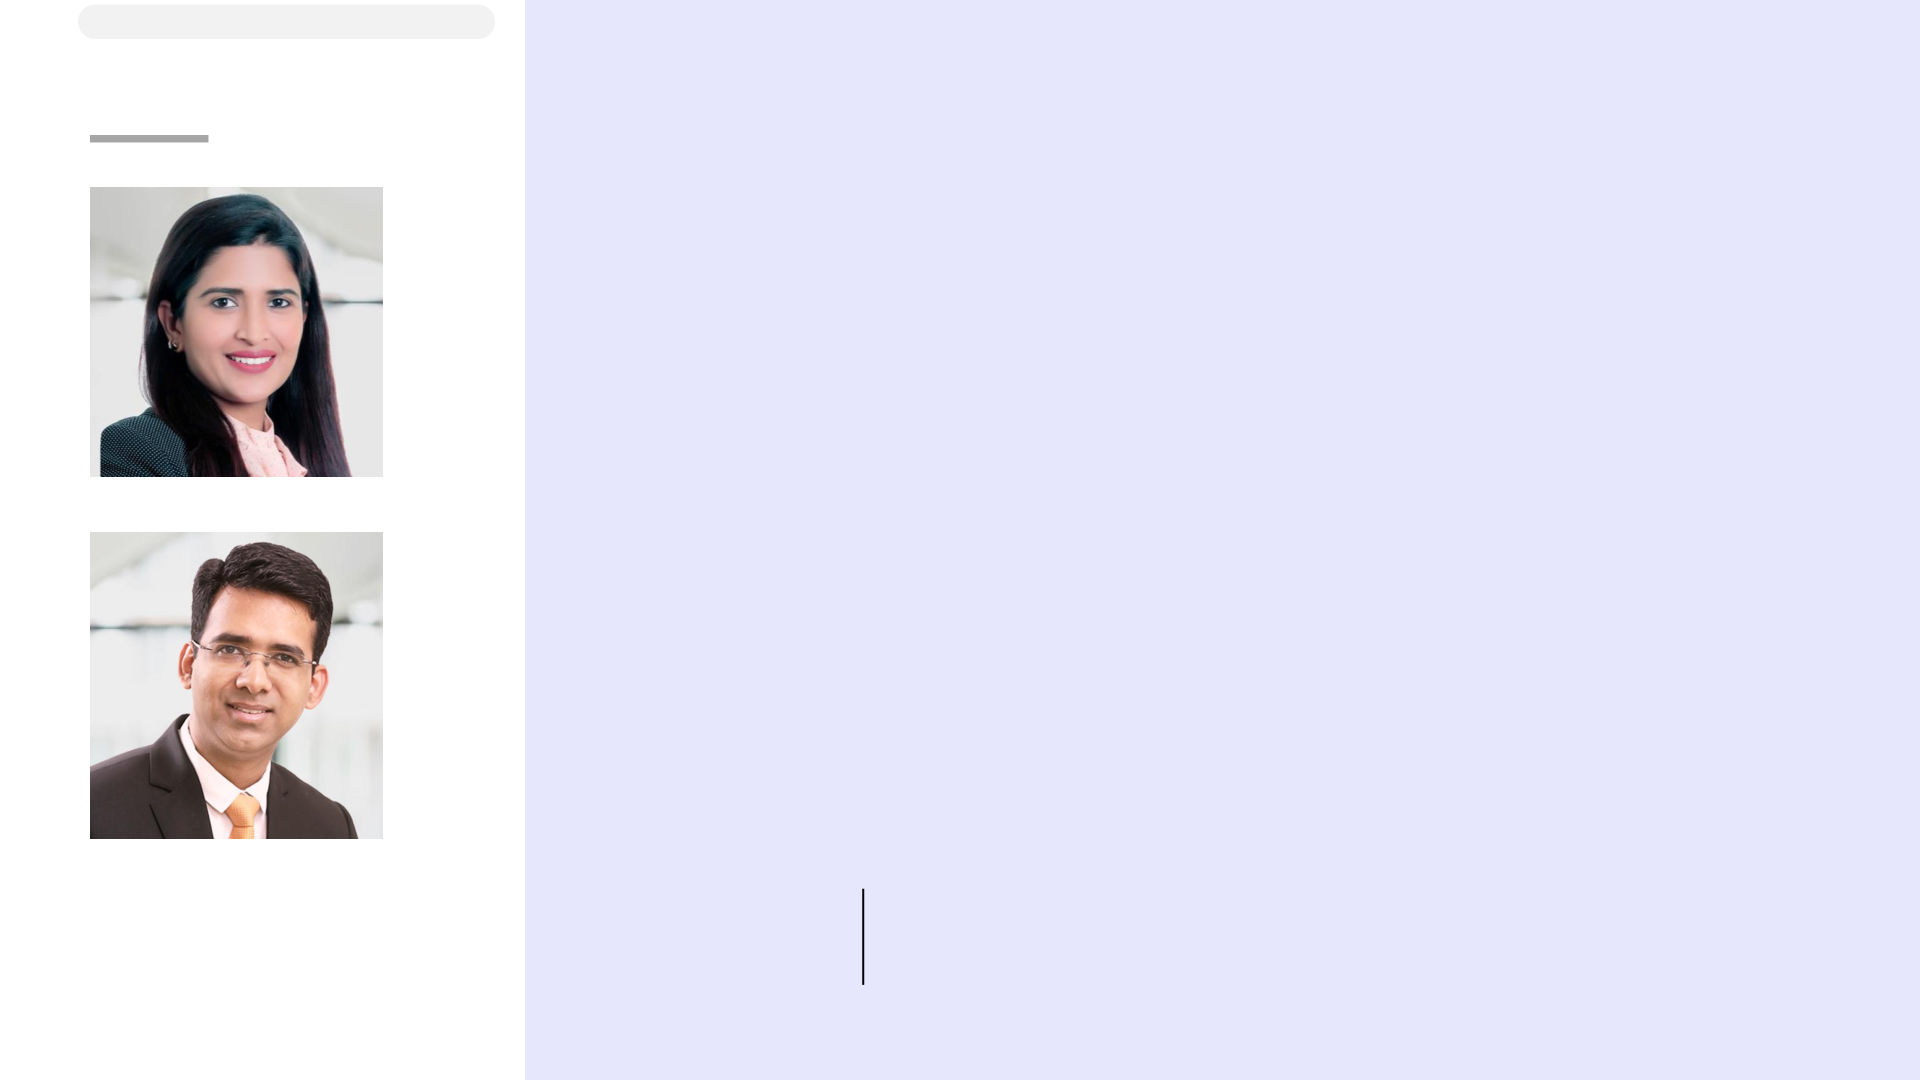
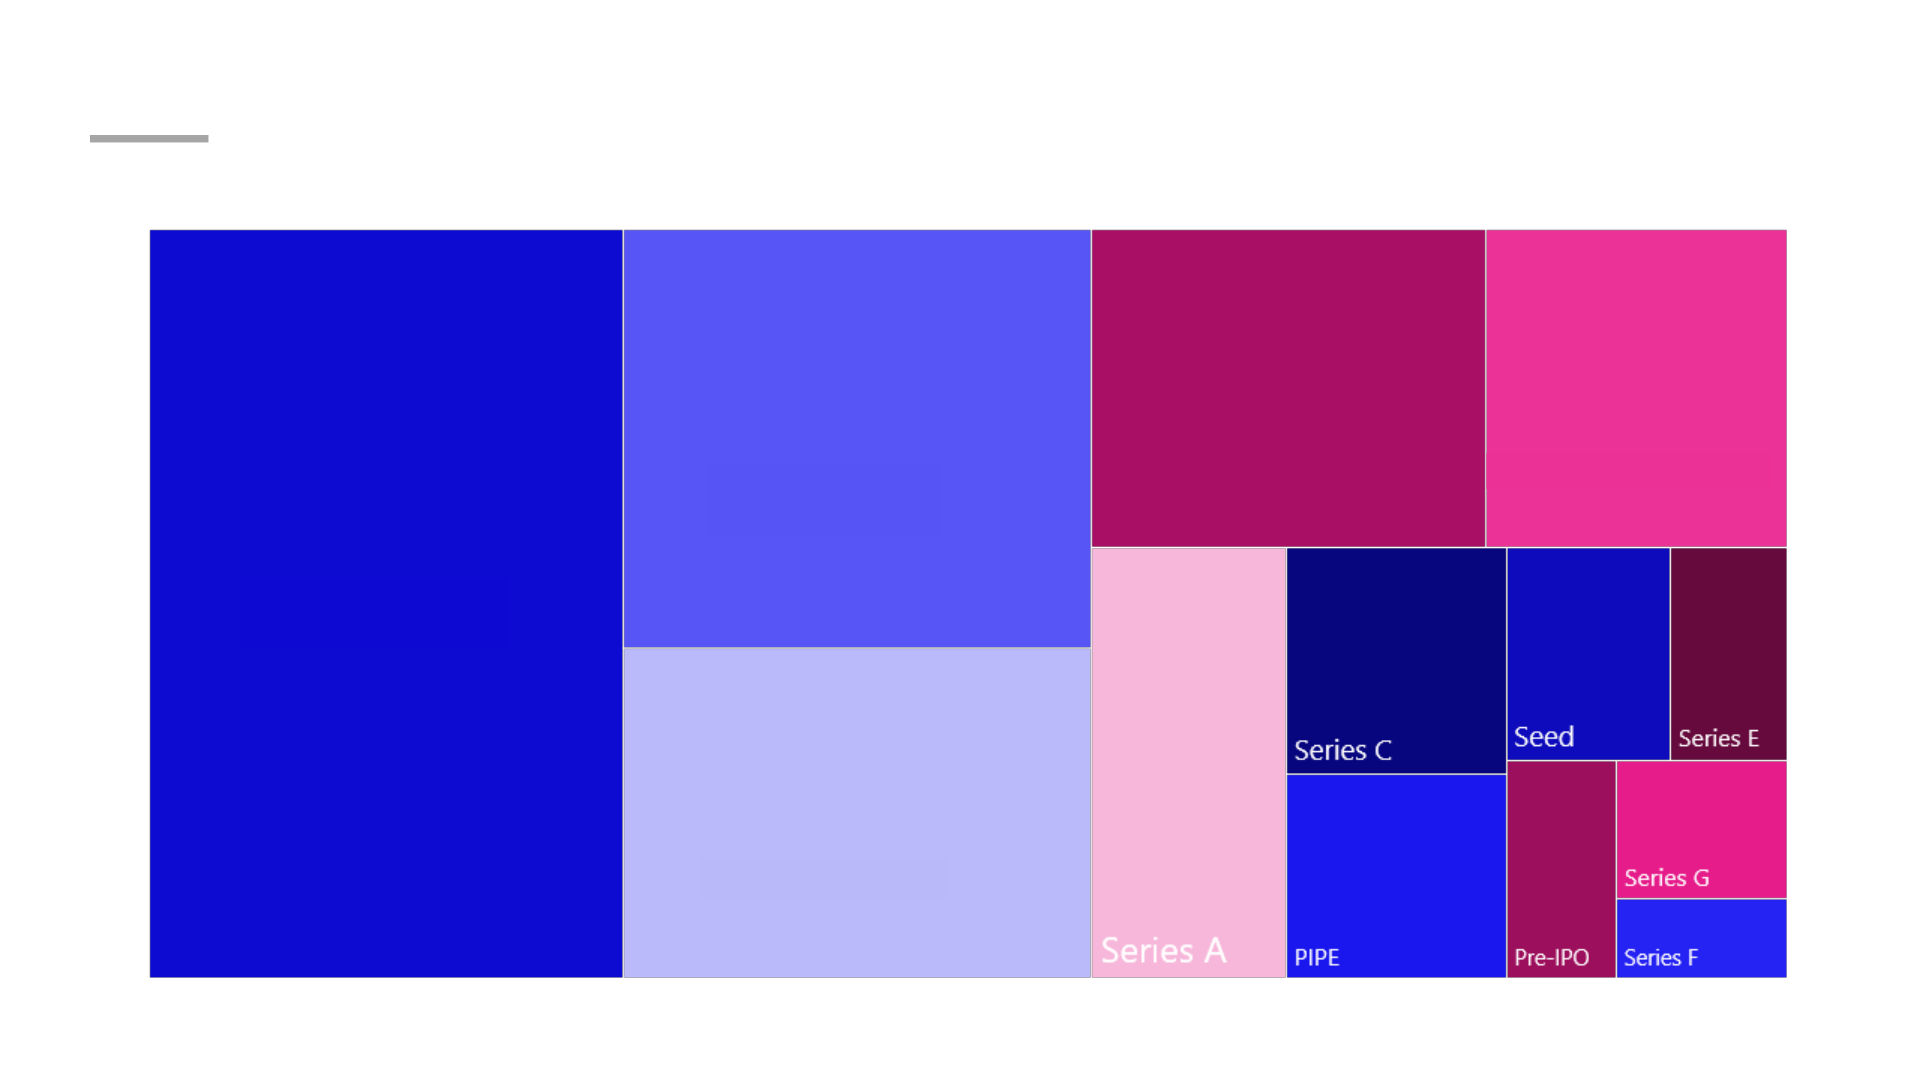
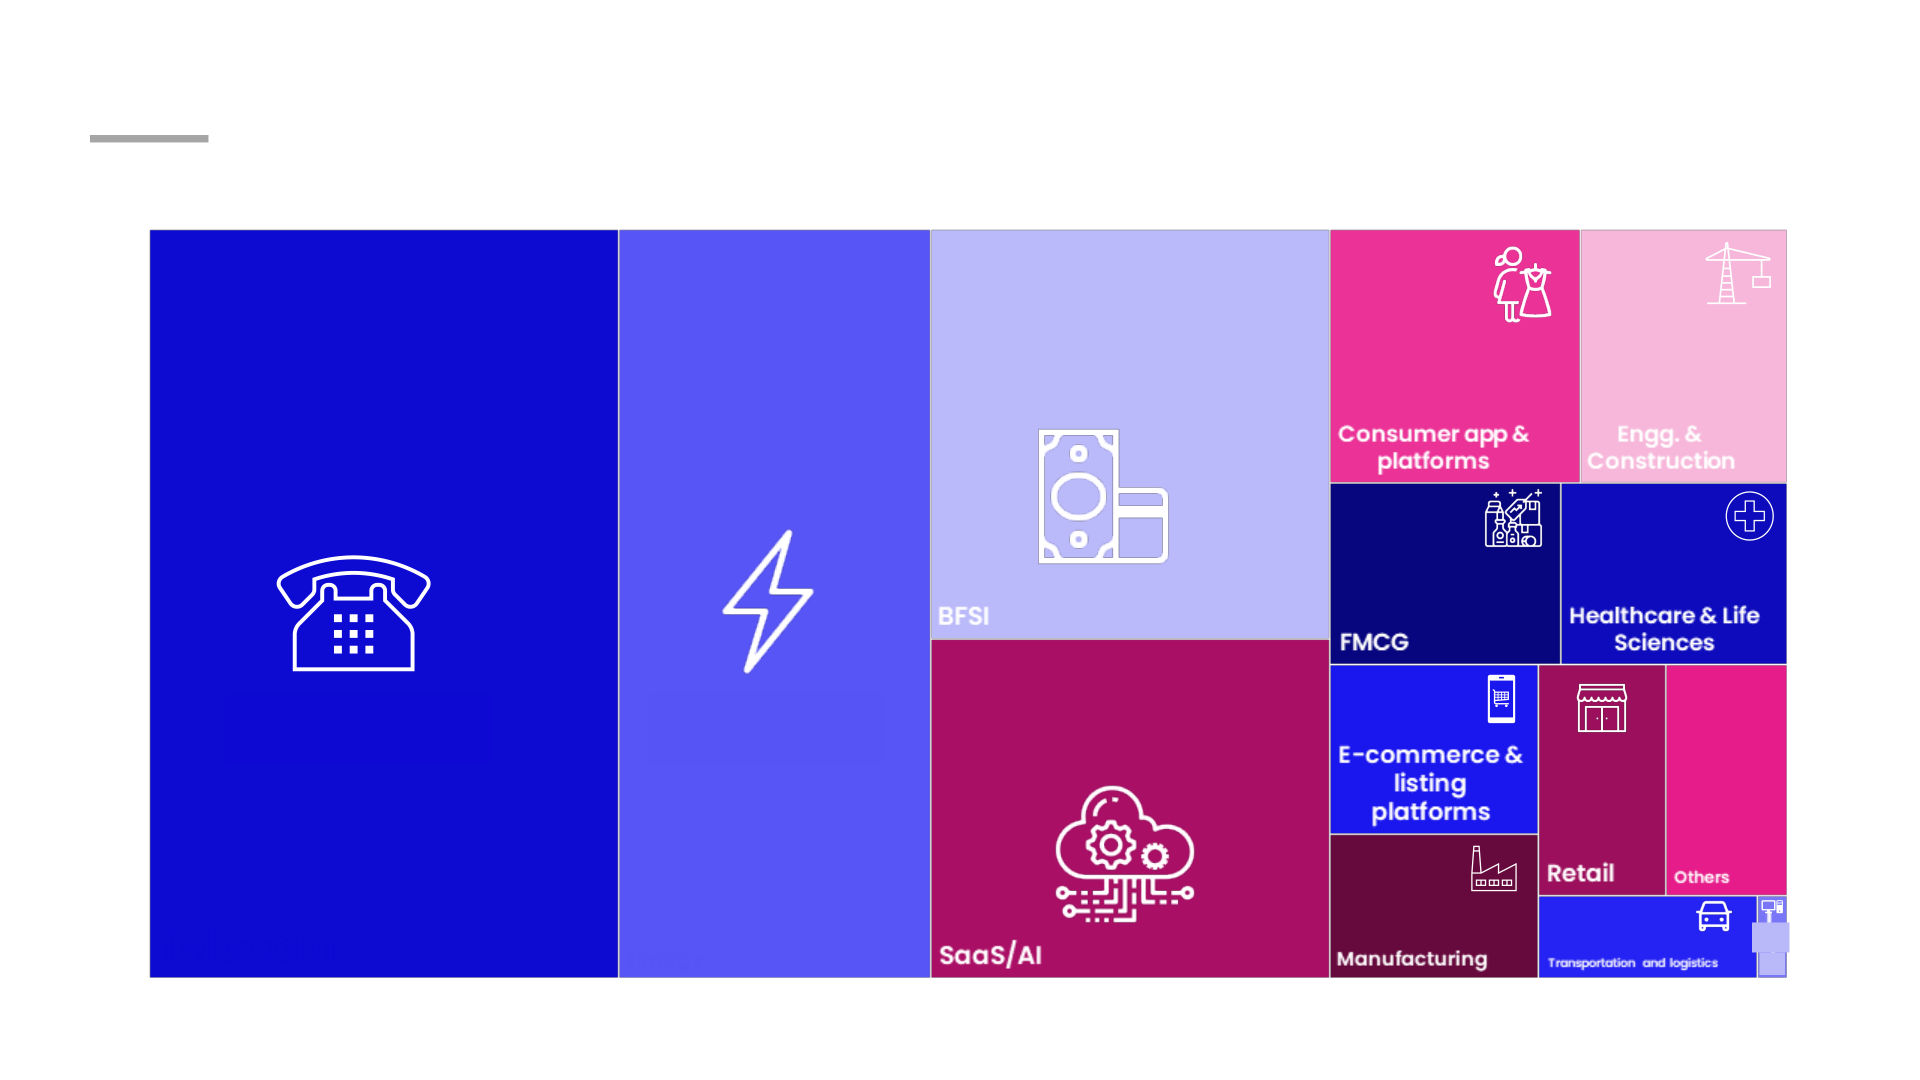
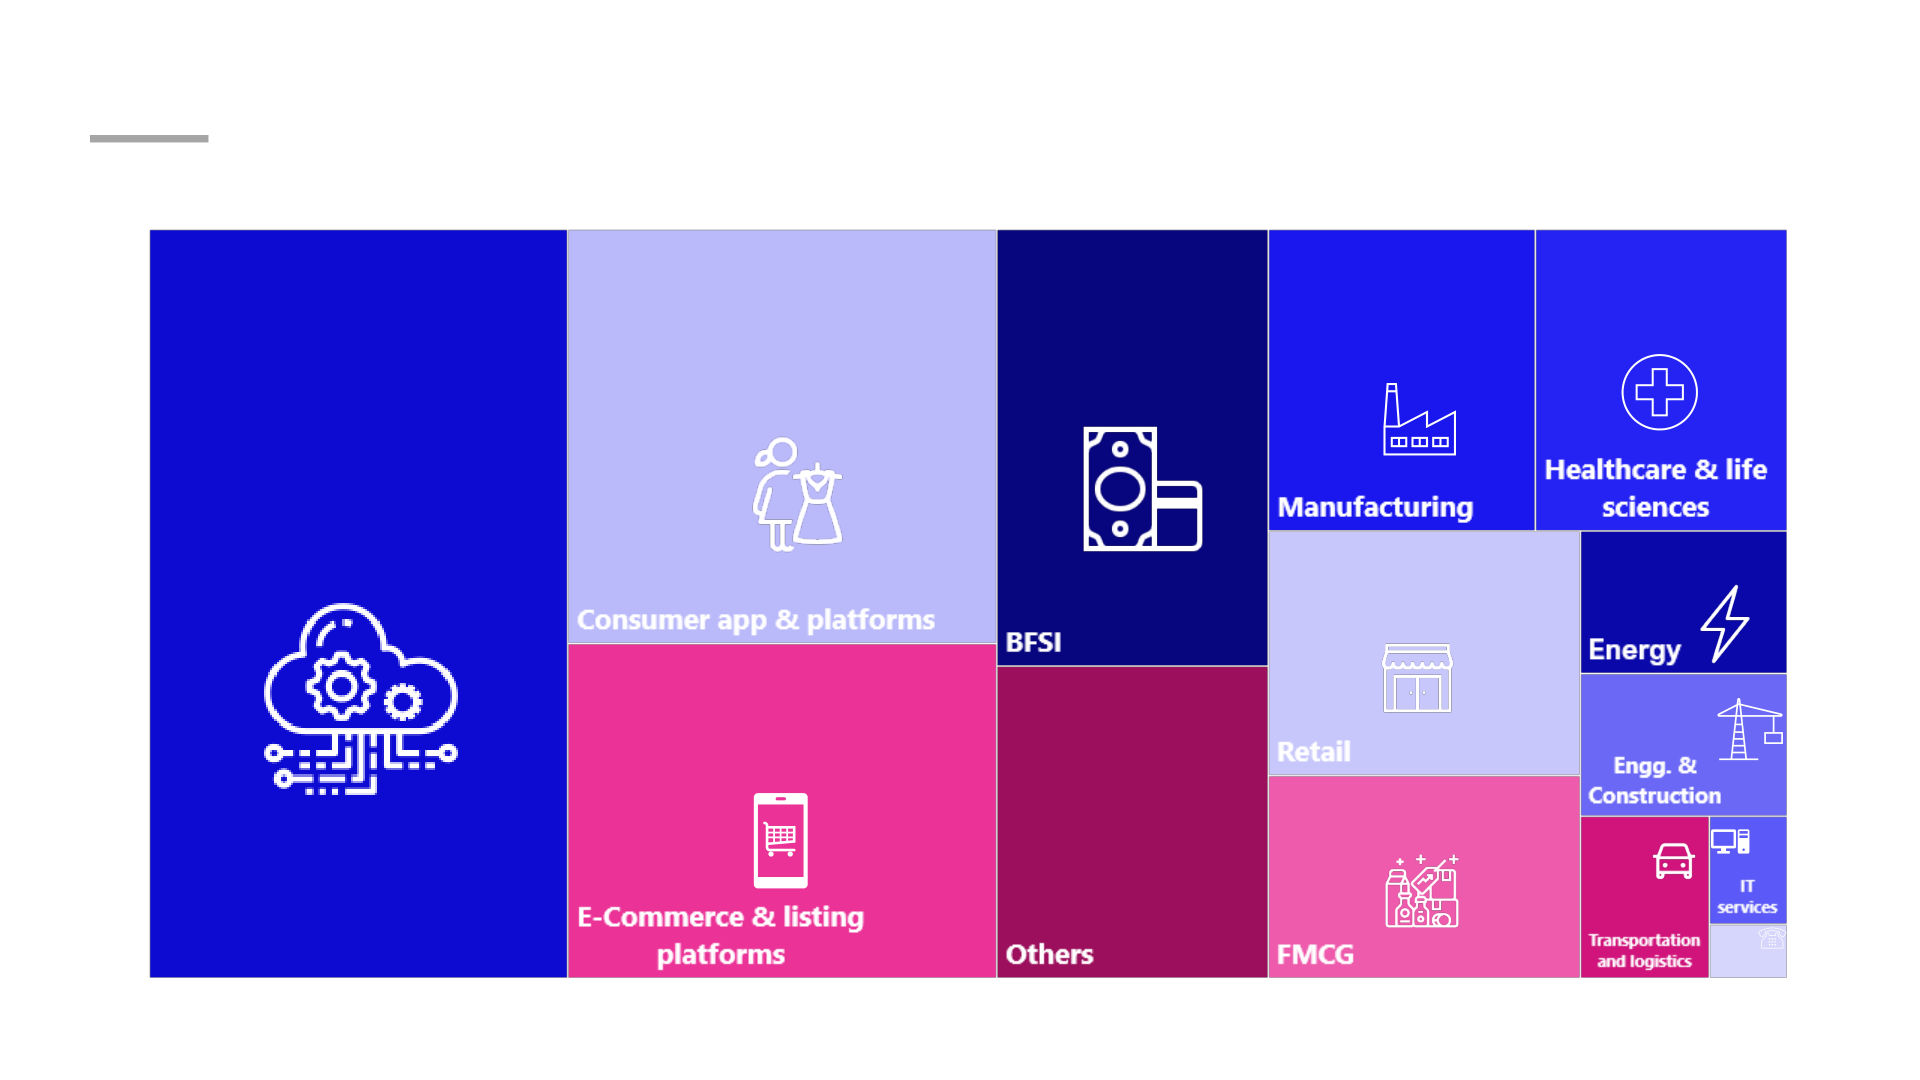
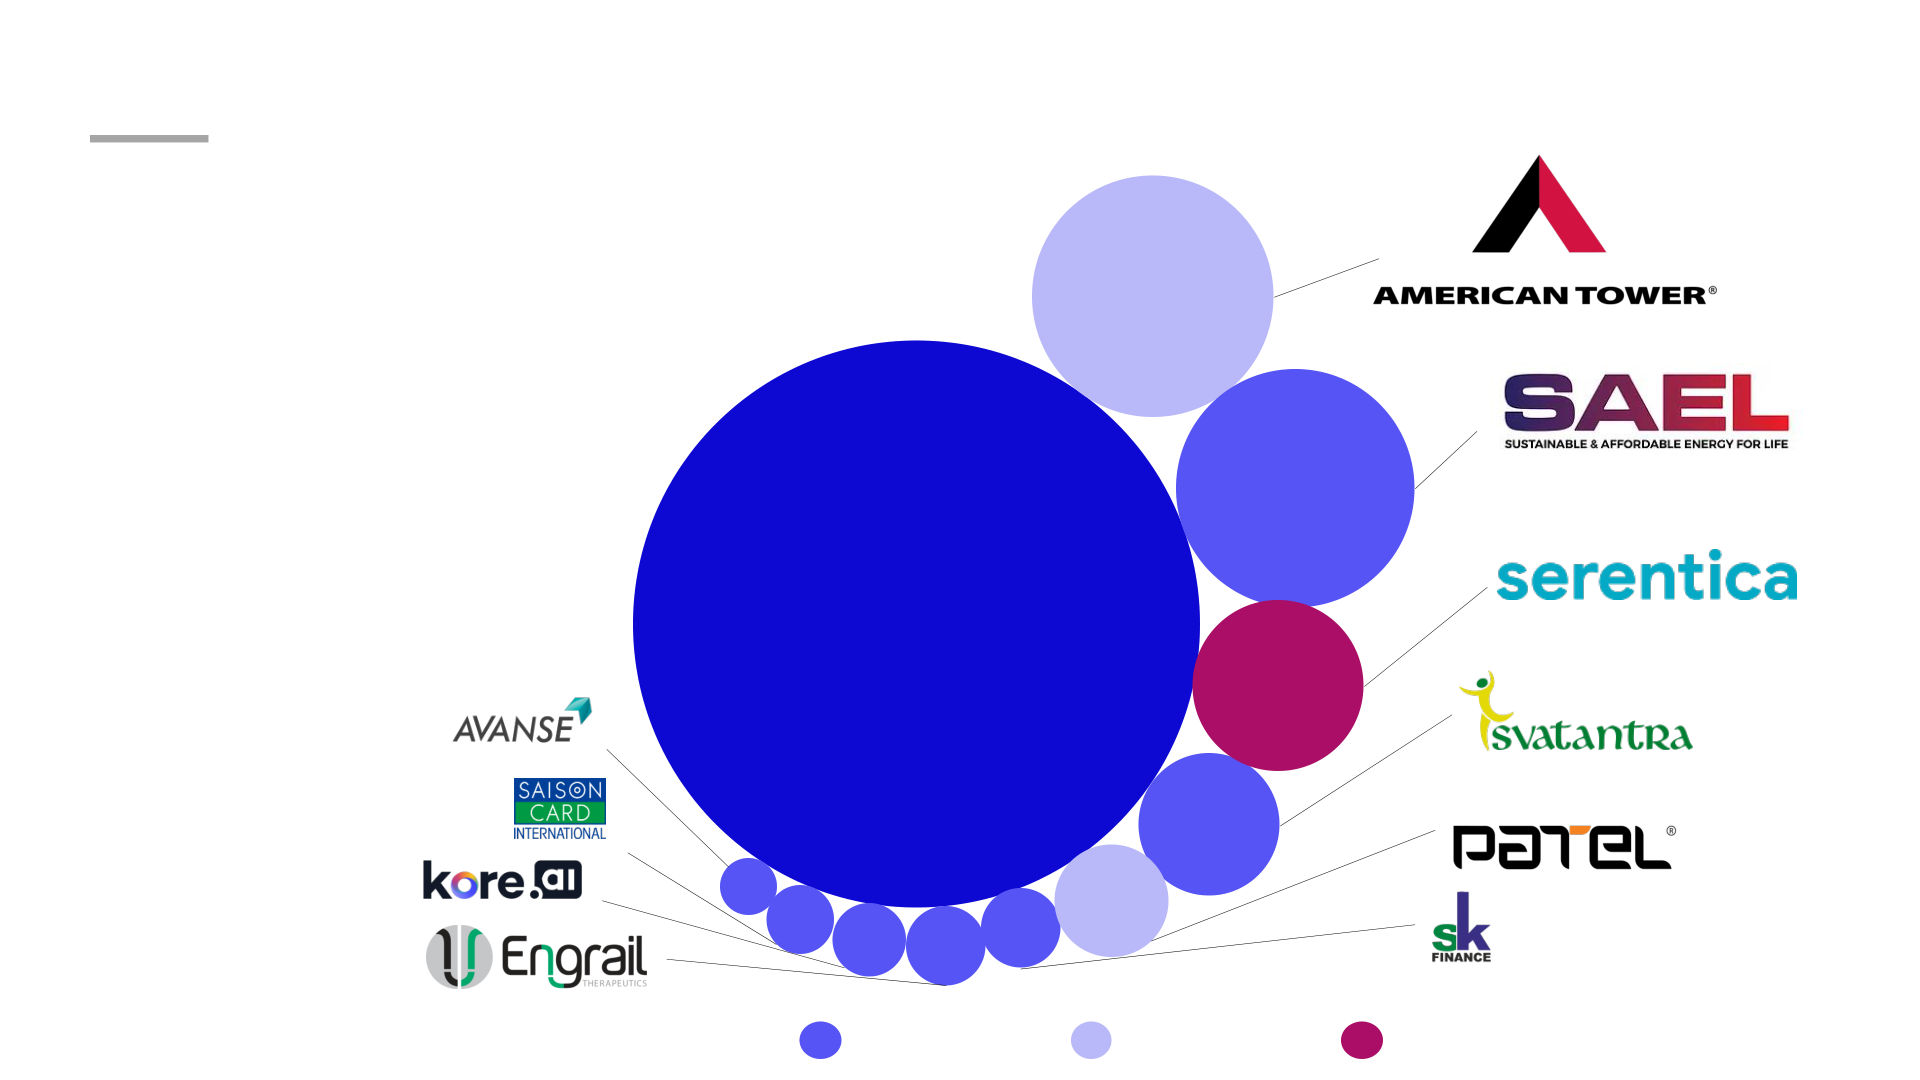
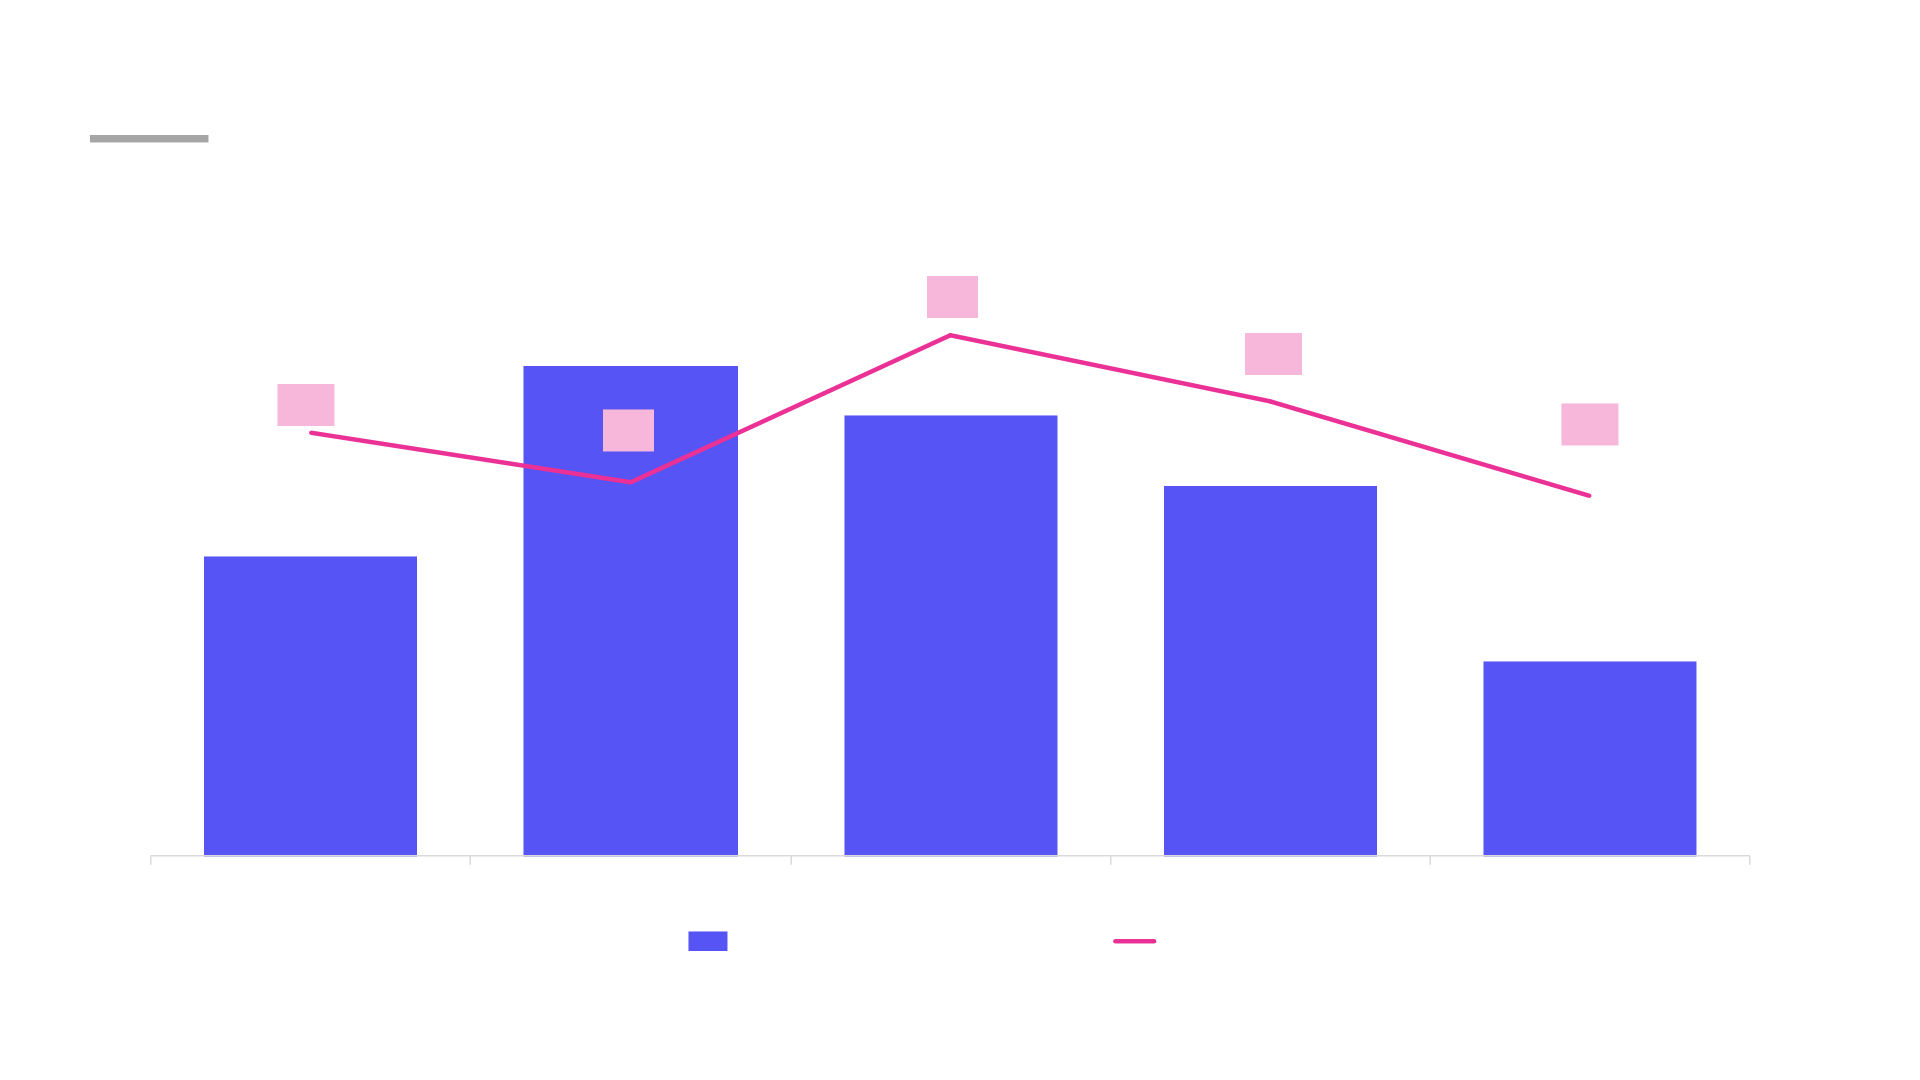
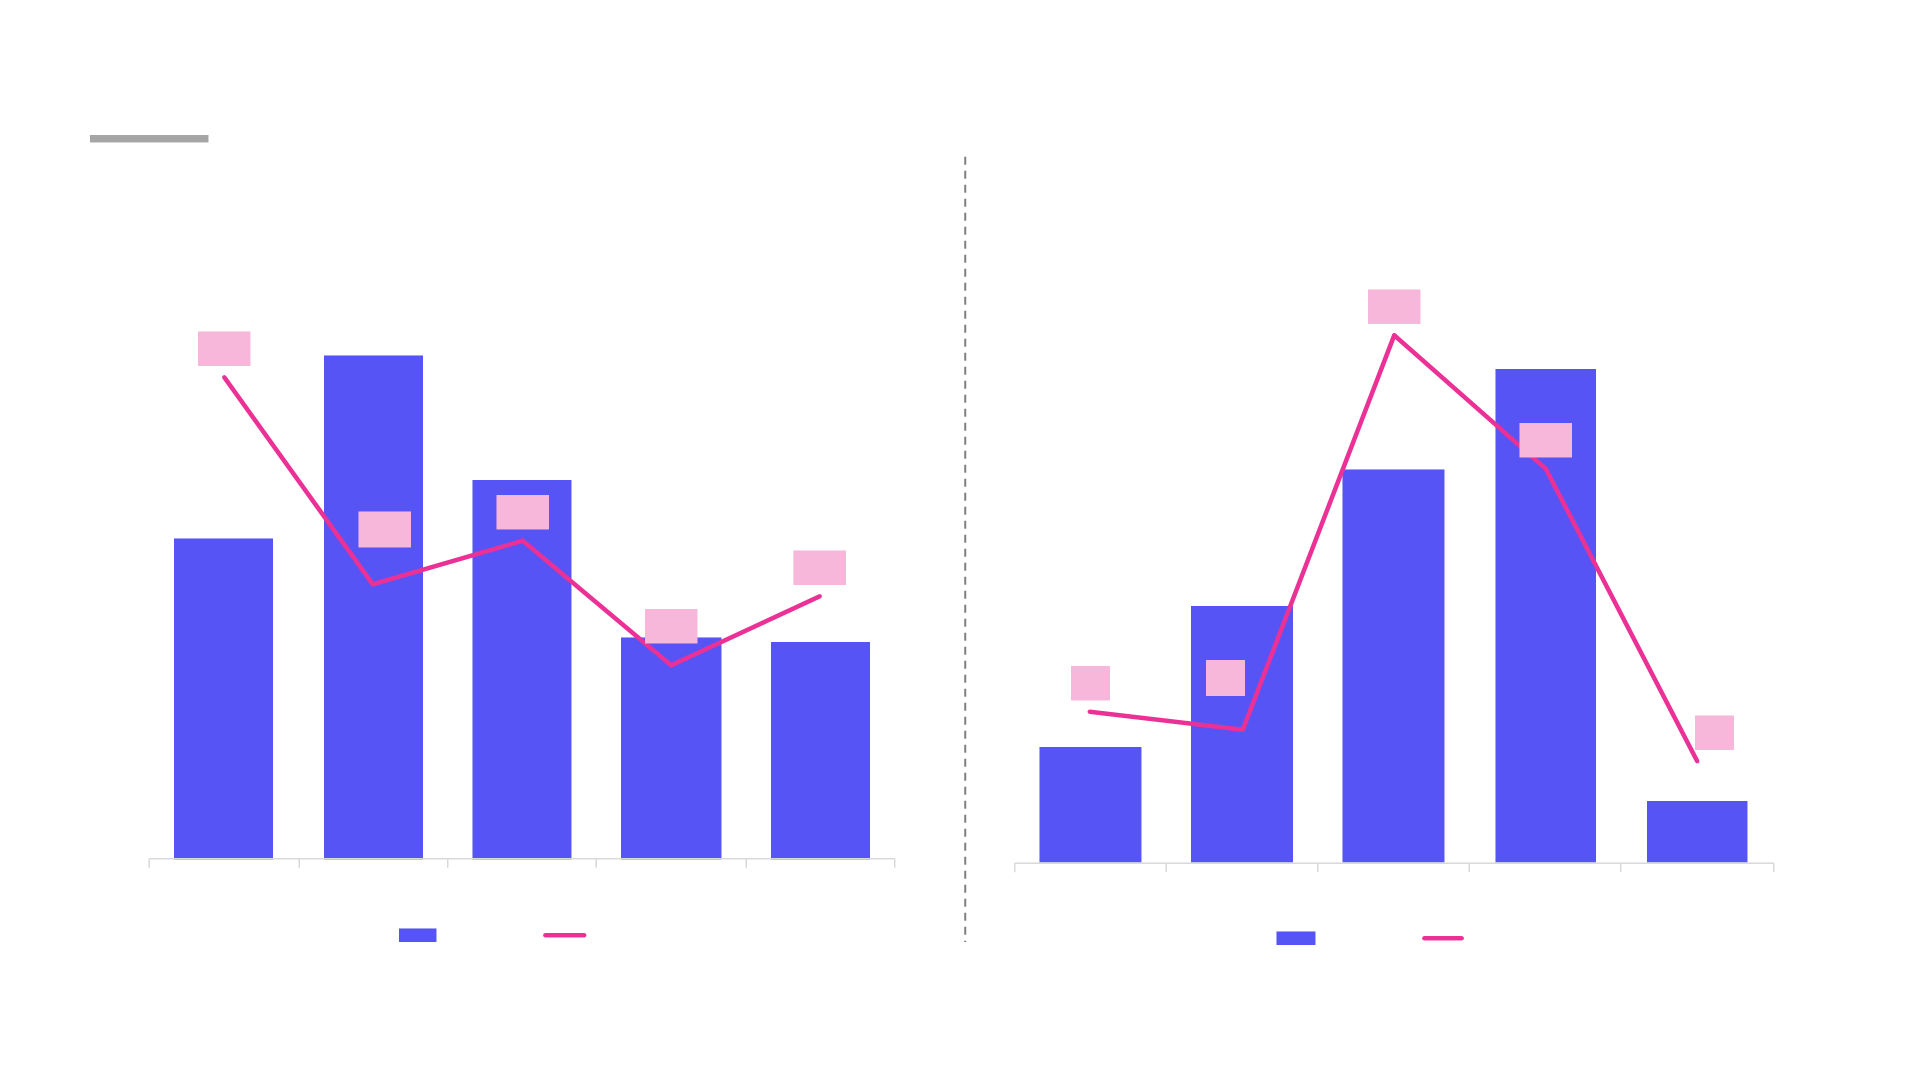
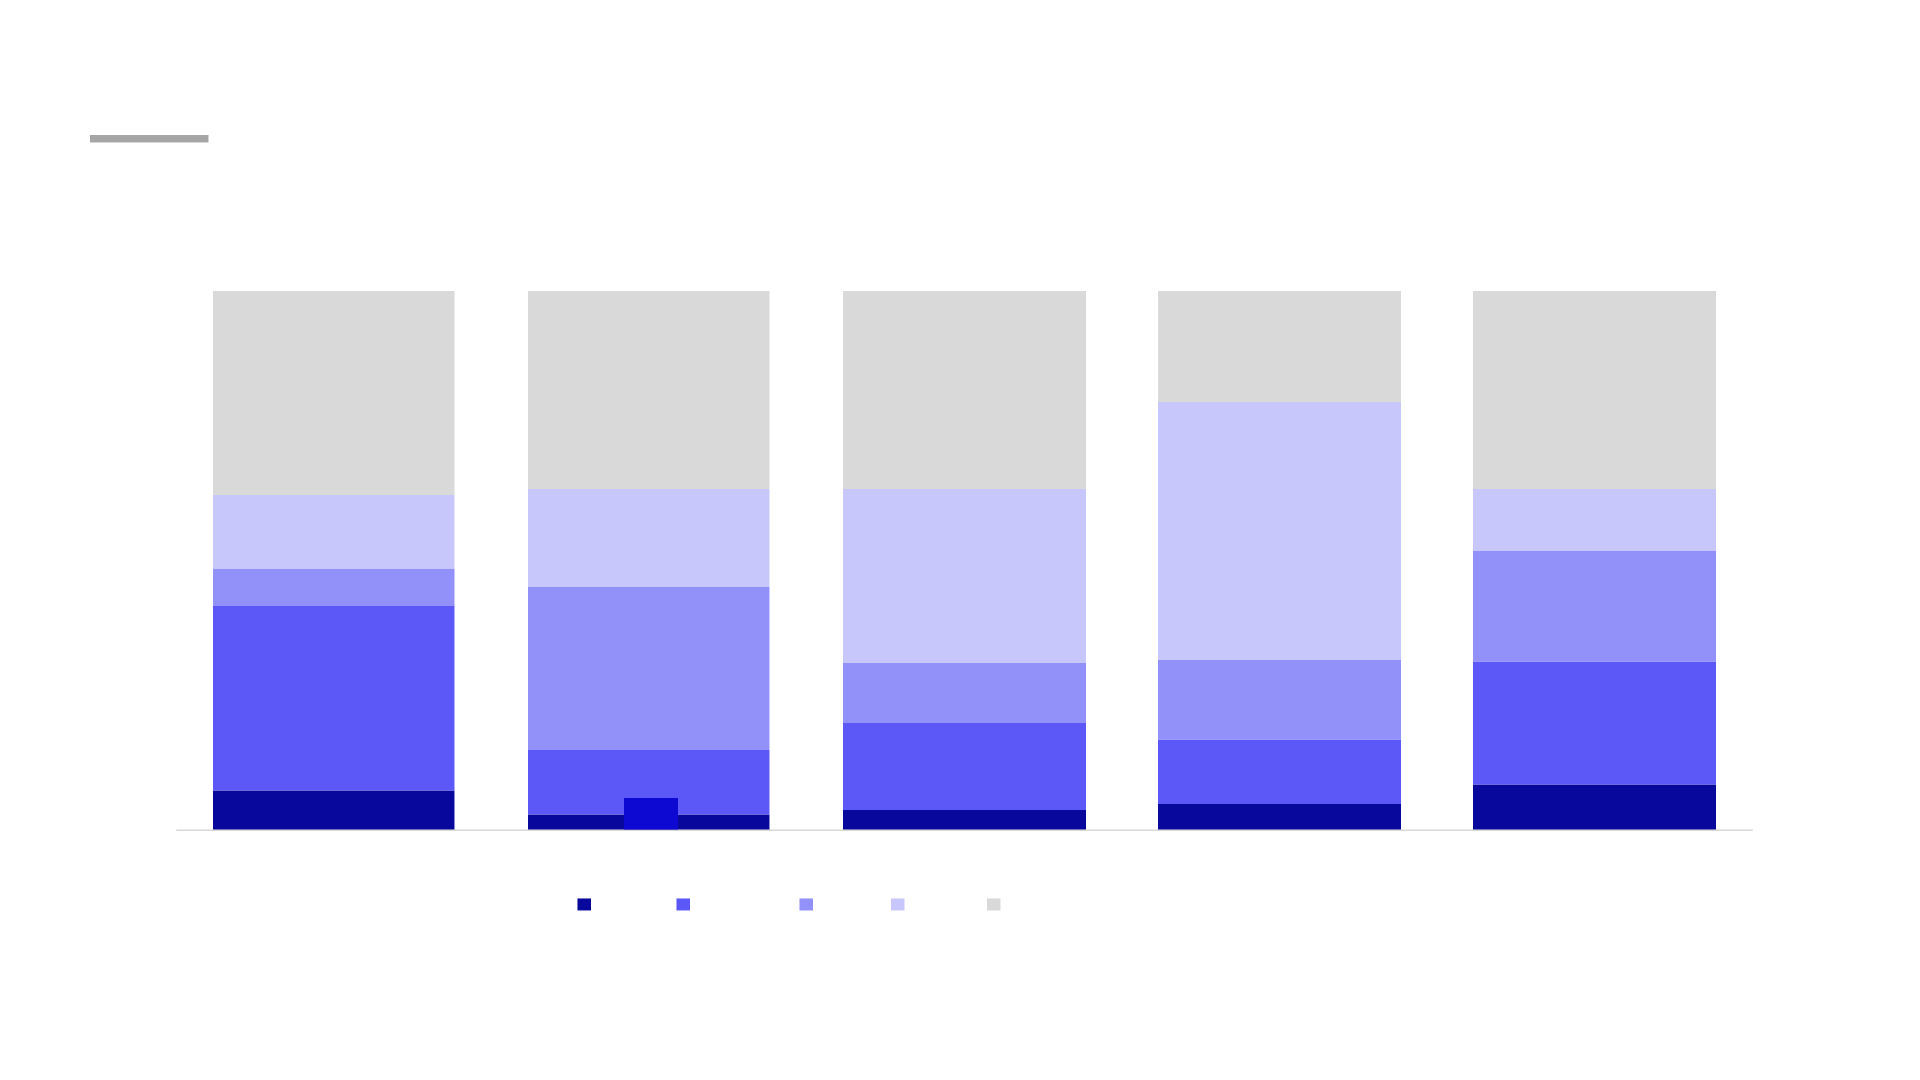
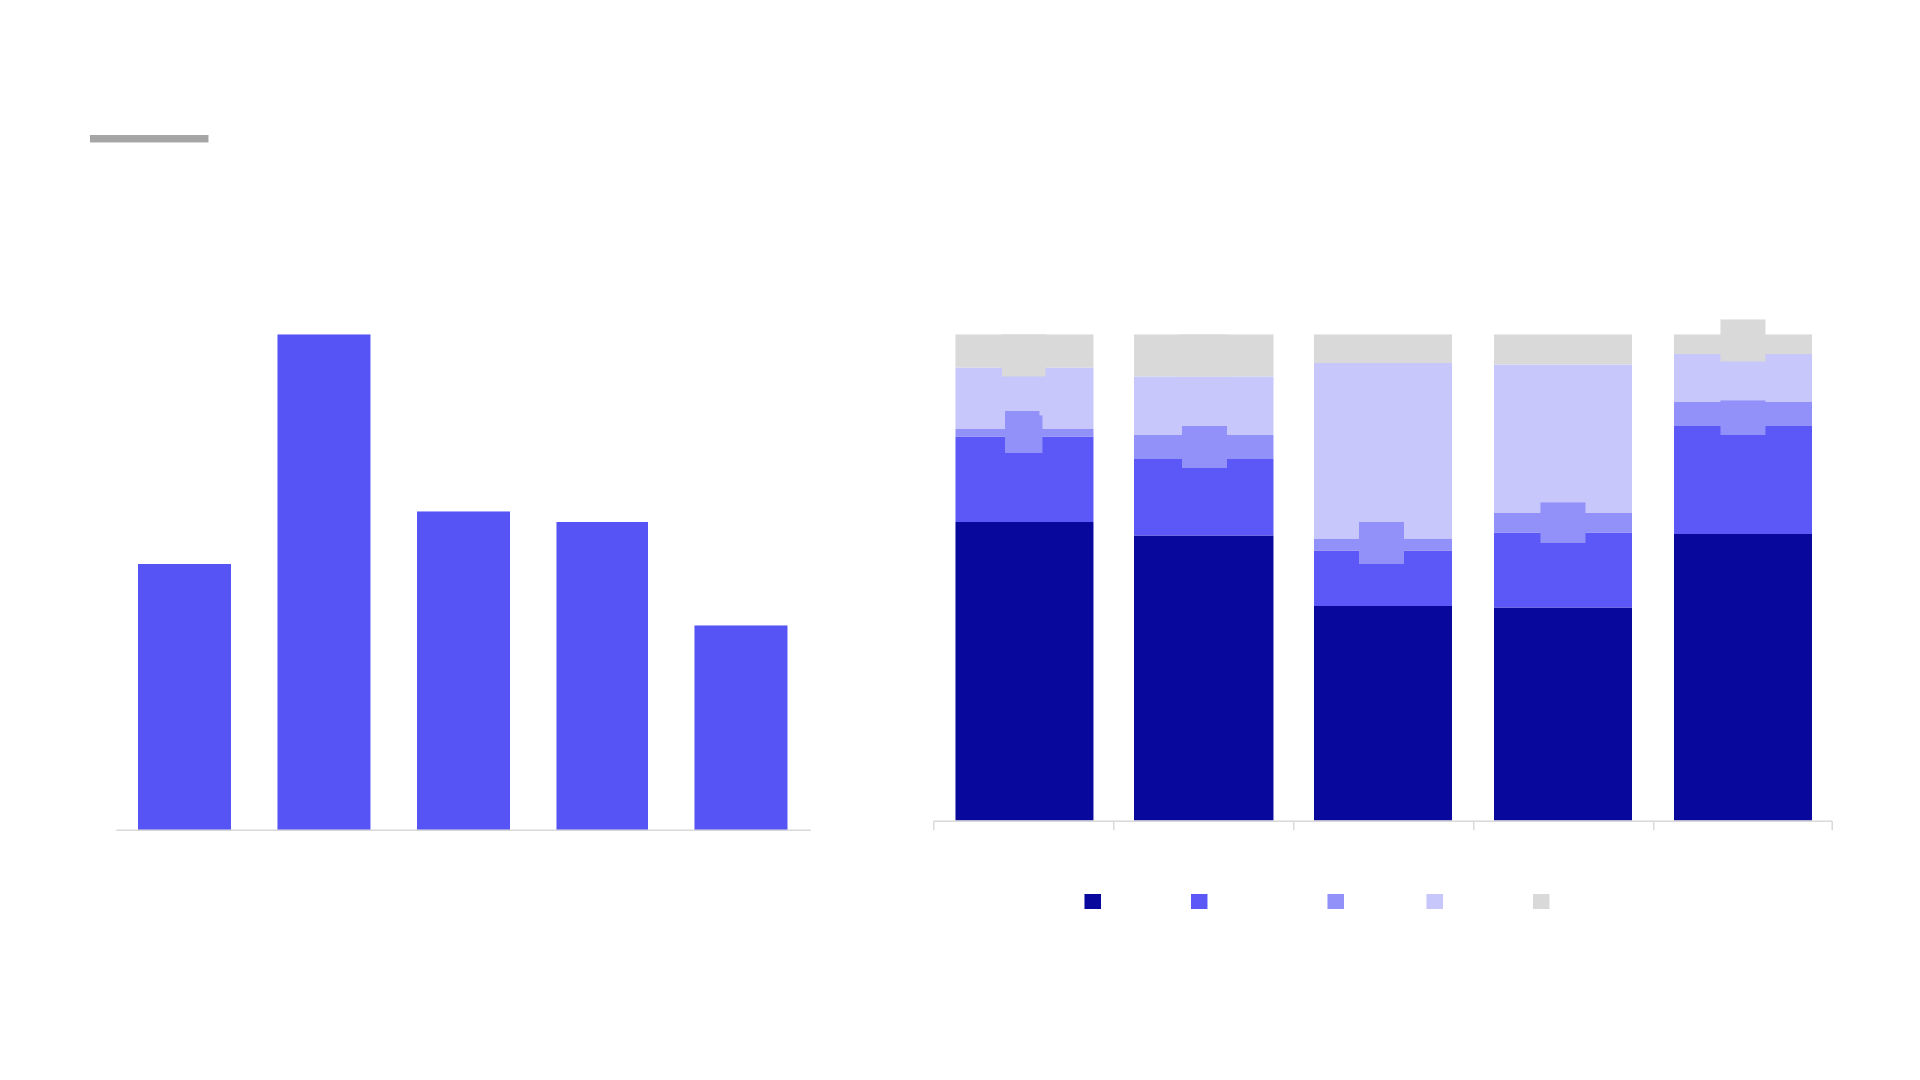
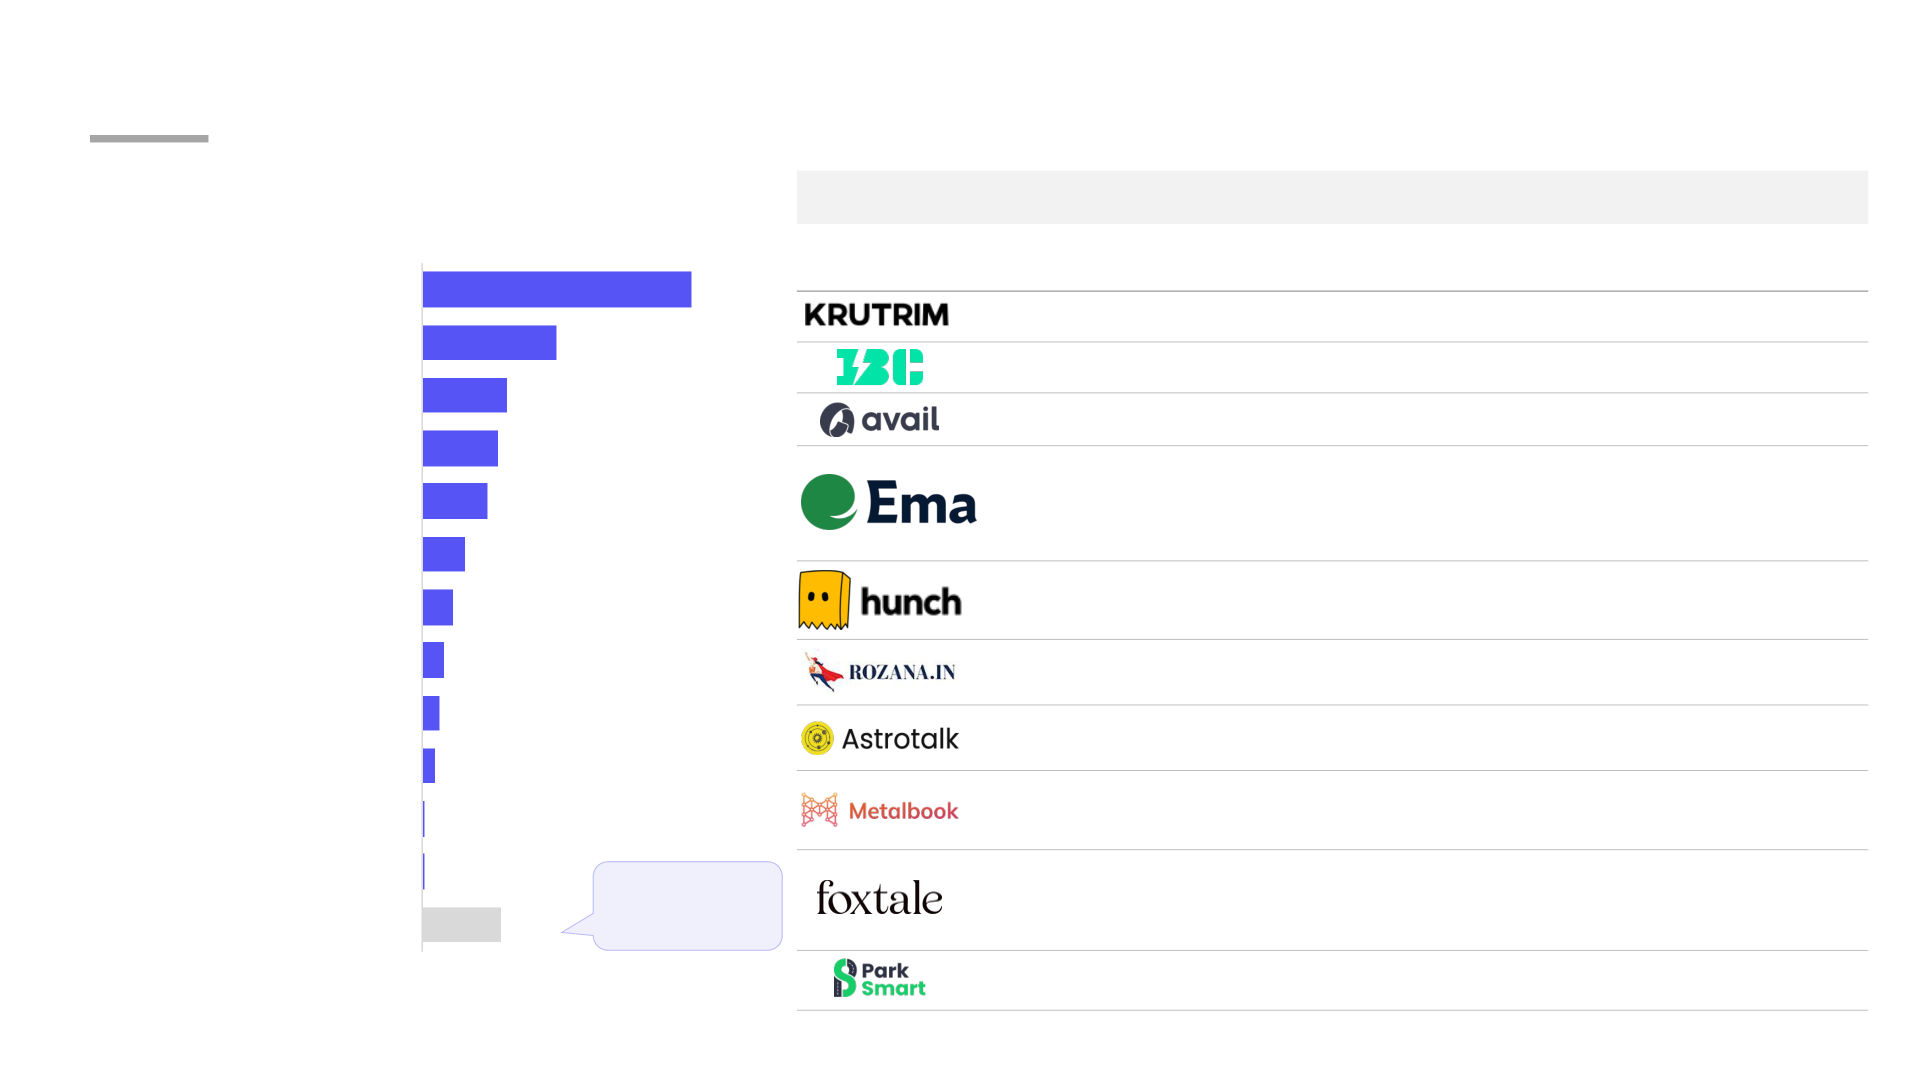
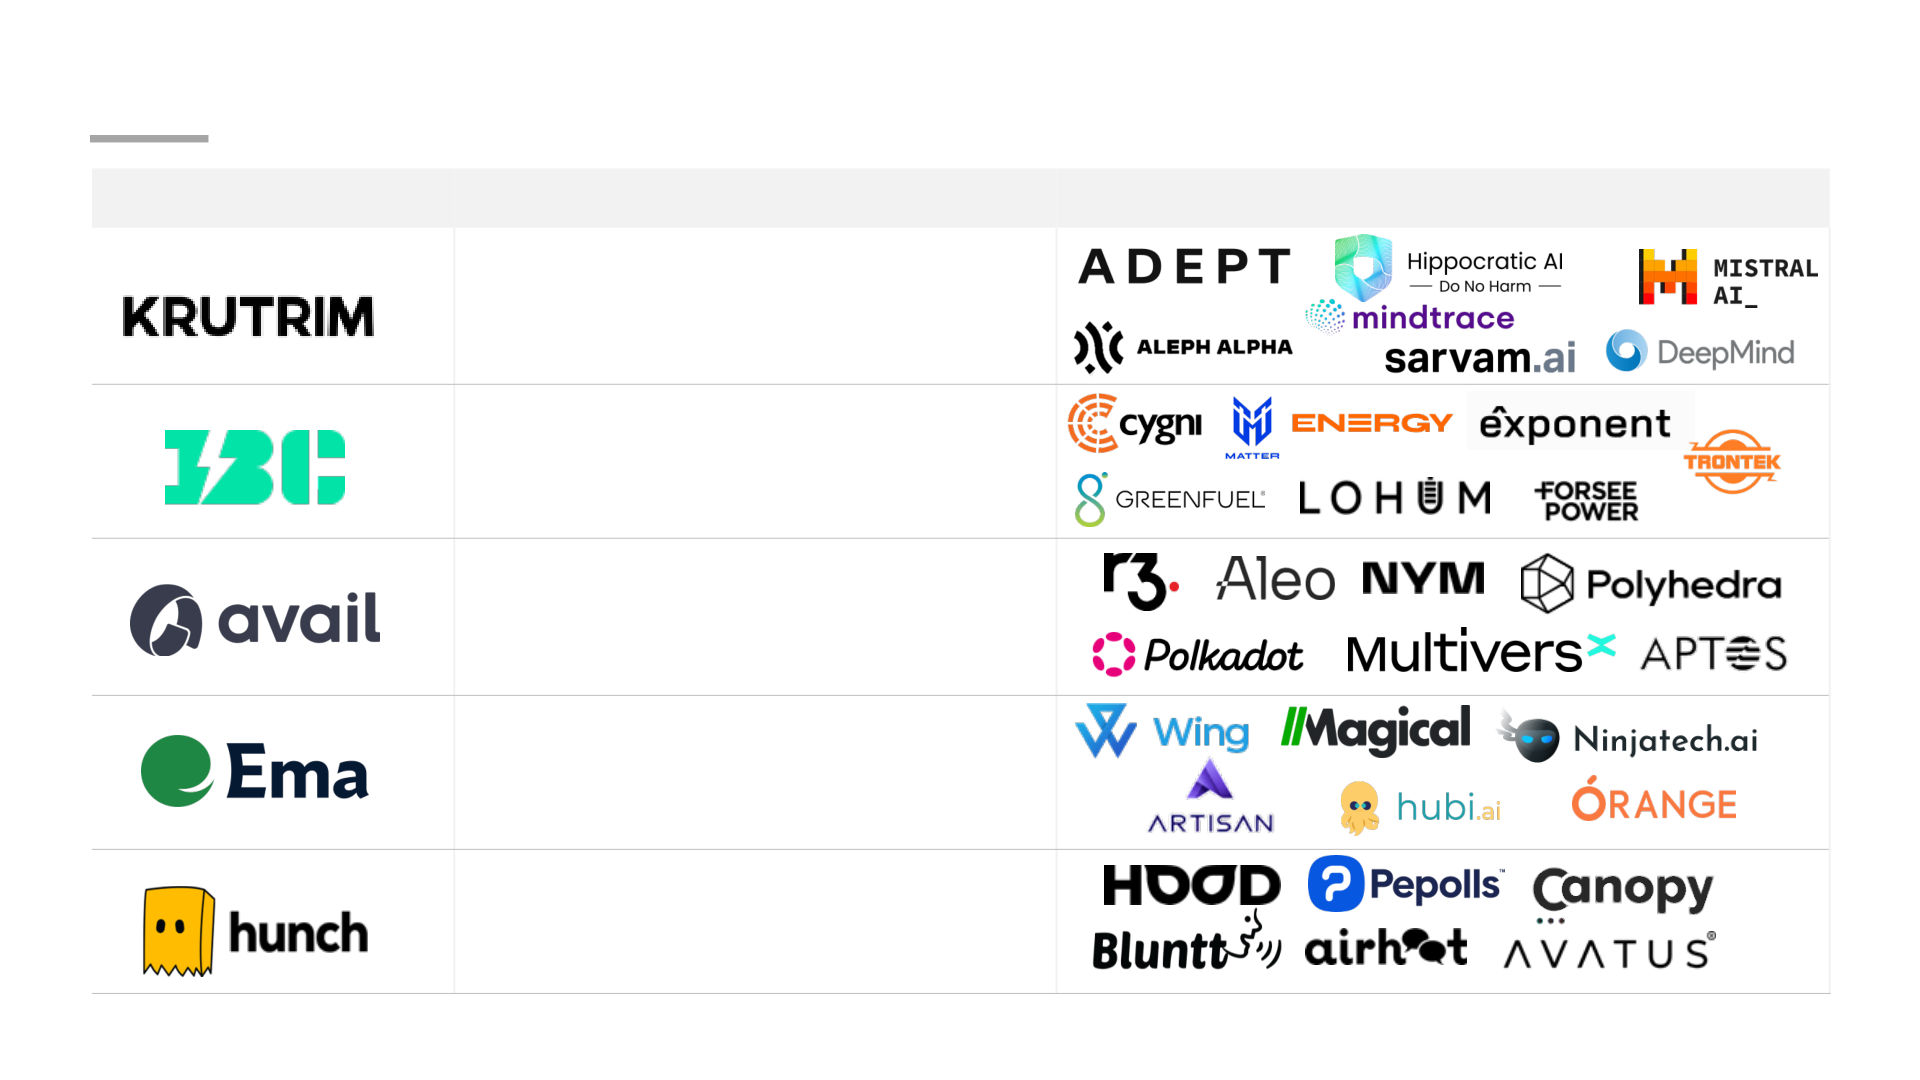
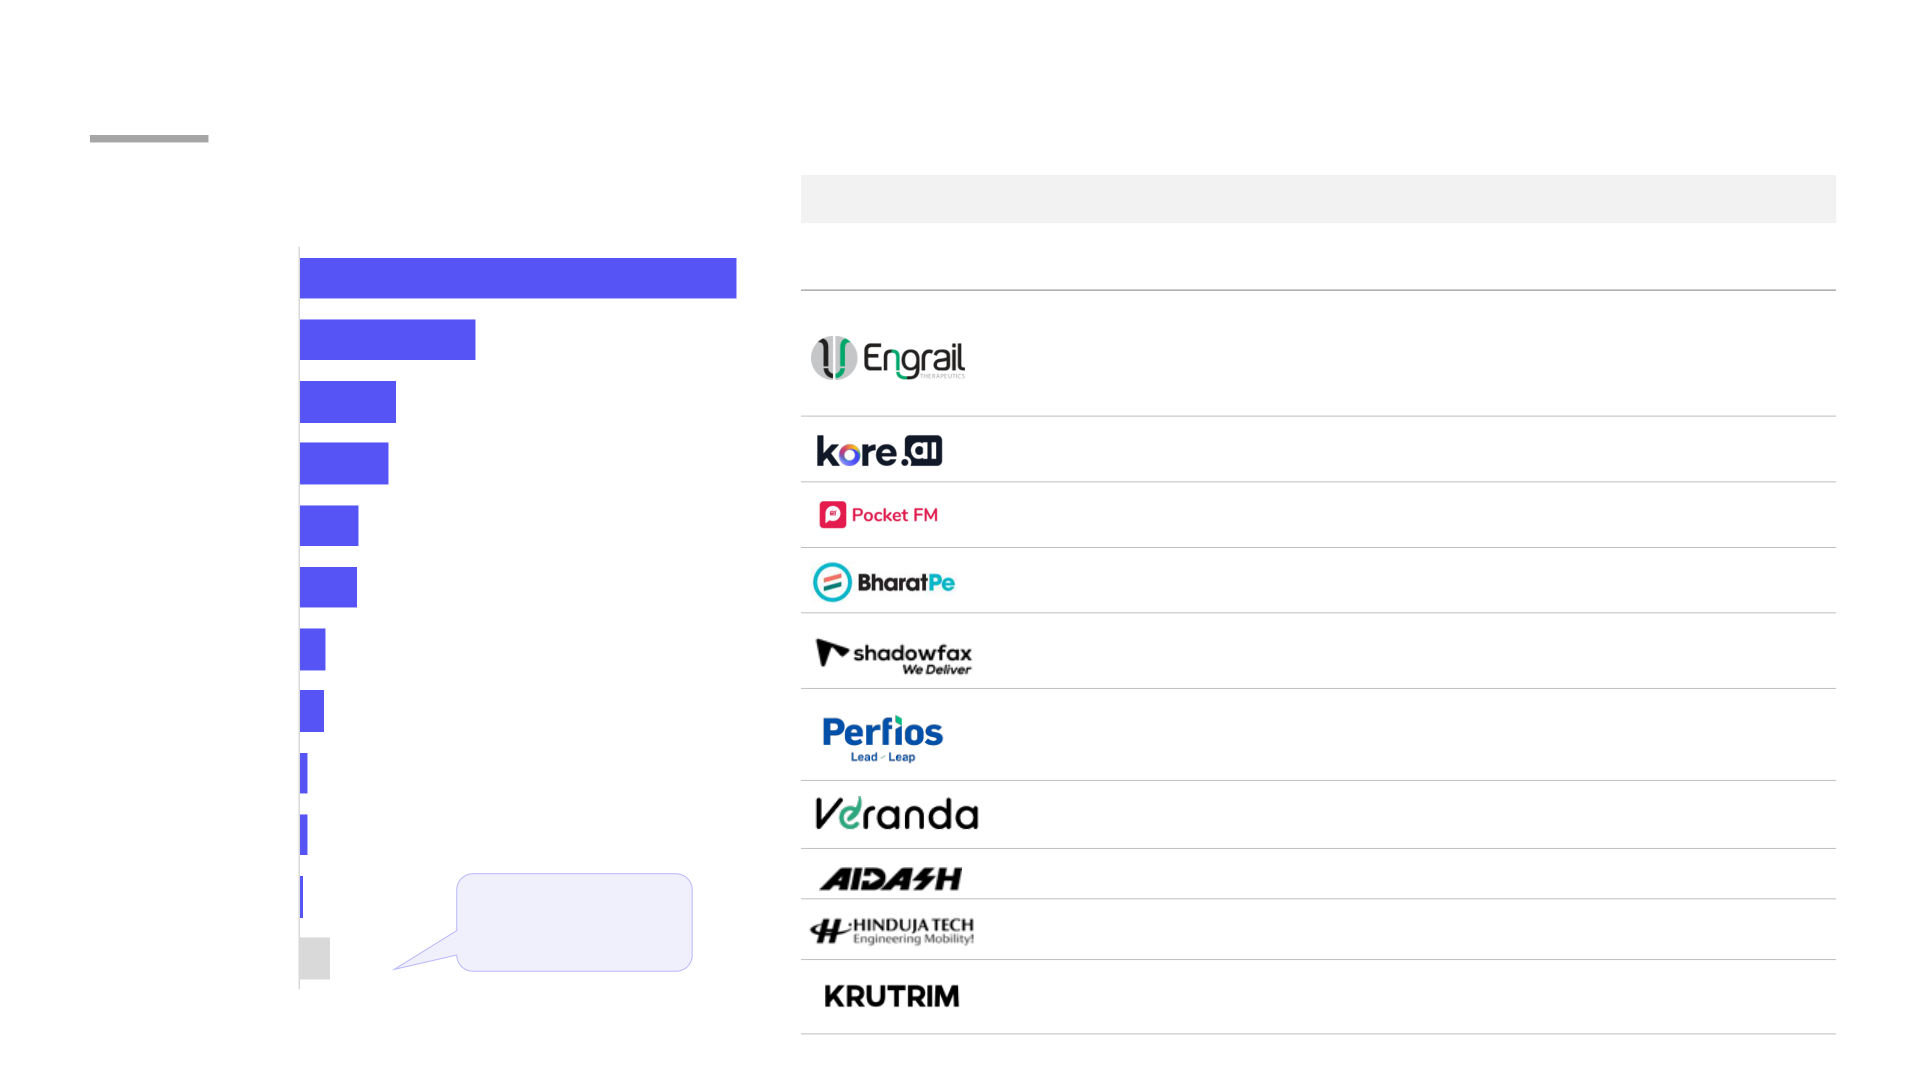
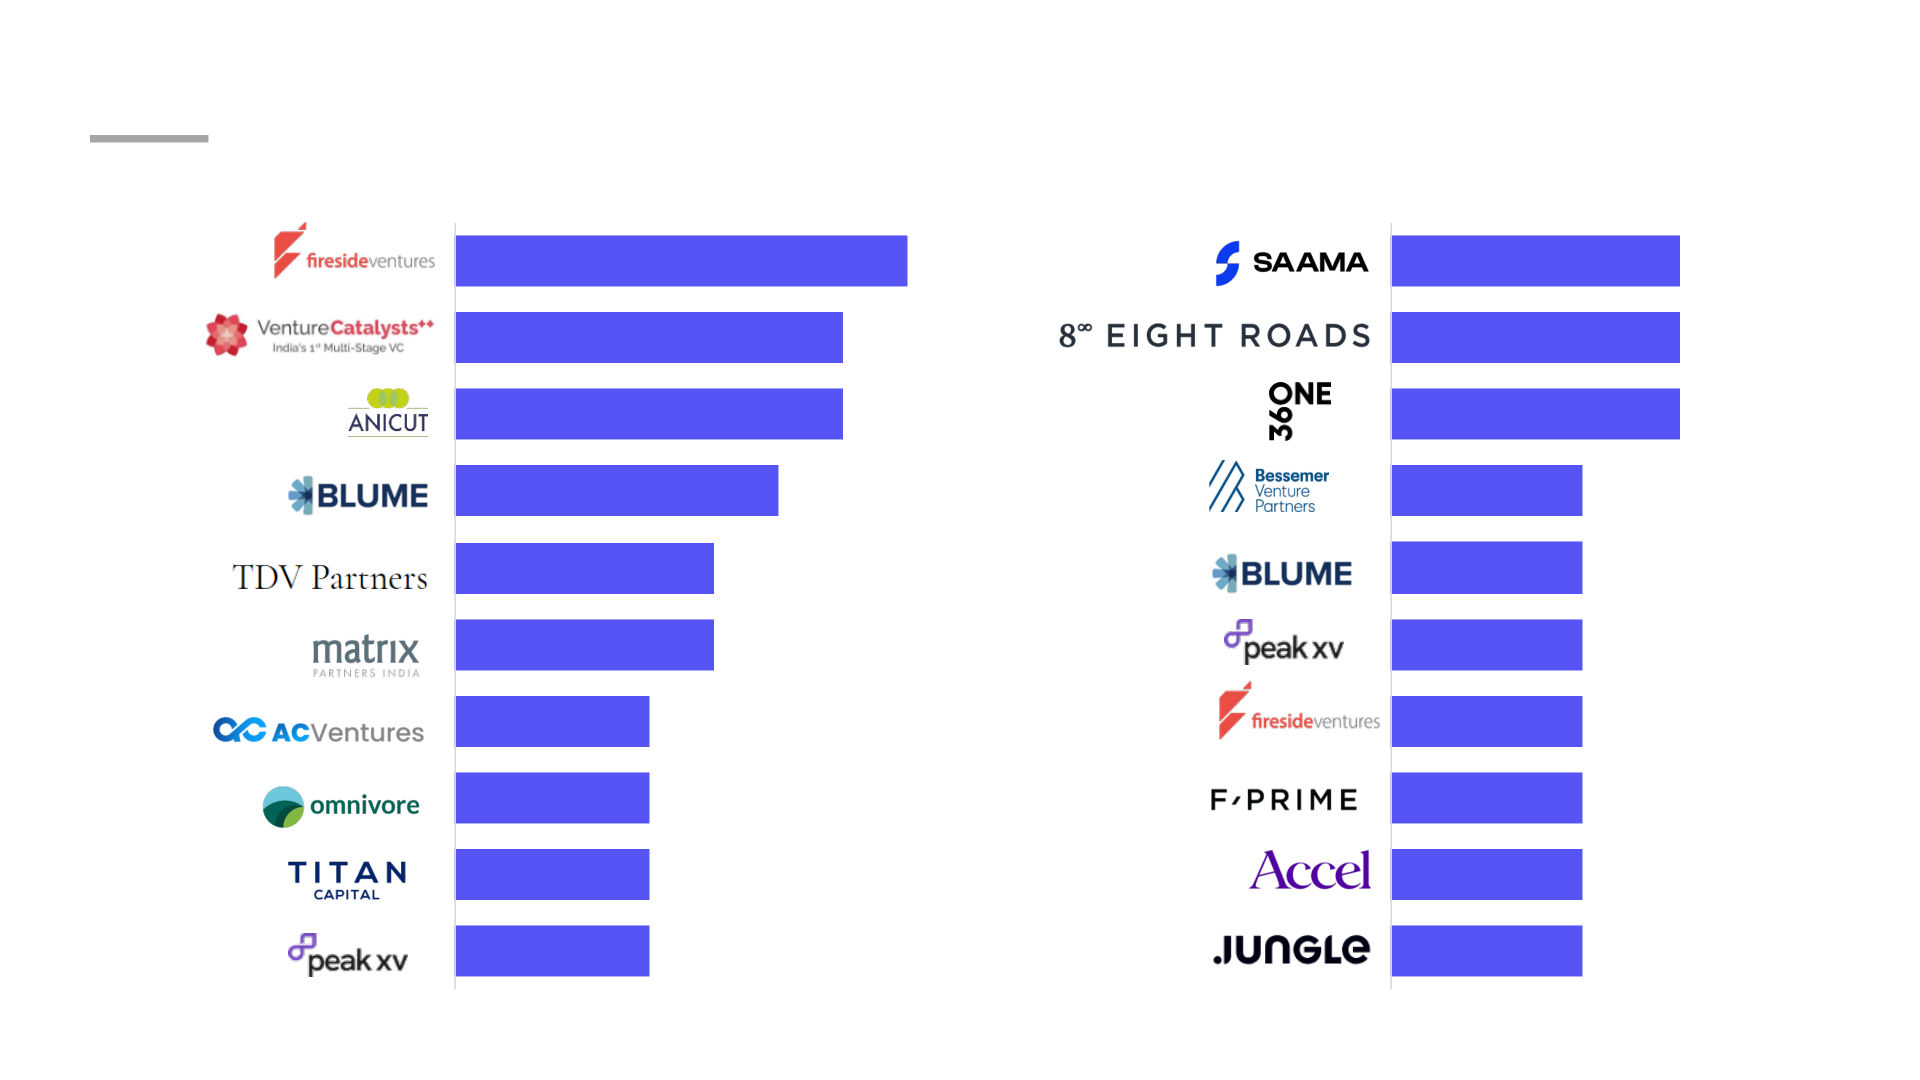
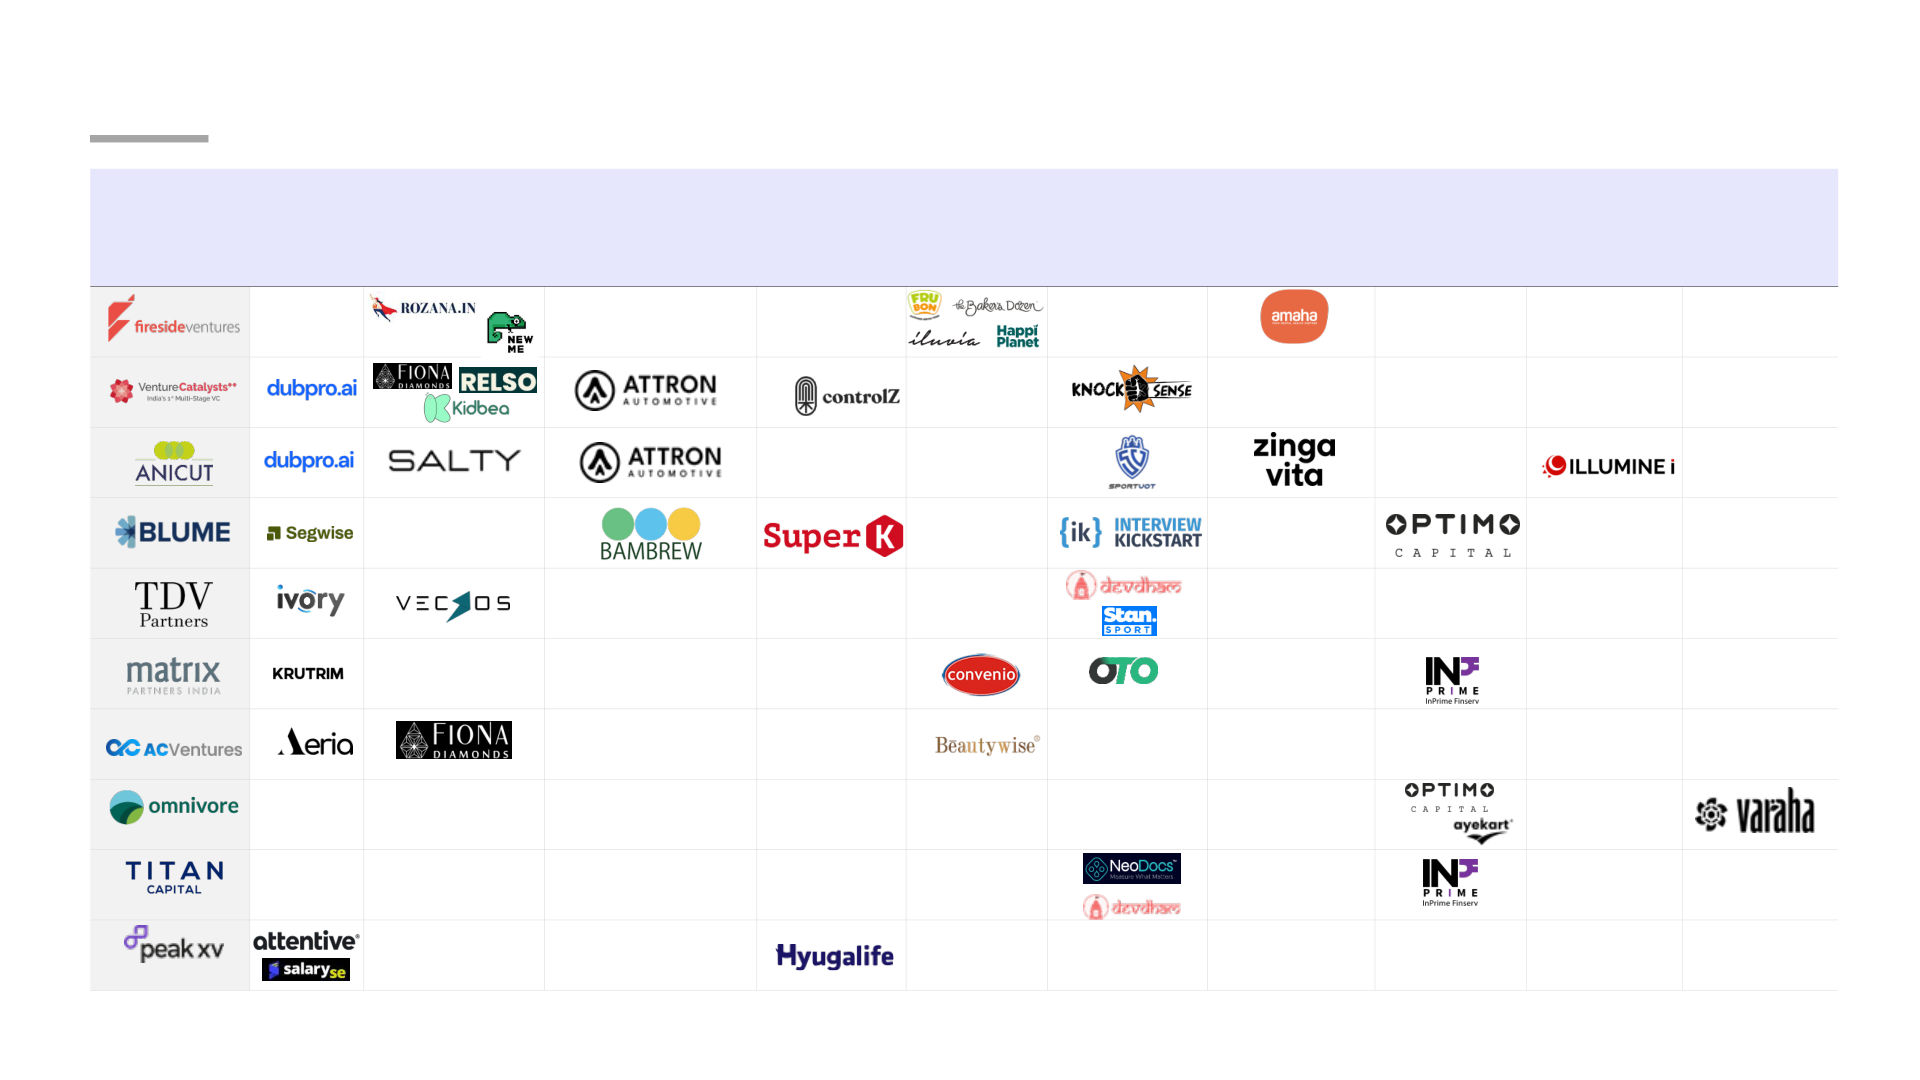
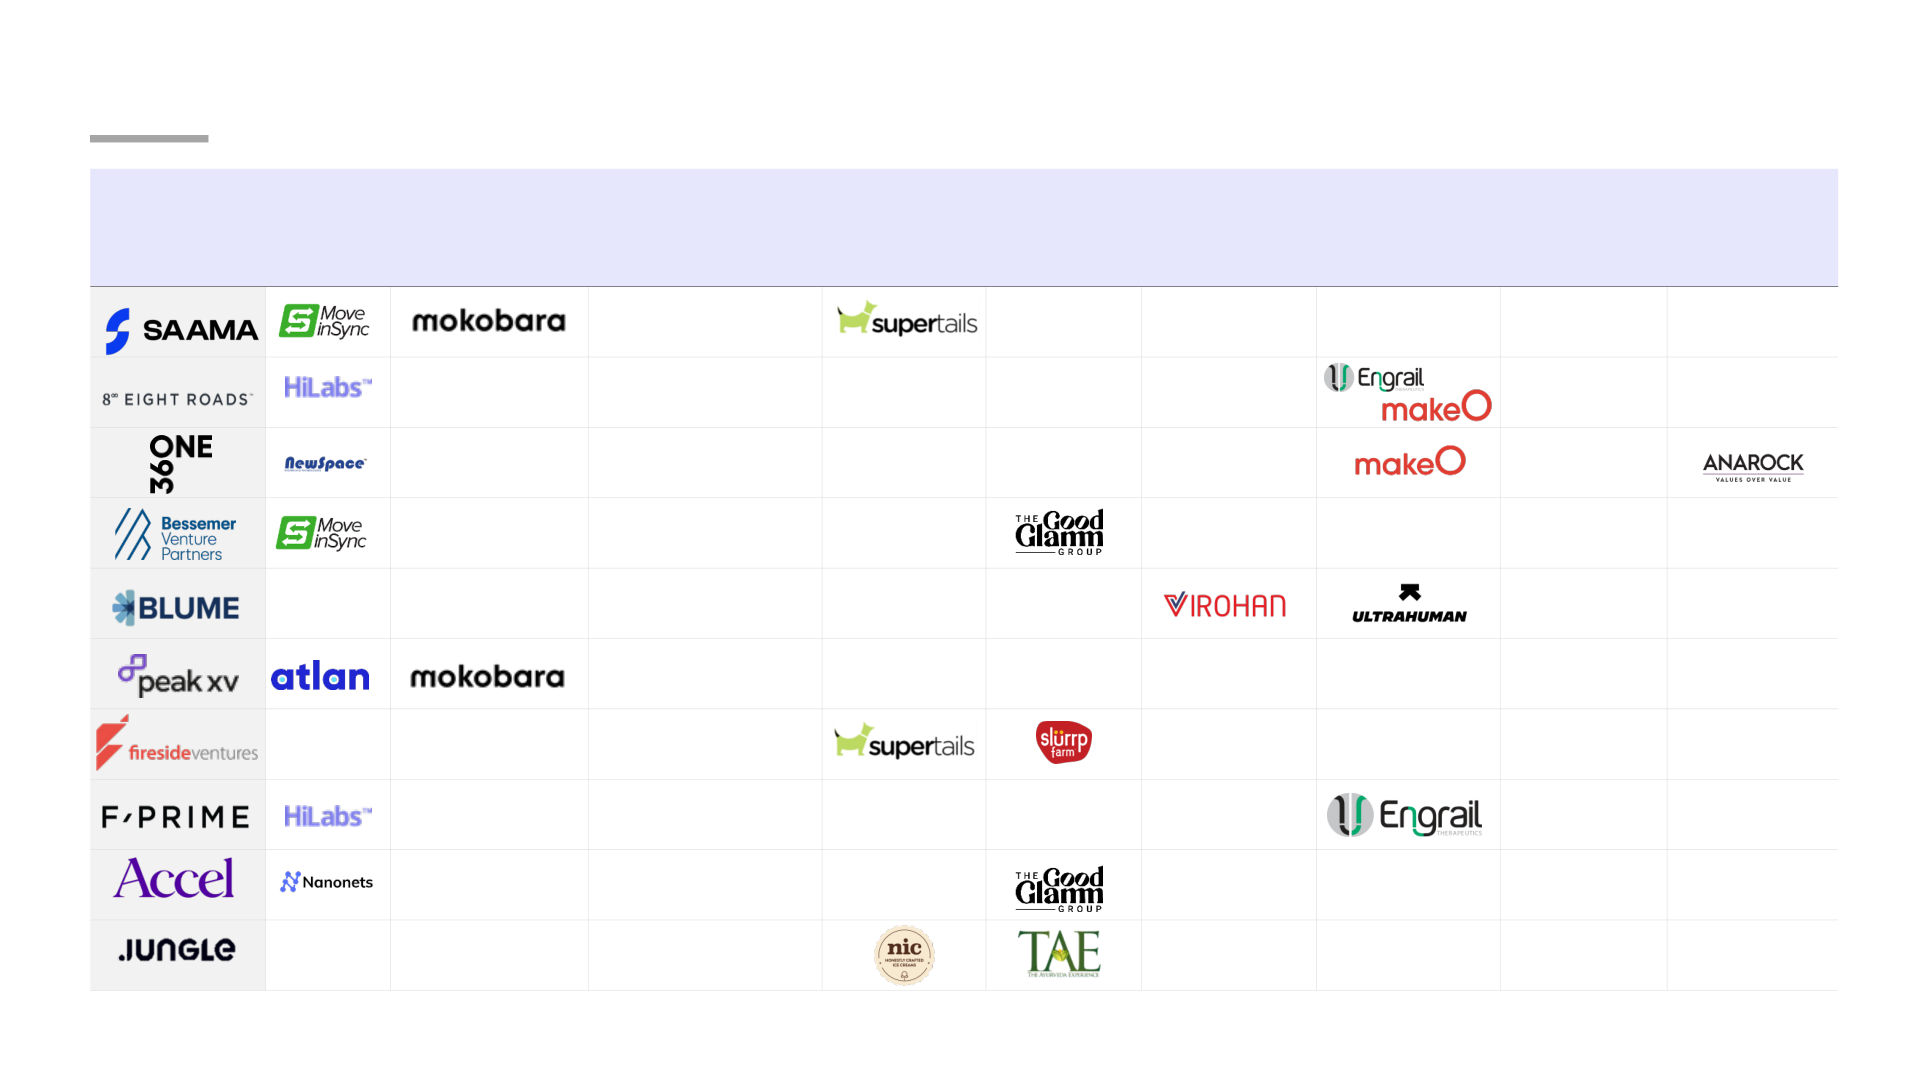
Q1 CY24 April, 2024 500+ 30% Technology - backed business annual engagements faster to outcomes support that helps you 600+ 8 ENABLE BETTER years domain practices expertise DECISIONS 130+ 98% + Deep on - ground insights that you can act on team members accuracy 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 100+ 2.5M towns & cities panel members One - ness of data and people networks to harness the collective power of data, network, and technology Multi - faceted teams offering a stack of consulting, 15+ 40:60 advisory, and research services languages covered she/he ratio At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (1/2) Intelligence Input Validate Execute Measure & Insights • Market assessment, TAM, SAM • PMF test / feasibility studies • Time motion studies • SOP / process audits • GTM planning • B - plan validation • Brand health track studies • M&A landscape scan • Competitive landscape & scan • B2C Qualitative research • Segmentation and personas • Campaign evaluation • Tracking panels • Customer retention and loyalty • NPS studies • B2C Quantitative research • Customer journey mapping analyses • UI / UX testing • B2B Qualitative research • Account potential • Customer retention analysis • NPS health check • B2B Quantitative research assessment • Sales force productivity • Customer segment GTM • Contract benchmarking • Retail store audits • Competitive intelligence (Share • Retail Measurement of wallet analysis) Survey (RMS) • Competitive intelligence • Benchmarking • Mystery shopping • Sentiment analysis • Channel checks • ‘Early insights’ on Listed cos • Brand tracks • MM demand supply assessment • Concept Validation • Go to market Approach • MM competitive • MM planning intelligence • Funding GTM strategy • Program management • Impact tracking • Reputation diligence • Leadership assessment • Founder integrity DD • Employee NPS • IPO program management • IPO / QIP reports • ESG assessment • BRSR reporting • Risk audits and tracking © 1Lattice | 3 At 1Lattice, we address the problem statement and serve as the one - stop platform for all your knowledge and decision support requirements (2/2) Input Validate Execute Measure Networks • Expert interactions • Due diligence • Short - term projects • Expert transcript library • Enterprise surveys • Vendor/target search • Capability assessment • Coaches and mentoring network • Skill matrix benchmarking • Role transition support • Sales & soft skills academy • Functional skills academy • Custom trainings • Engineering/Technical Due • Marketing / creative hub • Compliance Diligence • Sales hub management • Analyst hub • Analysts on demand • Leadership hiring • Reference checks • Outplacement Support • Mid - Level hiring • Board placement • Internships • Roadshows • Pre - employment testing • Knowledge events / fairs • Fundraising campaigns • Channel appointments (distributors, franchisee, etc.) • M&A target search • AI/ML solutions • Lead generation • Cybersecurity • SaaS reselling of business productivity tools and enterprise solutions © 1Lattice | 4 Foreword Foreword Attracting global investor attention, India boasts a enthusiastic about supporting promising companies substantial consumer base and is recognized as one of that have attained product - market fit. Growth - stage the world's fastest - growing economies, supported by startups that can demonstrate a strong leadership rising discretionary incomes, increasing exports, and a team, a scalable business model, and the potential to rising digital economy. However, due to a global be category leaders will find success in this economic slowdown and cautious investor behavior, environment. fu nding has seen an overall decline of 35% , with US$ Backed by favorable government policies, a robust and 8.7 billion raised compared to US$ 13.4 billion during rising economy, and ongoing infrastructure the same period last year. enhancements, India maintains an optimistic funding Early - stage startups dominated the investment outlook. The relentless drive for technological landscape, accounting for 60% of the total funding advancement and innovation, spearheaded by rounds , with disruptive ideas, particularly in SaaS/AI startups, stands as a key driving force and Consumer Tech sectors. However, investors are This report aims to uncover some of the key trends cautious in this funding environment. Startups require during Q1 2024. At 1Lattice, we hold an optimistic to demonstrate strong unit economics, a clear path to outlook, believing that this report will provide valuable profitability, and a focus on building a loyal user base in insights. We eagerly anticipate the opportunity to order to attract investors attention. engage in an open dialogue with our partners across Despite the rise in volume of growth stage deals from diverse industries, as we exchange notes and delve 15% to 22% compared to the last quarter, the funds deeper into these matters while closely monitoring the raised remain stagnant to US$ 2B. Investors remain evolving situation . Roma Dixit Praneet Singhal Senior Director, Director, Financial Investors Financial Investors © 1Lattice | 5 Key highlights Funding Deal v olume Average ticket size US $ 8.7 B 290 US$ 30M SNAPSHOT Q1 CY 2024 Most funded stage Total equity Top funded sector funding Early Telecom US$ 7.7B Key takeaways Funding landscape & investment dynamics • Startups raised US $ 8 . 7 B across 290 deals in Q 1 CY 24 , signaling a drop in total funding ( 47 % ) on a Q - on - Q basis ; deal volume decreased from 366 to 290 deals ( 20 % ) compared to Q 4 CY 23 • Telecom sector received the highest funding of US $ 2 . 5 B followed by Energy sector receiving a funding of ~US $ 1 . 7 B and BFSI sector receiving funding of US $ 1 . 2 B − Investments across late stage experienced a decrease in value by ~ 25 % on a Q - on - Q basis • Early - stag e deal volume increased from ~ 45 % to ~ 60 % and growth - stage deal volume increased from 15 % to ~ 20 % ; indicating a higher risk appetite among investors, as the Investors embrace uncertainty in innovative or expanding companies for potentially high returns • Avg deal size decreased by ~ 35 % to US $ 30 . 1 M as compared to the previous quarter Sectoral focus & key deals • The highest investments in Q 1 CY 24 were for American Tower Corporation (Telecom) and SAEL (Energy) with funding of US $ 2 . 5 B and US $ 1 B respectively • For the current quarter, SaaS / AI was the most attractive sector for early - stage (~US $ 240 M) and growth - stage investments (~US $ 605 M) • Late - stage investments were driven by the energy sector (US $ 1 B) and BFSI sector ~US $ 640 M • Fireside Ventures ( 7 deals) & Saama ( 3 deals) were the most prominent investors for early - stage & growth - stage investments respectively in Q 1 CY 24 Funding market breakup – by round Buyout (~US$ 3B) and PE round (~US$ 1.5B) funding were the highest contributors to overall funding raised in Q1 CY24 Funding market breakup – by round (US$ B, Q1 CY24) Total funding size: US$ 8.7B 0.6 0.8 1.3 Series B Series D 2.9 PE round Buyout 0.2 0.2 round 0.3 0.6 1.0 0.2 Debt 0.2 0.3 round 0.1 Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 8 Funding market breakup – by sectors Telecom sector (US$ 2.5B) saw the most interest from investors, followed by energy (US$ 1.65B) in Q1 CY24 Funding market breakup – by sectors (US$ B, Q1 CY24) Total funding size: US$ 8.7B 0.4 1.2 0.4 1.7 2.5 0.3 0.3 0.3 Energy Telecom 0.9 0.2 0.2 0.2 0.01 0.1 IT Note(s): *Others include Cloud Kitchen, Hospitality, Real Estate, QSR, etc. Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 9 Funding market breakup – by sectors Saas /AI sector saw the highest deal volume from investors (~75 deals), followed by consumer app & platforms (~40 deals) in Q1 CY24 Funding market breakup – by sectors (Q1 CY24) Total deals : 290 18 19 28 42 74 7 18 7 34 20 15 2 5 1 SaaS / AI Telecom Note(s): *Others include Cloud Kitchen, Hospitality, Real Estate, QSR, etc. Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 10 Top 10 highest funded companies American Tower Corporation received the highest deal size (US$2.5B), followed by SAEL in CY 2024 2 ,500 1,000 Top 10 highest funded companies of Q1 425 CY 2024 (US$ M) 23 0 1 32 181 145 160 150 157 Source(s): 1Lattice Deals Database © 1Lattice | 11 - Equity deals - Buyout deals - Debt deals Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Investment amount and # deals Investments in Q1 CY24 saw a significant drop continuing the gradual drop since Q3 CY23 Investment amount (US$ B) and # deals (Q1 CY23 – Q1 CY24) 419 366 340 290 301 21.9 19.7 16.5 13.4 8.7 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Amount Deals Note(s): The figures for the previous quarters have been revised since our last report as undisclosed / missing deals have been added Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, PIPE, Buyout and debt (Conventional, Venture, etc.) Source(s): 1Lattice Deals Database © 1Lattice | 13 Equity vs debt investments US$ 7.7B was raised through equity investments, while US$ 1B through debt deals in Q1 CY24 Debt investments (US$ B) and # deals Equity investments (US$ B) and # deals (Q1 CY23 – Q1 CY24) (Q1 CY23 – Q1 CY24) 150 297 112 271 264 261 7.9 251 6.3 38 43 13.5 17.9 11.4 29 7.9 7.7 4.1 1.9 1.0 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Amount Deals Amount Deals Note(s): The figures for the previous quarters have been revised since our last report as undisclosed / missing deals have be en added Equity includes early (Pre - seed, seed, pre - series and Series A), growth stage (Series B, C, D and E), late (Series F onwards) st age investments, others (PIPE and buyout) and debt includes conventional debt, venture debt, etc. Source(s): 1Lattice Deals Database © 1Lattice | 14 Stage - wise investments Debt deals witnessed a drop from ~US$8B to US$1B compared to the previous quarter, Late - stage deals amounted to ~US$ 1.8B Investment amount (US$ B) (Q1 CY23 – Q1 CY24) N* = 340 301 419 366 290 3.4 7.2 5.0 8 3.2 7.9 1.0 1.8 3.9 6.3 0.9 1.8 6.6 2.2 4.5 2.4 2.0 3.2 2.0 2.6 0.7 1 0.7 0.8 0.7 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Early Growth Late Debt Others (PIPE & Buyout) Note(s): TThe figures for the previous quarters have been revised since our last report as undisclosed / missing deals have been added Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage inv estments, others (PIPE and buyout) and debt (Conventional, Venture, etc.); *Number of deals Source(s): 1Lattice Deals Database © 1Lattice | 15 Average deal size Average deal size decreased to US$ ~30M from ~US$45M whereas total deals came down to 290 deals as compared to ~365 deals in Q4 CY23 Deal volume by stage Average deal size (%, Q1 CY23 – Q1 CY24 ) (US$ M, Q1 CY23 – Q1 CY24 ) 340 301 419 366 290 72.9 4% 6% 6% 7% 9% 10% 13% 12% 5% 1% 30% 5% 36% 18% 22% 46.9 45.3 16% 4% 39.2 2% 15% 12% 30.1 61% 58% 59% 44% 43% Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q1 CY24 Early Growth Late Debt Others* Note(s): The figures for the previous quarters have been revised since our last report as undisclosed / missing deals have been added Stage of investment here is decided by the round of investment. Pre - seed, seed, pre - series and Series A are classified as Early, Series B, C, D and E are classified as Growth, Series F onwards are classified as Late, Debt includes deals with Conventional, Venture, etc. Other s i nclude deals with undisclosed round, PIPE, Buyout etc. © 1Lattice | 16 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Top 10 investments in Q1 CY24 Top 10 investments in Q1 CY24 Top 10 investments in Q1 CY24 Amount Company Sector Funding stage Key Investors (US$ M) Telecom 2,500 Buyout Brookfield Asset Management Tata Cleantech capital, Asian Development Bank, Energy 1,000 Late Norfund Energy 425 Debt Rabobank, MUFG Bank, Societe Generale BFSI 230 Late Advent International, Multiples Engg. & Construction 181 Buyout Actis Motilal Oswal, Norwest Venture Partners, TPG Growth, BFSI 160 Late Baring Private Equity India, Duro Capital, Axis Alternatives, Ananta Capital, Mirae Asset Venture Investments (India) F - Prime Capital, Forbion, Norwest Venture Partners, RiverVest Venture Partners, Red Tree Venture Capital, Healthcare & Life Sciences 157 Growth Ysios Capital, Longwood Fund, Eight Roads Ventures, Pivotal Life Sciences FTV Capital, Vistara Growth, Sweetwater PE, NextEquity, SaaS/AI 150 Growth Nicola, Beedie BFSI 144 Growth Mizuho Financial Group Mubadala Investment Co, Kotak Pre - IPO Opportunities BFSI 132 Late Fund, Avendus Future Leaders Fund © 1Lattice | 18 Note(s): *Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice Deals Database Early - stage investments SaaS / AI received the highest funding of ~US$ 240M among early - stage investments; Krutrim received the highest funding within the sector Early - stage investments by sector Top 10 early - stage investments in Q1 CY24 (US$ M, Q1 CY24) Amount Company Sector Key Investors (US$ M) SaaS/AI 239 SaaS/AI 50 Matrix Partners India Consumer app & platforms 120 Manufacturing 35 RTP Global , BEENEXT , Veda VC Ecommerce & listing platforms 76 Founders Fund, Dragonfly Capital, SevenX , Others 27 Figment, and Nomad Capital Manufacturing 67 Accel, Prosus Ventures, Wipro Ventures, Venture Highway, AME Cloud Ventures, BFSI 59 SaaS/AI 25 Frontier Ventures, Maum Group, and Firebolt Ventures Healthcare & Life Sciences 38 Consumer app & 23 Alpha Wave Retail 28 platforms Bertelsmann India Investments, and Transportation and logistics E - Commerce & listing 19 22 platforms Fireside Ventures FMCG 15 Consumer app & 20 Left Lane Capital platforms Energy 11 Rigel Capital, FJ Labs, Axilor Ventures, Transportation and Foundamental , Stride Ventures, and 15 Engg. & Construction 3 logistics Trifecta Capital IT services 0.1 Others include E - Commerce & listing blockchain, 14 Panthera Growth Partners hospitality, platforms Others 70 agriculture, QSR etc. SaaS/AI 13 Sin Growth Partners, and Gruhas Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A © 1Lattice | 19 Source(s): 1Lattice Deals Database Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Platform to build Generative AI applications Manufactures large - sized lithium - ion NMC (nickel manganese cobalt) batteries used in electric vehicles Web3 infrastructure layer platform Generative AI startup Platform for asking and getting answers to question anonymously Source(s): 1Lattice Deals Database © 1Lattice | 20 Growth - stage investments SaaS/AI sectors dominated growth - stage investments with funding of ~US$ 605M followed by BFSI sector with ~US$ 250M Top 10 growth - stage investments in Q1 CY24 Growth - stage investments by sector Amount Company Sector Key Investors (US$ M) (US$ M, Q1 CY24) F - Prime Capital, Forbion , Norwest Venture Partners, RiverVest Venture Partners, Red Tree Healthcare & Life SaaS/AI 603 157 Sciences Venture Capital, Ysios Capital, Longwood Fund, Eight Roads Ventures, and Pivotal Life Sciences BFSI 248 FTV Capital, Vistara Growth, Sweetwater PE, SaaS/AI 150 NextEquity , Nicola, and Beedie Healthcare & Life Sciences 235 BFSI 144 Mizuho Financial Group Retail 180 Consumer app & 103 Lightspeed Ventures, and Stepstone Group platforms Consumer app & platforms 154 TPG NEWQUEST, Mirae Asset Venture Transportation and Investments (India), International Finance Ecommerce & listing platforms 129 100 logistics Corporation, Nokia Growth Partners, Qualcomm, and Trifecta Capital Transportation and logistics 111 SaaS/AI 80 Ontario Teachers' Pension Plan FMCG 109 BFSI 74 BP IN VPF Manufacturing 87 Lightrock , SE Ventures, G2 Venture Partners, SaaS/AI 50 Shell Ventures, and National Grid Partners Energy 31 Khazanah Nasional Berhad, Oaks Asset Others include cloud Retail 49 kitchen, real estate, Management Others 95 QSR, etc. SaaS/AI 40 Sageview Capital , Vistara Growth Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice Deals Database © 1Lattice | 21 Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors Developer of therapeutic compounds to treat neurological diseases An enterprise conversational and generative AI platform technology Online marketplace for consumer and business loans Online platform for streaming podcasts and audiobooks Provider of on - demand hyperlocal delivery services for e - commerce businesses Real - time credit - decisioning platform and data aggregation APIs Source(s): 1Lattice Deals Database © 1Lattice | 22 Late - stage investment Late - stage investments were driven by the energy sector (US$ 1B) and BFSI sector ~US$ 640M Late - stage investment, by sector Top late - stage investments in Q1 CY24 (US$ M, Q1 CY24) Amount Company Sector Key Investors (US$ M) Energy 1,000 Energy 1,000 BFSI 641 Engg. & Construction 60 BFSI 230 Consumer app & 35 platforms Ecommerce & listing 20 platforms BFSI 160 IT services 18 FMCG 7 BFSI 132 Note(s): Late - stage investments include Series F onwards Source(s): 1Lattice Deals Database © 1Lattice | 23 Top late - stage investments Top funded late - stage startups with their competitors Company Description Competitors Solar and agriculture waste to energy company Provider of micro loans Provider of loans for pre - owned and used vehicles Avanse provides educational loans globally and supports Indian academic institutions Source(s): 1Lattice Deals Database © 1Lattice | 24 Tech investments SaaS/AI attracted highest investments (~US$ 940M), followed by Consumer app & platforms (~US$ 375M), Ecommerce & listing platforms(~US$ 210M) within tech investments for Q1 CY24 Tech investments by sector Top 10 tech investments in Q1 CY24 (US$ M, Q1 CY24) Amount Sector Key Investors Company (US$ M) SaaS/AI 937 F - Prime Capital, Forbion , Norwest Venture Consumer app & Partners, RiverVest Venture Partners, Red Tree Healthcare & Life 376 platforms 157 Venture Capital, Abrdn Inc., Ysios Capital, Sciences Longwood Fund, Eight Roads Ventures, and Ecommerce & listing Pivotal Life Sciences 208 platforms FTV Capital, Vistara Growth, Sweetwater PE, Healthcare & Life 150 SaaS/AI NextEquity , Nicola, and Beedie 192 Sciences Consumer app & Lightspeed Venture Partners, and Stepstone Transportation and 103 126 platforms Group logistics SaaS/AI 100 InnoVen Capital Energy 125 TPG NEWQUEST, Mirae Asset Global Investments, Transportation FMCG 100 International Finance Corporation, Nokia Growth 56 and logistics Partners, Qualcomm, and Trifecta Capital Engg. & Construction 53 80 Ontario Teachers' Pension Plan SaaS/AI BFSI 18 Consumer app & 51 BPEA Credit platforms IT services 18 Lightrock , SE Ventures, G2 Venture Partners, Shell SaaS/AI 50 Ventures, and National Grid Partners Others includes Manufacturing 6 Gaming, HR Services, Engg. & 50 Creador FoodTech, SpaceTech & Construction more Others 67 SaaS/AI 50 Matrix Partners India Source(s): 1Lattice Deals Database 0 Agenda Deal landscape in Q1 CY24 Key deals and investment themes Key investors Active investors Most active investors of Q1 CY24 Growth - stage investors Early - stage investors (# deals) (# deals) 7 3 6 3 6 3 5 2 4 2 2 4 3 2 3 2 3 2 3 2 Source(s): 1Lattice Deals Database © 1Lattice | 27 4 Active early - stage investors Most active early - stage investors and their investment segments in Q1 CY24 Consumer Healthcare SaaS / E - commerce Investors Manufacturing Retail FMCG App & & Life BFSI Energy Others* AI & Listing Platforms Sciences - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - Note(s) : * Others include ClimateTech Source(s): 1Lattice Deals Database © 1Lattice | 28 Active growth - stage investors Most active growth - stage investors and their investment segments in Q1 CY24 Consumer Healthcare SaaS / Ecommerce Investors Manufacturing Retail FMCG App & & Life BFSI Others* AI & Listing Platforms Sciences - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - Note(s): *Others include real estate Source(s): 1Lattice Deals Database © 1Lattice | 29 +91 962 522 6697 roma.dixit@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore