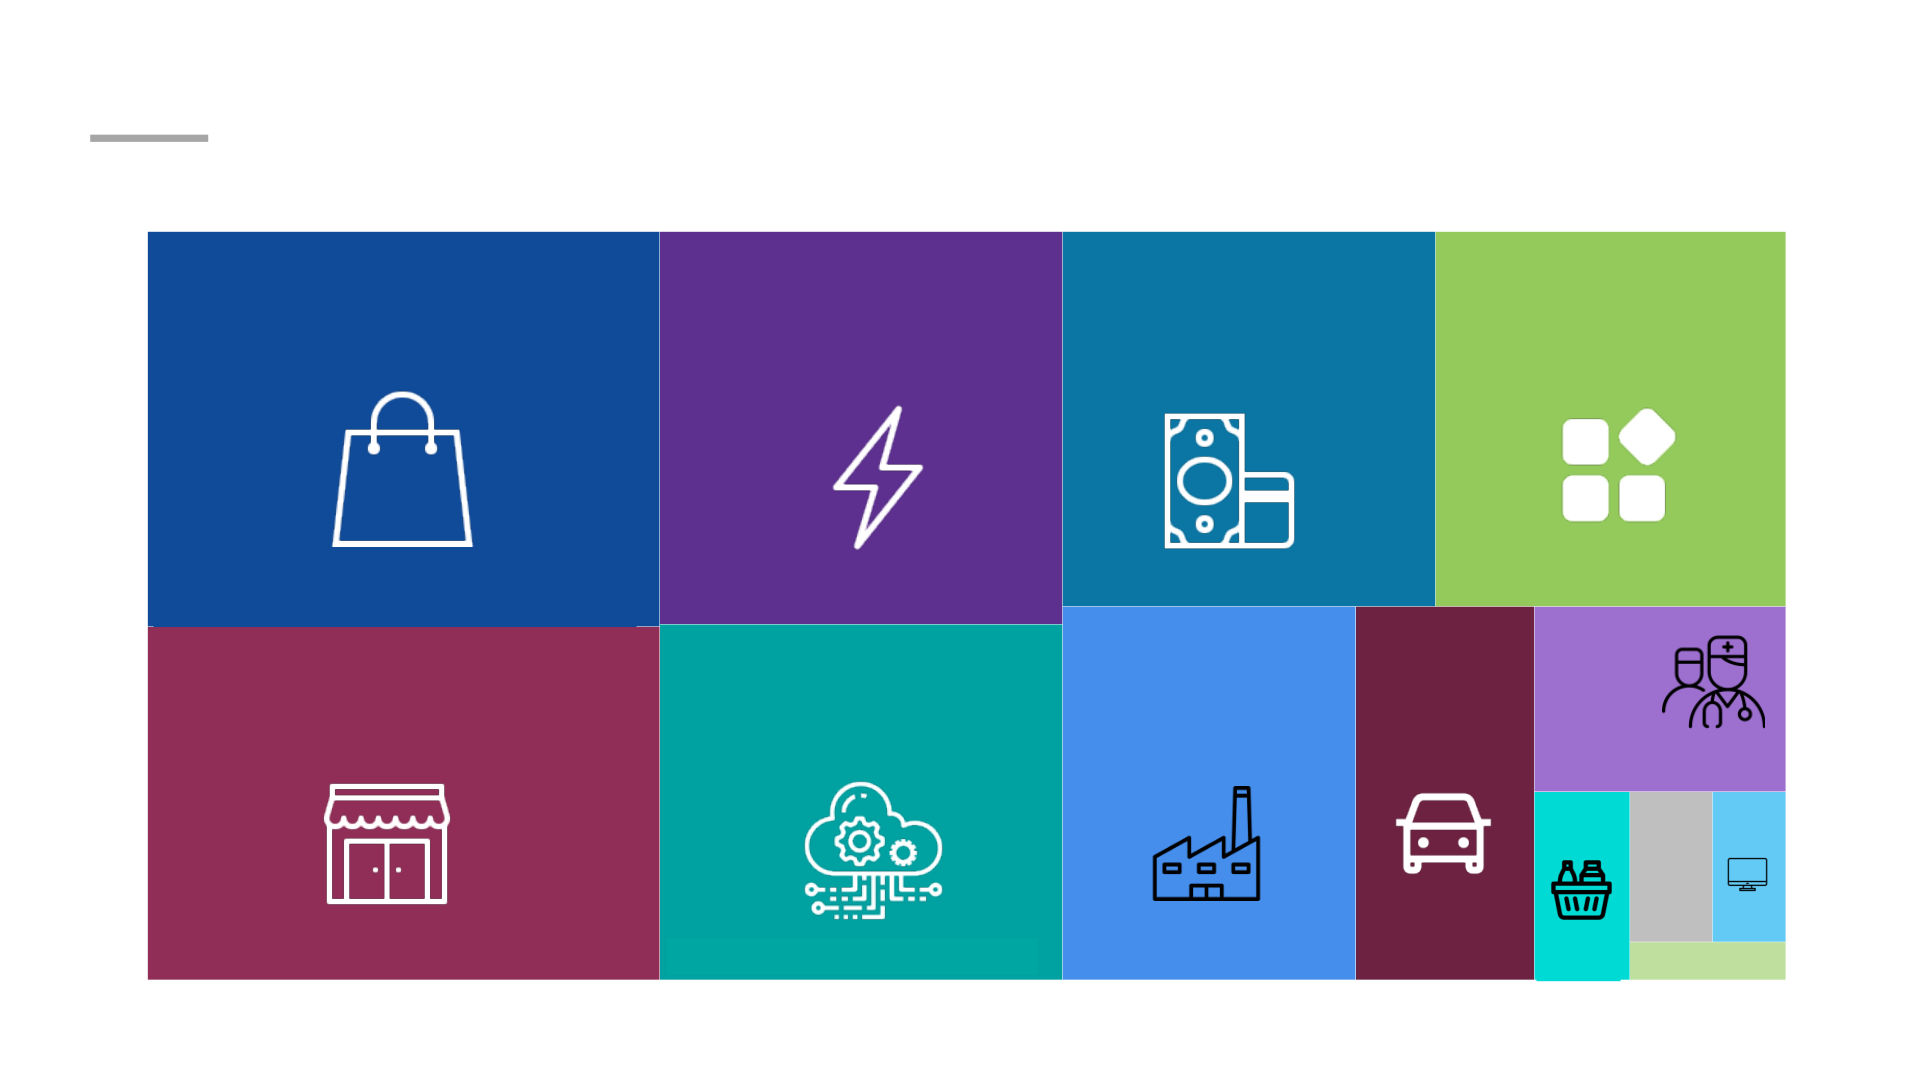
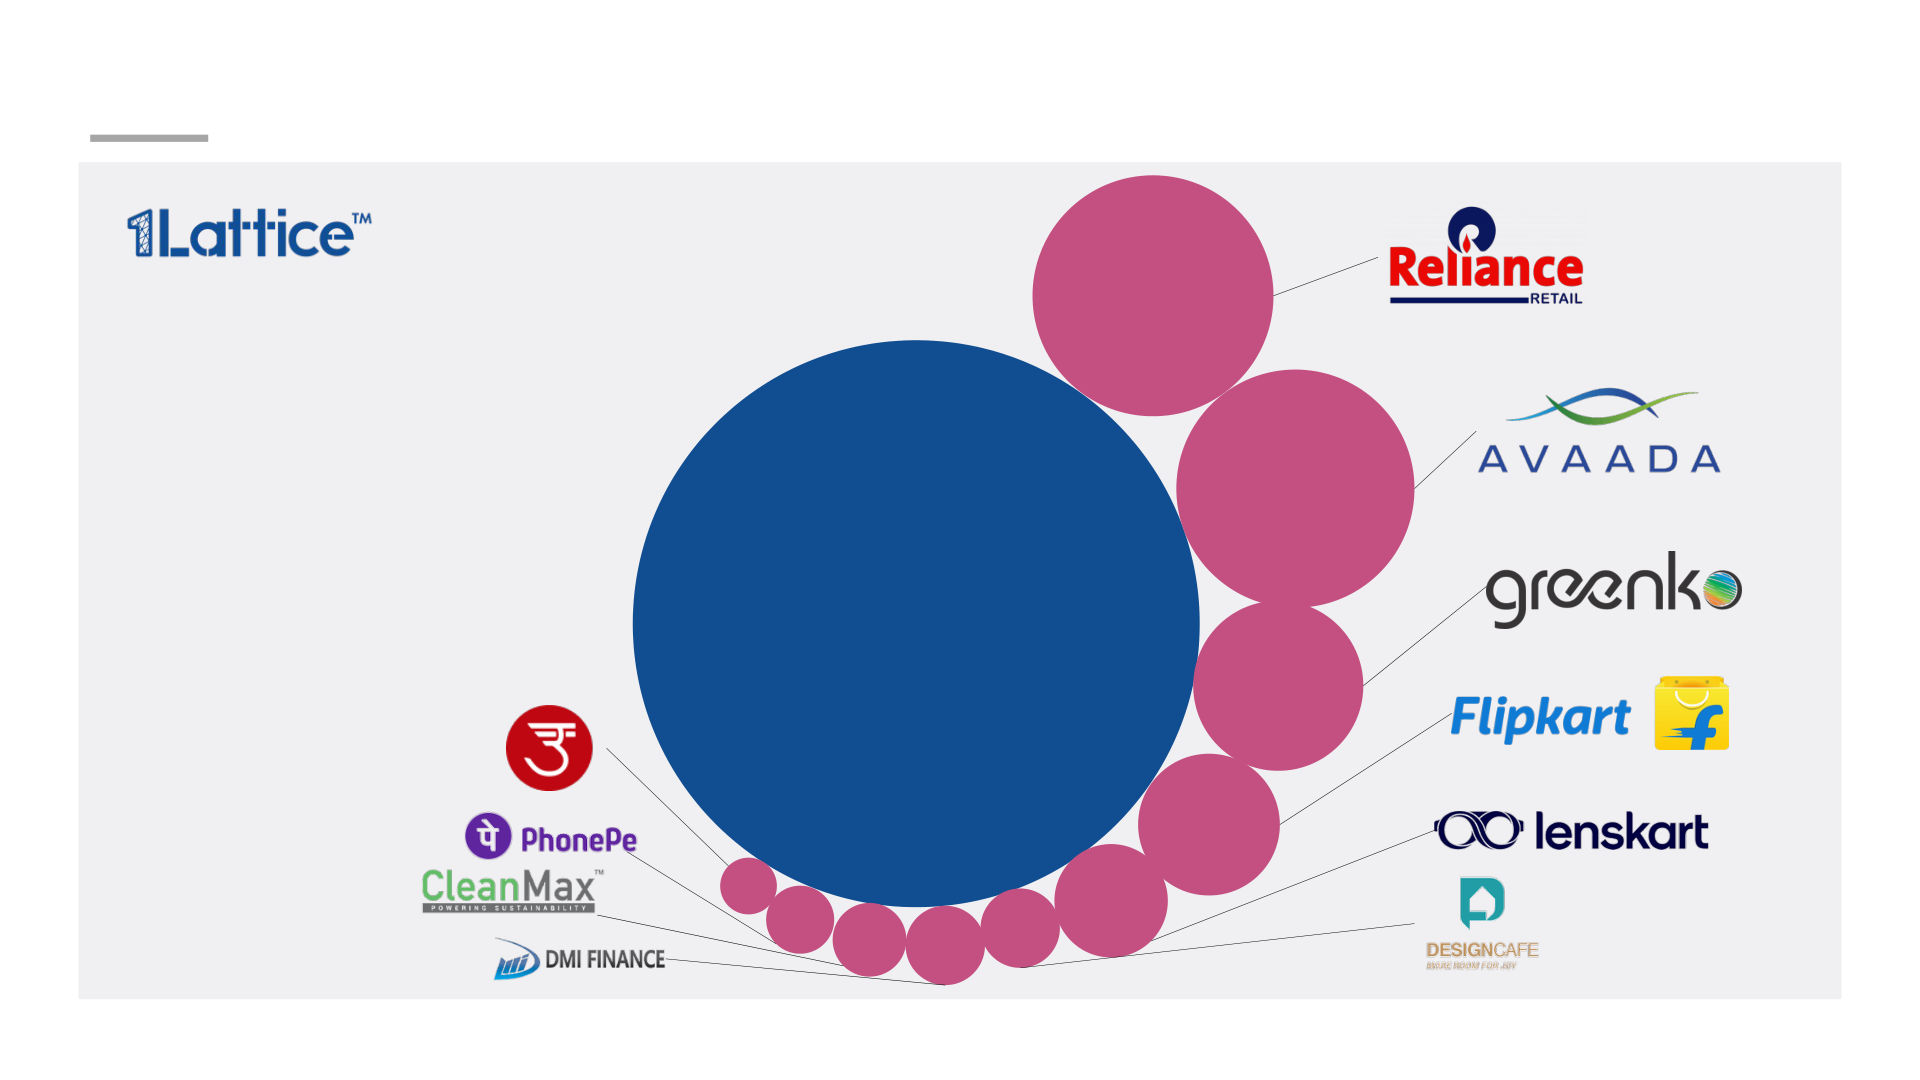
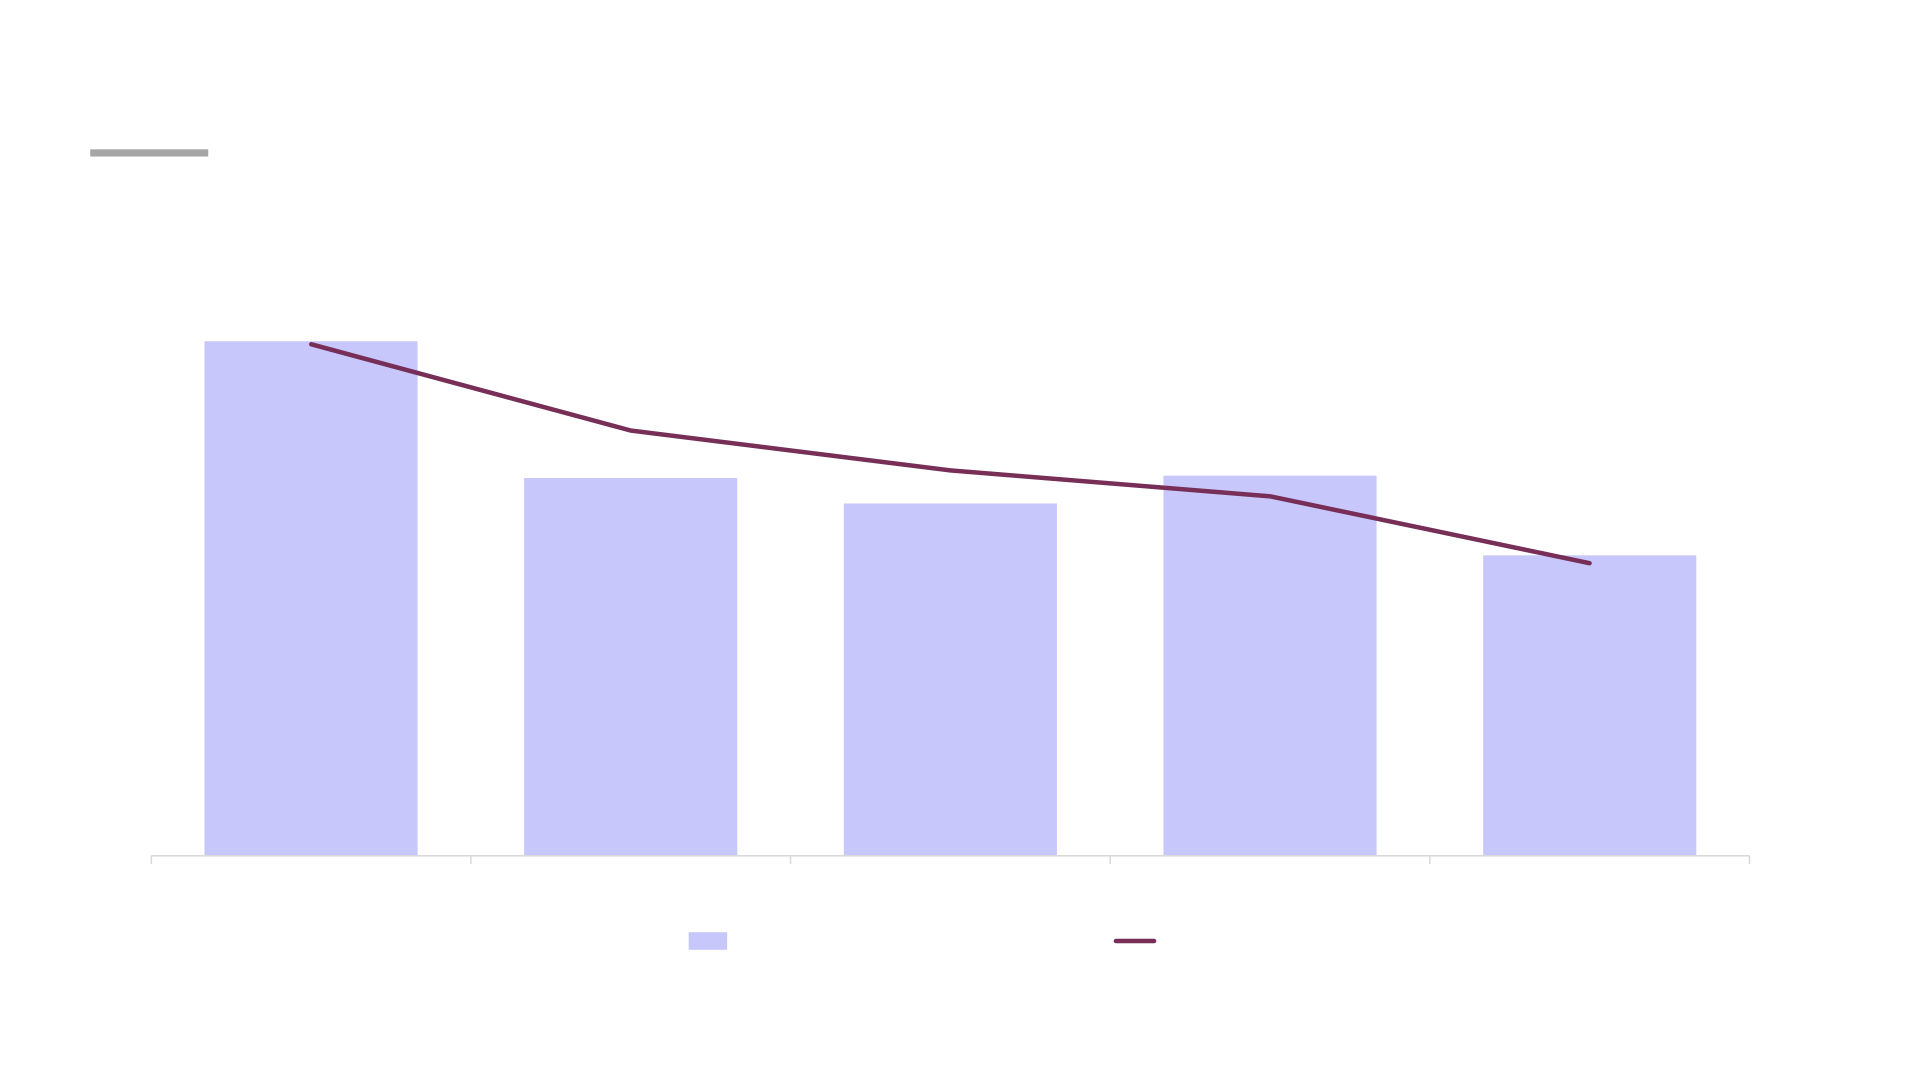
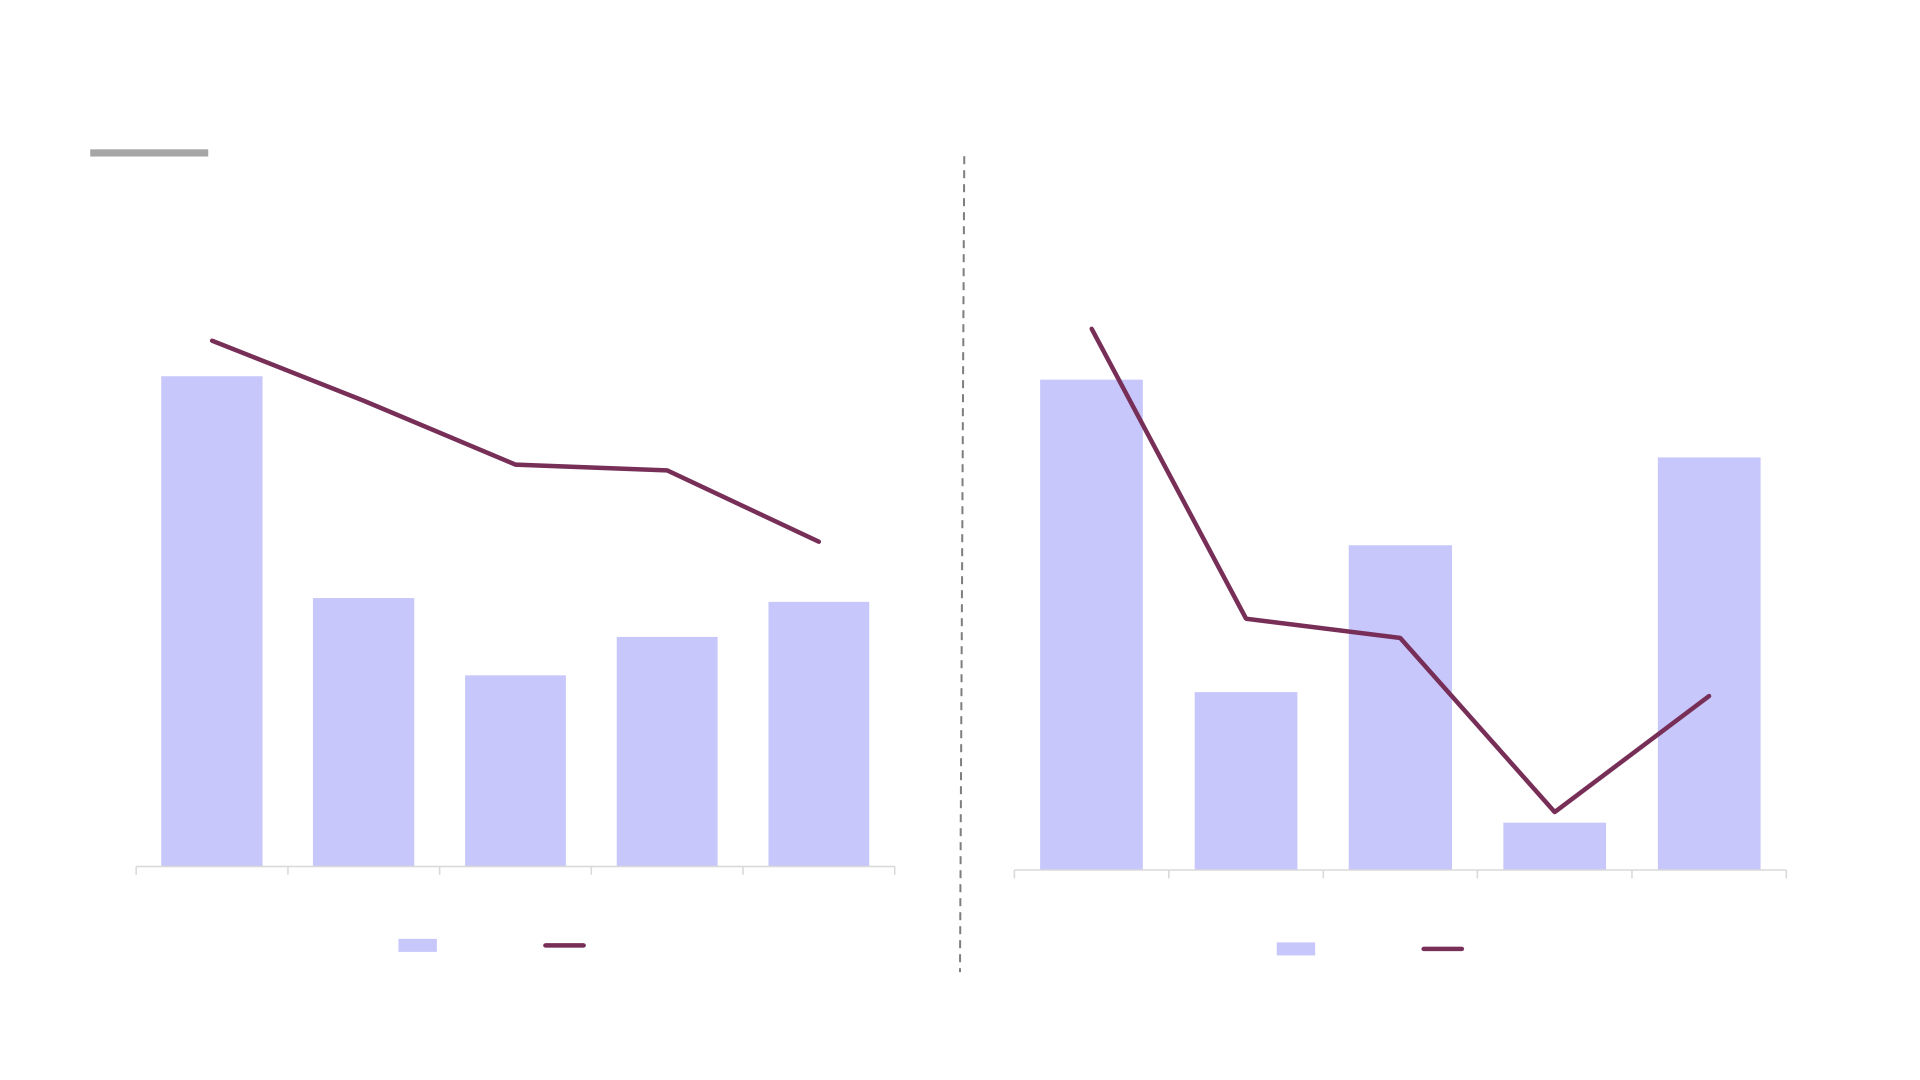
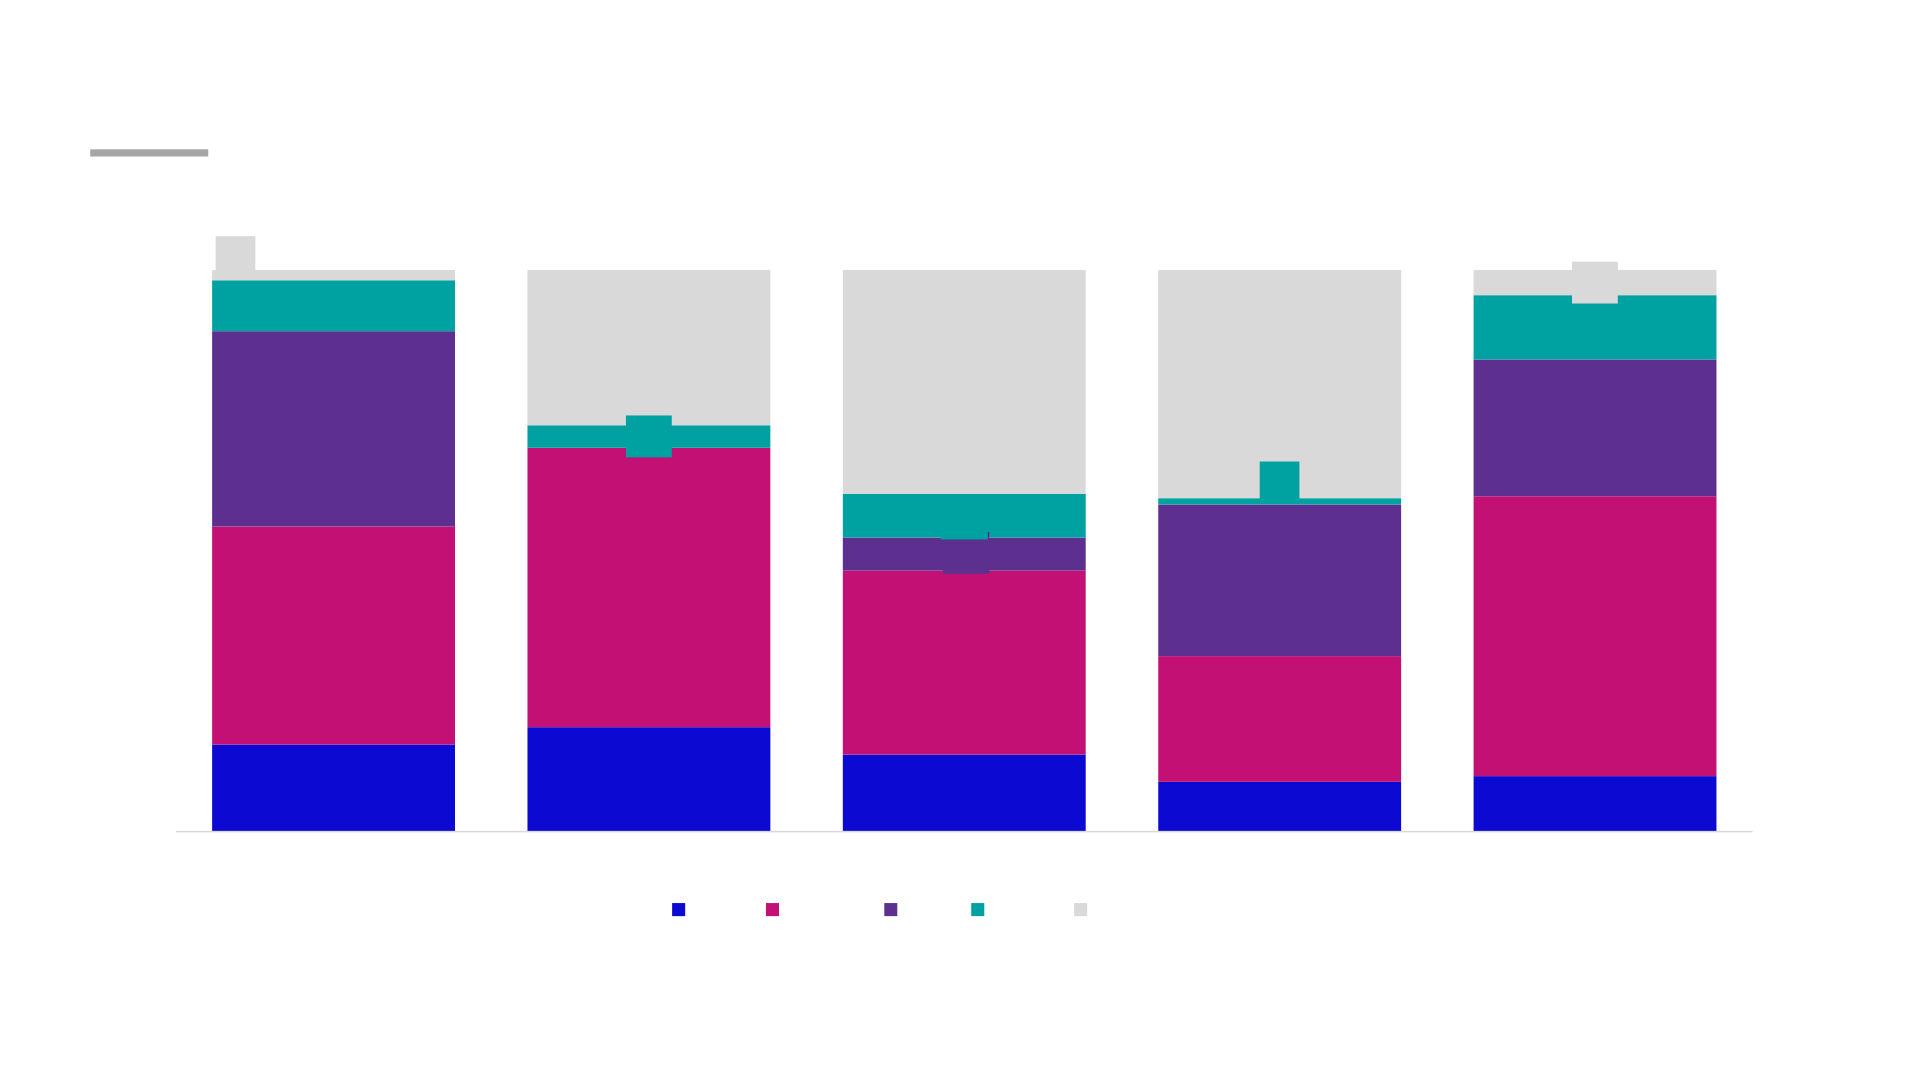
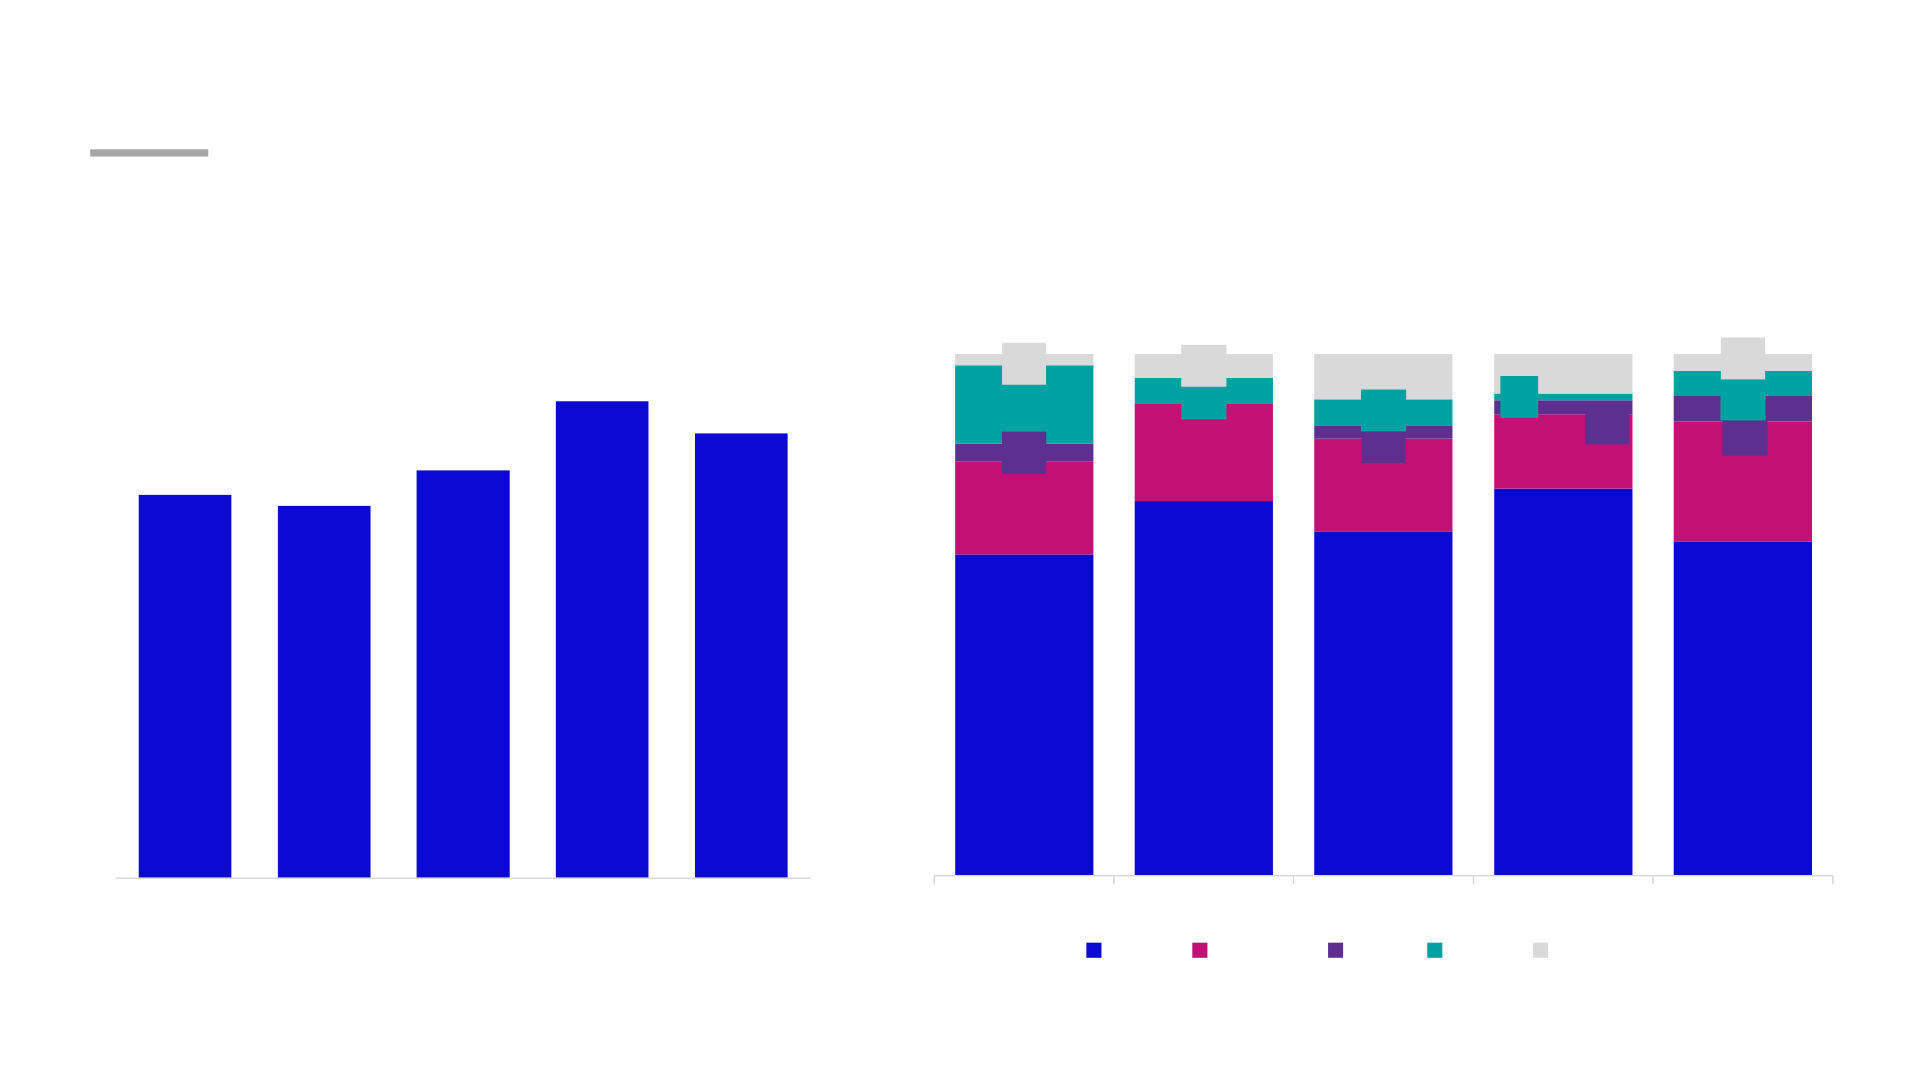
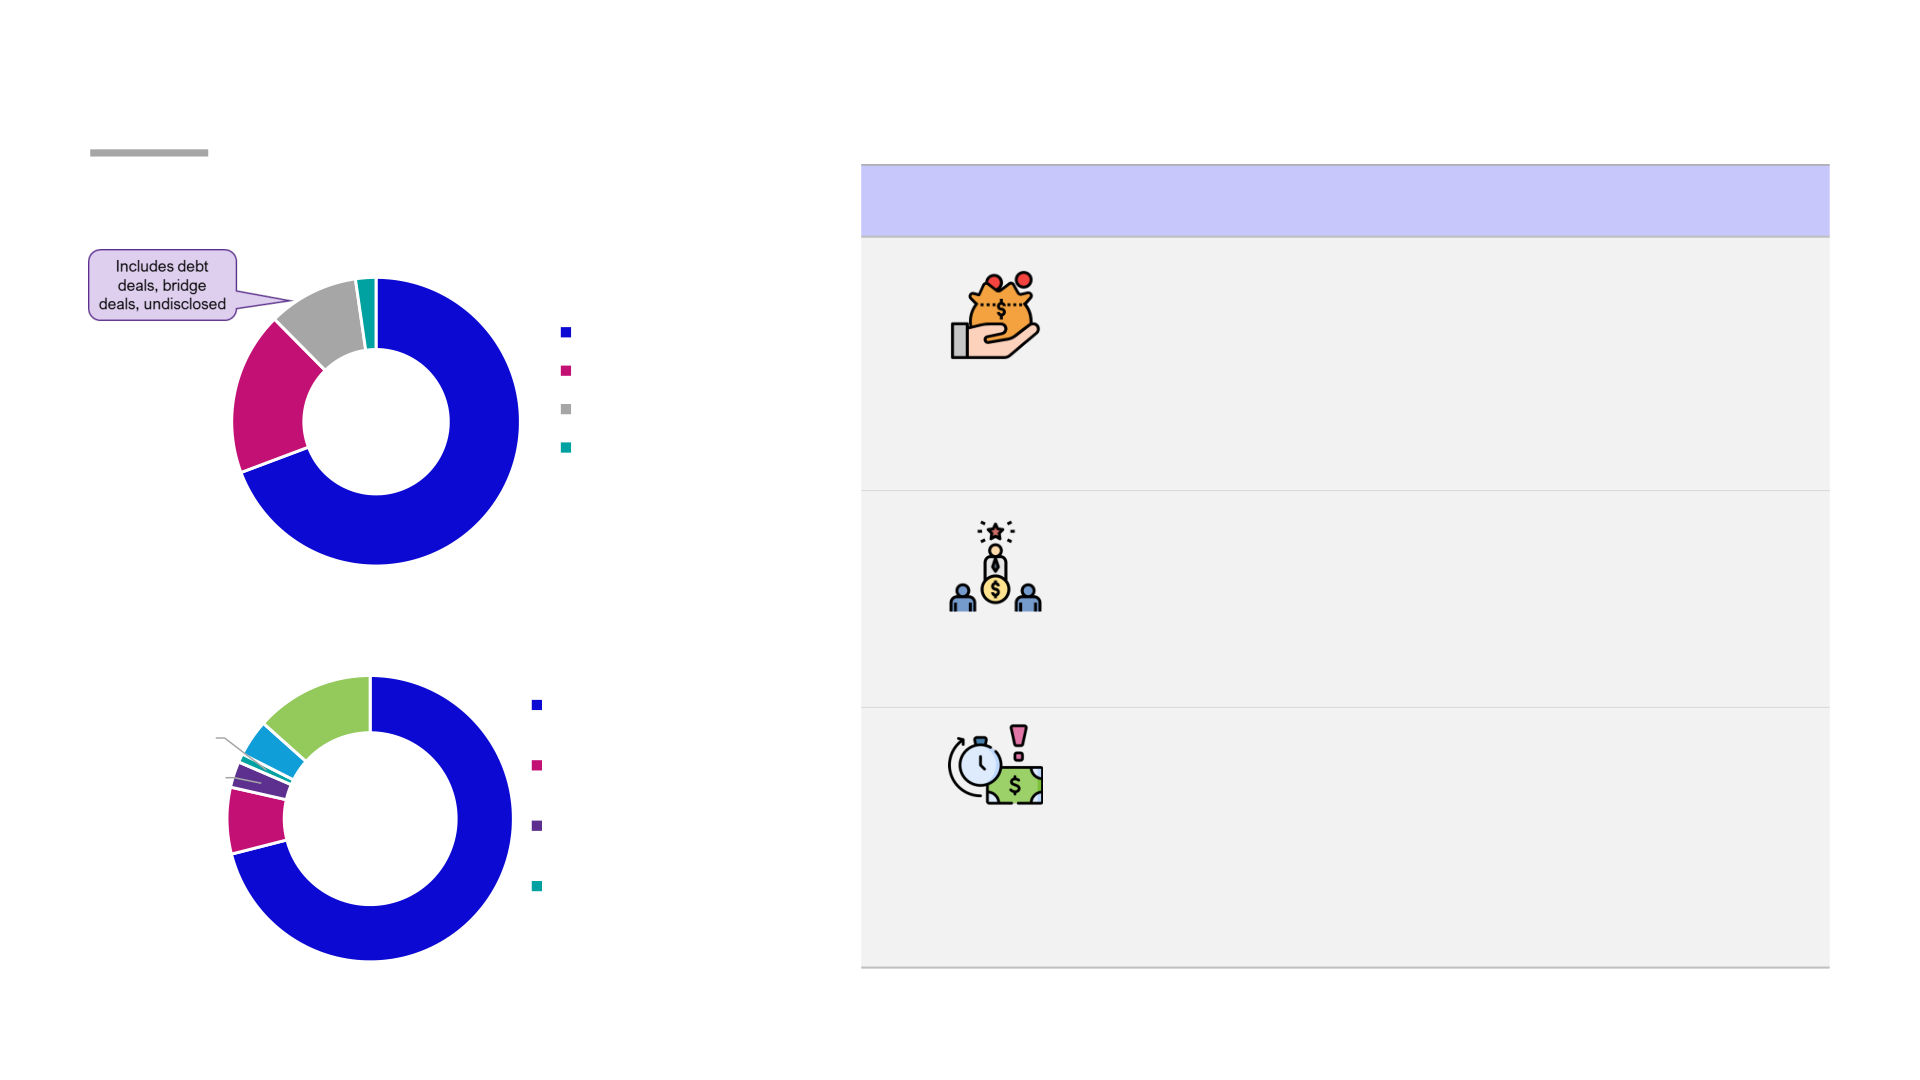
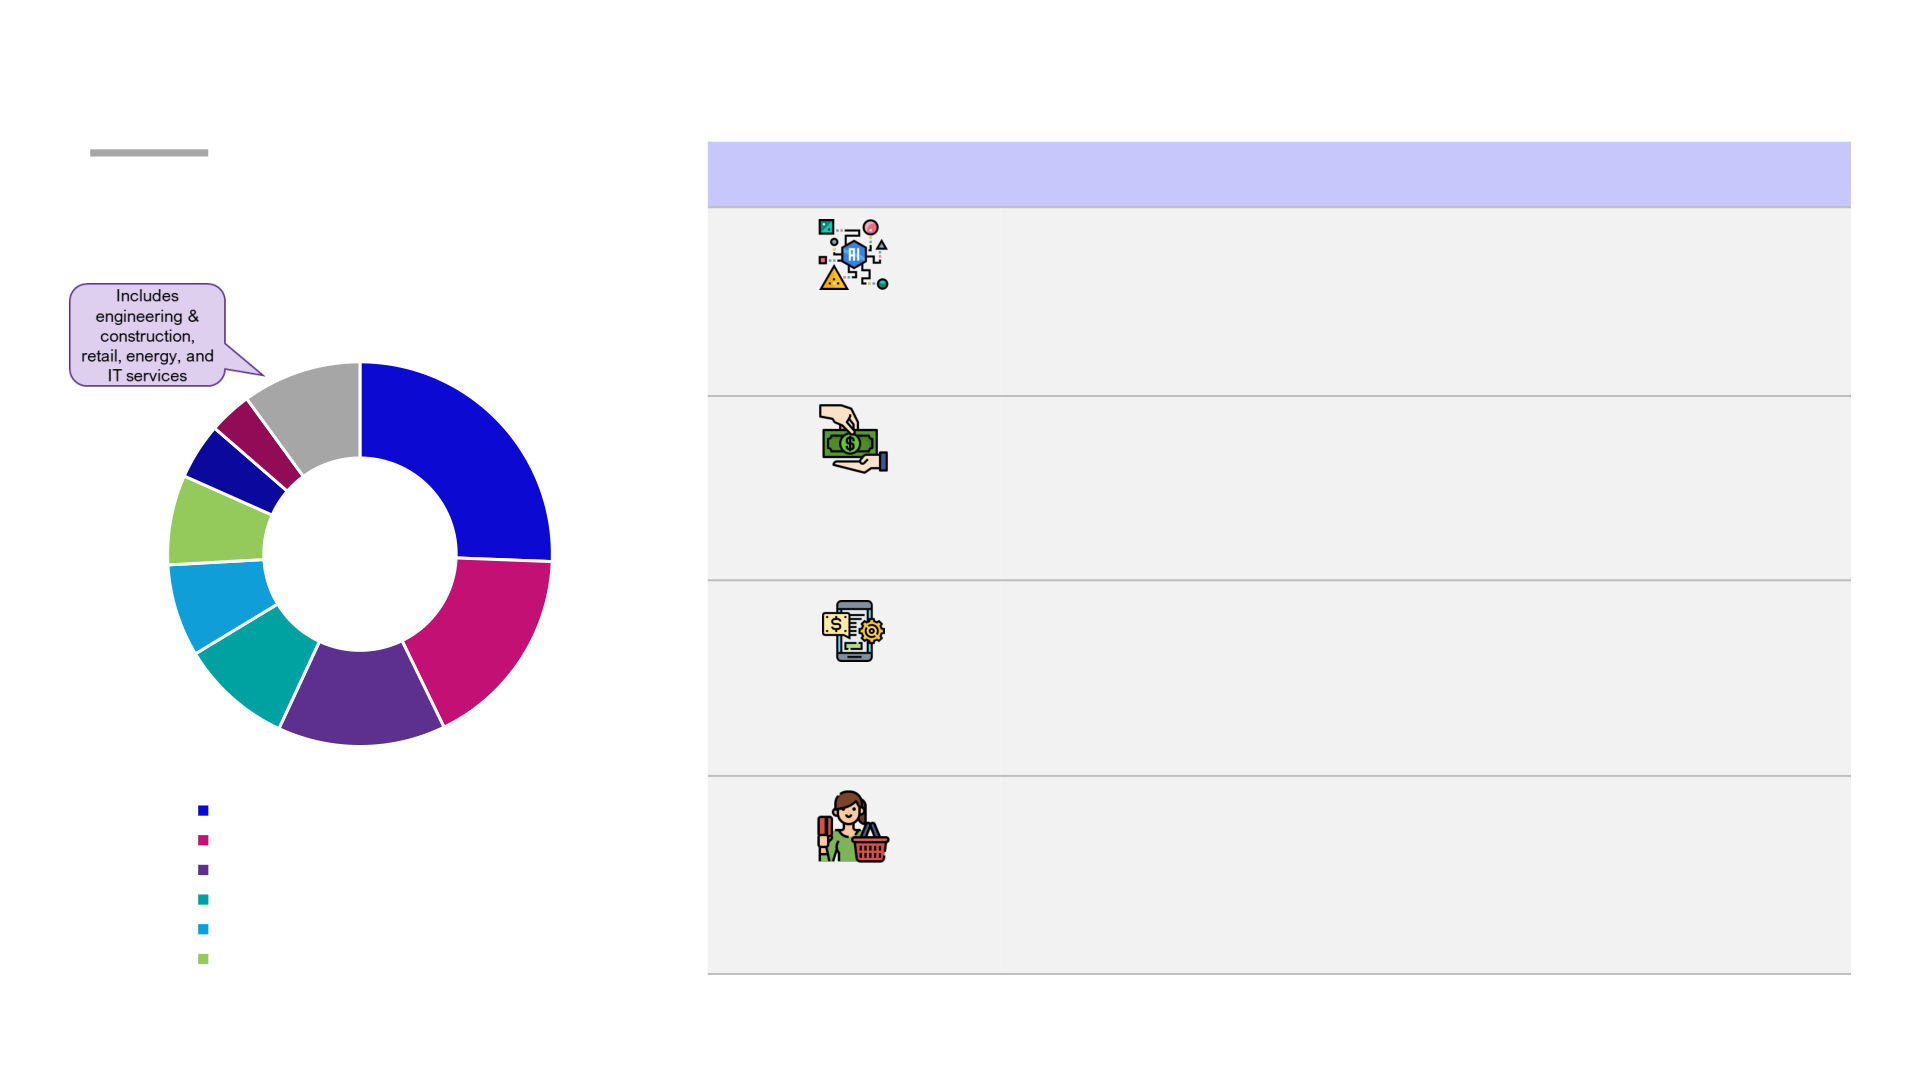
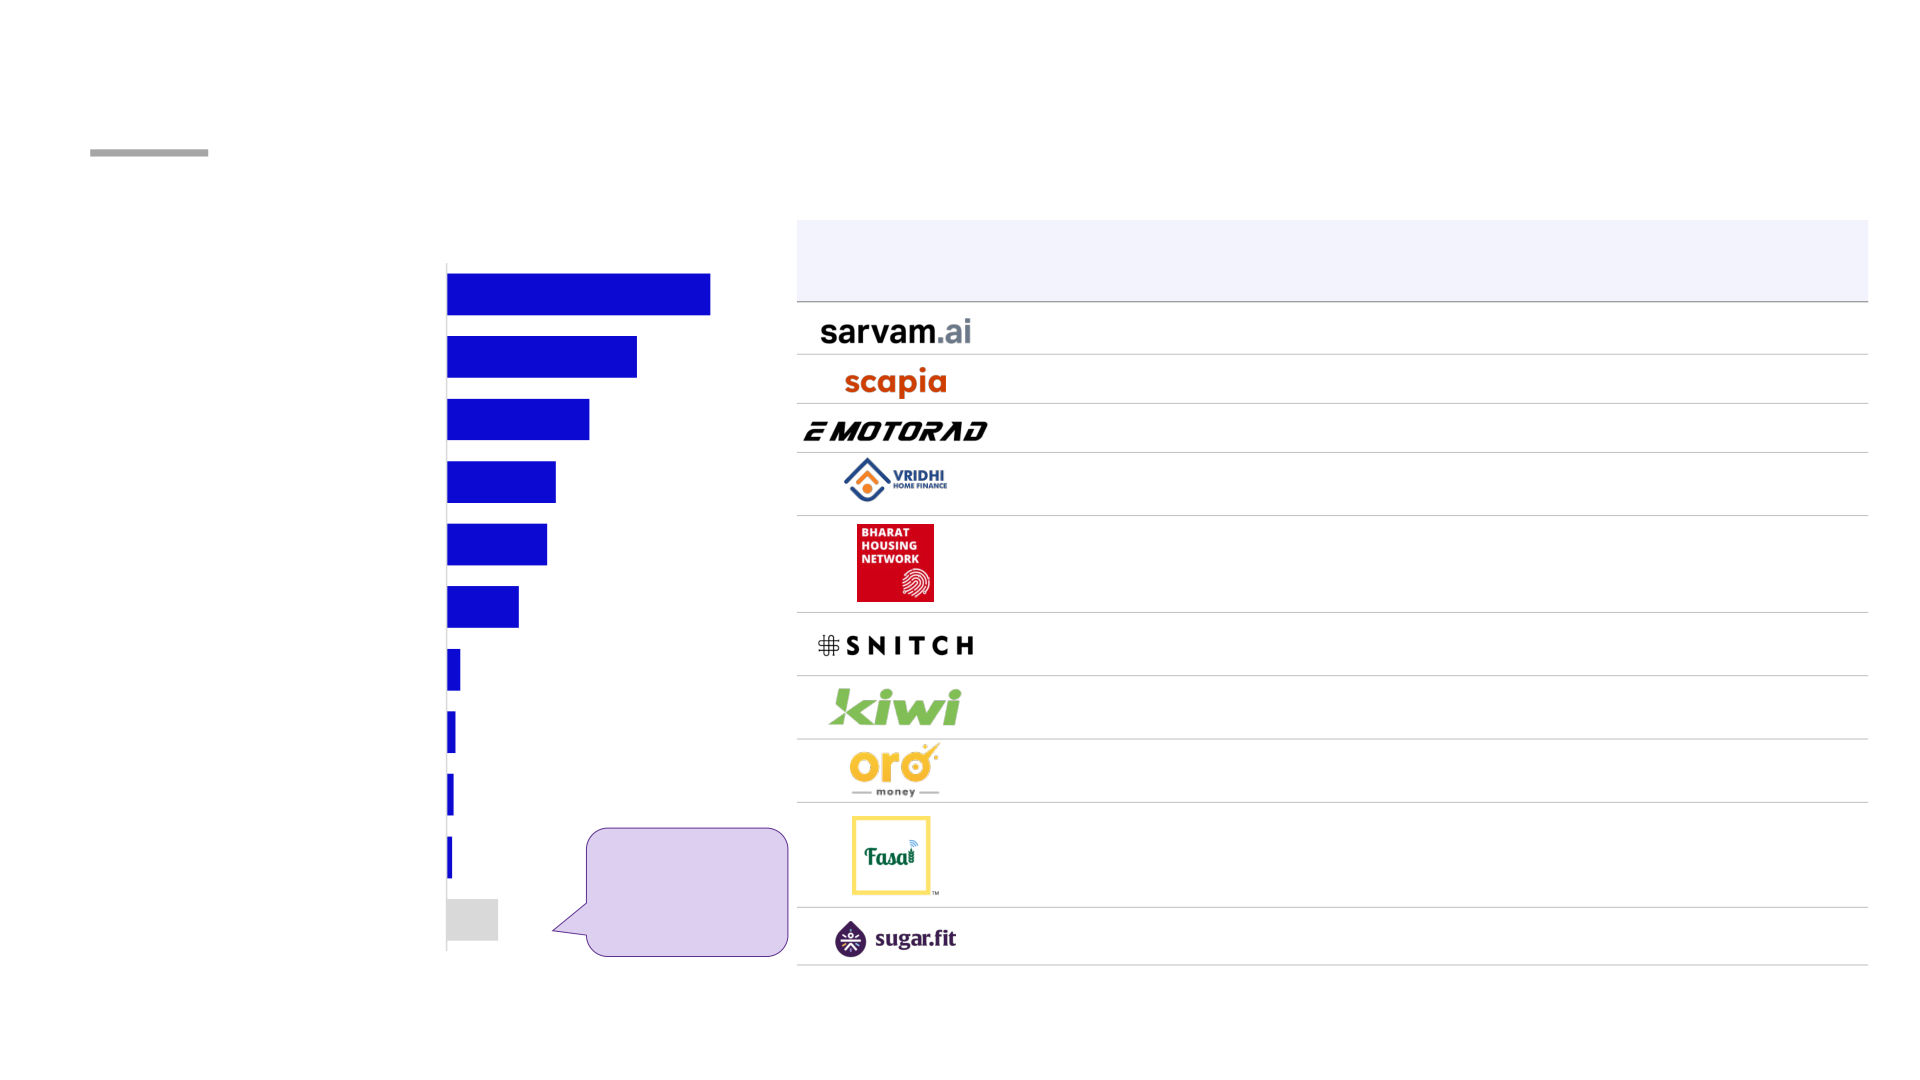
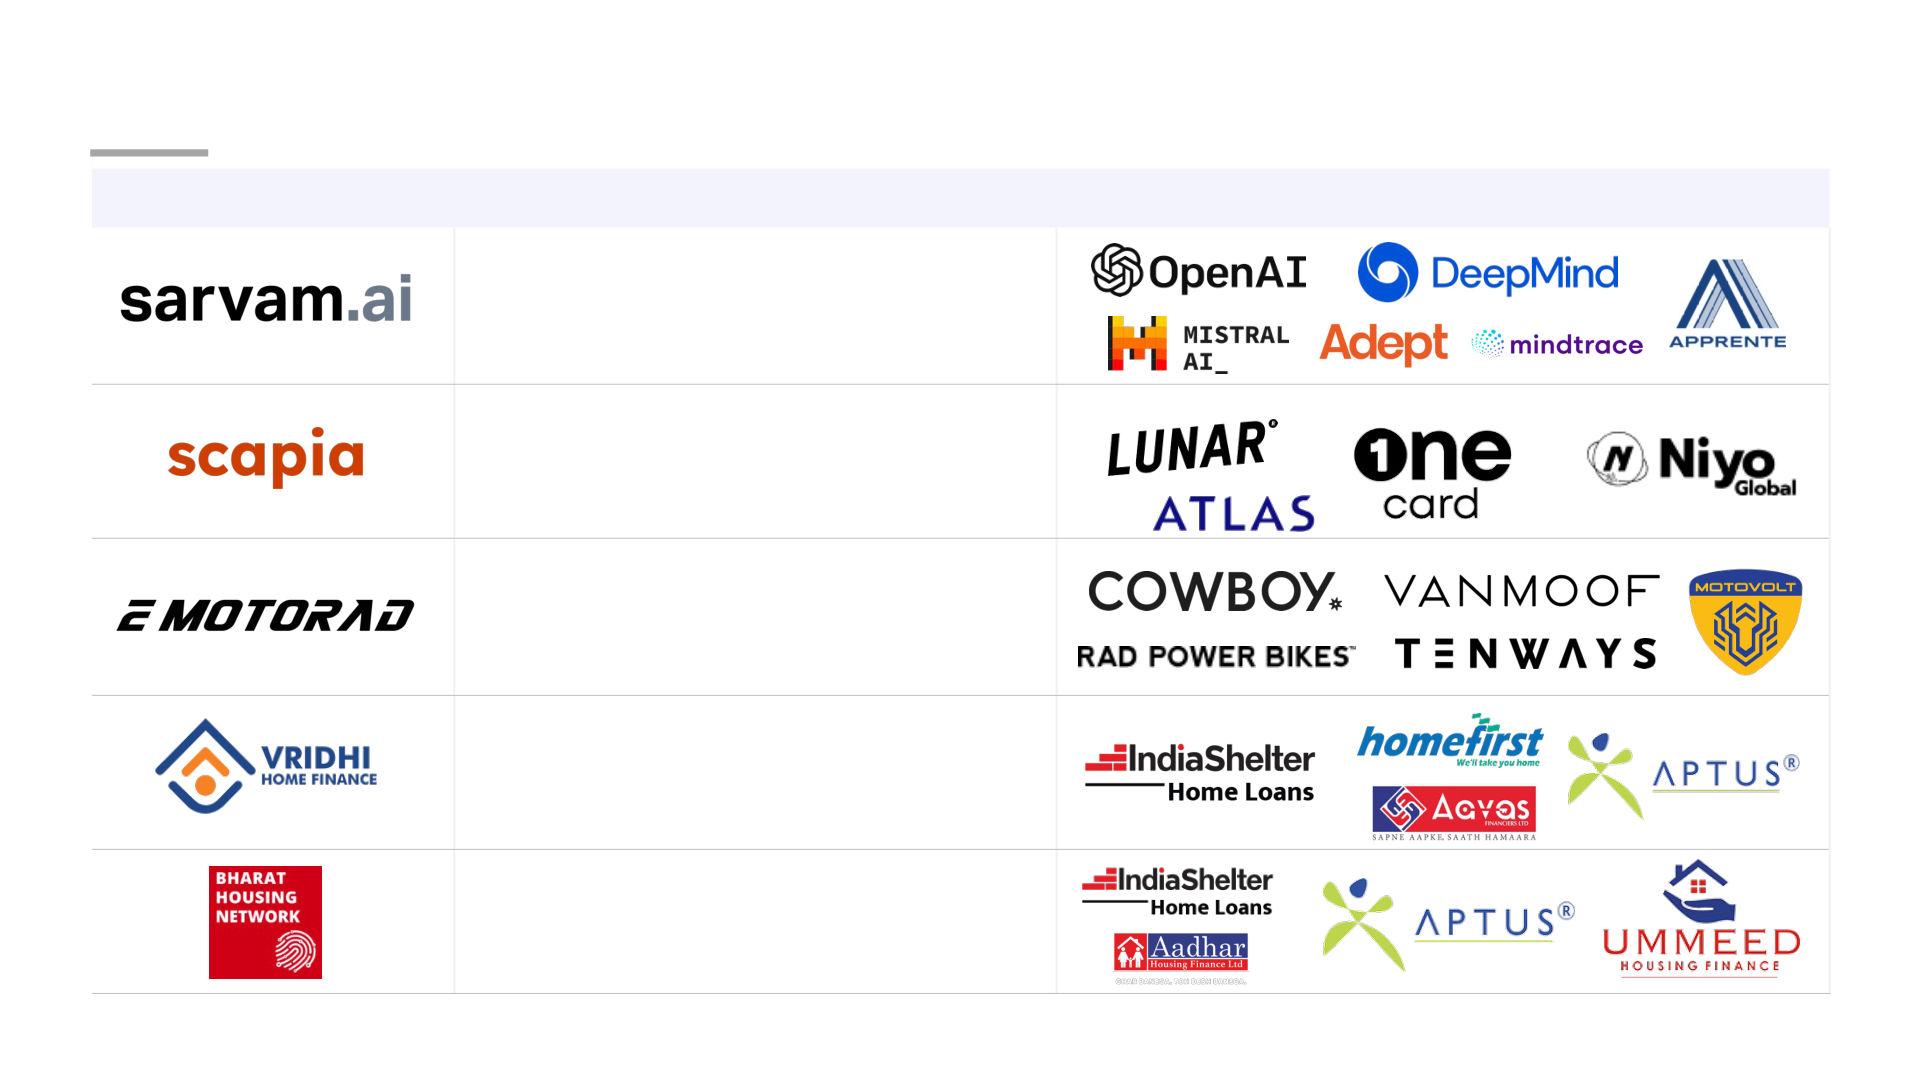
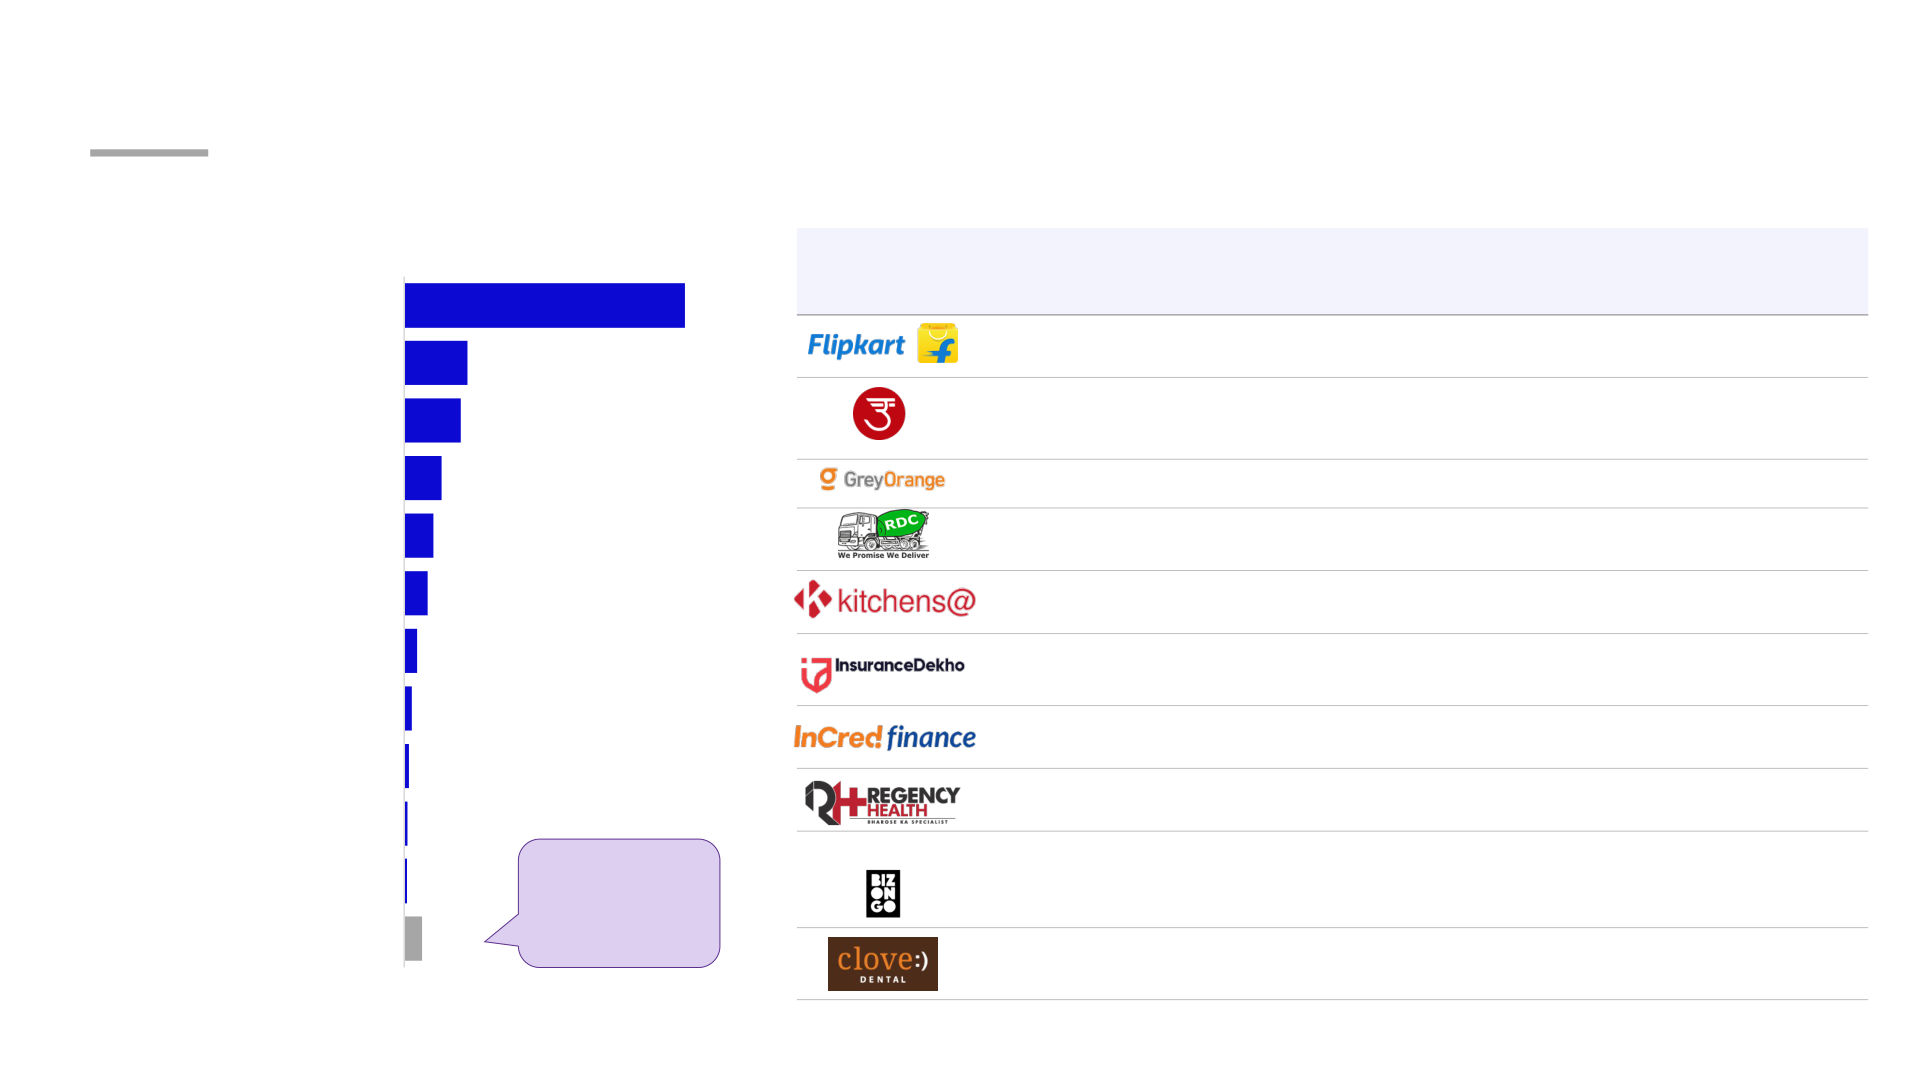
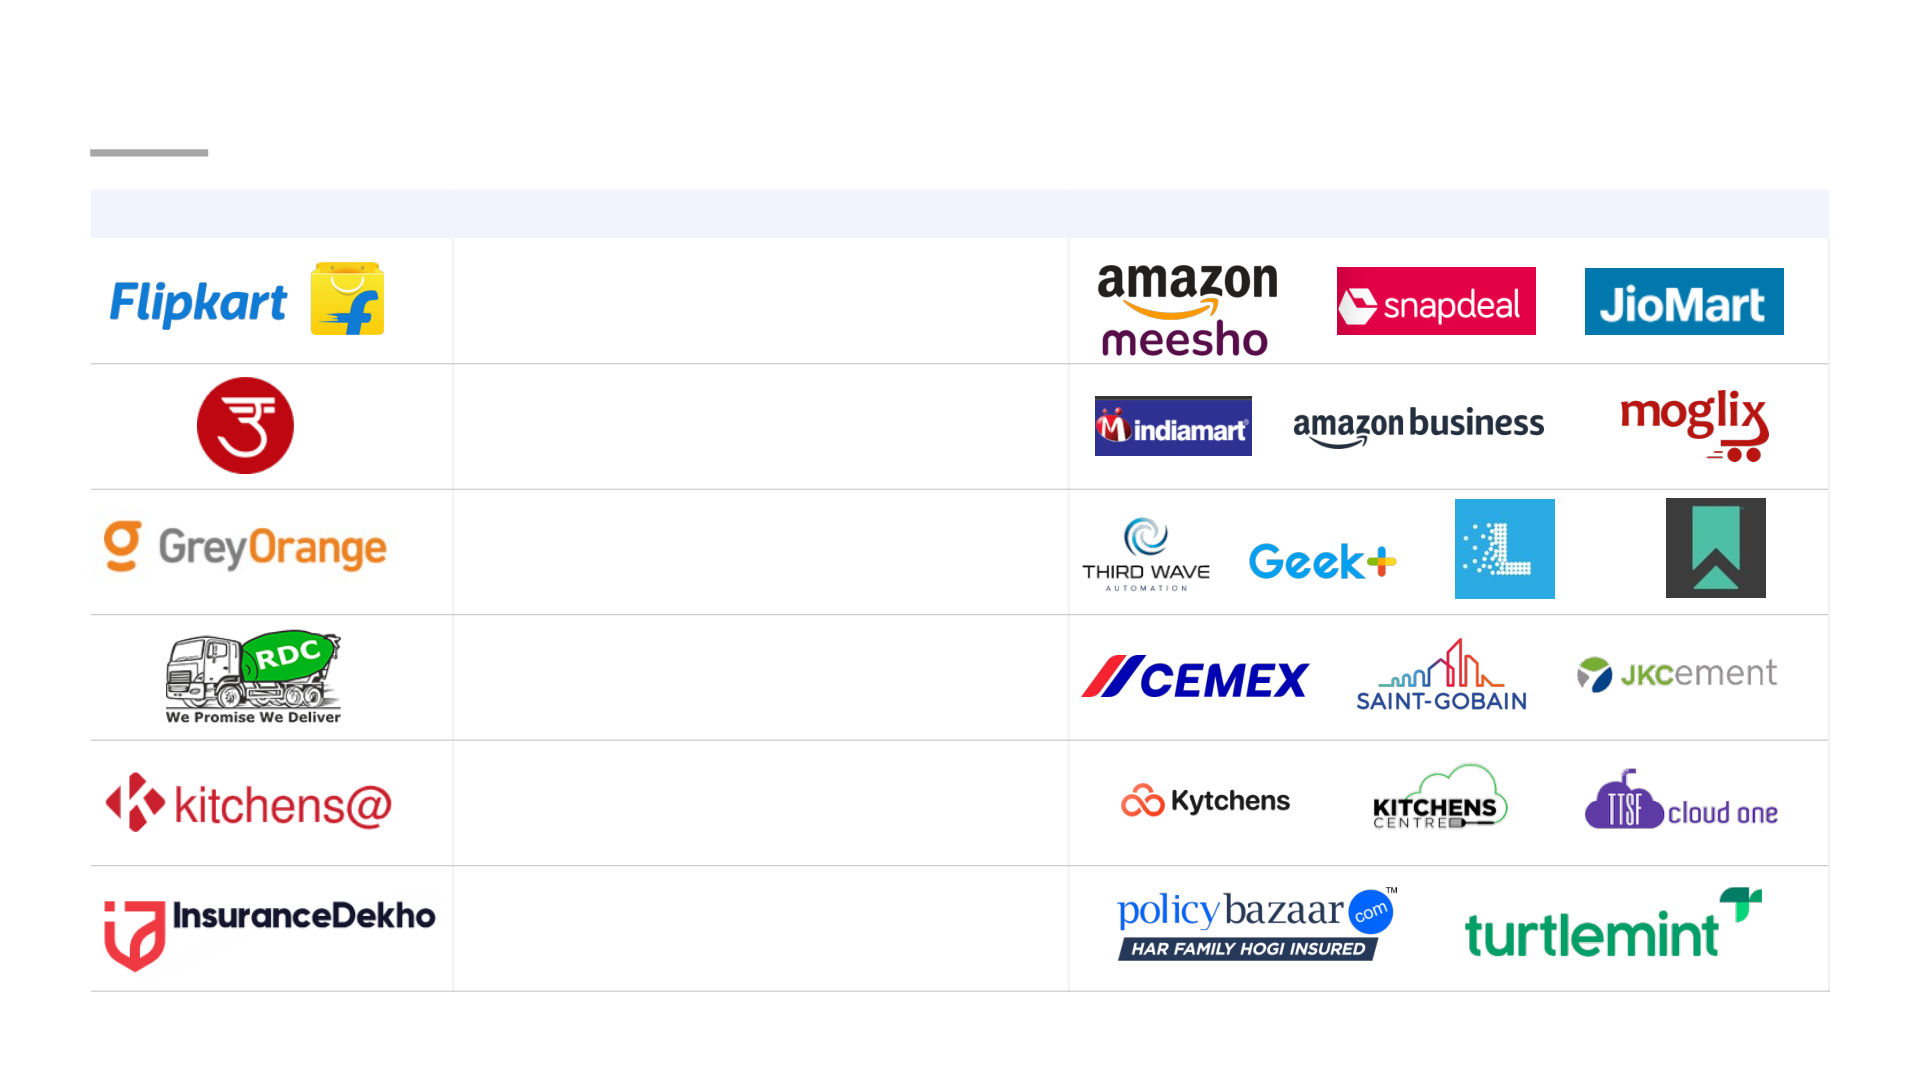
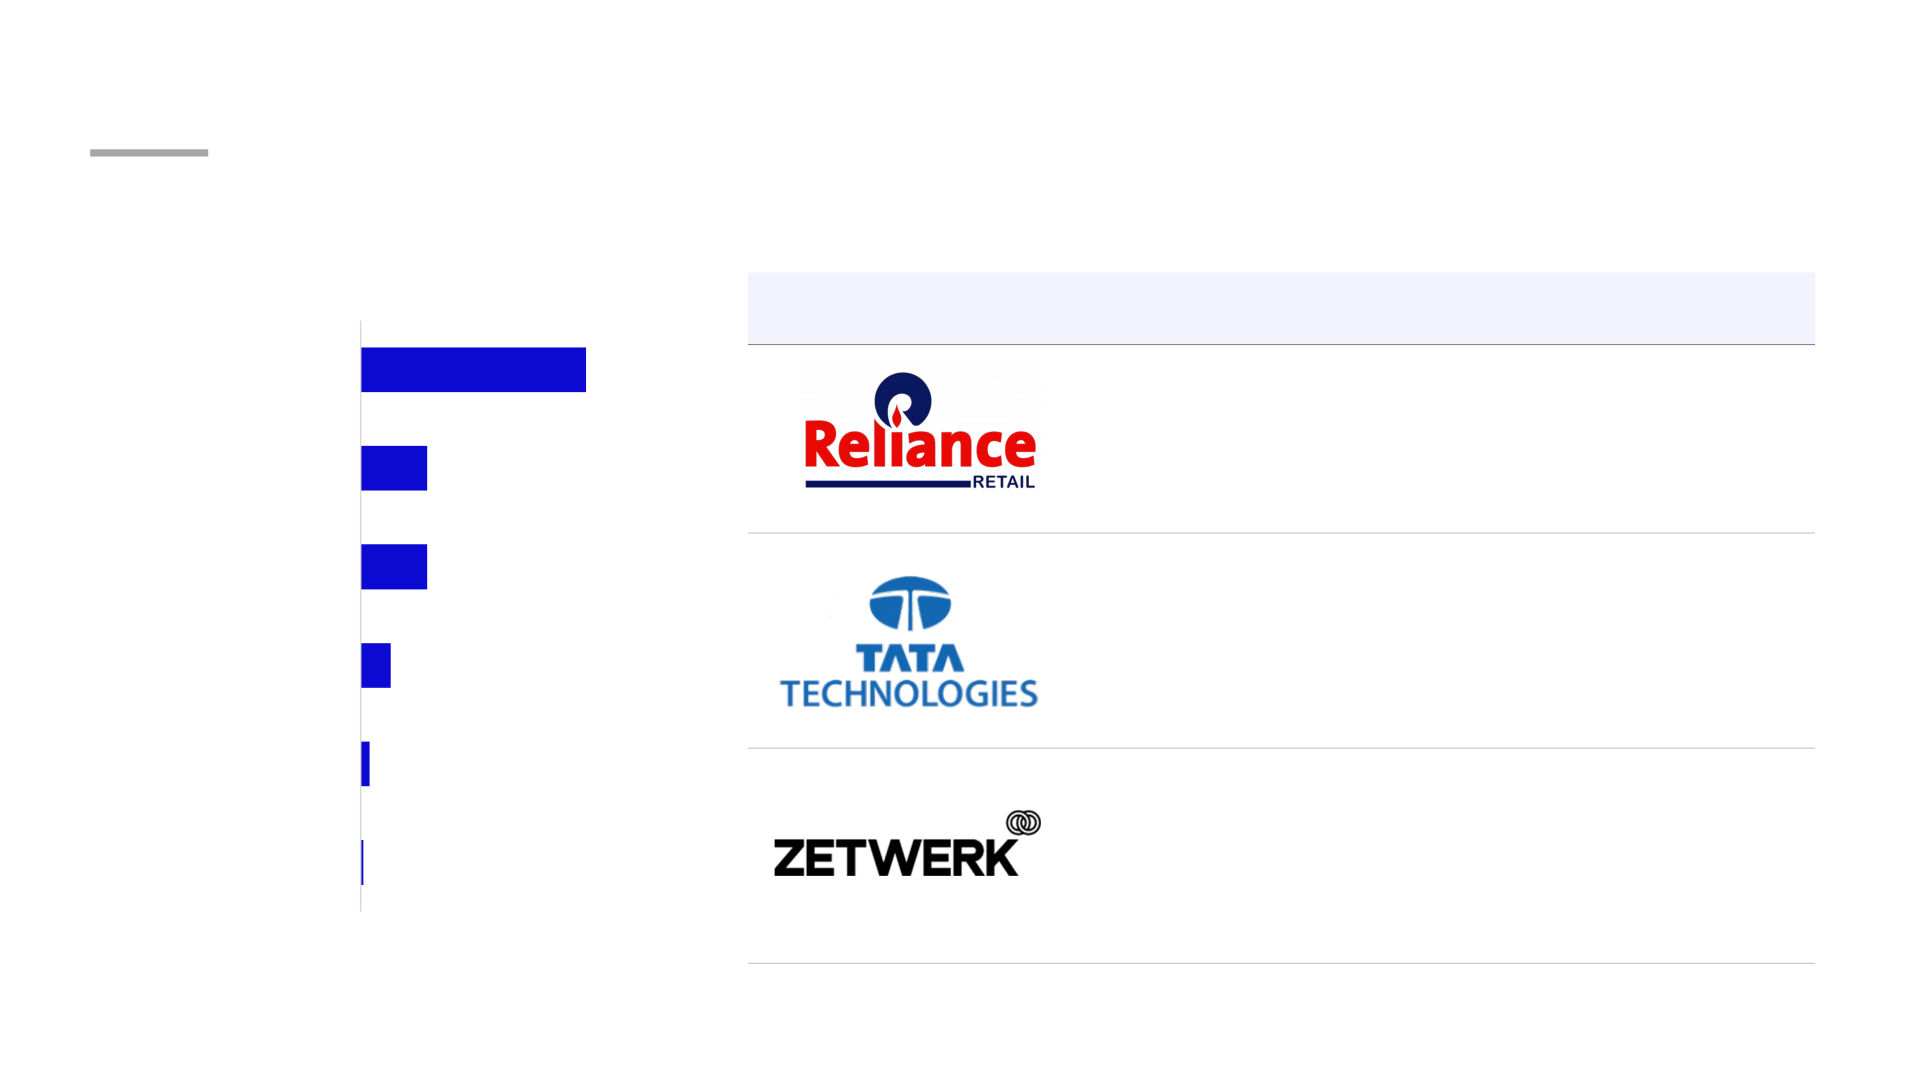
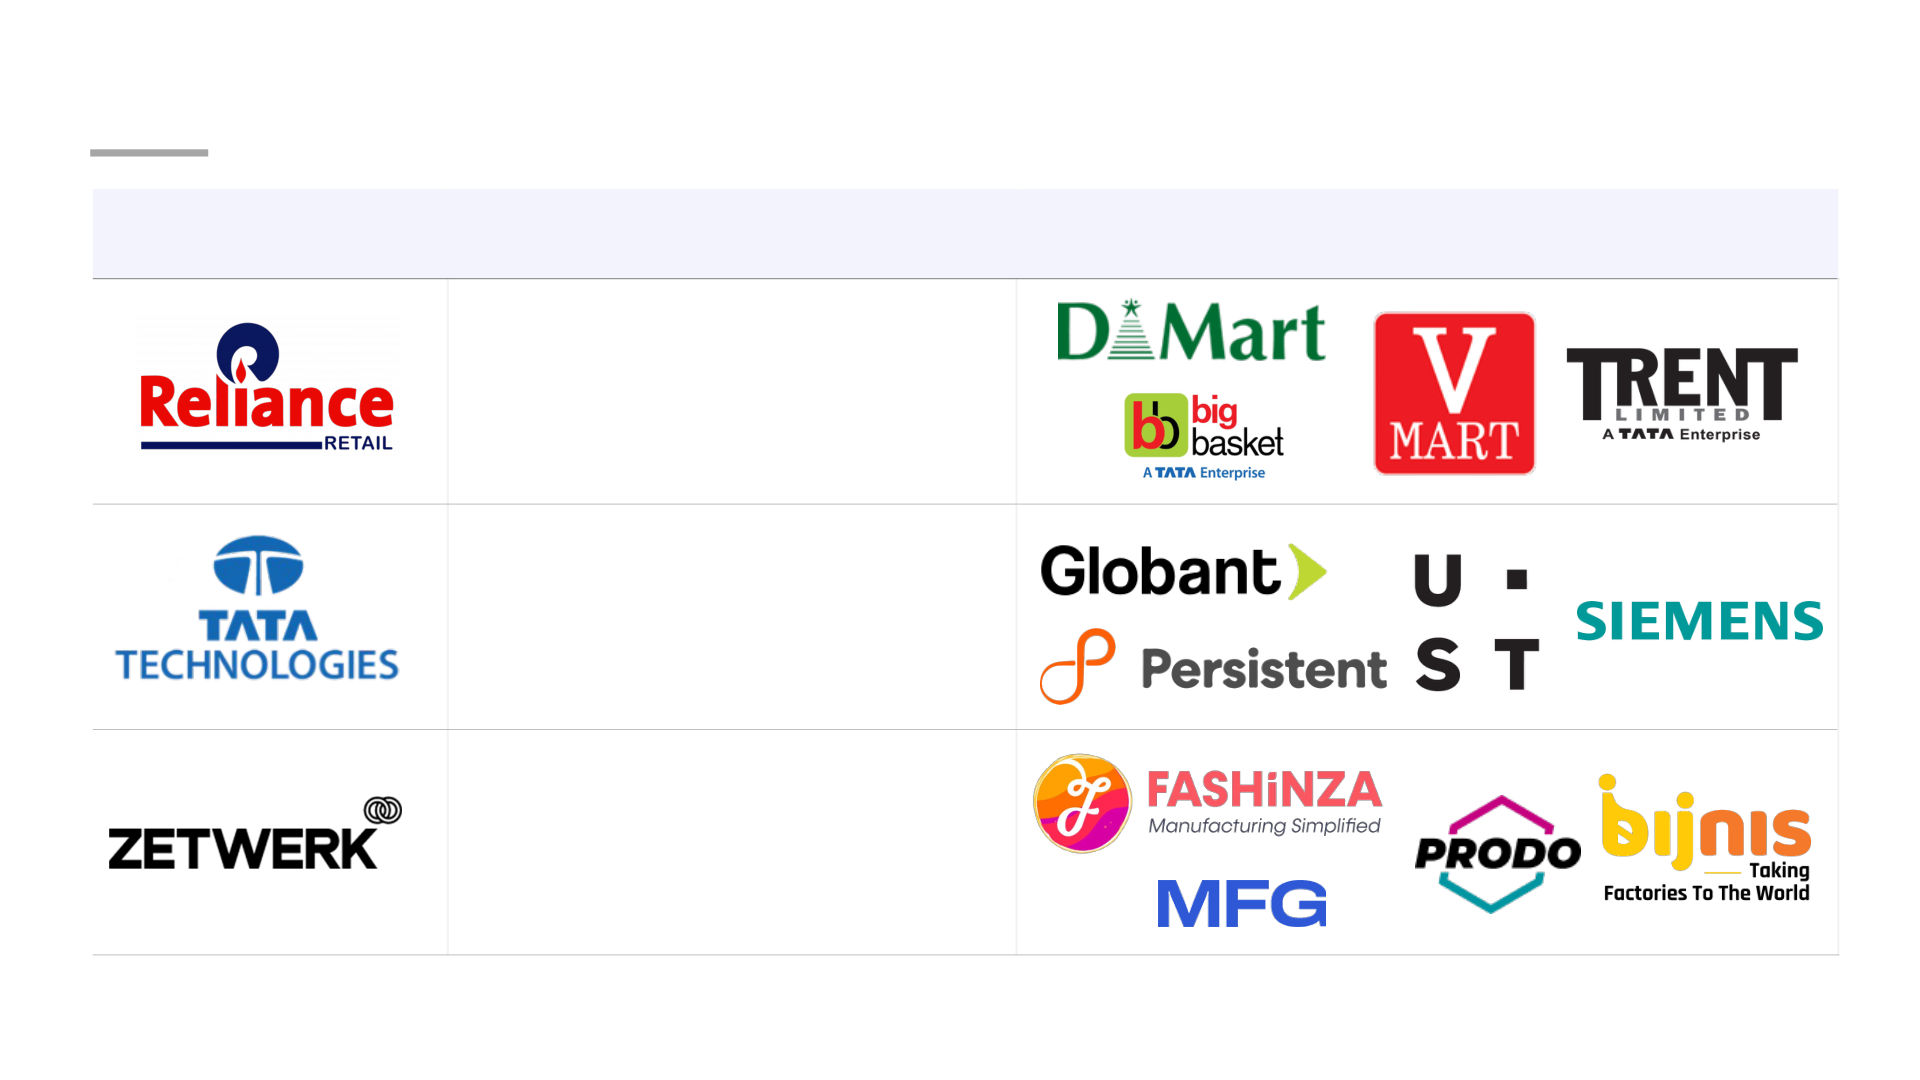
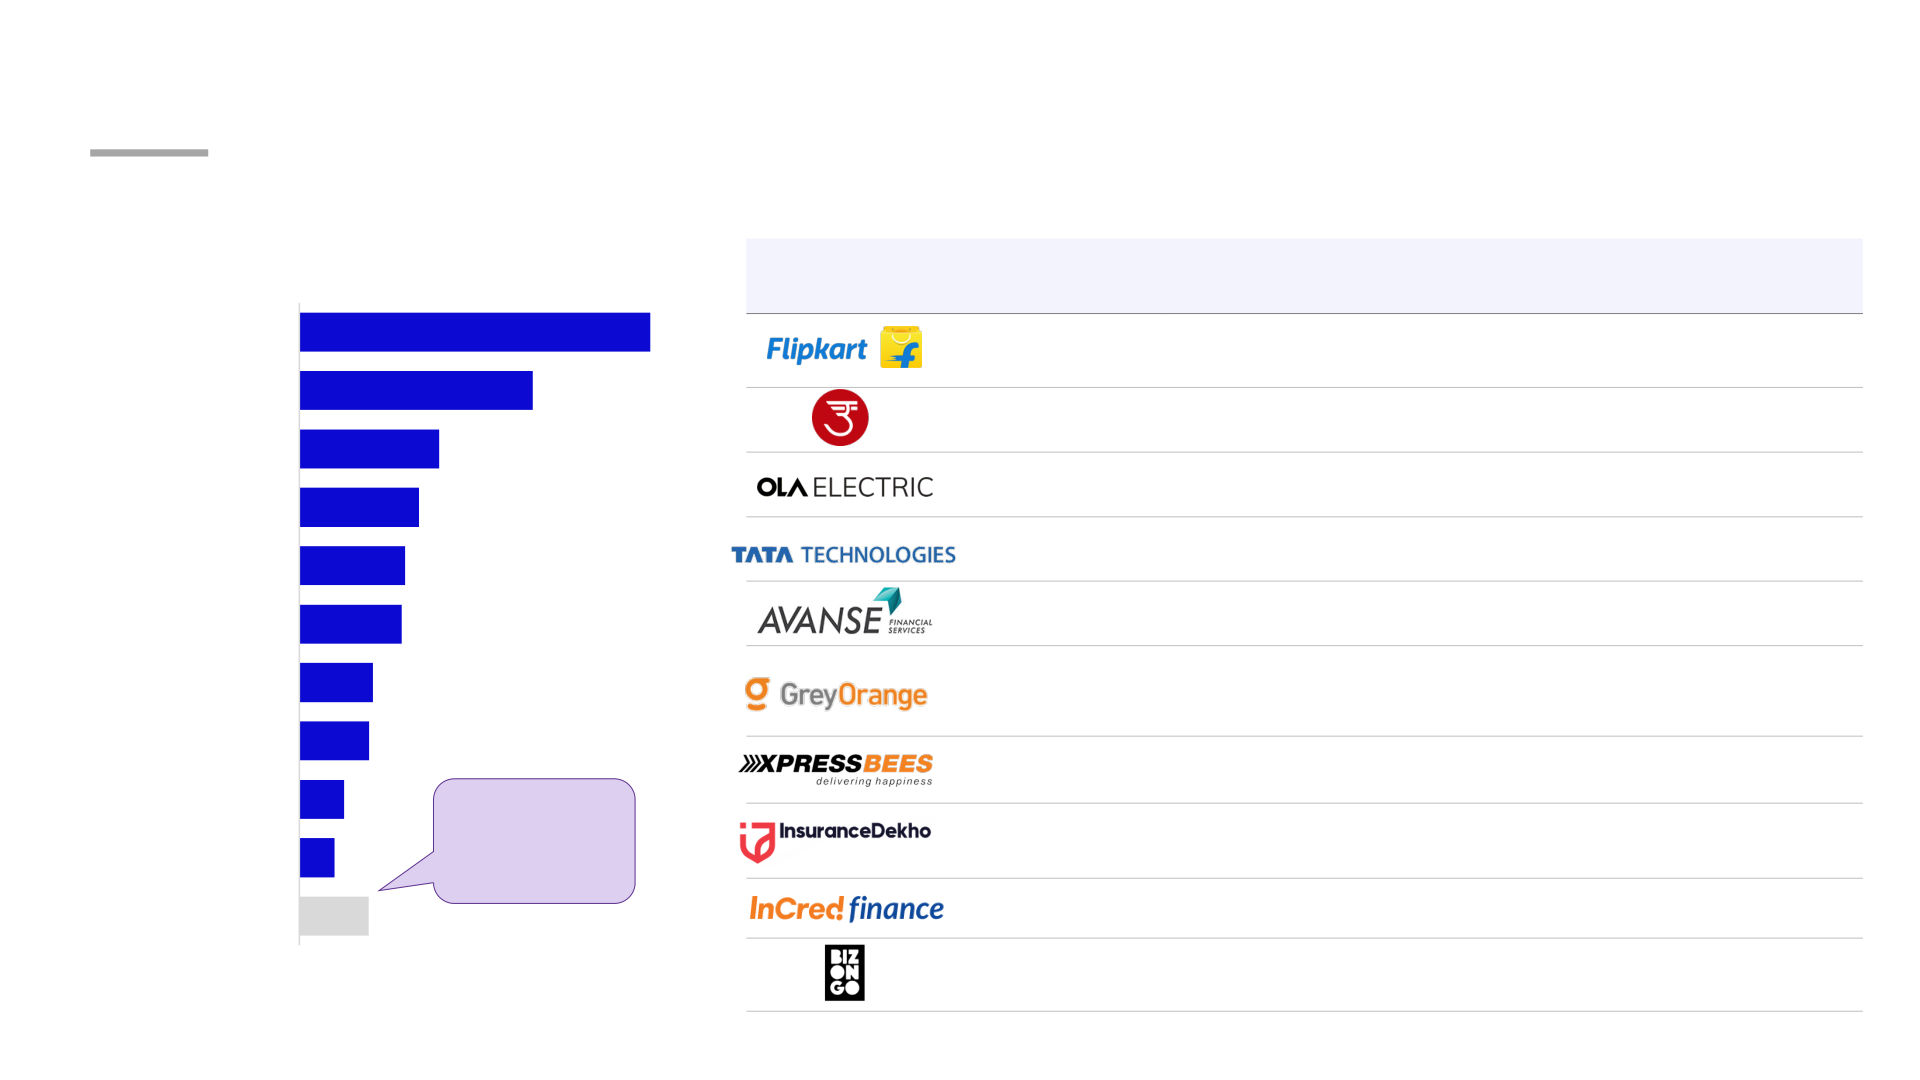
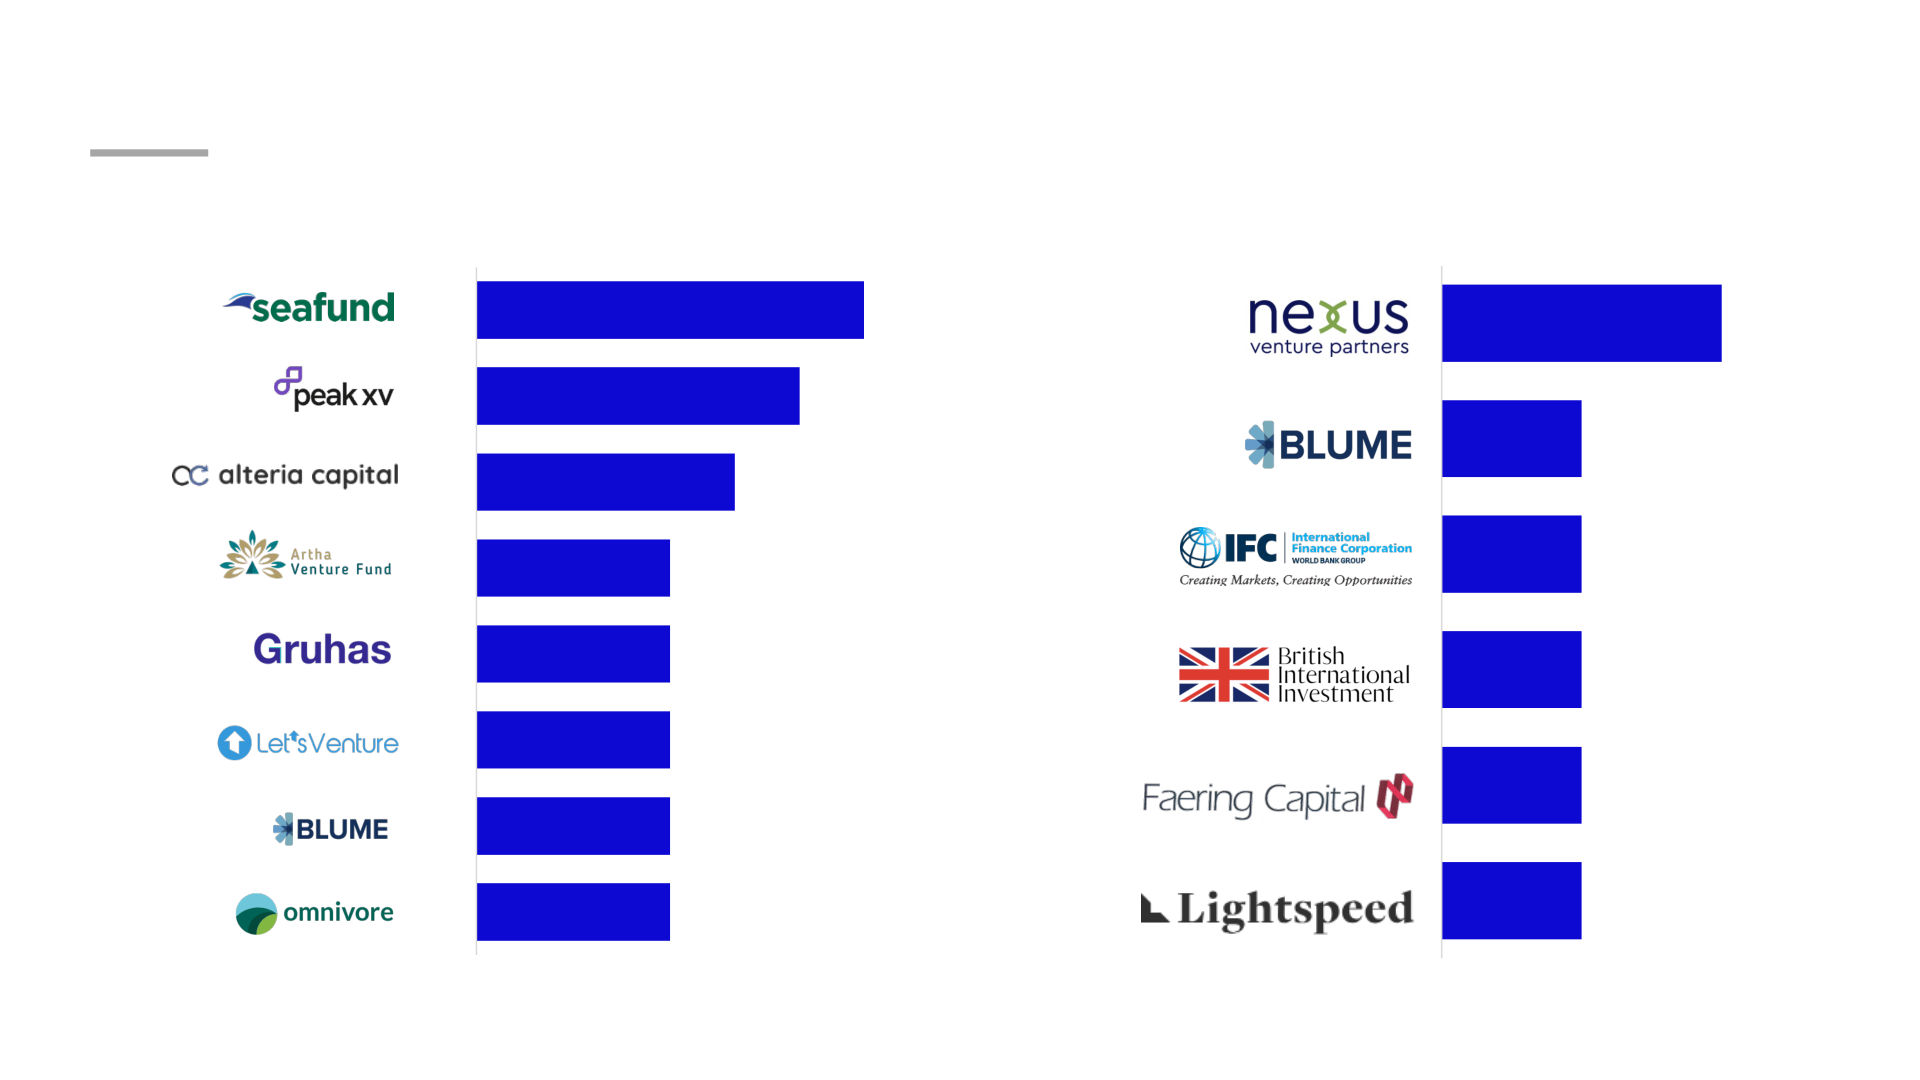
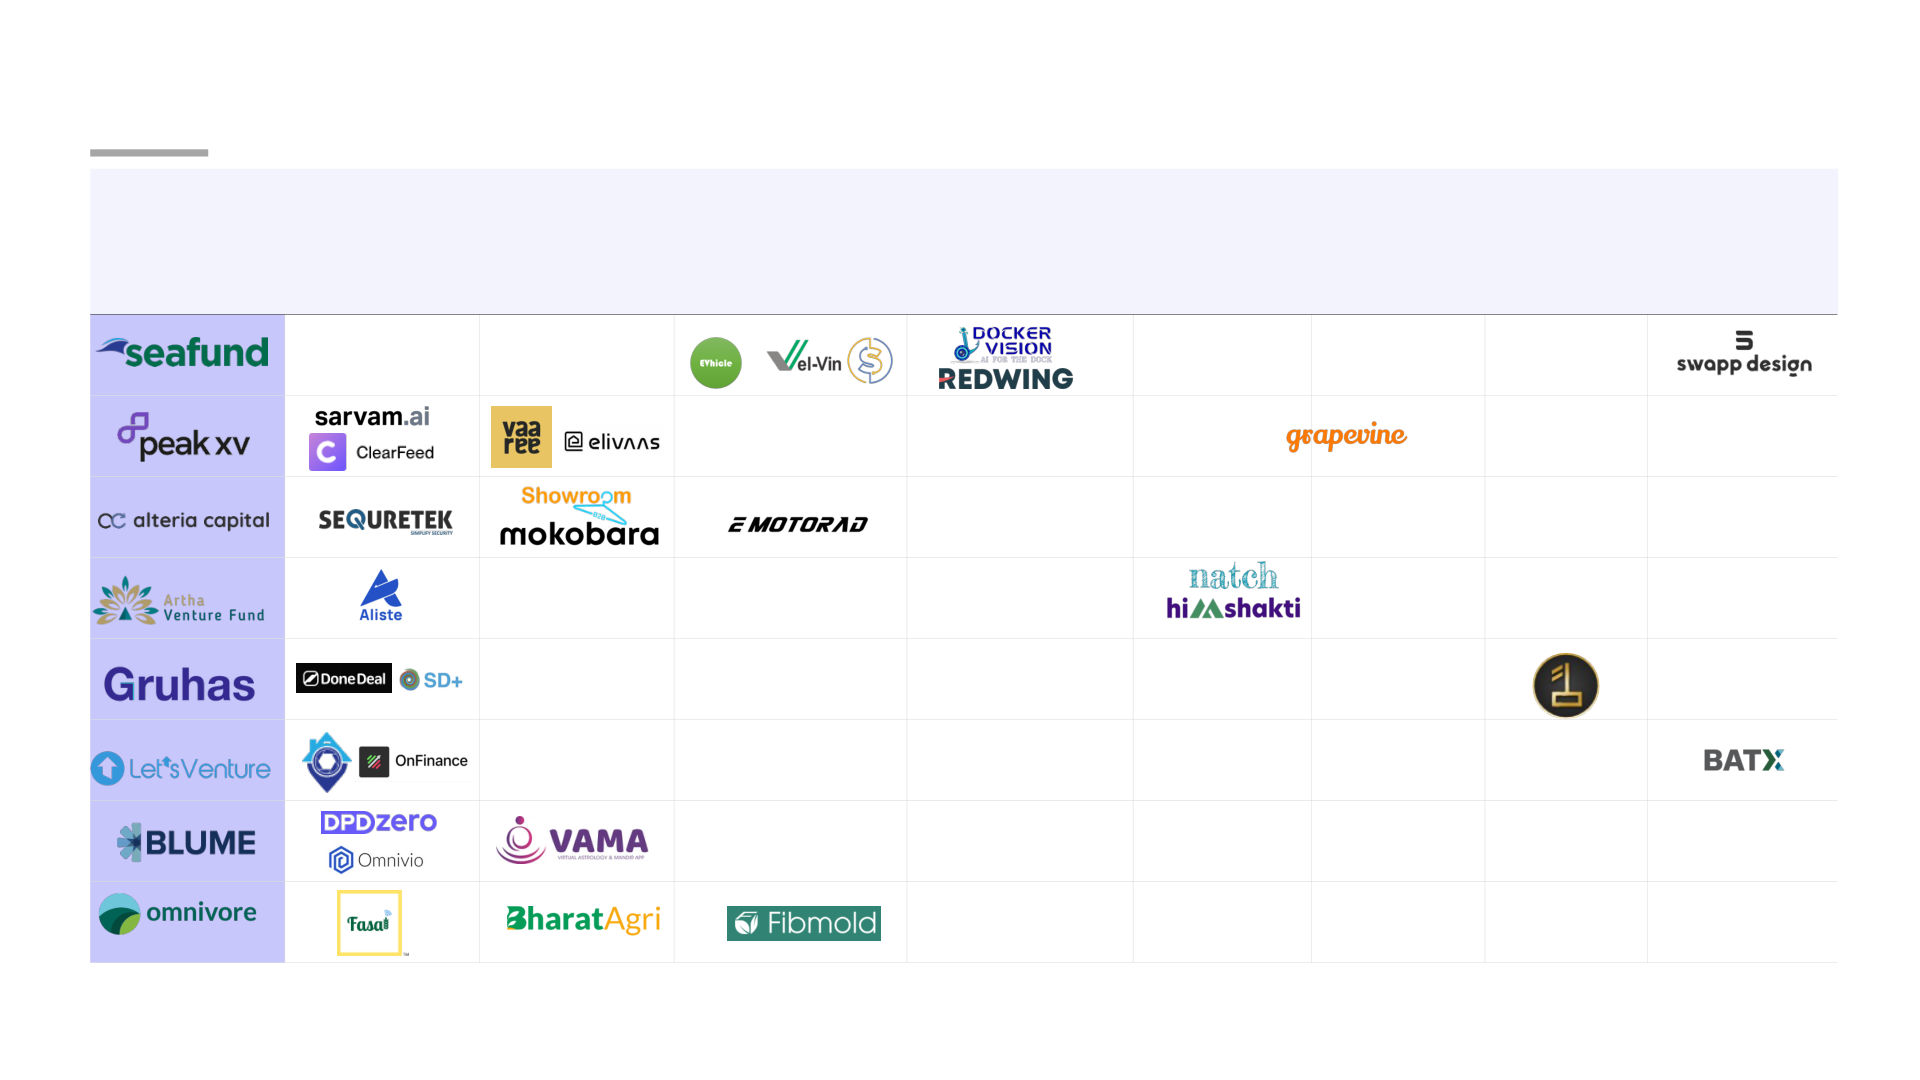
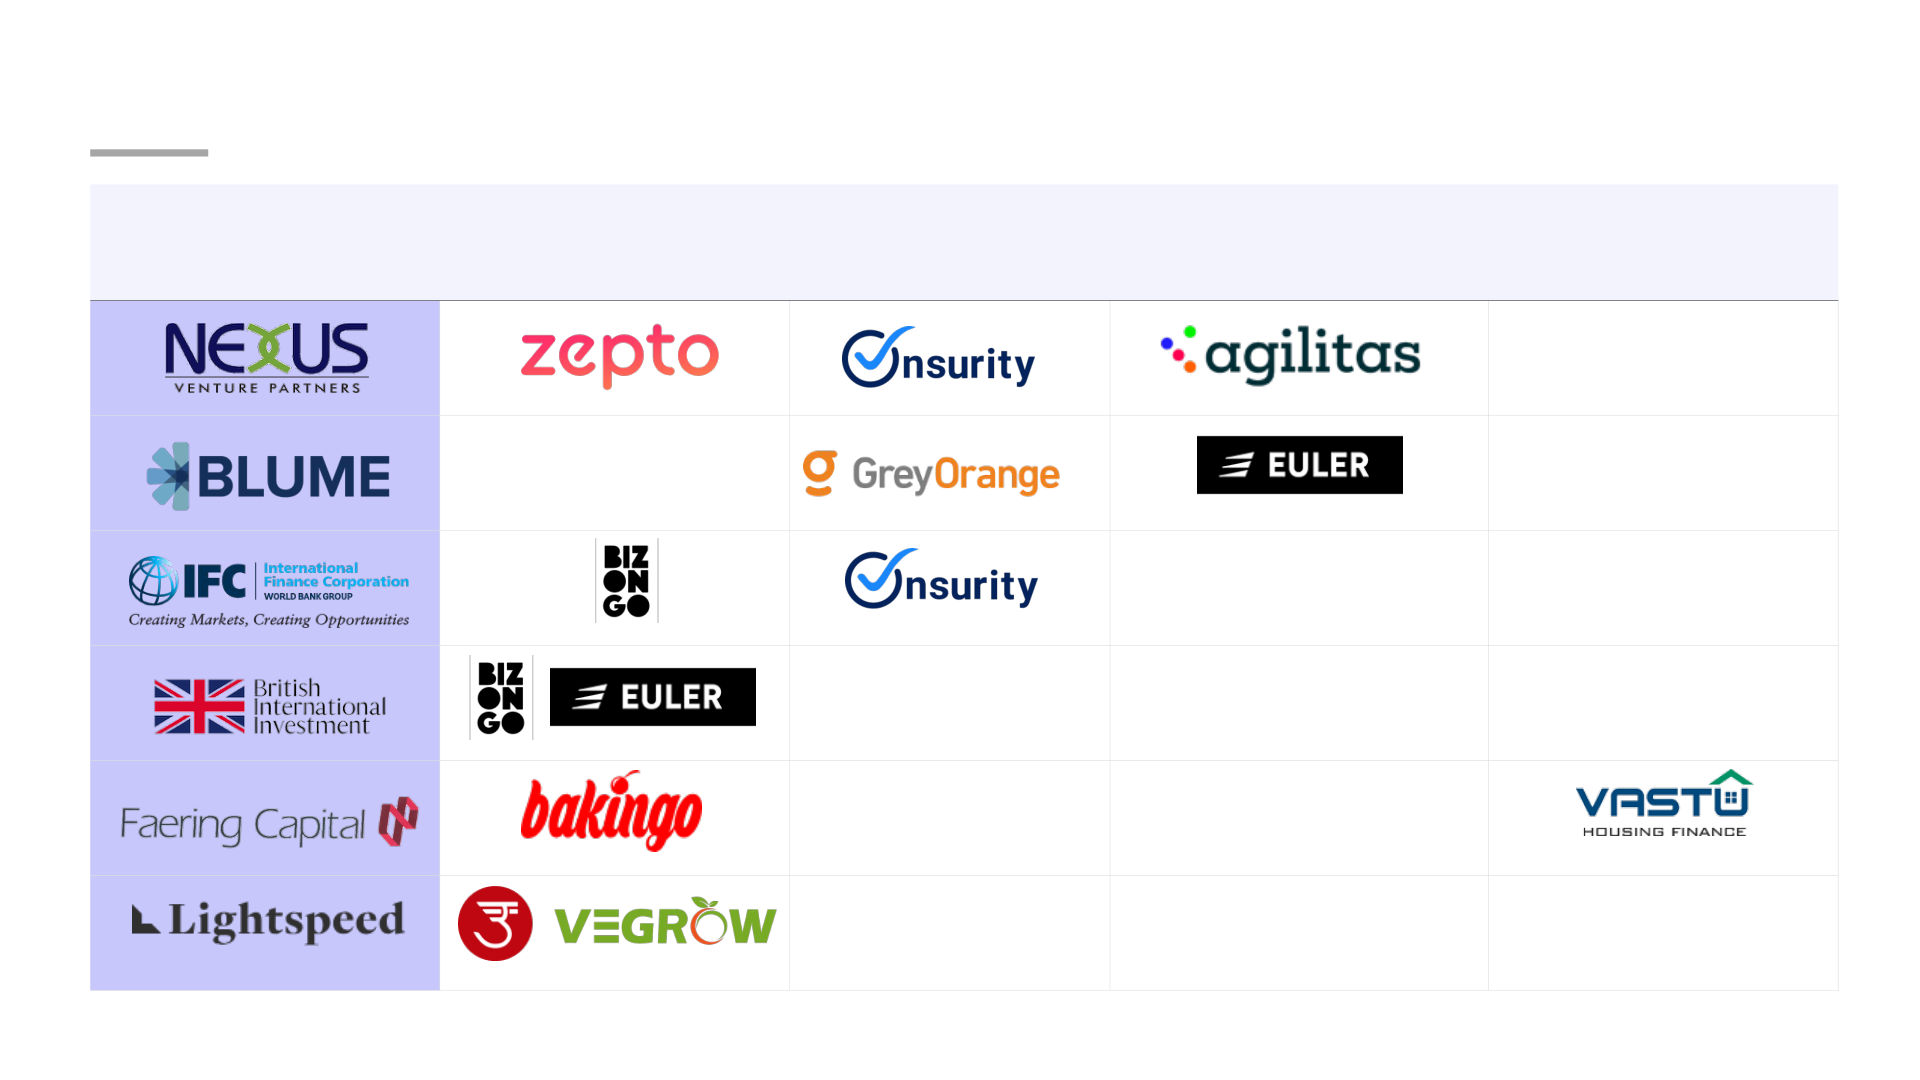
INDIA DEAL PULSE REPORT Q4 CY23 January 2024 500+ 30% Technology - backed business annual engagements faster to outcomes support that helps you 600+ 8 ENABLE BETTER years domain practices expertise DECISIONS 130+ 98% + Deep on - ground insights that you can act on team members accuracy 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 100+ 2.5M towns & cities panel members One - ness of data and people networks to harness the collective power of data, network, and technology Multi - faceted teams offering a stack of consulting, 15+ 40:60 advisory, and research services languages covered she/he ratio 1Lattice platform will host use cases across the decision support cycle of a client Foreword India is one of the fastest - growing economies globally and houses a large consumer base, comprising one of the world’s youngest populations with rising urban incomes, which has attracted attention of investors globally. However, India’s funding landscape felt the effects of a pronounced slowdown during 2023 with cutbacks across all stages of funding witnessing a decline of 30% compared previous year. The fourth quarter of 2023 recorded investments of around US$ 4.3 billion across 183 deals covering a range from seed to late - stage investments. Early - stage startups dominated the investment landscape, accounting for approximately 70% of the total funding, notwithstanding significant capital injections into players like Reliance Retail & Avaada . While India remains a coveted hub for early and growth - stage investments, the quarter witnessed a dip in funding levels compared to previous quarters in the year, attributed to factors like global economic uncertainties, high interest rates, valuation apprehensions, and a pivot towards profitability - centric growth strategies, which collectively exerted pressure on the funding ecosystem. However, prospects for India's financial landscape continue to exhibit positivity fueled by a blend of favorable government policies, resilience of the country's robust economy, and ongoing infrastructure enhancements. The relentless drive for technological advancements and innovation remains a powerful catalyst, with startups leading the way in transformative technologies like AI, biotech, and clean energy. This report aims to uncover some of the key trends during the fourth quarter of the calendar year 2023. At 1Lattice, we hold an optimistic outlook, believing that this report will provide valuable insights. We eagerly anticipate the opportunity to engage in an open dialogue with our partners across diverse industries, as we exchange notes and delve deeper into these matters while closely monitoring the evolving situation . Roma Dixit Director, Financial Investors © 1Lattice | 4 Key highlights Funding Deal v olume Average ticket size US $ 20.2 B ~900 US$ 25.2M SNAPSHOT CY 2023 Most funded stage Total equity funding Top funded sector Early US$ 19.1B Ecomm . & Listing Key takeaways Funding landscape & investment dynamics • Startups raised US $ 4 . 3 B across 183 deals in Q 4 CY 23 , signaling a slowdown in total funding ( 20 % ) ; deal volume decreased from 225 to 183 deals ( - 17 % ) compared to Q 3 CY 23 . • Investments across growth stage experienced a large increase (~ 85 % in deal value) compared to the previous quarter due to improving macro factors in the domestic market . • Early - stage deal volume decreased from 74 % to 64 % as investors shift focus towards investments in growth stage companies, indicating a lower risk appetite and maturity in the market . • Avg deal size fell by ~ 7 % to US $ 26 . 7 M as compared to previous quarter . Sectoral focus & key deals • The highest investments in Q 4 CY 23 were for Flipkart and Reliance retail with a funding amount of US $ 600 M each . • For the current quarter, SaaS / AI was the most attractive sector for early - stage investments ( US $ 118 M) while ecommerce & listing platforms was for growth stage investments (US $ 1 , 101 M) . • Horizontal e - commerce attracted highest investments (US $ 600 M) , followed by B 2 B ecommerce (US $ 400 M) and Automotive (US $ 240 M) within tech investments for Q 4 CY 23 . • Seafund ( 6 deals) & Nexus venture partners ( 4 deals) were the most prominent investors for early stage & growth stage investments respectively in Q 4 CY 23 . © 1Lattice | 6 Funding market by segments Ecommerce & listing platforms (US$ 3.3B) saw the most interest from investors, followed by retail (US$ 3B) in CY2023 Funding market segment wise break - up (US$ B, CY23) Total funding size: US$ 20B 3.3 2.6 2.3 2.1 Consumer apps & BFSI platforms Energy Ecommerce & listing platforms 1.1 0.7 3.0 2.3 1.8 Healthcare 0.3 0.2 0.1 Others* IT Transportation Manufacturing Retail SaaS / AI & logistics Engg . FMCG 0.1 Note(s): *These include laundry service, cloud kitchens, catering, etc. Source(s): Statistical reports, industry reports, secondary research, 1Lattice analysis © 1Lattice | 7 Top 10 highest funded companies Reliance Retail received the highest investment, followed by Avaada Energy in CY 2023 1,600* 1,000 Top 10 highest funded companies of CY 700 2023 (US$ M) 600 340 500 350 400 360 400 Note(s): In two successive rounds © 1Lattice | 8 Source(s): 1Lattice Deals Database Key funding trends of CY 2023 Early - stage startups dominated the funding rounds in CY23; SaaS / AI emerged as the most attractive sector Key Funding winter & lower E - Commerce ticket size deals witnessing strong trends growth The median deal size decreased from US$ 5.7M in E - commerce CY22 to US$ 4M in CY23, demonstrates signaling heightened outstanding investor caution due to performance ; Investor concerns about inflation, attraction persists in rising interest rates, and a these sectors due to global recession rising internet penetration SaaS / AI gain heavy Dominance of early - traction stage startups SaaS / AI excels in Around 70% of funding went FinTech, Enterprise Tech , Lower confidence in growth to early - stage startups in Environment Tech , Space and late - stage startups India, where founders Tech , and DeepTech; emphasize sustainable Notably, significant Growth and late - stage funding business models for long - investments in FinTech dropped by about 55% and 70% , term profitability, increasing focus on lending tech respectively, from CY22 , driven appeal to investors by investor skepticism regarding overvaluation and exit Source(s): Secondary research, 1Lattice Deals Database © 1Lattice | 9 challenges Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Investment amount and # deals Investment amount gradually dropped throughout CY23; Q4 CY23 saw a significant drop compared to the same quarter last year Investment amount (US$ B) and # deals (Q4 CY22 – Q4 CY23) 320 266 241 225 183 7.4 5.4 5.4 5.0 4.3 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Amount Deals Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage investments, PIPE and debt (Conventional, Venture, etc.) Source(s): 1Lattice Deals Database © 1Lattice | 11 Equity vs debt investments US$ 3.7B was raised through equity investments, while US$ 0.5B through debt deals in Q4 CY2318 Equity investments (US$ B) and # deals Debt investments (US$ B) and # deals (Q4 CY22 – Q4 CY23) (Q4 CY22 – Q4 CY23) 28 272 241 208 205 168 13 12 6.8 0.6 9 0.4 0.5 3.7 3.7 3.2 2.6 3 0.2 0.1 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Amount Deals Amount Deals Note(s): Equity includes early (Pre - seed, seed, pre - series and Series A), growth stage (Series B, C, D and E), late (Series F on wards) stage investments, and debt includes conventional debt, venture debt, etc.) Source(s): 1Lattice Deals Database © 1Lattice | 12 Stage - wise investments Growth stage witnessed an increase of US$ 1B in funding compared to previous quarter, but remained unchanged compared to the same period last year Investment amount (US$ B) (Q4 CY22 – Q4 CY23) 320 266 241 225 183 N* = 0.1 0.2 0.5 0.5 1.5 2 2.2 1.9 1.1 0.2 0.1 0.4 0.3 2.7 1.5 2.1 2.2 1.6 1.2 1 0.9 0.7 0.4 0.5 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Early Growth Late Debts Others Note(s): Chart includes early (Pre - seed, seed, pre - series and Series A), growth (Series B, C, D and E), late (Series F onwards) stage investments, others (undisclosed rounds) and debt (Conventional, Venture, etc.); *Number of deals Source(s): 1Lattice Deals Database © 1Lattice | 13 Average deal size Average deal size increased to US$ 26.7M from US$ 23M, whereas total deals fell to 183 deals from 320 deals compared to the same quarter in CY22 Average deal size Deal volume by stage (US$ M, Q4 CY22 – Q4 CY23) (%, Q4 CY22 – Q4 CY23) 320 266 241 225 183 3% 2% 5% 28.6 8% 9% 5% 1% 5% 15% 26.7 5% 3% 5% 2% 24.4 3% 19% 14% 23.0 22.3 23% 18% 18% 74% 72% 66% 64% 62% Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Q4 CY22 Q1 CY23 Q2 CY23 Q3 CY23 Q4 CY23 Early Growth Late Debt Others* Note(s): Stage of investment here is decided by the round of investment. Pre - seed, seed, pre - series and Series A are classified as Early, Series B, C, D and E are classified as Growth, Series F onwards are classified as Late, Debt includes deals with Conventional, Venture, etc. Others include deals with undisclosed round, PIPE, etc. Source(s): 1Lattice Deals Database © 1Lattice | 14 Stage – wise investments & trends in CY23 Early - stage startups dominated the funding rounds in CY23; ~70% of the deals had a ticket size of less than US$ 25M Key trends Stage - wise investment CY23 (%, N = 918)* 2% • Median deal size has decreased from US$ 5.7M in CY22 10% Early to US$ 4M in CY23 • Investors have become more careful in their diligence Growth Funding winter process and funding of startups due to inflation , rising 18% Others and lower ticket interest rates , global recession size deals Late 69% • ~ 70% of the total funding was secured by early - stage startups in India • Founders are focusing more on building sustainable businesses while aiming for long - term profitability to Dominance of Ticket size CY23 attract investments early - stage (%, N = 918)* startups Less than US$ 25M 13% 1% 4% US$ 25M - 50M • Funding in growth and late stages decreased 3% significantly by ~ 55% and ~70% respectively as compared to CY22 8% Lower confidence US$ 50M - 75M in growth and • Investors are skeptical to invest in startups because of late - stage worries around overvaluation and difficulties in US$ 75M - 100M 71% startups achieving successful exits, especially for late - stage Note(s): *N here represents number of deals in CY23 Source(s): 1Lattice Deals Database © 1Lattice | 15 Stage – wise investments & trends in CY23 Early - stage startups dominated the funding rounds in CY23; ~70% of the deals had a ticket size of less than US$ 25M Sector - wise trends in CY 2023 Sector - wise investment CY23 • Within SaaS / AI, FinTech, Enterprise - Tech, Environment - Tech, Space - (%, N = 918)* Tech & DeepTech have shown strong performance • The sector attracted significant investment due to its predictable Top sub - sectors within revenue , high growth prospects , and recurring business model SaaS / AI 10% 4% • With Phone Pe securing one of the top deals of CY2023, the payment 26% sub - sector saw significant interest from investors 5% Lending & payments • The sector also saw investments in lending tech driven by increasing per driving funding within capita income and the shift towards a cashless economy 8% FinTech 8% Driven by increasing adoption of digital payments & higher smartphone • 17% usage with lower data prices , the online shoppers’ population has been 9% on the rise Within ecommerce, as technological advancements & government Ecommerce driven by • 14% initiatives fuel the B2B segment , investors have been showing increasing increasing online interest in the sub - sector shoppers SaaS/AI Beyond urban markets, this sector has garnered investor attention due • Consumer app & platforms to increasing shoppers from non - metro cities Ecommerce & listing platforms The rise is fueled by the growing internet penetration in Tier II & Tier III • Consumer tech Manufacturing cities & an enhanced digital infrastructure , contributing to increased gaining traction Healthcare & Life Sciences consumption BFSI Note(s): *N here represents number of deals in CY23 Source(s): 1Lattice Deals Database © 1Lattice | 16 Top 10 investments in CY23 Top 10 investments in CY23 Amount Company City Sector Funding stage Key Investors (US$ M) Qatar Investment Authority, Abu Dhabi Mumbai 1,600* Retail Other Investment Authority 1,000 Mumbai Energy Other Brookfield Renewable GIC, Orix Corporation of Japan, Abu Dhabi Hyderabad Energy 700 O ther Investment Authority Ecommerce & listing Bengaluru 6 00 Walmart Late platforms Ecommerce & listing Gurgaon 500 Abu Dhabi Investment Authority O ther platforms WestBridge Capital,Alteria Capital - Venture Ecommerce & listing Bengaluru 400 Growth Debt Fund, Mirabilis Investment Trust, platforms Fireside Ventures, Sixth Sense Ventures Delhi BFSI 400 Growth MUFG, Sumitomo Mitsui Trust Bank Mumbai Energy 360 Other Brookfield Renewable Consumer app & Bengaluru Growth 350 General Atlantic platforms Ecommerce & listing Lightspeed Venture Partners and DST Bengaluru Growth 340 platforms Global Note(s): * In two successive rounds Source(s): 1Lattice Deals Database © 1Lattice | 17 Top 10 M&As* in CY23 Top 10 M&As* in CY23 Amount Acquired Company Sector Date Acquirer (US$ M) Healthcare & Life Feb 07, 2023 2,000 Sciences 1,110 May 11, 2023 BFSI 718 Jan 05, 2023 SaaS / AI Healthcare & Life 680 Dec 12, 2023 Sciences Healthcare & Life 657 July 28, 2023 Sciences Engineering & 605 Jan 12, 2023 Construction Apr 26, 2023 Energy 483 M anufacturing 456 Apr 13, 2023 Healthcare & Life 4 00 Aug 02, 2023 Sciences 3 60 Aug 21, 2023 Energy Note(s): *Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice Deals Database © 1Lattice | 18 Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Top 10 investments in Q4 CY23 Top 10 investments in Q4 CY23 Amount Company Sector Funding stage Key Investors (US$ M) 600 Ecommerce & listing platforms Late Walmart 597 Retail Late Abu Dhabi Investment Platform 340 Ecommerce & listing platforms Growth Lightspeed Venture Partners, DST Global Manufacturing 2 40 Debt SBI 176 T PG Growth IT Services Late U ndisclosed BFSI 1 45 D ebt Anthelion Capital, Mithril Capital (Peter Thiel's investment 135 SaaS / AI Growth firm), 3State Ventures, Blume Ventures Avenir growth capital, Lightspeed, Greenoaks Capital, 120 Growth Manufacturing Steadview , Footpath ventures, D1 capital BFSI 96 Other Paragon Partners, Temasek, Motilal Oswal Manufacturing 9 0 G rowth Infra.market Note(s): *Includes top M&A deals whose amounts were disclosed Source(s): 1Lattice Deals Database © 1Lattice | 20 Early - stage investments SaaS / AI received the highest funding of US$ 118M among early - stage investments Early - stage investments by sector Top 10 early - stage investments in Q4 CY23 (US$ M, Q4 CY23) Amount Company Sector Key Investors (US$ M) SaaS / AI 118 Lightspeed, Peak XV Partners, Khosla SaaS / AI 41 Ventures Ecommerce & listing platforms 85 23 BFSI Elevation capital, 3State Ventures BFSI 64 20 Manufacturing Panthera, Alteria Capital, xto10x Consumer app & Consumer app & platforms 18 49 Elevation Capital platforms Manufacturing 45 Varanium NexGen Fund, Riverwalk Holdings, BFSI 15 SMK Ventures, DMI Sparkle Fund, LC Nueva Healthcare & life sciences 32 Ecommerce & listing SWC Global , IvyCap Ventures Advisors 13 platforms Private Limited FMCG 6 Consumer app & Nexus Venture Partners, Stellaris Venture 13 platforms Partners Retail 4 Singularity Ventures, Three State Capital, PI BFSI 12 Opportunities Fund, 021 Capital Transportation & logistics 3 TDK Ventures, British International Investment, 3one4 Capital, Omnivore, Others include cloud SaaS / AI 12 IT services 2 Wavemaker Partners, Genting Ventures, The kitchen, water treatment startups, Yield Labs Asia Pacific laundry management Others 23 Healthcare & life MassMutual Ventures, Tanglin Venture services, etc. 11 sciences Partners, Endiya Partners Note(s): Early - stage investments include Pre - seed, Seed, Pre - series and Series A Source(s): 1Lattice Deals Database © 1Lattice | 21 Top early - stage investments Top funded early - stage startups with their competitors Company Description Competitors Developer of large language models Credit card for travel payments Manufacturer of electric bicycles Provider of consumer home loans Provider of consumer home loans Source(s): 1Lattice Deals Database © 1Lattice | 22 Growth - stage investments Ecommerce & listing sector dominated growth - stage investments with funding of US$ 1.1B Top 10 growth - stage investments in Q4 CY23 Growth - stage investments by sector (US$ M, Q4 CY23) Amount Company Sector Key Investors (US$ M) Ecommerce & listing platforms 1,101 Ecommerce & listing 600 Walmart platforms Manufacturing 248 Ecommerce & listing 340 Lightspeed Venture Partners, DST Global SaaS / AI 222 platforms Anthelion Capital, Mithril Capital, 3State BFSI 147 135 SaaS / AI Ventures, Blume Ventures Healthcare & Life Sciences 115 Manufacturing 90 Infra - Market Consumer app & platforms 91 Others 65 Finnest Mitsubishi UFJ Financial Group, BNP Paribas Energy 50 BFSI 60 Cardif , Beams VC, TVS Capital, Goldman Sachs Asset Management, Avataar Ventures Retail 29 Consumer app & platforms 60 Un - disclosed Engg. & Construction 18 Healthcare & Life Sciences 54 Norvest Venture Partners FMCG 12 Schroder Adveq , International Finance Corp, Others include cloud Ecommerce & listing Transportation and logistics 50 Chiratae Ventures, B Capital, British 11 kitchen, water platforms treatment startups, International Investment laundry management Others 70 services, etc. Investcorp , Qatar Investment Healthcare & Life Sciences 50 Authority,Tybourne Capital Management, SeaLink Capital Partners Note(s): Growth - stage investments include Series B, C, D and E Source(s): 1Lattice Deals Database © 1Lattice | 23 Top growth - stage investments Top funded growth - stage startups with their competitors Company Description Competitors E - commerce platform B2B e - commerce platform Warehouse robotics and automation company Manufactures ready mix concrete Platform offering shared kitchen solution for food businesses AI and cloud - based software for debt recovery solutions Source(s): 1Lattice Deals Database © 1Lattice | 24 Late - stage investment Late - stage investments were driven by the retail sector (US$ 597M) Late - stage investment, by sector Top late - stage investments in Q4 CY23 (US$ M, Q4 CY23) Amount Company Sector Key Investors (US$ M) Retail 597 Abu Dhabi Investment Retail 597 Authority IT services 176 Manufacturing 175 IT services 176 TPG Growth Transportation & 80 logistics Healthcare & life 23 sciences Avenir Growth Capital, Lightspeed, Greenoaks Capital, Ecommerce & listing Manufacturing 120 7 Steadview Capital, Footpath platforms Ventures, D1 Capital Note(s): Late - stage investments include Series F onwards Source(s): 1Lattice Deals Database © 1Lattice | 25 Top late - stage investments Top funded late - stage startups with their competitors Company Description Competitors Retail chain of convenience stores and supermarkets Provider of design, product development, and engineering services Online B2B platform providing manufacturing services Source(s): 1Lattice Deals Database © 1Lattice | 26 Tech investments Horizontal e - commerce attracted highest investments (US$ 602M), followed by B2B Ecommerce (US$ 400M), Automotive (US$ 240M) within tech investments for Q4 CY23 Top 10 tech investments in Q4 CY23 Tech investments by sector (US$ M, Q4 CY23) Amount Company Sector Key Investors (US$ M) Horizontal ecommerce 602 Ecommerce & listing 600 Walmart platforms B2B ecommerce 400 Ecommerce & listing 340 Lightspeed Venture Partners and DST Global platforms Automotive 240 Manufacturing 240 SBI NBFC 205 IT services 176 TPG growth EnterpriseTech 181 BFSI 145 Information not available PES 176 Anthelion Capital, Mithril Capital (Peter Thiel's Fintech 126 135 SaaS / AI investment firm), 3State Ventures, and Blume Ventures Logistics services 120 Transportation and 80 Ontario Teachers’ Venture Growth logistics HealthTech 77 Others include Mitsubishi UFJ Financial Group, BNP Paribas Cardif , ConstructionTech, BFSI 60 Beams VC, TVS Capital, Goldman Sachs Asset FoodTech, InsuranceTech 60 Management, Avataar Ventures SpaceTech & more Consumer app & 60 Undisclosed Others 119 platforms Ecommerce & listing Schroder Adveq , International Finance Corp, Chiratae 50 platforms Ventures, B Capital, British International Investment Source(s): 1Lattice Deals Database © 1Lattice | 27 Agenda Deal landscape in Q4 CY23 Key deals and investment themes Key investors Active investors Most active investors of Q4 CY23 Early - stage investors Growth - stage investors (# deals) (# deals) 6 4 5 2 4 2 3 3 2 3 2 3 2 3 Source(s): 1Lattice Deals Database © 1Lattice | 29 Active early-stage investors Most active early-stage investors and their investment segments in Q4 CY23 Consumer Ecommerce Transport & 1 app & Investors SaaS / AI Manufacturing FMCG BFSI Others & listing logistics platforms - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - - Note(s): 1.Includes BaaS and battery recycling companies Source(s): 1Lattice Deals Database © 1Lattice | 30 Active growth - stage investors Most active growth - stage investors and their investment segments in Q4 CY23 Investors E - commerce & listing SaaS / AI Manufacturing BFSI - - - - - - - - - - - - - Source(s): 1Lattice Deals Database © 1Lattice | 31 We are here for you Let us know how we can meet your business requirement? Roma Dixit Director, Insights and Consulting For media queries, please contact Vaishnav Kumar Rai Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1L att ice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Latt ice , if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best dat a we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the sam e before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available info rma tion and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant inf ormation available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing conta ine d here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its busines s, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affi lia tes, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible f or any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1La ttice does not hold any liability in connection therewith. +91 987 390 5272 roma.dixit@1lattice.com Delhi NCR | Mumbai | Bengaluru | UAE | KSA | Singapore