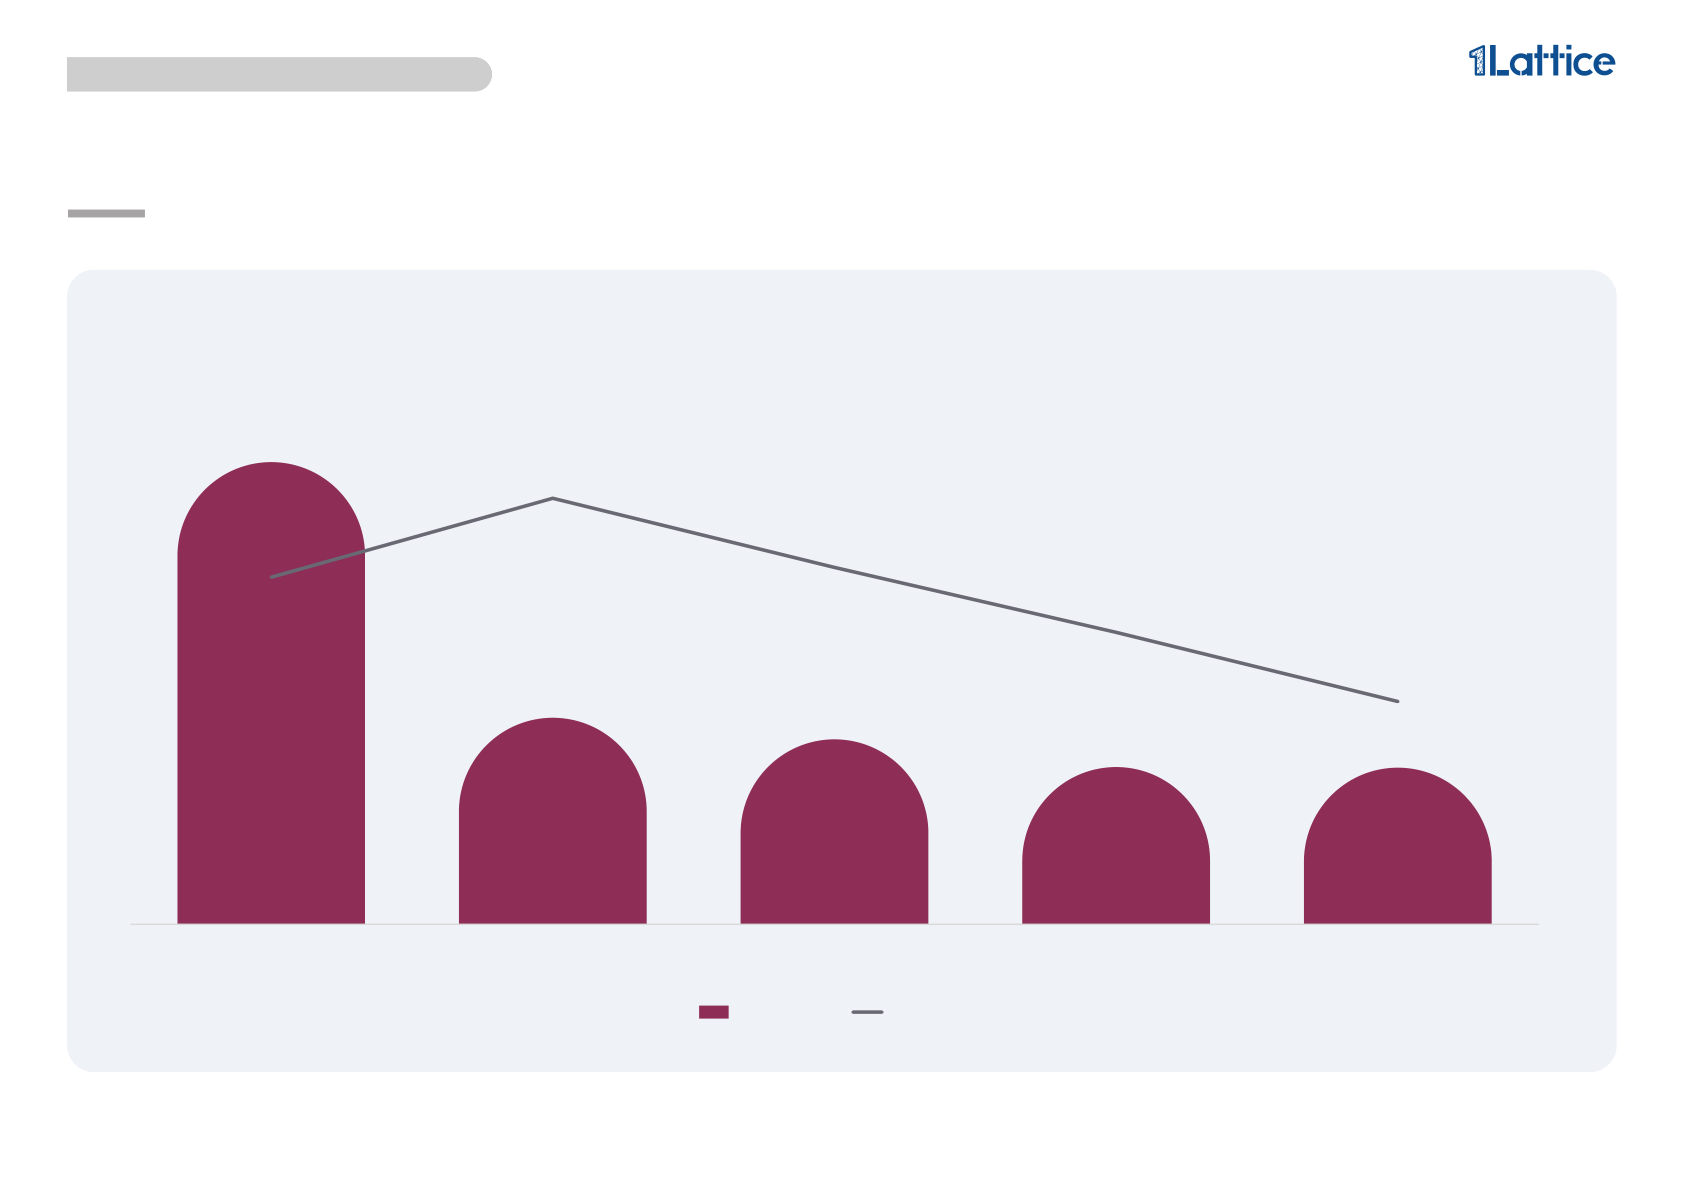
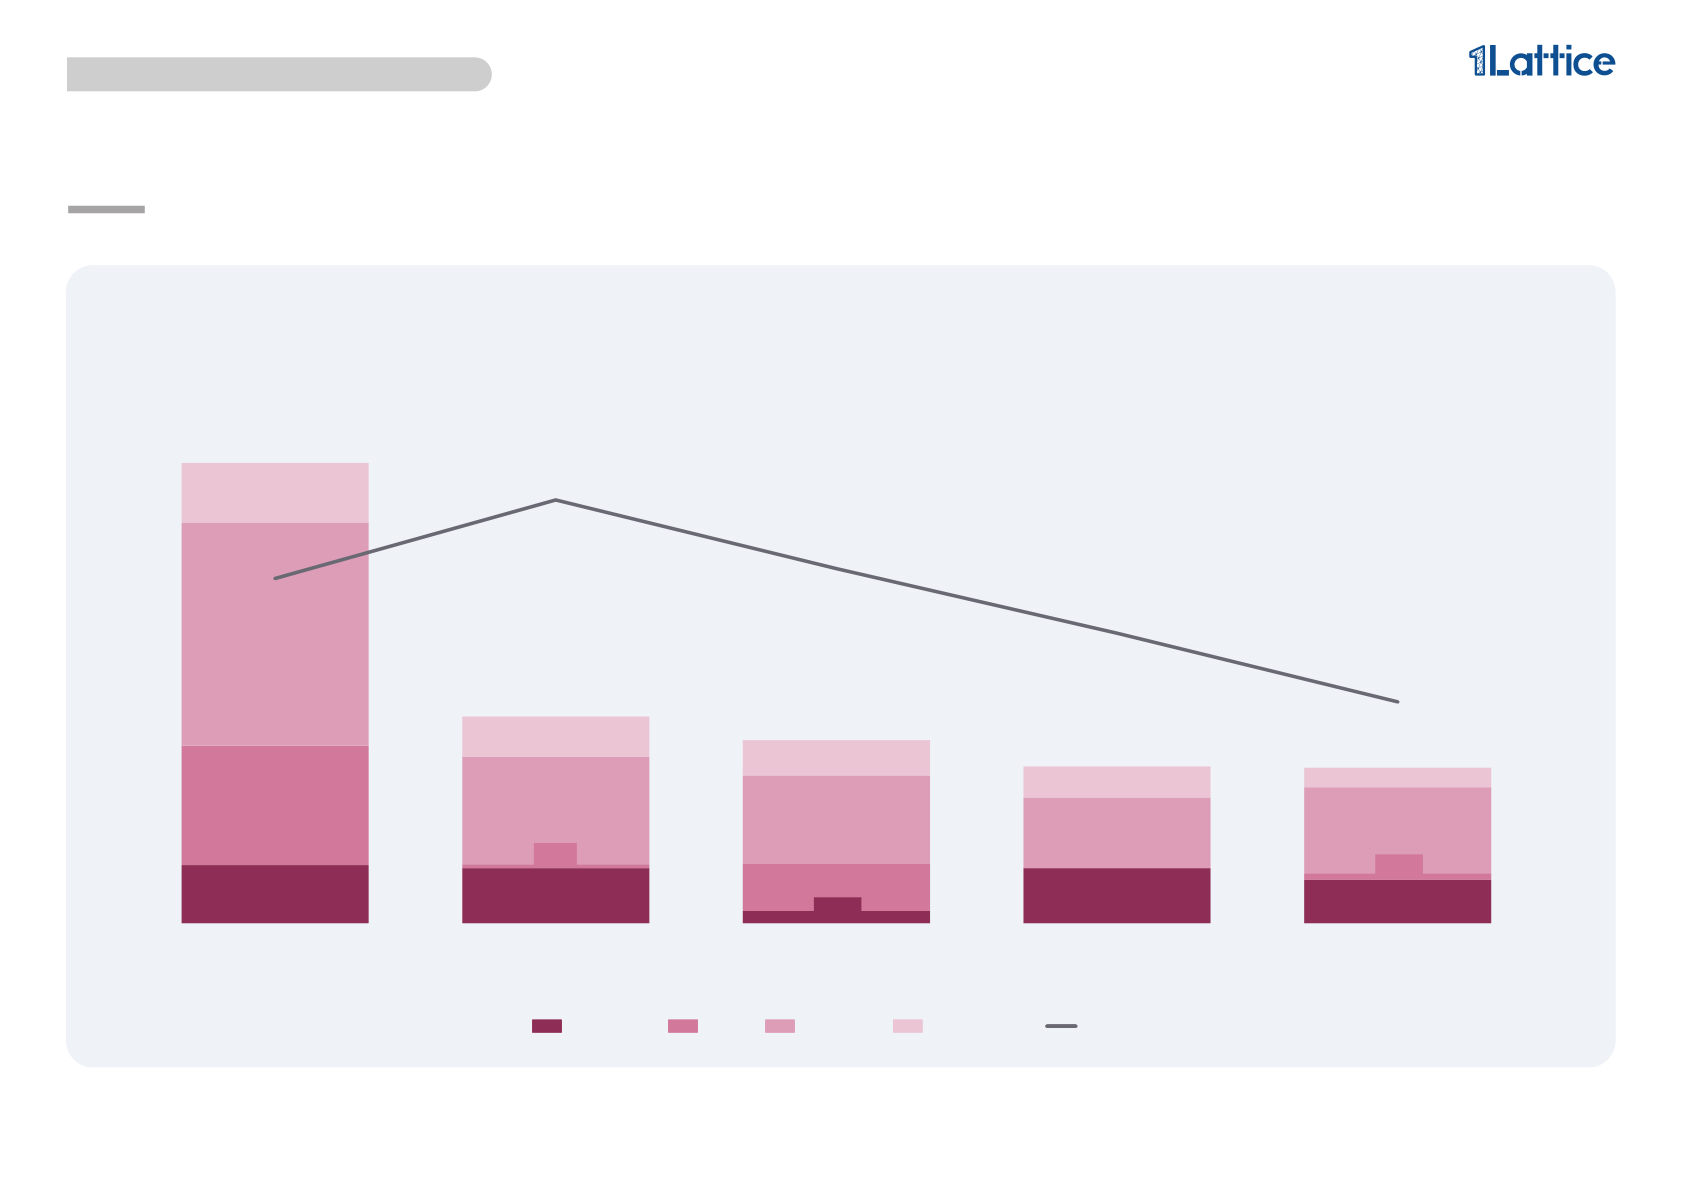
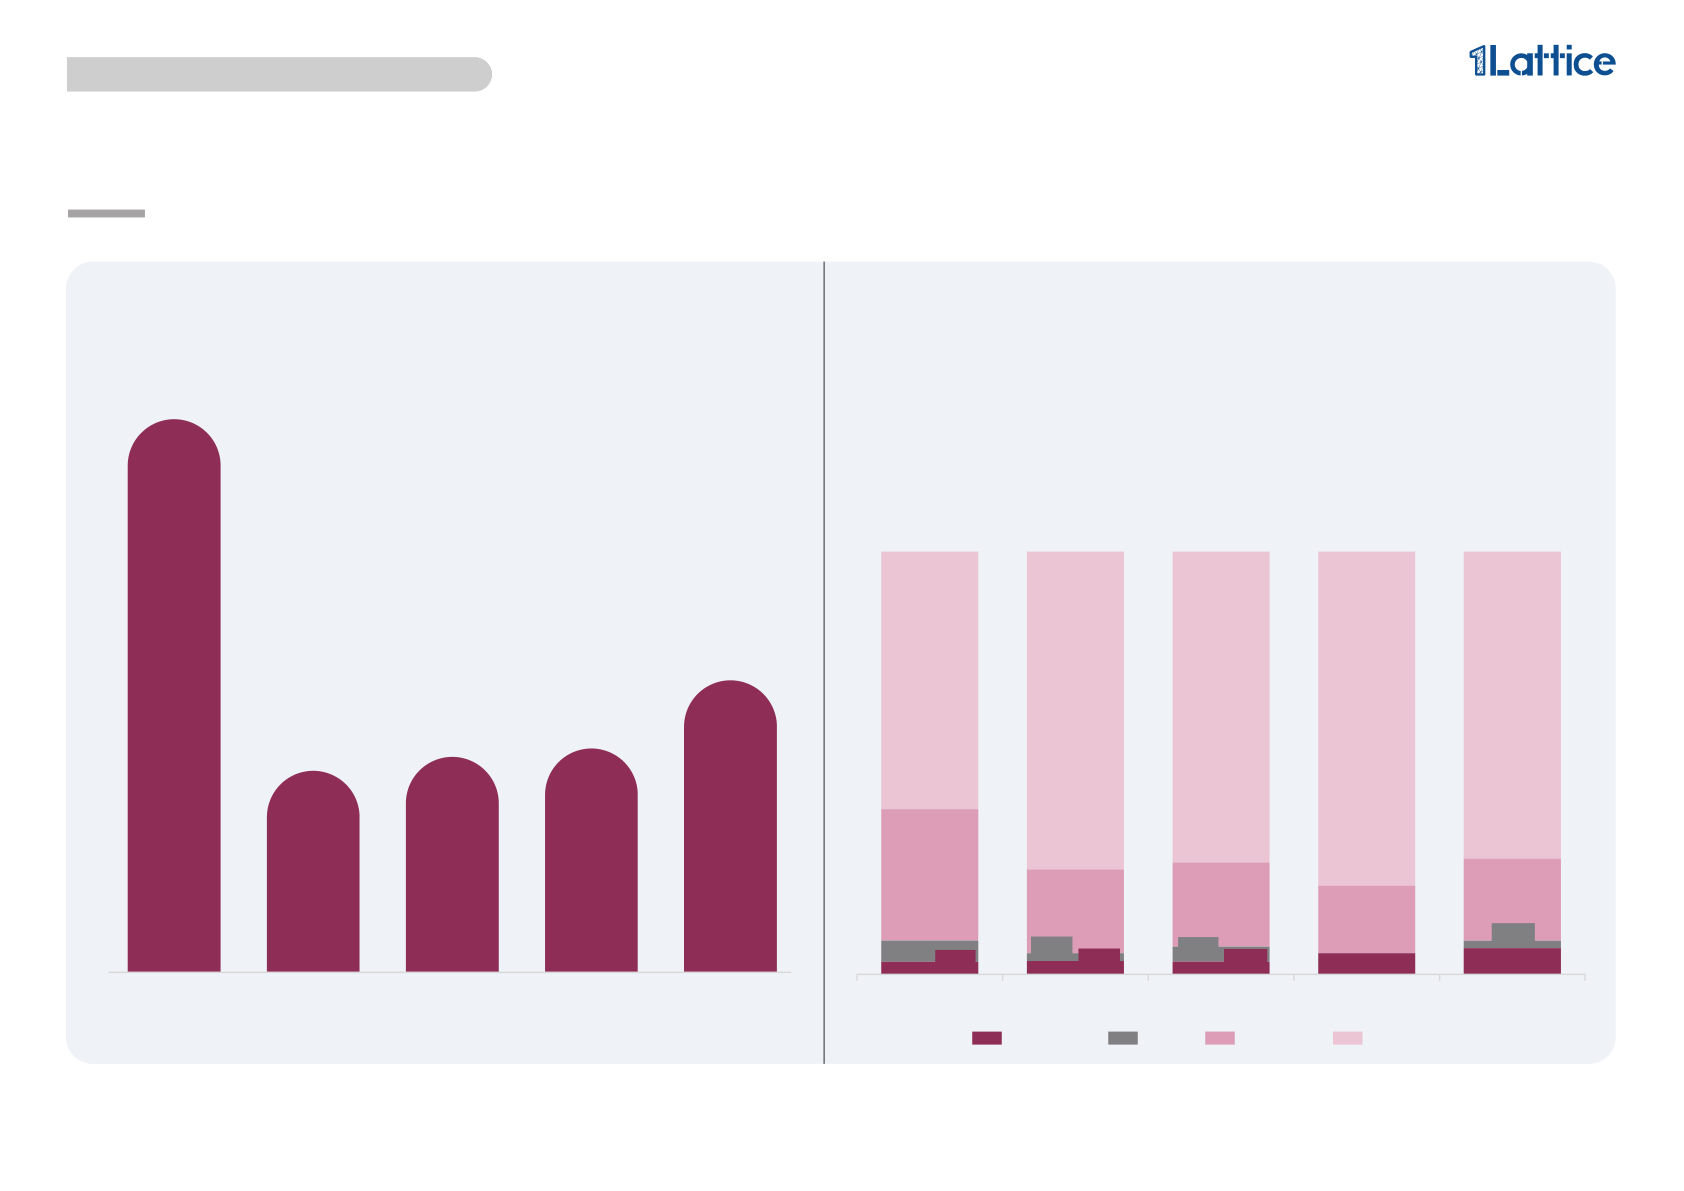
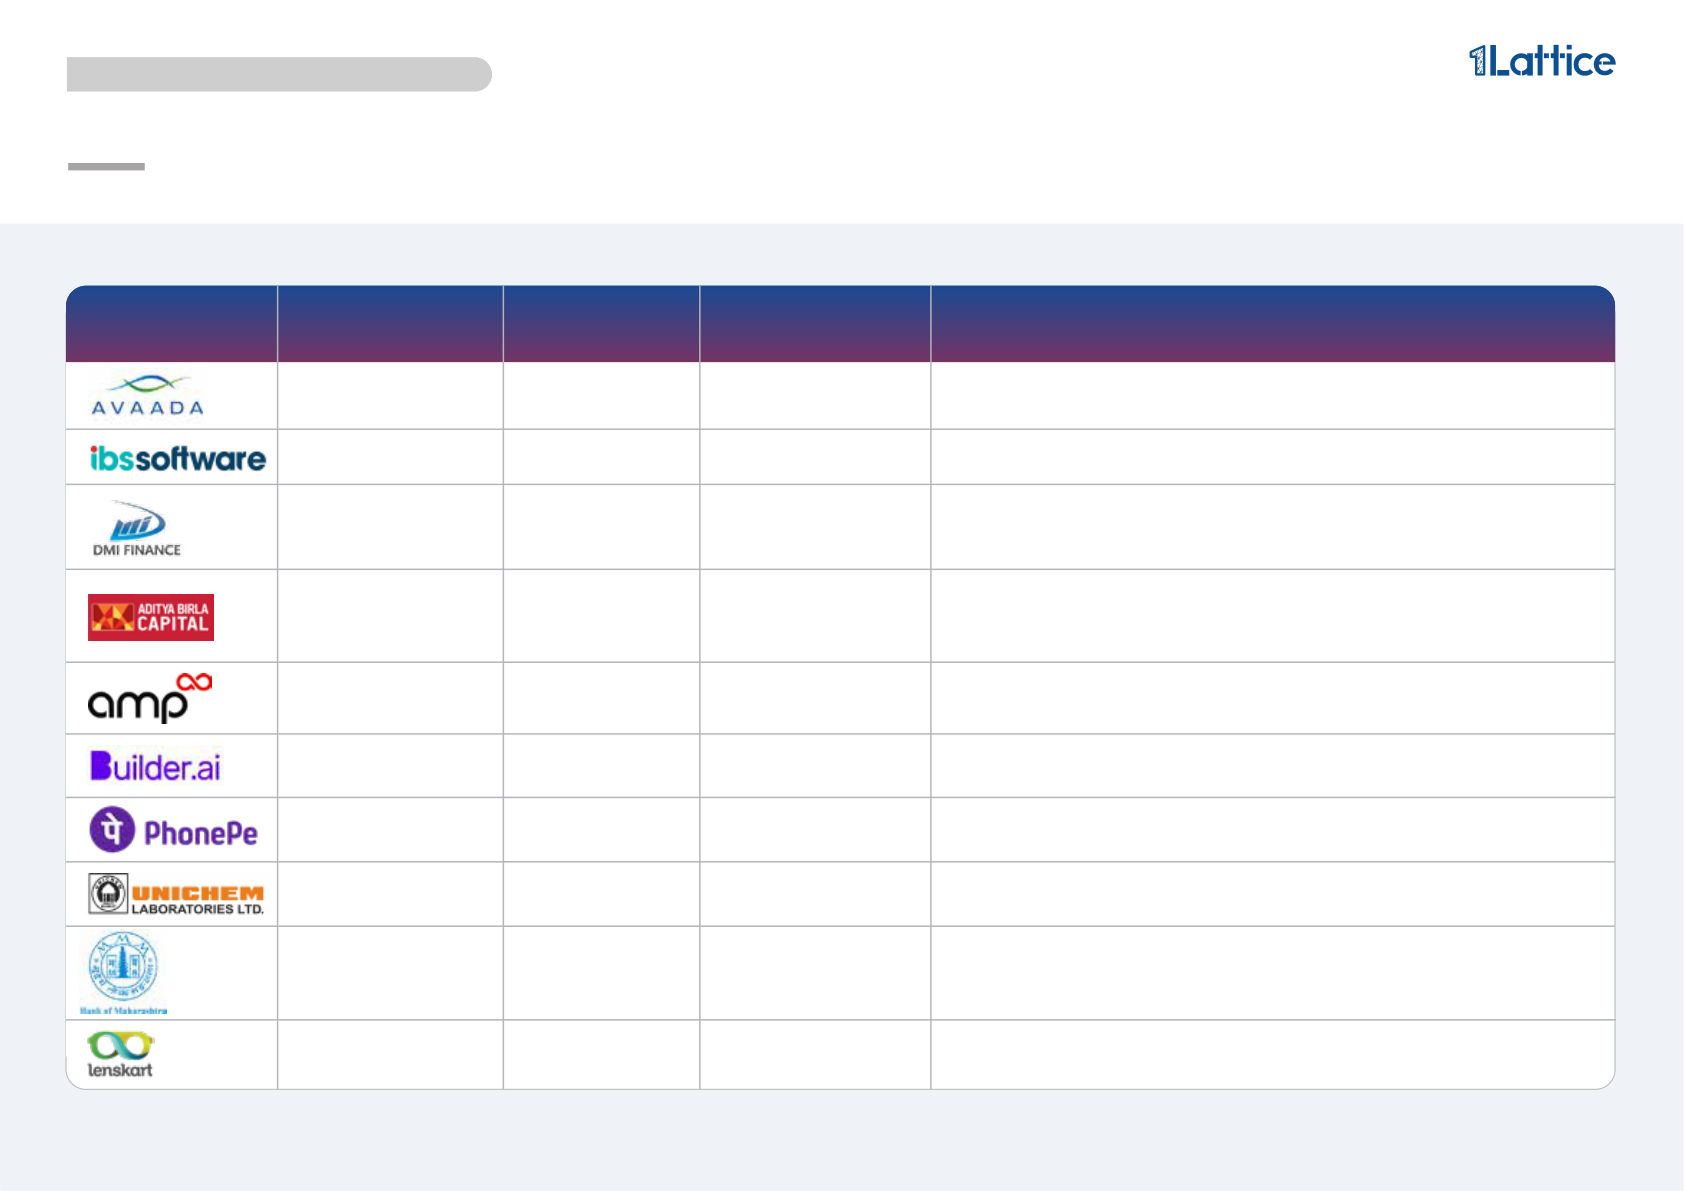
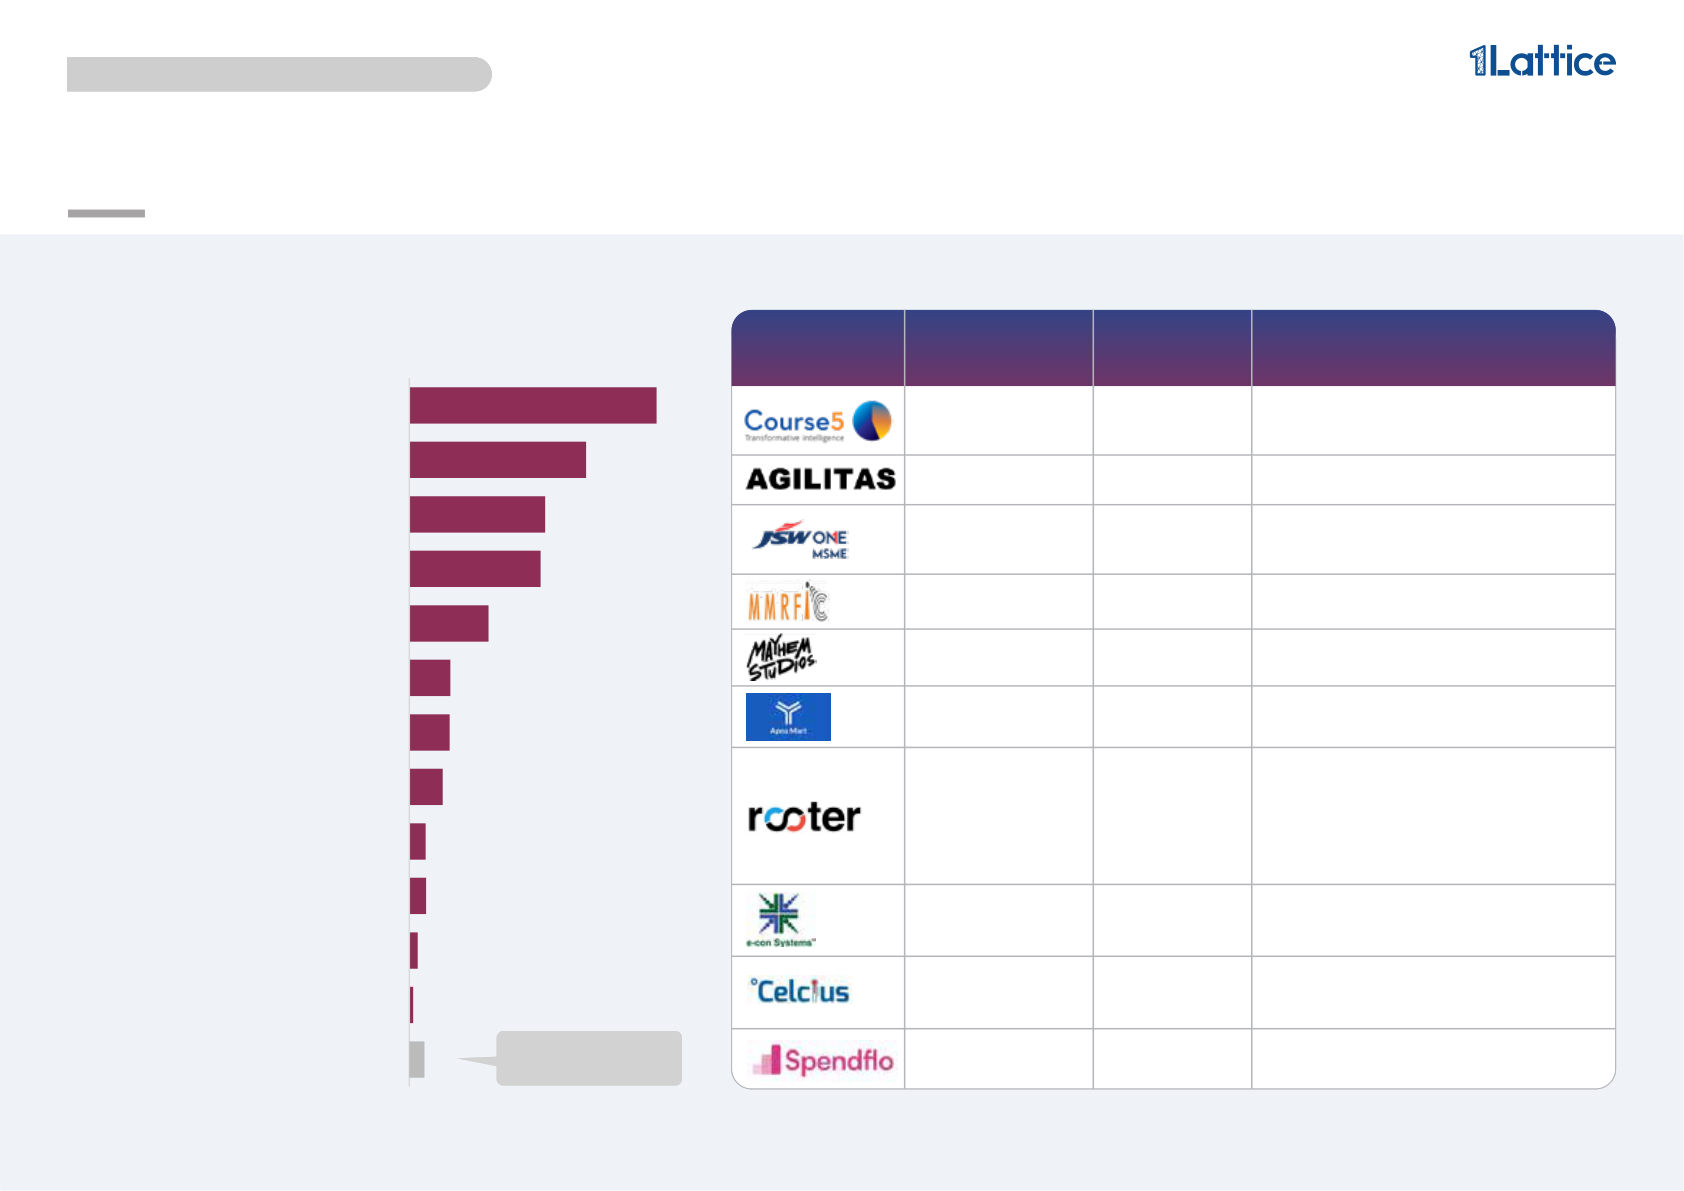
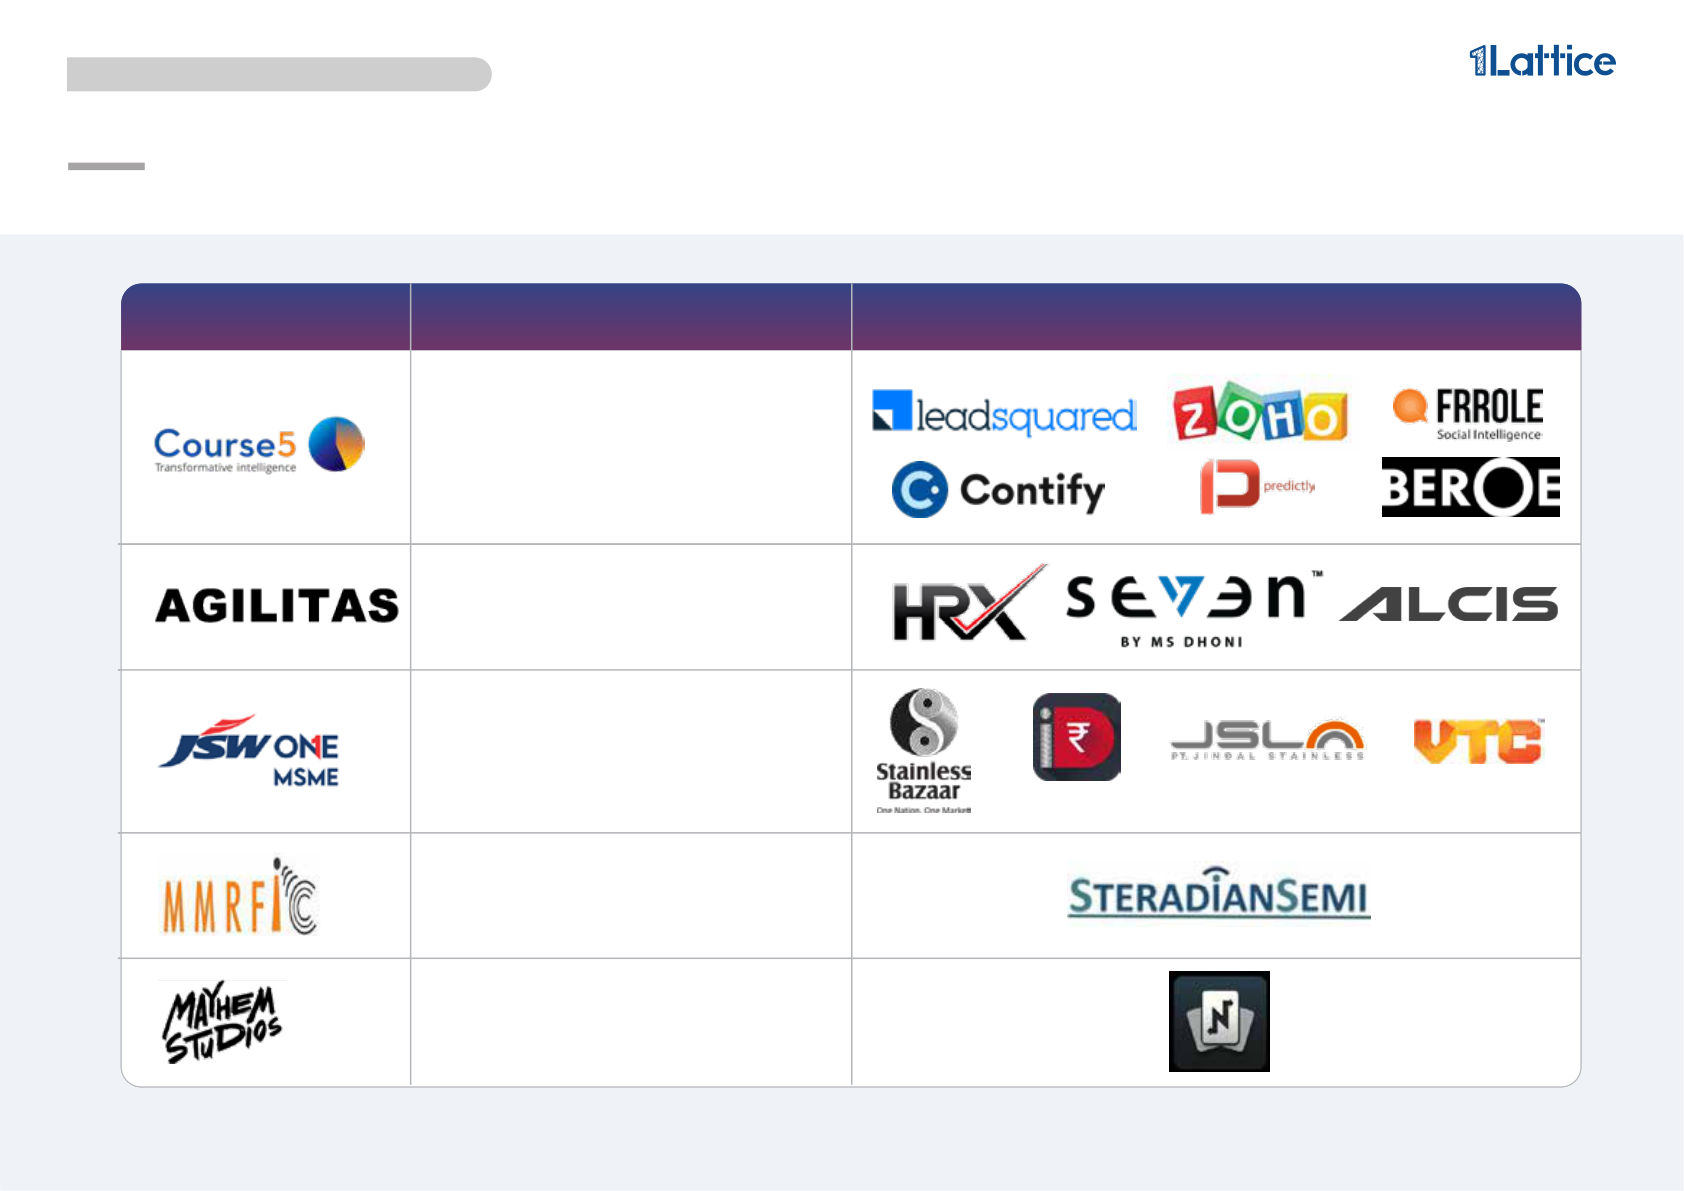
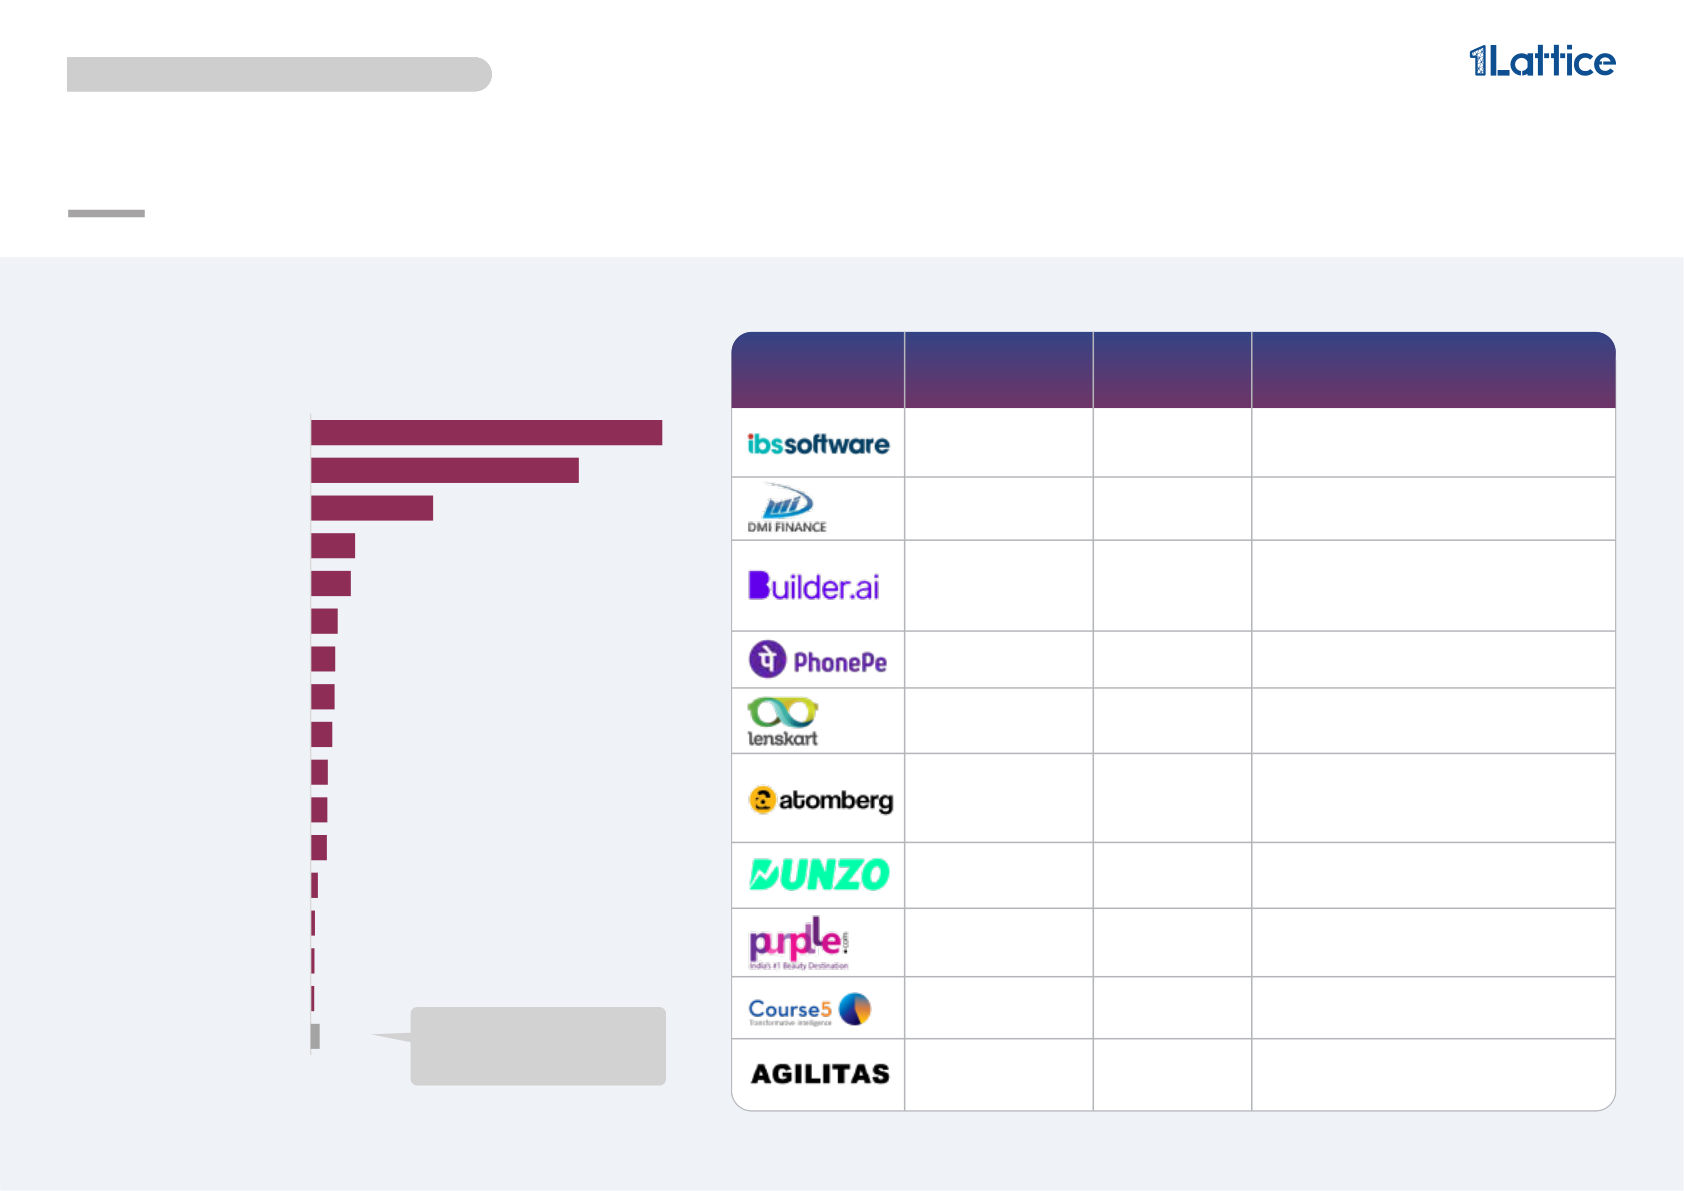
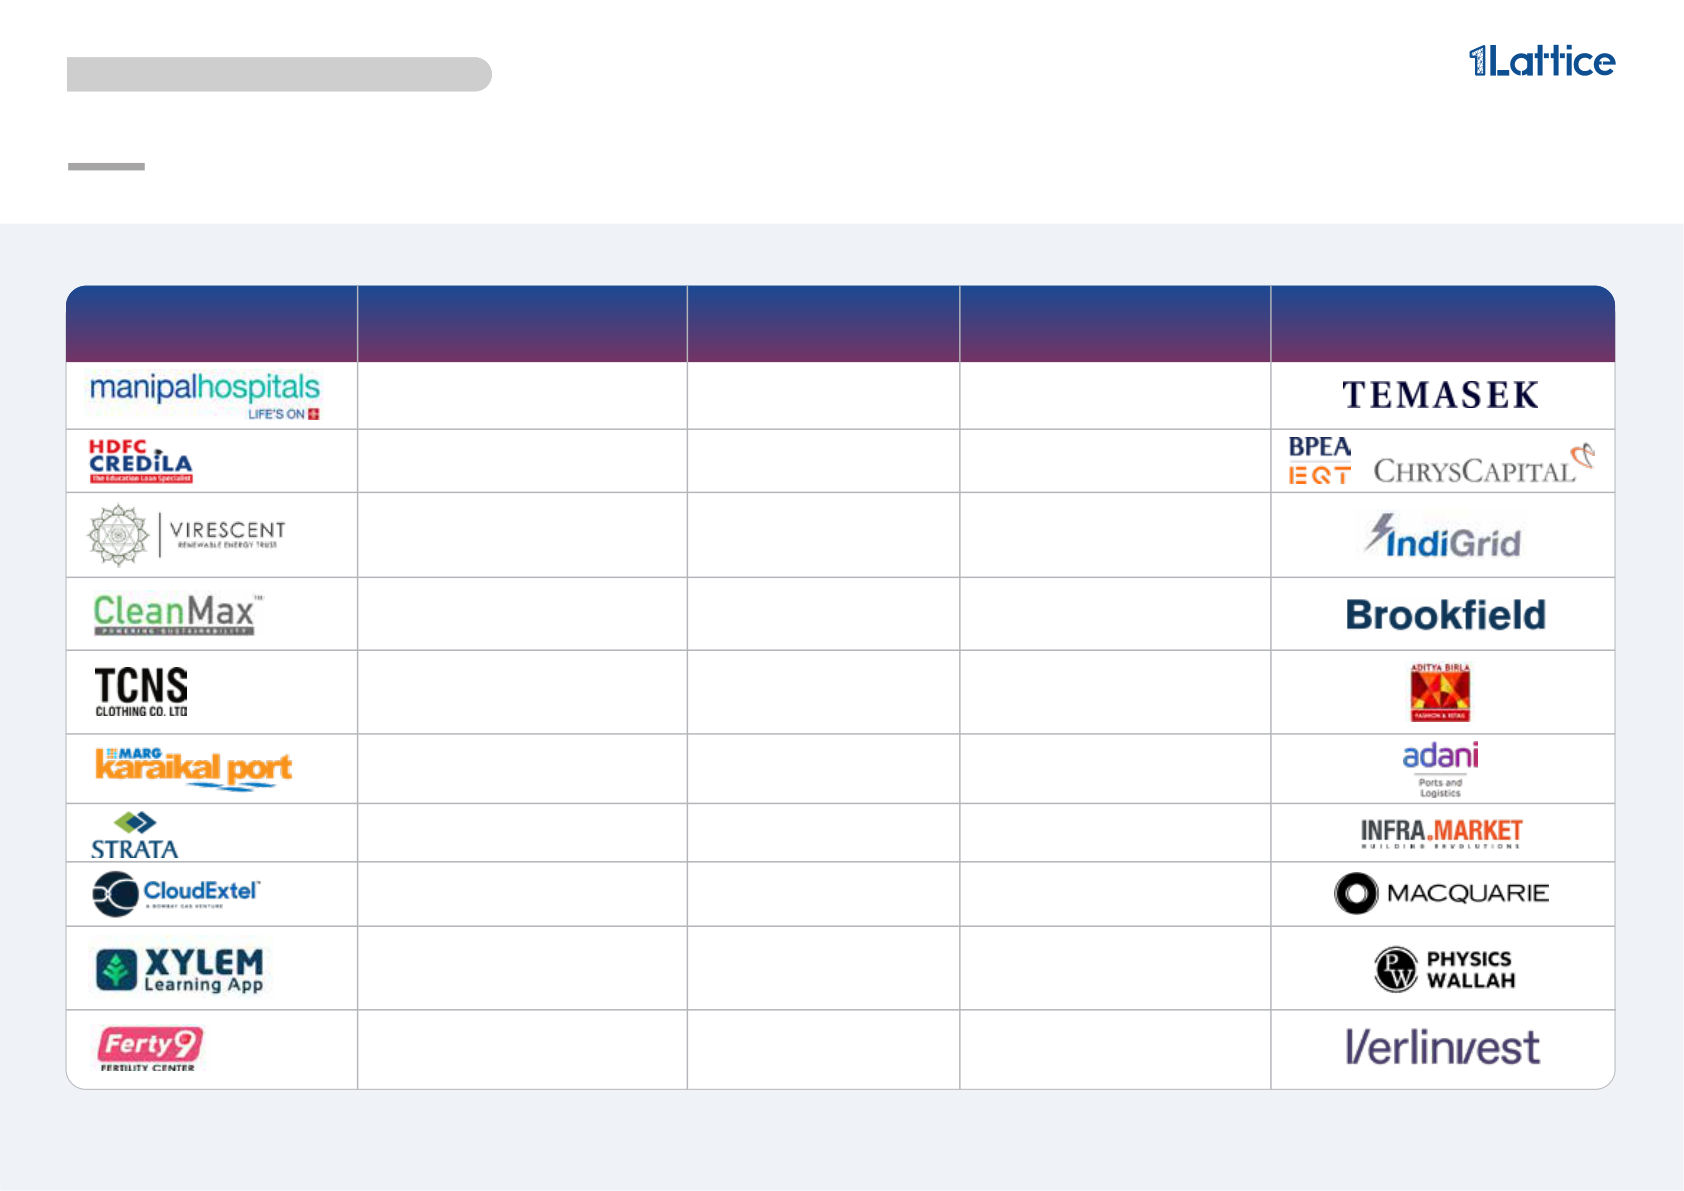
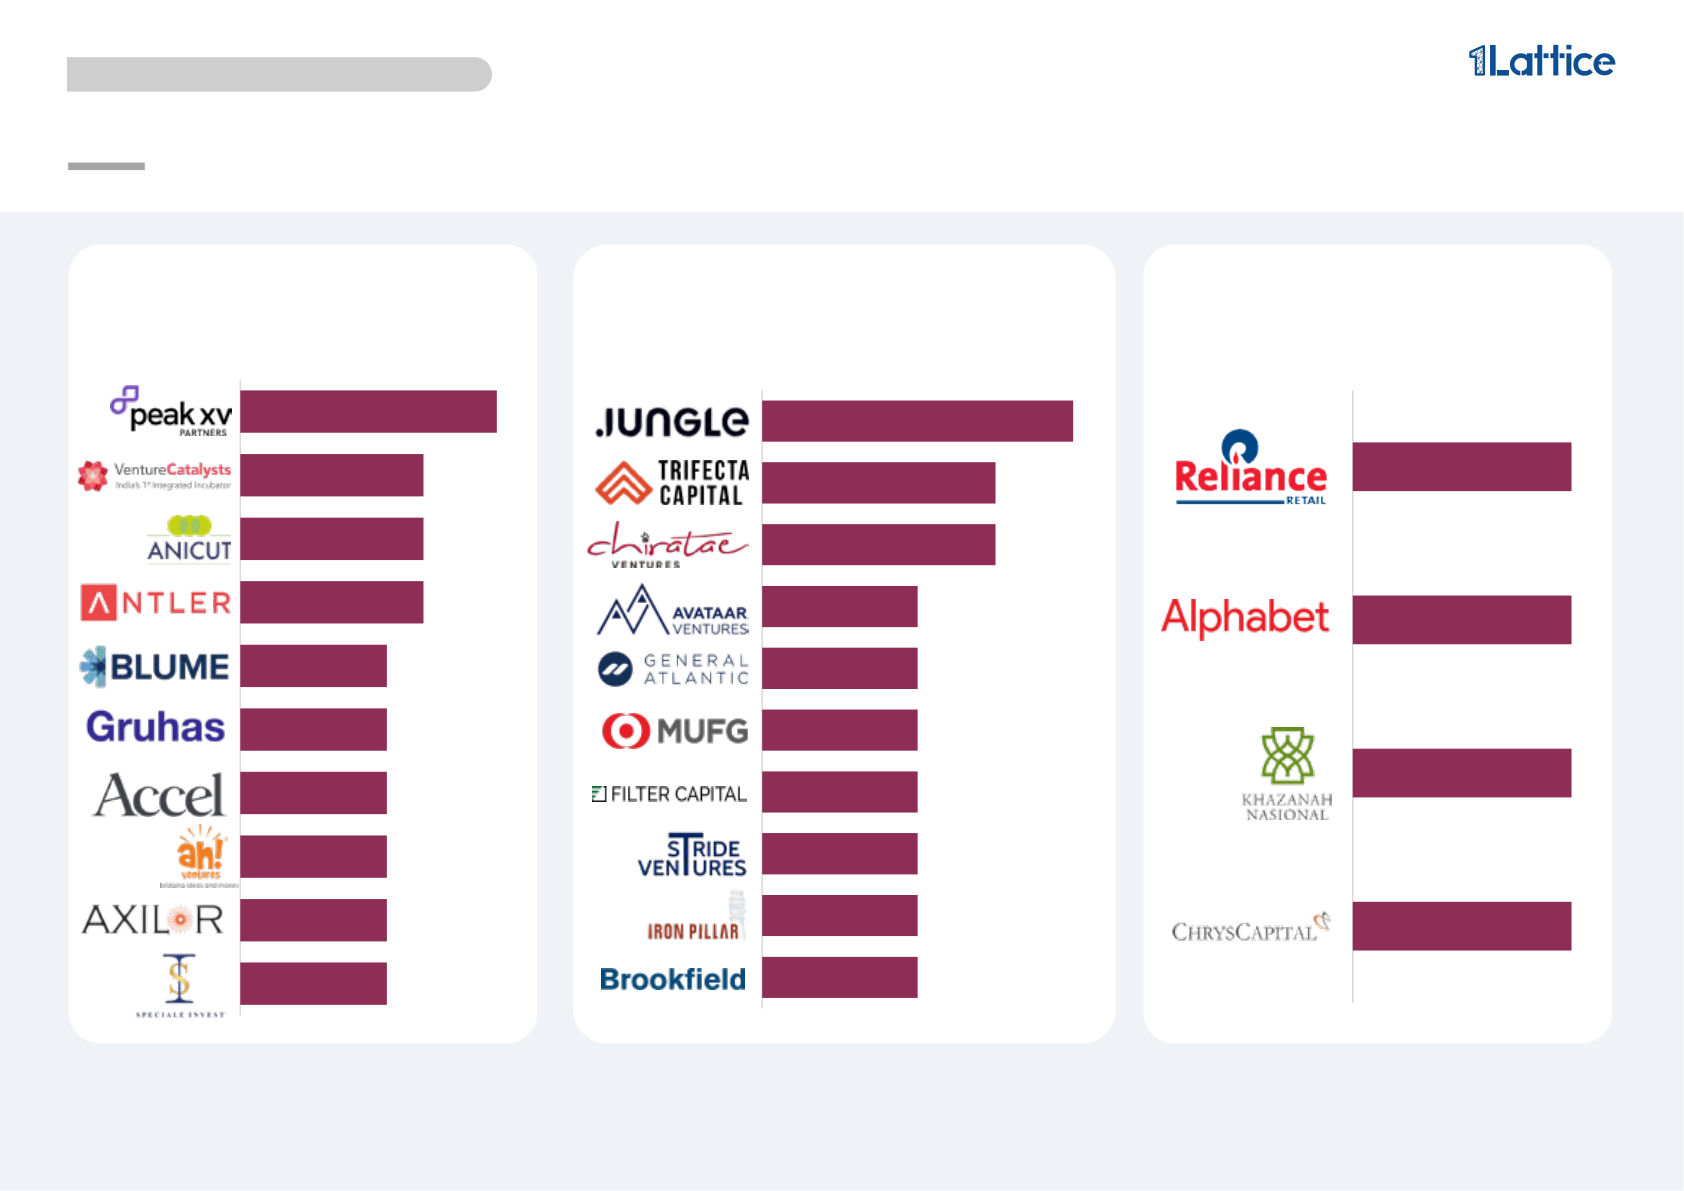
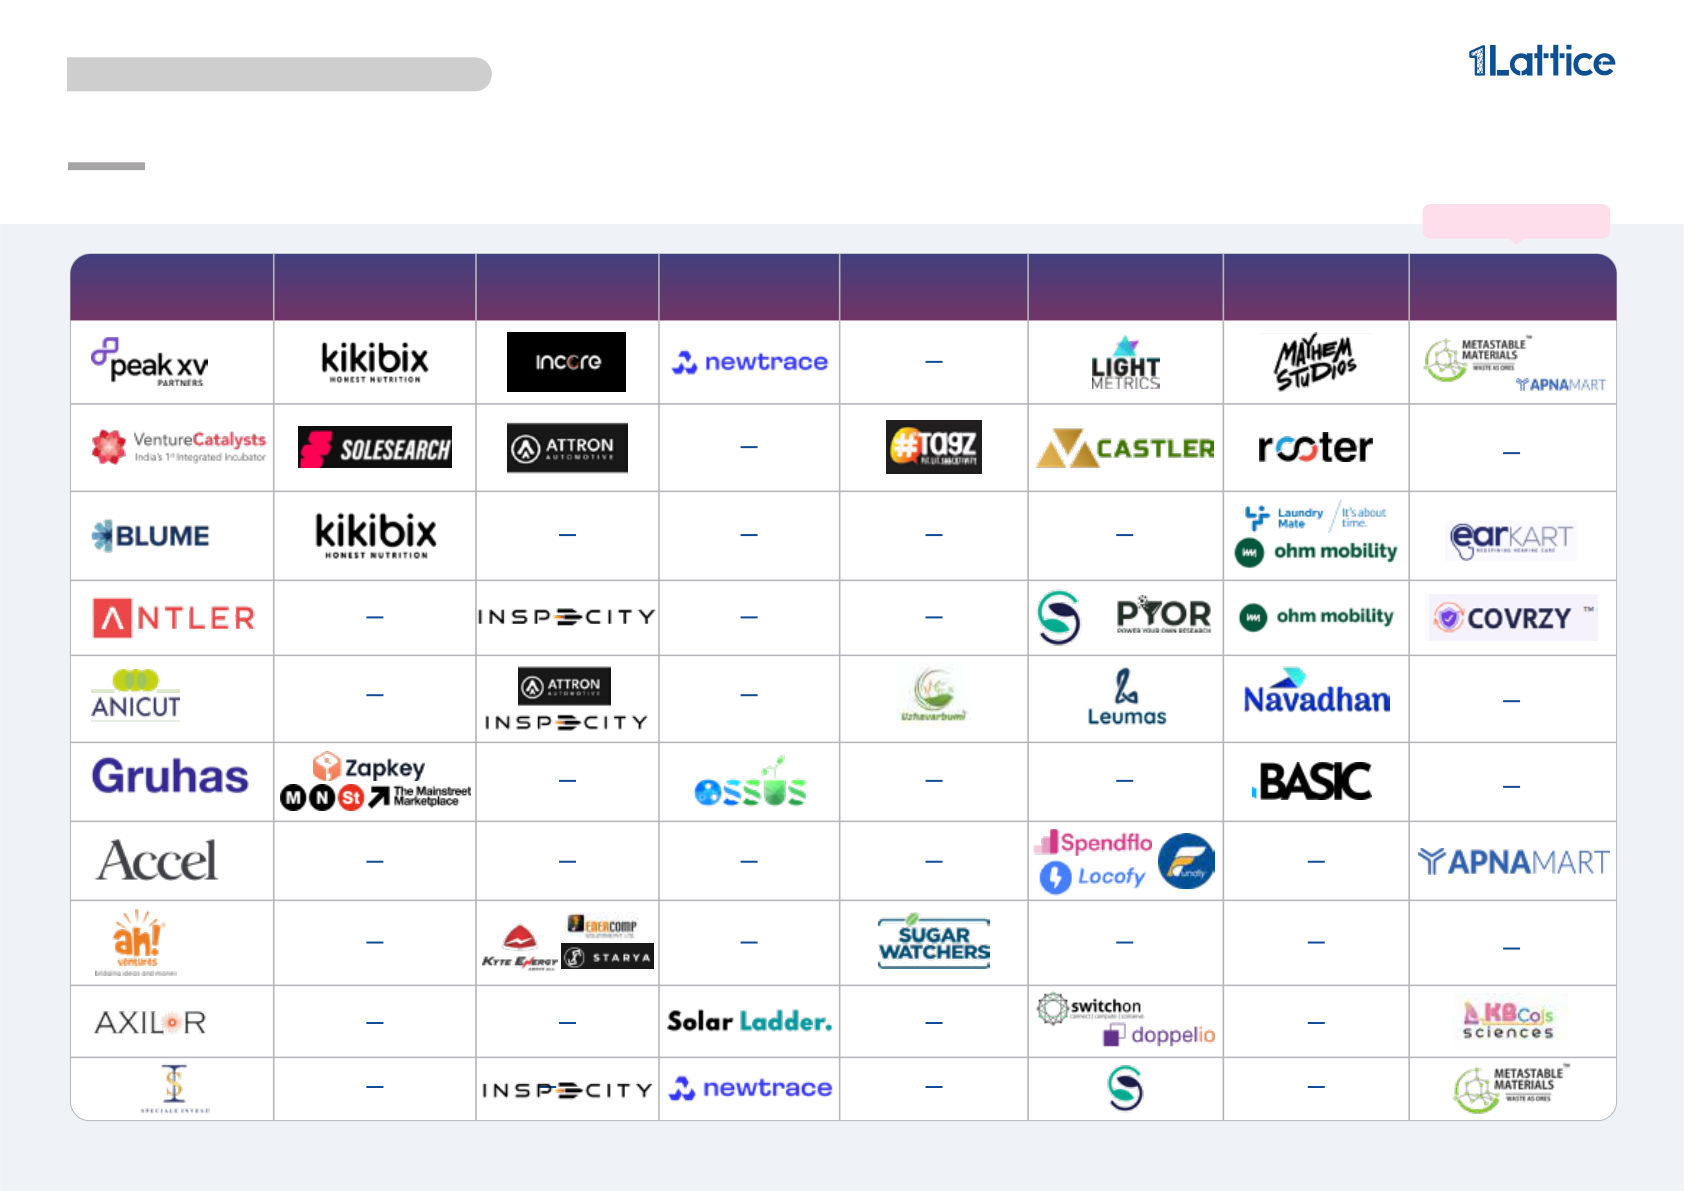
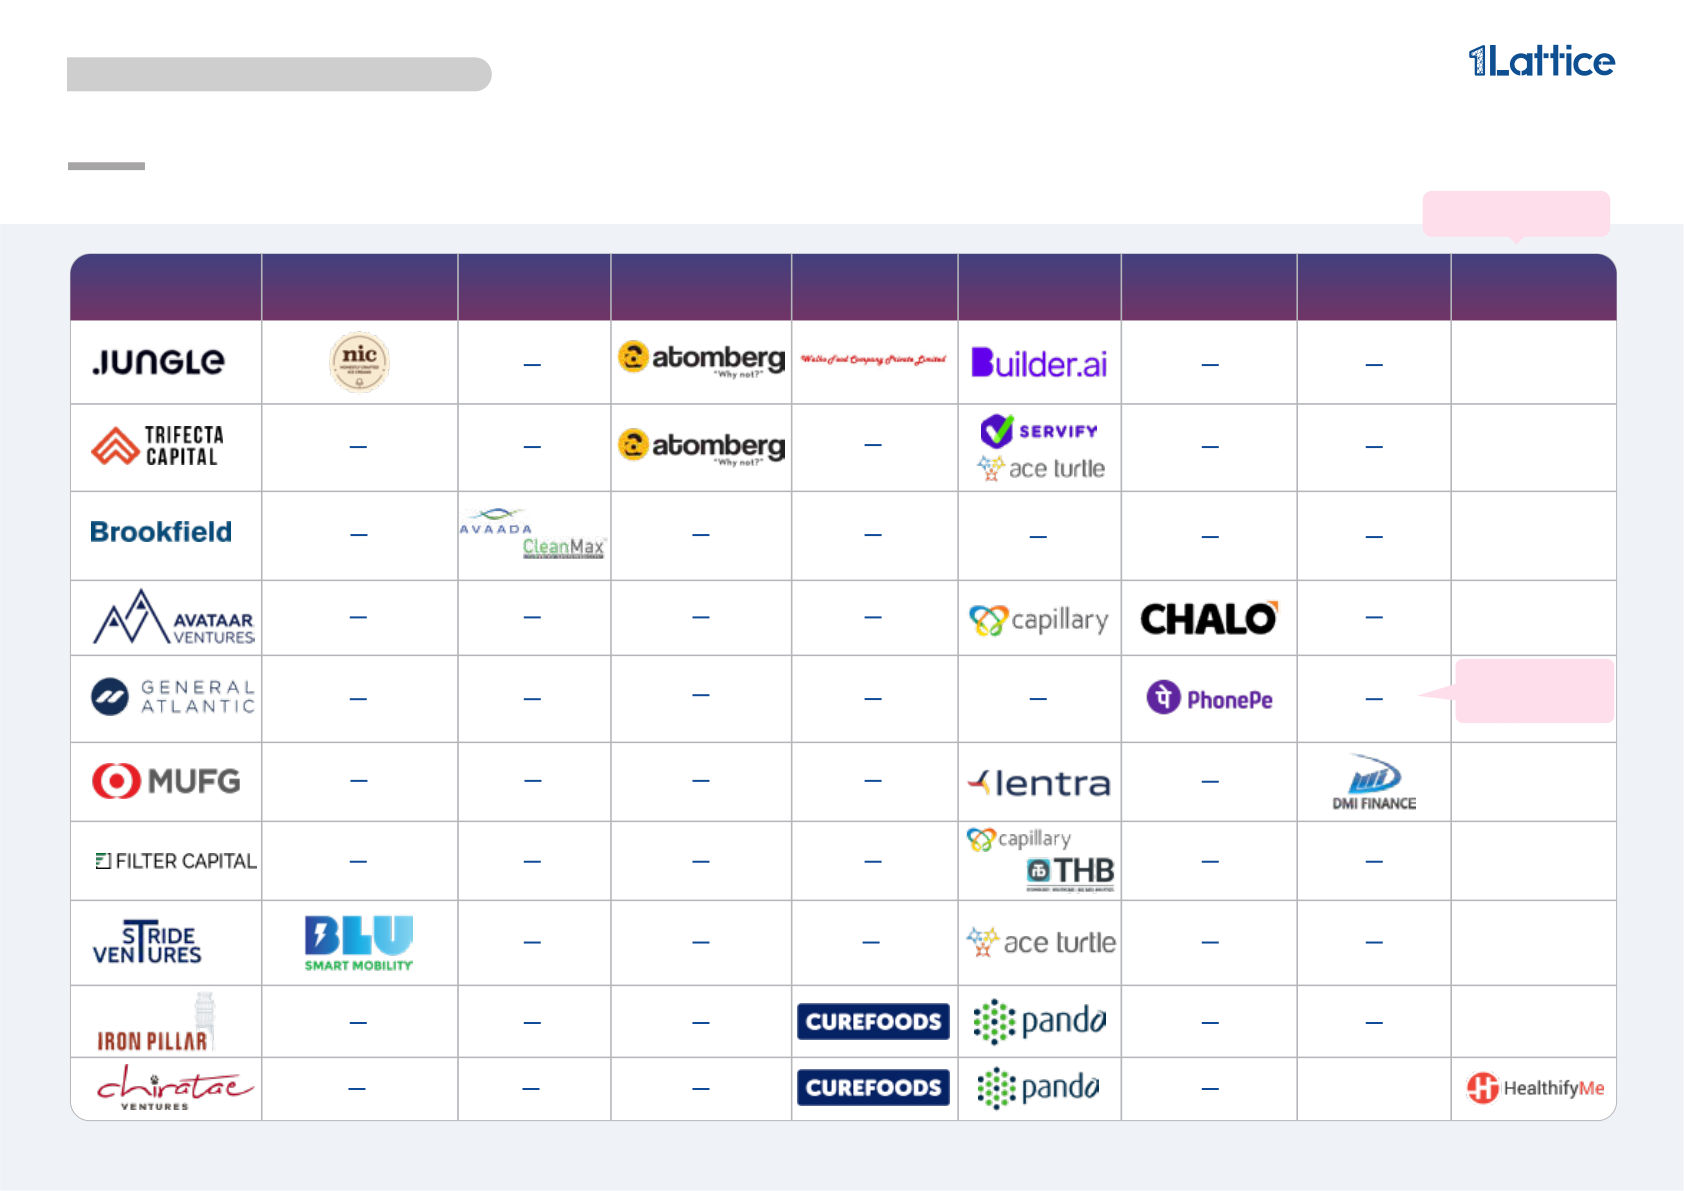
DEAL PULSE REPORT INDIA Q2 CY23 August 2023 @Lattice Technologies Pvt. Ltd. India has emerged as an attractive witnessed several successful exits from Foreword destination for growth-stage early-stage startups over the last few investments in recent times due to a years and this trend is expected to rapidly growing Indian economy, continue with early-stage startups favorable regulatory environment, seeing higher traction w.r.t to deals vibrant start-up ecosystem along with volume as compared to other stage technological advancements and investments. potential for scalability. In the second This report aims to uncover some of the quarter of the calendar year 2023, key trends during the second quarter of startups in India secured ~US$ 5.1B the calendar year 2023. At 1Lattice, we across 226 deals, spanning from seed hold an optimistic outlook, believing to late stages. Over the years, India has that this report will provide valuable also witnessed remarkable growth in insights. We eagerly anticipate the the number of unicorns, escalating from opportunity to engage in an open merely 8 in 2018 to an impressive 108 by dialogue with our partners across May 2023. diverse industries, as we exchange Projections indicate that by 2026, India notes and delve deeper into these will position itself as the third largest matters while closely monitoring the economy worldwide, boasting a evolving situation. substantial GDP of US$ 5T. India has Roma Dixit Director, Financial Investors We support investors & brands through the deal & fund cycle Pre-deal: Prospect better Deal: Understand opportunities Post-deal: Portfolio monitoring & be prepared & risks better & benchmarks • Expert calls (SME, Industry • Commercial DD (market • Brand tracks, brand assessment experts – self or 1Lattice led) assessment, comp landscape, (NPS/CSAT tracks, voice of value prop validation, customer & customer sentiment, reviews) • Market landscape (existing stakeholder NPS) offerings, whitespaces, market • Portfolio monitoring (Monitoring sizing, target attractiveness) • Supply chain diligence Dashboard) (scalability, performance • Micro market assessment • Social & digital listening (UI/UX monitoring, network strength) assessment, web scrapes) • Customer segmentation • Integrity/culture assessment (personas, forward trends) • Marketing & campaign evaluation (primary feedback on (validation, feedback) management, sustainability • Market expansion strategy (new product categories and markets) © 1Lattice | 03 Key Takeaways Startups raised ~US$ 5.1B across 226 deals (early to late stages) in Q2 CY23, signaling a slowdown in amount of -66% & # volume (-36%) as compared to Q2 CY22 Investments in all stages experienced a significant decline, with growth stage suffering the largest drop in absolute terms (~US$ -4.5B), while late stage fell the most in % terms (-94%) Avg deal size fell by ~47% to ~US$ 22.5M as compared to Q2 CY22 (~US$ 42.6M), while early-stage deal volume increased to ~75% from ~61% in the same period SaaS / AI was the most attractive sector for early-stage investments with funding of ~US$ 167M followed by consumer apps & platforms; Course5 received the highest funding of ~US$ 53M Energy sector dominated growth-stage investments with funding of ~US$ 1,250M; Avaada received highest funding in the Energy space (~US$ 1,000M) Majority of late-stage investments came from e-commerce & listing platforms (~US$ 184M); Lenskart received the highest funding of ~US$ 100M in Q2 CY23 Enterprise tech attracted highest investments (~US$ 980M), followed by Fintech (~US$ 745M) and Retail tech (US$ 340M) within tech investments for Q2 CY23 © 1Lattice | 03 Agenda Deal landscape in Q2 CY23 in India Key deals and investment themes Key investors Investment amount and # deals ~US$ 5.1B was raised in India across 226 deals (early to late stages) in Q2 CY23, signaling a ~US$ 5.1B was raised in India across 226 deals (early to late stages) in Q2 CY23, signaling a slowdown in $ value (-66%) & # volume (-36%) as compared to Q2 CY22 slowdown in $ value (-66%) & # volume (-36%) as compared to Q2 CY22 Investment amount (US$ B) and # deals (Q2 CY22 – Q2 CY23) 432 362 352 296 226 15.0 6.7 6.0 5.1 5.1 Q2 CY 22 Q3 CY22 Q4 CY22 Q1 CY23 Q2 CY23 Amount Deals Note(s): Chart includes early (Pre-seed, seed, pre-series and Series A), growth (Series B, C, D and E), and late (Series F onwards) stage investments, PIPE © 1Lattice | 06 Source(s): 1Lattice Deals Database Stage-wise investments Investments in all stages experienced a significant decline, with growth stage suffering the largest drop in absolute terms (~US$ -4.5B), while late stage fell the most in % terms (-94%) Investment amount (US$ B) and # deals (Q2 CY22 – Q2 CY23) 432 1.9 362 352 296 7.3 226 1.3 1.2 0.6 1.0 3.9 3.5 2.9 2.8 2.3 0.1 0.2 1.5 1.9 1.8 1.8 1.4 0.4 Q2 CY 22 Q3 CY 22 Q4 CY22 Q1 CY23 Q2 CY23 Others* Others* Late Late Growth Growth Early Early Deals Deals Note(s): Stage of investment here is decided by the round of investment. Pre-seed, seed, pre-series and Series A are classified as Early, Series B, C, D and E are classified as Growth, and Series F onwards are classified as Late. Others © 1Lattice | 07 include deals with undisclosed round, PIPE, etc. Source(s): 1Lattice Deals Database Average deal size Avg deal size fell by ~47% to ~US$ 22.5M compared to Q2 CY22 (~US$ 42.6M), while Avg deal size fell by ~47% to ~US$ 22.5M compared to Q2 CY22 (~US$ 42.6M), while early-stage deal volume increased to ~73% from ~61% in the same period early-stage deal volume increased to ~73% from ~61% in the same period Average deal size Deal volume by stage (US$ M, Q2 CY22 – Q2 CY23) (%, Q2 CY22 – Q2 CY23) 42.6 352 432 362 296 226 22.5 61% 73% 73% 76% 79% 17.2 16.6 15.5 31% 19% 20% 20% 16% 2% 5% 2% 4% 6% 3% 3% 3% 5% Q2 CY 22 Q3 CY 22 Q4 CY22 Q1 CY23 Q2 CY23 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 Q2 CY23 Others* Late Growth Early Note(s): Stage of investment here is decided by the round of investment. Pre-seed, seed, pre-series and Series A are classified as Early, Series B, C, D and E are classified as Growth, and Series F onwards are classified as Late. Others © 1Lattice | 08 include deals with undisclosed round, PIPE, etc. Source(s): 1Lattice Deals Database Agenda Deal landscape in Q2 CY23 in India Key deals and investment themes Key investors Top 10 investments Top 10 investments in Q2 CY23 Top 10 investments in Q2 CY23 Amount Company Sector Funding stage Key Investors Key Investors (US$ M) Energy 1,000 Growth Brookfield Renewable SaaS / AI 450 Private Equity Apax MUFG, Sumitomo Mitsui Trust Bank BFSI 400 Growth BlackRock, Capital Group, Norges Bank, RBC Royal Bank, M&G, BFSI 366 PIPE Abu Dhabi Investment Authority, MIT, PSP Investments, SBI Life Insurance SMBC Bank of Japan, ICG, AIIB Energy 250 Growth Qatar Investment Authority (QIA), Jungle Ventures, Iconiq SaaS / AI 250 Growth Capital, Insight Partners Consumer app & 200 Growth General Atlantic platforms Healthcare & Life 126 PIPE Ipca Sciences BFSI 121 PIPE Undisclosed Ecommerce & listing ChrysCapital 100 Late platforms Source(s): 1Lattice Deals Database © 1Lattice | 10 Early-stage investments SaaS / AI was the most attractive sector with funding of ~US$ 167M followed by consumer app SaaS / AI was the most attractive sector with funding of ~US$ 167M followed by consumer app & platforms; Course5 received highest funding of ~US$ 53M & platforms; Course5 received highest funding of ~US$ 53M Top early-stage investments in Q2 CY23 Top early-stage investments in Q2 CY23 Early-stage investments, by sector Early-stage investments, by sector (US$ M, Q2 CY23) (US$ M, Q2 CY23) Amount Company Sector Key Investors (US$ M) SaaS / AI 167 SaaS / AI 53 360 ONE Asset, Nuvama Private Consumer app & platforms 115 Retail 52 Convergent Finance LLP Ecommerce & listing platforms 81 Ecommerce Mitsui’s 25 listing platforms R etail 78 Sansera Engineering Telecom 24 Manufacturing 47 Consumer app & Peak XV Partners1, Steadview, 20 platforms Truecaller Telecom 24 1 Retail 20 Accel, Peak XV Partners Transportation & logistics 24 Lightbox including Trifecta Capital, Energy 20 Pivot Ventures, Baldota Family Consumer app & 16 Office, Global Play Media, Denlow platforms FMCG 10 Private Trust, Venture Catalysts, Potential Ventures BFSI 10 Manufacturing 13 GR 2022 Holdings Inc Healthcare & Life Sciences 5 Transportation IvyCap Ventures 12 & logistics IT services 2 Others include ESG Others 9 SaaS / AI 11 Prosus Ventures, Accel solution provider Note(s): Early-stage investments include Pre-seed, Seed, Pre-series and Series A 1. Peak XV Partners (Erstwhile Sequoia India & SEA) © 1Lattice | 11 Source(s): 1Lattice Deals Database Top early-stage investments Top funded early-stage investments and their competitors Company Company Description Description Competitors Competitors Company Company Sector Sector Country Country Business Intelligence platform for marketing teams Sportswear and athleisure solutions platform Manufacturer of industrial material equipment Provider of millimeter wave ICs for communication applications Mobile game development arm of gaming unicorn MPL Note(s): *Setup in 2023 and currently has no Indian direct competitors © 1Lattice | 12 Source(s): 1Lattice Deals Database Growth-stage investments Energy sector dominated growth-stage investments with funding of ~US$ 1.3B; Avaada received highest funding in the Energy space (~US$ 1B) Growth-stage investment, by sector Growth-stage investment, by sector Top 10 growth-stage investments in Q2 CY23 Top 10 growth-stage investments in Q2 CY23 (US$ M, Q2 CY23) (US$ M, Q2 CY23) Amount Company Sector Key Investors (US$ M) Energy 1,000 Brookfield Renewable SaaS/AI 571 BFSI 400 MUFG, Sumitomo Mitsui Trust Bank BFSI 512 SMBC Bank of Japan, ICG, AIIB Energy 250 Consumer app 338 & platforms Qatar Investment Authority (QIA), SaaS/AI 250 Jungle Ventures, Iconiq Capital, Ecommerce & 158 Insight Partners listing platforms ReConsumer app General Atlantic 200 & platforms tail Manufacturing 131 Temasek, Steadview Capital, Manufacturing 86 Trifecta Capital, Jungle Ventures, FMCG 69 Inflexor Ecommerce & 60 Abu Dhabi Investment Authority Healthcare & listing platforms 48 life sciences BFSI 58 Premji Invest Transportation 20 Sorenson Capital, Eight Roads & logistics SaaS/AI 50 Ventures, Telstra Ventures, WTI Others include 3 Others Agritech Avataar Ventures, Lightrock India, Consumer app & 45 WaterBridge Ventures and debt platforms from Trifecta, Stride Ventures Note(s): Growth-stage investments include Series B, C, D and E © 1Lattice | 13 Source(s): 1Lattice Deals Database Top growth-stage investments Top funded growth-stage investments and their competitors Company Description Competitors Company Sector Country Offers an energy platform for manufacturing solar cells, modules, and electrolysers Provider of consumer and SME loans Developer of solar and wind energy projects Modular app-building platform One app for all things money - Pay bills, recharge, send money, buy gold, invest and shop at stores Source(s): 1Lattice Deals Database © 1Lattice | 14 Late-stage investment Majority of late-stage investments came from E-commerce & listing platforms (~US$ 184M); Majority of late-stage investments came from E-commerce & listing platforms (~US$ 184M); Majority of late-stage investments came from E-commerce & listing platforms (~US$ 184M); Lenskart received the highest funding of ~US$ 100M in Q2 CY23 Lenskart received the highest funding of ~US$ 100M in Q2 CY23 Lenskart received the highest funding of ~US$ 100M in Q2 CY23 Top late-stage investments in Q2 CY23 Late-stage investment, by sector (US$ M, Q2 CY23) Amount Company Sector Key Investors (US$ M) E-commerce & ChrysCapital 100 listing platforms Ecommerce & 184 listing platforms Reliance Retail, Alphabet and Ecommerce & 75 other existing investors listing platforms Transportation 40 Khazanah Nasional Berhad & logistics Transportation & 40 logistics Ecommerce & 9 Undisclosed listing platforms Note(s): Late-stage investments include Series F onwards © 1Lattice © 1Lattice | | 15 15 Source(s): 1Lattice Deals Database Top late-stage investments Top funded late-stage investments and their competitors Company Company Description Description Competitors Competitors Company Company Sector Sector Country Country Multinational optical prescription eyewear retail chain Online platform offering multi-category delivery services Provider of e-commerce fulfillment solutions Online platform that provides interior design solutions Source(s): 1Lattice Deals Database © 1Lattice | 16 Tech investments Enterprise tech attracted highest investments (~US$ 980M), followed by Fintech (~US$ 745M) and Retail tech (US$ 340M) within tech investments for Q2 CY23 Top 10 tech investments in Q2 CY23 Early-stage investments, by sector Early-stage investments, by sector (US$ M, Q2 CY23) (US$ M, Q2 CY23) Amount Company Sector Key Investors (US$ M) Enterprise Tech 978 Enterprise Tech 450 Apax Fintech 746 MUFG and Sumitomo Mitsui R etail Tech 340 Fintech 400 Trust Bank SCM & logistics 123 Qatar Investment Authority (QIA), Industrial & Manufacturing Enterprise Tech 250 Jungle Ventures, Iconiq Capital, 112 and Insight Partners Automotive 75 HealthTech Fintech 200 General Atlantic 68 Gaming 66 ChrysCapital Retail Tech 100 Marketing Tech 60 Food & Foodtech 47 Temasek, Steadview Capital, Industrial & Trifecta Capital, Jungle Ventures, 86 Aerospace & Defense 46 Manufacturing and Inflexor Travel & Hospitality 45 Reliance Retail, Alphabet & other Retail Tech 75 Media & entertainment 20 existing investors Edtech 12 Abu Dhabi Investment Authority Marketing Tech 60 Agritech 11 Energy & utilities 10 Enterprise Tech 53 360 ONE Asset, Nuvama Private Others include HR tech, Others 25 Real estate & construction, Advertising & more Retail Tech 52 Convergent Finance LLP Source(s): 1Lattice Deals Database © 1Lattice | 17 Top 10 M&As* Top 10 M&A* deals in Q2 CY23 Top 10 M&As* in Q2 CY23 Acquired Company Sector Amount (US$ M) Date Acquirer Healthcare & Life Sciences 2,000 April 08, 2023 BFSI 1,110 June 20, 2023 Others* 487 May 12, 2023 Energy 360 June 01, 2023 Manufacturing 202 May 06, 2023 Transportation & Logistics 181 April 01, 2023 Engineering & Construction 111 June 26, 2023 Telecom 100 May 11, 2023 Consumer app & platforms 61 June 18, 2023 Healthcare & Life Sciences 50 April 19, 2023 Note(s): Includes top M&A deals whose amounts were disclosed; * Includes an infrastructure investment trust © 1Lattice | 18 Source(s): 1Lattice Deals Database Agenda Deal landscape in Q2 CY23 in India Key deals and investment themes Key investors Active investors Most active investors of Q2 CY23 Early-stage investors Growth-stage investors Late-stage investors (# deals) (# deals) (# deals) 7 4 1 5 3 5 3 5 2 1 4 2 4 2 1 2 4 2 4 2 4 1 2 4 Note(s): Sequoia Capital is now Peak XV Partners © 1Lattice | 20 Source(s): 1Lattice Deals Database Active early-stage investors Most active early-stage investors and their investment segments in Q2 CY23 Includes Retail & BFSI Ecommerce & Consumer app Investors Manufacturing Energy FMCG SaaS/AI Others listing platforms & platforms Note(s): Sequoia Capital is now Peak XV Partners © 1Lattice | 21 Source(s): 1Lattice Deals Database Active growth-stage investors Most active growth-stage investors and their investment segments in Q2 CY23 Includes healthcare & Life Sciences Ecommerce & Consumer app Investors Energy Manufacturing FMCG SaaS/AI BFSI Others listing platforms & platforms General Atlantic made 2 investments in the last quarter Source(s): 1Lattice Deals Database © 1Lattice | 22 We are here for you Let us know how we can meet your business requirement? Connect now Roma Dixit Director - Financial Investors Vaishnav Kumar Rai 1Lattice Manager – Corporate Communications E: romadixit@1lattice.com E: communications@1lattice.com M: +91 962 522 6697 M: +91 782 794 4925 Gurugram Bengaluru New Delhi Mumbai www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice’s intellectual property and are a combination of the collection of the best data we could find publicly, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accurate or complete, and nothing contained here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein by the viewer shall be at the sole risk of the viewer and 1Lattice or its business partners, affiliates, agents, officers or employees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. 1Lattice does not have any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. 1Lattice We enable better decision making. Technology-backed business support that helps you ENABLE BETTER 200+ 30% annual engagements faster to outcomes DECISIONS Deep on-ground insights that you can act on 8 600+ practices years domain expertise 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy One-ness of data and people networks to harness the collective power of data, network, and technology 100+ 2.5M towns & cities panel members Multi-faceted teams offering a stack of consulting, advisory, and research services 15+ 40:60 languages covered she/he ratio The team at appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, Tower A, 4th Floor, DLF 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District Centre Court, DLF Phase Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 5, Sector 42, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram-122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025