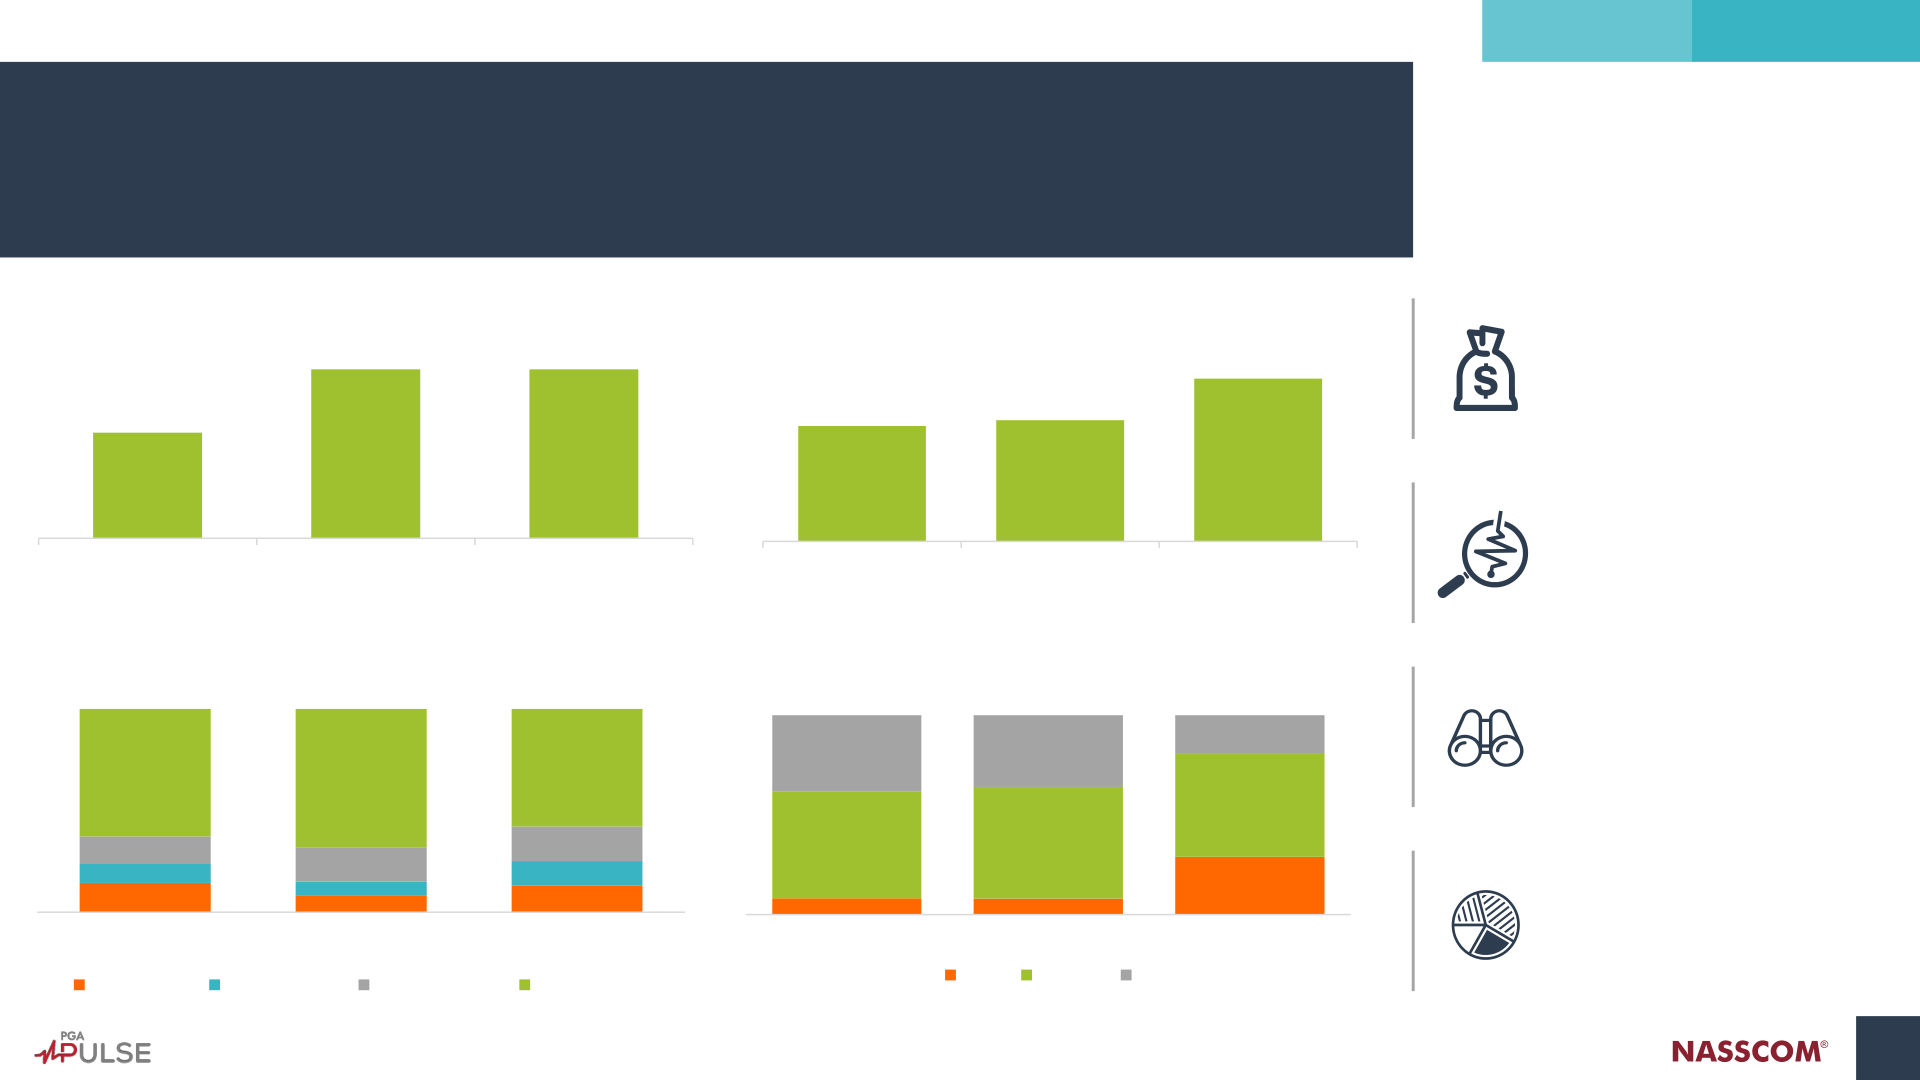
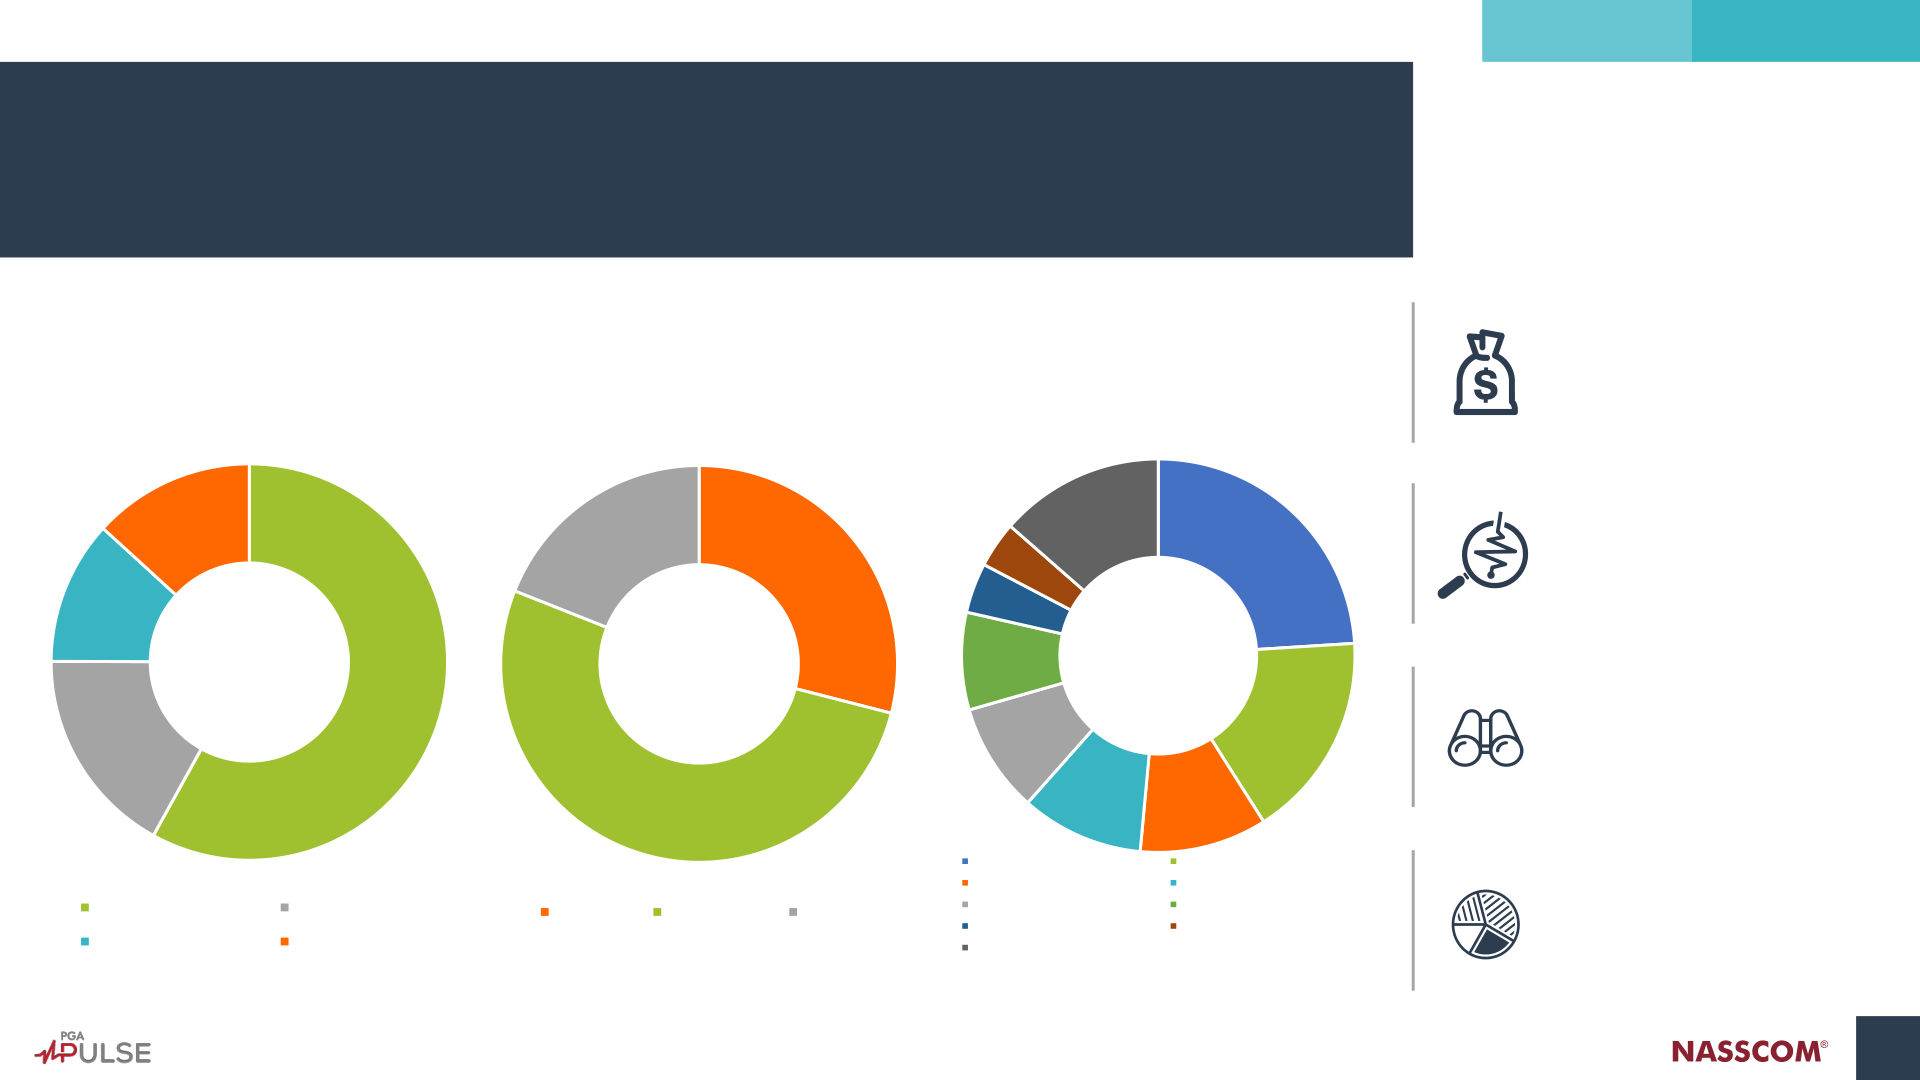
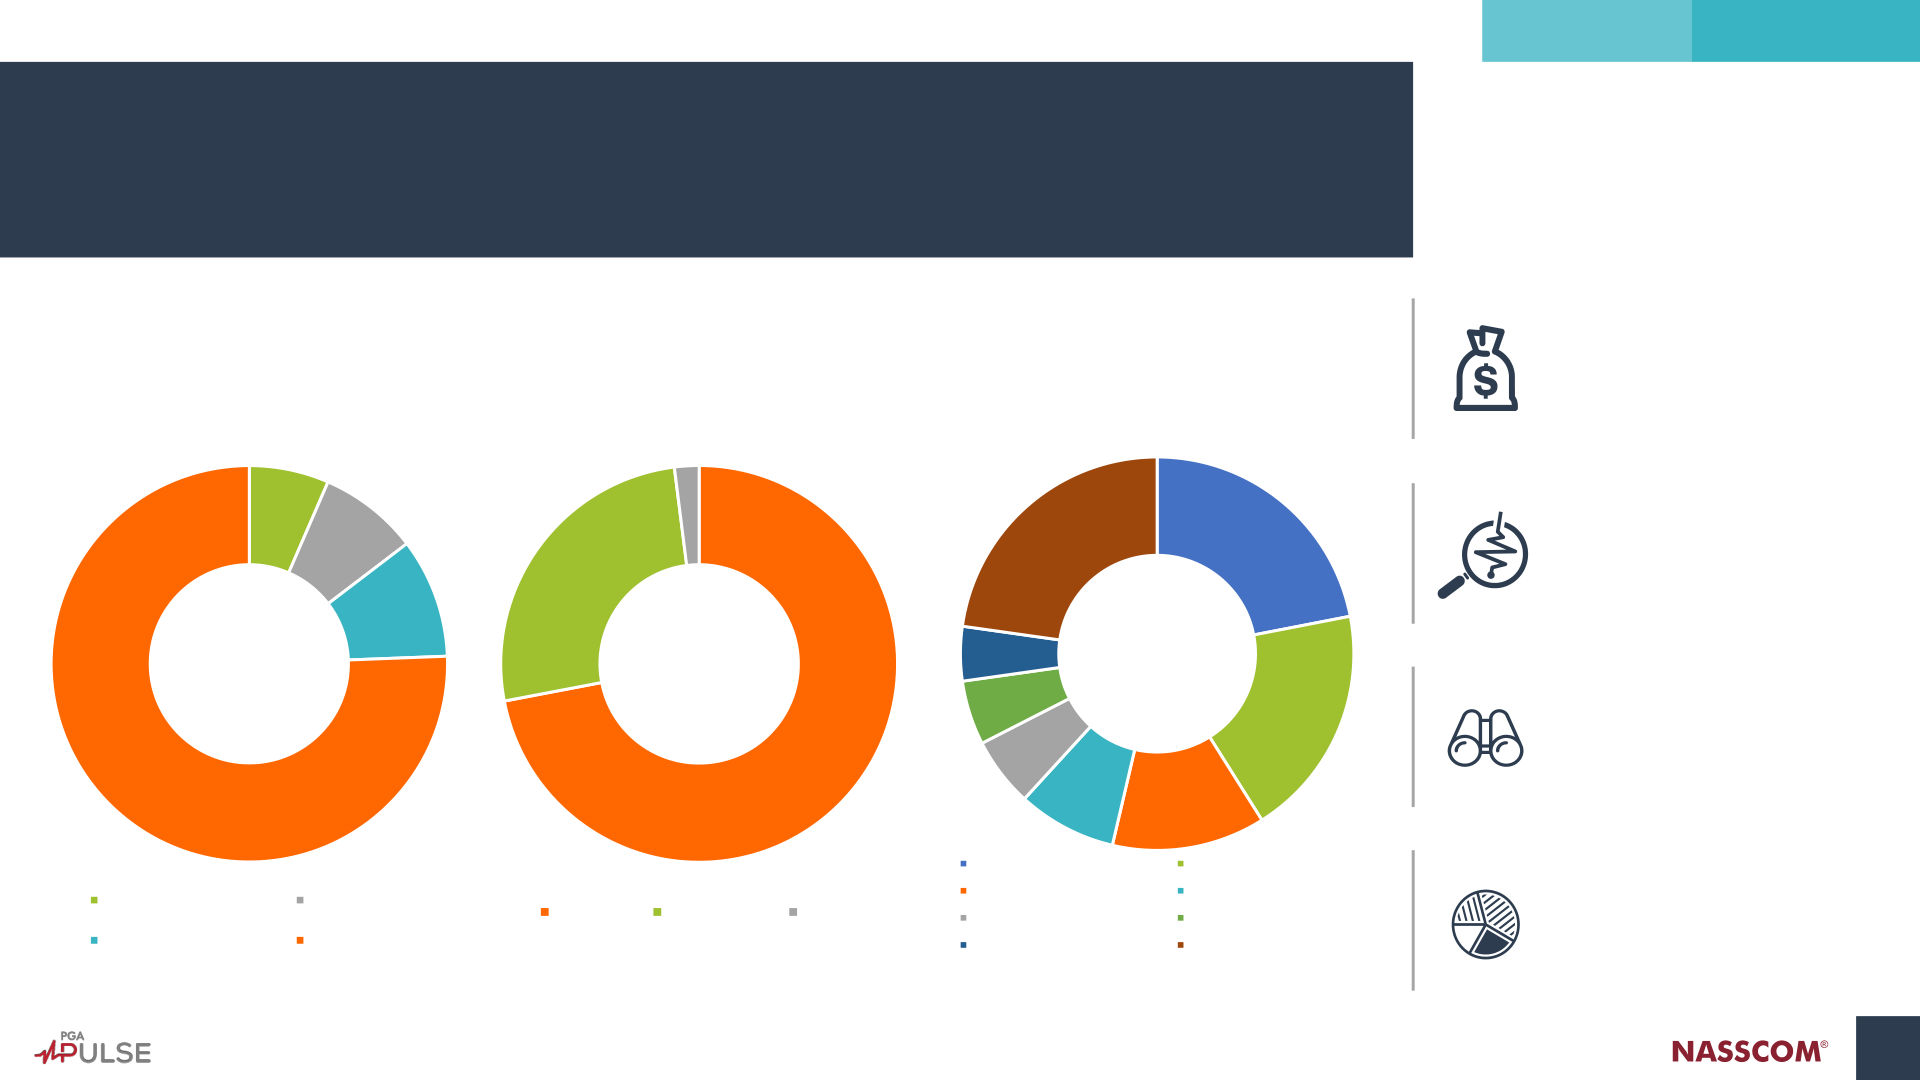
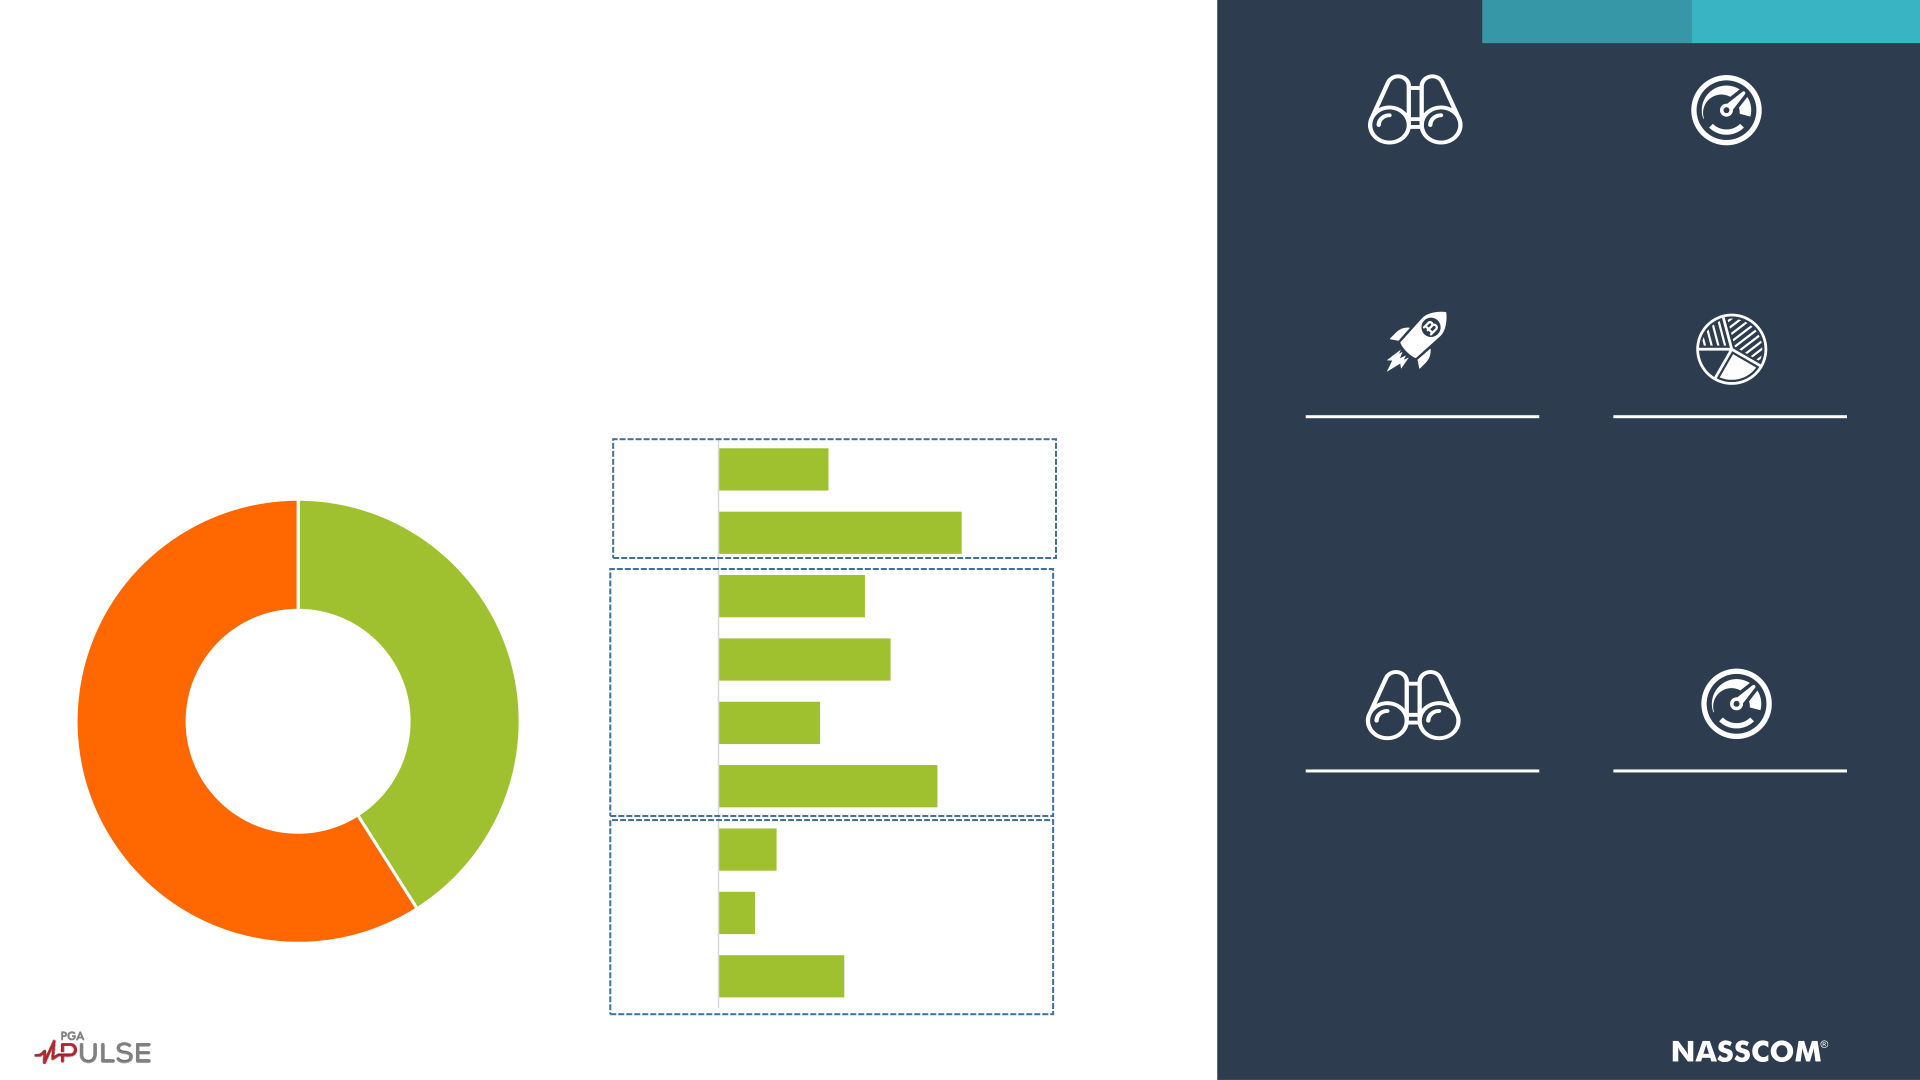
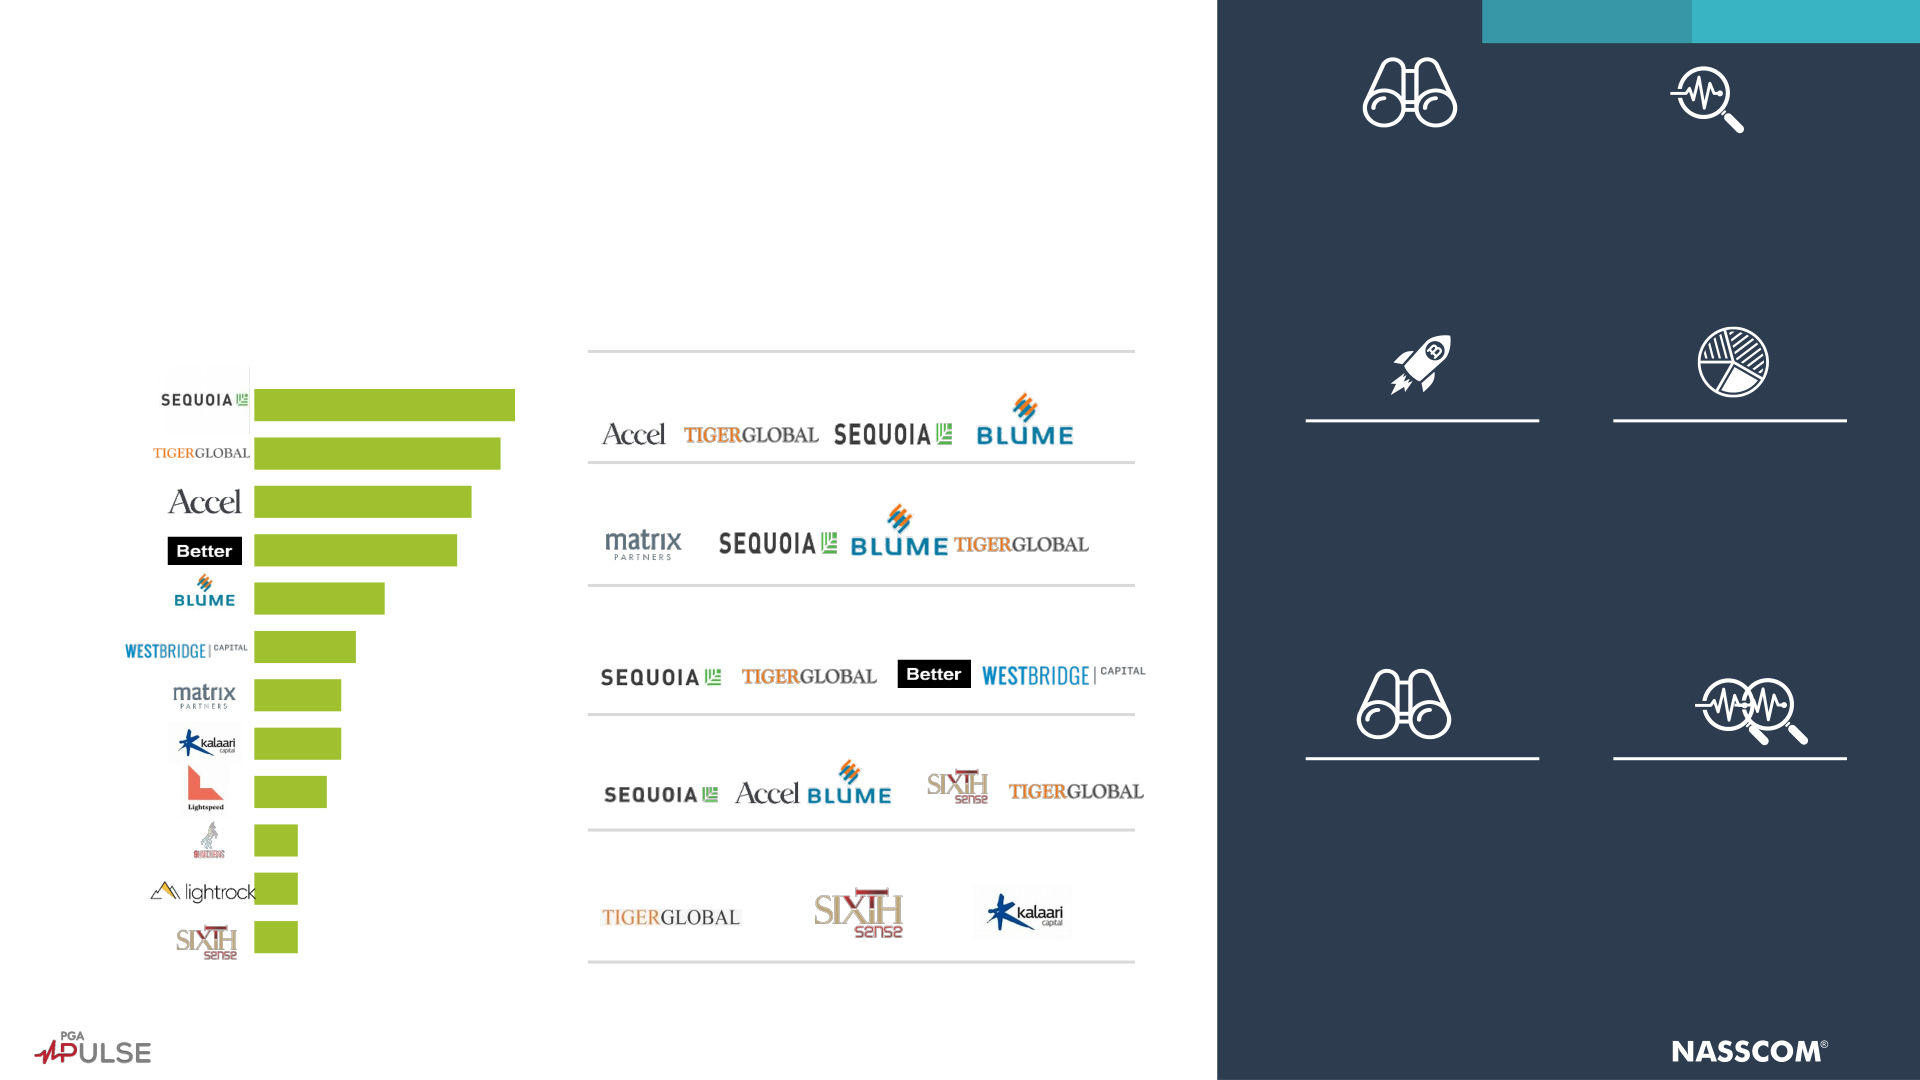
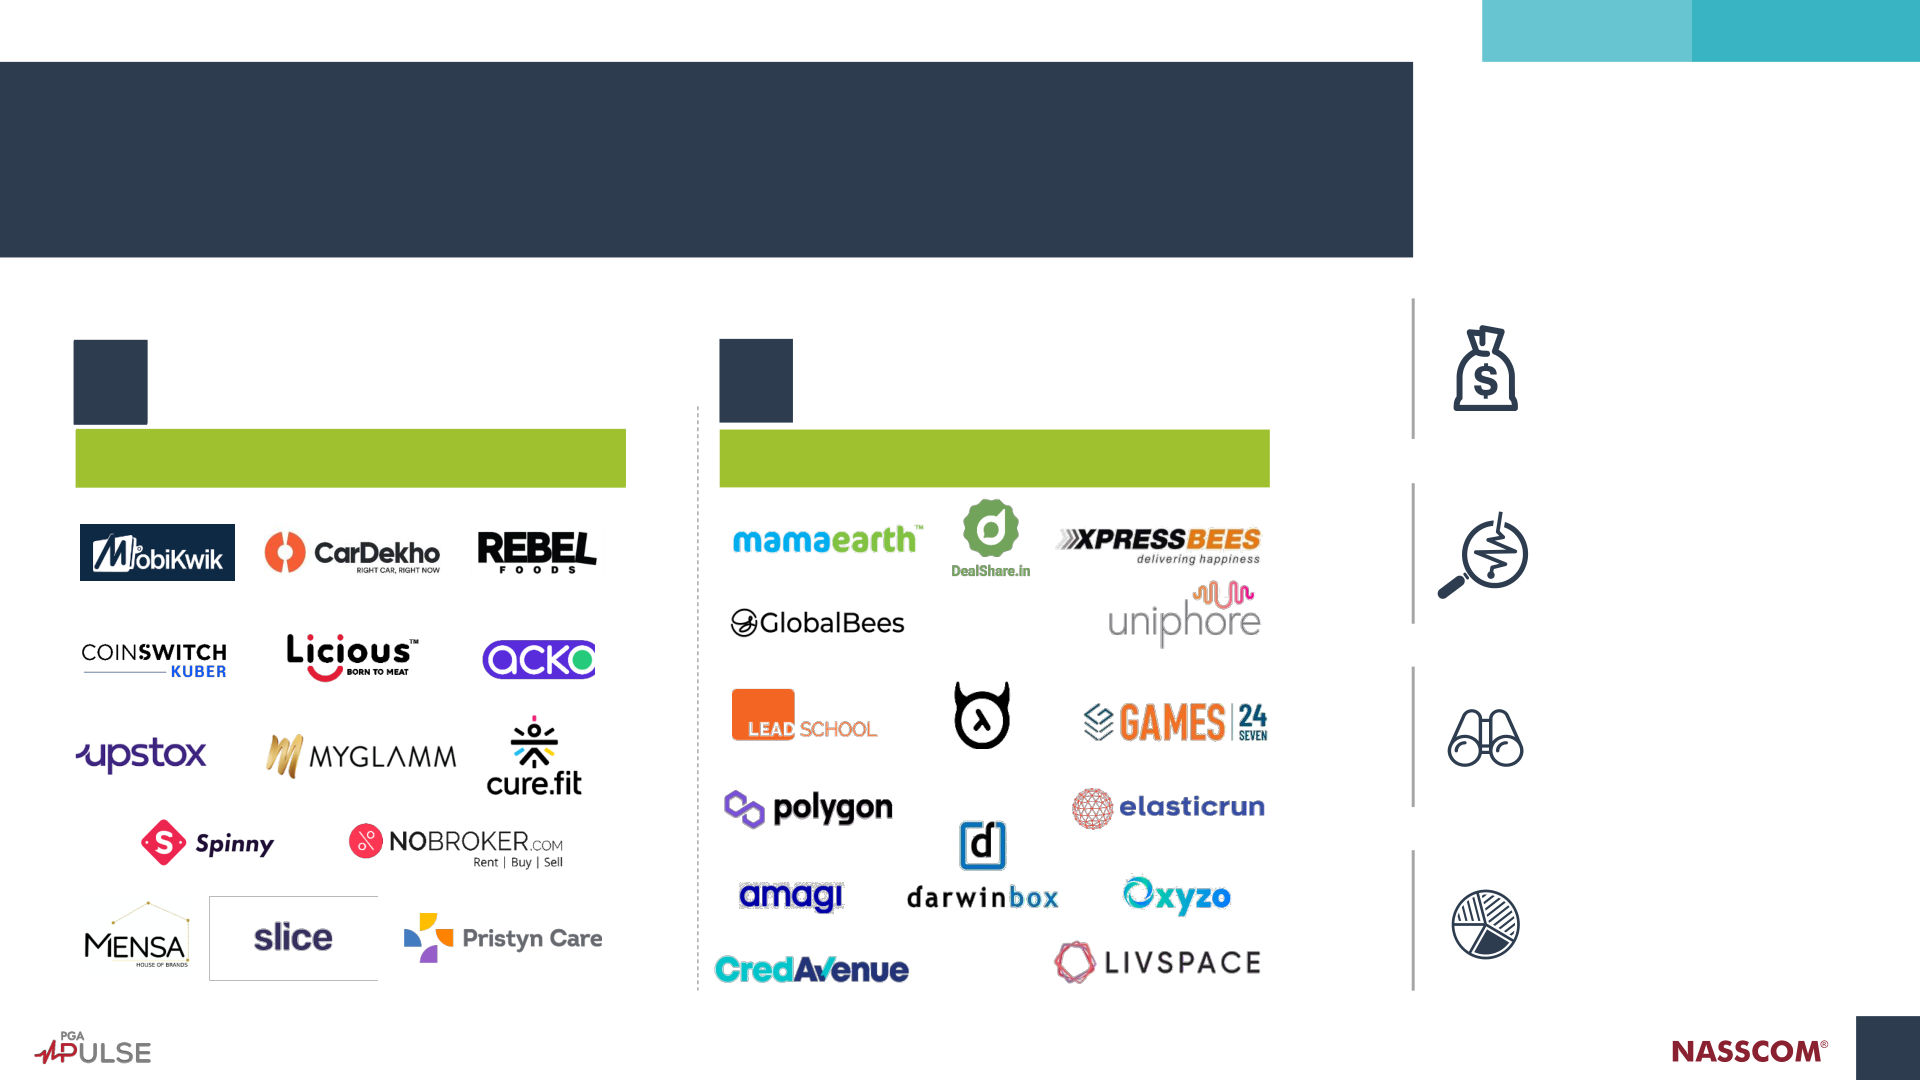
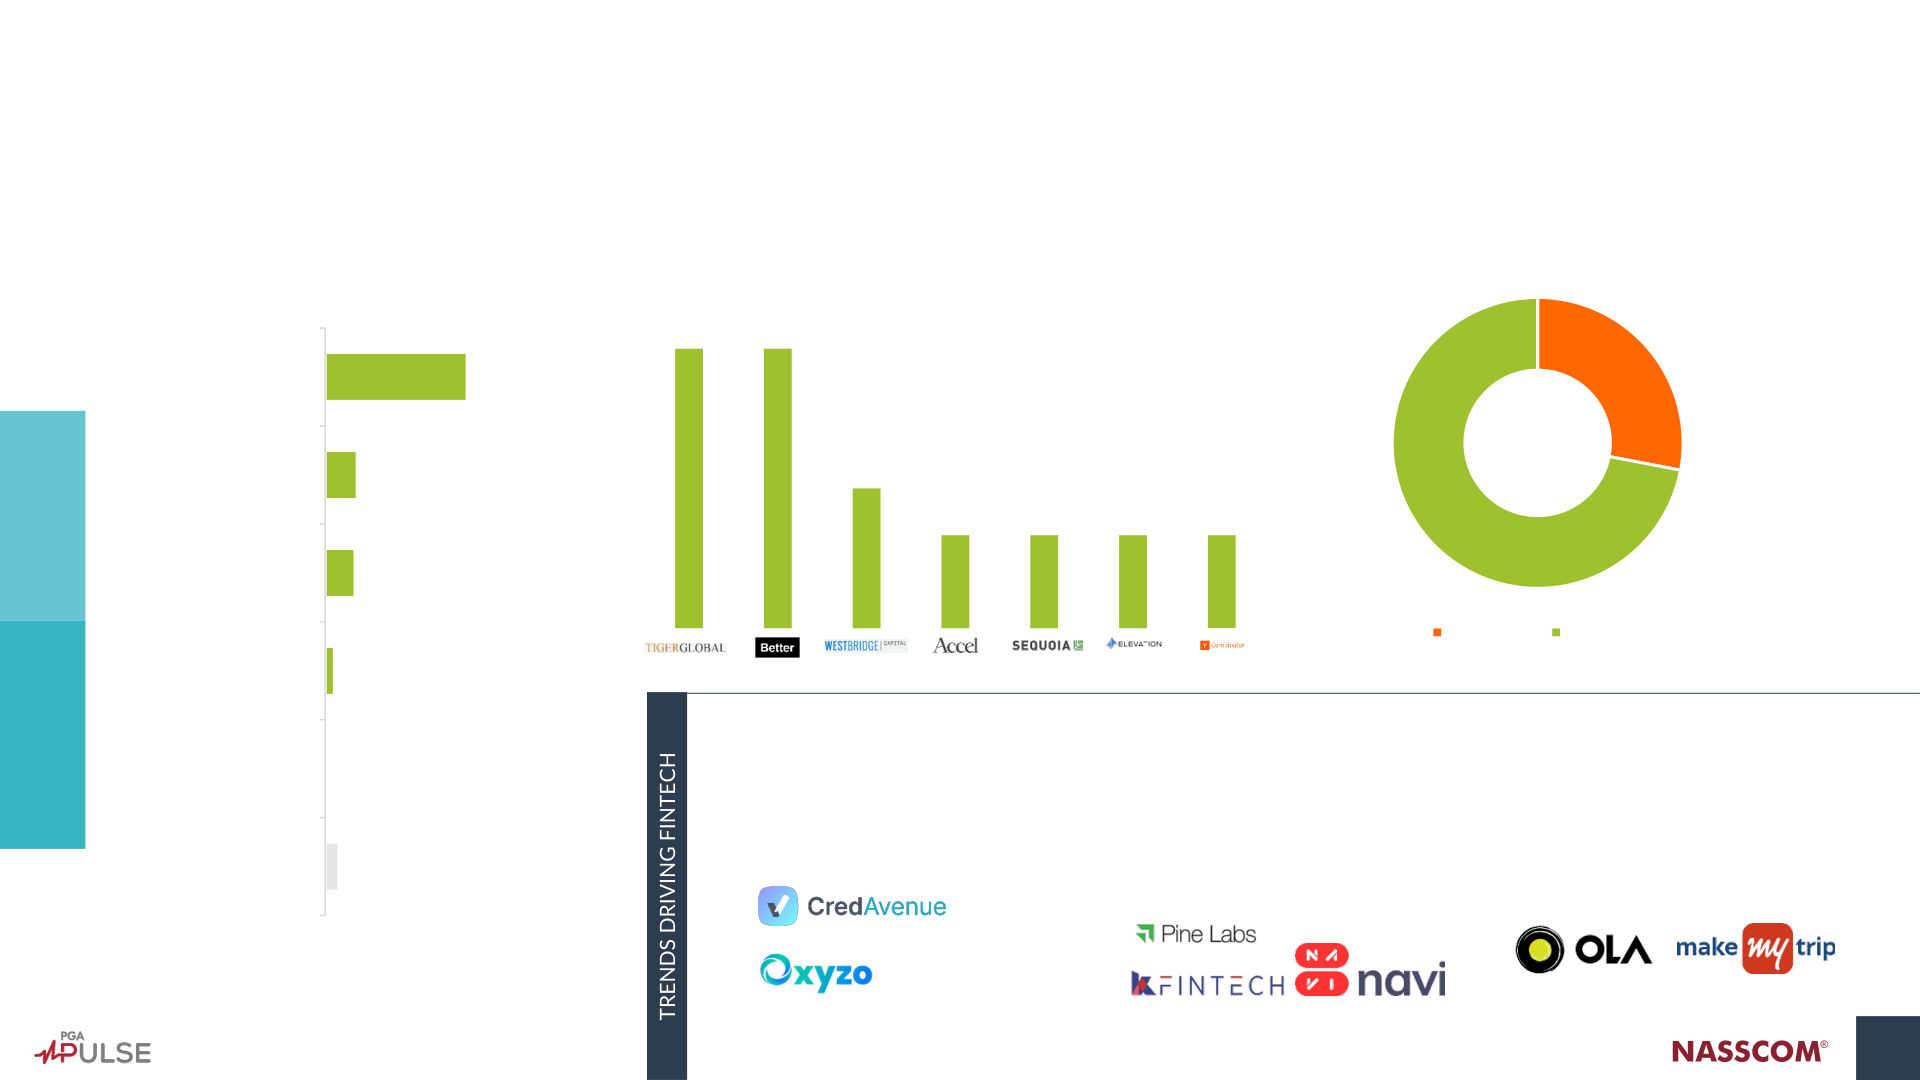
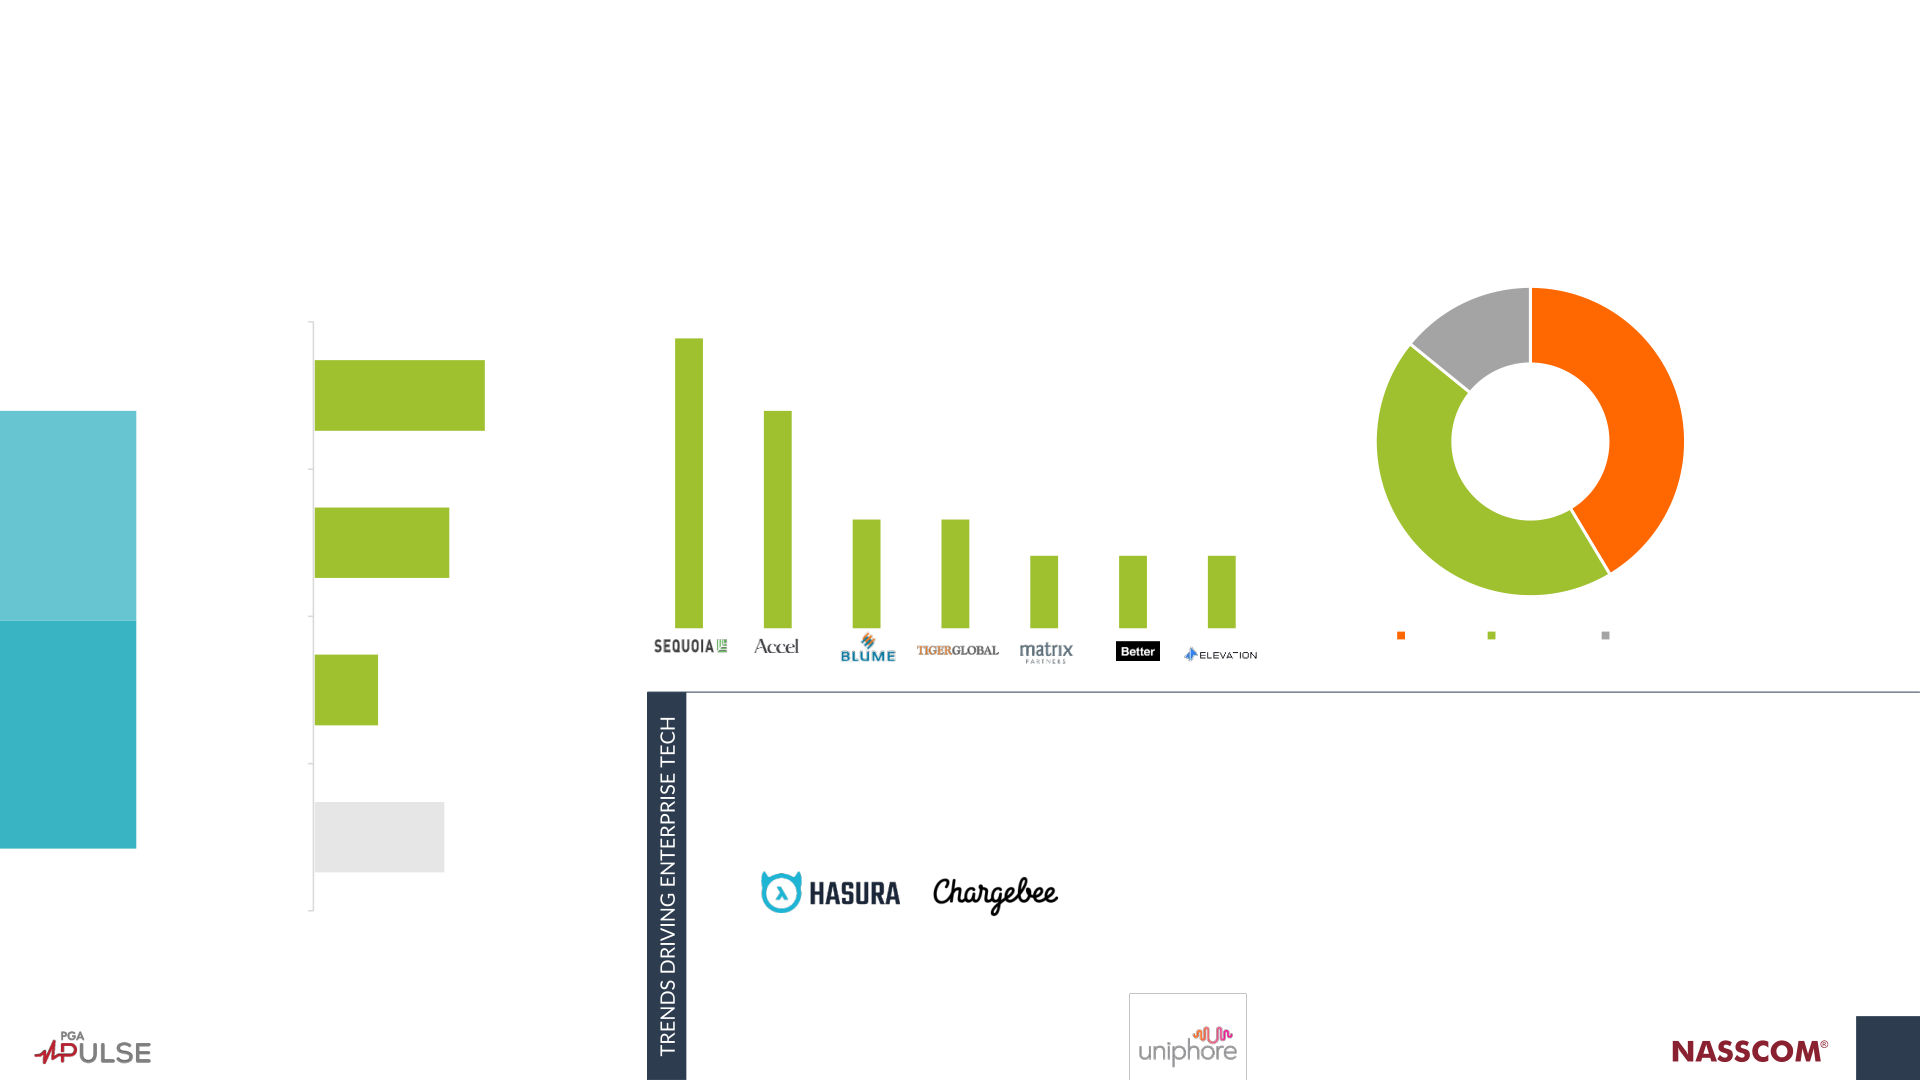
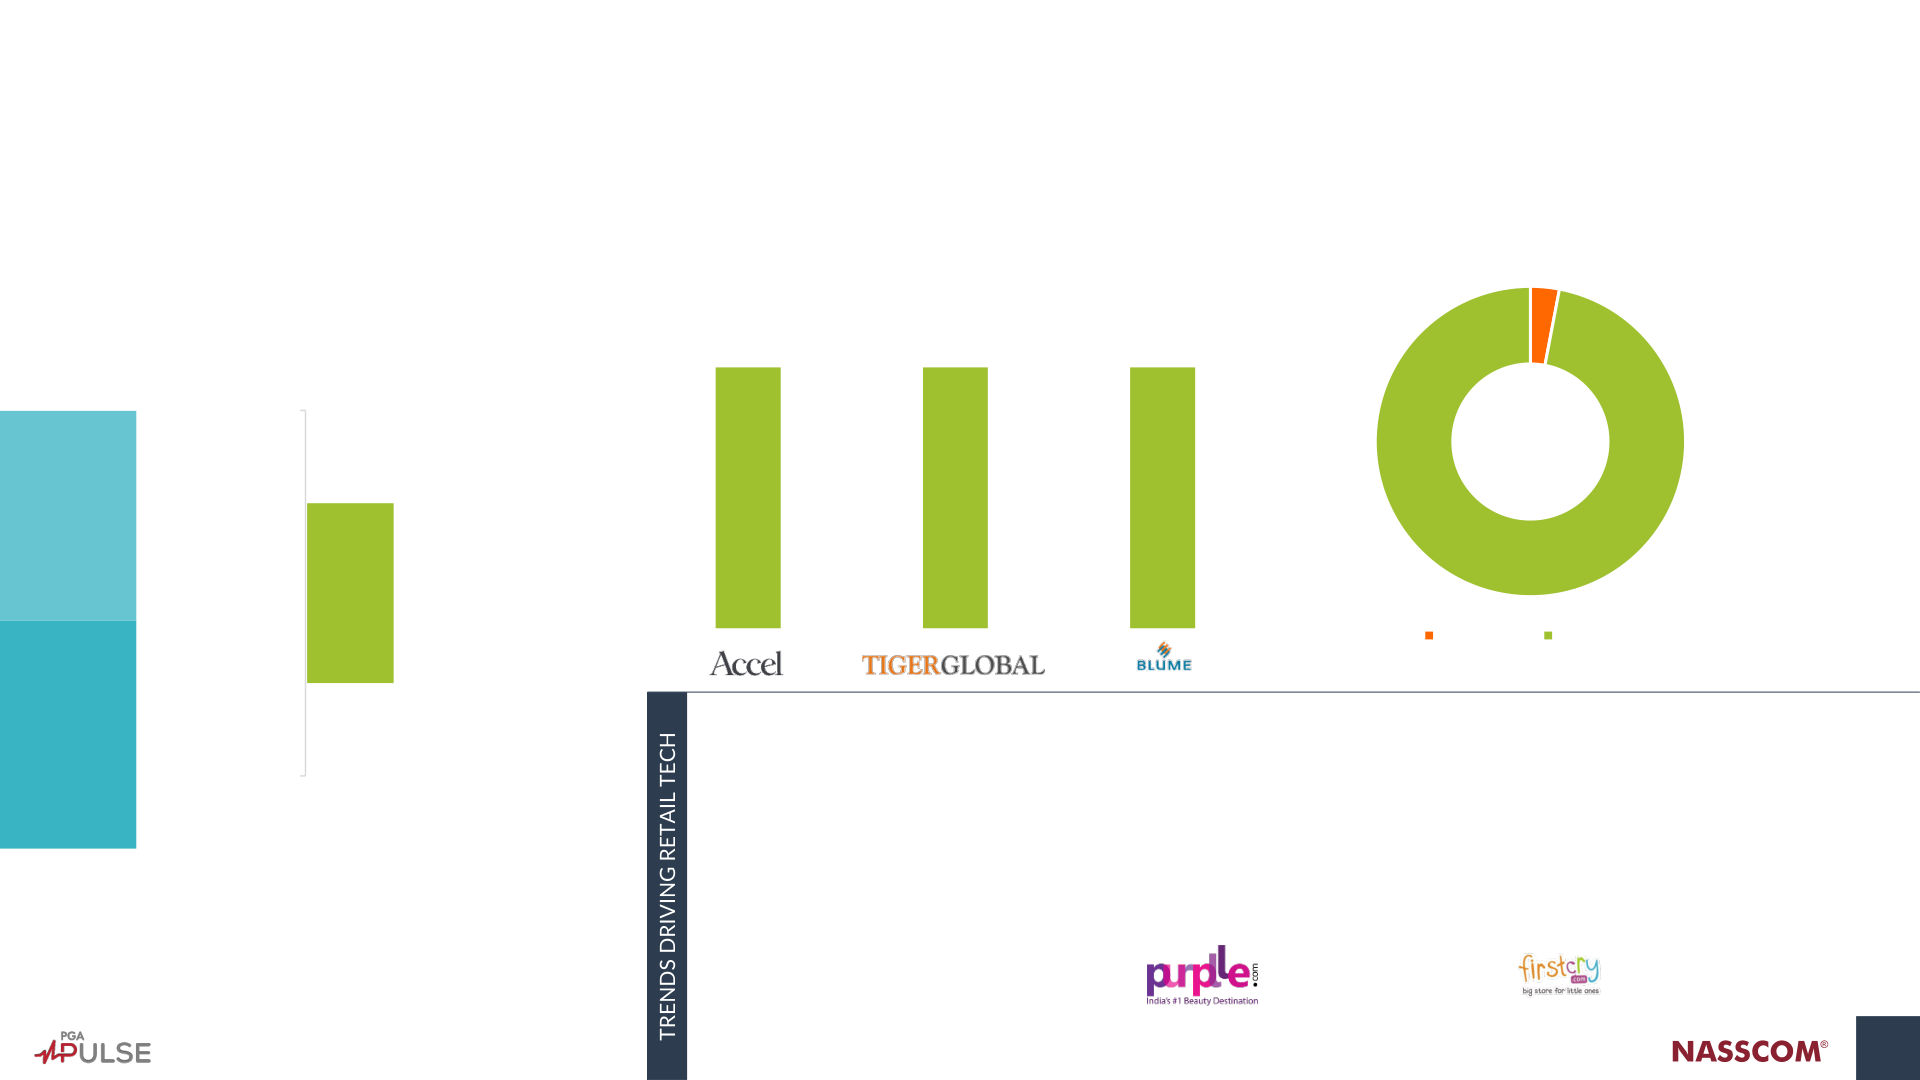
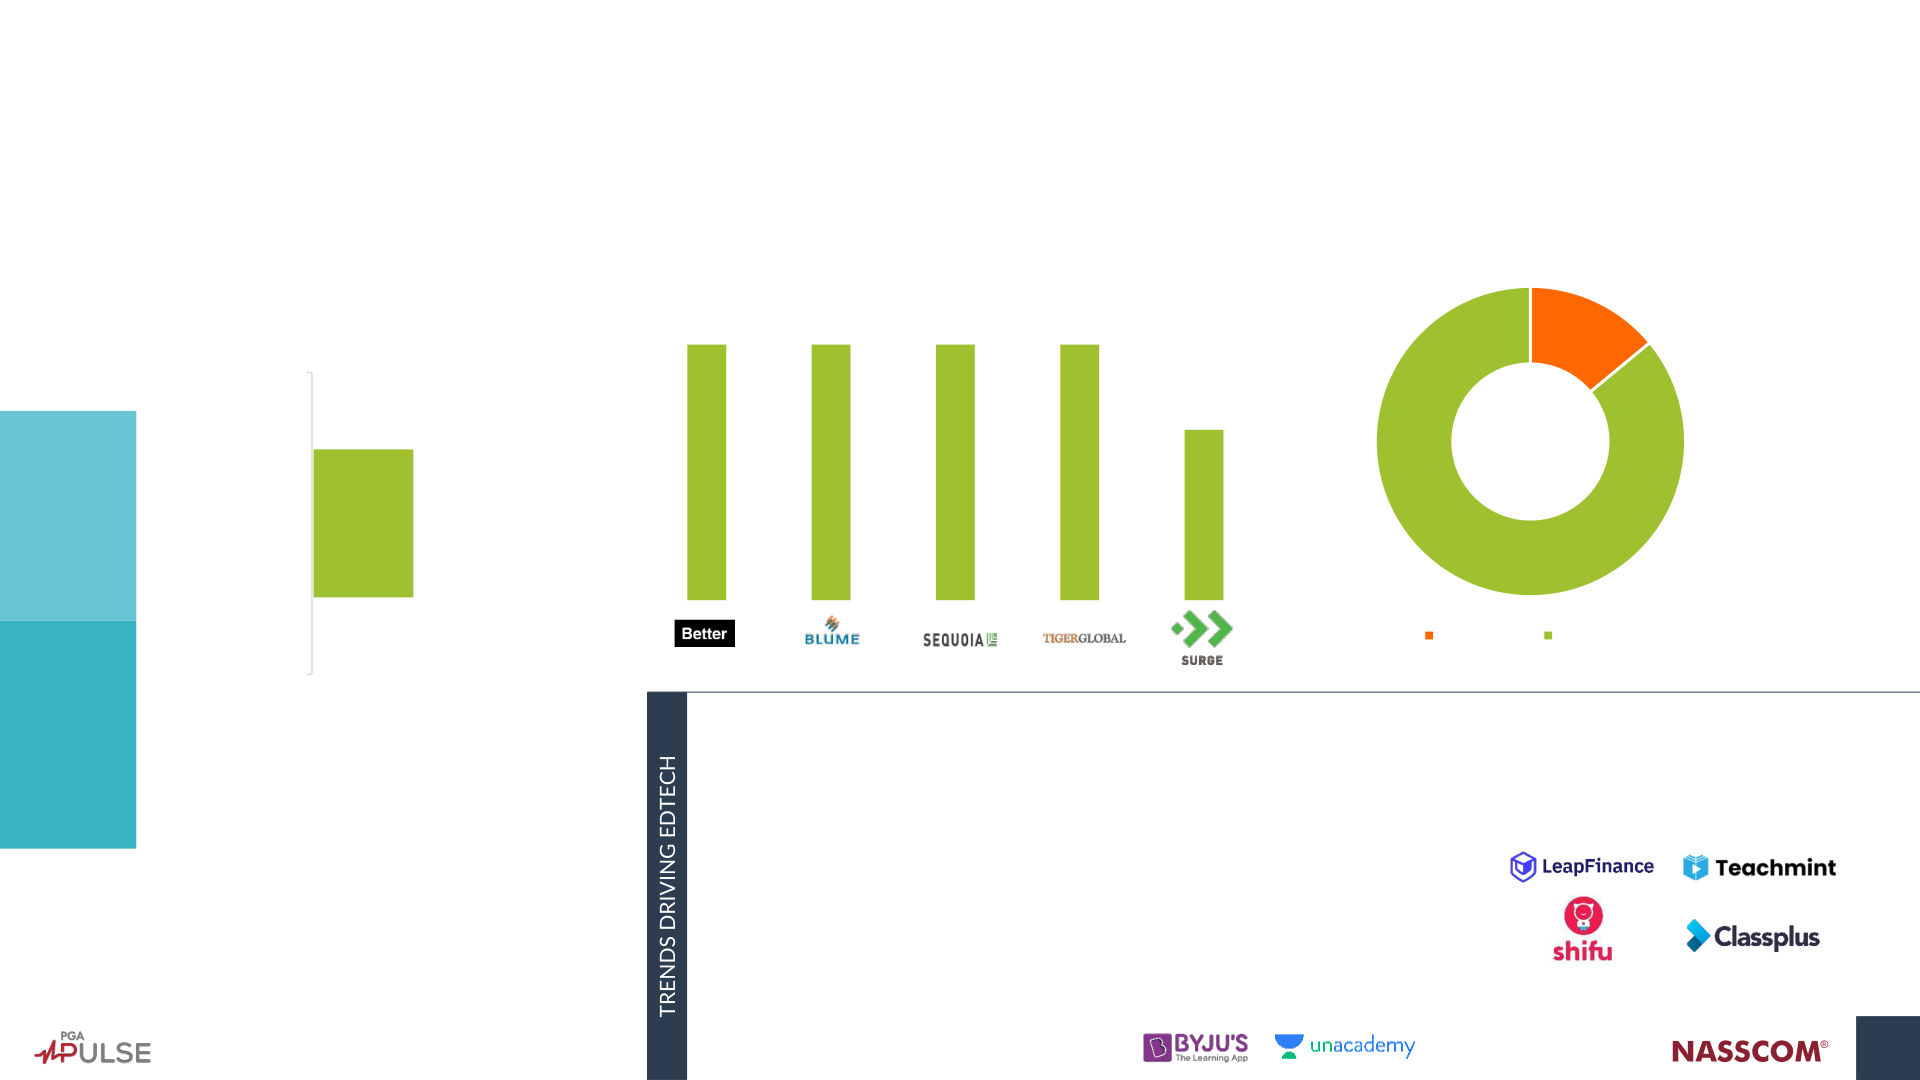
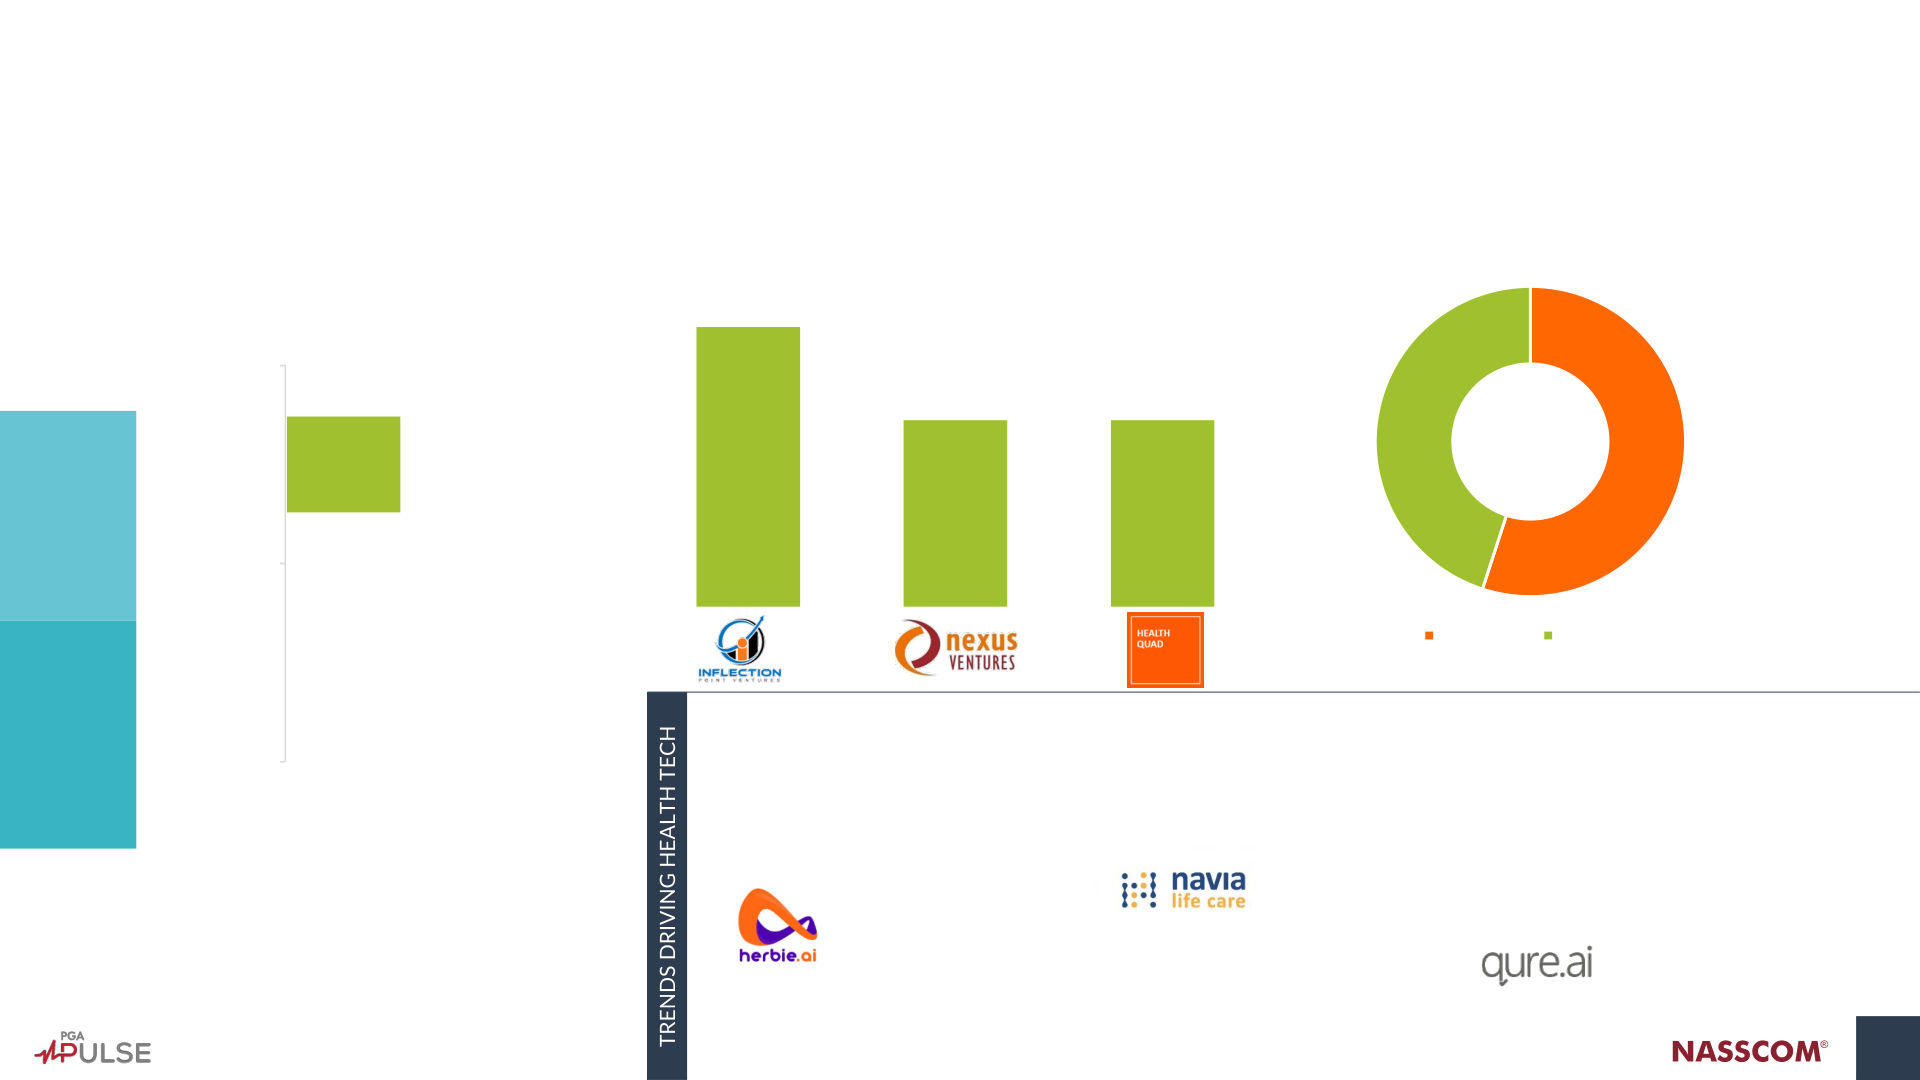
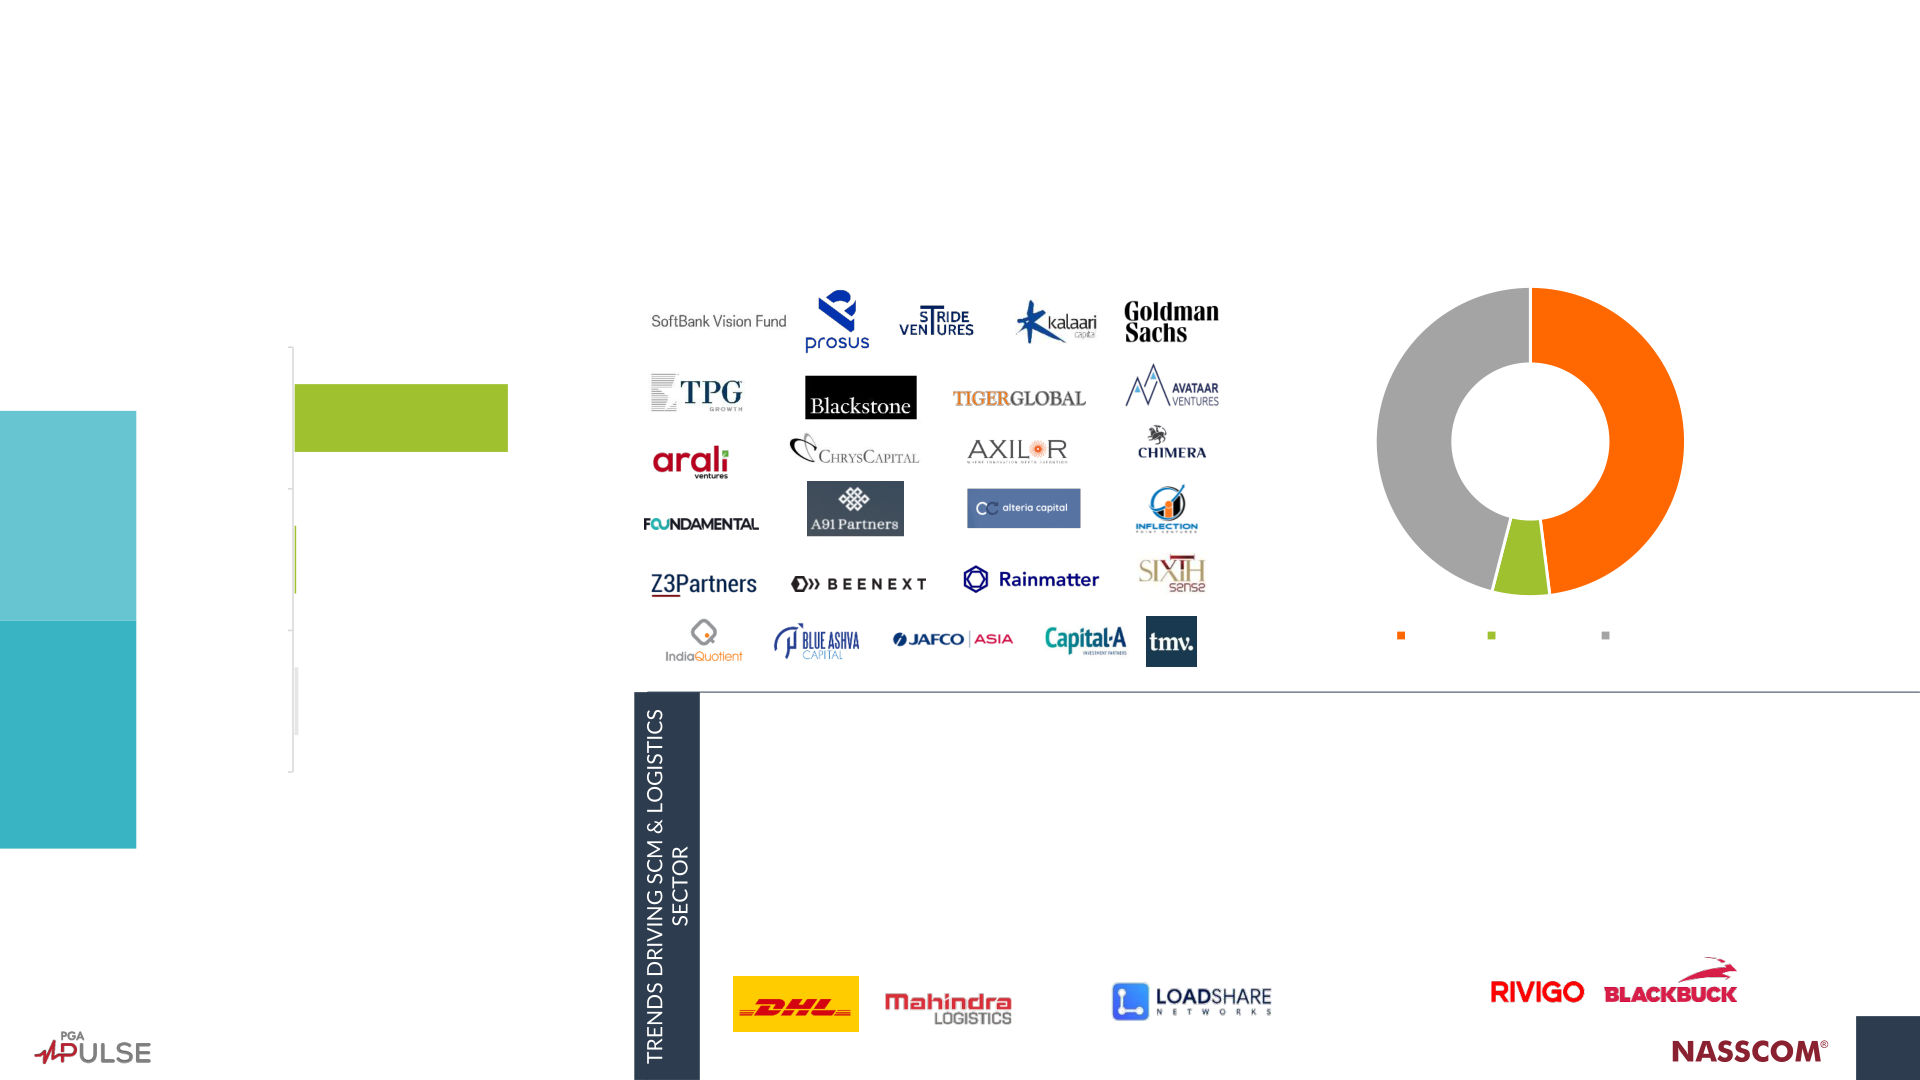
A p r i l 2 0 2 2 QUARTERLY INVESTMENT FACTBOOK TECH START - UPS Q 1 CY2 2 START - UP DEAL ANALYSIS SUMMARY 03 CONTENT TECH START - UPS INVESTMENT TREND ANALYSIS 04 VERTICAL TREND ANALYSIS 11 APPENDIX 2 4 2 # Deal Volume Funding US $ 7.2 B 247 Up by ~ 34 % Q - o - Q Similar at Q - o - Q Unicorns 1 5 SUMMARY Large ticket sizes of deals helped in total funding of ~US $ 7 . 2 B in Q 1 CY 2022 . Tech start - up ecosystem received a major boost with the formation of 15 unicorns during the quarter . EnterpriseTech has Top Funded Vertical Most Funded Stage emerged as the top - funded vertical, followed by FinTech . Enterprise Tech Growth ~52 % of total funding 25 % of the t otal f unding 3 TECH START - UPS Q - o - Q AND CUMULATIVE COMPARISON INVESTMENT DEAL VALUE BY LATEST QUARTER TREND ANALYSIS DEAL VOLUME BY LATEST QUARTER FUNDING BY SALES CHANNEL AND FUNDING ROUNDS TOP INVESTORS AND THEIR FOCUS SECTOR UNICORNS US $ 7.2 B raised by Indian tech start - ups in Q 1 CY2 2 , similar compared to Q 1 CY2 1 Q - o - Q and Cumulative Comparison TOTAL FUNDING DEAL VOLUMES (NO. OF DEALS) (US$ in B) Indian tech start - ups remain (# of deals) 7.2 7.2 attractive, raised US$ ~7.2B in 247 Q1 CY2022 184 175 4.5 The number of deals closed in Q1 CY22 increased by ~34% Q1 CY21 Q4 CY21 Q1 CY22 Q1 CY21 Q4 CY21 Q1 CY22 when compared to Q4 CY21 FUNDING BY DEAL SIZE FUNDING BY STAGE ( US$ B, % of total funding) ( US$ B, % of total funding) 4.5 7.2 7.2 4.5 7.2 7.2 Percentage of funding in large 19% funding rounds reduced from 36% 38% 58% 68% to 58% in Q1 CY22 63 % 68% 52% 56% 17% 53% 14 % 17% 9 % 12% Approximately 81% of the 29% 7% 14 % 13% 8% 8% 8% funding activity was driven by early - stage and growth - stage Q1 CY21 Q4 CY21 Q1 CY22 Q1 CY21 Q4 CY21 Q1 CY22 deals Early Growth Late < US$ 25M US$ 25-50M US$ 50-100M >= US$ 100M 5 Source: PGA Labs Deals Database EnterpriseTech and FinTech were the top sector s in Q 1 CY2 2 attracting ~ 41 % of total funding Deal value by latest quarter SPLIT OF DEAL VALUE ( US $, Jan 2 2 – Mar. 2 2 ) Q1 CY22 deal value similar to Q4 CY21 FUNDING BY DEAL SIZE FUNDING BY STAGE FUNDING BY SECTOR ~52% of funding activity was 14% 13% 19% driven by growth - stage 24% companies. However, they 29% 4% represented ~26% by deal 12% 4% count 8% US$ 7.2 B US$ 7.2 B US$ 7.2 B 58% 58% funding by deal size were 17% 9% 17% in the ticket size of US$ 100M or above 10% 10% 52% Enterprise Tech Fintech Large ticket deals helped SCM & Logistics Food & Foodtech EdTech Retail Tech >= US$ 100M US$ 50-100M EnterpriseTech and FinTech Early Growth Late Real estate & construction Media & entertainment account for ~41% of total US$ 25-50M < US$ 25M Others funding Notes(s): Others includes Marketing, HR Tech, Hospitality, Manufacturing, AgriTech, Aerospace, Mobility, Gaming, Real Estate Source: PGA Labs Deals Database 6 76 % of deals by volume were <US$ 25M; Enterprise Tech remains most active ( 22 % deals) Deal volume by latest quarter SPLIT OF DEAL VOLUME 76% of total deals in Q1 CY22 ( Jan 2 2 – Mar 2 2 ) were of the ticket size <US$ 25M DEAL VOLUMES BY SIZE DEAL VOLUMES BY STAGE DEAL VOLUMES BY SECTOR 2% 7% 72% of deal activity was driven 22% 23% 8% by early - stage start - ups (deal 26% size remains small) 10% 4% 247 247 247 Nos. 5% Nos. Nos. ~54% deals were in 3 specific 19% verticals – EnterpriseTech, 6% 72% FinTech and EdTech 76% 8% 13% Enterprise Tech Fintech EdTech HealthTech >= US$ 100M US$ 50-100M 22% of total deals in Q1CY22 Early Growth Late Retail Tech Agritech focused on EnterpriseTech US$ 25-50M < US$ 25M Media & entertainment Others Notes(s): Others includes Food Tech, Marketing, Automotive, HR Tech, Hospitality, Manufacturing, Aerospace, Energy, Mobility, Le gal Tech, Gaming Source: PGA Labs Deals Database 7 B2B tech start - ups funding accounts for ~59% of the total ~US$ 7.2B Series E accounted Top 3 B2B funded for ~18% of total start - ups Uniphore, Funding by sales channel and funding rounds funding ElasticRun and XpressBees B2 B S tart - ups led the race in deal Series A funding accounts for 20 % of deal value value DEAL FLOW SPLIT SPLIT BY SERIES (%, Jan 22 – Mar. 22) (%, Jan 22 – Mar 22) Seed 9% B2B start - ups raised over Top 3 B2C funded Early - stage US$ 4.2B in Q1 CY22, start - ups are Swiggy, accounting for ~59% of Polygon and 20% Series A total funding (owing to Network FP large ticket sizes of 12% Series B Uniphore, ElasticRun etc.) Series C 14% B2C 41% Growth - stage 8% Series D US$ 7.2 B B2B, 59% 18% Series E 29% of the funding Growth - stage Series F 5% went to early - stage companies raised companies 52% of total funding Late - stage amount, series E 3% Series H being the top round at 18% 10% Series J Source : PGA Labs Deals Database 8 Leading firms such as Sequoia, Tiger Global have shown interest towards diversified verticals in Q1 CY22 Top investors and their focus sector s Prominent investors EnterpriseTech , Sequoia Capital, Tiger FinTech are the top MOST PROMINENT INVESTOR IN TERMS OF DEAL VOLUME Global, Better Capital two invested sectors and Accel have done in Q1 CY22 10+ deals across TOP INVESTORS, SPLIT OF DEAL FLOW INVESTOR DIVERSIFICATION sectors (#, Jan 22 – Mar 22) EnterpriseTech 18 17 Enterprise 17 deals with funding Tech accounted for >=US$ 100M in Q1 FinTech 15 22% of deal volume, CY22 followed by 14 FinTech (19%) 9 EdTech 7 6 6 Retail Tech 5 Q1 CY22 has seen Sequoia has majorly multiple investments invested in almost all 3 from emerging major sectors SCM & Logistics investors such as including Enterprise 3 Sixth Sense (3 deals) Tech, FinTech, Retail 3 Tech, EdTech etc. 9 Source : PGA Labs Deals Database 1 5 new unicorns added in the Indian tech start - up ecosystem in Q 1 CY2 2 7 out of 15 Unicorns added in Q1 CY22 are from Enterprise 1 5 14 tech, fintech & SCM & logistics UNICORNS ADDED IN Q4 CY21 (OCT - DEC) UNICORNS ADDED IN Q 1 CY2 2 ( JAN - MAR ) Mamaearth (beauty & personal care brand) was the 1st unicorn of 2022 with US$ 52M funding led by Sequoia Capital LEAD School the first Edtech unicorn of 2022 and is also the first school Edtech player to get unicorn status Livspace becomes the first unicorn from the Home furnishing space in Q1 CY22 Source : PGA Labs Deals Database 10 KEY VERTICALS WHICH HAVE CREATED IMPACT DURING THE QUARTER VERTICAL TREND FinTech EnterpriseTech RetailTech EdTech HealthTech ANALYSIS OUTPE R FORMING VERTICAL SCM & Logistics FinTech FinTech continues to develop and grow but at a rate lower than the previous quarter . Growth in banking, investment and cryptocurrency will continue to keep this sector in limelight FinTech continues to 2 unicorns added under dominate by raising FinTech: Oxyzo, 17% of the total Q1 CredAvenue CY22 funding value Growth - stage funding Lending & collection apps & platforms dominated funding raised ~60% of total deals by value (~72% FinTech funding share) Areas like Neo Banking, Buy Now Pay Later, and Crypto and NFTs are taking the market by storm and getting significant traction 12 ~72% investments in FinTech sector are in growth stage; Lending and collection leads with US$ 755M investments Lending & collection have received the Tiger Global and Better capital lead the number ~72 % of total investment is in growth highest funding of deals done in Fintech sector stage Split by funding By # of deals 100% = ~ US$ 1.2B 6 6 28% Lending & collection 62% US$ 1.2 B Personal wealth & 3 14% finance 72% 2 2 2 2 Neobanking 13% Early Growth Payments 4% Lending & collection Fintech IPOs journey continues Embedded Finance in India Crypto exchange 1% • Lending & collections start ups like Oxyzo & • FinTech start - ups like Navi and KFin Tech • A number of platforms surface to enable CredAvenue raise US$ 200M & US$ 137M file DRHP with SEBI – plan to raise ~US$ embedded finance for different use cases in Q1 CY22 850M • Indian firms have forayed into the space Others 6% • Indian FinTech start - ups go abroad – Pine with embedded insurance products Labs files for IPO in the US Source: PGA Labs Deals Database 13 EnterpriseTech EnterpriseTech in India has streamlined workflows, improved communication, and made provision for big data thus, helping employees to work with utmost efficiency Traceability and AI security have been driving this tech space Total amount raised by Sequoia, Accel Partners, EnterpriseTech sector in Blume and Tiger Global Q1CY22 is ~US$ 1.7B have been the most which is ~24% of total active in this space funds raised in Q1CY22 Fastest - growing B2B SaaS is driving trends are in global EnterpriseTech blockchain, advanced growth and Investment manufacturing and in this space has robotics, AI, and big witnessed a data tremendous increase EnterpriseTech sector is packed with companies capitalizing on increasing demand for tools in the world of big data, cloud, IoT, and cybersecurity 14 EnterpriseTech sector received a total funding of ~US$ 1.7B in Q1 CY22; Prominent investors Sequoia and Accel AI & SaaS based tech start - ups have received the Sequoia Capital and Accel are the prominent investors highest funding in EnterpriseTech 41 % investments are in Early stage Split by funding By # of deals 100% = ~ US$ 1.7B 8 14% 6 AI 34% 41% ~ US$ 1.7B 3 3 44% 2 2 2 SaaS 27% Early Growth Late IT & ITES 13% Cloud integration at all levels Customer experience will SaaS platforms raising and increased investment in emerge as the most important large rounds of funding automation processes KPI at core • Expedite the adoption of cloud - native • SaaS platforms like ChargeBee & Hasura • Going forward, every major enterprise technologies Others 26% raised US$ 250M & US$ 100M in Q1 CY22 decision will be taken using CX data metrics • Elevated customer experience and digitized as a key input variable company - wide operations • Ready - to - use templates for organizations which want to automate • Conversational Automation - voice AI, computer vision and tonal emotion Source: PGA Labs Deals Database 15 RetailTech RetailTech solutions have been key drivers in the retail revolution, enhancing operational excellence and shopper experience With the global pandemic acting as an accelerant, digital transformation across domains and verticals in the retail industry has gained new highs RetailTech continues to Tiger Global, Accel and see good momentum Blume have been active with 8% of the total Q1 in this space CY22 funding E - commerce raised Dealshare & Udaan US$ 588M of the total raised over US$ 200M funding each in Q1 CY22 New areas like inventory procurement, beauty marketplaces are taking the market by storm and getting lot of traction 16 RetailTech is booming with E - commerce platforms; ~97% investments are in growth stage E - commerce platforms have received Accel and Blume are the prominent investors in Retail 97% of investments are in Growth the highest funding T ech stage By # of deals Split by funding 3% 100% = ~ US$ 588M 2 2 2 US$ 588M 97% E-commerce 100% Early Growth Merchandising & Vertical marketplaces gaining E - commerce innovation Inventory procurement traction in beauty and cosmetics continues • Enables movement to digitalize informal • Purplle raised significant funding in this • Citymall secured Series C funding of US$ retail in emerging markets. Platforms like quarter (US$ 35M) 75M led by Norwest Venture partners ElasticRun and Udaan are simplifying and • Organic beauty marketplaces like Anveya • FirstCry (Omnichannel children’s retailer) digitizing inventory procurement for small attracted investor interest in organic secured an investment of US$ 250M in Q1 retailers in India cosmetics CY22 • Dealshare & Udaan raised US$ 200M+ in Series E funding rounds taking their valuation to US$ 1B + Source: PGA Labs Deals Database 17 EdTech EdTech market in India is rapidly evolving in terms of growth, acquisitions, hybrid learning models – together aided by positive Government policies Global market leaders are emerging from the Indian startup ecosystem – with large scale acquisitions and global expansion, projecting India as the ’educator - of - the - world’ Strong growth potential Better Capital and in EdTech, with a Blume are the most funding of ~US$ 627 M active institutional in Q 1 CY 2 2 investors Network FP and LEAD Integration of AI and School were the highest AR / VR / XR tools funded in EdTech with into conventional fundings of US$ 300M EdTech to engage and US$ 100M students better respectively The Indian EdTech space saw ~30 deals in Q1CY22 18 Adoption of EdTech in smaller cities and rural market is driving growth; ~86% of EdTech funding is towards start - ups in the growth stage E - learning has received the total B etter Capital, Blume, Sequoia and Tiger Global are the 86% investments are in Growth stage funding in EdTech prominent investors in the EdTech sector with 3 deals By # of deals Split by funding 3 3 3 3 100% = ~ US$ 627M 14% 2 US$ 627 M E-learning 100% 86% Early Growth Inclusivity of multiple segments Product offerings by startups Peripheral models in EdTech • Financing solutions in EdTech • Growing adoption of supplementary EdTech • B2B models in EdTech are emerging – • Web Infrastructure as a Service products in T3, T4 and rural markets owing driving innovations for schools, tuition • D2C products for learning (e.g. toys, robots, etc.) to better internet presentation and growing centers, coaching classes, etc. enhancing the aspirations supply ecosystem • Skill development and lifelong learning • Hybrid learning models being promoted, opportunities for blue - collar segments with leading EdTech players acquisition of driving better income earning potential traditional (offline) Education companies and opening of offline stores augmenting physical touchpoints for pre - sales Source : PGA Labs Deals Database 19 HealthTech Digitization of healthcare has been accelerated due to the pandemic . Areas such as personalized medicine, telemedicine, genomics, wearables with organizers leveraging artificial intelligence (AI), cloud computing, extender reality (XR) and the internet of things (IoT) continue seeing growth in developing and delivering new treatments HealthTech industry Qure.ai and Ekincare continues to see growth were the highest funded and has received a start - ups in the Health funding of US$ 123M in Tech sector with the Q1 CY2 2 respective fundings of US$ 40M and US$ 15M Major investors in the 55% investments in the HealthTech segment HealthTech sector are was done by Inflection towards early stage Point Ventures (IPV) start - ups; followed by growth start - ups (45%) Streamlining clinical communication & collaboration is the next big task for the HealthTech industry 20 HealthTech secured an investment of US$ 123M in Q1 CY22; Infection Point Ventures (IPV) being the major investor Healthcare has received the highest Inflection Point Ventures is the major investor in 55 % investments are in Early stage funding Health Tech sector By # of deals Split by funding 3 100% = ~ US$ 123M 2 2 45% US$ 55% Healthcare 98% 123M Early Growth Others 2% Symptom checker chatbots Remote Patient Monitoring AI in Healthcare AI products are empowering healthcare Chatbots are increasingly being used in the Remote Patient Monitoring is fast becoming the professionals by providing assistance during healthcare space and can be integrated with future of delivering healthcare services. preventive screenings, disease detection, custom patient portals for hospitals and clinics. emergency care enabling a seamless workflow in the healthcare space Source: PGA Labs Deals Database 21 SCM & Logistics The annual trade volume of India with other countries has increased consistently over previous years, and as India ramps up its manufacturing sector, it is expected that India’s share in world trade will further increase, resulting in increased 3 PL and logistics demand ElasticRun and Xpress SCM & Logistics bees were the highest industry has received a funded start - ups in the funding of US$ 730M in sector with the Q1 CY2 2 respective fundings of US$ 320M and US$ 300M Many investors 48% investments in the participated, including SCM & logistics sector Goldman Sachs, Tiger are towards early stage Global, Blackstone start - ups; followed by among others late start - ups (46%) Government initiatives such as GATI Shakti are resulting in increased investment in logistics sector and modernizing existing facilities, along with other measures aimed at reducing logistics cost in the country 22 Emerging interest of investors in SCM & logistics sector; ~48% of investments are in early stage start - ups A number of investors have been involved in the Logistics has received the highest 48 % investments are in Early stage deals in the logistics sector * funding Split by funding 100% = ~ US$ 729M Logistics 95% 46% US$ 48% 729M 6% Warehousing 2% Early Growth Late Others 3% Deployment of EV in the last mile Adoption of asset light model Digitization of processes space to achieve scale The concept of digital transformation focuses on India is rapidly building infrastructure to promote The idea of an asset - light and investment - the implementation of new technologies in all EVs as the new means of transport in line with friendly business model is to keep the capital areas of a company to improve its efficiency. It assets less in comparison to the operations. It is India's pledge to reduce 40% of its fossil fuel constitutes the integration of new digital consumption by 2030. Implementing EVs for last the key to the success of most logistics firms, capabilities in fields such as storage, order prep, mile delivery is seen as an immediate solution to because of its ability to scale them up, and transportation, among others. India’s pollution problem. compared to other methods. Note: *All investors mentioned above have been involved in 1 deal each Source: PGA Labs Deals Database 23 TOP 10 DEALS APPENDIX SECTOR WISE TOP DEALS TECH START - UPS FILING DRHPS WITH SEBI STAKEHOLDER INITIATIVES METHODOLOGY DEFINITIONS : STAGES / SECTORS Appendix Top deals of Q 1 CY2 2 FUNDING (US$ FUNDING # COMPANY FOUNDED SECTOR SUB - SECTOR INVESTORS M) STAGE Ecommerce & listing 1 2014 Food & Foodtech 700 Late Invesco, Baron Capital Group, Kotak platform Sequoia Capital, Tiger Global, Elevation Capital, Accel 2 2017 Enterprise Tech Others 450 Early Partners and Steadview Capital 3 2008 Enterprise Tech AI 400 Growth NEA, March Capital SoftBank Vision Fund II, Prosus Ventures, Chimera 4 2016 SCM & Logistics Logistics 332 Late Investments, Kalaari Capital, and Avatar Ventures, Goldman Sachs 5 2011 EdTech E - learning 300 Growth Undisclosed 6 2015 SCM & Logistics Logistics 300 Early Blackstone, TPG Growth and ChrysCapital Tiger Global, Sequoia Capital, Insight Partners, 7 2011 Enterprise Tech SaaS 250 Late Sapphire, SteadviewCapital 8 2018 Retail Tech E - commerce 210 Growth ADIA, Tiger Global 9 2016 Retail Tech E - commerce 200 Growth Undisclosed Lending and Alpha Wave, Tiger Global, Norwest Venture Partners, 10 2016 Fintech 200 Early collection Matrix Partners, Creation Investments. Total of top deals 3,342 Source ( s ): PGA Labs deal database , PGA Labs analysis 25 Appendix Sector wise top deals in Q 1 CY2 2 FUNDING FUNDING FUNDING FUNDING COMPANY SUB - SECTOR INVESTORS COMPANY SUB - SECTOR INVESTORS (US$ M) STAGE (US$ M) STAGE ENTERPRISE TECH FINTECH Sequoia Capital, Tiger Global, Elevation Alpha Wave, Tiger Global, Norwest Lending and Polygon Others 450 Early Capital, Accel Partners and Steadview Oxyzo 200 Early Venture Partners, Matrix Partners, collection Capital Creation Investments. Lending and Insight Partners, B Capital Group, and Uniphore 400 NEA, March Capital CredAvenue 137 Growth AI Growth collection Dragoneer Tiger Global, Sequoia Capital, Insight Chargebee SaaS 250 Late Niyo Neobanking 100 Growth Accel, Lightrock India Partners, Sapphire, Steadview Capital SCM & LOGISTICS EDTECH SoftBank Vision Fund II, Prosus Network FP E - learning 300 Undisclosed Ventures, Chimera Investments, Kalaari Growth ElasticRun Logistics 332 Late Capital, and Avatar Ventures, Goldman Sachs LEAD School E - learning 100 Growth WestBridge, GSV Ventures Blackstone, TPG Growth and XpressBees Logistics 300 Early ChrysCapital Alpha Wave Global, Tiger Global where Tiger Global Management, Axilor, Classplus E - learning 62 Abu Dhabi’s Chimera Investment and Growth Foundamental, Arali Ventures, Stride TRP Global Partners Wiz Logistics 36 Early Ventures and Alteria Capital RETAIL TECH HEALTH TECH Novo Holdings, HealthQuad, Dealshare E - commerce 210 Growth ADIA, Tiger Global Qure.ai Healthcare 40 Growth MassMutual Ventures Udaan E - commerce 200 Growth Undisclosed EKincare Healthcare 15 Growth HealthQuad Source ( s ): PGA Labs deal database , PGA Labs analysis 26 Appendix Tech start - ups filing DRHPs with SEBI # COMPANY FOUNDED SECTOR SUB - SECTOR DATE DRHP (Q 1 CY2 2 ) Travel & 1 2011 Travel planning 21/01/2022 Hospitality 2 2004 Enterprise Tech AI 04/02/2022 Lending and 3 2018 FinTech 10/03/2022 collection Travel & 4 2006 Travel planning 24/03/2022 Hospitality Source ( s ): Secondary research , PGA Labs analysis 27 Appendix Microsoft AI Innovate Appscale Academy Positive outlook for start - up • Microsoft has launched Microsoft AI • Google and MeiTY to launch a growth ecosystem is evident from Innovate for nurturing and scaling start - and development programme for early ups that are leveraging Artificial different stakeholder to mid - stage startups Intelligence • Focus on gaming, healthcare, fintech, initiatives • Qualified seed to series B startups will edtech, social impact sectors be provided with technical enablement • 100 start - ups will be selected based on benefits, including Azure benefits and defined qualitative and quantitative product engineering support etc. parameters • 10 - week - long initiative would support startups in India leveraging AI technologies Apollo India Elevate • Kickstarted in November 2021, the first cohort focused on manufacturing and • Program to provide expert advise, logistics with the second one focusing assistance, and the opportunity to take on fintech advantage of Oppo's products, resources, and distribution channels to launch their idea • Focus on camera and image processing, battery, networks (5G), system performance, payments, AI, and gaming Source ( s ): Secondary research , PGA Labs analysis 28 Appendix Scope WHAT’S EXCLUDED FROM WHAT'S INCLUDED IN THE Inclusions & Exclusions THE REPORT? REPORT? • Non - tech start - ups operating in the • Only tech start - ups have been consumer space have not been considered for this report which are included in this report working towards innovation in technology , business process or • Investments from angel investors , business model incubators and start - up accelerators have been excluded • Start - ups which have received funding from private equities or venture capital • Debt investments and strategic deals firms have been considered into tech start - ups have not been considered • Founders of Indian origin with HQ or core product development in India • Start - ups at the idea stage without a prototype or minimum viable product • Start - up to have a prototype or MVP; have also not been considered idea stage start - ups are not considered 29 Appendix PRIMARY INPUT FOR THIS REPORT Methodology INCLUDES THE FOLLOWING SOURCES Extensive research of media This pulse report has been co developed by NASSCOM and PGA Labs through a articles comprehensive study to understand the tech start - up landscape in India Inc42 Mint This report analyses the following : Your story Business • Current investment scenario and trends that define the Indian tech start up IVCA Standard ecosystem Economic Times • Ecosystem enablers like Incubators / Accelerators as well as government policies • Recent DRHPs filed with the regulators PGA Labs proprietary deal database Government websites Ministry of corporate affairs SEBI Sector analyst reports 30 Definitions of stages and sectors Appendix Media & Entertainment FoodTech Automotive STAGES OF FUNDINGS HAVE BEEN Provides content for entertainment across the Tech enabled companies supporting the Companies involved in production, web and mobile medium FoodTech industry MAPPED AS manufacturing, sales and services of motorized E.g., News & Media Apps, Live Streaming Apps, News Platforms, E.g., Online Food Ordering, Restaurant Management Cloud vehicles OTT Content, Video Intelligence Apps, etc. Solutions, Food Discovery Platform E.g., Electronic Engineering, System Integration, Automotive Maintenance, Electric Vehicles, Automotive marketplaces, etc. Series A and prior rounds are early stage SCM & Logistics Retail Tech Enabling tech in logistics services and supply Series B,C,D and E are growth stage Companies enabling Sales of goods and product FinTech chain management online or Integration of tech in offline markets Enables financial services, banking and insurance Series F and above are late stage E.g., Logistics and Distribution Platform, Fleet Management, E.g., Products/Services cutting across several verticals through technology Warehousing, IoT Platform for Logistics, IoT Platform for E.g., Online Banks, Financial Management Apps, Payment Goods Transportation Marketplace, etc. Fashion & Lifestyle Management Platforms, Alternative Lending Platforms, Money Transfer Platform, Expense Management, Investment Marketplaces, Online grocery & Home essentials Gaming Platforms, Cryptocurrency & Trading Platforms, etc. platforms. Also includes Retail enablers, B2B Tech Innovation and facilitation in the Gaming marketplaces, Social commerce platforms, Rental industry EdTech E.g., AR/VR Gaming, Community platform Games, Fantasy platforms etc. Provides learning solutions & services through Gaming Platforms etc. technology SECTOR DEFINITIONS AgriTech Legal Tech E.g., Learning Apps, Test Preparation Tech, Education Advisory Platform, K 12/Higher education platforms, Language Learning Start ups engaged in tech enablement in the Tech based companies for Legal help to Enterprise Tech Platforms etc. Agricultural industry Individuals/Corporates E.g., Field Surveillance, Precision AgriTech, Farm infrastructure, B2B Product companies targeting Horizontal E.g., Contract Management, Brand Protection and Anti Soil Testing, Farm Input E Commerce etc. Travel & Hospitality Counterfeit, Legal Services Discovery/Booking marketplaces, solutions for Large Enterprises / SMBs E.g., Data Analytics/AI/ML Platforms, Development Platforms, etc. Tech companies engaged in supporting the travel Collaboration tools Productivity Applications, Customer Advertising & Marketing Tech and hospitality industry Services, Big Data/Cloud/Security Infrastructure, etc. Provides direct advertising and marketing E.g., Hotel Booking Services, Travel Planning, Travel Packages Portal, Travel Collaboration Community, etc. assistance through technology HealthTech E.g., Content marketing, influential marketing, Push notifications Provides technology platform for solving etc. Mobility HealthTech problems Tech - enabled companies providing simplified E.g., Medical Solutions, Marketplace for Health Services, Aerospace & Defense Transportation services to users Health Lab Aggregators, Online Pharmacies, E - Diagnostics, Tech - based companies supporting the Defence E.g., Car pooling, Self Drive Rentals, Two - wheeler taxi Ambulance Aggregator, etc. and Aviation industry aggregators, Mass Transit, Tech Enablers E.g., Military Drones, Green Propulsion Systems developers, HRTech Sensors and Platforms for security applications etc. Industrial & Manufacturing Tech - enabled companies supporting Human Engaged in manufacturing of tech - enabled Resources Activities Energy & Utilities devices or machines; Construction/Mining E.g., Applicant Tracking systems, HR Management System, Tech Enablement for Natural Resource Candidate Assistance & Sourcing, Corporate Training/Learning sector, etc. Management and Utilization and Development, Recruitment Marketplaces, etc.. E.g., IoT based Predictive Maintenance of Machines, 3D E.g., Renewable Energy products, Recycling of Resources, Energy Printing (Manufacturing) Production and Distribution, EV charging Infrastructure etc. 31 About NASSCOM is the industry association for the technology sector in India A not for PGA Labs is a technology - enabled business research & intelligence services firm that profit organization funded by the industry, its objective is to build a growth led and specializes in driving decision from on - ground insights Our teams are multifaceted with sustainable technology and business services sector in the country with over 3100 a unique mixture of qualitative , quantitative and digital research experts . With a holistic members NASSCOM Insights is the in house research and analytics arm of NASSCOM approach focusing on the “ What and Why ”, we are able to extract relevant insights generating insights and driving thought leadership for today’s business leaders and from data employing advanced technology tools and innovative data gathering entrepreneurs to strengthen India’s position as a hub for digital technologies and approaches . innovation Our clients use our capabilities to generate competitive / market insights for the sectors they operate in, sectors they want to expand to or the sectors of interest for their USAGE OF INFORMATION portfolio companies Forwarding / copy / using in publications without approval from NASSCOM will be considered as infringement of intellectual property rights . www.pgalabs.in FOR QUERIES, PLEASE CONTACT VAISHNAV KUMAR RAI Manager, Co r p o rate Communications vaishnav.rai@praxisga.com +91 7827 944 925 32 PGA Labs We enable better decisions. Deep business research and intelligence that helps make 50% BETTER DECISIONS 250 + faster to annual outcomes engagements Deep on - ground insights that you can act on 98%+ 4 offices, deep experience across accuracy geographies – India, US, Europe, MEA, and 600+ SEA region years domain expertise Advanced technology tools and innovative 34 data gathering approach practices Multifaceted teams with a unique mixture of qualitative, quantitative, and digital research 100+ 40 - 60 experts team members she/he ratio DISCLAIMER The information contained herein has been obtained from sources believed to be reliable NASSCOM and its advisors & service providers disclaims all warranties as to the accuracy completeness or adequacy of such information NASSCOM and its advisors & service providers shall have no liability for errors , omissions or inadequacies in the information contained herein or for interpretations thereof . The material or information is not intended to be relied upon as the sole basis for any decision which may affect any business Before making any decision or taking any action that might affect anybody’s personal finances or business , they should consult a qualified professional adviser . Use or reference of companies / third parties in the report is merely for the purpose of exemplifying the trends in the industry and that no bias is intended towards any company This report does not purport to represent the views of the companies mentioned in the report Reference herein to any specific commercial product process or service by trade name , trademark , manufacturer , or otherwise , does not necessarily constitute or imply its endorsement , recommendation or favouring by NASSCOM or any agency thereof or its contractors or subcontractors . The material in this publication is copyrighted No part of this report can be reproduced either on paper or electronic media without permission in writing from NASSCOM Request for permission to reproduce any part of the report may be sent to NASSCOM 34 C o p y r i g h t © 2 0 2 2 NASSCOM Plot 7 to 10, Sector 126, Noida - 201303 /NasscomVideos /NASSCOMOfficial /nasscomR www . nasscom . in research@nasscom in + 91 - 120 - 4990111