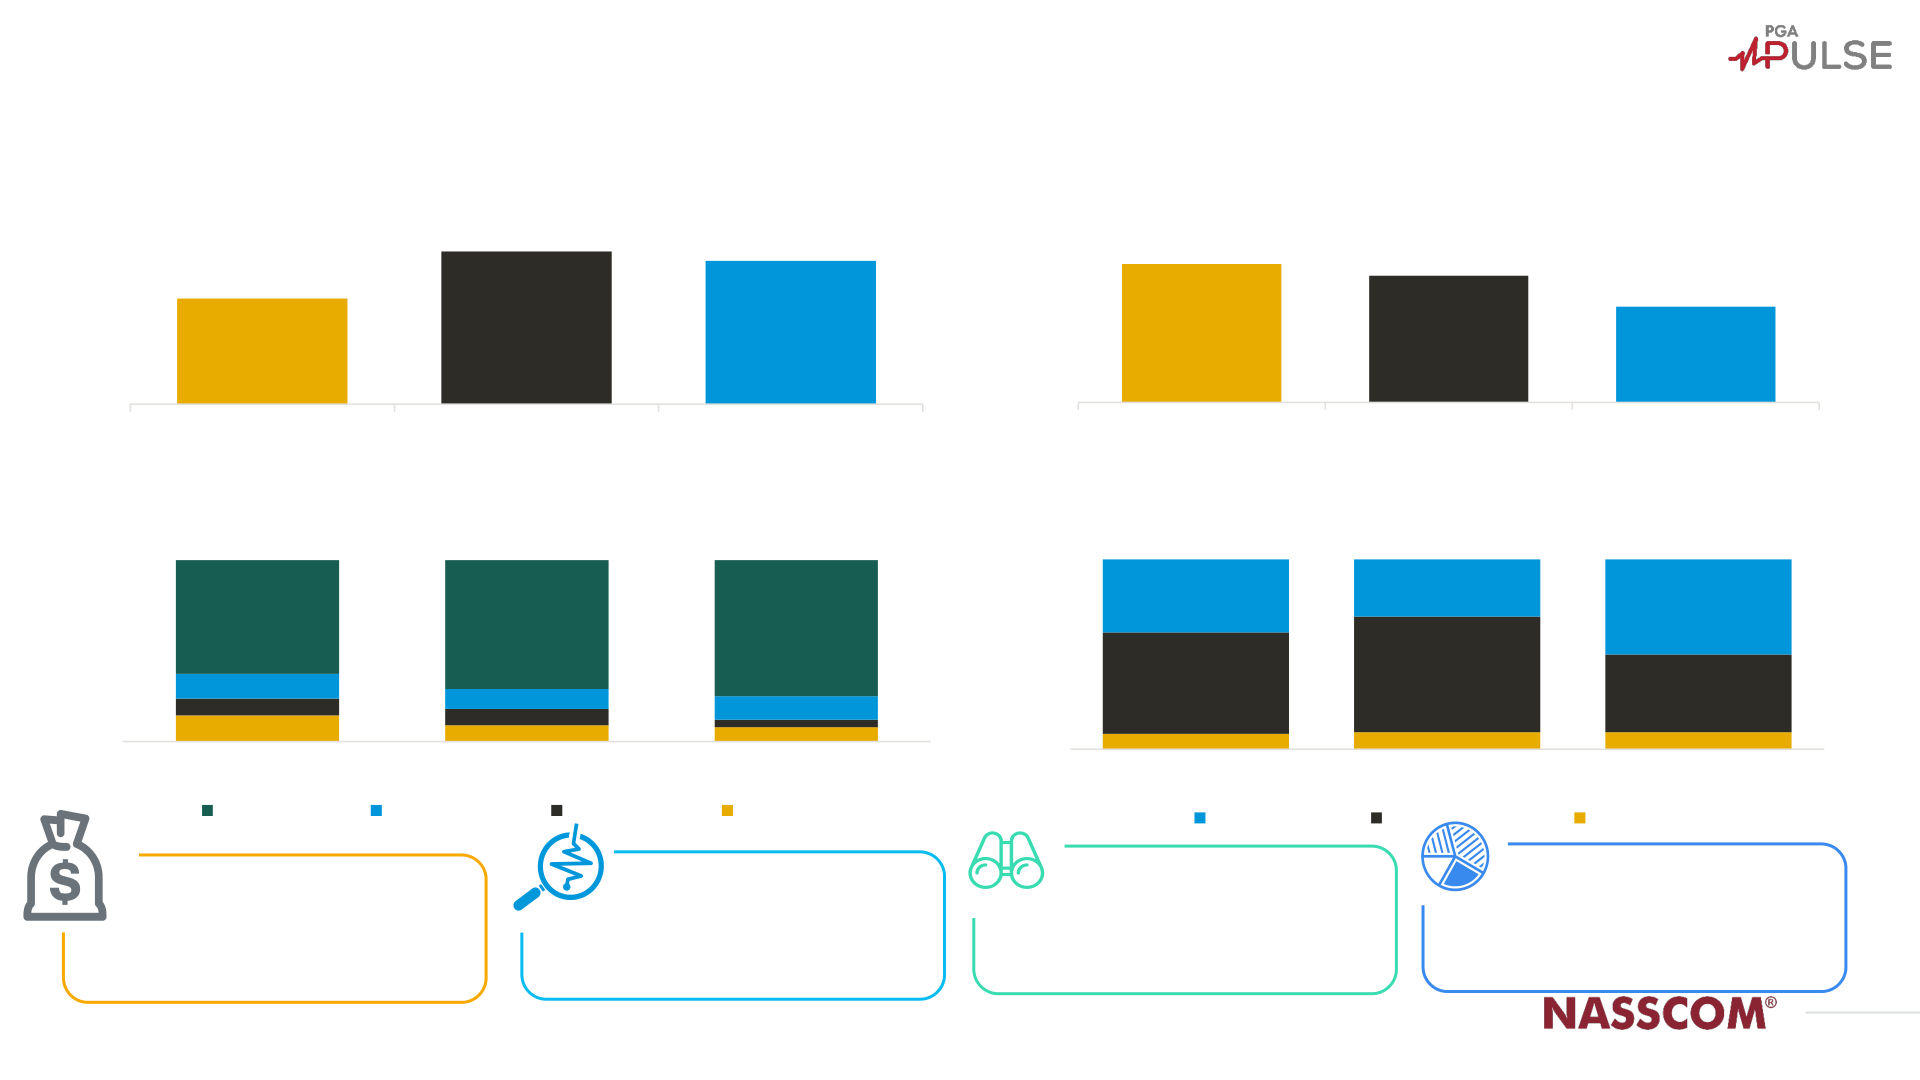
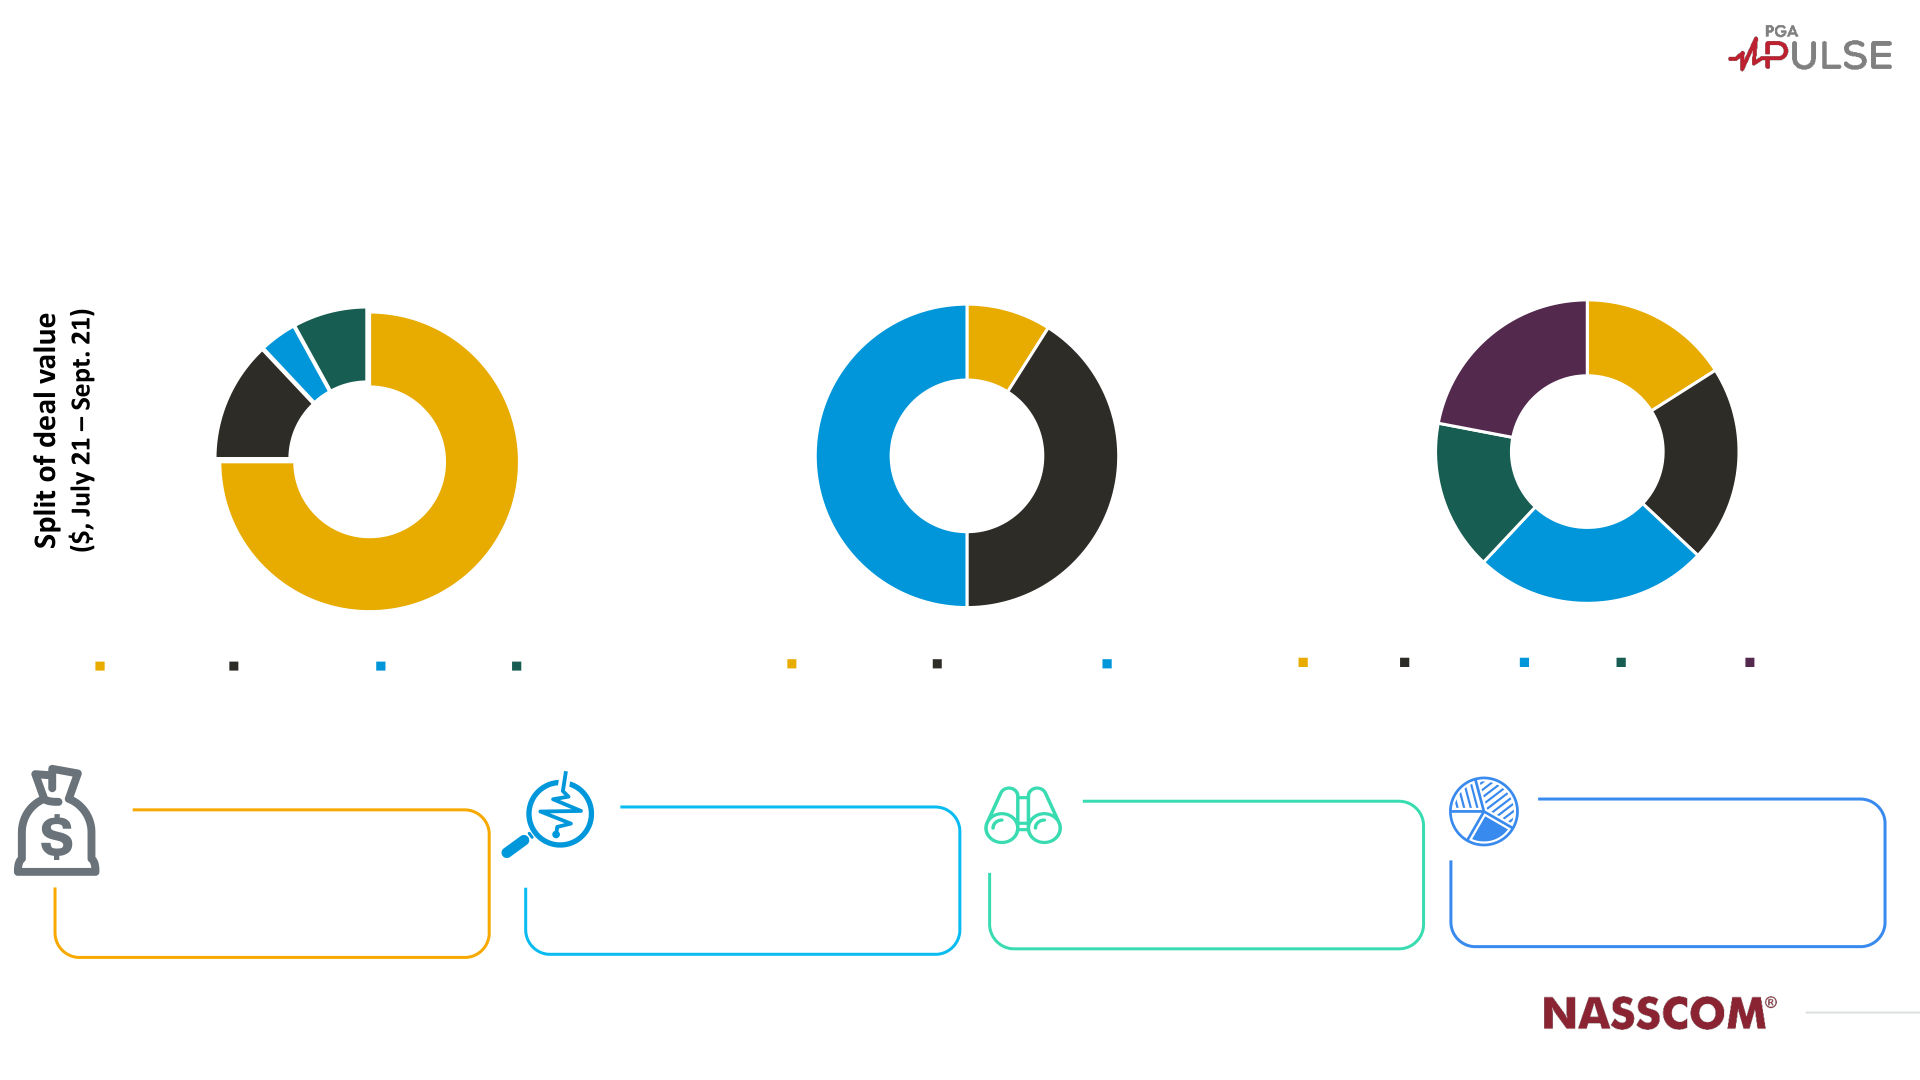
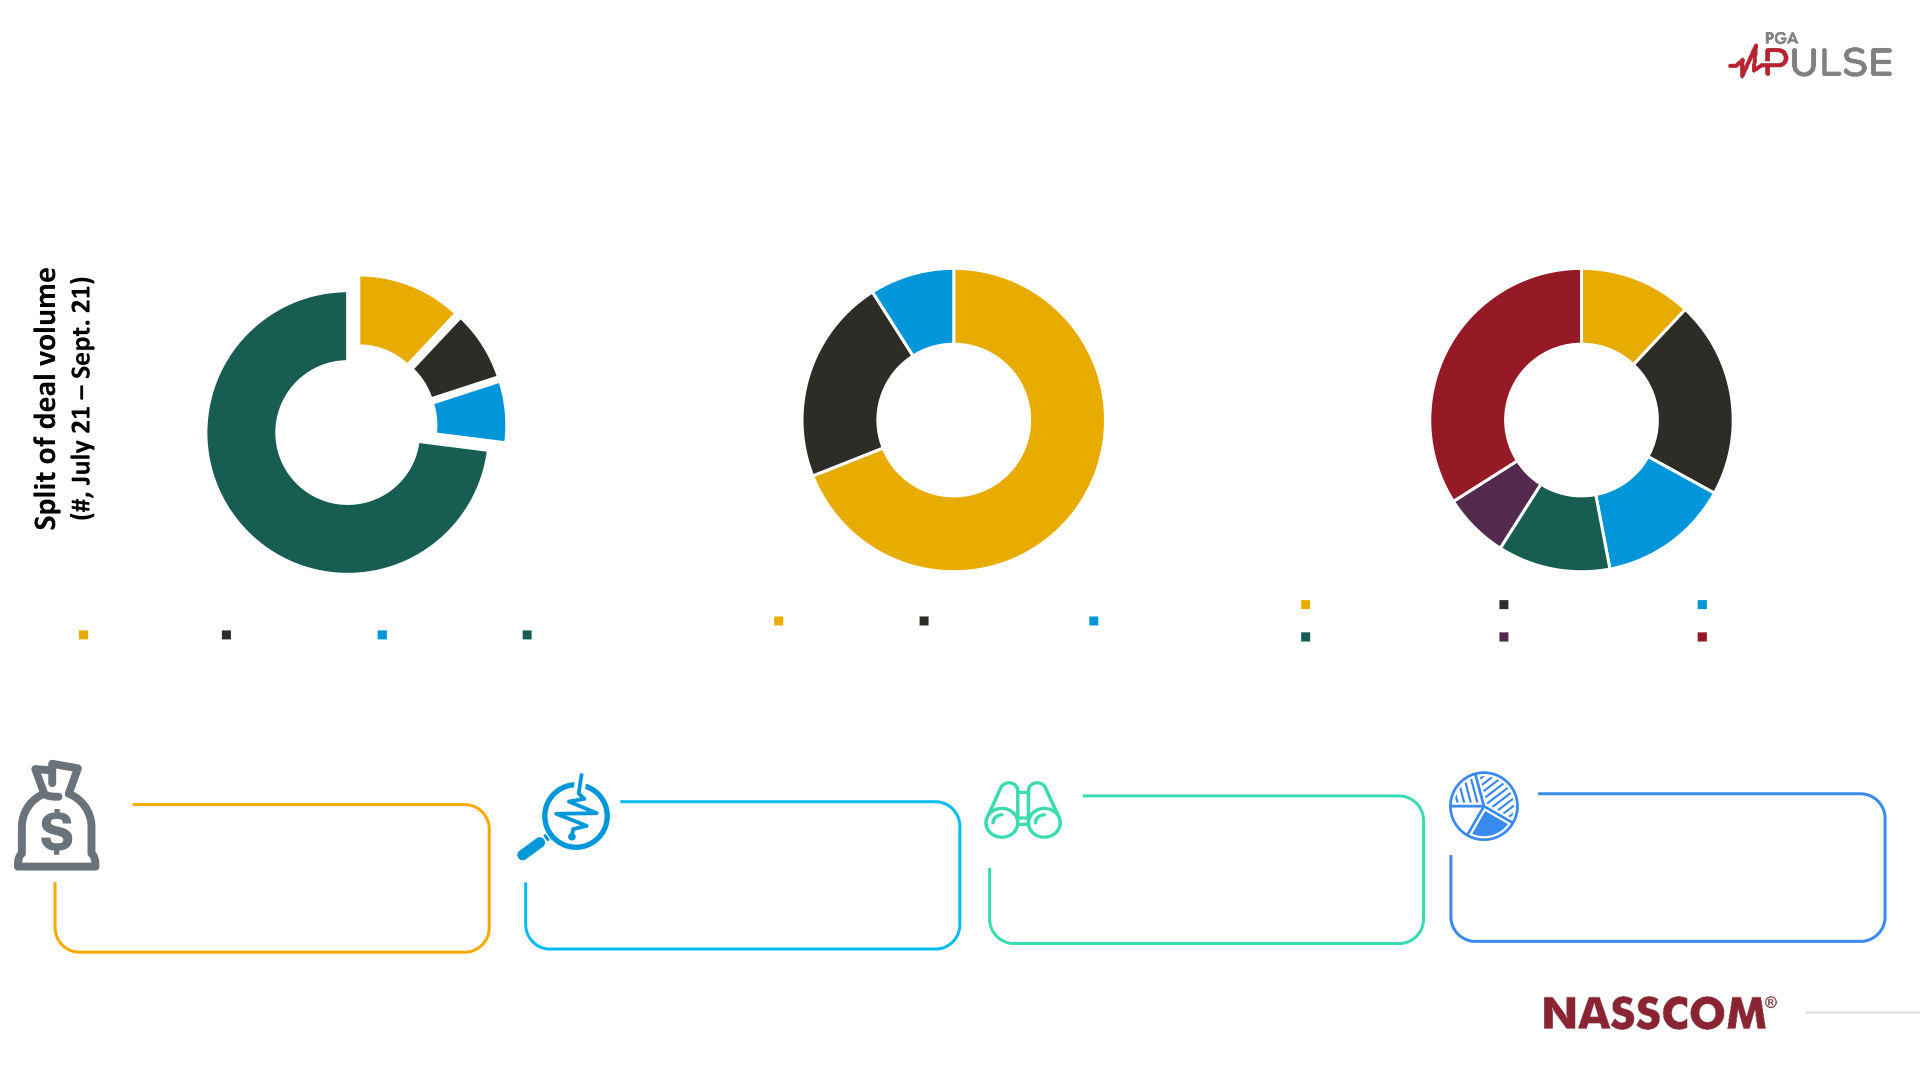
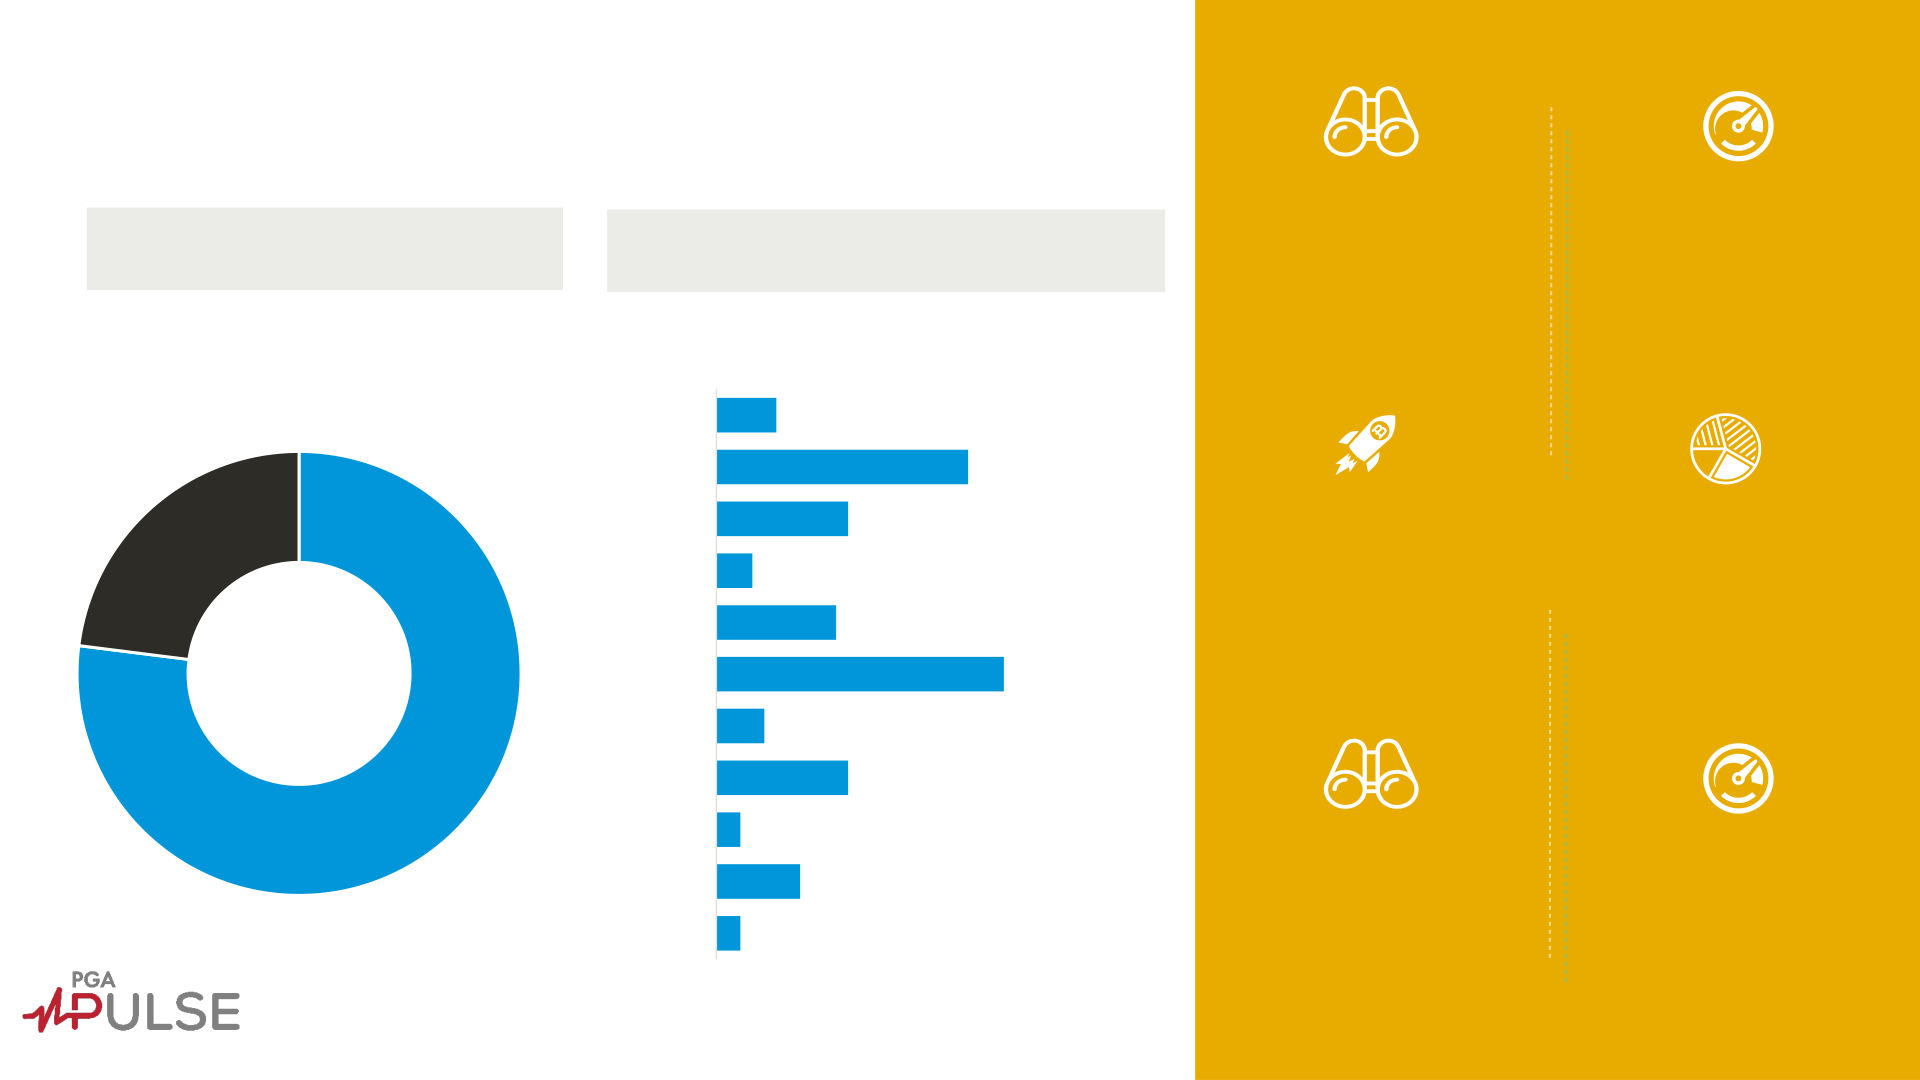
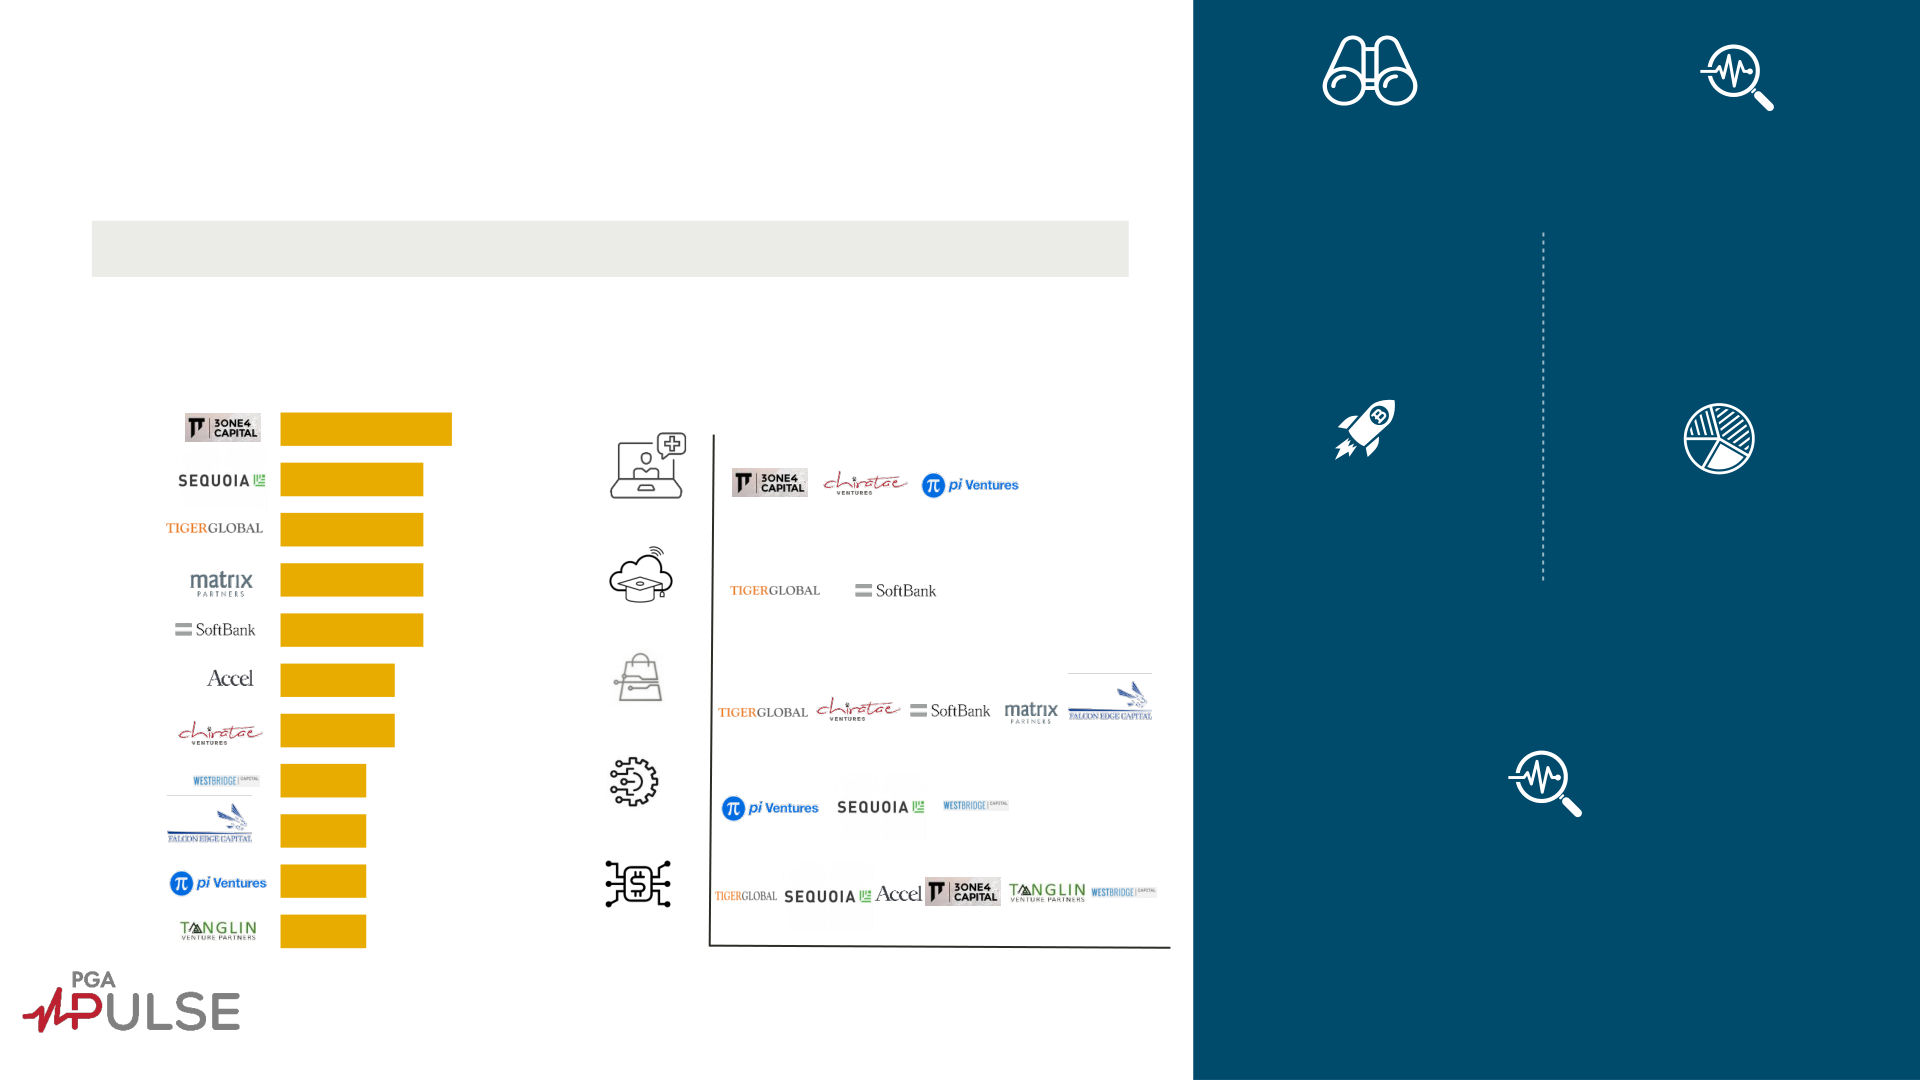
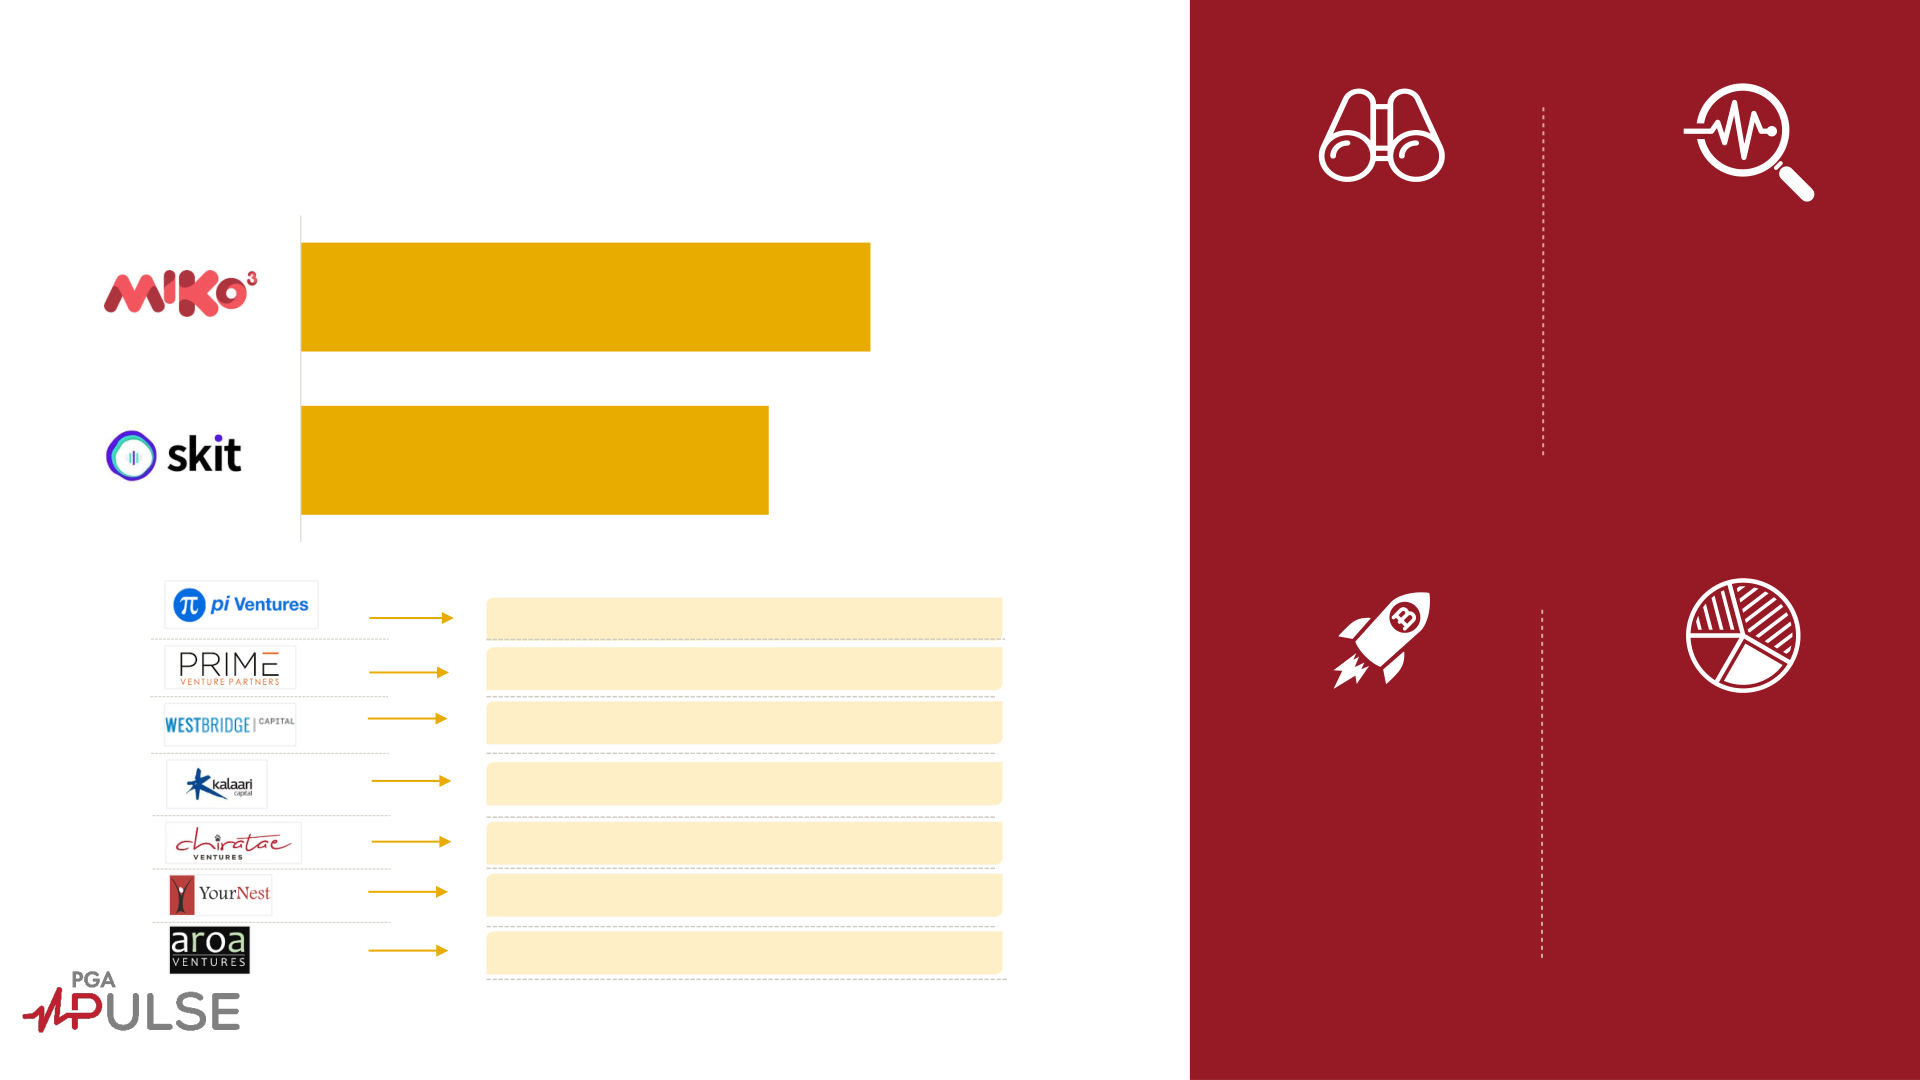
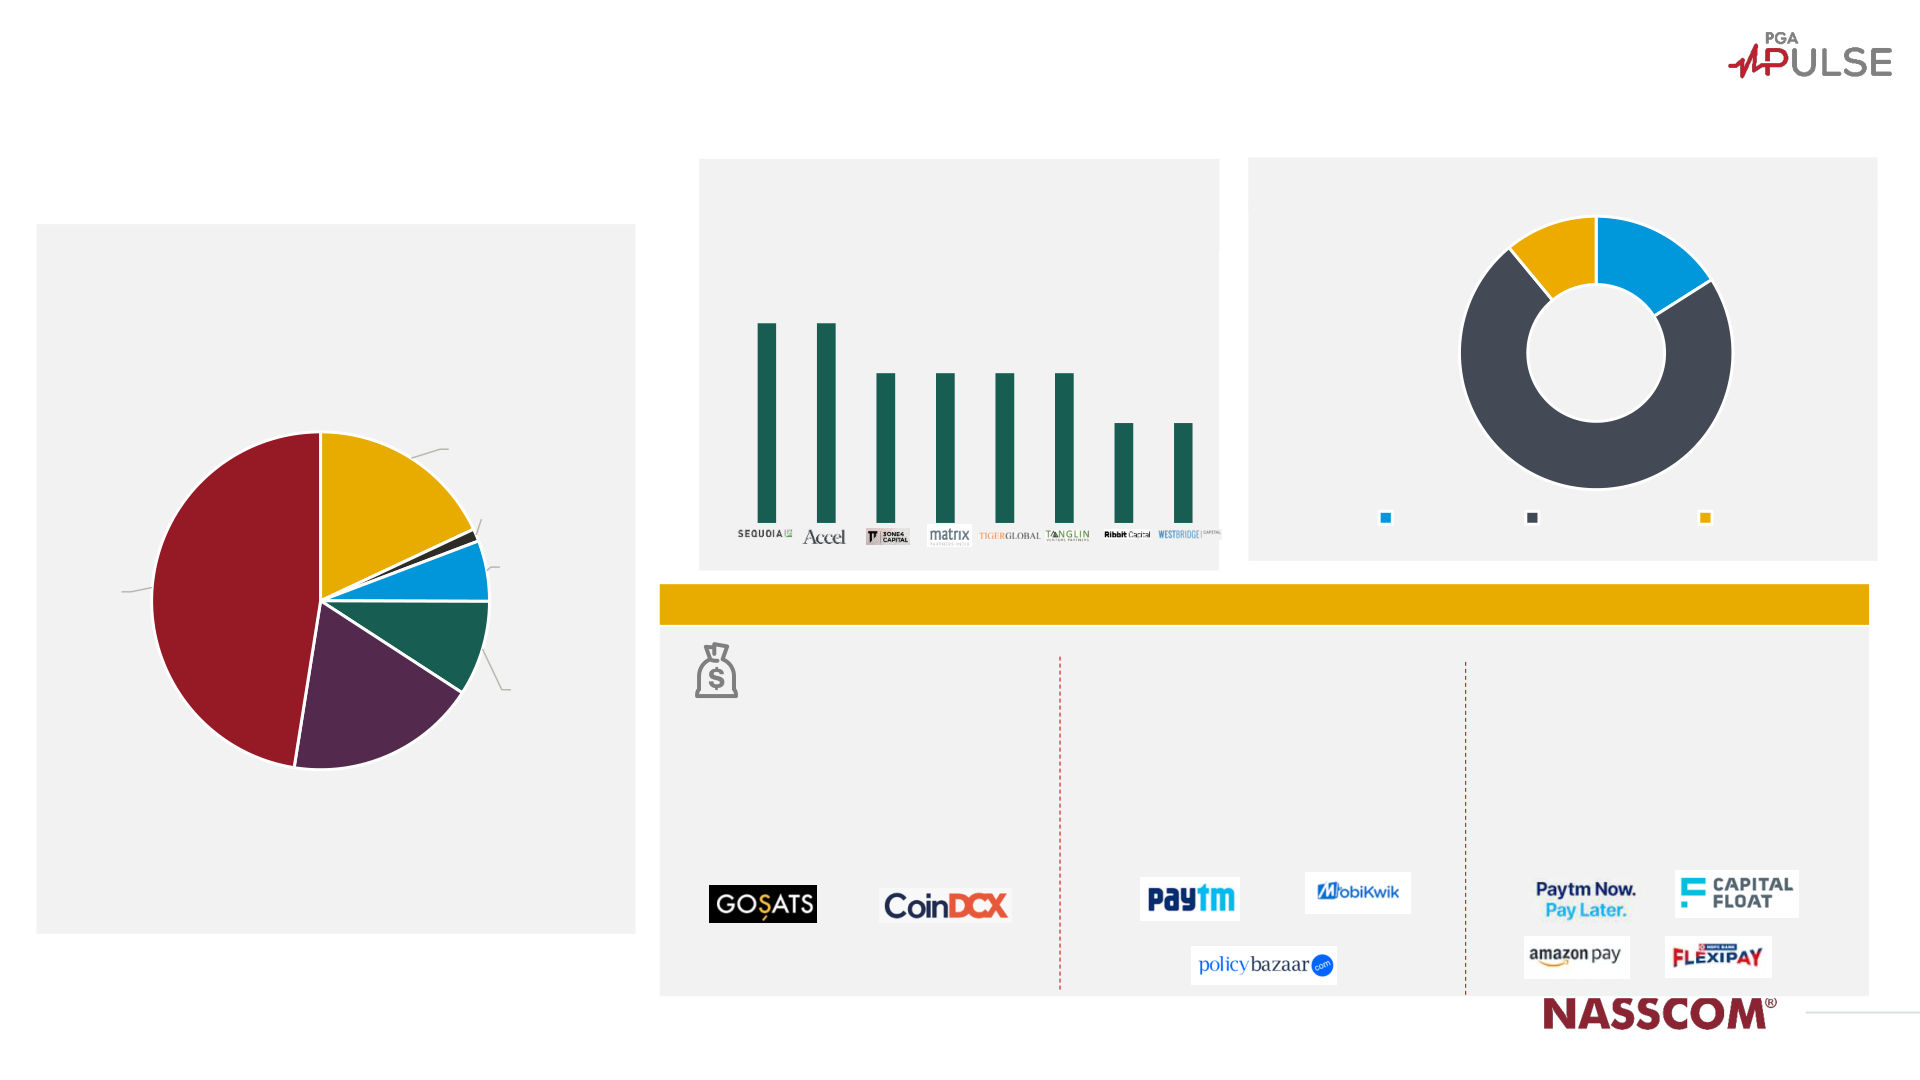
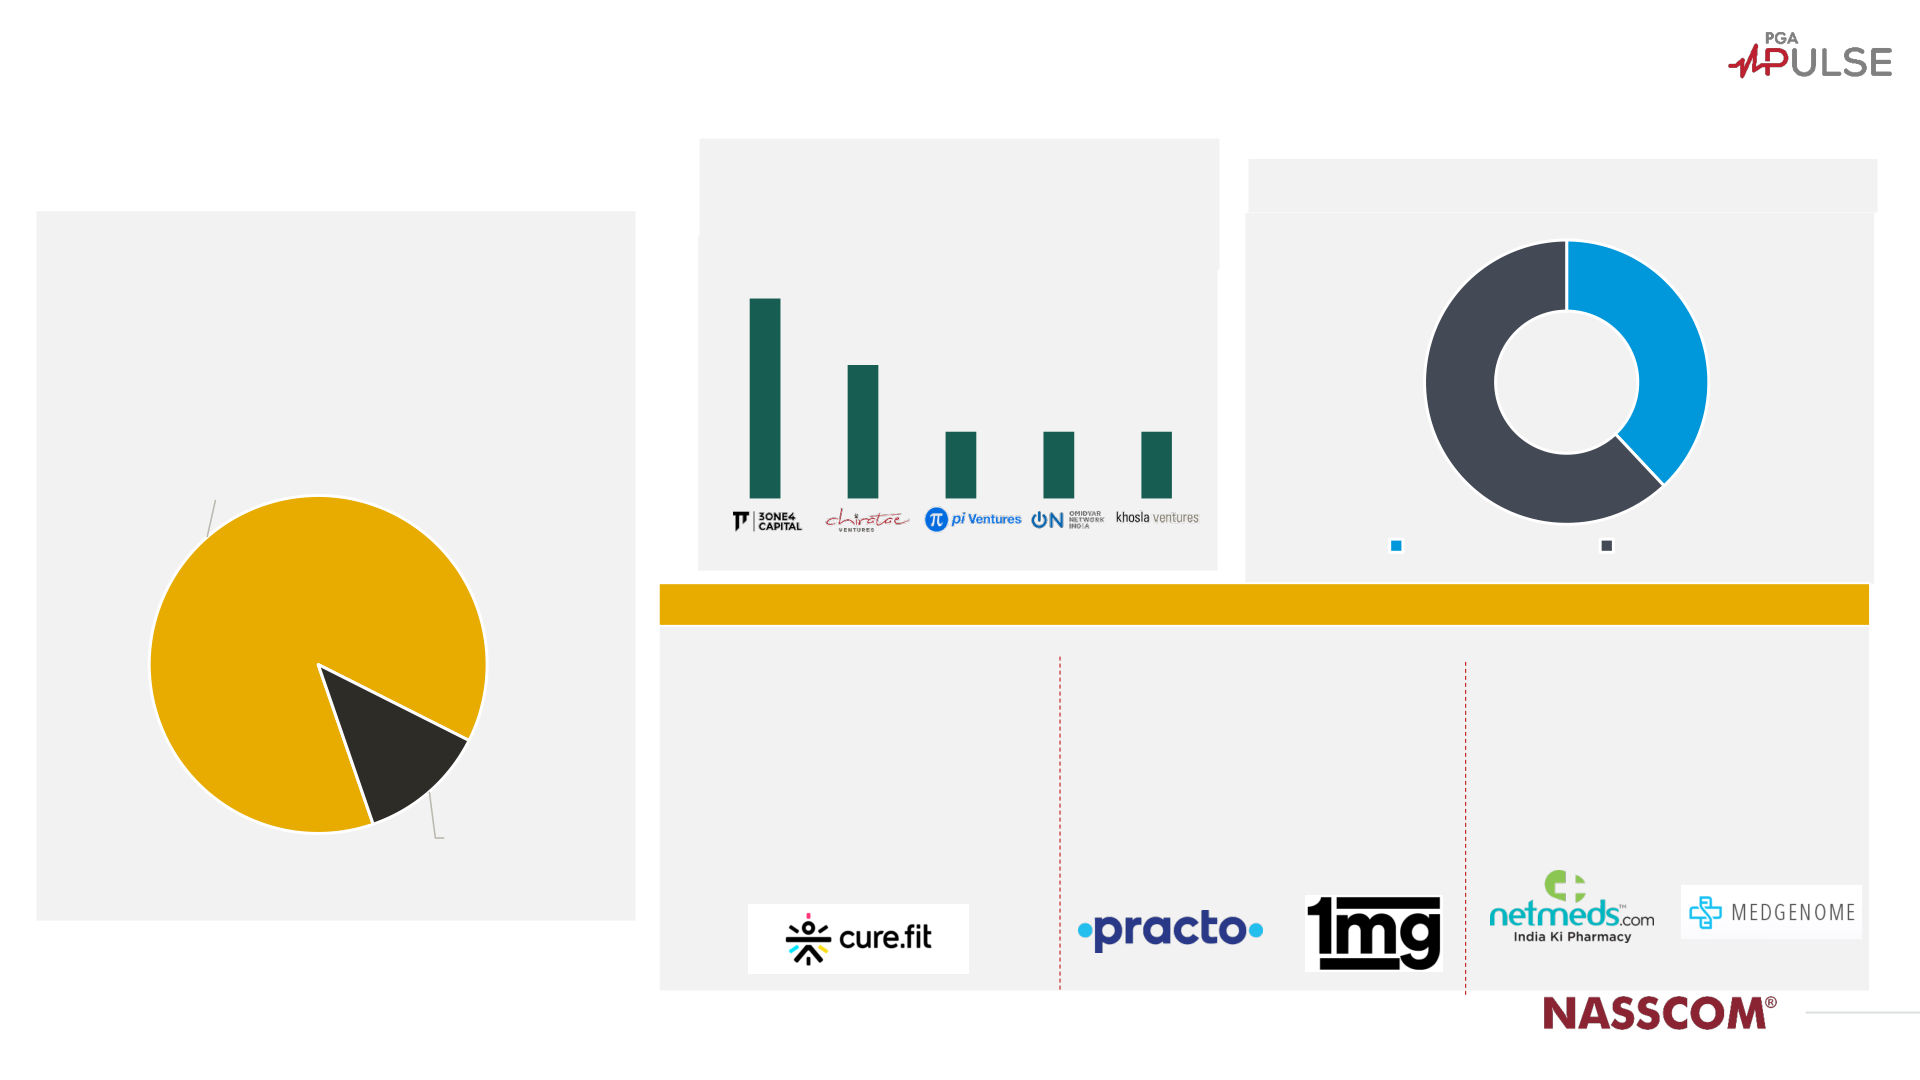
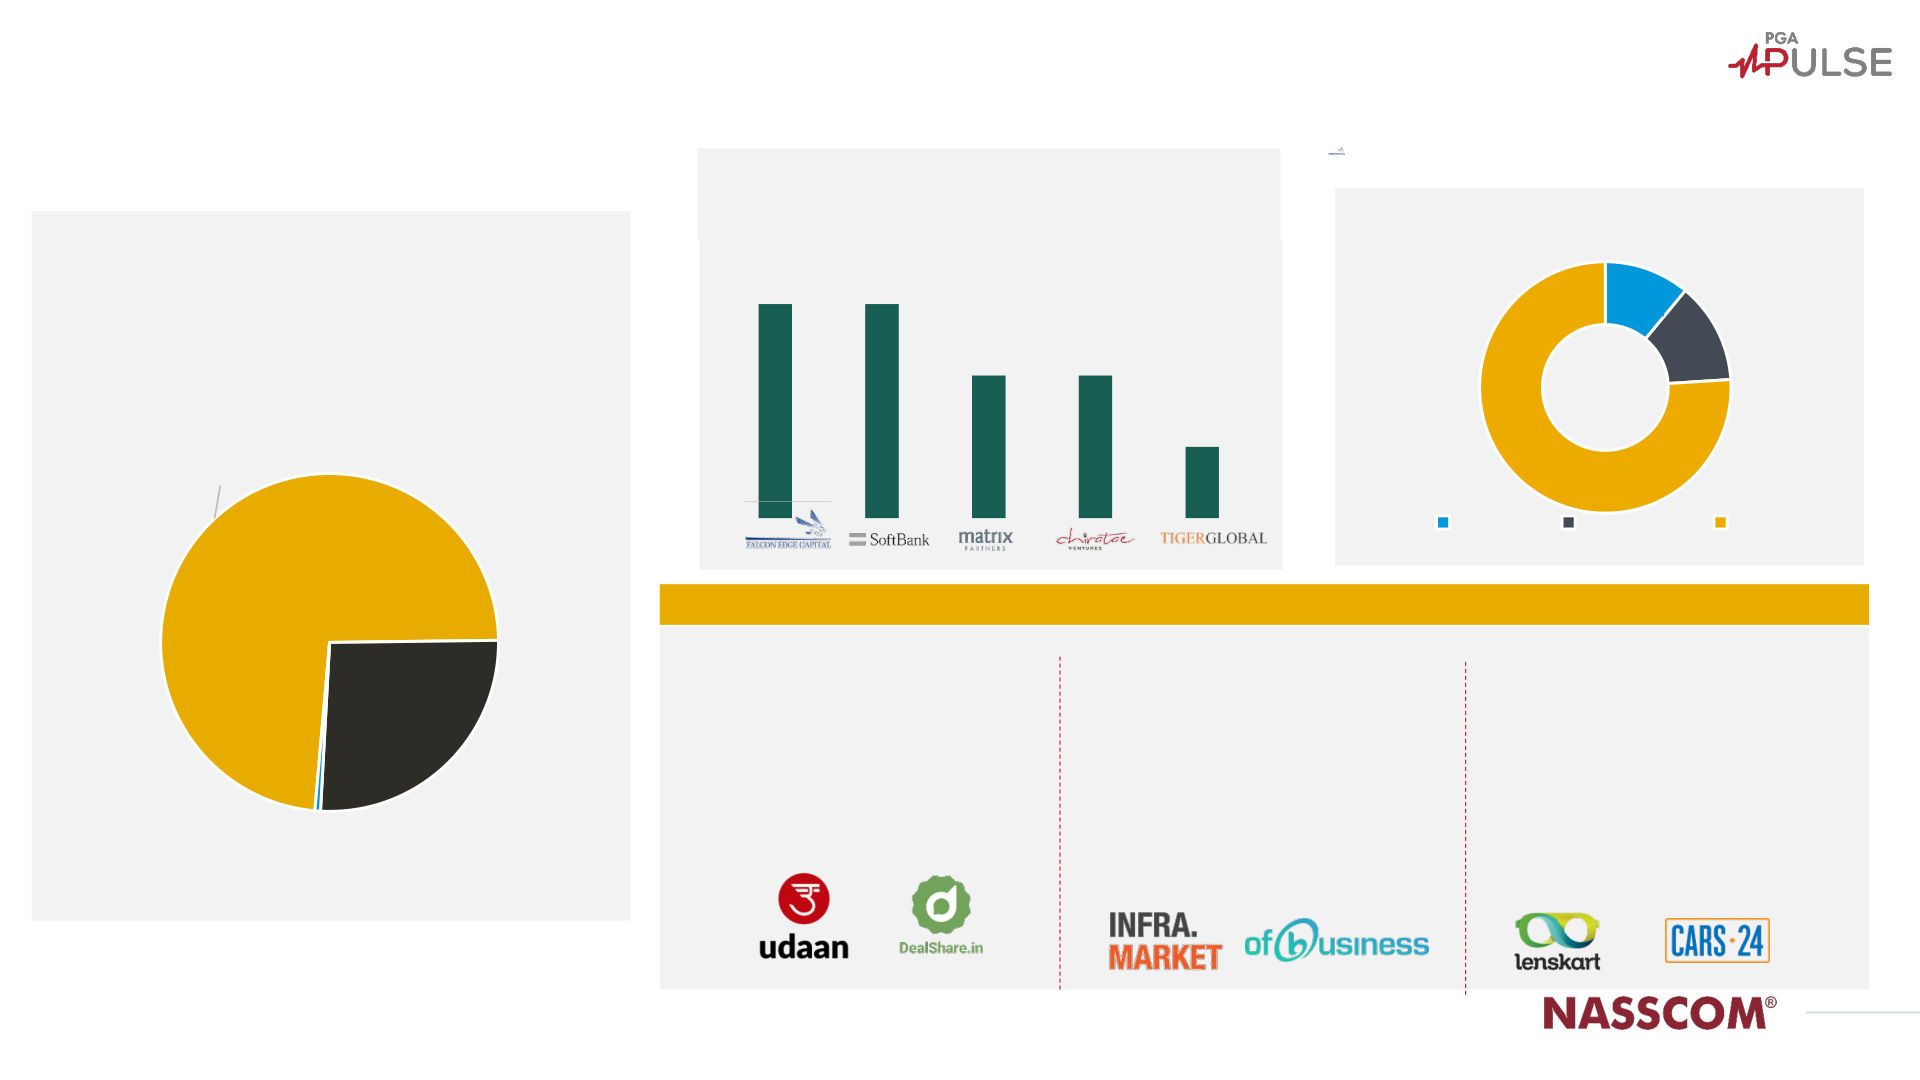
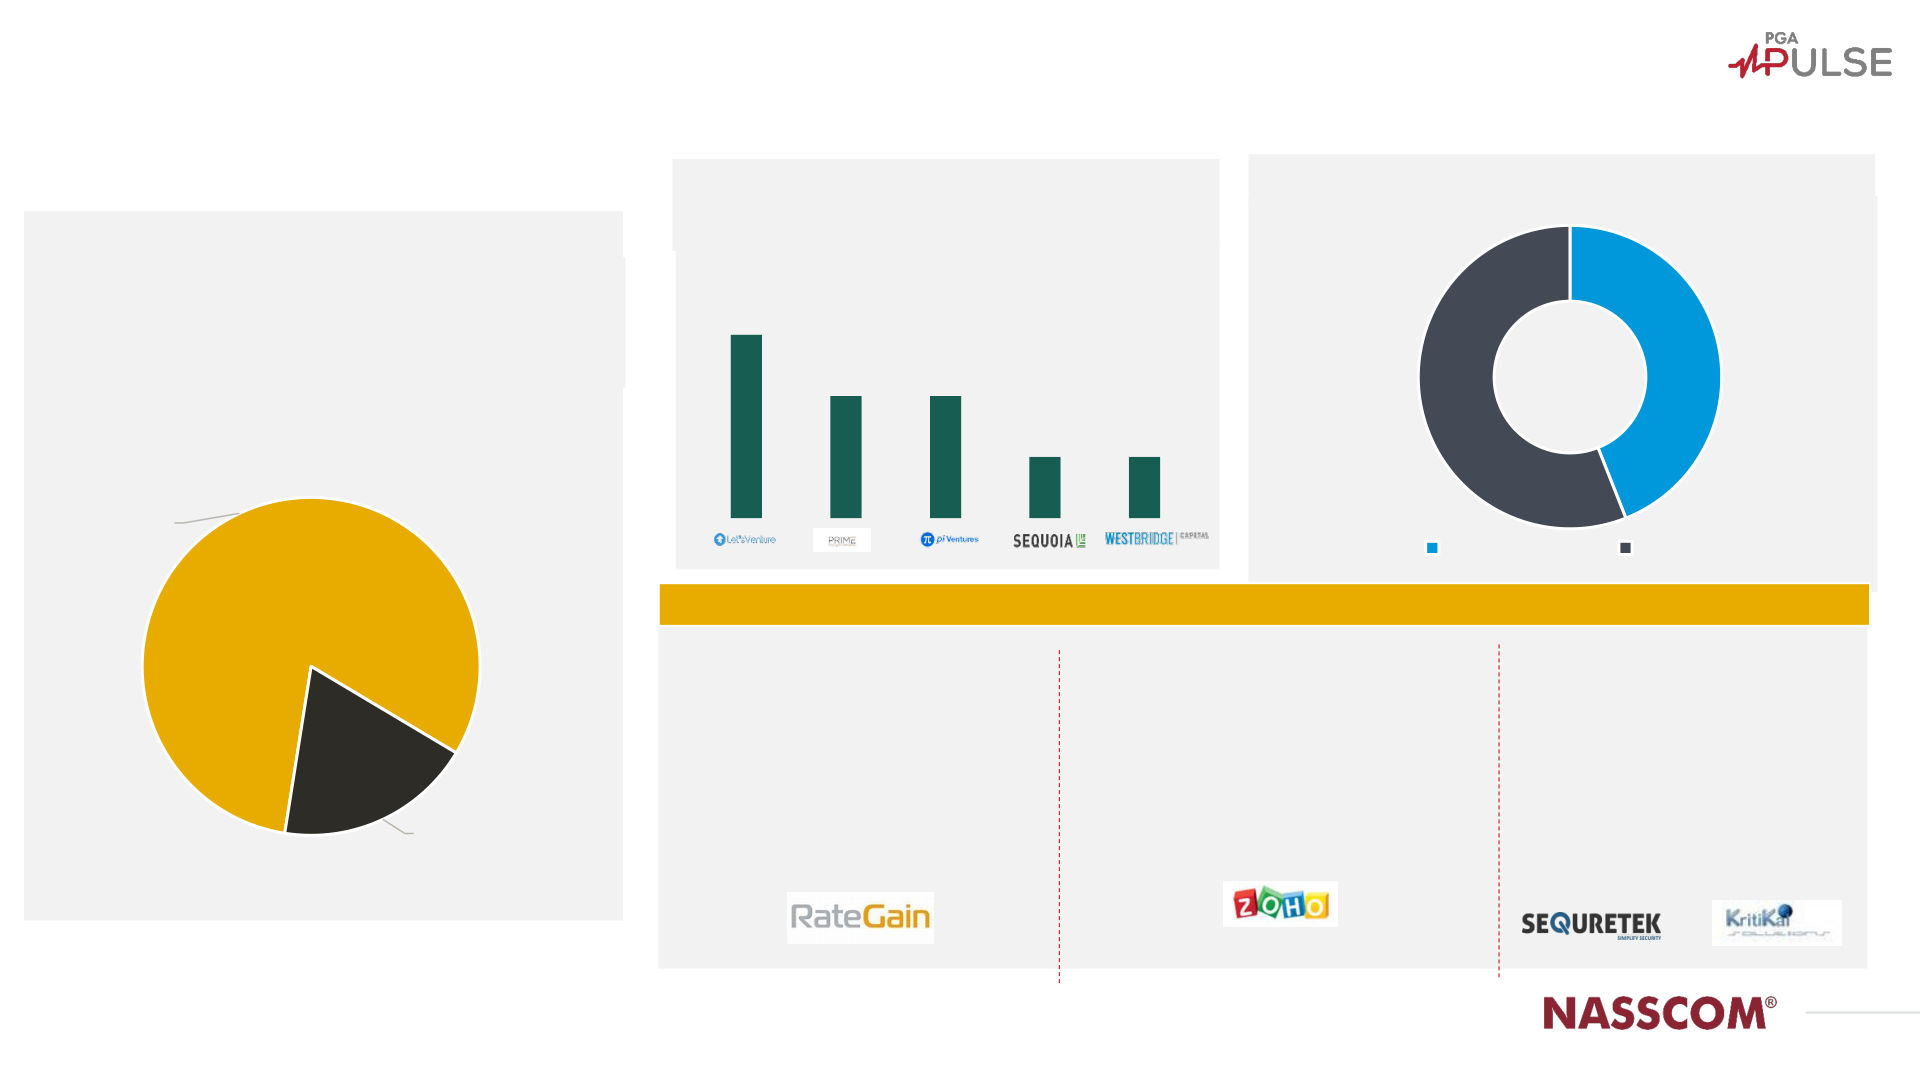
Tech Start - ups: Quarterly Investment Factbook Q3 CY21 Start - up Deal Analysis November 2021 Table of Contents Funding Analysis ……………… 04 Vertical Trends ……… ……… 1 2 ……………… 23 Additional Data ……………… 27 Appendix 2 © 2021 NASSCOM. All rights reserved. Summary: Q3 CY21 (July – Sept. 2021) • India’s start - up ecosystem continues to see considerable acceleration in Q3 CY21. • A record thirteen start - ups joined the unicorn club this quarter. • The EdTech sector demonstrated maximum traction and remained a favorite among global investor community this quarter. Funding # Deal Volume Unicorns Top Funded Vertical Most Funded Stage US$ 6.1B 121 EdTech 13 Late 25% of the Total Funding 50% of total funding Total Unicorns(till Sept’ 21): 66 Down ~6% Q - o - Q Down ~24% Q - o - Q 3 Funding Analysis Unicorns Q - o - Q Comparison Deal volume by latest quarter Top investors and their focus sector Deal value by latest quarter Funding by sales channel and funding rounds DeepTech deal flow 4 © 2021 NASSCOM. All rights reserved. Q - o - Q Comparison US$ 6B+ raised by Indian start - ups in Q3 CY21 Total Funding (US$ B) Deal Volumes (No. of deals) 6.5 6.1 175 160 4.5 121 Q1 CY21 Q2 CY21 Q3 CY21 Q1 CY21 Q2 CY21 Q3 CY21 Funding by Deal Size Funding by Stage % of total funding % of total funding 30% 38% 50% 63 % 71 % 75 % 61% 53% 14 % 41% 11 % 9 % 13 % 9 % 4 %% 14 % 9 % 8 % 8% 9% 9% Q1 CY21 Q2 CY21 Q3 CY21 Q1 CY21 Q2 CY21 Q3 CY21 > US$ 100M US$ 50-100M US$ 25-50M < US$ 25M Late Growth Early 91% of the funding activity The number of deals closed 75% of the total funding Indian start - ups remain driven by growth and late - in Q3 CY21 decreased by driven by 14 large deals (> attractive, raised >US$ 6B in stage deals ~24% compared to Q2 US$ 100 M) in 3Q CY21 two consecutive quarters in CY21 CY21 5 © 2021 NASSCOM. All rights reserved. Deal value by latest quarter FoodTech and EdTech together attracted ~46% of total funding in Q3 CY21 Funding by Deal Size Funding by Stage Funding by Sector 9% 8% 4% 16% 22% 13% 50% US$ 6.1B US$ 6.1B 21% US$ 6.1B 41% 16% 75% 25% FinTech FoodTech EdTech Retail tech Others Early Growth Late > US$ 100M US$ 50-100M US$ 25-50M < US$ 25M Large ticket deals helped ~50% of funding activity driven EdTech and FoodTech to 75% deals by value were in the ~6% fall in Q3 CY21 deal by late - stage companies. account for more than 46% of ticket size of US$ 100M or above value compared to Q2 CY21 However, they represented just total funding 9% by deal count Notes(s): Others includes SCM, Media and Entertainment, HealthTech, Marketing, Automotive, HR Tech, Hospitality, Manufacturin g, AgriTech, Aerospace, Energy, Mobility, Legal Tech, Gaming, Enterprise Tech 6 Source: PGA Labs Deals Database Deal volume by latest quarter 73% of deals by volume were <US$ 25M; FinTech remains most active (21% deals) Deal Volumes by Size Deal Volumes by Stage Deal Volumes by Sector 9% 12% 12% 8% 34% 22% 21% 7% 121 121 121 69% 7% 73% 14% 12% Enterprise Tech FinTech EdTech Early Growth Late > US$ 100M US$ 50-100M US$ 25-50M < US$ 25M HealthTech SCM & Logistics Other FoodTech though stands high in Lower ticket size deals 69% of deal activity was driven ~50% deals were in 3 specific term of deal value but due to dominate; 14 deals were of by early - stage innovative start - verticals - Enterprise Tech, monopolistic model it lack far ticket size >US$ 100M ups (deal size remains small) FinTech and Ed Tech behind in deal volume compared to 19 in Q2 CY21 Notes(s): Others includes Food Tech, Retail Tech, Marketing, Automotive, HR Tech, Hospitality, Manufacturing, AgriTech, Aeros pac e, Energy, Mobility, Legal Tech, Gaming 7 Source: PGA Labs Deals Database Funding by sales channel and funding rounds B2C tech start - ups funding up ~2% Q - o - Q in Q3 CY21 B2B start - ups raised over Top 3 B2B funded B2C start - ups led the race in Series E and above account for US$ 1.4B across 51 deals, start - ups are th deal value ~3/4 of the total deal value with an average deal size BharatPe*, OfBusiness of ~US$ 27M and Zetwerk Deal flow split Split by series (%, July 21 – Sept. 21) (%, July 21 – Sept 21) Venture 5% Series J 21% Series H 11% B2C start - ups raised Top 3 B2C funded start - B2B, over US$ 4.7B across ups are Unacademy , 23% Series G 3% 70 deals, with an Swiggy and Eruditus average deal size of Series F 10% Executive Education ~US$ 67M Series E 24% US$ 6.1B Series D 4% Series C 11% B2C , 77% Series B 2% 84 start - ups received 41% of the funding (27 Series A funding in the early 7% deals) went to growth - stage, accounting for 9% stage companies Seed 2% of total funding raised Source: PGA Labs Deals Database Note: *BharatPe is both B2B and B2C Top investors and their focus sector Diversified investor interest across sectors Prominent investors 3One4 FinTech, EdTech, HealthTech Capital, Sequoia Capital and Foodtech are the top and Tiger Global have done three invested sectors in Q3 16+ deals across sectors Most prominent investor in terms of deal volume CY21 Top Investors, Split of deal flow Investor diversification (#, July 21 – Sept. 21) 6 5 HealthTech witnessing a Edtech start - ups valuation HealthTech surge as the pandemic 5 rose significantly since pushed up demand for pandemic 5 healthcare & life products EdTech (~US$ 122M funding in Q3 5 CY21) 4 4 Retail Tech 3 Enterprise Tech 3 Tiger Global has invested 3 in 3 sectors - FinTech, Ed Tech and Retail Tech 3 FinTech Source: PGA Labs Deals Database DeepTech deal flow Growing investor interest towards DeepTech start - ups Top DeepTech start - ups by funding (US$ M, July 21 – Sept. 21) 15% of deals by volume DeepTech start - ups catering to start - ups AI - based life 28 raised ~US$ 80M across leveraging DeepTech sciences software 18 deals in Q3 CY21 solutions AI - based life sciences 23 software Top DeepTech Investors ImmunitoAI , Insane AI , Ai Palette Revos, CollPoll Skit Pi Ventures is the top 15 deals were in early Skit investor in AI/ML stage in DeepTech start - technologies ups Goodmeetings Miko Miko Note(s): DeepTech includes AI/ML, AR/VR, IoT, Blockchain, Robotics, 3D Printing, Big Data & Analytics Source(s): Secondary research, PGA Labs deal database, PGA Labs analysis Unicorns 13 new unicorns added in the Indian tech start - up ecosystem in Q3 CY21 11 13 66 Unicorns added in Unicorns added in Total Unicorns in Q2 CY21 (Apr - Jun) Q3 CY21 ( July - Sept) India as of September 2021 Zomato and CarTrade Tech CoinDCX becomes the first USA ranked first with the most 5 out of 13 Unicorns added in listed in Q3 CY21; Nykaa, Indian cryptocurrency unicorns added in Q3 CY21, Q3 CY21 are from EdTech and India’s first women led Unicorn exchange to achieve unicorn India ranked second Fintech sector files DRHP in Q3 CY21 status in Q3 CY21 11 Source: PGA Labs Deals Database Vertical Trends Key verticals which have created impact during the quarter Outperforming Vertical EdTech RetailTech EnterpriseTech FinTech HealthTech 12 © 2021 NASSCOM. All rights reserved. FinTech FinTech continues to develop its legacy and penetration into the start - up ecosystem. Growing infrastructure stack, innovative solutions and new business models will continue to keep this sector in limelight FinTech continues to 2 unicorns added under Payments and BFSI Growth - stage funding Areas like Neo Banking, Buy dominate by raising Fintech: CoinDCX, investors raised ~55% of dominated funding deals by Now Pay Later, and Crypto 16% of the total Q3 BharatPe total Fintech funding value (~73% share) are taking the market by CY21 funding storm and getting significant traction 13 © 2021 NASSCOM. All rights reserved. FinTech is going through a transformational phase owing to newer innovations and strengthening Fintech ecosystem 73% investments are in Growth stage Sequoia Capital and Accel leads with 4 deals in the Fintech sector 11% By # of deals Payments received the highest funding 16% 4 4 3 3 3 3 US$0.9 B Total Funding: ~US$ 0.9B 2 2 Others* , 18% 73% Personal wealth and finance , 1% Early Growth Late Neobanking , 6% Payments , 47% Trends Driving Fintech Crypto Crypto goes mainstream Fintech IPOs journey kicked off Buy Now Pay Later (BNPL) Exchange , 9% • Due to high growth, increased • Low credit card penetration in India • Many Indian Fintech start - ups have popularity and adoption Crypto has and digital payment boost is helping filed their DHRP with SEBI Lending and seen a major boom this area to grow collection , 18% • Plan to raise up to US$ 3.7B through • Large entrepreneurs and VCs are • High potential market which is IPOs actively investing in Crypto start - ups expected to reach US$ 100B by 2025 Raised US$ 90M in Raised US$ 0.7M in Series C round Seed round Note(s): * includes accounting , book - keeping and expense management companies 14 © 2021 NASSCOM. All rights reserved. Source: PGA Labs Deals Database HealthTech The digital transformation of healthcare is paving way for a more holistic delivery of care. Increasing burden of chronic diseases, rising internet penetration, need for higher accessibility and increasing innovations act as drivers of growth for this sector. Healthtech industry has E - pharmacy, Features: Expanded Preventive healthcare is Mature Healthtech start - ups seen exponential growth teleconsultation, personal healthcare access, remote expected to act as a catalyst are getting closer attention and received a funding of health management, monitoring, improved for HealthTech growth in the from investors US$ 122M in Q3 CY21 EHR/EMR and increasing convenience, patient next 5 years use of AI/ML gain traction consumerization and personalization of care 15 © 2021 NASSCOM. All rights reserved. HealthTech start - ups driving business expansion through newer solution development 3one4 capital and Chiratae are 62 % investments are in growth stage prominent investors in HealthTech sector 3 Healthcare has received the highest By # of deals funding 2 38% US$ 122M 1 1 1 62% Total Funding: ~US$ 122M Healthcare** , 88% Early Growth Trends driving HealthTech Remote monitoring and Changing consumer Internet of Medical Things virtual consultations behavior (IoMT) • New, more digitally educated • Provides solutions to healthcare • Post pandemic world has seen a rise consumer segments are pushing for problems, helps optimize workflow, in delivering care right at people’s innovative health and wellness provide real - time data and increase homes Others* , 12% solutions operational efficiency Raised US$ 16.5M Source: PGA Labs Deals Database Note: *Others include Diagnostic platforms 16 © 2021 NASSCOM. All rights reserved. ** Healthcare includes companies linked to health and wellness RetailTech The surge in online retail came on the back of rapid, massive digital adoption in the country due to the ongoing pandemic RetailTech continues to Falcon Edge Capital, Marketplaces catch 4 firms raising over US$ New areas like social see good momentum SoftBank Vision Fund and investor’s eyes and raised 100M in Q3 CY21 commerce, B2B with 16% of the total Q3 Matrix Partners have been ~25% of total RetailTech (Infra.market, Ofbusiness, marketplaces are taking CY21 funding active in this space funding Lenskart and Cars24) the market by storm and getting lot of traction 17 © 2021 NASSCOM. All rights reserved. RetailTech is booming due to increased eCommerce adoption in smaller towns and B2B marketplaces gaining traction among customers Falcon Edge and SoftBank are prominent investors in RetailTech sector 76 % of investments are in late stage By # of deals eC ommerce received the highest funding 3 3 11% 13% 2 2 US$ 0.9 B Total Funding: ~US$ 0.9B 1 76% eCommerce , 73% Early Growth Late Trends Driving RetailTech Increasing e - commerce B2B marketplaces gain traction Aggressive national and overseas adoption in smaller towns expansion • Consumers in small towns are • Infra.Market and OfBusiness raised • Lenskart is looking to expand into adopting eCommerce and remains a significant funding during the quarter Southeast Asia and Middle East focus start - ups Marketplace , with proceeds from recent round • Infra.Market plans to expand into 26% of US$ 220M • Social commerce is gaining traction categories like paints, pipes, roofing as it allows tapping into underserved Online and flooring, and tiles and • Cars24 plans to use proceeds for Services , 1% market sanitaryware expansion, improving tech stack and financing 18 © 2021 NASSCOM. All rights reserved. Source: PGA Labs Deals Database EnterpriseTech India’s EnterpriseTech sector remains attractive driven by increasing demand for tools in the world of big data, cloud, mobility, IoT and cybersecurity Strong growth in EnterpriseTech Total amount raised by LetsVenture, Sequoia, PI SaaS / AI continue to Growth - stage funding is driving investments in EnterpriseTech is ~US$ 95M Ventures and Prime Partners attract investor’s interest dominated with 56% of total reskilling the talent in new which is ~ 2% of total funds have been active in this with ~81% of total EnterpriseTech funding growth areas such as SaaS, raised in Q3CY21 space EnterpriseTech funding cybersecurity, AI, 5G, IoT, product engineering 19 © 2021 NASSCOM. All rights reserved. The Freshworks IPO, and the success of Zoho, have earned Indian EnterpriseTech start - ups a spot in the global software community 44% investments are in growth stage LetsVenture is the prominent investor in Enterprise Tech By # of deals SaaS /Artificial Intelligence based tech 3 start - ups have received the highest 44% funding 2 2 US$ 95M 56% 1 1 Total Funding: ~US$ 95M SaaS / AI , 81% Early Growth Trends Driving EnterpriseTech Freshworks NASDAQ listing to Rise in cyber threat increases Growing SaaS adoption with more act as catalyst for SaaS firms demand for AI driven products penetration / solutions • Freshworks IPO raised US$ 1B at a • SaaS companies building strategies valuation of US$ 10B around penetrating SMB market, small • AI and ML security tools help retailers • Other Indian SaaS based start - ups, automate and streamline IT & ITES * , • Large SaaS companies setting up office such as RateGain, lining up for IPO manual business processes 19% in rural and non - urban areas in India Setting up offices in rural areas Note: * IT & ITES means Information Technology and Information Technology Enabled Platform 20 © 2021 NASSCOM. All rights reserved. Source: PGA Labs Deals Database EdTech The future of EdTech looks promising post Covid - 19. The key growth drivers propelling EdTech are uniform democratic access for all learners, wide selection of tools and educational aids, and rise in disposable income of the households. Importance of critical EdTech has seen Education market is E - learning continues to 3 unicorns added: thinking and exponential growth and expected to grow 2X to gain traction Vedantu, upGrad, and problem - solving skills has received a funding of US$ 225B by FY25 @ Eruditus pushed EdTech to include CAGR 14% over FY20 - 25 . ~US$ 1.5B in Q3 CY21 holistic development 21 © 2021 NASSCOM. All rights reserved. EdTech is going consolidation phase start - ups with mature start - ups focusing on expansion and newer start - ups building innovative solutions Elevation is one of the most 57% investments are in l ate stage prominent investor 4% By # of deals 39% 2 2 2 2 Total EdTech Funding US$ 1.5 B 1 57% Early Growth Late Trends driving EdTec h ~US$ 1.5B AR/VR in education Online STEM learning Holistic learning • EdTech platforms focus on holistic • Use of immersive tools for training • Platforms providing STEM courses curriculum to attract new - age with real world like experience on including coding & mathematics learners digital platforms learning tools for students • Platforms have also expanded to • Platforms providing AR/VR based domains other than academics immersive learning to students 22 © 2021 NASSCOM. All rights reserved. Source: PGA Labs Deals Database Additional Data Top 10 deals Sector wise top deals Tech start - ups filing DRHPs with SEBI 23 Additional Data - Deals Top deals of Q3 CY21 # Company Founded Sector Sub - sector Funding (US$ M) Funding stage Investors Prosus Ventures, SoftBank, Accel,QIA, Wellington 1 2014 FoodTech Food delivery 1,300 Late Management, Falcon Edge Capital, Think Investments, Carmignac, Goldman Sachs, Amansa Holdings 2 2010 EdTech E - learning 660 Growth Accel, SoftBank Vision Fund Temasek, Mirae Asset Venture, General Atlantic, Tiger 3 2015 EdTech 440 E - learning Late Global, SoftBank Vision Fund, Aroa Ventures Tiger Global, Sequoia Capital, Steadfast Capital, Ribbit 4 2018 FinTech Payment gateway 370 Growth Capital, Dragoneer Investment, Insight Partners, Amplo, Coatue Online marketplace - 5 2015 Retail Tech 340 Late DST Global, Falcon Edge and SoftBank Vision Fund cars Falcon Edge Capital, Temasek Holdings, Chiratae 6 2010 Retail Tech Eyewear 223 Late Ventures, Bay Capital 7 2014 Automotive 200 Late Automobile 57 Stars, SevenTrain Ventures 8 2015 EdTech 185 Growth Temasek, International Finance Corporation, IIFL E - learning SoftBank, Alpha Wave Incubation, Matrix Partners, Falcon 9 2015 Retail Tech 160 Late E - commerce Edge Capital Industrial and D1 Capital, Sequoia Capital, IIFL, 10 2018 E - commerce 150 Growth Manufacturing Greenoaks , Lightspeed Venture, Kae Capital, Accel Total of top deals 4,028 Source(s): PGA Labs deal database, PGA Labs analysis 24 Additional Data Sector wise top deals in Q3 CY21 FinTech EnterpriseTech Sub - Funding Funding Sub - Funding Funding Company Investors Company Investors sector (US$ M) stage sector (US$ M) stage Tiger Global, Sequoia Capital, Steadfast, Ribbit Aroa Ventures, IIFL, Mankind Pharma, Miko SaaS/AI 28 Growth Bharat Pe Payments 370 Growth Capital, Dragoneer Investment, Insight YourNest Venture, Ivy Cap Ventures Partners, Amplo, Coatue Westridge, Kalaari , Exfinity Venture, SenseAI , 23 Growth Skit SaaS/AI LetsVenture , IAN Fund K hatabook Accounting 100 Growth Moore Strategic Ventures, Tribe Capital 640 Oxford, Snow Leopard, Lightspeed , Matrix Dukaan SaaS 11 Early Partners, HOF Capital, Old Well Ventures, Pine Labs BFSI 100 Late Invesco LetsVenture , 9Unicorn E dTech RetailTech Sub - Funding Funding Sub - Funding Funding Company Investors Company Investors sector (US$ M) stage sector (US$ M) stage Eruditus DST Global, Falcon Edge and SoftBank Vision C ars24 340 Ecommerce Late 660 Executive E - learning Growth Accel, SoftBank Vision Fund Fund Education Temasek , Mirae Asset Venture, General Falcon Edge Capital, Temasek, Chiratae Lenskart Ecommerce 223 Late Unacademy 440 E - learning Late Atlantic, Tiger Global, SoftBank, Aroa Ventures Ventures, Bay Capital O fbusiness SoftBank , Alpha Wave Incubation, Matrix Temasek, International Finance Corporation, Ecommerce 160 Late E - learning 185 Growth Partners , Falcon Edge Capital upGrad IIFL FoodTech Media & Entertainment Sub - Funding Funding Sub - Funding Funding Company Investors Company Investors sector (US$ M) stage sector (US$ M) stage Tiger Global, Malabar Investment, Think Prosus Ventures, SoftBank, Accel, QIA, GupShup Social Media 2 40 Late Investments, Fidelity Management, Harbor Wellington Management, Falcon Edge, Think Swiggy 1, 300 Food delivery Late Spring, Neuberger Berman, White Oak Global Investments, Carmignac, GS, Amansa Holdings ShareChat Social Media 1 45 Late Moore Strategic Ventures, Mirae Asset - Naver Source(s): PGA Labs deal database, PGA Labs analysis 25 Additional Data - DRHPs Tech start - ups filing DRHPs with SEBI (Q3 CY21) # Company Founded Sector Sub - sector Date DRHP 1 2012 Retail Tech Ecommerce platform 3/8/2021 2 2017 FinTech Payment Bank 2/8/2021 3 2008 FinTech Insurance marketplace 2/08/2021 4 2009 FinTech Payments 16/7/2021 5 2009 FinTech Payments 13/7/2021 Source(s): Secondary research, Praxis analysis 26 Appendix Methodology Definitions: Stages / Sectors Stakeholder Initiatives 27 Appendix - Stakeholder initiatives Positive outlook for start - up ecosystem is evident from different stakeholder initiatives Illustrative Appscale Academy • Google and MeiTY to launch a growth and development programme for early to mid - stage start - ups • Focus on gaming, healthcare, fintech, edtech , Microsoft AI Innovate social impact sectors • Microsoft has launched Microsoft AI Innovate • 100 start - ups will be selected based on for nurturing and scaling start - ups that are defined qualitative and quantitative leveraging Artificial Intelligence parameters • Qualified seed to series B start - ups will be Oppo India: Elevate provided with technical enablement benefits, including Azure benefits and product • Program to provide expert advise, engineering support etc. assistance, and the opportunity to take • 10 - week - long initiative would support start - advantage of Oppo's products, resources, and distribution channels to launch their ups in India leveraging AI technologies idea • Backed by TiE Mumbai, the launch cohort will • Focus on camera and image processing, kickstart in November 2021 . The first cohort battery, networks (5G), system will focus on manufacturing and logistics and performance, payments, AI, and gaming the second one will focus on fintech Source(s): Secondary research, PGA Labs analysis 28 Scope Inclusions Exclusions What's included in the report? What’s excluded from the report? • Non - tech start - ups operating in the consumer • Only tech start - ups have been considered for this space have not been included in this report report which are working towards innovation in technology, business process or business model • Investments from angel investors, incubators and start - up accelerators have been excluded • Start - ups which have received funding from private equities or venture capital firms have • Debt investments and strategic deals into tech been considered start - ups have not been considered searching... • Founders of Indian origin, with HQ or core • Start - ups at the idea stage without a prototype product development in India or minimum viable product have also not been considered • Start - up to have a prototype or MVP; idea stage start - ups are not considered 29 Methodology This pulse report has been co - developed by NASSCOM and PGA Labs through a comprehensive study to understand the tech start - up la ndscape in India This report analyses the following – ● Current investment scenario and trends that define the Indian tech start - up ecosystem ● Ecosystem enablers like Incubators/Accelerators as well as government policies ● Recent DRHPs filed with the regulators Primary input for this report includes the following sources Extensive research of media PGA Labs proprietary deal Government websites Sector analyst reports articles database • Inc42 • Ministry of corporate affairs • Your story • SEBI • IVCA • Economic Times • Mint • Business Standard Appendix Definitions of stages and sectors (1/2) Stages of fundings have been mapped as: ● FinTech: Enables financial services, banking and insurance through technology ● Series A and prior rounds are early stage E.g., Online Banks, Financial Management Apps, Payment Management Platforms, ● Series B,C,D and E are growth stage Alternative Lending Platforms, Money Transfer Platform, Expense Management, Investment Platforms, Cryptocurrency & Trading Platforms, etc. ● Series F and above are late stage ● EdTech: Provides learning solutions & services through technology Sector definitions are given below: E.g., Learning Apps, Test Preparation Tech, Education Advisory Platform, K - 12/Higher education platforms, Language Learning Platforms etc. ● Enterprise Tech: B2B Product companies targeting Horizontal solutions for Large Enterprises / SMBs ● Travel & Hospitality: Tech companies engaged in supporting the E.g., Data Analytics/AI/ML Platforms, Development Platforms, Collaboration travel and hospitality industry tools Productivity Applications, Customer Services, Big Data/Cloud/Security E.g., Hotel Booking Services, Travel Planning, Travel Packages Portal, Travel Infrastructure, etc. Collaboration Community, etc. ● HealthTech: Provides technology platform for solving ● Mobility: Tech - enabled companies providing simplified HealthTech problems Transportation services to users E.g., Medical Solutions, Marketplace for Health Services, Health Lab E.g., Car - pooling, Self - Drive Rentals, Two - wheeler taxi aggregators, Mass Transit, Tech Aggregators, Online Pharmacies, E - Diagnostics, Ambulance Aggregator, etc. Enablers ● HRTech: Tech - enabled companies supporting Human ● Industrial & Manufacturing: Engaged in manufacturing of tech - Resources Activities enabled devices or machines; Construction/Mining sector, etc. E.g., Applicant Tracking systems, HR Management System, Candidate Assistance E.g., IoT based Predictive Maintenance of Machines, 3D Printing (Manufacturing) & Sourcing, Corporate Training/Learning and Development, Recruitment Marketplaces, etc.. ● Automotive: Companies involved in production, manufacturing, sales and services of motorized vehicles E.g., Electronic Engineering, System Integration, Automotive Maintenance, Electric Vehicles, Automotive marketplaces, etc. 31 Appendix Definitions of stages and sectors (2/2) ● Media & Entertainment: Provides content for entertainment across ● SCM & Logistics: Enabling tech in logistics services and supply chain the web and mobile medium management E.g., News & Media Apps, Live Streaming Apps, News Platforms, OTT Content, Video E.g., Logistics and Distribution Platform, Fleet Management, Warehousing, IoT Platform Intelligence Apps, etc. for Logistics, IoT Platform for Goods Transportation Marketplace, etc. ● Retail Tech: Companies enabling Sales of goods and product online ● Gaming: Tech Innovation and facilitation in the Gaming industry E.g., AR/VR Gaming, Community platform Games, Fantasy Gaming Platforms etc. or Integration of tech in offline markets E.g., Products/Services cutting across several verticals - . Fashion & Lifestyle ● Legal Tech: Tech - based companies for Legal help to Marketplaces, Online grocery & Home essentials platforms. Also includes Retail enablers, B2B marketplaces, Social commerce platforms, Rental platforms etc. Individuals/Corporates E.g., Contract Management, Brand Protection and Anti Counterfeit, Legal Services ● AgriTech: Start - ups engaged in tech enablement in the Agricultural Discovery/Booking marketplaces, etc. industry ● Advertising & Marketing Tech: Provides direct advertising and E.g., Field Surveillance, Precision AgriTech, Farm infrastructure, Soil Testing, Farm Input E - Commerce etc. marketing assistance through technology E.g., Content marketing, influential marketing, Push notifications etc. ● Aerospace & Defense: Tech - based companies supporting the Defence and Aviation industry E.g., Military Drones, Green Propulsion Systems developers, Sensors and Platforms for security applications etc. ● Energy & Utilities: Tech Enablement for Natural Resource Management and Utilization E.g., Renewable Energy products, Recycling of Resources, Energy Production and Distribution, EV charging Infrastructure etc. ● FoodTech : Tech - enabled companies supporting the FoodTech industry E.g., Online Food Ordering, Restaurant Management Cloud Solutions, Food Discovery Platform PGA Labs We enable better decisions. Deep business research and intelligence that helps make 50% BETTER DECISIONS 250 + faster to annual outcomes engagements Deep on - ground insights that you can act on 98%+ 4 offices, deep experience across accuracy geographies – India, US, Europe, MEA, and 600+ SEA region years domain expertise Advanced technology tools and innovative 34 data gathering approach practices Multifaceted teams with a unique mixture of qualitative, quantitative, and digital research 100+ 40 - 60 experts team members she/he ratio About About NASSCOM is the industry association for the IT - BPM sector in India A not - for - profit PGA Labs is a technology - enabled business research & intelligence services firm that organization funded by the industry, its objective is to build a growth led and specializes in driving decision from on - ground insights Our teams are multifaceted with a sustainable technology and business services sector in the country with over 3100 unique mixture of qualitative, quantitative and digital research experts . With a holistic members NASSCOM Research is the in - house research and analytics arm of approach focusing on the “What and Why”, we are able to extract relevant insights from data NASSCOM generating insights and driving thought leadership for today’s business employing advanced technology tools and innovative data gathering approaches leaders and entrepreneurs to strengthen India’s position as a hub for digital technologies and innovation Our clients use our capabilities to generate competitive / market insights for the sectors they operate in, sectors they want to expand to or the sectors of interest for their portfolio Usage of Information companies Forwarding/copy/using in publications without approval from NASSCOM Kno w more about us: www.pgalabs.in www.pgalabs.in will be considered as infringement of intellectual property rights Acknowledgements: For queries, please contact: Achyuta Ghosh Ashish Gupta Poonam Karkera Diksha Bhutani Manager -- Research Head - Research Associate Manager, Strategic Initiatives Associate Manager, PR & Corporate Communications asgupta@nasscom.in a chyuta@nasscom.in poonam.karkera @praxisga.com diksha.bhutani@praxisga.com M: +91 998 749 8982 M: +91 989 999 7679 Nirmala Balakrishnan Practice Lead – Research Vaishnav Kumar Rai nirmala@nasscom.in Manager, Cooperate Communications vaishnav.rai@praxisga.com M: +91 783 895 5743 34 Disclaimer Disclaimer The information contained herein has been obtained from sources believed to be reliable. NASSCOM and its advisors & service p rov iders disclaims all warranties as to the accuracy, completeness or adequacy of such information. NASSCOM and its advisors & service providers shall have no liability for errors , o missions or inadequacies in the information contained herein, or for interpretations thereof. The material or information is not intended to be relied upon as the sole basis for a ny decision which may affect any business. Before making any decision or taking any action that might affect anybody’s personal finances or business, they should consult a qualified prof ess ional adviser. Use or reference of companies/third parties in the report is merely for the purpose of exemplifying the trends in the industr y a nd that no bias is intended towards any company. This report does not purport to represent the views of the companies mentioned in the report. Reference herein to any specific com mer cial product, process or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by NASSCOM or any agency thereof or its contractors or subcontractors. The material in this publication is copyrighted. No part of this report can be reproduced either on paper or electronic media wi thout permission in writing from NASSCOM. Request for permission to reproduce any part of the report may be sent to NASSCOM. www.nasscom.in /NASSCOMOfficial research@nasscom.in Copyright © 2021 /nasscomR NASSCOM Plot 7 to 10, Sector 126, Noida - 201303 +91 - 120 - 4990111 /NasscomVideos