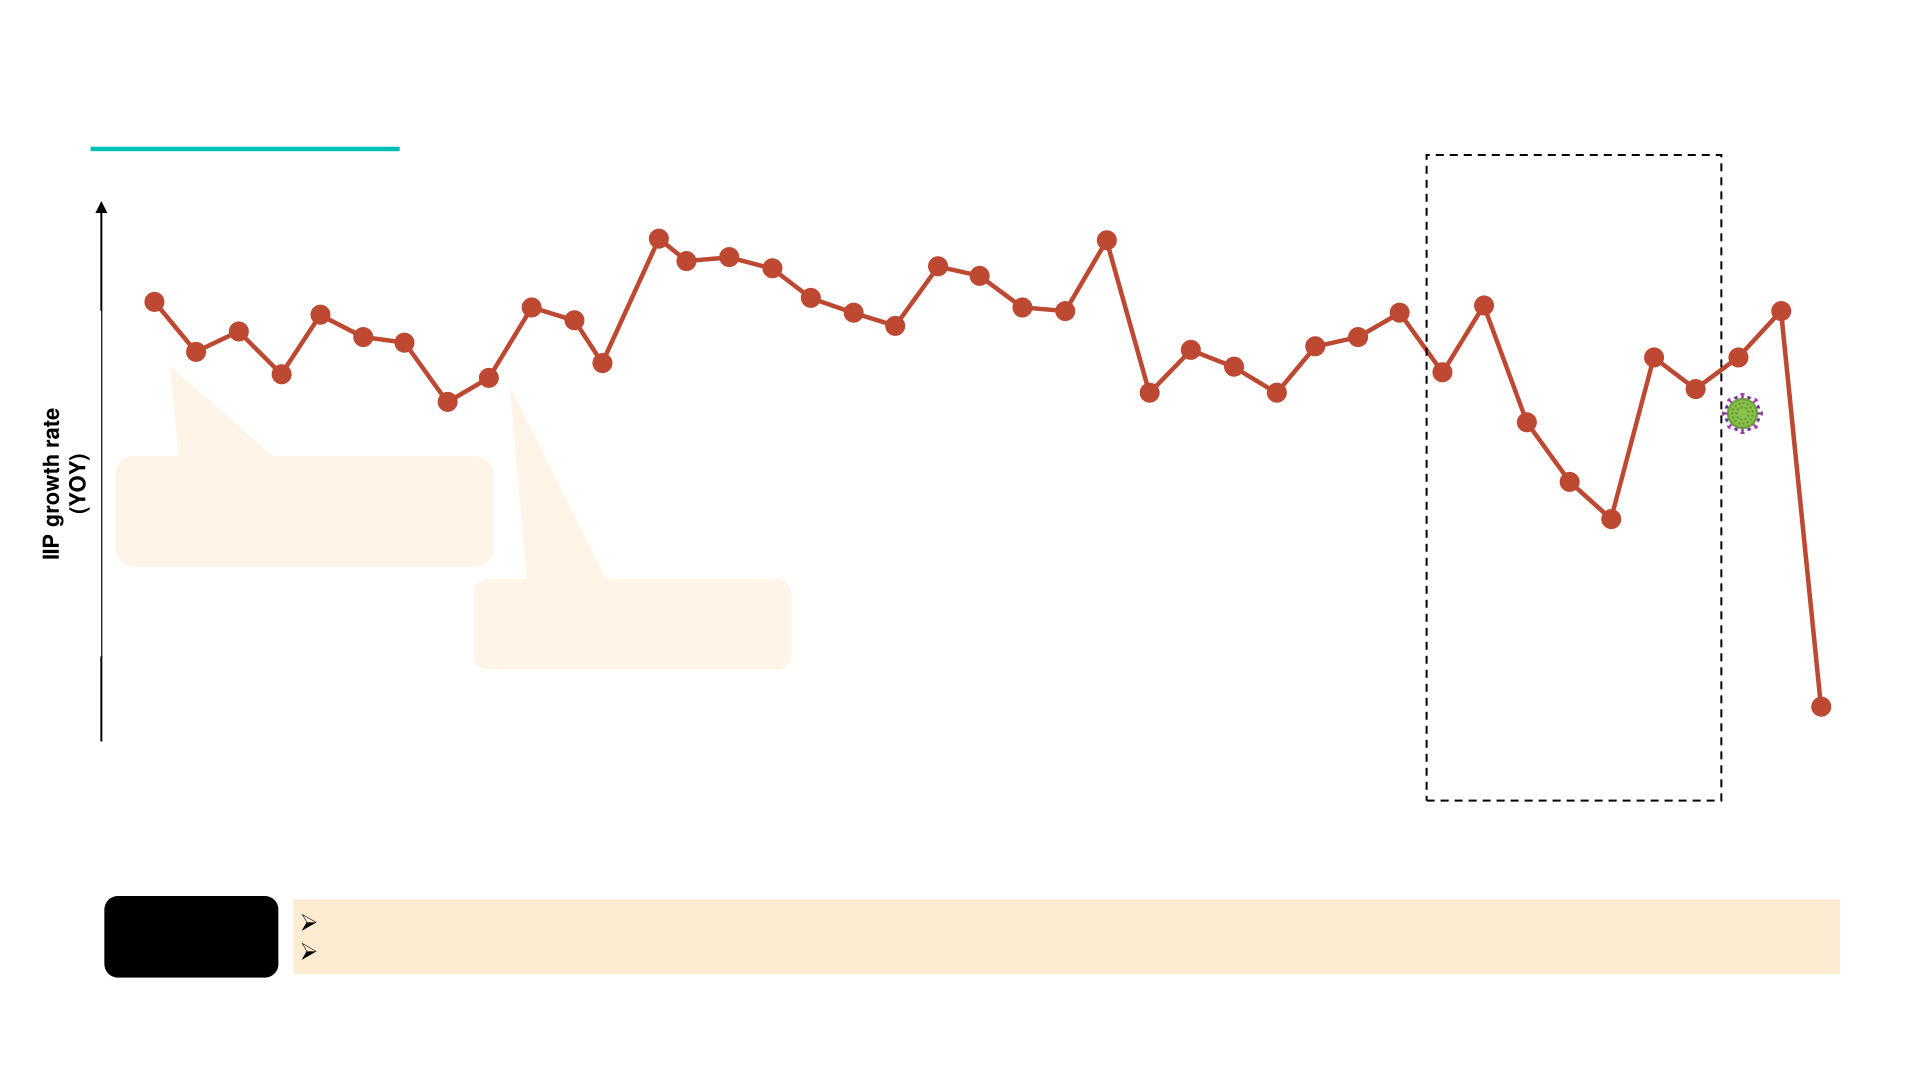
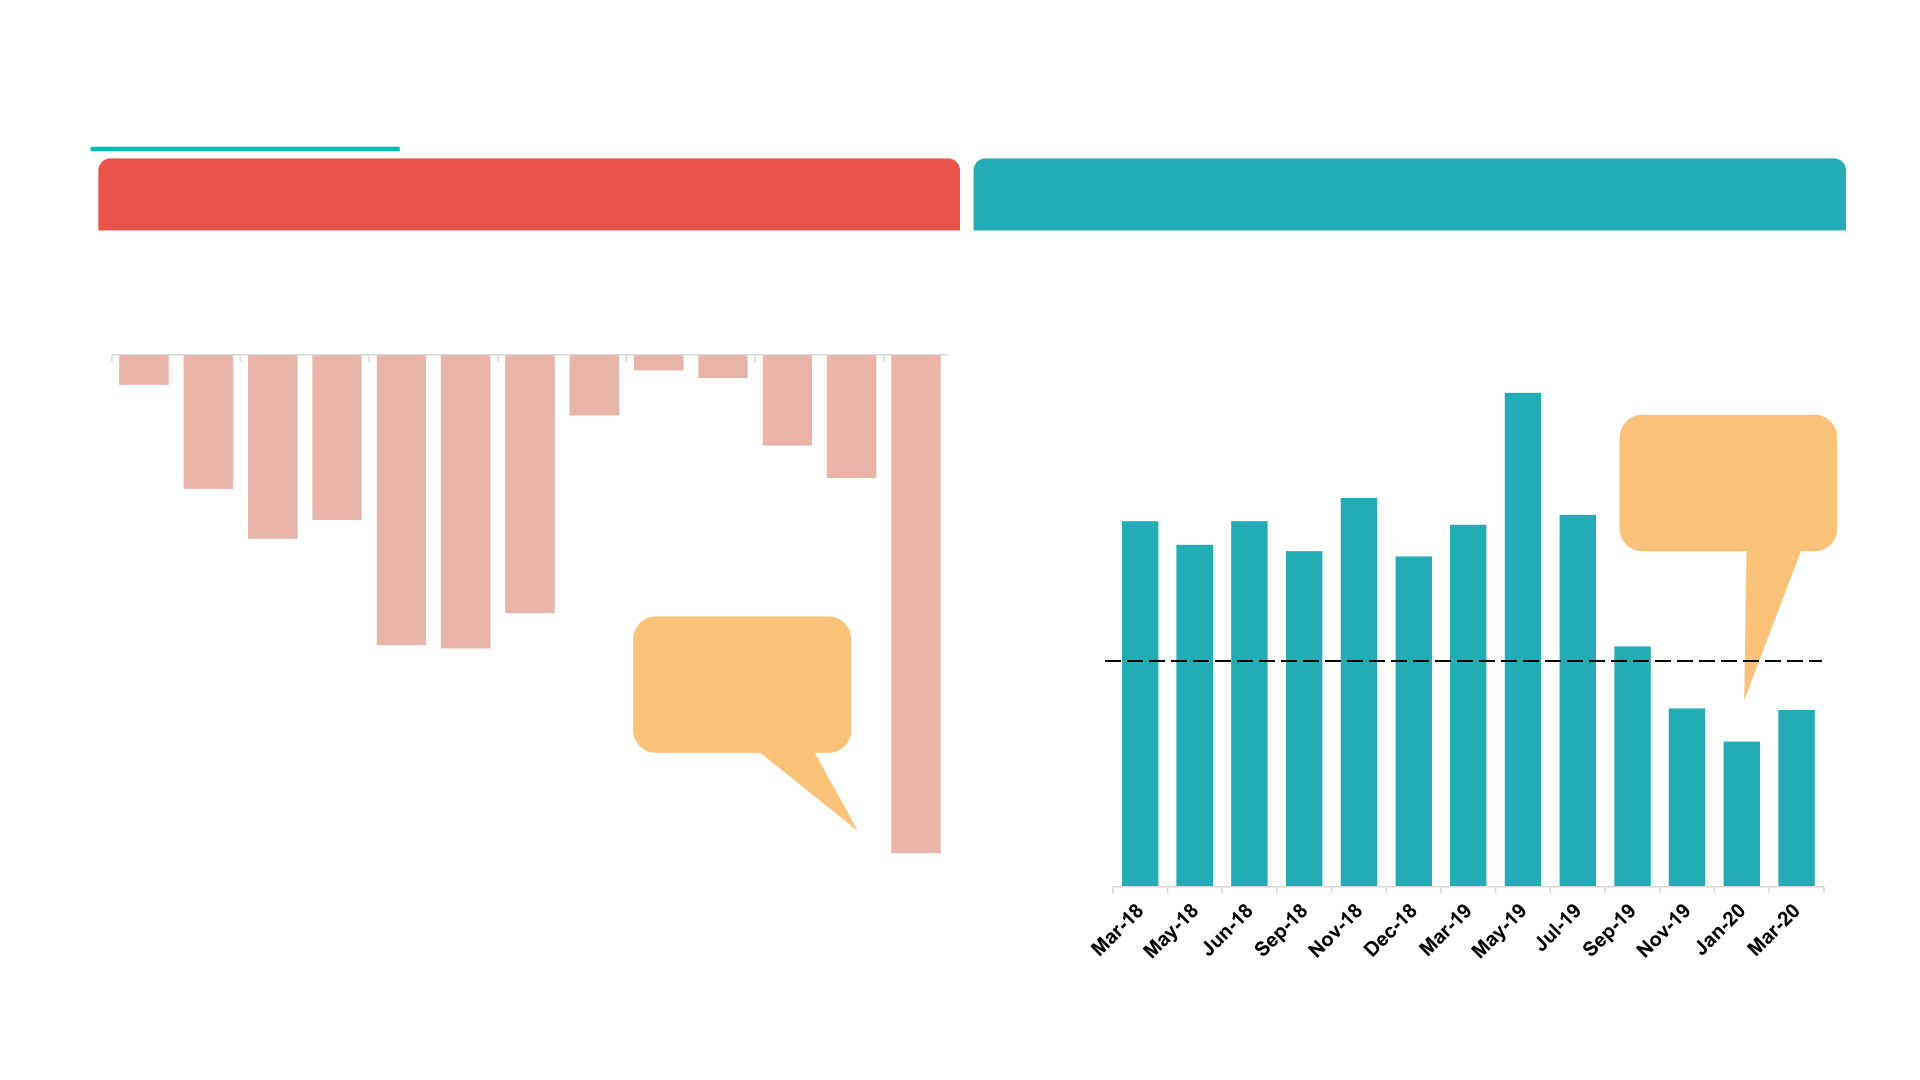
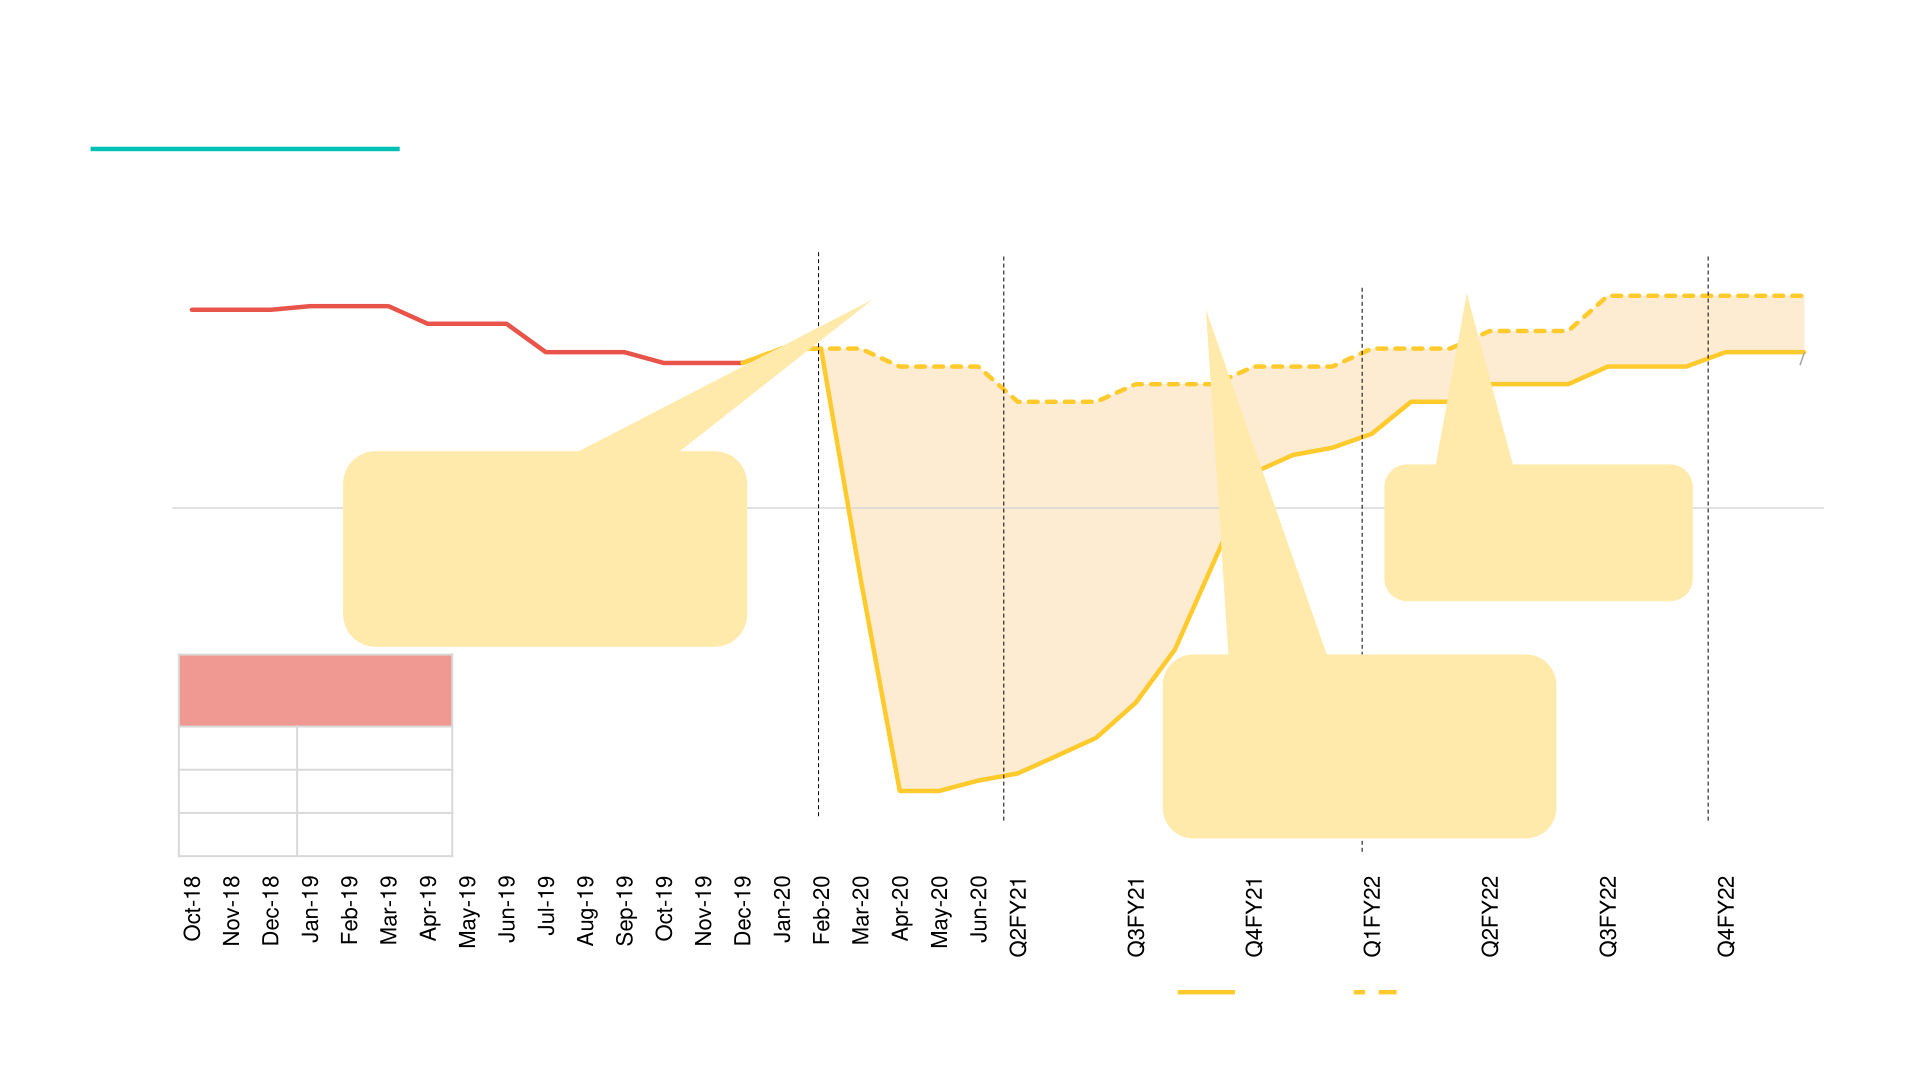
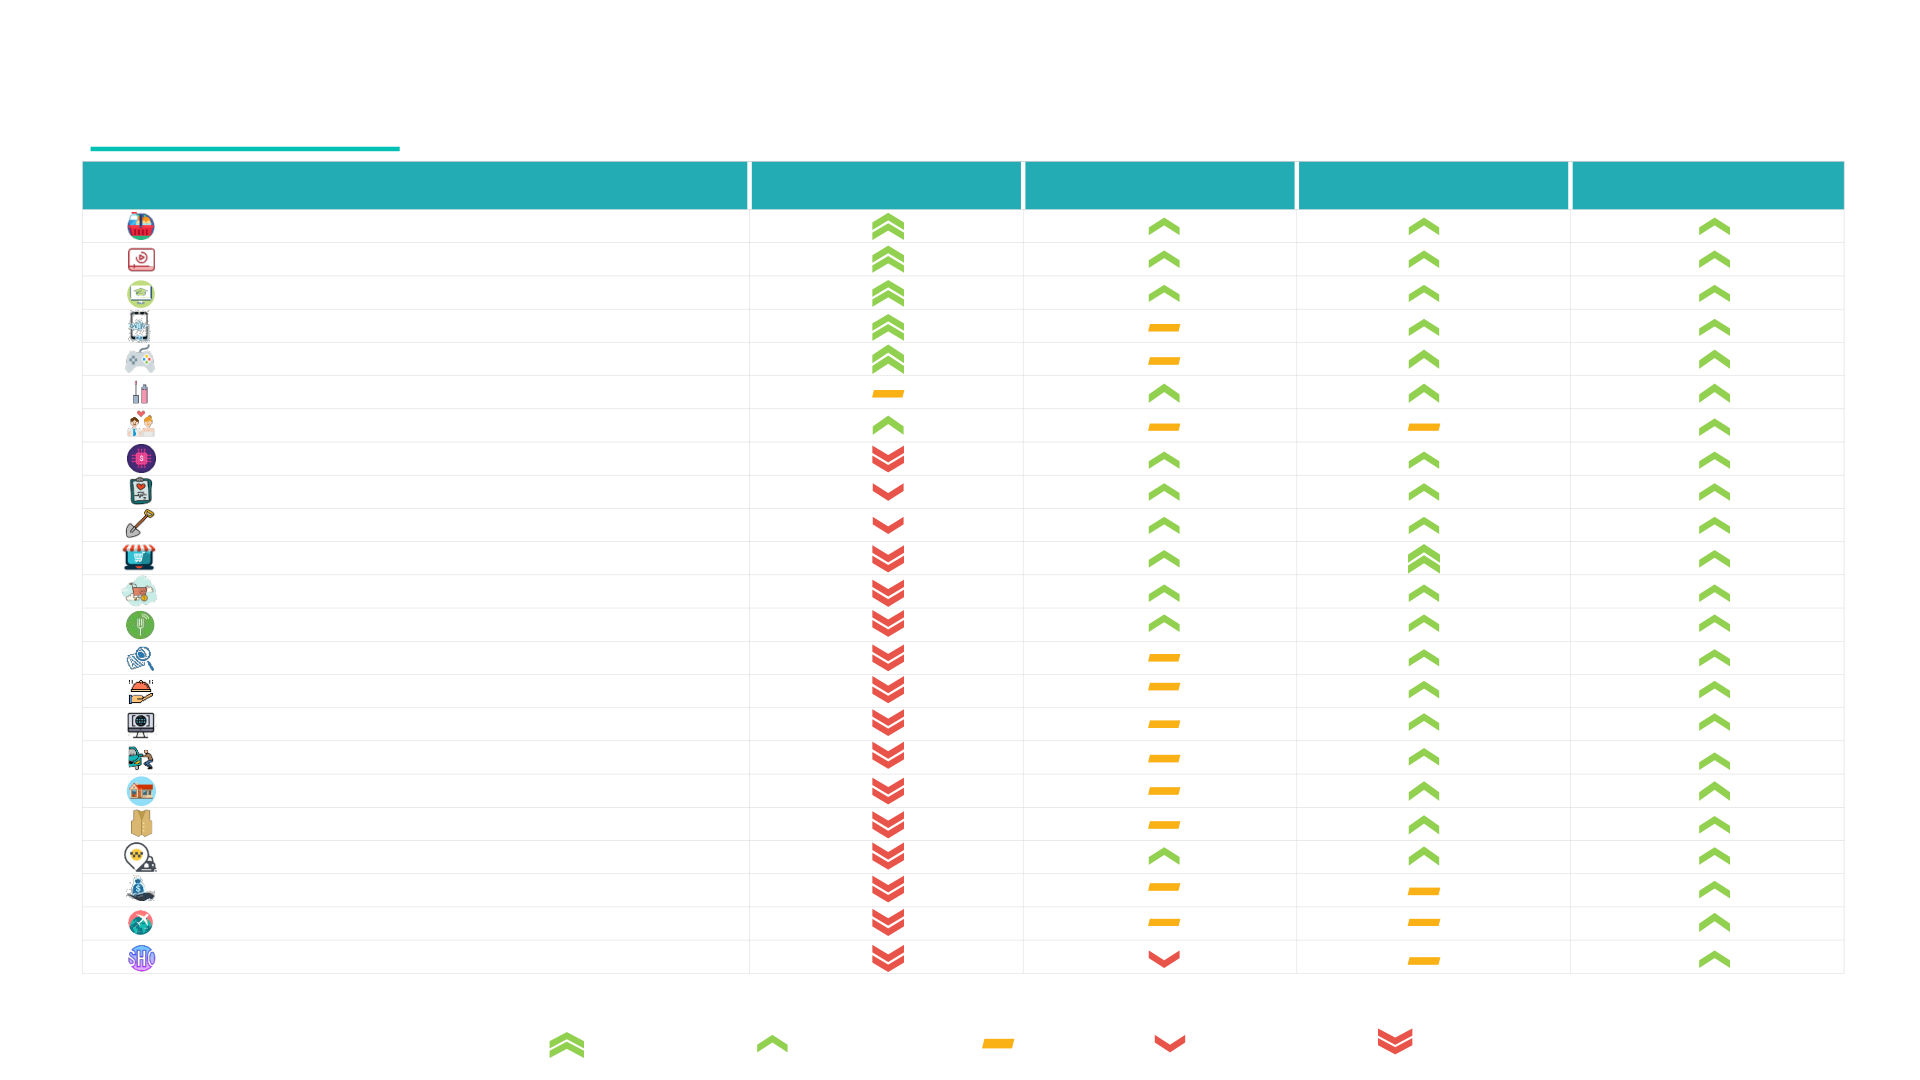
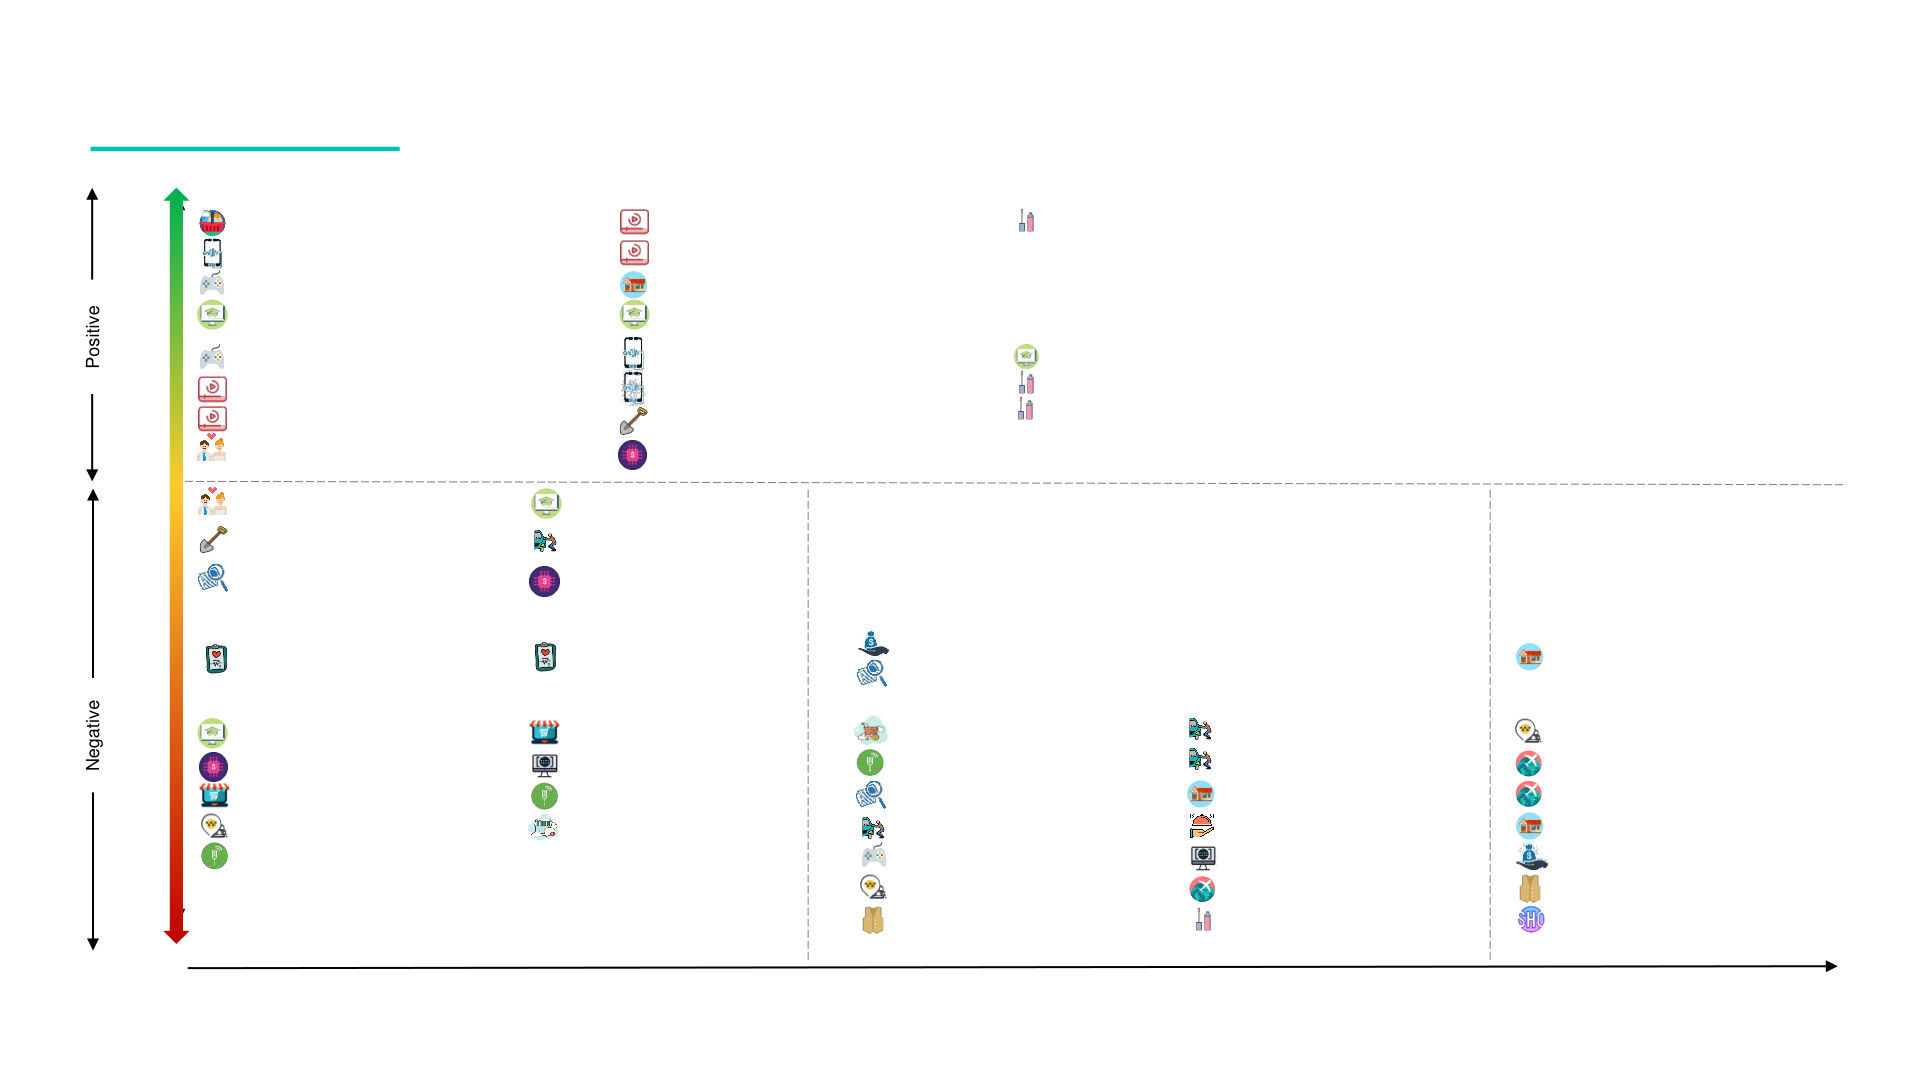
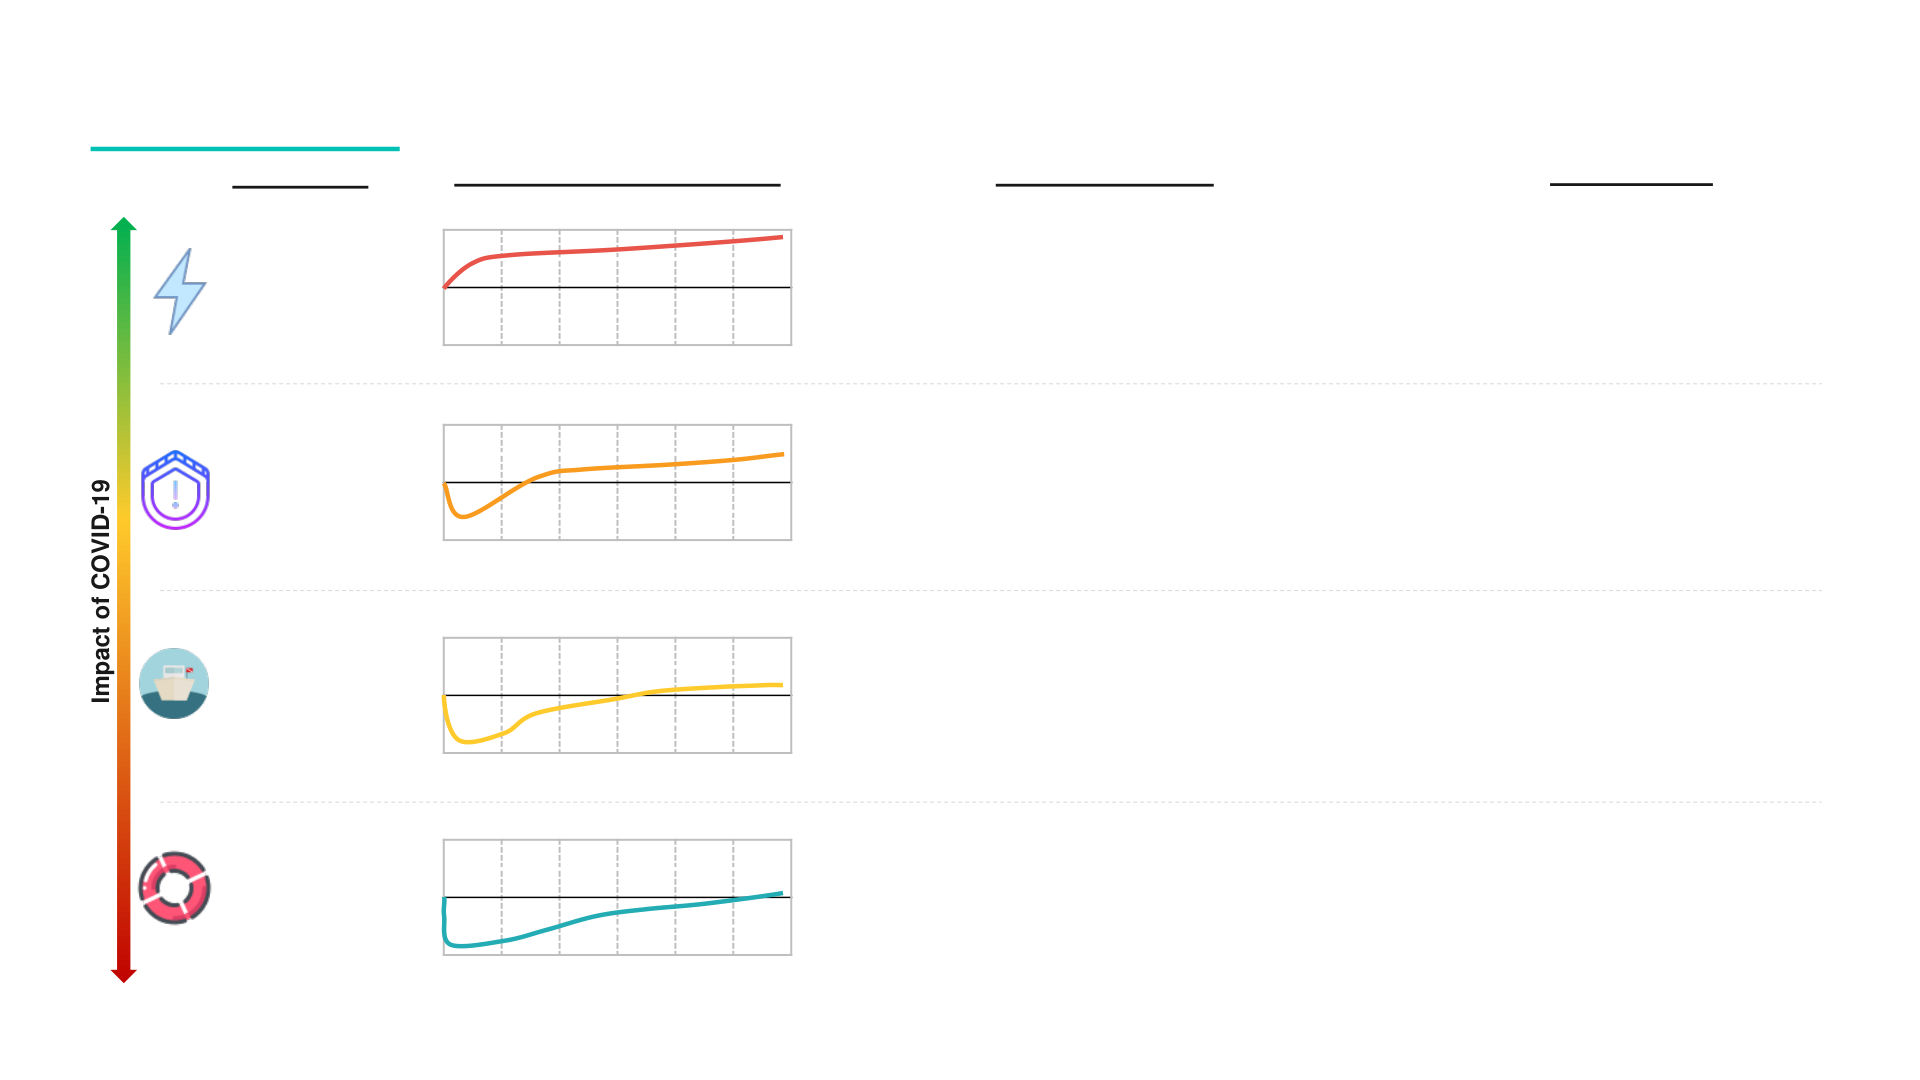
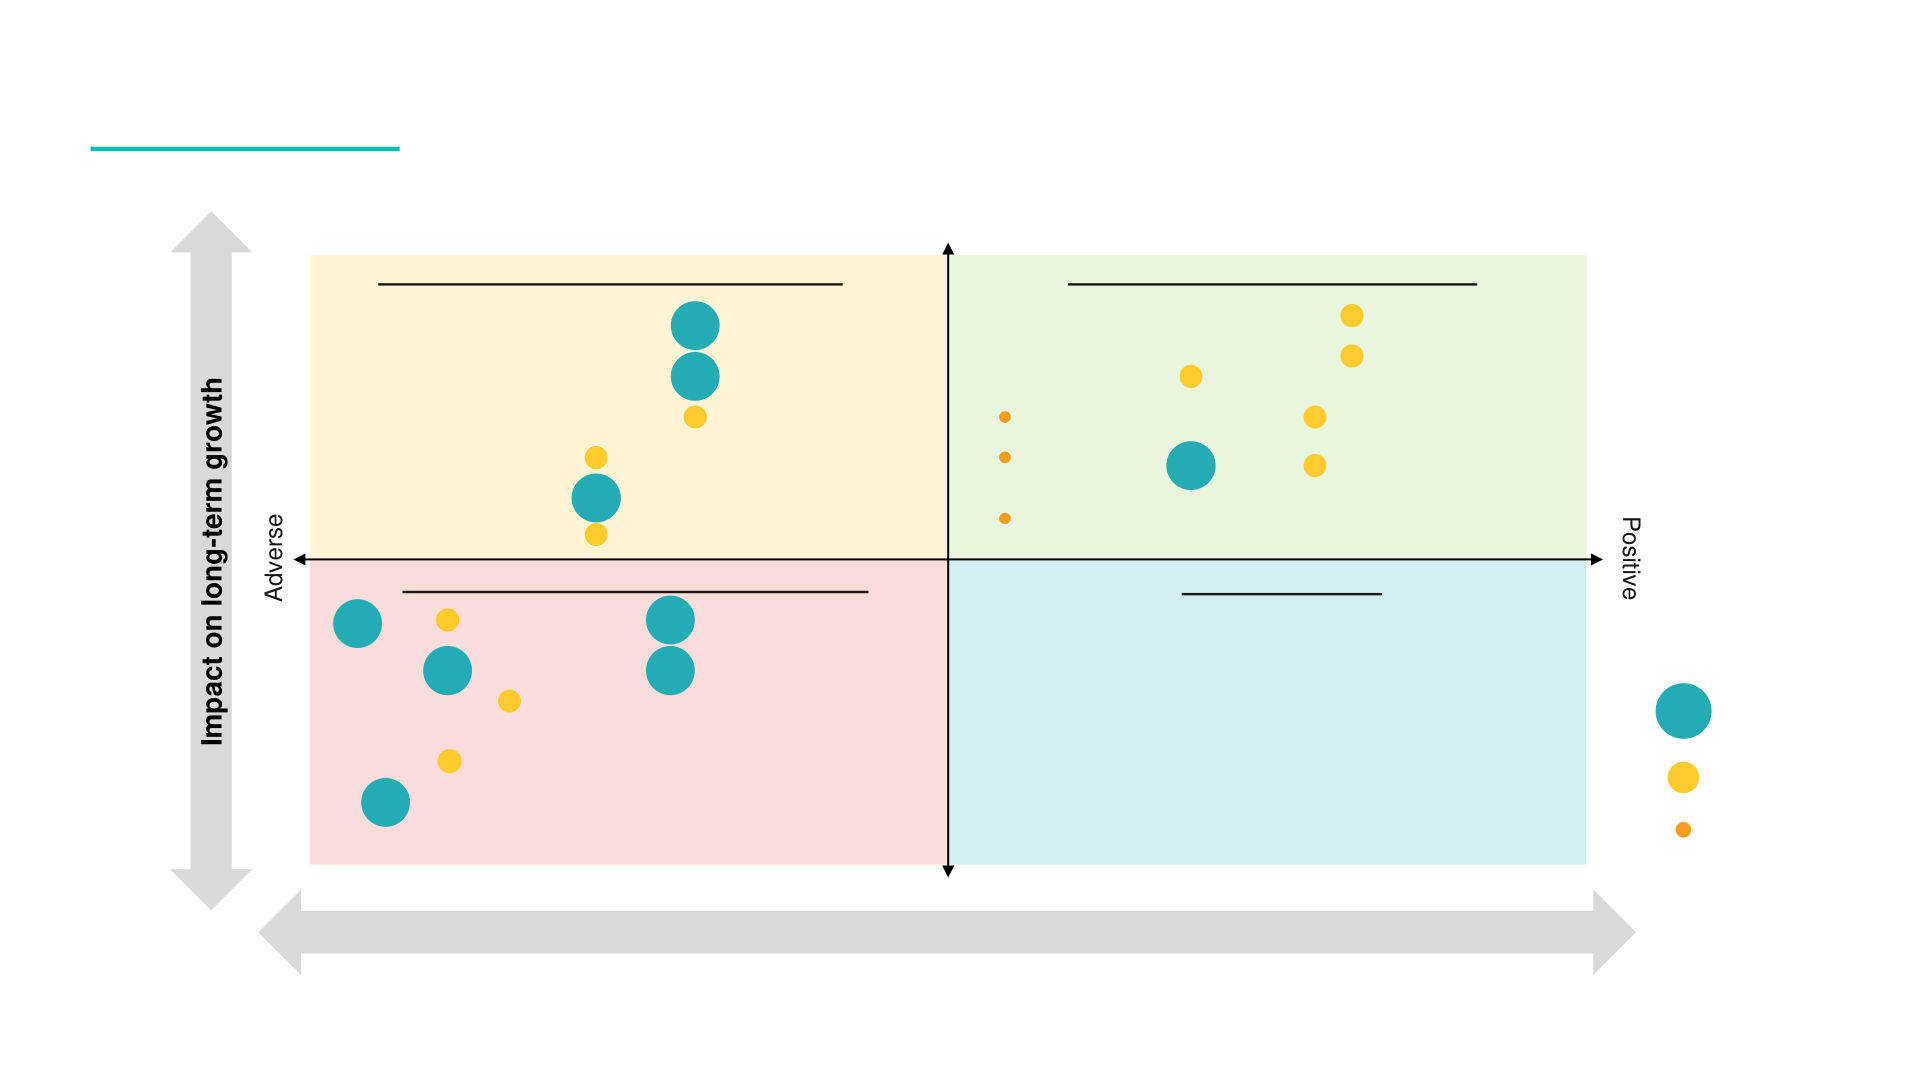
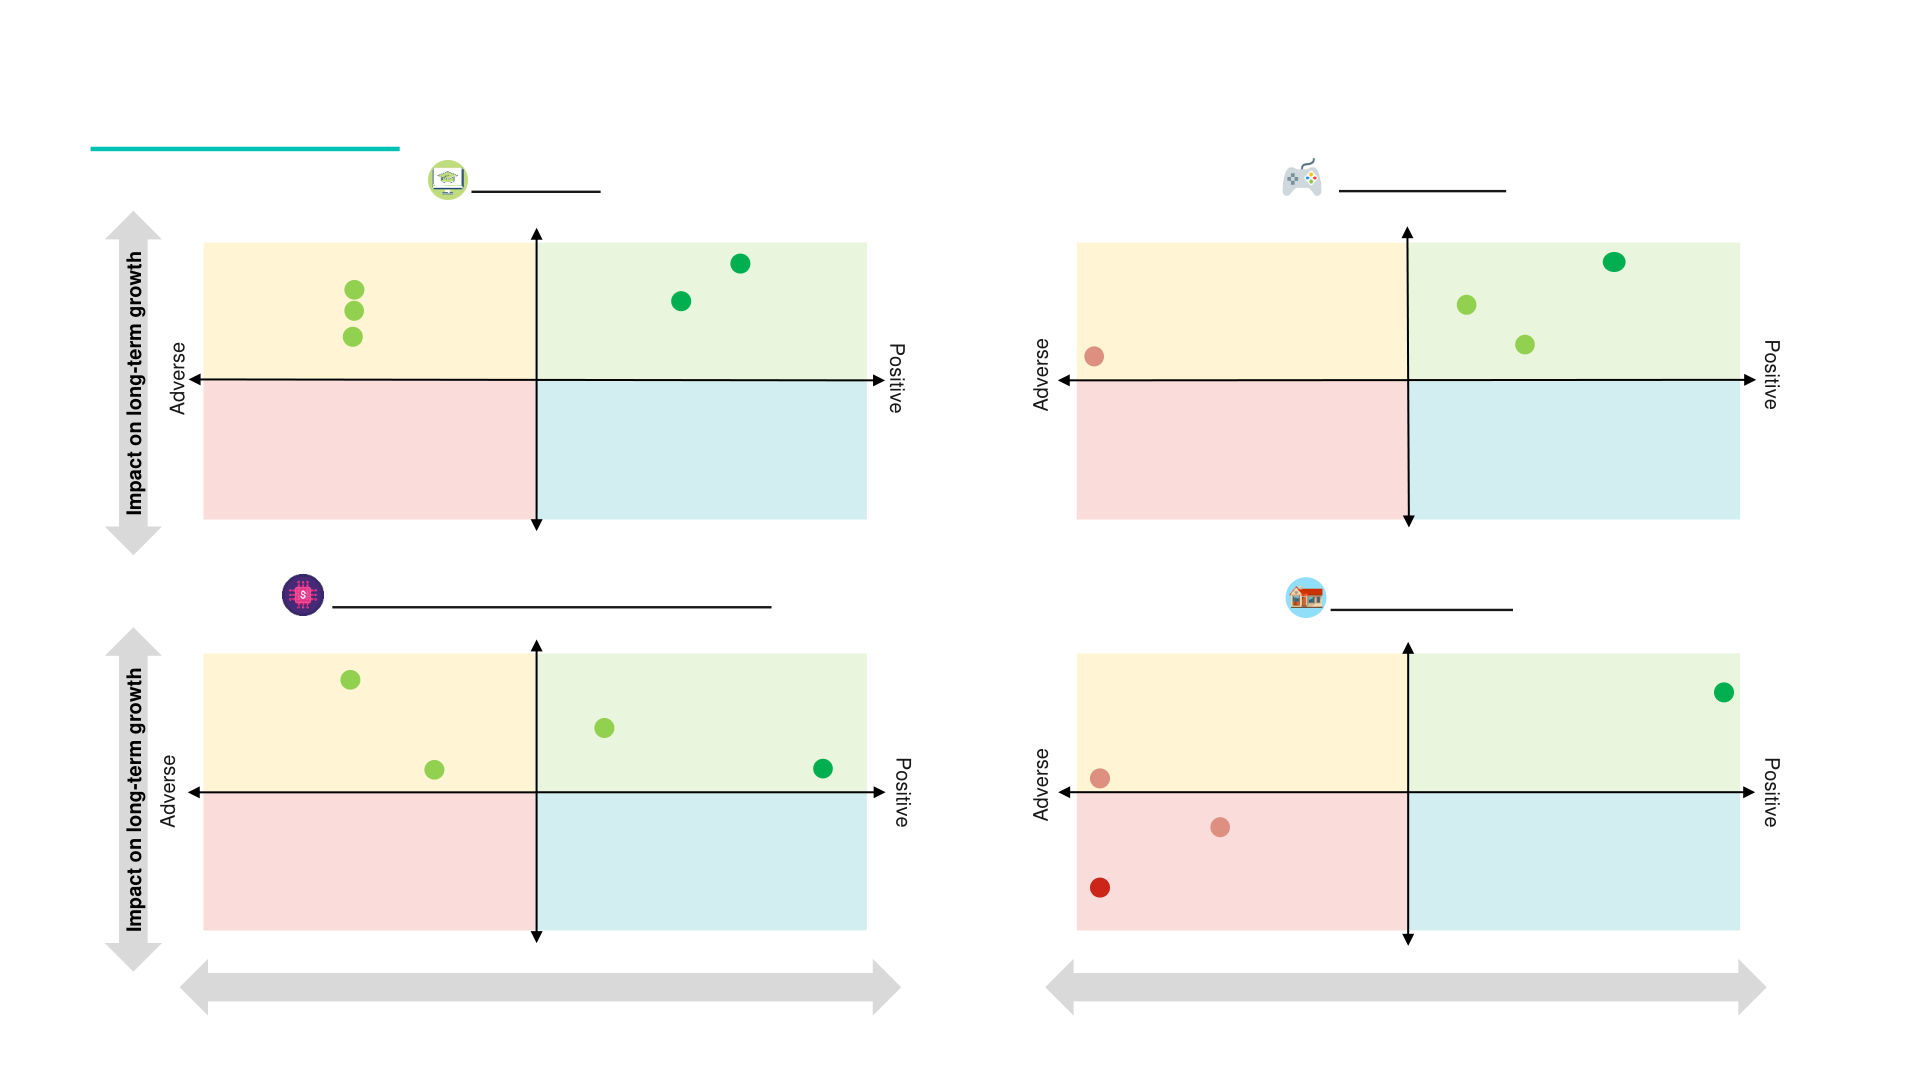
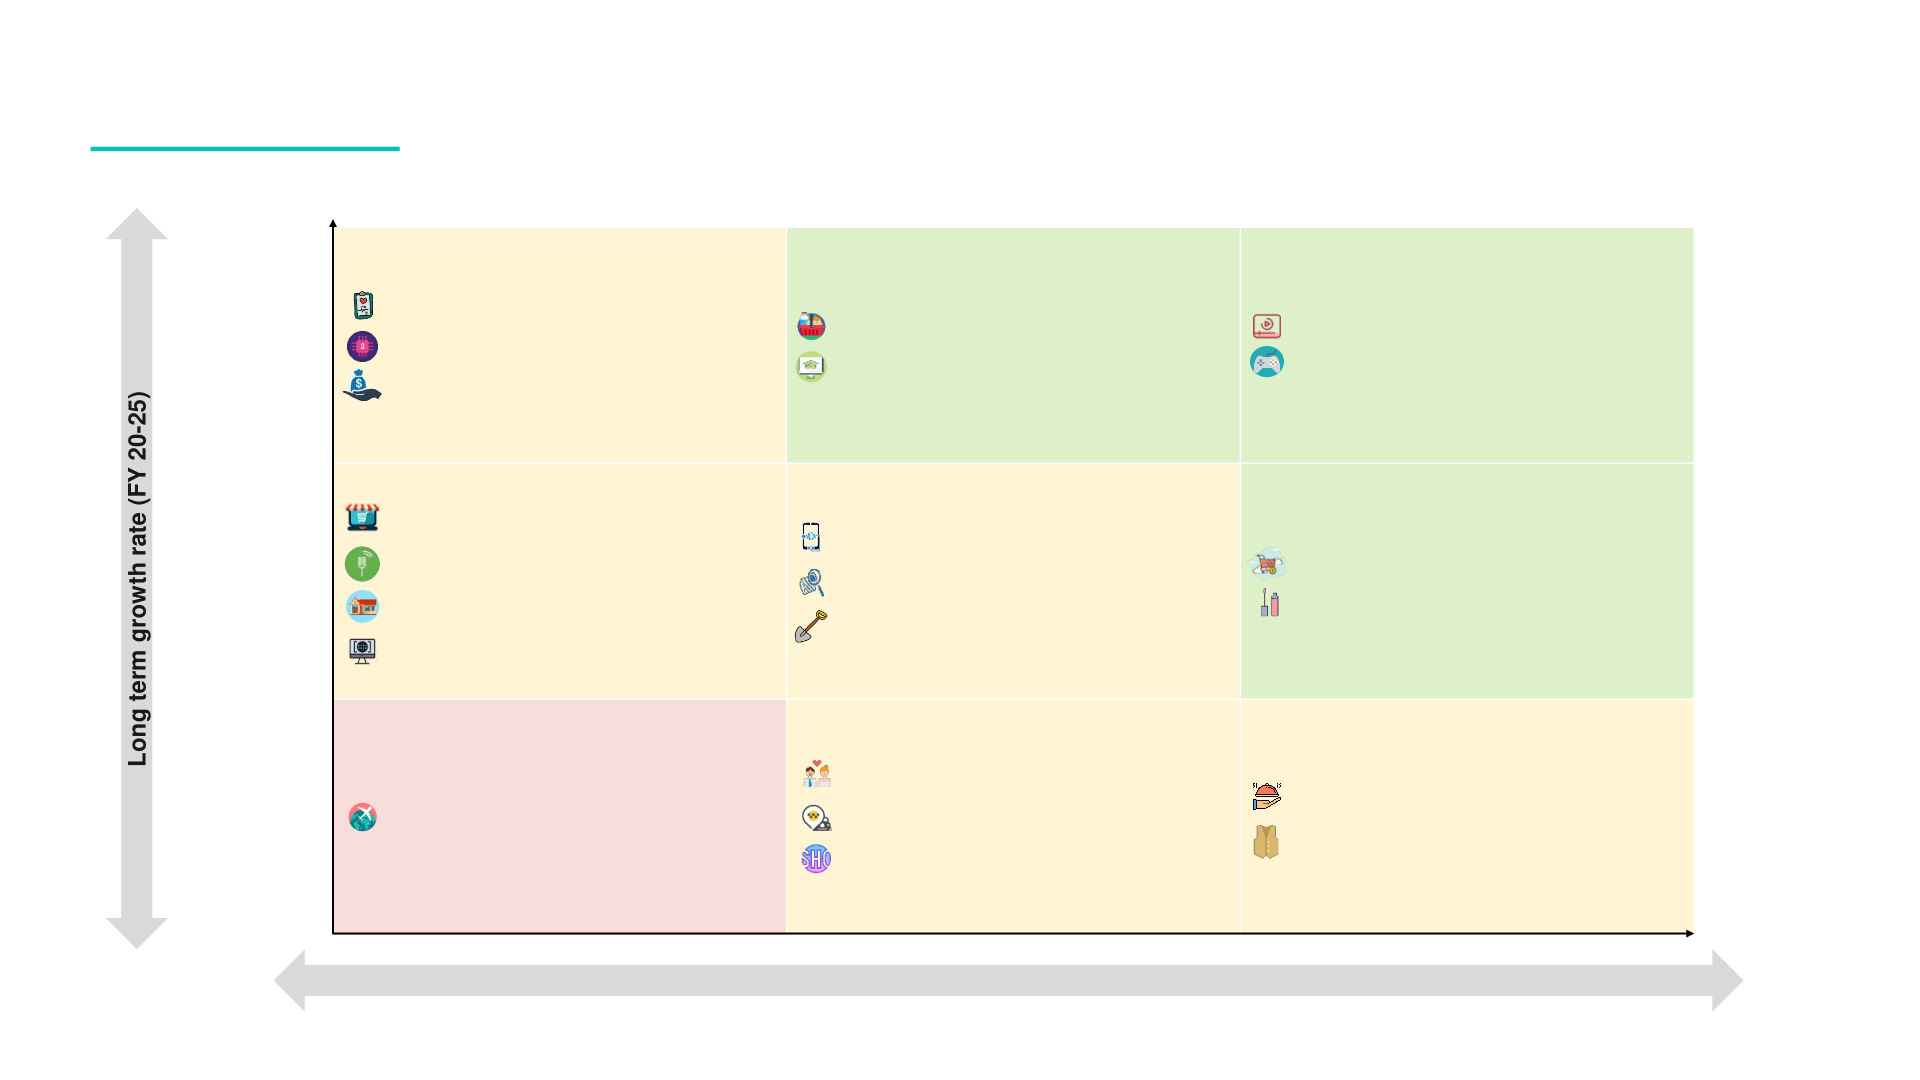
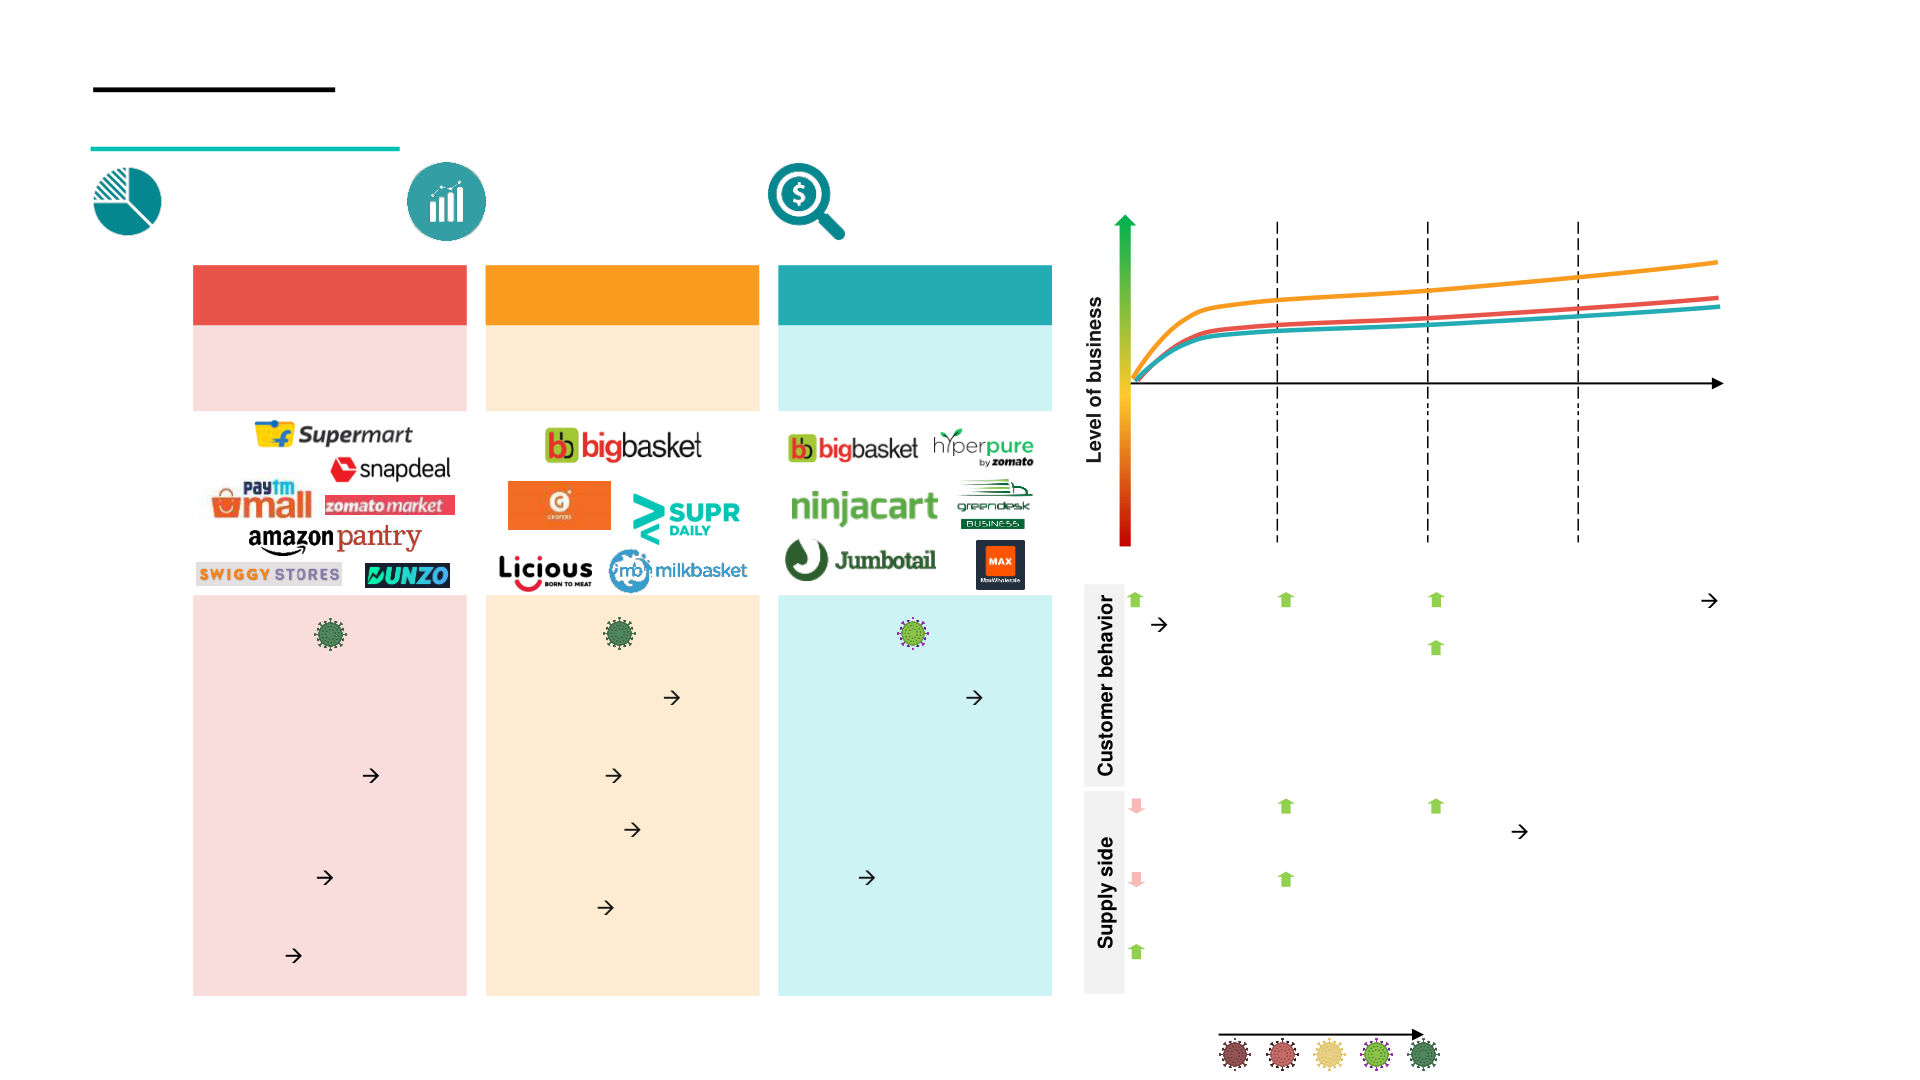
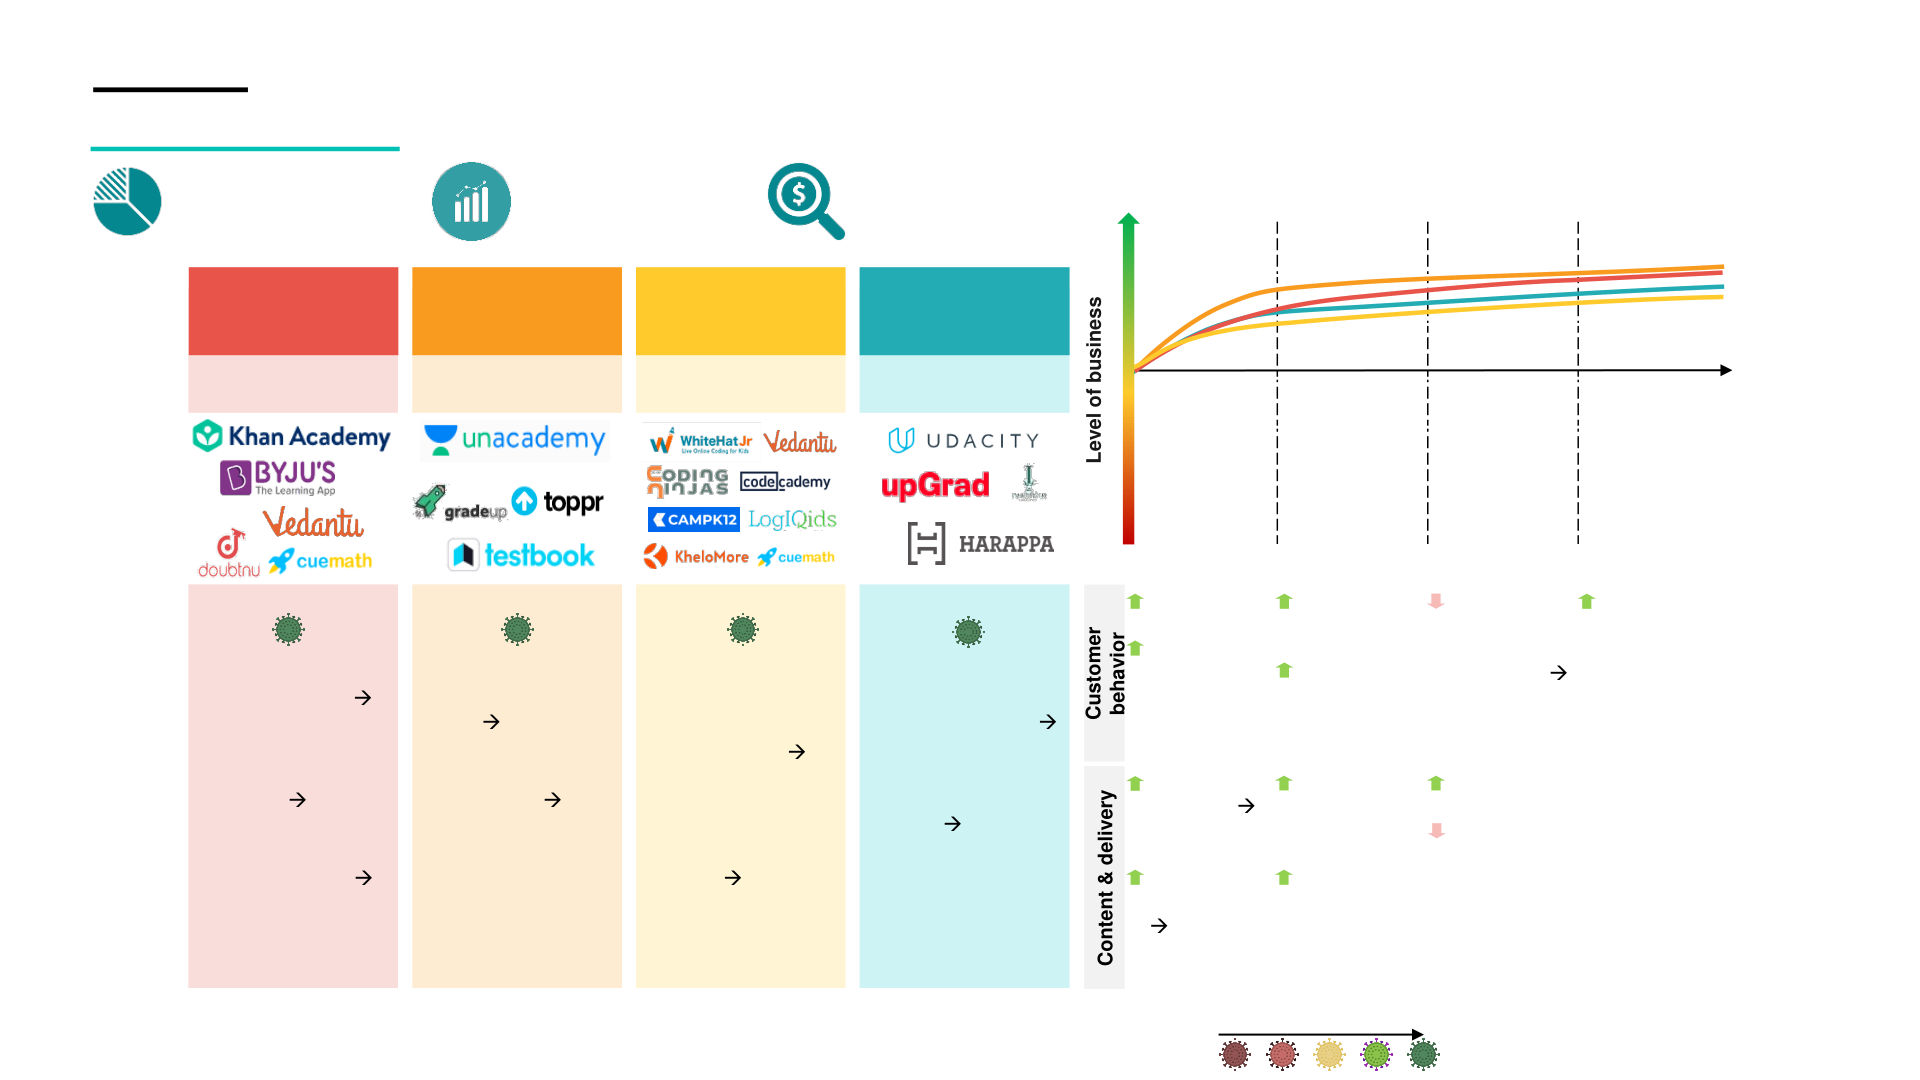
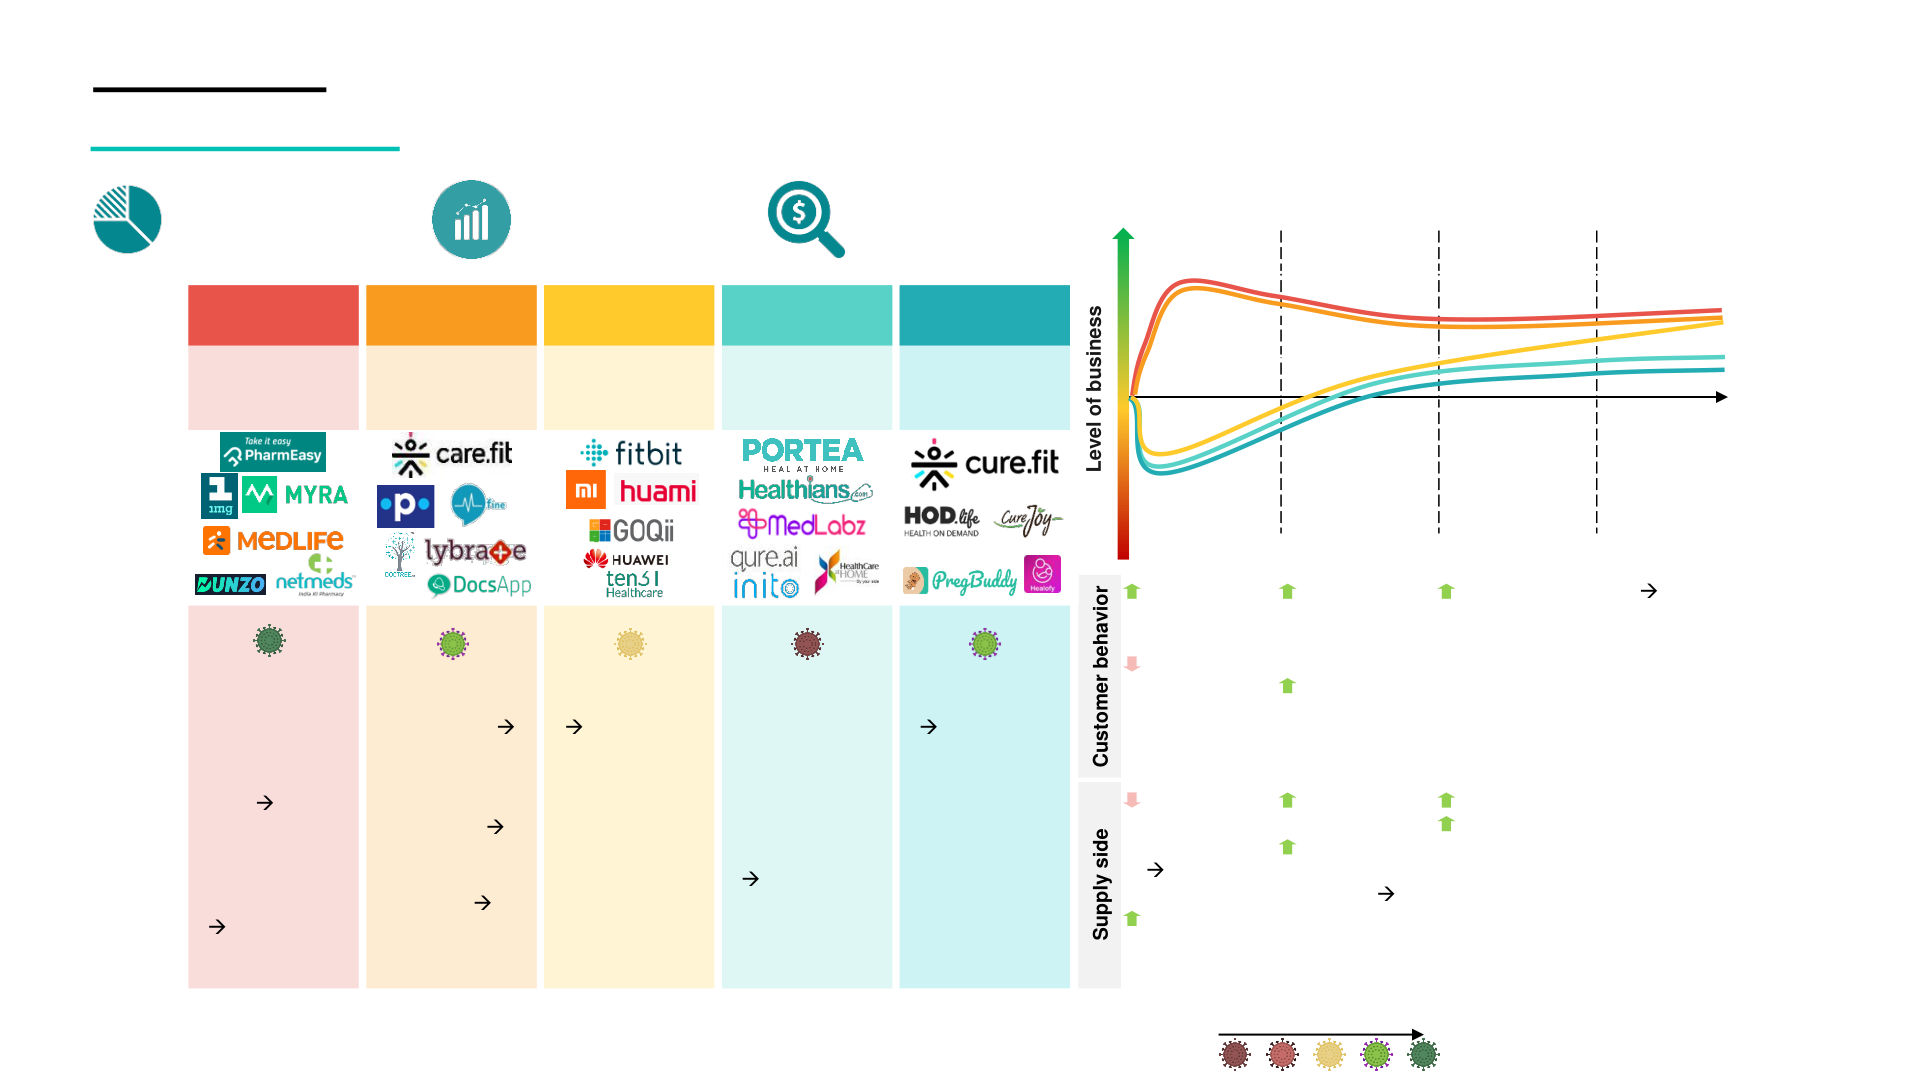
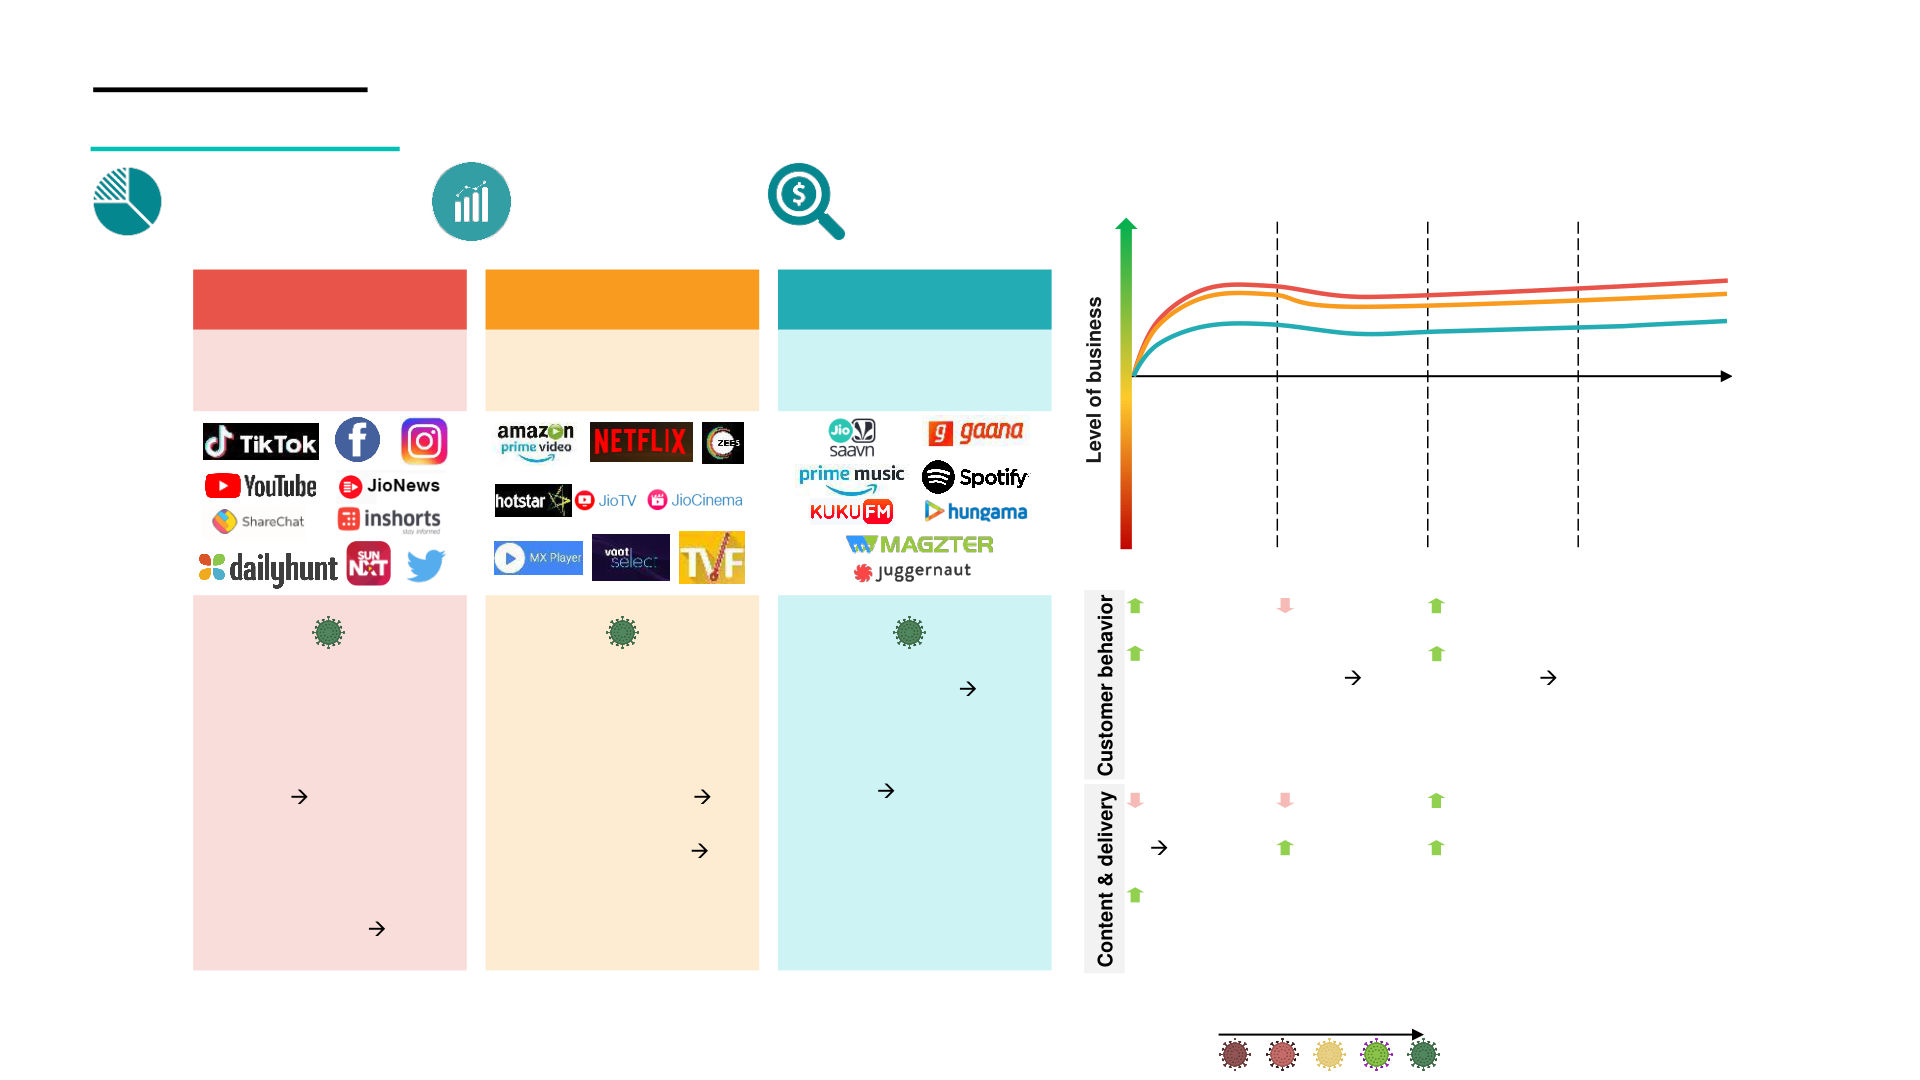
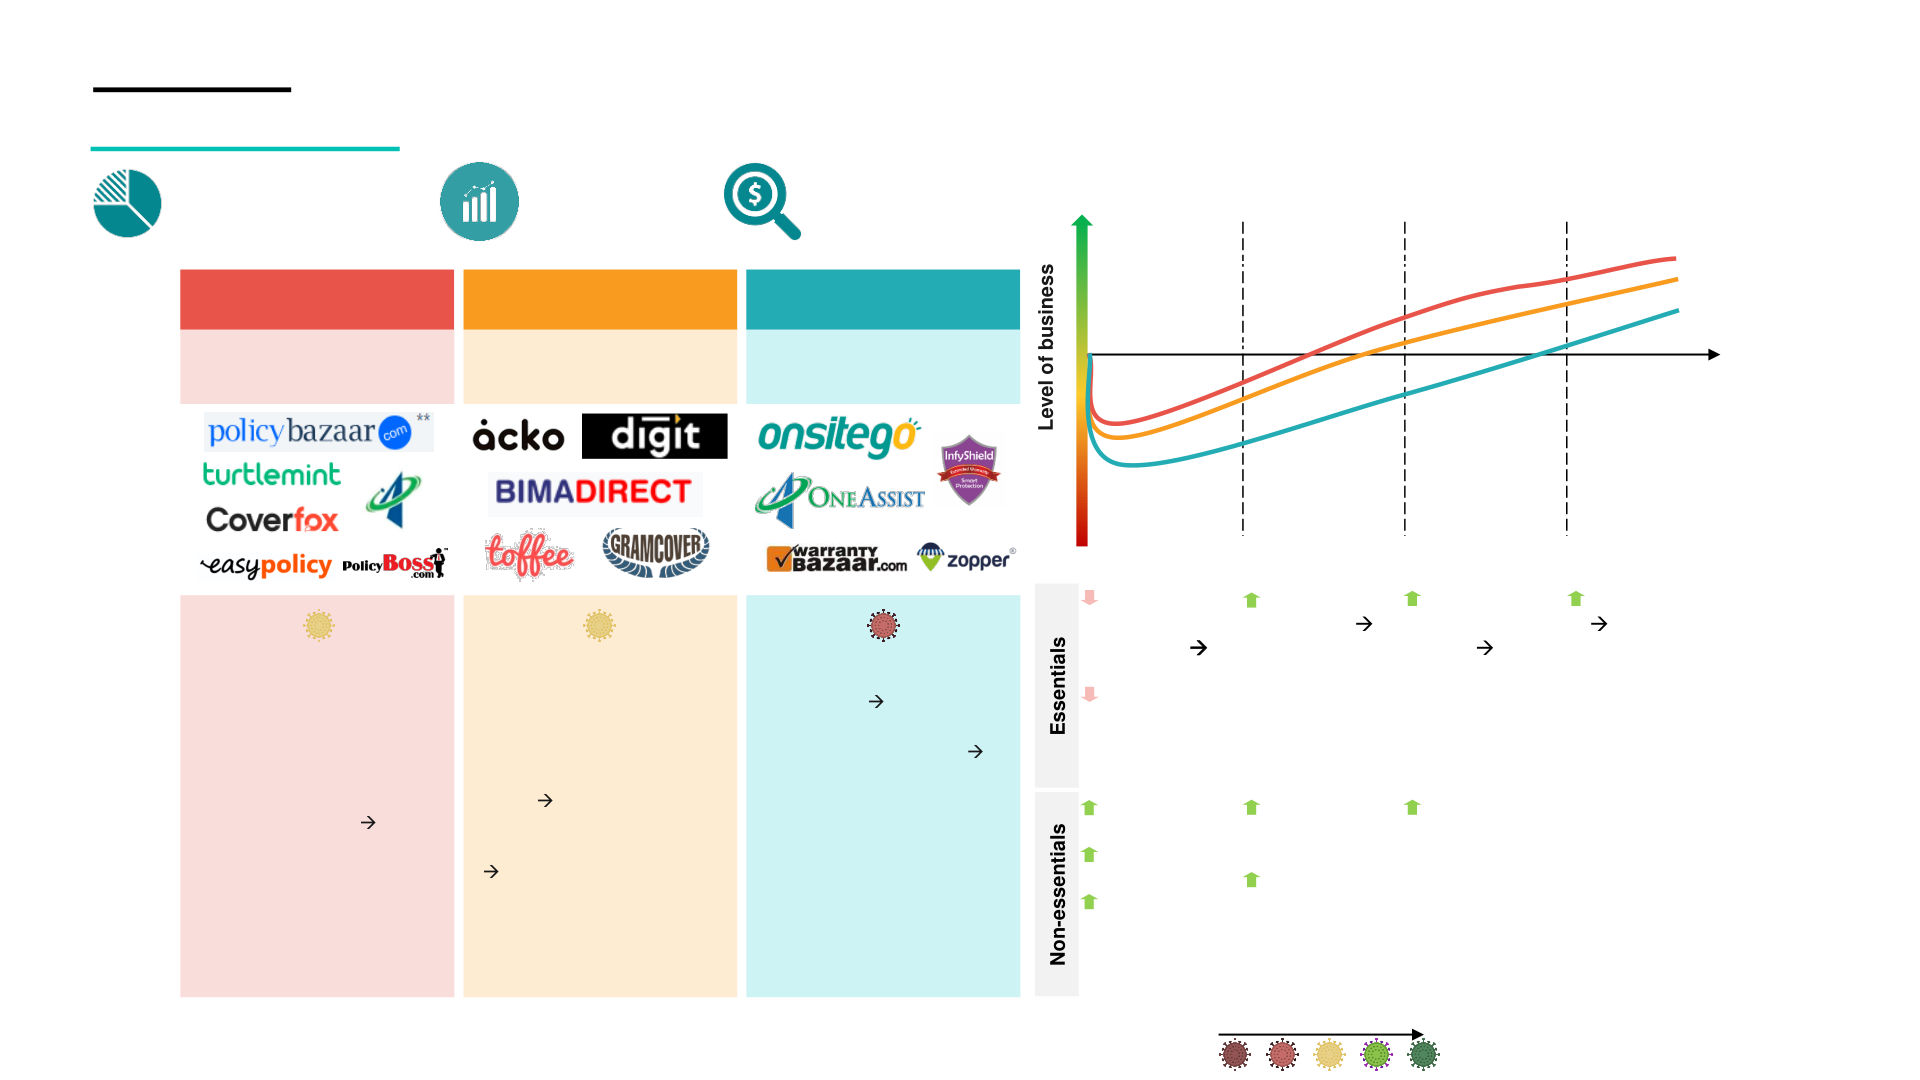
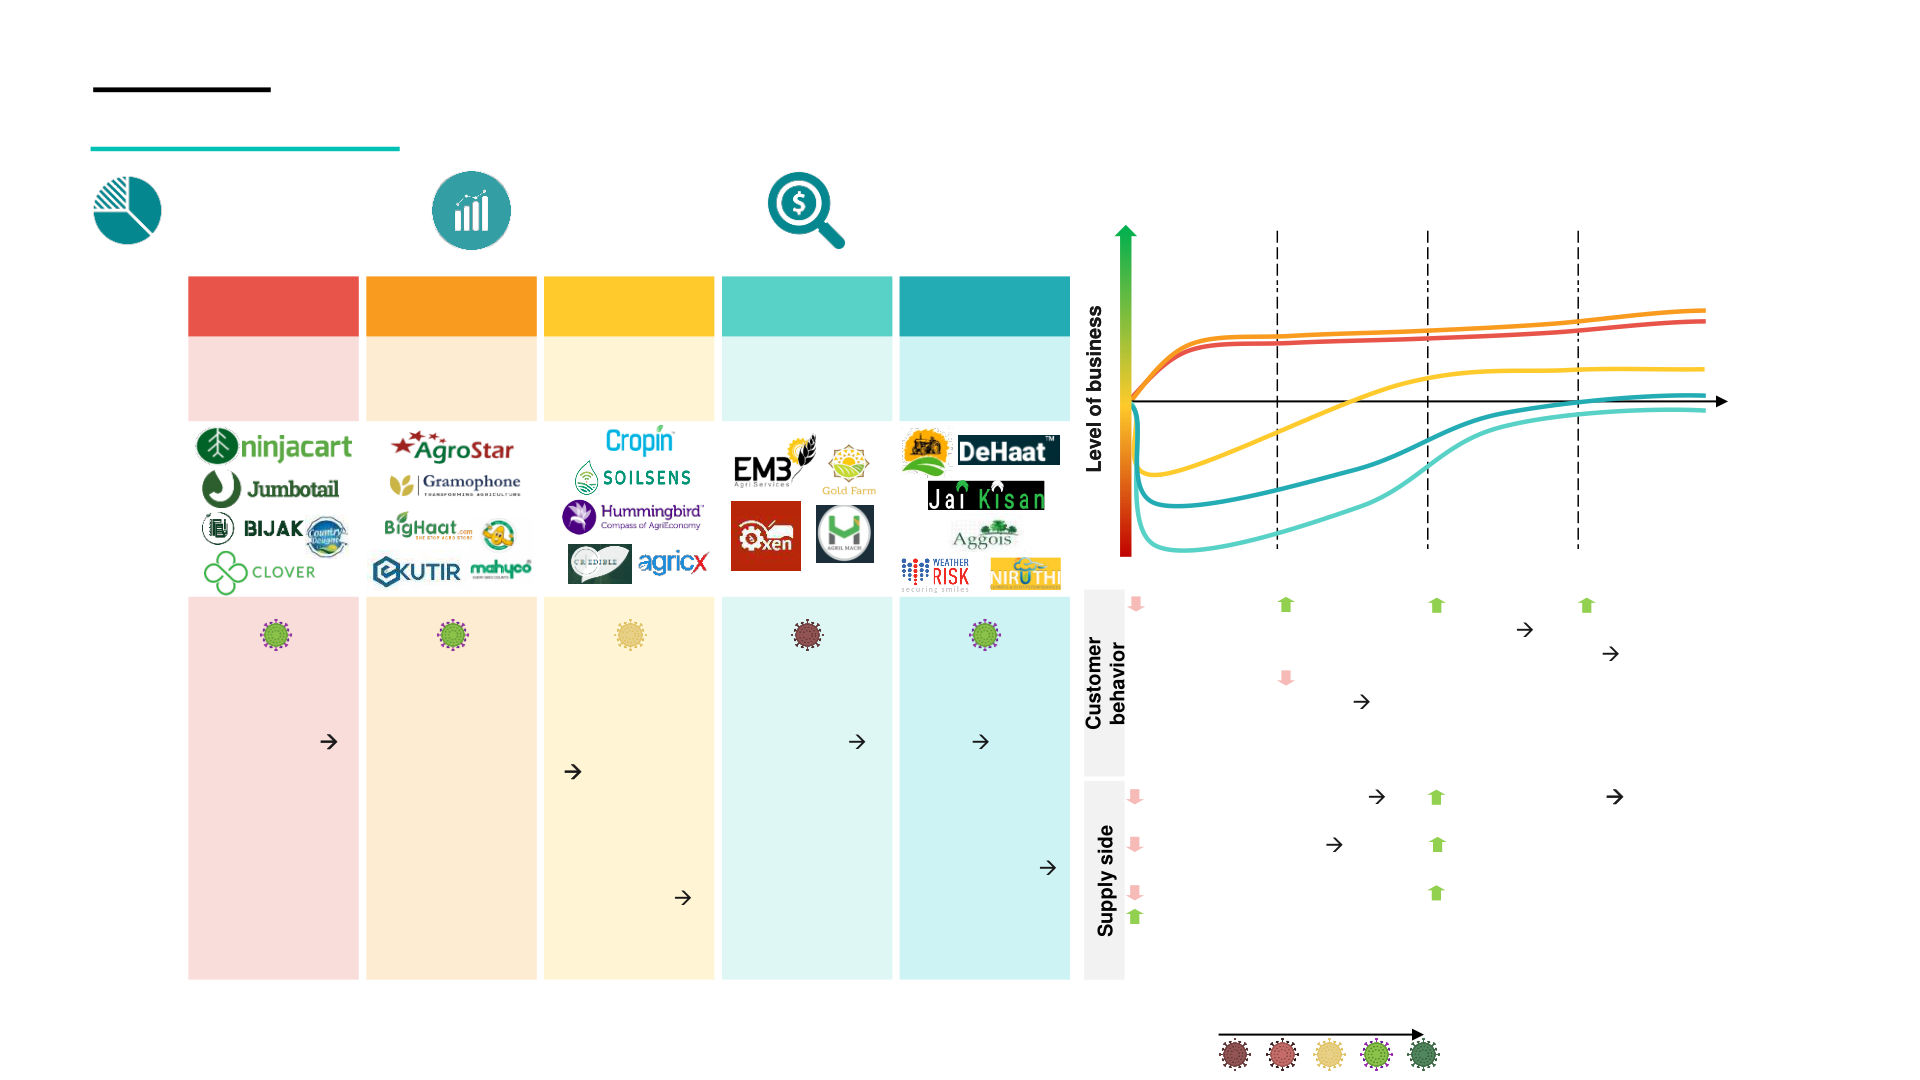
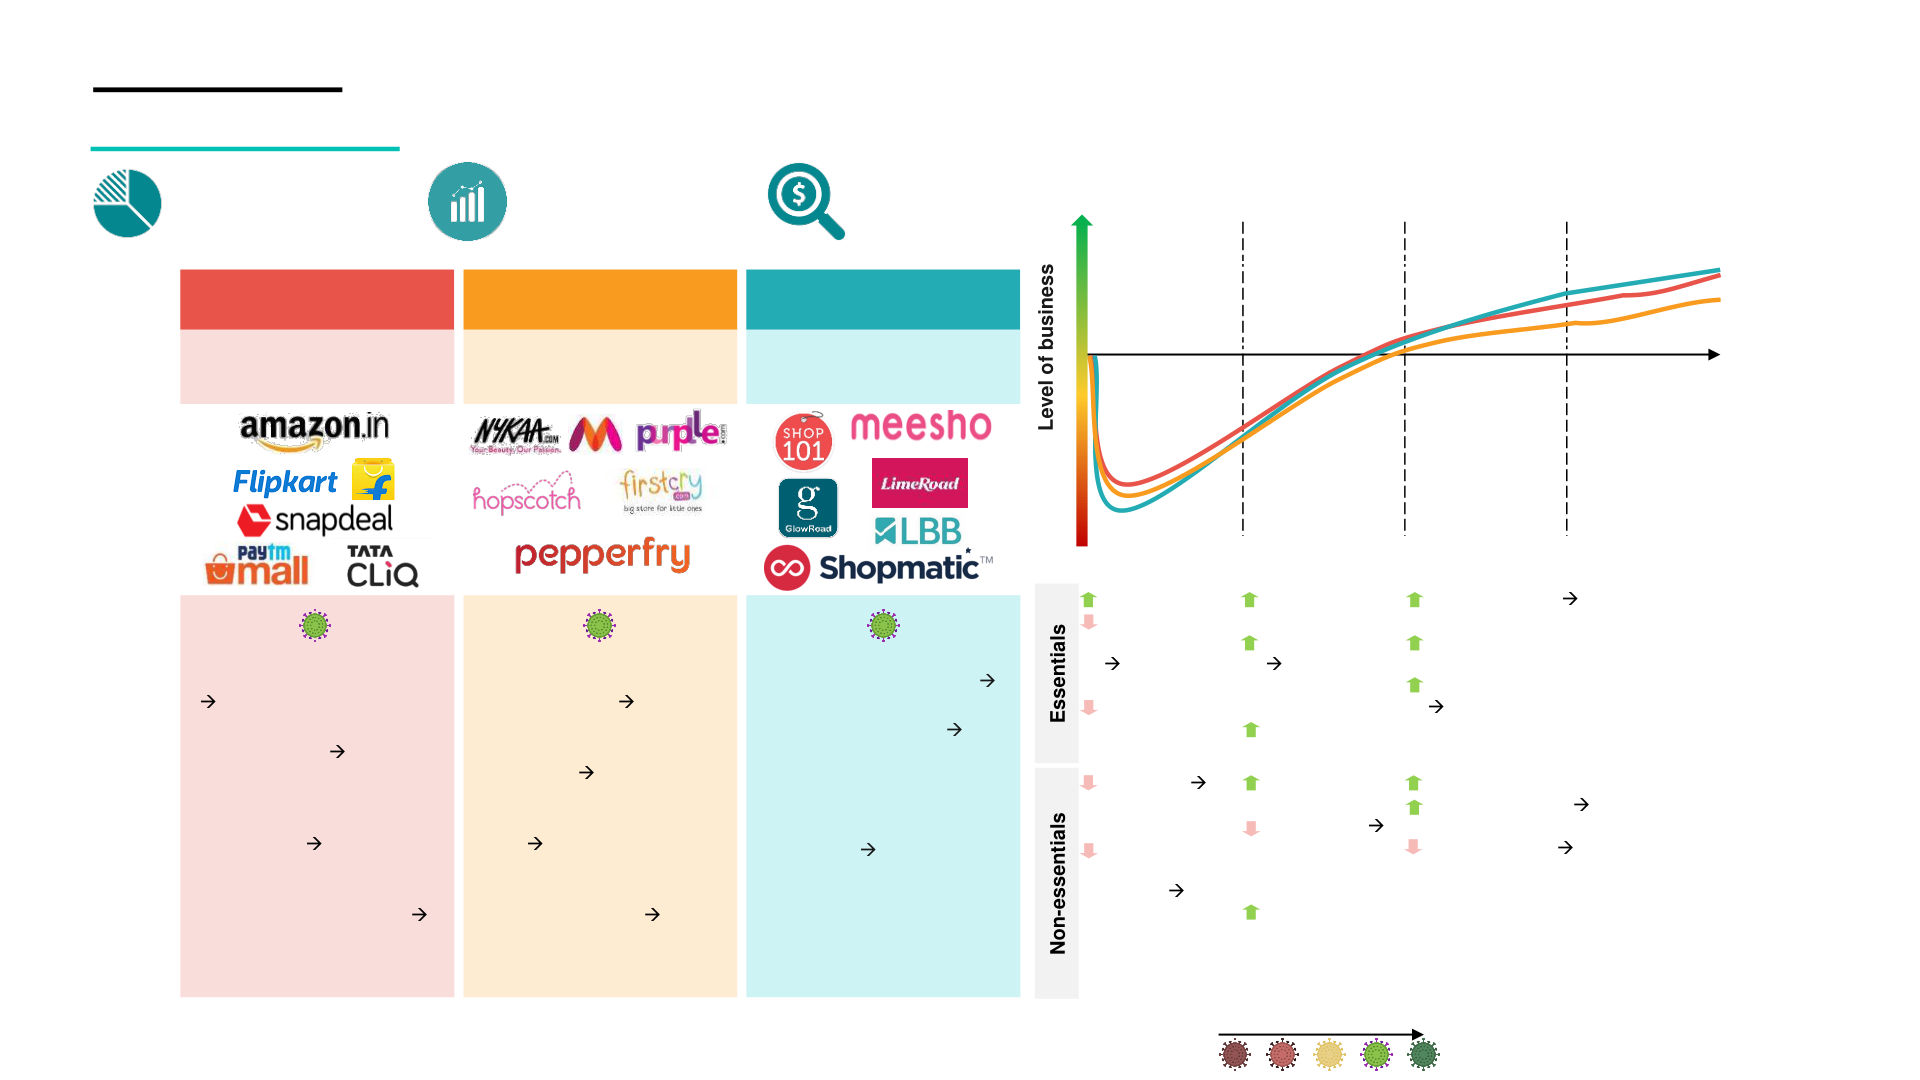
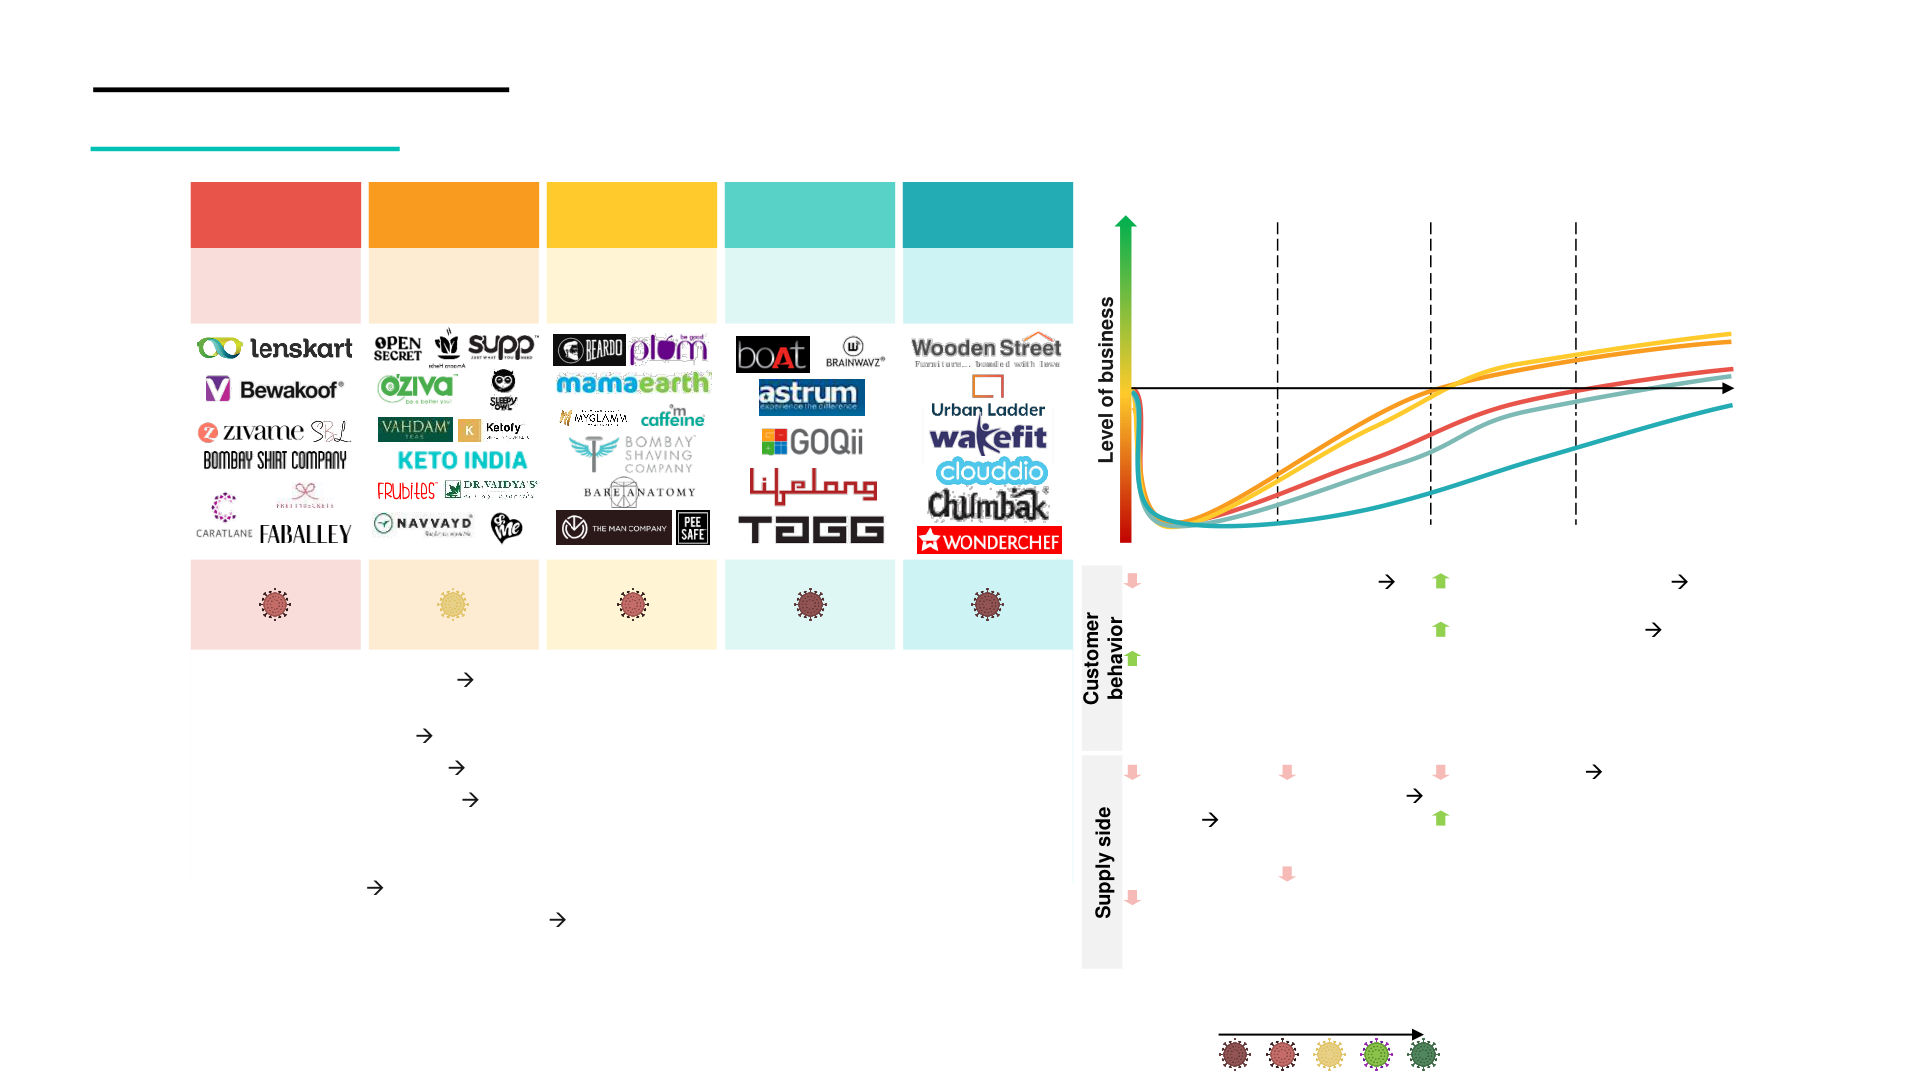
Consumer Internet ‘Re - accelerate’ series From Crisis to Opportunity: How India's Consumer Internet sector will rebound from the COVID - 19 crisis June 2020 Foreword The aftereffects of COVID - 19 pandemic will be wide and large. The pandemic including EdTech, Ecommerce, HealthTech, F&B services, Automobiles to has already affected the economy severely. Although the recovery is going to name a few. We have examined each industry’s pre - COVID - 19 growth, impact be a long - drawn and hard - fought process, Indian economy is resilient and shall of COVID - 19 on key parameters like consumer demand, raw materials bounce back. sourcing, manpower availability, production volumes, supply chain & distribution, and challenges that lie ahead. In addition to the likely recovery scenario based on these key indicators in a post - COVID - 19 world, we have This report is intended to provide various industry stakeholders including outlined some key emerging opportunities that the stakeholders can benefit business leaders an overall perspective on the impact of COVID - 19 on the from to revive their respective organizations & economy at large. Indian economy with a deep - dive on Consumer Internet space as the economy nd starts recovering post a nation - wide lockdown that started on 22 March 2020. In the section on “Impact of COVID - 19 on Indian economy”, we have The situation is evolving rapidly, and some of the expected scenarios might st discussed impact of the current economic cycle on the Indian growth story. have slight variations. This report reflects our perspectives as of 1 June 2020. Contact us for latest updates. We also discuss how the current economic crisis is different from previous ones and India’s likely recovery scenario. In the section on “Shifts in Consumer We, at PGA Labs, look forward to continuing the discussion with our friends Internet”, we have looked at the recovery patterns of different consumer across sectors and exchanging notes as the situation evolves. internet sub - sectors and initiatives that companies in those sub - sectors will need to undertake to make the most of the opportunity brought on by this unprecedented crisis. In the section on “Sectoral impact of COVID - 19”, we have covered over fifty sub - sectors across twenty key industry verticals _____________________ _____________________ Madhur Singhal Aryaman Tandon Managing Director Director © PGA Labs | 2 Key takeaways • India was already slowing down since April 2019; COVID - 19 has exacerbated the impact . Economic ‘recovery’ expected to take seven quarters; FY21 GDP projected to contract by 3.0% • We are observing 4 archetypes of growth trajectories across Consumer Internet sub - sectors: ‒ Sharp increase in growth due to positive changes in consumer behavior ‒ V - shaped recovery within 3 to 6 months followed by steady growth ‒ Slow and steady recovery taking around 12 months ‒ Prolonged period of stress with recovery taking 15 to 18 months • Impact of COVID - 19 has not been homogeneous within sub - sectors e.g. Online gaming • Irrespective of how the segment evolves, winners in each segment will gain share across sub - sectors • Unit economics will improve due to higher revenue per customer, lower CAC and lower operating costs across sub - sectors © PGA Labs | 3 Agenda Impact of COVID - 19 on Indian economy Shifts in Consumer Internet Sectoral impact of COVID - 19 © PGA Labs | 4 India was already slowing down since April 2019; COVID - 19 has exacerbated the impact and made it worse Monthly IIP growth rate in India (%) 8.5 8.4 7.5 7.3 6.9 7.0 6.5 5.3 5.1 4.9 4.8 4.8 4.6 4.6 4.5 4.5 4.4 4.1 3.8 3.5 3.2 3.2 2.9 2.7 2.5 2.4 2.1 2.1 1.8 1.6 1.3 1.2 1.0 0.4 0.2 0.2 - 0.3 - 1.4 - 4.6 - 6.6 Demonetization hitting the cash - based manufacturing sector GST leading to some business re - adjustment - 16.7 Significant recessionary pressure (very visible in Auto, Pharma exports and Real Estate) N D J F M A M J J A S O N D J F M A M J J A S O N D J F M A M J J A S O N D J F M 2016 2017 2018 2019 2020 Index of Industrial Production (IIP) is a metric for health of industry What is IIP ? It is a composite score (out of 100) of performance measure across mining (~14% weight), manufacturing (~78%) and electricity (~ 8%) Note: IIP is measured relative to IIP annual value in FY2011 - 12 Sources: MoSPI , CEIC data, PGA Labs analysis © PGA Labs | 5 COVID - 19 driven economic crisis is different in four ways More pervasive Very fragile backdrop • Has started across countries, simultaneously Difficult geo - political backdrop (escalating • Impacting industries and verticals US - China trade war, US - Iran conflict, HK protests, Turkey/Europe refugee crisis, US elections) More intense/ sudden De - globalization despite Sudden drop in business more global coordination volumes and consumer • Exports as % of GDP grew from ~19% confidence in 2001 to ~30% in 2018 • International tourist arrivals increased from 682M in 2000 to 1.4B in 2018 • But, rapidly growing unemployment, Brexit, diverging fiscal strengths in BRICS Sources: World bank, PGA Labs analysis © PGA Labs | 6 Indian economy was already showing signs of a slowdown Capital purchases have been slow Consumer confidence at a 6 - year low Indian auto sales - volume (%, same month last year) Consumer confidence index (India) Mar-19 May-19 Jul-19 Sep-19 Nov-19 Jan-20 Mar-20 104.6 - 1.4% - 2.1% - 2.7% - 5.5% Jan 20 in dex is - 8.2% 98.3 lowest in over 6 97.3 96.9 96.9 96.7 - 11.1% years - 12.1% 95.5 95.1 94.8 - 14.9% - 16.6% 89.4 Previous - 23.3% Apr 20 sales is lowest: 88.0 - 26.2% zero due to Sep - 13 - 26.5% 85.7 85.6 complete 83.7 lockdown - 45.0% Note: Consumer confidence is a key driver of economic growth and is widely considered a leading economic indicator of household spendi ng on consumption Sources: SIAM, RBI, PGA Labs analysis © PGA Labs | 7 Current economic crisis will have deep impact; we expect economic ‘recovery’ in seven quarters settling into a new normal Real GDP growth rate (%, FY20 - FY22) Phase 1: Phase 2: Phase 3: 8% Sharp Tepid Sluggish growth decline recovery (3 - 4 quarters) 5.6% 6% 4% 4.4% 2% • Growth is expected to • Rapidly declining due to COVID - 19 0% remain sluggish for ~3 ‘black swan’ event quarters • Lockdowns to severely affect output • Slow recovery due to shock due to global lockdowns and worldwide -2% (COVID - 19) containment of trade -4% Real GDP growth • 3 quarters of tepid recovery majorly rate led by Government interventions -6% • Some ‘pent up demand’ comes back FY20 4.2% but recovery of consumer spending remains weak -8% FY21P - 3.0% • Retail liquidity crisis intensifies FY22P 3.7% -10% COVID - 19 Non COVID - 19 Sources: Government data, PGA Labs analysis © PGA Labs | 8 Agenda Impact of COVID - 19 on Indian economy Shifts in Consumer Internet Sectoral impact of COVID - 19 © PGA Labs | 9 E - groceries, Edtech, HealthTech, Digital media and Online gaming are expected to benefit the most due to rapidly changing consumer behavior Sub - sectors AMJ 20 JAS 20 OND 20 JFM 21 E - groceries EdTech HealthTech Digital media Online gaming Beauty, hygiene and personal care Online dating and matrimony Digital payments and personal finance Insurtech Agritech Ecommerce Internet first brands Foodtech Online classifieds and rentals F&B services Home services Automobiles Real estate tech Apparel and footwear Shared mobility Digital lending Hospitality, travel & tourism Entertainment Notes: The trends of increase and decrease in sales are quarter - on - quarter. The first quarter impact is with respect to pre - COVI D - 19 levels in JFM 20 Source: PGA Labs analysis Substantial Moderate About the Moderate decline Substantial © PGA Labs | 10 increase in sales increase in sales same in sales decline in sales Growth trajectory and roadmap for sub - sectors to bounce back Impact of COVID - 19 on revenue (April) E - groceries Certification & training platforms Hygiene products Digital media - news & entertainment EdTech - supplementary education >20% Real money games (excl. FSG) Property management E - pharmacy Telemedicine & scheduling Casual games, e - sports (incl MMORPG) • OTT platforms Fitness wearables • Personal care • Test preparation Audio streaming 0 - 20% • Home care • Out of school / extra - curricular • Agritech - crop inputs • Online dating & matrimony Personal finance Offline dating Personal health mgmt. AgriTech - market linkages Automotive marketplaces 0 - 20% Online rentals Neobanks Loan marketplace 20 - 40% Real estate listing platforms Insurance aggregators Digital insurers Classifieds – recruitment Diagnostics & care Vertical Ecommerce Internet first brands Automotive vehicles Shared mobility – buses Digital payments Home services - local Loyalty services Auto service Premium hotels, OTAs 40 - 80% Horizontal Ecommerce Dark kitchens Horizontal classifieds Co - living Hostels & home - stays Shared mobility – rentals Social Ecommerce and O2O Electric vehicles Restaurants, PBCLs Co - working spaces QSRs RMG - Fantasy sports Home design services Direct lending, P2P lending Shared mobility - ride hailing Budget hotels Formal wear, footwear Casual wear Color cosmetics Multiplexes, fitness centers Time for recovery to pre - COVID - 19 level 1 - 6 months 6 - 12 months > 12 months Source: PGA Labs analysis © PGA Labs | 11 We are observing 4 archetypes of growth trajectories across sectors – each archetype will need to respond differently to the crisis Focus areas Likely recovery scenario Key sub - sectors Archetype • E - groceries • News & entertainment media • Micro market analysis for growth (non - FSG) • Real money games • OTT platforms • Scan for consolidation opportunities Being • Manage customer behavior change • Supplementary EdTech • E - pharmacy opportunistic • EdTech certification • Refining product - market fit • Telemedicine platforms • Customer loyalty programs Q1 Q2 Q3 Q4 Q5 Q6 • Personal care and hygiene • Property management • Diagnostics & care • Ecommerce • Preparing for scale : SOPs, automation, digitization Being • Personal health mgmt. • Dark kitchens • New product iterations and launch cautiously • Online dating and matrimony • QSRs • Navigating geographical expansion optimistic • Digital insurers, aggregators • Automotive marketplaces • Reevaluate GTM plans Q1 Q2 Q3 Q4 Q5 Q6 • Digital payments • Personal finance • Hotels • Co - living • Employment decisions (hiring / rightsizing / furlough) Navigating • Automotive vehicles • Restaurants • ‘Muscle building’ & process through the • RMG - fantasy sports • Internet first brands improvement to increase productivity rough waters • Food delivery aggregators • Property listing platforms • Streamline product portfolio • Foodtech – loyalty services • Casual wear and lifestyle Q1 Q2 Q3 Q4 Q5 Q6 • Incentivize to buy now - than - later • Ride hailing platforms • Zero - based assessment of costs • Co - working • Online travel aggregators • Pubs, clubs and lounges • Renegotiate the long - term contracts Surviving the Monetize assets • Bags and luggage • Formal wear crisis • Aggressive targets for receivables • Multiplexes • Fitness and wellness centers • Incentivize customers to pay in Q1 Q2 Q3 Q4 Q5 Q6 advance Source: PGA Labs analysis © PGA Labs | 12 Sectors have been impacted by COVID - 19 in varying degrees and will need to focus on different initiatives Impact of COVID - 19 on consumer internet sectors Positive Build muscle; Transform unit economics Drive penetration and chase growth Online gaming Digital payments and personal finance E - groceries Ecommerce EdTech Insurtech Internet first brands Digital media Foodtech Agritech HealthTech Beauty, Digital lending hygiene and Online dating Online classifieds and rentals personal Care and matrimony Manage cost and cash; Retool the model Opportunistic bet Home services F&B services Apparel Market size 2019 (US$) Shared mobility Automobile and Real estate >10B footwear tech Entertainment 1 - 10B Hospitality, travel & tourism <1B Adverse Impact on short - term growth Source: PGA Labs analysis © PGA Labs | 13 Impact of COVID - 19 has not been homogeneous even within a sub - sector Health tech Online gaming Positive Positive RMG (non - FSG) E - pharmacy Fitness wearables Telemedicine E - sports ( incl MMORPG) Diagnostics Personal health Casual gaming RMG - Fantasy sports management Adverse Adverse Digital payments and personal finance Real estate tech Positive Positive Digital payments Property management Personal finance Fundraising Neobank Listing platforms Co - living Co - working Adverse Impact on short - term growth Impact on short - term growth Source: PGA Labs analysis © PGA Labs | 14 EdTech, Online gaming, E - groceries and HealthTech have become attractive opportunities for investors given the positive impact of COVID - 19 on long term growth Insurtech EdTech E - groceries CAGR: >30% Digital payments HealthTech Online gaming Digital lending Ecommerce Digital media FoodTech Internet first brands CAGR: 12 - 30% Online classifieds and rentals Real estate tech Beauty, hygiene & personal care AgriTech Home services Online dating and matrimony F&B services CAGR: 0 - 12% Hospitality, travel and tourism Shared mobility Apparel and footwear Entertainment Long Mid Short Path to profitability Source: PGA Labs analysis © PGA Labs | 15 Irrespective of how the segment evolves, winners in each segment will gain share across sub - sectors ILLUSTRATIVE E - Grocery Digital Media E - Pharmacy Diagnostics and care Personal Health & Fitness Food delivery Dark kitchens Vertical Ecommerce Home improvement services Shared mobility App based buses Automotive classifieds Budget hotels Co - working Co - living Source: PGA Labs analysis © PGA Labs | 16 Unit economics will improve due to higher revenue per customer, lower CAC and lower operating costs, for example, E - groceries Impact of Unit economics (per order, US$) Pre - COVID - 19 % of AOV Post - COVID - 19 % of AOV COVID - 19 Average order value (net of GST) 15.3 100% 18.7 100% Wastage cost 0.1 1% 0.2 1% Transaction cost 0.1 <1% 0.1 1% Net revenue 15.1 18.4 Cost of goods sold 11.5 75% 14.0 75% Contribution margin 1 / Gross margin 3.6 24% 4.4 23% Fulfilment cost 1.5 10% 1.8 9% Packaging cost 0.0 0% 0.0 0% Last mile delivery cost 1.2 8% 1.1 6% Contribution margin 2 0.9 6% 1.5 8% G&A and other cost 1.5 10% 1.5 8% Tech & product cost 0.5 3% 0.5 3% Customer acquisition cost 0.5 3% 0.3 2% Contribution margin 3 / EBITDA - 1.7 - 11% - 0.9 - 5% Change from pre - COVID - 19 levels Increase, positive Increase, adverse Decrease, positive Decrease, adverse No change Source: PGA Labs analysis business impact business impact business impact business impact © PGA Labs | 17 Unit economics will improve due to higher revenue per customer, lower CAC and lower operating costs, for example, EdTech Impact of Unit economics (per user, US$) Pre - COVID - 19 % of revenue Post - COVID - 19 % of revenue COVID - 19 Average revenue per user 180 100% 180 100% Less: Taxes 16 9% 16 9% Earnings after taxes 164 91% 164 91% Cost of revenue 25 14% 22 13% Consumption (Assets cost) 20 11% 20 11% Payment transaction charges 2 1% 2 1% Logistics cost 2 1% 1 1% Printing material cost 2 1% - 0% S&M Costs 49 27% 41 23% Digital, marketing & sales cost (CAC) 49 27% 41 23% Contribution margin 90 50% 100 56% G&A costs (US$ M) 34 19% 34 19% Salaries 11 6% 11 6% Facility cost 9 5% 9 5% G&A 14 8% 14 8% EBITDA 56 31% 66 37% Change from pre - COVID - 19 levels Increase, positive Increase, adverse Decrease, positive Decrease, adverse No change Source: PGA Labs analysis business impact business impact business impact business impact © PGA Labs | 18 Unit economics will improve due to higher revenue per customer, lower CAC and lower operating costs, for example, Foodtech (Dark kitchens) Pre - COVID - 19 Post - COVID - 19 Monthly unit economics Impact of Units Total Per order Total Per order (At steady state, kitchen area 2,500 sq.ft .) COVID - 19 Revenue Average order value (AOV) US$ 3.0 3.1 Number of orders fulfilled in a day # 1,400 1,540 Total number of orders in a month # 42,000 46,200 Total revenue US$ 123,000 3.0 143,000 3.1 Variable costs Supplies per month (food) US$ 42,000 1.0 46,200 1.0 Packaging costs US$ 12,500 0.3 13,860 0.3 Delivery cost US$ 25,000 0.6 26,334 0.6 Others (PG, gas) US$ 1,500 1,650 - Total variable costs US$ 81,000 1.9 88,000 1.9 Fixed costs Kitchen overheads US$ 13,500 0.3 15,000 0.3 Aggregate payout to kitchen staff US$ 13,500 0.3 15,000 0.3 Total fixed costs US$ 27,000 0.6 30,000 0.6 Total costs US$ 108,000 2.6 118,000 2.6 Kitchen level EBITDA US$ 15,000 0.4 25,000 0.5 Kitchen level EBITDA margin % 12% 12% 17% 17% Kitchen level EBITDA per order US$ 0.4 0.5 Kitchen level profit per sq ft. US$ 6 10 Change from pre - COVID - 19 levels Increase, positive Increase, adverse Decrease, positive Decrease, adverse No change Source: PGA Labs analysis business impact business impact business impact business impact © PGA Labs | 19 Agenda Impact of COVID - 19 on Indian economy Shift in Consumer Internet Sectoral impact of COVID - 19 © PGA Labs | 20 E - groceries : Sector to benefit from crisis as consumer behavior changes and short - term operational challenges are overcome Expected industry recovery pattern (relative to pre - GMV (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) ~US$ 3.2B 40 - 50% ~US$ 0.8B Highly positive B2C - Horizontals B2C - Verticals B2B Positive ` Market Pre - COVID Oligopoly Oligopoly Oligopoly structure levels Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Fear of virus Targeted Long - term behavioral shift panic buying of higher digital adoption COVID - 19 buying & essentials Demand stabilizes due to impact safe home normalcy in market deliveries • Realignment of supply • Surge in demand high • Surge in demand higher Industry chain to cater to essentials digital adoption ticket value purchases by outlook kirana shops • Focus on procurement of • Ensure seamless essential SKUs seller operations hiring of • Expansion of services partnerships delivery partners across regions to increase Operational More Change in salesman driven coverage • Accessibility and • Partnerships s trengthen challenges targeted ads model higher tech convenience for the supply chain operations • Focus on procurement of in delivery by FMCG integration consumers increased goods more alliances Longer & Higher digital • Increased use of data time slots for deliveries with sellers planned adoption by analytics demand accessibility retail stores • Measures to ensure fair forecasting & preparation • Increase in # tie - ups with More tie - ups pricing blocking sellers local kiranas • AI to prevent hoarding Degree of COVID impact Sources: Euromonitor, PGA Labs analysis © PGA Labs | 21 Highly negative Highly positive EdTech : Growing sector to get a fillip as traditional education channels are disrupted, and job uncertainty grows Expected industry recovery pattern (relative to pre - Market potential (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) ~US$ 80B 50 - 55% ~US$ 1.7B Highly positive Supplementary Certification & Out of school / Positive education & Test preparation training extra - curricular tutoring platforms Pre - COVID Market Oligopoly Oligopoly Fragmented Fragmented levels Time period structure Negative Players Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Availability of Higher Festive Greater COVID - 19 spare time conversion distractions acceptance impact Greater of free users + l ack of and comfort with More spare time adoption Industry e - learning demand for stabilized among users • School closures • Physical to digital • Nascent stage • Job uncertainty + outlook upskilling growth in long - term increase in user shift focus on time availability • Competition for adoption c ustomer increased demand student’s time acquisition for upskilling • Partnerships with surge in adoption Availability of More Focus on refining quality of schools higher • High stakes to drop off • More organic teachers interactive content B2B growth content quality key reach l ower CAC • Lower i ncrease in modules Shift to traditional methods differentiator • Market leaders to discretionary • Increase in # content introduced benefit the most • Focus on spend offset customers over a Offline Expansion trust + content vernacular growth long period partnership through variety modules creation of vernacular e - learning content solutions Degree of COVID impact Sources: UDISE, NSDC, AISHE, CRISIL, PGA Labs analysis © PGA Labs | 22 Highly negative Highly positive HealthTech : Sector expected to benefit in the long - run as more people turn to HealthTech solutions for healthcare related problems Expected industry recovery pattern (relative to pre - Funding (2018 - 19) Market size (FY20) Growth rate (FY20 - 24) COVID - 19 level) ~US$ 1.6B 30 - 40% ~US$ 1.3B Highly positive Telemedicine Diagnostics Health and E - pharmacy Wearables Positive & scheduling and care fitness Pre - COVID Market Fragmented Fragmented Fragmented Fragmented Fragmented levels structure Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 S urge in Increased Change in behavior higher demand for e - demand for at - digital adoption in tele COVID - 19 pharmacy home medicine impact Drop in services bookings but Preventive • Continued • Customer • Fall in imports • Fall in demand • Fear of illness Industry shift to tele health operations acquisition supply for existing better health outlook consultation monitoring amidst promotional constraints offerings management lockdowns pricing and trials • New features • Increased • Personalized Labor New product Expansion of service offerings • Fear panic • Professionals introduced e.g. demand for at - insights shortage + launches Supply chain constraints buying + PPE onboarded temperature home service through procurement Exhaustive stabilizing demand higher costs check analytics • New offerings s upply quality • Strengthening • Focus on B2B • Corporate tie - f aster • Focus on low chain issues checks supply chain segment ups testing & cost T ie - ups with better increased more tie - ups & approvals for innovation • Entrant of new govt. & products hiring partnerships essential players private org. services Degree of COVID impact Source: PGA Labs analysis © PGA Labs | 23 Highly negative Highly positive Digital media : Sector to witness a growth spurt on the back of increased user adoption and subscription revenue Expected industry recovery pattern (relative to pre - Digital ad spend (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) > US$ 3.5B 25 - 30% ~US$ 0.5B Highly positive News & entertainment OTT platforms Audio streaming Positive Market Pre - COVID Fragmented Oligopoly Fragmented structure levels Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Surge in Live in - Live sports streaming COVID - 19 viewership person demand picks up impact Shift from entmt. + l ess Change in customer mobile to TV time behavior stickiness + • Surge in daily active users • Increase in viewership • Time availability Industry streaming viewership renewals and new subscribers adoption of various outlook • Shift from newspapers to decline platforms, formats alternate source of news • Reduced ad revenue but more paid subscribers • Demand for diversity in • News, health related content podcasts content partnerships • More organic reach Network Content Focus on creating originals with credible organizations, focus on retention • Focus on personalized congestion pipeline dry and vernacular content celebrities experience and AI/ML e.g. reduced Acquisitions / Sports events restart • Differentiate offering p re - curated playlists quality tie - ups to • Focus on regional content investment in original Virtual boost and expansion content + delivery systems • Launch of social features events + new content to build network effects • Build credibility tools / shows variety features to curb “fake news” Degree of COVID impact Sources: Annual reports, PGA Labs analysis © PGA Labs | 24 Highly negative Highly positive Online gaming : Real money gaming to witness a growth spurt with increased user adoption and engagement; fantasy sports segment hurt by lack of real - life activity Expected industry recovery pattern (relative to pre - Funding (2018 - 19) Annual revenue (FY20) Growth rate (FY20 - 24) COVID - 19 level) ~US$ 1.6B 30 - 35% ~US$ 0.3B Highly positive Real money Real money E - sports games – Fantasy Casual games Positive games - Others (incl. MMORPG) sports Pre - COVID Market Oligopoly Fragmented Fragmented Fragmented levels Time period structure Negative Players Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Lack of Normal Sports activity fantasy recreation routine sports picks up surge in resumes Habit formation demand to COVID - 19 downloads, less time stabilize impact engagement availability • Cancellation of • More time available • Social distancing • Lack of actual Industry major sporting h igher adoption of social outlook sports increase activities no participation games in e - sports Sporting activity cancelled Marketing spends reduced revenue more organic viewership and • Growth offset by hit in f antasy sports revenue lower ad revenue downloads leagues • Temporary s hift to lower ad revenue Investment in platform and card and other real • Focus on user • Social distancing scaling up technology • Introduction of new money games engagement and shift from physical games to cater to More online events and e - retention more to virtual events increased demand sports competitions new offerings and competitions Degree of COVID impact Source: PGA Labs analysis © PGA Labs | 25 Highly negative Highly positive Beauty, hygiene and personal care : Increased focus on personal wellness and greater institutional adoption to drive steady growth Expected industry recovery pattern Market size (FY20) Growth rate (FY20 - 24) (relative to pre - COVID - 19 level) > US$ 16B 18 - 22% Highly positive Beauty and color Personal care Hygiene Home care cosmetics Positive Market Fragmented Fragmented Oligopoly Oligopoly Pre - COVID structure levels Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 COVID - 19 Retail closure Increased Continued demand for home impact Accelerated going out care, hygiene products adoption in recovery in • Lower tendency to • Considered • Consumer focus • Increased Industry online sales beauty go out + use of essential limited on wellness emphasis on outlook Increased products masks drop in impact on demand increase in demand hygiene demand for Personal care sales increased demand • Lower visits to • Hand hygiene to home care, demand • Eye makeup and salons personal drive growth • Greater institutional hygiene steady hair color growth to care demand to demand e.g. offices, • Greater institutional offset temporary increase airports, etc. Shift in offline retail channels Supply chain and demand e.g. offices, drop in lipsticks • Supply chain + production manufacturing normalizes • Shift from offline to airports, etc. issues • Promotions + online channels discounts to move • New product seasonal inventory launches Degree of COVID impact Source: PGA Labs analysis © PGA Labs | 26 Highly negative Highly positive Online dating and matrimony : Sector seeing increased customer engagement levels, but monetization challenges remain Expected industry recovery pattern (relative to pre - Market size (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) ~US$ 300M 10 - 12% < US$ 0.1B Highly positive Online dating Offline dating Matrimony Positive Market Fragmented Oligopoly Oligopoly Pre - COVID structure levels Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Social distancing + time Change in user behavior new users + increased i ncrease in subscriptions COVID - 19 engagement Higher adoption to new impact No real - life interactions offerings • Social distancing more • Real life events virtual • More time availability Industry lower subscription rate free users, engagement events h igher registrations outlook • Customer acquisition • Stress + isolation more • Increase customer base free features like ‘Passport’ users and engagement discounts, free trials • Change in user • Older customers signing • Uptake in virtual feature Organic increase in profile preferences and filters up new offerings in app video and tele - acquisitions more engagement calling Free features / trials to • More organic signups enhance acquisitions • Tie - ups and partnerships l ower CAC • Increased focus on Collaboration / tie - ups for for new offerings, content marketing “Weddings • Focus on acquisition and content and events from home” • Lower subscription monetization revenue Degree of COVID impact Sources: Annual reports, PGA Labs analysis © PGA Labs | 27 Highly negative Highly positive Digital payments and personal finance : Sector expected to gain in the long - term due to higher preference for contactless payments Gross transactions value Expected industry recovery pattern (relative to pre - Growth rate (FY20 - 24) Funding (2018 - 19) (FY20) COVID - 19 level) 25 - 30% ~US$ 2.0B ~US$ 430B Highly positive Others Digital payments Personal finance Neobank Positive (Fundraising, etc.) Pre - COVID Market Highly fragmented Fragmented Oligopoly Fragmented levels structure Time period Negative Players Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Reduced Digital Festive demand increase economic enablement in transactions activity fall for MSMEs Rebound in equity markets COVID - 19 in Recovery in more investments impact transaction transaction Behavioral shift customer volume volume stickiness Industry • Increased • Time availability • Immediate impact • Pandemic needs Stock market No COD outlook preference for i ncreased trial of cushioned due to Increase in # volatility digital contactless apps ongoing projects fundraising payments payments campaigns • Market uncertainty • Realignment of Short - term Product Emerging new use cases • Diversification of and volatility expansion plans funding need innovation Revival of interest in AI / ML offerings lesser investments conserving capital Increased driven by due to signs of normalcy from retail users • Positive change in • Long - term demand cross - selling analytics consumer behavior • Investment in for integrated across Regional technology for finances unaffected businesses expansion scaling up and new product features Degree of COVID impact Sources: NPCI, Statista, PGA Labs analysis © PGA Labs | 28 Highly negative Highly positive Insurtech : Sector affected in the short - term but expected to recover strongly as the crisis accelerates transition to online and mobile sales Expected industry recovery pattern (relative to pre - Gross premium Growth rate Funding (2018 - 19) COVID - 19 level) collected (FY20) (FY20 - 24) ~US$ 0.5B Highly ~US$ 350M 40 - 43% positive Aggregators and Device protection and Digital insurers Positive Distributors maintenance Market Pre - COVID Oligopoly Oligopoly Oligopoly Time structure levels period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Weak macro - Fear of Long - term High demand COVID - 19 economic infection behavioral tax - saving impact condition high digital shift higher related f all in sales adoption for digital adoption purchases • Increase in traffic due to • New products introduced • Focus on customer Industry Reduced essential preference for contactless, related to COVID 19 acquisition l aunch of outlook consumer products digital sales remote troubleshooting service • Sales conversion lower in spending • Tie - ups and partnerships for new businesses, life insurance • Maintain supplier base increasing the # offerings financial assistance to partners • Lower CAC for non - life / during lockdown • Difficulty in closing high health better conversions & Offline entities Ease in Building ticket value policies focus margins • Lower revenue from new going digital premium awareness on marketing, awareness customers due to low • Increase in marketing spend Diverse payments around health smartphone sale • Tele - underwriting preferred drive awareness around life offerings Marketing and life over medical check - ups and health products Tele - campaigns to products • Tie ups and partnerships underwriting drive with other fintech firms and adopted awareness banks Degree of COVID impact Sources: ICRA, IRDA, PGA Labs analysis © PGA Labs | 29 Highly negative Highly positive Agritech : Sector will recover quickly and grow by capitalizing on opportunities arising from changes in traditional agricultural supply chain Expected industry recovery pattern (relative to pre - Market potential (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) > US$ 0.3B > US$ 4B 20 - 25% Highly positive Market Farm data Farming as a Finance and Crop inputs linkages and analytics service Insurance Positive Market Highly Highly Highly Highly Highly Pre - COVID structure fragmented fragmented fragmented fragmented fragmented levels Time period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Drop in B2B Demand for Harvest Preparation COVID - 19 sales offset kharif crop season for rabi crops impact by direct to inputs demand for demand consumer Lower rabi labor and for inputs • Direct delivery • Increased • Nascent stage • Challenge in • Lower crop sales delivery Industry to kiranas , demand for last mobilizing sales + supply • Focus on demand for outlook consumers mile delivery as equipment shifts supply chain credit limited drop in rural retail shut missed harvest increase low demand order volumes season demand for • Investment in for analytics in Delay in crop harvests Average rainfall normal credit • Focus on capacity near term crop losses kharif harvest customer • Difficulty in Migration of worker labor Traditional supply chain • Direct • Emphasis on acquisition assessment shortages restored partnerships crop disbursal S upply chain shift Geographical expansion + • Greater investor with input monitoring challenges Direct tie - ups with input deeper partnerships interest manufacturers higher adoption manufacturers and end by govt consumers Degree of COVID impact Source: PGA Labs analysis © PGA Labs | 30 Highly negative Highly positive Ecommerce : Sector affected by ban on sale of non - essentials but expected to recover strongly as more consumers adopt online channel Expected industry recovery pattern (relative to pre - Market size (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) ~ US$ 56B 17 - 20% > US$ 1.5B Highly positive Social Ecommerce Horizontal Vertical Positive and O2O Market Pre - COVID Oligopoly Oligopoly Oligopoly Time structure levels period Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Demand surge Demand Fear of infection d emand for Operating at stabilizes essentials continues rising COVID - 19 ~50% capacity Faster delivery Increase in warehousing storage impact h iring of i ncrease in demand • Non - essentials sale banned • Operations suspended • Heavy layoffs to sustain Industry labor small Transition to unmanned operations drop in revenue during lockdown drop in fall in # orders Inter - state warehouses automation & digitization outlook revenue borders closed Rise in • Greater adoption in grocery • Supply chain issues competition and essentials renewed • Expansion of product backlog for deliveries focus and investment on categories focus on • Increased sign ups from Lockdown Partial recovery Festive sales to boost demand hyperlocal essentials like PPE sellers in tier 2 & 3 cities supply of demand Fear of infection consumer base • Supply issues in electronics • Monetize existing customer suspended Low imports increase • Diversification, focus on and apparel focus on niche base a lternate revenue Shut down of supply Lower imports supply changes essentials selling groceries products like beauty, personal streams like advertising, lead production and changes continue care generation etc. imports continue inventory Efforts to clear • Labor and logistics issues • Reduce cash burn shortage existing partnership with 3P logistics reduction in personnel, inventory provider marketing spends Degree of COVID impact Sources: Euromonitor, PGA Labs analysis © PGA Labs | 31 Highly negative Highly positive Internet first brands : Sector expected to recover post ease in lockdown, witness growth as more people shop online Expected industry recovery pattern (relative to pre - Clothing & Food & Home & COVID - 19 level) Personal care Electronics accessories Beverages Furnishings Highly positive Market Highly Highly Highly Highly Oligopoly structure fragmented fragmented fragmented fragmented Positive Players Pre - COVID levels Time period Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Only essentials allowed Festive season demand COVID - 19 electronics, apparel and home normalcy in sales impact furnishing sales drop Change in behavior consumer base increase Partial recovery through pent • Non - essential sale reduced introduction of non - commerce, tech - enabled offerings e.g. up demand Industry advisory outlook • Operations suspended focus on website / app development and innovation such as AR / VR • Focus on reducing OPEX job and salary cuts , reduced marketing spend Production / Freight Lower imports supply imports slow prices rise shifts continue • Limited ability to raise funds larger players with cash in better positions + expansion plans down higher raw Domestic sourcing to bolster postponed inventory material costs supply • Strategic tie - ups with logistics players for supply chain support shortage Offers / • Reduced imports shift to local manufacturing / sourcing Delivery discounts to • More consumer brands moving online increased competition challenges clear inventory Degree of COVID impact Sources: Euromonitor, PGA Labs analysis © PGA Labs | 32 Highly negative Highly positive Foodtech : Sector to witness shift in focus to driving profitable unit economics; dark kitchens to lead recovery Expected industry recovery pattern (relative to pre - Market size (FY20) Growth rate (FY20 - 24) Funding (2018 - 19) COVID - 19 level) > US$ 5B 25 - 30% ~US$ 2.3B Highly positive Aggregators Dark kitchens Loyalty services Positive Time period Market Duopoly Fragmented Oligopoly Pre - COVID structure levels Players Negative Highly negative AMJ 20 JAS 20 OND 20 JFM 21 Lack of trust Release of Change in behaviour COVID - 19 in food some pent - preference of online impact handling up demand ordering Preference Lower • Change of focus from scale • Flexible menu • Zero footfall in restaurants Industry for propensity to profitability ingredients availability negligible demand for outlook processed spend services • OPEX realignment • Focus on hygiene food withdrawal from dark regenerate customer trust • Expansion of offerings Lack of riders Contactless Supply chain issues overcome kitchens, job cuts, etc. • Margins reduced higher • Strengthening relationship Supply chain dining Increased availability of • Diversification in product ingredient, marketing cost with restaurants disrupted adopted riders categories leverage • Constraint on availability Expansion Higher network for essentials, of labor into delivery concerns for personal care delivery • Consolidation smaller of essentials safety and • Supply chain challenges players to shut down or be hygiene fear & labor migration acquired Degree of COVID impact Sources: PGA Labs analysis © PGA Labs | 33 Highly negative Highly positive