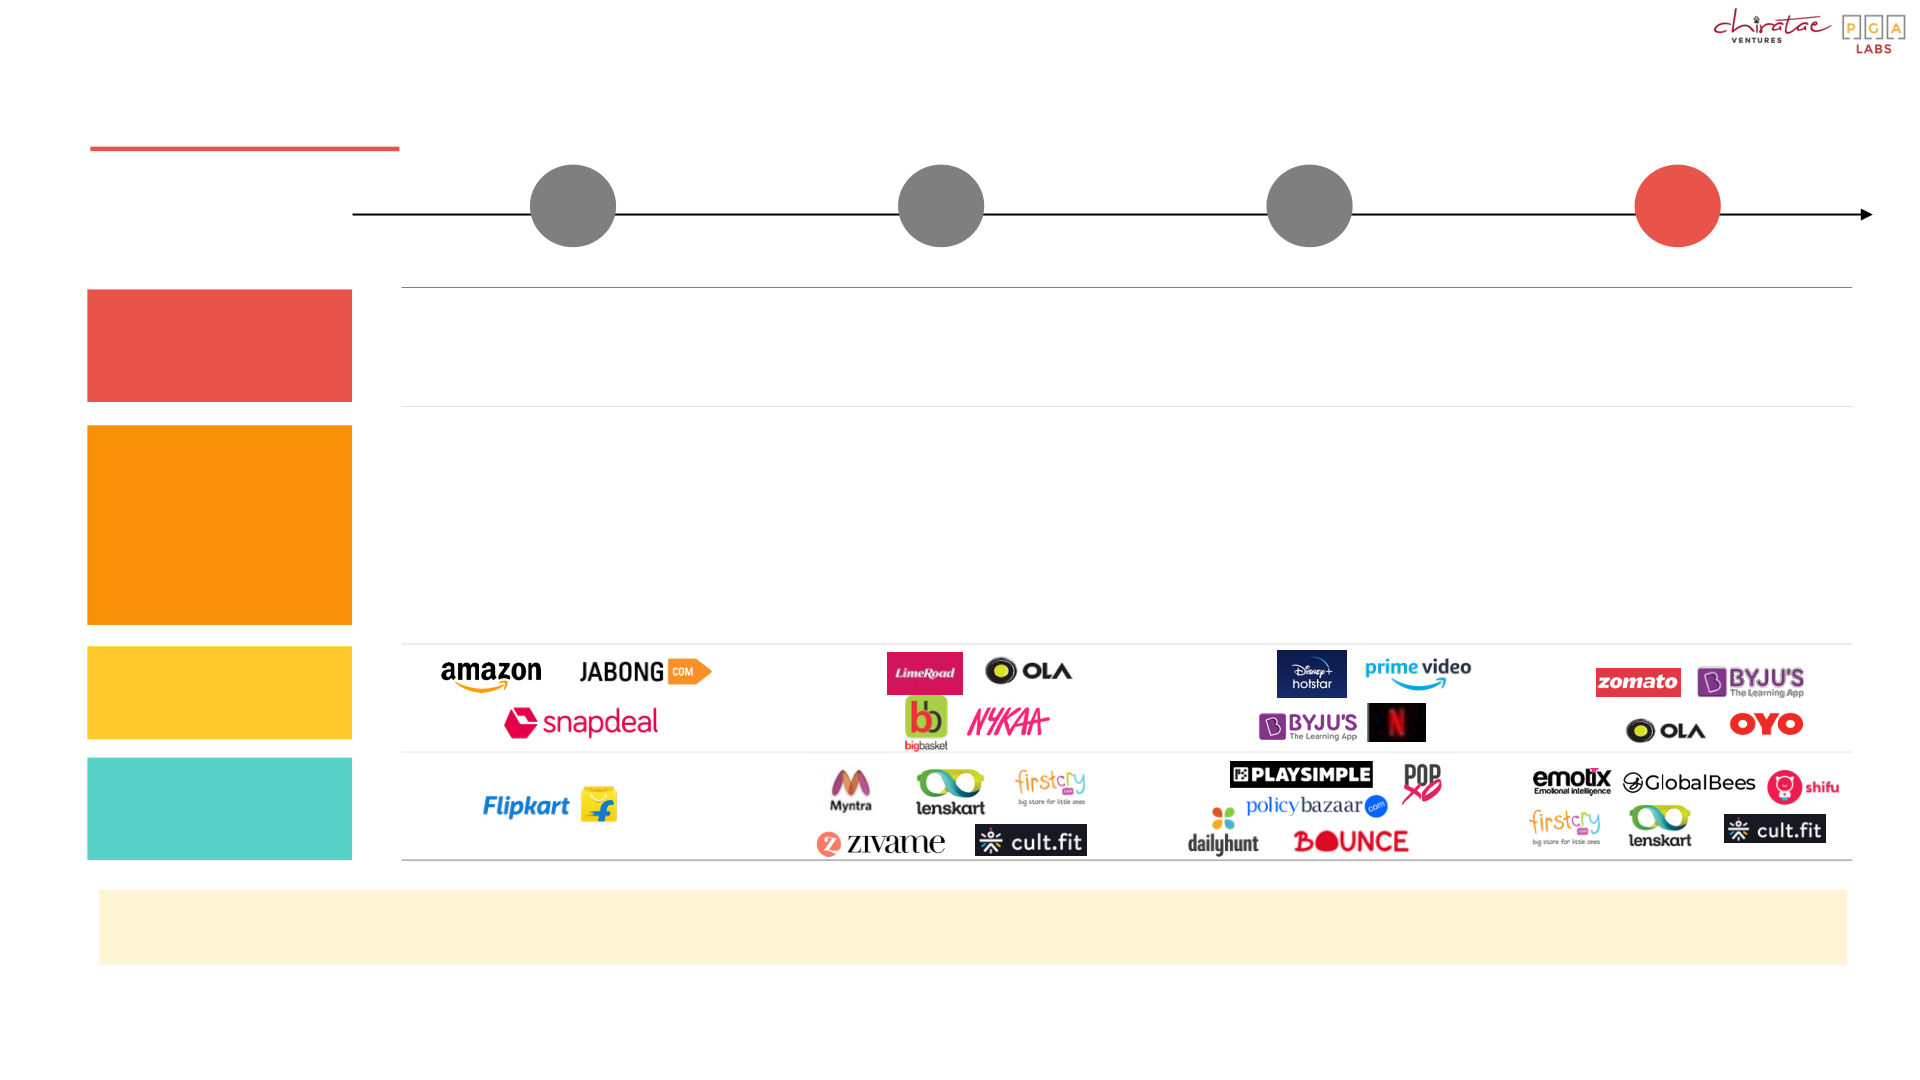
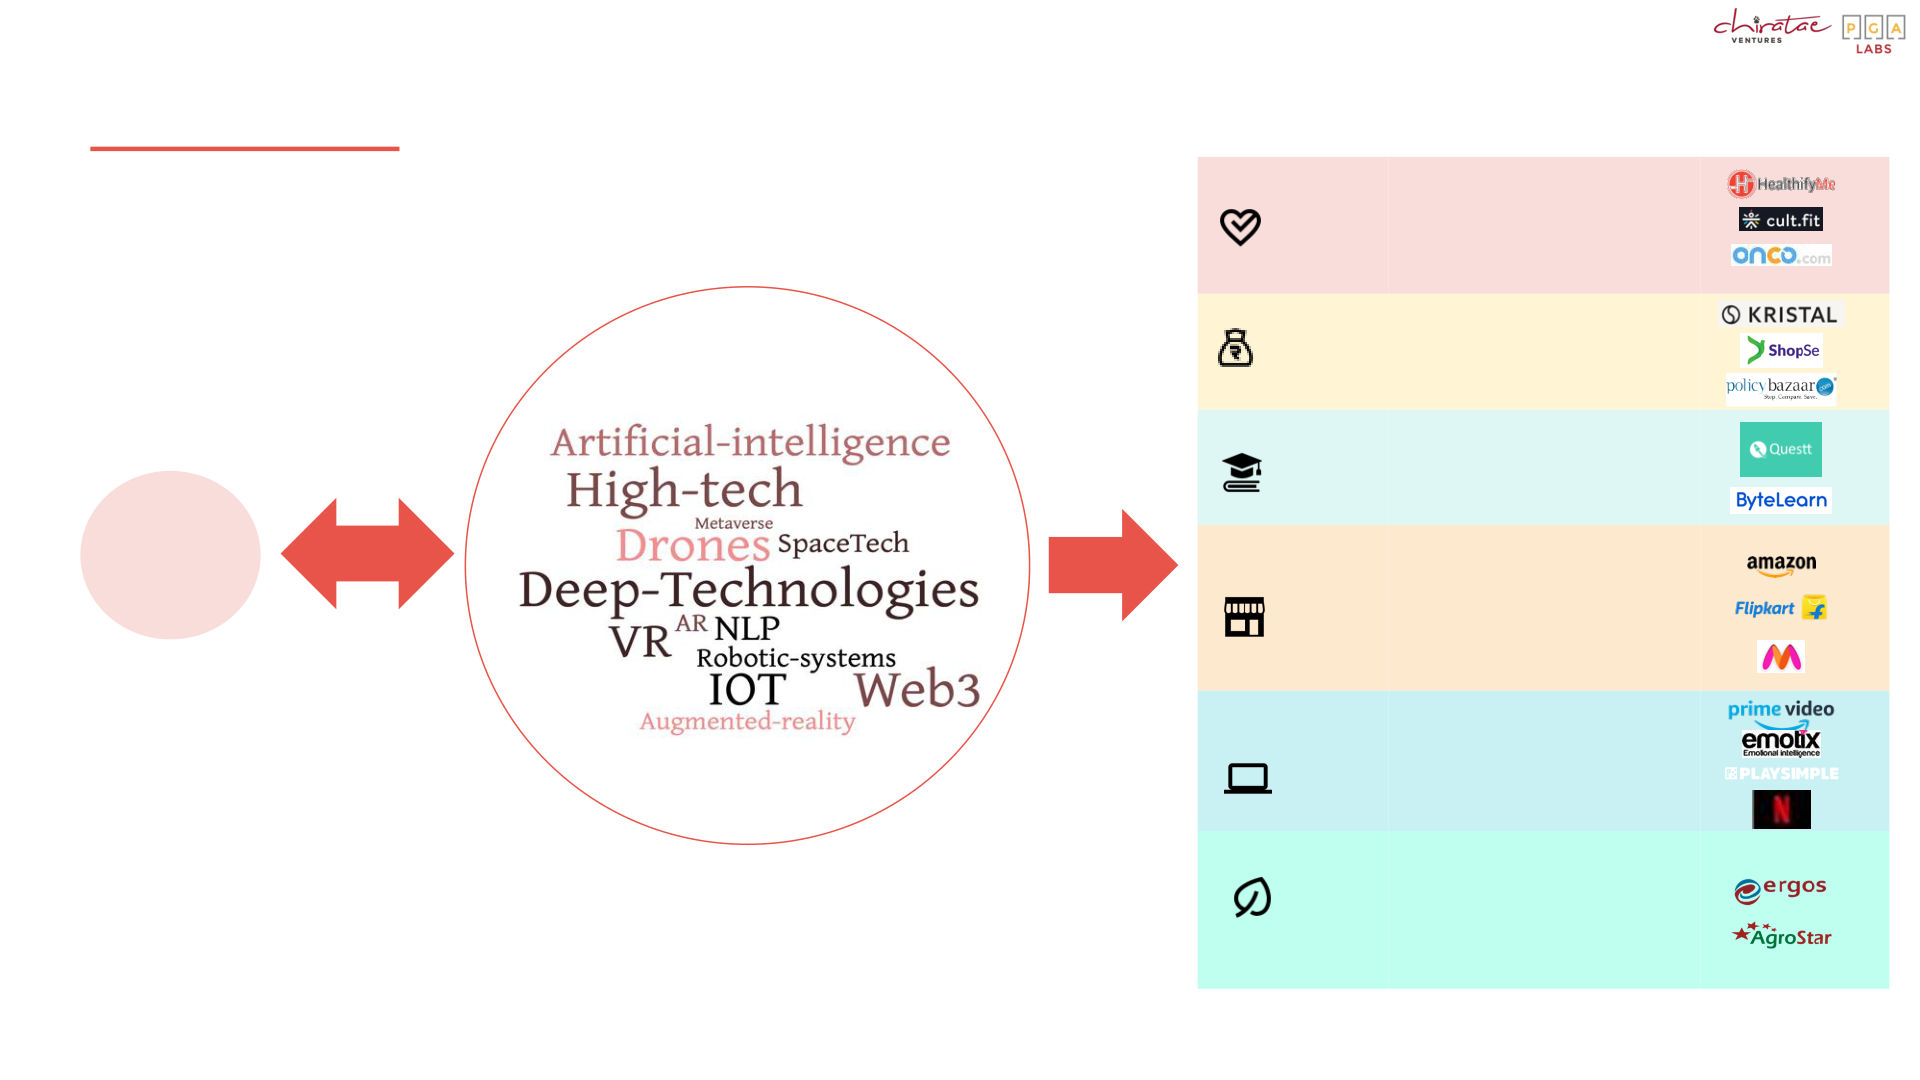
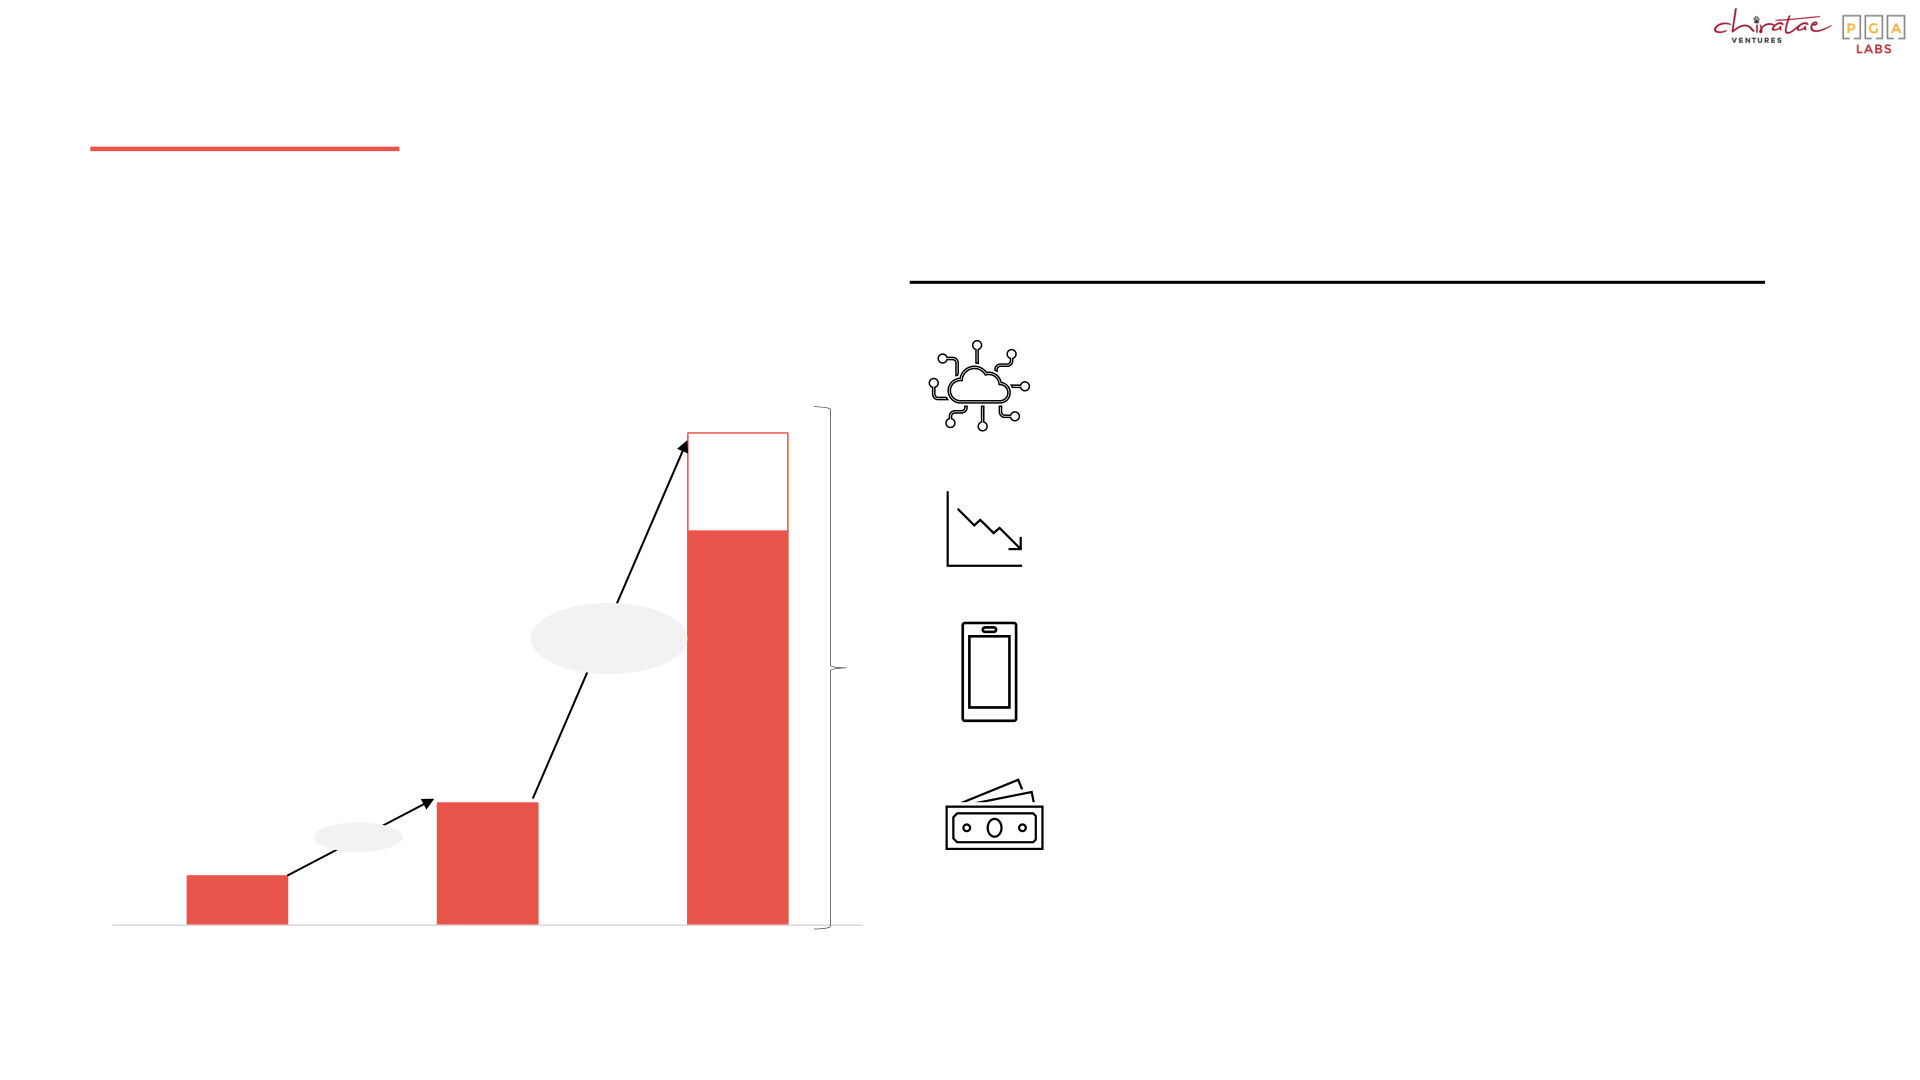
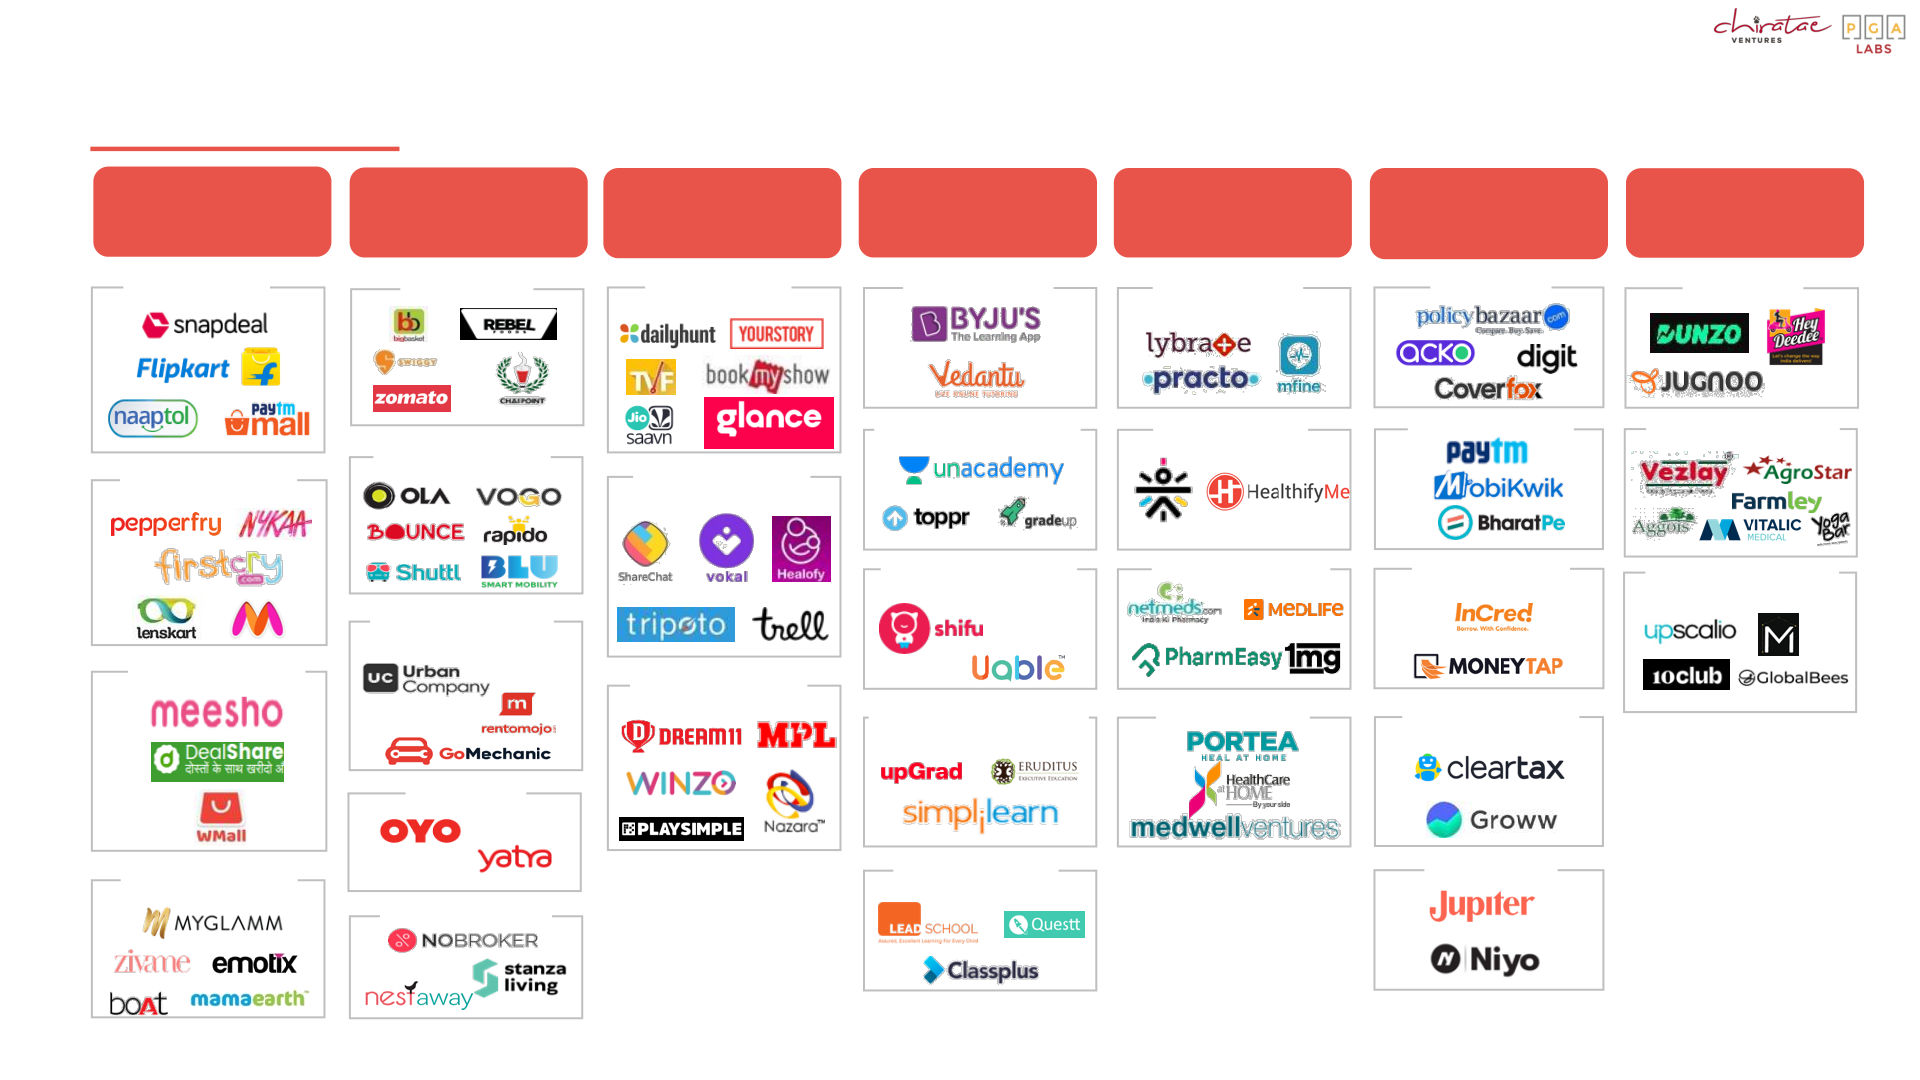
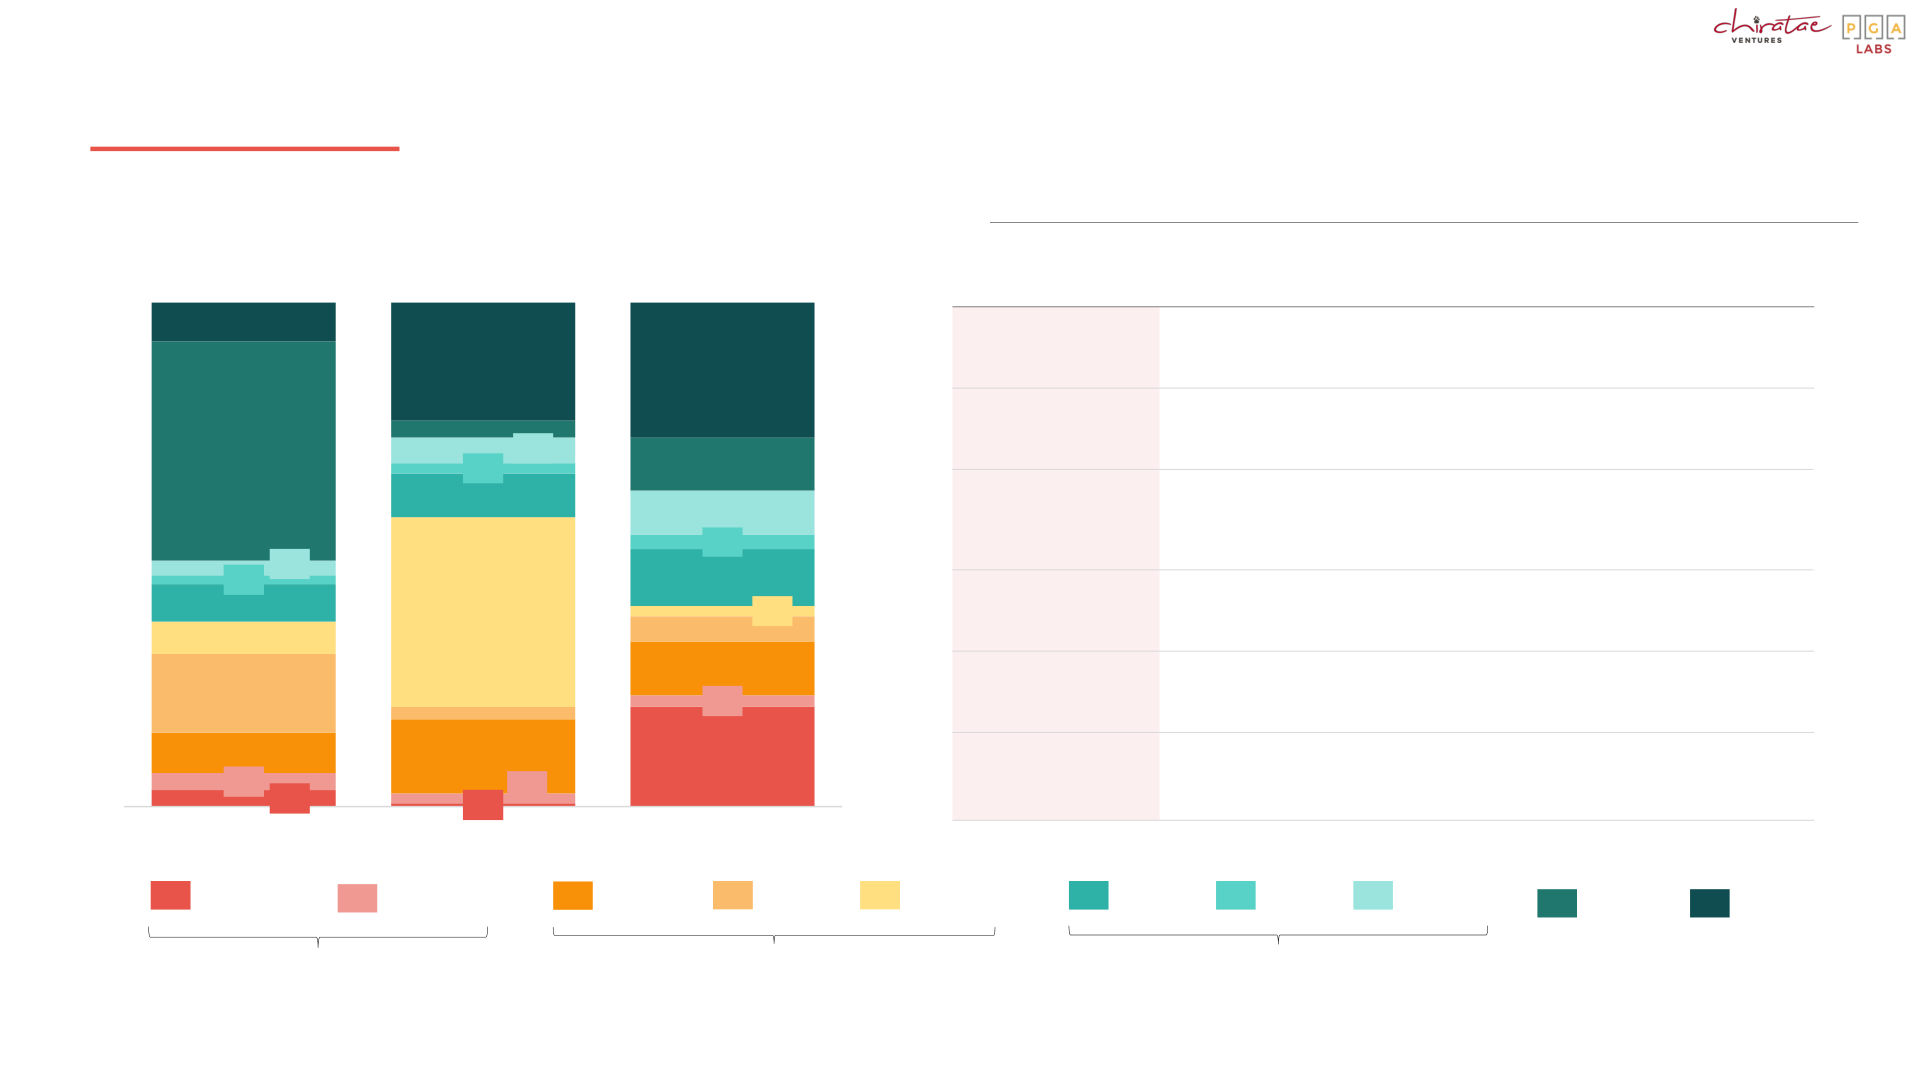
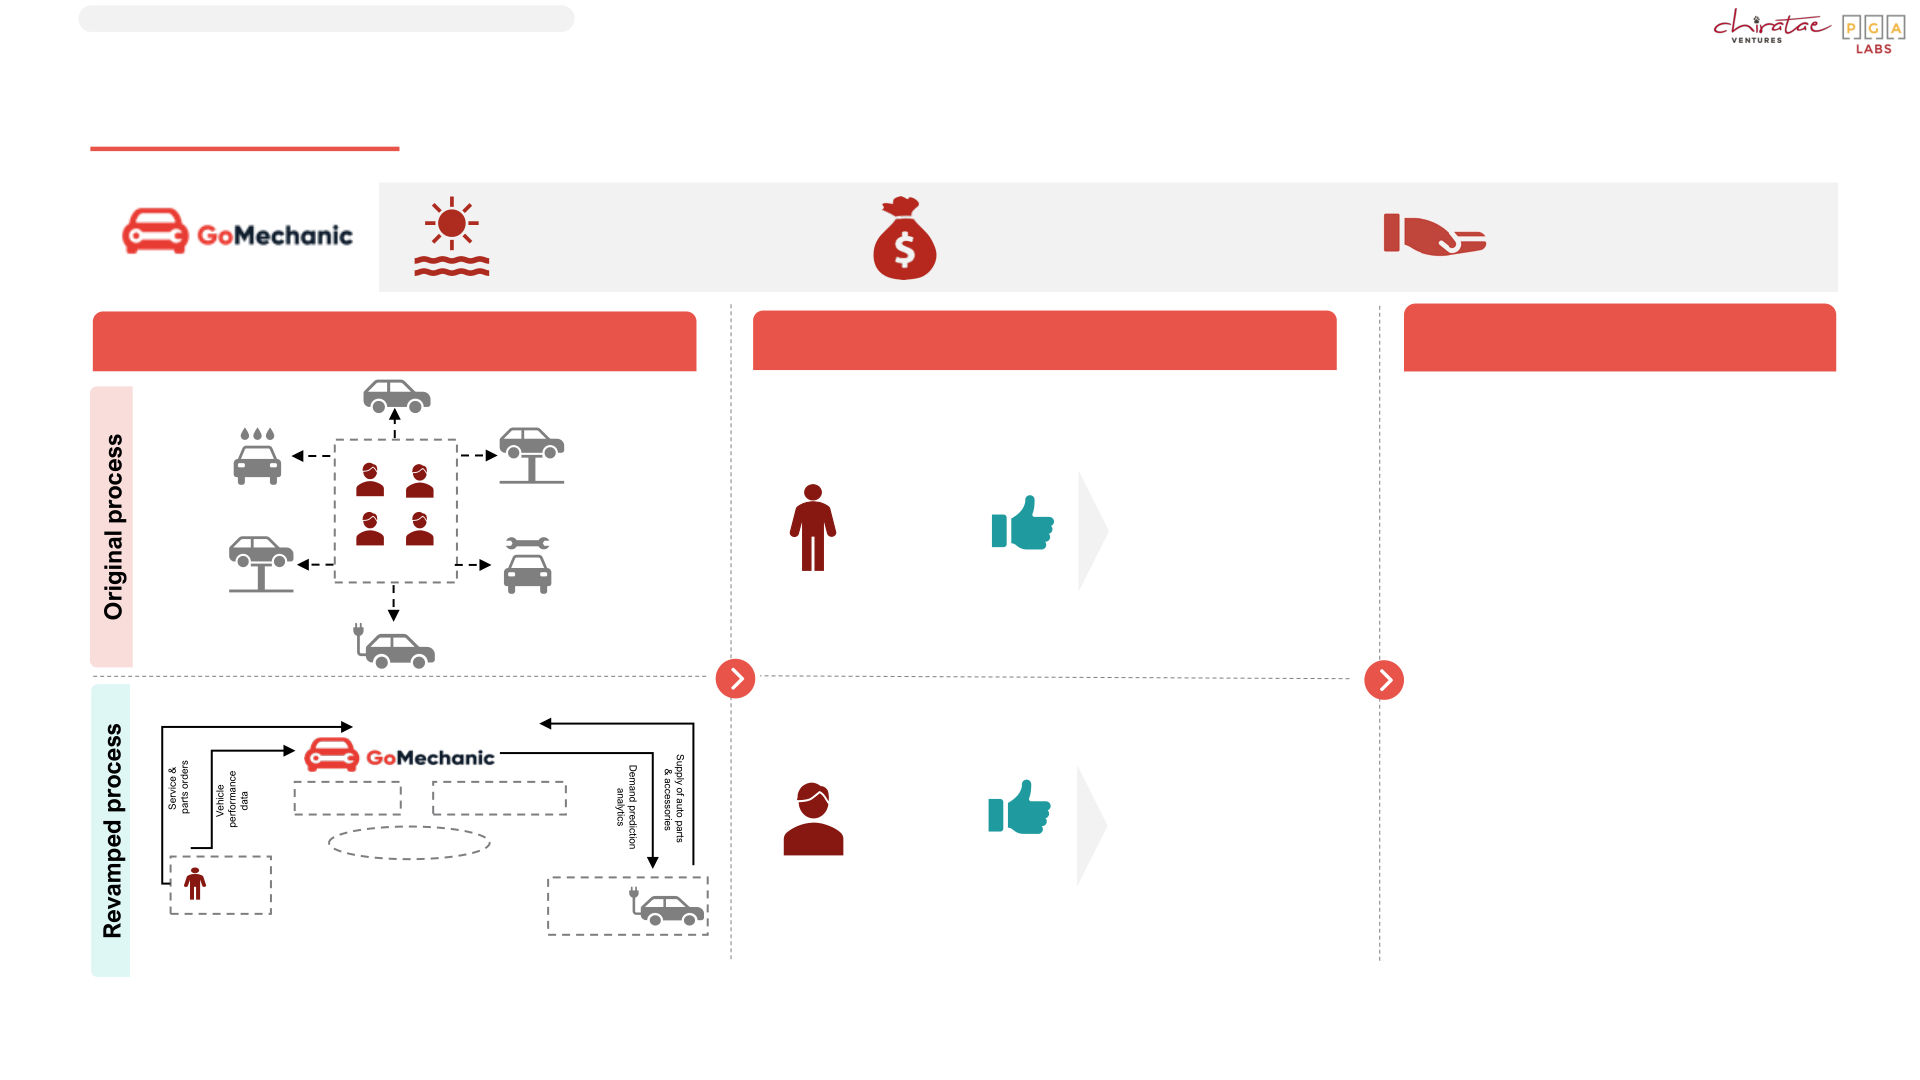
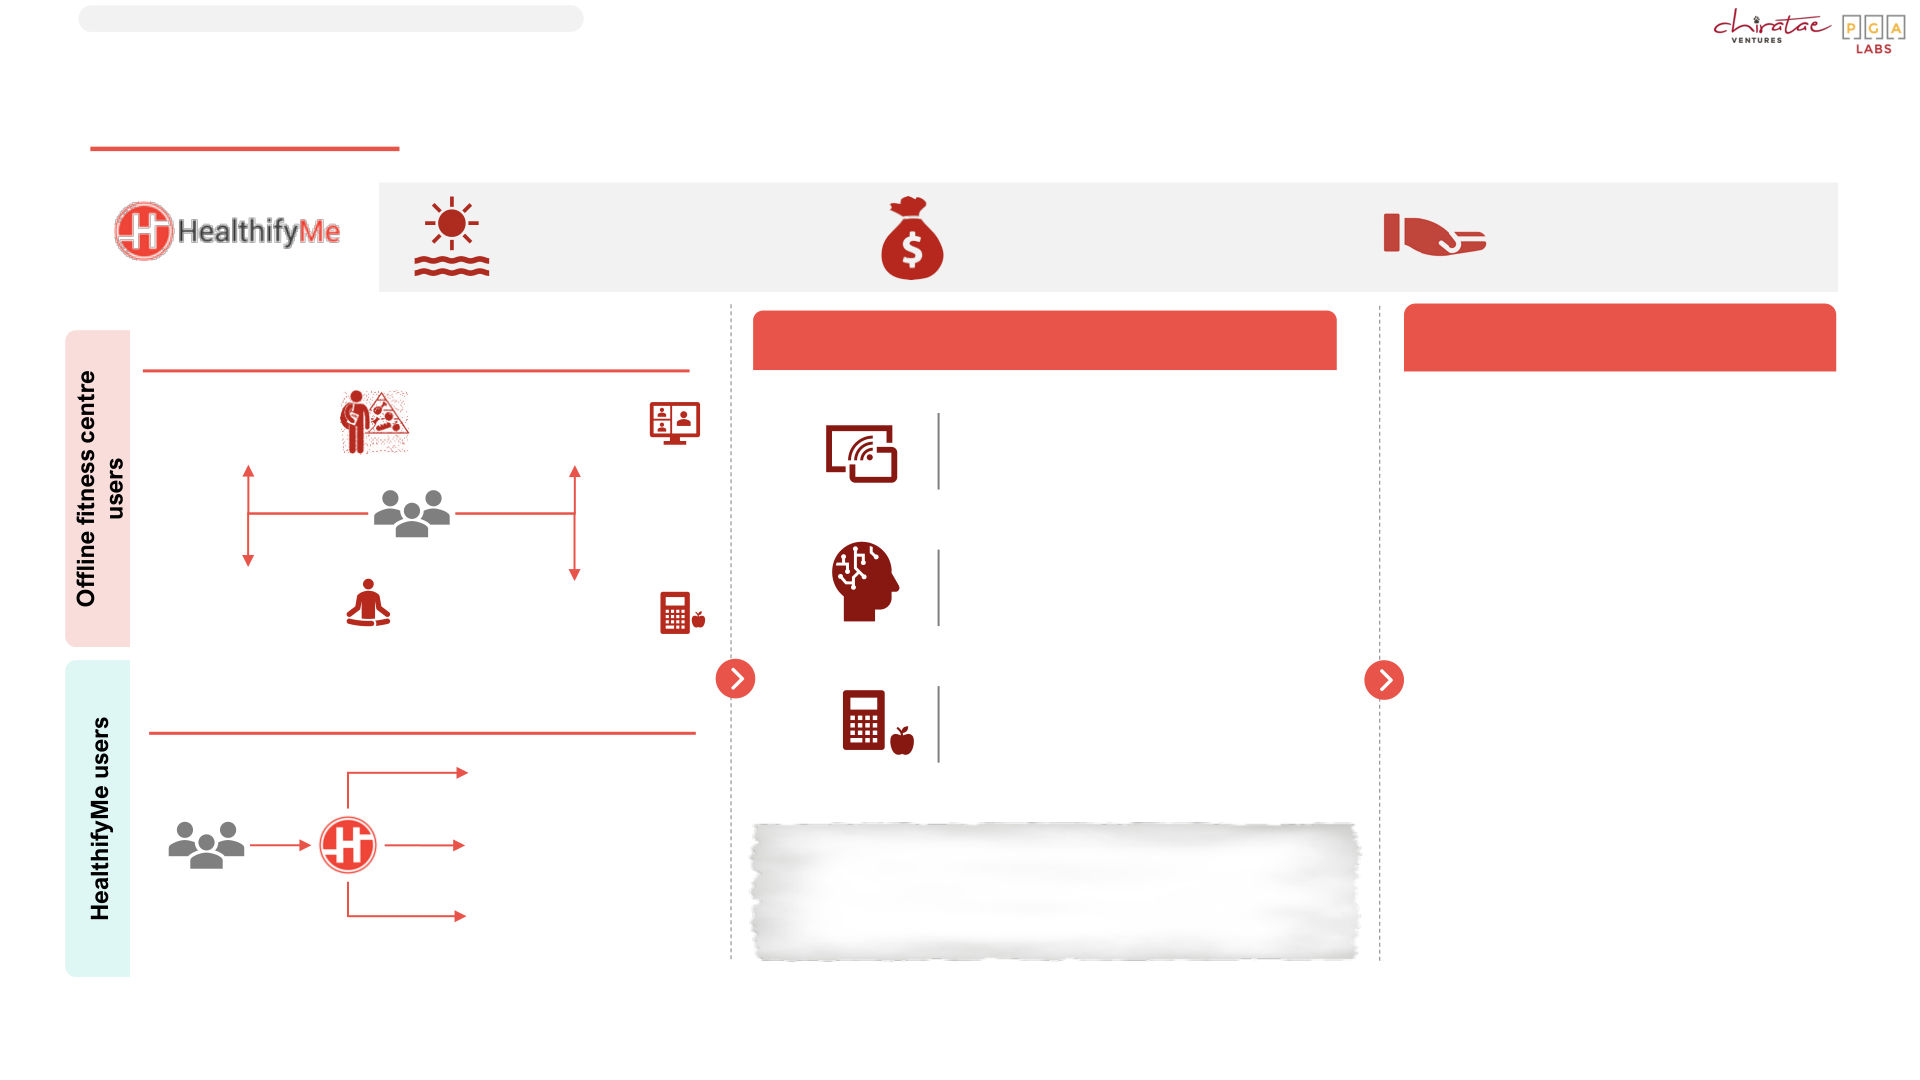
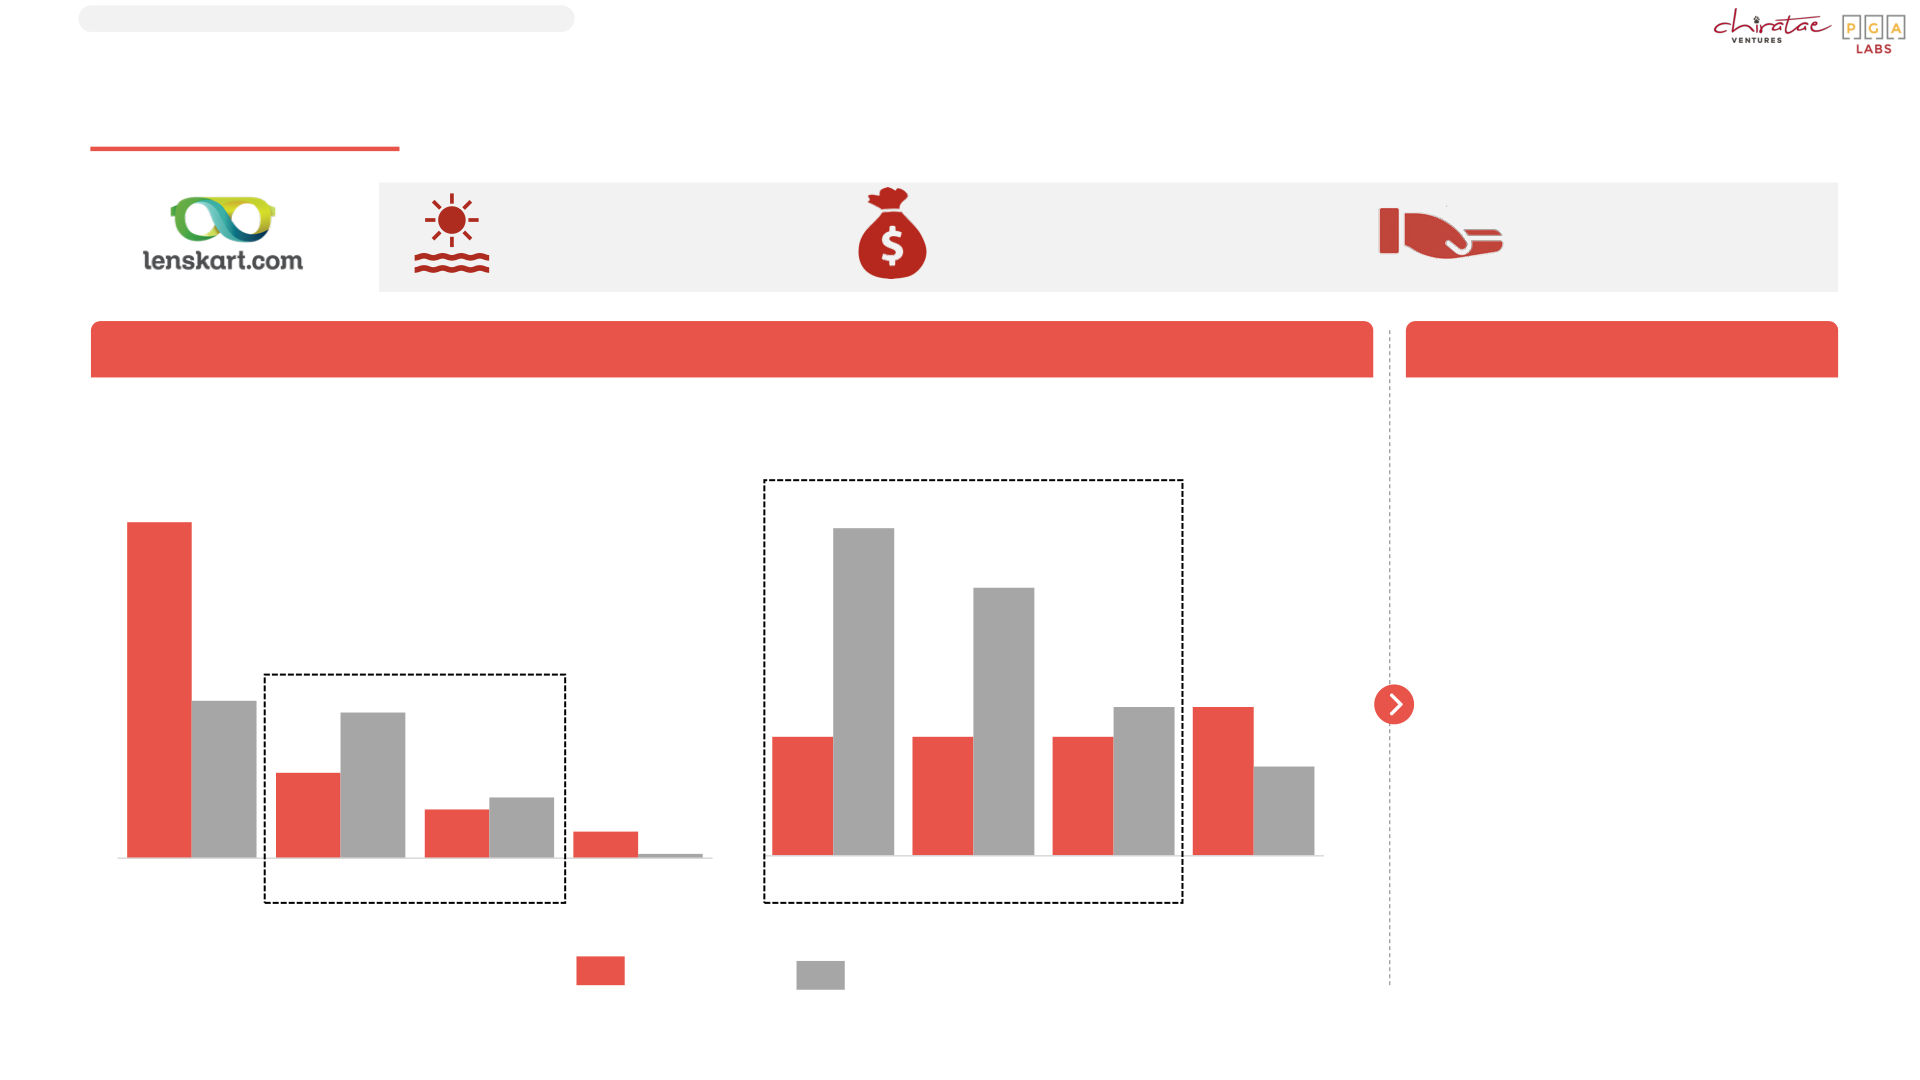
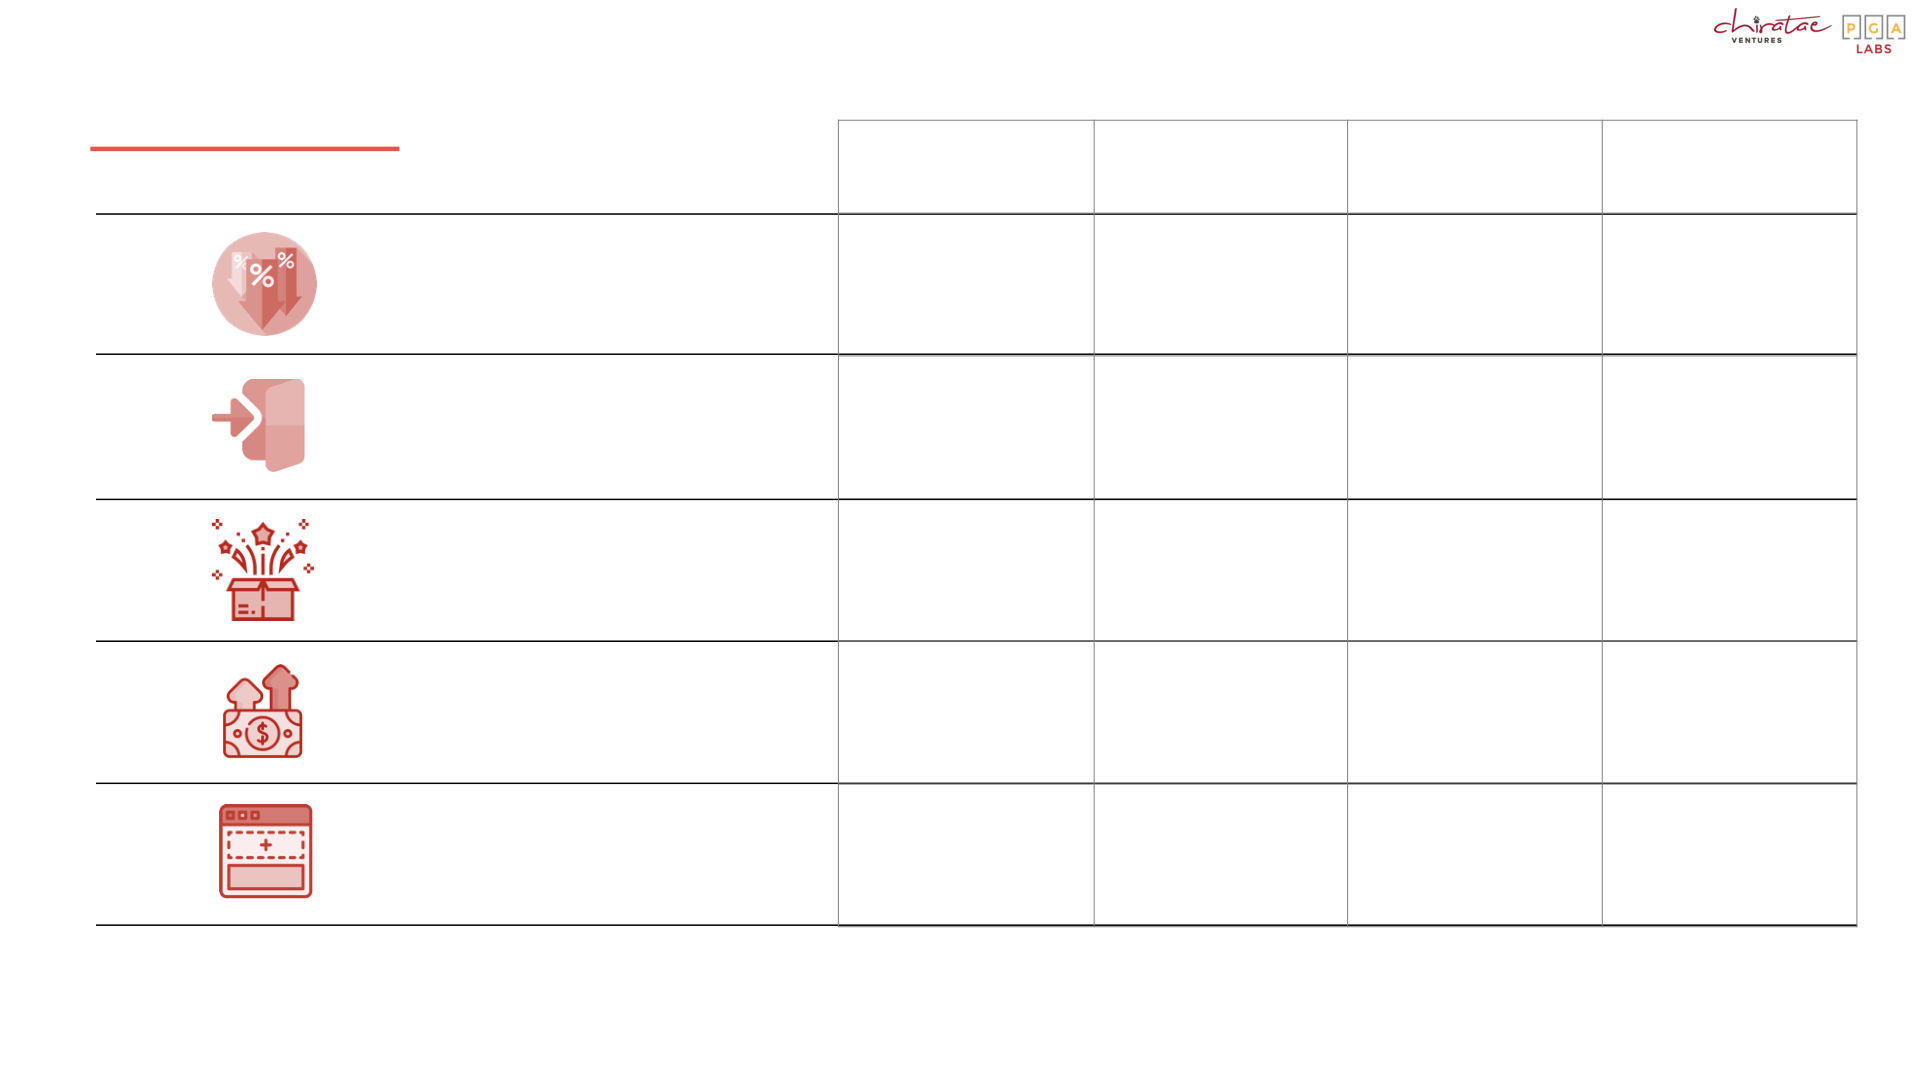
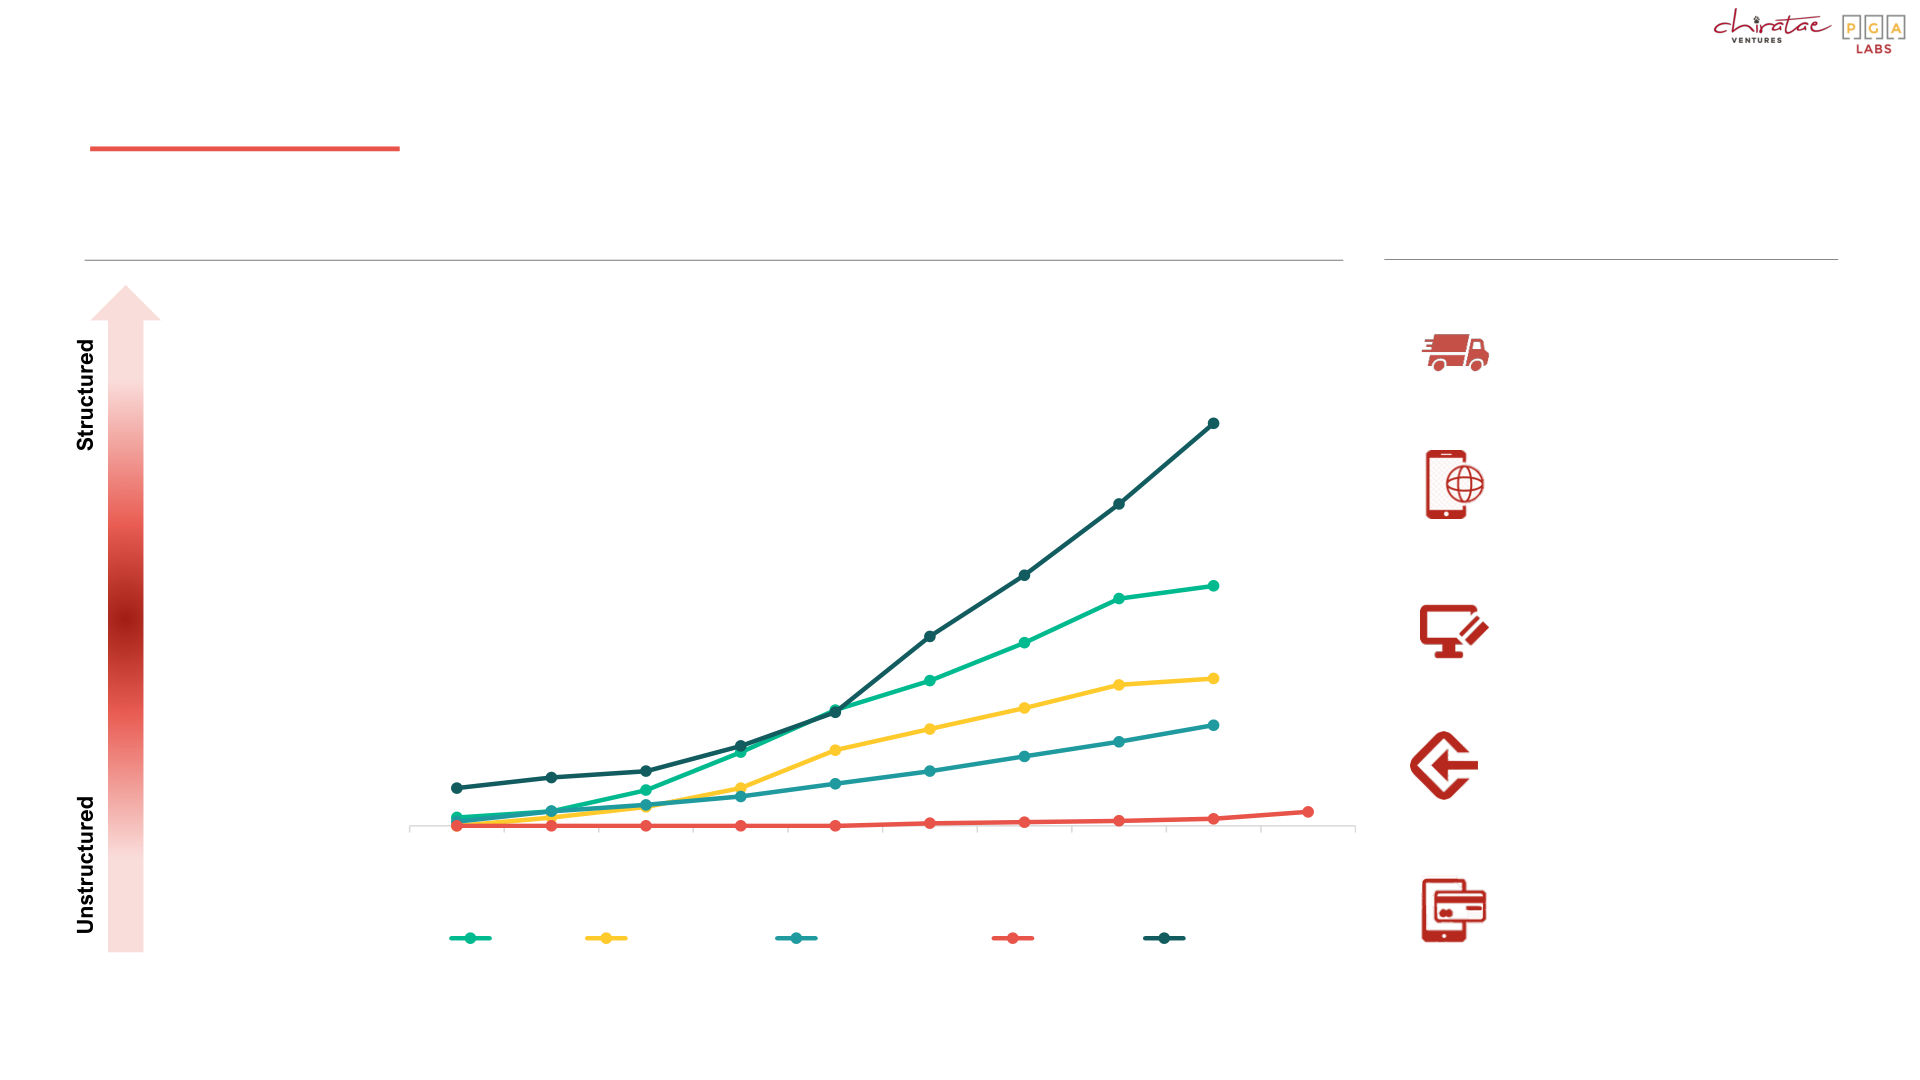
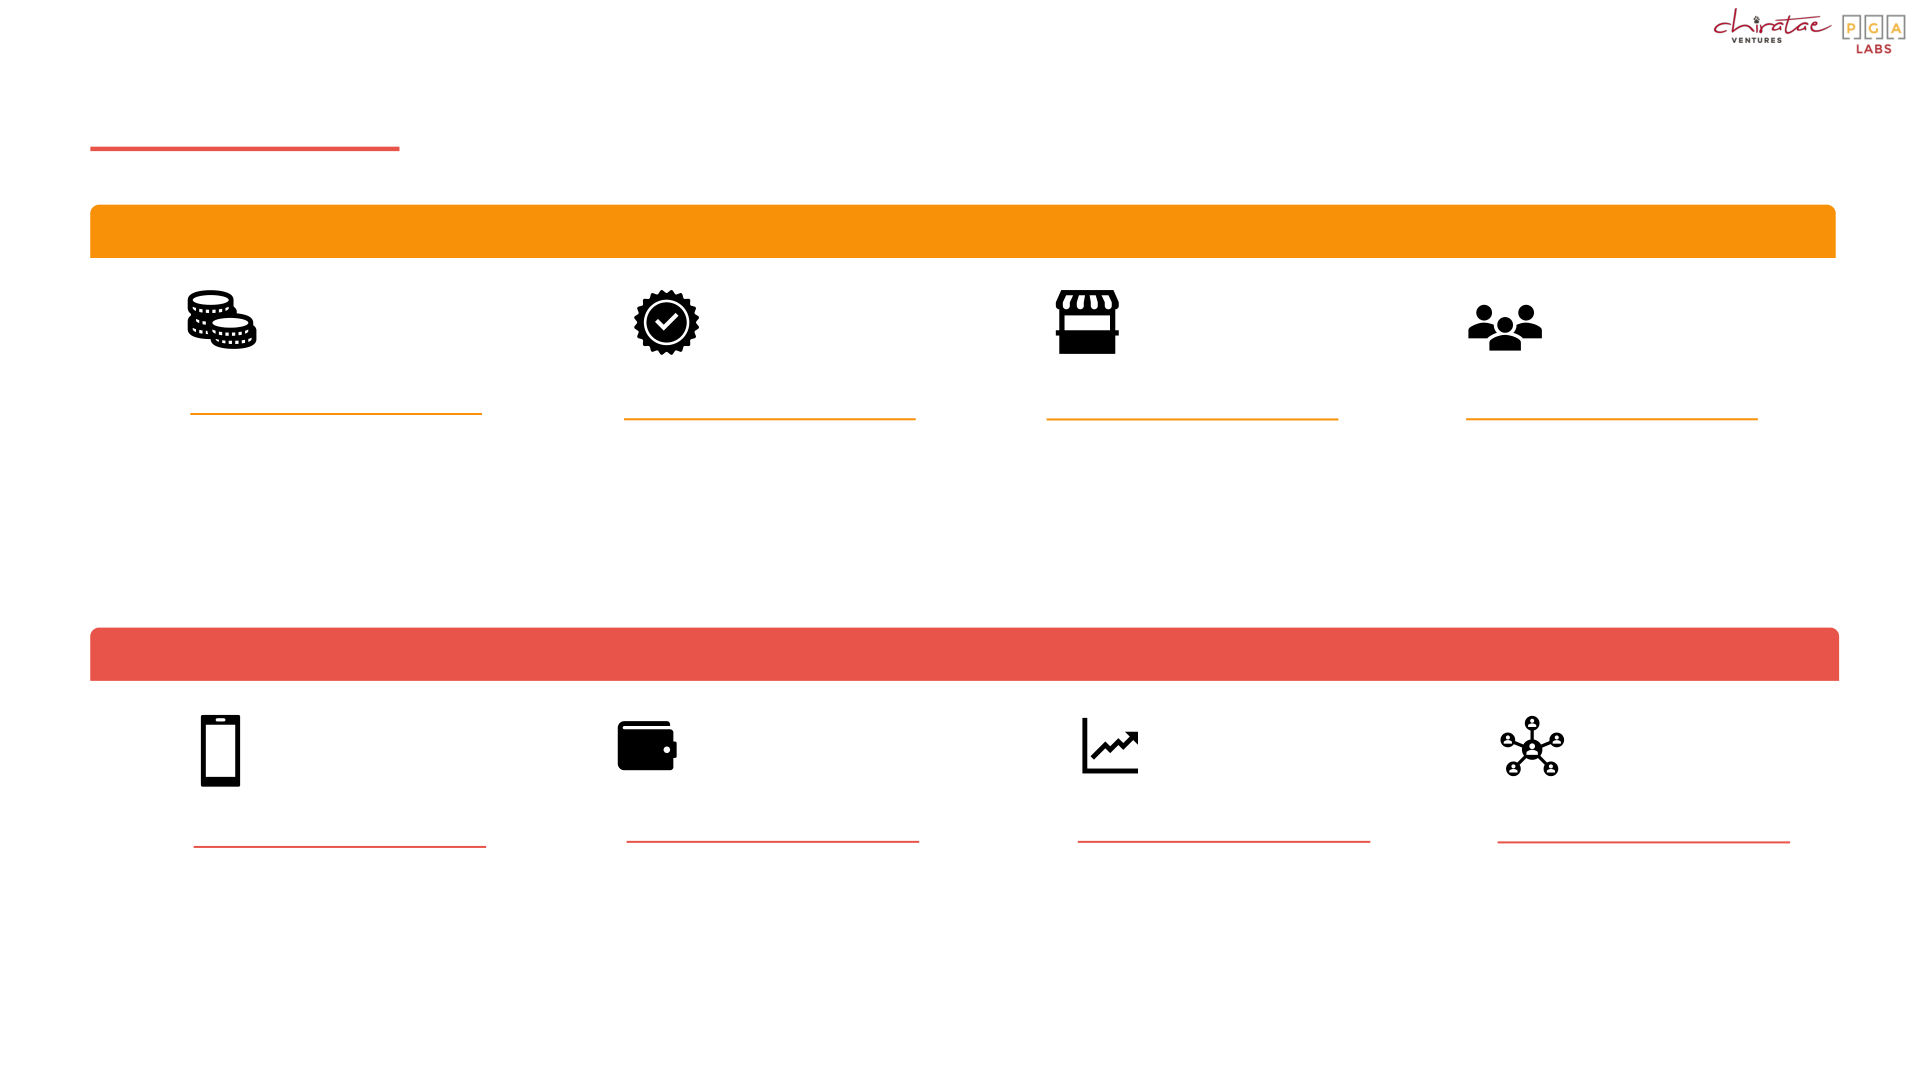
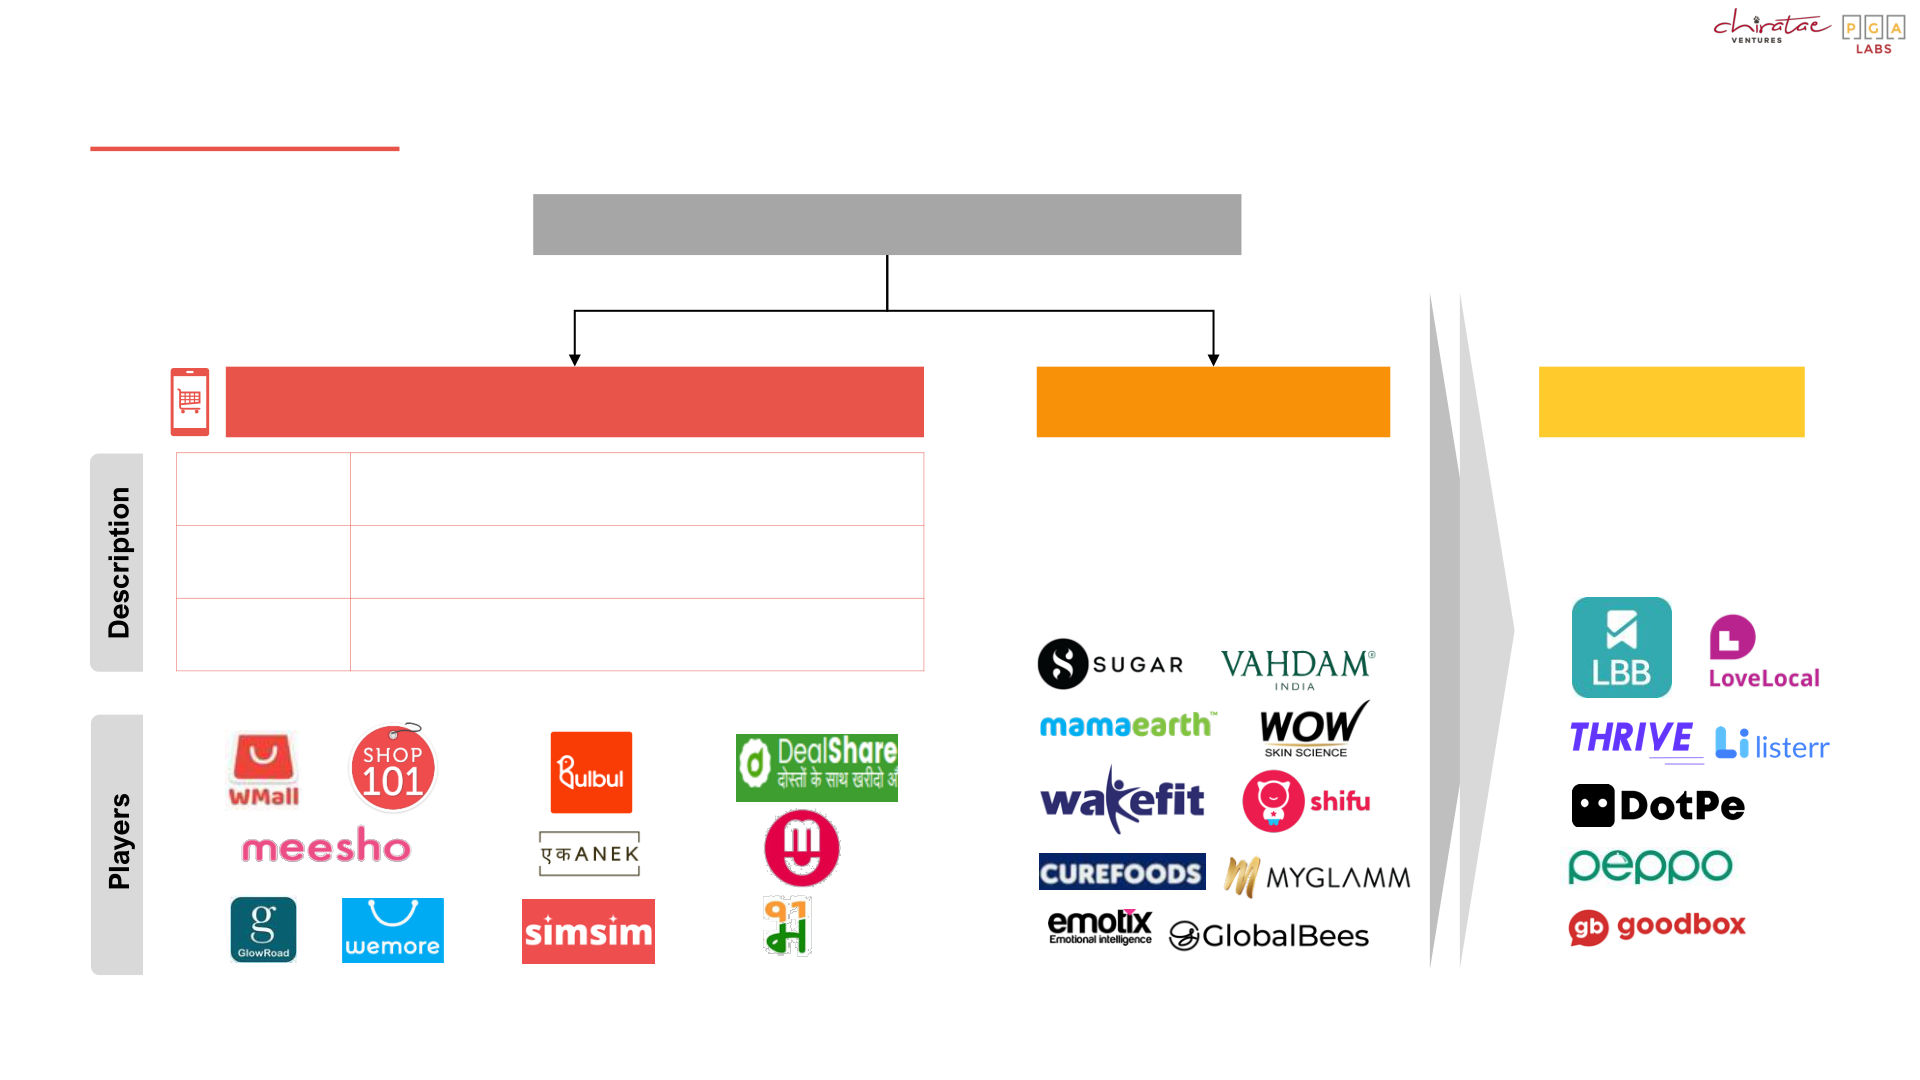
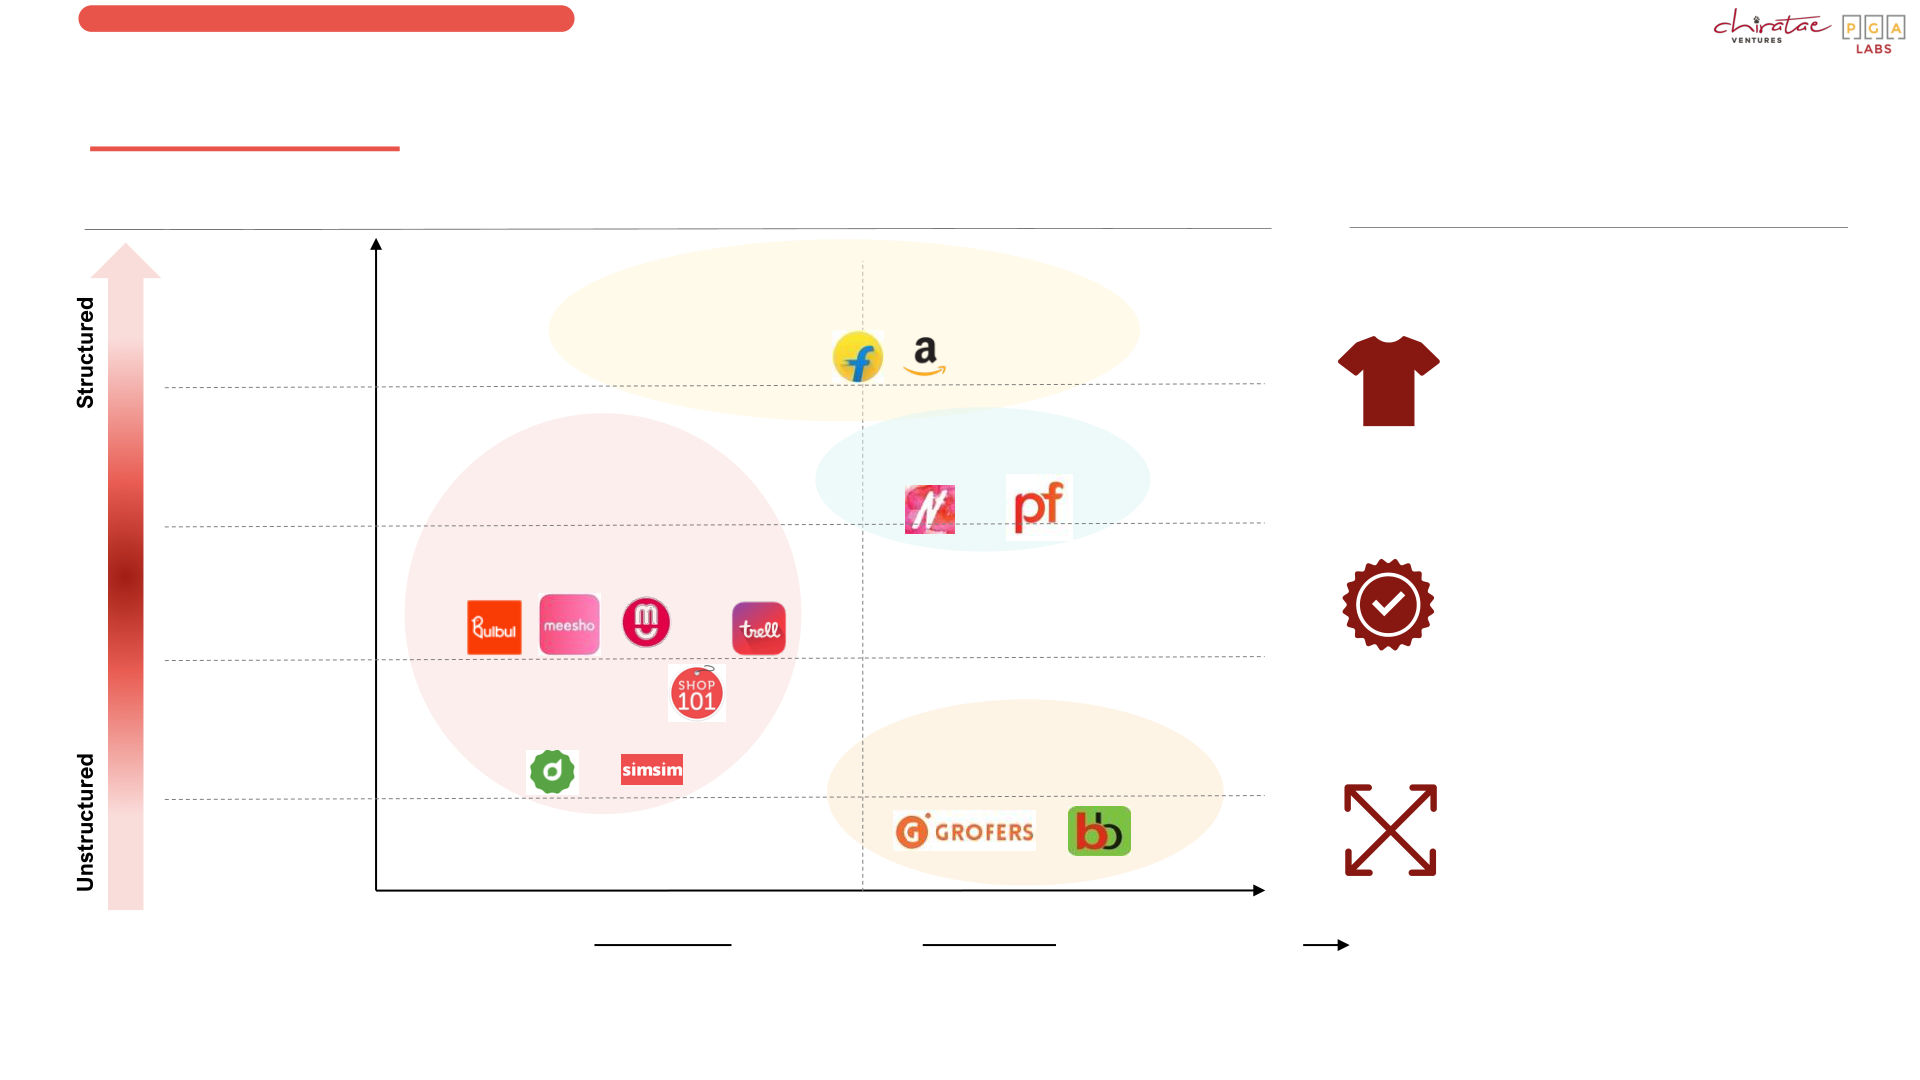
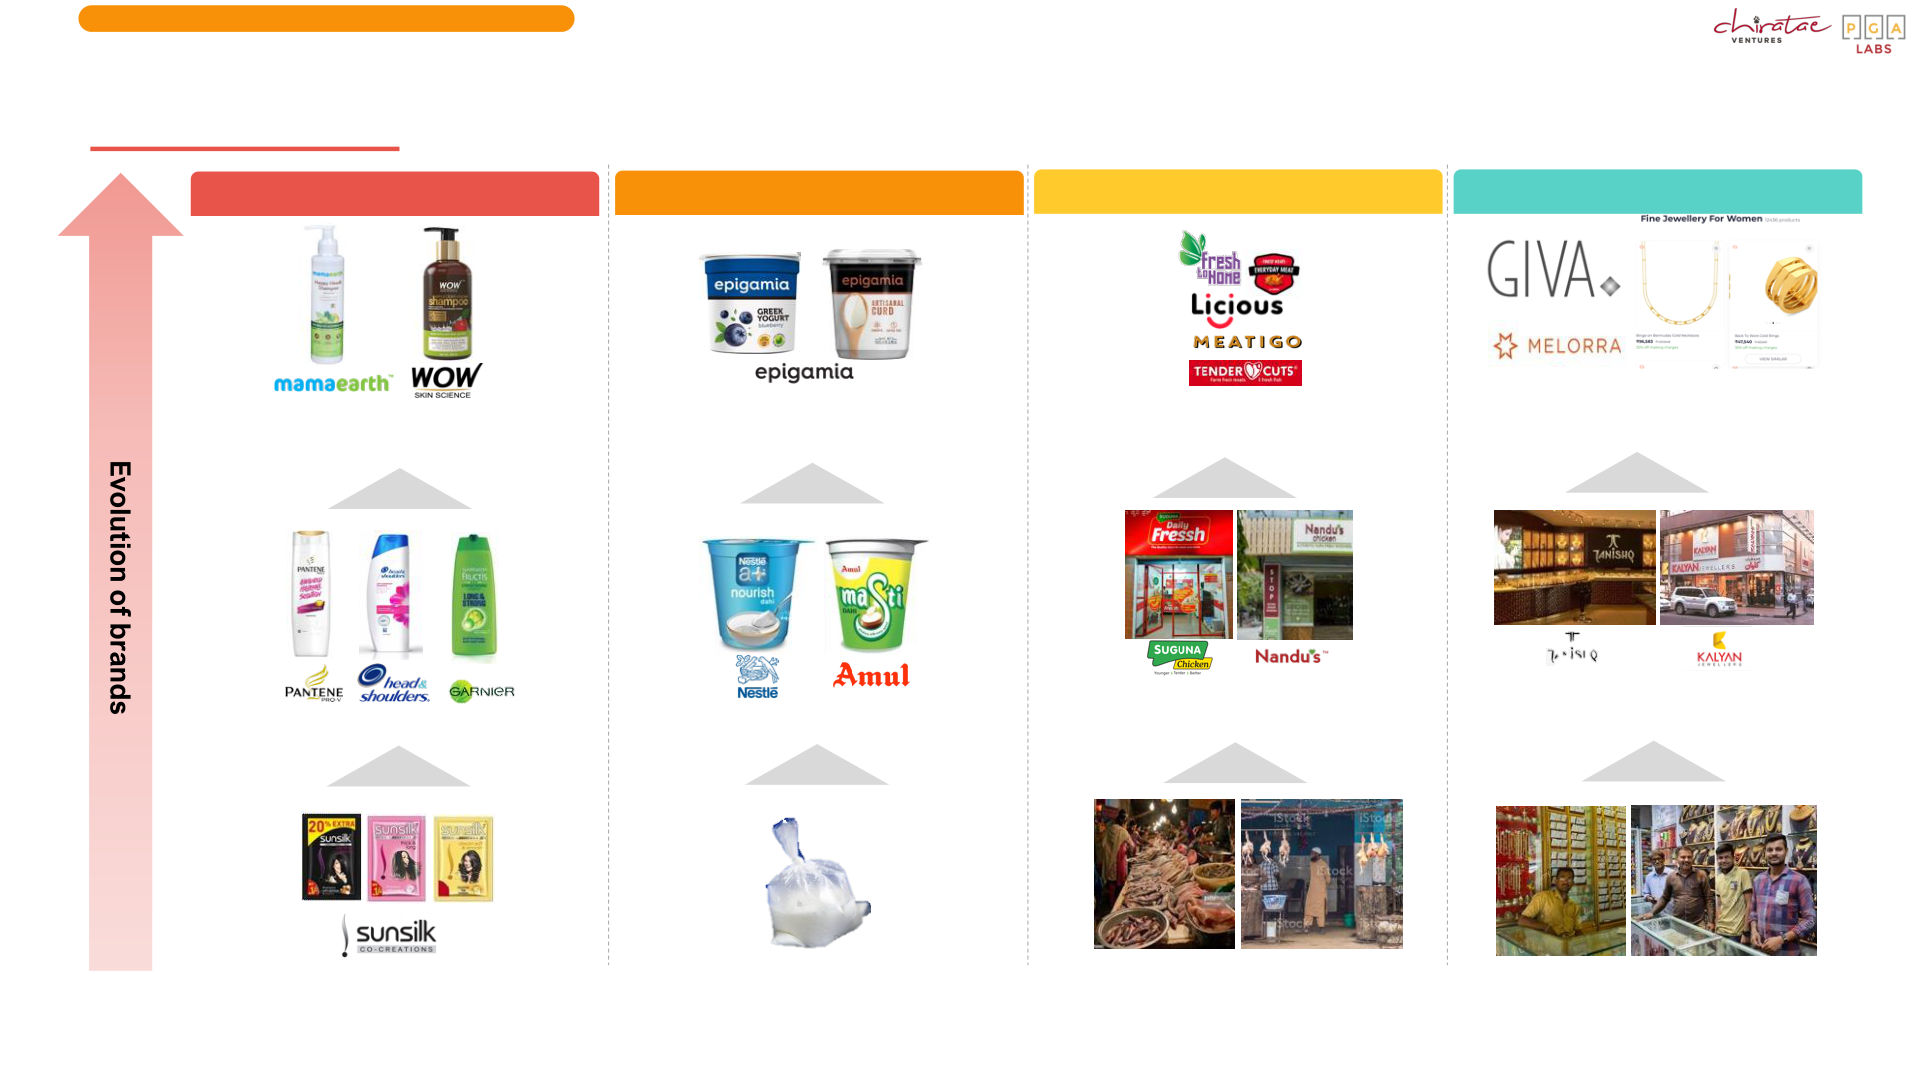
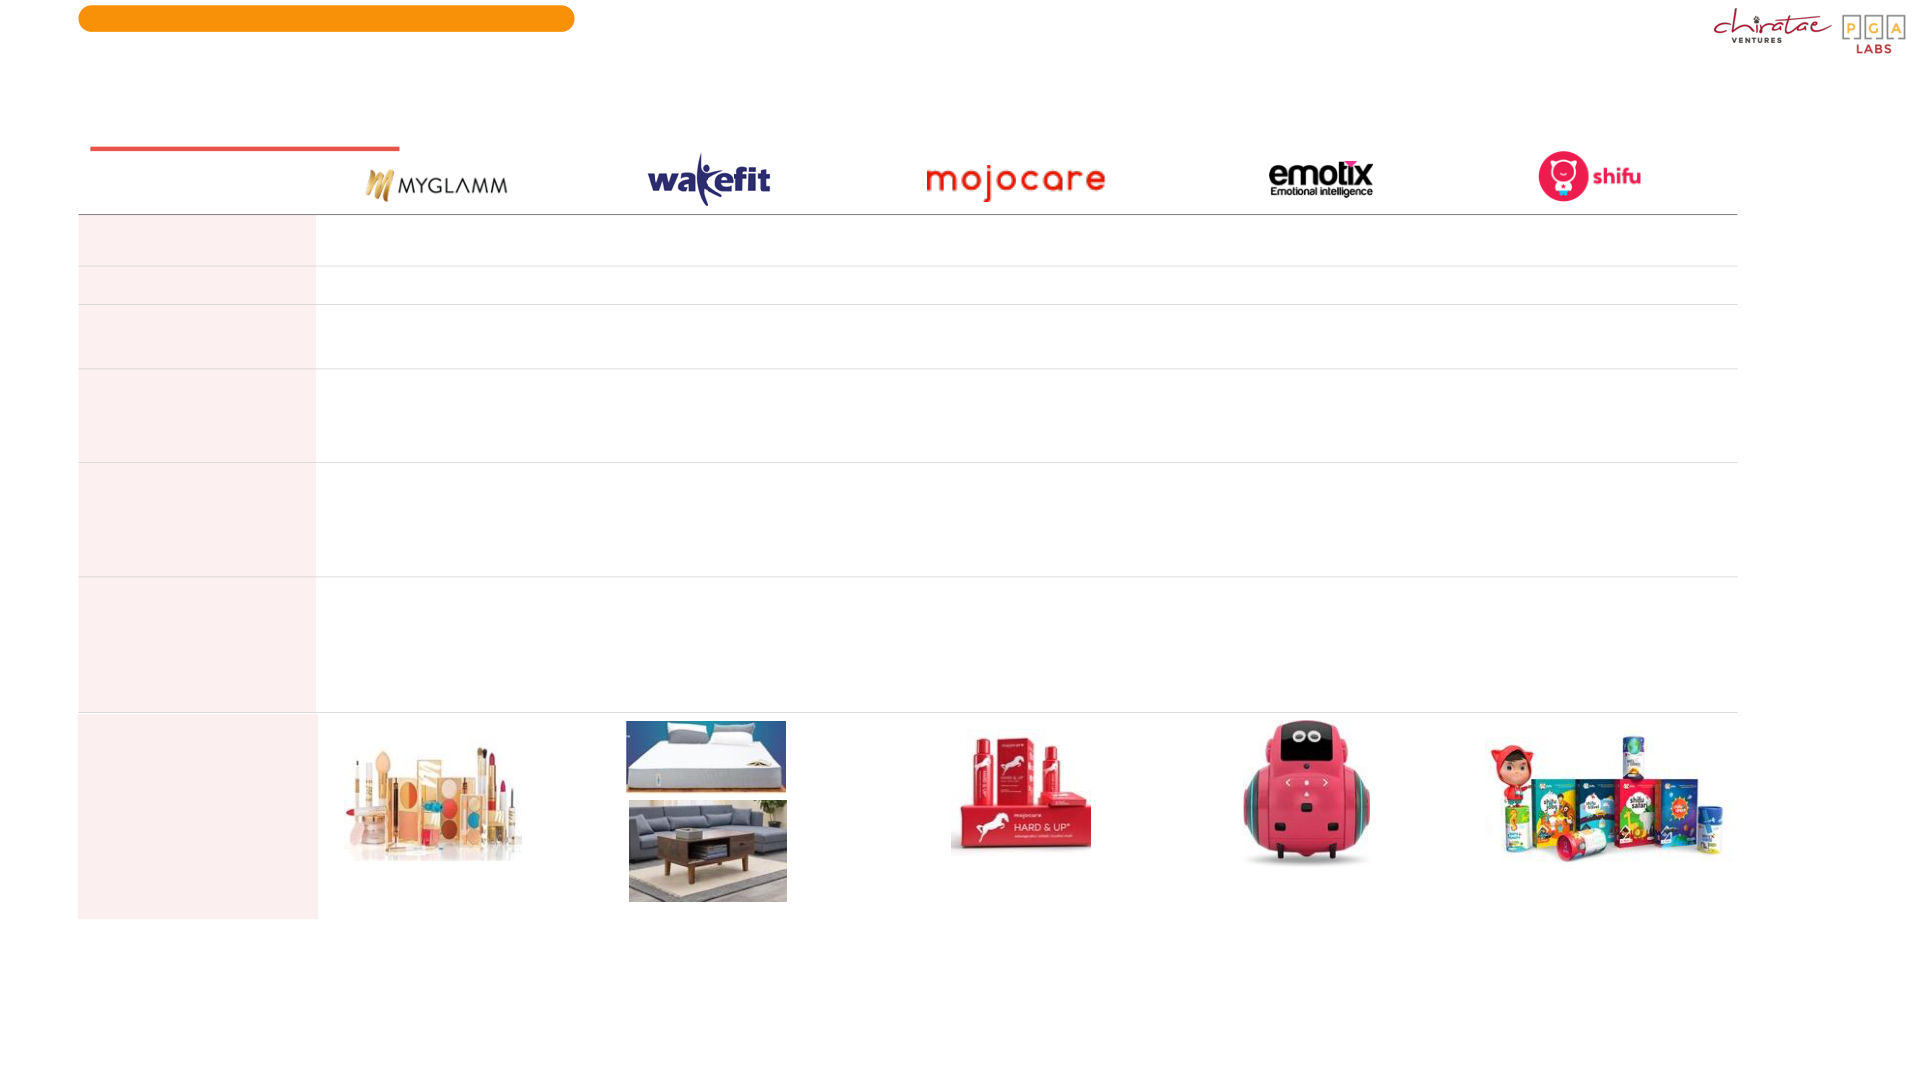
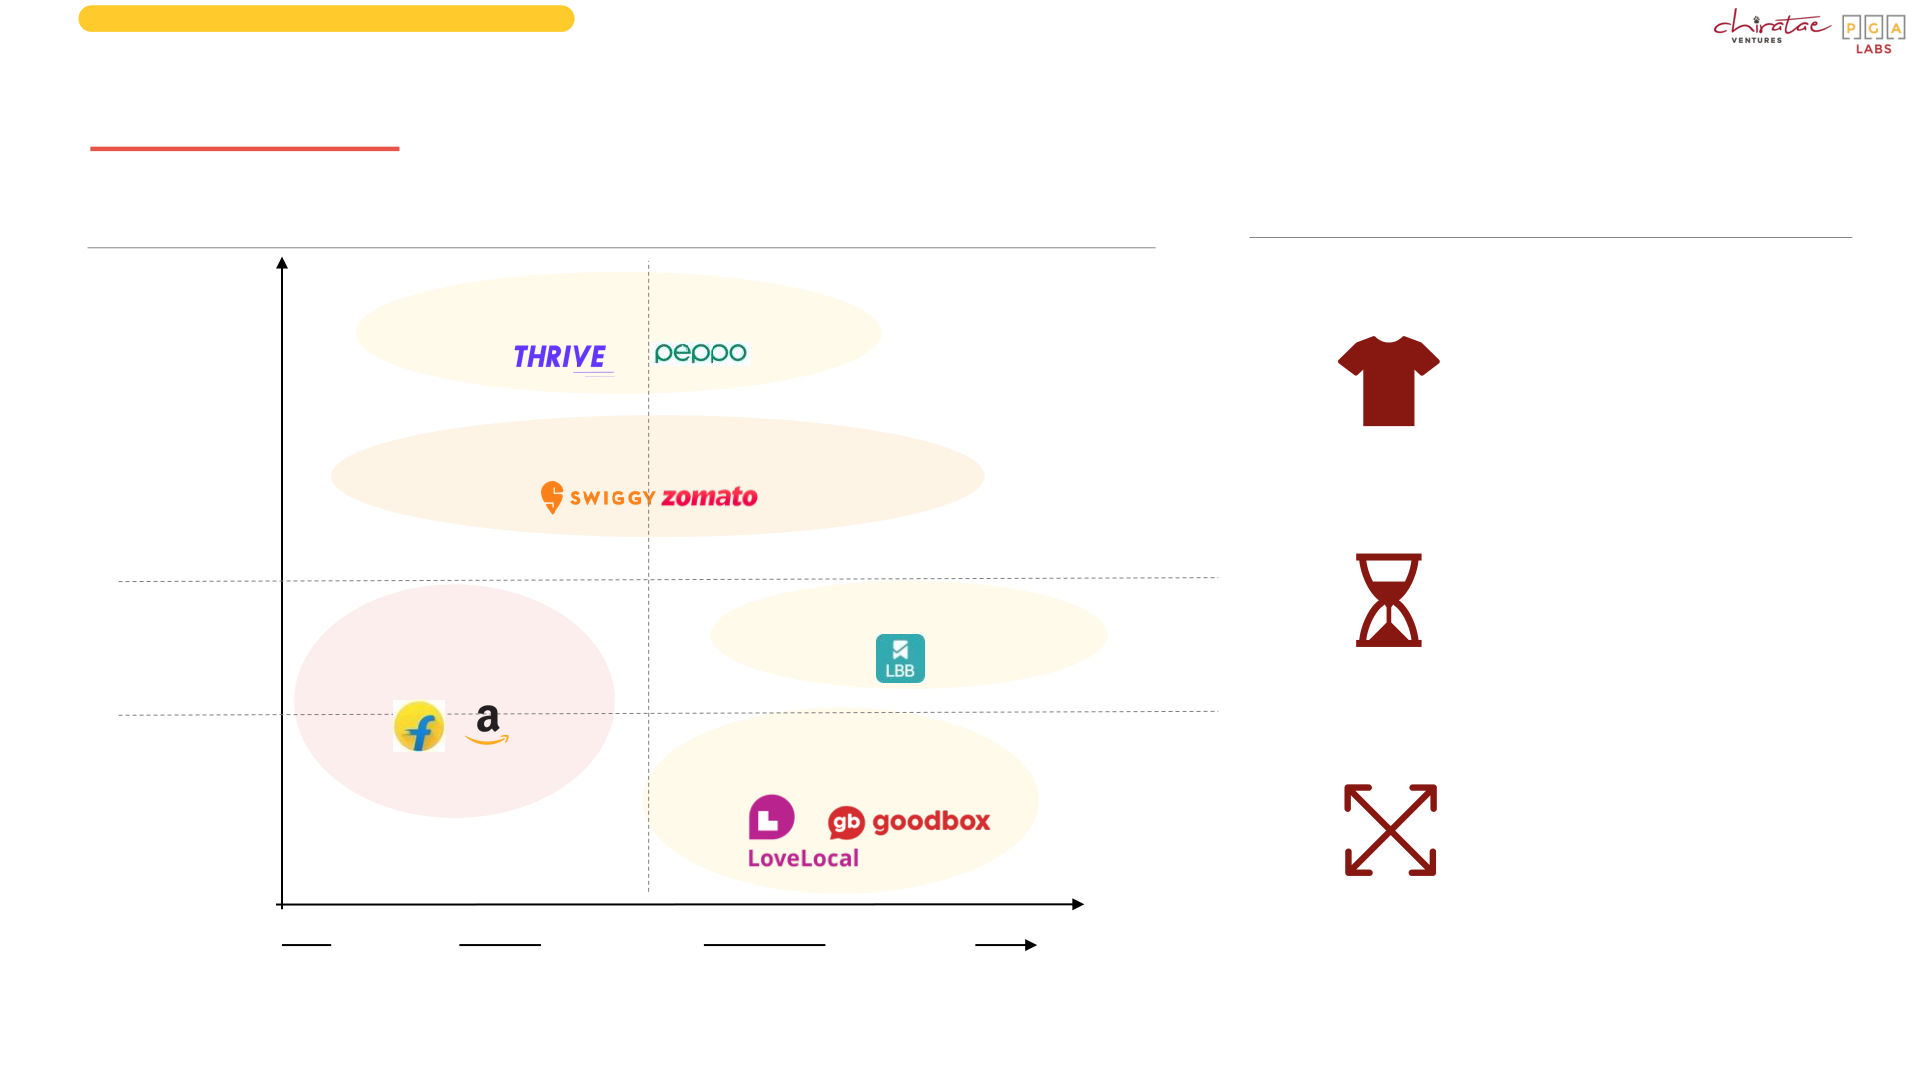
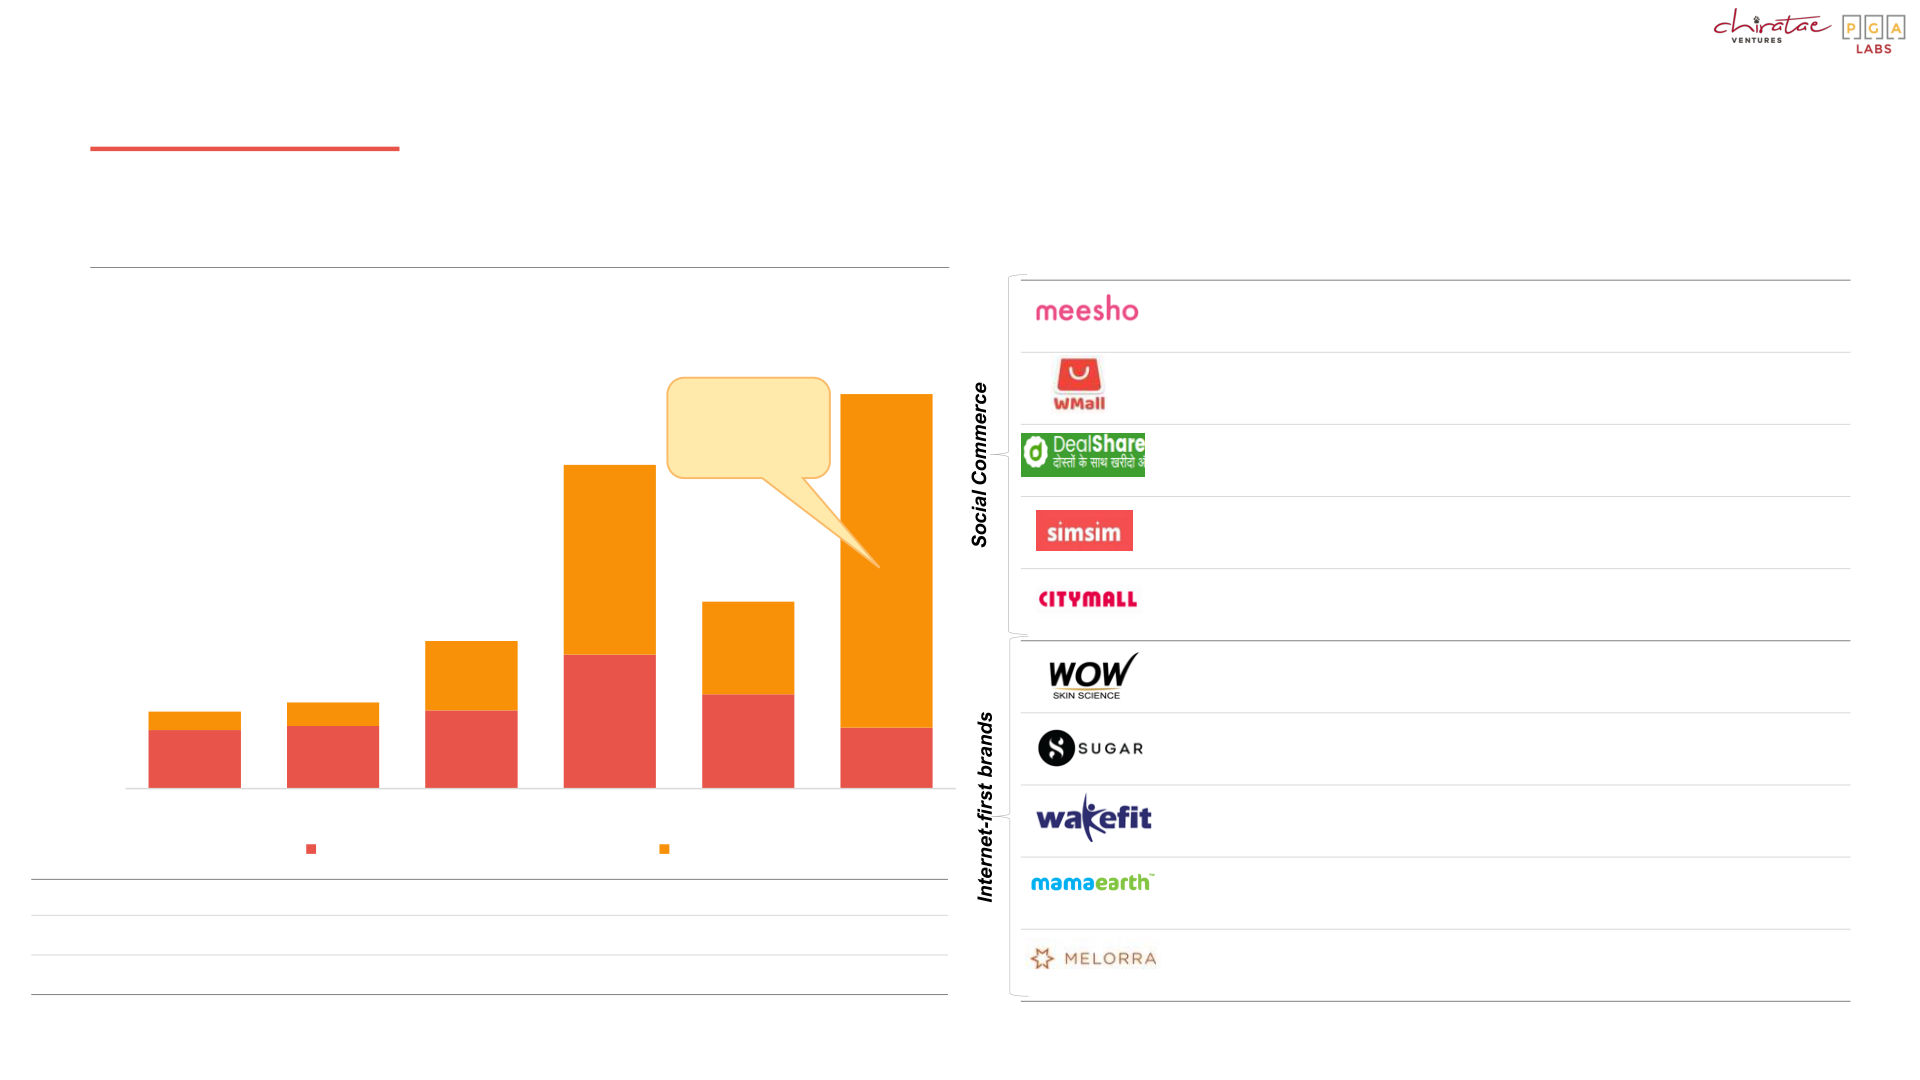
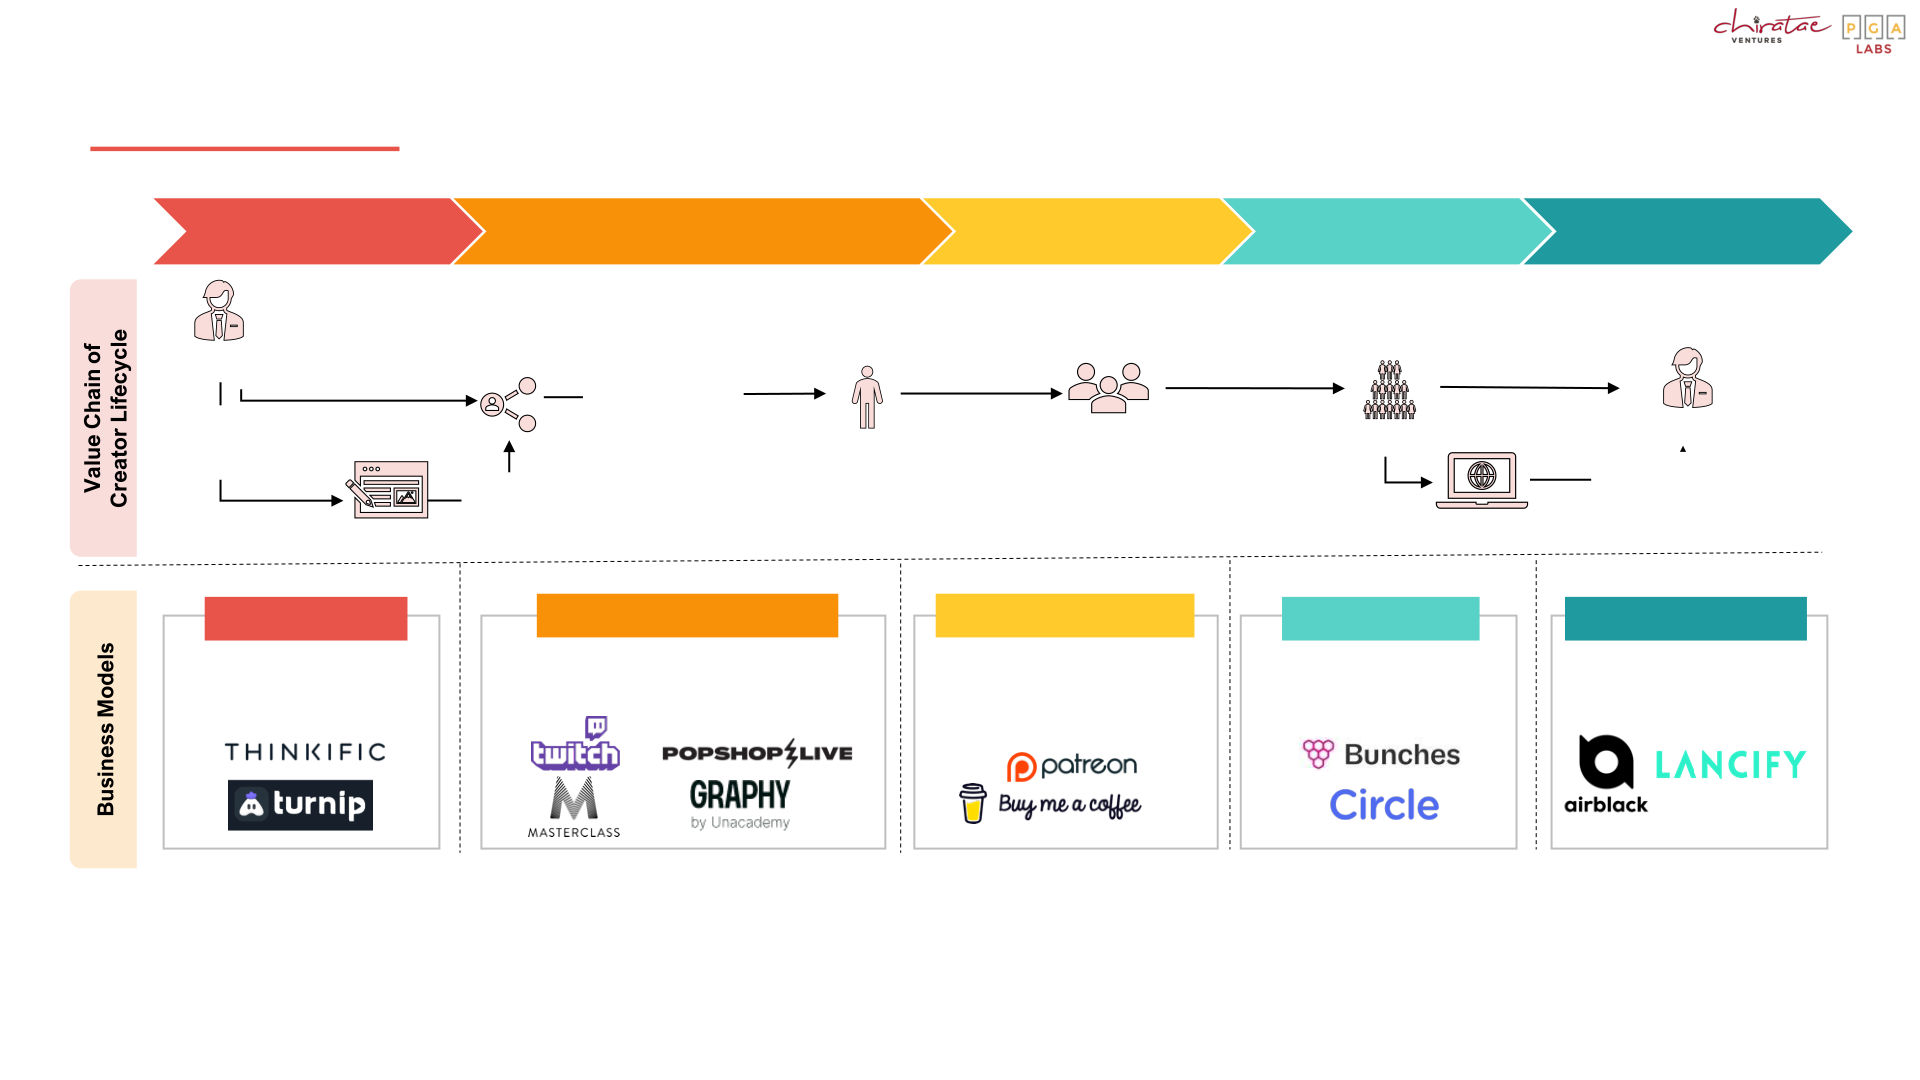
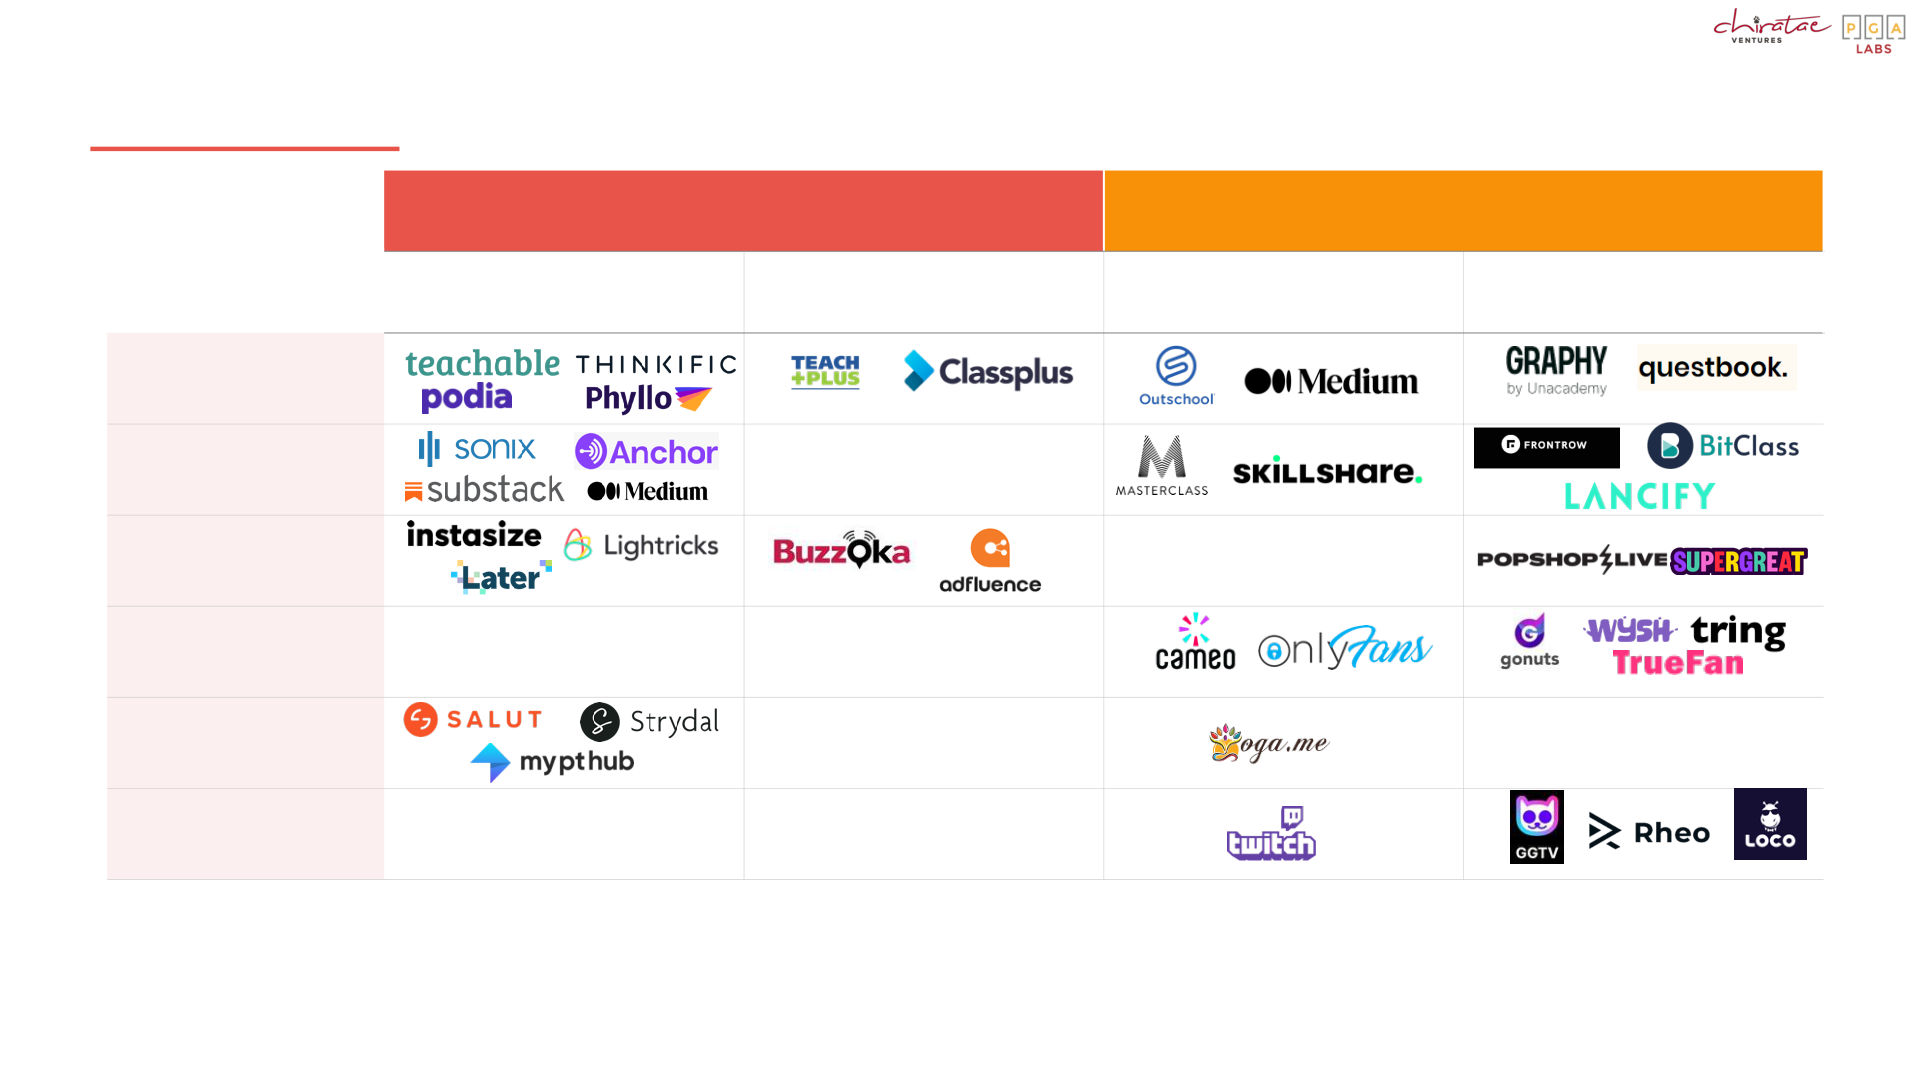
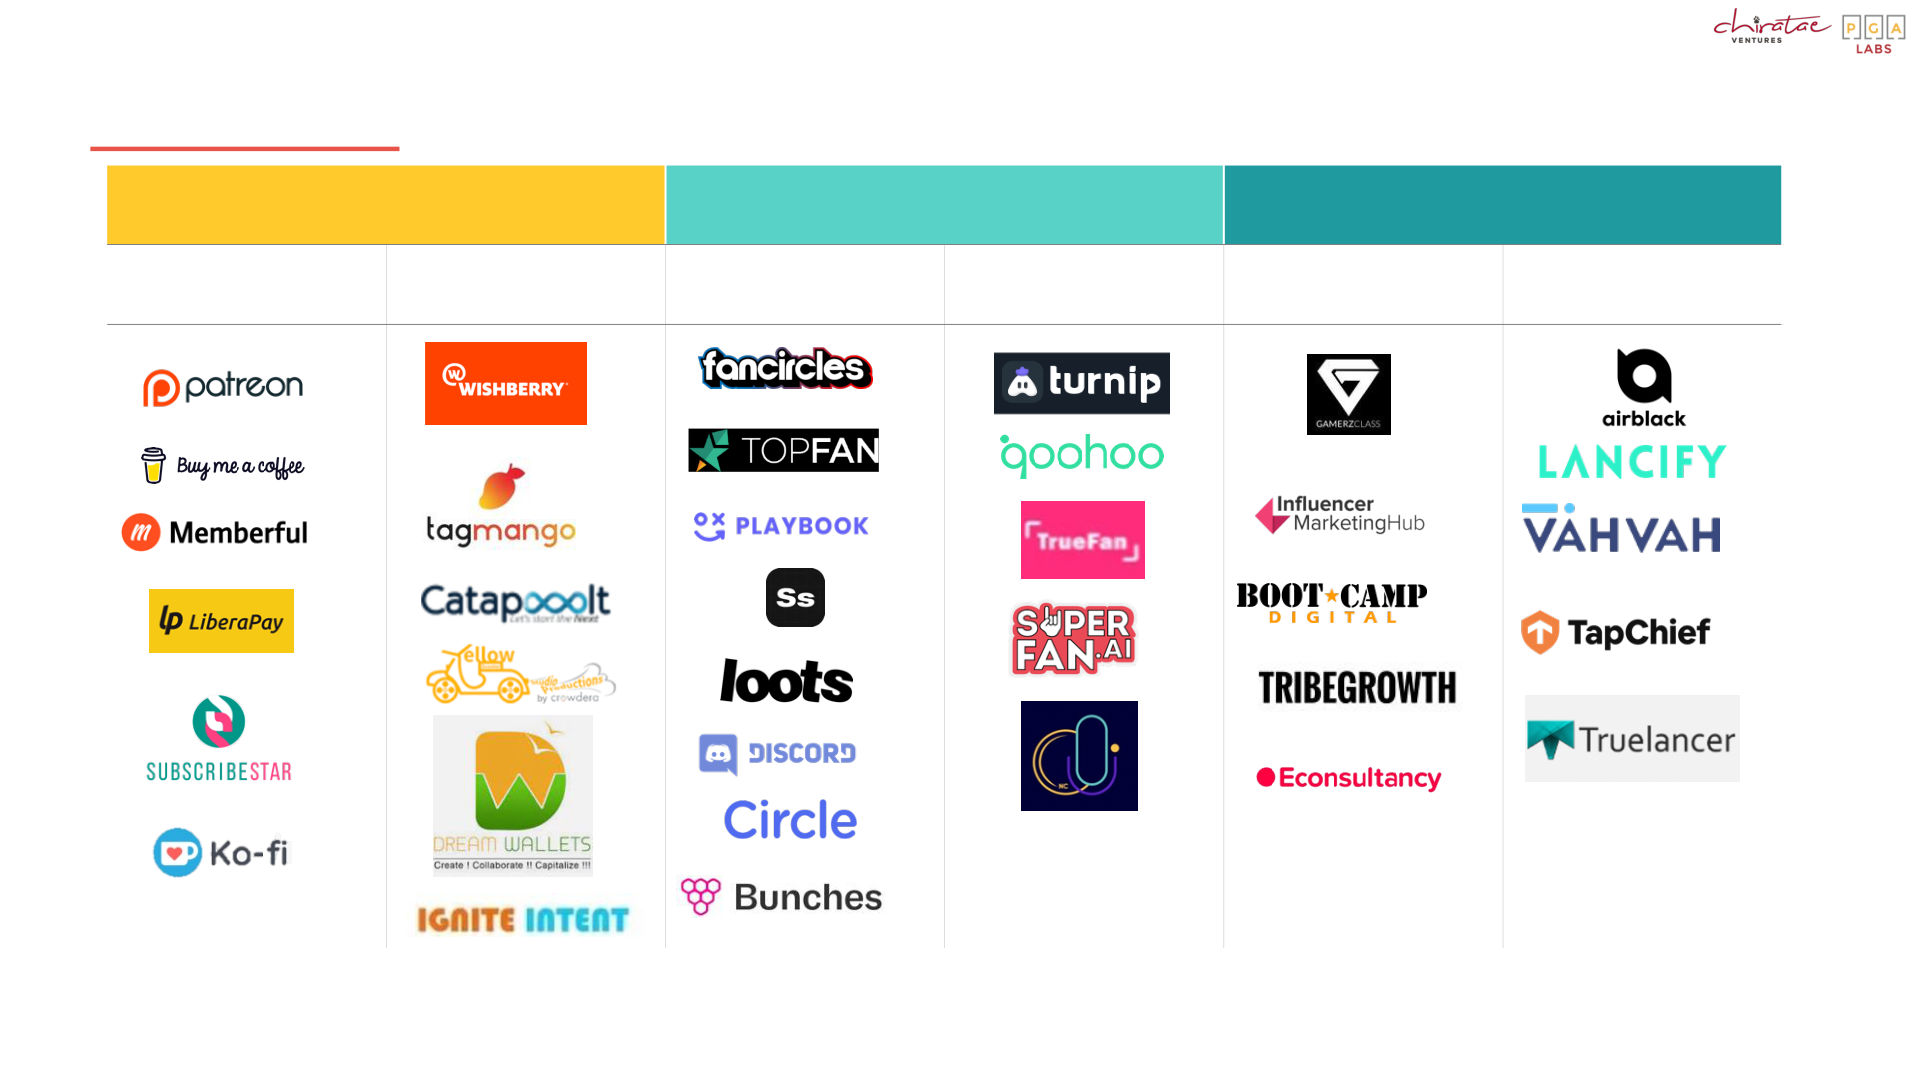
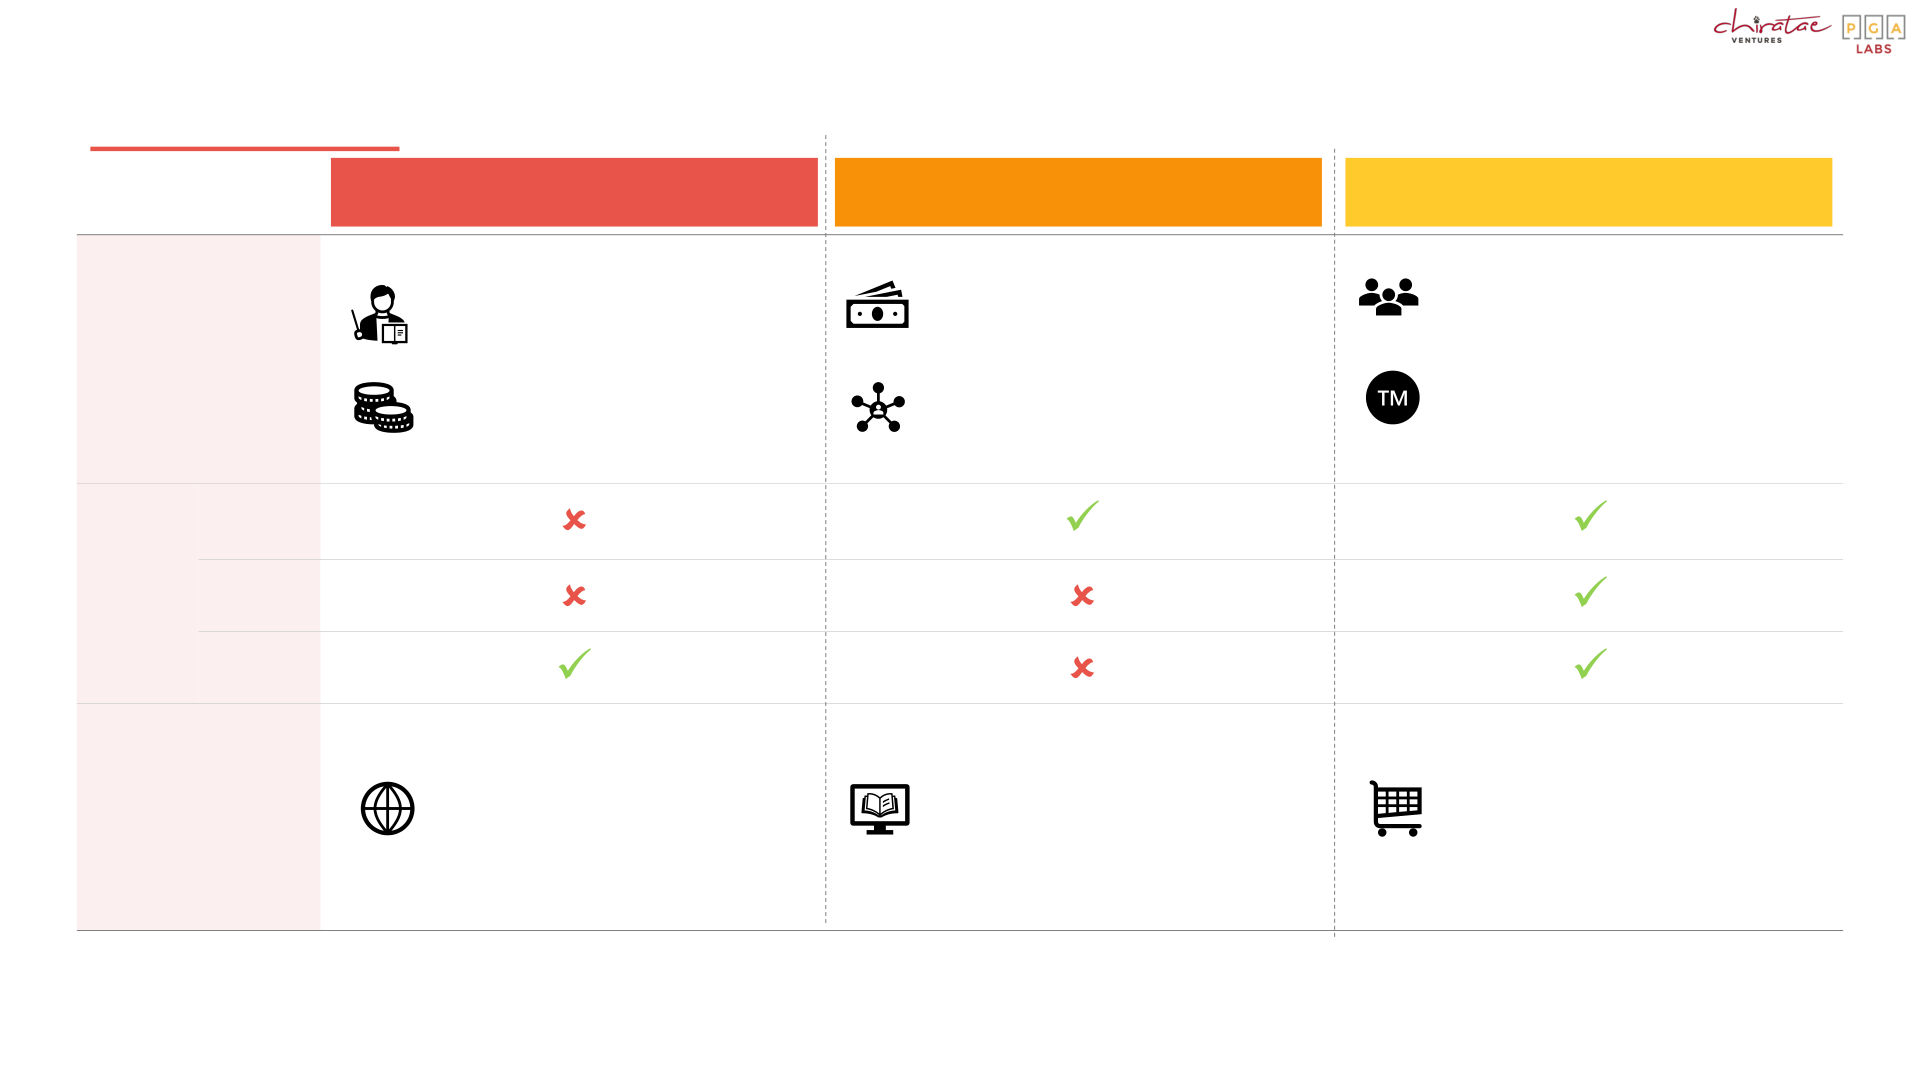
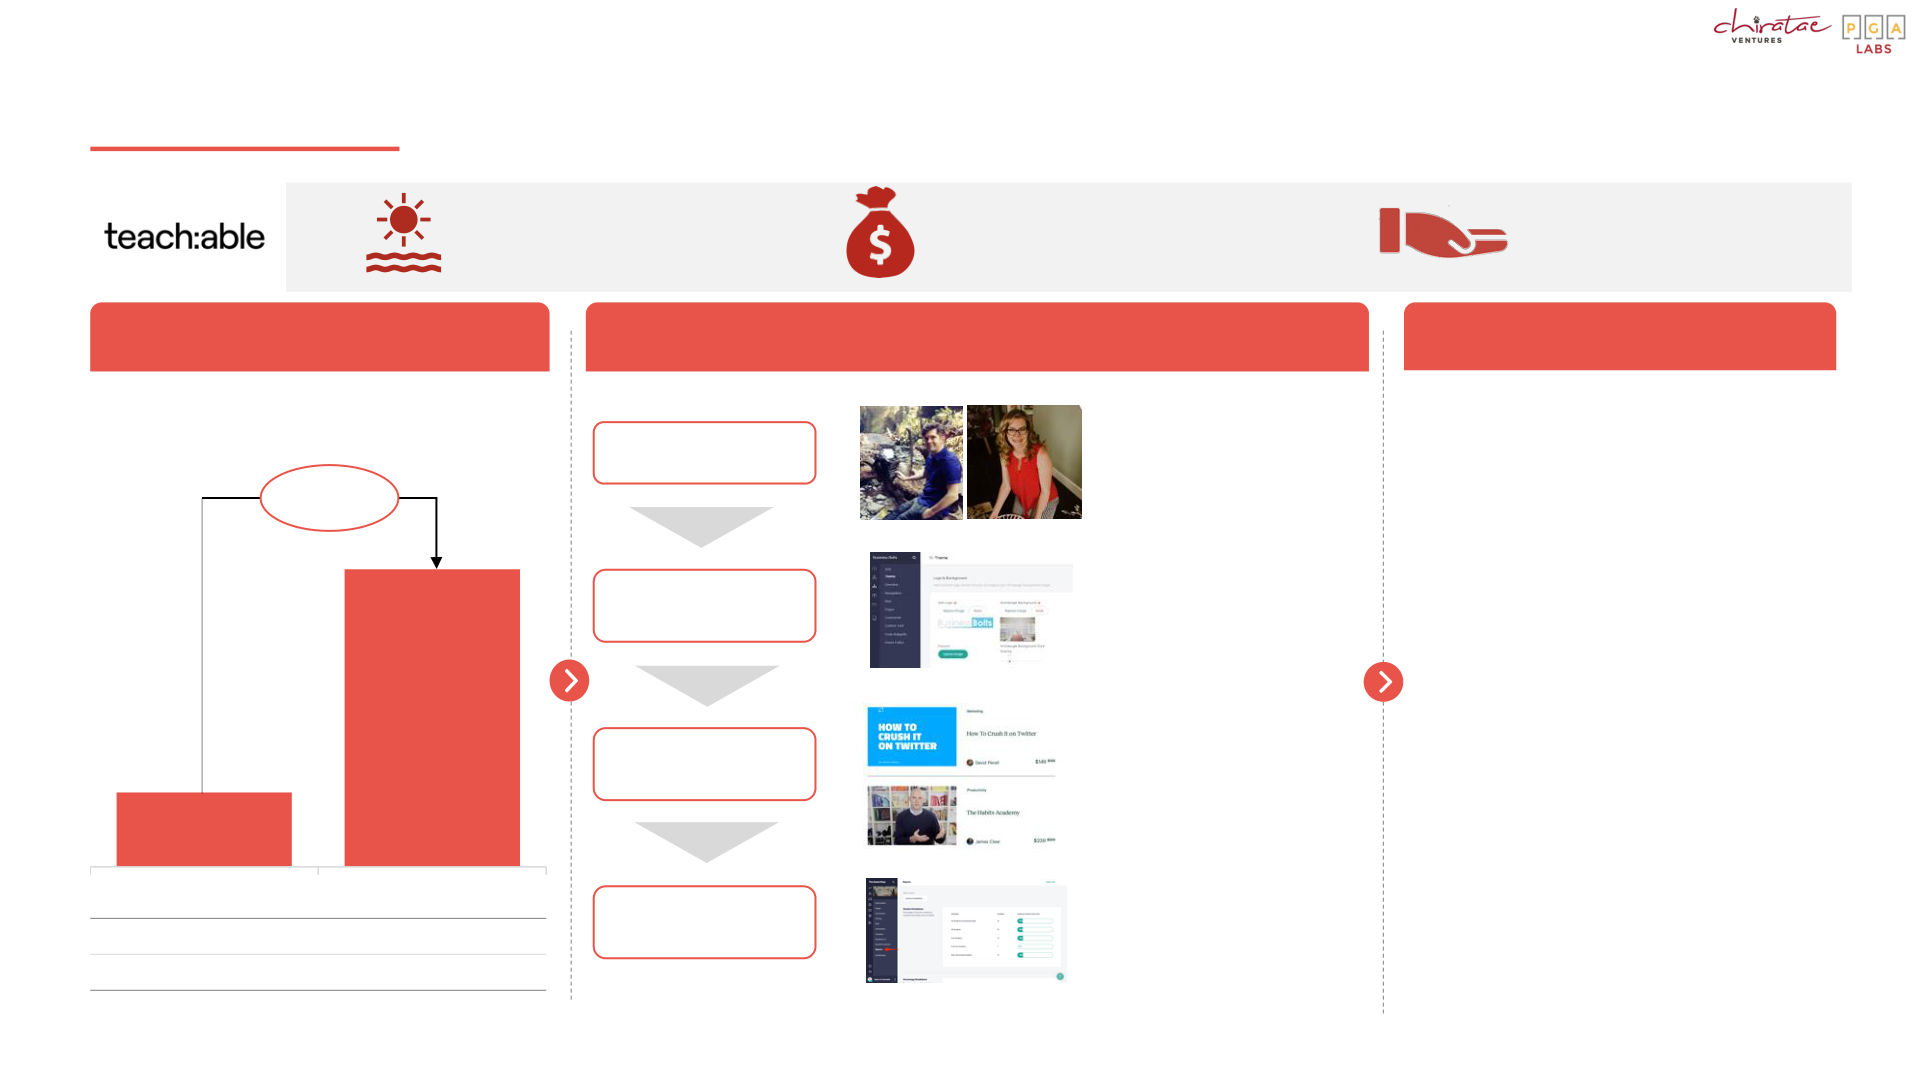
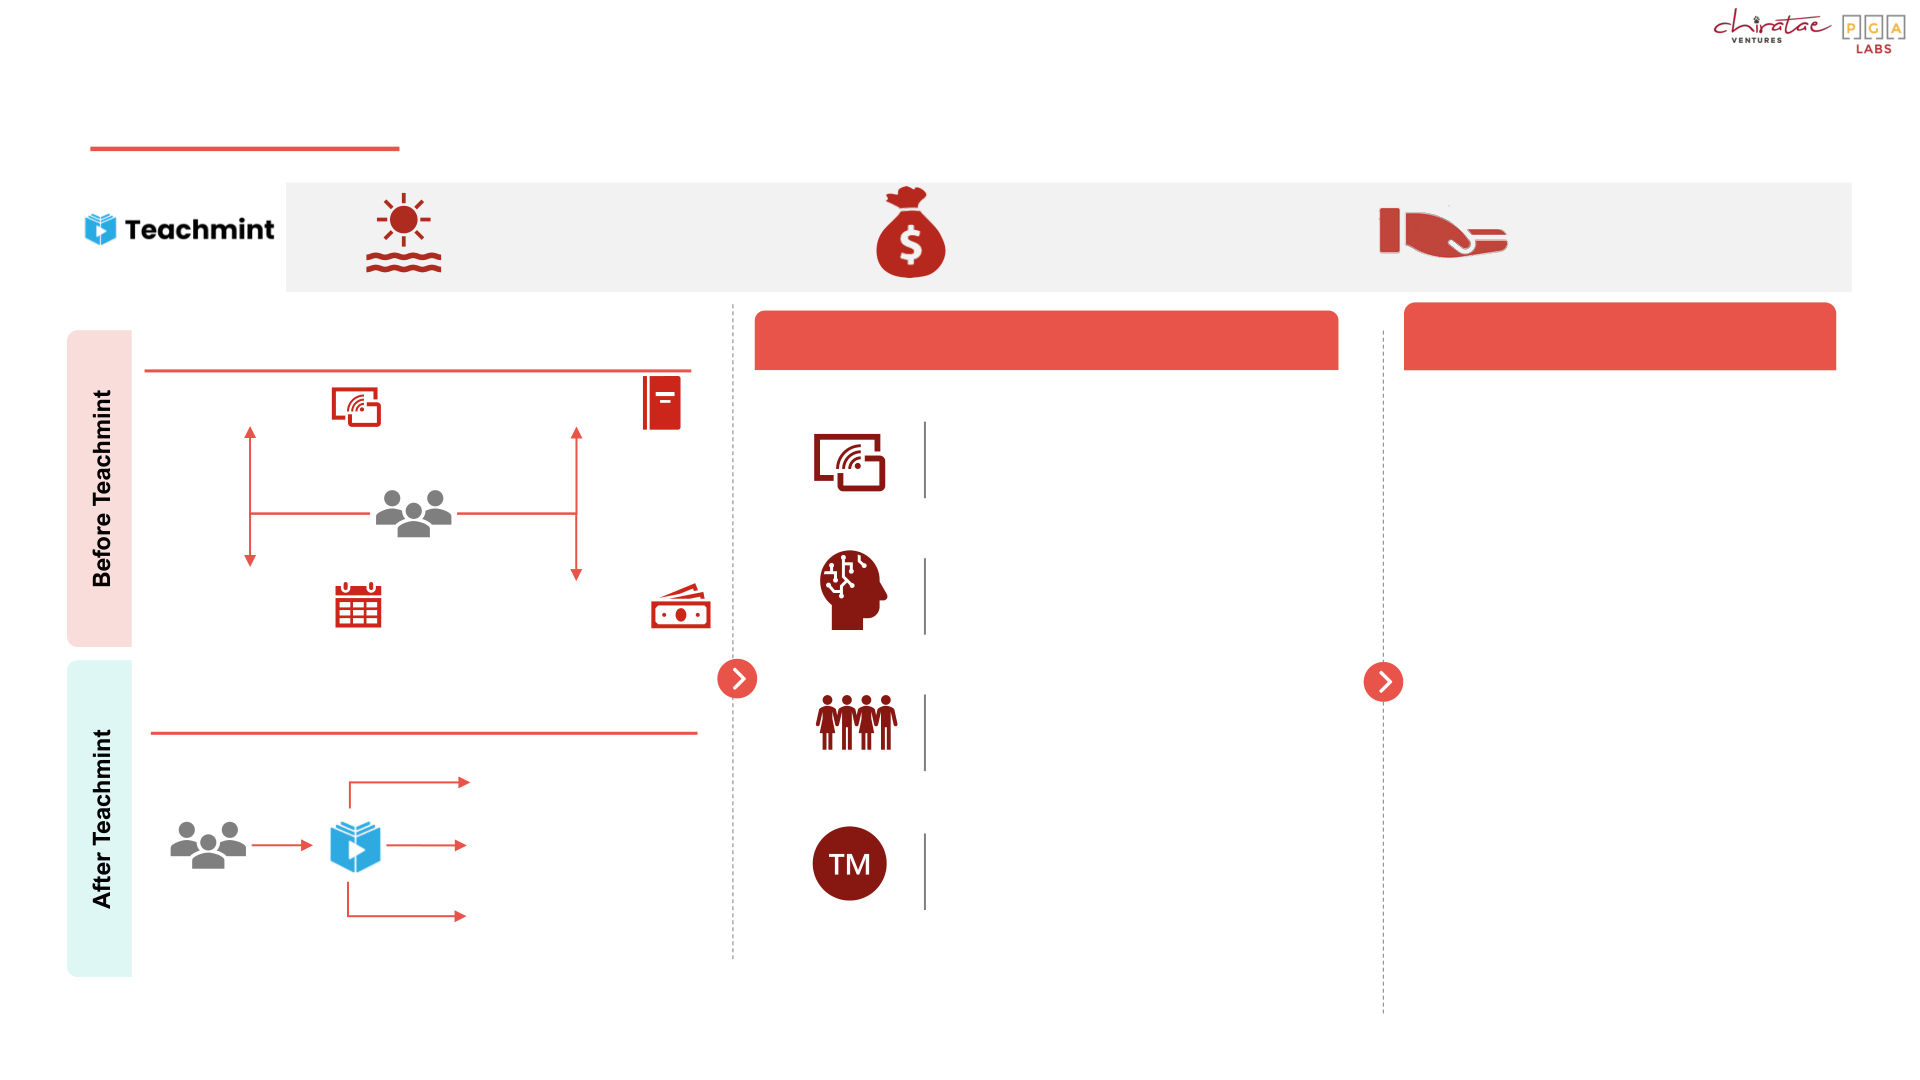
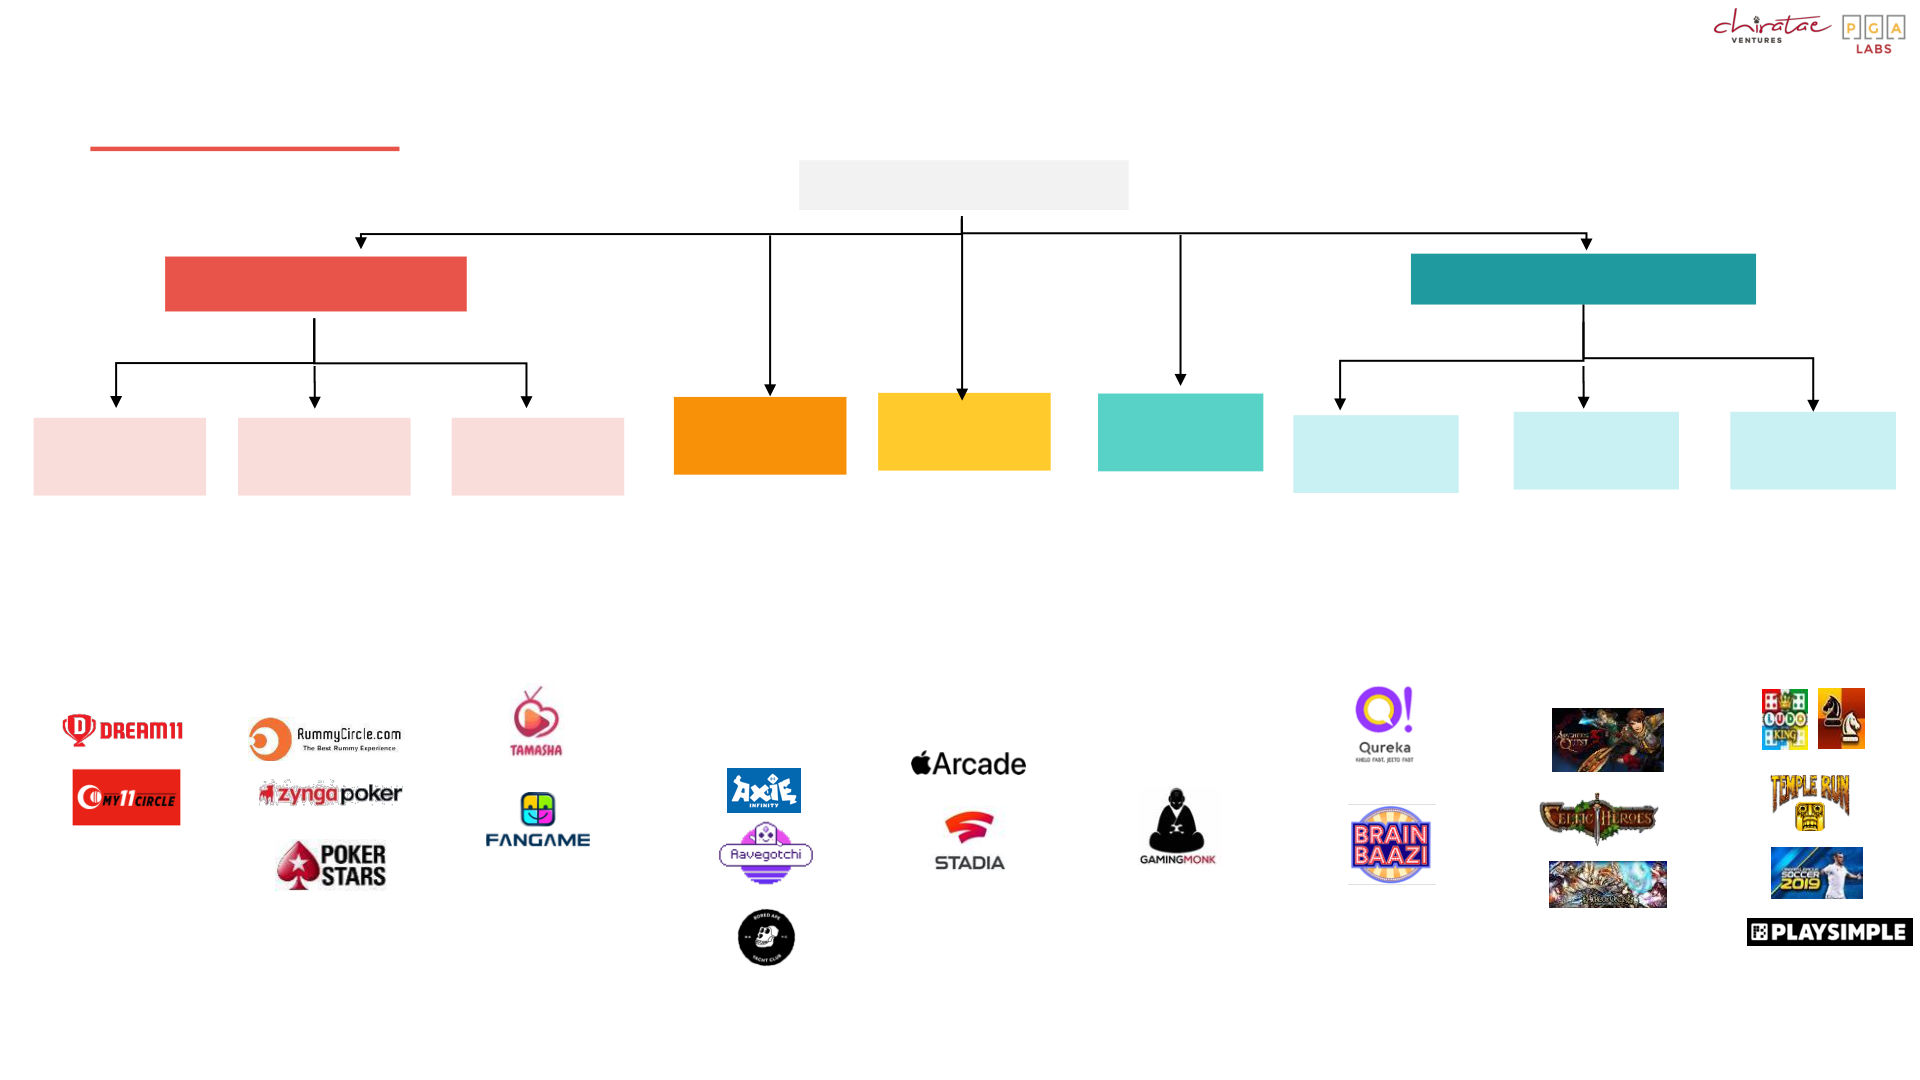
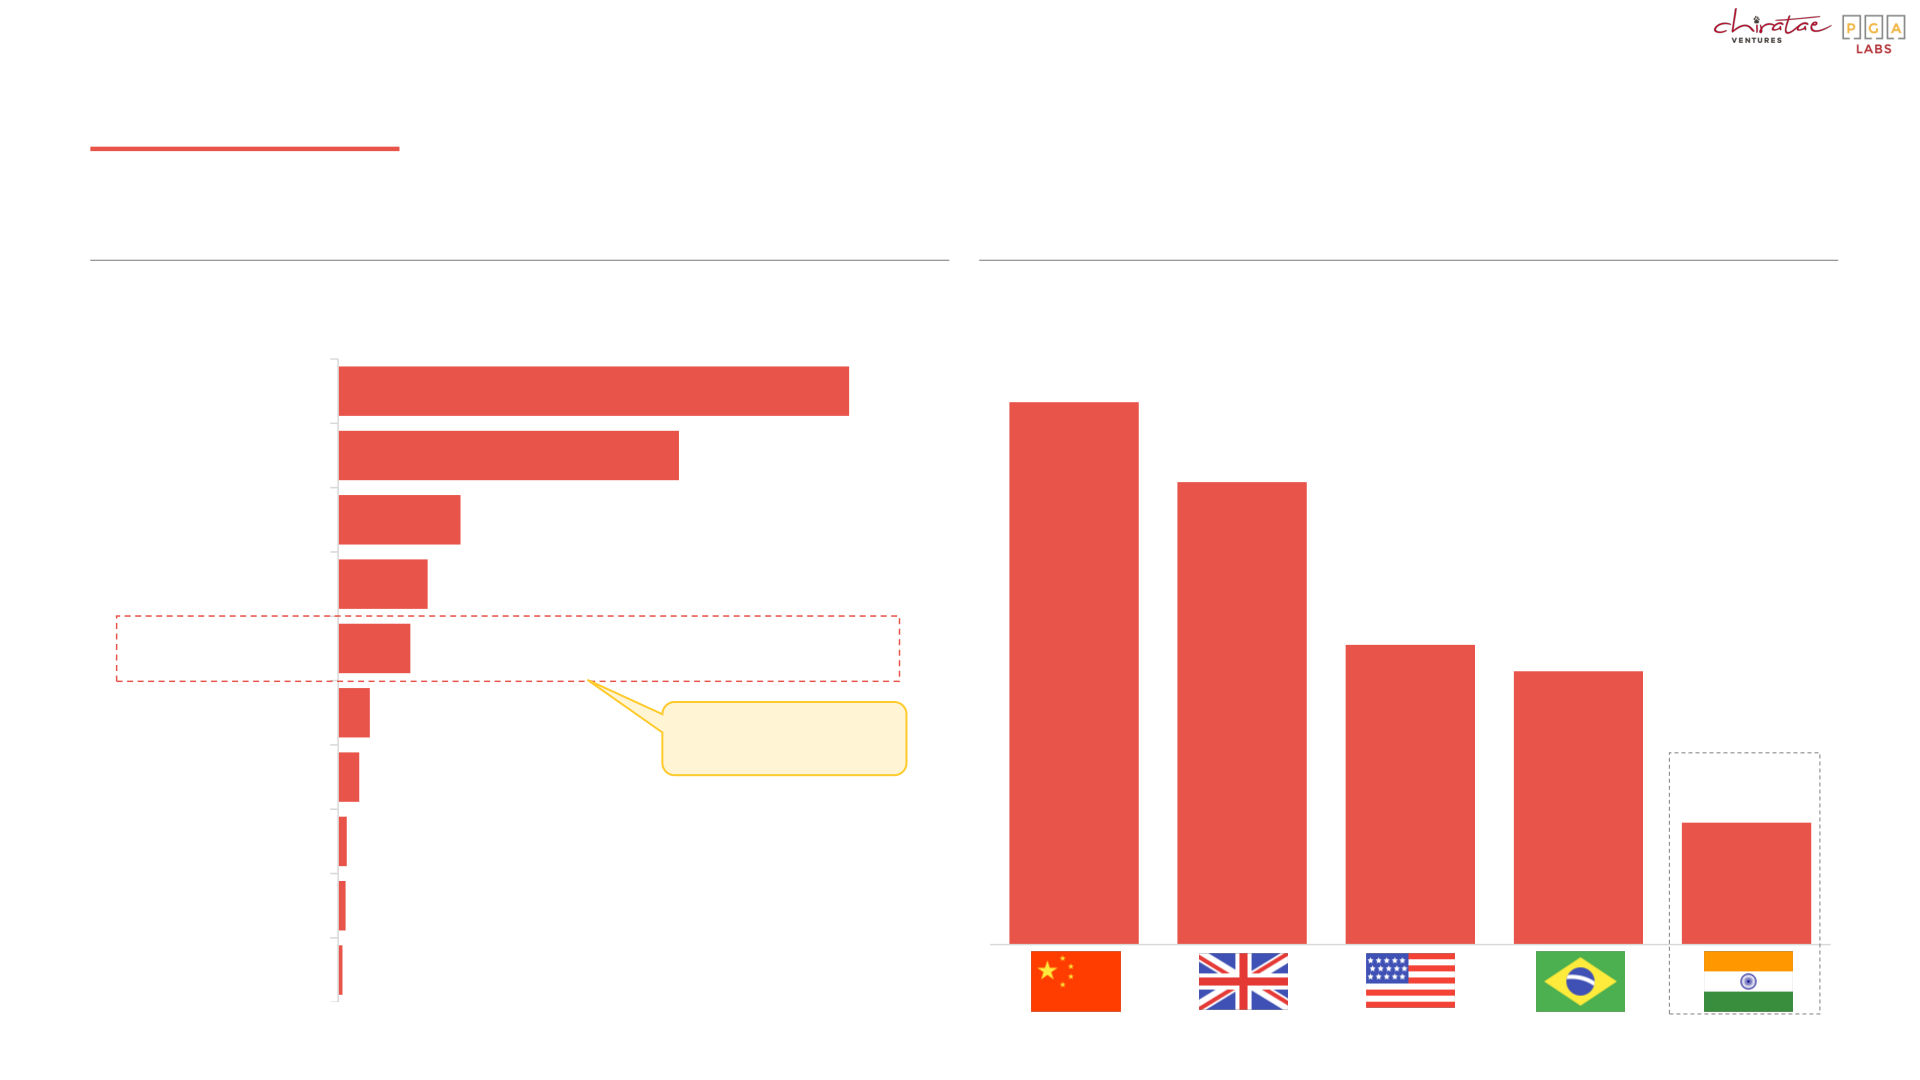
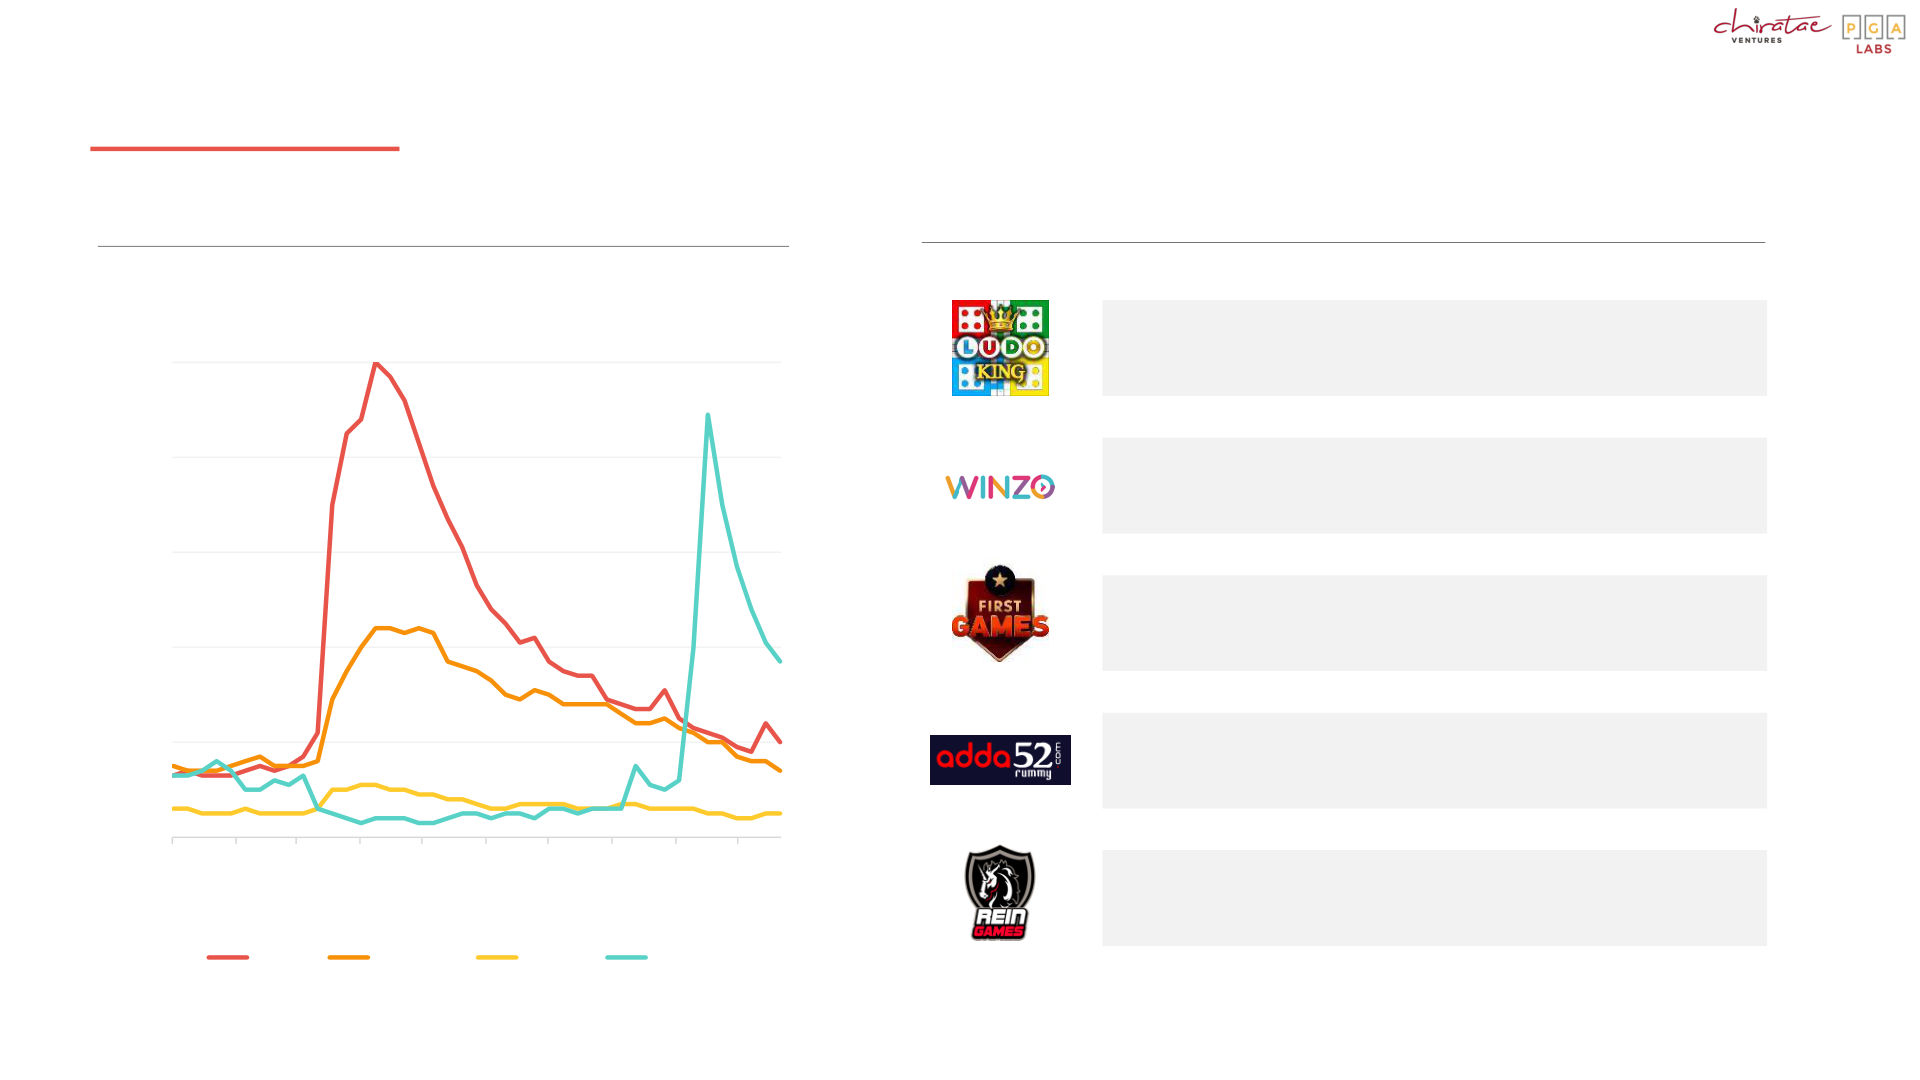
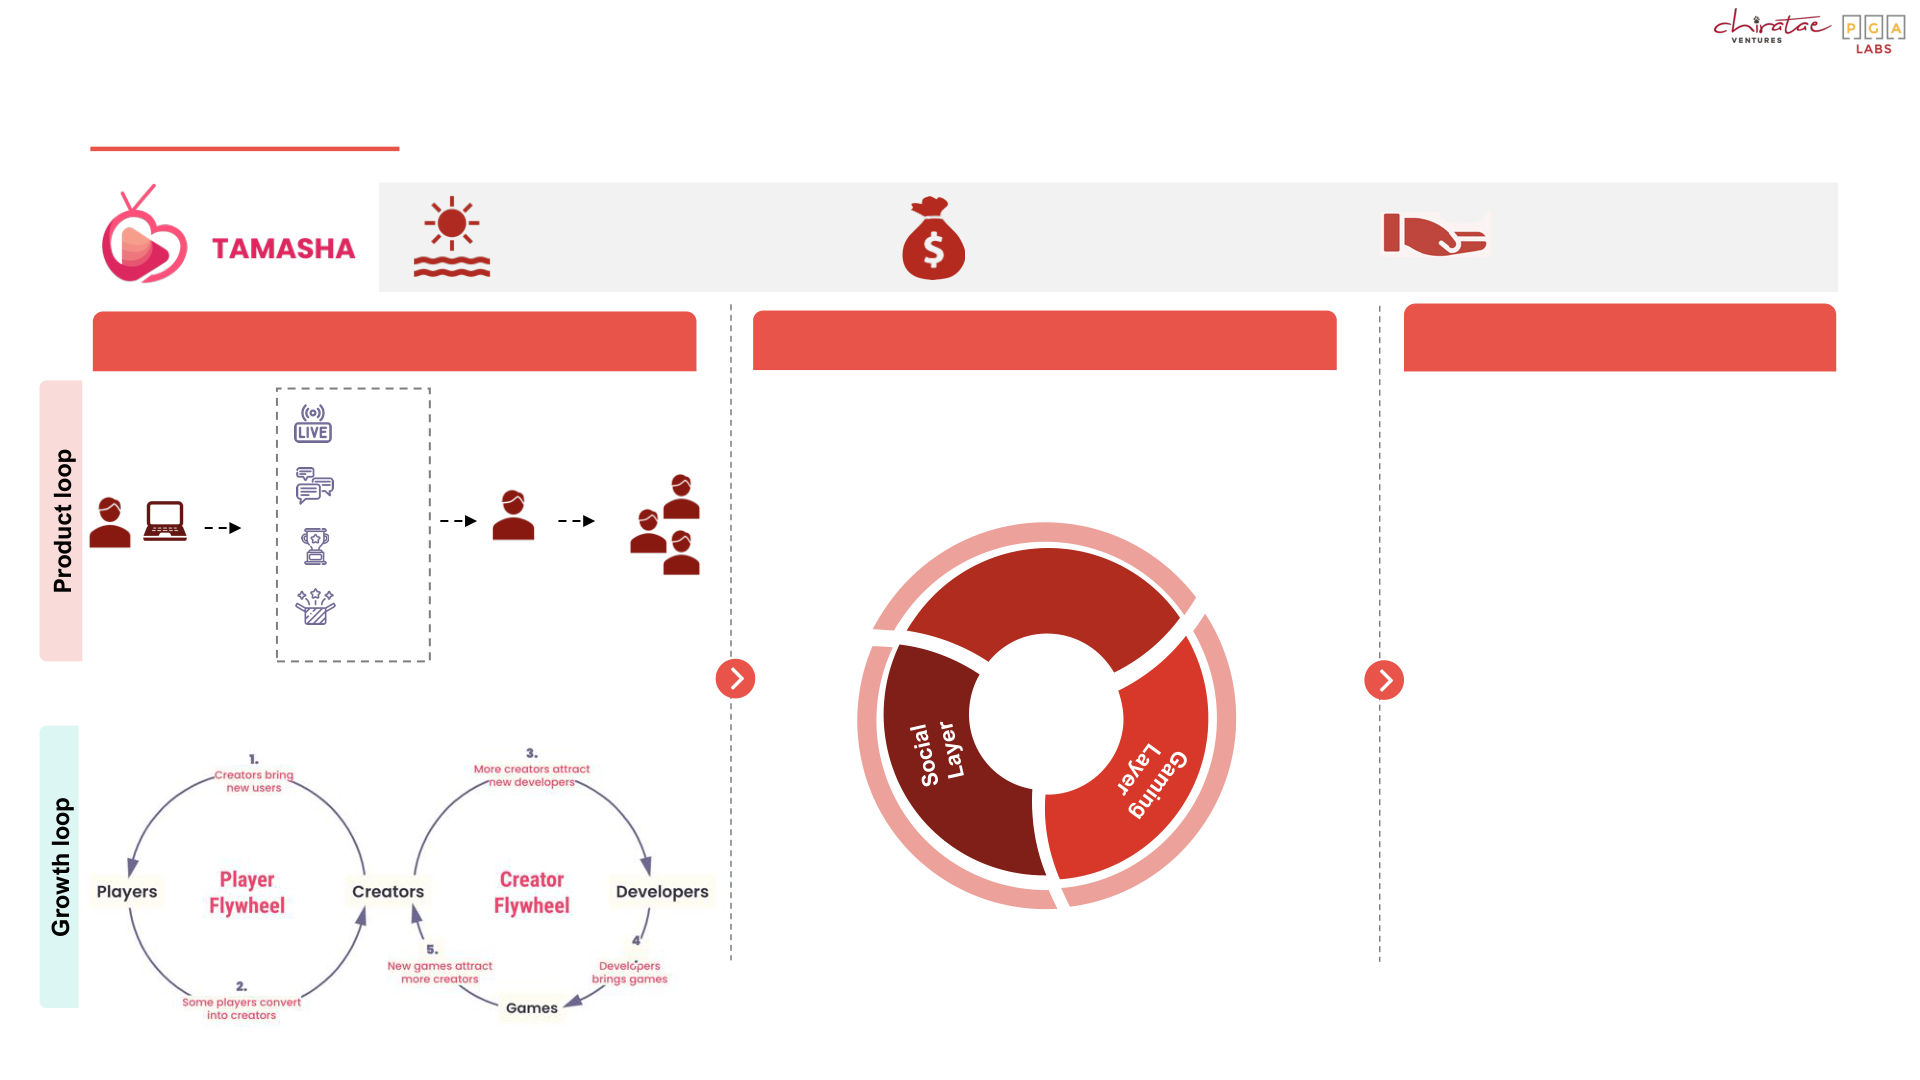
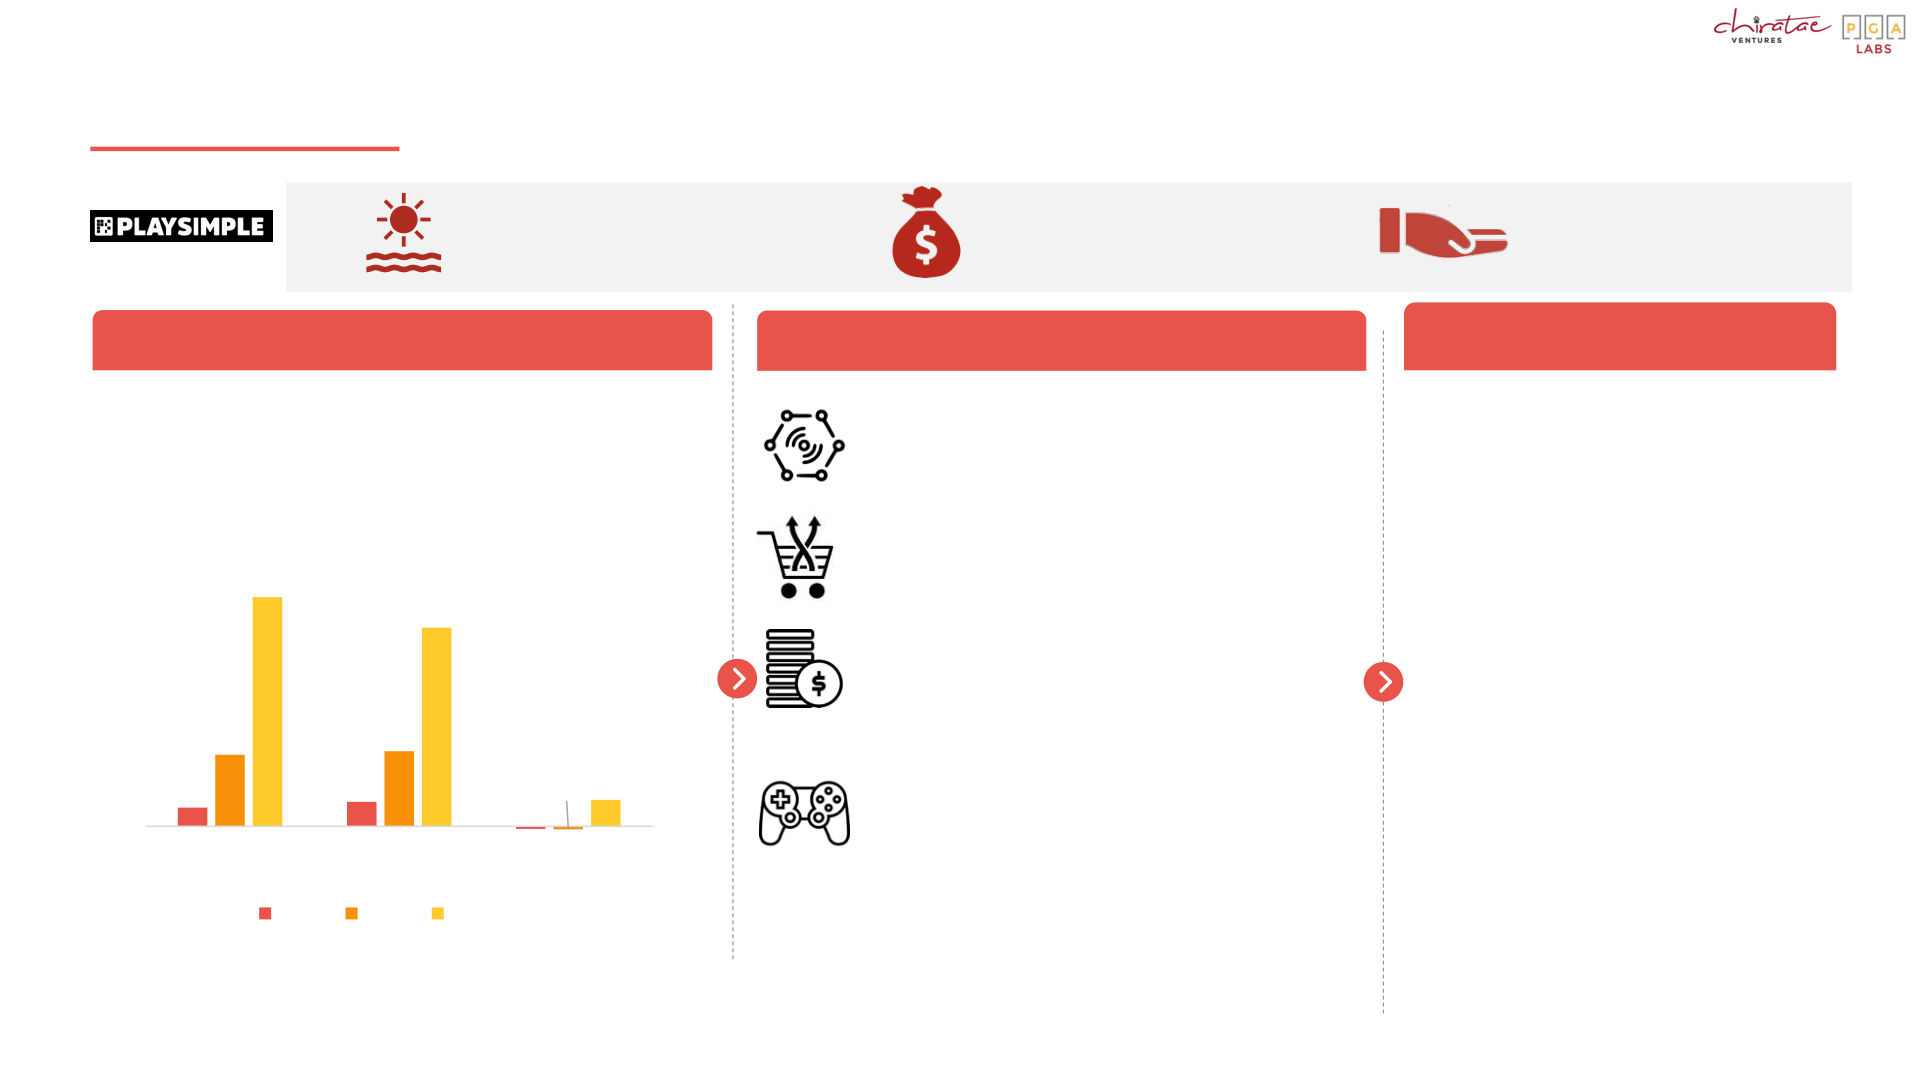
ConsumerTech report March 2022 Confidential and proprietary © Praxian Global Pvt. Ltd. Foreword – Sudhir Sethi, Chiratae Ventures India’s internet penetration over the last decade has increased from the 50 M Tier - 1 centered affluent Indians to 825 M Indians across India . This was propelled by internet access at low cost but also by a wave of consumer - focused internet startups that drew people online . Indians not only browse and shop online but invest & earn money, educate themselves, meet people, entertain themselves, find doctors/trainers, order food, needless to say process most of their daily payments online . At Chiratae , we anticipated some of these changes taking shape back when we made our first few investments as a fund as we invested into companies like First Cry, Lenskart , Myntra, Flipkart which are all category creators & market leaders in their own right . While the first wave of Consumer Tech companies were eCommerce players, starting with horizontals and moving to niche verticals as the internet expanded, the second wave saw a swing of internet adoption across categories like Health, Gaming, Entertainment, Media, Finance, Education etc. The “netizen” in India benefitted hugely by innovation during this period as various aspects of their life started getting digitized. As Covid struck, consumer - focused internet companies only grew as the acuteness of the need increased multi - fold. So much has happened within the evolution of the sector but we’re also seeing a new beginning of Indian consumer companies going global and dominating within several large niches outside India . Companies like First Cry, Go Mechanic, Lenskart , Emotix , Healthify Me within our portfolio are all good examples . We believe that the next wave of innovation and value creation will occur on one hand via globalization and on the other hand across furthering access to commerce to 1 B Indians (e . g . via Social Commerce ), growing pools of supply Sudhir Sethi by enterpization of the consumer ( The growth of the Creators Economy ), enabling engaging entertainment ( E . g via new age gaming apps) and enabling access to affordable & convenient mobility solutions (E . g . via EV - driven mobility ) . We are bullish that India’s Consumer - tech industry will grow to a $ 200 B - $ 250 B opportunity Founder Chairman by 2025 & we are happy to bring to you our thoughts, in partnership with PGA Labs, on key drivers for this Chiratae Ventures growth . We look forward to hearing your thoughts & discussing various aspects of this report with entrepreneurs, investors, LPs, industry practitioners and other stakeholders . Happy reading! 2 Foreword – Anoop Menon, Chiratae Ventures The world for consumer has never been as transient as seen in the last year or so. Hybrid is the current normal for the way one goes about her daily life – be it the way one eats, works, shops, learns, travels, entertains, invests, connects with people. Intersperse the above behavior change with time - in - hand, and we arrive at consumption patterns that were not dominant before – quick commerce, live commerce, sustainability linked choices in food and mobility, discerning choices in consumer products to name a few. All of this, enabled by startups who have leveraged technology to disrupt product, distribution and reach. It is not a coincidence that about 50% of the Unicorns that India saw in 2021 are from the Consumer - tech space. Today the consumers want to be heard and the same is reflected in the growing traction on social platforms. And being heard; they are – by the Digital Native Brands who are building a strong social and direct - to - consumer channel to build, launch, expand product and services portfolio tweaked to different micro - segments of customers keeping in mind demographics, behavior, price sensitivity aspects. Our report on Consumer Tech presents some of the opportunities that we believe are going to be dominant Anoop Menon trends in the years to come. We look forward to engaging with all stakeholders in the Venture ecosystem to enable and accelerate this journey. Principal Chiratae Ventures 3 Agenda ConsumerTech in India: An overview Value creation through technology Upcoming themes in ConsumerTech E - commerce 2.0 Creators’ economy Online gaming and entertainment Electric Vehicles About us 4 Key Points of Context ConsumerTech has evolved from horizontal & vertical e - commerce to consumer apps across 1 various verticals like health, entertainment, finance, mobility, education – with an underlying current of the ability to go global ConsumerTech is expected grow to a ~US$ 200 - 250B opportunity by 2025 driven by growth 2 across internet accessibility cum affordability, growth of supply pools & increase in propensity of demand to pay for products & solutions More than $42.4B has been infused in the space, funding received with a few sectors beginning 3 to mature – with a significant increase of investments in areas like EdTech, Social Commerce, Gaming & media, Creators economy The market opportunity can be categorized into 7 key sub - segments – Commerce, Verticalized Marketplaces, Entertainment & gaming, EdTech, HealthTech , FinTech, Enablers & Emerging 4 areas Commerce 2.0, Creator’s economy, Online gaming and entertainment, EV driven mobility are emerging themes which will be key growth drivers of the sector 5 5 Five megatrends that are re - shaping ConsumerTech in the world Verticalization Horizontal e - commerce – Specialization the everything store Personalization Large enterprises driving Enterprization of business customers Long - form supply - chain Direct - to - consumer, distribution Internet - first brands Limited sources of Digital consumption commerce, banking, through smartphones entertainment, etc. Accessibility to local Globalization world is markets the consumer 6 ConsumerTech has evolved from enablers (horizontal e - commerce) to verticals (specialization) across categories and is moving towards globalization 2010 2015 2020 2025 Internet adoption across Vast customer demand leading Indian consumer companies go Inflection points Introduction to e - commerce categories – health, content, to opportunity of verticals global and at scale community, media & fintech Verticalization: Creation of digital ecosystem • Fashion – citizen became netizen and Rise of internationalization • Eyewear started using Digital media for Development of Horizontal with market winners going • Baby products entertainment (OTT, gaming), Developments commerce global & newer opportunities • Health & fitness health & wellness, D2C brands, for emerging players • Mobility digital payments, mobility, EdTech, etc. Companies Chiratae’s picks on this wave Chiratae identified winners that have continued to thrive over a decade , some of these are well positioned to transform consumerism globally 7 Indian Consumer Internet Companies have the potential to go global Today / India 2025 / Global • Internationalization • Verticalization • Indian companies dominating India • Integration of consumer - commerce and going global with various sectors - FinTech, • Increased accessible - tappable Trend HealthTech , Mobility, etc. population due to reduced barriers • Own the ecosystem with content & • Proliferation of “essential community plays commerce” across India ~1.3B consumers ~5B consumers ~950M internet users ~4B internet users Opportunity ~150M farmers ~600M farmers ~510M gamers ~1.3B gamers ~80$B Market size ~>$1T Market size Source(s): Statista, World Bank, PGA Labs analysis 8 How is Technology being leveraged in various consumer sub - segments Sectors Use Cases Companies HealthTech • AI fitness Coach • Computer vision based live tracking • Electronic health records FinTech • AI in fraud detection • Tech - driven underwriting • NLP to detect risk of insurance Frontier Technologies in EdTech • AI tailored lessons • AI for repetitive ConsumerTech administrative tasks • Metaverse for education E - commerce • Smart assistants & Consumer and Retail chatbots • AI tailored personalized advertisements & recommendations while shopping Entertainment, • Content personalization media & gaming through AI • Search optimization • In - game customizations AgriTech • Crop quality assessment via AI imagery • Farmer commerce & communication networks in low bandwidth areas 9 ConsumerTech is expected grow to a ~US$ 200 - 250B opportunity by 2025 Consumer Tech sector market size Growth drivers of ConsumerTech sector in India (in US$ B) ~25% YoY growth in internet user base 250 ~95 % reduction in data prices since launch of Jio ~25 - 30% ~65 % smartphone penetration in India by 2025 200 ~30 % more per capita income of Indian households 20% as compared to FY15 62 25 2015 2020 2025 Note(s): Smartphone penetration is no. of smartphone users in India divided by total Indian population Source(s): IBEF, Inc42 Ed - tech report, NASSCOM, Spire, YourStory , PGA Labs analysis 10 The market opportunity can be categorized into the following sub - segments Verticalized Entertainment & Enablers & Commerce EdTech HealthTech FinTech Marketplaces Gaming Emerging Areas Online media & Telemedicine / K12 education Horizontal 1.0 Insurtech Food tech B2C logistics content tele - consultation Test preparation Online Payments Consumer AgriTech Shared mobility & healthtech Auto tech Social networking & Vertical 1.0 UGC E - pharmacy Out of school / Online Lending Digital Brand extracurricular aggregators Online rentals, classifieds & services S ocial Commerce Gaming Higher education, up Home healthcare Personal finance skilling and certification apps Travel tech Digital education Neo - banking Internet first & tools and enablers online retailers Real estate tech 11 ConsumerTech has grown tremendously with $42.4B funding received over the years with few sectors beginning to mature Sector - wise investment distribution Deal flow distribution in these segments of 2021 (2019 - 21, US$ B) # Funding Sector # Unicorn Key companies 6.7 10.1 18.2 deals (US$) 8% B2C Ecommerce 30 ~US$ 12.2B 18 Nykaa , Flipkart 23% 27% 3% Marketplace 62 ~US$ 13.1B 17 Ola, Swiggy , Cars24 5% 43% 10% 2% Dream Sports, MPL 9% Entertainment & 9% 40 ~US$ 1.4B 2 GameNagri , Global IP Gaming 3% Trust, Red Radio Band 3% 11% 2% Unacademy , BYJU’S, 7% 2% EdTech ~US$ 4.88B 5 38% 93 Simplilearn , upGrad 5% 6% 11% HealthifyMe , mFine , 16% Health Tech ~US$ 2.39B 4 56 2% Cure Fit, Redcliffe 2% Policy Bazaar, 8% 20% 15% FinTech ~US$9.34B 16 PhonePe , RazorPay , - 3% 2% 3% 1% CRED, Pine Labs 2019 2020 2021 Online Online Shared Rentals, media & Social Internet - mobility & Horizontal FoodTech Gaming TravelTech Ed Tech classifieds, entertainm networking first Auto Tech & services ent Marketplaces Entertainment & Gaming E - commerce Source(s): Tracxn , PGA Labs analysis 12 Four emerging themes identified across the Consumer Tech space which could potentially scale soon EV / Shared Mobility Commerce 2.0 Creators’ Economy Online gaming and entertainment Creators become businesses and Next wave of ecommerce is satisfying Digital Gaming has been existing since With running costs, only a fraction as directly make money from their customers by building trust through a long time and has been growing compared to their respective crude oil customers basis content and influencers and providing greater product rapidly recently due to the newer counterparts, EVs in shared mobility popularity allowing various platforms to variety, access to local shops, cheaper opportunities being created through are the true pinnacle of sustainability be built around them prices and a fun/ engaging shopping many innovations and future - ready societies experience Global Funding in 2021 compared to Funding in 2021, compared to $ 1.2 B Funding in 2021 , compared to $0.28B Funding in 2021 , compared to $0.12B $0.46B in 2020 $1 .3B+ $0.6B+ $0.6B+ in 2020 in 2020 in 2020 $1 .8B+ Indian Creators with 1M+ subscribers Market Size in 2020, expected to Market Size in 2020, expected to Market Size in 2020, expected to on YouTube in 2021; 3x increase from reach $2B by 2023 reach $47B by 2026 $1B+ $5B+ reach $20B by 2025 1.7K+ $2.2 B+ 2019 Internet penetration expected in rural Current monthly users , estimated to Cumulative EV sales in FY21 , declined Active internet users in 2021 ; areas by 2025 compared to 2021 reach 510M by 2023 from 0.29M in FY2020 estimated to be 900M by 2025 360M+ +0.23M 62% 622 M+ Source(s): Tracxn , PGA Labs analysis 13 Agenda ConsumerTech in India: An overview Value creation through technology Upcoming themes in ConsumerTech E - commerce 2.0 Creators’ economy Online gaming and entertainment Electric Vehicles About us 14 Utilizing technology, new - age companies in ConsumerTech are creating value through 5 value propositions Reducing market inefficiencies 1 Access to new markets and products 2 Better product - price propositions 3 Full - stack ecosystem 4 Additional capacity creation 5 15 Case study: Reducing market inefficiencies GoMechanic has reduced inefficiencies in repairing services via tech - driven approach Total funding Offering Founded US$ 62M Online garage aggregator for 2016 (Series C) automotive repairing services Key highlights Benefits for cab aggregators Business model ~480% Better customer Better experience through r evenue CAGR customer better quality cars NPS due to regular maintenance 800+ workshops in India Better partner NPS Tools and Availability & due to: Tech utilisation of data Better • Low cost partner Workshops NPS • High quality 1M+ • Faster service Customer Part supplier daily active customers Note(s) : *Original Equipment Supplier Source(s): Tracxn , PGA Labs analysis 16 Case study: Better access to markets and products HealthifyMe uses AI to drive personalized recommendations on health & fitness Total funding Offering Founded US$ 100M India’s leading digital lifestyle 2012 (Series C) modification platform Customer interacts with multiple fitness sources Key highlights Key features Separate consultations Online workout with Nutritionists / classes through One - stop shop for all online fitness Dieticians unorganised sources activities with safety & comfort of home 600+ Convenience fitness coaches Customers Instant answers, feedback and Separate classes for Manual monitoring of insights on diet plan and workouts different health - related health parametrers activities AI - based assistance ~30M+ Offers disciplined, one - stop solution towards fitness Online record of key health metrics mobile app downloads like calorie and nutrient intake Tech - based regular Online record monitoring of calorie intake Instructors & nutritionists at “Due to this disciplined approach, I’ve lost ~8kg and went back one place for holistic fitness to my normal self. Over time, I enjoy entering the food details of Customers what I have eaten and become more health conscious” 2M+ Online live and pre - recorded workout classes - HealthifyMe user monthly active users for health - related activities Source(s): Secondary research, Traxcn , Company website / apps, PGA Labs analysis 17 Case study: Better product - price propositions Lenskart leverages a 3D try - on technology to give superior customer experience, driving trials that eventually lead to higher traction Total funding Offering Founded US$ 815M Internet first brand of 2010 (Series G) eyewear Comparing SKUs and brands of Lenskart and Titan Plus Key highlights # brands across price ranges # SKUs across price ranges INR 5K+ 1172 11 styles of eyewear 9 549 5 5 508 ~80% 4 4 4 revenue CAGR 3 298 212 170 93 15 0-3K 3K-6K 6K-9K >9K 0-3K 3K-6K 6K-9K >9K ~100K+ customers monthly Titan Eyeplus Lenskart Source(s): Owler , Tracxn , Primary study, PGA Labs analysis 18 Emerging Consumer Tech themes Online gaming and Electric Vehicles Commerce 2.0 Creators’ economy entertainment (Shared mobility) • Enabling individuals to • Easy availability of • Accessibility to • Aggregating local monetize own patches and updates environmentally Reducing market inefficiencies retailers/shops on a talent/skills without a through downloadable friendly alternates for 1 single platform formal setup content mobility • Enabling distribution • Competitive intensity • Enabling access to • Cloud Gaming acts as Better access to markets and and reach to wider driving mobility wider variety of local, an alternative to discs audience through alternatives at products 2 indigenous products and cartridges online mode economical pricces • Direct - to - customer • Platforms selling • Innovation and R&D • Providing relevant Better product - price ecosystem pushing games from multiple driving improved and relatable content towards better publishers and efficiency and cost of propositions 3 through online portals margins developers batteries • Integrated platforms • Providing all products • Game launchers and • Regulatory and Govt - for content creation, and services related consoles with party push towards distribution, customer Creating a full - stack ecosystem to a vertical on a creation and chat sustained mobility 4 engagement and single platform features across categories feedback • Increased supply of • Innovating games • Increased supply / • Concepts like cloud content through targeting different availability through Additional capacity creation kitchen and influencer individuals, audiences in the alternate modes of 5 sell freelancers market transport 19 Agenda ConsumerTech in India: An overview Value creation through technology Upcoming themes in ConsumerTech E - commerce 2.0 Creators’ economy Online gaming and entertainment Electric Vehicles About us 20 Commerce 1.0 has influenced purchase behavior in structured categories primarily through fast deliveries and easy payments Online penetration is increasing more in structured categories than unstructured categories Impact on consumer behavior Online penetration by category (%, CY09 - 20) Easy and fast delivery Electronics 19.1% Increase in commerce on mobile phones Beauty & Hygiene 11.4% Trust on online payments Apparels through COD 7% 4.8% Strong penetration growth Home and Living in structured categories 0.7% CY11 CY12 CY13 CY14 CY15 CY16 CY17 CY18 CY19 CY20 Rise in transactor Grocery population Apparel Home & Living Beauty & Hygiene E-grocery Other electronics Source(s): Industry databases, Statista, PGA Labs analysis 21 Commerce 2.0 has huge headroom for growth in categories & customer demographic that cannot effectively shop with traditional online models Advantages over C ommerce 1.0 Targets Trust - based Mimicking Value Conscious unstructured selling offline buying categories behavior • Caters to ~250M • ~90% (~US$ 700B in • Harnessing the power of • Apparels, BHPC, home population in lower tier 2019) of large retail offline buying behaviour living, Jewelry, toys, etc. cities who buys low - priced market is unorganized through vernacular from can be sold and unbranded products and operates on trust and language and trust efficiently through demos familiarity and influencers Growth drivers of C ommerce 2.0 Deepening Social media Mobile P2P marketing customer wallets penetration penetration • Increased penetration into • MAU for Facebook • P2P is reducing CAC • Smartphone users cheaper and unorganized and Whatsapp are and cost to serve expected to grow from product categories which expected to reach through local 415M in FY20 to were uncommon in E - ~700M by FY25 influencers and trust - ~880M in FY25P commerce 1.0 based selling Source(s): Secondary research, Literature review, PGA Labs analysis 22 Commerce 2.0 can be primarily structured as Social Commerce and Digital Brands, with enablers that drive effective implementation of these opportunities Commerce 2.0 Social Commerce (Alternative commerce) Brand creation Digital E nablers Reselling / Enable reselling of products through other social networks Enables multiple small/ Platforms which sells their influencer - led products (of a specific brand) medium businesses to directly to the customers without go and grow online Video Enable sellers and influencers to sell through live or recorded including any middlemen shopping videos Group Enable users to purchase products as a group buying City Mall Mall91 23 Social Commerce Social Commerce targets low to mid income segment through trust - based selling of unstructured product categories Benefits of Social Commerce Social Commerce targets Low - mid income segment & unstructured categories Horizontal Ecommerce 1.0 Electronics Low - priced products in unstructured categories Vertical Ecommerce Beauty & Hygiene 1.0 Social Commerce (Group buying, Reselling ad Livestream models) Enhanced trust in Apparels online shopping Home and Living Vertical Ecommerce 1.0 (Hyperlocal) Increased access to markets for Tier 2+ population Grocery Middle / Bottom of pyramid Consumer High affluence, literate (Typically vernacular) segment 24 Social Commerce Social Commerce platforms position as low - priced, high - discounts platforms along with earning opportunities for women Founded year • 2018 Funding • US$ 183M GMV (2020) • US$ 40M • WestBridge Key investors • Matrix Partners India • Omidyar Network Commerce model • Group buying • 1M+ downloads # sellers and customers • Vernacular advertisements focusing on low priced and high discount products Brand positioning Customer engagement Note(s): 1US$ = INR 75 Source(s) : Company websites, Tracxn , Press review, Secondary research, PGA Labs analysis 25 Brand creation New - age brands with innovative value propositions are coming up to cater to the needs of evolving consumers Dairy Fresh meat Jewelry Beauty One stop online jewelry store for One stop online shop with almost all Packaged lactose free curd and sugar Presence of natural and customized every occasion types and cuts of meat free yoghurt without preservatives ingredients based on skin types Modern trade offline brand stores Brand stores with new & innovative with better offerings and packaging Packaged curd from multiple brands jewelry designs for modern wardrobe Advent of multiple brands Unorganized butchers offering Simple variants in a brand Loosely packed curd Traditional jewelery store loose meat Source(s): Secondary research, PGA Labs analysis 26 Brand creation In India, brand creation is happening across multiple sectors ranging from skin care to education via advanced robotics Founded year 2015 2014 2020 2015 2016 Funding (2021) ~US$ 294M ~US$ 60 M - ~US$ 15.2 M ~US$ 3 0M Revenue (FY20) ~US$ 6.5M ~US$ 27.6M - ~US$ 2.3 M ~US$ 4.7 M Categories • Beauty • Home improvement – • Healthcare - Sexual • Consumer Electronics - • EdTech - AR/VR Mattress etc. Wellbeing Robotics / AI Brand positioning • International skin • To provide great quality • Secure platform to • Advanced Personal • Fun platform for kids care products sleep affordable discuss sexual issues Robot for kids to learn USP • Offers cruelty free • 100 night trail • Trusted advisors along • Niche focus • Engaging, fun & and vegan products • Risk free returns with effective medicines • Child - Safe educational content • Customizable mattress • Adaptive to situation Product Source(s): Tracxn , Entrackr , Company website, PGA Labs analysis 27 Digital Enablers Digital Enablers are making the unorganized market accessible to consumers online Benefits of Digital Enablers to customers Digital Enablers are helping unorganized stores sell customers online Digital Enablers Availability of high variety of products Service Aggregators Service Stores - Restaurants Quicker Delivery Digital enablers Horizontal Retail Brands Ecommerce Digital Enablers Makes access to local Retail Shops products easier Store Organized Unorganized Format 28 Digital Enablers Digital Enablers are providing stores with their own brand identity and access to customer data Services Provided by Digital Enablers to Retailers Benefits of Digital Enablers to Retailers Horizontal Service Digital Enablers Ecommerce Aggregators Reaching wider consumers Store Discovery Increased Store Visibility P roduct Discovery O rder Intimation Lower Commissions L ast Mile Delivery Customer Insights Customer Data 29 Investments in Commerce 2.0 brands have increased over the past few years and has reached ~US$ 666M in 2021 Investment in social commerce platforms has been growing Amount Revenue with rising adoption of these platforms Target Year Investors (US$ M) (US$) 48.2M SoftBank Vision Fund, Prosus, Investment trend in E - commerce 2.0 companies 2021 300 (FY20) Venture Highway, Facebook ( US$ M, 2016 - 21) 666 3.6K Chiratae Ventures, Venture 2019 10.6 (FY19) Highway, Elevation capital Major funding round was US$ 546 300M for Meesho 424K 2021 100 Tiger Global Management (FY19) 2020 8 - Accel, Shunwei Capital 320 563 315 Elevation Capital, Jungle Ventures, 2021 11 - 249 Accel, WaterBridge Ventures 156 ChrysCapital, PwC, J Sagar 92.7M 117 145 2021 50 130 Associates, Quillon (FY19) 40 31 226 Elevation Capital, Stride Ventures, 14.8M 159 132 2021 21 105 98 103 India Quotient, A91 partners (FY20) Verlinvest, Sequoia Capital, 28M 2016 2017 2018 2019 2020 2021 2020 25.1 redwood Trust (FY20) Internet-first brands Social Commerce 15.8M Sequoia Capital, Fireside Ventures, 2020 18.2 #rounds 2016 2017 2018 2019 2020 2021 (FY20) Stellaris Venture Partners Social 38 23 17 36 19 16 Commerce 2.5M Symphony Asia, Lightbox, Alteria Internet - first 2020 12.5 65 75 78 124 76 24 (FY19) Capital brands Source(s) : Tracxn , Secondary research, PGA Labs analysis 30 Ecommerce 2.0 players have developed various capabilities to remain competitive in the segment Social Commerce Brand creation Digital enablers Low cost for customer acquisition Creating Full Stack Ecosystem Innovation in consumer retail WMall has reduced CAC and customer cost by: GlobalBees has become one of the prominent players L ove Local is one of the prominent hyperlocal to bring innovation in D2C consumer retail by: delivery firms : • Trust based selling and selling through influencers • Tie - ups with many retailers to provide wider reach • Acquiring rapidly - growing brands in the digital - • Targeting Tier 2+ cities first space, building a solid portfolio of these • Provide them with a full suite solution for digitizing brands and scaling their products . customer relationships, access business data & manage operations Strong ecosystem partnerships Deep investments in tech to build scalability Content backed by technology Curefoods has become highly standardised, efficient, LBB has managed to grow very well through: DealShare is one of the major group buying platform and hygienic kitchen network across the nation by: due to: • Engaging well with the audience through content and provide them with variety of options • Tie - ups with a large number of brands , • Acquisition of 10+ D2C food brands like - CakeZone , • Provide personalized recommendations and manufacturers and suppliers MasalaBox , Paratha Box, etc. content to each user according to his / her interests • Leveraging market expertise & advanced technology • Sourcing deep inside the supply chain to lower cost to elevate & amplify customer experience 31 Innovative models like GlobalBees are emerging, that offer brand acceleration by acquiring D2C brands and scaling them with data driven marketing & rebranding Total funding Offering Founded US$ 186M Acquiring D2C brands and 2021 (Series B) scaling them up Key highlights Value Proposition Business model • GB - type players act as ‘incubators’ offering capital • Focusses on the sports, auto - ancillaries, food & investment, ecosystem accessibility → take the brand nutrition, general merchandize, etc. i.e., categories 15+ ‘global’ on day - 1 which are immune to founder - led IP or constant - innovation • GB is building a strong practitioner - led ecosystem → Acquisitions Completed operations, exports, payments, accounting, etc. • Brand acceleration - operations - intensive i.e., raw - material • Key selection criteria for acquisition: growth, culture, operational expertise, etc. • Sourcing, packaging, logistics/distribution, exports, customer reach, etc. against Thrasio - kind model with • GB offers to make an investment of 40% of the size of data - driven marketing, rebranding, etc. the business and promises to improve the revenue by 2x ~100 • Partnering with GB provides seller access to GB’s Employee count technology - stack, which helps the brand/SMBs overcome technical glitches faced working with marketplaces like Amazon/Flipkart • GB offers a 1 - month trial period for the brand to gauge “ I am aware of partnership of GlobalBees and The Better Home, if the sales are improving as per the promise before and that it had a tremendous growth of 150 million in last 3 closing the final deal 10+ months and it’s impressive to see that it is receiving a lot of investment and is partnering with big companies” Acquisitions in Immediate - Seller, Amazon Pipeline Source(s): Secondary research, Traxcn , Company website / apps, PGA Labs analysis 32 Key takeaways Commerce 1.0 while influenced consumer behavior in structured categories, it has paved the emergence of Commerce 2.0 with a large headroom for growth across categories & customer 1 demographic, that cannot effectively shop online with traditional online models Commerce 2.0 opportunity can be structured under 2 headers: ‘Social Commerce’ that targets low to mid income segment through trust - based sales and ‘Digital Brands’ with innovative value 2 propositions catering to evolving customer needs, with enablers driving effective implementation of these opportunities Investments in Commerce 2.0 brands has grown to ~$665M in in 2021, driven by rising adoption of 3 these platforms by consumers especially in interior parts of India These opportunities have led to emergence of Digital Enablers for discovery, delivery and logistical 4 support to unorganized stores and sellers to reach their customers through online channels Players are innovating and developing capabilities such ecosystem partnerships, scalable service 5 models, content - led commerce, and others to remain competitive in their respective segments 33 Agenda ConsumerTech in India: An overview Value creation through technology Upcoming themes in ConsumerTech E - commerce 2.0 Creators’ economy Online gaming and entertainment Electric Vehicles About us 34 Creators Economy is ‘ enterprisation ’ of individuals & is led by 4 key growth drivers Key drivers for Creator’s Economy Elements Constituting Creator’s Economy Reduction in hurdles of content Creators Economy creation People become businesses and directly make money from their audience and fans basis popularity Positive feedback loops from success of other creators Internet Entrepreneurs Individuality Ownership Normalization of independent work since pandemic Individuals who are Finds audiences, creates Take ownership of good at creating fans, basis skills, talents & content, keep the authentic content in ideas to become brands distribution of content their respective niches themselves with themselves Internet - First Generation attracted to content creation 35 Content creators are witnessing positive responses due to the online consumption during the COVID lockdown Tools • Hosts 30 - 60 mins long live / pre - recorded lectures Online K 12 • Earns through fees from selling different courses • Good infrastructure has been established through presence of various platforms for stakeholders Teacher • Opportunity for a global platform to help market teachers in India and abroad • Hosts 120 - 180 mins long live - streams Game • Earns through Competitions, Brand Deals & Ads Streamers • Focus has shifted from gaming to engagement while streaming as they make bulk of the earnings • Emergence of gamer centric platforms & tools can provide further boost to game streaming Online • Hosts 30 - 60 mins long live / pre - recorded sessions Fitness • Earns through live group training ,personal training & nutrition tips • Lack of marketplace platforms to connect fitness trainers in India Trainer • Content ranging from 5 - mins videos to live streams Mega • Earns through Ads, Brand Deals, Shows, Memberships, Own Merchandise • Tremendous growth in subscribers , since lockdown Influencer • Opportunity to manage end to end operations through providing SaaS 36 Five major business models arise throughout the value chain of creators’ lifecycle Search Potential Content Creation Content Distribution Direct Monetization Building Community Opportunities Engages followers regularly to build Hires management to A udience consumes manage his deals and look a community leverages them to D istributing the content & make an for further opportunities obtain offers for brand deals opinion on the same Followers Platforms Makes content C reator available to the intended audience through its platform Ideates the Management content and ways Consumers Community Basis content, creator builds Providing traffic analysis, to executes it fanbase which are ready to pay user engagement data to the creator in various forms and many other services Assist in execution and to understand consumer enhancement of the Tools content Software to create better content Vertical Marketplaces Patronage Platforms SAAS Tools Fan Platforms Creator Support Create member groups to Such tools simplify and Enables creator to list their Platforms offering support to Fans can pay to the creators engage & connect more enhance the content content and reach a wide set of creators through education , directly based on their love with the audience creation process audience management etc. for the creator 37 Market landscape of various players in creators ’ economy (1/2) Creator SaaS Tools Marketplaces/ Discovery - led Global India Global India Knowledge Creators Passion Creators Lifestyle Creators Celebrities Health & Fitness Instructors Gamers 38 Market landscape of various players in creators ’ economy (2/2) Patronage Platforms Fan/Community Platforms Support (Educate / Train) Global India Global India Global India 39 Opportunities across creators’ economy segments (1/3) Knowledge Passion Lifesty le Large number of creators in the Mid - tier creators struggling to 40 - 50 K teachers with >100 K space due to low barriers to entry earn ; Unproven consumer spending followers, lack of market depth Observations Creators monetizing through Mid - tail creators need to Social Capital can be utilized brand deals , affiliate marketing monetize through value - adding better by top - tier creators courses Top Tier of creato Mid rs Low Creation of a global product Enabling commerce through Creators can utilize social capital through differentiated product creators - Live streaming products or through platform associations Opportunities offering & targeting specific facilitate logistics for their or creating own value - based vericals like - Personal finance merchandise course 40 Opportunities across creators’ economy segments (2/3) Celebrities Health & Fitness Gaming Low propensity to pay , Low Game streaming has boomed in No start - ups identified yet ; Need ARPU’s vis - à - vis celebrity India making it one of the highest Observations expectations and Low frequency for discovery of fitness trainers volume creating segment of uses are concerns Top Tier Mid Low While discovery is youtube - led , Potential opportunity for start - ups Marketplace building opportunity various tools help creators monetize in the space with exclusive given robust supply in India contact to celebrities Opportunities Full stack systems like YogaMe Influencer / Micro influencer - led Opportunity for B2B service by available for top - tier instructors, marketing presents big opportunity providing start - ups access to however lack of tools for others celebrities for promotions 41 Opportunities across creators’ economy segments (3/3) Patronage Platforms Fan Community S upp ort (EdTech) Positive feedback loops enticing a lot of youngsters to be creators’ Limited global c ompetition and Consumer’s propensity to O bservations greater market depth as high pay for paid content is low Propensity to pay lower fanbase amongst the young creators Top Tier Mid Low Building a community platform given the market Possibility of a freemium model in depth Opportunities Provide additional services untapped creator segments Building a community to the existing benefit to tap platform given the market into deeper revenue streams depth 42 In US, Teachable has seen 4x growth in 1 year with 1L+ creators and 1.5L+ new courses Offering Founded Total funding Cloud based course creation 2013 ~US$ 15.2M platform Key highlights Teachable’s GMV growth Monetizing skillset by providing freedom to creators GMV • Deciding the course (US$ M) 100K+ Skillset content based on skillset creators ~ 4x increase • Structure, length and US$ 400M+ Designing format of creator’s earned by creators choice in 2020 1000 • Creator has pricing power ~150K Publishing • Language flexibility on new courses launched in 2020 pre - defined landing page templates 250 • Scalable courses with 2019 2020 easy student 37M+ Viewers management Revenue (US$) students enrolled • Increased reach 21M 25M across the globe Source(s) : Tracxn , Company website, Secondary research, PGA Labs analysis 43 Similarly in India & SEA, Teachmint has driven digitization of teachers at scale Total funding Offering Founded ~US$ 118M Tuition Class Management 2020 (Series B) Software Teachers face multiple issues to conduct activities Key highlights Key Services Inferior recording & M anual Attendance streaming quality through registers 1M+ Easy to use software providing all solutions at a single place teachers Convenience Teachers Scheduling multiple Automated routine tasks & enables Monitoring & meetings & inviting sharing of resources at a single place reminding fee students payment manually Tech Based 4M+ Management Offers one - stop solution towards teaching Access to a large community of classrooms teachers & students facilitating further information sharing Superior video quality at lower Community bandwidth enabling quality live Learning streaming & recording A utomated attendance, fee Facilitates recording , uploading & reminders & class scheduling 5K+ selling of self - created course through Teachers Assistance in selling self - created it‘s network Brand building cities online courses through student leads & marketing Source(s) : Tracxn , Company website, Secondary research, PGA Labs analysis 44 Key takeways Creators Economy is effectively the ‘ enterprisation ’ of individuals, enabling creators to monetize their skills / talents without the need for formal training or setup – driven by mobile - first consumption, 1 feedback loops and reduced hurdles in content creation Various Content creators like Online K 12 Teacher, Game Streamers, Online Fitness Trainer & Mega Influencers are receiving positive responses due to increased online consumption during COVID 2 lockdowns Five major business models arise throughout the value chain of creator’s lifestyle – SaaS Tools, 3 Vertical Marketplace, Patronage platforms, Fan platforms, Creator support These models have led to creation of new opportunities across segments, including creators across Knowledge, Passion, Lifestyle, Celebrities, Health & Fitness, Gaming, Patronage Platforms, Fan 4 Community, and Education 45 Agenda ConsumerTech in India: An overview Value creation through technology Upcoming themes in ConsumerTech E - commerce 2.0 Creators’ economy Online gaming and entertainment Electric Vehicles About us 46 Online gaming and entertainment in India can be a US$ 2B opportunity by 2023 driven by 5 major growth drivers Real money gaming (RMG) is expected to grow at CAGR of Growth drivers of Online entertainment & Gaming 27% to reach US$ 1.6B market size by 2023 Online gaming revenue (US$ M) • Greater than 50% of Indian population is CAGR Young India under the age of 30 years 2019 - 23 25% 2,085 • Number of internet users expected to Higher internet 230 2 6% reach ~830 M by 2022 penetration 300 15% • Increase in availability of content / games Content in vernacular in local languages language 1,025 866 106 186 93 • Digital payment users are expected to 2 7% 1,555 Increase in digital reach ~300M users in 2022 from 100M 173 payment adoption in 2019 733 600 • Availability to traditional games (rummy / Round the clock ludo) 24/7 without need for people to availability gather at one place 2019 2020 2023P Real money gaming Casual gaming Esports Source(s): FICCI, PGA Labs analysis 47 Online gaming is composed of real money gaming, casual gaming, esports and subscription based pay to play games/ cloud gaming Online gaming Real money gaming Casual gaming (RMG) C loud Play to earn E - sports Other casual Trivia Games / Online fantasy Live Interactive Gaming MMORPG games Card games games Contests sports (OFS) G aming • Video game • Subscription • Enables users to • Story driven tournaments, • Participants • Participants • Participants based games, • These games • These include all use their skill of online role typically played assemble use digital play games where include apps other categories gaming to earn playing video between imaginary or cards to live with other participants trivia games / of casual games rewards with real games with professional virtual teams compete competitors pay a monthly contests with a including board world value. many players gamers, and the of real players among and earn subscription chance to win games, sports, • Built on a participating companies of professional themselves money fee to play cash action, arcade, blockchain and simultaneously involved in sports while games as and strategy etc. enables people to developing, interacting when they hold unique game organizing, and want assets which are propagating trade - able for value them Note(s): MMORPG – Massively multiplayer online role playing game is a game genre that allows thousands to play at the same time Source(s): PGA Labs analysis 48 Market Landscape of Online gaming and entertainment C loud Real money gaming(RMG) E - sports Casual gaming Gaming Online Live FPS and Board / Trivia games Sports and Fantasy Card games interactive MMORPG Arcade Battle Royale Puzzle games / contests Racing Sports gaming Kids and Action Adventure Strategy RPG VR Educational Note(s): MMORPG – Massively multiplayer online role playing game is a game genre that allows thousands to play at the same time 49 Market Landscape of various business models in online gaming and entertainment Developer Publisher Distributer Gaming Utility / SaaS • Company or individual(s) who • Large game studios which • Distributor or marketplaces are • S upport that enables better reach create the game or provide promote and market the game large buying and ordering for game developers and infrastructure to create the game • Own the license platforms amplifies user experience of consumers 50 Popularity of gaming is on the rise among Indian audience, however engagement time is still less than half as compared to US th Gaming represents 1/5 of time spent by Indian users on Gamers in India only spend 290 mins per month vs. 1290 mins entertainment and media spent by Chinese gamers Average time spent on gaming apps Time spent on mobile devices in India (M Hours, 2019) (mins per visitor per month, 2019) 1,290 Social Media 4,684 Entertainment 3,125 1,100 Retail 1,122 News/Information 821 713 Games 650 662 Financial services 290 Time spent i.e. engagement increased by 21% during lockdown Search/Navigation 194 290 Travel 78 Sports 67 Education 40 Source(s): FICCI, ComScore, Press releases, PGA Labs analysis 51 Lockdown has proved to be a boon for casual and card - based gaming in India, led to increase in users (2 - 3x), user sessions and engagement time (40 - 50%) ‘Ludo’ and ‘rummy’ search on Google surged to Casual gaming and ‘card - based’ games companies have seen ~5x and 2x respectively post lockdown (Mar 2020) 40 - 50% surge in engagement post lockdown Google keyword search trend • 2.5x growth in revenue • Daily time spent increased to 45 mins from 25 mins 100% • DAU grew by 3.4x to 51M 80% • 3x increase in game sessions • 30% increase in daily active users 60% • 2x increase in user base • 50% increase in engagement time 40% 20% • 100% increase in new registrations • User acquisition cost is down by 40% 0% 05 05 05 05 05 05 05 Jul 05 05 05 25 • Customer acquisition cost reduced by 50% Jan Feb Mar Apr May Jun Aug Sep Oct Oct • Engagement time on the platform increase by 70% to 3 hours Ludo Rummy Poker Dream11 Note(s): Growth in revenue and engagement for individual company is benchmarked against Pre - Covid period Source(s): Press releases, PGA Labs analysis 52 For instance, Tamasha enables users to play games with celebrities and other popular individuals Total funding Offering Founded US$ 3.3M Creator led live social gaming 2020 ( Pre - Series A ) platform Key highlights Proposition to segments Tech enabled business model Live Stream Community monetizes 200K+ Host, interact & through RMG, virtual gifts & engage Build & Live Chat paid interactions GameShows integrate Prize Distribution Creators Game Transaction Virtual Developer Players 2 M+ Gifting Layer Gameplays Tamasha Tamasha Wrapper Ecosystem 4M+ Minutes of live streaming Game developers build, Communities interact, publish & monetise games engage & express using on Tamasha social tools 53 Play Simple offers engaged platform that has been able to monetize at scale Founded Total Funding Offering 2014 US$ 4.5M Casual Game Developer Key highlights Revenue growth Key Services • The gaming company generates its revenues Popular casual game titles built in - house primarily through the sale of advertising space and 7M+ with tweaks that enhance engagement and application income generated through the sale of retention digital content & subscriptions users Promote cross - promotion of users from Play Simple financials (US$) one game to another – retaining users 330 within the PlaySimple ecosystem 40%+ 286 female audience Highly engaged platform offered to advertisers – proprietary tech at play to enhance ad serving and monetization 108 103 PlaySimple offers five games: 9 38 35 - 4.7 27 • Daily themed crossword titles - 4.05 • Word trip • Crossward Jam Revenue from Total expenses Profit/Loss • Word Wars operations • Solitare FY18 FY19 FY20 $360M acquired by MTG Source(s) : Tracxn , Company website, Secondary research, PGA Labs analysis 54