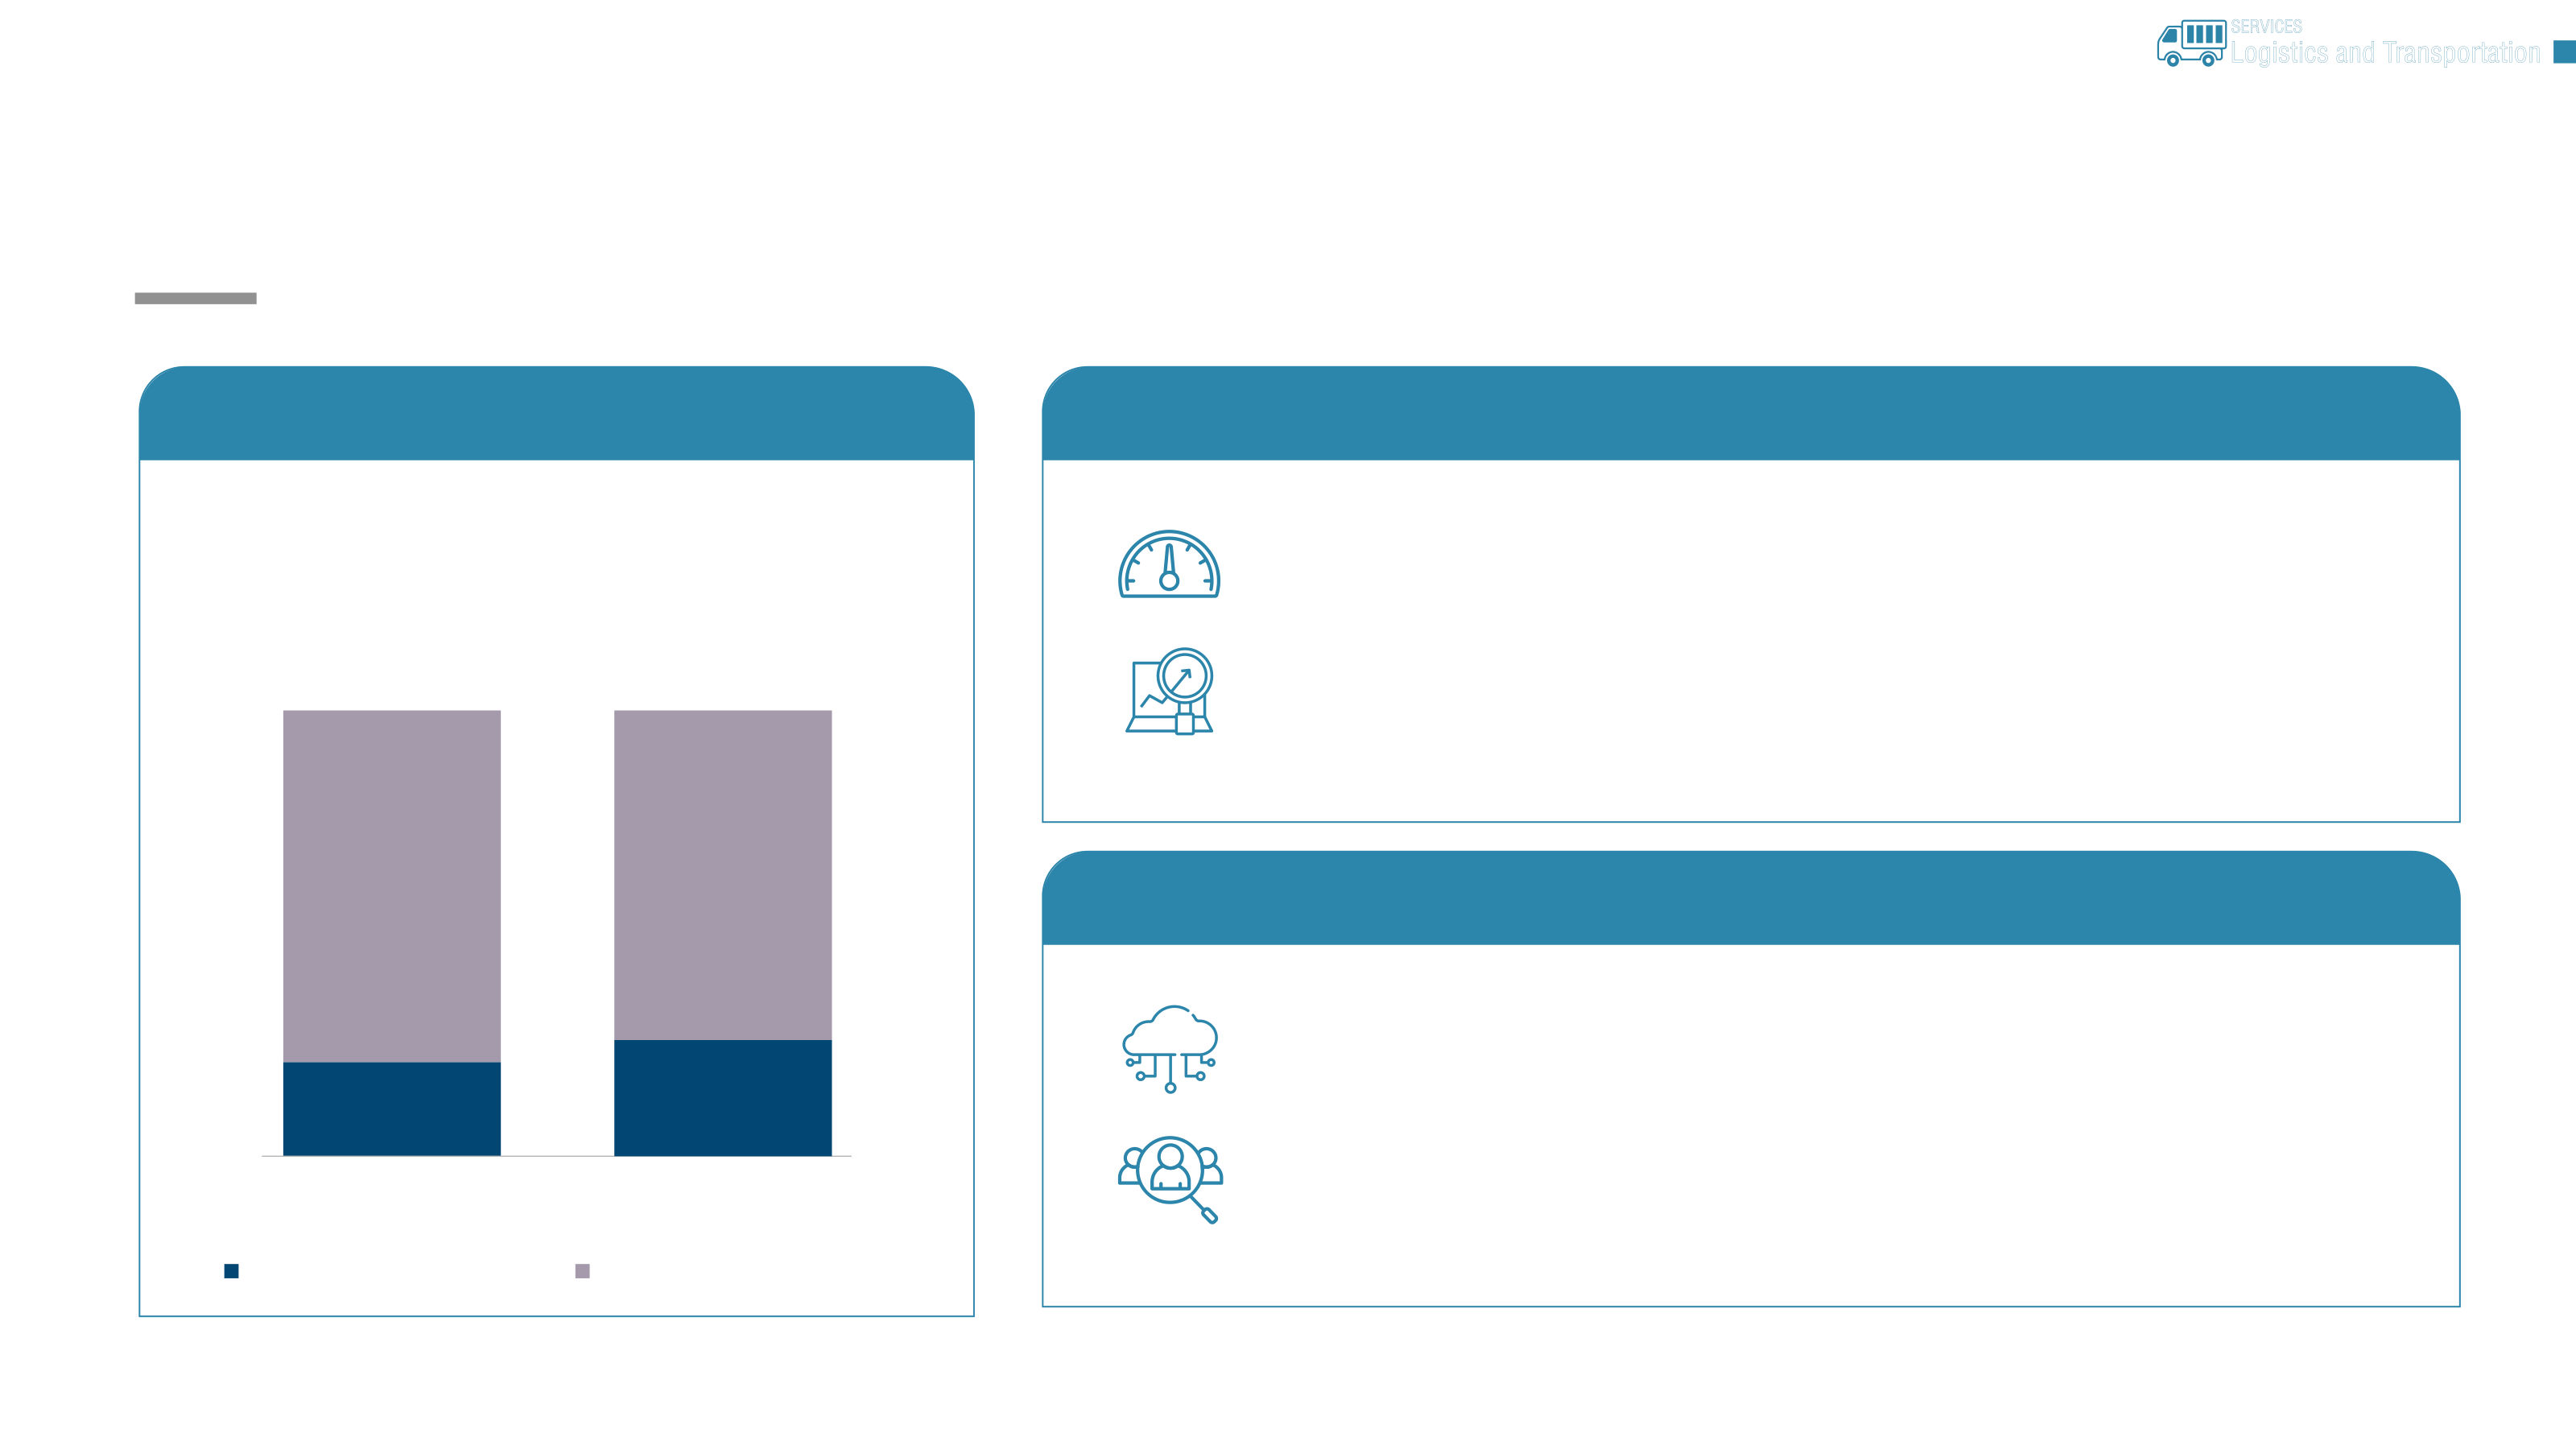
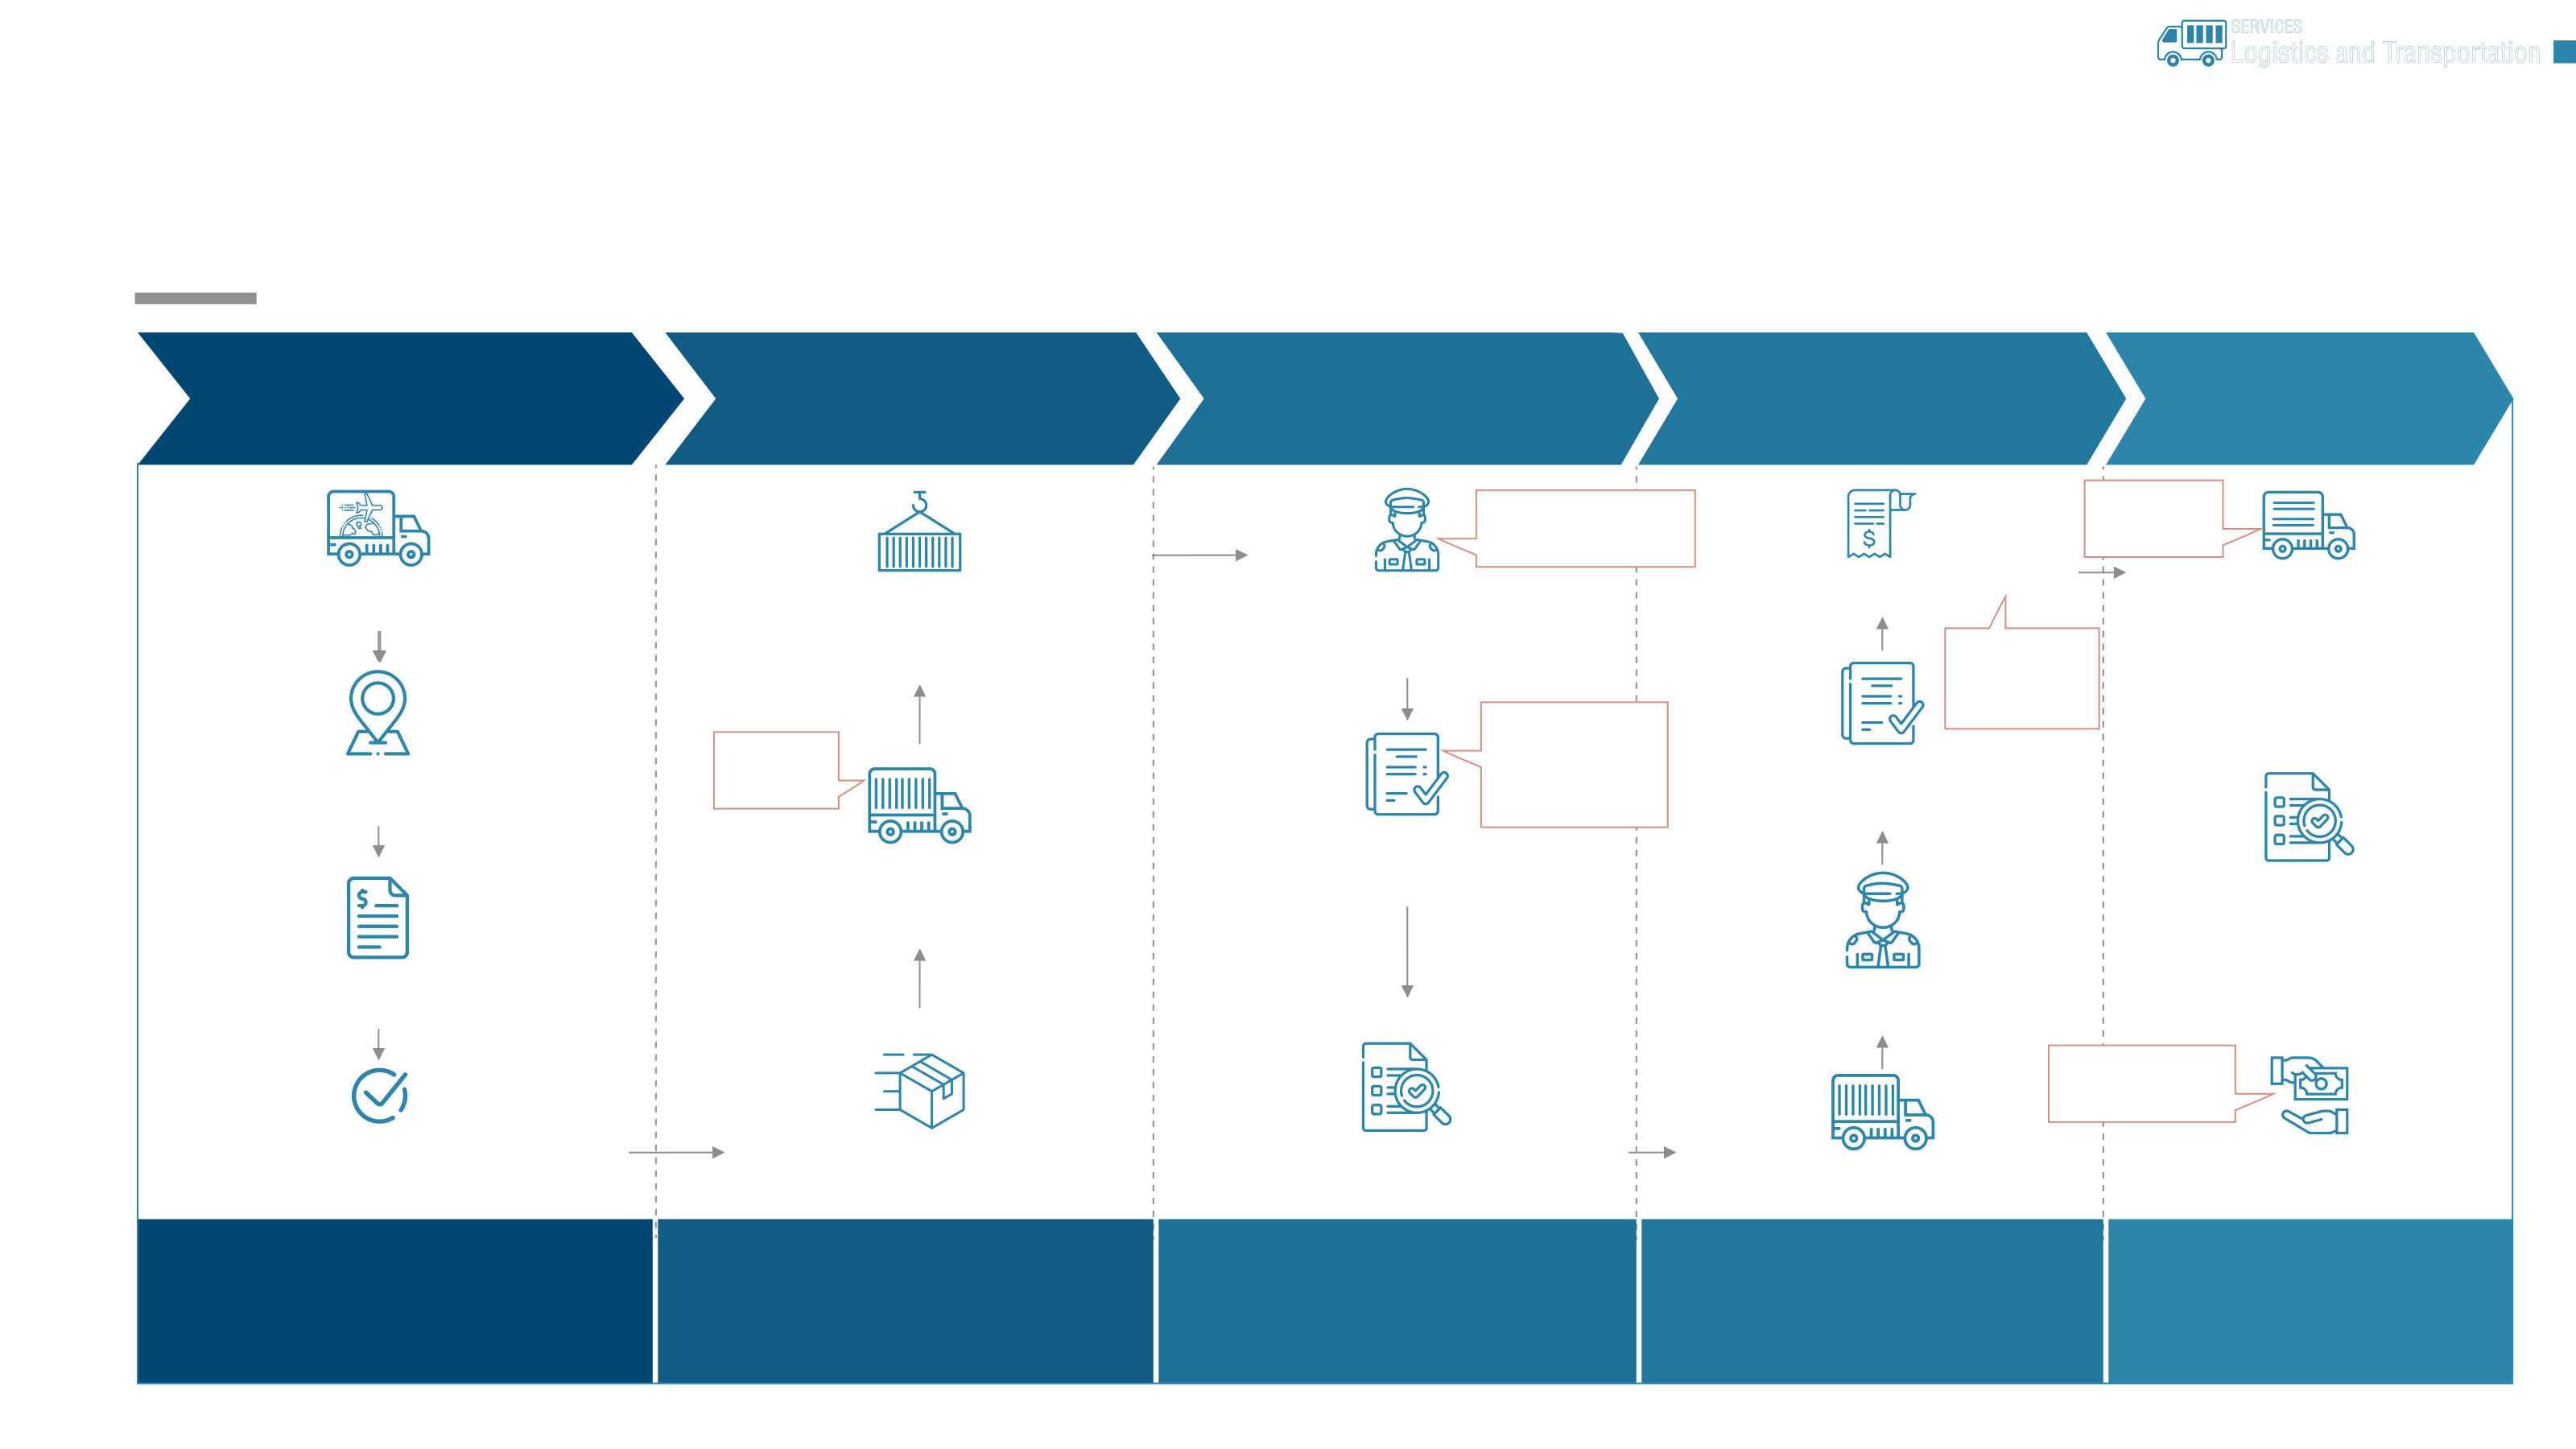
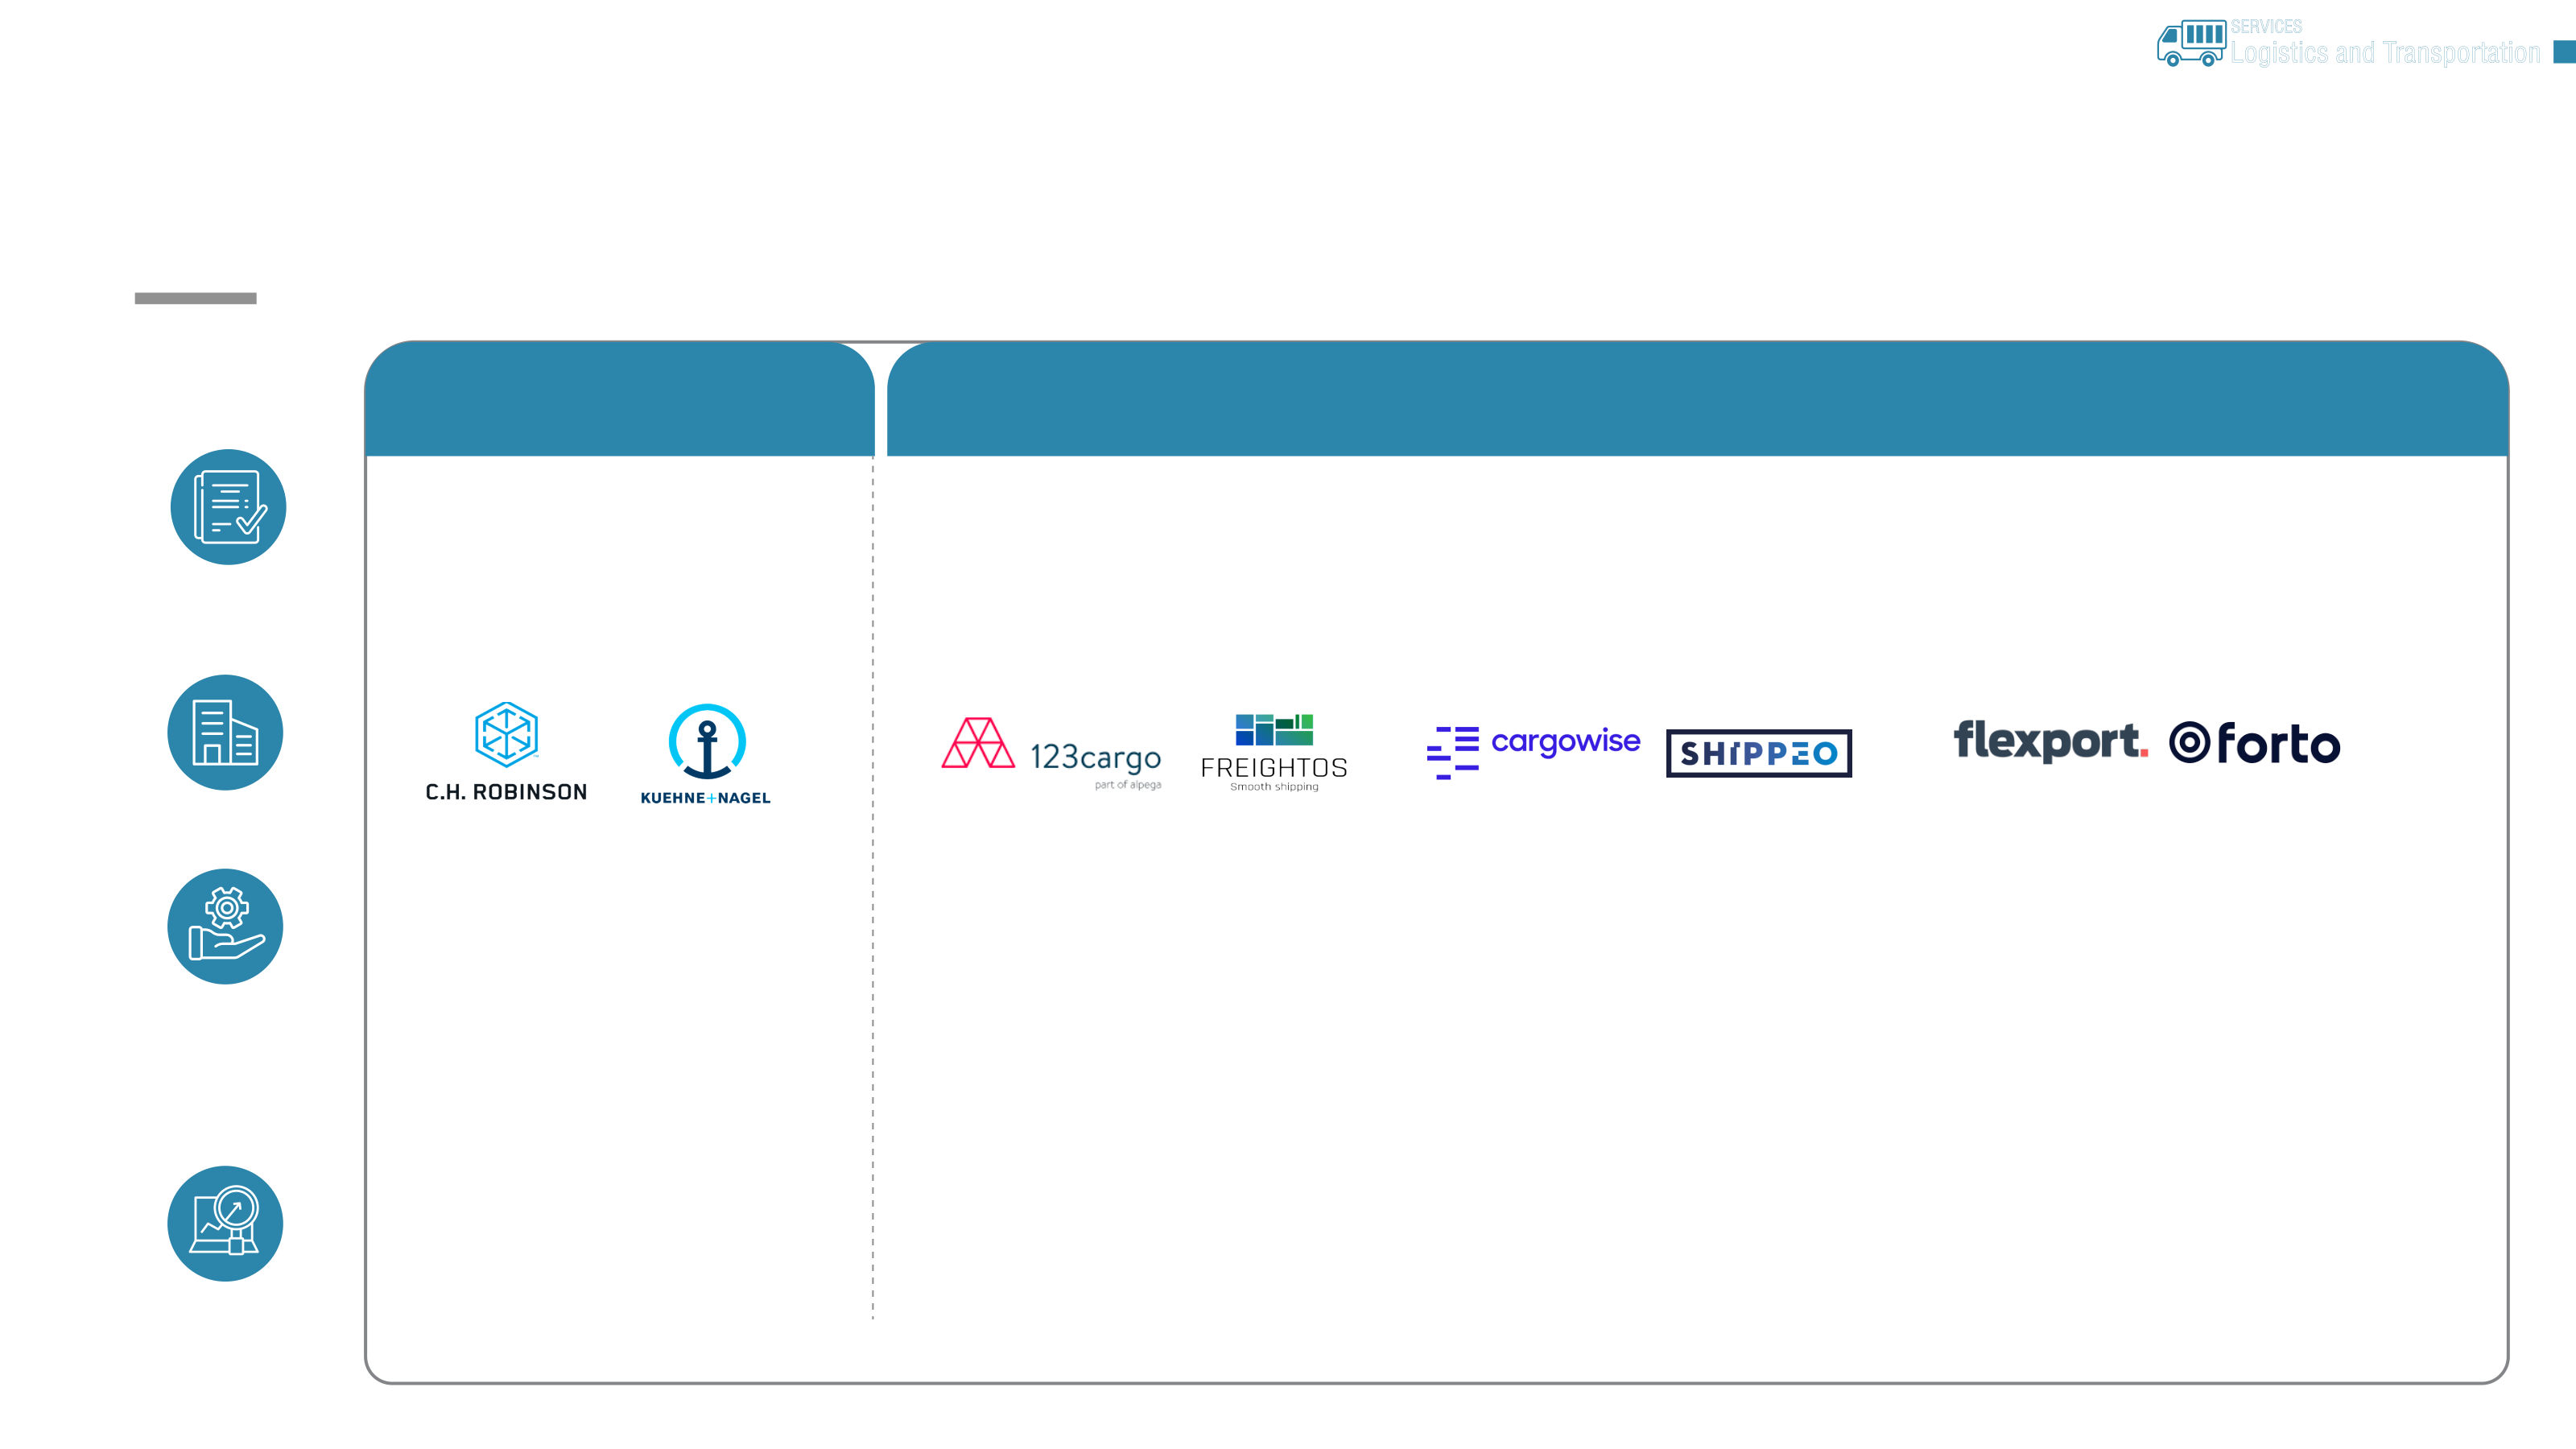
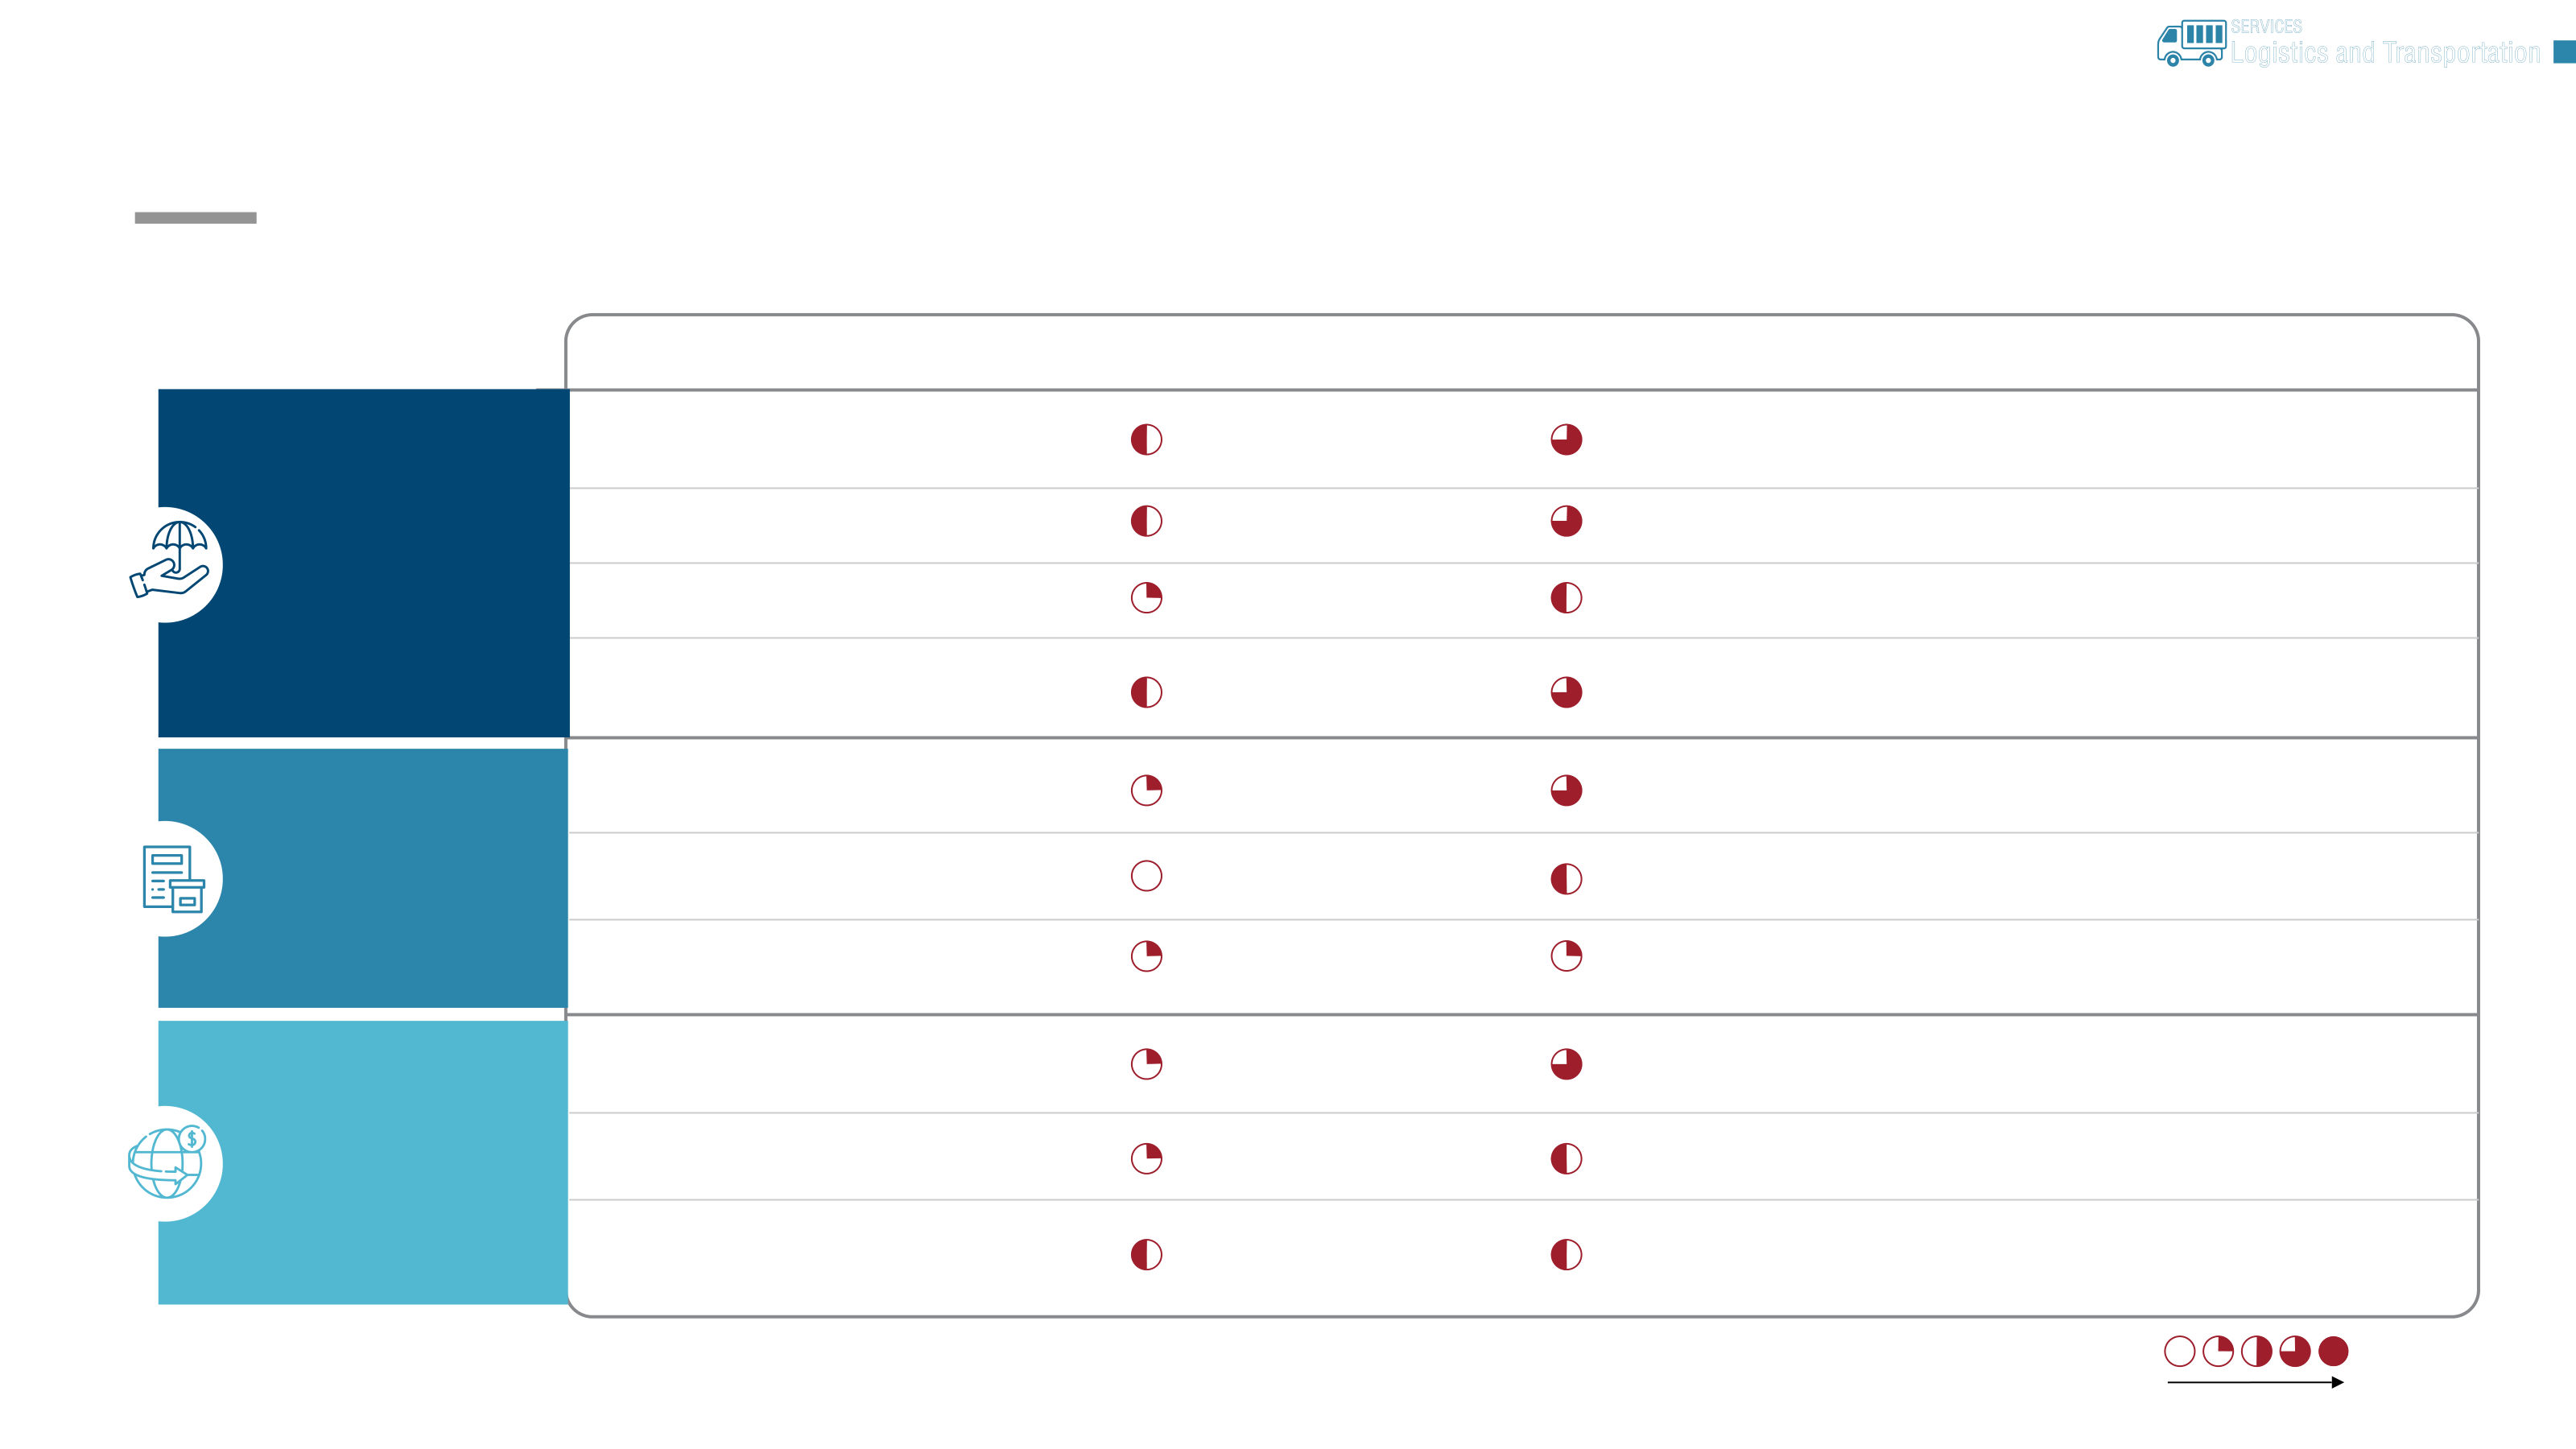
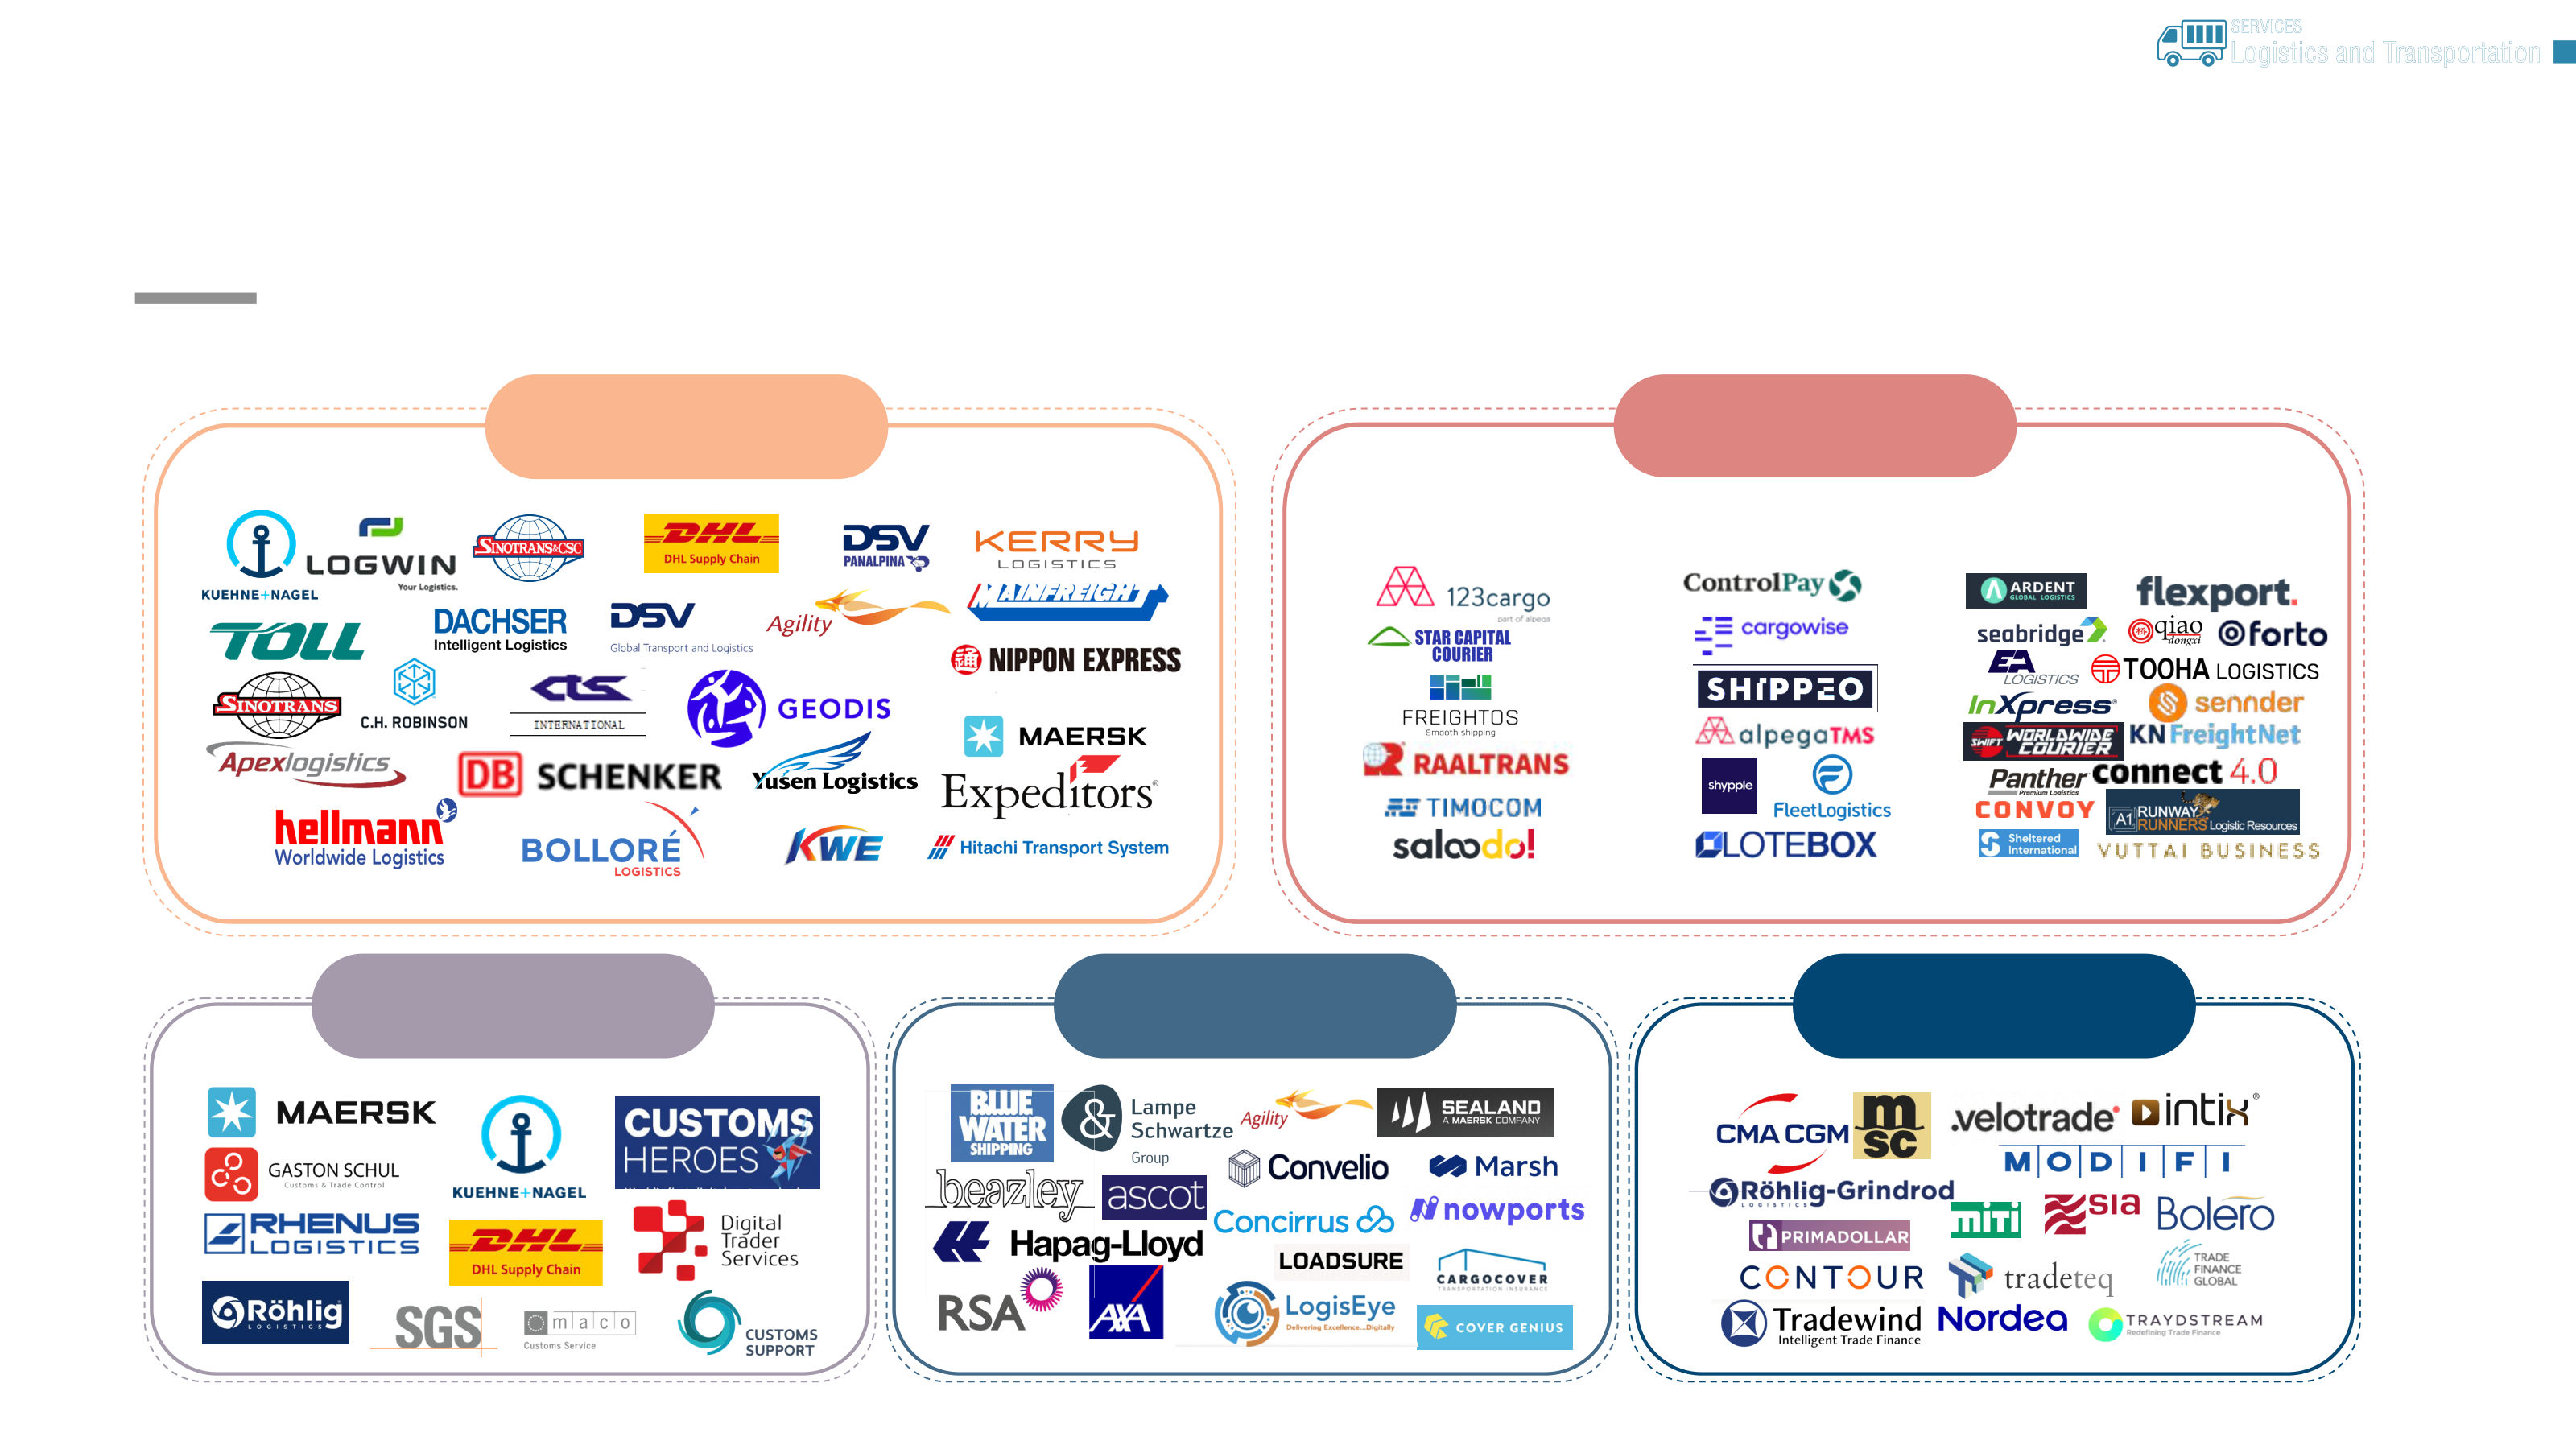
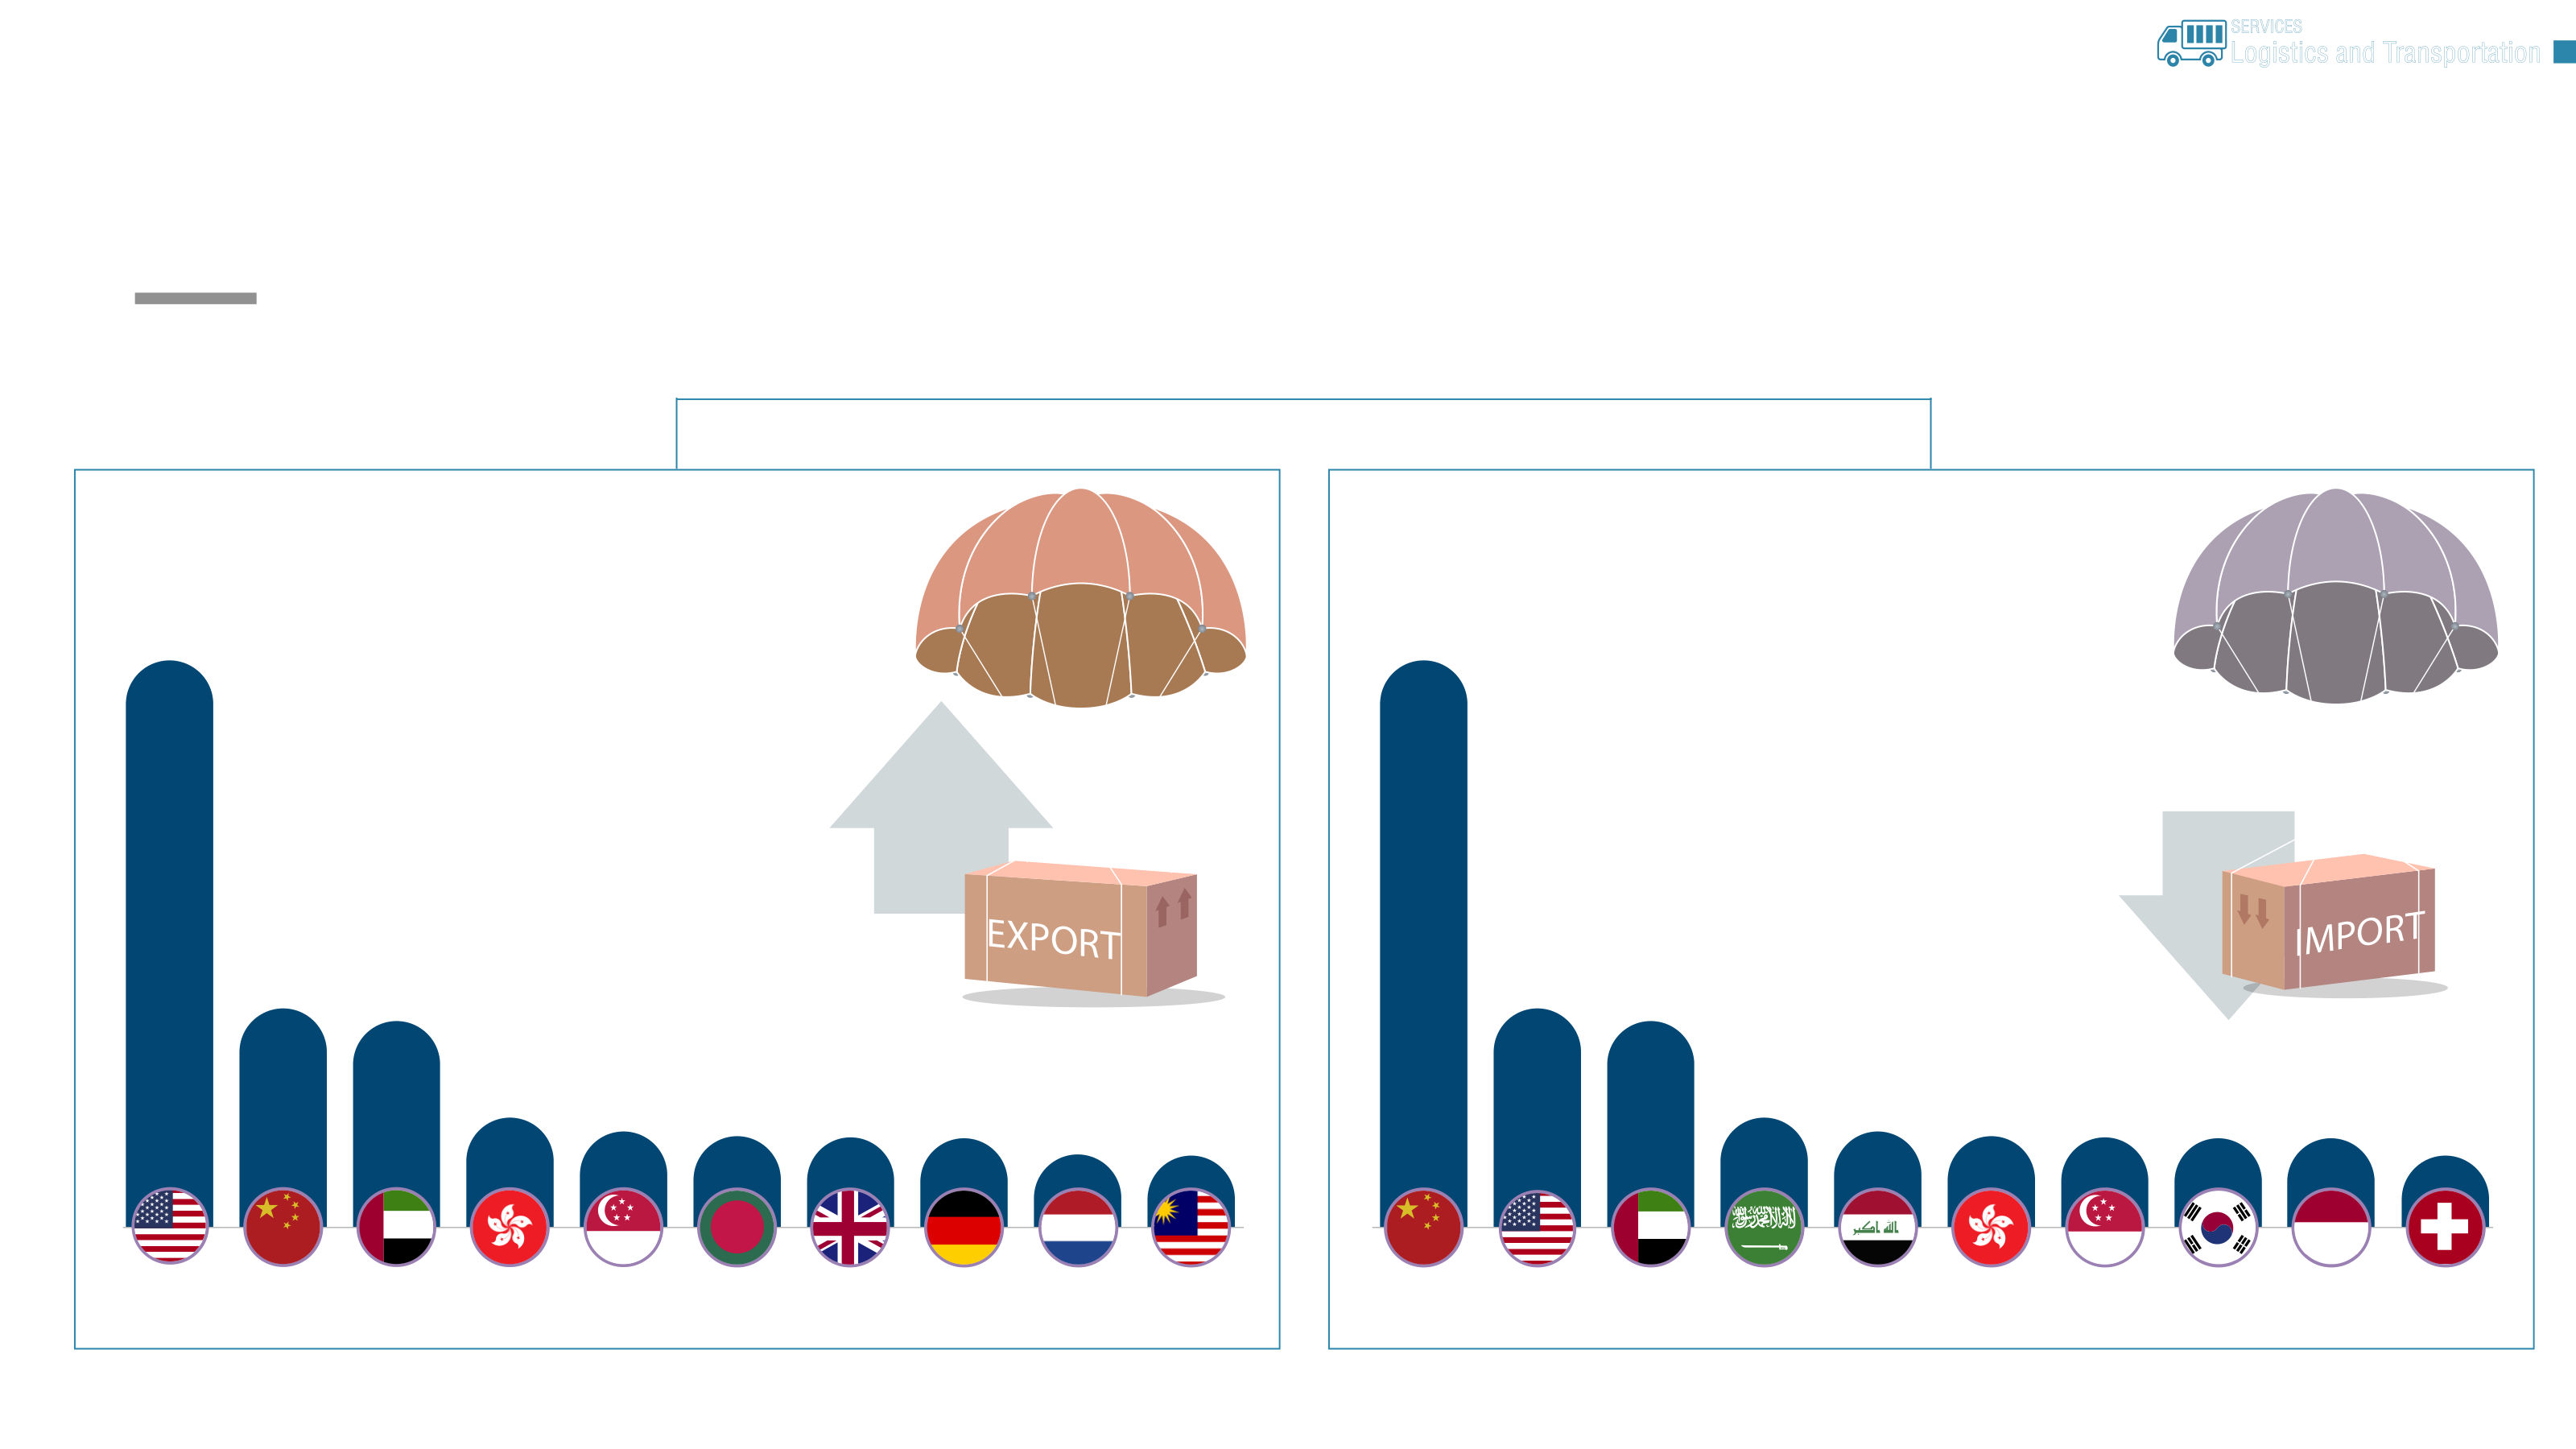
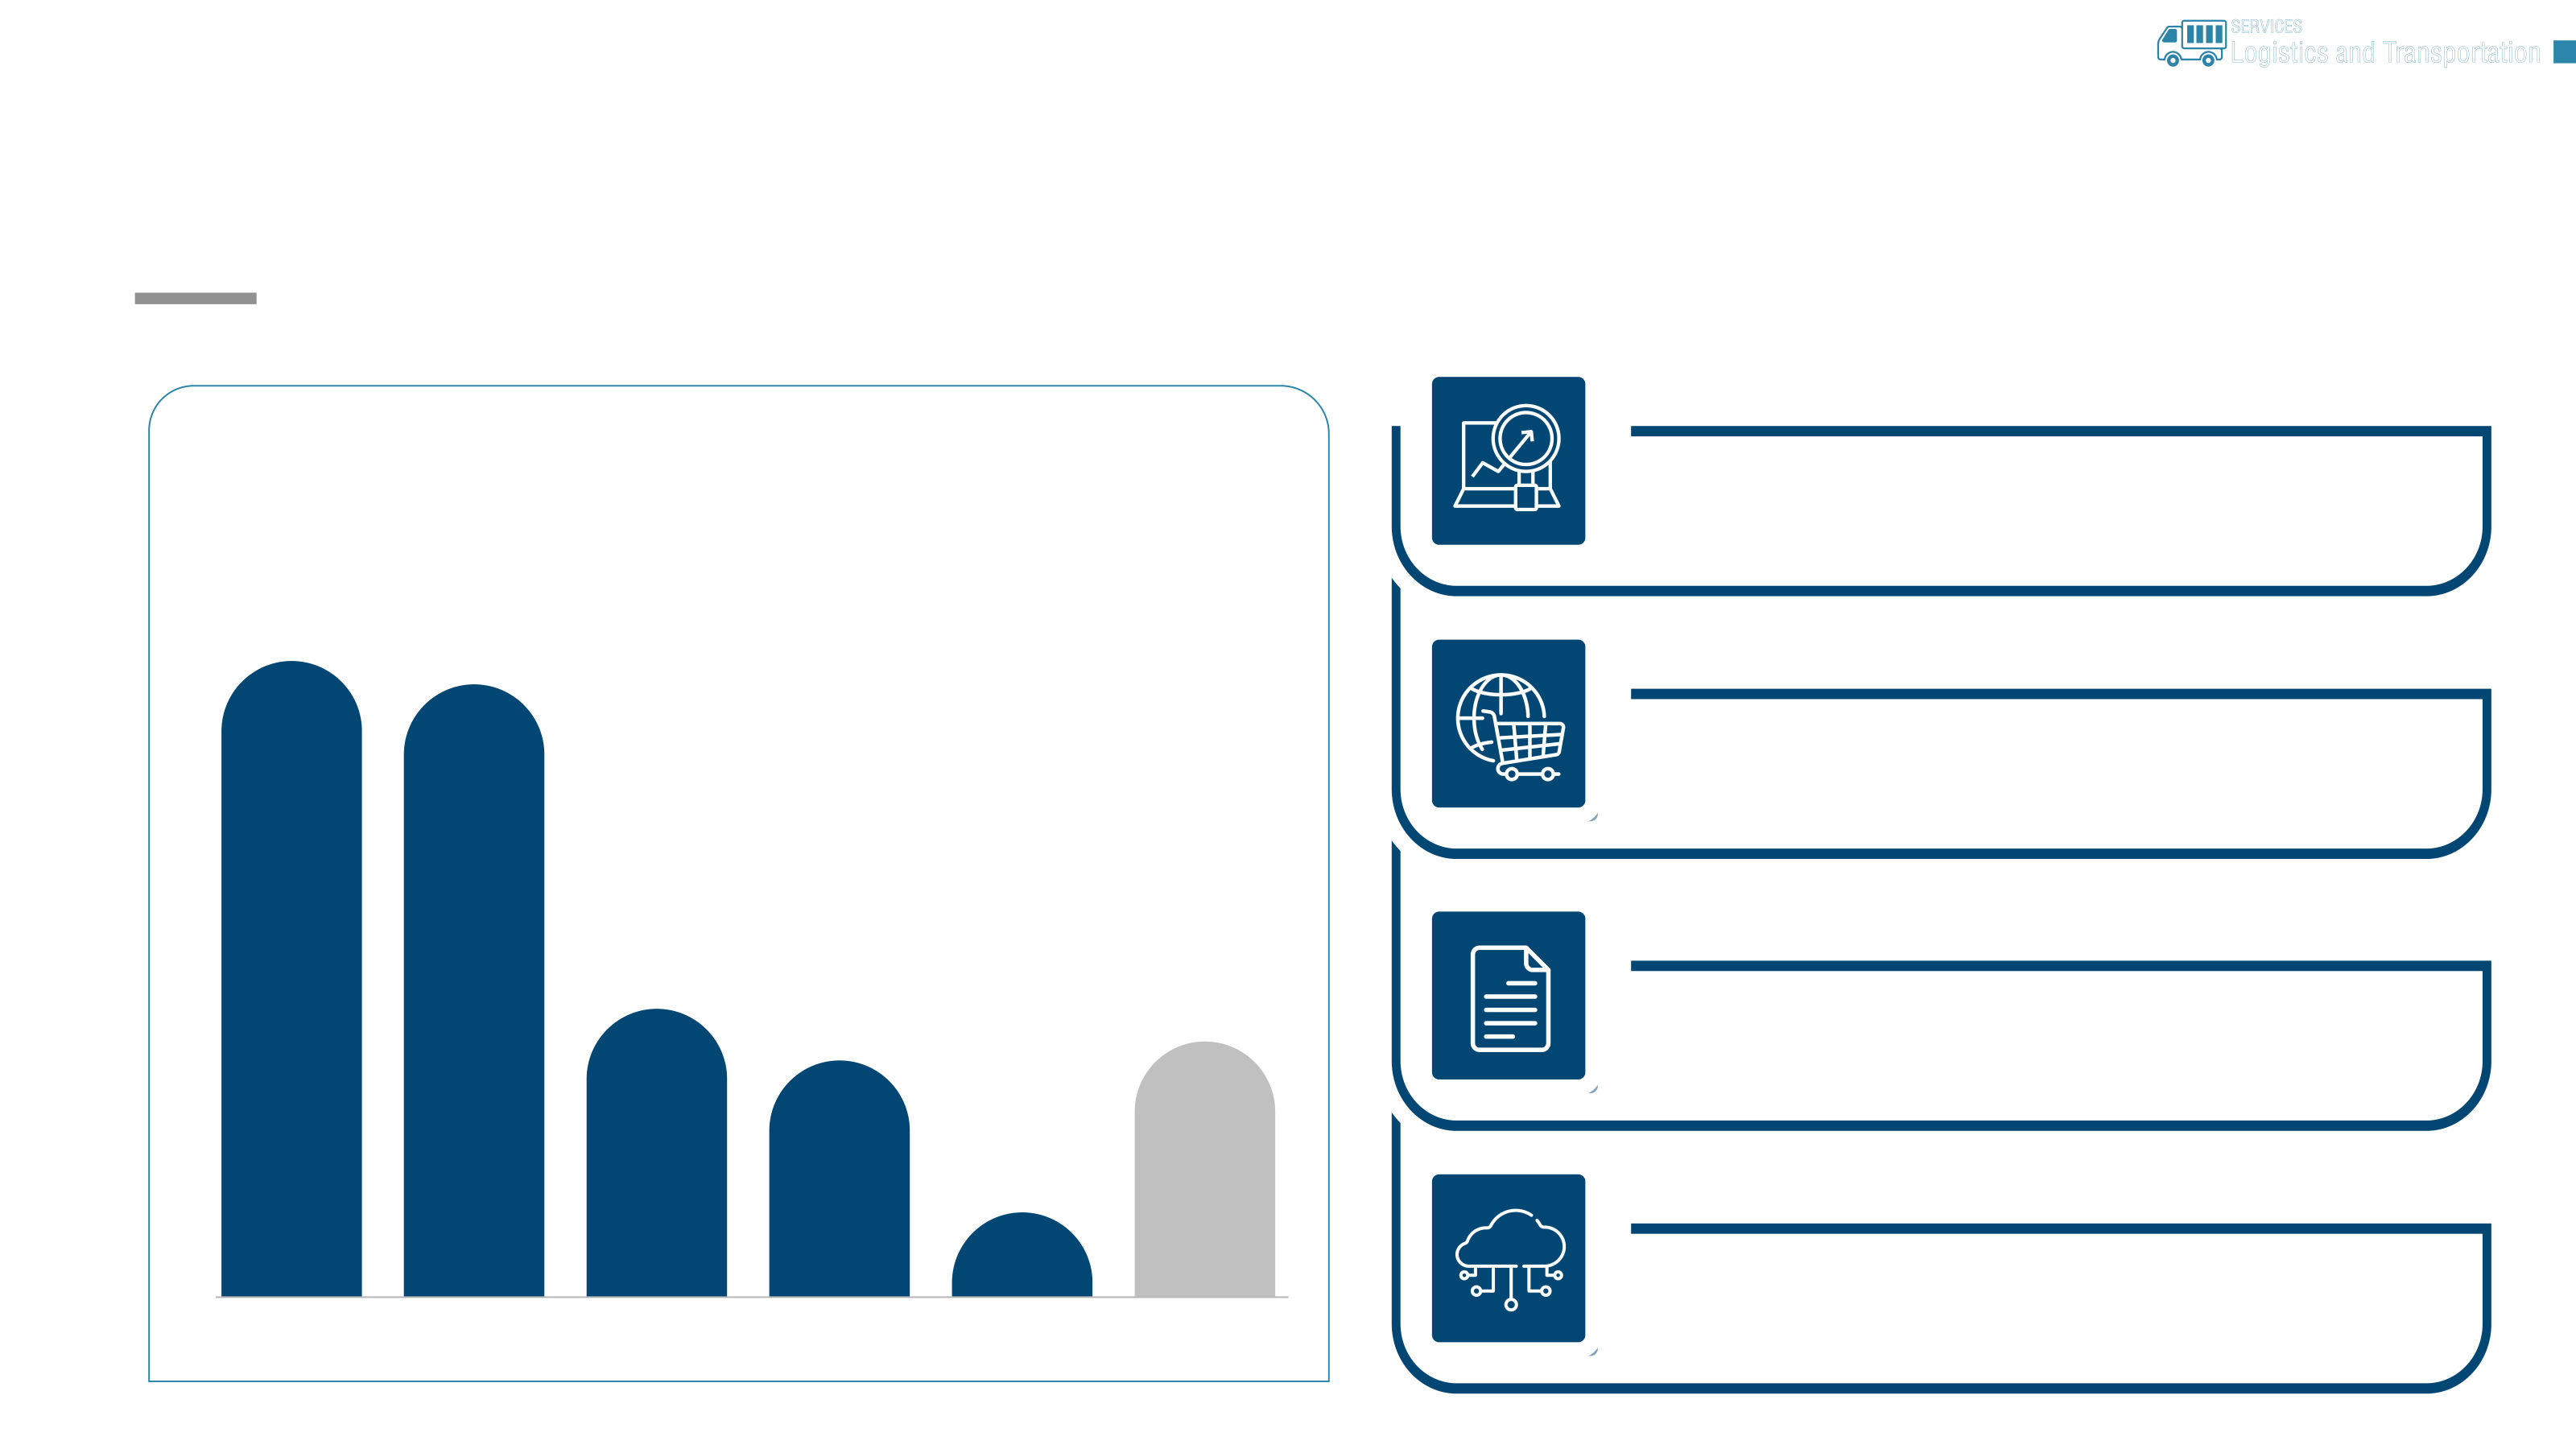
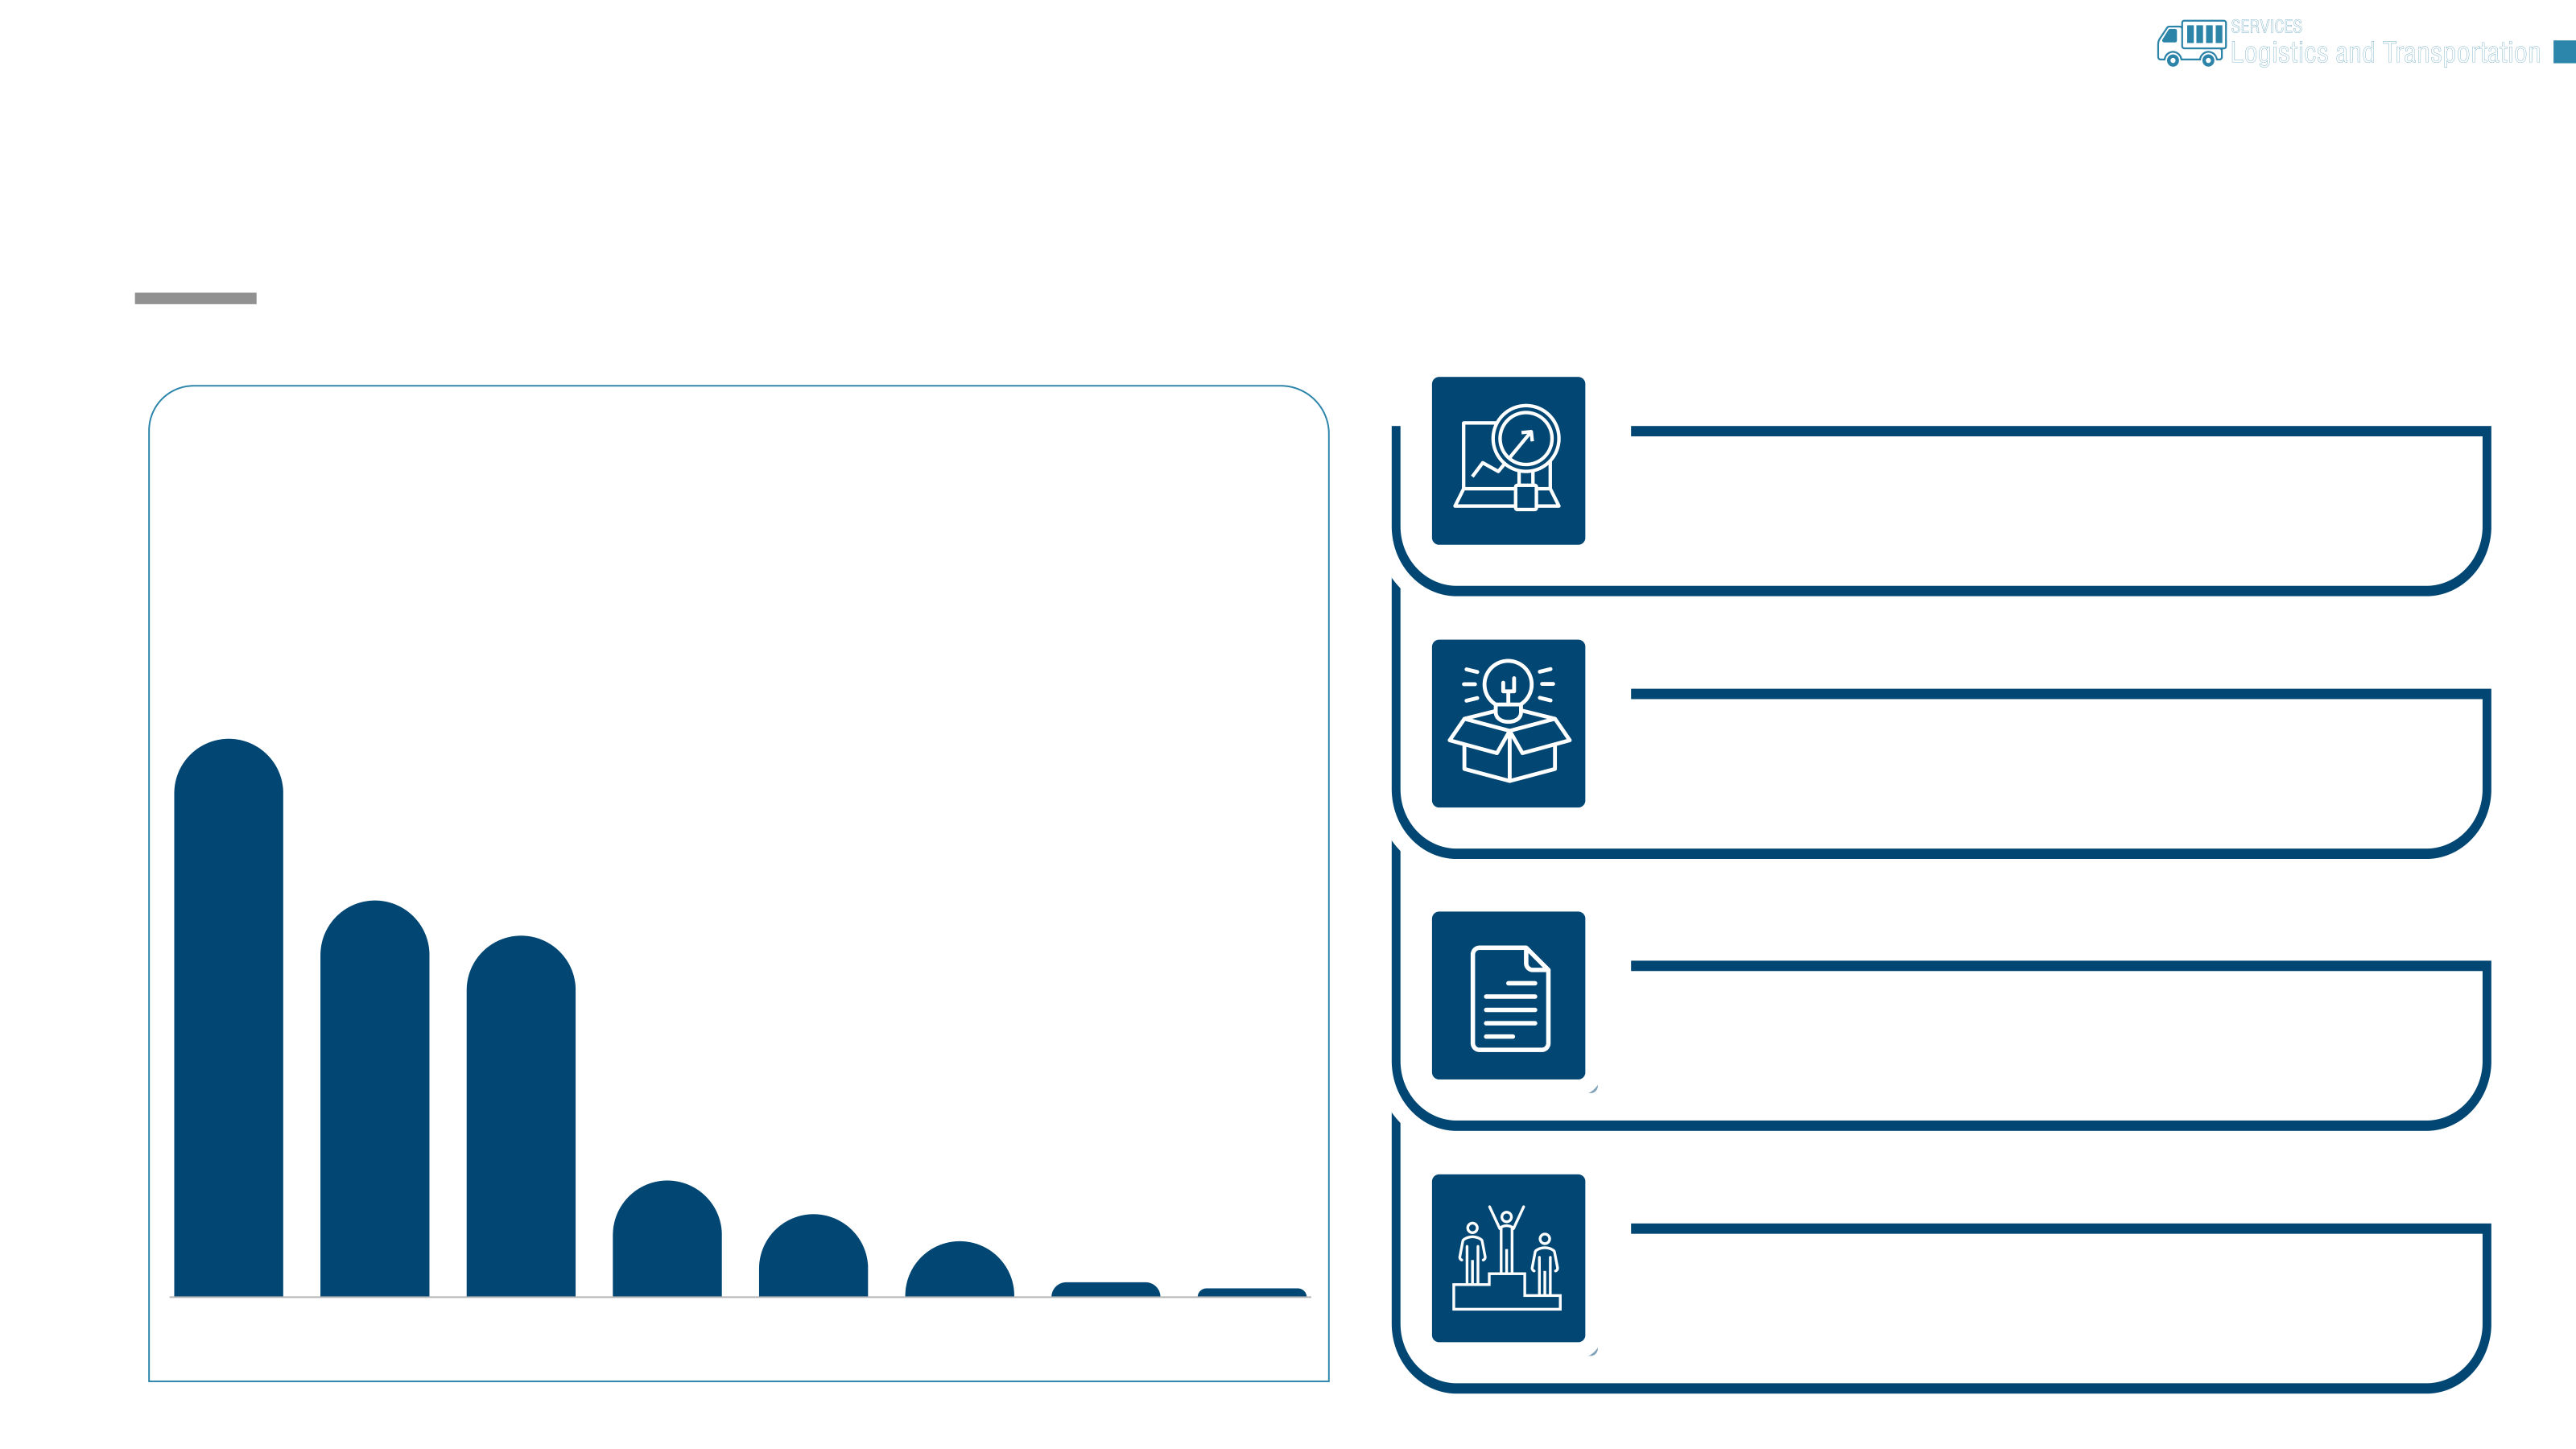
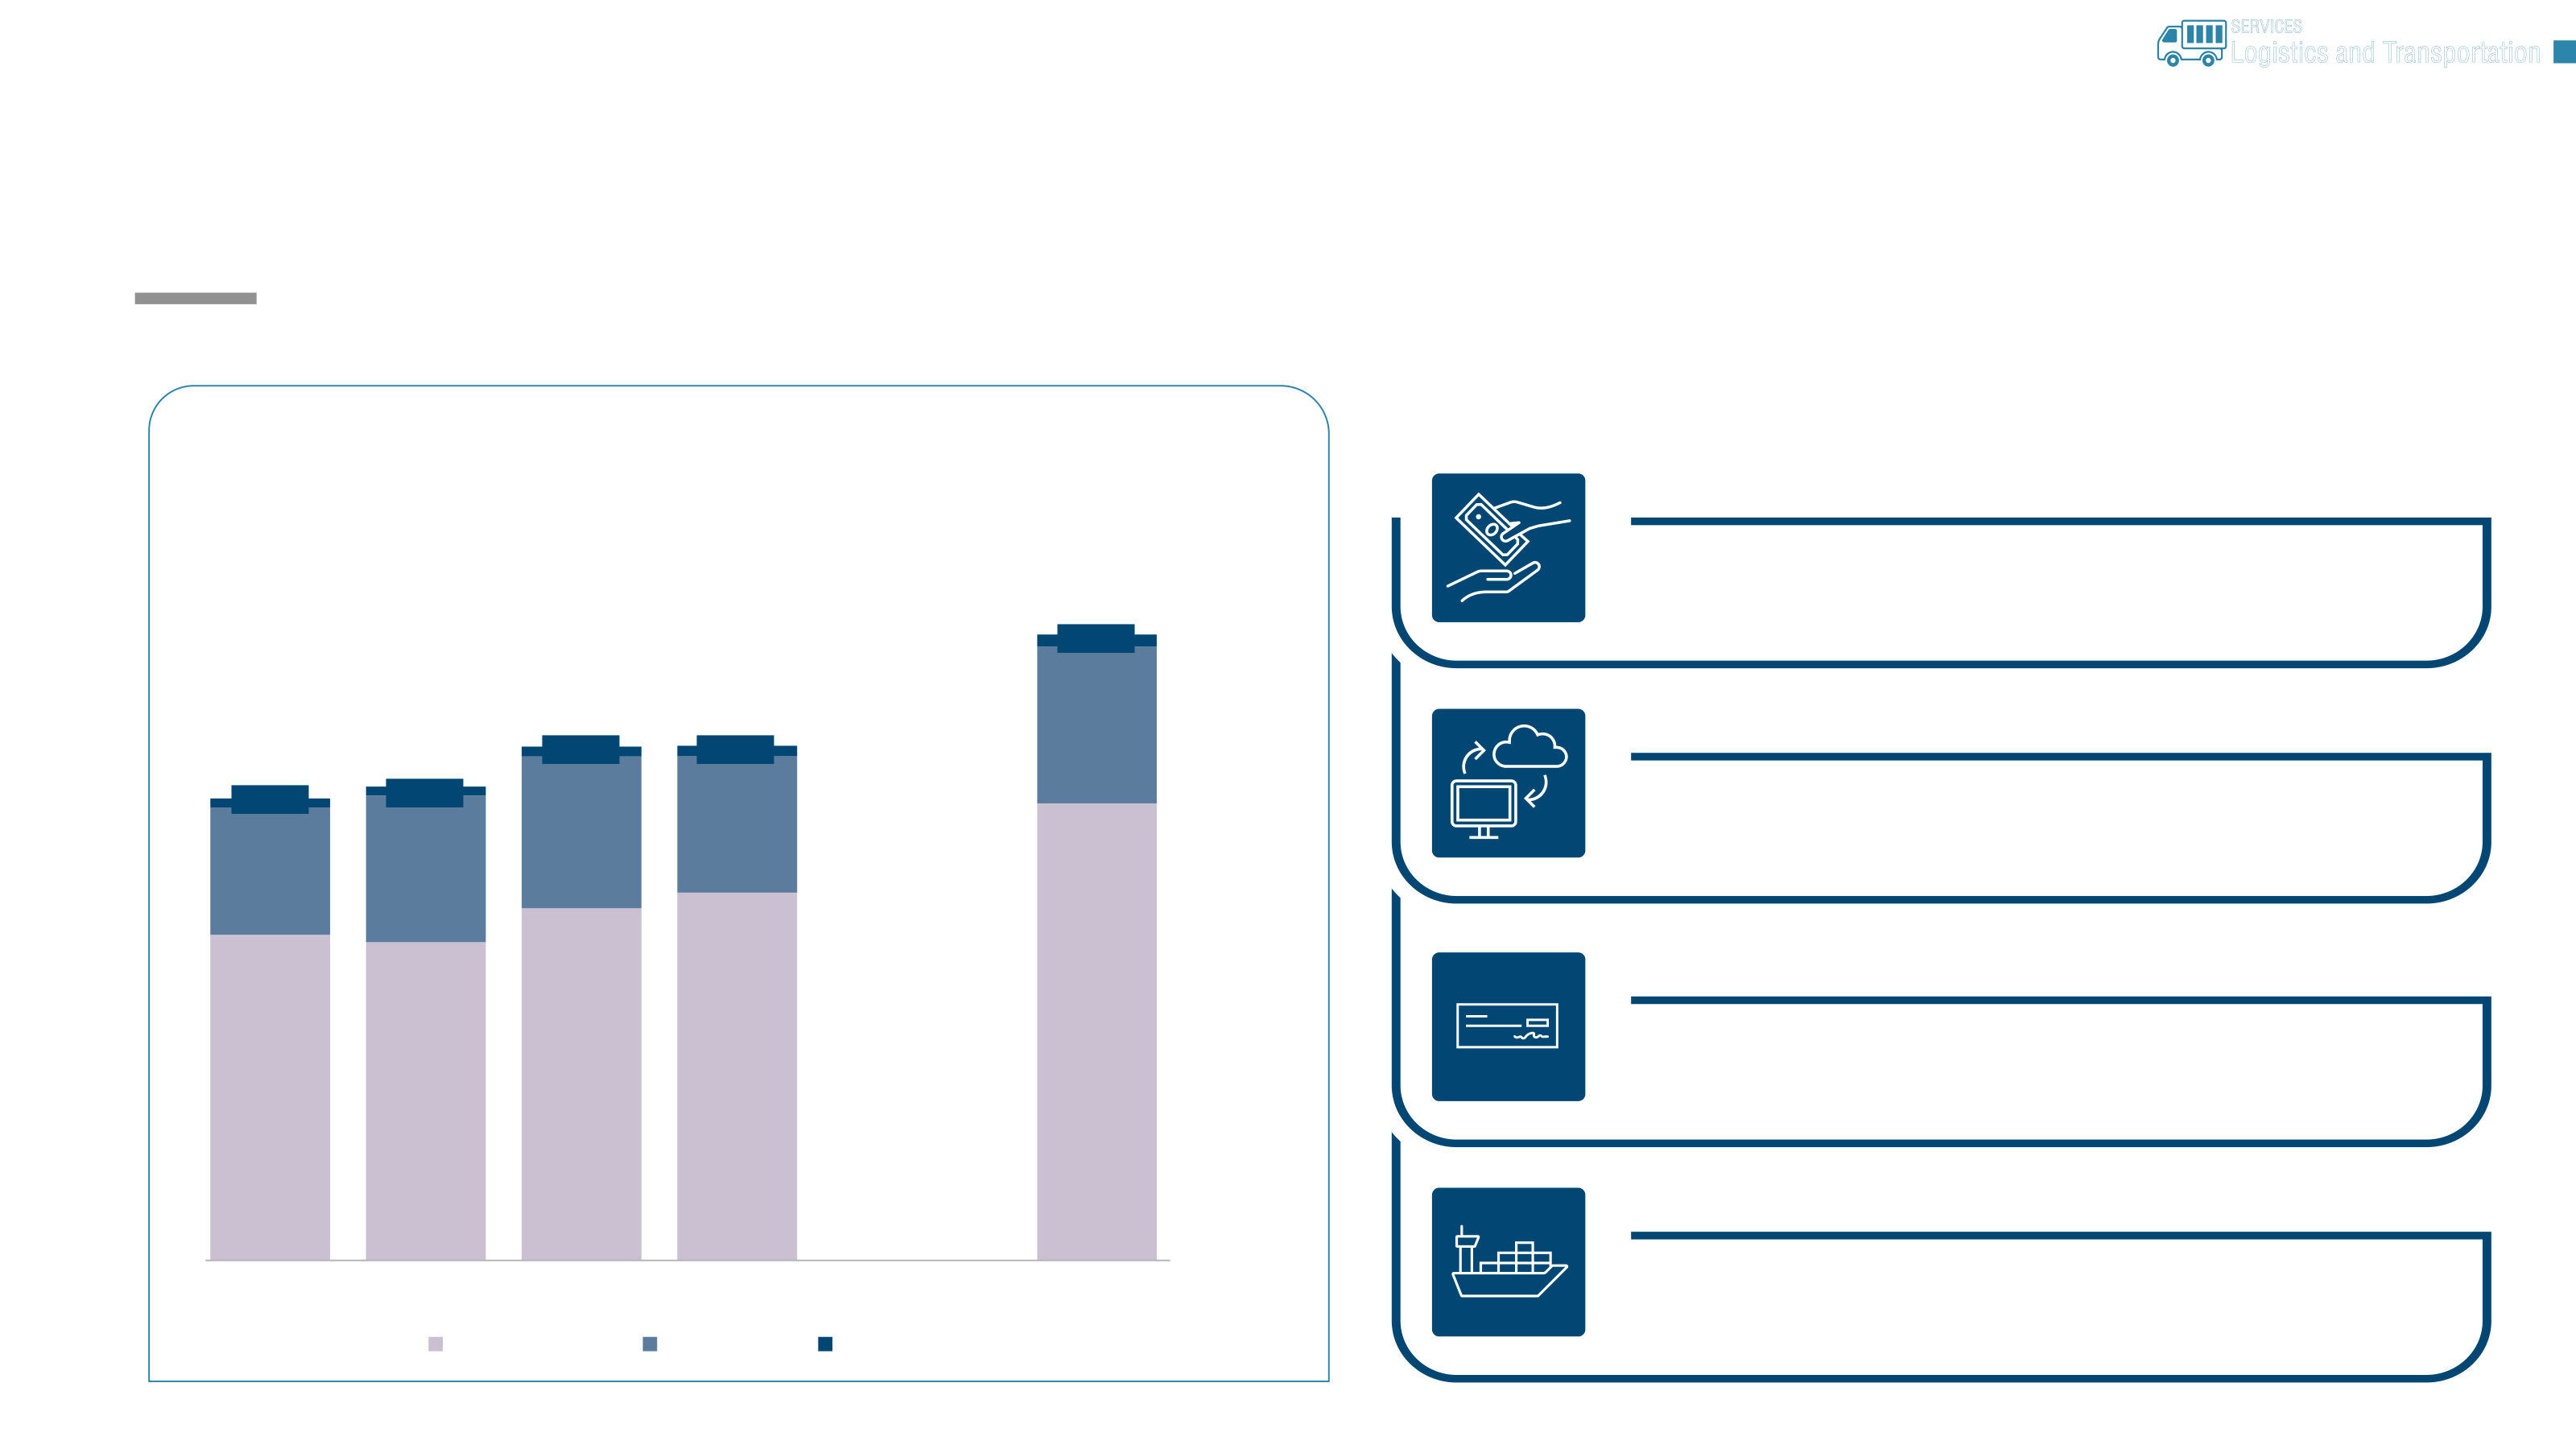
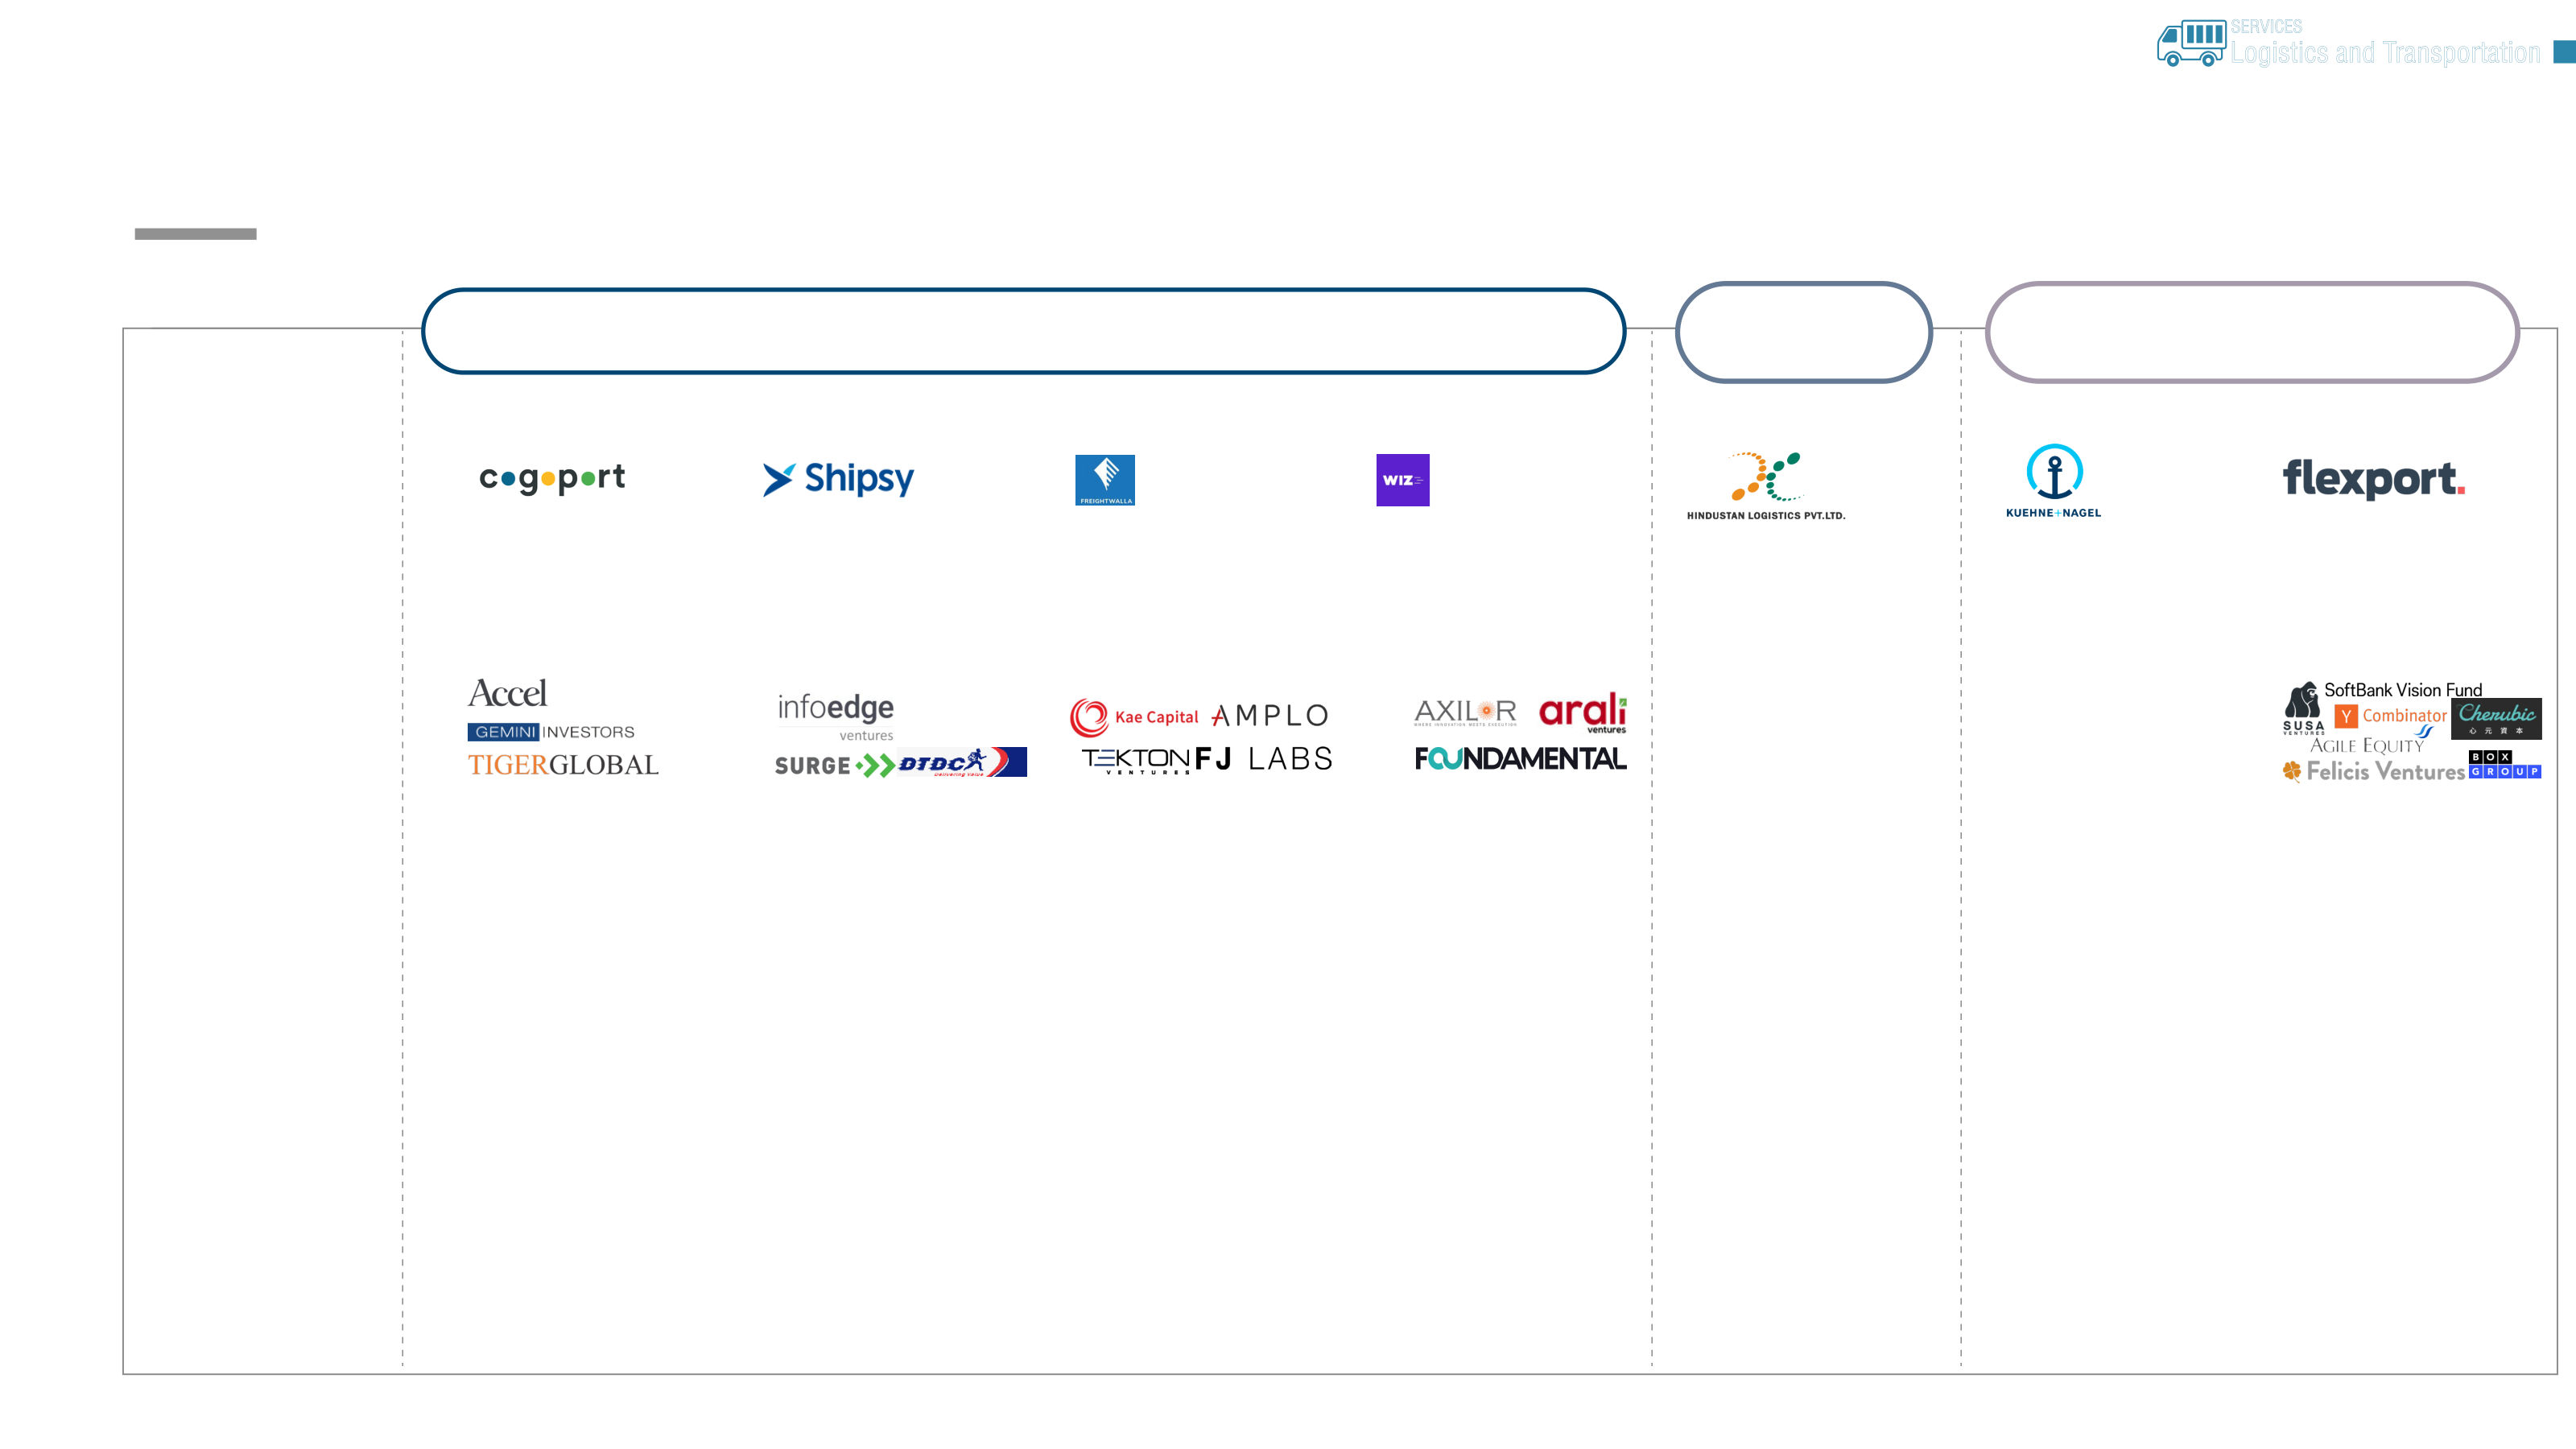
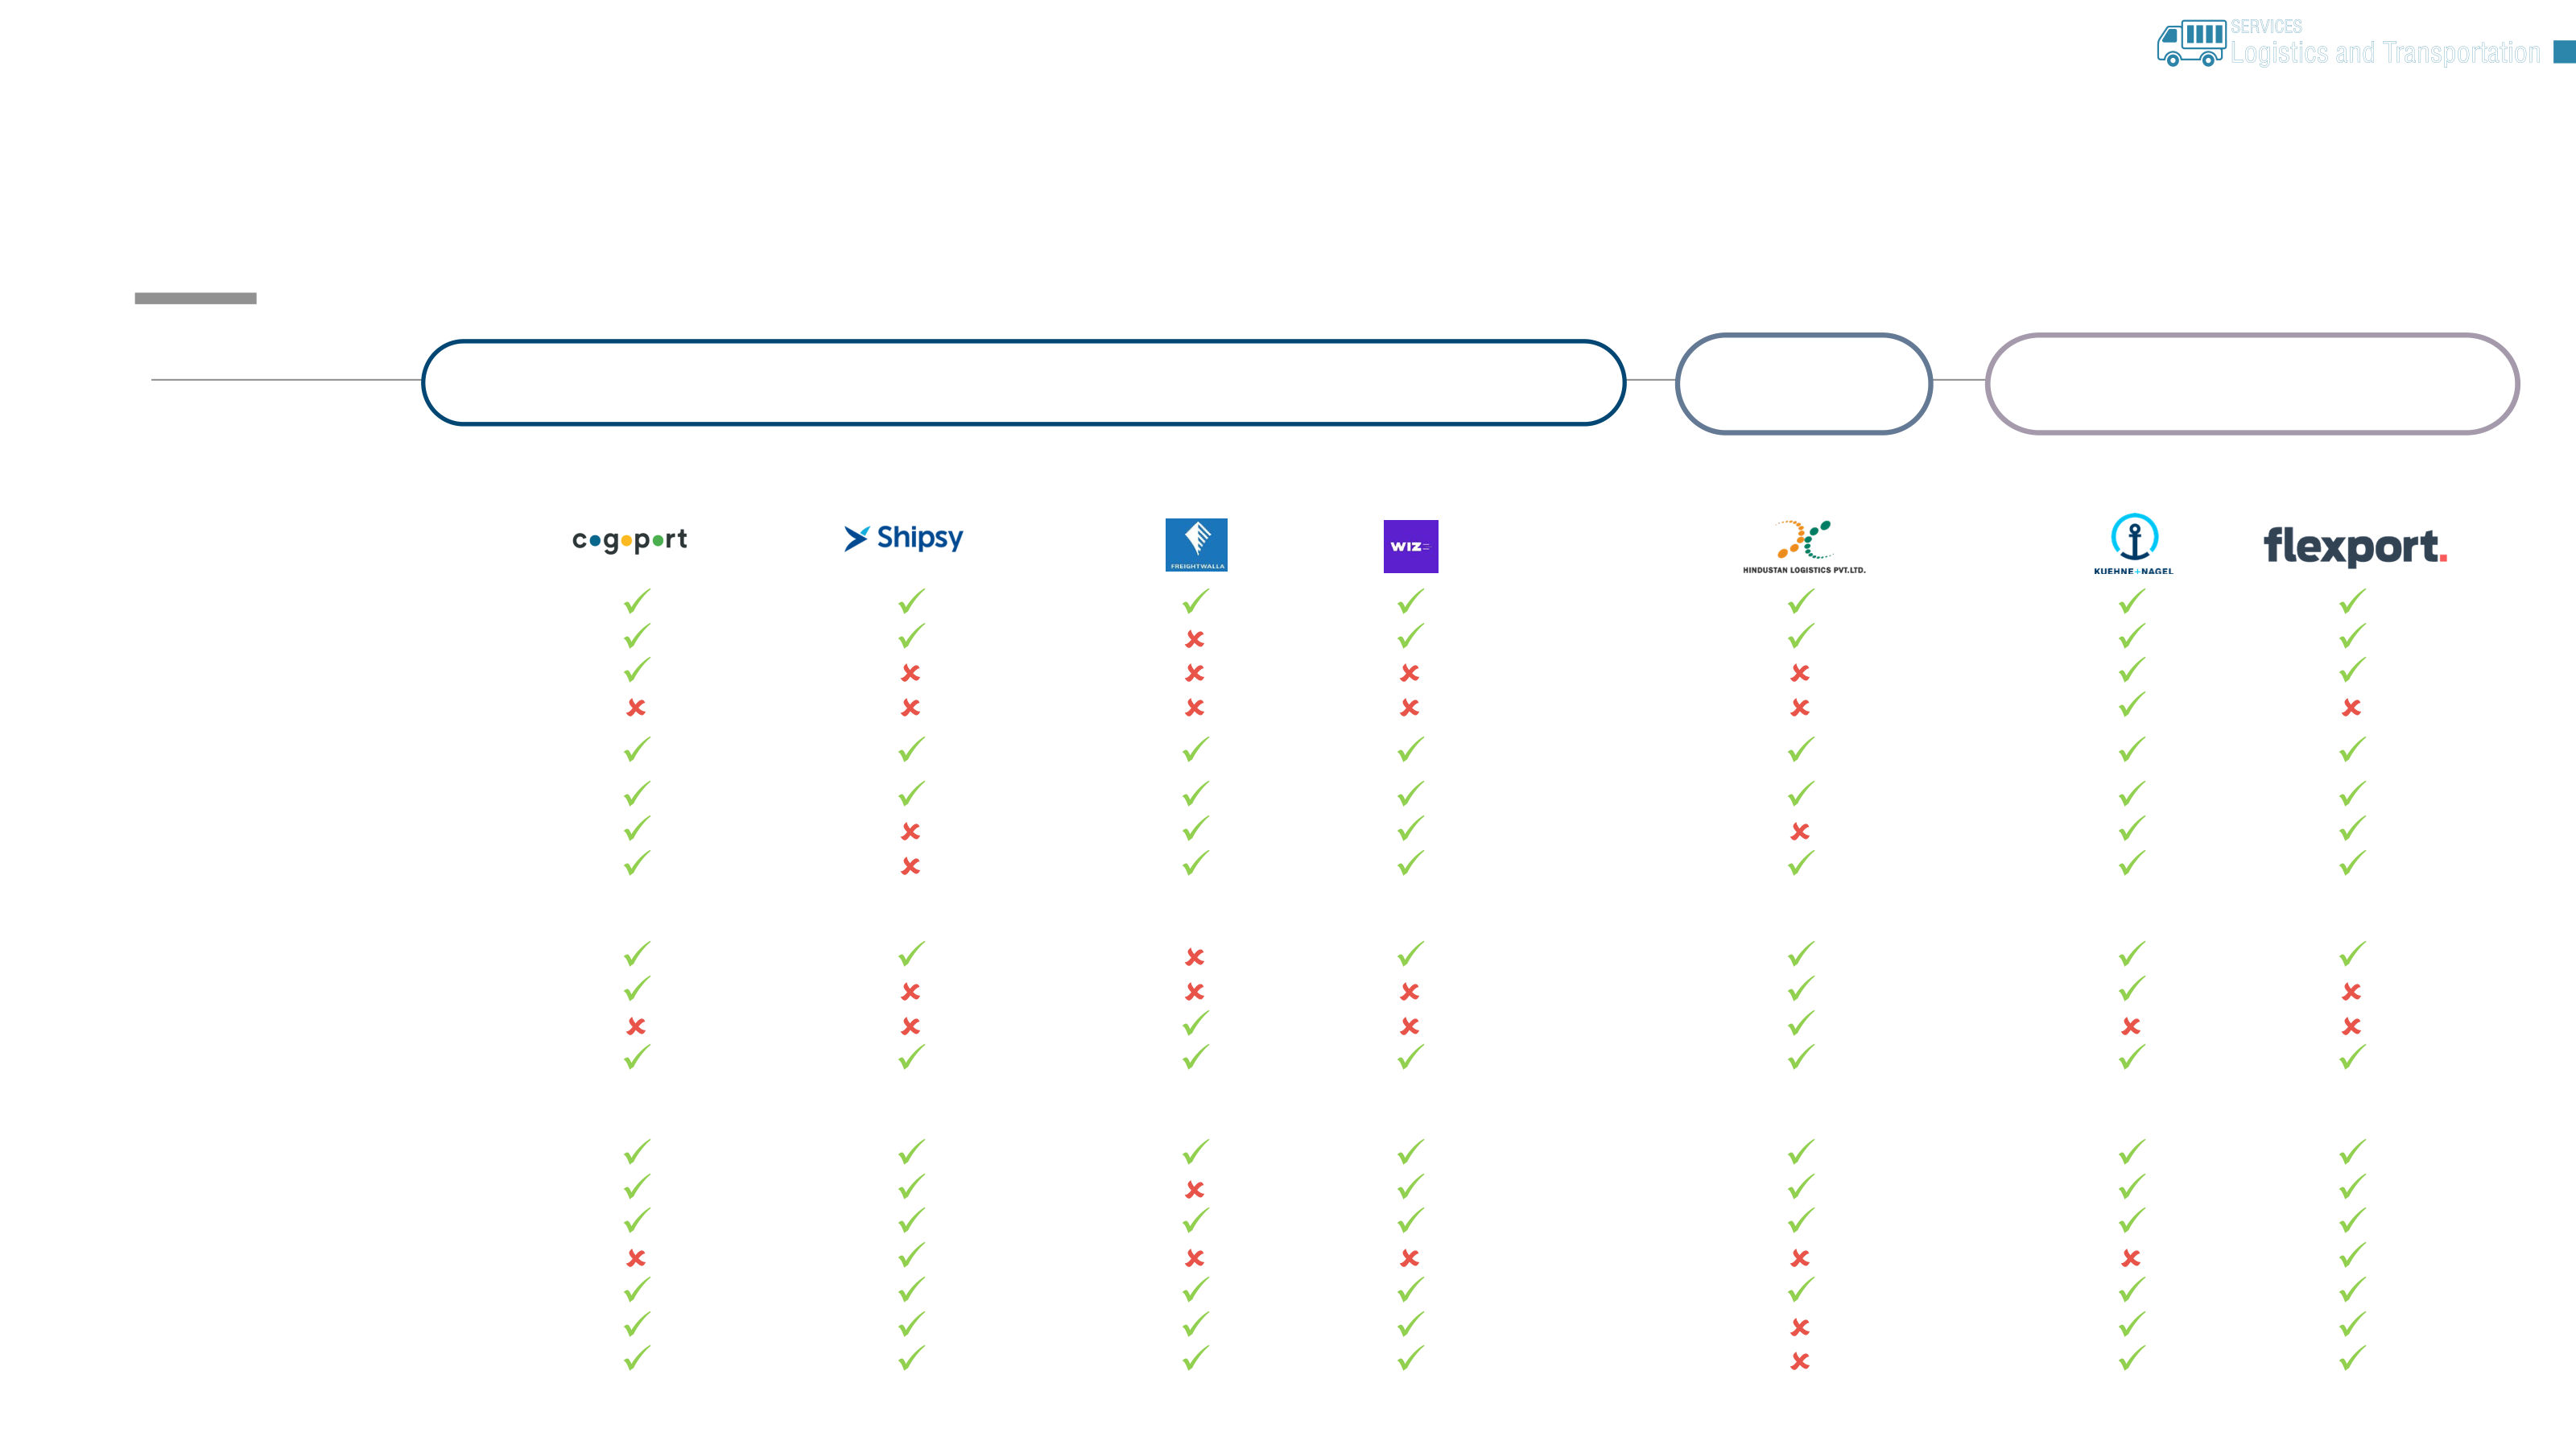
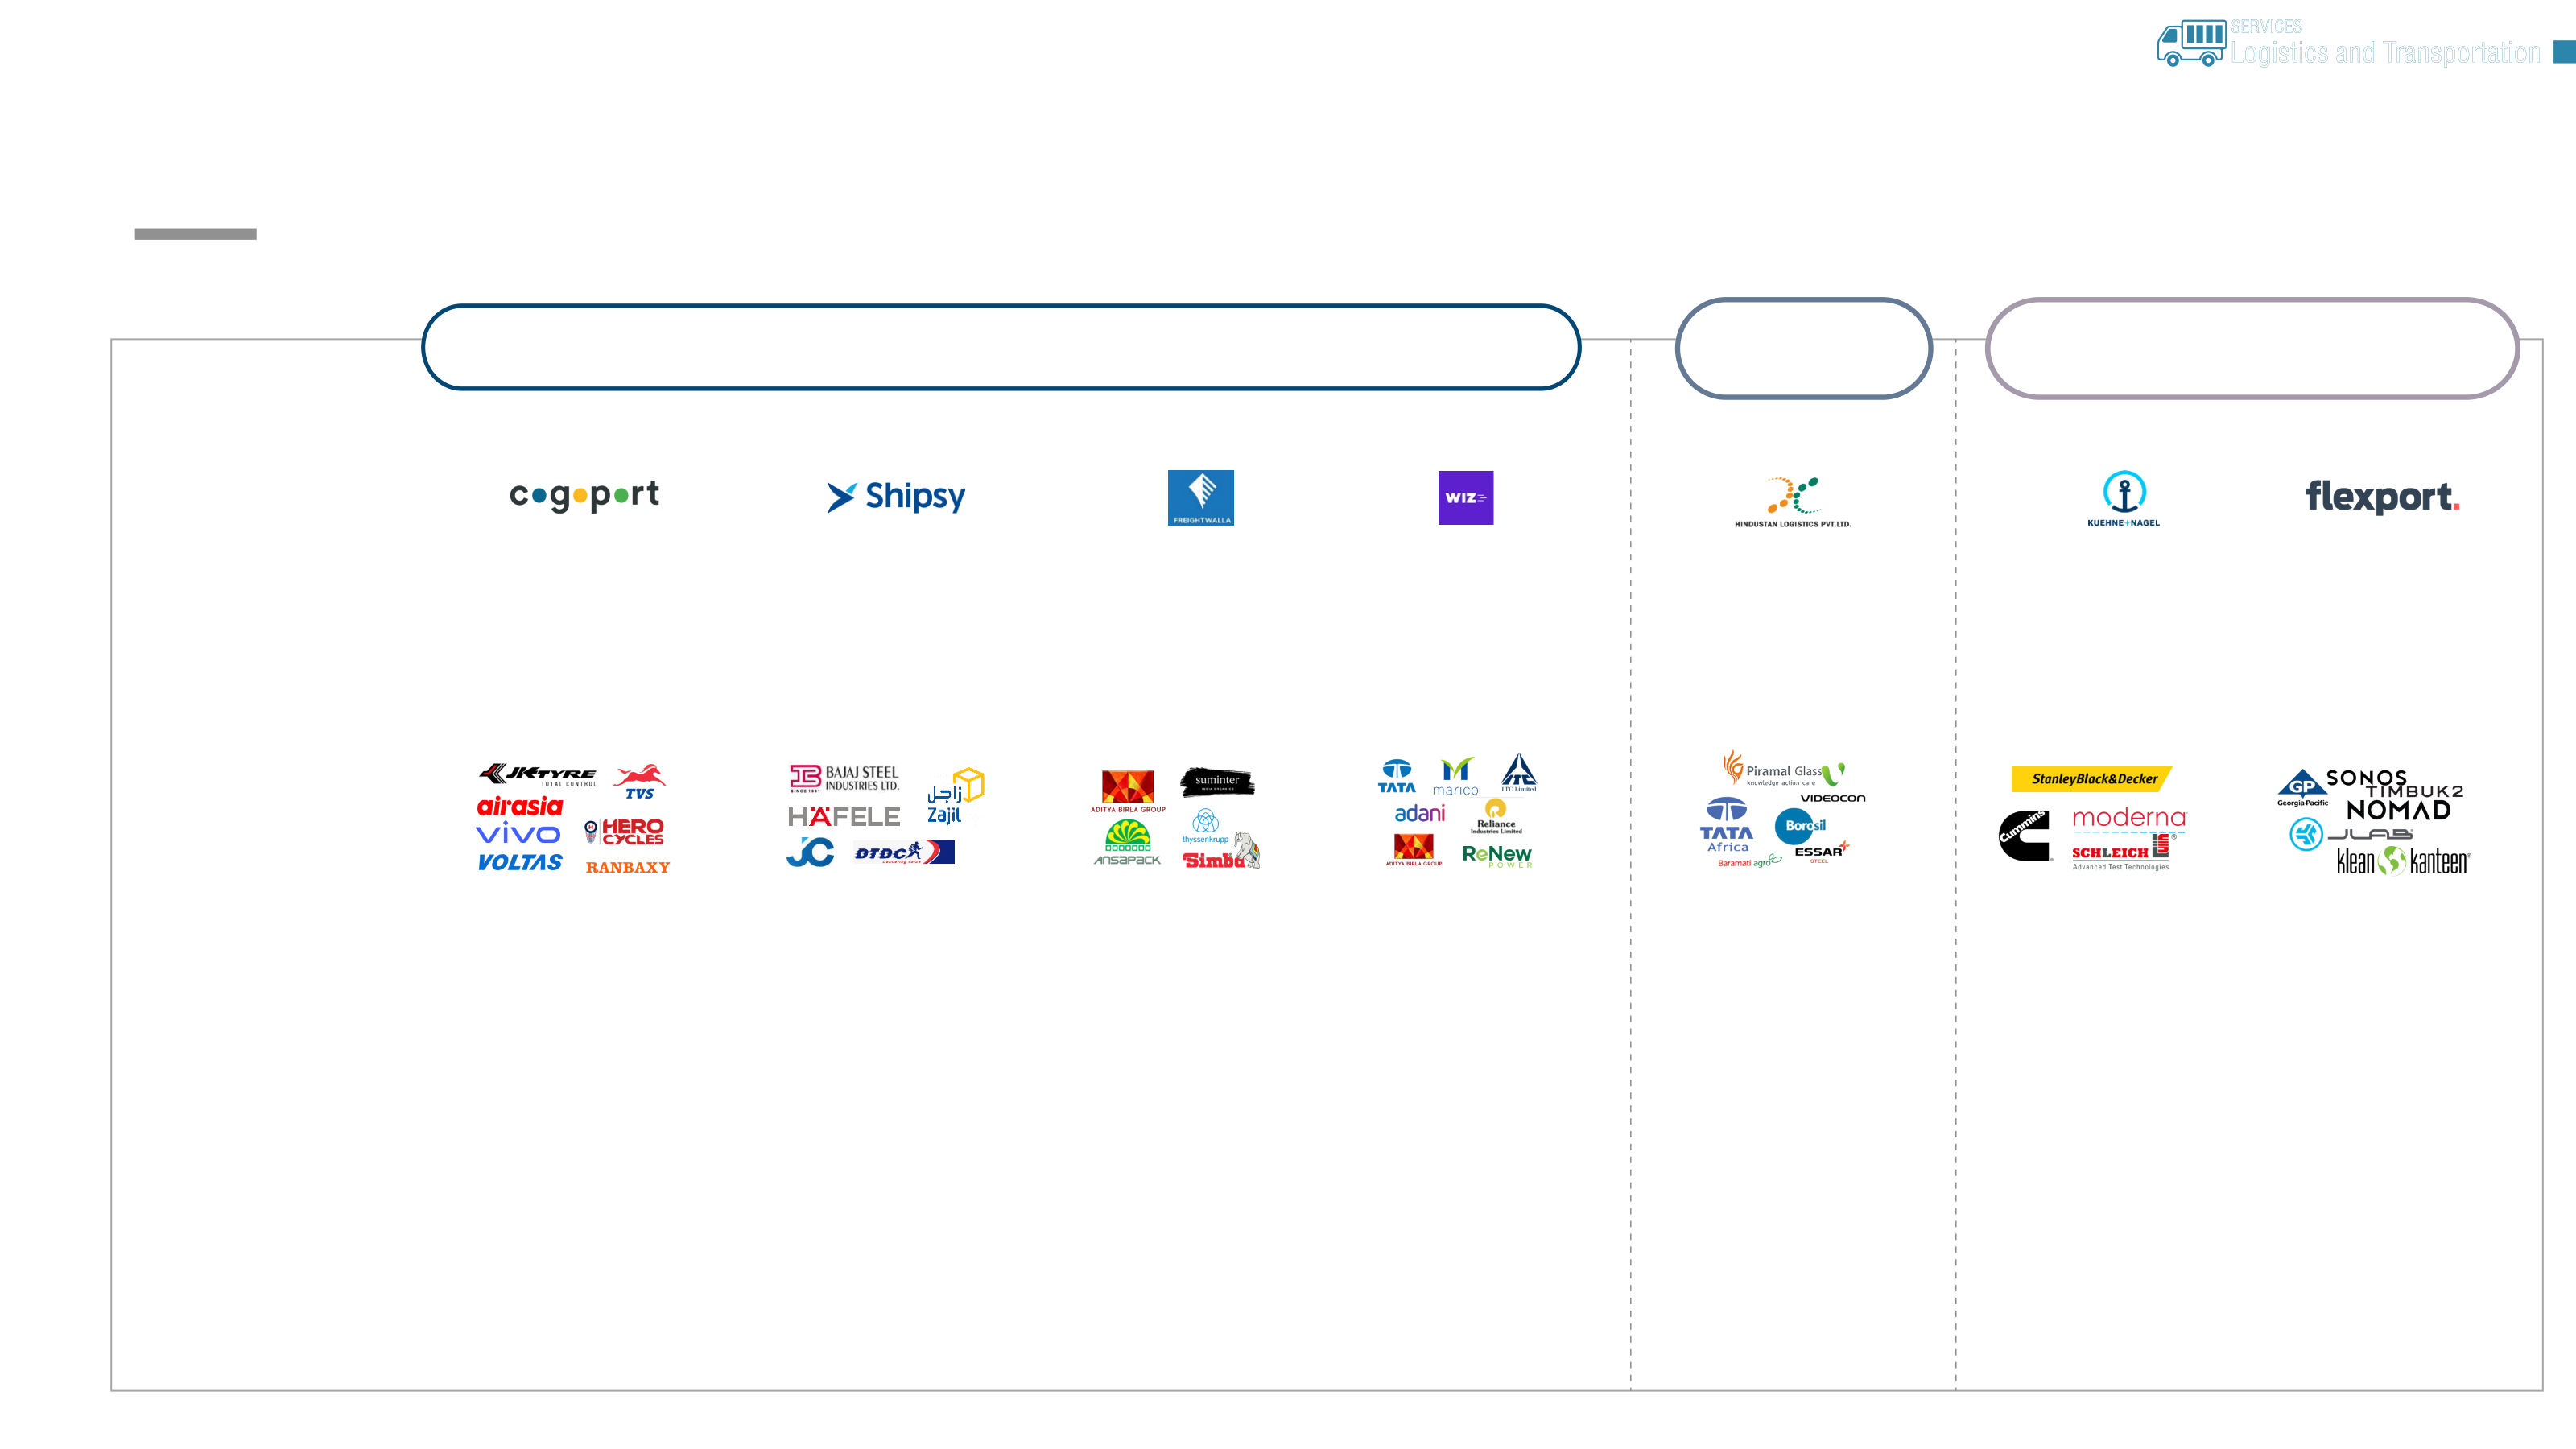
SERVICES Logistics and Transportation Report NOVEMBER 2022 Foreword The global freight forwarding market has evolved transparent. We have discussed key trends in the significantly in the last decade, largely owing to global freight forwarding market, keeping a special newer business models and the adoption of focus on the Indian freight forwarding market in new–age technologies across the value chain. The the later half of the report. For India, we have global freight forwarding market is highly projected the growth trajectories for the modes of fragmented, with the top 25 freight forwarders forwarding up to FY26, showcasing the modes capturing around 21% of ocean freight and 26% of which will see significant growth, as well as the the air freight market providing digital freight emerging trends in the market. We have also forwarders with a large market to capture and portrayed the competitive landscape across create their own leadership position. Countries various business models and benchmarked key have seen the rise of numerous tech-enabled digital freight forwarders on several parameters. players in this space, dealing with forwarding, The market is rapidly evolving, and some of the customs clearance, insurance and trade financing. scenarios presented here may have slight In terms of digitization, India is at a very nascent variations. This report reflects our perspectives as stage. of August 2022. Contact us for the latest updates. In this report, we have covered the various We, at PGA Labs, look forward to continuing the business models existing in this space and discussion with our friends across sectors and assessed how they have impacted the stakeholder exchanging notes as the situation evolves. journeys, making them simpler and more Abhishek Maiti Director SERVICES Logistics and Transportation Key takeaways • The global freight forwarding market is highly fragmented with global top 25 freight forwarders capturing around 21% of ocean freight and 26% of air freight market • Mainland east-west routes trade the highest volume in ocean trade, whereas Asia Pacific witnesses the highest air traffic by region • The inbound and outbound trade flow from India provides a view on the priority of country corridors from a freight forwarding standpoint • Air Cargo is transferred mostly though metropolitan cities with Mumbai & Delhi cumulatively handling 60% of air cargo traffic • Ports in Gujarat, Maharashtra and Tamil Nadu contribute to around 80% of ocean freight & also consist of high concentration of freight forwarders. • Target Addressable Market of Indian freight forwarding market is expected to reach US$ 8B by FY26 owing to improved transportation infrastructure and government policy support © PGA Labs | 03 SERVICES Logistics and Transportation Executive Summary • Value chain of freight forwarding spans five key steps, with specific activities being undertaken from booking initiation to delivery of the consignment • There are four broad business models in freight forwarding which differ in their value proposition namely, traditional freight forwarder, digital marketplace, SaaS provider, digital service provider. • Digitalization has enhanced the delivery quality of value-added services • Indian freight forwarding market is to grow at 3.3% from FY2020 to reach US$ 8B by FY26 • Target Addressable Market of the Indian freight forwarding market is expected to reach US$ 8B by FY26 owing to improved transportation infrastructure and government policy support • Indian ocean freight is concentrated towards the Americas and APAC while air freight is concentrated towards EMEA © PGA Labs | 04 SERVICES Logistics and Transportation The global freight forwarding market is highly fragmented, with the top 25 freight forwarders capturing around 21% of ocean freight and 26% of the air freight market Market is highly fragmented due to the presence Market is highly fragmented due to the presence of several traditional players and of several traditional players in the market relatively low technology penetration Share of freight forwarding basis volume (TEU ¹ M, MMT ² , CY20) Digital forwarding platforms are not mature enough to offer sophisticated services and hence are not a competitive ‘threat’ currently Customers use a mix of online marketplaces, booking platforms and digital forwarders; this mix represents 144 56 an important part of their overall shipping strategy Emergence of new technology and appropriate market positioning might lead 79% 74% towards consolidation New technology in the forwarding market might aid operational efficiency, generate competitive advantage and increase value for shippers 21% 26% Specialized business models would be required in the future; it is essential to understand what customers Ocean Freight Volume Air Freight Volume require and be positioned accordingly (TEUs) (metric tonnes) Top 25 freight forwarders Other freight forwarders Note(s): (1) Twenty-foot Equivalent Units ; (2) Million Metric Tonnes © PGA Labs | Source(s): Armstrong & Associates, IATA, UNCTAD, Secondary research, PGA Labs analysis 05 SERVICES Logistics and Transportation Value chain of freight forwarding spans five key steps, with specific activities being undertaken from booking initiation to delivery of the consignment Import documentation, Import haulage Export documentation and Booking Haulage and stuffing destination handling and and payment origin handling transit By the freight Responsibility can be on forwarder or consignee or consigner consignee as per agreement Settling terms of carrier bill Selection of freight forwarder by Stuffing - cargo is loaded into the Stuffing - cargo is loaded into the Import haulage - transfer of the consigner container by freight forwarder based container by freight forwarder based cargo from the freight forwarder’s Payment terms on FCL or LCL on FCL or LCL warehouse to the destination are agreed upon by the consignee and consigner E.g., commercial invoice, bill of lading, By the freight certificate of origin, forwarder or Adding address, shipment volume and Reviewing supporting documents and insurance consigner other details on the portal certificate and checking for damage Supporting document verification by Export haulage - transfer of cargo from its freight forwarder origin to the freight forwarder’s warehouse Final inspection of cargo is made by the consignee Quotation proposal and determination Unloading cargo and obtaining import based on mode and route of transportation customs clearance Facility of trade financing provided by freight forwarder Confirmation of booking by freight forwarder Meeting packaging requirements Inspection of cargo by freight forwarder Payment for the cargo is made by Track and trace of transportation of and consignee leading to payment terms to check inventory list and prior damage the consignee to the consigner cargo by freight forwarders Key pain • Manual, lengthy and time-consuming process • Communication across involved parties • Process flow dominated with paper documents • Irregular track and trace • Manual invoicing points Digital • Transparent marketplaces • Increased network capabilities • Digitalized document verification to avoid errors • Real time visibility and alerts, improving carrier • Integrated payments • Instant & standardized quotations across carriers • Time efficient due to visibility • Eliminates broker overhead fees accountability • Transparency in payments value • Visibility across transportation • Automated invoicing creation Note(s): FCL stands for full container load, LCL stands for less-than container load © PGA Labs | Source(s): Primary Interviews , International Cargo Express, Secondary research, PGA Labs analysis 06 SERVICES Logistics and Transportation There are four broad business models in freight forwarding which differ in their value proposition By service offering Digital freight forwarder Parameters Traditional freight forwarder SaaS provider Digital service provider Digital marketplace • Planning and coordination of movement of • Provides a platform for matching shippers to • This model allows users to manage the • Similar to traditional freight forwarding, but relies cargo internationally, on behalf of shippers, freight forwarders interaction with partners across a freight completely on technology through integrated digital with the help of a specialized network of transaction platforms and software to be more efficient • Integrates their own value-added services or carriers • Offers a better customer experience through digital alternative offerings on the platform • They provide specialized software systems for Description modes of communication and interaction selected parts of the freight forwarding value • Process flow dominated by physical touch • Offers end-to-end transaction management points and manual processes/interactions chain • They are neutral platform operators • Price engine leading to instant quote generation Companies • Warehousing • Quotations for modes of transport • Haulage of cargo • Documentation handling • Pricing engine • Cloud based management platform for tracking • Digitised document handling • Customs clearance services • Instant price quotation and booking • Digitised documentation handling • Customs clearance services • Warehousing • Digital customer platform • Modular integration with pre-existing software • Real time track and trace • Haulage of cargo • Tracking Services • Customised software solutions • Modular integration with pre-existing software • Value added services (e.g., trade finance Services offered • Automated invoicing and insurance) • Planning and analytics • Value added services (e.g., trade finance and insurance) • Tracking software subscription/ fees • Haulage brokerage charges • Haulage charges • Subscription based model • Warehousing fees • Warehousing fees • Flat fees on the platform provided • Value added or alternative freight • Customs clearance services • Customs brokerage • Transaction based fees services are charged by transaction • Shipment insurance service fees • Shipment insurance service fees • Subscription based pricing for platform usage with an included profit margin • Trade financing • Trade financing Revenue stream • Software solutions for advanced analytics (e.g., cost optimization, predictive analytics) Source(s): Secondary research, PGA Labs analysis © PGA Labs | 07 SERVICES Logistics and Transportation Digitalization has enhanced the delivery quality of value added services Activities Traditional model Digital model Rationale Additional services • Digital policy consultation & comparison Settlement of terms • AI & predictive analysis for the policy amount • Online insurance policy initiation and payment notice issuance Initiation of insurance process Cargo insurance • Surveyor used in traditional model Damage impact assessment • Self-completion survey option adoption • Fully automated claims process Claims pay-out process • Collaboration with brokers and claims adjusters on single portal Submission of information by • Digital submission of all documents on portal customer • Future value creation via text analytics; not implemented Review and inconsistencies Customs clearance widely yet addressal by CSP Validation and approval of • Requires tech adoption and integration by customs department customs declaration • Real-time KYC & AML checks Letter of credit creation • Digitalized document submission • Centralized visibility on portal Letter of credit processing Trade finance • Predictive analysis of LC patterns yet to be implemented • Auto-trigger payments Payment processing • Direct payment on portal existent Very low Very high Level of digitalization Note(s): CSP stands for Customs Service Provider, LC stands for letter of credit, KYC stands for Know Your Customer © PGA Labs | Source(s): Infosys ‘Process automation for efficient data entry’ 2020 report, Deloitte ‘The Impact of Digitalization on Customs Service Provider 2020’ report, Secondary research, PGA Labs analysis 08 SERVICES Logistics and Transportation The global market landscape of traditional and digital freight forwarding has several participants across the value chain Digital freight Traditional freight forwarding forwarding Marketplace SaaS Provider Service Provider Customs Insurance Trade Finance © PGA Labs | 09 Source(s): Tracxn, Company websites, PGA Labs analysis SERVICES Logistics and Transportation Supply-side bottlenecks along with a boost in demand have pushed the shipping prices upwards in 2021, providing higher margins to freight forwarders Supply-side factors A sharp rise in prices was witnessed in all trade corridors for ocean freight forwarding from 2020 Continuous lockdowns and travel restrictions due to COVID-19 resulted in the docking of containers; many of which remain docked even now, leading to less ships available in the market Aug ’21 ($/FEU) Lane Aug ’20 ($/FEU) Change (%)* Port congestion - Port congestion and delays at LA/ Long Beach are keeping Asia-US prices extremely high and causing higher turnaround times for existing ships Global $ 10,097 $ 3,205 351% Demand-side factors Asia-US East Global economy recovering since COVID-19 aiming for high GDP growth leading to $ 19,429 $6,168 330% Coast increased international trade for various items - retail goods, industrial commodities, etc. Availability of fewer alternative options as air freight costs also increased due to Asia-US West $ 16,749 $ 5,075 315% growth in industries like pharmaceuticals, e-commerce, and perishables leading to Coast consistent demand for ocean freight. Asia-North $ 14, 492 $2,547 569% Outlook Europe With port congestions reducing, prices are expected to fall by early 2022 marginally as capacity will still be limited. North Europe-US $ 7,126 $2,159 330% East Coast Capacity is estimated to be added by 2023-24, which might help the prices to be at much more stable levels. Note(s): * Compared to corresponding week in 2020 © PGA Labs | Source(s): Freightos website, PGA Labs analysis 10 SERVICES Logistics and Transportation Mainland east-west routes trade the highest volume in ocean trade, whereas Asia Pacific witnesses the highest air traffic by region Ocean trade volumes have reduced by 5.2% owing to the pandemic; Air freight Macroeconomic Trends traffic has also seen a reduction across regions Ocean volume by major trade lane Air freight traffic by region % change % change (M TEU, 2019, 2020) (B CTK, 2019, 2020) 2019-20 2019-20 Global economic growth decelerated against a 41 403 backdrop of lingering trade tensions between North 152 5% 9% 40 144 11 365 America and China and high policy uncertainty 18 18% 9 36 41 14 22% 2% 40 11% 32 94 19 4% 90 18 5% Global merchandise trade contracted as 12 manufacturing activity slowed over the course of 12 0% 105 the year 20 16% 18 88 10% 60 56 6% 6% 140 131 Developed and developing economies alike were affected, reflecting the continued trade tensions between China and the United States 2019 2020 2019 2020 Mainland East-West routes Non-mainland West-West Asia Pacific Europe North America North-South South-South Intraregional Middle East Latin America Africa Note(s): CTK: Cargo tonne kilometers, Mainland East-West : Trade involving Asia, Europe & America, Non-mainland East–West: Trade involving East Asia, Europe, North America and Western Asia and the Indian subcontinent. North South: Trade involving Europe, Latin America, North America, Oceania and sub-Saharan Africa, South–South: Trade involving East Asia, Latin America, Oceania, sub-Saharan Africa and Western Asia. © PGA Labs | Source(s): Secondary research, PGA Labs analysis 11 SERVICES Logistics and Transportation Digital value propositions and services have become competitive as legacy players start increasing their presence in the digital space In some areas, such as spot pricing, digital platforms Many major players are slowly building and expanding are more agile than traditional channels their digital presence in the market Broad scope: While digital business models originally covered a • C.H. Robinson has created an entire digital ecosystem early on and narrow field of use cases, they have extended their service is a frontrunner scope toward comprehensive solutions for a broader customer base • Players like DHL, Kuehne + Nagel, DB Schenker, or Maersk have followed suit, with relatively less market penetration in the digital space Emergence of new tech: Artificial intelligence (AI), big data analytics, and cloud computing are evolving fast; players have started to integrate state-of-the-art solutions in their platforms Digital freight forwarding is a promising sector showing high growth opportunities Proven to deliver: Digital businesses can deliver on their value • While digital revenues may still be low compared to the overall propositions and execute services even under difficult market industry, business is developing rapidly. conditions (e.g., COVID-19 and associated capacity shortages) • Depending on the market segment, annual growth rates can be in the high double-digit percentage area – compared to an average forecasted annual freight industry growth of 4%-6% Brazil logistics start-up CargoX leverages blockchain by using a public network to securely validate document transactions • Flexport, founded in 2013, showed rapid revenue growth (CAGR 105%, CY19-21E) making it one of the best examples to underline the strong growth potential Similarly, Hapag-Lloyd partners with Internet of Things (IoT) start-up Globe Tracker to power its new real-time container monitoring system Hapag-Lloyd LIVE © PGA Labs | Source(s): TI Logistics, PGA Labs repository, Secondary research, PGA Labs analysis 12 SERVICES Logistics and Transportation Overview of Indian freight forwarding market 10K+ 6.5K+ 8L+ Freight forwarders Customs brokers Importers and Scale in India exporters registered 1.5L+ 13M+ 2M+ Active importers and Container traffic (TEU) Volume of air freight exporters handled by Indian ports in FY20 (MT) traffic handled at Trade Indian airports in FY20 US$ 4.7B US$ 1.7B US$ 0.1B Value of ocean freight Value of air freight Customs revenue Market (FY20) Note(s): (1) Market size of freight forwarding market as calculated, Data is for FY20 © PGA Labs | Source(s): Primary research, Secondary research, PGA Labs analysis 13 SERVICES Logistics and Transportation The inbound and outbound trade flow from India provides a view on the priority of country corridors from a freight forwarding standpoint China, USA and UAE are the key import and export hubs for India India top 10 export markets India top 10 import markets (CY20, US$ B) (CY20, US$ B) 49 59 19 27 18 24 10 18 16 8 8 8 8 12 15 12 12 6 6 11 USA China UAE Hong Singapore Bangladesh UK Germany Netherlands Malaysia China USA UAE Saudi Iraq Hong Kong Singapore South Indonesia Switzerland Kong Arabia Korea Source(s): UN Comtrade, Directorate General of Commercial Intelligence & Statistics, PGA Labs analysis © PGA Labs | 14 SERVICES Logistics and Transportation Air Cargo is transferred mostly though metropolitan cities with Mumbai & Delhi cumulatively handling 60% of air cargo traffic Growth drivers for air freight market in India Growth in deployment of passenger planes as freighters City-wise total air cargo traffic at Indian airports • With the grounding of passenger planes, planes underwent conversions (MMT, FY20) into freighters • Budget operators like SpiceJet started augmenting belly space with cabin space for cargo 0.6 Demand from Pharma and Ecommerce 0.6 • Ecommerce is expected to grow five times its current size in India to US$ 200B by CY 2026 • India saw a record 18% growth in pharma exports during FY20 Development of fully digitized record-keeping 0.3 • Air cargo industry is incorporating digitization and utilization of emergent 0.2 technologies, leading to higher efficiency, reduced waiting time, and lower 0.2 costs making freight rates more competitive 0.1 Policy support for growth as a transit hub • National Air Cargo Policy 2019 aims to make India one of the top air freight markets by2025 and create shipment hubs at all major airports Delhi Mumbai Others Chennai Bangalore Hyderabad • The policy aims to leverage India’s location as a transit hub between Europe and SEA and a gateway to South Asia Source(s): Airports Authority of India, International Cargo Forwarders, Secondary research, PGA Labs analysis © PGA Labs | 15 SERVICES Logistics and Transportation Ports in Gujarat, Maharashtra and Tamil Nadu contribute to around 80% of ocean freight & also consist of a high concentration of freight forwarders Growth drivers for ocean freight market in India Robust demand 1 Region-wise ocean containerized traffic in India • Ports sector in India is being driven by high growth in external trade (MMT, FY20) • Containerized traffic at all ports of the country reached approx. 246 million metric tonnes in FY20 Attractive opportunities 86 • Key ports are expected to deliver seven projects on a public-private partnership basis in FY22 61 56 Policy support • Union Budget 2021 announced subsidy funding worth 1,624Cr to Indian shipping companies 18 Competitive advantage 13 8.6 • India has a coastline more than 7,517km long interspersed with 200+ ports 2.3 1.3 • Most East Asia, America, Europe and Africa cargo ships pass through Indian Tamil Nadu Maharashtra Andhra West Bengal Kerala Karnataka Others Gujarat territorial waters Pradesh Note(s): Others includes Orissa, Goa, Puducherry, Andaman and Nicobar Islands and Lakshadweep Islands © PGA Labs | Source(s): Ministry of Shipping, Secondary research, PGA Labs analysis 16 SERVICES Logistics and Transportation The container market in India is witnessing increased use of technology to streamline operations • Shipping container shortage: The busiest trade routes are thriving, but port congestion is still a real problem. Many ports struggle to deal with the backlog of containers, and ongoing trade means they continue to pile up. There is currently a race for container manufacturers to produce adequate supplies of new storage carriers • Freight rate instability: In December 2020, spot freight rates were over 260% higher from Asia to North Europe than the previous year. Rates per 40 ft. container went from around US$1,400 in April 2020 to almost $5,000 in April 2021. • Digital transformation: Carriers use technology to streamline freight booking, particularly spot booking. Due to the volatility of freight over the past year, short-term bookings are extremely popular. The growth in this area has made digital spot booking an emerging trend for 2021. • Increased focus on sustainability: Major shipping companies are committed to neutralizing carbon emissions as part of the “Mission 2020-Zero Emissions”. The shipping industry represents approximately 2.2% of all global greenhouse gas emissions, and it is expected to rise by 50% by 2050 if action isn’t taken. • Increased cybersecurity: With an increased reliance on technology, there is an increased risk of cyberattacks. From 2017 to the present, almost half of the top 10 freight carriers worldwide were victims of digital security breaches, including a $300 million loss from Maersk due to a ransomware cyberattack. Source(s): PGA Labs analysis © PGA Labs | 17 SERVICES Logistics and Transportation TAM of the Indian freight forwarding market is expected to reach US$ 8B by FY26 owing to improved transportation infrastructure and government policy support Growth drivers for freight forwarding volume in India TAM of Indian freight forwarding market (US$ B, FY17-FY26P) CAGR FY20-26P 1 • The SEIS is expected to be revamped, offering exporters duty credit 8.0 scrips at 5-7% of the net foreign exchange earned 3.3% 0.16 3.5% 6.5 6.5 2.0 2.4% 0.13 0.13 6.1 5.9 0.12 0.11 • Automation, AI, ML, data analytics, and IoT are significantly contributing 1.9 1.7 to increasing operational efficiency 1.6 1.9 2 • For merchandise exporters, RoDTEP is expected to be a part of the new FTP, which offers reimbursement of central, state, and local taxes/duties 3.6% 4.2 4.1 4.5 4.7 5.8 • Improved transportation infrastructure and rising competitiveness among FY17 FY18 FY19 FY20 FY26P domestic companies Ocean Freight Air Freight Customs Note(s): (1) Service Exports from India Scheme; (2) Remission of Duties and Taxes on Exported Products, (3) Target Addressable Market © PGA Labs | Source(s): Shipping Ministry, Ministry of Civil Aviation, Industry interviews, Secondary research, PGA Labs analysis 18 SERVICES Logistics and Transportation Indian ocean freight is concentrated towards the Americas and APAC while air freight is concentrated towards EMEA Indian ocean freight market Indian air freight market (US$ B, FY17-26P) (US$ B, FY17-26P) 5.8 0.3 1.0 4.7 4.5 0.3 0.3 4.2 4.1 0.2 0.8 0.8 0.2 1.1 0.7 0.7 0.9 0.9 1.9 1.9 1.7 2.0 0.8 0.8 1.6 1.4 0.6 0.7 0.7 0.7 0.6 1.1 1.1 1.0 1.0 0.2 0.2 0.2 0.2 0.2 0.6 0.6 0.6 0.6 0.5 1.9 1.4 1.3 1.5 1.5 0.3 0.3 0.3 0.3 0.3 0.05 0.1 0.1 0.1 0.1 FY17 FY18 FY19 FY20 FY26P FY17 FY18 FY19 FY20 FY26P Americas APAC Europe China & North Asia Middle East and Africa Americas APAC Europe China & North Asia Middle East and Africa Source(s): Shipping Ministry, Ministry of Civil Aviation, Industry interviews, Secondary research, PGA Labs analysis © PGA Labs | 19 SERVICES Logistics and Transportation The India market is witnessing activity in the digital freight forwarding space; however, the other spaces are dominated by traditional players Digital freight Traditional freight 10K+ freight forwarders forwarding forwarding (500 are organized players) Marketplace SaaS Provider Service Provider Customs Insurance Trade Finance Source(s): Tracxn, Company websites, PGA Labs analysis © PGA Labs | 20 SERVICES Logistics and Transportation Digital freight forwarding in India: Overview of key players and global benchmarks Digital Traditional Global Model Marketplace SaaS Provider Service Provider Company 2016 2015 2015 2019 2009 1997 2013 Founded 31 7.89 4.9 5 NA NA 1300 Total funding (US$ M) NA NA Key investors • Online platform for • Freight forwarding • Tech-enabled freight • Freight forwarding • Integrated logistics • Supply chain • Online Freight Brief description freight forwarding platform and supply forwarding services platform to manage solutions provider management and forwarding platform chain visibility provider partner for consigners end-to-end operations across a supply chain logistics solutions to manage end-to-end operations • Ocean, air and road • Ocean, air and road • Ocean, air and road • Ocean, air and road • Ocean, air and road • Ocean, air and road • Ocean, air and road Modalities • Customs • Advisory services • Customs • Customs • Customs • Customs • Customs Value added services • Trade finance • Inland trucking • Trade finance • Advisory services • Advisory services • Advisory services • Trade finance • Insurance • Planning and analytics • Insurance • Insurance • Insurance • Insurance • Insurance • Testing • Trade advisory • 149 countries • India, MENA, SEA • 40+ countries • SEA, Europe, USA • SEA, Europe, USA • SEA, Europe, USA • SEA, Europe, USA Geographic presence 1 30K+ 15K+ 2K+ 15K+ Global Global Global # of customers - - 4L+ 24M+ Revenue (US$ M) 77.3 2 3.5 2 2 269 (FY19) 3100 (21E) Note(s): Businesses enrolled with provider , 2 - K+N’s Indian operations are considered © PGA Labs | Source(s): Tracxn, Company websites, PGA Labs analysis 21 SERVICES Logistics and Transportation Global players like K+N have superior product feature stack, whereas digital and traditional Indian players need to catch-up in terms of certain service offerings Digital Traditional Global Model Marketplace SaaS Provider Service Provider Core Services Ocean freight Air freight International trucking International rail freight Inland haulage & warehousing Customs clearance Trade finance Cargo insurance Value added services Inland trucking Inland rail Cargo inspection Specialized trade advisory Tech–based services Milestone based tracking GPS tracking Descriptive analytics Predictive analytics Document handling Automated invoicing Instant rate generation © PGA Labs | Source(s): Company websites, Secondary research, PGA Labs analysis 22 SERVICES Logistics and Transportation Customer profile of key players Digital Traditional Global Marketplace SaaS Provider Service Provider Company 15K+ # customers 30K+ 2K+ - - 4L+ 24M+ • USP • Voice assistant • • • • • Full-stack player to Instant rate Partnership with Full-stack Extensively Specialized • Maersk Spot Multifaceted offer door-to-door generation player to offer networked contract and • Instant quote value capture multimodal and superior door-to-door with over 60+ project generation for for end solutionsand credit availability multimodal offices across logistics select ships & customers supply chain solutions India lines visibility Marquee customers • Online inbound Channel mix • Online inbound • Online inbound • Online inbound • Online inbound • • Online inbound Online inbound • Sales Team • Sales Team • Sales Team • Sales Team • Sales team • Sales Team • Sales Team • Partners • • • • • • Agents Agents Agents Agents Agents Agents • Manufacturing Key verticals • • • • • • Infrastructure FMCG FMCG Automotive Automotive Ecommerce • Courier Express • Logistics • Electricals • Infrastructure • Electronics • FMCG • High value • Retail goods • FMCG • Infrastructure • Automotive • Glassware • Electricals • Freight Forwarders • Automotive • Logistics and ancillaries • Infrastructure • Infrastructure • Packaging • Quick service • Pharma • Retail • Logistics • Agriculture • Pharma and • Electronics • Electricals • Healthcare Lifestyle • Small Client size mix • Small • Small • Medium • Medium • Medium • Medium • Medium • • • • Large • Large • Large Medium Medium Large • Large • Large • Large SoW of digital freight forwarders has risen to 15-20% in the last few years; estimated to reach 35-45% in Customer share of • the next few years as players gain specialization in more trade lanes, enter contracts with carriers for wallet (SoW) for digital additional capacity and enhance their technology platform with additional services freight forwarders © PGA Labs | Source(s): Company websites, LinkedIn, Primary discussions, PGA Labs analysis 23 Our team Abhishek Maiti Kiran Achanta Arindam Gupta Industrial Good & Services, Technology & Internet Healthcare & life sciences Technology & Internet Roma Dixit Tarak Pandey Vamsi Krishna Financial Investor Group, Financial Services Technology & Internet Consumer & Retail Parul Garg Vaibhav Tamrakar Prasun Dey Consumer Fintech, Ed Tech & Food Tech Technology & Internet Praneet Singhal Abhilasha Jaju Bharanikaran Karunakaran Technology & Internet Financial Services Healthcare & life sciences We understand the LogisticsTech space very well and have experience in several pieces of deep research work • Conducted deep research on Logistics SaaS and its growth drivers in India • Estimated market size of e-commerce retail & D2C logistics space in India which act as the key growth drivers of e-commerce Logistics. Also, benchmarked key trends in D2C space in India • Mapped various Logistics supply chains and value chains from first-mile to last-mile including e-commerce logistics • Benchmarked critical metrics of competitor intelligence including delivery closure rates, % damaged shipment, % RTO shipment, etc. across major LogisticsTech players in India • Estimated trip economics for various value chain participants in transportation business across geos • Conducted deep supply side surveys / IDIs of truckers / DCOs (driver cum owners) • Also conducted deep demand side in-depth interviews to understand customers of Logistics aggregator platforms © PGA Labs | 24 Connect with us We will be happy to share perspectives Abhishek Maiti Milan Banthiya Director Business Associate PGA Labs PGA Labs For media queries, please contact Vaishnav Kumar Rai Manager - Marketing E: communications@pgalabs.in M: +91 78389 55743 New Delhi | Gurugram | Mumbai | Bengaluru www.pgalabs.in Disclaimer: This material has been prepared by PGA Labs, which is the trade name of Praxian Global Private Limited (“PGA”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the viewers on the internet but should be referenced to PGA Labs, if reused or adapted in any form or in any forum. The frameworks, approaches, tools, analysis and opinions are solely PGA’s intellectual property and are a combination of collection of best data we could find publicly, and PGA Labs team’s own experiences and observations. We make no representation or warranty, express or implied, that such information is accurate or complete, and nothing contained in here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing Recipient, its business and the markets within which it operates, nor all possible market conditions. No responsibility or liability whatsoever is accepted by any person including PGA or its Business partners and affiliates and their respective officers, employees or agents for any errors or omissions in this document. Any and all logos of companies used in the post have been published for information purposes only and PGA Labs does not hold any and all liability in connection therewith. This document is not complete without an accompanying oral discussion and presentation by PGA though PGA is not obligated to do so. PGA does not have any duty to update or supplement any information in this document. PGA shall not be responsible for any loss sustained by any person who relies on this presentation. The team at PGA Labs appreciates your time and support THANK YOU Enabling better decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, CP-003, 004, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District GF Tower 4B, DLF Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 Corporate Park, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram -122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Praxian Global Pvt. Ltd., Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025