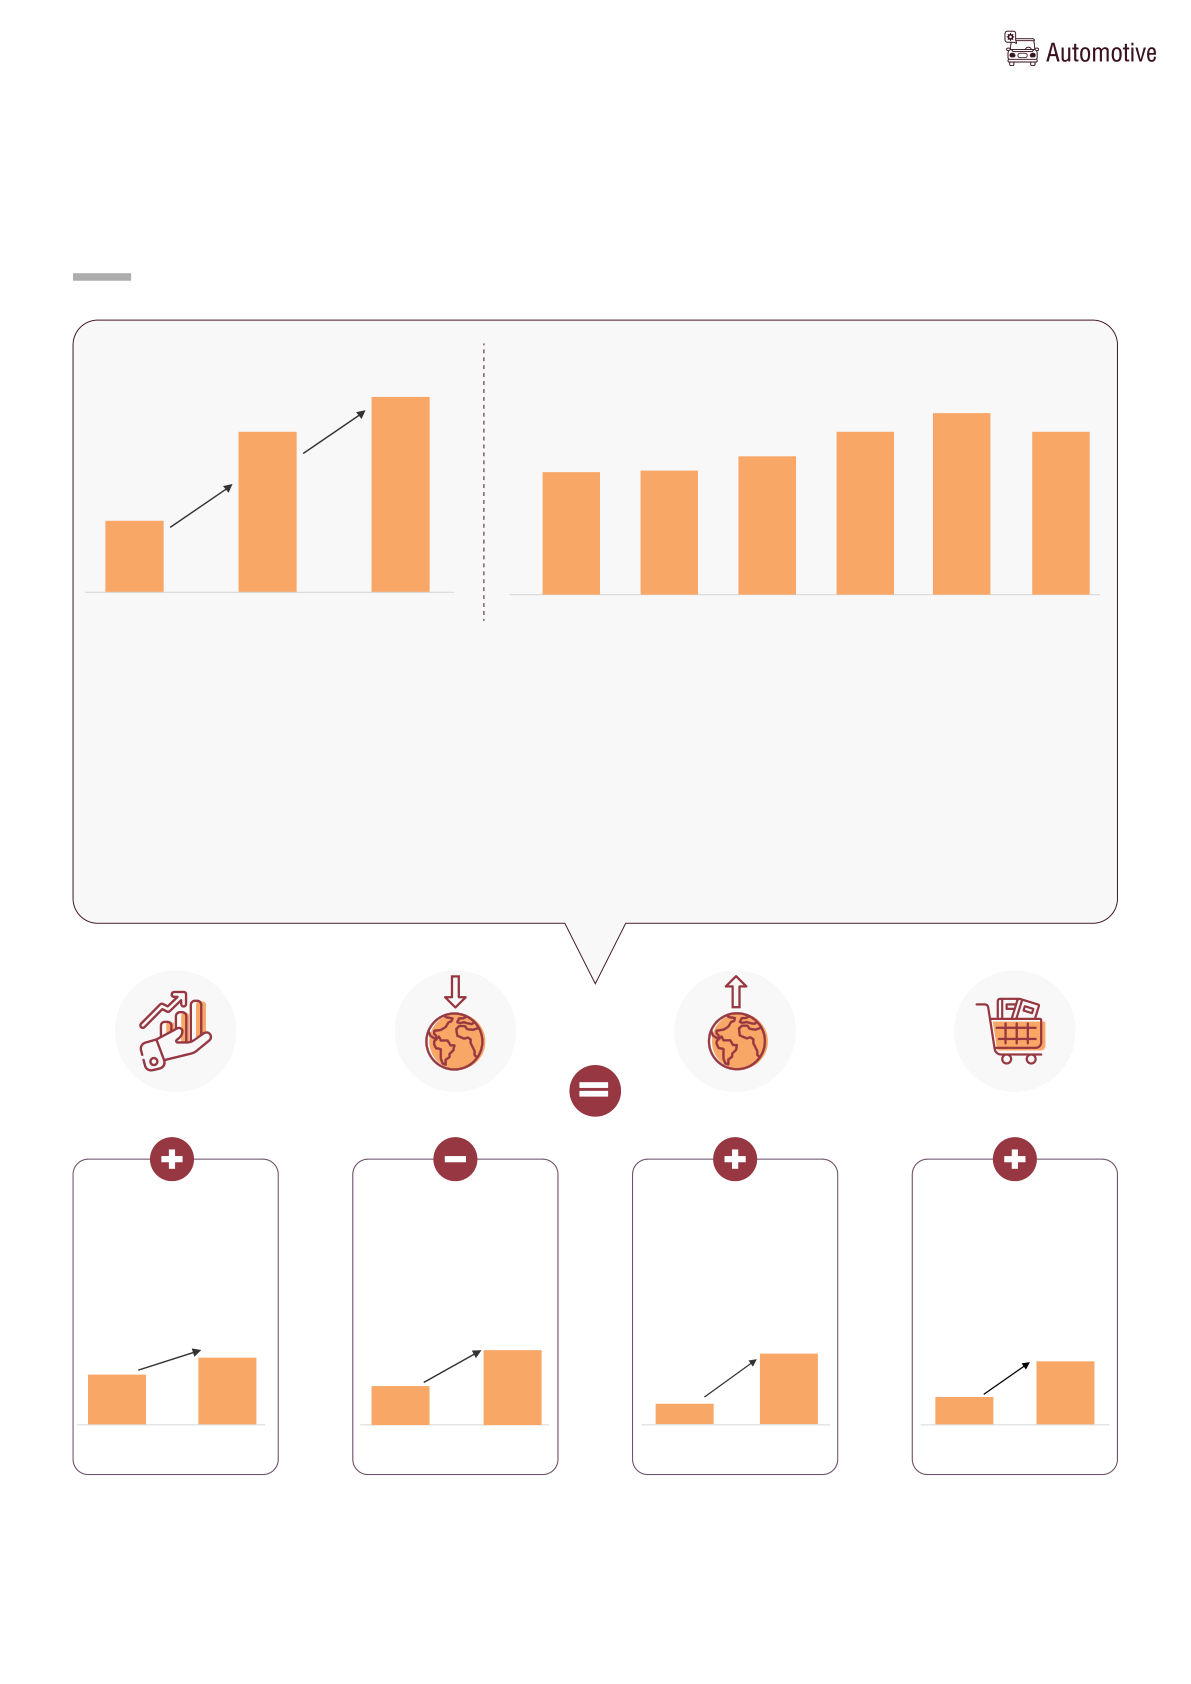
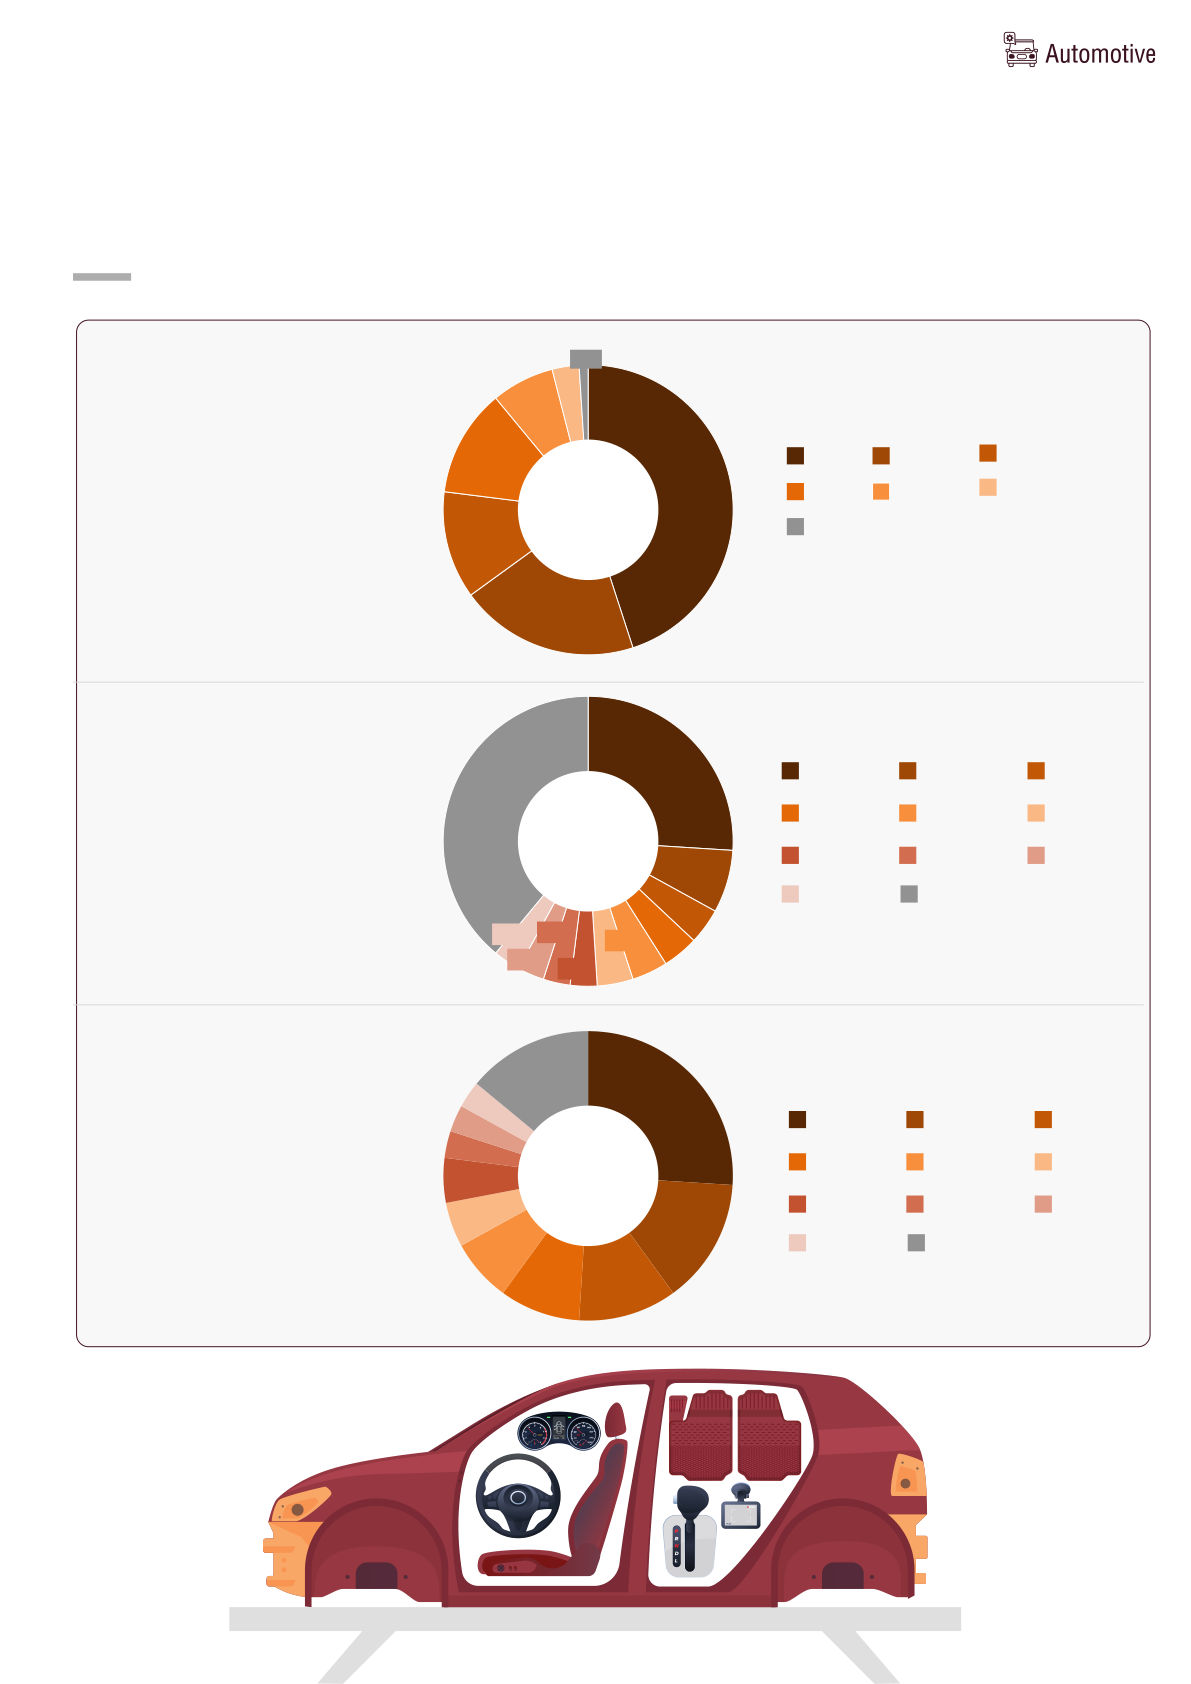
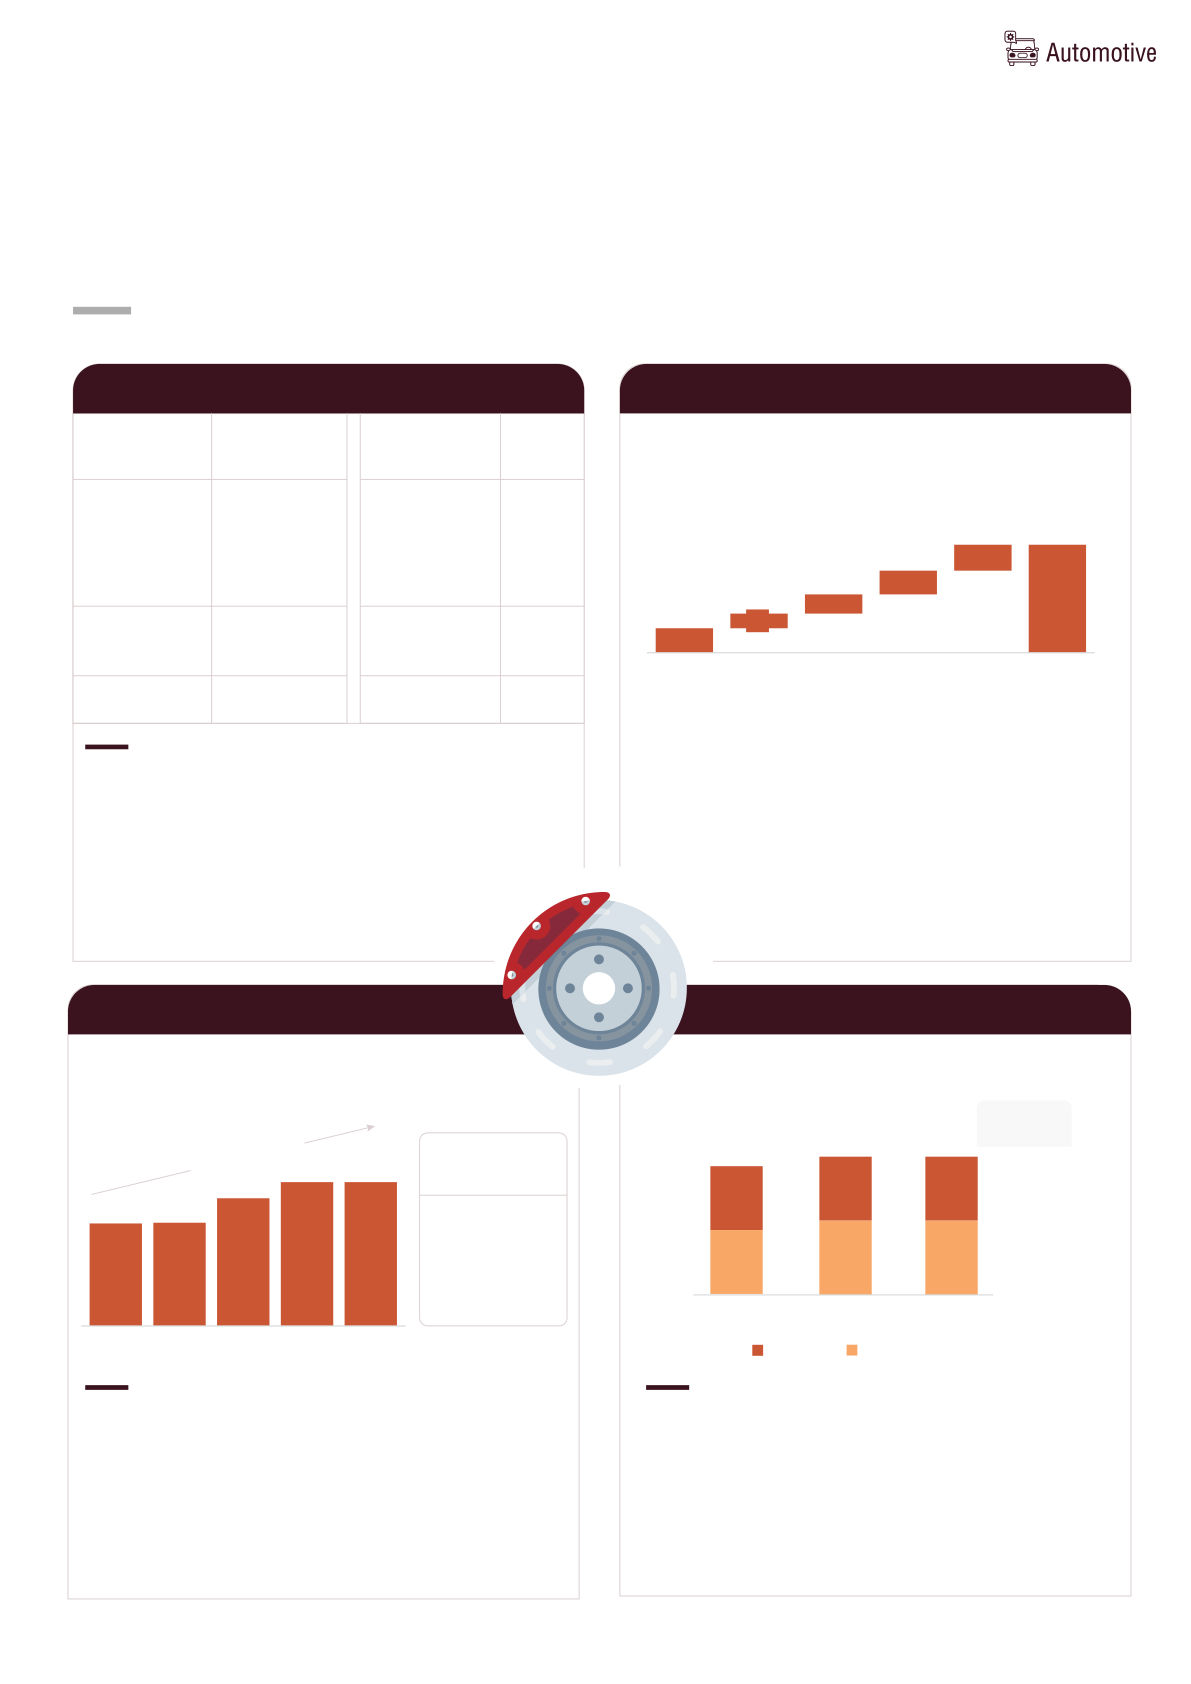
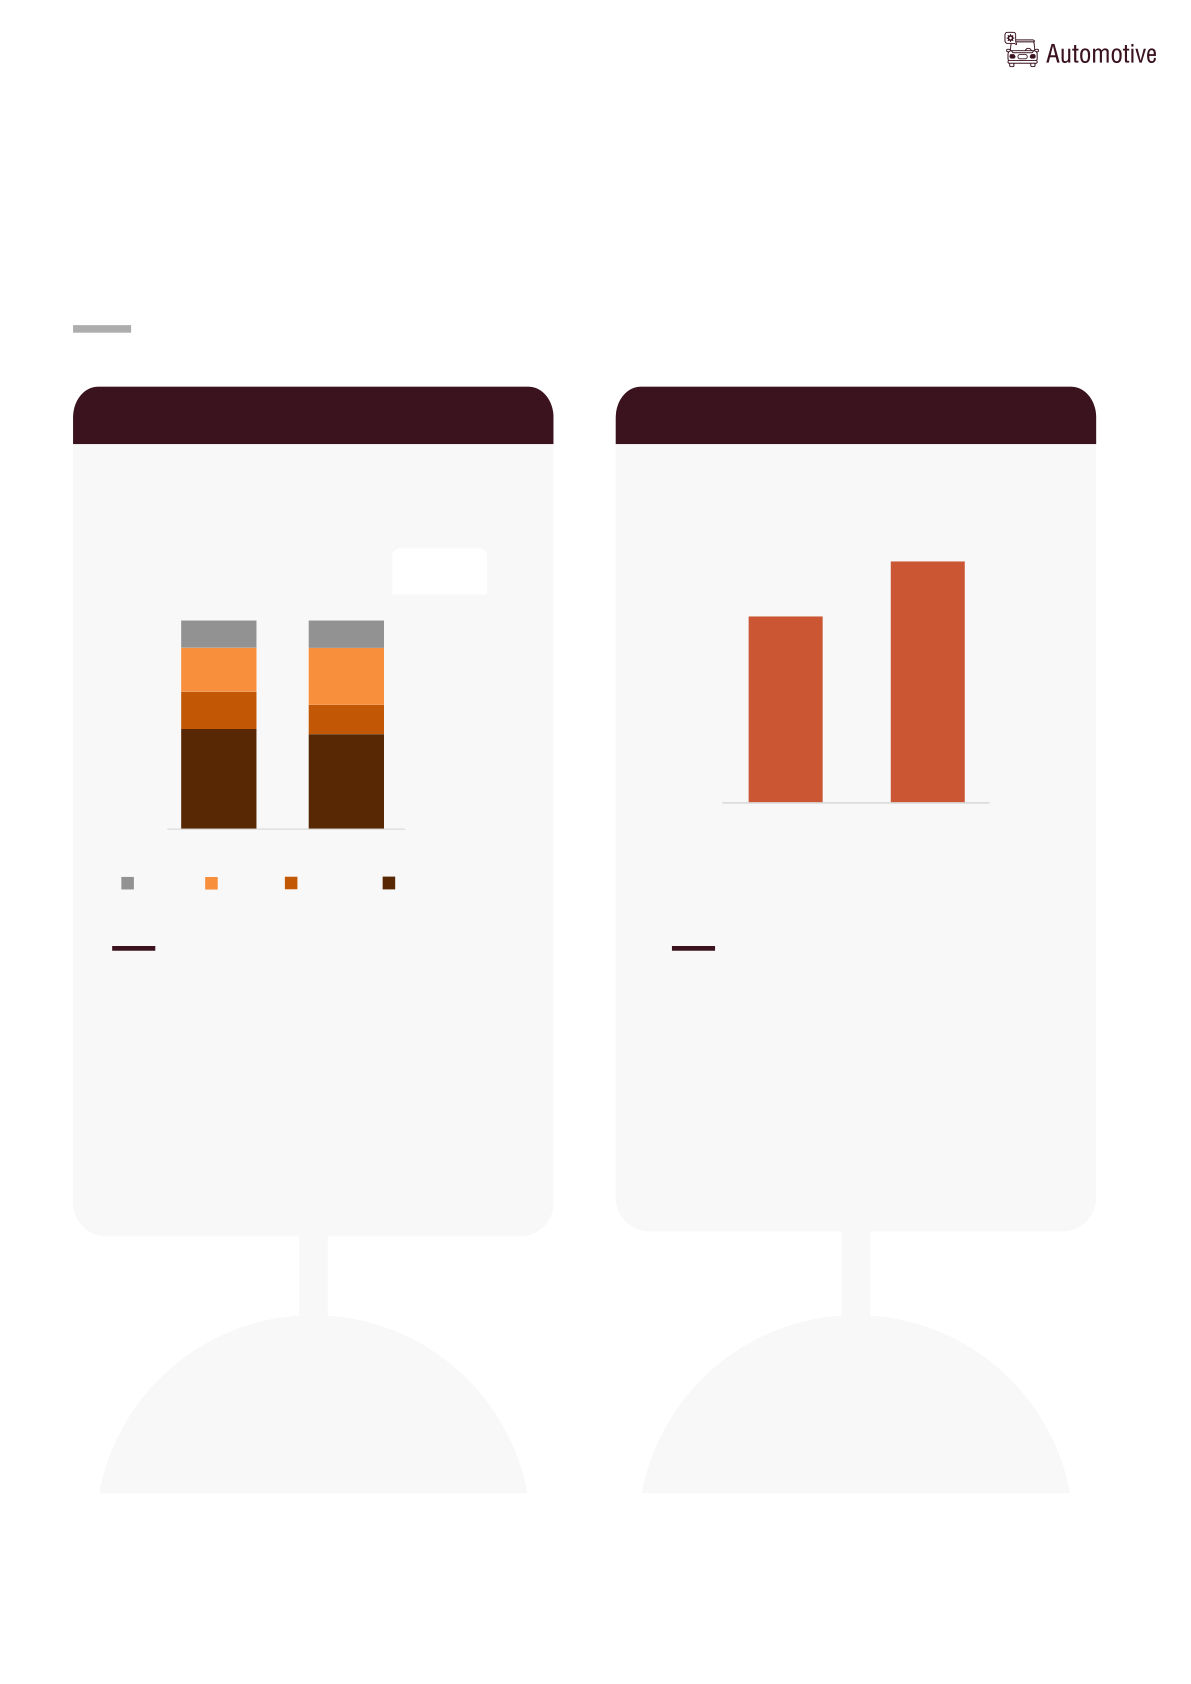
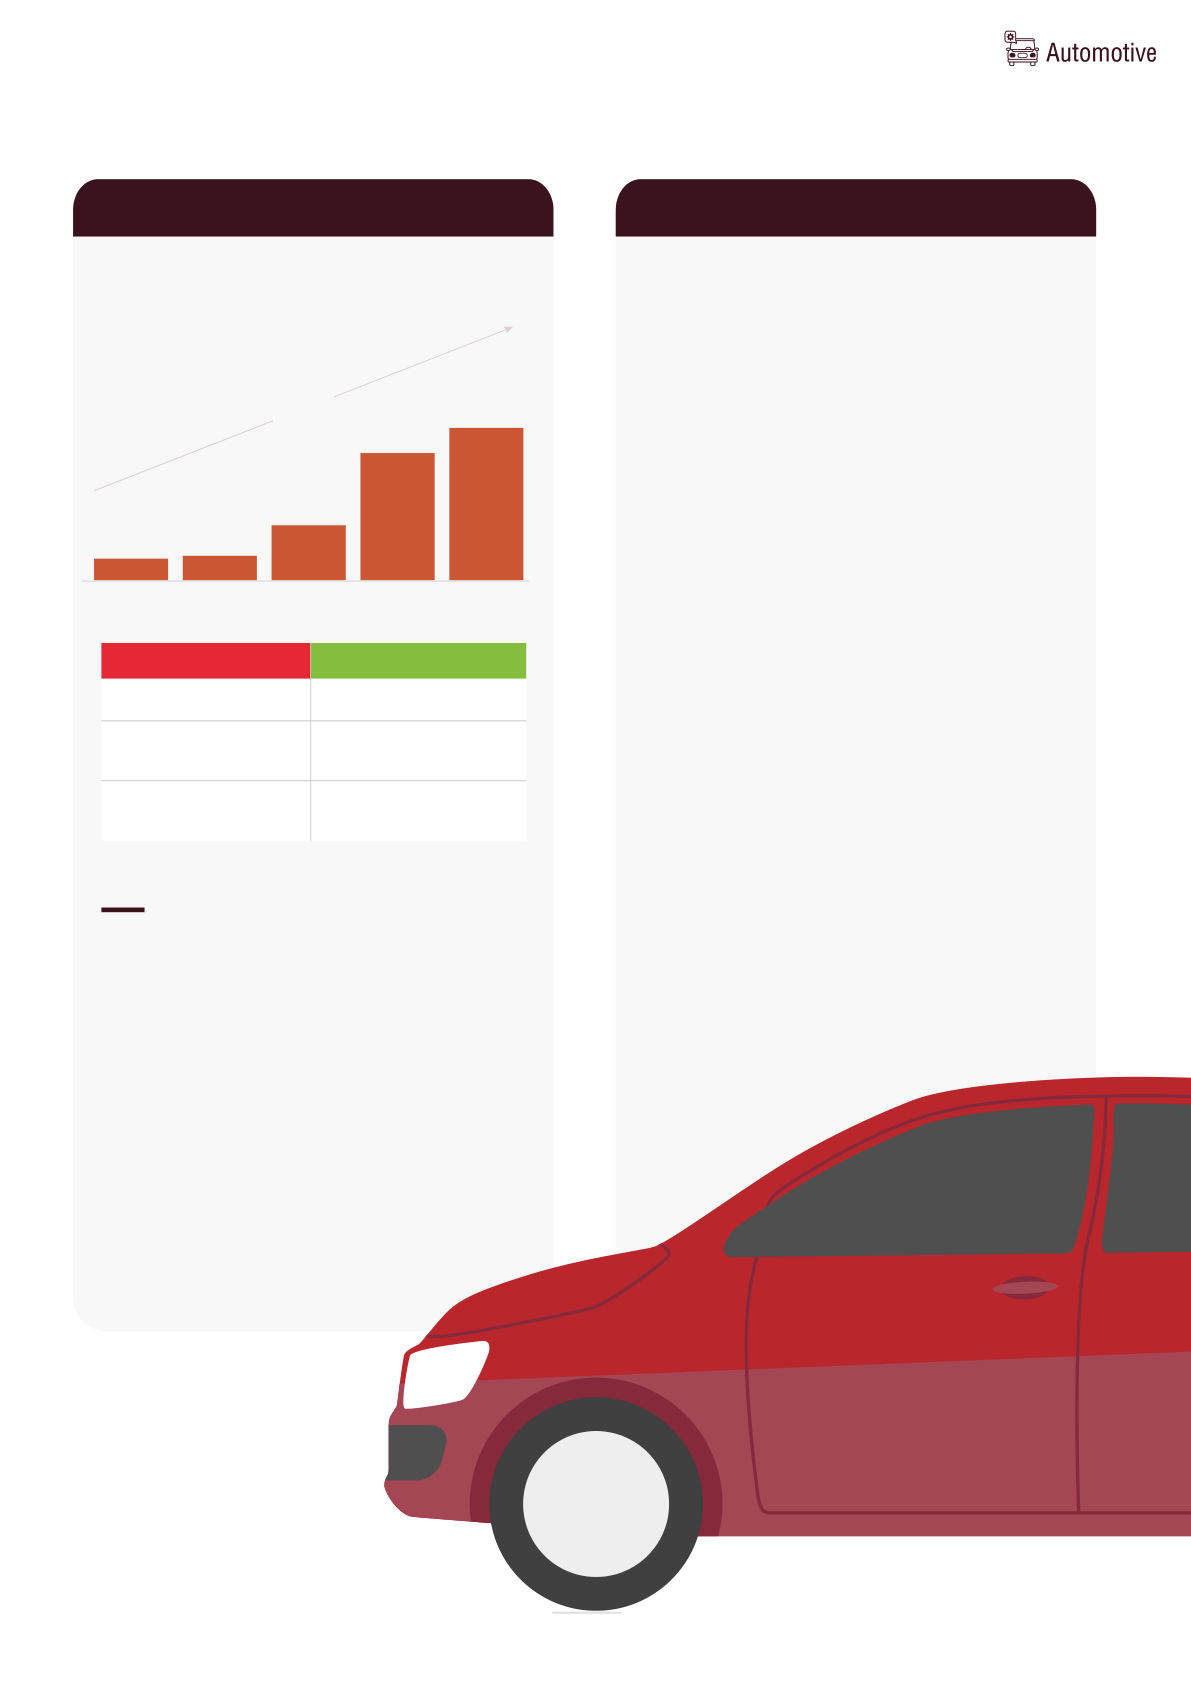
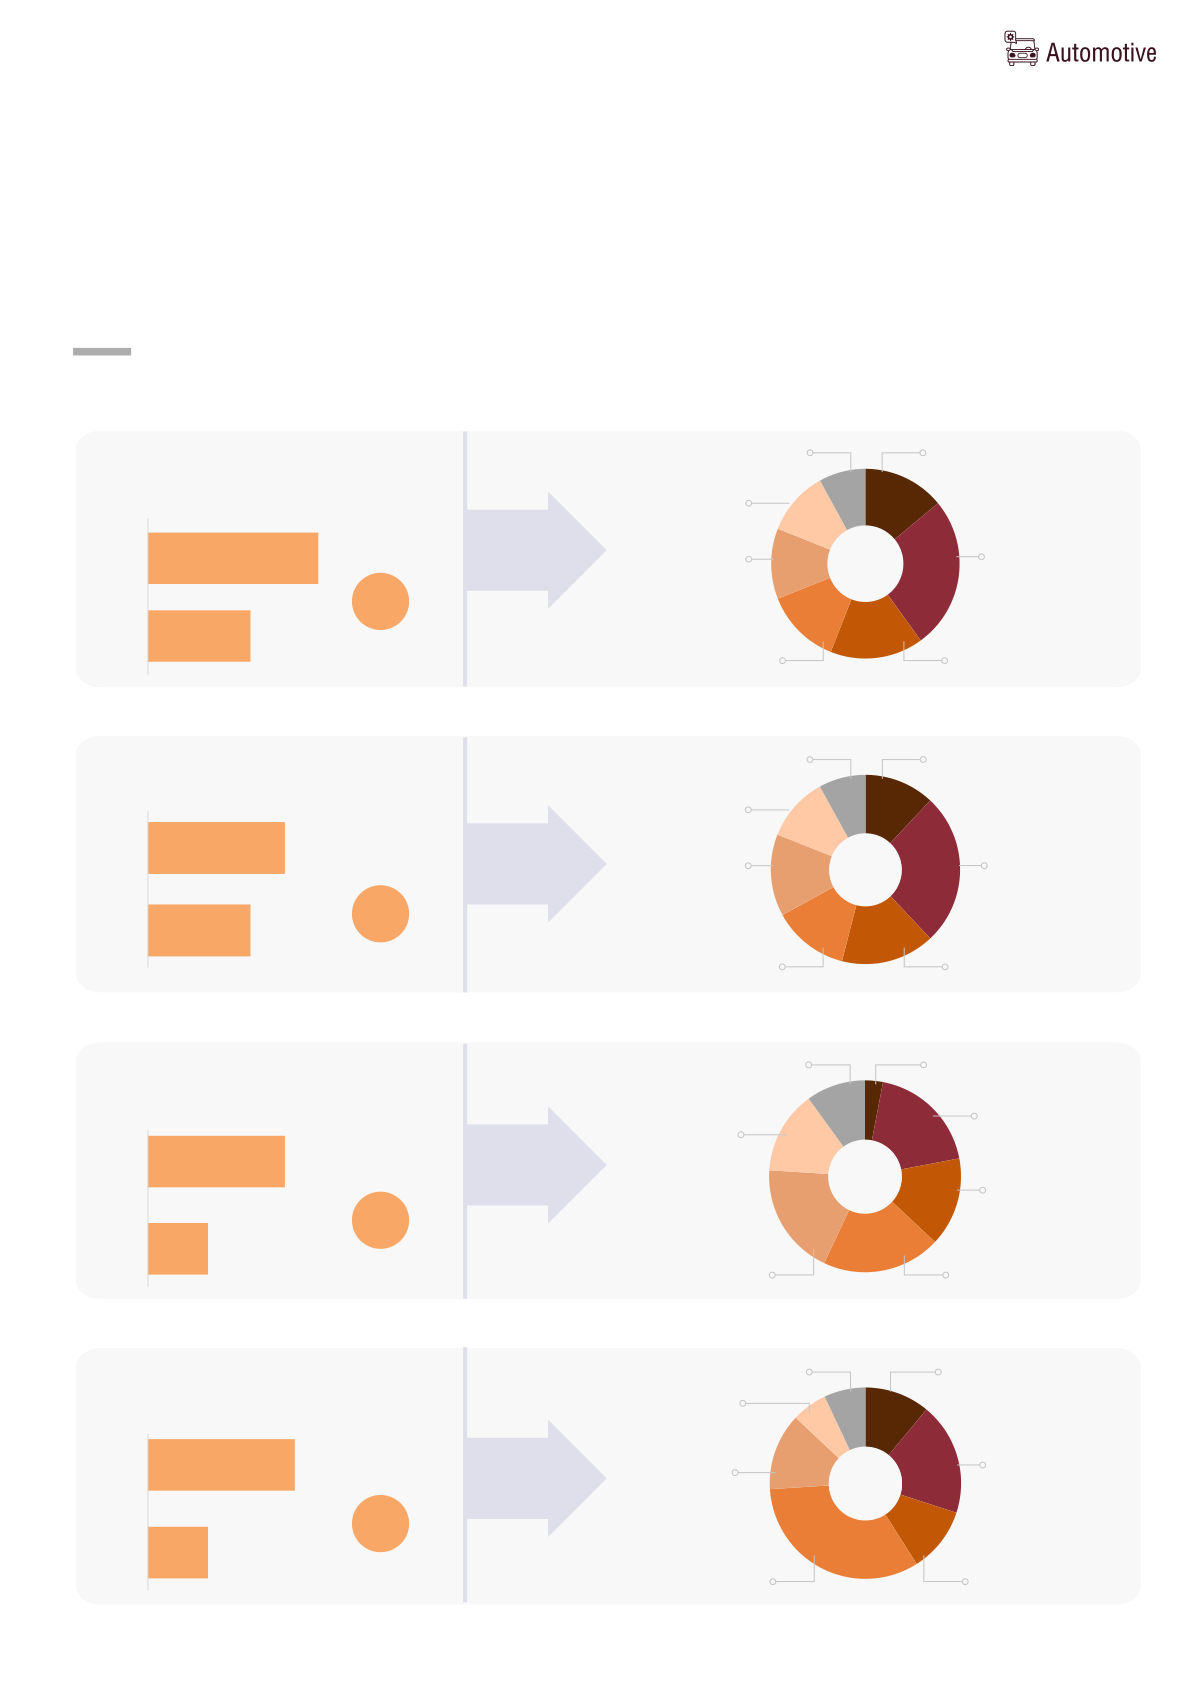
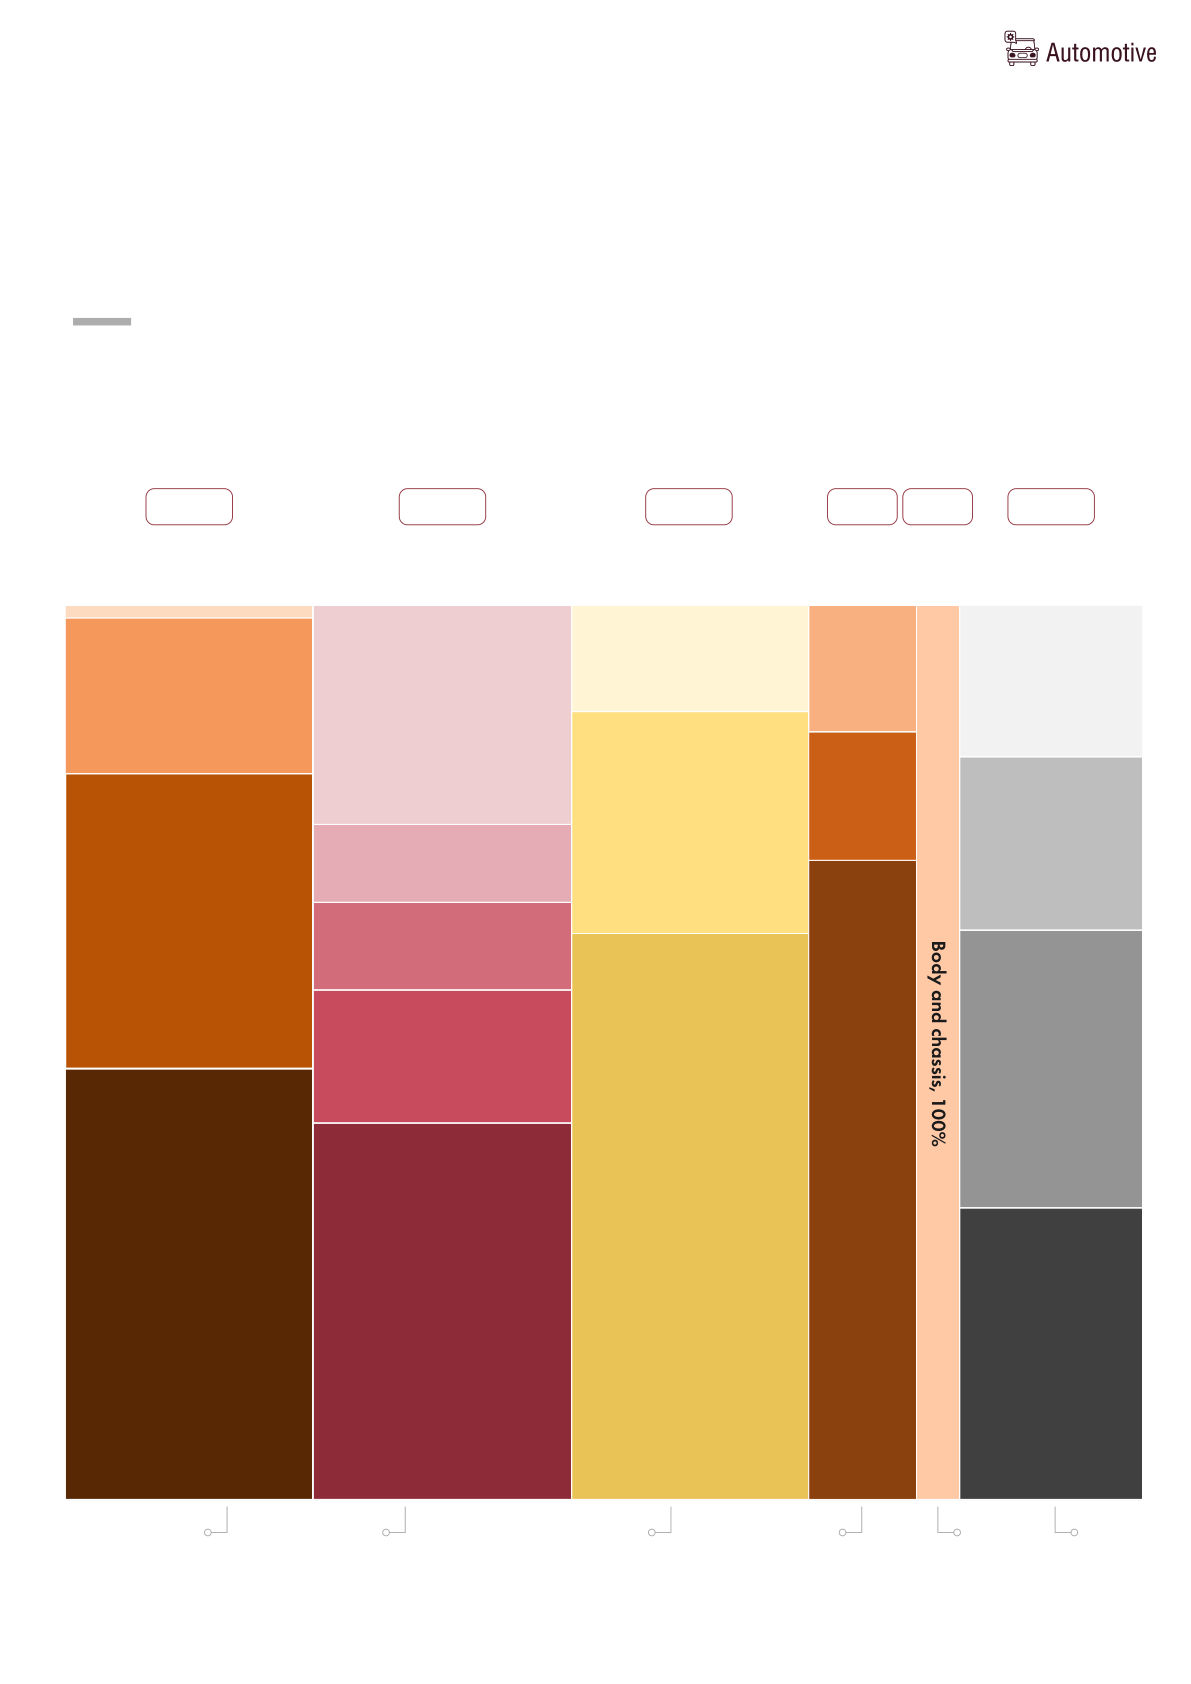
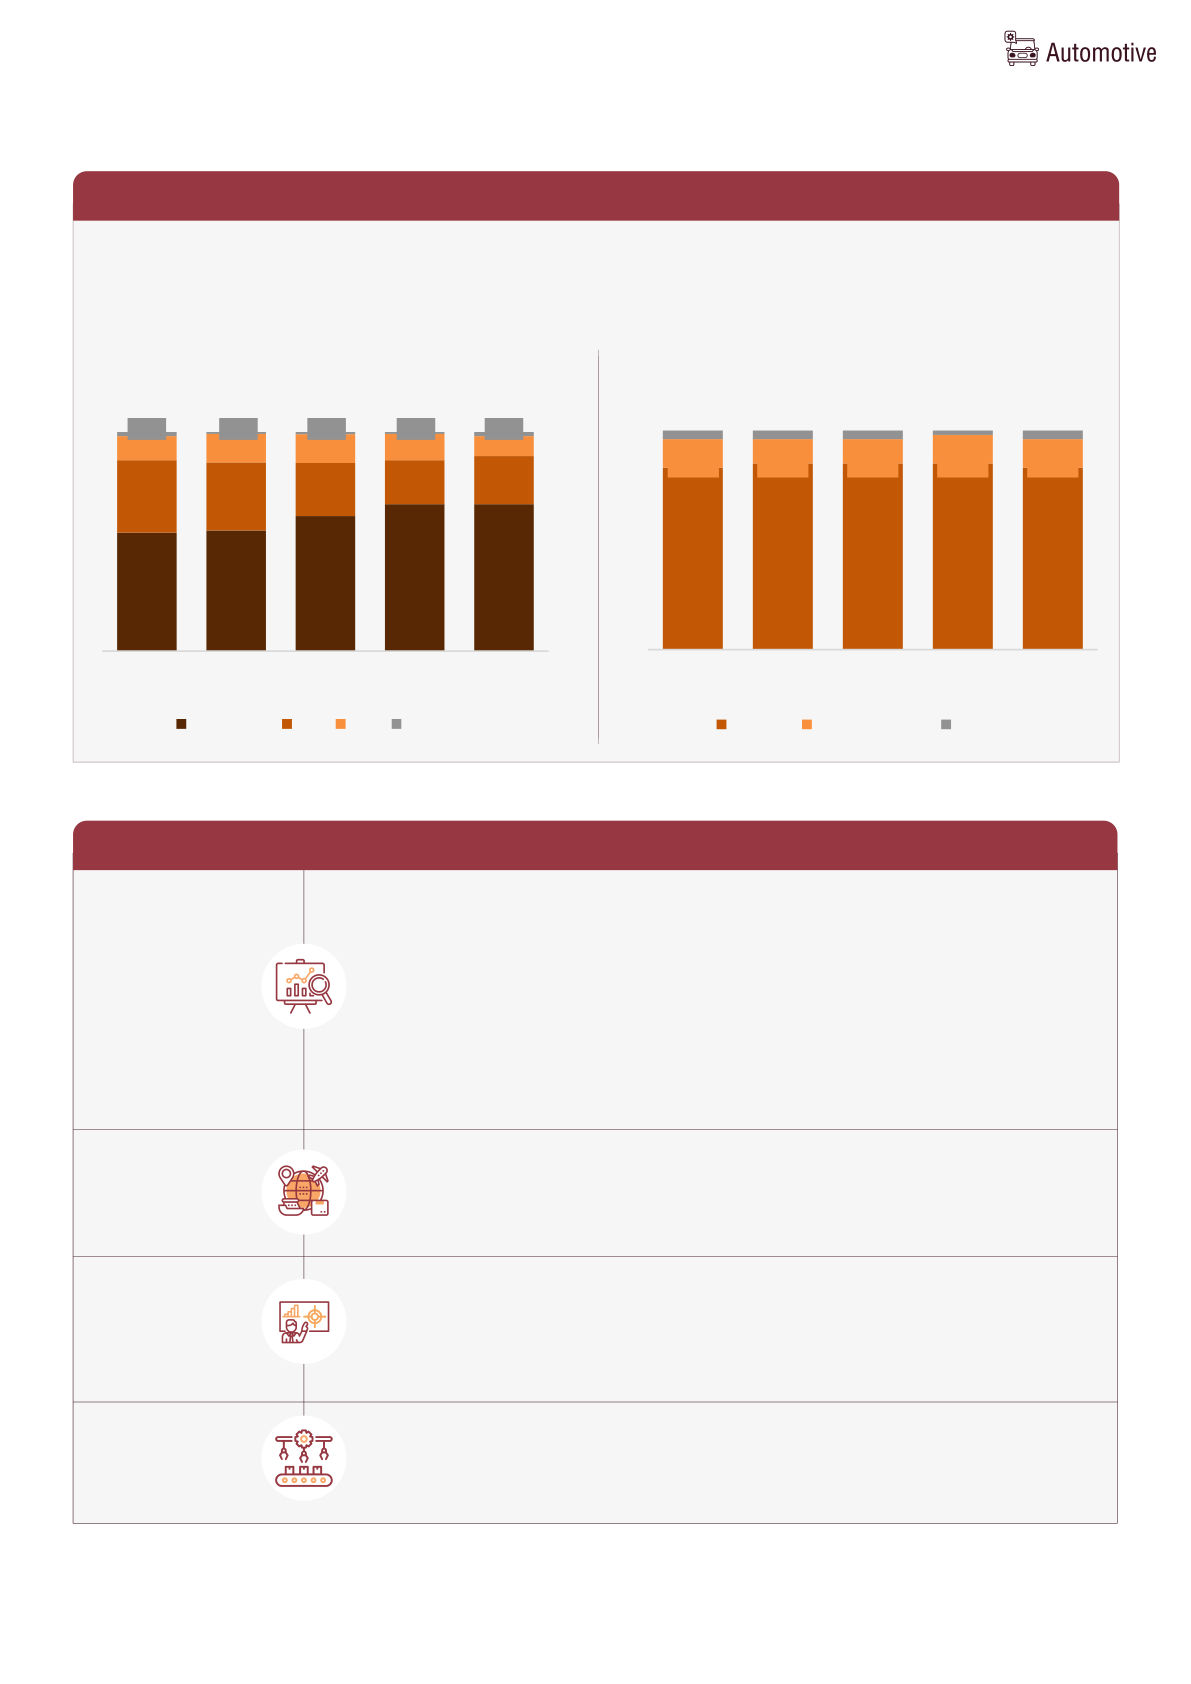
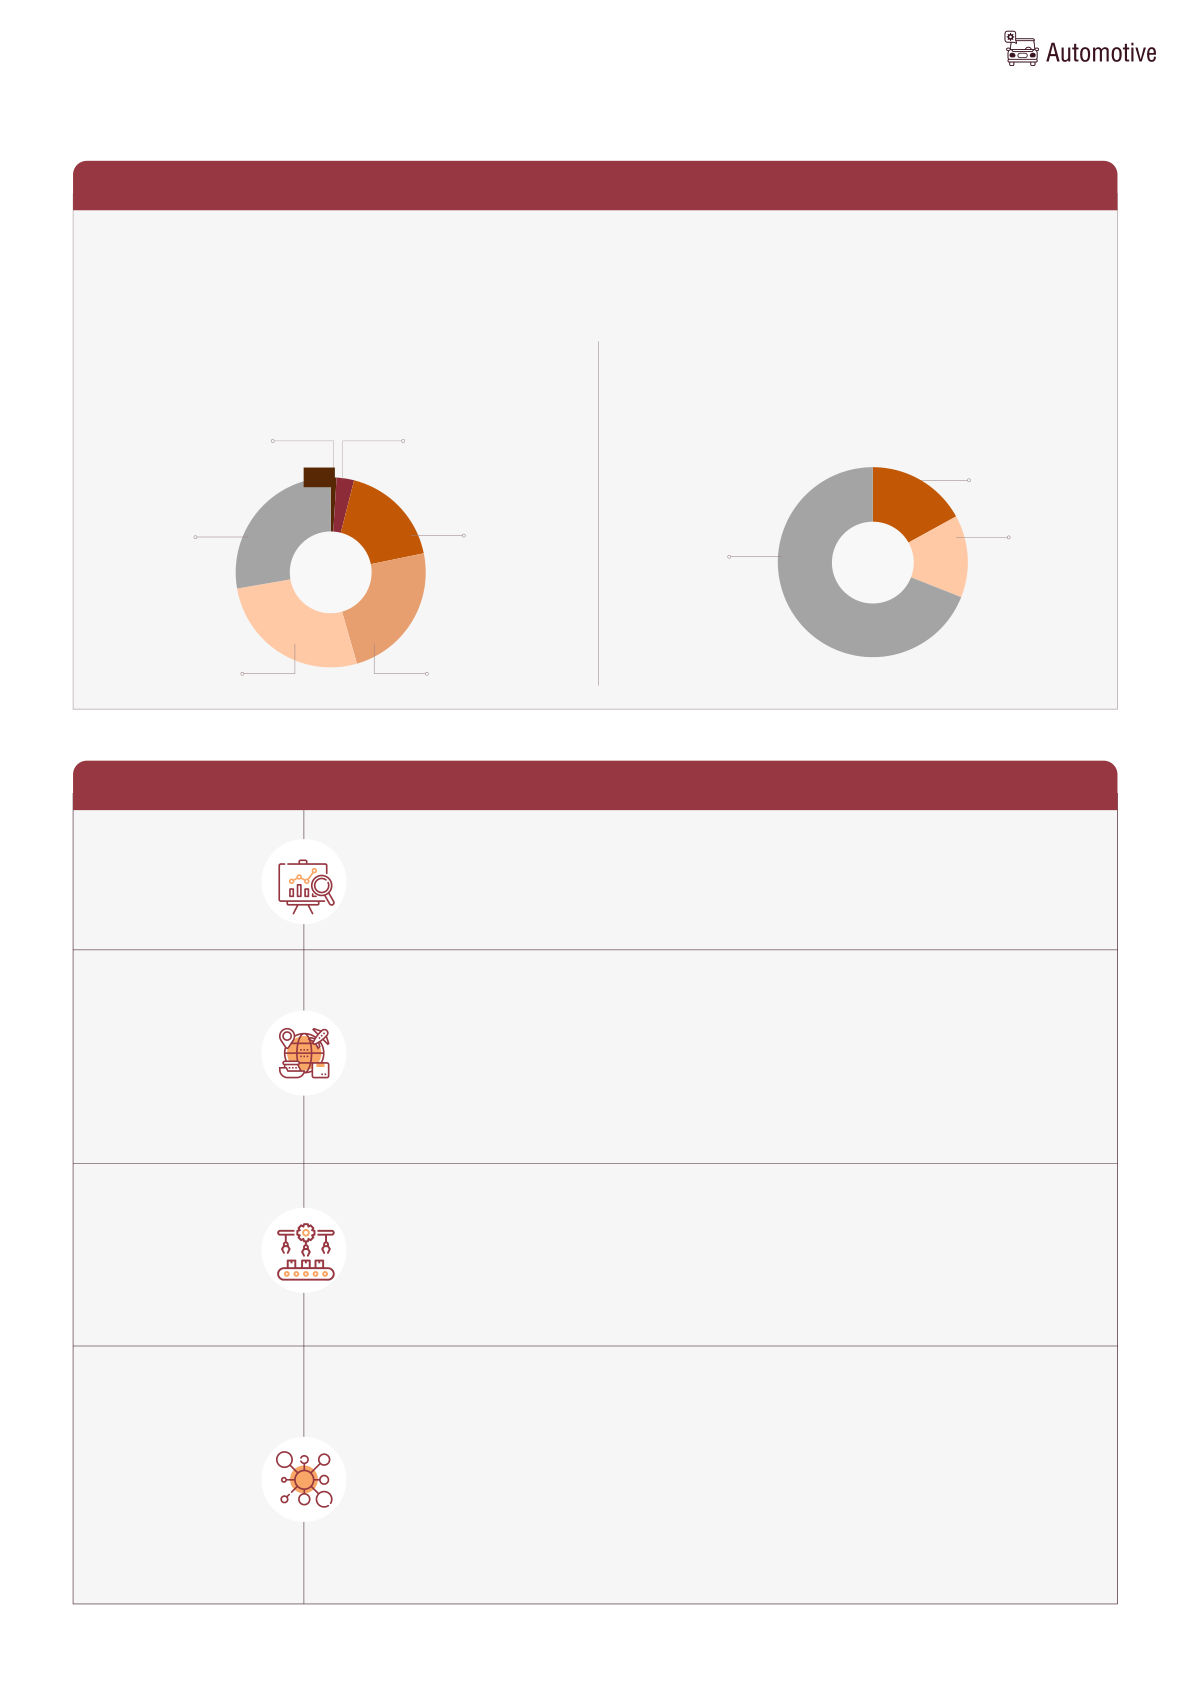
AUTO COMPONENT MANUFACTURING SECTOR Confidential and proprietary © PGA Labs October , 2022 Contents Foreword 3 Glossary 4 Key takeaways 5 Executive summary 6 ACM industry in India 7-8 ACM industry in India - outlook 9 ACM industry trends 10 Market dynamics 11 OEM landscape 12-13 Technology 14-15 Policy and regulatory 16 ACM segments 17-18 Component segments 19 Suspension & braking 20-21 Transmission & steering 22-23 Electrical & electronics 24-25 Engine components 26-27 Focus areas for suppliers 28 Foreword India's auto-component manufacturing (ACM) sector is likely to register robust growth on the back of a growing middle class and working population, as well as a surge in electrification of vehicles. The ACM industry in India has traditionally been a substantial contributor to the national GDP and employs over 50 lakh people. ACM industry’s revenue is estimated to rise from US$ 49 billion in FY20 to US$ 67 billion in FY25. Passenger vehicle (PV) segment receives 45 percent of ACM supply, while 2W receives 20 percent. We have seen a tactical shift among ACM players, with more emphasis on localization and exports. Companies in the ACM sector are trying to expand their position in the used car and aftermarket segments. We are also witnessing that technology-focused partnerships are influencing the auto component industry. We have analysed the key trends impacting the ACM industry, historical growth of major segments of the auto-components market and strategic initiatives undertaken by some of the key players in each segment in this report. We have also highlighted fresh demand segments and discussed the factors that drive them. This report further underlines the need for technology upgrades, standardisation, and integration across the automotive supply chain to help suppliers grow in the present market. The auto-components market in India is rapidly evolving, and some of the scenarios presented here may have slight variations. Contact us for the latest updates. We, at PGA Labs, look forward to continuing the discussion with our friends across sectors, and exchanging notes as the situation evolves. Abhishek Maiti Director Glossary Acronyms Description CAFE Corporate average fuel efficiency CAGR Compounded annual growth rate CASE Connected, autonomous, shared and electrification CV Commercial vehicle EV Electric vehicle FAME Faster adoption and manufacturing of hybrid and electric vehicles FDI Foreign direct investment FFV Flex fuel vehicle GDP Gross domestic product NEMMP National Electric Mobility Mission Plan OEM Original equipment manufacturer OES Original equipment supplier PLI Production linked incentive PV Passenger vehicle R&D Research and development SUV Sport utility vehicle Key takeaways • Indian auto components industry Govt. policies are supporting the sector accounts for 7.1% of the national GDP with 100% FDI allowed under the and contributes 49% to the automatic route, PLI scheme for ACM manufacturing GDP of India sector • Exports segment has been the fastest • Initiatives like “Make in India” and growing, with a CAGR of 13% over 10 NEMMP 2020 will boost the local ACM years (FY10 to FY20), with North industry in the near future America and Europe emerging as the • EVs and SUVs will lead the growth of PVs biggest markets accounting for a in India; focus will be on R&D to boost combined share of 60% of overall the early adoption of new technologies exports • CASE (connected, autonomous, shared, • Indian auto components market is and electrification) is gaining strong gearing towards greater localization traction in India; technological and players are looking to increase innovations & partnerships are shaping presence in used cars, aftermarket, and the components market export segments • Increased push from Govt. for • Recent policy level initiatives have electrification through FAME II, PLI presented an opportunity to the ACM scheme, and CAFÉ norms designed to segment entities for growth and reduce carbon emissions from vehicles movement up the value chain; will give boost to EV manufacturers © PGA Labs | 05 Executive summary • The four major customer segments in the growing demand; reducing the gap in ACM industry are OEM segment, global and Indian emission norms will exports, imports, and domestic boost exports in transmission & steering aftermarket with exports being the • Electrical & electronic parts will witness fastest-growing segment increasing demand on the back of • The major component segments are growing demand for SUVs and EVs suspension & braking, electronics & • EVs and technological enhancements electricals, and engine components with will disrupt the market for engine 70% of the top 20 players’ business components coming from these three segments • Strategies mainly focusing on • Suspension & braking segment is technology upgrades, standardization, poised for growth from aftermarket and and integration across the automotive exports value chain will help suppliers grow in • New offerings like automatic the current market transmission systems are witnessing © PGA Labs | 06 ACM industry in India Auto component manufacturing (ACM) industry – A key driver of Indian economy ACM industry revenue Year wise turnover (US$ B, FY10-25P) (US$ B, FY15-20) CAGR 6% CAGR 5% 57 67 51 51 51 44 39 39 30 FY10 FY20 FY25P FY15 FY16 FY17 FY18 FY19 FY20 • Accounts for 7.1% of National GDP; 49% of manufacturing GDP • Employs about 50 lakh people • Cost competitive; globally renowned for frugal engineering • North America & Europe account for 60% of exports • India auto component exports' share increased from 0.6% to 1.3% from FY10 to FY20 US$ B US$ B US$ B US$ B Sales to OEMs Imports Exports Domestic aftermarket CAGR CAGR CAGR CAGR 3% 7% 13% 9% 15 15 41 10 30 8 4 4 FY10 FY20 FY10 FY20 FY10 FY20 FY10 FY20 Note(s): Turnover includes sales to OEMs, aftermarket sales and exports - imports © PGA Labs | 07 Source(s): PGA Labs analysis ACM industry in India PV segment accounts for around 45% of the India’s overall ACM industry; industry has net trade deficits 1% Overall ACM industry 3% 7% Auto comp OEM supply (US$ B, FY20) M & HCVs PV 2W 12% 3W LCVs Tractors 45% 51 CE 12% 20% Exports USA Germany Turkey 26% Auto comp exports 20% Thailand UK Brazil (US$ B, FY20) 39% 15 Italy Bangladesh Mexico 7% UAE Others 4% 3% 3% 4% 4% 3% 3%3% Imports 14% Auto comp imports 20% 26% 3% China South Korea Germany (US$ B, FY20) 3% 3% Japan USA Thailand 15 5% Singapore Italy UK 5% 14% Belgium Others 7% 11% 9% © PGA Labs | 08 Source(s): ACMA, PGA Labs analysis ACM industry in India - outlook ACM market is poised for strong long-term growth, with ample of opportunities in both local and export market Headwinds Tailwinds Economic slowdown: Y-o-Y, Automobile penetration to increase: India is still automobile sales continue to decline way behind in automobile penetration globally, which from Q3 FY 2019 due to lower is expected to increase with growing urbanization, discretionary spending because of poor increased income, better financing, and better road sentiment amid economic uncertainty connectivity. BSVI standard will ensure movement and weak rural demand. The situation towards lower emissions and fuel economy. was further exacerbated by COVID 19 Global components sourcing hub: Indian ACMs pandemic. are on the path to become sourcing hubs for global Competition from other countries: players (Ford, Suzuki, Hyundai), esp. for engines part. India is being hampered by increased Ex: Varroc partner for TESLA. competition from other low-cost Policy support from the Government (AMP countries, especially China. Also, Free 2016-26): 100% FDI allowed under automatic route; Trade Agreements (FTAs) with countries PLI scheme launched by GoI for ACM industry. in the ASEAN region and others pose a Initiatives like ‘Make in India’ and NEMMP 2020 etc., threat as they will make India’s exports are expected to give a massive boost to the local to these countries less competitive. automotive component manufacturing sector in the Unorganized manufacturers: Scaling near future. up the business and capacities and Increased indigenization and export hub: The addressing critical issues such as access growth of global OEM sourcing from India (low cost) to capital at feasible costs and better & the increased indigenization of global OEMs is access to technology is a challenge for turning the country into a preferable designing and large number of unorganized auto manufacturing base for automotive components. component players in India. Improved product development: Increased Fragmented aftermarket: investments in R&D operations and laboratories, being Unorganized and fragmented set up to conduct activities such as analysis, simulation operations in the aftermarket makes it and engineering animations. Ex: Bosch Chassis highly inefficient and, in many cases, Systems, Tenneco, and Faurecia adapt global designs unreliable. This leads to higher costs or & develop new products. Ex: Faurecia’s tie-up with higher dissatisfaction among consumers. IISc to develop state of the art products in the ACM Counterfeit products: Counterfeit industry, Bosch and Tenneco has Indian R&D facilities. components account for 45 percent of EV adoption: Increased push from the Indian the passenger car aftermarket. Government for EV inclusion through FAME II, PLI Substandard parts and services impact schemes (ACC) and CAFÉ Norms designed to reduce the safety standards and vehicle fitness, carbon emissions from vehicles along with GST which contributes to road fatalities. reduction is bound to push EV manufacturers. This is expected to create opportunities for ACM players Note(s): Automotive Mission Plan of GoI, 2016-26; CNBC report, Economic Times, Money Control, © PGA Labs | 09 Company websites, SIAM, ACMA, FADA, IBEF, SME futures, Source(s): PGA Labs analysis ACM industry trends Key trends impacting ACM industry in India Indian auto component industry Policy and Market dynamics Technology OEM landscape regulatory • Changing pockets • Emissions - BS-VI, • Increasing • CASE (connected, of growth CAFÉ norms localization autonomous, shared & electrification) • Shorter product • Scrappage policy - • Global players lifecycle reverse value chain setting shops in • Flex fuel engine and India mixed fuel • Adoption of EVs • Production Linked Incentive (PLI) • Global component • Weight reduction • Indian platform scheme sourcing hub and climate design and R&D resistance • Make in India • Emerging revenue streams • Technology partnerships Source(s): PGA Labs analysis © PGA Labs | 10 Market dynamics Indian ACM market is gearing towards greater localization and exports Players are looking to increase presence in used cars and aftermarket segment Increasing localization Global players setting shop in India Average Auto comp. Import Vehicle FDI in automotive sector localization segment (%) category (US$ B, FY16-20) Hatchbacks, Drive 22% 90-95% compact transmission sedans and & steering 3 3 SUVs 13 2 2 Premium Electrical & 27% 85-90% 3 sedans electronics FY16 FY17 FY18 FY19 FY20 Total Engine 13% • Investments by foreign entities in India on the • Opportunity for import substitution in components rise - ZF (Germany), Aisin Seiki (Japan), Bosch with high potential for localization (Germany), Continental Engines (USA), Delphi (UK), • Collaborations with global suppliers relocating Denso (Japan), Magneti Marelli (Italy), WABCO manufacturing operations to India could further (Germany), Valeo (France), FAG (Germany), TRW help in building new capabilities (USA) have already made investments in the country Emerging revenue streams Global component sourcing hub Auto component exports from India India car sales trend ( US$ B, FY16-20) (M units, FY16-20) CAGR FY16-20 CAGR FY16-20 Top 7.6% destinations 3 3 -0.2% 3 Europe 32% 15 15 4 6.2% 4 14 USA 3 30% 11 11 Asia 27% FY16 FY18 FY20 FY16 FY17 FY18 FY19 FY20 •Scope to pursue higher exports in product categories •Multiple OEMs and players have announced to where the country has a competitive edge, such as bolster their used car business post lockdowns by shafts, bearings, and fasteners expanding network and buying stock •Need to broaden global export presence by building • Auto component players looking to increase capabilities for high-value products such as gear-box aftermarket sales by leveraging existing OEMs and parts, heating, ventilation, and air-conditioning OESs relationships Note(s): Average localization in top selling models © PGA Labs | 11 Source(s): ACMA, IBEF, Secondary research, PGA Labs analysis OEM landscape EVs and SUVs to lead the growth of PVs in India; focus on Indian platforms and R&D will boost the early adoption of new technologies Changing pockets of growth Shorter product lifecycle PV sales PV launches India (M units, FY16-20) (No. units) CAGR FY16-20 3 3 13% 13% 0% 21% 28% 7% 22 17 18% 14% -6% 48% 45% -2% FY16 FY20 FY16 FY20 MPV SUV Sedan Hatchback • SUV segment is showcasing the •Product lifecycles for many car highest growth in the sector manufacturers have been shrinking • Avg. price of car rising demand for • OEMs offering newer, more premium features increasing varied options leading to more increased demand of tech. and complexity in their supply chain electronic components •Buyers looking for fresh options and frequent upgrades Note(s): EV sales includes 2W and 4W; IC engine = internal combustion engines; PV launches includes hatchbacks, SUV and Sedans © PGA Labs | 12 Source(s): ACMA, SIAM, IBEF, IHS Markit, CII, Companies’ annual report, PGA Labs analysis OEM landscape Adoption of EVs Indian platform design or R&D EV Sales India Indian platform design (‘000 units, FY16-20) •New product launches for major OEMs to have Indian platform design •Maruti, Mahindra, and TATA have large CAGR 63% established R&D centers •Hyundai opening up UAM (new mobility seek designs) in India 155 130 • Bosch, Tenneco, and Tesla have also set up a state of the art Indian R&D units 56 25 22 and augmenting capacities in those units FY16 FY17 FY18 FY19 FY20 OEMs focusing on R&D effort Losers Gainers IC engines •Mahindra & Mahindra and Tata Motors Battery packs spearheading the development of Transmission Battery management autonomous vehicles in India system systems •Minda iConnect and Microsoft India are Fuel controller Electric motors part of a strategic collaboration to or injector develop connected vehicle technologies locally and enhance driving experiences •India has more than 25 R&D centers within the Indian auto sector, which • Growth: E2W is driving the market at accounts for roughly 10% of domestic present R&D expenditure • Govt policy: FAME II scheme aimed at pushing EV adoption • Environment: India to cut GHG emission intensity by 35% • Industry: M&M plans to invest US$ 400M in EVs; Hyundai plans to invest US$ 533M © PGA Labs | 13 Technology CASE is gaining strong traction in India; technological innovations & partnerships are shaping the components market CASE Comfort, safety and 48% of new vehicles shipped Connected C entertainment globally with built-in connectivity An intelligent system inside the 45% of new vehicles shipped globally Autonomous A vehicle that assists drivers with L2 autonomy or higher 1% of mobility profits derived from new Shared use of vehicles S Shared sources (e.g., on-demand mobility) Electric Use of electric vehicles 3% of new cars sold were EV E Flex fuel vehicles • Indian government is planning to introduce Euro 6 compliant flex-fuel engine • FFV: Mixed fuels are used in the world in different % compositions for long • State run oil corporations started blending ethanol in Tamil Nadu • Ethanol blending rose from 1.9% per liter in Apr’20 to 7% in Jan’21. The initial target is FLEX FUEL E10, i.e., 10% ethanol, while the final target is for 20% ethanol blending, i.e., E20 • Flex fuel vehicles already operating in USA, Brazil and Canada among other countries • Pilot project launched for E100 fuel © PGA Labs | 14 Source(s): Secondary research, PGA Labs analysis Technology Weight reduction and Technology driven climate resistance partnerships Braking parts Braking parts • Mando India making • Brakes India has technology lightweight parts with license & supply agreements with low emissions ZF • Mando India has an agreement Suspension system with Continental Teeves Germany • Aptiv components use for brake systems for US or EU cataphoretic coating, temp • Kalyani forge has JV with range -40°C to 120°C Germany's Refu Electronik GmbH for EV parts Driveshaft assemblies • GKN driveline working on Suspension system lightweight driveshafts • Gabriel India has technology • Dana Anand making partnerships with KYB (PV) and lightweight, fuel-efficient, and KONI (CV) high torque carrying • Aptiv components has JV with capacity parts Alpine F1 team and investing in smart mobilities technologies Fuel tanks Electrical & electronics • BAPL making plastic fuel • Varroc engineering has JV in tanks to reduce 20-50KG China for expansion in SUV and weight in a truck EV segments New materials Transmission & steering • Usage of carbon fiber, • Sona comstar has JV with IRP Israel magnesium, aluminium and plastics to reduce weight Driveshaft assemblies • JTEKT India absorbs technology from parent company © PGA Labs | 15 Source(s): Secondary research, PGA Labs analysis Policy and regulatory Recent policy level initiatives have provided an opportunity to the ACM segment for growth and movement up the value chain Movement towards BSVI is Recent policy level initiatives expected likely to push Indian auto to positively impact auto component component industry up the manufacturing value chain Incentive-based vehicle scrappage policy • Expected to lead to a significant rise in BSVI: automobile sales provided it is made mandatory Lower emissions & fuel economy • Discount of 5% on the purchase of a new vehicle against the scrapping certificate Impact on auto sector • Private and commercial vehicles to be de-registered after 20 and 15 years respectively Change in engine & 01 if found unfit exhaust parts design • Increased availability of scrapped materials such • Increased electronic as steel, plastic, rubber, and aluminum to components in the powertrain manufacture automobile parts. Likely to reduce • Introduction of engine control cost by 30-40% according to estimates units (ECUs) Production linked-incentive (PLI) scheme Proliferation of advanced 02 technologies for the auto component industry • Automated manual transmission • Intended to achieve import substitution by encouraging local manufacturing • Electronic braking systems • Incentive (8-13%) on net incremental sales of • Electronically controlled air eligible products over the base year suspension • Auto-component makers with a minimum revenue of INR 500 crore and INR 150 crore in fixed Impact on auto component sector assets investment to be eligible for the PLI • BSVI compliance - need investments to upgrade manufacturing facilities Make in India Direct impact on engine & engine • “Make in India” initiative is expected to parts segment facilitate substantial investment in the auto • Strict emission norms necessitate the use components sector of low-weight components for better fuel • National engineering industries ltd. to invest economy INR 100 crore over three years for needle Increased technological complexity roller bearing may oust some unorganized players • Opportunity for component manufacturers to move up the value chain and target exports © PGA Labs | 16 Source(s): Secondary research, PGA Labs analysis ACM segments Auto components industry - segments Auto components Engine Body & Equipment Others parts chassis Drive Suspension transmission Electrical & braking & steering parts parts parts Sheet Piston & Headlights metal parts piston rings Starter Brake & brake Gears motors assemblies Engine Hydraulic Halogen valves pneumatic bulbs & parts instruments Brake Spark Wheels linings plugs Fuel-injection Wiper Fan belts systems & motors carburetors Electric Steering Shock ignition systems absorbers systems Cooling Dashboard Pressure die systems & instruments castings parts Leaf Flywheel Axels springs magnetos Power train Other panel components instruments Other Clutches equipment Source(s): PGA Labs analysis © PGA Labs | 17 ACM segments Historical CAGR of 5% in the ACM industry; double digit CAGR for export segment Four component segments (body & chassis, engineering components, suspension & braking, drive transmission & steering) command 65%+ of the total market Overall ACM industry Others Body & chassis ACM industry revenue (US$ B) 8% Interiors 14% Break up of 11% CAGR market by Engg. Electrical & FY10-20 FY20 51 components 26% 12% components (FY20) electronics 5% 13% 16% FY10 30 Drive transmission Suspension & steering & braking OEM segment Others Body & chassis Revenue (US$ B) 8% Interiors 12% 11% Break up of CAGR FY20 41 market by Electrical & Engg. FY10-20 components 26% 14% electronics components (FY20) 3% 13% FY10 30 16% Drive transmission Suspension & steering & braking Aftermarket segment Others Rubber components Revenue (US$ B) 3% Engg. 10% Cooling Break up of 19% components 14% CAGR market by systems FY20 10 FY10-20 components Suspension (FY20) 15% 19% & braking 9% 20% FY10 Drive transmission 4 Electrical & electronics & steering Export segment Others Body & chassis Revenue (US$ B) Interiors 7% 11% 6% Break up of Engg. CAGR Electrical & 13% 19% FY20 15 market by components FY10-20 components electronics (FY20) 13% 11% 33% FY10 4 Drive transmission Suspension & steering & braking Note(s): Turnover includes sales to OEMs, aftermarket sales, and exports - imports; Others include Consumables, Rubber, and miscellaneous © PGA Labs | 18 Source(s): PGA Labs analysis Component segments ~70% of top 20 players’ business comes from 3 segments – suspension & braking, electronics & electricals and engine components Market overview by value % based on sales of top 20 companies by revenue (US$ B, FY19) Total ~US$ 8.6B 24.4% 23.2% 22.1% 9.4% 4.7% 16.2% US$ US$ US$ US$ US$ US$ 2.1B 2.0B 1.9B 0.8B 0.4B 1.4B Axles, 1% Powertrain Transmission Unaccounted, components, and clutches, 17% 12% Leaf springs, 14% Others, 17% 25% Steering systems, Heat exchangers 14% and cooling, 25% Seating, Starter motors, 19% 9% Shock absorbers, Dashboard instruments, 33% 10% Lightning solutions, Polymers, 15% 31% Fuel injections systems Wheels, & carburettors, 71% 63% Brake & brake assemblies, Wiring harnesses, 48% 42% Pressure die casting, 33% Suspension Electronics & Engine components Transmission Body, Others & steering chassis and braking electricals (exhausts & heat parts & structure parts exchanger) © PGA Labs | 19 Source(s): PGA Labs analysis Suspension & braking Suspension & braking segment is looking for growth from after-market and export Evolving landscape for suspension & braking New strategies • Players looking at a diversified customer base in the replacement and OEM segment as it faces high demand • Rising penetration of electric vehicles (EVs) presenting new avenues for growth • Need to counter the increase in competition from global players in sub-segments such as shock absorbers Diversification • Entities looking to increase aftermarket sales by leveraging existing OEMs or OESs relationships, focusing on tier 2 & 3 cities • Also, entities engaging with mechanics and retailers to reach closer to customers • Adding new products to the portfolio Exports orientation • Expanding into the global market is a focus area • For some of the players such as Brakes India, over dependence on exports exposes them to the global downturn Integration • Players looking to create backward integration and become less dependent on imports Source(s): Equity research reports, Company annual reports, PGA Labs analysis © PGA Labs | 20 Suspension & braking Case study - Gabriel India Limited PROFILE Gabriel is one of the largest players in automobile suspension components and has a strong domestic presence. Besides leading OEMs, it has also penetrated aftermarket and export segments through 12,000 retailers in 19 locations Share of automotive segments (%) Share of market segments (%) 2% 1% 1% 1% 2% 4% 2% 4% 4% 4% 9% 11% 13% 13% 12% 13% 13% 11% 11% 13% 22% 20% 24% 33% 31% 85% 85% 85% 83% 83% 67% 67% 61% 55% 54% FY17 FY18 FY19 FY20 Q3FY21 FY17 FY18 FY19 FY20 Q3FY21 2W/3W PC CV Trading OEM Aftermarket Exports Case study - Gabriel India Limited GROWTH STRATEGIES • Developing new technologies with OEMs in both CV (cabin shock absorbers) and PV (electronic damper) • In PV, reduced weight of the components by 30% for EVs New • Developing products for electric vehicle OEMs such as OLA Electric, strategies Okinawa, Ather, etc. • Operationalized two product lines for the driveshaft, brake fluid, and brake pads • Target of ~10% of its revenue over the next 3-4 years from current 4% Exports • New contracts with OEMs such as DAF Netherlands and Volkswagen Russia • Plans to increase domestic aftermarket sales through national channels with a Focus on significant focus on tier-2 and tie-3 cities aftermarket • Looking to increase aftermarket’s contribution to exports • Looking to increase local procurement through captive capacity and Integration engaging local suppliers Source(s): PGA Labs analysis © PGA Labs | 21 Transmission & steering New offerings like automatic transmission systems is witnessing growing demand; reducing gap in global and Indian emission norms will boost exports Evolving landscape for transmission & steering New strategies • Aftermarket sales are being targeted as the sector is growing • Rising penetration of electric vehicles (EVs) presenting new avenues for growth • New products like automatic transmission to increase growth and focus on R&D • Share of automatic transmission increased to 16% in FY21 from 3% in FY15 Diversification • Entities looking to increase aftermarket sales by leveraging existing OEMs or OESs relationships, focusing on tier 2 & 3 cities • Also, entities engaging with mechanics and retailers to reach closer to customers • Focusing on exports to reduce dependency on one region Exports orientation • Exports to increase due to reduction in the gap between global and Indian emission norms • GoI incentivizing industry to make in India and export to the world Integration • Focusing on offering complete solutions rather than a component Source(s): PGA Labs analysis © PGA Labs | 22 Transmission & steering Case study - Sona Comstar PROFILE Sona Comstar is a leading Indian auto component manufacturer. It operates nine state-of-the-art manufacturing facilities in India, the USA, Mexico and China Revenue share - vehicles Revenue share - vehicles US$ M, FY21 US$ M, FY21 Diff. gears Mc-h starter motors 1% PV 3% 17% 18% Conv. starter Others 27% CV motors OHV 14% 69% 24% 27% Other gears Diff. assembly Case study - Sona Comstar GROWTH STRATEGIES • Development of magnet free motors with IRP of Israel New • Exclusive rights to manufacture the system in India strategies • Global market share increasing across categories • Differential gears Exports 4% (CY19) --> 5% (CY20) --> 6% (H1 CY21) • Starter motors 2% (CY19) --> 3% (CY20) --> 5% (H1 CY21) • Looking to capitalize on the impending EV boom • One of the few companies globally with the capability to integrate the Integration three key constituents of the electric powertrain (differential assembly, high voltage traction motors, and high voltage inverters) into a single matched unit • Largest manufacturer of differential gears for passenger vehicles, commercial vehicles, and tractor OEMs in India with a high market share PV – 55-60% Diversification CV – 80-90% Tractor OEM – 75-85% • Among the top two exporters of starter motors from India and top 10 global starter motor suppliers in CY 2020 Source(s): PGA Labs analysis © PGA Labs | 23 Electrical & Electronics Electrical & electronic parts to witness increased demand on the back of rising SUV and EV demand Evolving landscape for electrical & electronics New strategies • New mobility and digital transformation to drive demand for automotive lighting and LEDs • R&D focus based on increased use of electronics, electrification, autonomous driving, connectivity, and stricter environmental regulations • Tritium will soon be delivering fast charging technology for EVs after the company signed an MoU with Tata Autocomp Systems Diversification • Focus on the development of new products for the electric vehicle segment • Increasing global presence for existing products • Enhancing know-how of mechatronics and engineering to target the non-automotive market Exports orientation • Focus on expanding aftermarket and export business • Entities looking to expand manufacturing footprint closer to target markets Integration • Leading players like Varroc Engineering have been taking steps towards vertical integration Source(s): Company annual reports, Secondary research, PGA Labs analysis © PGA Labs | 24 Electrical & Electronics Case study - Varroc Engineering PROFILE Varroc is a global tier-1 automotive component group. It is into design, manufacturing, and supply of exterior lighting systems, plastic and polymer components, electrical-electronics components, and precision metallic components to PV, CV, 2 or 3-wheelers and off-highway vehicle (“OHV”) OEMs directly worldwide No. of countries of presence 12 Share of revenue from international sales 68% Europe, India, Key business regions North America No. of manufacturing facilities 43 Manufacturing facilities in India 26 Market share in global exterior •4% in 2016 automotive lighting market •6% in 2020 R&D centres 15 centers located in low- cost geographies, such as India, Czech Republic, Poland, Romania and Mexico Case study - Varroc Engineering GROWTH STRATEGIES • Strategic acquisitions and collaborations to manufacture Printed Circuit Board Assembly (PCBA) and other electronic equipment • Cater to the requirements of the local SUV demand and EV segment New through China JV strategies • Expanded the array of products to cater to the 2-wheeler and EV segments (Acquired CarIQ and entered exclusive manufacturing tie-ups) • Strategic expansions towards access to additional markets Exports (South America, Southern Europe, North Africa) • Acquired 30% stake (Dec 2020) held by JV partner in Varroc Lighting Integration Systems Electronics Romania SA engaged in manufacturing & sale of electronic lighting solutions for captive consumption of VLS and other OEMs Source(s): PGA Labs analysis © PGA Labs | 25 Engine components EVs and technological enhancements to disrupt the market for engine components Evolving landscape for engine components New strategies • New technological changes include the introduction of turbochargers and common rail systems • Players looking to work on streamlining engines for flex-fuel vehicles Diversification • Established firms looking to ride the EV wave • Focus on exports to reduce dependence on one region • Companies focusing on end-to-end solutions rather than offering just one part Exports orientation • Exports to increase due to reduction in the gap between global and Indian emission norms • GoI incentivizing industry to make in India and export to the world; exports for aftermarket segment is growing Integration • Players are looking to create backward integration and become less dependent on imports Source(s): Equity research reports, Company annual reports, PGA Labs analysis © PGA Labs | 26 Engine components Case study - Shriram Pistons & Rings Ltd. PROFILE Shriram Pistons and Rings limited (SPR) is India's largest exporter of Pistons and Rings. The company has tie-ups across industries and hence supplies components to various OEMs across the globe No. of countries of presence 40+ Tech and R&D center 1 (Ghaziabad) No. of domestic OEMs served 25+ No. of global collaborators 4 Manufacturing facilities in India 2 Case study - Shriram Pistons & Rings Ltd. GROWTH STRATEGIES • Moving to an “end to end” solution provider model New • Company has earmarked a strategy to diversify its product portfolio and is strategies identifying product & technology partners to enter the electric mobility segment • Largest exporter of pistons & rings from India Exports • Exports worth US$ 37M in FY21 • Company taking steps to increase focus on aftermarket both in India Integration & exports • SPR tech center for providing necessary research and testing support • Technology partnerships with global players like M/s KS Kolbenschmidt R&D GmbH, Germany, M/s Honda Foundry, Japan, M/s Riken Corporation, Japan, etc. Source(s): Equity research reports, Company annual reports, PGA Labs analysis © PGA Labs | 27 Focus areas Strategies focusing on technology upgrades, standardization and integration across the automotive value chain will help suppliers grow Key focus areas for suppliers Increased Close collaboration R&D spend with OEMs • Design capabilities are being • Stricter regulations mandate upgraded to co-develop India standardization and specific models with OEMs high-precision components necessitating closer • Current portfolio being updated collaborations with OEMs to match changing auto norms and customer preference for • OEMs’ growing preference to new features outsource complete systems and not separate parts Vertical Global integration expansion • Supplier focus shifting from • With Indian auto norms commodity products to special, traversing towards global high value-added, and standards, export markets are safety-critical products, which earn being targeted higher recognition and margins • Dual-Shoring and building • Suppliers are increasingly strong sales teams in high providing solutions to customers, opportunity areas are being adding more content per car, and considered giving stable pricing Source(s): PGA Labs analysis © PGA Labs | 28 Our team Abhishek Maiti Arindam Gupta Ashish Dhir Industrial Good & Services, Healthcare & Lifesciences Consumer & Retail Technology & Internet 25+ yrs. of experience 25 yrs. of experience 16+ yrs. of experience Faculty of Management Masters of Business Administration IIT Delhi, IIM Indore Studies, New Delhi from Lancaster University Management School, United Kingdom Roma Dixit Vamsi Krishna Praneet Singhal Financial Investor Group, Technology & Internet Technology & Internet Consumer & Retail 14+ yrs. of experience 13+ yrs. of experience 14+ yrs. of experience ICFAI Business School NMIMS, Mumbai ICFAI Business School, Hyderabad Anil Razdan Vaibhav Tamrakar Abhilasha Jaju Consumer & Retail Fintech, Ed Tech & Food Tech Financial Services 10+ yrs. of experience 9+ yrs. of experience 6.5+ yrs. of experience MBA from University of Mumbai IIT Bombay BITS Pilani, IIM Lucknow Tarak Pandey Harsh Salgaonkar Kiran Achanta Financial Services Business Development Technology & Internet Manager 6+ yrs. of experience 5+ yrs. of experience 6+ yrs. of experience SRM University, Chennai VIT University, IMT Ghaziabad Mumbai University Parul Garg Prasun Dey Aastha Singh Consumer Technology & Internet Financial Investor Group, Consumer & Retail 5+ yrs. of experience 5+ yrs. of experience NIT Kurukshetra, IIT Bombay, IIM Kozhikode 1.5+ yrs. of experience University of Delhi LSR, Delhi Connect with us We will be happy to share perspectives Abhishek Maiti Milan Banthiya Director Business Associate PGA Labs PGA Labs For media queries, please contact Vaishnav Kumar Rai Manager - Marketing E: communications@pgalabs.in M: +91 78279 44925 www.pgalabs.in New Delhi | Gurugram | Mumbai | Bengaluru Disclaimer: This material has been prepared by PGA Labs, which is the trade name of Praxian Global Private Limited (“PGA”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the viewers on the internet but should be referenced to PGA Labs, if reused or adapted in any form or in any forum. The frameworks, approaches, tools, analysis and opinions are solely PGA’s intellectual property and are a combination of collection of best data we could find publicly, and PGA Labs team’s own experiences and observations. We make no representation or warranty, express or implied, that such information is accurate or complete, and nothing contained in here can be construed as definitive predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing Recipient, its business and the markets within which it operates, nor all possible market conditions. No responsibility or liability whatsoever is accepted by any person including PGA or its Business partners and affiliates and their respective officers, employees or agents for any errors or omissions in this document. Any and all logos of companies used in the post have been published for information purposes only and PGA Labs does not hold any and all liability in connection therewith. This document is not complete without an accompanying oral discussion and presentation by PGA though PGA is not obligated to do so. PGA does not have any duty to update or supplement any information in this document. PGA shall not be responsible for any loss sustained by any person who relies on this presentation. PGA Labs We enable better decision making. 500+ 30% annual engagements faster to outcomes 8 600+ practices years domain expertise 130+ 98%+ team members accuracy 100+ 2.5M+ towns & cities panel members 15+ 40:60 languages covered she-he ratio Deep business research and intelligence that helps in driving SMARTER DECISIONS Deep on-ground insights that you can act on 4 offices, deep experience across geographies – India, US, Europe, MEA, and SEA region Advanced technology tools and innovative data gathering approach Multifaceted teams with a unique mixture of qualitative, quantitative, and digital research experts The team at PGA Labs appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, CP-003, 004, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District GF Tower 4B, DLF Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 Corporate Park, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram -122 002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Praxian Global Pvt. Ltd., Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025