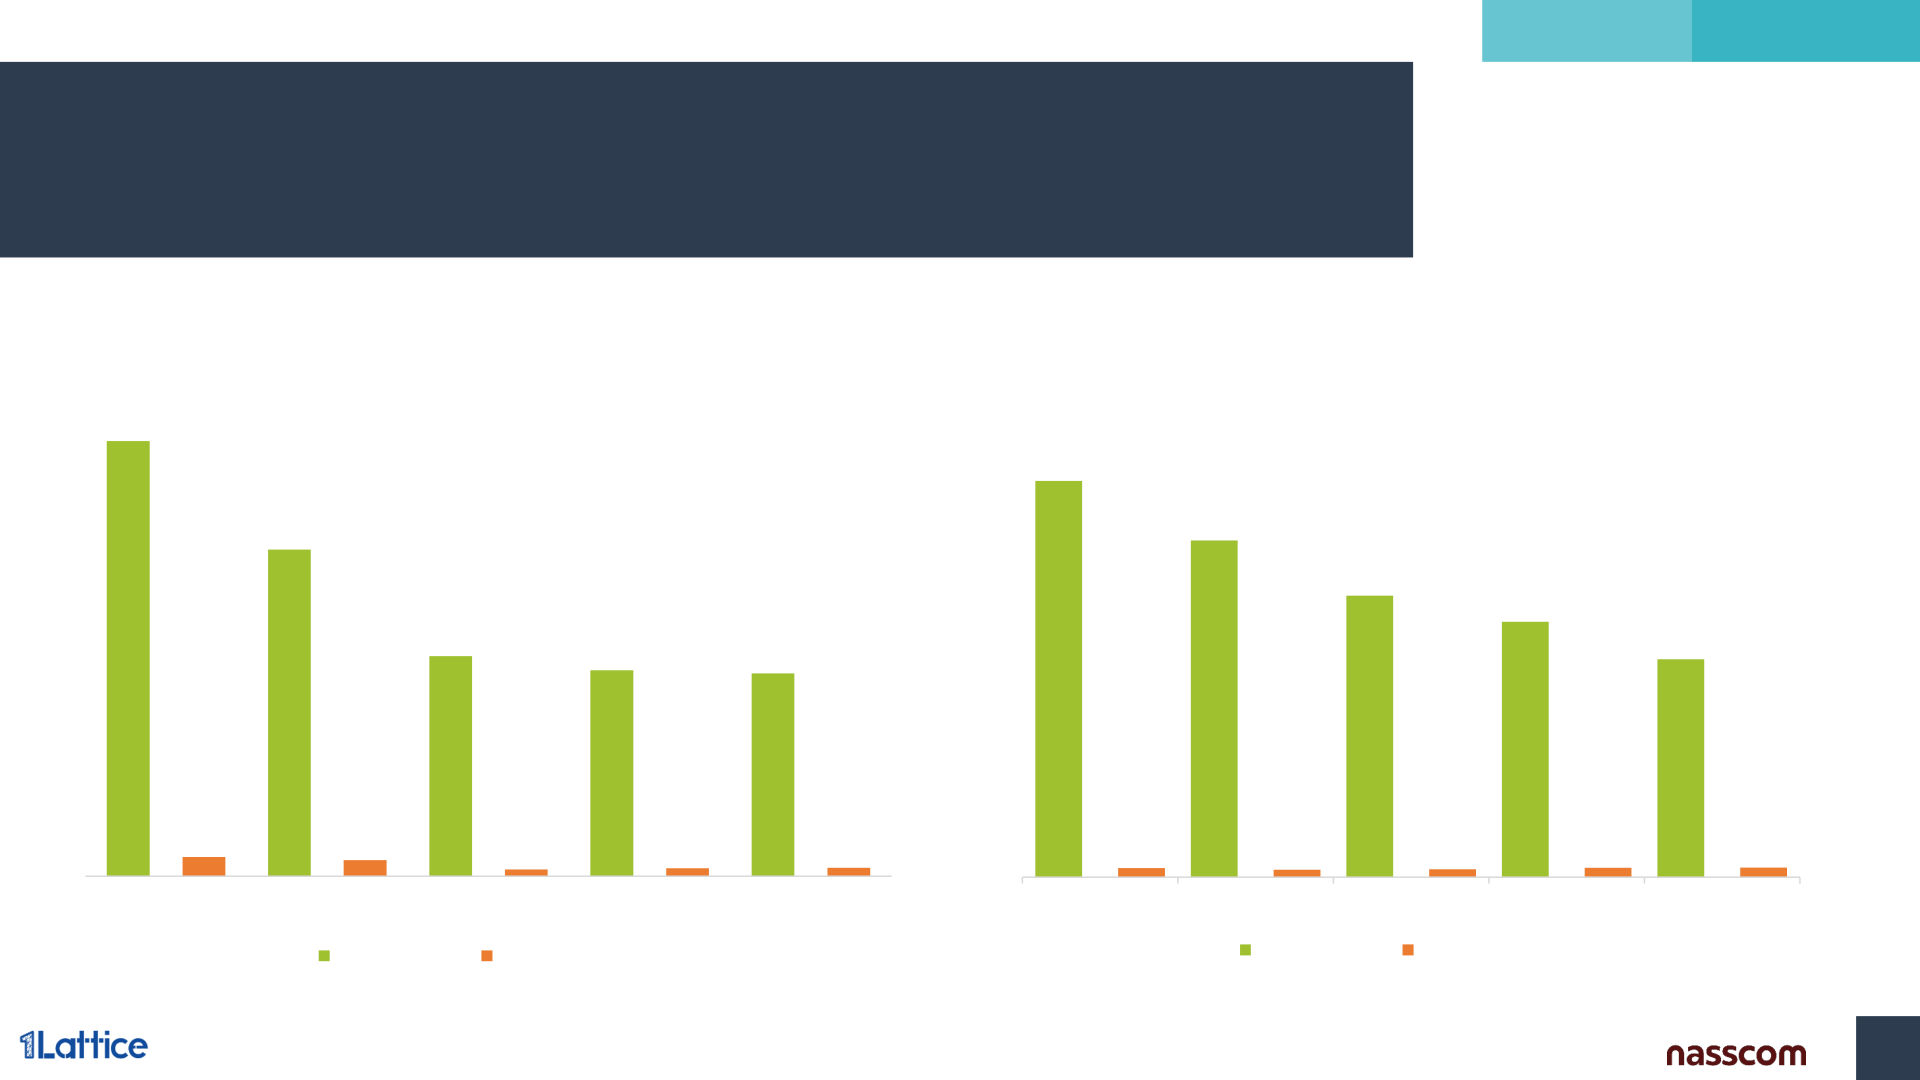
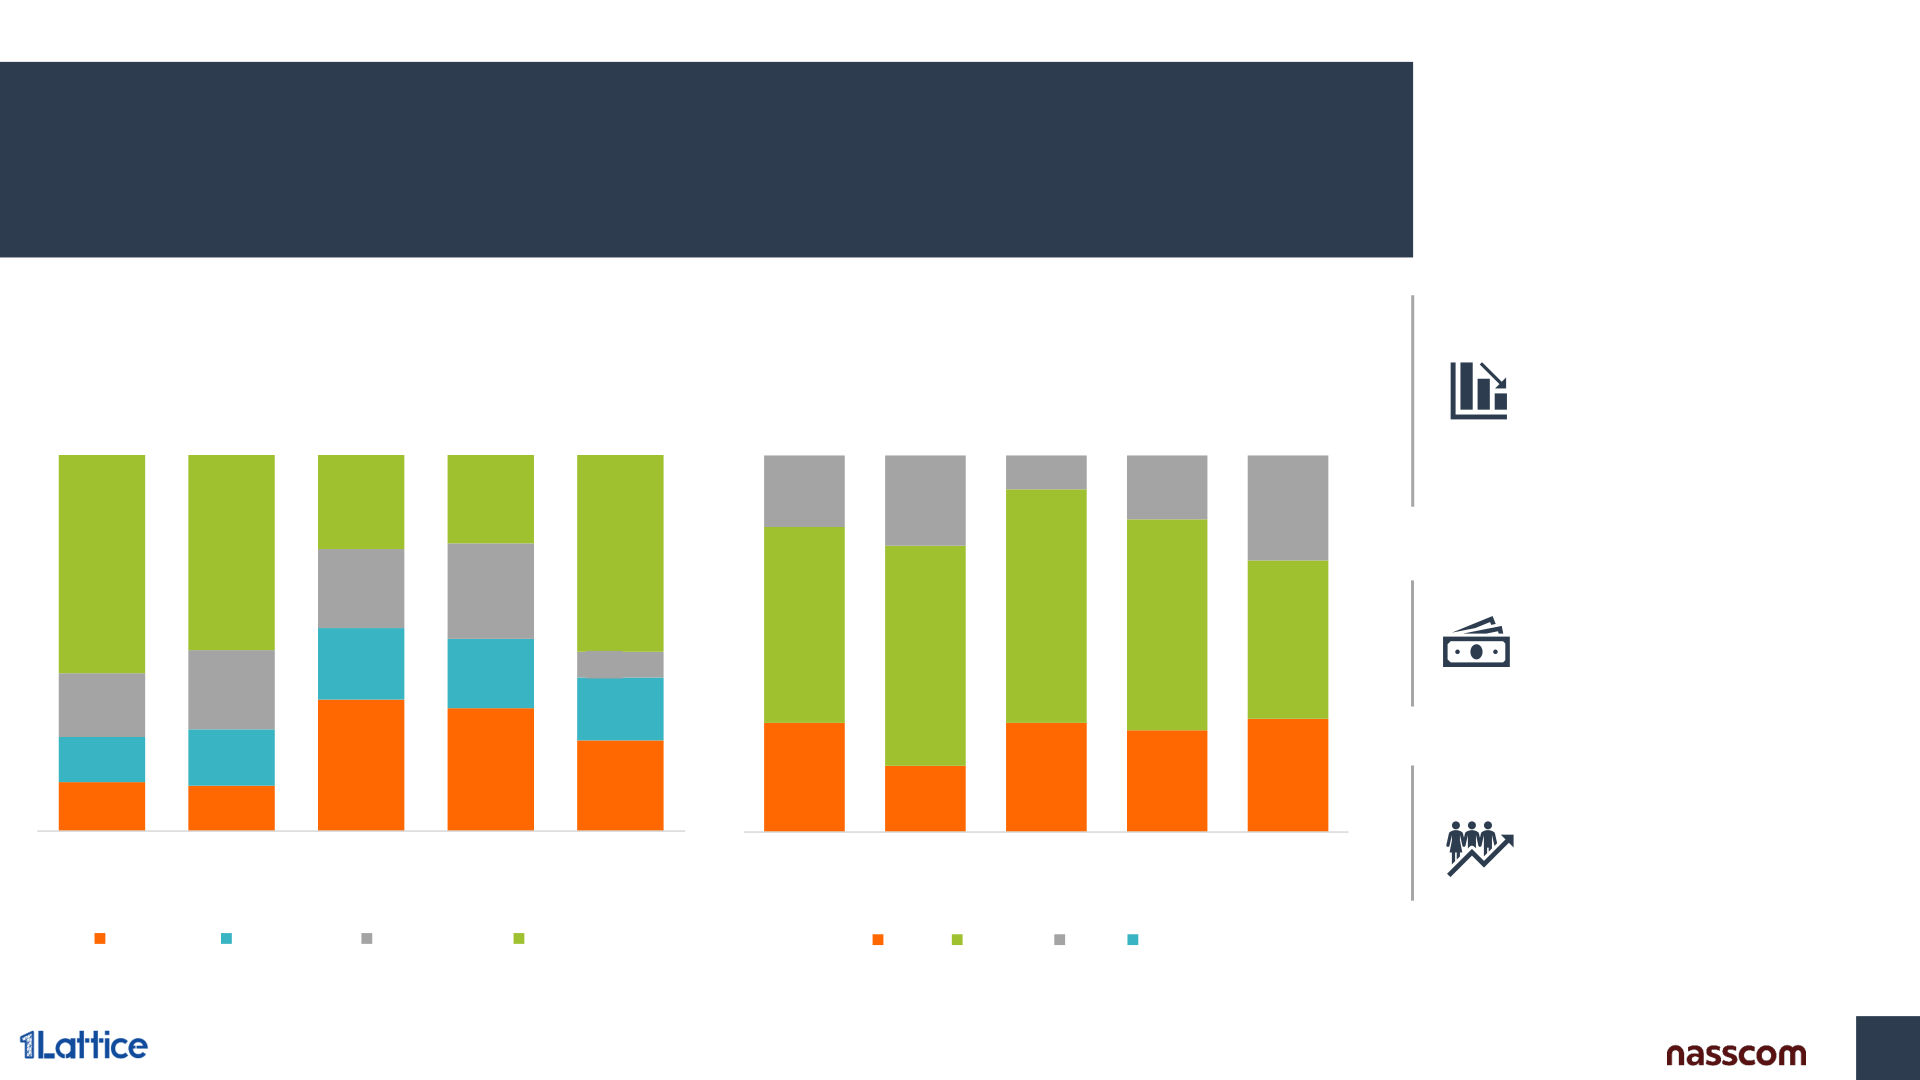
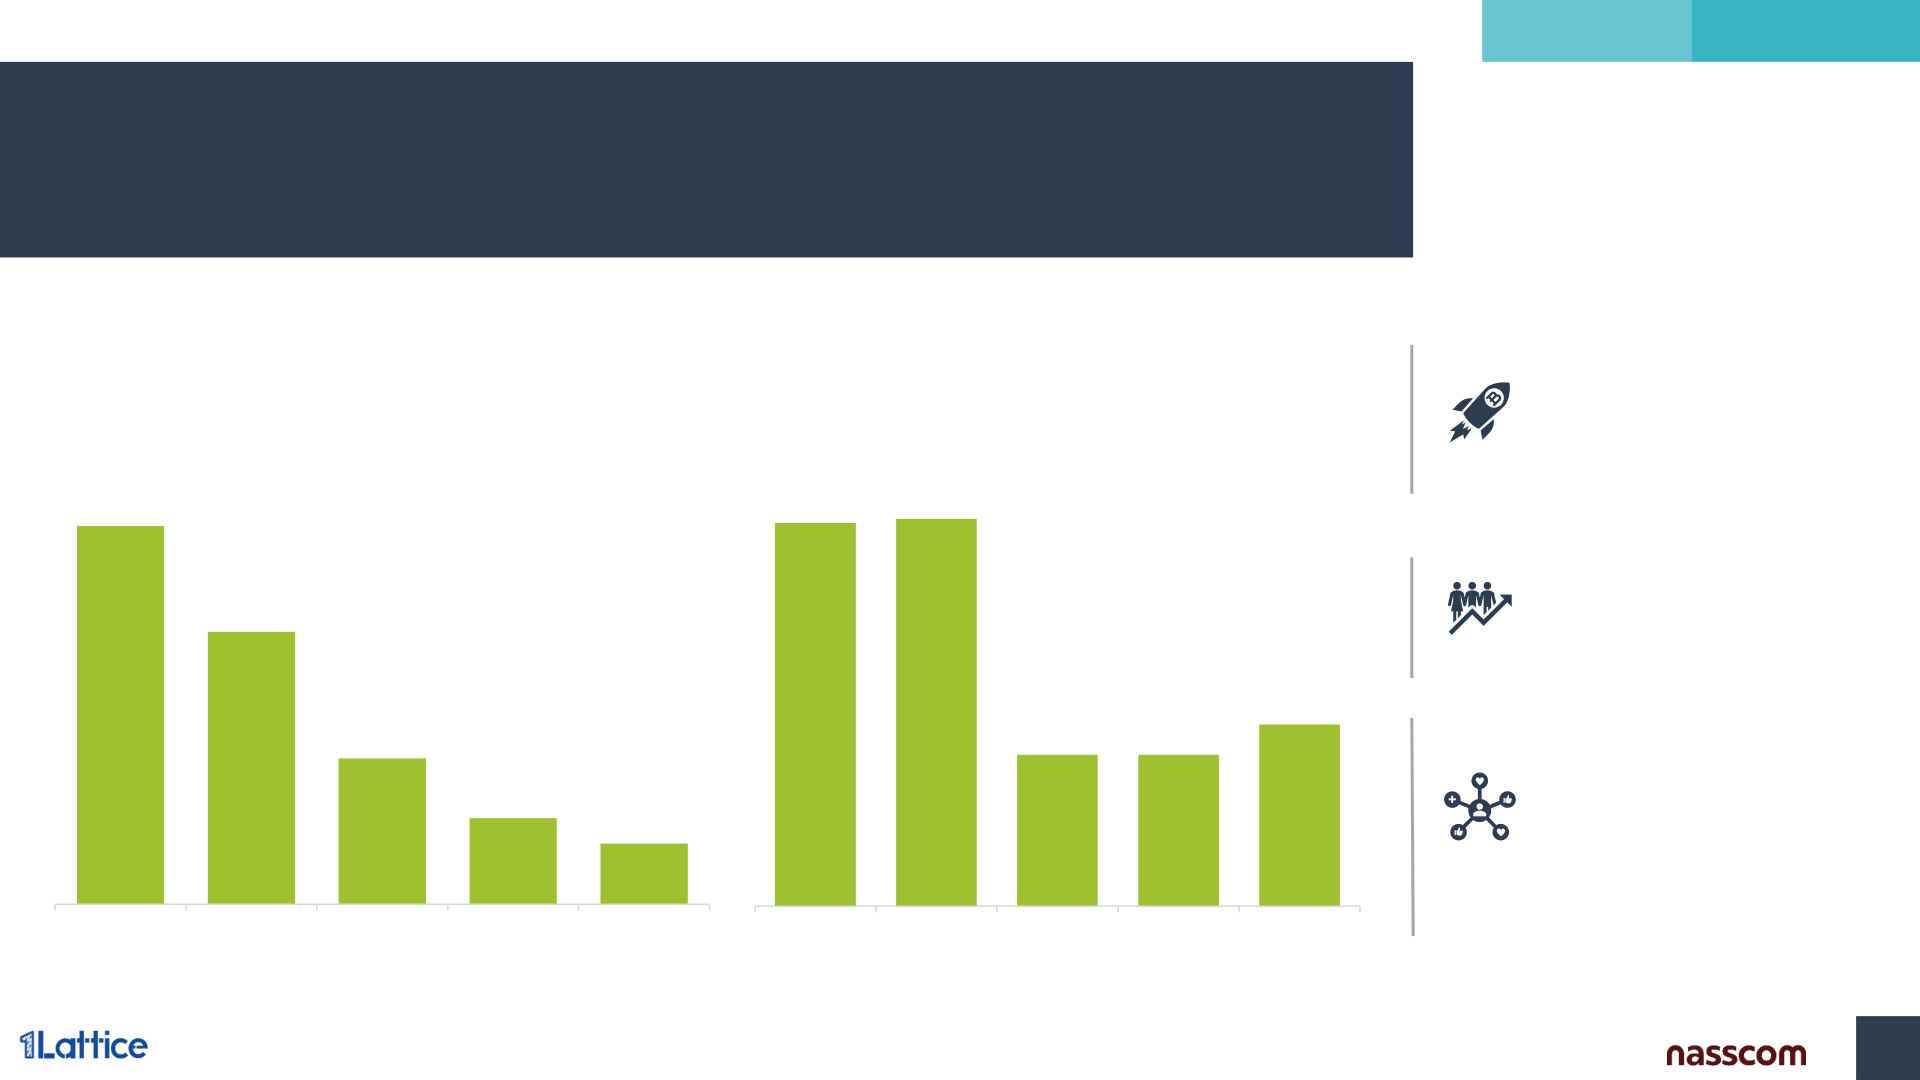
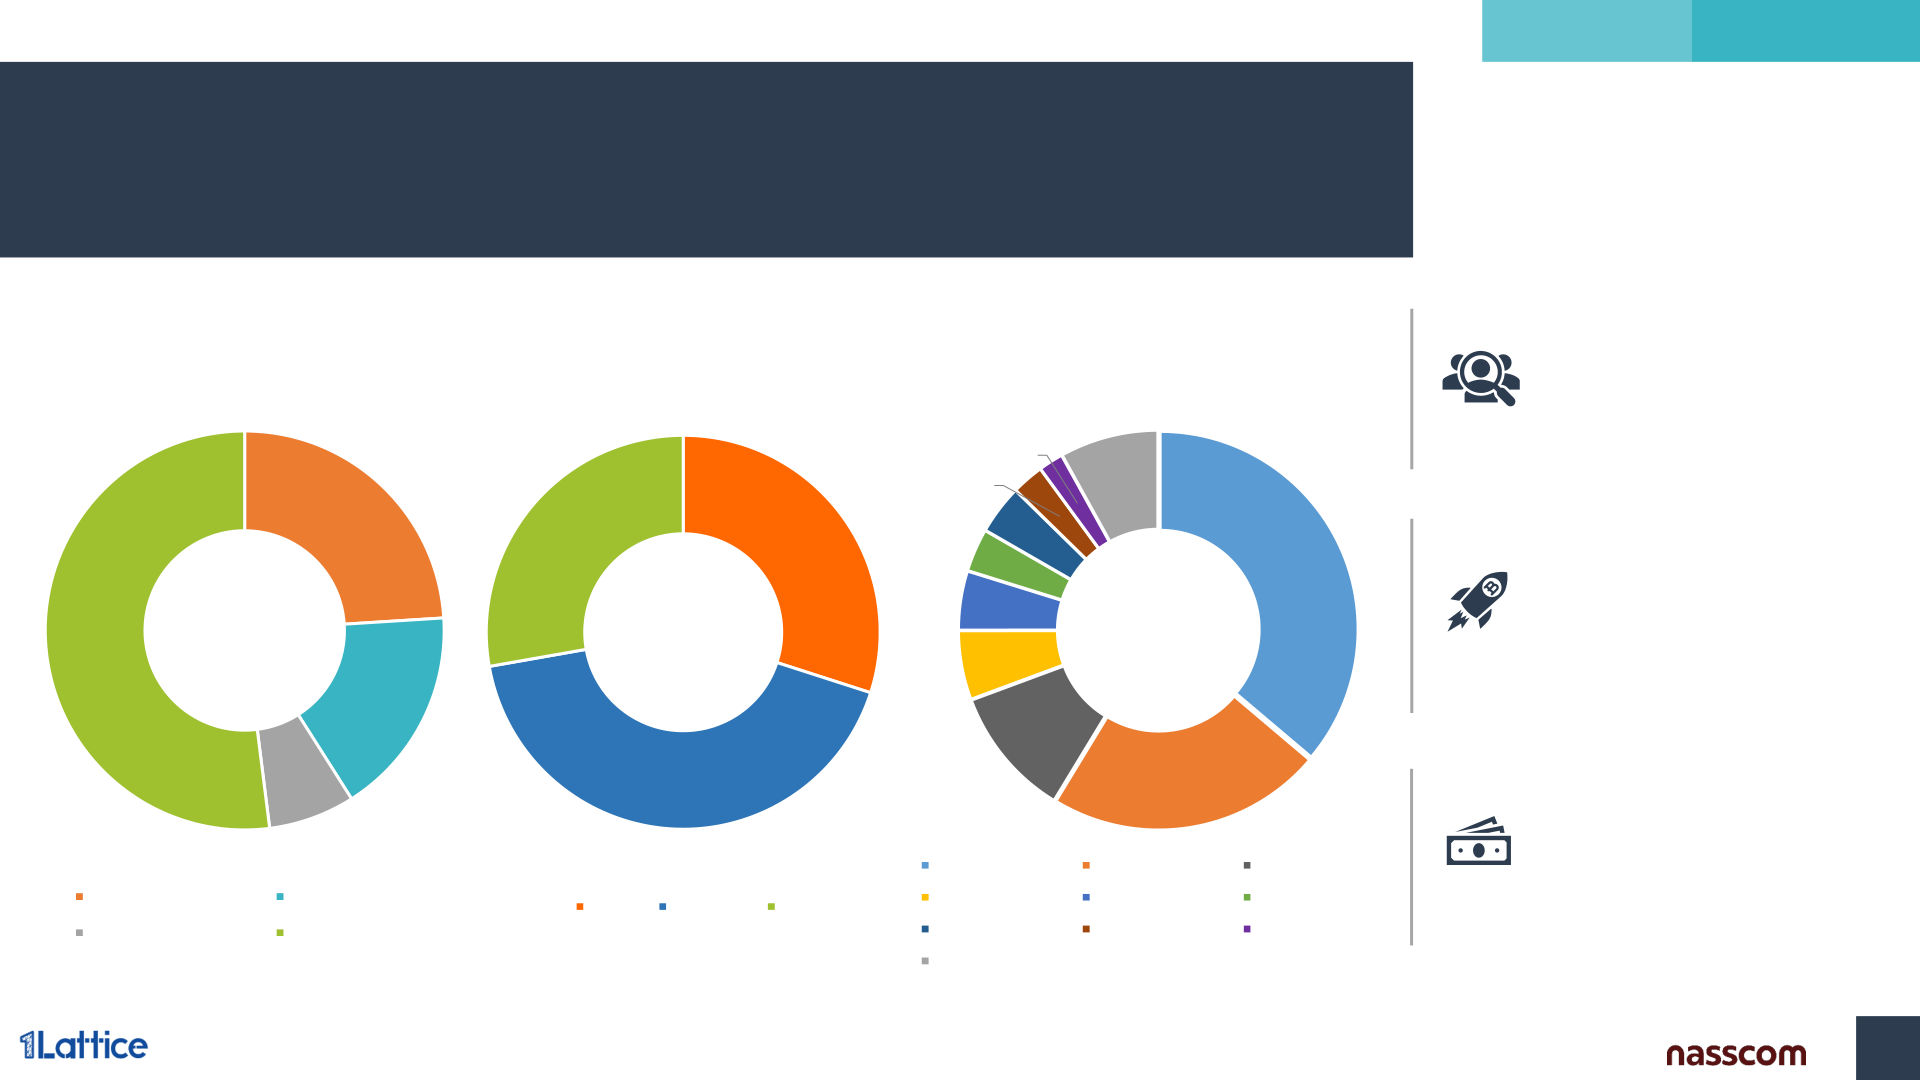
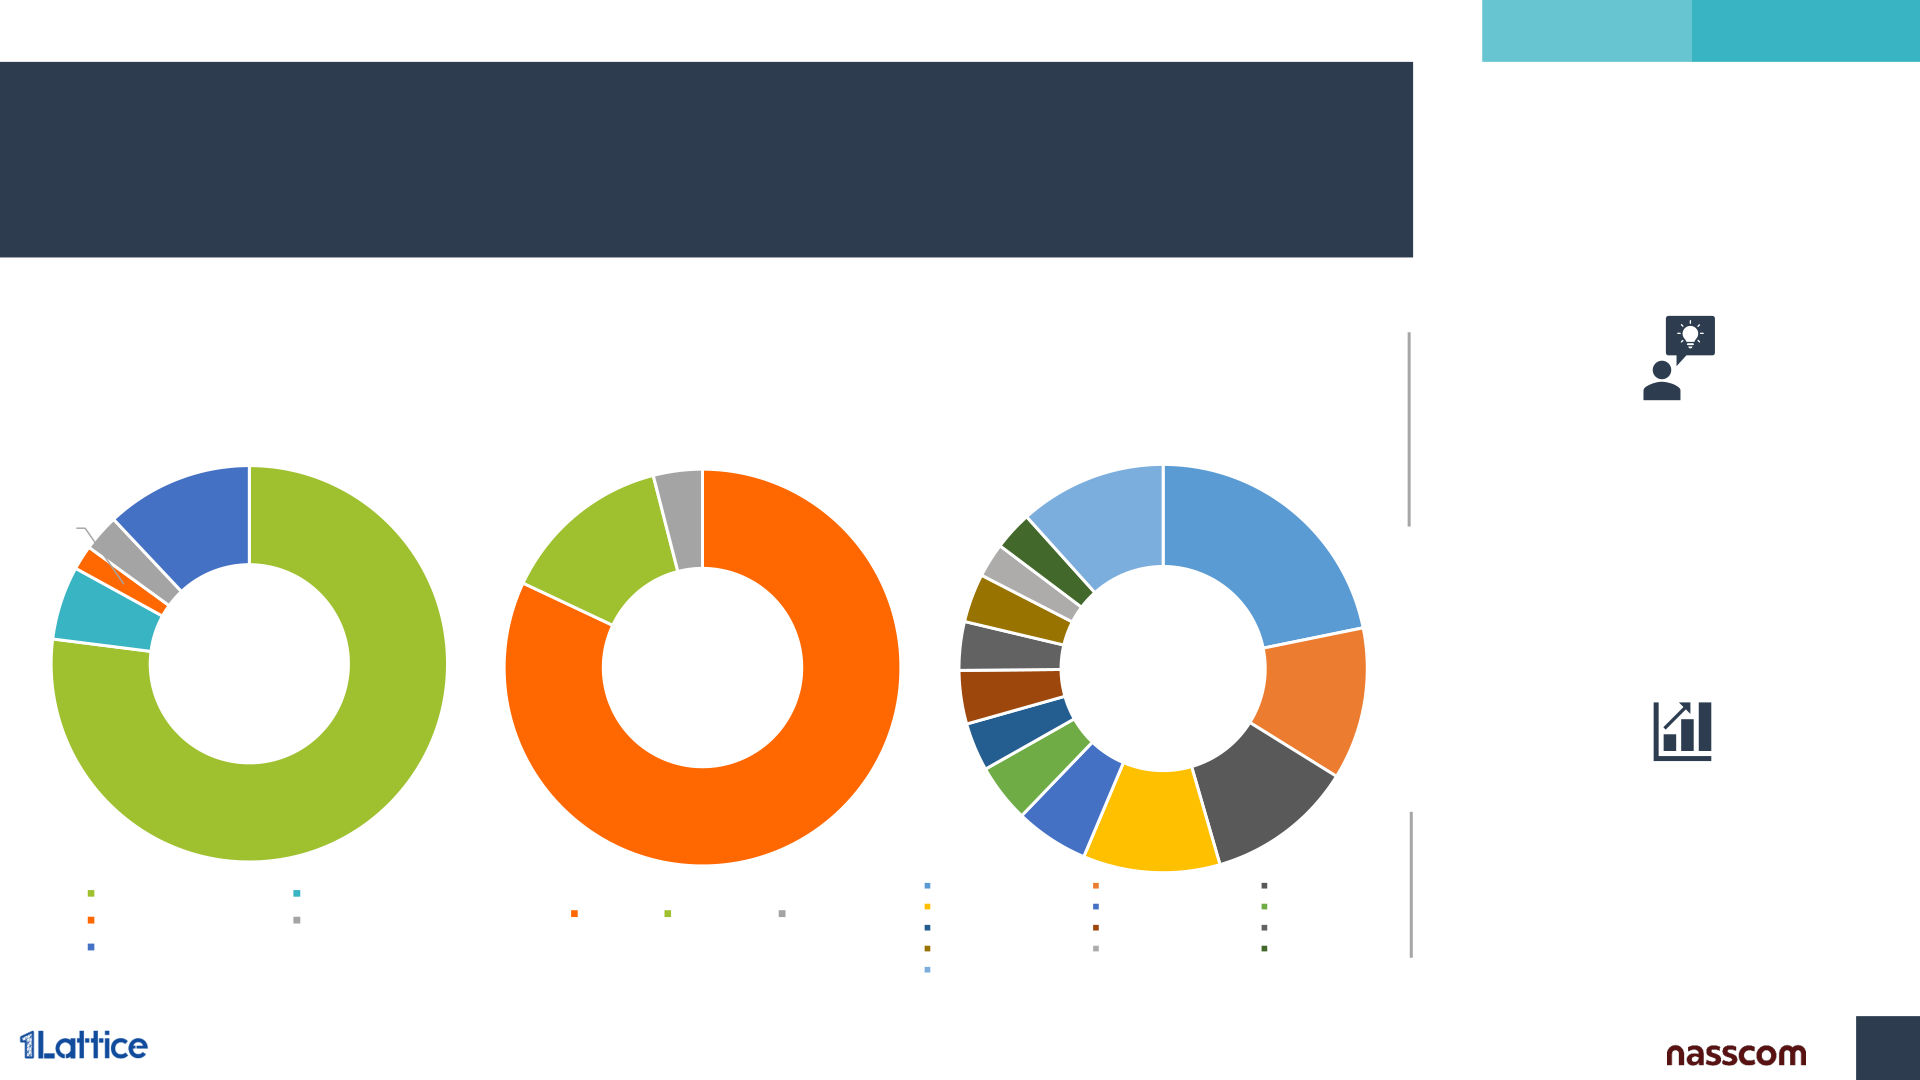
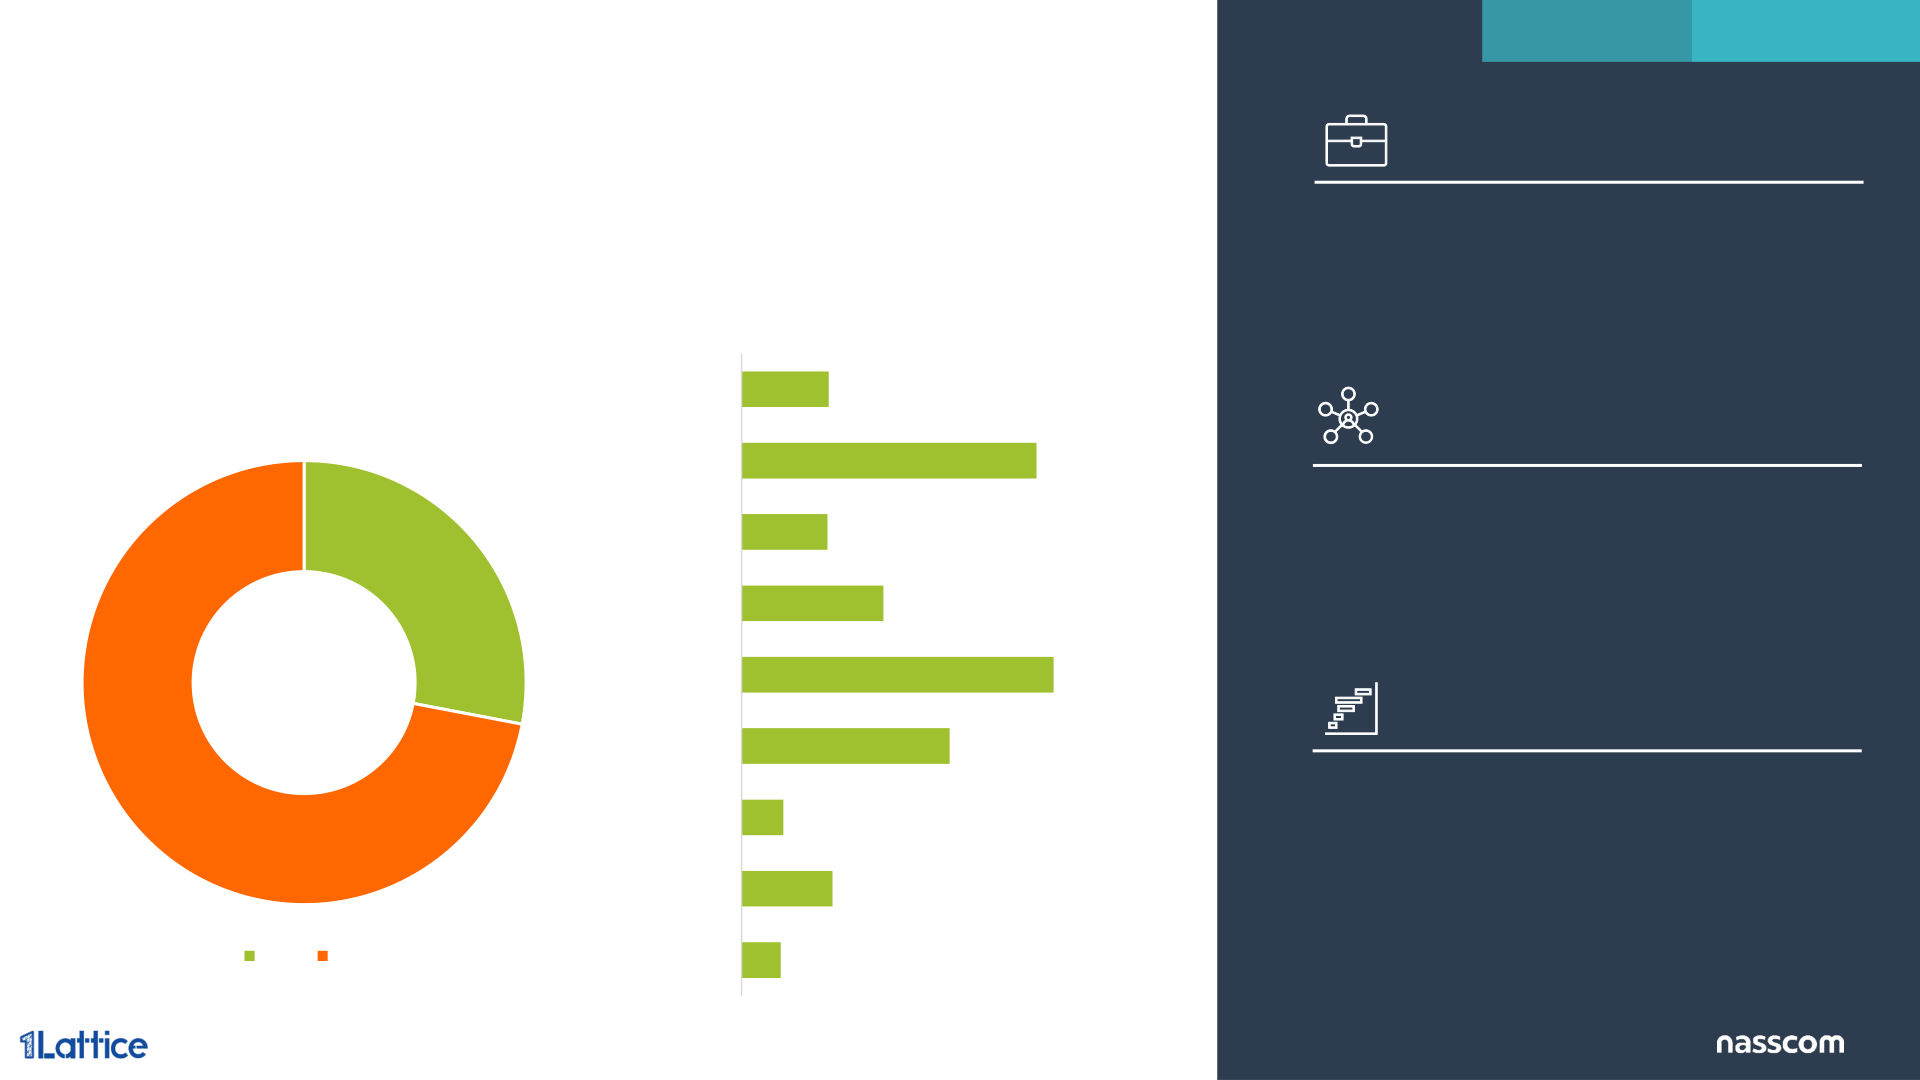
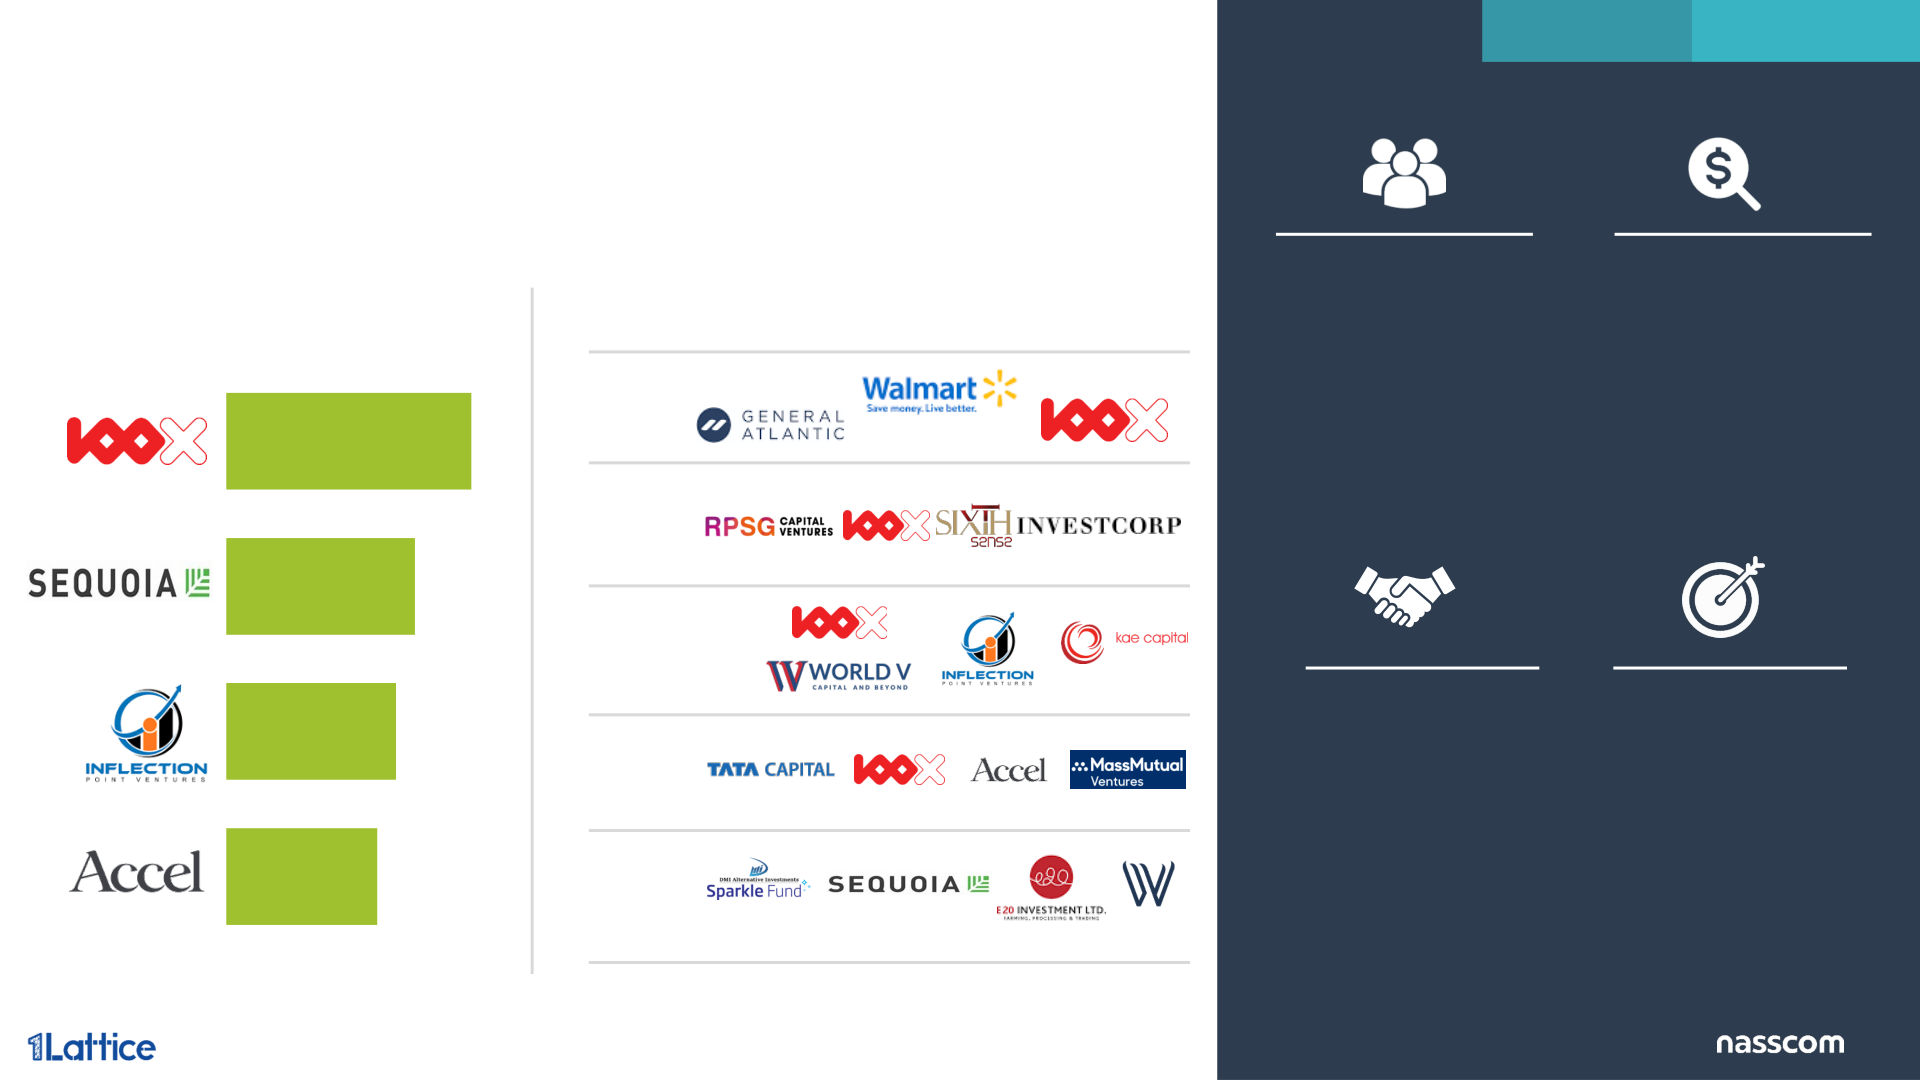
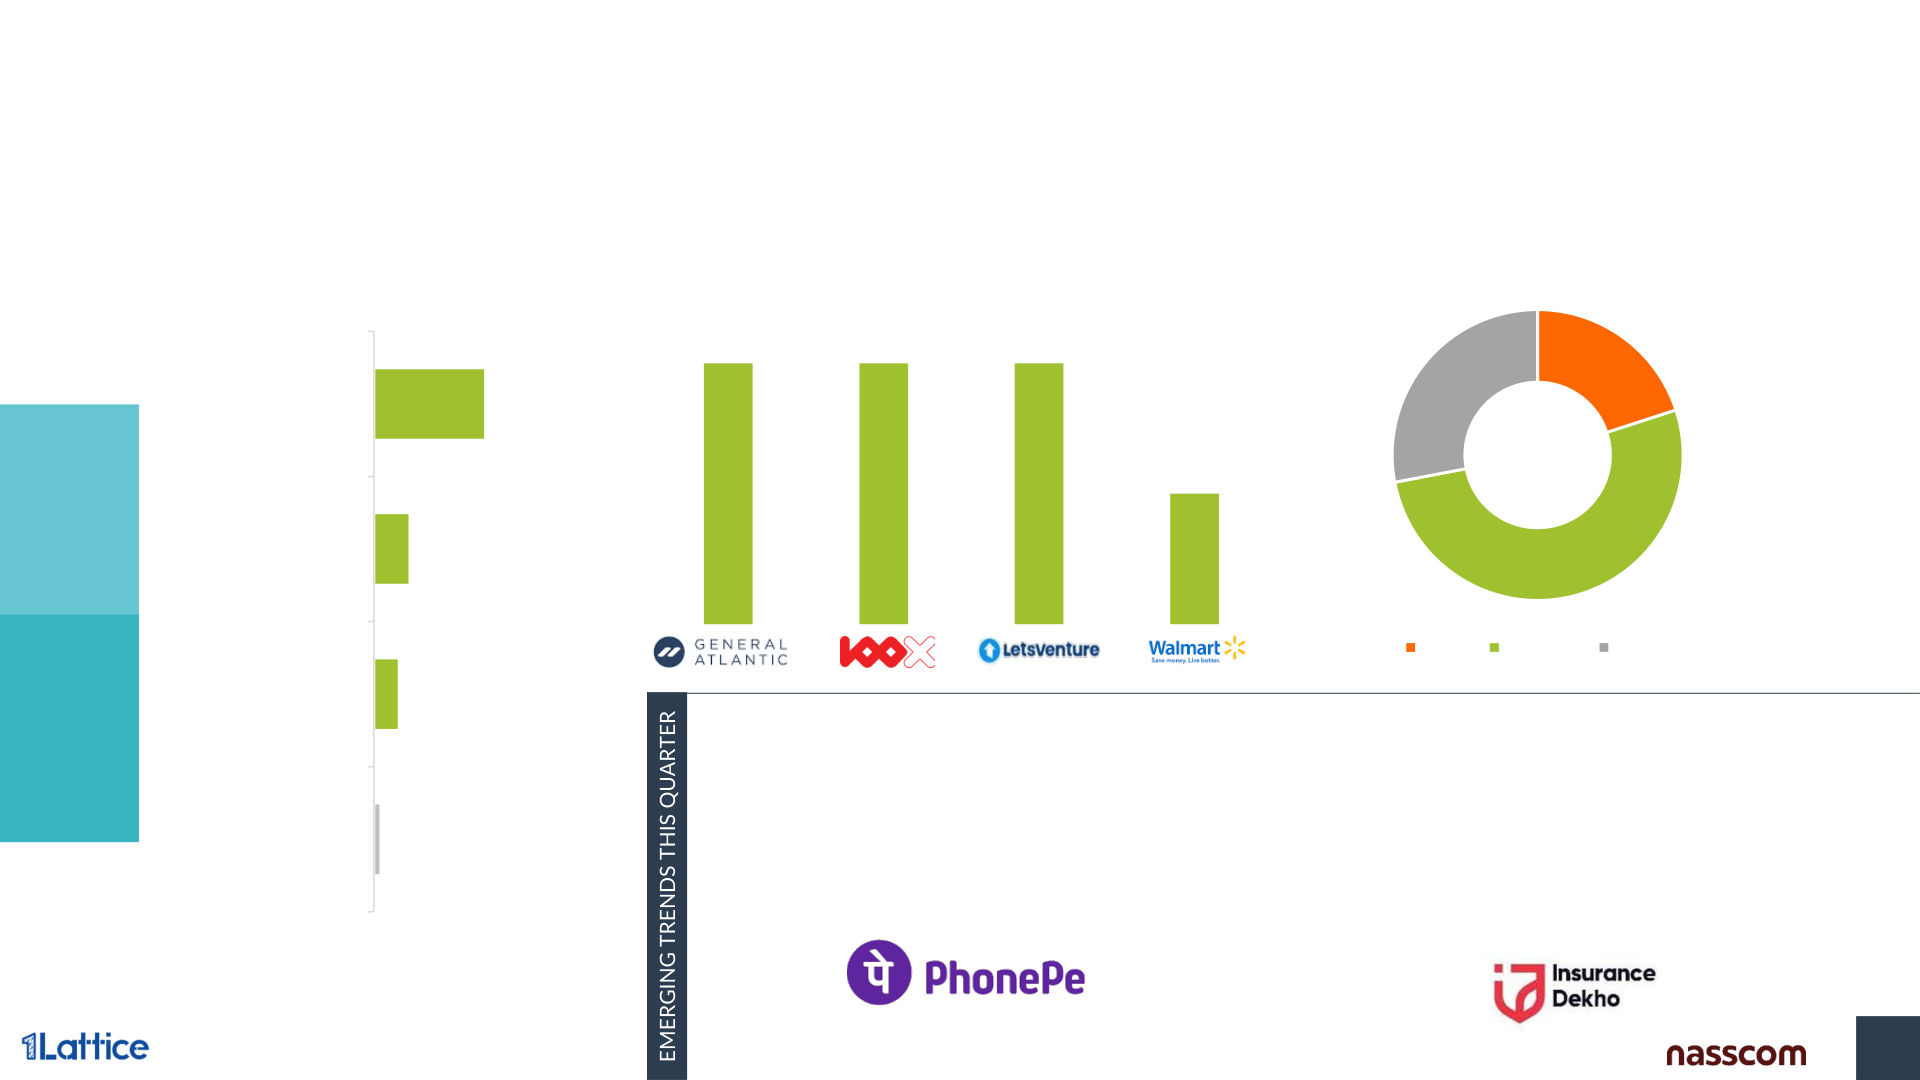
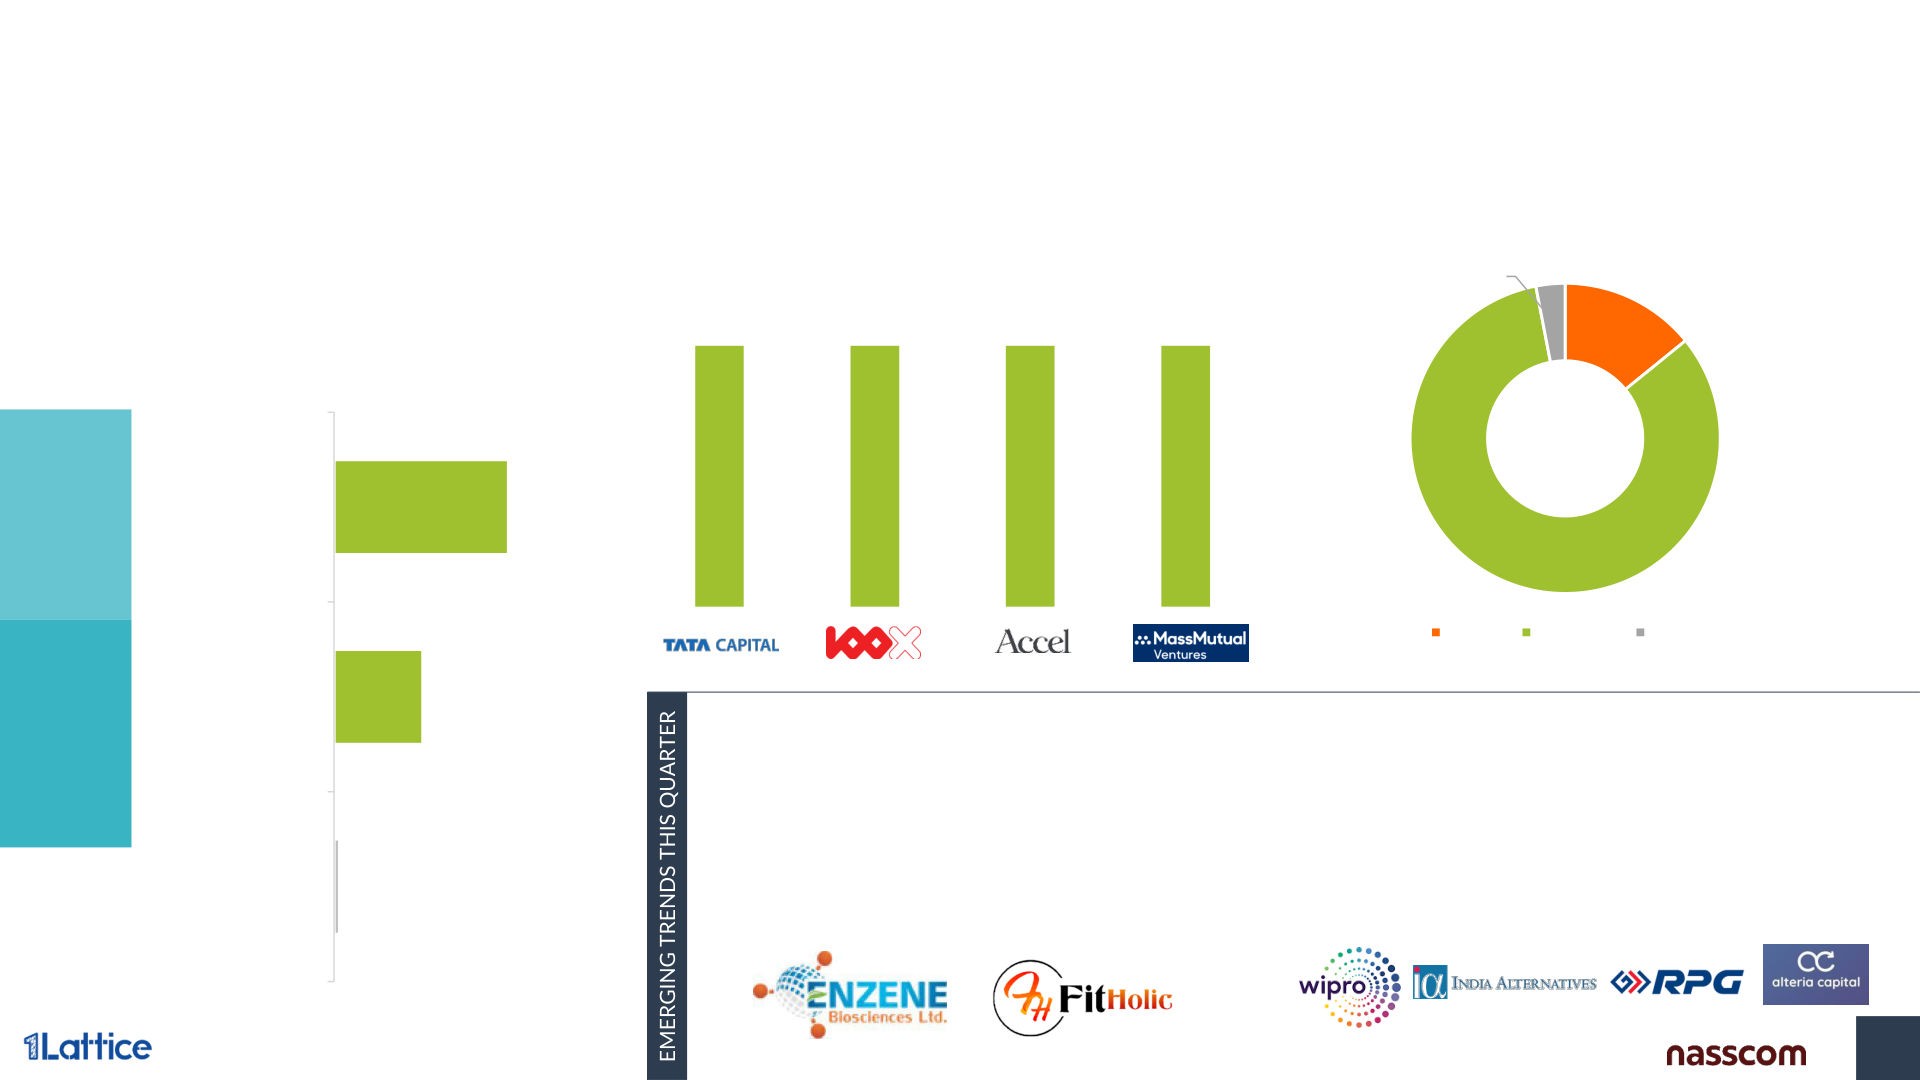
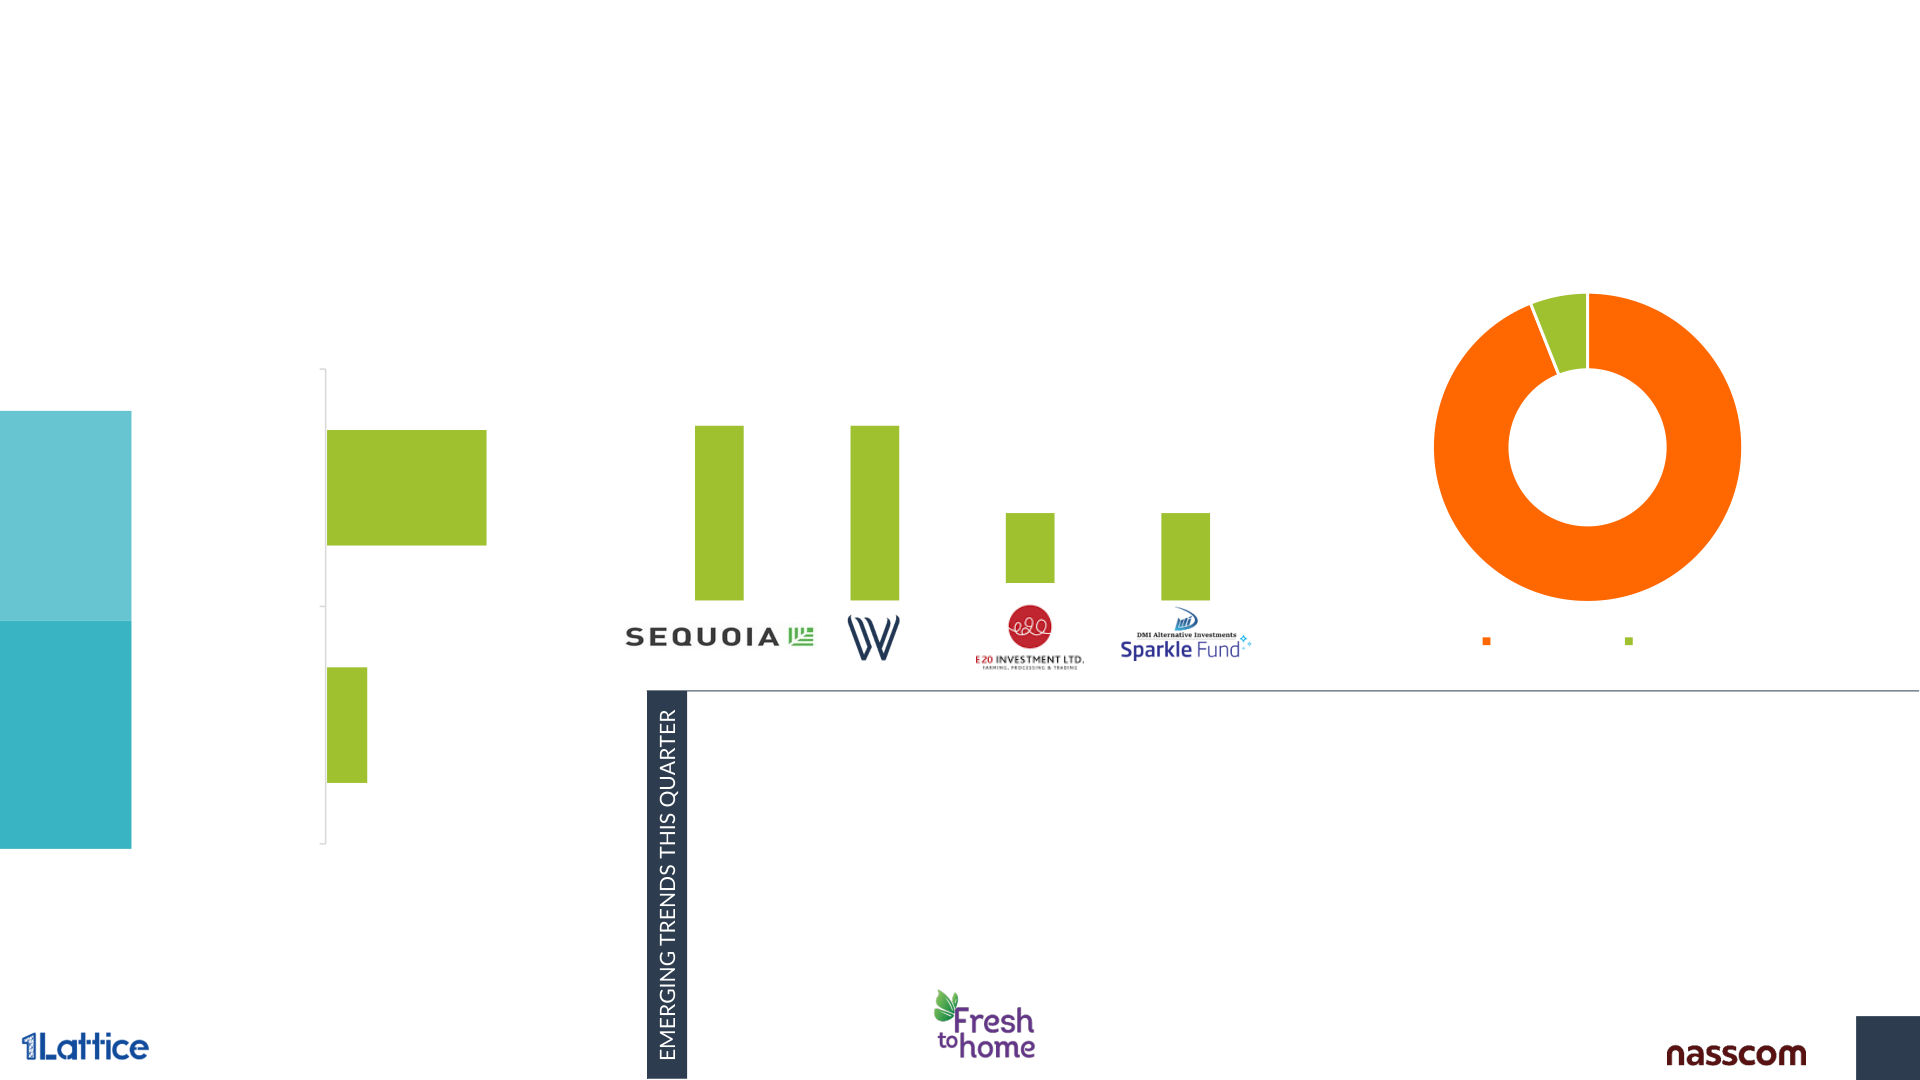
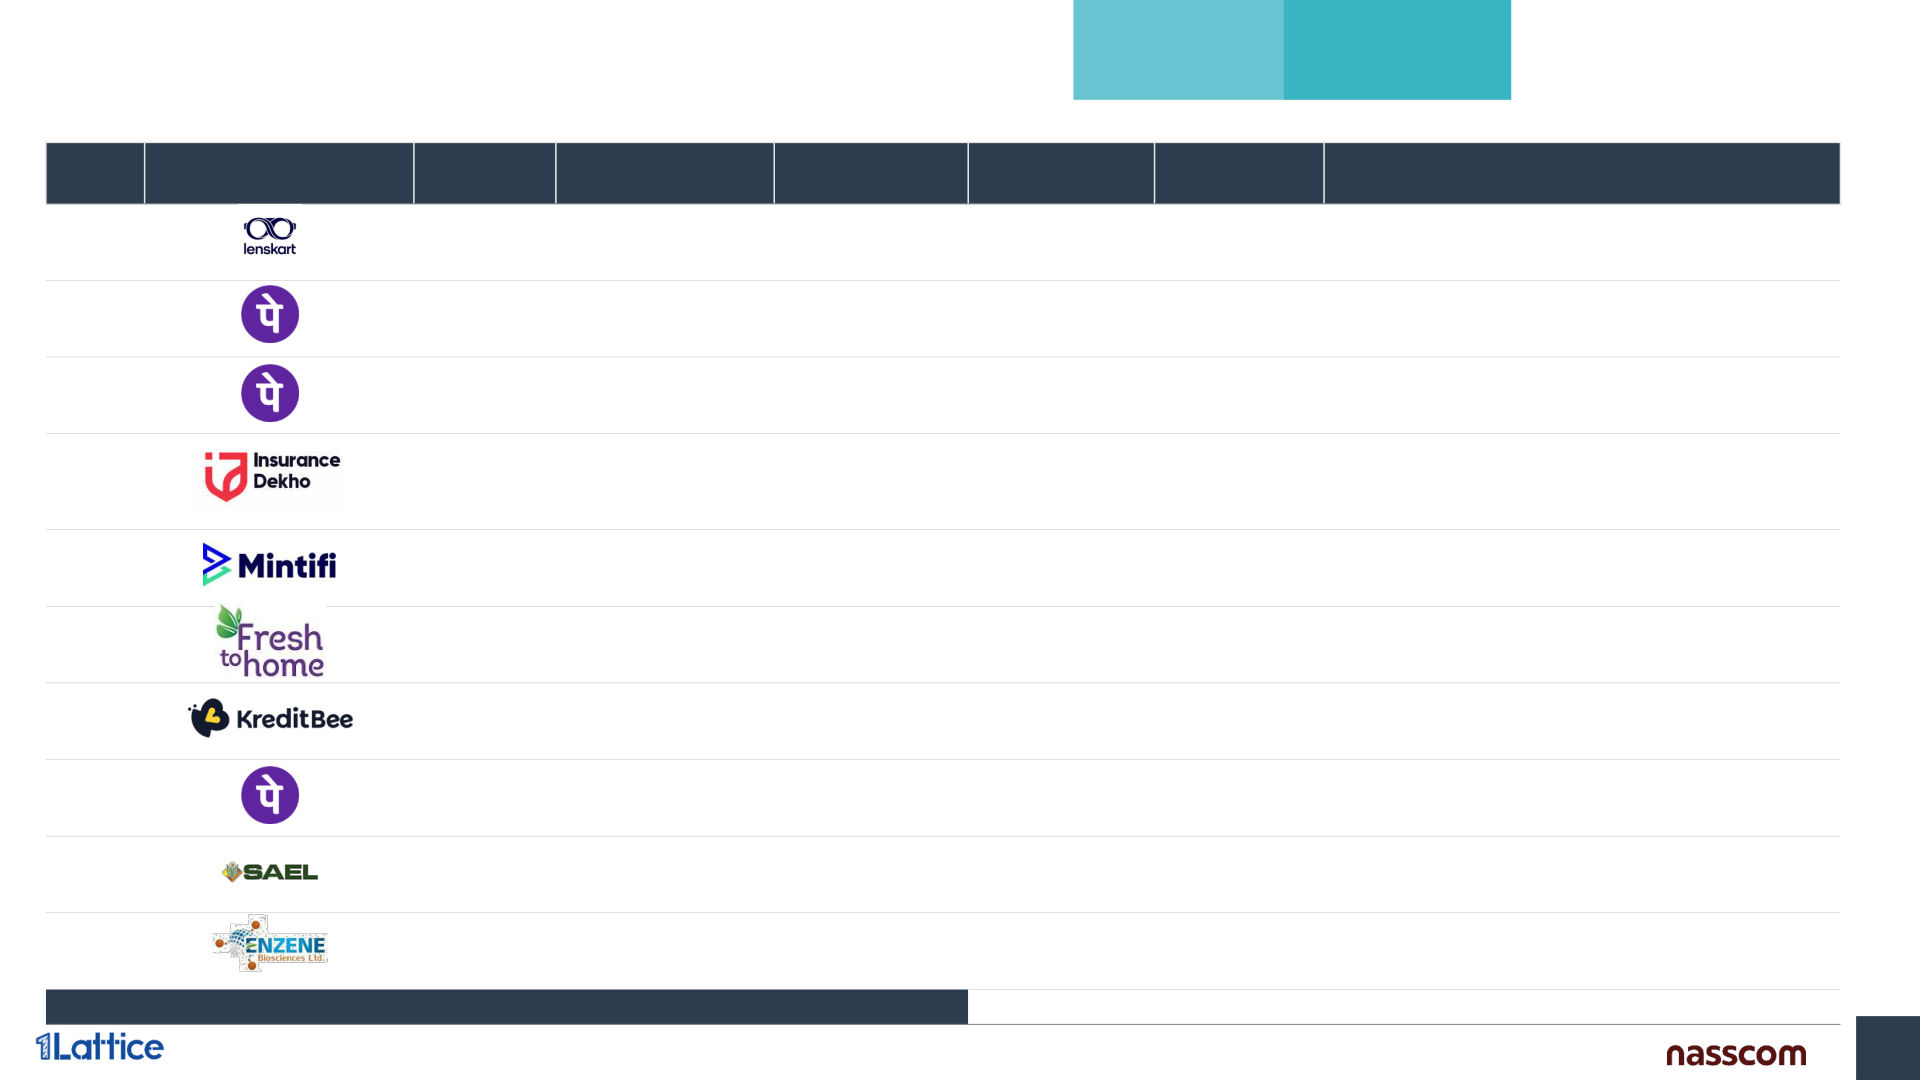
M a y , 2 0 2 3 QUARTERLY INVESTMENT FACTBOOK TECH START - UPS Q 1 CY2 3 START - UP DEAL ANALYSIS SUMMARY 02 CONTENT TECH START - UPS INVESTMENT TREND ANALYSIS 05 VERTICAL TREND ANALYSIS 13 GOVERNMENT SCHEMES 24 APPENDIX 26 2 Q1 CY23 Q4 CY22 Funding # Deal Volume Funding # Deal Volume US $ 2.9 B 252 US $ 3.1 B 258 SUMMARY SUMMARY Unicorns Unicorns NIL NIL ( 1 /2) Top Funded Vertical Most Funded Stage Top Funded Vertical Most Funded Stage FinTech Growth FinTech Growth ~56 % of the total funding ~42 % of the total funding ~35 % of the t otal f unding ~23 % of the t otal f unding o Global start - up funding environment continues to be tepid o Q1 CY2023 funding totaled US$76B — 2% lower Q - o - Q, 50% lower Y - o - Y o No of deals in Q1 CY2023 lower by 15% Q - o - Q, 45% lower Y - o - Y o Indian start - up funding environment – Green shoots visible • India tech start - ups funding at US$ 3.1B in Q1 CY23, up 7% Q - o - Q • The steady increase in deal volumes observed through last year continues - 2.3% up Q - o - Q, 4.5% up Y - o - Y • Late - stage deals emerge as key driver this quarter – share in total deal value increased by >60% from the previous quarter SUMMARY • Average deal value in this quarter to reach US$ 13.8M , up by 20% Q - o - Q ( 2 /2) • Rise in B2C funding - 48% higher Q - o - Q, 72% share of overall funding this quarter: rd • > 1/3 (US$ 1B) of Q1 CY23 funding went to FinTech , majorly driven by Payments that accounted for >60% of total FinTech funding • RetailTech funding also continues to soar with rise of >60% from the previous quarter to reach ~US$ 697M with B2C marketplace model getting the most traction nd • However, large valuations still not visible - 2 successive quarter with no unicorns TECH START - UPS Q - o - Q AND CUMULATIVE COMPARISON INVESTMENT DEAL VALUE BY LATEST QUARTER TREND ANALYSIS DEAL VOLUME BY LATEST QUARTER FUNDING BY SALES CHANNEL AND FUNDING ROUNDS TOP INVESTORS AND THEIR FOCUS SECTOR Global start - up ecosystem still under pressure, but steady recovery visible in Indian tech start - up funding environment - funding in Q1 CY23 increased by ~7% Q - o - Q TOTAL F UNDING DEAL VOLUMES (In US$ B, Q1 CY22 - Q1 CY23) (# of deals) 163.1 10,843 9,213 122.4 7,704 6,986 82.5 5,959 77.2 76 7.2 6.0 2.9 3.1 247 252 258 2.5 204 215 Q1 CY22 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 Q1 CY22 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 Global funding Indian Tech funding Global funding Indian Tech funding Note(s): Improved coverage has led to an increase in the number of deals. Global funding is at an overall level whereas Indian fundin g i s specifically for Tech sector 6 Source(s): 1Lattice Deals Database Large deals are back with ~52% total deals with ticket size >US$100M leading to >60% growth in share of late - stage funding Q - o - Q and Cumulative Comparison FUNDING BY DEAL SIZE FUNDING BY STAGE Indian tech start - up (% of total funding) (% of total funding) investments in Q1 CY23 reached $3.1 billion, an increase from $2.9 billion 7.2 6.0 2.4 2.9 3.1 7.2 6.0 2.5 2.9 3.1 recorded in Q4 CY22, but this 9% is still 60% lower when 17% 19% 23% 24% 25% 28% compared Y - o - Y 52% 52% 58% 21% 25% 62% In Q1 CY23, the percentage 52% 56% 42% share of late - stage funding 58% 19% 7% increased from 17% to 28% 18% 21% 17% 17% 15% 12% 35% 33% 30% 29% 29% 27% 24% ~52% of total deals were above 18% 13% 12% $100 million as compared to only ~23% deals in the previous Q1 CY22 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 Q1 CY22 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 quarter < US$ 25M US$ 25-50M US$ 50-100M >= US$ 100M Early Growth Late Undisclosed Note(s): Out of 258, 32 deals are undisclosed 7 Source(s): 1Lattice Deals Database Average deal value increased by 20% - FinTech and RetailTech are the key driving sectors with average deal value of >US$ 35 M and >US$ 25 M respectively Q - o - Q and Cumulative Comparison FinTech & RetailTech had the TOP 5 SECTORS BY AVERAGE DEAL VALUE AVERAGE DEAL VALUE BY QUARTER highest average deal value, ( In US$ M, Jan 2 3 – Mar 2 3 ) (In US$ M) experiencing high growth rates (FinTech ~134% and RetailTech ~100%) 29.4 29.1 38.6 Average deal value in Q1 CY23 increased by ~20% to 27.8 $13.8 million as compared to the previous quarter 13.8 11.5 11.5 14.9 PhonePe and Lenskart were the highest funded companies in 8.79 6.2 the FinTech & RetailTech sectors with a funding value of ~$650 million and ~$500 million respectively FinTech RetailTech FoodTech HealthTech EnterpriseTech Q1 CY22 Q2 CY22 Q3 CY22 Q4 CY22 Q1 CY23 Note(s): Out of 258, 32 deals are undisclosed; Mega deals (US$ 100M+) 8 Source ( s ): 1Lattice Deals Database FinTech and RetailTech attracted ~58% of the total funding, with ~42% deals in growth stage Deal value by latest quarter SPLIT OF DEAL VALUE In Q1 CY23, FinTech saw (In US $ B , Jan 2 3 – Mar 2 3 ) highest traction due to growth in sub sectors like Lending and FUNDING BY TICKET SIZE FUNDING BY STAGE FUNDING BY SECTOR Collection 2% 3% 8% 24% Growth stage start - ups received 28% 4% 30% ~42% of total funding in Q1 36% 4% CY23, indicating investors' 5% preference for investing in ~ US$ 3.1 B ~ US$ 3.1 B ~ US$ 3.1 B 52% businesses that have already 6% achieved significant growth and 17% scale in their operations 11% 7% 42% 22% ~52% of the funding in Q1 CY23 were from deals with a ticket size of >US$100 million, FinTech RetailTech EnterpriseTech with Lenskart securing the < US$ 25M US$ 25M-50M HealthTech Food & Foodtech Energy & utilities highest deal amount in the Early Growth Late EdTech Automotive AgriTech US$ 50M-100M >= US$ 100M quarter (~US$500 million) Others Notes(s): Others includes SCM & Logistics, Gaming, Travel & Hospitality, HRTech, Media & Entertainment, Mobility, Aerospace & Defence, Real estate & co nst ruction, Advertising & Marketing Tech, LegalTech, Industrial & Manufacturing ; Out of 258, 32 deals are undisclosed 9 Source(s): 1Lattice Deals Database Low ticket early - stage investments saw the highest number of deals; EnterpriseTech was the most attractive sector by deal volume Deal volume by latest quarter SPLIT OF DEAL V OLUME ( #, Jan 2 3 – Mar 2 3 ) DEAL VOLUMES BY TICKET SIZE DEAL VOLUMES BY STAGE DEAL VOLUMES BY SECTOR In Q1 CY23, EnterpriseTech alone attributed to ~22% of all deals, concentrating on 4% 12% 12% 2% improving company flexibility, 3% 3% 22% 14% efficiency and competitiveness 3% 6% 4% 4% 258 258 258 4% 12% 4% 5% 77% 12% 82% 6% 11% Early - stage deals accounted for ~82% of total deals by volume, EnterpriseTech RetailTech FinTech showing rising investors < US$ 25M US$ 25M-50M HealthTech EdTech Food & Foodtech Early Growth Late preference for start - ups in their US$ 50-100M >= US$ 100M SCM & Logistics Gaming Automotive development stage Undisclosed HRTech Energy & utilities AgriTech Others Notes(s): Others includes Media & Entertainment, Travel & Hospitality, Real estate & construction, Industrial & Manufacturing, Legal Tech, Advertising & Marketing Tech, Aerospace & Defense, Autotech & Mobility 10 Source(s): 1Lattice Deals Database % share of B2C tech start - ups in Q1 CY23 has increased to ~72% from 48% in Q4 CY22 Investment rounds Funding by sales channel and funding rounds Series A accounted for ~$705M owing to deals like InsuranceDekho and Charge Zone, whereas Series D B2 C start - ups accounted for ~72% of Series A & Series D deals account for ~47 % of deal value accounted for ~US$ 744M and included deals like total deal value SPLIT BY SERIES PhonePe and Mintifi (%, Jan 23 – Mar 23) DEAL FLOW SPLIT Seed 7% (%, Jan 23 – Mar 23) B2B & B2C businesses Series A 23% Lenskart, PhonePe, and InsuranceDekho are the top three B2C - funded start - ups of Q1 CY23. Mintifi, Series B 7% Sukhbir Agro, Energyint are the top B2B - funded start - 28% ups of this quarter Series C 11% Series D 24% ~ US$ 3.1 B Start - ups stages Series I 16% 72% Late - stage start - ups raised ~$862M in Q1 CY23, with Private equity 3% 11 deals. Investors have faith and are showing support for start - ups that have scaled and experienced substantial growth in their respective Corporate 7% sectors B2B B2C Venture 3% Source ( s ): 1Lattice Deals Database 11 100X.VC and Sequoia were the most active investors across sectors in Q1 CY23 Top investors and their focus sectors MOST PROMINENT INVESTOR IN TERMS OF DEAL VOLUME 100x was the most 100X.VC, Sequoia, IPV TOP INVESTORS, SPLIT OF DEAL FLOW active player in and Accel are leading INVESTOR DIVERSIFICATION (#, Jan 23 – Mar 23) EnterpriseTech with investors with AccelData and Ushur investments across raising highest funding sectors, indicating their FinTech in this vertical diverse portfolio and 13 potential across different verticals RetailTech 10 EnterpriseTech 100X.VC was the In the FoodTech 9 sector, Sequoia and most diversified White wale venture investor, investing HealthTech across FinTech, investment had maximum no. of deals RetailTech, EnterpriseTech and with FreshToHome 8 and The Whole Truth HealthTech FoodTech (TWT) raising the highest funding Source ( s ): 1Lattice Deals Database 12 KEY VERTICALS THAT HAVE ATTRACTED MAXIMUM DEALS IN TERMS OF VALUE VERTICAL TREND FinTech RetailTech EnterpriseTech HealthTech FoodTech ANALYSIS FinTech FinTech has been the one of the most attractive sectors in the start - up ecosystem, with payments and insurance gaining traction Overall, the fintech sector in India is expected to continue to grow in the coming years, driven by increasing digitization, rising consumer demand for financial services, and favorable government policies FinTech continues to General Atlantic among dominate by raising the most active investor ~36% of the total Q1 in the sector CY23 funding Growth - stage funding Payments raised dominated funding ~62% of total FinTech deals by value (~52% funding share) Top 3 deals in FinTech sector in Q1 CY23: PhonePe (US$ 350M), PhonePe (US$ 200M) and InsuranceDekho (US$ 150M) 14 FinTech start - ups witnessed investments of ~US$ 1.1B in Q1 CY23; ~62% of the total funding arising from Payments sub - sectors General Atlantic, 100X.VC & LetsVenture have ~52 % of total investment is in the Payment start - ups received the highest made 2 deals each in FinTech in this quarter growth stage funding in FinTech # of deals Split by FinTech funding ( % ) 2 2 2 20% 28% Payments 62% ~ US$ 1 1.1B Lending & Collection 20% 52% Early Growth Late Insurance 14% Insurance has been gaining traction with Payments emerged as an attractive area of one of the biggest deals of the sector investment • InsuranceDekho is the highest funded start - up in the insurance sub - sector • PhonePe raised highest funding in the payment sub - sector (~US$ Others* 4% and only the second highest funded among all FinTech deals 350M, ~US$ 100M, and ~US$ 200M), Via Ribbit capital, General • InsuranceDekho is an online platform that lets to compare insurance quotes Atlantic, Walmart, Tiger global and more over 3 rounds in the last from top - rated insurance companies and purchase the insurance policy that quarter suits individual’ need Note(s) : Others include FinTech Infrastructure, Personal wealth & finance, Crypto Exchange Source ( s ): 1Lattice Deals Database 15 RetailTech Utilizing data analytics to identify patterns and improving decision making, the RetailTech industry has shifted its focus towards technology enhancement, resulting in the transformation of traditional retail business models It has accounted for ~ 22 % of the total Q 1 CY 23 funding and has almost doubled RPSG Capital Venture RetailTech companies and 100X.VC Catalysts raised ~US$ 697M in were the largest Q1 CY23 investors in the sector B2C vertical 62% investments in the marketplace raised RetailTech sector are in ~92% of total late stage start - ups RetailTech funding in this quarter Top 3 deals in RetailTech sector in Q1 CY23: Lenskart (US$ 500M), and PAN Healthcare (~US$ 48M) and Wakefit.co (~US$ 40M) 16 B2C vertical marketplace start - ups dominated Q1 CY23; ~62% investments in RetailTech were in Late stage B2C vertical marketplace platforms RPSG Capital Venture and 100X.VC Catalysts ~62% investments are in Late stage have received the highest funding were the most prominent investors # of deals Split by RetailTech funding ( % ) 8% 2 2 B2C vertical 92% 30% ~ US$ marketplace 1 1 1 697M 62% B2B marketplace 7% Early Growth Late Social commerce 1% Higher adoption of advanced Evolution of the B2B Market Growth of social commerce start - technology in the B2C vertical ups • Start - ups were observed disrupting traditional • The use of cutting - edge technology like • B2B marketplace segment of the RetailTech machine learning & big data analytics to retail models and providing innovative solutions for industry in India is rapidly evolving, providing sellers and buyers improve inventory management, customize businesses with new opportunities to marketing, & improve customer experience • Betterhalf raised ~US$ 8.5M, being the highest in connect, trade, and grow the social commerce vertical marketplace in Q1 • B2C marketplace start - ups like The Souled • Fashinza raised ~US$ 30M being the highest CY23 Store raised funding of ~US$ 16M in series in the B2B vertical marketplace in Q1 CY23 stage in Q1 CY23 followed by Vilcart (~US$ 18M) Source ( s ): 1Lattice Deals Database 17 EnterpriseTech EnterpriseTech start ups attracted ~US$ 329M, ~11% of the total funding amount raised in Q1 CY23. EnterpriseTech industry has undergone unique changes that are enabling businesses to become more agile, efficient, and competitive. S egments such as Product Engineering Services and Software / Platform as a Service have exhibited substantial growth in the last quarter. 100X.VC has been one EnterpriseTech sector of the most active raised ~11% of total investor in this space in funds raised in Q1 CY23 Q1 CY23 Fastest - growing Growth - stage funding trends in dominated funding by EnterpriseTech space value (~57% share) are Artificial Intelligence, PES & SaaS / PaaS Top 3 deals in EnterpriseTech sector in Q1 CY23: Acceldata, (US$ 50M), Ushur (US$ 50M), and Mad Street Den (US$ 30M) 18 EnterpriseTech industry in Q1 CY23 attracted total funding of ~US$ 329M; ~52% was raised by start - ups based on AI AI based tech start - ups have received the 100V.VC is a major investor in ~57 % investments are in Growth stage highest funding in EnterpriseTech space EnterpriseTech sector with 4 deals in Q1 CY23 2% Split by EnterpriseTech funding ( % ) By # of deals 4 AI 52% 41% ~ US$ 2 2 329M 57% PES 24% SaaS / PaaS Early Growth Late 20% Adapting & Outpacing Competition AI Transforming Business Operations IT-BPM 3% with PES • AI is being leveraged to identify patterns & predict • Swiftly adapting to market changes and staying future trends, enabling businesses to make more ahead in competition through flexibility and informed decisions, detect potential security breaches in Cybersecurity 1% responsiveness in software development real - time and to optimize supply chain operations • Acceldata was the highest funded company in the • Ushar raised ~US$ 50M in the PES vertical in Q1 CY23 PES vertical, raising ~US$ 50M in growth stage followed by Mad Street Den (~US$30M) Source ( s ): 1Lattice Deals Database 19 HealthTech With a population of over 1 3 billion people, India has a large and growing demand for healthcare services . HealthTech companies are leveraging technology to bridge this gap and provide more accessible, affordable, and efficient healthcare solutions as the traditional healthcare system in India often becomes overstretched and underfunded HealthTech sector Tata Capital Healthcare raised ~6% of the total Fund has been one of investment raised in Q1 the most active investors CY23 in the HealthTech space Consumer healthcare ~82% investments in the space has raised ~65% HealthTech sector are in of the total HealthTech growth stage start - ups funding Top 3 deals in HealthTech sector in Q1 CY23: Enzene Biosciences (US$ 50M), Fitholic (US$ 49M), and HealthPlix (US$ 22M) 20 HealthTech start - ups witnessed investments of ~US$ 192M in Q1 CY23; Tata Capital Healthcare Fund was one of the major investors in this space Consumer healthcare has received Tata Capital Healthcare Fund has been one of ~82 % investments are in Growth stage the highest funding in HealthTech the most active investors in HealthTech sector space 3% By # of deals Split by HealthTech funding ( % ) 2 2 2 2 14% ~ US$ 192M Consumer 65% healthcare 82% Early Growth Late Pharma & Biotech 33% HealthTech is gaining momentum Pharma & Biotech start - ups • Investors have also shown interest in Pharma & Biotech start - ups due to the high • HealthTech companies are leveraging mobile technology to reach a demand for healthcare services and products, including medicines, vaccines, and wider audience and provide on - demand healthcare services. medical devices • Start - ups such as Enzene Biosciences & Fitholic raised ~US$ 50M & • Pharma & Biotech start - up Fitholic has raised US$ 49M from India Alternatives, US$ 49M respectively in Q1 CY23 Others 2% Wipro Enterprises, DS Group, Alteria Capital, RPG Ventures, Fireside Ventures in Q1 CY23 Source ( s ): 1Lattice Deals Database 21 FoodTech FoodTech industry in India has been evolving rapidly, driven by changing consumer preferences, urbanization, and the rise of the middle class . One of the key drivers of food tech funding in India has been the increasing adoption of online food ordering and delivery platforms These platforms have disrupted the traditional food industry and created new opportunities for start - ups to innovate and grow . Amazon Sambhav Venture Fund, E20 Strong growth potential Investment Ltd Mount in FoodTech, with a Judi Ventures, and funding of ~US$ 164 M Dallah Albaraka have in Q 1 CY 2 3 been active in this quarter Growth funding Online food ordering dominated funding start - ups have raised deals by value (~94% ~79% of the total share) owing to FoodTech funding FreshtoHome deal (US$ 104M) 22 Online food ordering start - ups raised 79 % of total FoodTech investments Online food ordering start - ups raised Sequoia and White Whale Ventures, were the ~94% investments are in growth prominent investors in the FoodTech sector ~79% of the total funding stage Split by FoodTech funding ( % ) By # of deals 6% 2 2 ~ US$ 164 M Online Food 79% 1 1 Ordering 94% Growth Early Restaurant Management Cloud 21% Growing technology integration in Health and wellness quotient Solutions food ordering systems • Investors are attracted towards technology integration as there • Investors have recognized the growing significance of physical fitness has been a shift towards digitalization in the food industry among consumers who are becoming increasingly health - conscious and • More consumers are ordering food online, and food tech seeking out nutritious food choices. In response to this trend, FoodTech companies are leveraging digital technologies to streamline companies are providing healthier options like organic and plant - based operations, enhance customer experience, and increase efficiency products. This presents a promising opportunity for start - ups to • FreshToHome was the highest funded company in the FoodTech complement the shift towards healthier eating sector, raising ~US$ 100M in growth stage Source ( s ): 1Lattice Deals Database 23 Amendments in regulations Government initiatives & schemes Amendments in regulations & notifications pertaining to start - ups in India The government has recently made some amendments in the start - up India Action Plan with the goal of creating a solid ecosystem for fostering innovation among start - ups Date of policy Ministry / Amendments Description change Department Foreign in vestments RBI has rationalized the reporting process in Single Master Form (SMF) on Jan – 23 reporting FIRMS Portal for Foreign Investment in India The Finance Bill 2023 proposes to amend Section 79 of the Income Tax Act, Extended period for Feb – 23 1961 and extend the period for eligible start - ups to carry forward and set off paying off losses losses incurred in the first 10 years vis - a - vis 7 years of their incorporation The Finance Bill 2023 proposes to amend Section 80 - IAC of the Income Tax Act, 1961 and extend the period of incorporation of the eligible start - ups by one Tax Incentive for Feb – 23 more year, that is, up to 31st March 2024. Eligible start - ups incorporated eligible start - ups within this period will be provided a tax incentive for three consecutive years out of ten years from the date of incorporation The Finance Bill 2023 proposes to cap the surcharge on the long - term capital Long - term capital Feb – 23 gain at 25% for unlisted companies from existing 37% under the new tax gain tax rate regime. The effective rate of tax has been reduced from 42.74% to 39.0% Source ( s ): Secondary research, 1Lattice Deals Database 25 TOP 10 DEALS APPENDIX SECTOR WISE TOP DEALS METHODOLOGY DEFINITIONS : STAGES / SECTORS Appendix Top deals of Q 1 CY2 3 FUNDING FUNDING # COMPANY FOUNDED SECTOR SUB - SECTOR INVESTORS (US$ M) STAGE B2C vertical 1 2010 Retail Tech 500 Late Abu Dhabi Investment Authority (ADIA) marketplace 2 2013 FinTech Payments 350 Growth General Atlantic 3 2013 FinTech Payments 200 Late Walmart Goldman Sachs Asset Management and TVS Capital Funds, Investcorp, Avataar Ventures and LeapFrog 4 2016 FinTech Insurance 150 Early Investments, West Street Global, Alstroemeria Investments, LeapFrog 5 2017 FinTech Lending & collection 110 Growth Premjiinvest, Norwest Venture Partners, Elevation, IFC Amazon Smbhav Venture Fund, E20 Investment Ltd, 6 2011 Food & FoodTech Online Food Ordering 104 Growth Mount Judi Ventures, and Dallah Albaraka 7 2018 FinTech Lending & collection 100 Growth Advent International Ribbit Capital, Tiger Global and TVS Capital Funds, General 8 2013 FinTech Payments 100 Late Atlantic 9 1999 AgriTech - 61 Growth Norfund Alkem Laboratories, Eight Roads Ventures, and F - Prime 10 2006 HealthTech Consumer Healthcare 50 Growth Capital Total of top deals 1,725 Source ( s ): 1Lattice Deals Database 27 Appendix Sector wise top deals in Q1 CY2 3 SUB - FUNDING FUNDING FUNDING FUNDING COMPANY INVESTORS COMPANY SUB - SECTOR INVESTORS SECTOR (US$ M) STAGE (US$ M) STAGE FINTECH HEALTHTECH Enzene Consumer Alkem Laboratories, Eight Roads 50 Growth Biosciences healthcare Ventures, and F - Prime Capital PhonePe Payments 350 Growth General Atlantic Pharma & Fitholic 49 Early Undisclosed biotech PhonePe Payments 200 Late Walmart Avataar Ventures, SIG Venture Capital, Goldman Sachs Asset Management and Consumer Lightspeed Venture Partners, JSW HealthPlix 22 Growth TVS Capital Funds, Investcorp, Avataar healthcare Ventures, Kalaari Capital, Chiratae InsuranceDekho Insurance 150 Early Ventures and LeapFrog Investments, Ventures, BlackSoil West Street Global, Alstroemeria Investments, LeapFrog FOOD & FOODTECH RETAILTECH Amazon Smbhav Venture Fund, E20 Online Food B2C vertical FreshToHome 104 Growth Investment Ltd, Mount Judi Ventures, Lenskart 500 Late Abu Dhabi Investment Authority (ADIA) Ordering marketplace Dallah Albaraka Restaurant A91 Partners, White Whale Ventures, B2C vertical Blue Tokai Management PAN Healthcare 48.4 Growth Motilal Oswal, Orbit Financial Capital 30 Growth 8i Ventures, Grand Anicut Fund, and marketplace Coffee Cloud leading family offices Solutions B2C vertical Investcorp, Sequoia Capital India, Wakefit .co marketplace 40 Growth Verlinvest, SIG The Whole Online Food Sequoia Capital India, Matrix Partners 15 Growth Truth (TWT) Ordering India, Sauce.VC ENTERPRISETECH March Capital, Sanabil Investments, Acceldata PES 50 Growth Industry Ventures and Insight Partners Third Point Ventures and Iron Pillar, Ushur AI 50 Growth 8VC, Aflac Ventures and Pentland Ventures Avatar Growth Capital, Sequoia Capital Mad Street Den AI 30 Growth and Alpha Wave Global Source ( s ): 1Lattice Deals Database 28 Appendix Scope WHAT’S EXCLUDED FROM WHAT'S INCLUDED IN THE Inclusions & Exclusions THE REPORT? REPORT? • Non - tech start - ups operating in the • Only tech start - ups have been consumer space have not been considered for this report which are included in this report (For example - working towards innovation in Serentica Global) technology , business process or business model • Investments from angel investors, incubators and start - up accelerators • Start - ups which have received funding have been excluded from private equities or venture capital firms have been considered • Debt investments and strategic deals into tech start - ups have not been • Founders of Indian origin with HQ or considered (For example - BigBasket, core product development in India MyGate) • Start - up to have a prototype or MVP; • Start - ups at the idea stage without a idea stage start - ups are not considered prototype or minimum viable product have also not been considered 29 Appendix PRIMARY INPUT FOR THIS REPORT Methodology INCLUDES THE FOLLOWING SOURCES This pulse report has been co - developed by nasscom and 1 Lattice through a comprehensive study to Extensive research of media understand the tech start - up landscape in India articles Inc42 Mint This report analyses the following : Your story Business • Current investment scenario and trends that define the Indian tech start - up ecosystem IVCA Standard • Ecosystem enablers like Incubators/Accelerators as well as government policies Economic Times • Recent DRHPs filed with the regulators • The total of all quarters is not comparable to the data published in nasscom’s Annual Start - up report as the definitions and criteria considered are different 1Lattice proprietary deal database Government websites Ministry of corporate affairs SEBI Sector analyst reports 30 Definitions of stages and sectors Appendix Media & Entertainment FoodTech Automotive STAGES OF FUNDINGS HAVE BEEN Provides content for entertainment across the Tech enabled companies supporting the Companies involved in production, web and mobile medium FoodTech industry MAPPED AS manufacturing, sales and services of motorized E.g., News & Media Apps, Live Streaming Apps, News E.g., Online Food Ordering, Restaurant Management Cloud vehicles Platforms, OTT Content, Video Intelligence Apps, etc. Solutions, Food Discovery Platform E.g., Electronic Engineering, System Integration, Automotive Maintenance, Electric Vehicles, Automotive marketplaces, etc. Series A and prior rounds are early stage SCM & Logistics RetailTech Enabling tech in logistics services and supply Series B,C,D and E are growth stage Companies enabling Sales of goods and product FinTech chain management online or Integration of tech in offline markets ; Enables financial services, banking and insurance Series F and above are late stage E.g., Logistics and Distribution Platform, Fleet Management, E.g., Products/Services cutting across several verticals, through technology Warehousing, IoT Platform for Logistics, IoT Platform for Marketplaces, Online grocery & Home essentials platforms. E.g., Online Banks, Financial Management Apps, Payment Goods Transportation Marketplace, etc. Also includes Retail enablers, B2B marketplaces, Social Management Platforms, Alternative Lending Platforms, Money commerce platforms, Rental platforms etc. Transfer Platform, Expense Management, Investment Gaming Platforms, Cryptocurrency & Trading Platforms, etc. Tech Innovation and facilitation in the Gaming AgriTech industry Start ups engaged in tech enablement in the EdTech E.g., AR/VR Gaming, Community platform Games, Fantasy Agricultural industry Provides learning solutions & services through Gaming Platforms etc. E.g., Field Surveillance, Precision AgriTech, Farm infrastructure, technology SECTOR DEFINITIONS Soil Testing, Farm Input E Commerce etc. Legal Tech E.g., Learning Apps, Test Preparation Tech, Education Advisory Platform, K 12/Higher education platforms, Language Learning Tech based companies for Legal help to Advertising & Marketing Tech EnterpriseTech Platforms etc. Individuals/Corporates Provides direct advertising and marketing B2B Product companies targeting Horizontal E.g., Contract Management, Brand Protection and Anti assistance through technology Travel & Hospitality Counterfeit, Legal Services Discovery/Booking marketplaces, solutions for Large Enterprises / SMBs E.g., Content marketing, influential marketing, Push E.g., Data Analytics/AI/ML Platforms, Development Platforms, etc. Tech companies engaged in supporting the travel notifications etc. Collaboration tools Productivity Applications, Customer and hospitality industry Services, Big Data/Cloud/Security Infrastructure, etc. E.g., Hotel Booking Services, Travel Planning, Travel Packages Aerospace & Defense Portal, Travel Collaboration Community, etc. Tech - based companies supporting the Defence HealthTech and Aviation industry Provides technology platform for solving Mobility E.g., Military Drones, Green Propulsion Systems developers, HealthTech problems Tech - enabled companies providing simplified Sensors and Platforms for security applications etc. E.g., Medical Solutions, Marketplace for Health Services, Transportation services to users Health Lab Aggregators, Online Pharmacies, E - Diagnostics, E.g., Car pooling, Self Drive Rentals, Two - wheeler taxi Ambulance Aggregator, etc. Energy & Utilities aggregators, Mass Transit, Tech Enablers Tech Enablement for Natural Resource HRTech Management and Utilization Industrial & Manufacturing Tech - enabled companies supporting Human E.g., Renewable Energy products, Recycling of Resources, Engaged in manufacturing of tech - enabled Energy Production and Distribution, EV charging Infrastructure Resources Activities etc. devices or machines; Construction/Mining E.g., Applicant Tracking systems, HR Management System, Candidate Assistance & Sourcing, Corporate Training/Learning sector, etc. and Development, Recruitment Marketplaces, etc.. E.g., IoT based Predictive Maintenance of Machines, 3D Printing (Manufacturing) 31 Definitions of sub - sectors Appendix FINTECH RETAILTECH • Lending & collection: Tech start - ups dealing with financing services to • B2B marketplace: Companies enabling buying or selling products to other consumers or other businesses businesses on a single platform • Personal wealth & finance: Platforms enabling trading, personal wealth • Social commerce: Companies dealing with buying or selling of products via planning, etc. social media / community platforms • Neo Banking: Digital banks that does not have physical branches • B2C horizontal marketplace: E - commerce companies that sell products directly • Payments: Apps & platforms which enables payment service to consumers from a large number of categories • Crypto Exchange: Companies dealing with cryptocurrency exchange • B2C vertical marketplace: E - commerce companies that sells products directly to • Insurance: Companies providing & selling personal & digital insurances consumers around a specific niche • FinTech Infrastructure: Companies that provides technology / platforms • Re - commerce : E - commerce Companies that allow customers to buy & sell used / solutions to FinTech players for their businesses products online • Retail Enablers: Companies that provides end - to - end solution for brands to do e - commerce business ENTERPRISETECH • Online Grocery: Companies dealing with instant delivery of groceries • AI: B2B companies which deal in Artificial Intelligence • SaaS / PaaS: New age tech companies providing software solutions / HEALTHTECH products to other business • IT - BPM: Providing IT services to other businesses - Consumer healthcare : Companies focusing on OTC medicines, dietary • PES: Companies dealing with hardware / software / processes to supplements, medical devices, or personal care products. streamline business operations for an end - to - end product development - HealthTech : Companies using technology to improve the efficiency, effectiveness, and delivery of healthcare services - Pharma & Biotech - Companies involved in the development and production of drugs, therapies, and medical products for the treatment and prevention of Companies dealing with chains of restaurants, diseases. FOOD & FOODTECH • Restaurant Management Cloud Solutions: Companies dealing with the management of restaurants which includes tech support 32 About 1Lattice is a technology-enabled business research & intelligence services firm that nasscom is the industry association for the technology sector in India A not - for profit specializes in driving decision from on-ground insights. Our teams are multifaceted with organization funded by the industry, its objective is to build a growth led and a unique mixture of qualitative, quantitative and digital research experts. With a holistic sustainable technology and business services sector in the country with over 3 , 000 approach focusing on the “ What and Why ”, we are able to extract relevant insights members nasscom Insights is the in house research and analytics arm of nasscom from data employing advanced technology tools and innovative data gathering generating insights and driving thought leadership for today’s business leaders and approaches. entrepreneurs to strengthen India’s position as a hub for digital technologies and innovation Our clients use our capabilities to generate competitive / market insights for the sectors they operate in, sectors they want to expand to or the sectors of interest for their USAGE OF INFORMATION portfolio companies. Forwarding/copy/using in publications without approval from nasscom will be considered as infringement of intellectual property rights . www.1Lattice.in FOR QUERIES, PLEASE CONTACT VAISHNAV KUMAR RAI Manager, Corporate Communications vaishnav.rai@praxisga.com +91 7827 944 925 33 1Lattice We enable better decision making. Deep business research and intelligence that helps in driving 30% 500+ faster to annual SMARTER DECISIONS outcomes engagements 600+ Deep on - ground insights that you can act on 8 years of domain practices expertise 4 offices, deep experience across geographies – India, US, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy Advanced technology tools and innovative data gathering approach 100+ 2.5M+ Multifaceted teams with a unique mixture of towns & cities panel members qualitative, quantitative, and digital research experts 40:60 15+ she - he ratio languages covered DISCLAIMER The information contained herein has been obtained from sources believed to be reliable nasscom and its advisors & service providers disclaims all warranties as to the accuracy, completeness or adequacy of such information nasscom and its advisors & service providers shall have no liability for errors, omissions or inadequacies in the information contained herein, or for interpretations thereof . The material or information is not intended to be relied upon as the sole basis for any decision which may affect any business Before making any decision or taking any action that might affect anybody’s personal finances or business, they should consult a qualified professional adviser . Use or reference of companies/third parties in the report is merely for the purpose of exemplifying the trends in the industry and that no bias is intended towards any company This report does not purport to represent the views of the companies mentioned in the report Reference herein to any specific commercial product, process or service by trade name, trademark, manufacturer, or otherwise, does not necessarily constitute or imply its endorsement, recommendation, or favouring by nasscom or any agency thereof or its contractors or subcontractors The material in this publication is copyrighted No part of this report can be reproduced either on paper or electronic media without permission in writing from nasscom Request for permission to reproduce any part of the report may be sent to nasscom 35 C o p y r i g h t © 2 0 2 3 nasscom Plot 7 to 10, Sector 126, Noida - 201303 / nasscomVideos / nasscomOfficial / nasscomR www . nasscom . in research@nasscom in + 91 - 120 - 4990111