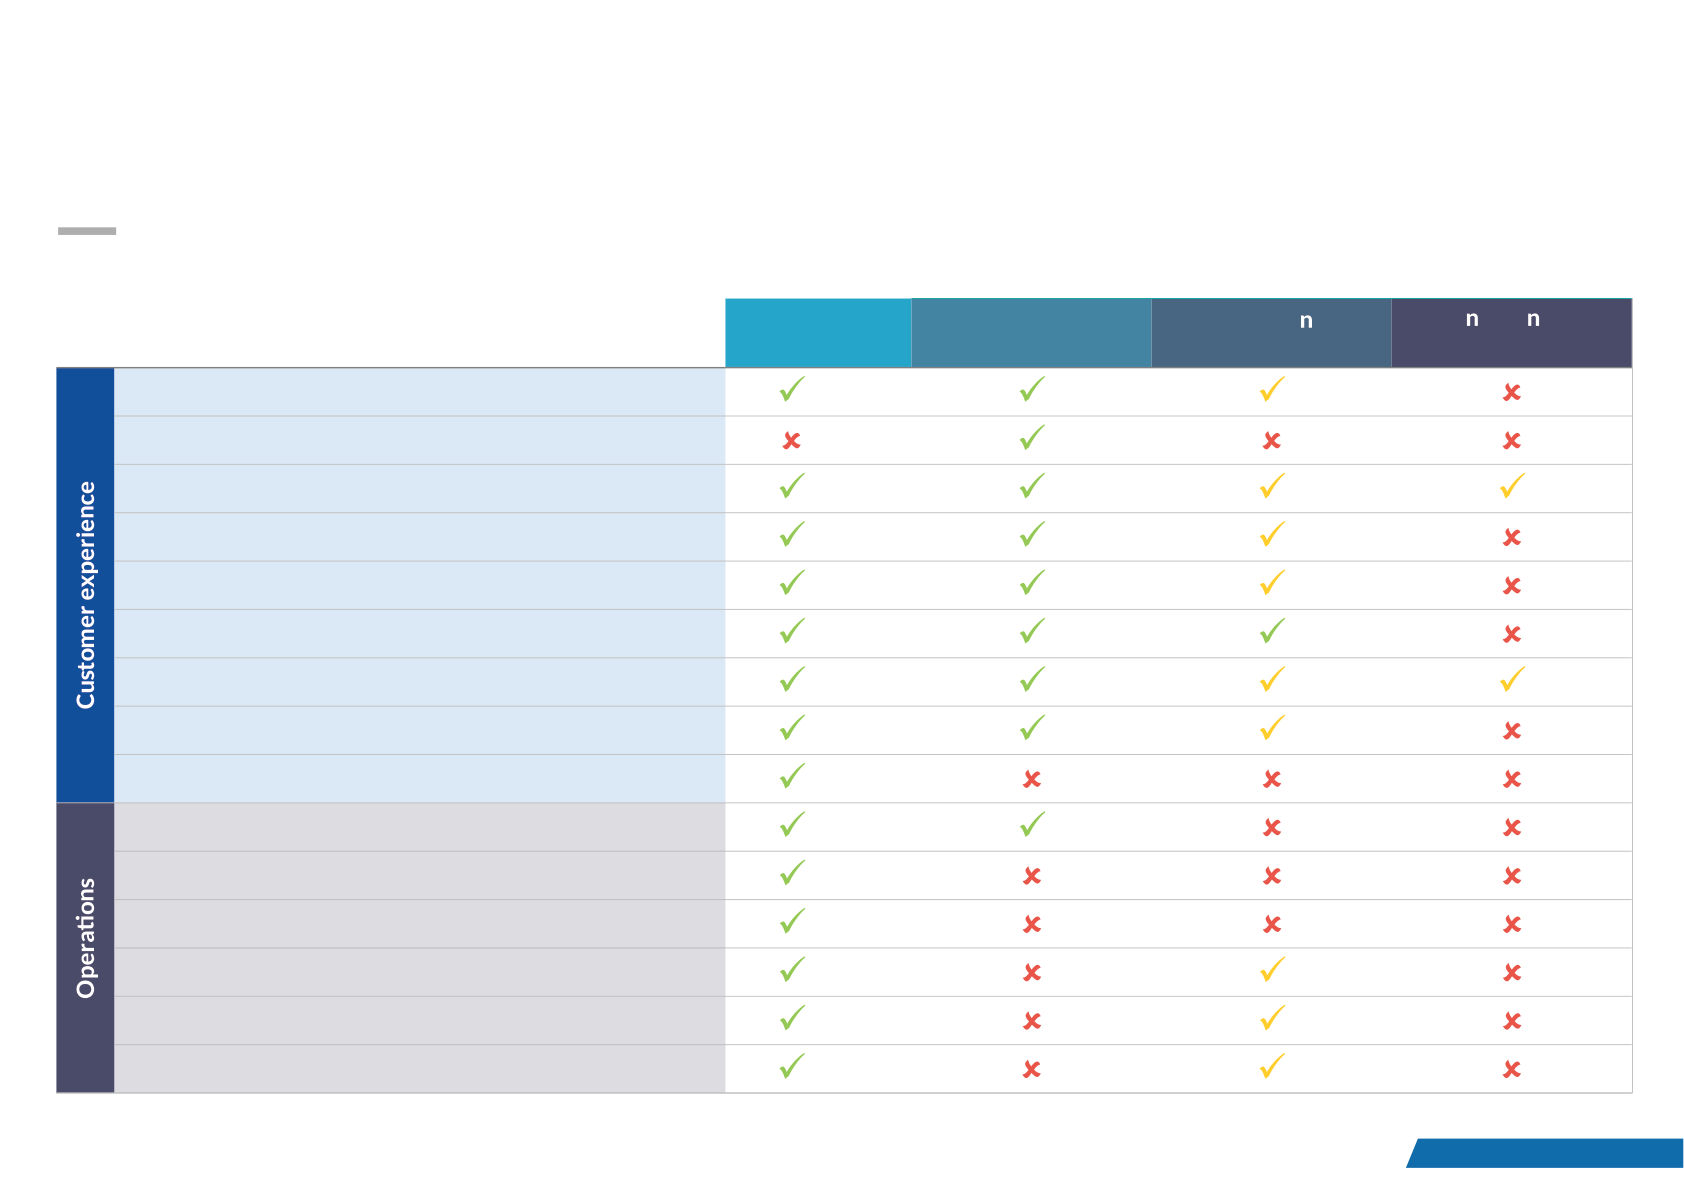
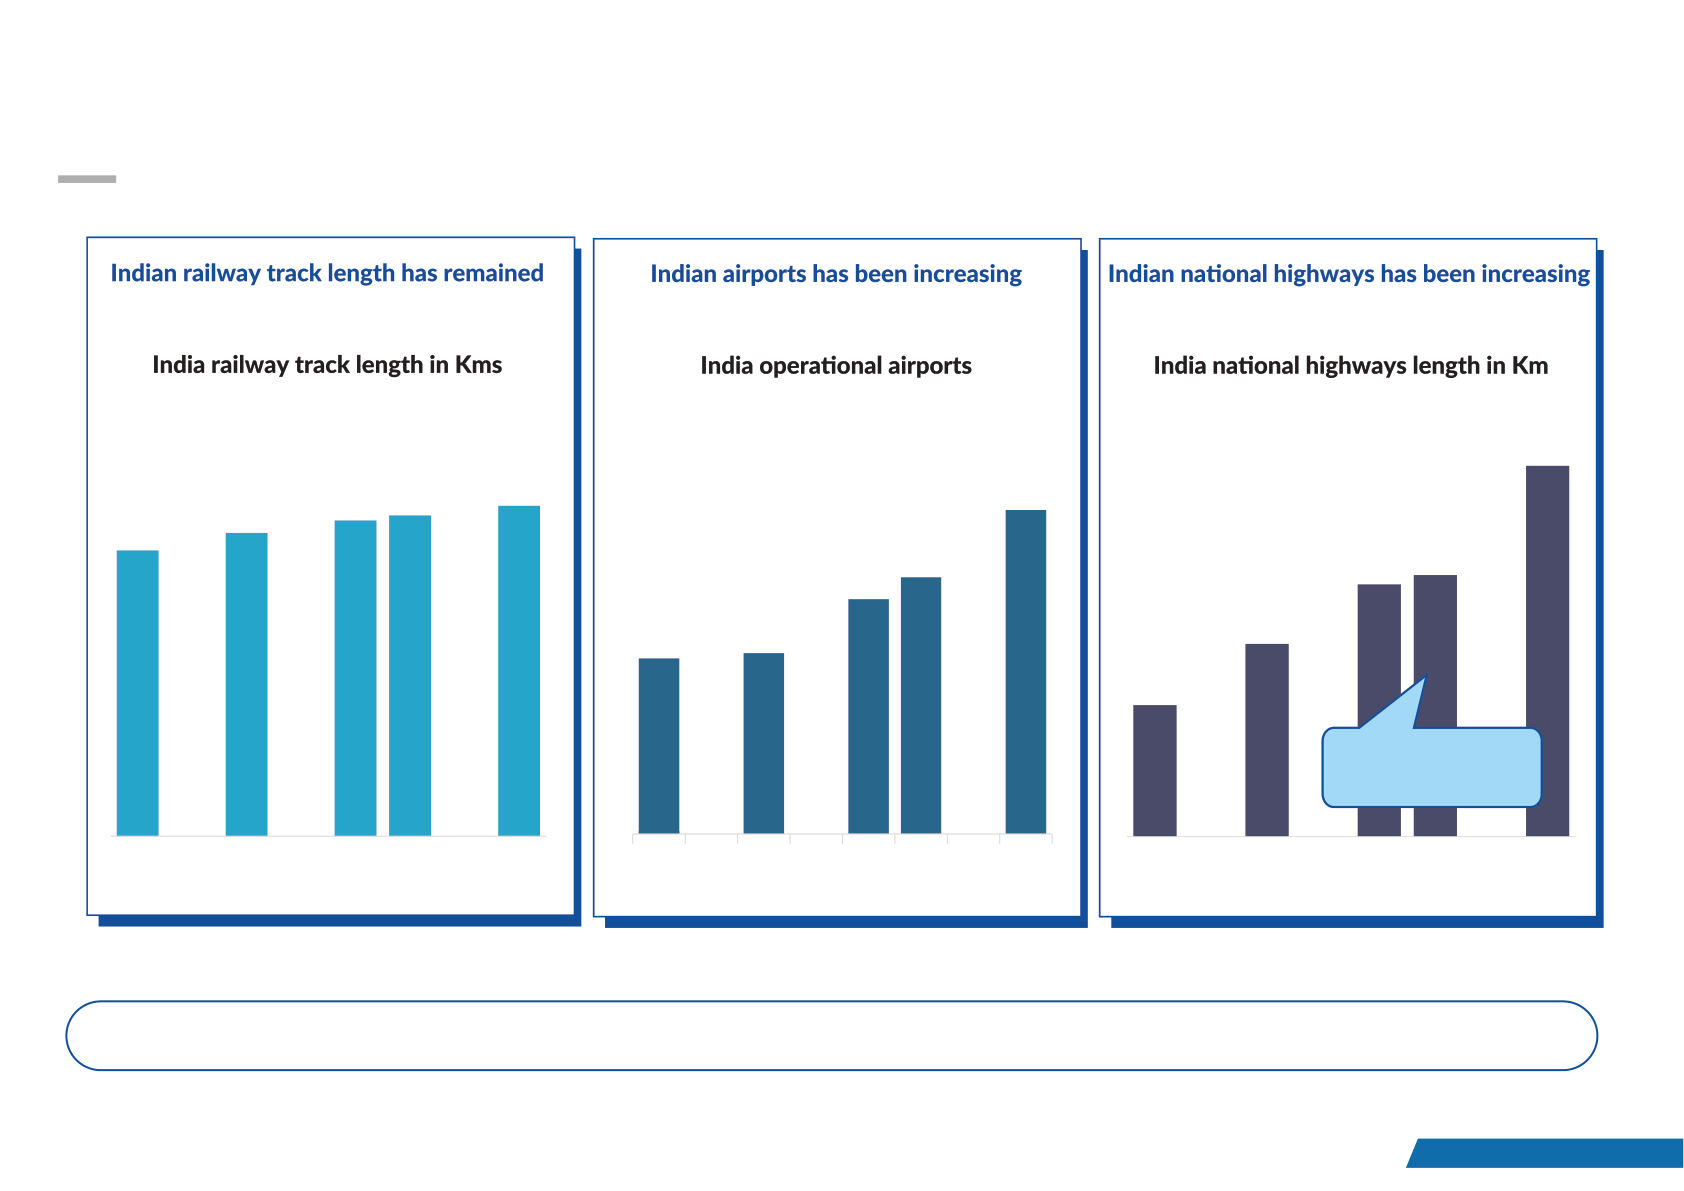
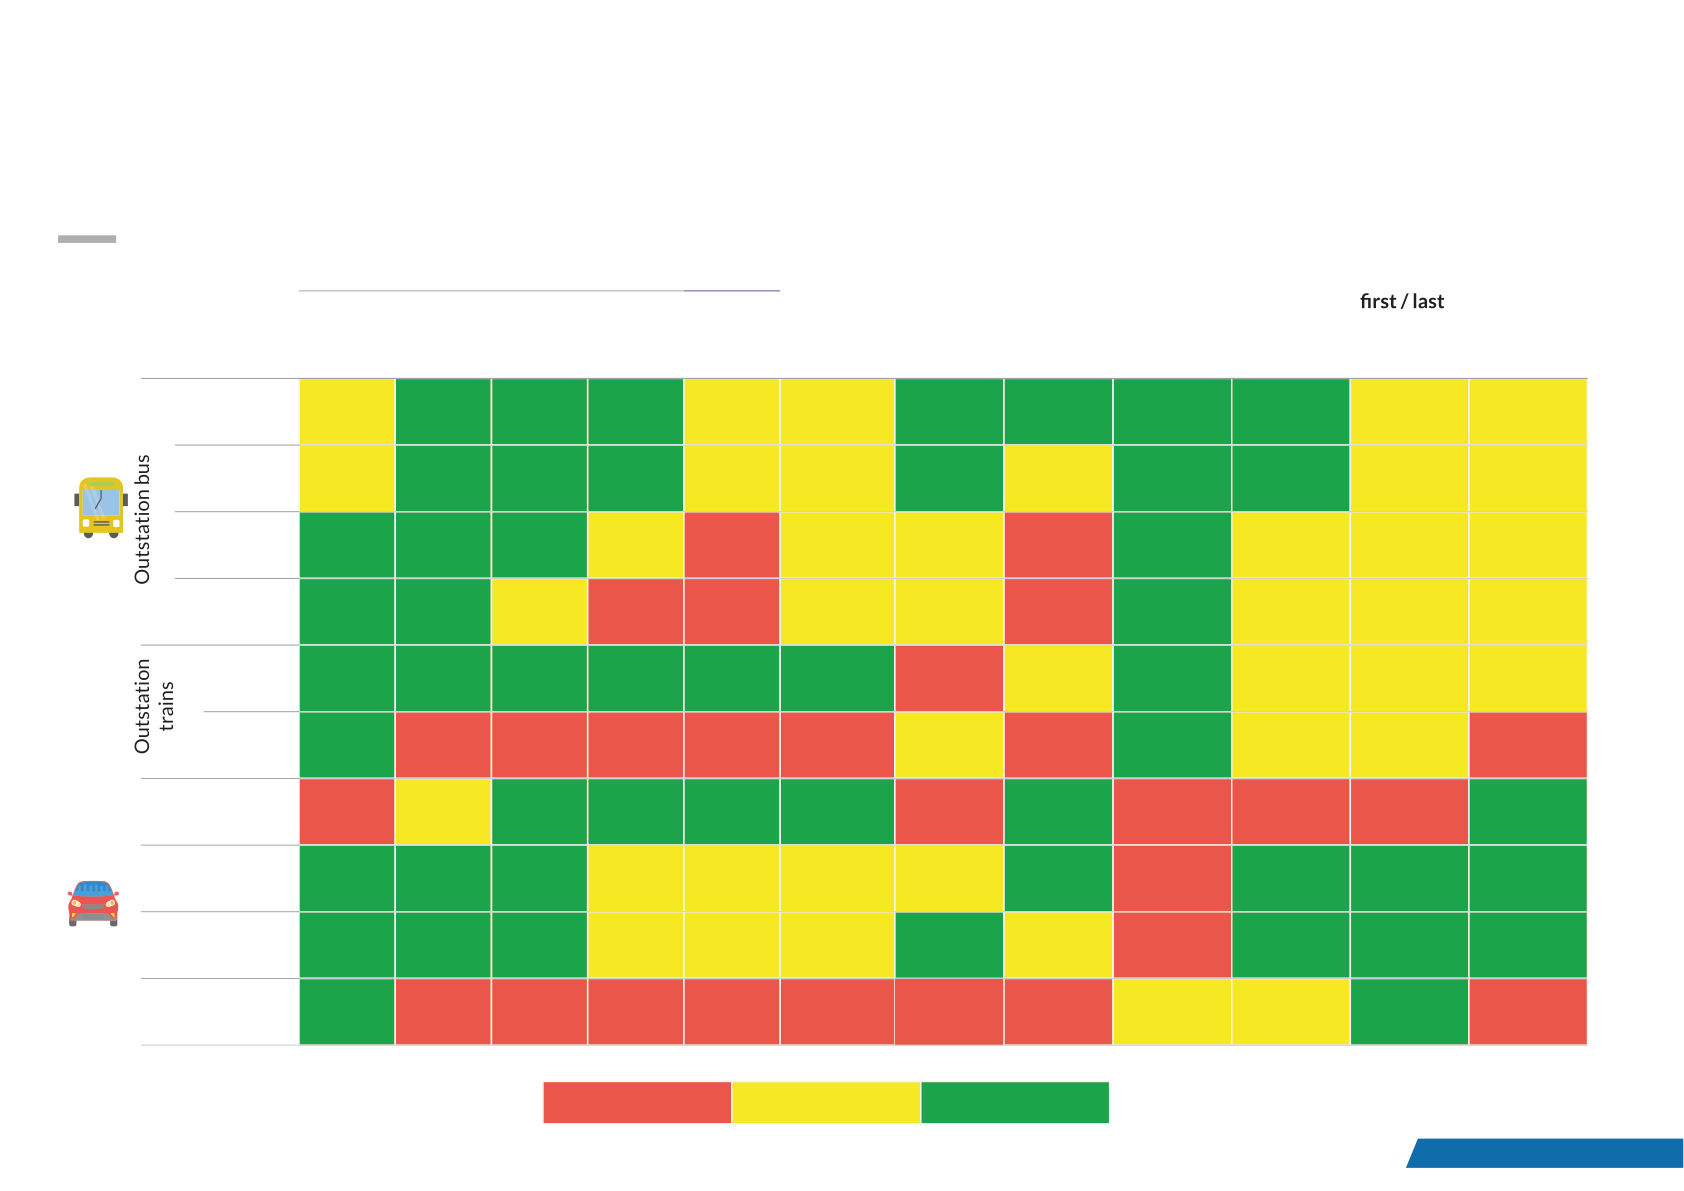
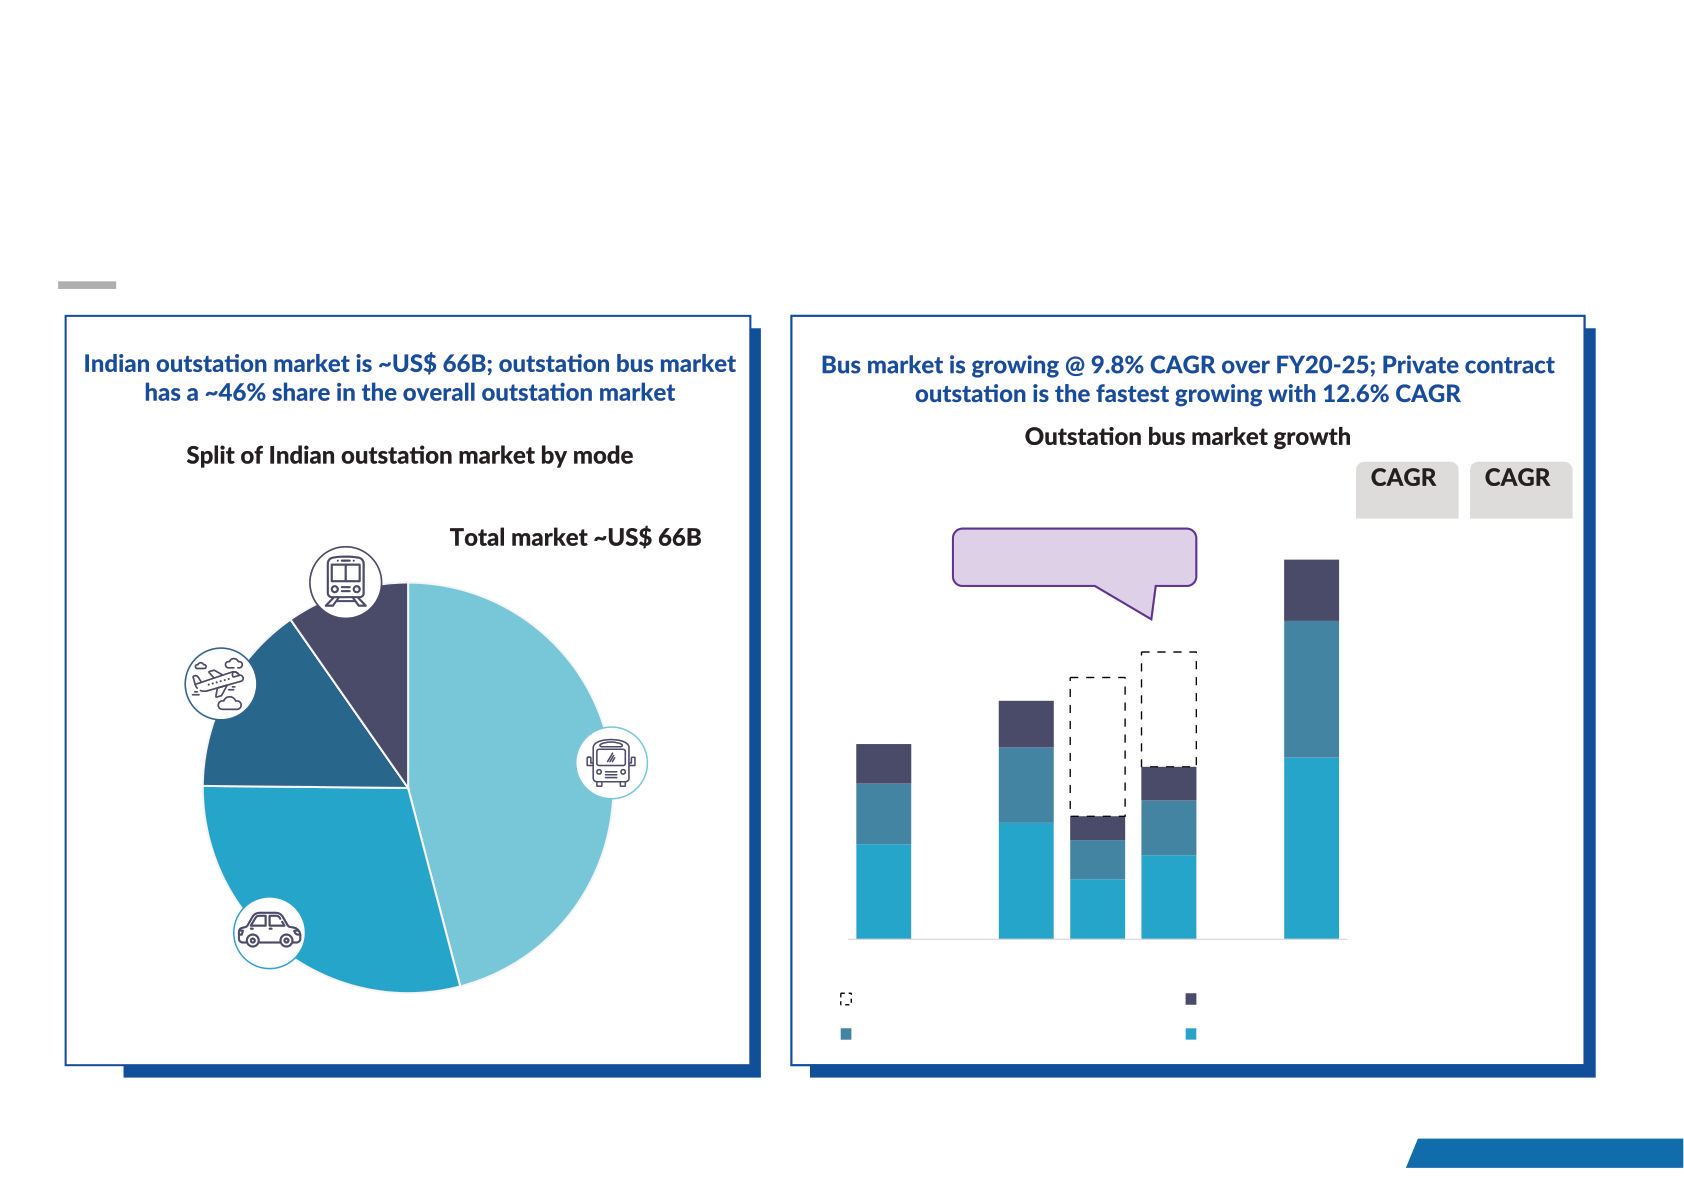
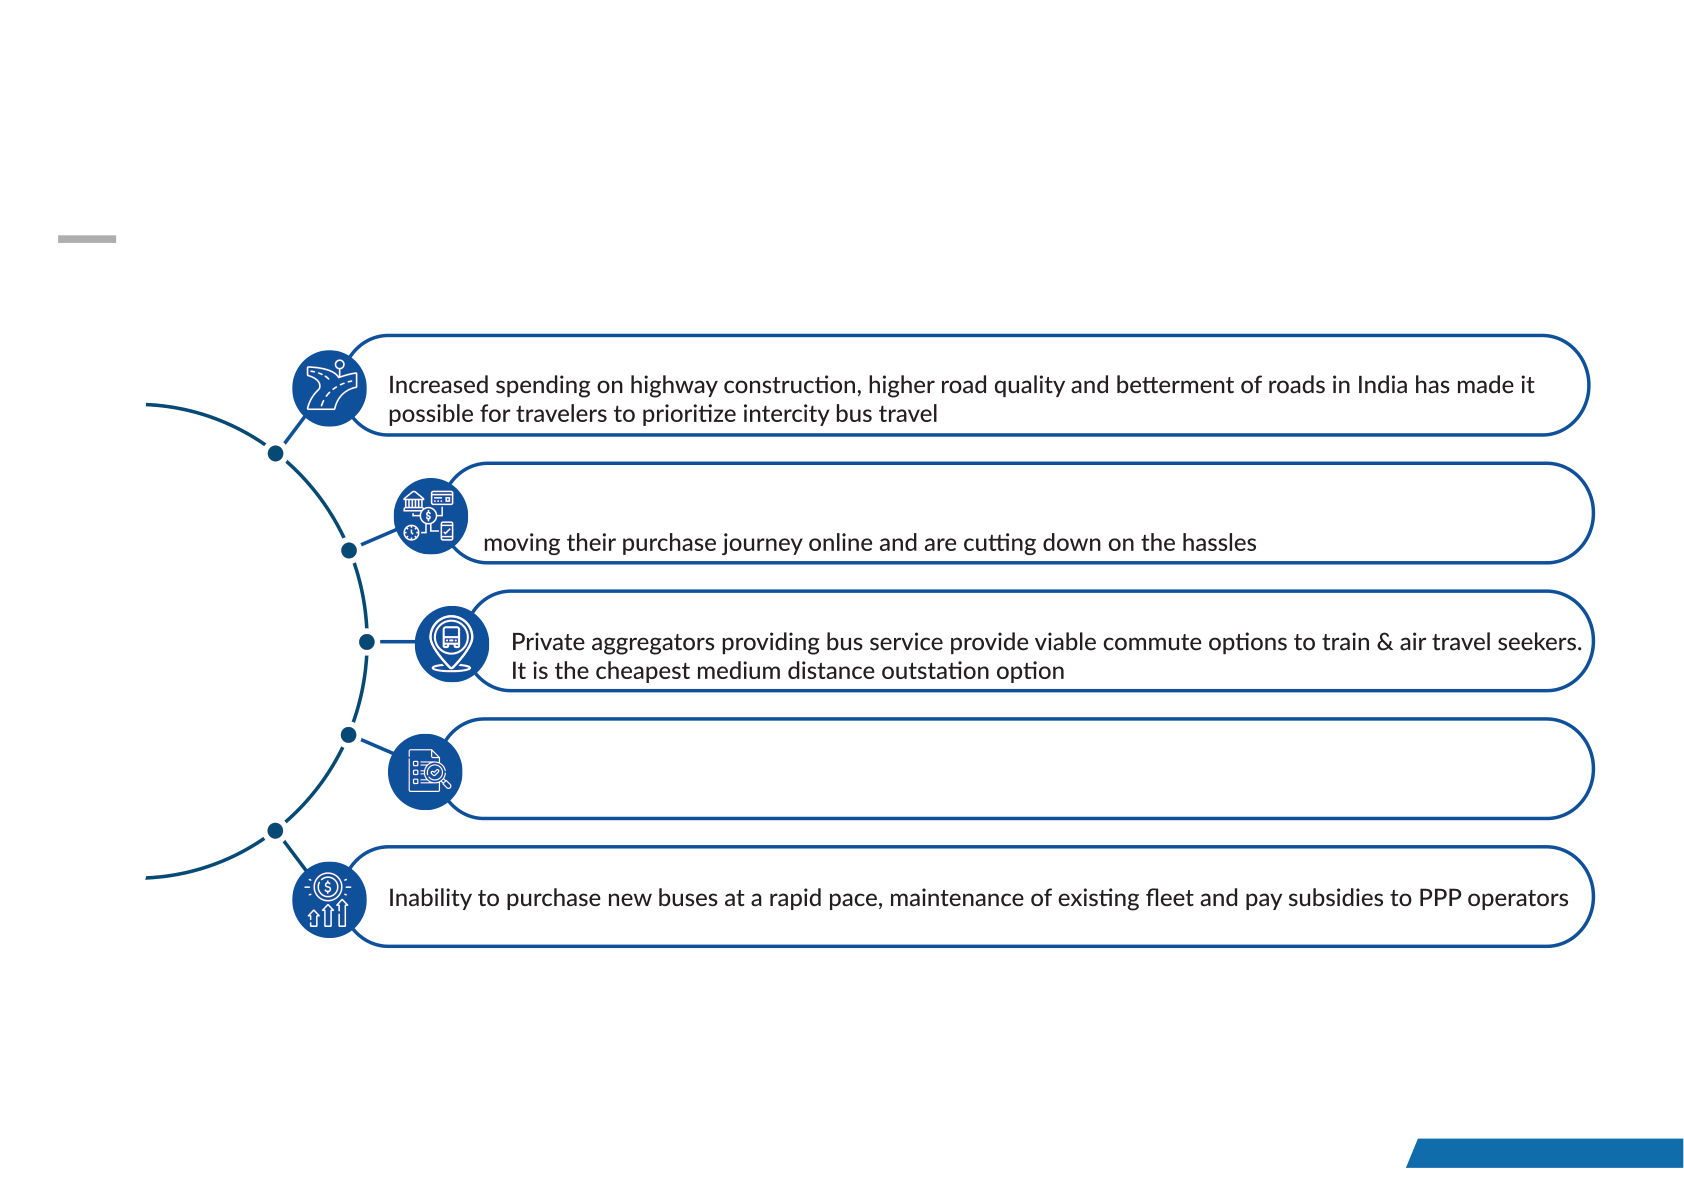
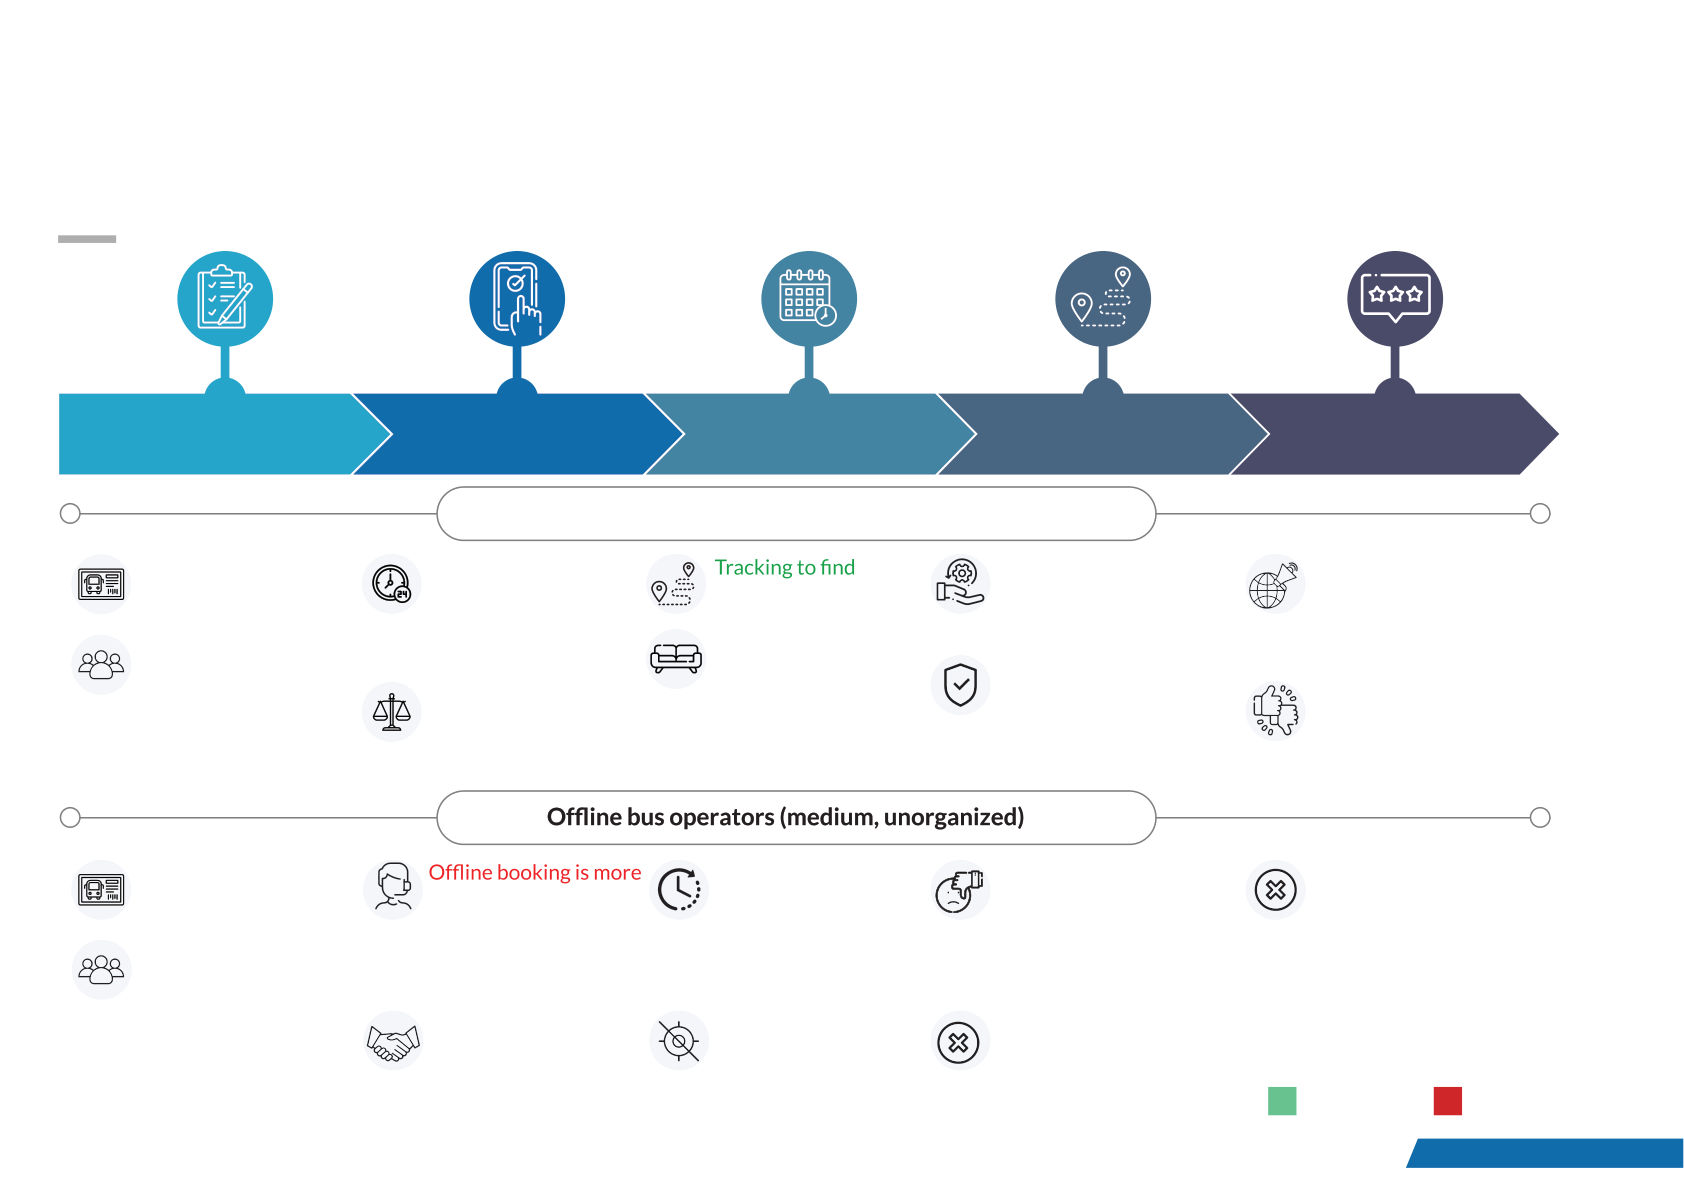
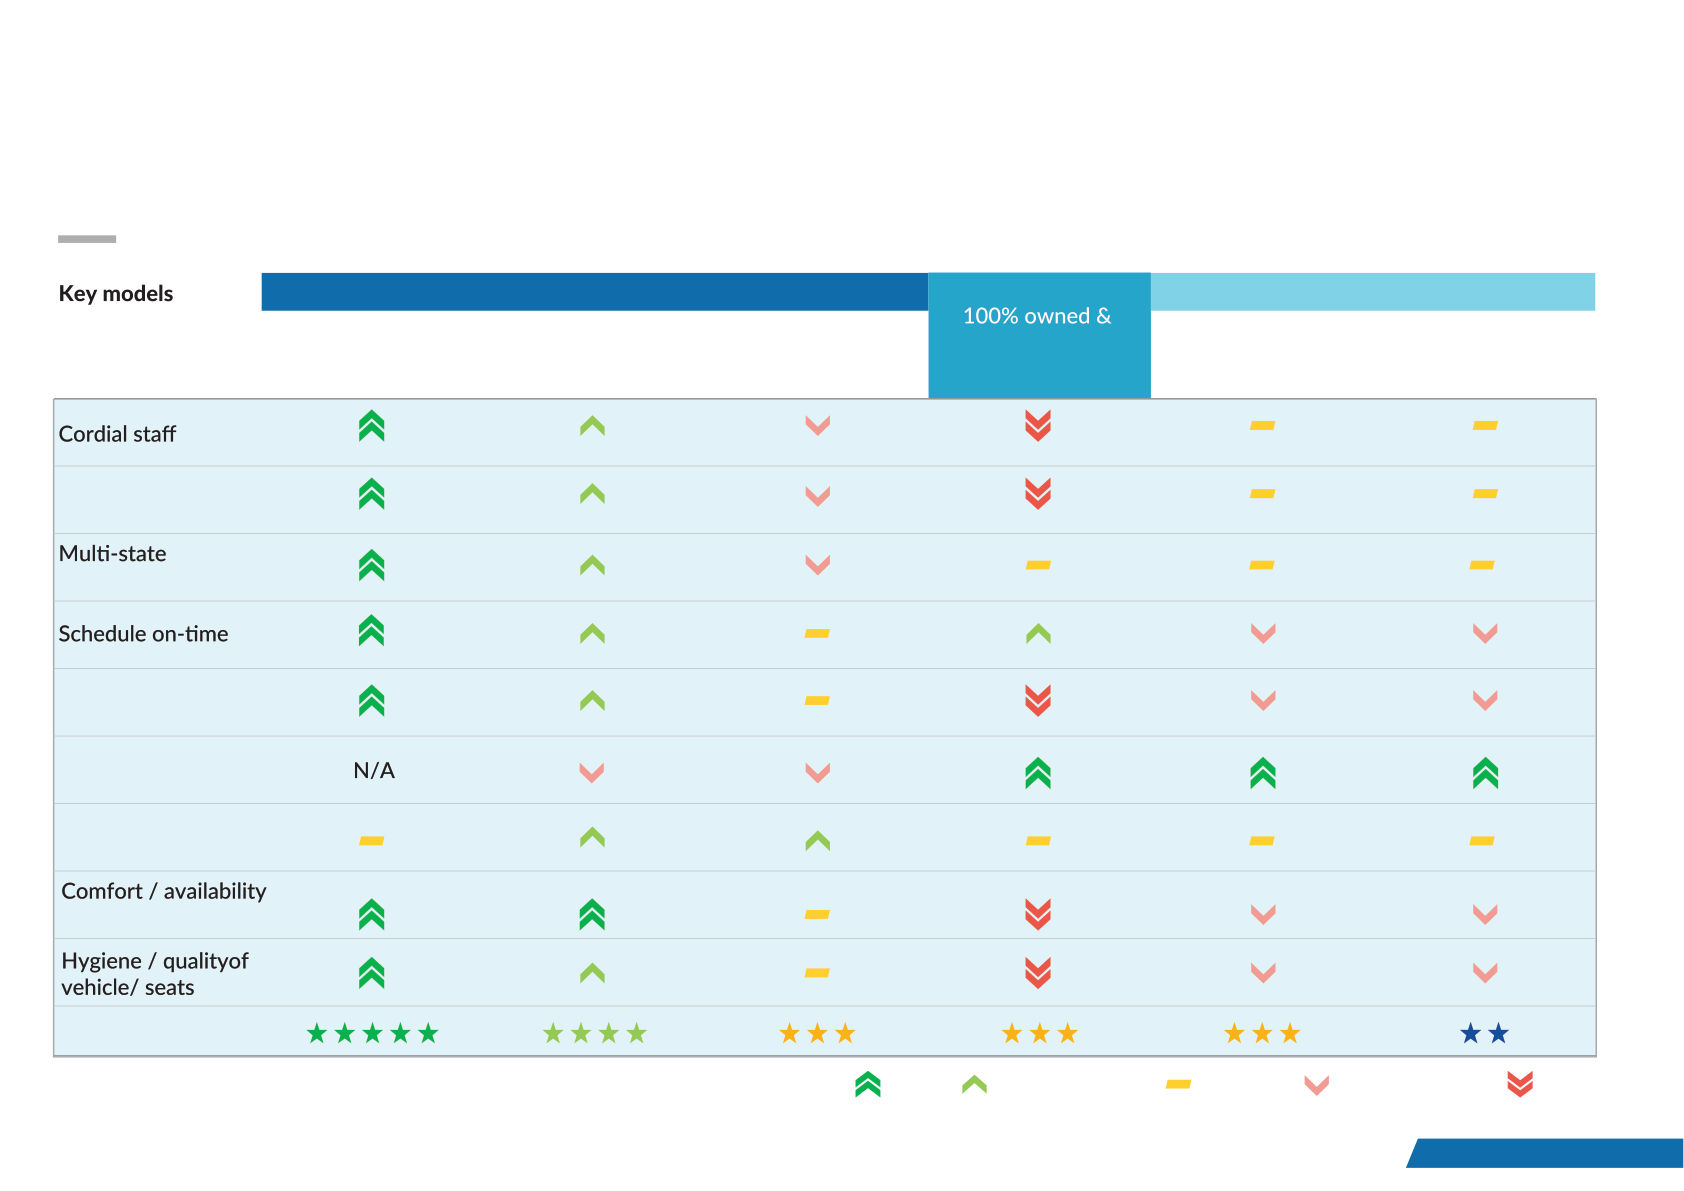
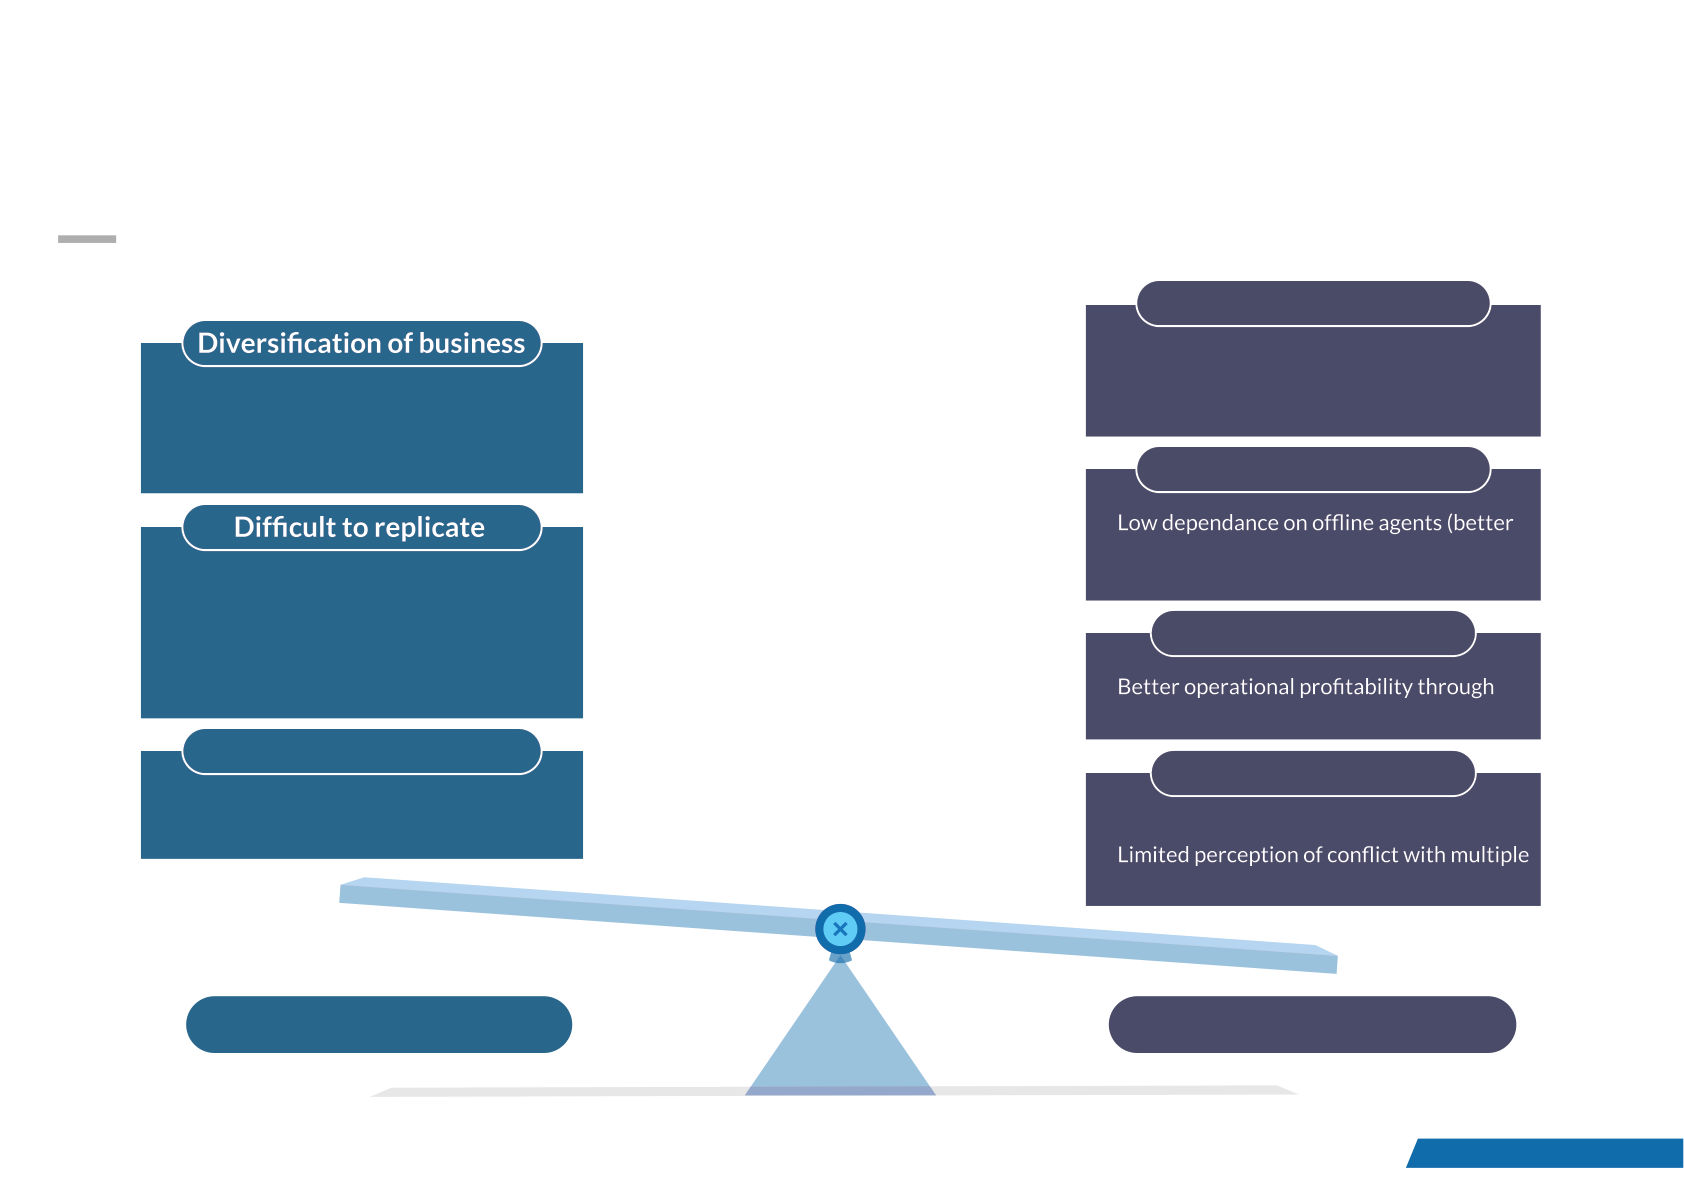
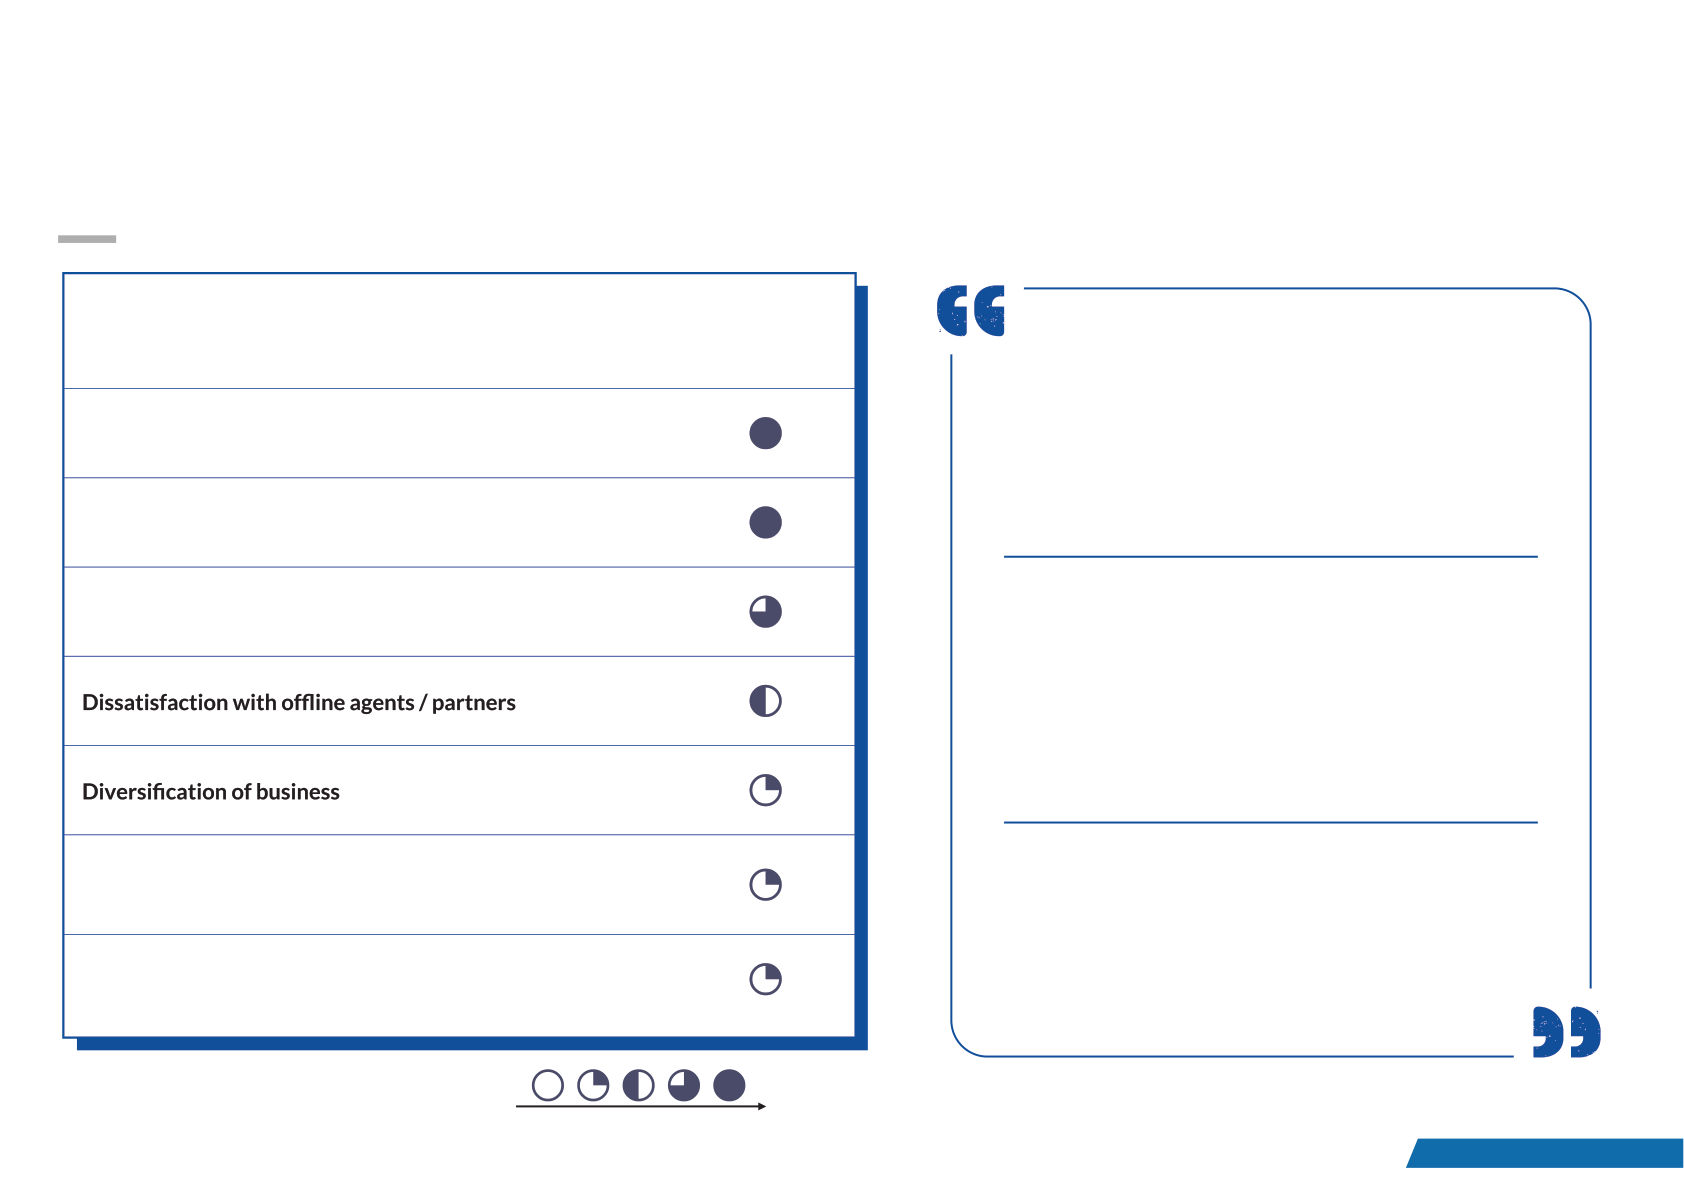
(Erstwhile PGA Labs) Report Top Trends Driving growth of outstation bus market March 2023 Foreword The Indian outstation travel We have examined the market is largely untapped by parameters of choice for organized players. The huge outstation bus commuters for population of the country coupled various service providers, and with a rapid increase in how that varies with different urbanization has led to more and factors. We have also discussed more individuals adopting to how the infrastructure has various modes of transport, developed in last few years for ranging from personal transport to various modes. We have outlined public. The increase in mobile the drivers and barriers for Praneet Singhal penetration and availability of online penetration for outstation Director cheap data has led to an advent of bus travel. The situation is MobilityTech, 1Lattice several online travel agents and evolving rapidly, and some of the aggregator platforms in the expected scenarios might have country, with affordability as the slight variations. This 20th Jan central offering which would help 2023. Please contact us for in expanding the operators to latest updates on outstation bus reach beyond metro and travel. tier-1 centres. We, at 1Lattice, look forward to This report is intended to provide continuing the discussion with various industry stakeholders our friends across sectors and including business leaders an exchanging notes as the overall perspective on the Indian situation evolves. outstation ecosystem in India. Glossary of terms Biomass • Asset-light model players, but responsible for technology, marketing and experience (players such as IntrCity, Full stack tech Zingbus, Flixbus etc.) aggregator • Online Travel Agency; Third-party websites that allow consumers to search for, book, and buy various travel OTA offerings online • Original Equipment Manufacturers (e.g. Tata Motors, Ashok Leyland, Mahindra & Mahindra, etc.) OEM Outstation • Intercity trips that are not restricted to travel within a single city / town • Rides that do not require advance booking, but can be availed at the designated bus stops or Hail and ride by signalling the driver • State Transport Undertakings that provide public transport services STUs • Public-Private Partnerships, involving collaboration between a government agency and a private-sector company PPP Gross Cost Contract; Public bus agency collects farebox revenue and pays a fixed fee on pre-decided • GCC performance to operators • Net Cost Contract; Operators retain farebox revenue and pay a premium to the public agency NCC • Combination of ‘telecommunication’ and ‘informatics’, with several applications in transport such as vehicle Telematics tracking & diagnostics © 1Lattice | 03 Table of contents S. No Content Page No. 1. Outstation bus travel is the fastest growing segment in outstation travel industry 8 Growth drivers for online outstation bus travel market 9 2. 3. The online outstation bus market potential is high and growing faster 10 4. Emerging trends in the outstation bus market – (Showcase growth in online and Tech-based play) 11 Full stack tech aggregators driving the growth of outstation bus market 5. 12 Customer – Delivering consumer delight and supe rior experience 13 6. 7. What is restricting incumbents to become large national level 15 8. Value creation for bus operators by Full stack tech aggregators 16 Full stack tech aggregators driving the growth of technology adoption in outstation bus market 17 9. © 1Lattice | 04 Full stack tech aggregators have end-to-end integrated features that are unparalleled by other players in outstation bus market Full stack tech U orga ized Large Orga ized Features OTAs aggregators operators operators Customer app / website for booking tickets Robust search engine with wide inventory Rescheduling / cancellation ability Chatbots & helpline Access to ratings and reviews Payment gateways & wallet facility Email and SMS confirmation, push notifications Real-time bus tracking IVR automation for boarding intimation Facilitate dynamic pricing Proprietary in-bus connectivity and applications platform IoT enabled buses Crew app / platform for trip management Operator dashboard and reporting Predictive analysis for profitable routes / timings © 1Lattice | 05 Growth of road infra is faster compared to others and relatively low priced the same over the last decade @ ~6% over FY15-20 @ ~7.5% over FY11-20 (in K, FY11-25) (FY15-25) (in K, FY11-25) 200 132 120 126 128 121 114 141 95 136 87 104 67 65 71 COVID impact has led to slower growth of national highways FY11 FY17 FY20 FY22E FY25P FY15 FY17 FY20 FY22E FY25P FY11 FY17 FY20 FY22E FY25P CAGR 1.1% 0.9% 6.0% 6.6% 7.5% 8.0% Price range per INR 0.2-2 INR 5-15 INR 1-3* km in FY20 Note(s): *Indicates private contract carriage buses only doesn’t include public and private hail and ride buses Source(s): MORTH, DGCA, IRECP, 1Lattice analysis © 1Lattice | 06 Private buses are convenient for outstation travel <1,000 kms as they are cheaper, time-efficient and enable superior reach Average Average Convenience Average wait time Time for total journey price / for time taken 100-250 250-500 500-1000 >1000 100 km Comfort & departure mile (indexed to <100 km km km km km Safety Availability (in USD) amenities (in mins) connectivity buses) Private 1.9 15 mins 20 mins 1x (pre-bookable) Public 0.9 15 mins 20 mins 1x (pre-bookable) Private(Hail 0.9 30 mins 20 mins 1.1x & ride) Public(Hail & 0.9 30 mins 20 mins 1.1x ride) Non Sub 0.7 20 mins 20 mins 1.1x Urban Sub urban 0.3 20 mins 20 mins 2.1x Flights 14 90 mins 60 mins 0.6x 4W cab 18 5 mins 5 mins 0.8x aggregators 4W taxi 21 5 mins 5 mins 0.8x 4W –Maxi 3 20 mins 5 mins 1.4x cab Least favourable Most favourable Moderate Source(s): Secondary research, 1Lattice analysis © 1Lattice | 07 Outstation bus market commands >45% of the total Indian outstation market; Private contract pre-bookable segment in outstation buses is leading to growth with ~13% CAGR in FY20-25 (US$ B) (%, FY20) FY17-20 FY20-25 COVID impact on travel has 48.2 6.9% 9.8% led to decrease in market 7.8 5.7% 5.7% 36.5 10%, 33.3 Trains 30.3 17.4 15%, 14.6 7.6% 12.6% 5.9 24.8 Flights 17.6 46%, 5.0 Buses 4.3 9.6 3.0 7.7 3.0 6.9 23.1 29%, 5.0 6.9% 9.3% 14.8 4-wheeler 12.1 10.7 7.6 FY17 FY20 FY21E FY22E FY25P COVID loss Others Public long distance prebookable Private long distance non-prebookable Note(s): 1. Buses that travel >100Kms are considered as long distance, 2. Buses that travel <100Kms are considered as short distance, Others includes private short distance, public buses Source(s): MORTH, DGCA, Indian railways, UIPT India, Ministry of urban development, 1Lattice analysis © 1Lattice | 08 Economic and structural enablers are driving the Indian private outstation bus market Infrastructure spend and development Digitization of economy With falling costs and rising availability of smartphones and internet, Indian consumers are increasingly Growth drivers of Organized private players private outstation One Nation - One Permit bus market Launch of All Indian tourist permit for commercial vehicles to reduce barriers for inter-city travels Decrease in share of STUs and rise in online players has led to decrease in the share of public buses Source(s): Secondary research, 1Lattice analysis © 1Lattice | 09 Online bus market is expected to be at 10% but has potential to reach 25% driven by a shift in customer behavior and overhaul in bus operator business operations (%, FY10-25P) 80% 70% 70% prices would lead many consumers to use online 60% 60% 54% 49% 50% and reliability of services which leads to prefer- 40% 35% 30% Max potential 28% 30% 25% 18% 20% Bus operators would be educated on advantages 11.4% 9.5% 8% 6.9% 10% 5.0% 0% be willing to list their inventory on online 2.5% 0% Mobile & internet Rise in smart- Jio usage adoption phone disruption Intra-city Taxi Hotels Trains Flights Inter-city Buses Note(s): * Indicates expected penetration of overall market if not impacted by COVID Source(s): Industry databases, Secondary research, 1Lattice analysis © 1Lattice | 10 Outstation bus industry is driven by integration of tech, improved facilities and emergence of bus aggregators / OTAs • Growth in tech start-ups & emergence of online 1992 2006 players (including full stack tech aggregators, OTAs, Global market saw Advancements operators, etc.) & innovations / in late 1990s • Advent of mobile wallets & remote payments integration of 2007 1997 leading to growing popularity of online channels tech • Rise in use of tech-led pricing algorithm, back-end bus management software, GPS tracking, etc. 2008 2011 • With increase in disposable income led to increase Rising demand for in preference for sleeper buses for comfortable Sleeper buses journeys • Bus market saw rise in OTA players 2012 Improved service • Rise in demand for amenities like GPS tracking, during early 2000s to 2010s and amenities lounge services, blankets, pillows, water, etc. • This was followed by rise in demand for comfortable and luxurious buses Rising demand for • Increasing expectations of consumers for better • Post 2018 industry saw emergence 2013 standardized services and standardized of services from bus of various full stack tech aggregators services which adopted apps & website model operators • Growing awareness & demand for sustainable and 2016 Rising popularity • Launch of EV buses for outstation short distance 2019 of electric buses haul (<250 Kms) 2017 • Europe: Various measures have been taken by the government to curb pollution Very low Very high Note(s): Timelines are indicative of major players in Indian and global bus market; Founding year of OTAs is mentioned Source: Secondary research, Company websites, 1Lattice analysis © 1Lattice | 11 Growth of full stack tech aggregators will enable value creation across stakeholders • Access to multiple trip options and • More transparent revenue transparent pricing reporting & tax collection • Standardized operations and • Greater entrepreneurship and quality employment • Comfortable journey experience • Streamlined operations and • Consumer maturity in booking models and payments providers • Lower sales effort for OEMs with Bus operators tie-ups • Higher penetration of insurance, • Steady revenue generation • Higher occupancies and lower after-sales offering pilferages • Higher adoption of new technologies • Pre-negotiated pricing with (telematics, entertainment systems) OEMs and service providers creating more job opportunities • Tech integrations, training and additional support 02 03 01 04 Note(s): *PPP stands for public private partnerships Source(s): 1Lattice analysis © 1Lattice | 12 Full stack tech aggregators and large organized players provide superior customer experience Planning Booking Waiting Journey Post-journey Full stack tech aggregators and large organized operators Planning the time and Ease of booking ‘24/7’ Have the option to get Easier to reach out to the destination of the trip via online through abou bus location picked / dropped off operators in case of any company website / at multiple locations concern that the passenger Duration of travel and app, OTA Lounge area for may want to relay # of people travelling waiting and in few The journey is are decided based on Easy of comparison of cases, refreshments comfortable as the buses Full stack tech aggregators the budget of the prices and availability provided are well maintained and and OTAs ask their customer of buses of superior quality customers to share their experience Planning the time and Waiting time can be The buses are not well Cannot reach out to the destination of the trip common for public higher sometimes as maintained, and the operators in case of any buses. Tickets are sold they are not as orga- journey can get feedback. Operators do not Duration of travel and via tickets counter and nized as large private uncomfortable in some ask their passengers to # of people travelling travel agents operators cases share their experience post are decided based on journey the budget of the Negotiation on price Poor infrastructure for May / may not have the customer for regular / repeat waiting passengers option for multiple pick customers up, drop location Positives Negatives Source(s): Customer discussion, 1Lattice analysis © 1Lattice | 13 Full stack tech aggregators have higher customer satisfaction levels compared to others Private operators PPP –Public private partnership Full stack tech operated by ‘STU aggregators(IntrCity, Organized Unorganized GCC NCC Zingbusetc.) Safe driving presence Maintenance of safety standards Non AC bus prices AC bus prices of seats Overall score High Above average Average Below average Low Customer satisfaction level Note(s): OTAs have not been considered for comparison Source(s): Outstation commute customer survey, Secondary Research, 1Lattice analysis © 1Lattice | 14 Full stack tech aggregators have better advantage over legacy players to build national-level operations Advanced tech-stack • Premium pricing by offering superior experience • Prefer to utilize their investment in other • Optimize large-scale operations existing / new business such as logistics, hotels, cabs etc. within their key Reduced commission rates geographies • margins) • Challenges in operating beyond their • Easier customer acquisition via OTAs catchment areas including low brand popularity, developing operational Dynamic pricing processes & partnerships, and • professional talent AI-based pricing algorithm Regional operations Asset-light model • Expansion to other states remains limited • Scalable model with low capex around the hub regions • operators Legacy players Full stack tech aggregators Source(s): 1Lattice analysis © 1Lattice | 15 Bus operators Requirement of a steady revenue stream and better value proposition for bus operators are the key reasons to choose full stack tech aggregators Key reasons for choosing full stack tech Importance aggregators (IntrCity, Zingbus, Flixbus etc.) “Our business was not able to pickup post the pandemic, during which an full stack tech aggregator approached us — their value proposition was good Requirement of a steady revenue stream and helped us earn steady revenue without worrying about customer acquisition costs” Better value proposition (revenue terms, operating -Bus operator with more than 50 buses conditions etc.) “The minimum guarantee we get is almost half the Goodwill / reliability of tech operators bus’s EMI which is helpful and helps us in making our EMI payments. Also, there is never delay in payments. If there is a public holiday on the payment date, we receive it 1-2 days prior” -Bus operator with 10-50 buses’ Belief that the full stack tech aggregators will grow in the “The brand of the aggregator helps to pull in more long term and are the next big thing in the bus travel segment customers based on its service record of on-time arrivals, maintenance standards, cleanliness and safety during trip” Positive feedback from peers / other operators -Bus operator with less than 10 buses Very low Very High Importance Source(s): 1Lattice analysis © 1Lattice | 16 Full stack tech aggregators have democratised the use of superior end-to-end tech for better operations and consumer experience Mobility tech utility for operations Mobility tech utility for consumer experience Fleet & route Seamless digital Real-time updates Dynamic bus pricing optimization booking and 24x7 booking Integrated feedback Access to Wi-Fi Enhanced performance loops and add-ons rescheduling ability Rewards and Customer retention subscriptions Source(s): 1Lattice analysis © 1Lattice | 17 Value proposition offered to operators and customers by full stack tech aggregators Operator problems solved Customer problems solved Tech-enabled integrated model Lack of clarity on Unable to maximize Inaccurate real-time Unpredictable bus location ticket availability Tech value proposition integrated operations Superior Sudden breakdowns Manually monitor and Lack of service Cumbersome booking passenger or maintenances standardization procedure experience time Key technologies Managing cash Compromise on Inability to reschedule Repeated customer payments & accessibility / cancel tickets calls for queries / info • Comprehensive GDS platform pilferages • Partner platform and crew platform • IoT-based telematics and big data analytics • Partner dashboard and reporting module • Connected vehicles (CCTV, Wi-Fi, GPS, entertainment, smart lounge, IVR automation) Low consideration for Ineffective avenues • Self-serve web portal and customer app Limited oversight over Delays in operations passenger safety for reporting driver performance due to lack of SOPs • Integrated payment systems grievances • Source(s): 1Lattice analysis © 1Lattice | 18 Full Stack Tech aggregators have democratised the access of superior end-to-end tech for better operations and consumer experience paving the path for other bus operators Mobility tech utility for operations Mobility tech utility for consumer experience • Connected app ecosystem with real-time data insights • Online booking and contactless payments bring in helps manage operations more efficiently convenience in customer boarding experience Fleet & route Seamless digital optimization • Vehicle utilization and profitability is improved by booking • Access to larger trip inventory across regions to choose better demand prediction technologies from and easier comparison of prices • AI-enabled pricing algorithm to optimize occupancy • IoT-based fleet analytics allows for live route tracking, Real-time and maximize trip revenue scheduling trip updates and alerts Dynamic bus updates & pricing • Helps offer higher flexibility in offerings for • Dedicated customer support to manage grievances 24x7 support consumers across different days and time and offer resolution • Tracking vehicles condition (fuel use, tyre pressure, • WiFi and in-bus entertainment helps reimagine the Telematics for battery, speed sensors, rough braking, etc.) can help in Access to WiFi service delivery with added comfort vehicle timely scheduling of maintenance & add-ons • Other VAS including pre-booked meals, clean performance • Driver performance and fatigue alerts received washrooms, luggage handling and sanitization • Consumer engagement, reviews & feedback can be • Greater access to modifying trip, rescheduling or Enhanced received and met with service excellence cancellation options with a platform setup Integrated rescheduling feedback loops • Corrective actions for complaints about availability, • Higher transparency in pricing and cancellation terms ability timeliness, security and hygiene taken generate stronger trust • Scalable delivery model with reliable operations helps • Offers, cashback & referrals can be availed to make drive repeat purchases the trip more affordable & rewarding Customer Rewards and • Cutting-edge data capabilities and insights allow for • Subscriptions, packages or exclusive curations garner retention subscriptions higher degree of personalization for customers customer loyalty among satisfied customers Source(s): Secondary research, 1Lattice analysis © 1Lattice | 19 We’re here for you Let us know how can we meet your business requirement? Praneet Singhal Connect now Director, MobilityTech, Vaishnav Kumar Rai 1Lattice Manager – Corporate Communications E: communications@1lattice.com M: +91 782 794 4925 Gurugram Bengaluru hello@1lattice.com New Delhi Mumbai www.1lattice.com Disclaimer: This material has been prepared by 1Lattice, which is the trade name of Lattice Technologies Private Limited (“1Lattice”, “we” or “our”) with the intent to showcase our capability and disseminate learnings to potential partners/clients. This material can be referred to by the readers on the internet but should be referenced to 1Lattice, if reused or adapted in any form, or medium and on any forum. The frameworks, approaches, tools, analysis and opinions are solely 1Lattice y, and the 1Lattice team’s own experiences and observations. Any information provided herein is only for informational purposes and you are advised to perform an independent analysis of the same before making any decision based on such information. The information does not constitute any business advice or guidance and is to be construed as a general summary based upon the publicly available information and our interpretation of the same using our resources. For this material, we may have relied upon different sources of information which may be primary sources, publicly available information, and relevant information available with us. We make no representation or warranty, expressed or implied, that such information is accur ve predictions or forecasts. Before reading further, the Recipient expressly agrees that this might not address any and all risks and challenges facing the Recipient, its business, and the markets within which it operates, nor all possible market conditions. Any use of the information provided herein b oyees shall not be liable for any unintended or adverse effect or outcome from the use of such information by the reader. ave any duty to update or supplement any information in this document. 1Lattice shall not be responsible for any business or commercial loss sustained by any person who relies on any information provided herein. Any and all logos of companies used in the information provided herein have been published for information purposes only and 1Lattice does not hold any liability in connection therewith. 1Lattice We enable better decision making. Technology-backed business support that helps you ENABLE BETTER 500+ 30% annual engagements faster to outcomes DECISIONS Deep on-ground insights that you can act on 8 600+ practices years domain expertise 4 offices, deep experience across geographies – India, the USA, Europe, MEA, and SEA regions 130+ 98%+ team members accuracy One-ness of data and people networks to harness the collective power of data, network, and technology 100+ 2.5M towns & cities panel members Multi-faceted teams offering a stack of consulting, advisory, and research services 15+ 40:60 languages covered she/he ratio The team at appreciates your time and support THANK YOU Enabling Better Decisions. New Delhi Gurugram Mumbai Bengaluru Unit 5, Ground Floor, Tower A, 4th Floor, 112, First floor, 2734, Fourth floor, Uppal Plaza M6, District DLF Centre Court, Workafella, AK Estate, HSR Layout, Sector 1, Centre, Jasola -110 025 DLF Phase 5, Sector 42, Goregaon West, 27th Main, 16th Cross, New Delhi, India Gurugram-122002 Mumbai - 400 062 Bengaluru - 560 102 Haryana, India Maharashtra, India Karnataka, India Registered address: Unit 5, Ground Floor, Uppal Plaza M6, District Centre, Jasola, New Delhi -110025